
- Market Size (2026)
- USD 129.4 Bn
- Forecast (2036)
- USD 264.3 Bn
- CAGR (2026 to 2036)
- 7.4%
How big is the Bioethanol Market in 2026?
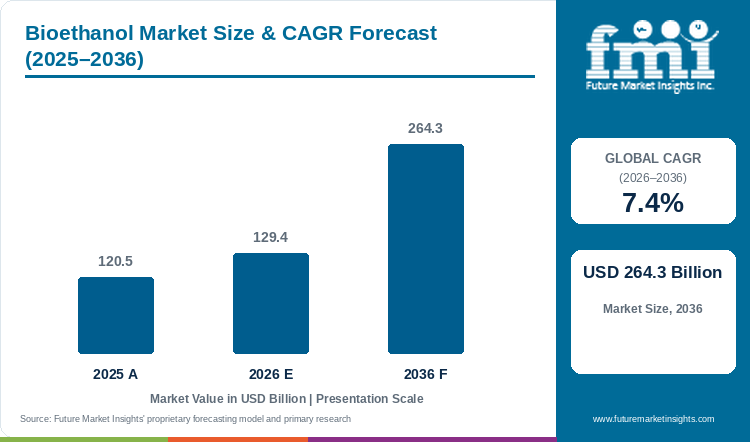
The global bioethanol market is estimated at USD 129.42 billion in 2026, compared with USD 120.50 billion in 2025, and is forecast to reach USD 264.26 billion by 2036, expanding at a CAGR of 7.4% from 2026 to 2036.
Demand for bioethanol is supported by government blending requirements that increase ethanol consumption in transportation fuels. India's Ministry of Petroleum and Natural Gas reported average ethanol blending of 20.0% between November 2025 and June 2026, compared with 19.2% in the preceding supply year. Brazil introduced a temporary E32 blending requirement on August 1, 2026, increasing the ethanol content of regular gasoline from 30.0% to 32.0% for 180 days, with a possible extension. The Brazilian government expects this change to reduce gasoline imports by approximately 900 million litres annually. Manufacturers are also expanding production capacity to meet higher blending requirements. In June 2026, the Asian Infrastructure Investment Bank approved financing of up to USD 70 million for FS Group's fourth corn-based ethanol facility in Mato Grosso, Brazil. The project is expected to add 540 million litres of annual ethanol production capacity, strengthening domestic supply as fuel blending requirements increase.
The supply response differs from the policy target. Green Plains reported about 764.9 million gallons of ethanol production in 2025, against about 846.2 million in 2024. Its February 2026 filing described nine plants with approximately 850 million gallons of annual nameplate capacity, with eight operating at the filing date. [4] FMI finds that blending growth supports an outlet for ethanol, while plant availability determines how much of it each producer supplies.
Key Market Trends & Insights
- India's July 2026 statement rejected a return to parallel nationwide E0, E10 and E20 supply, citing the logistics, inventory and handling cost across more than one lakh retail outlets. [2] Its policy supports continued concentration of ordinary petrol distribution on E20 rather than three competing base grades.
- The UK's RTFO review identifies double rewards for eligible wastes and residues and a declining cap for crop-derived fuels. [6] The compliance value of ethanol therefore depends partly on its feedstock classification, with a waste pathway competing on different terms from a conventional crop pathway.
- USDA identifies METI's consideration of Brazilian corn-based and Thai sugarcane- and cassava-based ethanol in revised standards. [10] Approval would add new feedstock and origin pathways to Japan's refining supply, widening the eligible supplier pool before direct gasoline blending expands nationwide.
Regional Highlights
- North America's ethanol supply increasingly serves markets outside the region. The EIA reported that US exports represented 13% of production in January to July 2025, compared with 12% in 2024. [8] This gives producers another outlet when domestic gasoline consumption provides limited growth.
- East Asia has contrasting routes to additional demand. USDA staff reported weak Chinese ethanol blending and pressure from electric vehicles in 2025, [11] while Japan published a plan for an initial E10 introduction around 2028. [16] The regional opportunity depends on country-specific fuel policy and infrastructure, rather than a uniform rise in blending.
Table 1: Bioethanol Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 120.50 billion |
| Estimated market size in 2026 | USD 129.42 billion |
| Projected market size by 2036 | USD 264.26 billion |
| CAGR from 2026 to 2036 | 7.4% |
| Added revenue from 2026 to 2036 | USD 134.84 billion |
Source: Future Market Insights, Bioethanol Market Report, 2026-2036.
Analyst Perspective
“A fuel-blending rule creates an outlet, but a producer is paid for ethanol delivered to specification. Plant utilisation and feedstock cost can change that supply even when the long-term market forecast rises.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Bioethanol Market segmented?
- By Feedstock: Starch-based; Sugar-based; Cellulose-based; Other biological feedstock.
- By Fuel Generation: First generation; Second generation; Third generation.
- By Fuel Blend: Low blends (E10 and below); E15 to E70; E75 to E85; Other fuel blends.
- By Region: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Why does starch-based feedstock lead by feedstock?
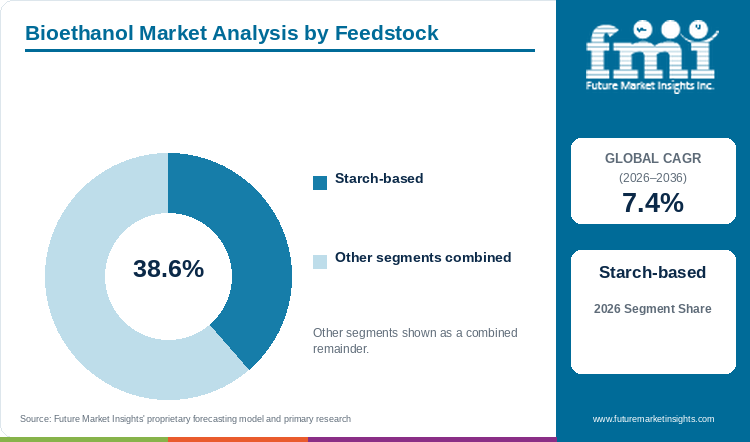
Starch-based feedstock holds 38.6% of the Bioethanol Market by feedstock in FMI's 2026 assessment.
Grain-processing coproduct sales help support the starch route alongside ethanol revenue. Green Plains reports distillers grains, higher-protein feed products and renewable corn oil as outputs of its corn plants. [4] These sales spread the plant's revenue across fuel and feed markets, while corn remains a purchased input. FMI finds that the starch lead rests on this established processing base, rather than on a guarantee that an ethanol blending rule makes every plant profitable.
Cargill's Eddyville site processes approximately 90 million bushels of corn annually and lists fuel-grade ethanol with starches, sweeteners, corn oil and feed ingredients. [15] The site illustrates a wider corn-processing model than a stand-alone fuel sale. Sugar-based and cellulose-based feedstocks retain separate conversion routes and costs; Eddyville's integration does not establish the same cost advantage at every starch plant.
Table 2: Bioethanol Market Leading Feedstock Share, 2026
| Leading Share | 2026 market share |
|---|---|
| Starch-based feedstock | 38.6% |
| All Other Segments Combined Share | 61.4% |
Source: Future Market Insights, Bioethanol Market Report, 2026-2036.
Why is first-generation ethanol the largest fuel generation?
First-generation ethanol holds 61.4% of the Bioethanol Market by fuel generation in FMI's 2026 assessment.
First-generation supply draws on operating corn and sugar conversion plants rather than the commercial scale-up still required for some cellulosic routes. Green Plains reports its annual output and corn use, [4] while Aemetis describes ethanol, wet distillers grains and corn oil production at Keyes in California. [14] These disclosures show the fuel and coproduct business already supporting conventional production.
The IEA identifies cellulosic ethanol as a potential expansion pathway, especially after 2030, and links the scaling of emerging technologies to grants, concessional finance, guaranteed pricing and targeted mandates. [5] FMI finds that this leaves first-generation production with the larger established supply base during the forecast's opening years. Existing plants also have an improvement route: ADM's Columbus programme targets additional corn grind and lower dryer natural-gas intensity. [13] Those changes concern a conventional plant's output and energy use; the fuel-generation label alone does not measure a consignment's emissions performance.
Table 3: Bioethanol Market Leading Fuel Generation Share, 2026
| Leading Share | 2026 market share |
|---|---|
| First-generation ethanol | 61.4% |
| All Other Segments Combined Share | 38.6% |
Source: Future Market Insights, Bioethanol Market Report, 2026-2036.
What supports low blends (E10 and below) as the leading fuel blend?
Low blends (E10 and below) hold 59.0% of the Bioethanol Market by fuel blend in FMI's 2026 assessment.
Low blends lead through their place in established gasoline sales. The US Department of Energy identifies E10 as the country's most common ethanol blend, and EIA reports that nearly all US motor gasoline contains about 10% ethanol. [17][8] This links a large recurring ethanol outlet to gasoline consumption. Higher ethanol content is a separate growth route: India's ordinary petrol programme has reached E20, while Brazil's E32 requirement applies temporarily to its specified gasoline pool. [2][3] These programmes support higher-blend demand without changing the broad low-blend outlet already served in other markets.
The low-blend category covers positive nominal E-designations through E10, including E5, E7 and E10. Nominal E15 to E70 and E75 to E85 form separate categories; other covered blends and fuel routes, including ethanol for ETBE, remain outside the low-blend cohort. Classification follows the marketed designation: US E85, for example, varies seasonally in actual ethanol content and requires a compatible flex-fuel vehicle. [21]
Table 4: Bioethanol Market Leading Fuel Blend Share, 2026
| Leading Share | 2026 market share |
|---|---|
| Low blends (E10 and below) | 59.0% |
| All Other Segments Combined Share | 41.0% |
Source: Future Market Insights, Bioethanol Market Report, 2026-2036.
What are the key drivers restraints and opportunities?
Blending policy increases the ethanol outlet, but grain and energy costs still determine plant margins. The market's main mechanisms are the size of the mandated gasoline pool, the economics of operating plants and the value of lower-emissions production.
Driver
India's reported 20% average blend for November 2025 to June 2026 raised ethanol's share of its petrol supply above the previous supply year's 19.2%. [2] In the United States, EPA's March 2026 final rule establishes 2026 and 2027 obligations across several renewable-fuel categories. [1] FMI finds that the Indian blend directly specifies an ethanol outlet, while the US framework supports qualifying renewable fuel through a broader compliance market.
Restraint
Green Plains' ethanol production declined in 2025 despite its large installed network; the filing also identifies exposure to corn prices and operating risks. [4] A higher required blend does not fix the spread between the grain purchase, ethanol sale and coproduct revenue. FMI finds that poor plant economics can restrict output even while the national fuel programme supports demand.
Opportunity
Lower energy use in conventional ethanol production offers a route to better plant economics and a stronger emissions position. In October 2026, ADM reported completed first-stage Columbus improvements and planned further investment, including work expected to reduce natural-gas intensity in distillers-grain dryers. [13] The opening is in improving existing production; the expected second-stage benefit depends on completion and operation of the equipment.
How do fuel rules and quality requirements affect purchasing?
Eligibility rules change which ethanol pathway earns compliance value. The UK's RTFO distinguishes crop fuels from qualifying wastes and residues, [6] while Germany's 2026 law strengthens the rules around certification and access for on-site checks, with the on-site-check credit exclusion applying to quantities placed on the market from the 2027 obligation year. [18] Brazil's temporary E32 measure separately fixes the period and anhydrous product used in gasoline. [3] These requirements affect the value and eligible destination of the ethanol, rather than making renewable origin a universal qualification.
What limits reliable ethanol delivery?
Plant shutdowns reduce available ethanol before national nameplate capacity changes. Green Plains' February 2026 filing distinguishes nine owned plants from eight operating facilities. [4] Logistics then constrain where operating gallons are sold: the EIA identifies the Netherlands as a major route for rising US exports and notes onward shipments to other European markets. [8] FMI finds that an operating plant and an export terminal address different parts of delivery; adding distillation capacity alone does not establish the overseas route.
Where can producers win additional business?
The export opening lies in markets drawing more ethanol through established trading routes. EIA attributes most of the increase in US exports from 2024 through July 2025 to the Netherlands and identifies Canada as the largest destination. [8] Japan's planned direct-blending introduction adds a different, later opportunity alongside its existing ETBE route. [10][16] Suppliers serving current European and Canadian flows compete for near-term deliveries; those pursuing Japanese direct blending face a qualification and rollout timetable before the planned outlet expands.
Bioethanol Market by Country (2026 to 2036)
Table 5: Bioethanol Market Country Growth, 2026 to 2036
| Country | CAGR |
|---|---|
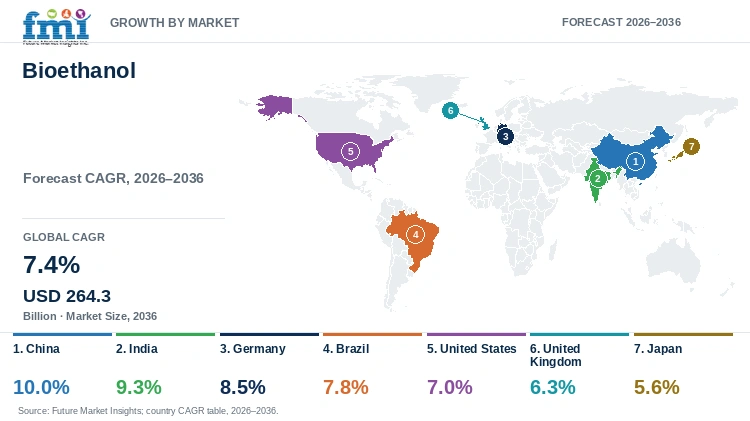
| China | 10.0% |
| India | 9.3% |
| Germany | 8.5% |
| Brazil | 7.8% |
| United States | 7.0% |
| United Kingdom | 6.3% |
| Japan | 5.6% |
Source: Future Market Insights, Bioethanol Market Report, 2026-2036.
What shapes bioethanol demand in China?
China's biological-ethanol producers face a shrinking gasoline outlet before they face a shortage of distillation capacity. USDA staff's August 2025 assessment put the national average ethanol blend at approximately 2.1%, with E10 mandates in only 15 provinces and no expansion of those areas since 2019. The report forecast 2025 fuel-ethanol consumption at 4.3 billion litres, down 11% from 2024, as electric vehicles reduced gasoline demand. [11] This makes wider blending within the remaining gasoline pool more important than adding another plant to a weak local outlet.
Coal-derived ethanol adds competition within that outlet. USDA reported that synthetic ethanol production doubled to 1.2 billion litres in 2024, including 436 million litres for fuel use. [11] These gallons sit outside the biological-feedstock boundary of the Bioethanol Market. Their presence nevertheless affects the supply available to Chinese fuel buyers, so growth in total ethanol production cannot be read as equivalent growth in biological ethanol sales. The source of the alcohol remains commercially relevant even when the resulting molecule is similar.
FMI's forecast 10.0% CAGR from 2026 to 2036, the highest among the countries profiled, describes expansion from this constrained biological-ethanol base. It requires more biological fuel reaching the gasoline pool as policy and consumption evolve. The forecast does not describe a nationwide high-blend programme already in operation. With electric vehicles reducing the underlying gasoline outlet and synthetic supply competing within it, the commercial case for biological capacity depends on additional eligible fuel sales, rather than the national total of installed ethanol capacity.
What supports bioethanol demand in India?
India has moved its petrol programme from incremental blending towards sustaining E20 supply. The Ministry of Petroleum and Natural Gas reported averages of about 12% in 2022-23, 14.6% in 2023-24 and 19.2% in 2024-25, followed by 20% for November 2025 to June 2026. [2] The sequence gives distilleries a larger ethanol outlet within ordinary petrol sales. Its commercial effect is repeated fuel-marketer demand across an established programme, rather than a one-off purchase associated with a test fleet.
That established outlet supports India's forecast 9.3% CAGR from 2026 to 2036, but a further base-blend increase is conditional. The government's July 2026 statement said no decision had been taken to move beyond 20%; any such decision would follow scientific and technical studies and consultation with vehicle manufacturers, oil marketing companies and research institutions. It separately described E85 for vehicles designed and certified for the fuel. [2] E85 therefore creates a vehicle-specific outlet alongside the petrol programme, rather than raising the ethanol requirement at every ordinary petrol sale.
The procurement terms also differ by feedstock. The ministry's July 2026 provisional price table for the 2025-26 supply year lists maize ethanol at INR 71.86 per litre, FCI-rice ethanol at INR 60.32 and C-molasses ethanol at INR 57.97. It states that the maize price precedes GST, transport, storage and depot handling. [22] These separate prices give grain and molasses distilleries different gross sales terms within the same blending programme. Feedstock and delivery costs still determine the margin available from each route.
What supports bioethanol demand in Germany?
Germany is increasing the emissions reduction required of transport-fuel suppliers, which raises the importance of ethanol's carbon performance alongside its price. The Second Act to Develop the Greenhouse Gas Quota sets the overall reduction percentage at 12% from 2026, 17.5% from 2027 and 26.5% from 2030. These are greenhouse-gas reduction requirements, not ethanol blending percentages. [18] A fuel supplier's choice therefore concerns the recognised emissions savings and cost of each eligible compliance option, rather than simply buying a fixed ethanol volume.
The wider EU framework similarly permits a transport target based on emissions-intensity reduction or renewable-energy share. [7] Ethanol competes within that framework with other qualifying fuels and energy routes. FMI's forecast 8.5% CAGR for Germany from 2026 to 2036 rests on biological ethanol taking business within this tightening compliance market and gasoline blending. It is not a direct conversion of the overall quota into ethanol revenue.
The Bundestag records the enacted law as dated 1 June 2026, promulgated on 5 June, with provisions commencing on 6 and 7 June. [12] The enacted text also provides for excluding biofuels from quota credit when access for the required on-site checks is not granted. That exclusion does not apply to quantities placed on the market before the 2027 obligation year. The law also adds related information to sustainability documentation. [18] For affected 2027 and subsequent quantities, denial of that access can therefore remove an ethanol cargo's intended compliance value.
For producers, lower-emissions processing and an auditable feedstock route address the same purchasing calculation. The quota trajectory strengthens the demand for recognised savings, while verification rules restrict which supplies can provide them. That combination favours eligible biological ethanol with substantiated carbon attributes without reserving the entire transport obligation for the product.
What supports bioethanol demand in Brazil?
Brazil's ethanol market is moving differently across its two main fuel outlets. ANP reported total ethanol production of 35.9 billion litres in 2025, down 2.8%, while anhydrous production rose 3.1% after the gasoline blend moved from 27% to 30% in August. Hydrated ethanol sales fell 5.9% as the fuel became less price-competitive against gasoline C. [19] The same market therefore combined a stronger mandatory blending outlet with weaker direct-fuel sales. A single national production number conceals that difference in demand.
The next change directly affects anhydrous ethanol for common gasoline. The Ministry of Mines and Energy introduced E32 from 1 August 2026 for 180 days, with a possible further 180-day extension. [3] At a given covered gasoline volume, moving from E30 to E32 raises ethanol consumption in that pool. It does not establish the demand for hydrated fuel, whose sales also respond to its relative price at the pump.
Brazil's forecast 7.8% CAGR from 2026 to 2036 extends beyond the temporary E32 period. The ministry conditions permanent E32 or higher blends on further E35 testing. [3] FMI finds that near-term anhydrous demand has a defined policy basis, while the longer outlook also depends on subsequent blend decisions and the competitiveness of hydrated ethanol. Producers must allocate output between those outlets as their returns change. This distinction also preserves the product boundary: anhydrous fuel blended into gasoline, hydrated fuel sold for direct use and industrial alcohol do not represent interchangeable demand. The market forecast covers the biological fuel business, while the cited E32 measure governs one specified part of it.
What supports bioethanol demand in the United States?
US ethanol growth increasingly depends on customers beyond the domestic gasoline pool. EIA reported average exports of 138,000 barrels a day in January to July 2025, the highest average for those months in its series. Exports grew while domestic consumption remained below pre-pandemic levels, reflecting lower gasoline use. [8] FMI's forecast 7.0% CAGR from 2026 to 2036 therefore sits alongside two different outlets: a large established blending market at home and expanding trade in fuel ethanol.
EIA linked much of the export increase through July 2025 to the Netherlands and identified Canada as the largest destination. [8] These flows give US production an outlet beyond changes in domestic gasoline consumption. They also make the destination mix important: ethanol sold through a European trading port follows a different commercial route from fuel blended within the United States. A rising national export total does not prescribe the same sales mix for every plant.
Operating evidence tempers the national growth argument. Green Plains produced about 764.9 million gallons in 2025, compared with about 846.2 million in 2024, and distinguished nine owned plants from eight operating at its February 2026 filing date. [4] The company demonstrates that output can contract within an expanding export market when plant and feedstock economics differ.
EPA's March 2026 final rule adds a continuing compliance framework for 2026 and 2027 across renewable-fuel categories. [1] Its total includes fuels other than ethanol, so it cannot be treated as a committed ethanol sales volume. FMI finds that US producers compete through the combination of domestic blending, exports and actual plant output. The forecast concerns the market's revenue outlook; it does not imply that each producer's gallons or utilisation rise at the same rate.
What supports bioethanol demand in the United Kingdom?
The closure of Vivergo reduced Britain's domestic ethanol supply while verified fuel use had been rising. ABF's 2025 annual report records that all Vivergo trading ceased by 31 August 2025. [9] Separately, Department for Transport statistics show 1,485 million litres of verified bioethanol supplied in 2024, 79 million litres more than in 2023. [20] The combination creates an opening for replacement supply through other plants and import routes, rather than evidence that the closure removed the blending outlet itself.
The official statistics put bioethanol at 39% of verified renewable fuel in 2024 and associate its growth since 2021 with the introduction of E10. [20] The RTFO remains broader than this ethanol business: its main obligation is 12.5% in 2026 across eligible renewable fuels, with different treatment for crop-derived supply and eligible waste or residue pathways. [6] An increase in the overall obligation therefore supports competition among compliance options, not an ethanol-only allocation. Ethanol's feedstock and carbon treatment affect its place within that competition.
FMI forecasts 6.3% CAGR for the United Kingdom from 2026 to 2036 against this combination of an established petrol-blending outlet, a smaller domestic production base and a changing renewable-fuel mix. Supply growth may come through imports as well as British plants. EIA identifies the United Kingdom among destinations receiving increased onward ethanol shipments from the Netherlands. [8] That trade route gives concrete context to the replacement opportunity after Vivergo. The revenue forecast should consequently be read as a UK market outlook, rather than the same growth rate for domestic distillation capacity.
What supports bioethanol demand in Japan?
Japanese refiners currently obtain most of their fuel ethanol through ETBE, making the conversion route central to supplier access. USDA's December 2025 assessment said the country met its 824 million-litre bioethanol target through ETBE and reported an average ethanol blend of about 1.9%. Imported bio-ETBE made from US corn-based and Brazilian sugarcane-based ethanol was supplemented by domestic conversion of imported ethanol. [10] This is an existing import-linked outlet, distinct from the direct E10 market now being prepared.
The planned sequence gives direct-blending suppliers a later entry point. METI's roadmap describes an initial E10 introduction in some regions around fiscal 2028, [16] while USDA identifies Okinawa test runs from fiscal 2028, a nationwide E10 option by 2030 and an E20 objective for 2040. The assessment expected on-road ethanol consumption to remain at the existing level until fiscal 2028. [10] Qualification, compatible handling and vehicle availability precede the larger planned outlet; the programme does not describe nationwide high-blend sales already under way.
Japan's forecast 5.6% CAGR from 2026 to 2036 spans both the established ETBE business and the period intended for direct-blend expansion. FMI finds that the commercial opportunity changes with the customer's route. Ethanol for local ETBE conversion competes within current refinery arrangements, while direct-blending supply depends on the planned regional introduction and wider rollout. Carbon and product attributes still have to satisfy the applicable Japanese framework. This staged outlook gives suppliers a defined preparation period without counting the entire E10 or E20 ambition as current demand, and it leaves implementation timing material to the additional business.
Who are the notable companies in the Bioethanol Market?
Green Plains, Aemetis, Cargill and ADM occupy different positions in biological ethanol supply. Green Plains operates a US corn-ethanol network, Aemetis supplies ethanol from Keyes in California, Cargill includes fuel ethanol within integrated corn processing, and ADM is expanding grind at Columbus in Nebraska. [4][14][15][13] Their competition concerns plant economics and the outlets for fuel and coproducts.
Green Plains' production and operating-plant disclosures distinguish its installed network from actual annual gallons. [4] Aemetis describes ethanol, wet distillers grains and corn oil at Keyes, with an improvement programme aimed at plant energy use. [14] Both examples link the ethanol offer to feed coproducts, but their geography and plant base differ. California delivery and the conditions attached to a fuel's carbon attributes cannot be inferred from the size of a national network alone.
Cargill's Eddyville plant processes corn into food, feed, industrial and energy products, including fuel-grade ethanol. [15] ADM's October 2026 Columbus announcement instead identifies staged investment at an existing dry mill: completed initial work and a further phase expected in 2027. [13] FMI finds that integration broadens coproduct exposure, while the Columbus programme changes the processing offer within a stated timetable. Its expected additional grind should enter the competitive assessment on that timetable, rather than as completed ethanol production.
Key Developments in the Bioethanol Market
- On 23 October 2026, ADM said first-stage improvements at its Columbus, Nebraska dry mill were complete and were expected to increase corn grind by 10 million bushels in 2026. A second investment phase was expected to add another 10 million bushels in 2027. [13]
Key Players in the Bioethanol Market
- Green Plains
- Aemetis
- Cargill
- ADM
Bioethanol Market Report Scope
Table 6: Bioethanol Market Report Scope, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Fuel-grade ethanol made from biological feedstocks for blending and other covered fuel uses. |
| Market boundaries | Excludes beverage alcohol, industrial solvent ethanol and coal-derived synthetic ethanol. |
| Quantitative units | USD billion for market value; percentages for segment shares and country CAGRs. |
| Forecast period | 2026 to 2036, with 2025 as the preceding reference year. |
| Feedstock coverage | Starch-based, sugar-based, cellulose-based and other biological feedstocks. |
| Generation and blends | First, second and third generations; low blends (E10 and below, including E5, E7 and E10), E15 to E70, E75 to E85 and other fuel blends. Low blends follow positive nominal E-designations through E10; other blends and fuel routes remain outside this cohort. |
| Regional coverage | Seven global regions and their nested country and subregion coverage. |
| Country profiles | China, India, Germany, Brazil, United States, United Kingdom and Japan; these profiles do not delimit the global total. |
| Commercial evidence | Fuel obligations, blend implementation, plant output, company investment and documented supply routes. |
Bioethanol Market Research Methodology
The Bioethanol Market assessment combines market-value and country forecasts with secondary analysis of government fuel rules, company operating disclosures and published energy research. FMI assesses feedstock, fuel generation and nominal fuel blend as separate classifications. The research checks policy periods and implementation status, distinguishes biological ethanol from coal-derived supply, and compares production with nameplate capacity. Company positioning uses documented facilities and activity; the methodology does not include new interviews, plant inspections or a global company-share survey.
Bioethanol Market by Segments
Bioethanol Market segmented by Feedstock:
- Starch-based
- Sugar-based
- Cellulose-based
- Other biological feedstock
Bioethanol Market segmented by Fuel Generation:
- First generation
- Second generation
- Third generation
Bioethanol Market segmented by Fuel Blend:
- Low blends (E10 and below)
- E15 to E70
- E75 to E85
- Other fuel blends
Bioethanol Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] US Environmental Protection Agency. Final Renewable Fuel Standards for 2026 and 2027. March 2026; page updated 9 July 2026.
- [2] India Ministry of Petroleum and Natural Gas, Press Information Bureau. Government Highlights Safety, Performance and National Benefits of Ethanol-Blended Petrol. 23 July 2026.
- [3] Brazil Ministry of Mines and Energy. Resolução que institui o E32 é publicada e nova mistura passa a valer neste sábado. 31 July 2026; updated 26 October 2026.
- [4] Green Plains Inc. Form 10-K for the year ended 31 December 2025. Filed 10 February 2026.
- [5] International Energy Agency. Renewables 2025, Renewable Transport chapter. October 2025.
- [6] UK Department for Transport. RTFO statutory review and future of the scheme. Accessed 31 October 2026.
- [7] European Parliament and Council. Directive (EU) 2023/2413, revised renewable-energy transport provisions. 18 October 2023.
- [8] US Energy Information Administration. U.S. fuel ethanol exports on track to set record, driving more domestic production. 22 October 2025.
- [9] Associated British Foods. Annual Report 2025, closure of the Vivergo Fuels bioethanol business. 2025.
- [10] USDA Foreign Agricultural Service. Japan: Biofuels Annual, JA2025-0063. 10 December 2025.
- [11] USDA Foreign Agricultural Service. China: Biofuels Annual, CH2025-0151. 27 August 2025.
- [12] German Bundestag, DIP legislative record. Zweites Gesetz zur Weiterentwicklung der Treibhausgasminderungs-Quote, law of 1 June 2026, BGBl. I 2026 No. 163. Accessed 31 October 2026.
- [13] ADM. ADM Investments in Columbus, Nebraska, Ethanol Facility Expected to Increase Annual Corn Grind by 20 Million Bushels. 23 October 2026.
- [14] Aemetis. US Products and Keyes ethanol facility description. Accessed 31 October 2026.
- [15] Cargill. Eddyville, Iowa facility description. Accessed 31 October 2026.
- [16] Japan Ministry of Economy, Trade and Industry. Automotive transition roadmap 2025, biofuel action-plan discussion. 2025.
- [17] US Department of Energy, Alternative Fuels Data Center. Ethanol. Accessed 31 October 2026.
- [18] Federal Republic of Germany. Zweites Gesetz zur Weiterentwicklung der Treibhausgasminderungs-Quote. Law of 1 June 2026, Bundesgesetzblatt I 2026 No. 163, published 5 June 2026, Articles 1, 4 and 6.
- [19] Brazil National Agency of Petroleum, Natural Gas and Biofuels (ANP). ANP divulga dados consolidados do setor regulado em 2025. 30 June 2026; updated 7 July 2026.
- [20] UK Department for Transport. Renewable Transport Fuel Obligation (RTFO) statistics 2024: Final report. Updated 12 February 2026.
- [21] US Department of Energy, Alternative Fuels Data Center. Ethanol Blends. Accessed 1 November 2026.
- [22] India Ministry of Petroleum and Natural Gas, Press Information Bureau. Ethanol Blended Petrol Programme Q&A, provisional 2025-26 feedstock price table. 10 July 2026.
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Feedstock, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Feedstock, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Feedstock, 2026 to 2036
- Starch-based
- Sugar-based
- Cellulose-based
- Other biological feedstock
- Y-o-Y Growth Trend Analysis By Feedstock, 2021 to 2025
- Absolute $ Opportunity Analysis By Feedstock, 2026 to 2036
- Global Market Analysis and Forecast, By Fuel Generation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Generation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Generation, 2026 to 2036
- First generation
- Second generation
- Third generation
- Y-o-Y Growth Trend Analysis By Fuel Generation, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Generation, 2026 to 2036
- Global Market Analysis and Forecast, By Fuel Blend, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Blend, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Blend, 2026 to 2036
- Low blends (E10 and below)
- E15 to E70
- E75 to E85
- Other fuel blends
- Y-o-Y Growth Trend Analysis By Fuel Blend, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Blend, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- By Country
- Market Attractiveness Analysis
- By Country
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Feedstock
- By Fuel Generation
- By Fuel Blend
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Green Plains
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Aemetis
- Cargill
- ADM
- Green Plains
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Feedstock, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Fuel Generation, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Fuel Blend, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Feedstock
- Figure 6: Global Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Fuel Generation
- Figure 9: Global Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Fuel Blend
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Feedstock
- Figure 26: North America Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Fuel Generation
- Figure 29: North America Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Fuel Blend
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Feedstock
- Figure 36: Latin America Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Fuel Generation
- Figure 39: Latin America Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Fuel Blend
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Feedstock
- Figure 46: Western Europe Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Fuel Generation
- Figure 49: Western Europe Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Fuel Blend
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Feedstock
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Fuel Generation
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Fuel Blend
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Feedstock
- Figure 66: East Asia Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Fuel Generation
- Figure 69: East Asia Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Fuel Blend
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Feedstock
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Fuel Generation
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Fuel Blend
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Feedstock, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Feedstock, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Feedstock
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Fuel Generation, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Fuel Generation, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Fuel Generation
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Fuel Blend, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Fuel Blend, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Fuel Blend
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
What is the size and forecast of the Bioethanol Market?
The market is estimated at USD 129.42 billion in 2026, compared with USD 120.50 billion in 2025, and is forecast to reach USD 264.26 billion by 2036 at a 7.4% CAGR.
Which feedstock leads the Bioethanol Market?
Starch-based feedstock holds 38.6% by feedstock in FMI's 2026 assessment.
Which fuel generation and fuel blend lead the Bioethanol Market?
First-generation ethanol holds 61.4% by fuel generation, and low blends (E10 and below) hold 59.0% by fuel blend in FMI's 2026 assessment. In the United States, E10 is the most common blend; E85 requires a compatible flex-fuel vehicle. [17]
Which profiled country has the highest forecast growth?
China has the highest forecast CAGR at 10.0%, followed by India at 9.3%, Germany at 8.5%, Brazil at 7.8%, the United States at 7.0%, the United Kingdom at 6.3% and Japan at 5.6% from 2026 to 2036.
Is Brazil's E32 a permanent requirement?
The measure took effect on 1 August 2026 for 180 days, with a possible further 180-day extension. The ministry described permanent E32 or higher blends as conditional on further testing. [3]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
