
- Market Size (2026)
- USD 633.0 Mn
- Forecast (2036)
- USD 859.0 Mn
- CAGR (2026 to 2036)
- 3.1%
How Big Is the Fluorotelomers Market in 2026?
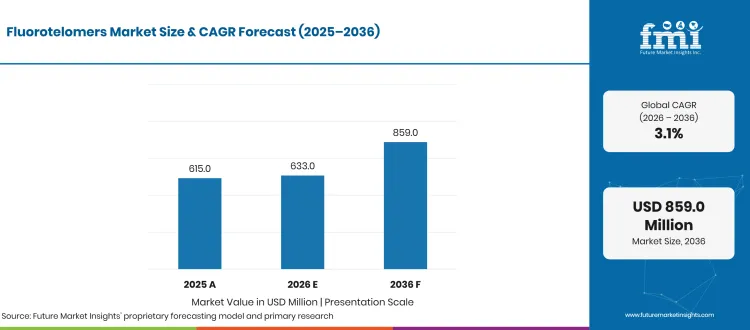
The global fluorotelomers market reaches an estimated valuation of USD 633.0 million in 2026, advancing from USD 615.0 million in 2025, with Future Market Insights (FMI) projecting category revenue to hit USD 859.0 million by 2036, expanding at a 3.1% CAGR from 2026 to 2036 and generating USD 226.0 million in incremental revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 615.0 million |
| 2026 Market Size (Estimated) | USD 633.0 million |
| 2036 Market Size (Projected) | USD 859.0 million |
| Compound Annual Growth Rate (2026 to 2036) | 3.1% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 226.0 million |
| Dominant Chemical Intermediate (2026 Share) | Fluorotelomer Alcohols (40.5% in 2026, rising to 42.2% by 2036) |
| Leading Application & Fastest-Growing Segment | Stain & Soil Resistant Textile Finishes (35.9% share in 2026) | Industrial Chemical Surfactants (3.9% CAGR) |
| Leading & Fastest-Growing End-Use Sectors | Textiles & Technical Apparel (39.7% share in 2026) | Semiconductor & Electronics Manufacturing (4.4% CAGR) |
| Leading Chain Length & Sales Channel (2026) | Short-Chain C6 Fluorotelomers (68.5% share) | Direct to Chemical Processors (64.0% share) |
| Largest Country Markets (2026 Global Share) | China (27.0%), United States (22.5%), Japan (13.5%), Germany (8.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | China (3.8% CAGR), United States (3.6% CAGR), Australia (3.4% CAGR) |
| Leading Tier-1 Companies | Daikin Industries, The Chemours Company, AGC Inc., Arkema SA, Syensqo SA |
Source: Future Market Insights analysis of the fluorotelomers market, 2026.
Executive Market Overview
Industrial procurement of fluorotelomers rests on essential surface-protection and chemical-synthesis applications across semiconductor photolithography, architectural low-VOC coatings and aerospace fluorosurfactants. Semiconductor trade tracking from the Semiconductor Industry Association (February 2026) confirms that global chip sales reached USD 602.4 billion in 2025, expanding commercial demand for ultra-pure short-chain C6 and C4 fluorotelomer ethoxylates and iodides required to wet sub-2-nanometer wafers. North America and East Asia represent over 62% of global consumption in 2026, driven by high-density cleanroom manufacturing hubs, while regional chemical clusters in Europe and Japan invest in closed-loop telomerization to eliminate long-chain PFOA precursors and secure high-margin intermediate supply through 2036, which stabilizes electronic-grade raw material pipelines for the formulators who buy them.
Abandonment of consumer food-contact grease-proofers has removed low-margin paper volume, pushing chemical synthesizers to lift realized price per metric ton through vacuum-distilled short-chain C6 and ultrashort-chain C4 building blocks. After the U.S. Food and Drug Administration (January 2025) declared 35 food-contact notifications for fluorinated paper grease-proofers no longer effective, producers redirected reactor capacity toward high-margin semiconductor wet-etch surfactants, medical nonwovens and non-fluorosurfactant fluoropolymers synthesis, exemplified by Syensqo SA (October 2026) transitioning nearly 100% of its specialty fluoropolymers to non-fluorosurfactant polymerization. FMI projects ultrashort-chain C4 intermediates to grow at a 4.1% CAGR and fluorotelomer acrylates at a 3.5% CAGR through 2036, outpacing the 3.1% market average. Sizing covers synthesized fluorotelomer iodides, alcohols, acrylates and methacrylates plus phosphate surfactants, while excluding bulk PTFE and PVDF molding resins, inorganic fluoride salts and hydrofluorocarbon refrigerants.
Analyst Perspective
"Fluorotelomer producers will expand revenue through purity premiums rather than bulk tonnage, as semiconductor fabs and surgical gown mills pay higher unit prices for vacuum-distilled C6 and C4 monomers certified below 25 ppb for legacy PFOA precursors. The primary commercial risk is open-dispersive regulatory attrition in Europe as REACH Annex XVII Entry 79 caps take effect between 2026 and 2029."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights (FMI)
Major Market Trends and Insights
- Closed-Loop Emissions Capture Becomes Mandatory for Industrial Coating Lines: Converters of technical textiles and fluoropolymer films install thermal oxidizers and carbon-bed scrubbers to stop volatile telomer monomers escaping during curing. Field monitoring published in Environmental Science & Technology by the American Chemical Society (November 2025) found 6:2 and 8:2 fluorotelomer alcohols represented over 95% of volatile fluorinated compounds across 30 U.S. municipal landfill gas systems at a median 19,000 nanograms per cubic meter. Bioaccumulation modeling in Environmental Science & Technology by the American Chemical Society (August 2026) showed neutral fluorotelomer alcohols and methacrylates partitioning into storage lipids, so industrial coaters adopt closed-loop vapor recovery.
- Rapid Screening Enforcement Eliminates Residual Food-Wrapper Formulations: Regulators and retail packaging auditors deploy high-speed mass spectrometry to verify the complete removal of polymeric fluorotelomer grease-proofers from fiber food wrappers. Following the U.S. Food and Drug Administration (January 2025) withdrawal of 35 food-contact notifications for fluorinated paperboard coatings, analytical chemists reporting in the Journal of Agricultural and Food Chemistry via the American Chemical Society (March 2026) validated a hydrolysis isotope-dilution DART-MS screening method that detects hydrolyzable 6:2 fluorotelomer alcohol from 4 micrograms per kilogram to 130 milligrams per kilogram within 14 minutes per sample, accelerating supplier shifts toward closed-loop industrial fluoropolymer additives.
- Semiconductor Lithography and Battery Binders Anchor High-Purity Monomer Sales: With consumer textile and paper volumes contracting, fluorochemical producers dedicate distillation columns to electronic-grade C6 and C4 telomer surfactants used in sub-2-nanometer photolithography developers and lithium-ion battery electrode slurries. In August 2026, AGC Inc. (August 2026) presented its semiconductor fluoropolymer films, high-purity process materials and closed-loop fluorochemical recycling systems at SEMICON India 2026 across more than 500 microelectronics exhibitors. Financial disclosures from Arkema SA (November 2026) confirm this industrial pivot, recording 1.7% year-on-year volume expansion in Specialty Materials during third-quarter 2026 as battery, water management and electronics orders offset softer construction demand.
What Are the Main Drivers, Restraints, and Opportunities?
Wafer fabrication buildouts and occupational liquid-barrier standards sustain orders for purified C6 telomer monomers, while tightening toxic-release reporting and European PFHxA limits constrain open-dispersive uses, making fluorous-resin wastewater capture and non-fluorosurfactant synthesis the primary routes to wider supplier margins.
Driver: Semiconductor Fab Expansions and Occupational Barrier Standards
High-speed wafer spin-coating and hospital surgical gown finishing require surface tension reduction below 18 millinewtons per meter that hydrocarbon and silicone modifiers cannot match against low-tension solvents and oils. Leachate and risk testing published in Regulatory Toxicology and Pharmacology via the National Library of Medicine (July 2025) analyzed 173 water-repellent winter glove components across eight brands, finding zero detectable PFAS migration in artificial sebum leachate and cumulative hazard indices well below 0.001. The Chemours Company (November 2026) reported third-quarter 2026 net income of USD 196 million, supported by Advanced Performance Materials sales into semiconductor and high-precision industrial barrier applications, which strengthens buyer confidence in multi-year supply agreements.
Restraint: Tightening Toxic Release Reporting and EU PFHxA Concentration Caps
Mandatory emissions reporting and strict parts-per-billion concentration limits on six-carbon degradation acids raise compliance costs for downstream formulators and restrict open consumer applications. On 29 September 2026, the U.S. Environmental Protection Agency (September 2026) automatically added perfluorohexanesulfonic acid and related fluorinated compounds to the Toxics Release Inventory under the Toxic Substances Control Act, building on nine PFAS additions enforced for reporting year 2025. In parallel, guidance from the European Chemicals Agency (April 2026) details REACH Annex XVII Entry 79 under Regulation (EU) 2024/2462, which enforces a 25 ppb limit on undecafluorohexanoic acid and its salts and a 1,000 ppb cap on PFHxA-related substances across consumer textiles, food packaging and municipal firefighting foam mixtures starting in 2026.
Opportunity: Fluorous Ion-Exchange Capture Resins and Surfactant-Free Polymerization
Chemical suppliers that bundle purified short-chain telomer intermediates with on-site wastewater capture resins and non-fluorosurfactant emulsion aids capture recurring industrial contracts in regulated Western and Asian plants. Experimental work published in ACS ES&T Water by the American Chemical Society (November 2025) demonstrated that modifying commercial weak-base anion-exchange resins named Lewatit VP OC 1065 with four-carbon fluorous chains retained over 98% of ultrashort-chain trifluoroacetic acid over 72 hours, with under 2% capacity loss against 15% loss for unmodified resin. Commercial execution is advancing, with Syensqo SA (October 2026) eliminating fluorosurfactant processing aids across nearly 100% of its specialty fluoropolymers while Evonik Industries AG (February 2026) streamlined North American distribution for low-emission PFAS-free slip and leveling coating additives.
How Is the Fluorotelomers Market Segmented?
The global fluorotelomers market is segmented by chemical intermediate, application, end-use sector, chain length chemistry, sales channel and region, standardized on active metric tonnage of synthesized monomer equivalents.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Main Growth Benchmark (2026 to 2036) |
|---|---|---|---|
| Chemical Intermediate | Fluorotelomer Alcohols (FTOH), Fluorotelomer Acrylates (FTA/FTMA), Fluorotelomer Iodides (FTI), Fluorotelomer Sulfonates | Fluorotelomer Alcohols (40.5% revenue share) | FTOH share rises to 42.2% by 2036; Fluorotelomer Acrylates grow at 3.5% CAGR |
| Application | Stain & Soil Resistant Textile Finishes, Industrial Chemical Surfactants, Aqueous Film Forming Foams, Food Contact Paper Coatings | Stain & Soil Resistant Textile Finishes (35.9% revenue share) | Industrial Chemical Surfactants lead application growth at 3.9% CAGR |
| End-Use Sector | Textiles & Technical Apparel, Semiconductor & Electronics Manufacturing, Fire Protection Services, Industrial Paints & Inks, Paper Packaging | Textiles & Technical Apparel (39.7% revenue share) | Semiconductor & Electronics Manufacturing leads end-use growth at 4.4% CAGR |
| Chain Length Chemistry | Short-Chain C6 Fluorotelomers, Ultrashort-Chain C4 Intermediates, Hybrid Fluorinated Copolymers, Legacy Long-Chain C8 Exemptions | Short-Chain C6 Fluorotelomers (68.5% revenue share) | Ultrashort-Chain C4 Intermediates expand fastest at 4.1% CAGR |
| Sales Channel | Direct to Chemical Processors, Specialty Chemical Distributors, Toll Synthesis & Custom Blending, Digital B2B Procurement | Direct to Chemical Processors (64.0% sales share) | Toll Synthesis & Custom Blending expands at 3.4% CAGR through 2036 |
Source: Future Market Insights analysis of the fluorotelomers market, 2026.
Why Does the Fluorotelomer Alcohols Segment Lead by Chemical Intermediate?
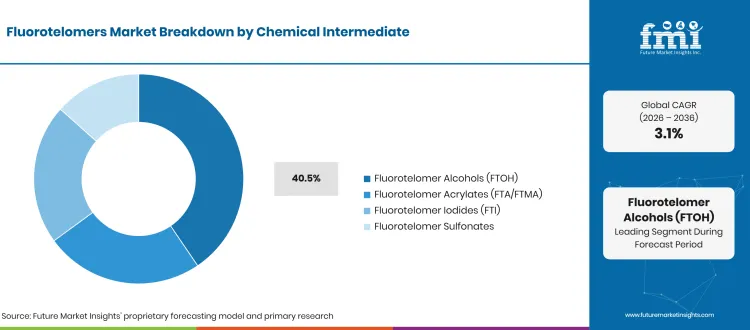
Fluorotelomer Alcohols lead the global fluorotelomers market by chemical intermediate, accounting for 40.5% of category revenue in 2026 and projected to reach 42.2% by 2036. Chemical compounders purchase terminal hydroxyl-functional 6:2 fluorotelomer alcohol as the primary reactive intermediate for esterification into fluoroacrylate monomers, fluorinated polyurethanes and non-ionic ethoxylate surfactants, so the buying decision is set by what the intermediate becomes downstream. Vacuum fractional distillation allows upstream synthesizers to strip trace eight-carbon homologues before polymerization, whereas fluorotelomer acrylates expand at a 3.5% CAGR as textile coaters adopt pre-polymerized aqueous dispersions. Comparative pad-dry-cure testing published in Polymers by MDPI (June 2025) showed that sol-gel octylsilane-modified silicone coatings reached static water contact angles of 130 degrees on cotton and 145 degrees on polyester across five ISO 105-C10 washes, yet fluorinated alcohol derivatives remain the industrial benchmark for fluorochemicals synthesis.
Why Do Stain and Soil Resistant Textile Finishes Lead by Application?
Stain & Soil Resistant Textile Finishes capture 35.9% of 2026 market revenue by application, while industrial chemical surfactants record the fastest application growth at a 3.9% CAGR through 2036. Hospital surgical drapes, petrochemical flame-resistant coveralls and cleanroom garments require durable finishes that repel blood, hydraulic fluids and organic solvents without blocking fabric breathability. Outdoor consumer apparel brands are reformulating light rainwear with PFAS-free textile repellent chemicals, yet institutional medical and defense workwear specifications retain short-chain C6 telomer acrylate baths because wax and silicone emulsions fail oil-drop penetration standards. Supplier investment in regional surface-modifier capacity reinforces this dual-track strategy, with Clariant AG (November 2025) completing its Care Chemicals and specialty surface-active additives expansion at Daya Bay in November 2025 to serve Asian industrial coating and technical textile formulators.
Why Does the Textiles and Technical Apparel Segment Lead by End-Use Sector?
Textiles & Technical Apparel account for 39.7% of global fluorotelomers revenue in 2026, whereas semiconductor and electronics manufacturing leads end-use expansion at a 4.4% CAGR from 2026 to 2036. Industrial finishing mills treating medical barrier nonwovens, chemical protective garments and woven filtration media form the largest volume buyer pool for aqueous C6 telomer dispersions, competing with functional textile finishing agents in multi-step tenter-frame baths. Exposure and migration research published in Regulatory Toxicology and Pharmacology via the National Library of Medicine (July 2025) evaluated 38 targeted fluorinated analytes across 173 water-repellent glove components from eight brands, detecting fluorotelomer residues in only 6 of 173 components with zero migration into artificial sebum over 24 hours. Wafer fabs drive high-margin growth by specifying parts-per-million telomer wetting agents in photolithography developers.
Why Do Short-Chain C6 Fluorotelomers Lead by Chain Length Chemistry?
Short-Chain C6 Fluorotelomers command 68.5% of 2026 revenue by chain length chemistry, while ultrashort-chain C4 intermediates grow fastest at a 4.1% CAGR through 2036. Global enforcement of Stockholm Convention persistent organic pollutant bans on eight-carbon perfluorooctanoic acid and its 8:2 precursors pushed primary manufacturers to re-engineer telomerization reactors around six-carbon perfluorohexyl chains that cannot degrade into that acid. Formulators must then reformulate rather than wait. As mills evaluate PFAS replacement chemistries for textiles, biomonitoring scrutiny on six-carbon ethoxylates is rising. Human serum analysis published in Toxics by MDPI (August 2025) detected nine 6:2 fluorotelomer ethoxylate homologues at frequencies of 22% to 81%, with a mean of 0.69 ng/mL for 6:2 FTEO8 and 0.71 ng/mL for 6:2 FTEO9, which accelerates research into ultrashort C4 building blocks.
Why Does Direct to Chemical Processors Lead by Sales Channel?
Direct sales to chemical processors account for 64.0% of global revenue in 2026, while toll synthesis and custom blending expands at a 3.4% CAGR through 2036. Because fluorotelomer iodides and alcohols require inhibitor stabilization, heated stainless-steel isotank transport and gas-chromatography certificates proving legacy C8 isomers remain below 25 parts per billion, a test most formulators audit on every incoming drum. Upstream fluorochemical producers contract directly with polymerization plants and industrial coaters. Quarterly disclosures from The Chemours Company (November 2026) highlight how direct technical qualification with semiconductor and industrial OEMs anchors recurring Advanced Performance Materials shipments, while Evonik Industries AG (February 2026) consolidated its U.S. and Canadian specialty coating additives distribution effective 1 May 2026 across Dorset & Jackson, Palmer Holland and Chem-Materials to serve regional paint and ink blenders.
Fluorotelomers Market by Region and Country (2026 to 2036)
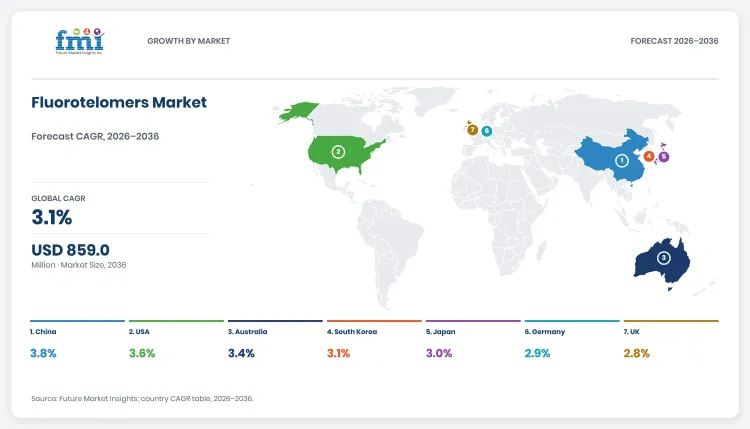
East Asia and North America retain the majority of global fluorotelomers revenue through 2036, with the eight tracked countries below increasing their combined share from 88.0% in 2026 at USD 557.0 million to 90.5% by 2036 at USD 777.7 million. China remains the largest national market and records the fastest expansion at a 3.8% CAGR, lifting its global revenue share from 27.0% to 28.9% and adding USD 77.3 million, over one-third of total global dollar growth. The United States adds USD 60.4 million at a 3.6% CAGR on semiconductor fab and aerospace barrier demand, whereas Western European countries grow between 2.7% and 2.9% as REACH Annex XVII PFHxA limits restrict consumer finishes.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 -> 2036) |
|---|---|---|---|---|---|
| China | USD 170.9 million | USD 248.2 million | +USD 77.3 million | 3.8% | 27.0% -> 28.9% |
| United States | USD 142.4 million | USD 202.8 million | +USD 60.4 million | 3.6% | 22.5% -> 23.6% |
| Japan | USD 85.5 million | USD 114.9 million | +USD 29.4 million | 3.0% | 13.5% -> 13.4% |
| Germany | USD 50.6 million | USD 67.3 million | +USD 16.7 million | 2.9% | 8.0% -> 7.8% |
| South Korea | USD 44.3 million | USD 60.1 million | +USD 15.8 million | 3.1% | 7.0% -> 7.0% |
| Italy | USD 25.3 million | USD 33.0 million | +USD 7.7 million | 2.7% | 4.0% -> 3.8% |
| United Kingdom | USD 22.2 million | USD 29.3 million | +USD 7.1 million | 2.8% | 3.5% -> 3.4% |
| Australia | USD 15.8 million | USD 22.1 million | +USD 6.3 million | 3.4% | 2.5% -> 2.6% |
Source: Future Market Insights analysis of the fluorotelomers market, 2026.
China
Chinese procurement anchors the fluorotelomers market, expanding 1.45-fold at a 3.8% CAGR from USD 170.9 million in 2026 to USD 248.2 million by 2036, adding USD 77.3 million and lifting global revenue share from 27.0% to 28.9%. Chemical complexes in Zhejiang and Jiangsu integrate upstream anhydrous hydrofluoric acid directly into 6:2 fluorotelomer alcohol and acrylate synthesis for domestic wafer fabs, lithium-ion battery plants and export textile mills. Commodity tracking by the U.S. Geological Survey (January 2026) shows nationwide safety inspections across Chinese fluorspar mines tightened domestic acid-grade fluorspar supply and increased first-half 2025 fluorspar imports, while Clariant AG (November 2025) expanded specialty surface-active additive production at Daya Bay. Captive fluorspar integration and domestic fab commissioning should keep China as the primary engine of volume expansion through 2036.
United States
American consumption of specialty fluorotelomers expands from USD 142.4 million in 2026 to USD 202.8 million by 2036 at a 3.6% CAGR, generating USD 60.4 million of incremental sales and raising global share from 22.5% to 23.6%. Demand has shifted away from consumer food packaging toward high-purity semiconductor photolithography surfactants, military aviation barrier coatings and hospital surgical nonwovens. Industry data from the American Chemistry Council (June 2026) show U.S. chemical output volumes rising 0.5% in 2026 as AI data-center and semiconductor investments offset softer construction activity, while U.S. Environmental Protection Agency (September 2026) Toxics Release Inventory additions enforce strict plant-level reporting. Wafer fab buildouts and closed-loop resin abatement upgrades should sustain premium C6 monomer procurement through 2036.
Japan
Japanese orders grow from USD 85.5 million in 2026 to USD 114.9 million by 2036 at a 3.0% CAGR, adding USD 29.4 million while global share holds near 13.5% and 13.4%. Domestic fluorochemical leaders focus on precision tetrafluoroethylene telomerization for optical anti-smudge coatings and photoresists, and they export monomers rather than bulk textile finishes. Under updated drinking-water regulations enforced by the Ministry of the Environment, Japan (July 2026), public water suppliers have been legally required since 1 April 2026 to meet a mandatory 50 nanograms per liter combined tap-water standard for PFOS and PFOA, with AGC Inc. (August 2026) expanding closed-loop fluorochemical recycling for microelectronics. Moving domestic reactors toward sub-25 ppb electronic and optical telomer grades should protect Japanese supplier margins through 2036.
Germany
German revenue climbs from USD 50.6 million in 2026 to USD 67.3 million by 2036 at a 2.9% CAGR, adding USD 16.7 million as Germany's global share edges from 8.0% to 7.8%. Chemical parks in Ludwigshafen and Leverkusen concentrate on REACH-exempt medical filtration membranes, automotive fuel-system seals and industrial sensor coatings. Regulatory implementation tracked by the European Chemicals Agency (April 2026) enforces Regulation (EU) 2024/2462 under REACH Annex XVII Entry 79, capping undecafluorohexanoic acid at 25 ppb in consumer apparel and food contact materials from October 2026 while preserving industrial exemptions. Qualification of surfactant-free fluoropolymers and closed-loop C6 industrial coatings across German automotive and medical device OEMs should anchor steady national demand through 2036.
South Korea
South Korean demand expands in line with the global average at a 3.1% CAGR, rising 1.36-fold from USD 44.3 million in 2026 to USD 60.1 million by 2036, adding USD 15.8 million and holding a steady 7.0% global revenue share. Korean demand is weighted toward ultra-low-trace-metal fluorotelomer surfactants consumed in memory wafer lithography, OLED display anti-reflective layers and EV battery cathode binders. On 30 June 2026, the Ministry of Climate, Energy and Environment of Korea (June 2026) finalized a master infrastructure plan supplying 650,000 metric tons per day of industrial process water, including 300,000 tons per day of reclaimed reverse-osmosis water, for the new Southwest Semiconductor Complex. Multi-year fab expansions and display line upgrades should drive sustained repeat orders for electronic-grade C6 and C4 telomer surfactants through 2036.
Italy
Italian sales advance from USD 25.3 million in 2026 to USD 33.0 million by 2036 at a 2.7% CAGR, adding USD 7.7 million while Italy's share of global revenue moderates from 4.0% to 3.8%. Northern Italian chemical formulators in Lombardy and Piedmont specialize in short-chain C6 dispersions for occupational protective textiles, architectural stone sealers and fluoropolymer manufacturing. On 28 October 2026, Syensqo SA (October 2026) ceased production of the fluorosurfactant C6O4 at its Spinetta Marengo facility after transitioning nearly 100% of its specialty fluoropolymers to non-fluorosurfactant technology, while the Italian Institute for Environmental Protection and Research (June 2026) advanced safe-by-design monitoring priorities. Reformulating textile and stone auxiliaries around certified sub-25 ppb C6 dispersions should support stable B2B turnover through 2036.
United Kingdom
British procurement of fluorotelomers grows from USD 22.2 million in 2026 to USD 29.3 million by 2036 at a 2.8% CAGR, generating USD 7.1 million of new revenue and maintaining global share from 3.5% to 3.4%. Buying centers on North Sea offshore energy workwear, defense aviation hydraulic-fluid barrier coatings and sterile medical filtration media. Policy documentation released by the UK Department for Environment, Food & Rural Affairs (August 2026) under the national PFAS Plan: Building a Safer Future Together outlines risk-based UK REACH evaluations through 2028 that restrict dispersive firefighting foams while preserving safety-critical industrial coatings. Continued reliance on risk-based exemptions for aerospace and energy protective fabrics should sustain specialized C6 urethane and acrylate demand through 2036.
Australia
Australian demand expands 1.40-fold at a 3.4% CAGR from USD 15.8 million in 2026 to USD 22.1 million by 2036, adding USD 6.3 million and lifting global share from 2.5% to 2.6%. Because Australia has no domestic tetrafluoroethylene telomerization reactors, local specialty blenders import pre-certified C6 dispersions and amphoteric surfactants for heavy mining baghouse filtration fabrics and industrial vapor-suppression systems. On 21 October 2026, the Australian Industrial Chemicals Introduction Scheme (October 2026) published Draft Evaluation Statement EVA00204 reviewing importation and industrial use volumes across all 522 PFAS entries on the Australian Inventory of Industrial Chemicals from September 2023 to August 2025. Stricter federal inventory verification should channel mining and industrial buyers toward fully documented C6 barrier finishes through 2036.
Competitive Environment and Notable Companies
Notable companies in this market include Daikin Industries, Ltd., The Chemours Company, AGC Inc., Arkema SA, Syensqo SA, Dynax Corporation, Maflon S.p.A., Clariant AG, Evonik Industries AG and BASF SE. Competition operates in two tiers. Upstream vertically integrated fluorochemical producers run anhydrous hydrofluoric acid and tetrafluoroethylene telomerization reactors, and downstream specialty formulators engineer C6 textile repellents, electronic wetting agents and hybrid surface modifiers. Because semiconductor and battery expansion is concentrated across Asia and North America, upstream producers open localized technical hubs to lock in OEM qualification, which shifts negotiating advantage toward whoever holds the qualification file.
How Are Companies Positioned in the Fluorotelomers Market?
Daikin Industries, Ltd., The Chemours Company, AGC Inc. and Arkema SA anchor upstream telomerization capacity, synthesizing purified 6:2 fluorotelomer iodides and alcohols across Japan and Europe. The Chemours Company (November 2026) and Arkema SA (November 2026) both highlighted resilient third-quarter 2026 demand for specialty fluorinated materials in semiconductors and batteries management. In the formulation tier, Syensqo SA, Dynax Corporation and Maflon S.p.A. specialize in high-purity C6 surfactants, fluoropolymers and textile sealers, while Clariant AG (November 2025), Evonik Industries AG (February 2026) and BASF SE supply competing fluorinated and fluorine-free coating additives.
What Matters When a Buyer Selects a Fluorotelomers Supplier?
Industrial polymerizers, semiconductor chemical blenders and technical textile mills evaluate suppliers on batch-specific gas-chromatography certificates proving unintended C8 PFOA precursors remain below 25 parts per billion, aligned with European Chemicals Agency (April 2026) REACH Annex XVII Entry 79 thresholds. Buyers also audit suppliers on closed-loop emissions abatement support and regulatory registration across EU REACH, U.S. TSCA and the Australian Industrial Chemicals Introduction Scheme (October 2026) 522-chemical inventory. Suppliers able to support on-site fluorous resin wastewater capture hold a decisive qualification advantage, since the compliance burden sits with the formulator rather than with the monomer producer.
Which Capabilities Distinguish Product Offers?
Portfolios diverge across telomer chain-length purity, non-fluorosurfactant polymerization and dual-chemistry flexibility. Syensqo SA (October 2026) eliminated fluorosurfactant processing aids such as C6O4 across nearly 100% of its specialty fluoropolymers by October 2026, AGC Inc. (August 2026) pairs AsahiGuard E-Series C6 repellents with semiconductor fluorochemical recycling, Daikin Industries markets UNIDYNE C6 repellents as well as OPTOOL optical anti-smudge coatings. Dynax Corporation with Maflon S.p.A. formulate specialized C6 amphoteric betaines and HEXAFOR dispersions for safety-critical barrier applications.
How Does Geographic Reach Affect Competition?
Upstream telomerization reactors remain concentrated in Japan, the United States and China, while percentage volume growth shifts toward South Asian and East Asian electronics and technical textile hubs. Daikin Industries, Ltd. (March 2026) established Daikin Chemical India Private Limited in Gurugram in March 2026 to accelerate local semiconductor and battery qualification, whereas Evonik Industries AG (February 2026) restructured its U.S. and Canadian coating-additives distribution network into three regional basin partners effective May 2026 to shorten North American formulation lead times. Local stock and local technical service decide the next order for a formulator working to a tight cure schedule.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 25 March 2026: Daikin Industries, Ltd. established Daikin Chemical India Private Limited in Gurugram with INR 600 million capital (Daikin Industries, Ltd., March 2026). | Creates localized fluorochemical technical service and inventory for Indian semiconductor and EV battery factories. | Qualify local Indian fluorochemical supply hubs to reduce import lead times for electronic surfactants. |
| 28 October 2026: Syensqo SA halted C6O4 fluorosurfactant production at Spinetta Marengo, transitioning nearly 100% of fluoropolymers to non-fluorosurfactant synthesis (Syensqo SA, October 2026). | Eliminates persistent polymerization processing-aid emissions across semiconductor and membrane grades. | Specify non-fluorosurfactant-manufactured fluoropolymers to meet tightening European and U.S. scope audits. |
| 5 November 2026: Arkema SA reported 1.7% YoY Specialty Materials volume growth and EUR 332 million EBITDA in Q3 2026 on battery and fluorochemical demand (Arkema SA, November 2026). | Confirms resilient industrial demand in battery binders, water filtration, and specialty fluorochemicals. | Lock in multi-year supply agreements for electronic and battery-grade fluorinated intermediates. |
| 5 February 2026: Evonik Coating Additives streamlined its U.S. and Canadian distribution network effective 1 May 2026 (Evonik Industries AG, February 2026). | Consolidates North American specialty wetting and leveling additive supply across three dedicated regional distributors. | Align regional North American coating plants with designated basin distributors for faster technical sampling. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Daikin Industries, Ltd. | Integrated producer of UNIDYNE C6 water/oil repellents, OPTOOL anti-smudge coatings, and fluorotelomer monomers | Established Daikin Chemical India Private Limited in Gurugram on 25 March 2026 to supply semiconductor and battery fluorochemicals (Daikin Industries, Ltd., March 2026). |
| The Chemours Company | North American synthesizer of C6 fluorotelomer intermediates, Capstone repellents, and Advanced Performance Materials | Reported USD 196 million in Q3 2026 net income on 3 November 2026, supported by semiconductor and industrial fluorochemical demand (The Chemours Company, November 2026). |
| AGC Inc. | Japanese producer of AsahiGuard E-Series C6 telomer dispersions, Fluon resins, and semiconductor fluorochemicals | Showcased semiconductor fluoropolymer films and closed-loop fluorochemical recycling at SEMICON India 2026 (AGC Inc., August 2026). |
| Arkema SA | Global specialty materials group producing Forane fluorochemicals, Kynar PVDF, and fluorinated acrylic derivatives | Recorded 1.7% YoY Specialty Materials volume growth and EUR 2.4 billion sales in Q3 2026 driven by battery and water sectors (Arkema SA, November 2026). |
| Syensqo SA | Specialty fluoropolymer and fluorinated surfactant innovator serving semiconductor, membrane, and energy markets | Completed transition of nearly 100% of specialty fluoropolymers to non-fluorosurfactant manufacturing on 28 October 2026 (Syensqo SA, October 2026). |
| Dynax Corporation | U.S. formulator of high-purity C6 fluorotelomer betaines, sulfonates, and firefighting foam stabilizers | Supplies sub-25 ppb PFOA-precursor-certified C6 amphoteric and non-ionic fluorosurfactants for industrial and aviation vapor suppression. |
| Maflon S.p.A. | Italian producer of HEXAFOR C6 fluorotelomer dispersions, stone sealers, and fluorine-free specialty surfactants | Markets OEKO-TEX and REACH Annex XVII compliant C6 dispersions for medical barrier nonwovens and protective workwear. |
| Clariant AG | Swiss specialty chemical manufacturer supplying surface-active wetting, dispersing, and stabilizing additives | Completed Care Chemicals and specialty surface-modifier capacity expansion at Daya Bay, China on 5 November 2025 (Clariant AG, November 2025). |
| Evonik Industries AG | German specialty chemicals producer of TEGO wetting and leveling additives for industrial coatings and inks | Streamlined its U.S. and Canadian Coating Additives distribution network in February 2026, effective 1 May 2026 (Evonik Industries AG, February 2026). |
| BASF SE | Global chemical group manufacturing Hydropalat wetting agents, Efka leveling modifiers, and acrylic dispersions | Supplies fluorinated and non-fluorinated surface-tension modifiers from integrated European and Asian Verbund sites. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Fluorotelomers Market Report Scope and Research Methodology
FMI sizes the global fluorotelomers market from synthesized telomer monomer tonnage and realized intermediate selling prices across each country, cross-checked against upstream tetrafluoroethylene telomerization reactor utilization and downstream industrial coating and textile bath consumption. Active intermediate volumes, running from 31.5 thousand to 34.2 thousand metric tons in 2026, are standardized to metric tons of monomer equivalent so iodides and alcohol dispersions sit on a single volume basis. Country revenue is recorded in the jurisdiction where chemical processors and finishing mills consume the intermediate, with national and segment totals summing to the global market in every year. Corporate filings and regulatory dockets are used strictly to verify capacity additions, purity thresholds and product transitions across the forecast period.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Synthesized fluorotelomer intermediates and functional derivatives sold to chemical processors, textile mills, and industrial formulators. |
| Chemical intermediates | Fluorotelomer alcohols (FTOH), fluorotelomer acrylates and methacrylates (FTA/FTMA), fluorotelomer iodides (FTI), and fluorotelomer sulfonates and phosphates. |
| Applications covered | Stain and soil resistant textile finishes, industrial chemical surfactants, aqueous film forming foams (AFFF), and food contact paper barrier coatings. |
| End-use sectors | Textiles and technical apparel, semiconductor and electronics manufacturing, fire protection services, industrial paints and inks, and paper packaging. |
| Chain length chemistries | Short-chain C6 fluorotelomers, ultrashort-chain C4 intermediates, hybrid fluorinated copolymers, and legacy long-chain C8 medical/defense exemptions. |
| Sales channels | Direct to chemical processors, specialty chemical distributors, toll synthesis and custom blending, and digital B2B chemical procurement. |
| Exclusions | Bulk homopolymer PTFE and PVDF molding resins, inorganic fluoride salts, hydrofluorocarbon refrigerant gases, and non-fluorinated silicone repellents. |
| Quantitative units | USD million for value; thousand metric tons for active synthesized monomer volume. |
| Volume basis | Metric tons of active fluorotelomer monomer equivalent, converting aqueous dispersions to active fluorinated solids content. |
| Value basis | Ex-works and contract supplier revenue from sales to industrial processors and formulators in each country. |
| Base & forecast years | 2025 historical base year; 2026 estimated year; 2026 to 2036 10-year forecast period. |
| Regions covered | East Asia, North America, Western Europe, Eastern Europe, South Asia and Pacific, Latin America, and Middle East and Africa. |
| National coverage | China, United States, Japan, Germany, South Korea, Italy, United Kingdom, and Australia. |
| Companies covered | Daikin Industries, Ltd., The Chemours Company, AGC Inc., Arkema SA, Syensqo SA, Dynax Corporation, Maflon S.p.A., Clariant AG, Evonik Industries AG, and BASF SE. |
Source: Future Market Insights analysis of the fluorotelomers market, 2026.
Research Sources and Bibliography
- AGC Inc. (2026, August 25). SEMICON INDIA 2026: AGC Exhibits Semiconductor Materials and Equipment Components.
- American Chemical Society. (2025, November 4). Fluorous Modification of Commercial Resins for Ultrashort and Short Chain PFAS Removal (ACS ES&T Water 5(11), 6633-6643). https://pubs.acs.org/aewcaa/article/5/11/6633/3676306/Fluorous-Modification-of-Commercial-Resins-for
- American Chemical Society. (2025, November 17). Nationwide Estimate of Volatile Per- and Polyfluoroalkyl Substance (PFAS) Emissions from U.S. Landfills via Landfill Gas (Environmental Science & Technology 59(46), 24899).
- American Chemical Society. (2026, March 19). Validating Direct Mass Spectrometry Screening for Grease-Proofers Containing 6:2-Fluorotelomer Alcohol in Fiber-Based Food Packaging (Journal of Agricultural and Food Chemistry 74(12), 10577).
- American Chemical Society. (2026, August 31). Expanding the Scope of PFAS Research to Include Adipose Tissues (Environmental Science & Technology 60(36), 25149). https://pubs.acs.org/esthag/article/60/36/25149/5389118/Expanding-the-Scope-of-PFAS-Research-to-Include
- American Chemistry Council. (2026, June 12). Mid-Year 2026 Outlook: A Pivotal Moment for American Chemistry.
- Arkema SA. (2026, November 5). Third-Quarter 2026 Results: Solid Performance Driven by Specialty Materials. https://www.arkema.com/global/en/media/newslist/news/global/investorrelations/2026/20261105-third-quarter-2026-results/
- Australian Industrial Chemicals Introduction Scheme. (2026, October 21). PFAS Introduction and Use in Australia: Draft Evaluation Statement Open for Comments Until 2 December 2026. https://www.industrialchemicals.gov.au/news-and-notices/pfas-introduction-and-use-australia-draft-evaluation-statement-open-comments-until-2-december-2026
- Clariant AG. (2025, November 5). Clariant Celebrates Care Chemicals Expansion at Daya Bay, Strengthening Its Position in China. https://www.clariant.com/en/Corporate/News/2025/11/Clariant-celebrates-Care-Chemicals-expansion-at-Daya-Bay-strengthening-its-position-in-China
- Daikin Industries, Ltd. (2026, March 25). Daikin Establishes Daikin Chemical India Private Limited in Gurugram. https://www.daikin.com/press/2026/20260325
- European Chemicals Agency. (2025, August 27). ECHA Announces Timeline for PFAS Restriction Evaluation (ECHA/NR/25/25). https://echa.europa.eu/-/echa-announces-timeline-for-pfas-restriction-evaluation
- European Chemicals Agency. (2026, April 10). Per- and Polyfluoroalkyl Substances (PFAS) Restriction and REACH Annex XVII PFHxA Provisions. https://echa.europa.eu/hot-topics/perfluoroalkyl-chemicals-pfas
- Evonik Industries AG. (2026, February 5). Evonik Coating Additives Announces Streamlined Distribution Network for the U.S. and Canada. https://www.evonik.com/en/news/press-releases/2026/02/evonik-coating-additives-announces-streamlined-distribution-netw.html
- Italian Institute for Environmental Protection and Research. (2026, June 18). KARC 2026: ECHA Identifies New Research Priorities to Strengthen Chemical Safety. https://www.isprambiente.gov.it/en/news/karc-2026-echa-identifies-new-research-priorities-to-strengthen-chemical-safety
- Ministry of Climate, Energy and Environment of Korea. (2026, June 30). 650,000 Tons a Day: Water Supply Plan Set for New Southwest Semiconductor Complex. https://mcee.go.kr/eng/web/board/read.do?boardId=1874930&boardMasterId=522&menuId=461
- Ministry of the Environment, Japan. (2026, July 7). Comprehensive Tap Water Standards and FAQ on PFOS and PFOA (50 ng/L Mandatory Standard Effective April 1, 2026). https://www.env.go.jp/water/pfas/faq.html
- National Library of Medicine. (2025, July 30). An Evaluation and Risk Assessment of Children's Exposures to Water-Soluble PFAS in Treated Winter Gloves (Regulatory Toxicology and Pharmacology, PMC12745961). https://pmc.ncbi.nlm.nih.gov/articles/PMC12745961/
- Polymers - MDPI. (2025, June 5). Eco-Friendly Octylsilane-Modified Amino-Functional Silicone and Silica Hybrid Sol-Gel Coatings for Durable Water-Repellent Fabrics (Polymers 17(11), 1578). https://www.mdpi.com/2073-4360/17/11/1578
- Syensqo SA. (2026, October 28). Syensqo Delivers on Its PFAS Commitment: Production Stop of Fluorosurfactant C6O4 and Non-Fluorosurfactant Transition. https://www.syensqo.com/en/press-release/syensqo-delivers-on-its-pfas-commitment
- The Chemours Company. (2026, November 3). The Chemours Company Reports Third Quarter 2026 Results and Advanced Performance Materials Performance. https://www.chemours.com/en/news-media-center/all-news/press-releases/2026/the-chemours-company-reports-third-quarter-results
- Toxics - MDPI. (2025, August 6). Association of 6:2 Fluorotelomer Ethoxylate Exposure with Serum Lipids in the General Population (Toxics 13(8), 664). https://www.mdpi.com/2305-6304/13/8/664
- UK Department for Environment, Food & Rural Affairs. (2026, August 17). PFAS Plan: Building a Safer Future Together. https://www.gov.uk/government/publications/pfas-plan/pfas-plan-building-a-safer-future-together
- U.S. Environmental Protection Agency. (2026, September 29). EPA Adds Additional Per- and Polyfluoroalkyl Substances to the Toxics Release Inventory Under TSCA. https://www.epa.gov/chemicals-under-tsca/epa-adds-additional-pfas-toxics-release-inventory
- U.S. Food and Drug Administration. (2025, January 6). Food Contact Notifications for PFAS Grease-Proofing Agents on Paper and Paperboard Packaging No Longer Effective (90 FR 653). https://www.fda.gov/food/environmental-contaminants-food/and-polyfluoroalkyl-substances-pfas
- U.S. Geological Survey. (2026, January 30). Mineral Commodity Summaries 2026: Fluorspar Supply, Demand, and Chinese Trade Flows. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-fluorspar.pdf
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemical Intermediate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Chemical Intermediate, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Chemical Intermediate, 2026 to 2036
- Fluorotelomer Alcohols (FTOH)
- Fluorotelomer Acrylates (FTA/FTMA)
- Fluorotelomer Iodides (FTI)
- Fluorotelomer Sulfonates
- Y-o-Y Growth Trend Analysis By Chemical Intermediate, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemical Intermediate, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Stain & Soil Resistant Textile Finishes
- Industrial Chemical Surfactants
- Aqueous Film Forming Foams
- Food Contact Paper Coatings
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Textiles & Technical Apparel
- Semiconductor & Electronics Manufacturing
- Fire Protection Services
- Industrial Paints & Inks
- Paper Packaging
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Chain Length Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Chain Length Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Chain Length Chemistry, 2026 to 2036
- Short-Chain C6 Fluorotelomers
- Ultrashort-Chain C4 Intermediates
- Hybrid Fluorinated Copolymers
- Legacy Long-Chain C8 Exemptions
- Y-o-Y Growth Trend Analysis By Chain Length Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Chain Length Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to Chemical Processors
- Specialty Chemical Distributors
- Toll Synthesis & Custom Blending
- Digital B2B Procurement
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemical Intermediate
- By Application
- By End-Use Sector
- By Chain Length Chemistry
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Daikin Industries, Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Chemours Company
- AGC Inc.
- Arkema SA
- Syensqo SA
- Dynax Corporation
- Maflon S.p.A.
- Clariant AG
- Evonik Industries AG
- BASF SE
- Daikin Industries, Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Chemical Intermediate, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Chain Length Chemistry, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Chemical Intermediate, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Chain Length Chemistry, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Chemical Intermediate, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Chain Length Chemistry, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 19: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: East Asia Market Value (USD Million) Forecast by Chemical Intermediate, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Chain Length Chemistry, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Chemical Intermediate, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 29: South Asia and Pacific Market Value (USD Million) Forecast by Chain Length Chemistry, 2021 to 2036
- Table 30: South Asia and Pacific Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chemical Intermediate, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chemical Intermediate, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chemical Intermediate
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value Share and BPS Analysis by Chain Length Chemistry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Chain Length Chemistry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Chain Length Chemistry
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Chemical Intermediate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Chemical Intermediate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Chemical Intermediate
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End-Use Sector
- Figure 35: North America Market Value Share and BPS Analysis by Chain Length Chemistry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Chain Length Chemistry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Chain Length Chemistry
- Figure 38: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sales Channel
- Figure 41: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: Western Europe Market Value Share and BPS Analysis by Chemical Intermediate, 2026 and 2036
- Figure 43: Western Europe Market Y-o-Y Growth Comparison by Chemical Intermediate, 2026-2036
- Figure 44: Western Europe Market Attractiveness Analysis by Chemical Intermediate
- Figure 45: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 46: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 47: Western Europe Market Attractiveness Analysis by Application
- Figure 48: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 49: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 50: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 51: Western Europe Market Value Share and BPS Analysis by Chain Length Chemistry, 2026 and 2036
- Figure 52: Western Europe Market Y-o-Y Growth Comparison by Chain Length Chemistry, 2026-2036
- Figure 53: Western Europe Market Attractiveness Analysis by Chain Length Chemistry
- Figure 54: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 55: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 56: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 57: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 58: East Asia Market Value Share and BPS Analysis by Chemical Intermediate, 2026 and 2036
- Figure 59: East Asia Market Y-o-Y Growth Comparison by Chemical Intermediate, 2026-2036
- Figure 60: East Asia Market Attractiveness Analysis by Chemical Intermediate
- Figure 61: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 62: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 63: East Asia Market Attractiveness Analysis by Application
- Figure 64: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 65: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 66: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 67: East Asia Market Value Share and BPS Analysis by Chain Length Chemistry, 2026 and 2036
- Figure 68: East Asia Market Y-o-Y Growth Comparison by Chain Length Chemistry, 2026-2036
- Figure 69: East Asia Market Attractiveness Analysis by Chain Length Chemistry
- Figure 70: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 71: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 72: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: South Asia and Pacific Market Value Share and BPS Analysis by Chemical Intermediate, 2026 and 2036
- Figure 75: South Asia and Pacific Market Y-o-Y Growth Comparison by Chemical Intermediate, 2026-2036
- Figure 76: South Asia and Pacific Market Attractiveness Analysis by Chemical Intermediate
- Figure 77: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 78: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 79: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 80: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 81: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 82: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 83: South Asia and Pacific Market Value Share and BPS Analysis by Chain Length Chemistry, 2026 and 2036
- Figure 84: South Asia and Pacific Market Y-o-Y Growth Comparison by Chain Length Chemistry, 2026-2036
- Figure 85: South Asia and Pacific Market Attractiveness Analysis by Chain Length Chemistry
- Figure 86: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 87: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 88: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 89: Global Market - Tier Structure Analysis
- Figure 90: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the fluorotelomers market in 2026?
Future Market Insights estimates the global fluorotelomers market at USD 633.0 million in 2026, advancing from a historical valuation of USD 615.0 million in 2025 across industrial chemical and textile applications.
How fast is the fluorotelomers market expected to grow through 2036?
FMI projects the global fluorotelomers market to expand at a 3.1% CAGR from 2026 to 2036, reaching USD 859.0 million by 2036 and generating USD 226.0 million in incremental 10-year revenue.
Which chemical intermediate segment leads the fluorotelomers market?
Fluorotelomer alcohols (FTOH) lead by chemical intermediate with 40.5% of global revenue in 2026, and FTOH share is projected to rise to 42.2% by 2036 as processors esterify purified 6:2 alcohols into acrylates and surfactants.
Which application and end-use sector lead the fluorotelomers market?
Stain and soil resistant textile finishes lead by application at 35.9% of 2026 revenue, while textiles and technical apparel lead by end-use sector at 39.7%, followed by fast-growing semiconductor manufacturing at a 4.4% CAGR.
Which chain length chemistry dominates fluorotelomers demand?
Short-chain C6 fluorotelomers capture 68.5% of 2026 revenue because six-carbon perfluorohexyl intermediates comply with global Stockholm Convention bans on eight-carbon PFOA precursors, while ultrashort-chain C4 intermediates expand fastest at a 4.1% CAGR.
Which country is the largest and fastest-growing fluorotelomers market?
China is both the largest and fastest-growing country market, holding 27.0% of global revenue in 2026 (USD 170.9 million) and expanding at a 3.8% CAGR to reach USD 248.2 million by 2036, followed by the United States at a 3.6% CAGR.
What regulatory rules restrain open-dispersive fluorotelomers demand?
EU REACH Annex XVII Entry 79 caps undecafluorohexanoic acid (PFHxA) at 25 ppb in consumer textiles and food packaging from 2026, while U.S. EPA TSCA Toxics Release Inventory rules mandate facility-level PFAS reporting.
Who are the notable companies in the fluorotelomers market?
Notable companies operating in the fluorotelomers market include Daikin Industries, Ltd., The Chemours Company, AGC Inc., Arkema SA, Syensqo SA, Dynax Corporation, Maflon S.p.A., Clariant AG, Evonik Industries AG, and BASF SE.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
