
- Market Size (2026)
- USD 8.9 Bn
- Forecast (2036)
- USD 18.5 Bn
- CAGR (2026 to 2036)
- 7.6%
How big is the FPGA Market in 2026?
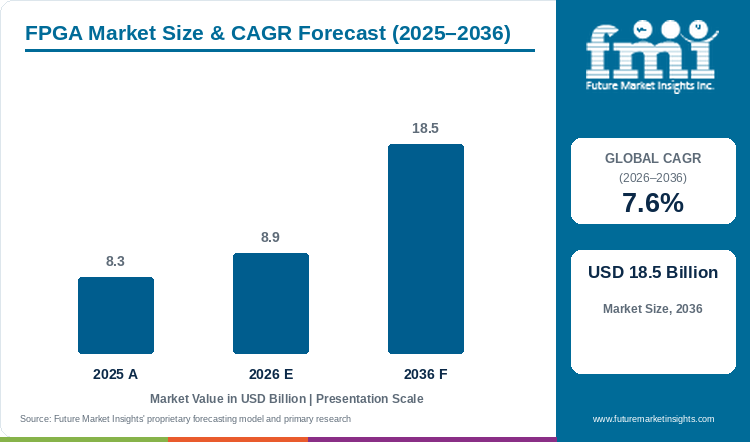
The global FPGA Market is estimated at USD 8.9 billion in 2026, compared with USD 8.3 billion in 2025, and is forecast to reach USD 18.5 billion by 2036, expanding at a CAGR of 7.6% from 2026 to 2036. The SRAM FPGA segment leads product type with 56.0%, the advanced node segment leads the node breakdown with 41.0%, and the mid-range FPGA segment leads configuration with 45.0% in 2026.
Demand for field-programmable gate arrays (FPGAs) is increasingly influenced by how quickly equipment manufacturers can complete designs and move them into commercial production. Altera's September 2025 announcement confirmed production availability across its Agilex FPGA families, alongside an expansion of Agilex 5 D-Series devices to 1.6 million logic elements. The company also increased supported DDR5 and LPDDR5 interface speeds by approximately 25%, addressing bandwidth requirements in AI processing and advanced communications equipment. These improvements give manufacturers greater flexibility when selecting components for new designs. However, commercial orders also depend on the time required to validate interfaces and complete board-level development before production begins.
Manufacturers are investing in development software to shorten this process. In September 2025, Altera introduced Visual Designer Studio through Quartus Prime version 25.3, reporting that initial FPGA design setup could be reduced from five days to two hours. The release also delivered a 6% improvement in compilation times compared with the previous software version. In October 2026, Altera announced QuartusIQ, an AI-assisted development tool designed to support design verification and timing closure. The company estimates that the software could accelerate overall development cycles by up to 1.5 times. These investments strengthen Altera's ability to compete for OEM programmes where engineering time and production readiness influence component selection.
Key Market Trends & Insights
- Lattice's fiscal 2025 channel disclosure assigns 84% of revenue to distribution. That company-specific result shows why stock, application support and resale reporting matter to smaller programmable-logic accounts. It is not a global FPGA channel share. [5]
- Microchip's FPGA longevity policy makes continued supply conditional on the availability of sub-materials. Long equipment programmes therefore need a component roadmap and material-continuity discussions alongside their initial qualification. [6]
- AMD's June 2026 Versal design guide permits adaptable-subsystem verification on a standard platform before integration into a custom platform. This allows a design team to settle part of the logic risk before committing its own board. [7]
Regional Highlights
- In East Asia, SIA's 2025 regional sales comparison records growth in China and in Asia Pacific outside China and Japan, while Japan declined. Different regional chip cycles favour a local design pipeline over a single Asia-wide FPGA sales assumption. These are semiconductor-wide data. [8]
- Across the Americas and Europe, SIA reports 2025 semiconductor sales growth of 30.5% and 6.3%, respectively. The wider cycle gives suppliers different inventory conditions; it does not establish the size of either region's programmable-logic market. [8]
Table 1: FPGA Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 8.3 billion |
| Estimated market size in 2026 | USD 8.9 billion |
| Projected market size by 2036 | USD 18.5 billion |
| CAGR from 2026 to 2036 | 7.6% |
| Added revenue from 2026 to 2036 | USD 9.6 billion |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
Analyst Perspective
“An FPGA design win can lead to years of purchases, but the chip must remain available with supported tools and interfaces. Broad semiconductor sales and an individual supplier's embedded revenue are too wide to stand in for that order book.”
- Sudip Saha, Principal Consultant, FMI
How is the FPGA Market segmented?
The report separates the device's product family, fabrication node and performance configuration from its application and route to the customer.
- By Product Type: SRAM FPGA segment, Flash and nonvolatile FPGA, Antifuse FPGA, SoC FPGA.
- By Node: Advanced node segment, Mid nodes, Legacy nodes, Radiation nodes.
- By Configuration: High-end FPGA, Mid-range FPGA segment, Low-power FPGA, Embedded FPGA.
- By Application: Data centres and computing, Communications, Automotive and industrial control, Aerospace and other electronics.
- By Sales Channel: Direct sales, Distributor sales, Online sales, Design partners.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why does the SRAM FPGA segment lead by product type?
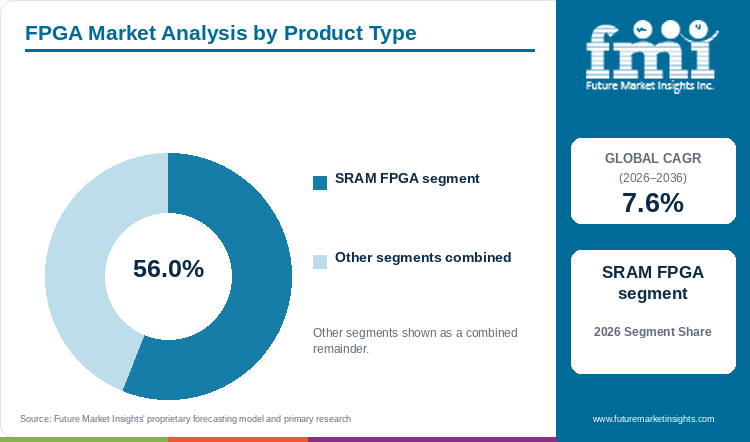
The SRAM FPGA segment holds 56.0% of the FPGA Market by product type in 2026, according to FMI's assessment.
The commercial advantage is the ability to revise a hardware implementation as the customer's processing or interface requirement changes. A design team can preserve its board while modifying the programmable fabric, provided that the revised design still fits its power and timing limits. AMD's Versal Premium Series Gen 2 illustrates the dense adaptive end of this offer, combining programmable logic with hardened host and memory interfaces. [2] Customers buying that combination are paying for a usable system connection as well as reconfigurable gates.
The lead does not remove demand for nonvolatile and antifuse alternatives. Microchip documents nonvolatile FPGA products for applications where configuration integrity, startup and service life carry particular weight. [6] FMI finds that suppliers retain an account by meeting the environment in which the board will operate. An industrial controller and a high-throughput accelerator do not need the same configuration technology, even when both require programmable logic.
Table 2: FPGA Market Share by Product Type, 2026
| Leading Share | 2026 market share |
|---|---|
| SRAM FPGA segment | 56.0% |
| All Other Segments Combined Share | 44.0% |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
Why does the advanced node segment lead by node?
The advanced node segment accounts for 41.0% of the FPGA Market by node in 2026, according to FMI's assessment.
FMI links the lead to designs that have to move data through the device as well as process it. AMD's Premium Gen 2 specifications include hardened PCIe Gen6 and CXL 3.1 support, with feature combinations dependent on the selected device and package. [2] When a board requires that interface class, the qualification effort covers transceiver operation, memory bandwidth and software support. A lower-density alternative cannot win solely through a cheaper logic element if the required connection is missing.
Advanced fabrication does not make every older device commercially obsolete. A released control board may have enough processing capacity and place greater value on continuity than on a new interface. Microchip's documented longevity policy addresses that purchasing requirement. [6] FMI therefore expects advanced node segment sales to follow new designs with demanding data paths, while mid, legacy and radiation-oriented categories continue to serve different qualification and lifecycle needs. Suppliers need to support both the new family and the installed customer programme.
Table 3: FPGA Market Share by Node, 2026
| Leading Share | 2026 market share |
|---|---|
| Advanced node segment | 41.0% |
| All Other Segments Combined Share | 59.0% |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
What supports the mid-range FPGA segment as the leading configuration?
The mid-range FPGA segment holds 45.0% of the FPGA Market by configuration in 2026, according to FMI's assessment.
The order is won when the device can fit the customer's working design at an acceptable board cost. Embedded equipment often needs several hardware interfaces and predictable processing without requiring the largest available fabric. Microchip's PolarFire Core derivatives show how suppliers address that gap: removing integrated transceivers cuts the price for designs that do not need those interfaces. The company's stated comparison applies to the corresponding product family. [3] It does not describe a market-wide price reduction.
Altera also places power- and cost-optimised Agilex SoC devices alongside its broader portfolio and supplies integrated processor subsystems. [4] FMI finds that competition for the mid-range FPGA segment depends on whether a team can reuse software, IP and board work when it selects a smaller device. Savings disappear if the move forces a costly redesign or fails timing. A supplier with practical migration support can turn a prototype into repeat purchases without asking the customer to buy peak performance that the programme will never use.
Table 4: FPGA Market Share by Configuration, 2026
| Leading Share | 2026 market share |
|---|---|
| Mid-range FPGA segment | 45.0% |
| All Other Segments Combined Share | 55.0% |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
What are the key drivers restraints and opportunities?
FMI expects growth to follow the conversion of programmable designs into production boards. Interface requirements support new orders, while fixed-silicon substitution and qualification effort limit how much of that work remains in FPGAs.
Driver
Changing data paths support demand where hardware must be revised during a programme. Altera's June 2026 Agilex 9 Direct RF announcement offers an example in advanced RF systems, where integrated processing and converters are intended to address bandwidth and real-time operation. It announced engineering samples, with production silicon and kits scheduled later in 2026. [9] FMI sees an opening for programmable hardware where waiting for a new fixed chip would delay the system.
Restraint
The recurring price of programmable silicon can push a stable, high-volume design toward an ASIC. The UK Parliament's published semiconductor evidence describes the flexibility of FPGAs alongside their cost, size and power trade-offs against ASICs. [10] FMI finds that suppliers have to justify the recurring cost through field changes, programme volumes or avoided development work. A prototype win alone does not guarantee lifetime production revenue.
Opportunity
Suppliers can win additional embedded programmes by matching features to the actual board requirement. Devices with a smaller fabric or fewer interfaces can make a previously uneconomic design practical. Microchip's cost-focused Core derivatives support this opening, while Altera's integrated SoC devices offer a way to combine processor and logic work within one family. [3][4] The commercial task is to reduce the customer's complete development and component cost.
How do trade and quality rules affect FPGA purchasing?
Export classification and end-use checks can affect access to the device, software and technical data. AMD publishes a trade-compliance process and product HTS/ECCN information, including a route for Xilinx classifications. [11] The relevant classification must be checked for the particular item and transaction. FMI finds that an OEM should settle that access before freezing a design: approval of a hardware part does not automatically settle every software or technology transfer needed to develop it.
What limits reliable FPGA operation and delivery?
Timing closure and platform verification limit how readily a design can move between devices. AMD's Versal guide separates the verification of the adaptable subsystem from its integration with a custom platform. [7] FMI finds that this staged process matters commercially because a board spin consumes engineering time before volume orders arrive. A replacement part with similar logic capacity can still require changes to interfaces, IP, compilation and test. Supply continuity must therefore include supported tools and a verified implementation.
Where can FPGA suppliers win additional business?
FMI sees additional business in RF equipment that needs processing close to the signal and in board-control functions that require secure updates. Altera's Agilex 9 engineering-sample announcement addresses the first requirement. [9] Lattice's September 2026 Mach-N2 family announcement addresses secure control in infrastructure. [12] These are different design opportunities. A supplier should show which functions move into programmable logic and how the customer will qualify them, rather than treating all spending on AI infrastructure as an FPGA order.
FPGA Market by Country (2026 to 2036)
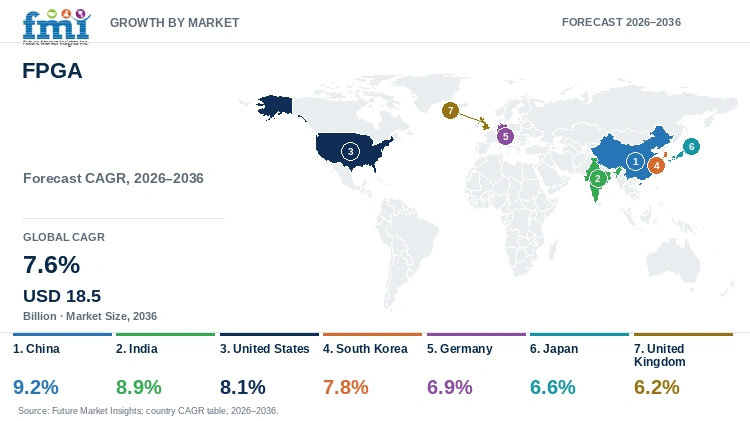
Table 5: FPGA Market Country CAGR Comparison, 2026 to 2036
| Country | CAGR |
|---|---|
| China | 9.2% |
| India | 8.9% |
| United States | 8.1% |
| South Korea | 7.8% |
| Germany | 6.9% |
| Japan | 6.6% |
| United Kingdom | 6.2% |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
What supports FPGA demand in China?
Keeping China's installed communications network current creates work for revised radio, transport and control designs. The Ministry of Industry and Information Technology records 4.838 million 5G base stations at the end of 2025, including 588,000 added during the year. Its preliminary statistics exclude Hong Kong, Macao and Taiwan. [13] That equipment base supports FMI's forecast of a 9.2% CAGR from 2026 to 2036, although the station count cannot establish the number of FPGA sockets or their value.
An equipment maker still has to decide which functions should remain changeable after the board is built. A programmable timing or interface block can retain value through successive equipment versions, whereas a stable function produced at higher volume may move to a dedicated chip. The resulting device orders depend on choices within individual programmes. Growth in the installed network therefore does not translate directly into the same increase in FPGA demand, and a supplier needs to follow the designs being released rather than apply one ratio to the network total.
Access to the selected device and its tools can also determine whether a design reaches production. Supplier and customer must establish the applicable classifications before committing engineering work; AMD's product-specific compliance information illustrates that requirement. [11] The 9.2% outlook assumes that qualified, accessible parts continue to win production roles. Local implementation support, documented interfaces and lawful repeat supply can help retain those roles. Headline performance alone offers less assurance that a customer can finish its board and keep ordering the device.
What supports FPGA demand in India?
Design support gives FPGA suppliers an earlier opening in India than the announcement of a manufacturing site does. The government's June 2026 account records 12 approved semiconductor manufacturing projects worth around INR 1.64 lakh crore, alongside fiscal support for 24 design companies and EDA-tool support for 105 applicants as of March 2026. [14] Access to design tools is the closer signal for development hardware: an approved packaging facility does not establish a production order for programmable logic. Converting that design activity into working boards underpins the 8.9% CAGR forecast for 2026 to 2036.
The immediate purchasing problem is practical. A team building its first board needs a working reference design and engineers who can implement and verify logic on the chosen device. Development kits and application assistance can bring a supplier into the account before device buying reaches volume. The relationship becomes more durable if the same family can take the design from simulation and early hardware into the customer's released equipment, preserving work already done on interfaces and implementation.
Tool access and fiscal support cannot ensure that this conversion happens. A supported applicant may use no programmable device in its final product, while a completed prototype may remain in testing as its power, interfaces and production cost are settled. India's 8.9% outlook rests on repeat commercial manufacture of usable boards, without assigning a share of government investment to FPGA sales. Suppliers need to track the release dates of individual programmes and maintain parts and tool support through that interval.
What supports FPGA demand in the United States?
Production status matters when a US equipment maker freezes a board around programmable interfaces and control. AMD's May 2026 update says two previously announced Versal Prime Series Gen 2 devices had entered production, while another was sampling; it also announced three additional devices. [15] Released silicon provides a firmer basis for a production schedule than a future portfolio promise. The distinction directs purchasing towards the particular part that the customer can qualify and use, rather than the breadth of a supplier's announced range.
Specialised US systems can sustain substantial engineering work within relatively modest unit programmes. A qualified board may stay in service while its logic changes, giving a supplier repeat orders if it preserves the tool environment and offers a practical migration route for the next board. That programme relationship supports FMI's 8.1% CAGR forecast for the United States from 2026 to 2036. Its purchasing cycle differs from the rapid replacement of a general-purpose processor: retaining a verified implementation can matter more than adopting the latest device at every revision.
National consumption also needs to be separated from the global sales of a US supplier. AMD's 2025 filing reports Embedded revenue across products and markets, extending beyond stand-alone FPGAs. [1] It cannot serve as a US FPGA total. The 8.1% outlook depends on domestic system design becoming shipments for US users and equipment programmes. A supplier's headquarters may ease engineering engagement, but the customer's production location and actual device use determine which demand is being served.
What supports FPGA demand in South Korea?
Radio experiments give South Korean equipment developers a reason to keep their test systems programmable. In August 2026, Samsung and KDDI tested an outdoor 7 GHz radio link at Samsung's research campus in Seoul; the European Commission's account reports up to 3.6 Gbps. [16] This demonstrates continuing radio-development work, without disclosing an FPGA bill of materials or a commercial 6G network deployment. Before a standard or product settles, changing signal paths create a different purchasing requirement from that of an established production radio.
Instruments and prototypes must reproduce new waveforms and timing conditions while engineers verify the equipment. The Korean NI distributor's published 5G offering identifies onboard FPGAs in software-defined radios and programmable FPGAs in vector signal transceivers. [17] That documented use provides the local mechanism behind the 7.8% CAGR forecast for 2026 to 2036. It is a more direct connection to programmable-logic demand than treating every new memory factory as a proportional source of FPGA orders based on wafer output.
Suppliers and design partners must consequently support the latency, interfaces and development environment of the particular instrument or radio platform. A successful demonstration may produce another test platform before it leads to a volume radio order. The South Korean outlook reflects this progression through engineering and equipment qualification. Reusable reference designs can reduce work on each revision, helping suppliers participate as programmes advance. Reliance on the country's overall semiconductor production figures would miss the selective nature and timing of these purchases.
What supports FPGA demand in Germany?
A German automotive or industrial developer needs a test bench that can follow changes to its controller and electronic interfaces. dSPACE identifies FPGA-based I/O within its SCALEXIO simulation hardware. [18] Programmable logic therefore serves equipment used to test control systems as well as any device fitted to the eventual vehicle or machine. In that purchasing decision, repeatable simulation and timing can carry more weight than the newest fabrication node. The useful capability is a verified way to reproduce the customer's changing system.
An adaptable test bench can remain useful across several engineering programmes as models and signal arrangements are revised. Suppliers compete on integration with the development environment and a stable hardware implementation. A lower chip price has limited value if adopting it requires engineers to repeat validation or replace functioning equipment. Maintaining documentation and implementation support can preserve the customer's existing work and help the equipment maker serve later revisions without rebuilding the whole testing arrangement.
Continuity also sets a limit on device replacement. An equipment maker may retain a qualified family even as its software changes; a new node does not automatically gain an order with each revision. Germany's 6.9% CAGR forecast from 2026 to 2036 follows incremental programme adoption and equipment replacement within those conditions. The opening may be the next test-bench generation, a new interface board or another system ordered by the customer. Suppliers offering migration assistance and predictable availability can pursue that work while protecting the value of the OEM's existing engineering investment.
What supports FPGA demand in Japan?
Access to real verification hardware can determine whether a Japanese engineering team moves its programmable design beyond evaluation. Avnet Japan's Adaptive Computing Research Initiative describes an industry-academic platform established in April 2020 to provide FPGA verification environments and learning opportunities. [19] It documents local design support, rather than Japanese FPGA sales, and does not establish that every research project becomes a product. Its commercial relevance lies in helping engineers test an implementation before committing to a board.
Training and platform access can lower the initial barrier to using programmable logic, but a demonstration still has to meet the customer's interfaces, thermal limits and manufacturing plan. Carrying that work into dependable equipment is the basis of Japan's 6.6% CAGR forecast from 2026 to 2036. The supplier must keep the implementation practical through final production qualification. Good evaluation results cannot replace this last stage, and a family that is easy to demonstrate may still lose an order if the released board cannot satisfy its operating requirements.
The resulting device relationship can endure without a sudden increase in annual unit volume. After compilation and verification, a move to another family can reopen work on IP, pinout and timing. A competing supplier has a clearer opening on a new platform while those choices remain undecided. Japan's outlook reflects the slower conversion of engineering activity into repeat shipments. Application support, reference designs and a clear lifecycle commitment can influence that conversion more than a stand-alone claim about maximum logic density, helping a customer preserve the work needed to bring its programme into production.
What supports FPGA demand in the United Kingdom?
Specialist UK hardware developers need a place to validate systems before a prototype can become a repeatable product. The government's 2026 AI Hardware Plan proposes a refocused Semiconductor Catapult to help UK companies integrate and validate systems, together with a manufacturing and foundry partner network. [20] These remain planned support measures. They do not establish a commissioned FPGA factory or a disclosed purchase order, but they address a practical stage in the development of equipment using programmable interfaces or processing.
For a small developer, an FPGA can provide hardware on which to test a design before paying for fixed silicon. This can bring a device supplier into the programme early. The eventual production choice still depends on unit cost, power and volume, so the supplier must help turn a working demonstration into equipment that can be built repeatedly. Support aimed at integration and validation is commercially relevant at that point; an initial prototype alone does not settle the component that the final product will retain.
Only some programmes will reach scale while keeping the programmable part. Others may adopt an ASIC, or sell modest quantities of specialist equipment over an extended period. These successive programmes underlie the United Kingdom's 6.2% CAGR forecast from 2026 to 2036. Suppliers need to understand each route before treating a design win as a large annual order. Local engineering assistance and preservation of a qualified implementation can retain accounts as customers move from research into commercial delivery, even when the opportunity consists of durable small programmes rather than rapid volume expansion.
Who are the notable companies in the FPGA Market?
AMD, Altera, Lattice Semiconductor and Microchip Technology cover different parts of the programmable-logic purchasing decision. AMD's adaptive SoCs combine programmable logic with processing and high-speed interfaces, while Altera supplies Agilex FPGA and SoC families with its Quartus environment. [2][4] Customers choosing between these offers have to compare the implementation of their own design, including available IP, memory connections and the work needed to close timing.
Lattice addresses compact and secure-control functions through families such as Mach-N2. [12] Microchip's PolarFire range includes cost-focused Core derivatives and nonvolatile devices supported by a published longevity policy. [3][6] FMI finds that these positions allow a smaller device to win a control function even when the main system uses a different vendor's processor or accelerator.
The supply chain also includes distributors, IP providers and engineering partners. Lattice's channel disclosure shows how extensively one supplier uses distribution, while Altera maintains an authorised distributor network across regions. [5][21] These partners can provide stock and implementation support, but a customer still qualifies the actual device and design flow. FMI does not turn mixed group revenue into company market shares: AMD's Embedded segment includes other products, and the supplier portfolios have different boundaries. [1] Competition is best assessed at the board and programme being won.
Key Developments in the FPGA Market
- On 27 May 2026, AMD expanded its Versal Prime Series Gen 2 portfolio with three additional devices and reported production status for two previously announced devices, with another sampling. [15]
- On 8 June 2026, Altera announced engineering-sample availability of its Agilex 9 Direct RF-Series AGRW039 device; its announcement scheduled production silicon and development kits for the third quarter of 2026. [9]
- On 16 September 2026, Lattice announced the Mach-N2 FPGA family for secure system control in infrastructure. [12]
Key Players in the FPGA Market
- AMD
- Altera
- Lattice Semiconductor
- Microchip Technology
FPGA Market Report Scope
Table 6: Report Scope for the FPGA Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Field-programmable logic devices, adaptive SoCs and associated design elements used in electronic systems. |
| Product boundary | Fixed-function ASICs and standalone general-purpose processors are excluded from FPGA device comparisons. |
| Quantitative units | USD billion for market value; percentage for segment shares and country CAGR. |
| Forecast period | 2026 to 2036, with 2025 as the preceding reference year. |
| Segment coverage | Product type, node, configuration, application and sales channel. |
| Geographic coverage | Seven regions, with the full country and subregion taxonomy below. |
| Country profiles | China, India, United States, South Korea, Germany, Japan and United Kingdom. |
| Competitive coverage | AMD, Altera, Lattice Semiconductor and Microchip Technology; product, channel and support roles. |
| Evidence boundaries | Company disclosures establish particular products and activities; semiconductor-wide sales are contextual indicators. |
Source: Future Market Insights, FPGA Market Report, 2026 to 2036.
FPGA Market Research Methodology
This assessment retains the market values and country forecasts in the report's 2026 to 2036 outlook. The editorial research reviewed company filings, device specifications, government publications and documented local applications. Product status was checked against the wording of each announcement. The review compared the three segment classifications independently and used semiconductor-wide data only as context. It did not conduct new interviews or derive company FPGA shares from mixed revenue segments.
FPGA Market by Segments
FPGA Market segmented by Product Type:
- SRAM FPGA segment
- Flash and nonvolatile FPGA
- Antifuse FPGA
- SoC FPGA
FPGA Market segmented by Node:
- Advanced node segment
- Mid nodes
- Legacy nodes
- Radiation nodes
FPGA Market segmented by Configuration:
- High-end FPGA
- Mid-range FPGA segment
- Low-power FPGA
- Embedded FPGA
FPGA Market segmented by Application:
- Data centres and computing
- Communications
- Automotive and industrial control
- Aerospace and other electronics
FPGA Market segmented by Sales Channel:
- Direct sales
- Distributor sales
- Online sales
- Design partners
FPGA Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] AMD. Annual Report on Form 10-K for the year ended 27 December 2025. Filed 2026.
- [2] AMD. Versal Premium Series Gen 2 product specifications. Accessed 31 October 2026.
- [3] Microchip Technology. Cost-Optimized PolarFire Core FPGAs and SoCs Deliver High Performance with a 30% Lower Price Tag. 20 May 2025.
- [4] Altera. Altera Expands Agilex FPGA Portfolio and Streamlines Developer Experience. 2025; accessed 31 October 2026.
- [5] Lattice Semiconductor. Form 10-K for fiscal 2025, revenue by channel. 13 February 2026.
- [6] Microchip Technology. FPGAs With Exceptional Reliability: Product Longevity, Heritage and Service History. Accessed 31 October 2026.
- [7] AMD. Versal Adaptive SoC Design Guide UG1273, Testing the Adaptable Subsystem Using a Standard AMD Platform, version 2026.1. 24 June 2026.
- [8] Semiconductor Industry Association. Global Annual Semiconductor Sales Increase 25.6% to USD 791.7 Billion in 2025. 6 February 2026.
- [9] Altera. Altera Introduces Next-Generation Agilex 9 Direct RF-Series SoC FPGA. 8 June 2026.
- [10] UK Parliament. Supplementary Written Evidence from Compound Semiconductor Applications Catapult, SEM0072. Accessed 31 October 2026.
- [11] AMD. Regulatory Trade Compliance and Product Classifications. Accessed 31 October 2026.
- [12] Lattice Semiconductor. Lattice Expands Secure Control FPGA Leadership with New Lattice Mach-N2 Family. 16 September 2026.
- [13] Ministry of Industry and Information Technology, China. 2025 Communications Industry Statistical Bulletin. 28 January 2026.
- [14] Government of India, Press Information Bureau. India Emerges as Global Technology Powerhouse via Mission-Mode Initiatives. 22 June 2026.
- [15] AMD. Announcing New AMD Versal Prime Series Gen 2 Devices. 27 May 2026.
- [16] European Commission, 5G Observatory. Japan / South Korea: KDDI and Samsung Reach 3.6 Gigabits per Second in the 7 Gigahertz Band for 6G. 2 September 2026.
- [17] Nubicom, NI authorised Korean distributor. NI 5G Solutions. Accessed 31 October 2026.
- [18] dSPACE. SCALEXIO simulator hardware. Accessed 31 October 2026.
- [19] Avnet Japan. Adaptive Computing Research Initiative. Accessed 31 October 2026.
- [20] UK Government. UK AI Hardware Plan. 2026; accessed 31 October 2026.
- [21] Altera. Contact Us: Authorised Distributors. Accessed 31 October 2026.
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- SRAM FPGA segment
- Flash and nonvolatile FPGA
- Antifuse FPGA
- SoC FPGA
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Node, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Node, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Node, 2026 to 2036
- Advanced node segment
- Mid nodes
- Legacy nodes
- Radiation nodes
- Y-o-Y Growth Trend Analysis By Node, 2021 to 2025
- Absolute $ Opportunity Analysis By Node, 2026 to 2036
- Global Market Analysis and Forecast, By Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Configuration, 2026 to 2036
- High-end FPGA
- Mid-range FPGA segment
- Low-power FPGA
- Embedded FPGA
- Y-o-Y Growth Trend Analysis By Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Data centres and computing
- Communications
- Automotive and industrial control
- Aerospace and other electronics
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct sales
- Distributor sales
- Online sales
- Design partners
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Node
- By Configuration
- By Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- AMD
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Altera
- Lattice Semiconductor
- Microchip Technology
- AMD
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Node, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Configuration, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Node
- Figure 9: Global Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Configuration
- Figure 12: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Application
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Node
- Figure 35: North America Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Configuration
- Figure 38: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Application
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Node
- Figure 51: Latin America Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Configuration
- Figure 54: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Application
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Node
- Figure 67: Western Europe Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Configuration
- Figure 70: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Application
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Node
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Configuration
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Application
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Node
- Figure 99: East Asia Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Configuration
- Figure 102: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Application
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Node
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Configuration
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Node, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Node, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Node
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Configuration, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Configuration, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Configuration
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
What is the FPGA Market forecast?
The market is estimated at USD 8.9 billion in 2026, compared with USD 8.3 billion in 2025, and is forecast to reach USD 18.5 billion by 2036 at a 7.6% CAGR, according to FMI.
Which product type leads the FPGA Market?
The SRAM FPGA segment leads the 2026 product-type breakdown with a 56.0% share in FMI's assessment.
Which node and configuration lead the FPGA Market?
The advanced node segment holds 41.0% by node and the mid-range FPGA segment holds 45.0% by configuration in 2026, according to FMI.
Which profiled country grows fastest?
China has the highest forecast CAGR among the seven profiled countries, at 9.2% from 2026 to 2036.
Why does device availability alone not settle an FPGA purchase?
The customer's implementation also needs supported tools, interfaces and verification. AMD's design guide describes subsystem testing before integration with a custom platform. [7]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
