
- Market Size (2026)
- USD 949.1 Mn
- Forecast (2036)
- USD 1657.9 Mn
- CAGR (2026 to 2036)
- 5.7%
How big is Isomaltulose Market in 2026?
USD 949.1 Million in 2026 and USD 1,657.9 Million by 2036 at a 5.7% CAGR.
Sales of isomaltulose are estimated to grow at 5.7% CAGR from USD 949.1 Million in 2026 to USD 1657.9 Million by 2036. The market was valued at USD 897.9 Million in 2025. Commercial demand is concentrated in formulations where manufacturers want digestible carbohydrate energy with slower glucose release while retaining physical bulk and usable sweetness. A 2025 human intervention study reported a lower glucose ascent rate with isomaltulose than sucrose in adults with metabolic syndrome, strengthening the ingredient's relevance to metabolic-health positioning.
The growth mechanism differs by country. Germany combines sugar-reduction targets with an established functional-food industry, Japan has visible Palatinose use in active nutrition, and South Korea is expanding reduced-sugar product positioning while competing sweetener systems gain capacity. These conditions connect isomaltulose with the broader functional carbohydrate market, where manufacturers increasingly evaluate carbohydrates for physiological and formulation functions rather than energy content alone.
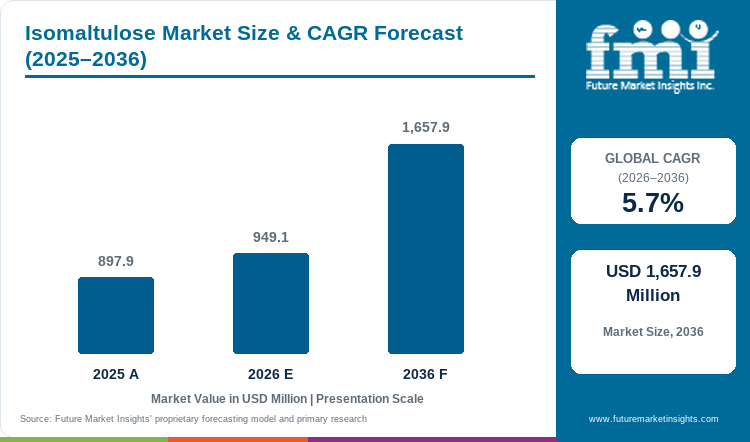
Key Takeaways of Isomaltulose Market
- Demand is strongest when manufacturers need digestible carbohydrate energy with a more gradual glycemic profile than conventional sucrose.
- Food Grade leads Form with a 93.6% share in 2026 because commercial demand is concentrated in food, beverage and nutrition formulations.
- Ingredients leads End-use with an 18.8% share in 2026 as isomaltulose is commonly specified upstream before being incorporated into a finished product.
- Isomaltulose provides carbohydrate energy and approximately half the sweetness of sucrose, supporting sustained-energy positioning rather than zero-calorie claims.
- Adoption can slow when brands must balance sweetness, added-sugar disclosure, claim conditions and the higher cost of a differentiated carbohydrate system.
- BENEO GmbH and Mitsui DM Sugar Co., Ltd. provide established direct commercial isomaltulose platforms.
Analyst Perspective
“Isomaltulose creates the strongest commercial case when carbohydrate energy itself is part of the product benefit. Sports nutrition, metabolic-wellness and sustained-energy formats can justify the ingredient more easily than mainstream products seeking sweetness alone.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Isomaltulose Market segmented?
Isomaltulose Market is segmented by Form, End-use, and Region.
By Form, the market includes Food Grade and Pharma Grade. By End-use, it includes Ingredients, Beverages (including Fruit Juice Beverages and Carbonated Beverages), Polyols, Confectionery, Bakery Products, and Breakfast Cereals and Bars.
Why does food grade lead demand within the form category?
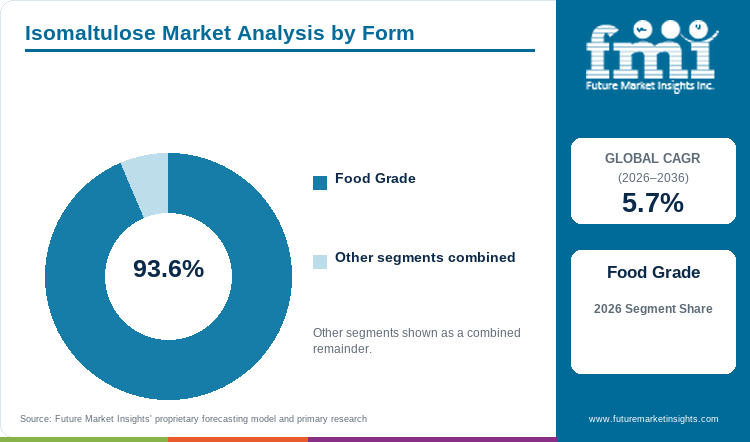
Food Grade dominates because the principal commercial applications for isomaltulose are beverages, confectionery, bakery products, bars and nutritional formulations. Its mild sweetness, carbohydrate energy and stability allow manufacturers to use it as a functional sugar rather than simply a high-intensity sweetening component. This position also places isomaltulose within the wider nutritive sweetener market, where manufacturers need sweetness together with bulk and physical functionality.
- Food Grade accounts for 93.6% of Form demand in 2026, reflecting the breadth of food and beverage applications.
- Food manufacturers value the combination of bulk, mild sweetness and process stability when the formulation requires a digestible carbohydrate source.
Why does ingredients lead demand within the end-use category?
Ingredients leads because isomaltulose is often purchased upstream and then incorporated into several downstream products. A nutrition company can use the same carbohydrate platform across drink powders, bars or beverage formulations rather than purchasing it only for a single finished-product format. BENEO's July 2025 performance-drink concept combined Palatinose with other functional ingredients, illustrating the role of isomaltulose within a broader formulation system.
- Ingredients accounts for 18.8% of End-use demand in 2026 because upstream specification allows the same carbohydrate to serve multiple finished-product applications.
- Ingredient-system demand reflects how formulators incorporate isomaltulose alongside proteins, minerals, colors, or higher-intensity sweeteners to serve multiple product objectives within a single formulation.
What are the drivers, restraints and opportunities in the Isomaltulose Market?
Demand is supported by interest in controlled carbohydrate energy, while formulation economics and sugar labeling constrain adoption. Sports and metabolic-wellness formats create higher-value opportunities.
- Driver: Manufacturers are evaluating carbohydrate systems that provide usable energy with a more gradual glycemic response than conventional sucrose.
- Restraint: Isomaltulose remains a caloric sugar, requiring manufacturers to manage sweetness, added-sugar labeling and ingredient cost.
- Opportunity: Sports nutrition and metabolic-wellness products can convert sustained-energy functionality into a clearer consumer benefit.
Demand comes from manufacturers that want carbohydrate energy but do not want the rapid delivery profile associated with conventional sugar. This clinical finding also informs how brands frame carbohydrate quality in metabolic-wellness formats, where a measurable physiological difference from sucrose can support on-pack positioning and B2B sales arguments to formulators.
The commercial restraint is that isomaltulose does not behave like a zero-calorie high-intensity sweetener. It provides energy and about half the sweetness of sucrose, which can require another sweetening component when the manufacturer wants a familiar sweetness profile. This difference means isomaltulose competes for reformulation budgets that also include products from the wider sugar substitute market. Its strongest proposition is carbohydrate quality rather than simple sugar removal.
Sports and endurance nutrition provide a more direct route to value because carbohydrate energy is part of the product's purpose. A 2025 ultra-endurance study using an isomaltulose-based low-glycemic carbohydrate approach reported lower glycemic variability while maintaining similar endurance capability. This connects directly with the growing sports nutrition market, where drinks, powders, gels and bars are already sold around energy delivery and exercise support.
Which country CAGRs are profiled in the Isomaltulose Market?
The profiled country CAGRs cover 2026 to 2036.
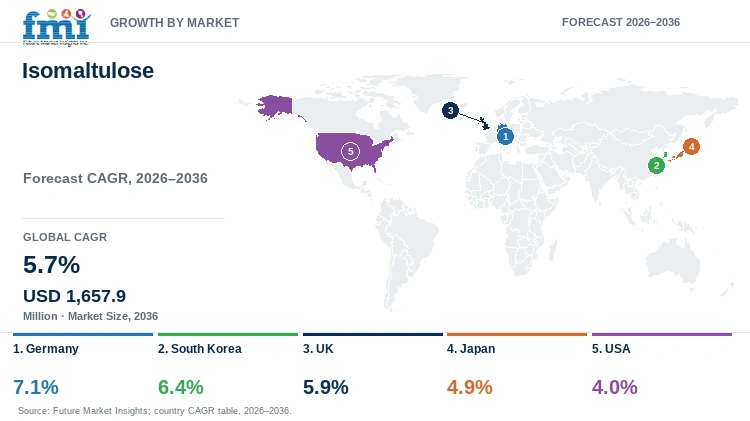
| Country | CAGR |
|---|---|
| Germany | 7.1% |
| South Korea | 6.4% |
| UK | 5.9% |
| Japan | 4.9% |
| USA | 4.0% |
How do country-level CAGRs compare in the Isomaltulose Market?
Germany records the fastest profiled expansion at 7.1%, followed by South Korea at 6.4% and the UK at 5.9%. Japan and the USA show more moderate growth. The difference between Germany and the USA is 3.1 percentage points. These figures describe growth pace rather than absolute country market size.
- Germany combines national sugar-reduction initiatives with an established food-processing sector that gives ingredient suppliers several routes into reformulation.
- South Korea has expanding reduced-sugar labeling and an active functional-ingredient sector, although allulose and other alternatives compete for the same formulation budgets.
- The UK is increasing pressure on beverage manufacturers to lower added sugar, while isomaltulose remains better suited to carbohydrate-quality positioning than direct levy avoidance.
- Japan has an established Palatinose commercial base in sports and functional nutrition, giving the ingredient greater application familiarity.
- The USA has a mature sweetener market where added-sugar disclosure means suppliers must build the commercial case around functionality rather than a sugar-free proposition.
These national conditions create different routes to adoption. Isomaltulose must compete against both conventional sugar and products within the low intensity sweeteners market, making application fit more important than a single global reformulation narrative.
Country-wise Analysis
- Germany has the fastest profiled growth rate at 7.1% CAGR from 2026 to 2036. This environment creates opportunities for carbohydrate reformulation, but isomaltulose must offer a benefit beyond sweetness. Suppliers are better positioned where slower carbohydrate delivery and retained product bulk are valuable enough to justify a differentiated ingredient cost.
- South Korea is profiled at a 6.4% CAGR from 2026 to 2036. In October 2025, the Ministry of Food and Drug Safety expanded categories eligible for sodium- and sugar-reduction labeling. Domestic sweetener manufacturers are also investing in alternatives such as allulose, giving formulators several routes to reformulation. Isomaltulose competes more effectively when manufacturers need sustained carbohydrate energy rather than the lowest possible sugar or calorie content.
- The UK is expected to expand at a 5.9% CAGR from 2026 to 2036. HM Revenue & Customs confirmed in July 2026 that the soft drinks industry Levy threshold will fall from 5 g to 4.5 g of total sugars per 100 ml from January 2028. Isomaltulose remains a caloric sugar, so replacing sucrose directly does not provide a simple route around the levy. Its commercial opportunity is stronger in beverages and nutrition products that can combine lower-glycemic carbohydrate energy with complementary sweeteners.
- Japan records a 4.9% CAGR from 2026 to 2036. Mitsui DM Sugar opened an official sports-focused Palatinose online shop in May 2025 with products from several brands, giving consumers direct exposure to the ingredient across active-nutrition formats. The company also promoted Palatinose at sports events during 2025. This established application base supports powders, gels, bars and drinks where sustained-energy positioning has an immediate consumer use case.
- The USA is profiled at a 4.0% CAGR from 2026 to 2036. The commercial environment is mature and manufacturers already have access to a broad range of sweetening systems. Nutrition Facts rules require added sugars to be disclosed, which limits the value of presenting isomaltulose as a conventional sugar-reduction shortcut. Suppliers therefore need to compete through functional nutrition, controlled carbohydrate delivery and formulations where bulk energy remains desirable.
Who are the notable companies in the Isomaltulose Market?
BENEO GmbH, part of the Südzucker Group, and Mitsui DM Sugar Co., Ltd. are the principal direct isomaltulose platforms profiled in this market.
BENEO markets isomaltulose under the Palatinose brand and supports its use across beverages, sports nutrition and other food applications. The business combines commercial ingredient supply with formulation guidance and nutrition-oriented application evidence.
Mitsui DM Sugar maintains a longstanding Palatinose business in Japan and continues to expand consumer-facing and sports-nutrition applications. Its 2025 activity included an official Palatinose sports shop, event sampling and adoption in commercial energy-bar products.
The competitive market is therefore narrower than the broader sweetener industry. High-intensity sweetener, allulose and polyol suppliers can compete for reformulation spending, but those businesses should not be treated as direct isomaltulose suppliers when they do not offer the ingredient itself.
Competitive Benchmarking: Isomaltulose Market
| Company | Direct Isomaltulose Evidence | Food & Beverage Application Coverage | Complementary Sweetener Breadth | Geographic Reach |
|---|---|---|---|---|
| BENEO GmbH (Südzucker Group) | High | High | Medium | Europe-based production and application platform with international commercial support |
| Mitsui DM Sugar Co., Ltd. | High | High | High | Japan-centered Palatinose platform with established food and sports-nutrition channels |
Scoring basis: Direct Isomaltulose Evidence is High where the company currently markets a dedicated isomaltulose product. Food & Beverage Application Coverage reflects documented use across relevant formulations and technical support. Complementary Sweetener Breadth compares the availability of other sweetening or carbohydrate options that can be combined with isomaltulose. Geographic Reach describes the company's commercial and application footprint.
Key Developments in the Isomaltulose Market
- In May 2025, Mitsui DM Sugar opened an official Palatinose online shop focused on sports applications. The initial assortment brought together multiple brands and Palatinose-containing products, giving the ingredient a consumer-facing platform across endurance and active-nutrition formats.
- In July 2025, BENEO partnered with California Natural Color and GELITA on a performance-drink concept incorporating Palatinose. The formulation combined carbohydrate energy with other functional components, showing how isomaltulose can operate as part of a multi-benefit nutrition system rather than as a stand-alone sweetener.
- In August 2025, Mitsui DM Sugar announced the use of Palatinose in Morinaga's in Bar Energy Sweet Potato. The development extends sustained-energy positioning beyond dedicated endurance products into a convenient bar format for active consumers.
Key Players in the Isomaltulose Market
Direct Isomaltulose Platforms
- BENEO GmbH (Südzucker Group)
- Mitsui DM Sugar Co., Ltd.
Isomaltulose Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form: Food Grade, Pharma Grade; End-use: Ingredients, Beverages, Polyols, Confectionery, Bakery Products, Fruit Juice Beverage, Carbonated Beverages, Breakfast Cereals and Bars |
| Quantitative Units | Revenue in USD Million and CAGR in %. |
| Market Definition | Includes revenue from isomaltulose sold in Food Grade and Pharma Grade forms across the stated End-use categories. Downstream finished-product revenue, substitute sweeteners, other carbohydrate products and standalone formulation services are outside the market scope. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | USA, UK, Germany, Japan, South Korea |
| Key Companies Profiled | BENEO GmbH (Südzucker Group), Mitsui DM Sugar Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Isomaltulose Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from ingredient manufacturers, food and beverage formulators, distributors, nutrition companies, procurement teams and subject-matter experts. Interviews examined purchasing criteria, application performance, approval requirements, pricing and formulation support. |
| Desk Research | Desk research covered government publications, current regulatory information, scientific literature, company product information and corporate developments relevant to isomaltulose. |
| Market Sizing and Forecasting | Market sizing considered the baseline market value, Form and End-use structure, pricing, application adoption, company activity and country demand. Forecast assumptions incorporated sugar-reduction trends, active nutrition demand, regulation and competing sweetener systems. |
| Data Validation | Estimates were compared with company activity, application developments, country reformulation conditions and primary research findings before segment and regional values were aligned with the market total. |
Isomaltulose Market by Segments
Isomaltulose Market segmented by Form:
- Food Grade
- Pharma Grade
Isomaltulose Market segmented by End-use:
- Ingredients
- Beverages
- Polyols
- Confectionery
- Bakery Products
- Fruit Juice Beverage
- Carbonated Beverages
- Breakfast Cereals and Bars
Isomaltulose Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Zhang, J. et al. (2025). Gut Hormones and Postprandial Metabolic Effects of Isomaltulose vs. Saccharose Consumption in People with Metabolic Syndrome.
- European Journal of Sport Science (2025). Glycaemic Impact of Low- and High-Glycaemic Index Carbohydrate Diets in Ultra-Endurance Athletes: Insights From Continuous Glucose Monitoring.
- HM Revenue & Customs (2026, July 13). Soft Drinks Industry Levy Changes.
- Ministry of Food and Drug Safety, Republic of Korea (2025, October 20). Amendment to the Sodium and Sugars Reduction Labeling Standards.
- Consumer Affairs Agency, Japan (n.d.). Foods with Function Claims.
- U.S. Food and Drug Administration (n.d.). Added Sugars on the Nutrition Facts Label.
- BENEO (n.d.). Palatinose: The Better Alternative to Common Sugars.
- BENEO (2025, July 7). BENEO, California Natural Color and GELITA Partner for Performance Drink Concept.
- BENEO (2025, September 11). Study Shows Palatinose Enhances Response of Gut Hormones GLP-1 and PYY.
- BENEO (2026, June 11). Palatinose Shows Lasting Energy Management Benefits in Ultra-Endurance Athletes.
- Mitsui DM Sugar Co., Ltd. (n.d.). Palatinose Functional Material Information.
- Mitsui DM Sugar Co., Ltd. (2025, April 11). Palatinose Sampling at ADIDAS TOKYO CITY RUN 2025.
- Mitsui DM Sugar Co., Ltd. (2025, May 20). Official Palatinose Online Shop for Sports Opens.
- Mitsui DM Sugar Co., Ltd. (2025, August 27). Palatinose Adopted in Morinaga in Bar Energy Sweet Potato.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Isomaltulose Market in 2026 and what value is forecast for 2036?
- Which commercial factors support demand for lower-glycemic carbohydrate ingredients?
- Why does Food Grade lead the Form category?
- Why does Ingredients lead the End-use category?
- How do the profiled country growth rates differ from 2026 to 2036?
- Which companies directly supply commercial isomaltulose platforms?
- What limits switching from conventional sugar or alternative sweetener systems?
- What should buyers evaluate before specifying isomaltulose in a food, beverage or specialty-nutrition formulation?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Food Grade
- Pharma Grade
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End-use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-use, 2026 to 2036
- Ingredients
- Beverages
- Polyols
- Confectionery
- Bakery Products
- Fruit Juice Beverage
- Carbonated Beverages
- Breakfast Cereals and Bars
- Y-o-Y Growth Trend Analysis By End-use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By End-use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End-use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End-use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By End-use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BENEO GmbH (Südzucker Group)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mitsui DM Sugar Co., Ltd.
- BENEO GmbH (Südzucker Group)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 4: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 7: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 10: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 12: Western Europe Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by End-use, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Million) Forecast by End-use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form
- Figure 6: Global Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End-use
- Figure 9: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Form
- Figure 23: North America Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End-use
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Form
- Figure 30: Latin America Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by End-use
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Form
- Figure 37: Western Europe Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by End-use
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Form
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by End-use
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Form
- Figure 51: East Asia Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by End-use
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by End-use
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by End-use, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by End-use, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by End-use
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Isomaltulose Market in 2026, and what is forecast for 2036?
The market is valued at USD 949.1 Million in 2026 and is forecast to reach USD 1657.9 Million by 2036. Growth reflects demand for carbohydrate systems that combine usable energy with differentiated glycemic performance.
What is the CAGR of the Isomaltulose Market from 2026 to 2036?
The market is forecast to expand at a 5.7% CAGR from 2026 to 2036. Growth depends on the ability of suppliers and brands to turn carbohydrate functionality into applications that justify higher formulation costs.
Which Form segment leads the Isomaltulose Market?
Food Grade leads Form with a 93.6% share in 2026. Food, beverage and nutrition products provide the broadest commercial application base for the ingredient.
Which End-use segment leads the Isomaltulose Market?
Ingredients leads End-use with an 18.8% share in 2026. The segment benefits from upstream specification in blends and formulation systems that can subsequently serve several finished-product categories.
Which profiled countries have the highest growth rates?
Germany has the highest profiled CAGR at 7.1%, followed by South Korea at 6.4% and the UK at 5.9%. These rates represent growth pace and not absolute country market size.
Which companies are active in the Isomaltulose Market?
BENEO GmbH, part of the Südzucker Group, and Mitsui DM Sugar Co., Ltd. operate established direct isomaltulose platforms through Palatinose. Both companies support food and nutrition applications alongside commercial ingredient supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
