
- Market Size (2026)
- USD 543.0 Mn
- Forecast (2036)
- USD 1048.3 Mn
- CAGR (2026 to 2036)
- 6.8%
How big is Mannitol Market in 2026?
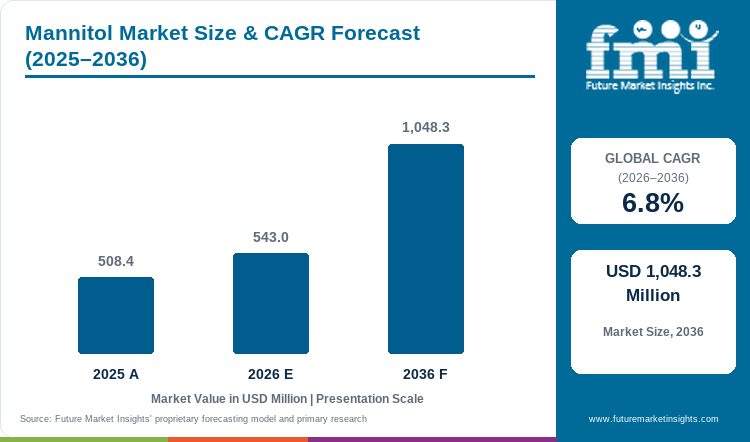
USD 543.0 Million in 2026 and USD 1048.3 Million by 2036 at a 6.8% CAGR.
Sales of mannitol are estimated to grow at 6.8% from USD 543.0 Million in 2026 to USD 1048.3 Million by 2036, up from USD 508.4 Million in 2025. Buyers use mannitol for a combination of sweetness, low moisture uptake, flow control and solid-dose functionality. In July 2026, the U.S. Food and Drug Administration continued to list mannitol as a non-nutritive sweetener, anticaking or free-flow agent and formulation aid, reinforcing its multi-function role across food processing and excipient use.
The growth mechanism differs by country. South Korea maintains a current Food Additives Code and recorded a D-mannitol import clearance in March 2026, while the UK lists E421 as an approved sweetener subject to food-specific conditions. In pharmaceutical use, route and dosage form shape excipient qualification in the United States, and Japan applies designated-additive and use-standard controls. This specification-led buying pattern connects mannitol demand to the wider sugar alcohol market, where formulation performance and regulatory fit matter alongside delivered cost.
Key Takeaways of Mannitol Market
- Mannitol demand is anchored in a dual functional role: food formulators use it for sweetness and moisture-management functions, while pharmaceutical formulators value low hygroscopicity and engineered tableting performance.
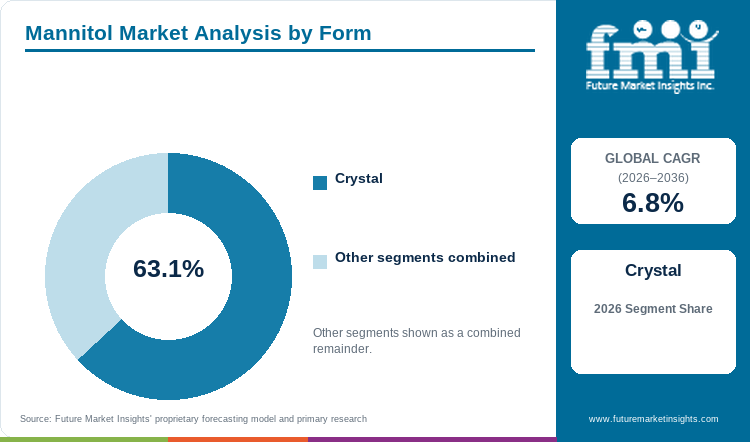
- Crystal leads the Form category with a 63.1% share in 2026 because crystalline grades fit established food handling and excipient workflows across dusting, bulking, blending, and solid-dose formulation.
- Qualification evidence is becoming a stronger differentiator in pharmaceutical mannitol. Recent supplier actions around nitrosamine testing and excipient GMP or GDP certification give buyers more material for risk review without changing the underlying molecule.
- Food leads the End Use category with a 26.2% share in 2026 because mannitol can provide sweetness, anticaking behavior, and moisture control across confectionery and other permitted food applications.
- The principal friction is application-specific compliance. Food-use limits and labeling rules narrow certain recipes, while pharmaceutical switching can require compendial, quality, impurity, and supply-chain documentation.
- Profiled companies are Roquette Frères, SPI Pharma, Cargill, Merck KGaA, B Food Science Co., Ingredion Incorporated, Univar Solutions, Zhejiang Huakang Pharmaceutical Co., Ltd., American International Foods, and Foodchem International.
Analyst Perspective
Mannitol demand converts into realized revenue only when functional performance is matched by application-specific compliance and supply documentation; commodity availability alone is not enough for higher-value pharmaceutical grades.
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the Mannitol Market segmented?
Form: Crystal and Powder. End Use: Food, Beverages, Pharmaceuticals, Carbonated Drinks, Bakery Goods, Confectionery, Powdered Drinks and Mixes, and Solid dosage forms.
By Form, the market includes Crystal and Powder. By End Use, the market includes Food, Beverages, Pharmaceuticals, Bakery Goods, Confectionery, Carbonated Drinks, Powdered Drinks and Mixes, and Solid Dosage Forms. Carbonated Drinks and Powdered Drinks and Mixes are tracked as distinct sub-segments within the broader Beverages category. These categories separate the physical format sold from the application in which buyers consume the ingredient. The structure also captures a market that spans routine food handling and higher-documentation pharmaceutical uses.
Why does Crystal lead demand within the Form category?
Crystal mannitol aligns with the material's established commercial identity as a white crystalline solid that can be supplied in controlled particle sizes. Buyers can use crystalline material directly or select finer and engineered grades for specific processing needs. The format works across food dusting and sweetening uses as well as pharmaceutical filling and tableting workflows, giving suppliers one core physical platform that can be tuned for different handling requirements.
- Crystal holds 63.1% of the Form category in 2026. Its position reflects broad handling familiarity and the ability to serve commodity food functions as well as specification-based excipient requirements.
- In July 2026, the FDA's food-substance inventory continued to identify mannitol for free-flow, anticaking, sweetening, and formulation functions. The range of recognized technical effects illustrates why crystalline material remains useful across multiple dry-processing settings.
Why does Food lead demand within the End Use category?
Food applications absorb mannitol where formulators need mild sweetness together with low hygroscopicity, reduced stickiness and useful bulking behavior. Confectionery is a visible use case, while bakery products and powdered mixes extend the addressable food base. That multifunctionality makes mannitol relevant to the wider food additive market, although each recipe still has to meet the applicable use and labeling conditions.
- Food holds 26.2% of the End Use category in 2026. The segment benefits from mannitol's combined sweetening, bulking, anticaking, and moisture-management functions in permitted formulations.
- The UK government's June 2026 additive list identifies E421 as mannitol and notes that many additives remain subject to food-specific quantitative limits. That combination of established authorization and formulation-specific limits is representative of the purchasing environment for food-grade material.
What are the drivers, restraints and opportunities in the Mannitol Market?
Food and solid-dose formulators value mannitol's low-hygroscopic and processing properties, while application-specific regulatory and qualification requirements constrain substitution, and engineered pharmaceutical grades create an opportunity for higher-value documented supply.
- Driver: Functional demand spans sugar-reduced food formulations and direct-compression pharmaceutical applications.
- Restraint: Use limits, labeling obligations, and pharmaceutical qualification requirements can delay adoption or supplier switching.
- Opportunity: Engineered low-hygroscopic grades with stronger quality documentation can capture formulation work that commodity mannitol does not serve well.
Why does functional versatility keep mannitol in formulation pipelines?
The main demand driver is functional versatility at the point of formulation. FDA records updated in July 2026 recognize mannitol as a non-nutritive sweetener and as an anticaking or free-flow agent. Pharmaceutical suppliers also market particle-engineered grades for direct compression and solid-dose work. That overlap links mannitol to the broader pharmaceutical excipient market, where flow, compactability and moisture behavior can determine whether a formulation scales cleanly from development to routine production.
Why do regulatory and qualification requirements slow substitution?
The restraint appears at qualification rather than at basic chemical availability. Food applications remain bounded by additive permissions and labeling rules, while pharmaceutical buyers qualify by route, dosage form, compendial status, impurity risk and supplier quality systems. Competition from the wider sugar substitute market also raises the performance threshold in reduced-sugar formulations. A lower purchase price does not offset revalidation work when a material change affects process performance or regulatory files.
Where do engineered pharmaceutical grades create higher-value opportunity?
The clearest opportunity is engineered pharmaceutical mannitol backed by auditable documentation. In June 2026, SPI Pharma reported completion of a nitrosamine risk assessment and analytical testing program for Mannogem. In April 2026, Mannitab Pharma Specialities received EXCiPACT GMP and GDP certification covering spray-dried and fine-powder mannitol grades. These actions address the quality and impurity-review burden that formulation teams manage before regular purchasing, giving documented direct-compression grades a stronger route into higher-value solid-dose programs.
Which country CAGRs are profiled in the Mannitol Market?
The profiled country CAGRs below cover 2026 to 2036.
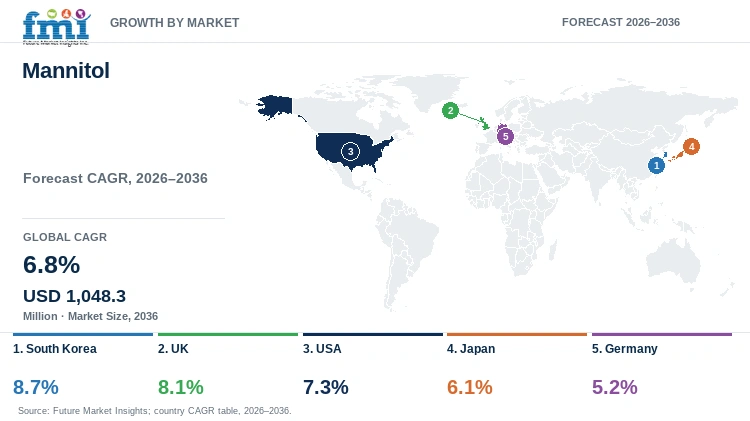
| Country | CAGR |
|---|---|
| South Korea | 8.7% |
| UK | 8.1% |
| USA | 7.3% |
| Japan | 6.1% |
| Germany | 5.2% |
How do country-level CAGRs compare in the Mannitol Market?
The profiled growth rates form three practical bands. South Korea and the UK sit above 8%, the USA is in the mid-7% range, and Japan and Germany expand more moderately. The difference between the highest and lowest profiled rates is 3.5 percentage points. These rates describe forecast pace rather than absolute market size. A faster CAGR can reflect a smaller starting base, channel expansion, or changing qualification conditions rather than a larger revenue pool.
- South Korea: A current additive code and an active import channel support a market where documentation and cross-border supply can translate into faster buying activity.
- UK: E421 remains an authorized sweetener, but food-specific limits keep formulation expertise and regulatory checking important for commercial use.
- USA: Food functionality is well established and pharmaceutical distribution is broadening, supporting demand across both conventional ingredient and excipient channels.
- Japan: A defined designated-additive framework and narrow food-use conditions make application selection more consequential than broad sweetener availability.
- Germany: EU polyol rules and mature pharmaceutical qualification standards favor compliant specialty use, but they also restrain rapid substitution in established formulations.
The country set should be read as a growth comparison rather than a ranking of market size. Coverage spans five profiled countries with different food rules, pharmaceutical practices, and distribution conditions.
Country-wise Analysis
- South Korea has the fastest profiled CAGR at 8.7% from 2026 to 2036. The Ministry of Food and Drug Safety published a consolidated Food Additives Code in July 2026, and an official import record shows a D-MANNITOL food-additive shipment cleared in March 2026. The combination of formal additive controls and an active import channel favors suppliers that can move current specifications, certificates and traceability records cleanly through the local buying process.
- The UK is profiled at an 8.1% CAGR from 2026 to 2036. A government additive list published in June 2026 identifies E421 as mannitol and notes that many additives remain subject to food-specific quantitative limits. Food manufacturers therefore need formulation support that links the grade to the permitted recipe, while pharmaceutical and nutraceutical customers apply a separate documentation test. Growth favors suppliers that can provide both consistent particle form and clear regulatory support.
- The USA is forecast to expand at a 7.3% CAGR from 2026 to 2036. FDA records list mannitol for several food functions and maintain route- and dosage-form based inactive-ingredient information for pharmaceutical use. In February 2026, Univar Solutions announced appointment as a distributor for Ingredion Pharma Solutions in the United States and Canada, covering pharmaceutical starches and specialty excipients including mannitol. Broader excipient access reinforces growth, but higher-value demand still depends on qualification evidence and technical service.
- Japan's profiled CAGR is 6.1% from 2026 to 2036. The market operates within a designated-additive system in which permitted substances and use standards matter at the application level. B Food Science Co. continues to position mannitol across selected food uses and a Japanese Pharmacopoeia grade. This makes application guidance central to selling: suppliers need to match the physical grade and regulatory route to a specific food or pharmaceutical use rather than rely on broad sweetener availability.
- Germany carries a 5.2% CAGR from 2026 to 2036. The country follows the current EU food-additive framework, which lists E421 mannitol as a sweetener with conditions of use, while pharmaceutical customers apply mature excipient qualification practices. Merck KGaA markets Parteck M for direct compression with major pharmacopoeial references. Germany therefore favors specification-led demand in the broader polyol sweetener market and in solid-dose manufacturing rather than rapid commodity substitution.
Who are the notable companies in the Mannitol Market?
Roquette Frères, SPI Pharma, Cargill, Merck KGaA, B Food Science Co., Ingredion Incorporated, Univar Solutions, Zhejiang Huakang Pharmaceutical Co., Ltd., American International Foods, and Foodchem International are the notable companies profiled in this market.
Competition separates into three practical positions. Pharmaceutical excipient specialists compete through compendial coverage, particle engineering and direct-compression performance. Food and polyol manufacturers compete through scale, food-grade availability and formulation familiarity. Distributors compete through local inventory, technical access and the ability to connect buyers with qualified excipient portfolios. Roquette Frères, SPI Pharma, Merck KGaA and Ingredion Incorporated anchor the specialty pharmaceutical side, while Cargill, B Food Science Co. and Zhejiang Huakang Pharmaceutical Co., Ltd. bring broader food and polyol capability. Univar Solutions, American International Foods and Foodchem International extend market access through distribution channels.
- Pharmaceutical excipient specialists: Roquette Frères, SPI Pharma, Merck KGaA, and Ingredion Incorporated compete around direct compression, particle engineering, compendial coverage, and formulation documentation.
- Food and polyol manufacturers: Cargill, B Food Science Co., and Zhejiang Huakang Pharmaceutical Co., Ltd. compete through food-grade availability, polyol manufacturing depth and application coverage.
- Distribution and ingredient channels: Univar Solutions, American International Foods, and Foodchem International compete through regional inventory, import access and broad ingredient portfolios.
Competitive Benchmarking: Mannitol Market
| Company | Pharma-grade & compendial mannitol | Direct-compression / engineered grades | Food-grade / bulk sweetener channel | Geographic Reach |
|---|---|---|---|---|
| Roquette Frères | High | High | Medium | Europe, North America, and Asia-Pacific; China manufacturing is documented for PEARLITOL mannitol. |
| SPI Pharma | High | High | Low | North American base with international pharmaceutical channels documented by company materials. |
| Cargill | Medium | Unscored | High | Global ingredient network with documented EMEA mannitol supply. |
| Merck KGaA | High | High | Low | Global life-science channels with Germany-based corporate footprint and international excipient distribution. |
| B Food Science Co. | Medium | Low | High | Japan-focused food and pharmaceutical-grade mannitol supply. |
| Ingredion Incorporated | High | High | Medium | North America and Asia; India-based specialty mannitol manufacturing is documented. |
| Univar Solutions | Medium | Medium | Low | United States and Canada for the documented Ingredion Pharma Solutions distribution relationship. |
| Zhejiang Huakang Pharmaceutical Co., Ltd. | Medium | Low | High | China-based polyol manufacturing with international food and ingredient channels. |
| American International Foods | Unscored | Low | High | United States through a nationwide food-ingredient warehouse and distribution network. |
| Foodchem International | Unscored | Low | High | China-based international food-ingredient distribution. |
Scoring basis: Pharma-grade & compendial mannitol rates the depth of dedicated pharmaceutical grades and pharmacopoeial or quality documentation. Direct-compression / engineered grades rates specialized particle or tableting capability. Food-grade / bulk sweetener channel rates commercial food-grade reach. High indicates broad capability, Medium indicates a narrower established position, and Unscored indicates that a capability is not rated in this benchmark.
Key Developments in the Mannitol Market
- In June 2026, Roquette Frères announced that China-manufactured PEARLITOL mannitol would be highlighted at CPHI China for oral, injectable, inhalation, and biologic formulation needs. The regional manufacturing point matters commercially because excipient buyers evaluate both technical suitability and continuity of supply. Local production can reduce reliance on long interregional replenishment routes for qualified grades.
- In April 2026, Mannitab Pharma Specialities received EXCiPACT GMP and GDP certification covering spray-dried and fine-powder mannitol grades. The certification strengthens the documented quality-system basis that pharmaceutical buyers can use during excipient approval and supplier review.
Key Players in the Mannitol Market
Pharmaceutical Excipient Specialists
- Roquette Frères
- SPI Pharma
- Merck KGaA
- Ingredion Incorporated
Food and Polyol Manufacturers
- Cargill
- B Food Science Co.
- Zhejiang Huakang Pharmaceutical Co., Ltd.
Distribution and Ingredient Channels
- Univar Solutions
- American International Foods
- Foodchem International
Mannitol Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; End Use |
| Quantitative Units | USD Million |
| Market Definition | Revenue from mannitol ingredient and excipient sales within the stated Form and End Use universe. Downstream finished-product revenue and adjacent or substitute product revenue are excluded. Where mannitol is sold with formulation or distribution services, only the separable mannitol component is within scope; downstream services and aftermarket activity are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Japan; South Korea |
| Key Companies Profiled | Roquette Frères; SPI Pharma; Cargill; Merck KGaA; B Food Science Co.; Ingredion Incorporated; Univar Solutions; Zhejiang Huakang Pharmaceutical Co., Ltd.; American International Foods; Foodchem International |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Mannitol Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments and findings from primary interviews. Validation also tested whether products, services, applications and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Mannitol Market by Segments
Mannitol Market segmented by Form:
- Crystal
- Powder
Mannitol Market segmented by End Use:
- Food
- Beverages
- Pharmaceuticals
- Carbonated Drinks
- Bakery Goods
- Confectionery
- Powdered Drinks and Mixes
- Solid dosage forms
Mannitol Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- U.S. Food and Drug Administration (2026, July 28). Substances Added to Food (formerly EAFUS): MANNITOL.
- U.S. Food and Drug Administration (n.d.). Inactive Ingredients Database Download.
- UK Government (2026, June 25). Approved additives and E numbers.
- European Commission (2026, February 18). Consolidated EU food-additives rules listing E421 Mannitol and current conditions of use.
- Ministry of Health, Labour and Welfare, Japan (n.d.). Food Additives.
- B Food Science Co. (n.d.). Mannitol.
- Ministry of Food and Drug Safety, South Korea (2026, July 13). Food Additives Code, Notice No. 2026-50.
- Ministry of Food and Drug Safety, South Korea (2026, March 27). D-MANNITOL import record.
- Roquette Frères (2026, June 10). Roquette Showcases Drug Delivery Innovations at CPHI China 2026.
- SPI Pharma (2026, June 4). SPI Pharma Completes Nitrosamine Testing Program for Mannogem.
- Ingredion Pharma Solutions (2026, April). Mannitab achieves EXCiPACT certification.
- Univar Solutions (2026, February 24). Univar Solutions Selected as Ingredion Pharma Solutions Distributor in United States and Canada.
- European Commission (2026, February 5). Food additives in the EU: safe use and clear labelling.
- European Commission Knowledge4Policy (2026, January 9). Main sweeteners and their sources.
- FoodPro (2026). Mannitol - Zhejiang Huakang Pharmaceutical Co., Ltd.
- Ingredion Pharma Solutions (n.d.). Ingredion announces investments in Pharma.
- Ingredion Pharma Solutions (n.d.). MANNITAB SD1: Spray Dried Mannitol.
- Cargill (n.d.). C Mannidex Mannitol.
- Merck KGaA (n.d.). Parteck M (Mannitol) Excipients.
- SPI Pharma (n.d.). Compendial Mannitol: Mannogem Mannitol.
- American International Foods (n.d.). Mannitol.
- Foodchem International (n.d.). Mannitol.
- Zhejiang Huakang Pharmaceutical Co., Ltd. (n.d.). Functional polyol manufacturing and product portfolio.
- Univar Solutions (n.d.). MANNITAB F1 (Mannitol Powder).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Mannitol Market in 2026, and what value is forecast for 2036?
- Which industry pressures are supporting demand for mannitol across food and pharmaceutical applications?
- Why does Crystal lead the Form category in 2026?
- Why does Food lead the End Use category in 2026?
- How do profiled country growth rates differ between South Korea, the UK, the USA, Japan, and Germany?
- Which companies supply or distribute relevant mannitol product categories?
- What limits adoption or supplier switching in regulated food and pharmaceutical applications?
- What should buyers evaluate before purchasing food-grade or pharmaceutical-grade mannitol?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Crystal
- Powder
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Food
- Beverages
- Pharmaceuticals
- Carbonated Drinks
- Bakery Goods
- Confectionery
- Powdered Drinks and Mixes
- Solid dosage forms
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Roquette Frères
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SPI Pharma
- Cargill
- Merck KGaA
- B Food Science Co.
- Ingredion Incorporated
- Univar Solutions
- Zhejiang Huakang Pharmaceutical Co., Ltd.
- American International Foods
- Foodchem International
- Roquette Frères
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 4: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 7: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 10: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 12: Western Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Million) Forecast by Form, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form
- Figure 6: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use
- Figure 9: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Form
- Figure 23: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End Use
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Form
- Figure 30: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by End Use
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Form
- Figure 37: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by End Use
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Form
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Form
- Figure 51: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by End Use
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Mannitol Market in 2026, and what is forecast for 2036?
The Mannitol Market was valued at USD 508.4 Million in 2025, reaches USD 543.0 Million in 2026, and is forecast to reach USD 1048.3 Million by 2036. Growth reflects demand across food and pharmaceutical uses, with realized sales shaped by application permission, particle performance and product-grade qualification.
What is the CAGR for the Mannitol Market from 2026 to 2036?
The market is forecast to grow at a 6.8% CAGR from 2026 to 2036. The rate describes the expected pace of revenue expansion and should not be treated as a measure of any country or company market share.
Which segment leads the Form category in the Mannitol Market?
Crystal leads the Form category with a 63.1% share in 2026. Its position reflects established handling formats that can serve both general ingredient uses and more controlled excipient workflows.
Which segment leads the End Use category in the Mannitol Market?
Food leads the End Use category with a 26.2% share in 2026. Mannitol's combination of sweetness, low hygroscopicity, and anticaking or moisture-management functions supports use in permitted food formulations.
Which profiled countries have the highest growth rates in the Mannitol Market?
South Korea has the highest profiled CAGR at 8.7% from 2026 to 2036, followed by the UK at 8.1%. Those rates indicate forecast pace rather than absolute market size and are influenced by local regulatory, sourcing, and qualification conditions.
Which companies are active in the Mannitol Market?
Profiled market participants include Roquette Frères, SPI Pharma, Cargill, Merck KGaA, B Food Science Co., Ingredion Incorporated, Univar Solutions, Zhejiang Huakang Pharmaceutical Co., Ltd., American International Foods, and Foodchem International. Their roles span pharmaceutical excipients, food-grade polyols, direct-compression grades and regional ingredient distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
