
- Market Size (2026)
- USD 85.1 Bn
- Forecast (2036)
- USD 142.6 Bn
- CAGR (2026 to 2036)
- 5.3%
How big is Microcatheter Market in 2026?
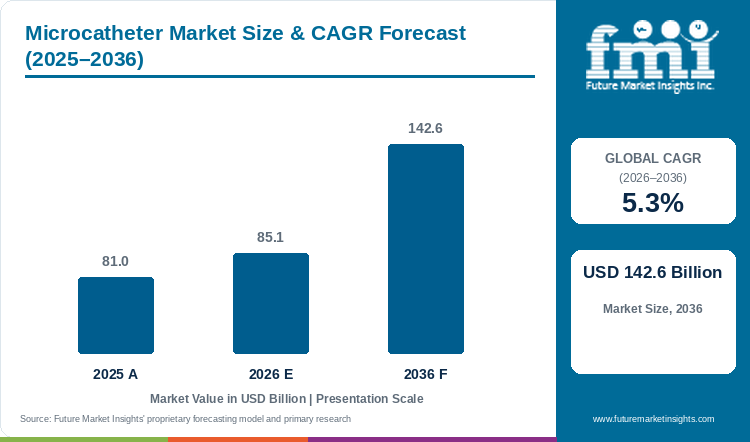
The microcatheter market establishes its foundation at USD 81.0 billion in 2025, advances to USD 85.1 billion in 2026, and is forecast to scale to USD 142.6 billion by 2036 at a CAGR of 5.3%.
Industry valuation for the microcatheter market reached USD 81.0 billion in 2025 and moves to USD 85.1 billion in 2026. Forecast modeling places 2036 market size at USD 142.6 billion, reflecting a 5.3% compound annual growth rate from 2026 through 2036. FMI research shows that flow-directed microcatheters command 50.0% of 2026 demand because hydrophilic distal tips travel with pulsatile arterial flow into sub-millimeter cerebral and visceral vessels where rigid guidewires risk perforation. Demand for sub-3.0 French microcatheters is driven by endovascular substitution of open craniotomy and surgical tumor resection, as interventionalists consume one to three single-use micro-probes per case to deliver detachable coils or chronic total occlusion guidewires. That per-case consumable intensity links the category directly to micro guide catheters, since complex neurovascular and coronary recanalizations require coaxial mother-and-child support to cross calcified or tortuous lesions. Medical device and biopharmaceutical leaders are expanding endovascular and oncology-embolization portfolios, with Medtronic reporting clinical registry milestones across its catheter platforms in October 2026. Hospital catheterization lab value-analysis committees award annual supply contracts on distal tip trackability and lumen burst-pressure ratings, whereas cyanoacrylate catheter entrapment risks and bundled DRG capitation restrain premium pricing through 2036.
Key Market Trends & Insights
- By design architecture: Flow-Directed Microcatheters hold an estimated 50.0% share in 2026 because floppy distal segments navigate tortuous M2/M3 cerebral and hepatic arteries via blood-flow propulsion.
- By clinical specialty: Neurovascular Brain Aneurysms and Stroke represent 45.4% in 2026 as 24-hour stroke thrombectomy centers and middle meningeal artery embolization expand.
- By outer diameter caliper: 1.5 to 2.0 French Micro-Probes account for 57.5% in 2026 due to superselective distal vessel access required for coil deployment and radioembolization.
- By end-user facility: Inpatient Cardiac and Neuro Cath Labs account for 55.9% in 2026 owing to biplane fluoroscopy suite infrastructure and 24/7 neurointerventional call teams.
- By lumen configuration: Single-Lumen Microcatheters command 72.4% in 2026 through low outer-profile geometry and universal compatibility with 0.010-inch to 0.018-inch micro-guidewires.
Regional Highlights
- Top tracked national expansion: United States demand climbs at a 5.6% CAGR while Canada paces the tracked peer group at 5.5% through 2036 under stroke-center certification and transradial TACE adoption.
- Broader country progression: The Netherlands tracks at a 5.3% CAGR ahead of France at 5.2% and Australia at 5.1%, while Germany records 5.0% and the United Kingdom advances at a 4.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Microcatheter Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 81.0 billion |
| Estimated Market Size in 2026 | USD 85.1 billion |
| Projected Market Size by 2036 | USD 142.6 billion |
| CAGR, 2026 to 2036 | 5.3% |
| Added Value, 2026 to 2036 | USD 57.5 billion |
Interventional neuroradiologists and cardiologists face severe procedural failure risks when standard guiding catheters cannot cross sharply angulated intracranial bifurcations or calcified coronary chronic total occlusions. When an oversized catheter wedges inside a 1.5-millimeter cerebral artery, stagnant blood flow triggers thromboembolism or vessel dissection. In July 2025, neurointerventional investigators reporting in the Journal of NeuroInterventional Surgery evaluated 180 experimental M1 middle cerebral artery thrombectomy runs, demonstrating that optimizing the microcatheter-to-vessel size ratio directly governs distal emboli migration during clot retrieval. Accordingly, hospital cath-lab directors pair low-profile hydrophilic micro-probes with peripheral micro catheters to preserve physiological perfusion during complex interventions.
Catheterization Procedure Volume and Consumable Intensity Sizing
Table 2: Endovascular Procedure and Unit-Consumption Sizing for the Microcatheter Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 81.0 | 85.1 | 142.6 |
| Global microcatheter-assisted interventions (million cases) | 46.5 to 51.0 | 48.8 to 53.6 | 78.5 to 86.2 |
| Single-use microcatheter units consumed (million units) | 74.5 to 82.0 | 78.2 to 86.0 | 128.0 to 141.0 |
| Average microcatheter kit & accessory value per case (USD) | 1,580 to 1,740 | 1,590 to 1,745 | 1,655 to 1,815 |
Operational note: Case-level figures reflect 1.4 to 1.8 single-use microcatheters consumed per neurovascular coiling or TACE oncology procedure including coaxial support and DMSO-compatible delivery assemblies.
Acute ischemic stroke thrombectomy and intracranial aneurysm coiling require microcatheters with polytetrafluoroethylene inner liners and braided nitinol-platinum shafts that resist kinking around the carotid siphon. Comprehensive stroke centers integrate these micro-probes with mechanical thrombectomy systems to restore cerebral reperfusion within golden-hour door-to-groin windows.
Per Capita & Hospital Cath-Lab Suite Sizing
Table 3: Per Capita and Cath-Lab Suite Indicators for the Microcatheter Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per capita (USD) | 9.9 | 10.3 | 15.8 |
| 1.5 to 2.0 French ultra-low-profile share (%) | 56.5% to 57.2% | 57.0% to 58.0% | 63.5% to 65.5% |
| Hospital Cardiac and Neuro Cath Labs share (%) | 56.2% to 56.8% | 55.5% to 56.3% | 51.5% to 53.0% |
Table 4: Cath-Lab Suite & Segment Allocation for the Microcatheter Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 85.1 billion | 2026 global valuation baseline |
| Flow-Directed Microcatheters valuation, 2026 | USD 42.6 billion | 50.0% design architecture allocation |
| Neurovascular Brain Aneurysms and Stroke valuation, 2026 | USD 38.6 billion | 45.4% clinical specialty allocation |
| Hospital Cardiac and Neuro Cath Labs valuation, 2026 | USD 47.6 billion | 55.9% end-user facility allocation |
Navigation across heavily calcified coronary chronic total occlusions via retrograde collateral channels demands torque-stable microcatheters with tapered tungsten-loaded radiopaque tips. Interventional cardiologists advance 0.014-inch neurovascular guidewires and coronary wires through braided micro-catheter shafts to prevent wire buckling and subintimal perforation.
Analyst Perspective
"Hospital cath-lab committees do not procure microcatheters on unit price alone. They buy predictable distal trackability into sub-2-millimeter cerebral and hepatic arteries without tip detachment or reflux. Manufacturers that combine dial-steerable tips and dual-lumen anti-reflux balloons with DMSO-compatible polymers will capture the fastest-growing neurovascular and interventional oncology procedures through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the microcatheter market segmented?
The microcatheter market is segmented by design architecture and clinical specialty with outer diameter caliper, end-user facility, and lumen configuration. In 2026, Flow-Directed Microcatheters are projected at 50.0% and Neurovascular Brain Aneurysms and Stroke at 45.4%. 1.5 to 2.0 French Micro-Probes stand at 57.5%, while Hospital Cardiac and Neuro Cath Labs reach 55.9% and Single-Lumen Microcatheters command 72.4%.
By design architecture: Flow-Directed Microcatheters and Steerable Guide-Wire Microcatheters with Co-Axial Dual Microcatheters.
By clinical specialty: Neurovascular Brain Aneurysms and Stroke and Interventional Oncology Chemoembolization (TACE) with Coronary Chronic Total Occlusion (CTO) and Peripheral Vascular Interventions.
By outer diameter caliper: 1.5 to 2.0 French Micro-Probes and 2.1 to 2.7 French Standard Delivery with 2.8 French High-Flow Microcatheters.
By end-user facility: Hospital Cardiac and Neuro Cath Labs and Ambulatory Surgical Centers (ASCs) with Specialty Vascular and Oncology Institutes.
By lumen configuration: Single-Lumen Microcatheters and Dual-Lumen Over-the-Wire Microcatheters with Reinforced Braided-Shaft Microcatheters.
Why do Flow-Directed Microcatheters lead the design architecture category?
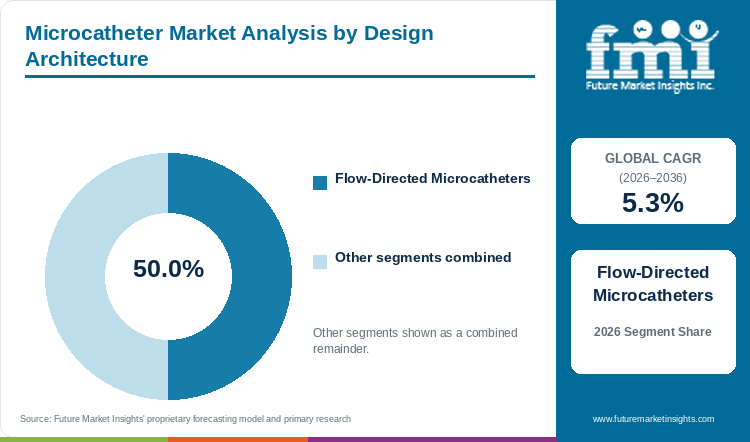
Flow-Directed Microcatheters hold an estimated 50.0% of design architecture demand in 2026, anchored by atraumatic blood-flow navigation into tortuous distal vasculature.
Table 5: Design Architecture Share for the Microcatheter Market (percentage share), 2026
| Design Architecture | Share (2026) |
|---|---|
| Flow-Directed Microcatheters | 50.0% |
| Other Segments Combined | 50.0%* |
| Total | 100.0% |
Note on segment balance: Steerable guide-wire microcatheters and co-axial dual microcatheters account for the balance of 2026 global microcatheter market demand.
Table 6: Design Architecture Leadership and Market Growth for the Microcatheter Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.3% |
| Leading Segment | Flow-Directed Microcatheters |
Flow-directed microcatheters feature progressive stiffness transitions from a supportive proximal nylon-polyurethane shaft down to an ultra-floppy 1.5 French distal segment that drifts forward with systolic blood flow. Neurointerventionalists deploying liquid embolics in intrasaccular embolization systems and brain arteriovenous malformations rely on flow-directed shafts to avoid wire-induced perforation of fragile cortical feeders.
- Flow-Directed Microcatheters hold 50.0% of design architecture valuation in 2026 because blood-flow propulsion enables superselective distal catheterization without rigid guidewire manipulation.
- In October 2025, neurovascular investigators reporting in PubMed demonstrated 100% technical success using flow-directed microcatheter navigation for superselective aneurysmal sac embolization across highly tortuous vessels.
What sustains Neurovascular Brain Aneurysms and Stroke leadership in clinical specialty?
Neurovascular Brain Aneurysms and Stroke represent 45.4% of the clinical specialty category in 2026, supported by global mechanical thrombectomy and middle meningeal artery embolization expansion.
Every stent-retriever thrombectomy and endosaccular coil embolization with flow-diverter deployment requires dedicated microcatheter access across the internal carotid or basilar artery. Hospitals scaling intracranial aneurysm and chronic subdural hematoma programs actively consume dual-lumen and DMSO-compatible microcatheters for Onyx and n-butyl cyanoacrylate delivery.
- Neurovascular Brain Aneurysms and Stroke represent 45.4% of the clinical specialty segment in 2026 as stroke centers extend mechanical thrombectomy windows up to 24 hours.
- In September 2025, a clinical study of 123 non-acute subdural hematoma patients published in JNIS showed that proximal Onyx middle meningeal artery embolization via Scepter Mini or Scepter XC microcatheters achieved 50% or greater hematoma reduction in 77.2% of cases at 6 months.
How do 1.5 to 2.0 French Micro-Probes lead the outer diameter caliper category?
1.5 to 2.0 French Micro-Probes account for 57.5% of outer diameter caliper demand in 2026, driven by sub-segmental hepatic chemoembolization and distal cerebral coiling.
Sub-2.0 French distal outer diameters allow interventional radiologists and neurosurgeons to advance micro-probes into third-order and fourth-order arterial branches while preserving coaxial contrast injection around the shaft. When combined with stroke catheters and intermediate aspiration catheters, 1.5 to 2.0 French probes minimize vasospasm during radial and distal transvenous access.
- 1.5 to 2.0 French Micro-Probes account for 57.5% of outer diameter caliper demand in 2026 because ultraselective tumor and aneurysm embolization requires sub-millimeter distal tip profiles.
- In August 2025, interventional oncology investigators reporting in European Radiology demonstrated that repeated ultraselective transarterial chemoembolization using a 1.7-French-tip microcatheter preserves hepatic function and achieves durable local tumor control in hepatocellular carcinoma.
Why do Hospital Cardiac and Neuro Cath Labs lead the end-user facility category?
Hospital Cardiac and Neuro Cath Labs secure 55.9% of end-user facility valuation in 2026, supported by biplane angiography infrastructure and inpatient ICU backup.
Complex coronary chronic total occlusion recanalizations and ruptured intracranial aneurysm coilings with yttrium-90 radioembolization mapping require hybrid biplane flat-panel detectors and immediate cardiothoracic or neurosurgical backup available only inside acute-care hospitals. While peripheral and diagnostic cases migrate toward outpatient centers, high-acuity multi-catheter procedures remain anchored in tertiary hospital suites.
- Hospital Cardiac and Neuro Cath Labs secure 55.9% of end-user facility demand in 2026 as high-risk coronary CTO and neurovascular interventions require inpatient intensive-care monitoring.
- In January 2026, interventional cardiologists publishing in Interventional Cardiology Clinics reviewed mechanical circulatory support and microcatheter strategies across high-risk chronic total occlusion percutaneous coronary interventions in hospital cath labs.
What gives Single-Lumen Microcatheters the leading position in lumen configuration?
Single-Lumen Microcatheters command 72.4% of lumen configuration share in 2026, anchored by minimal crossing profile and versatile coil and wire delivery.
Single-lumen over-the-wire and flow-directed microcatheters maximize internal lumen diameter relative to outer French caliper, allowing smooth passage of detachable platinum coils and calibrated drug-eluting microspheres or 0.014-inch guidewires without shaft ovalization. Dual-lumen catheters serve specialized bifurcation wiring and balloon-occlusion roles, whereas single-lumen probes anchor daily cath-lab stock.
- Single-Lumen Microcatheters command 72.4% of lumen configuration valuation in 2026 because streamlined shaft geometry provides the lowest crossing profile in stenotic and tortuous vessels.
- In September 2025, stroke investigators reporting in PubMed confirmed that initiating aspiration thrombectomy with single-lumen microcatheter navigation significantly improves crossing success across sharply angulated cerebral occlusions.
What are the drivers and restraints as well as opportunities in the microcatheter market?
In the microcatheter market, expanding transarterial chemoembolization plus immunotherapy combinations and mechanical stroke thrombectomy volumes are projected to drive adoption, whereas catheter tip entrapment in cyanoacrylate glue and nontarget orbital embolization risks restrain uncalibrated use and dial-steerable and dual-lumen anti-reflux microcatheters enable complex anatomical interventions.
- Driver: Higher neurovascular stroke thrombectomy and middle meningeal artery embolization volumes with hepatic TACE-immunotherapy procedures expand per-case microcatheter consumption.
- Restraint: Intraoperative catheter tip retention inside polymerized liquid embolics and nontarget vessel ischemia create severe surgical complications and regulatory scrutiny.
- Opportunity: Adoption of dial-controlled steerable tips and dual-lumen parallel-wiring shafts with 4-French transradial ambulatory microcatheters enables complex bifurcations and outpatient vascular suites.
Growth Analysis and Future Potential for Qualitative Demand Drivers
Oncology tumor boards and comprehensive stroke networks are rapidly expanding catheter-directed chemoembolization combined with hepatic arterial infusion and checkpoint inhibitors for unresectable liver cancer, as well as standalone middle meningeal artery embolization for chronic subdural hematomas. Because each superselective hepatic or meningeal procedure requires dedicated microcatheter cannulation of multiple feeding pedicles, procedural volume growth translates directly into multi-unit consumable pull. Placement of micro-probes into neurovascular devices procedural trays streamlines hospital stocking. In December 2025, oncology investigators reporting in PubMed across 972 hepatocellular carcinoma patients with vascular tumor thrombus demonstrated superior survival when transarterial chemoembolization was combined with systemic targeted and immune therapy.
Risk Assessment of the Microcatheter Market and Operational Friction
Catheter tip entrapment within rapidly polymerizing n-butyl cyanoacrylate or ethylene-vinyl alcohol copolymer casts and inadvertent embolic reflux into anastomotic cranial arteries represent the primary clinical risks restraining microcatheter interventions. When a wedged distal microcatheter tip becomes glued inside a ruptured cerebral or visceral branch, traction can avulse the parent artery and cause fatal hemorrhage. In March 2026, neurovascular clinicians publishing in Radiology Case Reports documented a retained microcatheter during n-butyl cyanoacrylate embolization of a ruptured distal posterior cerebral artery aneurysm, detailing four-year clinical follow-up and retrieval hazards. Interventional suites procuring coronary stents and neurovascular embolics consequently enforce strict detachable-tip and anti-reflux training gates.
Commercial Opportunity Analysis for Formulation Differentiation
Device engineers capture substantial price premiums by commercializing hand-dial steerable microcatheters and dual-lumen parallel-wiring catheters with magnet-guided ultraflexible probes that eliminate guidewire exchanges in acute vessel bifurcations. Rather than withdrawing and steam-shaping multiple pre-curved microcatheters to enter a retroflexed aneurysm neck or femoral pseudoaneurysm, operators articulate a steerable tip up to 180 degrees in situ. Alignment of steerable and robotic-compatible shafts with endovascular surgical robotics consoles further expands remote and precision catheterization. In July 2026, vascular interventionalists reporting in Radiology Case Reports demonstrated successful selective inflow embolization of a giant femoral artery bifurcation pseudoaneurysm using a steerable microcatheter without wire exchange.
Microcatheter Market by Country (2026 to 2036)
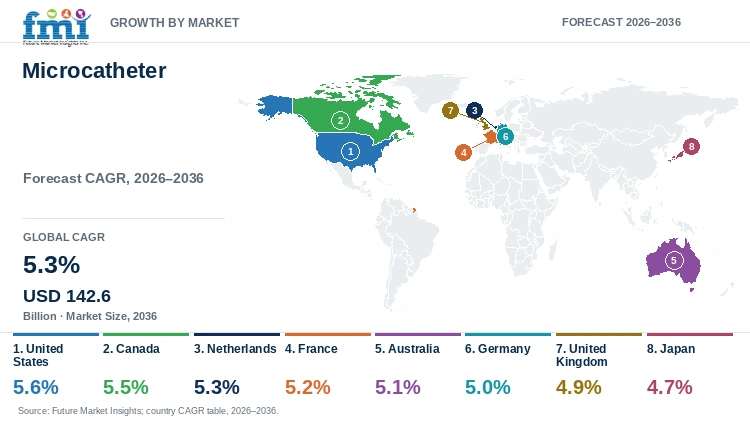
National catheterization projections show the United States advancing at a 5.6% CAGR while Canada paces the tracked peer group at 5.5% through 2036, ahead of the Netherlands at 5.3%. France progresses at 5.2% and Australia posts 5.1%, whereas Germany registers 5.0% ahead of the United Kingdom at 4.9% and Japan at 4.7%.
Table 7: Country CAGR and Primary Growth Levers for the Microcatheter Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United States | 5.6% | CMS outpatient ASC vascular reimbursement and rapid middle meningeal artery embolization scaling |
| Canada | 5.5% | Provincial stroke-network hub-and-spoke expansion and transradial hepatic chemoembolization adoption |
| Netherlands | 5.3% | High per-capita academic endovascular trial density and transradial interventional oncology leadership |
| France | 5.2% | Ambulatory 4-French peripheral arterial interventions and cyanoacrylate prostatic and neurovascular embolization |
| Australia | 5.1% | State retrieval stroke thrombectomy networks and interventional oncology TACE-HAIC adoption across metropolitan hubs |
| Germany | 5.0% | Europe's highest coronary CTO and TACE procedure volume balanced by DRG inpatient lump-sum reimbursement |
| United Kingdom | 4.9% | NHS England 24/7 mechanical thrombectomy commissioning and day-case uterine and prostatic artery embolization |
| Japan | 4.7% | Domestic steerable microcatheter innovation and ultra-high superselective TACE and coil embolization precision |
Source: Future Market Insights analysis
United States Microcatheter Market Outlook (2026 to 2036)
Microcatheter procurement across the United States scales at a 5.6% CAGR through 2036 as hospital neurointerventional suites adopt middle meningeal artery embolization as a primary therapy for chronic subdural hematoma and CMS reimburses peripheral endovascular procedures in ambulatory surgical centers. Unlike single-payer hospital systems that cap per-case consumable kits, cardiac and neuro cath labs in the United States rapidly adopt dual-lumen balloon microcatheters and specialty CTO crossing systems under new technology add-on payments. In October 2026, a multicenter study of 152 patients in PubMed confirmed that dual-lumen balloon-assisted Onyx middle meningeal artery embolization achieved greater than 50% hematoma reduction with low recurrence. High coronary CTO recanalization volumes further anchor hospital cath-lab contracts.
Key takeaway: In the United States, middle meningeal artery embolization scaling and outpatient ASC vascular reimbursement are projected to drive a 5.6% CAGR.
Canada Microcatheter Market Outlook (2026 to 2036)
Whereas growth in the United States is supported by ambulatory surgical centers, Canada achieves a 5.5% CAGR from 2026 to 2036 through provincial stroke networks and academic cancer centers expanding remote thrombectomy and transradial chemoembolization across vast geographic corridors. Provincial health authorities in Ontario and British Columbia as well as Alberta fund 24/7 neurovascular thrombectomy hubs that rely on coaxial micro-probes and remote simulation training to treat acute large-vessel occlusions transferred from rural hospitals. In October 2026, neurosurgeons publishing in the Journal of Neurosurgery validated causal machine-learning frameworks to optimize remote mechanical thrombectomy catheter navigation training across multicenter networks. Same-day transradial uterine and hepatic embolizations also expand hospital day-ward throughput.
Key takeaway: In Canada, provincial stroke-hub expansion and same-day transradial embolization protocols are forecast to support a 5.5% CAGR through 2036.
Netherlands Microcatheter Market Outlook (2026 to 2036)
The Netherlands records a 5.3% CAGR between 2026 and 2036 because its compact motorway hospital network and university medical centers in Amsterdam and Rotterdam as well as Utrecht achieve among Europe's fastest door-to-groin stroke thrombectomy times and highest holmium-166 and yttrium-90 liver radioembolization rates. Dutch interventional radiologists routinely perform workup angiography and therapeutic radioembolization using 1.7 French to 2.0 French anti-reflux and flow-directed microcatheters to spare healthy liver parenchyma. In January 2026, European cardiology investigators publishing in Cardiology provided an updated clinical framework for chronic total occlusion percutaneous coronary intervention microcatheter and wire escalation. Value-based procurement by Dutch hospital cooperatives rewards microcatheters that cut fluoroscopy time and contrast volume.
Key takeaway: In the Netherlands, high per-capita radioembolization and rapid stroke-center throughput are expected to sustain a 5.3% CAGR.
France Microcatheter Market Outlook (2026 to 2036)
France stands apart across European interventional suites through early clinical adoption of liquid n-butyl cyanoacrylate embolization across neurovascular and prostatic bleeding indications with rapid hospital shift toward ambulatory 4-French endovascular care. Microcatheter demand in France moves upward at a 5.2% CAGR across 2026 to 2036 within CHU university hospitals and private vascular clinics. In October 2025, hospital pharmacy and vascular investigators at Saint-Quentin Hospital in France published an evaluation in Annals of Vascular Surgery demonstrating how 4-French compatible endovascular microcatheters and materials enable safe ambulatory peripheral artery disease treatment. Additionally, clinicians in France published evidence in June 2026 validating blocked-flow microcatheter cyanoacrylate prostatic artery embolization.
Key takeaway: In France, ambulatory 4-French peripheral interventions and blocked-flow cyanoacrylate embolization leadership are anticipated to anchor a 5.2% CAGR.
Australia Microcatheter Market Outlook (2026 to 2036)
Australia posts a 5.1% CAGR across the 2026 to 2036 horizon as state health ministries in New South Wales and Victoria as well as Queensland expand aeromedical stroke retrieval hubs and interventional oncology suites in Sydney and Melbourne. Because patients retrieved from regional Australia frequently present with calcified or late-window vascular occlusions, metropolitan cath labs stock high-support braided and dual-lumen microcatheters with flow-directed embolization probes. In October 2026, international cardiovascular clinical guideline authors including investigators in Australia published updated hypertension and vascular care recommendations in PubMed emphasizing minimally invasive endovascular management. Prostheses List reimbursement for specialized neurovascular and peripheral catheters supports private hospital uptake across metropolitan stroke and oncology centers.
Key takeaway: In Australia, state stroke-retrieval hubs and private hospital Prostheses List reimbursement are projected to maintain a 5.1% CAGR.
Germany Microcatheter Market Outlook (2026 to 2036)
Whereas France leads in cyanoacrylate embolization, Germany represents Europe's largest absolute volume market for coronary chronic total occlusion recanalization and transarterial chemoembolization with intracranial aneurysm coiling. Microcatheter valuation in Germany progresses at a 5.0% CAGR through 2036 within certified stroke units and university heart centers as well as oncology clinics. In June 2026, biomedical engineers and interventionalists reporting in Computers in Biology and Medicine validated a novel dual-lumen microcatheter architecture that minimizes particle reflux under pulsatile arterial flow during tumor embolization. German G-DRG inpatient bundle caps encourage hospital purchasing groups to contract with suppliers offering multi-specialty coronary and neurovascular catheter portfolios across tertiary hospital networks.
Key takeaway: In Germany, high coronary CTO and oncology embolization case volumes under G-DRG hospital bundles are slated to yield a 5.0% CAGR.
United Kingdom Microcatheter Market Outlook (2026 to 2036)
Hospital demand in the United Kingdom is shaped by NHS England's national commissioning expansion of 24/7 mechanical thrombectomy centers and NHS Supply Chain framework agreements that favor day-case interventional radiology over inpatient surgery. Microcatheter demand across the United Kingdom registers a 4.9% CAGR during the 2026 to 2036 assessment window within tertiary neuroscience centers and regional vascular hubs. In October 2025, bioengineering and neurointerventional investigators reporting in Science Advances developed flow-driven ultraminiaturized magnetic microcatheters capable of navigating tortuous multi-branch arterial trees where passive microcatheters stall. Higher day-case prostatic artery embolization and fibroid embolization volumes in NHS trusts reduce surgical bed occupancy while lifting microcatheter unit demand.
Key takeaway: In the United Kingdom, NHS 24/7 thrombectomy expansion and day-case interventional radiology pathways are estimated to support a 4.9% CAGR.
Japan Microcatheter Market Outlook (2026 to 2036)
Japan is the global engineering epicenter for ultra-fine braided and dial-steerable microcatheters, driven by domestic masters in retrograde coronary CTO wiring and superselective hepatocellular carcinoma TACE with unruptured intracranial aneurysm coiling. Japanese hospital microcatheter demand climbs at a 4.7% CAGR across the 2026 through 2036 study window inside specialized neurosurgical and cardiovascular hospitals. In September 2025, neurosurgeons in Japan reporting in the Journal of Neuroendovascular Therapy demonstrated successful coil embolization of a complex internal carotid-posterior communicating artery aneurysm with multiple blebs using the hand-dial Leonis Mova steerable microcatheter and an Excelsior SL-10 probe. MHLW functional device reimbursement categories reward domestic and international catheters with proven crossing performance.
Key takeaway: In Japan, domestic dial-steerable microcatheter innovation and superselective neurovascular and hepatic interventions are predicted to sustain a 4.7% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the microcatheter market?
Sandoz Group AG and Pfizer Inc. with Novartis AG and Roche Holding AG plus Merck and Co. Inc. lead commercial supply. Additional notable participants in the microcatheter market include Sanofi SA and AstraZeneca plc with Medtronic plc and Boston Scientific Corporation plus Terumo Corporation.
Competitive positioning across the microcatheter value chain links primary neurovascular and interventional oncology catheter manufacturers with oncology/cardiovascular biopharmaceutical partners whose catheter-delivered therapies drive procedural pull, as well as hospital perioperative anticoagulant suppliers. Boston Scientific Corporation and Medtronic plc as well as Terumo Corporation engineer flow-directed and steerable braided microcatheters for stroke thrombectomy and hepatic TACE with coronary CTO recanalization. Merck and Co. Inc. and Roche Holding AG joined by Novartis AG and AstraZeneca plc drive catheter-based interventional oncology and cardiovascular care. Meanwhile, Sandoz Group AG and Pfizer Inc. joined by Sanofi SA supply the intraprocedural heparin flushes and oncology chemotherapeutics infused through microcatheter lumens.
- Neurovascular and Interventional Oncology Microcatheter Leaders: Medtronic plc and Boston Scientific Corporation with Terumo Corporation manufacture Marathon and Phenom neurovascular probes with Renegade and Progreat microcatheters across 1.5 French to 2.8 French calipers.
- Oncology Radioembolization and Cardiovascular Biopharma Partners: Novartis AG and Roche Holding AG with Merck and Co. Inc. and AstraZeneca plc advance targeted radioligand and systemic-plus-TACE hepatic oncology regimens that expand catheterization suite case volumes.
- Hospital Anticoagulation and Perioperative Injectable Suppliers: Pfizer Inc. and Sandoz Group AG with Sanofi SA supply sterile doxorubicin/epirubicin TACE payloads and heparinized catheter-flush injectables essential to maintaining patency in sub-2.0 French micro-lumens.
Competitive Benchmarking for the Microcatheter Market
Table 8: Competitive Benchmarking for the Microcatheter Market (qualitative capability ratings), 2026
| Company | Microcatheter & Shaft Engineering | Neuro & Oncology Suite Reach | Catheter-Delivered Therapy Fit | Geographic Reach |
|---|---|---|---|---|
| Sandoz Group AG | Unscored | High | High | Global hospital injectable supplier for catheter-flush anticoagulants and generic oncology TACE payloads |
| Pfizer Inc. | Unscored | High | High | Global sterile hospital injectable leader supplying epirubicin, doxorubicin, and heparin for cath-lab infusions |
| Novartis AG | Unscored | High | High | Global radioligand and cardiovascular leader; raised FY 2026 guidance in October 2026 on strong oncology adoption |
| Roche Holding AG | Unscored | High | High | Global oncology and diagnostics leader (+6% CER 9M 2026 growth) anchoring HCC immunotherapy-plus-TACE protocols |
| Merck and Co. Inc. | Unscored | High | High | Global oncology and cardiopulmonary leader; announced Q3 2026 financial results and TACE-combination trials in October 2026 |
| Sanofi SA | Unscored | High | High | Global cardiovascular and hospital thrombosis leader (+31.4% Q3 2026 launch growth) supporting cath-lab pharmacology |
| AstraZeneca plc | Unscored | High | High | Global hepatic oncology and CVRM leader (+7% 9M 2026 growth) driving combined TACE plus immunotherapy procedures |
| Medtronic plc | High | High | High | Global neurovascular leader supplying Marathon, Apollo, Echelon, and Phenom microcatheters; announced CathWorks acquisition intent in Feb 2026 |
| Boston Scientific Corporation | High | High | High | Global interventional oncology and coronary leader supplying Renegade, Direxion, and Mamba microcatheters; Q2 2026 net results of USD 5.442B |
| Terumo Corporation | High | High | High | Global transradial and interventional oncology leader manufacturing Progreat 1.7F-2.7F and Headway neurovascular microcatheters |
Evaluation basis: Microcatheter & Shaft Engineering evaluates proprietary braided nitinol-tungsten shafts and hydrophilic coatings with DMSO compatibility, while Neuro & Oncology Suite Reach measures hospital cath-lab and interventional radiology contract penetration. Catheter-Delivered Therapy Fit assesses clinical integration with embolic coils and drug-eluting microspheres as well as heparinized flush protocols.
Key Developments in the Microcatheter Market
- Boston Scientific Corporation reported second-quarter 2026 net results of USD 5.442 billion (up 7.5% reported and 7.8% organic in Cardiovascular) on July 29, 2026, expanding its global coronary CTO and interventional oncology microcatheter footprint.
- On October 29, 2026, Merck and Co. Inc. released third-quarter 2026 performance updates detailing oncology and cardiovascular clinical milestones that expand combined locoregional TACE and systemic interventional pathways.
- On October 21, 2026, Roche Holding AG reported 6% constant-exchange-rate group growth to CHF 46.49 billion across the first nine months of 2026 supported by hepatocellular carcinoma immunotherapy and diagnostic adoption.
Key Players in the Microcatheter Market
Neurovascular and Interventional Oncology Microcatheter Leaders
- Sandoz Group AG
- Pfizer Inc.
- Novartis AG
- Roche Holding AG
Oncology Radioembolization and Cardiovascular Biopharma Partners
- Merck and Co. Inc.
- Sanofi SA
- AstraZeneca plc
- Medtronic plc
Hospital Anticoagulation and Perioperative Injectable Suppliers
- Boston Scientific Corporation
- Terumo Corporation
Microcatheter Market - Report Scope
Table 9: Report Scope for the Microcatheter Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Design Architecture; Clinical Specialty; Outer Diameter Caliper; End-User Facility; Lumen Configuration |
| Quantitative Units | USD Billion |
| Market Definition | Includes global supplier valuation from single-use sub-3.0 French medical microcatheters covering flow-directed and steerable guide-wire designs with coaxial dual and dual-lumen balloon/over-the-wire microcatheters used across neurovascular, interventional oncology, coronary CTO, and peripheral vascular procedures. Category Scope Note: Excludes 5-French to 8-French guiding catheters, large-bore stroke aspiration catheters, standalone coronary angioplasty balloons, and central venous access catheters. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, Canada, Netherlands, France, Australia, Germany, United Kingdom, and Japan |
| Key Companies Covered | Sandoz Group AG, Pfizer Inc., Novartis AG, Roche Holding AG, Merck and Co. Inc., Sanofi SA, AstraZeneca plc, Medtronic plc, Boston Scientific Corporation, and Terumo Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Microcatheter Market - Research Methodology
Table 10: Research Methodology for the Microcatheter Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with hospital neurointerventional radiology directors, interventional oncology TACE chiefs, and coronary CTO operators to validate per-procedure microcatheter consumption and ASP tiers. |
| Secondary Research | Analysis of FDA 510(k) and CE-MDR catheter clearances, SNIS and CIRSE embolization guidelines, PubMed and PMC neurovascular and CTO registries, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down global pharmaceutical and medical technology baselines (child market representing 4.5% of the parent medical technology and interventional baseline) reconciled against bottom-up microcatheter-assisted procedure volumes (48.8M to 53.6M cases in 2026) and catheter kit realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight 24/7 mechanical thrombectomy stroke-center density, hepatic TACE and Y-90 radioembolization caseloads, and outpatient ASC vascular reimbursement across eight national markets. |
| Operational Benchmark Traceability | Procedural and cath-lab indicators in Tables 2, 3, and 4 trace to Journal of NeuroInterventional Surgery thrombectomy registries, Interventional Cardiology Clinics CTO benchmarks, and national hospital catheterization audits. |
| Data Triangulation and Validation | Valuation estimates isolate 1.5 French to 2.8 French diagnostic, delivery, and embolization microcatheters while strictly excluding large-bore guide sheaths, standalone guidewires, and implantable coils or stents. |
Microcatheter Market by Segments
Microcatheter Market segmented by Design Architecture:
- Flow-Directed Microcatheters
- Steerable Guide-Wire Microcatheters
- Co-Axial Dual Microcatheters
- Additional Design Architecture Categories
Microcatheter Market segmented by Clinical Specialty:
- Neurovascular Brain Aneurysms
- Stroke
- Interventional Oncology Chemoembolization (TACE)
- Coronary Chronic Total Occlusion (CTO)
Microcatheter Market segmented by Outer Diameter Caliper:
- 1.5 to 2.0 French Micro-Probes
- 2.1 to 2.7 French Standard Delivery
- 2.8 French High-Flow Microcatheters
- Additional Outer Diameter Caliper Categories
Microcatheter Market segmented by End-User Facility:
- Hospital Cardiac
- Neuro Cath Labs
- Ambulatory Surgical Centers (ASCs)
- Specialty Vascular
Microcatheter Market segmented by Lumen Configuration:
- Single-Lumen Microcatheters
- Dual-Lumen Over-the-Wire Microcatheters
- Reinforced Braided-Shaft Microcatheters
- Additional Lumen Configuration Categories
Microcatheter Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Dual Microcatheter Intracranial Aneurysm Meta-Analysis Group. (2025, September 28). Efficacy and Safety of Dual Microcatheter Interventional Embolization for Intracranial Aneurysms: A Systematic Review and Meta-Analysis. World Neurosurgery (PubMed PMID 41076241).
- [2] CrossFAST Complex PCI Clinical Investigators. (2026, February 24). Early Clinical Experience With CrossFAST, a Novel, Microcatheter-Led Advanced Device Delivery System for Complex Coronary Intervention. Cardiovascular Revascularization Medicine (PubMed PMID 41868774).
- [3] Medtronic plc. (2026, October 22). Medtronic announces positive results from real-world registries for the Sphere-9 catheter and PulseSelect PFA System at APHRS 2026. Medtronic Newsroom Press Releases.
- [4] Middle Cerebral Artery Thrombectomy Sizing Investigators. (2025, July 28). The impact of microcatheter-to-vessel size ratio on distal embolization during mechanical thrombectomy. Journal of NeuroInterventional Surgery (PubMed PMID 40718902).
- [5] Super-Selective Flow-Directed Embolization Group. (2025, October 4). Super-Selective Embolization Using Flow-Directed Microcatheter Navigation in Tortuous Visceral and Cerebral Aneurysms. Interventional Neuroradiology (PubMed PMID 41112819).
- [6] Temple Neurosciences Center POEM Study Group. (2025, September 5). Proximal Onyx embolization of the middle meningeal artery (POEM) using dual-lumen balloon microcatheters for non-acute subdural hematomas. Journal of NeuroInterventional Surgery (PubMed PMID 40912917).
- [7] Ultraselective 1.7-Fr Microcatheter TACE Investigators. (2025, August 1). Repeated ultraselective transcatheter arterial chemoembolization using a 1.7-Fr-tip microcatheter for hepatocellular carcinoma. European Radiology (PubMed PMID 40419936).
- [8] The Valley Hospital Cardiac Catheterization Laboratory Group. (2026, January 15). Mechanical Circulatory Support and Microcatheter Strategies in Chronic Total Occlusion Percutaneous Coronary Intervention. Interventional Cardiology Clinics, 15(1), 139-152 (PubMed PMID 41276389).
- [9] Acute Ischemic Stroke Vascular Angulation Study Group. (2025, September 19). Does initiating aspiration with microcatheter navigation improve the crossing of angulated cerebral occlusions in acute ischemic stroke?. Neuroradiology (PubMed PMID 40970958).
- [10] HCC Vascular Tumor Thrombus TACE Study Consortium. (2025, December 8). Should transarterial chemoembolization be applied with systemic targeted and immune therapy in hepatocellular carcinoma with hepatic or inferior vena cava tumor thrombus?. Liver Cancer (PubMed PMID 41363180).
- [11] Distal PCA Aneurysm Embolization Case Group. (2026, March 14). Retained Microcatheter During n-Butyl Cyanoacrylate Embolization of a Ruptured Distal Posterior Cerebral Artery Aneurysm: A Case Report With 4-Year Follow-Up. Radiology Case Reports, 21(6), 2323-2327 (PubMed PMID 41868468).
- [12] Steerable Microcatheter Pseudoaneurysm Investigators. (2026, July 31). Steerable microcatheter-assisted selective inflow embolization of a giant femoral artery bifurcation pseudoaneurysm: A case report. Radiology Case Reports, 21(10), 5047-5052 (PubMed PMID 42571400).
- [13] Multicenter Dual-Lumen MMAE Investigators. (2026, October 13). Dual-Lumen Balloon Assisted Onyx Embolization of Middle Meningeal Artery for Chronic Subdural Hematoma in 152 Patients. Neurosurgery (PubMed PMID 42869581).
- [14] Multicenter Remote Thrombectomy Training Consortium. (2026, October 30). Causal machine learning for remote mechanical thrombectomy catheter navigation training in a multicenter study. Journal of Neurosurgery (PubMed PMID 42962230).
- [15] European CTO PCI Consensus Group. (2026, January 9). Update on Chronic Total Occlusion Percutaneous Coronary Intervention: Microcatheter and Guidewire Escalation. Cardiology, 1-12 (PubMed PMID 41511912).
- [16] Saint-Quentin Hospital Endovascular Materials Group. (2025, October 31). 4-French compatible endovascular materials for peripheral artery disease in ambulatory care. Annals of Vascular Surgery (PubMed PMID 41177450).
- [17] International Society of Hypertension Vascular Guidelines Panel. (2026, October 20). 2026 International Society of Hypertension Global Vascular and Endovascular Practice Recommendations. Journal of Hypertension (PubMed PMID 42909506).
- [18] Multiphysics Embolization Microcatheter Engineering Group. (2026, June 1). A dual-lumen microcatheter for minimizing particle reflux during embolization: Proof-of-concept with multiphysics simulations. Computers in Biology and Medicine, 209, 111684 (PubMed PMID 42001767).
- [19] Flow-Driven Magnetic Microcatheter Bioengineering Group. (2025, October 22). Flow-driven magnetic microcatheter for superselective arterial embolization. Science Advances (PubMed PMID 41124295).
- [20] Leonis Mova Neuroendovascular Study Group. (2025, September 25). Microcatheter Shape Adjustment during Coil Embolization with the Leonis Mova Steerable Microcatheter. Journal of Neuroendovascular Therapy (PubMed PMID 41035542).
- [21] Boston Scientific Corporation. (2026, July 29). Boston Scientific announces results for second quarter 2026 with 7.8% organic Cardiovascular growth. Boston Scientific Media Room.
- [22] Merck and Co. Inc. (2026, October 29). Merck Announces Third-Quarter 2026 Financial Results and Oncology Pipeline Milestones. Merck Corporate Newsroom.
- [23] Roche Holding AG. (2026, October 21). Group sales increase +6% (CER), +7% in USD, in the first nine months of 2026 driven by Pharmaceuticals and Diagnostics. Roche Media Releases.
- [24] Department of Interventional Treatment TACE-HAIC Group. (2025, December 31). Safety and efficacy of transcatheter chemoembolization combined with hepatic arterial infusion chemotherapy in unresectable primary hepatocellular carcinoma. World Journal of Gastrointestinal Oncology (PubMed PMID 41522752).
- [25] TACE Plus Arterial Nivolumab Trialists. (2025, November 12). TACE Combined with Hepatic Arterial Infusion of Nivolumab for Hepatocellular Carcinoma. Journal of Hepatocellular Carcinoma (PubMed PMID 41223134).
- [26] Coronary False Lumen Dual-Lumen Microcatheter Group. (2026, March 28). Novel Use of Dual-Lumen Microcatheter for False Lumen Wiring and Stent Rescue in Iatrogenic Coronary Dissection. JACC: Case Reports (PubMed PMID 41902822).
- [27] Sandoz Group AG. (2026, October 28). Sandoz reports strong biosimilar sales momentum, narrowed full-year net-sales range and upgrade to margin guidance. Sandoz Corporate Newsroom.
- [28] Pfizer Inc. (2026, August 4). Pfizer Reports Second-Quarter 2026 Results and Raises Midpoint of 2026 Financial Guidance. Pfizer Investor Relations.
- [29] Novartis AG. (2026, October 27). Novartis delivered sales growth and core margin expansion in Q3; raised FY core operating income guidance. Novartis Media Releases.
- [30] Sanofi SA. (2026, October 30). Press Release: Q3 2026: double-digit growth in sales and business EPS; FY 2026 guidance upgraded. Sanofi Media Room.
- [31] AstraZeneca plc. (2026, October 30). 9M and Q3 2026 Results: Double-Digit Oncology and R&I Growth. AstraZeneca Media Centre.
- [32] Prostatic Artery Cyanoacrylate Embolization Group. (2026, June 10). Safe Prostatic Artery Embolization with Cyanoacrylate Using Blocked-Flow Microcatheter Technique. Journal of Vascular and Interventional Radiology (PubMed PMID 42351446).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the microcatheter market in 2026 and what is forecast for 2036?
- Which neurovascular thrombectomy and hepatic TACE pressures support demand for microcatheters?
- Why do Flow-Directed Microcatheters lead the design architecture category?
- Why do 1.5 to 2.0 French Micro-Probes lead the outer diameter caliper category globally?
- How do growth rates differ across the United States and Canada as well as the Netherlands?
- Which leading companies supply neurovascular and coronary microcatheters versus catheter-delivered oncology and antithrombotic therapies?
- What clinical risks from cyanoacrylate tip entrapment and nontarget embolization restrain uncalibrated microcatheter use?
- What should hospital cath-lab committees evaluate when qualifying steerable and dual-lumen microcatheters?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Design Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Design Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Design Architecture, 2026 to 2036
- Flow-Directed Microcatheters
- Steerable Guide-Wire Microcatheters
- Co-Axial Dual Microcatheters
- Additional Design Architecture Categories
- Y-o-Y Growth Trend Analysis By Design Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Design Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Specialty, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Specialty, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Specialty, 2026 to 2036
- Neurovascular Brain Aneurysms
- Stroke
- Interventional Oncology Chemoembolization (TACE)
- Coronary Chronic Total Occlusion (CTO)
- Y-o-Y Growth Trend Analysis By Clinical Specialty, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Specialty, 2026 to 2036
- Global Market Analysis and Forecast, By Outer Diameter Caliper, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Outer Diameter Caliper, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Outer Diameter Caliper, 2026 to 2036
- 1.5 to 2.0 French Micro-Probes
- 2.1 to 2.7 French Standard Delivery
- 2.8 French High-Flow Microcatheters
- Additional Outer Diameter Caliper Categories
- Y-o-Y Growth Trend Analysis By Outer Diameter Caliper, 2021 to 2025
- Absolute $ Opportunity Analysis By Outer Diameter Caliper, 2026 to 2036
- Global Market Analysis and Forecast, By End-User Facility, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-User Facility, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-User Facility, 2026 to 2036
- Hospital Cardiac
- Neuro Cath Labs
- Ambulatory Surgical Centers (ASCs)
- Specialty Vascular
- Y-o-Y Growth Trend Analysis By End-User Facility, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Facility, 2026 to 2036
- Global Market Analysis and Forecast, By Lumen Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Lumen Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Lumen Configuration, 2026 to 2036
- Single-Lumen Microcatheters
- Dual-Lumen Over-the-Wire Microcatheters
- Reinforced Braided-Shaft Microcatheters
- Additional Lumen Configuration Categories
- Y-o-Y Growth Trend Analysis By Lumen Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Lumen Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- By Country
- Market Attractiveness Analysis
- By Country
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Design Architecture
- By Clinical Specialty
- By Outer Diameter Caliper
- By End-User Facility
- By Lumen Configuration
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Sandoz Group AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pfizer Inc.
- Novartis AG
- Roche Holding AG
- Merck and Co. Inc.
- Sanofi SA
- AstraZeneca plc
- Medtronic plc
- Boston Scientific Corporation
- Terumo Corporation
- Sandoz Group AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Design Architecture, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Clinical Specialty, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Outer Diameter Caliper, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End-User Facility, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Lumen Configuration, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Design Architecture
- Figure 6: Global Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Clinical Specialty
- Figure 9: Global Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 12: Global Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-User Facility
- Figure 15: Global Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Lumen Configuration
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Design Architecture
- Figure 32: North America Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Clinical Specialty
- Figure 35: North America Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 38: North America Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-User Facility
- Figure 41: North America Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Lumen Configuration
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Design Architecture
- Figure 48: Latin America Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Clinical Specialty
- Figure 51: Latin America Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 54: Latin America Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-User Facility
- Figure 57: Latin America Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Lumen Configuration
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Design Architecture
- Figure 64: Western Europe Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Clinical Specialty
- Figure 67: Western Europe Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-User Facility
- Figure 73: Western Europe Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Lumen Configuration
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Design Architecture
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Clinical Specialty
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-User Facility
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Lumen Configuration
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Design Architecture
- Figure 96: East Asia Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Clinical Specialty
- Figure 99: East Asia Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 102: East Asia Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-User Facility
- Figure 105: East Asia Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Lumen Configuration
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Design Architecture
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Clinical Specialty
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-User Facility
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Lumen Configuration
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Design Architecture, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Design Architecture, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Design Architecture
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Clinical Specialty, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Specialty, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Clinical Specialty
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Outer Diameter Caliper, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Outer Diameter Caliper, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Outer Diameter Caliper
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-User Facility
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Lumen Configuration, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Lumen Configuration, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Lumen Configuration
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the microcatheter market in 2026, and what is forecast for 2036?
Global microcatheter industry valuation progressed from USD 81.0 billion in 2025 to USD 85.1 billion in 2026. Total market size is projected to reach USD 142.6 billion by 2036 as stroke thrombectomy and hepatic chemoembolization procedures expand globally.
What is the CAGR for the microcatheter market from 2026 to 2036?
The microcatheter market is projected to expand at a 5.3% CAGR over the 2026 to 2036 window, adding USD 57.5 billion in valuation across hospital cath labs and ambulatory vascular centers.
Which design architecture segment leads the microcatheter market?
Flow-Directed Microcatheters hold 50.0% of design architecture demand in 2026 because supple hydrophilic distal shafts use arterial blood flow to navigate tortuous cerebral and visceral branches.
Which outer diameter caliper segment leads the microcatheter market?
1.5 to 2.0 French Micro-Probes represent 57.5% of the outer diameter caliper category in 2026 as superselective aneurysm coiling and sub-segmental tumor embolization require sub-millimeter distal profiles.
Which countries have notable growth outlooks during the assessment period?
The United States advances at a 5.6% CAGR and Canada leads the tracked peer group at a 5.5% CAGR through 2036, followed by the Netherlands at 5.3% and France at 5.2%.
Who are the key players in the market?
Terumo Corporation and Medtronic plc with Boston Scientific Corporation plus Novartis AG participate plus Roche Holding AG and AstraZeneca plc. Key pharmaceutical suppliers include Merck and Co. Inc. and Pfizer Inc. joined by Sandoz Group AG and Sanofi SA.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
