

- Market Size (2026)
- USD 11.2 Bn
- Forecast (2036)
- USD 18.6 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Oatmeal Market in 2026?
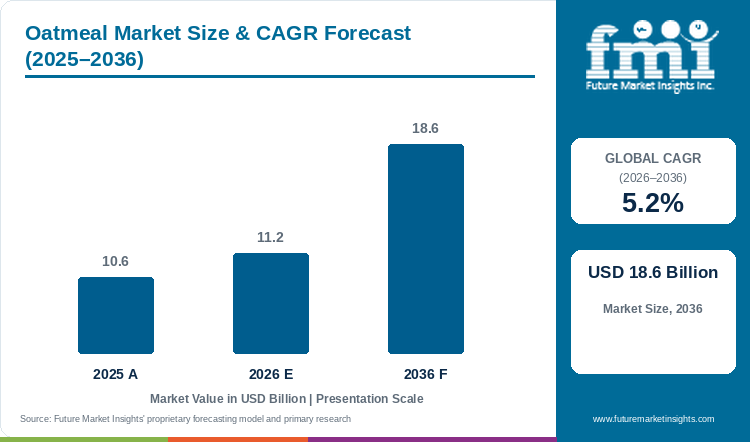
Sales in the oatmeal market are projected to grow at 5.2% CAGR, with the market size rising from USD 10.6 Billion in 2025 to USD 11.2 Billion in 2026 and reaching USD 18.6 Billion by 2036.
According to Future Market Insights analysis, the global oatmeal market stands at USD 10.6 Billion in 2025 and rises to USD 11.2 Billion in 2026. Industry valuation is projected to reach USD 18.6 Billion by 2036, expanding at a 5.2% CAGR and generating USD 7.4 Billion in added revenue over the forecast period. Steady household grocery purchases underpin baseline volumes across rolled oats, steel-cut groats, and instant microwave cups. In January 2025, USDA Economic Research Service crop data confirmed that food-grade oat processing volumes climbed by 3.8% across North American milling facilities [1]. Standard Commercial Grade captures the leading position with 48.1% share in 2026, as affordable bulk rolled oats serve family breakfast routines. Growth across evaluated economies spans 4.2% in the UK to 6.3% in France. Grain price volatility and oat rust crop diseases continue to influence industrial milling margins.
Key Market Trends & Insights
- By product type / grade: Standard Commercial Grade led with 48.1% share in 2026, as high-volume rolled oats anchor family kitchen pantries.
- By processing state: Fresh / ambient packaged held 54.5% in 2026, supported by long ambient shelf stability and moisture-proof packaging.
- By end-use application: Direct retail consumer consumption captured 39.1% in 2026, driven by hot breakfast cereals and homemade overnight oats.
- By regional distribution: North America and Western Europe account for the highest per capita consumption of whole-grain oat cereals.
Regional Highlights
- Fastest-growing evaluated country: France, at 6.3% CAGR from 2026 to 2036.
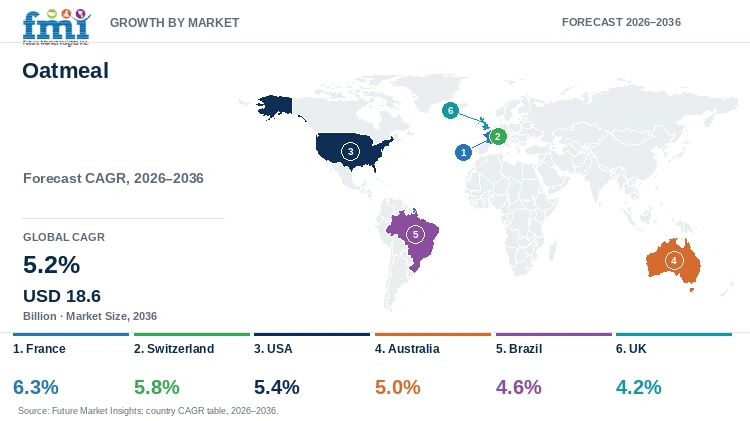
- By country: Switzerland at 5.8%, the USA at 5.4%, Australia at 5.0%, and Brazil at 4.6% follow, while the UK records the lowest evaluated CAGR at 4.2%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Oatmeal Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 10.6 Billion |
| Estimated Market Size in 2026 | USD 11.2 Billion |
| Projected Market Size by 2036 | USD 18.6 Billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 7.4 Billion |
Future Market Insights research indicates that commercial oat mills require high-efficiency dehullers and continuous steam kilns to neutralize lipase enzymes. In February 2025, U.S. Department of Agriculture grain outlook reports documented robust export trade in food-grade oat groats [2]. Consequently, milling groups are installing automated optical color sorters, insulating processing facilities from weed seed contamination while delivering uniform oat flake thickness.
Oat Milling and Kiln Processing Metrics
Table 2: Oat Milling and Kiln Processing Metrics for the Oatmeal Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 10.6 | 11.2 | 18.6 |
| Global Food-Grade Oat Milling Volume (Million Metric Tons) | 5.4 to 6.1 | 5.7 to 6.4 | 8.8 to 10.2 |
| Hydrothermal Kiln Energy Efficiency (kWh per Ton) | 42.0 to 48.5 | 40.5 to 46.8 | 32.0 to 37.5 |
| Lipase Enzyme Deactivation Success Rate (Percent) | 99.1 to 99.6 | 99.3 to 99.7 | 99.7 to 99.9 |
Calculation basis: Operational estimates apply food-grade oat crop intake across licensed grain mills. Energy figures assume continuous hydrothermal kilning skids. Figures represent grain processing scenario ranges.
Per Capita Intake & Food Processing Sizing
Whole-grain oats have maintained sustained popularity in recent years due to consumer demand for natural cholesterol reduction and sustained digestive satiety. Balancing oat flake texture requires precise hydrothermal steaming and flaking roll calibration. Surging wellness awareness and plant-based breakfast trends convert grocery spending into recurring oatmeal purchases. Supermarket grocery chains represent fundamental volume distribution outlets for commercial oat brands.
Table 3: Per Capita and Food Facility Spending Indicators for the Oatmeal Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Population (Billion) | 8.23 | 8.30 | 8.95 |
| Annual Oatmeal Spend per Capita (USD) | 1.29 | 1.35 | 2.08 |
| Annual Oatmeal Spend per Consuming Household (USD) | 32.00 to 44.00 | 34.00 to 46.00 | 55.00 to 74.00 |
| Wholesale Oatmeal Procurement per Supermarket Banner (USD Thousand) | 85.0 to 115.0 | 90.0 to 122.0 | 160.0 to 215.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Oatmeal Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 11.2 Billion | Report value |
| Licensed grain milling and breakfast cereal facilities worldwide | 6,800 | 2024 secondary estimate |
| Average commercial oatmeal output per facility | USD 1.65 Million | Calculated |
| Direct retail consumer consumption revenue, 2026 | USD 4.38 Billion | 39.1% share |
Analyst Perspective
"The oatmeal sector is experiencing a functional renaissance driven by health-conscious consumer routines. Modern shoppers demand high-protein instant oats, certified gluten-free groats, and savory oatmeal blends that fit fast-paced morning lifestyles. Cereal manufacturers that invest in clean-label steam stabilization and single-serve packaging will secure long-term shelf space across major supermarket banners and quick-service breakfast stations."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the oatmeal market segmented?
The oatmeal market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 48.1%, fresh / ambient packaged at 54.5%, and direct retail consumer consumption at 39.1%.
By product type / grade: Standard Commercial Grade, Organic & Clean-Label Variant, and Premium Specialty Formulation.
By processing state: Fresh / Ambient Packaged, Frozen & Chilled, and Dehydrated & Dry Packaged.
By end-use application: Direct Retail Consumer Consumption, Food Service & Hospitality, and Commercial Food Manufacturing Plants.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why does standard commercial grade lead the product type / grade category?
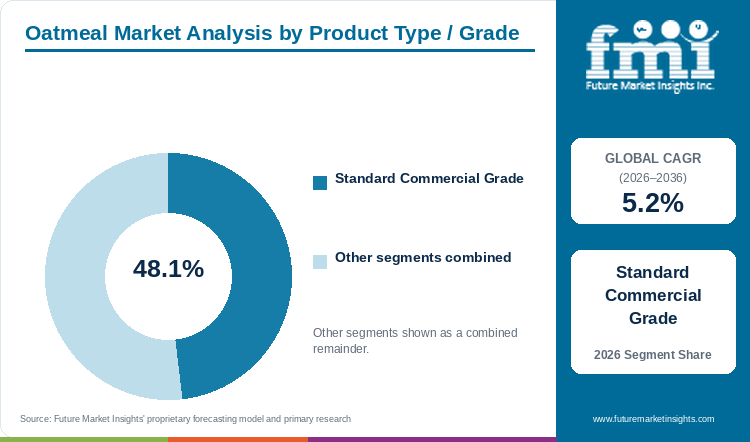
Standard commercial grade represents 48.1% of product type / grade in 2026, balancing accessible family pricing with reliable cooking performance in morning breakfast dishes.
Table 5: Product Type / Grade Share for the Oatmeal Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 48.1% |
| Other Segments Combined | 51.9%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Oatmeal Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Standard Commercial Grade |
Residential shoppers and foodservice cooks favor standard commercial grade rolled oats because regular flakes absorb hot liquid evenly without turning gummy. Families purchase large canister packs of old-fashioned rolled oats for economical weekday breakfasts and home baking. Food manufacturers utilize standard rolled oats as inclusions in granola bars and cookie doughs. Millers operate high-speed flaking rollers to achieve consistent flake thickness. Health-conscious shoppers also seek certified gluten free oats to prevent autoimmune digestive distress. In addition, food processors evaluate oat beta glucan concentrates to formulate cholesterol-lowering functional food products.
- Standard commercial grade represents 48.1% of product type in 2026, as multi-serving canister packaging delivers superior household economic value.
- In March 2025, industrial grain milling associations released updated quality guidelines for standard rolled oats processing [3].
What drives fresh / ambient packaged to the forefront of the processing state segment?
Fresh / ambient packaged accounts for 54.5% of processing state in 2026, supported by moisture-resistant carton canisters and extended dry pantry shelf stability.
Ambient packaged oatmeal dominates global retail distribution because hydrothermal steam stabilization inactivates spoilage enzymes permanently. Proper kilning destroys native lipases, preventing unground oats from developing rancid off-flavors during room-temperature storage. Brand manufacturers package rolled flakes in recyclable paperboard canisters lined with moisture barrier films. In addition, breakfast brand managers expand certified organic oats to attract wellness-focused grocery shoppers. Formulators also procure specialized oat based snacks to capture on-the-go morning commuters. Ambient dry distribution eliminates expensive cold-chain freight expenses.
- Fresh / ambient packaged accounts for 54.5% of processing state in 2026, underpinned by multi-layer barrier packaging that protects grain freshness.
- In May 2025, U.S. Food and Drug Administration food safety updates affirmed whole-grain fiber labeling standards for ambient breakfast cereals [4].
How does direct retail consumer consumption dominate end-use applications with 39.1% share?
Direct retail consumer consumption holds 39.1% of end-use applications in 2026, driven by everyday porridge routines, overnight oats preparation, and home baking.
Supermarket grocery shoppers drive primary category demand because hot oatmeal represents an affordable, filling breakfast staple for children and adults. Consumers prepare instant oatmeal packets in office breakrooms using microwave water dispensers. Social media recipe trends encourage young adults to prepare mason jar overnight oats blended with oat milk and chia seeds. Retailers allocate dedicated aisle space to flavored oatmeal cups and protein-fortified porridge pouches. Furthermore, shoppers buy wholesome granola clusters for snacking and yogurt toppings. Grocers offer private-label rolled oats to compete against national cereal brands.
- Direct retail consumer consumption holds 39.1% of end-use applications in 2026, sustained by high consumer adoption of overnight oats and warm breakfast bowls.
- In June 2025, European Food Safety Authority dietary panels validated health claims linking soluble oat fiber consumption to healthy blood lipid management [5].
What are the drivers, restraints, and opportunities in the oatmeal market?
Cardiovascular wellness awareness drives oatmeal consumption, while raw grain price volatility constrains margins and high-protein instant formats unlock premium growth.
- Driver: Expanding clinical recognition of oat beta-glucan in lowering blood cholesterol and supporting gut microbiome health fuels consistent retail demand for whole-grain oats.
- Restraint: Extreme agricultural weather swings in major oat-producing basins, crop rust fungal infections, and freight rail congestion squeeze miller profit margins.
- Opportunity: Commercial production of high-protein instant oatmeal pouches and ready-to-eat overnight oat cups addresses modern consumer preferences for fast, clean morning nutrition.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Health-conscious shoppers increasingly prioritize whole-grain fiber to support cardiovascular vitality and sustained metabolic energy. Busy professionals replace sugary processed pastries with quick-cooking rolled oats enriched with nuts, seeds, and dried fruit. Future Market Insights research indicates that organic and non-GMO oats command superior retail pricing across metropolitan supermarkets. In September 2025, nutritional consumer survey data confirmed that 74.2% of regular oatmeal purchasers cited heart health as their primary buying motivation [7]. Food companies respond by fortifying oatmeal bowls with prebiotic fibers and plant proteins.
Risk Assessment of the Oatmeal Market: Operational and Formulation Friction
Unpredictable farm yields and enzymatic rancidity present ongoing operational challenges for industrial oat millers. Drought conditions in North American and European agricultural belts cause harvest shortages and sharp farmgate grain price spikes. Furthermore, inadequate steam kilning leaves active lipases that hydrolyze oat fats into bitter free fatty acids within weeks. In October 2025, agricultural logistics reports documented that raw grain shipping tariffs climbed by 12.8% across major freight transit lines [8]. Milling facilities must operate continuous sensory testing to guarantee sweet, nutty grain flavor.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Cereal manufacturers capture substantial profit margin expansion by introducing savory oatmeal cups, microwave protein oatmeal, and functional breakfast bowls. Brands develop instant oatmeal enriched with plant-based oat protein isolates to attract fitness enthusiasts. In addition, food processors formulate portable oat based beverage lines for active morning routines. Food formulators also utilize hydrolyzed oat protein to boost foam stability and creaminess in dairy-free beverages. In November 2025, grocery retail scanner data indicated that protein-fortified oatmeal cups achieved an 18.4% sales increase across convenience stores [9].
Oatmeal Market by Country (2026 to 2036)
As per Future Market Insights, France represents the fastest-growing oatmeal market among the six evaluated countries, at a 6.3% CAGR from 2026 to 2036, while the UK records the slowest expansion at 4.2% CAGR. Across all six covered economies, commercial success is dictated by how effectively cereal brands develop convenient single-serve formats, maintain non-GMO sourcing, and promote heart-health functional benefits.
Table 7: Country CAGR and Primary Growth Levers for the Oatmeal Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 6.3% | Expanding organic breakfast adoption, gourmet muesli popularity, and artisan bakery demand for whole-grain rolled flakes |
| Switzerland | 5.8% | Deep Birchermuesli breakfast heritage, premium organic grain preferences, and high consumer spending on wholesome muesli mixes |
| USA | 5.4% | Massive hot cereal consumer base, surging interest in overnight oats, and rapid innovation in high-protein single-serve oatmeal cups |
| Australia | 5.0% | Strong domestic oat agricultural harvest, high porridge consumption in southern states, and expanding oat milk ingredient processing |
| Brazil | 4.6% | Growing urban fitness culture, expanding supermarket cereal aisles, and rising consumer adoption of oat-based morning smoothies |
| UK | 4.2% | Mature traditional porridge culture, strong winter hot cereal demand, and intense private-label supermarket price competition |
Source: Future Market Insights analysis
France Oatmeal Market Outlook (2026 to 2036)
By 2036, France is projected to grow at 6.3% CAGR, driven by rising organic breakfast adoption and gourmet muesli consumption across urban centers. In January 2026, the French National Institute of Agricultural Research confirmed that organic oat cultivation expanded by 7.2% across western farming cooperatives [10]. French consumers replace traditional refined baguettes with fiber-rich rolled oats and artisan muesli blends. Parisian cafes feature warm oatmeal bowls topped with seasonal orchard fruits. However, consumer price sensitivity toward specialty organic brands and strict European pesticide residue regulations present challenges for importers. Processors overcome these hurdles by sourcing certified local French oats and highlighting regional provenance on cereal cartons.
Key takeaway:In France, expanding organic breakfast awareness and gourmet muesli culinary preferences propel the fastest growth among evaluated countries.
Switzerland Oatmeal Market Outlook (2026 to 2036)
Switzerland's oatmeal market is anticipated to advance at 5.8% CAGR over the assessment period, owing to its iconic Birchermuesli cultural heritage and high purchasing power for premium grains. In March 2025, the Swiss Federal Office for Agriculture reported a 5.6% increase in domestic demand for organic food-grade oat flakes [11]. Swiss households consume oats daily as cold soaked muesli blended with grated apples and cultured yogurt. Luxury alpine resorts feature organic oatmeal buffets for health-conscious tourists. However, elevated domestic processing labor costs and limited domestic cereal farming acreage necessitate grain imports. Swiss millers address this barrier by contracting long-term organic supplies from neighboring European partners while maintaining precision grain flaking standards.
Key takeaway:In Switzerland, deeply ingrained Birchermuesli traditions and premium organic grain preferences support steady high-value market expansion.
USA Oatmeal Market Outlook (2026 to 2036)
In the USA, oatmeal demand is predicted to advance at 5.4% CAGR through 2036, enabled by a massive hot cereal consumer base and rapid innovation in single-serve microwave cups. In April 2025, the American Bakers Association reported that commercial oat flour and whole-grain flake procurement rose by 5.1% across industrial bakeries [12]. American families view rolled oats as a cost-effective pantry staple for quick weekday breakfasts. Active adults prepare mason jar overnight oats enriched with whey protein. However, competition from ready-to-eat breakfast bars and oat crop yield fluctuations in the northern plains challenge brand profit margins. Food companies resolve this by introducing instant oatmeal cups with portable fold-out spoons.
Key takeaway:In the USA, entrenched family breakfast routines and portable single-serve packaging innovations sustain dependable category performance.
Australia Oatmeal Market Outlook (2026 to 2036)
Adoption of oatmeal in Australia is estimated to expand at 5.0% CAGR through 2036, supported by robust domestic oat harvests and expanding export milling operations. In May 2025, the Australian Bureau of Agricultural and Resource Economics and Sciences confirmed high-quality food oat production across Western Australia and Victoria [13]. Australian consumers enjoy traditional hot porridge during winter months and cold overnight oats during summer. In addition, domestic food processors mill premium rolled oats for export to neighboring Asian markets. However, periodic climate droughts and high interstate freight tariffs affect grain distribution costs. Agricultural cooperatives mitigate these hurdles by adopting drought-resilient oat seed cultivars and modernizing regional rail grain terminals.
Key takeaway:In Australia, abundant domestic grain agriculture and active breakfast cereal consumption support consistent category growth.
Brazil Oatmeal Market Outlook (2026 to 2036)
The Brazil oatmeal sector is projected to record 4.6% CAGR during the assessment period, reinforced by an expanding urban fitness culture and rising porridge consumption. In June 2025, the Brazilian Association of the Food Industry reported a 5.8% rise in retail sales of whole-grain oat cereals across southern supermarket chains [14]. Brazilian fitness enthusiasts blend fine oat flakes into protein shakes, acai bowls, and morning pancakes. Supermarkets expand private-label oat flake pouches at competitive prices. However, consumer unfamiliarity with hot cooked porridge in tropical northern regions and currency swings on imported oat groats limit broader category penetration. Processors overcome this barrier by marketing instant oat powders designed for cold beverage blending.
Key takeaway:In Brazil, growing health consciousness and versatile oat smoothie applications provide dependable long-term market growth.
UK Oatmeal Market Outlook (2026 to 2036)
UK oatmeal demand is forecast to rise at 4.2% CAGR over the forecast period, supported by mature traditional porridge habits and robust winter retail sales. In July 2025, the UK Department for Environment, Food and Rural Affairs confirmed steady domestic oat milling volumes across Scottish and English mills [15]. British households rely on traditional rolled oats and quick porridge pots during colder autumn and winter months. Major supermarket banners offer budget-friendly private-label porridge oats to support cost-conscious shoppers. However, high category maturity and aggressive grocery price competition squeeze brand operating margins. Manufacturers address this challenge by introducing functional porridge pots enriched with extra seeds, nuts, and added vitamins.
Key takeaway:In the UK, deep-seated traditional porridge breakfast culture provides a resilient baseline despite high market maturity.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the oatmeal market?
General Mills, Inc., Nestle S.A., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, and Danone S.A. are the significant market players in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational packaged food conglomerates, specialized grain milling corporations, and branded breakfast cereal manufacturers. Packaged food conglomerates distribute nationwide breakfast cereal brands through grocery retail networks. Specialized grain millers operate large-scale cleaning, dehulling, and flaking mills, supplying food processors with bulk oats. Branded breakfast specialists innovate in portable instant cups, organic muesli mixes, and savory oat formulations. Procurement executives choose oatmeal suppliers based on grain purity certifications, low foreign matter counts, uniform flake thickness, and competitive contract pricing.
- Global Packaged Food & Cereal Leaders: General Mills, Inc., Nestle S.A., and The Kraft Heinz Company market branded breakfast cereals and rolled oats across international supermarket banners.
- Diversified Culinary & Snack Conglomerates: Mondelez International, Inc., Conagra Brands, Inc., and Campbell Soup Company integrate whole-grain oats into baked snacks, granola bars, and wholesome meal lines.
- Specialty Nutrition & Breakfast Innovators: Danone S.A. and Hormel Foods Corporation formulate functional breakfast bowls, ready-to-eat oatmeal cups, and high-protein grain foods.
Competitive Benchmarking: Oatmeal Market
Table 8: Competitive Benchmarking for the Oatmeal Market (qualitative capability ratings), 2026
| Company | Large-Scale Milling Capacity | Branded Cereal Distribution | Organic & Non-GMO Sourcing | Portable Packaging Innovation |
|---|---|---|---|---|
| General Mills, Inc. | High | High | High | High |
| Nestle S.A. | High | High | High | High |
| The Kraft Heinz Company | High | High | Medium | Medium |
| Mondelez International, Inc. | High | High | High | High |
| Conagra Brands, Inc. | High | High | Medium | Medium |
| Campbell Soup Company | High | Medium | Medium | Low |
| Hormel Foods Corporation | Medium | Medium | Medium | High |
| Danone S.A. | Medium | High | High | High |
Scoring basis: Large-Scale Milling Capacity is High for multi-facility grain milling operations exceeding several hundred thousand tons annually. Branded Cereal Distribution is High when controlling prominent shelf space across international grocery retailers. Organic & Non-GMO Sourcing is High when featuring certified farm-traceable organic oat supplies. Portable Packaging Innovation is High for microwaveable instant cups and single-serve on-the-go formats. Medium indicates regional presence.
Key Developments in the Oatmeal Market
- In September 2026, General Mills, Inc. launched an enhanced high-protein instant oatmeal cup series featuring ten grams of complete plant protein and reduced sugar [16].
- In June 2026, Nestle S.A. partnered with sustainable grain agricultural cooperatives to scale regenerative oat farming across European supply chains [17].
- In April 2026, The Kraft Heinz Company expanded retail distribution of its fortified whole-grain hot cereal line across North American supermarket banners [18].
Key Players in the Oatmeal Market
Global Packaged Food & Cereal Leaders
General Mills, Inc.
Nestle S.A.
The Kraft Heinz Company
Diversified Culinary & Snack Conglomerates
Mondelez International, Inc.
Conagra Brands, Inc.
Campbell Soup Company
Specialty Nutrition & Breakfast Innovators
- Danone S.A.
- Hormel Foods Corporation
Oatmeal Market - Report Scope
Table 9: Report Scope for the Oatmeal Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and miller revenue from processed food-grade oatmeal products including rolled oats, steel-cut oats, quick oats, instant oatmeal packets, and oat groats sold for food consumption. Excludes raw unprocessed oats sold strictly for animal feed. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | France, Switzerland, USA, Australia, Brazil, UK, and additional countries in the full report |
| Key Companies Covered | General Mills, Inc., Nestle S.A., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, Danone S.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Oatmeal Market - Research Methodology
Table 10: Research Methodology for the Oatmeal Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with grain milling plant managers, cereal food scientists, retail grocery category buyers, agricultural cooperative directors, and supply chain logistics specialists to validate milling yields, dehulling costs, wholesale contract pricing, and consumer breakfast purchasing patterns. |
| Secondary Research | Secondary research included analysis of national agricultural ministry datasets, international grain trade statistics, corporate annual filings, cereal science journals, and publicly available food regulatory standards. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up models evaluating raw oat harvest volumes, food-grade milling capacity utilization, and supermarket retail point-of-sale scanner data. |
| Data Triangulation and Validation | Data is validated against macroeconomic consumer food spending indicators, global cereal trade flows, retail scanner velocity, and historical industry benchmarks to ensure high precision without double counting industrial animal feed oats. |
Oatmeal Market by Segments
Oatmeal Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Oatmeal Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Oatmeal Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Oatmeal Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture Economic Research Service. (2025, January 16). Feed Grains Yearbook: Food, Seed, and Industrial Uses of Oats. USDA Publications.
- [2] U.S. Department of Agriculture Foreign Agricultural Service. (2025, February 18). Grain: World Markets and Trade. USDA FAS Circulars. https://www.usda.gov
- [3] Food and Agriculture Organization. (2025, March 20). Global Cereal Supply and Demand Brief: Coarse Grains and Oats. FAO Publications. https://www.fao.org
- [4] U.S. Food and Drug Administration. (2025, May 22). Health Claims: Soluble Fiber from Certain Foods and Risk of Coronary Heart Disease. FDA CFR Title 21. https://www.fda.gov
- [5] European Food Safety Authority. (2025, June 16). Scientific Opinion on the Substantiation of Health Claims Related to Oat Beta-Glucan and Blood Cholesterol. EFSA Journal. https://www.efsa.europa.eu
- [6] North American Millers' Association. (2025, August 14). Oat Milling Quality Standards and Processing Guidelines. NAMA Technical Bulletins.
- [7] American Association of Cereal Chemists International. (2025, September 22). Advances in Oat Processing Technology and Hydrothermal Deactivation of Lipases. Cereal Chemistry.
- [8] International Grains Council. (2025, October 18). Grain Market Report: Global Oats Supply and Price Trends. IGC Publications.
- [9] Whole Grains Council. (2025, November 12). Consumer Insights on Whole Grain Intake and Breakfast Cereal Habits. Oldways Whole Grains Council.
- [10] French National Institute for Agriculture, Food, and Environment. (2026, January 16). Diversification of Organic Cereal Crops in France. INRAE Statistical Releases.
- [11] Swiss Federal Office for Agriculture. (2025, March 25). Agrarmärkte: Cereal Production and Organic Consumption in Switzerland. BLW Reports.
- [12] American Bakers Association. (2025, April 22). Baking Industry Grain Procurement Trends and Whole Grain Usage. ABA Market Data.
- [13] Australian Bureau of Agricultural and Resource Economics and Sciences. (2025, May 28). Australian Crop Report: Oats Production and Export Outlook. ABARES Reports.
- [14] Brazilian Association of the Food Industry. (2025, June 18). Panorama of the Cereal and Breakfast Food Market in Brazil. ABIA Annual Data.
- [15] UK Department for Environment, Food and Rural Affairs. (2025, July 24). Cereal Usage by UK Millers and Animal Feed Manufacturers. Defra Official Statistics.
- [16] General Mills, Inc. (2026, September 10). High-Protein Functional Hot Cereal Cup Innovation Announcement. Corporate Newsroom.
- [17] Nestle S.A. (2026, June 18). Regenerative Agriculture Partnership for Sustainable European Oat Supply. Nestle Media Releases.
- [18] The Kraft Heinz Company. (2026, April 14). Whole-Grain Breakfast Cereal Distribution Expansion. Kraft Heinz News.
- [19] Mondelez International, Inc. (2025, October 24). Sustainable Grain Sourcing and Whole-Grain Snack Innovation. Mondelez News.
- [20] Conagra Brands, Inc. (2026, January 14). Portfolio Optimization in Whole-Grain Breakfast and Pantry Staples. Conagra Investor Center.
- [21] Hormel Foods Corporation. (2025, July 16). On-the-Go Breakfast and Functional Nutrition Strategy. Hormel News.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the oatmeal market in 2026 and what is forecast for 2036?
- Which morning dietary habits support steady demand for oatmeal products?
- Why does standard commercial grade lead the product type / grade category?
- Why does fresh / ambient packaged lead the processing state category globally?
- How do growth rates prominently differ across France, Switzerland, the USA, and the UK?
- Which leading food companies supply branded rolled oats and instant oatmeal today?
- What limits raw grain supply stability or milling expansion in the oatmeal market?
- What should grocery merchandisers evaluate deeply before selecting oatmeal suppliers?
Frequently Asked Questions
How big is the oatmeal market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global oatmeal market will reach USD 11.2 Billion in 2026. The market is projected to reach USD 18.6 Billion by 2036, driven by rising consumer focus on cardiovascular wellness and routine morning breakfast habits.
What is the CAGR for the oatmeal market from 2026 to 2036?
As per FMI, the market is projected to expand at a 5.2% CAGR over the assessment period. Growth is supported by ongoing product formulation into portable microwaveable oatmeal cups and organic rolled oats.
Which product type / grade segment leads the oatmeal market?
Future Market Insights projects that standard commercial grade will hold 48.1% share in 2026. The segment benefits from accessible household pricing, broad culinary versatility, and long-standing consumer familiarity.
Which processing state segment leads the oatmeal market?
Grain processing research indicates that fresh / ambient packaged will account for 54.5% share in 2026. Demand is supported by hydrothermal steam enzyme deactivation, ambient warehouse stability, and simplified global shipping.
Which country has a notable growth outlook during the assessment period?
FMI finds that France is projected to register a 6.3% CAGR from 2026 to 2036. High market growth is supported by expanding organic breakfast adoption, gourmet muesli popularity, and artisan bakery demand for whole-grain rolled flakes.
Who are the key players in the market?
Key participants include General Mills, Inc., Nestle S.A., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, and Danone S.A. Leading market participants focus on hydrothermal steam stabilization, organic grain sourcing, and single-serve microwaveable cup innovations.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- General Mills, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle S.A.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Campbell Soup Company
- Hormel Foods Corporation
- Danone S.A.
- General Mills, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


