

- Market Size (2026)
- USD 18392.2 Mn
- Forecast (2036)
- USD 31416.7 Mn
- CAGR (2026 to 2036)
- 5.5%
How big is Polyamide 6 Market in 2026?
Sales of polyamide 6 are projected to expand at a 5.5% CAGR between 2026 and 2036. Market size grows from USD 17,433.4 million in 2025 to USD 18,392.2 million in 2026 and is projected to reach USD 31,416.7 million by 2036.
Polyamide 6 market size stood at USD 17,433.4 million in 2025, is estimated at USD 18,392.2 million in 2026 and is projected to reach USD 31,416.7 million by 2036. Sales of polyamide 6 will grow at a CAGR of 5.5% from 2026 to 2036, according to FMI.
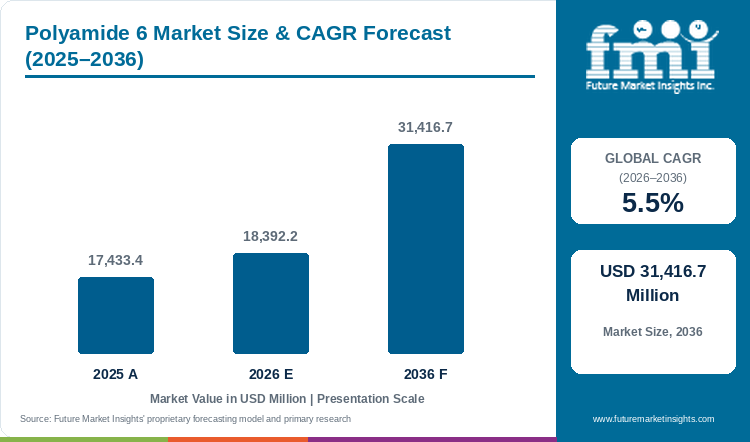
Overcapacity is the main challenge in the chain. Chinese caprolactam producers agreed a 20% production cut after an industry meeting on 5 November 2025, aimed at overcapacity and low prices[1].
A cut of this size shows producers will protect margins before adding volume. Prices for converters will firm, and textile and engineering plastics buyers will look for supply contracts to fix costs. Multi-year contracts will protect converters. Buyers will plan orders around the cut.
Opportunity for producers comes from recycled and bio-based grades. Brands in apparel and carpets will set recycled content targets, and recycled yarn and compounds will gain share. Demand for these grades will keep prices steadier than commodity resin. Producers with downstream yarn and compound capacity will keep more of the margin as supply and demand rebalance, and sales of polyamide 6 will grow with that balance through 2036. Textile mills and carpet makers will remain the largest buyers of the resin.
Key Market Trends & Insights
- By type, polyamide 6 fibre led the market with a share of 61.7% in 2026, ahead of polyamide 6 resin at 38.3%, supported by strength-to-weight ratio, dyeability and moisture management.
- By application, textiles accounted for 43.9% of sales in 2026, ahead of transportation at 22.3% and electrical and electronics at 14.6%. Carpet is the largest end-use for nylon 6 in North America, AdvanSix reports.[2]
Regional Highlights
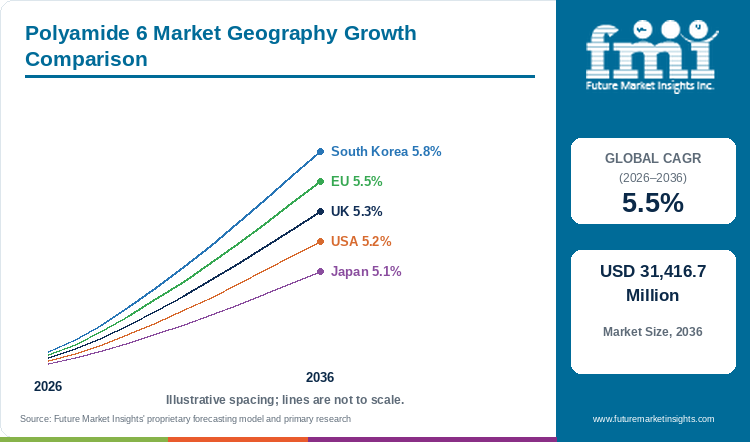
- Fastest-growing profiled country: South Korea (5.8% CAGR, 2026 to 2036).
- By country: the EU (5.5%) and the UK (5.3%) follow, with the USA at 5.2% and Japan recording the lowest profiled CAGR at 5.1%.
- Ten major South Korean petrochemical firms agreed to cut naphtha-cracking capacity by 2.7 million to 3.7 million tonnes a year, Hydrocarbon Processing reported in August 2025.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Polyamide 6 Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 17,433.4 million |
| Estimated Market Size in 2026 | USD 18,392.2 million |
| Projected Market Size by 2036 | USD 31,416.7 million |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 13,024.5 million |
| Market Expansion Multiple | 1.7x |
Demand for polyamide 6 follows a feedstock chain that runs from benzene to caprolactam.[4] As per FMI, caprolactam is the only commercially viable production route and is petroleum-based, which exposes supply to oil price swings and geopolitical shocks. AdvanSix calls caprolactam the key monomer used in the production of nylon 6 resin.[2] The adjacent nylon-6 and nylon-66 market also draws on caprolactam, and investment in caprolactam and adipic acid supports capacity there. Rising imports of polyamide resin from non-EU countries were among the reasons cited for the Domo insolvency in Germany.[5] Producers with owned caprolactam units carry less margin exposure than converters buying on the open market.
Caprolactam Supply and Backward Integration
Backward integration potential in the polyamide 6 market is not set by sales volume alone. Owned caprolactam units, offtake contracts and benzene access are likely to decide which producers keep steady supply. Company filings show integration advancing in the United States and China, and capacity leaving Germany, Thailand and Japan.
Table 2: Caprolactam Supply and Integration Indicators for the Polyamide 6 Market (tons, percentage and EUR values), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| China caprolactam output cut | 20% cut agreed after the 5 November 2025 meeting | The cut aims to address overcapacity and low prices. | [1] |
| AdvanSix Hopewell, 2025 | About 53% of caprolactam shipped to the Chesterfield plant | Chesterfield polymerises the caprolactam into nylon 6 resin. | [2] |
| Caprolactam utilisation, 2025 | Approximately 74% globally; over 80% in the United States | AdvanSix reports both rates for 2025. | [2] |
| China Risun caprolactam chain | 810,000 tons a year; 50,000 ton HMDA plant | The chain links benzene, caprolactam and hexamethylenediamine. | [4] |
| UBE Thailand and Japan | Thai reductions completed by March 2026; Japanese reductions in March 2027 and March 2028 | Production reductions are under way at two Asian locations. | [6] |
| Envalior price increase, March 2026 | EUR 550 a tonne on caprolactam and PA6 base resins | Raw material costs are passed on to converters. | [7] |
| Leuna-Polyamid, September 2026 | No binding offers; controlled shutdown due in early October | The plants were formed in spring 2026 from Domo Caproleuna assets. | [8] |
Analyst Perspective
“Producers with owned caprolactam capacity are expected to hold the steadiest supply and margins through 2036. European plant closures and Chinese output cuts will keep non-integrated fibre and resin makers exposed to feedstock cost swings.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the polyamide 6 market segmented?
The polyamide 6 market is segmented into type and application, and region. In 2026, polyamide 6 fibre holds 61.7% of type sales and textiles hold 43.9% of application sales.
By type: polyamide 6 fibre and polyamide 6 resin.
By application: textiles, transportation, electrical and electronics, industrial, and other.
By region: North America, Latin America, Europe, Asia Pacific, and Middle East and Africa.
Why does polyamide 6 fibre lead type sales?
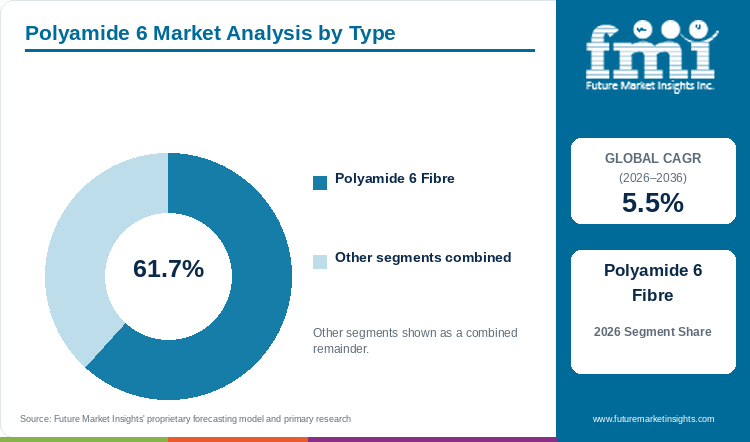
Polyamide 6 fibre accounts for 61.7% of type sales in 2026, ahead of polyamide 6 resin at 38.3%, supported by strength-to-weight ratio, dyeability and moisture management.
Table 3: Type Share for the Polyamide 6 Market (percentage share), 2026
| Type | Estimated Share (2026) |
|---|---|
| Polyamide 6 Fibre | 61.7% |
| Polyamide 6 Resin | 38.3% |
| Total | 100.0% |
Table 4: Type Leadership and Market Growth for the Polyamide 6 Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | Polyamide 6 Fibre |
Sales of polyamide 6 fibre lead the type split across clothing, technical textiles, hosiery, home furnishings and carpets. In the FMI report, fibre grades account for 61.7% of type sales in 2026. Polyamide 6 resin serves automotive parts, industrial equipment, electronic housings and packaging materials, and overlaps with the automotive composites market, which lists polyamide resins for engine components and heat resistant parts. Chinese polyamide yarn imports into the EU reached 21,183 tonnes in the investigation period, and duties of 60% to 67.6% took effect on 29 July 2026.[9] Duties and plant closures are reshaping yarn trade in Europe.
- Fibre grades account for 61.7% of type sales in 2026, supported by strength-to-weight ratio and dyeability.
- Customers use nylon 6 to produce fibers, filaments, engineered plastics and films, and about 7.7 million metric tons of nylon 6 resin were produced and consumed globally in 2025.[2]
Why do textiles lead demand by application?
Textiles are set to account for 43.9% of application sales in 2026, ahead of transportation at 22.3%, with use spanning clothing, technical textiles, hosiery, home furnishings and carpets.
Table 5: Application Share for the Polyamide 6 Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Textiles | 43.9% |
| Transportation | 22.3% |
| Electrical and Electronics | 14.6% |
| Industrial | 11.4% |
| Other | 7.8% |
| Total | 100.0% |
Adoption of polyamide 6 is highest in textiles, which hold 43.9% of application sales in 2026 as per FMI estimates. Transportation follows at 22.3%, with electrical and electronics at 14.6%, industrial at 11.4% and other uses at 7.8%. Polyester fibre from the polyethylene terephthalate market is another synthetic fibre route, as that market lists polyester fibre production as a significant driver. Carpet is the largest end-use for nylon 6 in North America, AdvanSix reports.[2] Sportswear and carpets drive textile demand.
- Clothing, hosiery and home furnishing uses drive textile sales, which reach 43.9% of application sales in 2026.
- Carpet and sportswear uses are expected to sustain textile leadership through the forecast period.
What are the drivers, restraints, and opportunities in the polyamide 6 market?
In the polyamide 6 market, textile and engineering use drives sales, caprolactam feedstock exposure and the loss of European plants constrain supply, and backward integration into caprolactam opens the principal commercial opportunity.
- Driver: Textile use and automotive light weighting support sales, and integrated caprolactam chains secure supply.
- Restraint: Petroleum-based caprolactam exposes supply to oil price swings, and plant closures reduce regional output.
- Opportunity: Backward integration into caprolactam, chemical recycling and bio-based caprolactam synthesis expand secure supply.
Integrated Producers Secure Supply
Integrated producers hold the steadier position when feedstock tightens. AdvanSix sent about 53% of the caprolactam made at Hopewell to the Chesterfield resin plant in 2025.[2] Caprolactam sales were USD 271.4 million in 2025, against USD 276.3 million in 2024.[10] In February 2026, AdvanSix described cyclical trough conditions, and the chief executive said recent industry announcements pointing to capacity rationalization should lead to more favourable supply and demand conditions over time.[10] Continued rationalization favours producers that make and use caprolactam in-house.
Feedstock Swings and Plant Closures Limit Supply
Weak demand, high energy prices and resin imports from non-EU countries were cited when three German Domo Chemicals companies filed for insolvency, CHEManager reported on 30 December 2025.[5] Plasticker reported on 9 September 2026 that Leuna-Polyamid, formed in spring 2026 from Domo Caproleuna assets, received no binding offers by the end-August deadline.[8] A controlled shutdown is due to begin in early October.[8] Envalior passed raw material increases to buyers with a EUR 550 a tonne price rise in March 2026.[7] Cost swings and closures remain a feature of the early forecast years.
Capacity Exits Open a Path for Backward Integration
Capacity exits in Europe and Asia leave room for producers that add caprolactam units or lock in offtake. UBE completed the Thai reductions by March 2026 and scheduled Japanese reductions for March 2027 and March 2028.[6] China Risun is extending the chain from benzene to caprolactam to hexamethylenediamine, with a 50,000 ton plant started on 4 May 2026.[4] Electrical and electronics is an application group of polyamide 6 and links demand to the automotive electronics market, which covers electronic control units and sensors. Joint ventures between fibre makers and caprolactam producers would widen supply security through 2036.
Which country CAGRs are profiled in the polyamide 6 market?
Table 6: Country CAGR Comparison for the Polyamide 6 Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| South Korea | 5.8% |
| EU | 5.5% |
| UK | 5.3% |
| USA | 5.2% |
| Japan | 5.1% |
How do country-level CAGRs compare in the polyamide 6 market?
Growth across the five profiled countries differs owing to feedstock position, trade measures and end-use mix. As per the analysis from FMI, South Korea is projected at 5.8% CAGR from 2026 to 2036, followed by the EU at 5.5% and the UK at 5.3%. The USA is estimated at 5.2%, and Japan is projected at 5.1%. Caprolactam access, yarn trade measures and end-use mix separate the country growth rates.
- South Korea pairs caprolactam investment for export competitiveness with naphtha-cracker capacity cuts.
- The EU combines recycling and bio-based production goals with plant closures and duties on Chinese yarn.
- UK sales draw on sustainable nylon-6 with renewable caprolactam, carpets, performance textiles and fasteners.
- US growth draws on under-the-hood parts, cable insulation and structural parts, with caprolactam utilisation above 80%.
- Japan links connectors, gears, hosiery and innerwear to scheduled reductions at UBE.
Full report country CAGRs cover: North America; Latin America; Europe; Asia Pacific; Middle East and Africa.
Country-wise Analysis
South Korea Polyamide 6 Market Outlook (2026 to 2036)
Korean producers are trimming the cracker base of the domestic petrochemical industry. Ten major petrochemical firms agreed to cut naphtha-cracking capacity by 2.7 million to 3.7 million tonnes a year, Hydrocarbon Processing reported in August 2025.[3] Companies were to submit restructuring outlines by the end of 2025.[3] FMI names caprolactam investment for export competitiveness as the lever for the country, which is projected to lead the profiled markets at 5.8% CAGR from 2026 to 2036.
Key takeaway: South Korea leads the profiled CAGRs at 5.8% through 2036, and cracker cuts of 2.7 million to 3.7 million tonnes a year are under way.
EU Polyamide 6 Market Outlook (2026 to 2036)
Plant closures and new duties shape the European position. CHEManager reported on 30 December 2025 that three German Domo Chemicals companies filed for insolvency, citing weak demand, high energy prices and polyamide resin imports from non-EU countries.[5] Leuna-Polyamid, formed in spring 2026 from Domo Caproleuna assets, was due to begin a controlled shutdown in early October 2026 after no binding offers arrived.[8] Duties of 60% to 67.6% on Chinese polyamide yarn took effect on 29 July 2026.[9] Envalior raised caprolactam and PA6 resin prices by EUR 550 a tonne in March 2026 for Europe, the Middle East, Africa and the Americas.[7] Closed-loop recycling and bio-based production under EU Green Deal policies drive growth, and the EU is projected at 5.5% CAGR from 2026 to 2036.
Key takeaway: EU growth of 5.5% is shaped by German closures on the supply side and duties on Chinese yarn on the import side.
UK Polyamide 6 Market Outlook (2026 to 2036)
Use of polyamide 6 in the UK is tied to carpets, performance textiles and fasteners. Sustainable nylon-6 made with renewable caprolactam leads UK growth, and the country is projected at 5.3% CAGR from 2026 to 2036. Duties of 60% to 67.6% on Chinese polyamide yarn took effect on 29 July 2026 and apply to EU imports.[9] FMI links UK sales to sportswear and automotive supply chains and to tightening environmental rules.
Key takeaway: UK growth of 5.3% draws on carpet, performance textile and fastener uses.
USA Polyamide 6 Market Outlook (2026 to 2036)
AdvanSix reported caprolactam utilisation of over 80% in the United States in 2025, against approximately 74% globally.[2] Carpet is the largest end-use for nylon 6 in North America.[2] The company described cyclical trough conditions for nylon in February 2026 and reported 2025 caprolactam sales of USD 271.4 million.[10] Under-the-hood components, cable insulation and structural parts anchor US demand, and the USA is projected at 5.2% CAGR from 2026 to 2036. AdvanSix makes caprolactam at Hopewell, Virginia, and nylon 6 resin at Chesterfield, Virginia.[2]
Key takeaway: US growth of 5.2% is anchored by an integrated domestic chain and carpet use.
Japan Polyamide 6 Market Outlook (2026 to 2036)
UBE reported in the annual securities report filed on 18 June 2026 that the reduction or shutdown of ammonia, caprolactam and nylon polymer production in Thailand was completed by March 2026, with Japanese reductions scheduled for March 2027 and March 2028.[6] The Spanish subsidiary of UBE produces caprolactam and nylon polymers.[6] Ube holds an estimated 7% to 11% share of the polyamide 6 market. Japan is projected at 5.1% CAGR from 2026 to 2036, the lowest of the five profiled countries, with connectors, gears, hosiery and innerwear among the main uses.
Key takeaway: Japan records the lowest profiled CAGR at 5.1%, and scheduled UBE reductions in 2027 and 2028 mark the supply change to watch.
Who are the notable companies in the polyamide 6 market?
BASF, AdvanSix, DSM Engineering Materials, Lanxess, Ube, Domo Chemicals, Toray, Asahi Kasei, RadiciGroup, Grupa Azoty, Formosa Chemicals & Fibre, Shenma Industrial, EMS-Chemie, Envalior, and China Risun are notable companies profiled in this market.
BASF leads polyamide 6 company shares at 20% to 24%, followed by AdvanSix at 15% to 19%, DSM Engineering Materials at 12% to 16%, Lanxess at 9% to 13%, Ube at 7% to 11% and Domo Chemicals at 6% to 10%, as per FMI. Other companies together hold 18% to 26%. Companies differ by caprolactam position. AdvanSix makes caprolactam and polymerises a share into nylon 6 resin, Ube is reducing production in Thailand and Japan, and the German Domo plants are moving towards shutdown. Producers with secure caprolactam have the clearest route to wider reach, and others lean towards contracted supply.
- Leading share-estimate producers: BASF, AdvanSix, DSM Engineering Materials, Lanxess, Ube, and Domo Chemicals.
- Other key producers: Toray, Asahi Kasei, RadiciGroup, Grupa Azoty, Formosa Chemicals & Fibre, Shenma Industrial, and EMS-Chemie.
- Producers with documented caprolactam or polyamide 6 activity in 2025 and 2026: Envalior, China Risun, AdvanSix, Ube, and Domo Chemicals.
Competitive Benchmarking: Polyamide 6 Market
Table 7: Competitive Benchmarking for the Polyamide 6 Market (qualitative documentation ratings), 2026
| Company | Caprolactam | Polymer | Activity | Disclosure |
|---|---|---|---|---|
| AdvanSix | High | High | Medium | High |
| Ube | Medium | Medium | High | High |
| Envalior | Medium | High | Medium | Medium |
| China Risun | High | Low | High | Medium |
| Domo Chemicals | Medium | Medium | High | Medium |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Polyamide 6 Market
- In September 2026, plasticker reported that Leuna-Polyamid received no binding offers by the end-August deadline, with a controlled shutdown due to begin in early October.[8]
- In August 2026, Textalks reported that EU duties of 60% to 67.6% on Chinese polyamide yarn had been in effect since 29 July 2026.[9]
- In May 2026, China Risun started a 50,000 ton caprolactam-to-hexamethylenediamine plant at Yuncheng.[4]
- In March 2026, Envalior announced a price increase of EUR 550 a tonne on caprolactam, Akulon and Durethan PA6 base resins and PA6 film, extrusion and copolymer grades.[7]
Key Players in the Polyamide 6 Market
Leading Share-estimate Producers
- BASF SE
- AdvanSix Inc.
- DSM Engineering Materials
- Lanxess AG
- Ube Corporation
- Domo Chemicals
Other Key Producers
- Toray Industries
- Asahi Kasei
- RadiciGroup
- Grupa Azoty
- Formosa Chemicals & Fibre
- Shenma Industrial
- EMS-Chemie Holding
Producers with Documented 2025 to 2026 Activity
- Envalior
- China Risun Group
Polyamide 6 Market - Report Scope
Table 8: Report Scope for the Polyamide 6 Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type; application; region |
| Quantitative units | USD million |
| Market definition | Polyamide 6 (nylon-6) market covering polyamide 6 fibre and polyamide 6 resin, tracked by application in transportation, electrical and electronics, textiles, industrial and other uses. |
| Regions covered | North America; Latin America; Europe; Asia Pacific; Middle East and Africa |
| Countries covered | South Korea; EU; UK; USA; Japan |
| Key companies profiled | BASF, AdvanSix, DSM Engineering Materials, Lanxess, Ube, Domo Chemicals, Toray, Asahi Kasei, RadiciGroup, Grupa Azoty, Formosa Chemicals & Fibre, Shenma Industrial, EMS-Chemie, Envalior, China Risun |
| Forecast period | 2026 to 2036 |
Polyamide 6 Market - Research Methodology
Table 9: Research Methodology for the Polyamide 6 Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Market sizes, segment shares, country CAGRs and company shares come from the market model. Supply chain facts come from company filings, press releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company filings, official press releases, regulation texts and trade press on caprolactam, nylon 6 and polyamide yarn. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 17,433.4 million and the 5.5% CAGR. |
| Data Validation | Plant, capacity and closure facts are cross-checked across company filings and trade press before use. |
Polyamide 6 Market by Segments
Polyamide 6 Market segmented by Type:
- Polyamide 6 Fibre
- Polyamide 6 Resin
Polyamide 6 Market segmented by Application:
- Textiles
- Transportation
- Electrical and Electronics
- Industrial
- Other
Polyamide 6 Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Europe
- Germany
- Italy
- France
- United Kingdom
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Thiam Hock Tan and Ian Young, Chemical Week. (2025, December 12). China's caprolactam producers agree to production cut. https://chemweek.mydigitalpublication.com/articles/china-s-caprolactam-producers-agree-to-production-cut
- [2] AdvanSix Inc. (SEC Form 10-K). (2026). AdvanSix Annual Report on Form 10-K for the fiscal year ended December 31, 2025. https://www.sec.gov/Archives/edgar/data/1673985/000167398526000008/asix-20251231.htm
- [3] Hydrocarbon Processing. (2025, August 28). South Korea Petrochemical Overhaul Likely to Shut Small, Stand-Alone Naphtha Crackers. https://www.hydrocarbonprocessing.com/news/2025/08/south-korea-petrochemical-overhaul-likely-to-shut-small-stand-alone-naphtha-crackers/
- [4] China Risun Group (ACN Newswire, via Finanznachrichten). (2026, May 4). China Risun Group breaking through chokepoint technology, China Risun's hexamethylenediamine plant commenced production. https://www.finanznachrichten.de/nachrichten-2026-05/68380275-china-risun-group-breaking-through-chokepoint-technology-china-risun-s-hexamethylenediamine-plant-commenced-production-011.htm
- [5] CHEManager. (2025, December 30). DOMO Chemicals files for insolvency for German companies. https://www.chemanager-online.com/en/news/domo-chemicals-files-for-insolvency-for-german-companies
- [6] UBE Corporation (EDINET filing). (2026, June 18). Annual Securities Report (fiscal year ended March 31, 2026). https://disclosure2dl.edinet-fsa.go.jp/searchdocument/pdf/S100YD42.pdf
- [7] Envalior. (2026, March 25). Envalior announces price increase for Caprolactam, Akulon and Durethan PA6 base resins, PA6 film extrusion, PA6 copolymer grades. https://www.envalior.com/en-us/insights/press-release/envalior-announces-price-increase-for-caprolactam-akulon-and-durethan-pa6-base-resins-pa6-film-extrusion-pa6-copolymer-grades
- [8] plasticker. (2026, September 9). Leuna-Polyamid to Shut Down Plants After Investor Search Fails. https://plasticker.de/news/shownews_en.php?nr=49311
- [9] Textalks. (2026, August 4). EU imposes duties of up to 67.6% on Chinese polyamide yarn. https://textalks.com/eu-imposes-duties-of-up-to-67-6-on-chinese-polyamide-yarn/
- [10] AdvanSix Inc. (Business Wire). (2026, February 19). AdvanSix Reports Fourth Quarter and Full Year 2025 Results. https://www.businesswire.com/news/home/20260219417617/en
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the polyamide 6 market during 2026?
- What market size is projected by 2036?
- Which type holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the polyamide 6 market expected in 2026?
Future Market Insights estimates the polyamide 6 market size at USD 18,392.2 million in 2026. The market is projected to reach USD 31,416.7 million by 2036, reflecting steady growth over the forecast period.
What CAGR is projected for the polyamide 6 market through 2036?
As per FMI analysis, polyamide 6 sales are projected to grow at a 5.5% CAGR from 2026 to 2036. Textile use and automotive light weighting support the outlook.
Which type holds a notable market share in 2026?
Polyamide 6 fibre accounts for 61.7% of type sales in 2026. Strength-to-weight ratio, dyeability and moisture management support the notable share.
Which application holds a notable market share in 2026?
Textiles account for 43.9% of application sales in 2026. Use spans clothing, technical textiles, hosiery, home furnishings and carpets.
Which country has a notable expansion outlook through 2036?
South Korea is projected to record the fastest growth at 5.8% CAGR from 2026 to 2036, according to FMI. Caprolactam investment for export competitiveness supports growth.
Who are the key companies in the polyamide 6 market?
Notable companies include BASF, AdvanSix, DSM Engineering Materials, Lanxess, Ube, Domo Chemicals, Toray, Asahi Kasei, RadiciGroup, Grupa Azoty, Formosa Chemicals & Fibre, Shenma Industrial, and EMS-Chemie.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Type, 2026 to 2036
- Polyamide 6 Fibre
- Polyamide 6 Resin
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Textiles
- Transportation
- Electrical and Electronics
- Industrial
- Other
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Application
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- Italy
- France
- United Kingdom
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- By Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- EU
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- AdvanSix
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ube
- Envalior
- China Risun
- Domo Chemicals
- BASF SE
- DSM Engineering Materials
- Lanxess AG
- Ube Corporation
- Toray Industries
- Asahi Kasei
- RadiciGroup
- Grupa Azoty
- Formosa Chemicals & Fibre
- Shenma Industrial
- EMS-Chemie Holding
- China Risun Group
- AdvanSix
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


