
- Market Size (2026)
- USD 19.1 Bn
- Forecast (2036)
- USD 49.1 Bn
- CAGR (2026 to 2036)
- 9.9%
How big is Polysilicon Market in 2026?
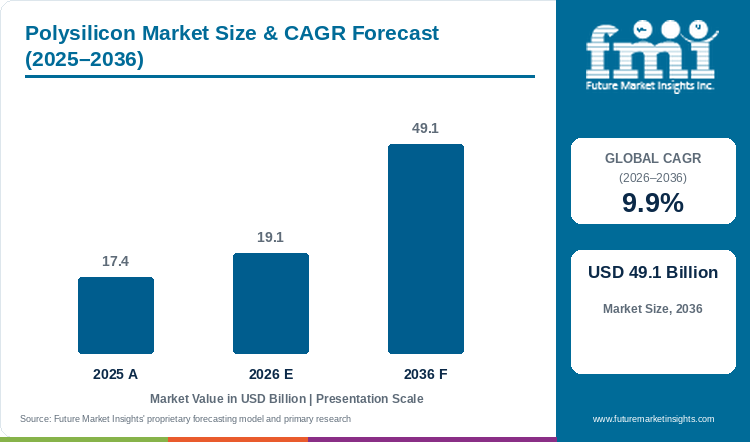
The polysilicon market is estimated at USD 17.4 billion in 2025 and is forecast to reach USD 19.1 billion in 2026. Polysilicon sales are projected to grow at a CAGR of 9.9% from 2026 to 2036 and reach USD 49.1 billion by 2036.
Growth of the polysilicon market, at a 9.9% CAGR projected for the decade to 2036, will raise sales from an estimated USD 17.4 billion in 2025 to an expected USD 19.1 billion in 2026 and USD 49.1 billion by 2036. Trade rules are splitting supply by origin, as importing countries set price floors on silicon products. A United States proclamation signed on 6 August 2026 sets a 15% tariff on polysilicon derivatives and a USD 21 per kg minimum import price for polysilicon from 4 December 2026. Ingot, wafer and cell plants in the United States will buy more domestic and tariff-exempt material, giving producers with American plants more room on price.
Chip fabs rank hottest on a purchase-heat map of polysilicon buyers, since chipmakers order electronics-grade polysilicon on multi-year contracts at the highest price per kilogram. Solar cell and module makers account for an expected 86% of 2026 end use sales, and price-led bidding keeps that large group warm. Silane and research buyers, about 2%, stay cool. Wacker said semiconductor polysilicon volumes kept rising in Q2 2026, and lower solar silicon prices cut segment EBITDA to EUR 11 million. FMI's base case has producers turning polysilicon market shifts into growth opportunities by moving capacity to electronics-grade and n-type material, which those buyers contract at steadier prices.
Key Market Trends & Insights
- Solar grade polysilicon heads grade sales with a projected 79% in 2026, and electronics grade is likely to account for the remaining 21%. A 15% United States tariff on polysilicon derivatives applies from 4 December 2026.
- Module and cell plants keep solar PV cells and modules at an expected 86% of 2026 end use sales, against 12% for semiconductors and about 2% for silane and research uses.
- Demand for Siemens process material gives that route an estimated 72% of production technology sales in 2026, with fluidized bed reactor output at 22% and upgraded metallurgical-grade silicon at 6%. Output at Daqo New Energy came in at 43,675 MT in the June 2026 quarter, at an average cash cost of USD 4.57 per kg.
Regional Highlights
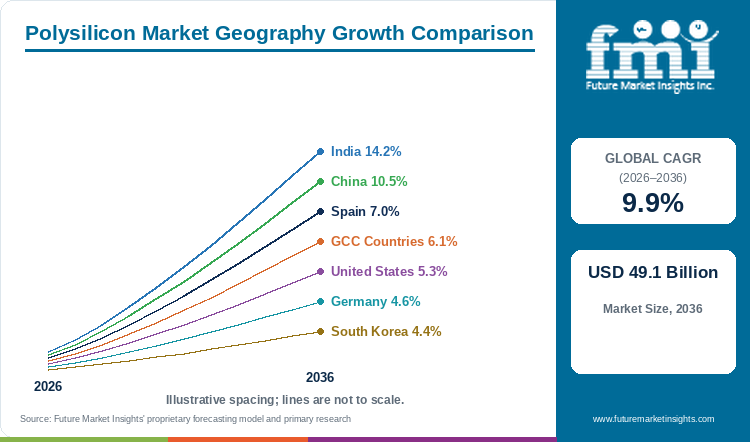
- Ingot and wafer lines built for domestic content rules carry India to a 14.2% CAGR, the highest rate among the seven profiled countries.
- Integrated wafer and module output keeps China second, at 10.5%. Solar build-outs in Spain and the Gulf and a price floor in the United States give those three rates of 5.3% to 7%. Rooftop solar and chip fabs hold Germany at 4.6%, and offshore production leaves South Korea last in the country ranking at 4.4%.
- Spain added 8.8 GW of solar PV in 2025, excluding self-consumption, and solar provided 18.4% of electricity generation, Red Eléctrica reported.
Market Size & Forecast
Table 1: Market Size and Forecast for the Polysilicon Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 17.4 billion |
| Estimated Market Size in 2026 | USD 19.1 billion |
| Projected Market Size by 2036 | USD 49.1 billion |
| CAGR, 2026 to 2036 | 9.9% |
| Added Revenue, 2026 to 2036 | USD 30 billion |
| Market Expansion Multiple | 2.6x |
Polysilicon orders follow wafer plant utilisation, and wafer makers cut or add purchases within weeks of a change in module prices. At an average selling price of USD 4.04 per kg, below the USD 5.95 average production cost, Daqo New Energy sold 15,190 MT in the June 2026 quarter. Tongwei shipped 155,300 tons of high-purity polysilicon over January to June 2026 and reported a net loss of CNY 5.12 billion. Demand for modules carries most of the forecast. Each new gigawatt of module output pulls more polysilicon, and the solar cells and module market is forecast to increase at a 7.7% CAGR as utility tenders and rooftop programmes expand. FMI data indicate that roughly USD 30 billion of extra polysilicon sales will be added between 2026 and 2036, so the 2036 polysilicon market is projected at about 2.6 times the size of 2026. Excess stock is the near-term risk, as inventories near 500,000 to 600,000 MT can delay any price recovery, and producers selling below cash cost show the changing economics of demand for solar grade.
Price Floors, Capacity Exits and Chip-Grade Demand
Prices below cash cost are pushing weak producers out. Daqo New Energy expects high-cost and cash-constrained producers to exit over six to 18 months and new energy-consumption standards of 6.3 kgce per kg to force out inefficient capacity by 1 January 2027. The China Nonferrous Metals Industry Association kept the regular polysilicon price assessment suspended as of 27 August 2026. Capacity closures will tighten supply, and survivors with low power costs will hold more of the solar grade volume.
Demand for chip grade is the steadier half of the polysilicon market. Global silicon wafer shipments rose 7.4% to 3,573 million square inches in Q2 2026, SEMI reported, on rising AI-related orders beyond advanced logic and memory. OCI TerraSus and Tokuyama are building a semiconductor-grade polysilicon plant in Bintulu, Sarawak, with an IFC loan of up to USD 125 million. More wafer starts will raise orders for 11-nine material, and producers with chip-grade lines will gain long contracts.
Table 2: Price, Output and Trade Indicators for the Polysilicon Market (prices, volumes and policy dates), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Daqo New Energy average selling price, Q2 2026 | USD 4.04 per kg | Solar grade prices stay below cost. | |
| Daqo New Energy production, Q2 2026 | 43,675 MT | Large producers keep output high. | |
| Tongwei polysilicon shipments, H1 2026 | 155,300 tons | Integrated groups lead solar volume. | |
| United States polysilicon minimum import price, from December 2026 | USD 21 per kg | Trade floors split supply by origin. | |
| Wacker Polysilicon EBITDA, Q2 2026 | EUR 11 million | Solar price falls squeeze Western producers. | |
| Silicon wafer shipments, Q2 2026 | 3,573 MSI; up 7.4% | Chip orders support electronics grade. |
Analyst Perspective
“Polysilicon now trades in two separate worlds, a solar grade priced near cash cost and a chip grade sold on long contracts with strict purity terms. I expect the next five years to reward producers that can certify origin and purity for both, and I would watch the United States price floor as the first test of that split, and chip-grade contracts as a second profit pool for certified producers.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the polysilicon market segmented?
The market is segmented into grade, end use, production technology, and region. Solar grade is expected to lead grade sales with 79% share in 2026, and solar PV cells and modules lead end use with 86%.
By grade: solar grade and electronics grade.
By end use: solar PV cells and modules, semiconductors, and others.
By production technology: Siemens process, fluidized bed reactor, and upgraded metallurgical-grade silicon.
By region: silicon, wafer and chip plants in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does solar grade lead polysilicon sales by grade?
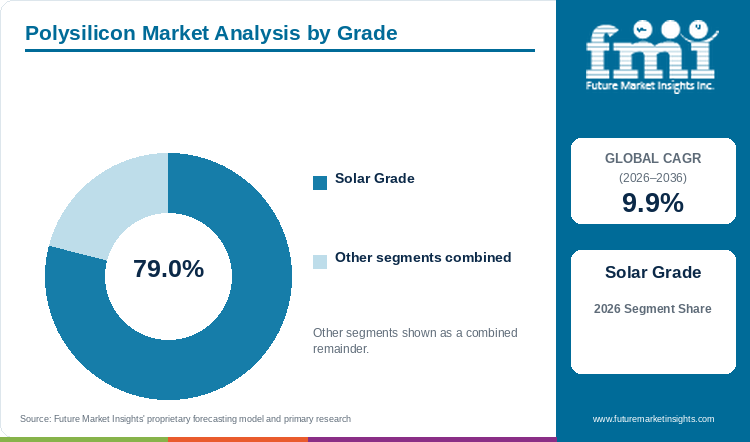
Solar grade is expected to lead grade sales with 79% share in 2026, ahead of electronics grade at 21%.
Table 3: Grade Share for the Polysilicon Market (percentage share), 2026
| Grade | Estimated Share (2026) |
|---|---|
| Solar Grade | 79% |
| Electronics Grade | 21% |
| Total | 100.0% |
Table 4: Grade Leadership and Market Growth for the Polysilicon Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.9% |
| Leading Segment | Solar Grade |
Solar grade is expected to lead grade sales at 79% in 2026, as module plants consume polysilicon by the hundred thousand tonnes each quarter. Electronics grade, at 21%, needs purity of eleven nines or higher and sells for many times the solar price, so a small tonnage gives a large share of sales. Part of the electronics-grade material ends up in premium n-type solar wafers, so the 21% grade share is larger than the 12% semiconductor end use share. Polysilicon sales at Wacker rose 3% to EUR 226 million in the June 2026 quarter, with semiconductor volumes up and solar prices down. A wafer maker choosing a grade buys the lowest purity the cell design allows, which keeps solar grade far ahead on volume.
- Mono PERC and TOPCon wafers use most solar grade material, with HJT and IBC wafers using the purest solar lots.
- Solar silicon prices and solar orders were both lower in Q2 2026, Wacker said in the 30 July results release.
Why do solar PV cells and modules lead polysilicon sales by end use?
Solar PV cells and modules are likely to hold 86% of end use sales in 2026, with semiconductors at 12% and other uses at about 2%.
Table 5: End Use Share for the Polysilicon Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Solar PV Cells and Modules | 86% |
| Semiconductors | 12% |
| Others | 2% |
| Total | 100.0% |
Utility solar farms, rooftop systems and commercial arrays all start as polysilicon ingots, so solar PV cells and modules will lead end use at 86% in 2026. Spain added 8.8 GW of solar PV in 2025, excluding self-consumption. Semiconductors, at 12%, use far less tonnage, but each wafer for a logic, memory or power chip needs the highest purity. SEMI counted a 7.4% gain in silicon wafer shipments for the June 2026 quarter. Other uses, about 2%, include silane derivatives and research, and a 7.2% CAGR is expected for the high-purity silane gases market as chip and display fabs add deposition steps. Solar volume decides the polysilicon market even in years of falling prices, since module plants buy the bulk of all tonnage.
- Utility-scale farms account for the largest part of solar end use, followed by commercial rooftops and homes.
- Germany added about 7.4 GW of solar PV in H1 2026, BSW-Solar said in July 2026.
Why does the Siemens process lead polysilicon sales by production technology?
The Siemens process is projected to account for 72% of production technology sales in 2026, against 22% for fluidized bed reactor material and 6% for upgraded metallurgical-grade silicon.
Table 6: Production Technology Share for the Polysilicon Market (percentage share), 2026
| Production Technology | Estimated Share (2026) |
|---|---|
| Siemens Process | 72% |
| Fluidized Bed Reactor | 22% |
| Upgraded Metallurgical-Grade | 6% |
| Total | 100.0% |
Rod deposition in bell-jar reactors is the proven route to both solar and chip purity, so the Siemens process is projected to lead production technology at 72% in 2026. Fluidized bed reactor granules, at 22%, use less power per kilogram and feed continuous ingot pullers, but chipmakers still qualify few granular grades. Upgraded metallurgical-grade silicon, at 6%, costs least but carries impurities that limit cell efficiency. Siemens reactors at Daqo New Energy ran at an average cash cost of USD 4.57 per kg in Q2 2026. Producers choosing a route for new capacity stay with Siemens reactors for chip grade and test granular silicon for solar lines.
- Siemens output covers dense rod polysilicon for Czochralski ingots and chip wafers.
- Tongwei shipped 155,300 tons of high-purity polysilicon over January to June 2026.
What are the drivers, restraints, and opportunities in the polysilicon market?
New solar capacity and chip fabs keep polysilicon tonnage rising. Prices below cash cost and trade barriers squeeze producers, and origin-certified and chip-grade material opens premium contracts.
- Driver: Solar installers and chip fabs both add capacity, which keeps wafer makers buying more polysilicon each year of the forecast.
- Restraint: Excess capacity holds solar grade prices near or below cash cost, which forces losses and delays new plants.
- Opportunity: Buyers facing origin rules and purity demands pay more for certified, traceable and chip-grade polysilicon.
Solar Farms and Chip Fabs Add Polysilicon Tonnage
Adoption of solar power keeps wafer plants running at scale. German solar additions reached about 7.4 GW over January to June 2026, up 9% on H1 2025. Saudi Power Procurement Company signed power purchase agreements for 12 GW of solar in July 2025, with operations due in 2027 and 2028. Each new solar farm and fab adds firm polysilicon orders over the next two to three years.
Prices Below Cash Cost Squeeze Producers
Prices that leave most producers without margin are the hardest problem polysilicon makers face. Selling prices at Daqo New Energy averaged USD 4.04 per kg in Q2 2026, against a USD 5.95 production cost. Losses at Tongwei reached CNY 5.12 billion over the six months to June 2026. In FMI's assessment, high-cost plants will close before new investment returns.
Origin-Certified and Chip-Grade Material Opens Premium Contracts
Polysilicon buyers are moving toward material with documented origin and higher purity. The United States will apply a minimum import price of USD 21 per kg for polysilicon from 4 December 2026. OCI TerraSus secured an IFC loan of up to USD 125 million for a semiconductor-grade polysilicon plant in Malaysia. Thin-film rivals add a long-run threat, and with a 15.3% CAGR projected for the perovskite photovoltaic modules market, silicon suppliers will push tandem-ready wafer grades.
Which country CAGRs are profiled in the polysilicon market?
Table 7: Country CAGR Comparison for the Polysilicon Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 14.2% |
| China | 10.5% |
| Spain | 7% |
| GCC Countries | 6.1% |
| United States | 5.3% |
| Germany | 4.6% |
| South Korea | 4.4% |
How do country-level CAGRs compare in the polysilicon market?
Wafers on India's approved list become mandatory for covered solar projects from 1 June 2028, and that rule pushes India to the fastest profiled rate, 14.2%. China, at 10.5%, keeps the largest integrated wafer and module base. FMI's base case has Spain at 7%, under the 9.9% CAGR for the polysilicon market, with large solar farms as the main buyers. GCC Countries grow at 6.1% on giga-scale solar tenders. The United States, at 5.3%, rebuilds wafer and cell capacity behind new trade floors. Chip-grade and premium solar material set the pace in Germany, at 4.6%. South Korea, with most national output now made in Malaysia, grows at 4.4%.
- Indian wafer and ingot plants are scaling up for domestic content rules.
- Integrated groups in China run polysilicon, wafer and module lines in one chain.
- Spanish solar farms keep module orders flowing.
- Saudi tenders give GCC Countries giga-scale solar projects.
- American cell and wafer plants gain from the December 2026 trade floors.
- German rooftops and chip fabs set a mixed but steady order pipeline.
- Korean producers focus on chip-grade output and overseas plants.
Full report country CAGRs cover: Two countries, India and China, make up the pair growing ahead of the polysilicon market, and Spain, GCC Countries and the United States form a middle group with rates of 5.3% to 7%. Germany and South Korea complete the profiled set, and regional summaries cover the other countries.
Country-wise Analysis
India Polysilicon Market Outlook (2026 to 2036)
Wafer and ingot plants built to meet approved-list rules point to a 14.2% CAGR for polysilicon in India. MNRE extended the approved list to ingots and wafers, effective 1 June 2028, and Premier Energies plans 10 GW of ingot-wafer capacity at INR 5,900 crore. FMI data indicate that India will import most polysilicon until local polysilicon plants open.
Key takeaway: Approved-list rules for wafers make India the fastest-growing country.
China Polysilicon Market Outlook (2026 to 2036)
Tongwei shipped 155,300 tons of polysilicon in H1 2026 and still lost CNY 5.12 billion. A 10.5% CAGR is forecast for China, as integrated groups keep module output high for export and home installations. Energy-consumption standards and price rules are expected to close inefficient plants by 2027, Daqo New Energy said. The survivors will hold more of the global solar grade supply.
Key takeaway: Capacity exits and integrated output keep China a little faster than the polysilicon market.
Spain Polysilicon Market Outlook (2026 to 2036)
Red Eléctrica reported nearly 50 GW of solar PV installed in Spain by the end of 2025, 33.1% of the capacity mix. Large solar farms carry a likely 7% CAGR for polysilicon linked to Spanish projects. Module buyers for those farms will favour low-cost n-type modules.
Key takeaway: Large solar farms keep Spain at the top of the European group.
GCC Countries Polysilicon Market Outlook (2026 to 2036)
On FMI's numbers, Saudi tenders for solar farms of several gigawatts each support a 6.1% CAGR for GCC Countries. Saudi Power Procurement Company signed agreements for five solar projects with 12 GW in July 2025, including 3 GW at Bisha and 3 GW at Humaji. ACWA Power and partners will buy modules for those plants, and the polysilicon inside will come mainly from Asian wafer makers.
Key takeaway: Giga-scale Saudi solar farms carry the GCC outlook.
United States Polysilicon Market Outlook (2026 to 2036)
New trade floors for polysilicon apply in the United States from 4 December 2026, with a USD 21 per kg minimum price for polysilicon and USD 100 per kg for ingots and wafers. FMI sees a 5.3% CAGR for the United States, as wafer and cell plants restart behind the new barriers. Hemlock Semiconductor and Wacker are named as likely beneficiaries of the decision.
Key takeaway: Trade floors help domestic producers, but wafer capacity in the United States stays small.
Germany Polysilicon Market Outlook (2026 to 2036)
German solar and chip plants point to a projected 4.6% CAGR for polysilicon in Germany. Germany installed about 7.4 GW of solar PV in H1 2026, and BSW-Solar linked the rise mainly to pull-forward ahead of planned subsidy cuts. Wacker grew semiconductor polysilicon volumes in Q2 2026, and higher energy costs weighed on the segment result. Chip-grade sales will carry most growth from Burghausen.
Key takeaway: Chip grade and rooftop solar keep Germany growing slowly.
South Korea Polysilicon Market Outlook (2026 to 2036)
OCI Holdings, through OCI TerraSus, is building a semiconductor-grade polysilicon plant with Tokuyama in Sarawak, backed by up to USD 125 million from IFC. The main Korean producer, OCI Holdings, runs polysilicon plants in Malaysia. For South Korea, a 4.4% CAGR, the slowest pace in the table, is predicted. Korean chipmakers will keep buying electronics grade for memory and logic fabs.
Key takeaway: Offshore production leaves South Korea with the lowest rate among the profiled countries.
Who are the notable companies in the polysilicon market?
Tongwei, Wacker, GCL Technology, Daqo New Energy, Xinte Energy, OCI Holdings, Asia Silicon, Hemlock Semiconductor and Tokuyama are the profiled companies.
FMI tracks nine producers, from integrated solar groups to chip-grade specialists. Tongwei, with 155,300 tons shipped in six months, is the largest solar grade supplier with dated volumes. Daqo New Energy expects to keep about 15% of the polysilicon market. At Wacker, the Polysilicon segment sold EUR 226 million of material in the June 2026 quarter. The move from established markets to emerging growth opportunities is visible in Malaysia, with OCI TerraSus and Tokuyama building chip-grade capacity there.
- Integrated solar grade producers: Tongwei, GCL Technology, Daqo New Energy, Xinte Energy and Asia Silicon.
- Chip and solar grade producers: Wacker, Hemlock Semiconductor and OCI Holdings.
- Chip grade specialist: Tokuyama.
Competitive Benchmarking: Polysilicon Market
Table 8: Competitive Benchmarking for the Polysilicon Market (qualitative documentation ratings), 2026
| Company | Solar Grade | Electronics Grade | Cost Position | Recency |
|---|---|---|---|---|
| Tongwei | High | Low | High | High |
| Daqo New Energy | High | Low | High | High |
| Wacker | Medium | High | Medium | High |
| OCI Holdings | Medium | Medium | Medium | High |
| Tokuyama | Low | High | Medium | Medium |
Several dated 2026 releases support each High score, and the scores say nothing about share.
Key Developments in the Polysilicon Market
- On 28 August 2026, pv magazine reported Tongwei H1 2026 polysilicon shipments of 155,300 tons.
- On 24 August 2026, Mercom reported Daqo New Energy Q2 2026 production of 43,675 MT.
- On 7 August 2026, TaiyangNews reported a 15% United States tariff on polysilicon derivatives from 4 December 2026.
- Polysilicon sales at Wacker came in at EUR 226 million for April to June 2026, in results issued on 30 July 2026.
- Silicon wafer shipments reached 3,573 million square inches in Q2 2026, SEMI data released on 29 July 2026 show.
- On 14 July 2026, BSW-Solar put German solar additions for H1 2026 at about 7.4 GW.
- On 30 March 2026, IFC agreed a loan of up to USD 125 million for the OCI TerraSus chip-grade plant.
- On 18 March 2026, MNRE extended the approved list in India to ingots and wafers.
- On 11 March 2026, Red Eléctrica published the 2025 review of the Spanish power system.
- On 14 July 2025, Saudi Power Procurement Company signed 12 GW of solar power purchase agreements.
Key Players in the Polysilicon Market
Integrated Solar Grade Producers
- Tongwei
- GCL Technology
- Daqo New Energy
- Xinte Energy
- Asia Silicon
Chip and Solar Grade Producers
- Wacker
- Hemlock Semiconductor
- OCI Holdings
Chip Grade Specialist
- Tokuyama
Polysilicon Market - Report Scope
Table 9: Report Scope for the Polysilicon Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Grade; end use; production technology; region |
| Quantitative units | USD billion |
| Market definition | High-purity silicon made by the Siemens process, fluidized bed reactors or metallurgical upgrading, sold in solar and electronics grades for PV ingots, wafers, cells and modules, semiconductor wafers and silane derivatives. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Tongwei, Wacker, GCL Technology, Daqo New Energy, Xinte Energy, OCI Holdings, Asia Silicon, Hemlock Semiconductor, Tokuyama |
| Forecast period | 2026 to 2036 |
Polysilicon Market - Research Methodology
Table 10: Research Methodology for the Polysilicon Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Producer results, trade rulings, grid operator reports, wafer shipment data, development finance releases and trade press from May 2025 onward. |
| Desk Research | Desk research covers polysilicon prices, producer output, trade measures, solar additions and chip wafer orders. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 19.1 billion and the 9.9% CAGR for 2026 to 2036. |
| Data Validation | Prices, volumes and capacity figures were matched to the company, agency or publication that reported them. |
Polysilicon Market by Segments
Polysilicon Market segmented by Grade:
- Solar Grade
- Electronics Grade
Polysilicon Market segmented by End Use:
- Solar PV Cells and Modules
- Semiconductors
- Others
Polysilicon Market segmented by Production Technology:
- Siemens Process
- Fluidized Bed Reactor
- Upgraded Metallurgical-Grade
Polysilicon Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] TaiyangNews. (2026, August 7). US announces 15% tariff on imported polysilicon under Section 232. https://taiyangnews.info/markets/us-announces-15-percent-tariff-polysilicon-under-section-232
- [2] Wacker Chemie AG. (2026, July 30). WACKER steigert Ergebnis im 2. Quartal. https://www.wacker.com/cms/media/de/documents/pressrelease-pdf/pm2026/wacker_q2_2026.pdf
- [3] Mercom India. (2026, August 24). Daqo New Energy's Q2 revenue falls 17% as polysilicon prices drop. https://mercomindia.com/daqo-new-energys-q2-revenue-falls-17-as-polysilicon-prices-drop
- [4] Red Eléctrica. (2026, March 11). El sistema eléctrico español en 2025. https://www.ree.es/sites/default/files/2026-03/1103_NP_ISE_2025.pdf
- [5] pv magazine. (2026, August 28). Chinese PV Industry Brief: Leading solar manufacturers report H1 losses. https://www.pv-magazine.com/2026/08/28/chinese-pv-industry-brief-leading-pv-manufacturers-report-h1-losses/
- [6] SEMI. (2026, July 29). SEMI reports worldwide silicon wafer shipments increase 7.4 percent year-on-year in Q2 2026. https://www.semi.org/en/semi-press-release/semi-reports-worldwide-silicon-wafer-shipments-increase-7.4-percent-year-on-year-in-q2-2026
- [7] International Finance Corporation. (2026, March 30). World Bank Group's IFC and OCI TerraSus partner on Southeast Asia's first semiconductor-grade polysilicon facility. https://www.ifc.org/en/pressroom/2026/world-bank-group-s-ifc-and-oci-terrasus-partner-on-southeast-asia-s-first-semicond
- [8] Solarserver. (2026, July 14). BSW-Solar: Photovoltaik-Ausbau im ersten Halbjahr 2026 bei 7,4 Gigawatt. https://www.solarserver.de/2026/07/14/bsw-solar-photovoltaik-ausbau-im-ersten-halbjahr-2026-bei-74-gigawatt/
- [9] pv magazine. (2025, July 14). Saudi Arabia signs 5 solar PPAs totaling 12 GW. https://www.pv-magazine.com/2025/07/14/saudi-arabia-signs-5-solar-ppas-totaling-12-gw/
- [10] Energetica India. (2026, March 18). MNRE extends ALMM to solar wafers and ingots, to be effective from June 1, 2028. https://www.energetica-india.net/news/mnre-extends-almm-to-solar-wafers-and-ingots-to-be-effective-from-june-1-2028
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the polysilicon market during 2026?
- What market size is projected by 2036?
- Which grade holds notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade, 2026 to 2036
- Solar Grade
- Electronics Grade
- Y-o-Y Growth Trend Analysis By Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Solar PV Cells and Modules
- Semiconductors
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Production Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Production Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Production Technology, 2026 to 2036
- Siemens Process
- Fluidized Bed Reactor
- Upgraded Metallurgical-Grade
- Y-o-Y Growth Trend Analysis By Production Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Production Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Grade
- By End Use
- By Production Technology
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By End Use
- By Production Technology
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By End Use
- By Production Technology
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Grade
- By End Use
- By Production Technology
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tongwei
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Daqo New Energy
- Wacker
- OCI Holdings
- Tokuyama
- GCL Technology
- Xinte Energy
- Asia Silicon
- Hemlock Semiconductor
- Tongwei
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Production Technology, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Grade
- Figure 6: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End Use
- Figure 9: Global Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Production Technology
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Grade
- Figure 26: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by End Use
- Figure 29: North America Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Production Technology
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by End Use
- Figure 39: Latin America Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Production Technology
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by End Use
- Figure 49: Western Europe Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Production Technology
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Production Technology
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by End Use
- Figure 69: East Asia Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Production Technology
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Production Technology
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Production Technology, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Production Technology, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Production Technology
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the polysilicon market expected in 2026?
Polysilicon sales are put by FMI at USD 19.1 billion in 2026, against USD 17.4 billion in 2025. The polysilicon market is forecast to reach USD 49.1 billion by 2036.
What CAGR is projected for the polysilicon market through 2036?
A 9.9% CAGR is projected for polysilicon sales over the forecast period to 2036. New solar farms and chip fabs carry that growth.
Which grade holds a notable market share in 2026?
Grade sales are led by solar grade, expected at 79% share in 2026. Electronics grade accounts for 21%.
Which end use holds a notable market share in 2026?
Solar PV cells and modules are likely to hold 86% of end use sales in 2026. Semiconductors follow at 12%.
Which country has a notable expansion outlook through 2036?
Wafer rules give India the fastest rate in the FMI country set, a 14.2% CAGR. China follows at 10.5%.
Who are the key companies in the polysilicon market?
Tongwei, GCL Technology, Daqo New Energy, Xinte Energy and Asia Silicon lead solar grade supply. Wacker, Hemlock Semiconductor, OCI Holdings and Tokuyama complete the profiled group with chip-grade output.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
