
- Market Size (2026)
- USD 44.8 Bn
- Forecast (2036)
- USD 127.2 Bn
- CAGR (2026 to 2036)
- 11.0%
How big is the Push-to-Talk Market in 2026?
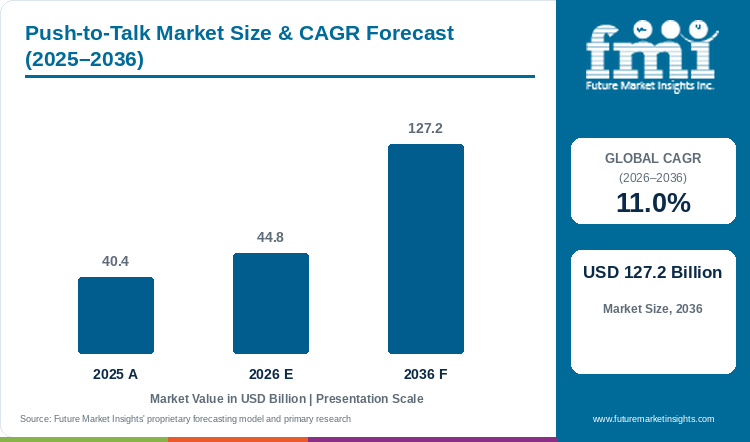
The global push-to-talk market is estimated at USD 44.80 billion in 2026, compared with USD 40.36 billion in 2025, and is forecast to reach USD 127.21 billion by 2036, expanding at a CAGR of 11.0% from 2026 to 2036.
Demand for push-to-talk is driven by public-safety and enterprise fleets that need one instruction to reach a whole team at once and is expanding from dedicated radio networks to cellular and broadband services. Programmes to replace public-safety radio are supporting this demand, and the market is expected to grow at a double-digit rate through 2036. In January 2025, the UK Home Office selected IBM to design, build and integrate the Emergency Services Network, which is intended to serve more than 300,000 emergency responders in Great Britain and provide push-to-talk on new handheld devices. [1] In the United States, AT&T's AdventHealth case study describes the replacement of UHF two-way radios with FirstNet Rapid Response to connect a healthcare system spanning 54 hospital campuses and hundreds of care sites in nine states. [2] One is a national programme and the other a single fleet, so together they show the two routes to orders and not how many users or devices move in a given year.
The move to broadband also keeps work going on existing radio systems. In March 2026, the German government said TETRA voice communication would remain available until the next generation of broadband public-safety radio could replace it. [3] NIST's March 2025 mission-critical voice report described the difficulty of combining equipment from different vendors and carrier services, and the training needed to use the combined systems. [4] Therefore, radio interworking and user training stay in the order alongside new push-to-talk platforms. According to analysis by FMI, compatibility with installed equipment affects supplier choice. Both sources describe public-safety needs, so they do not show the weight of commercial fleet demand.
Market Size & Forecast
Table 1: Push-to-Talk Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value | USD 40.36 billion |
| Estimated market size in 2026 | USD 44.80 billion |
| Projected market size by 2036 | USD 127.21 billion |
| CAGR (2026-2036) | 11.0% |
| Added revenue, 2026 to 2036 | USD 82.41 billion |
Key Market Trends & Insights
- Hardware is estimated to account for 44.2% of revenue by offering in 2026, because dedicated field devices and control-room endpoints are still bought next to phone-based services.
- Cellular or PoC services are expected to hold 58.7% of revenue by network in 2026, so connecting teams across several sites without a private radio network in each is the main route to orders.
- National programmes create the largest single contracts. The UK's Emergency Services Network is intended to put push-to-talk on new handhelds for more than 300,000 responders, [1] which supports device software and integration work.
- Fleet replacement adds a second route. AdventHealth moved from UHF two-way radios to FirstNet Rapid Response across nine states, [2] which shows how a single operator can order a cellular service for a whole workforce.
- Installed radio stays in service during migration. Germany keeps TETRA voice until broadband can replace it, [3] and NIST reports difficulty in combining vendors' equipment, [4] so interworking and training remain part of the spend.
- Standards define what a supplier can claim. ETSI's Release 19 architecture for mission-critical services sets functions and interfaces, [5] which gives buyers a reference for comparing implementations.
Regional Highlights
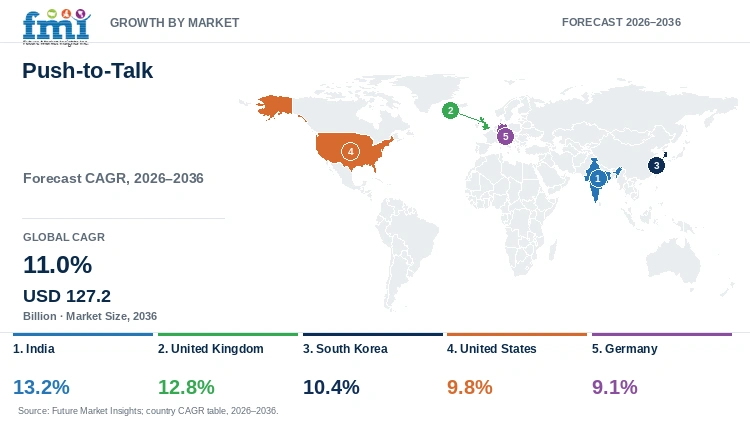
- India is likely to grow at a 13.2% CAGR during the forecast period, followed by the United Kingdom at 12.8%, South Korea at 10.4%, the United States at 9.8% and Germany at 9.1%.
Analyst Perspective
“The transition to broadband push-to-talk creates demand for services that work with radios already in use. Migration contracts will depend on proven route coverage and reliable group calling, with training and operational support helping customers make the change without disrupting team communications.”
- Sudip Saha, Principal Consultant, FMI
How is the Push-to-Talk Market segmented?
The Push-to-Talk Market is segmented by offering, network, enterprise size, vertical and region.
- By Offering: Hardware, Solutions and Services.
- By Network: Cellular or PoC and Land Mobile Radio.
- By Enterprise Size: Large Enterprises and SMEs.
- By Vertical: Public Safety and Security, Government and Defense, Transportation and Logistics, Travel and Hospitality, and Energy and Utility.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why is Hardware the Leading Offering in the Push-to-Talk Market?
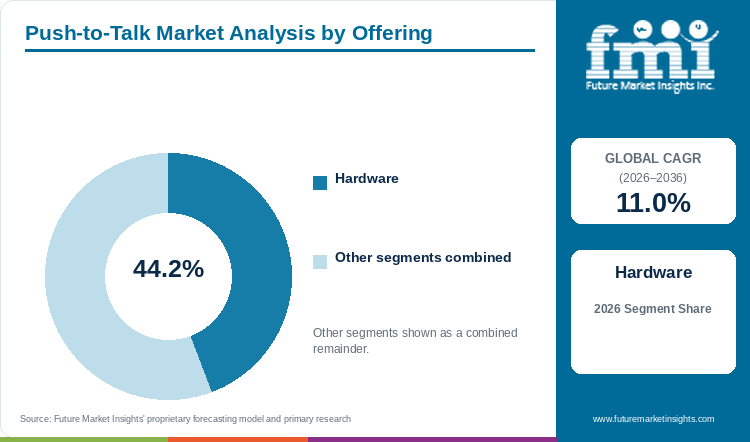
Hardware accounts for an estimated 44.2% of push-to-talk revenue by offering in 2026, equal to about USD 19.80 billion, as per FMI's analysis.
Table 2: Offering Share for the Push-to-Talk Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Hardware | 44.2% |
| Other segments combined | 55.8% |
The segment covers dedicated field devices and the endpoints and interfaces used around the control room. Motorola Solutions offers APX and MOTOTRBO radio products alongside WAVE PTX, while Hytera offers P50 PoC devices and the MNC360 mobile radio. Controls that work with gloves and audio that stays clear in a vehicle cab are purchasing criteria, which keeps dedicated devices in demand next to phone-based services.
Charging and replacement arrangements also support hardware spending, since equipment passes between shifts and batteries and accessories need to remain available during the support period. A radio that is inexpensive to buy becomes difficult to keep in service if a damaged unit has no compatible replacement.
However, solutions and services together hold the remaining 55.8% of offering revenue. Smaller organisations may begin with a limited subscription on existing phones and buy dedicated devices later for users whose shifts require them, so hardware leads the offering categories without accounting for the whole cost of running a push-to-talk service. Suppliers best placed to hold the share provide suitable controls and audio, keep batteries and accessories available and give the customer a clear replacement path for devices used across several sites.
Why is Cellular or PoC the Leading Network in the Push-to-Talk Market?
Cellular or PoC services are expected to hold 58.7% of push-to-talk revenue by network in 2026.
Table 3: Network Share for the Push-to-Talk Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Cellular or PoC | 58.7% |
| Other segments combined | 41.3% |
These services let an organisation connect teams working beyond the reach of one private radio site. Customers can start with a small user group and add routes or premises as the service becomes part of daily work, which suits fleets and other dispersed commercial operations. The recurring subscription also pays for administration: new workers need enrolment, departed staff need removal and supervisors need the correct group permissions.
However, a claim of national mobile coverage does not guarantee reception in a loading bay, an underground service area or every part of a working route. Land mobile radio remains important where an operator needs control over coverage and direct communication, and NIST identifies the integration of radio and broadband as a practical concern for mission-critical voice. [4]
Suppliers best placed demonstrate coverage on the customer's routes, make group changes straightforward and support the connection to existing radios where the customer needs both networks.
What are the Key Drivers, Restraints and Opportunities in the Push-to-Talk Market?
The push-to-talk market is expected to grow from USD 44.80 billion in 2026 to USD 127.21 billion by 2036, which adds USD 82.41 billion over the forecast period. Immediate group coordination supports demand, while coverage gaps and migration complexity can delay an order, and managed connections between radio and broadband create a separate service opportunity.
Driver: distributed operational work. A depot closure or a changed collection point requires a supervisor to reach the active team immediately, and security patrols and maintenance crews have the same need for a spoken group instruction. A service that can add a route or contractor without rebuilding local radio infrastructure gives these customers a reason to extend their use of push-to-talk.
Restraint: coverage and mixed equipment. Emergency organisations rarely replace every device at once, so a control room may need to reach old and new equipment during the same shift. A gateway can connect the systems yet behave differently when a priority call starts or a user changes groups, [4] and unresolved responsibility between network and equipment providers can hold up acceptance even when individual components work.
Opportunity: managed migration. The Emergency Services Network is intended to support more than 300,000 responders, which makes enrolment and operational transfer substantial tasks. [1] Suppliers can define talk groups, prepare devices and train staff around actual dispatch procedures, and a customer that undertakes such a change only once in many years has reason to buy that support.
Suppliers that keep dispatch connected during the transition and accept clear duties for configuration changes and restoration are best placed to secure recurring work as customers add users.
How do Standards and Service Requirements Influence Push-to-Talk Demand?
Standards and operating requirements affect which service a customer can accept. A common architecture gives suppliers a technical reference, while the customer's duty determines the reliability and support it needs, so an enterprise group-calling application does not automatically qualify for emergency response.
Standards that define service functions and interfaces
ETSI TS 123 280 V19.9.0, published in February 2026, sets out the Release 19 common functional architecture to support mission-critical services at Stage 2. [5] Defined functions and interfaces matter when the customer combines devices, dispatch software and network services from different providers. The relevant question is which functions the offered implementation supports and how its components work together.
Requirements that follow the operating duty
NIST's roundtable brought together 37 first responders and communications engineers to discuss mission-critical voice. [4] Its practical focus shows why a demonstration call alone is insufficient for emergency-service acceptance, since understandable speech, familiar controls and the behaviour of a group call under difficult conditions all affect use in the field.
Responsibilities that must be clear in the contract
The Emergency Services Network announcement describes a user-services partnership for a large planned national service. [1] Device management, training and control-room connections therefore need assigned responsibilities before users transfer, and an agreement must also state who diagnoses a fault when it crosses the interface between the radio system and a broadband service.
These requirements make documented service behaviour and support part of the purchase. A supplier that can explain the implemented functions, demonstrate the complete call route and maintain the service after handover has a stronger position with customers whose operations depend on immediate voice communication.
What Technical and Operational Constraints Affect Push-to-Talk Supply?
The constraints sit in coverage, equipment, interfaces and service continuity, and improving one of them does not make the complete service ready for operational use.
The first is reception. Cellular coverage needs to be checked in buildings, service areas and along the routes where workers spend their shifts, because a successful call in the sales office does not show how the service behaves during network congestion or a local power failure.
The second is the device. Buttons need to remain usable while a worker carries equipment or wears gloves, and audio needs to stay clear near machinery. Charging between shifts, battery endurance and access to replacement accessories can limit use even where the network signal is adequate.
The third is the radio and broadband interface, which NIST identifies as a practical concern. [4] The complete path from speaker to recipient needs to preserve the expected group-call behaviour during changes in priority or membership, and a fault involving several providers takes longer to resolve if no party owns the diagnosis.
The fourth is continuity away from normal infrastructure. The First Responder Network Authority's Release 19 discussion includes work on isolated operation and relaying. [6] These are areas of standards work, and their presence does not mean that every product on offer implements them, so a customer needs evidence of the functions available in its particular system.
These constraints favour suppliers that test equipment with actual users, document the behaviour of connected systems and provide a support route covering the whole service. Unfamiliar procedures can slow adoption even when a radio link works.
Where are the Commercial Opportunities for Push-to-Talk Suppliers?
The opportunity lies in extending commercial teams, supporting migration and maintaining deployments after installation. The value of each contract depends on the number of active users and the work the supplier accepts.
The first is commercial expansion. A warehouse or fleet may begin with existing phones and a limited subscription, then add dedicated devices for demanding shifts, and seasonal workers may need short licences while supervisors need permanent access. A supplier that prices these patterns clearly can expand with the customer and avoid disputes over inactive devices or unused subscriptions.
The second is commissioning and migration. Customers need talk groups defined, equipment enrolled and training matched to dispatch procedures before a transfer. Deployable systems used with emergency communication vehicles add work because the operating location can change at short notice, so repeatable commissioning and support at unfamiliar incident sites give suppliers a practical service offer.
The third is continuing administration. Staff leave, contractors join, and carriers or device models change. Training and radio gateways can be material parts of an order even where the initial software charge is modest, and suppliers that state clear duties for configuration changes, restoration and replacement equipment give customers a basis for judging renewal by operating results.
Push-to-Talk Market by Country (2026 to 2036)
Table 4: Country Growth Outlook for the Push-to-Talk Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026-2036) |
|---|---|
| India | 13.2% |
| United Kingdom | 12.8% |
| South Korea | 10.4% |
| United States | 9.8% |
| Germany | 9.1% |
What is driving push-to-talk demand in India?
India is likely to grow at a 13.2% CAGR during the forecast period, the highest rate among the countries analysed.
On 23 October 2026, the Ministry of Home Affairs sought input on the network architecture of a proposed nationwide public-safety broadband system with mission-critical push-to-talk. [7] The consultation is an advantage because it lets suppliers shape systems for police, disaster response, fire and medical services. The disadvantage is that it is a design consultation and not a purchase order, so the timing of equipment demand from it remains open.
Commercial demand runs alongside it. Organisations supervising work across city boundaries, such as a parcel operator directing drivers from one control room, favour straightforward group administration and subscription terms that let the customer add workers as operations grow. Suppliers with local support and clear rules for group access are best placed to turn an initial deployment into repeat business.
What is supporting push-to-talk demand in the United Kingdom?
The United Kingdom is likely to grow at a 12.8% CAGR during the forecast period.
The Emergency Services Network is the largest identified programme among the countries analysed, and the Home Office describes it as a user-services partnership for a national service. [1] That scale is an advantage because it makes training, device acceptance and service continuity central to procurement before an operational transfer takes place. The disadvantage is that individual emergency services can have different control-room arrangements, and the broader commercial market of transport and facility operators has different service needs.
Growth is likely to follow the transfer of responders to the new service. Suppliers that state their responsibilities at each interface and offer packages suited to the customer's actual work hold the stronger position.
What are the key sources of push-to-talk demand in South Korea?
South Korea is likely to grow at a 10.4% CAGR during the forecast period.
Samsung completed deployment of a nationwide public-safety LTE network in March 2021 with mission-critical push-to-talk for more than 330 public-safety organisations and agencies. [8] An installed system of that size is an advantage because it provides a base for continuing device support and service upgrades. The disadvantage is that a capable mobile network alone does not make an application useful, and industrial teams in noisy buildings and transport users moving between working locations judge the service by audio and handover.
Growth is likely to come from refresh and from commercial teams. Suppliers can secure additional orders by resolving a recurring operating problem, such as short battery endurance or cumbersome device enrolment.
What is leading push-to-talk demand in the United States?
The United States is likely to grow at a 9.8% CAGR during the forecast period.
NIST's March 2025 roundtable report examined concerns raised by 37 first responders and communications engineers, which makes user evaluation an important part of the purchasing discussion. [4] Agencies need communication across jurisdictions and equipment generations, and controls have to fit established response procedures as well as meet technical specifications, which is an advantage for suppliers that test with users. The disadvantage is that broad geography requires services to be assessed where personnel actually work, and an enterprise calling application is not a replacement for every function of a public-safety radio.
Commercial fleets form a separate source of managed cellular demand, as the AdventHealth case shows. Suppliers need to distinguish the two sets of service obligations.
What is shaping push-to-talk demand in Germany?
Germany is likely to grow at a 9.1% CAGR during the forecast period, the lowest rate among the countries analysed.
In March 2026, the German government reported more than 5,000 TETRA base stations covering 99.2% of the country's area. [3] That installed network keeps radio compatibility relevant to orders for new push-to-talk systems, which is an advantage for suppliers that can interwork with it. The disadvantage is that a fault can involve more than one provider, so customers need a clear support route.
Growth is likely to stay moderate while organisations with established radio procedures introduce broadband features selectively, adding images and location information for dispatch while field staff keep a familiar voice arrangement. Industrial users can begin with one maintenance or security team in a defined working area, and suppliers that make that first deployment reliable can support later expansion without requiring the whole organisation to change equipment at once.
Who are the notable companies in the Push-to-Talk Market?
Companies differ by the equipment and operating responsibilities they take on. The market includes professional radio manufacturers, suppliers of dedicated PoC devices and providers of application-based voice and dispatch services, and these positions carry no common market-share ranking.
Motorola Solutions combines professional radio products with broadband calling through its APX, MOTOTRBO and WAVE PTX offers. Hytera supplies radio equipment and dedicated PoC devices, including P50 devices and the MNC360 mobile radio, and JVCKENWOOD supplies KENWOOD land mobile radio products for business and industrial users.
Airbus offers the Agnet broadband communication platform for critical and enterprise operations. Zello offers application-based enterprise voice and dispatch functions for distributed frontline teams. Application providers can compete on the ease of deployment and administration, while radio suppliers bring experience with installed equipment and its replacement.
A customer may buy from more than one provider because the control room and the field device serve different needs, so the proposal has to show how these elements work together and who takes responsibility when service stops. Clear support obligations are expected to carry weight alongside device specifications as organisations extend their use of push-to-talk.
Key Developments in the Push-to-Talk Market
- On 23 October 2026, India's Ministry of Home Affairs sought public and stakeholder input on the network architecture of the proposed Broadband Public Protection and Disaster Relief system. [7]
- On 31 March 2026, the German Bundestag published the government's report on the further development of the BOS digital radio network, which keeps TETRA voice available until broadband can replace it. [3]
- In February 2026, ETSI published the Release 19 common functional architecture for mission-critical services, ETSI TS 123 280 V19.9.0. [5]
- In 2026, the First Responder Network Authority discussed completion of 3GPP Release 19 and work on isolated operation and relaying. [6]
- On 14 March 2025, NIST published the Mission Critical Voice Roundtable Report following discussions with 37 first responders and communications engineers. [4]
- On 15 January 2025, the UK Home Office announced IBM as its Emergency Services Network user-services partner and described support for more than 300,000 intended responders. [1]
Key Players in the Push-to-Talk Market
- Motorola Solutions
- Hytera
- JVCKENWOOD
- Airbus
- Zello
Push-to-Talk Market Report Scope
Table 5: Report Scope for the Push-to-Talk Market (coverage fields and definitions), 2026 to 2036
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Offering (Hardware, Solutions, Services); Network (Cellular or PoC, Land Mobile Radio); Enterprise Size (Large Enterprises, SMEs); Vertical (Public Safety and Security, Government and Defense, Transportation and Logistics, Travel and Hospitality, Energy and Utility) |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2036 |
| Market Definition | Revenue from dedicated push-to-talk hardware, software solutions and associated services used for immediate individual or group communication. It excludes general mobile subscriptions and ordinary voice-calling expenditure without a dedicated push-to-talk offer, and general-purpose smartphones unless sold as part of a dedicated push-to-talk commercial package. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | India, United Kingdom, South Korea, United States and Germany |
| Key Companies Covered | Motorola Solutions, Hytera, JVCKENWOOD, Airbus and Zello |
| Forecast Period | 2026 to 2036 (with 2025 historical baseline) |
| Approach | Combined primary interviews, secondary literature analysis, and top-down data triangulation |
Push-to-Talk Market - Research Methodology
The market assessment combines primary interviews with industry participants and secondary research drawn from company disclosures, trade data and industry publications. Market size is built from supply-side and demand-side estimates and validated top-down, and segment shares and competitive positioning are checked through data triangulation before publication.
Push-to-Talk Market by Segments
By Offering
- Hardware
- Solutions
- Services
By Network
- Cellular or PoC
- Land Mobile Radio
By Enterprise Size
- Large Enterprises
- SMEs
By Vertical
- Public Safety and Security
- Government and Defense
- Transportation and Logistics
- Travel and Hospitality
- Energy and Utility
By Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Home Office. Home Office and IBM to partner on Emergency Services Network. 15 January 2025.
- [2] AT&T FirstNet. Boosting AdventHealth safety and efficiency. n.d.
- [3] Deutscher Bundestag. Weiterentwicklung des Digitalfunks BOS. 31 March 2026.
- [4] Kahn, A., and Soucy, L. National Institute of Standards and Technology. Mission Critical Voice Roundtable Report. 14 March 2025.
- [5] European Telecommunications Standards Institute. LTE: Common functional architecture to support mission critical services, Stage 2 (ETSI TS 123 280 V19.9.0). February 2026.
- [6] First Responder Network Authority. 3GPP completes Release 19, while progress begins on 6G work. 2026.
- [7] Ministry of Home Affairs, India. Soliciting public opinion and stake holders input on Design of Network Architecture for the proposed Broadband Public Protection and Disaster Relief (BB-PPDR) System. 23 October 2026.
- [8] Samsung Electronics. Samsung Powers World's First 3GPP-Compliant Nationwide Public Safety Network With MCPTT Service in Korea. 26 April 2021.
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Offering, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Offering, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Offering, 2026 to 2036
- Hardware
- Solutions
- Services
- Y-o-Y Growth Trend Analysis By Offering, 2021 to 2025
- Absolute $ Opportunity Analysis By Offering, 2026 to 2036
- Global Market Analysis and Forecast, By Network, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Network, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Network, 2026 to 2036
- Cellular or PoC
- Land Mobile Radio
- Y-o-Y Growth Trend Analysis By Network, 2021 to 2025
- Absolute $ Opportunity Analysis By Network, 2026 to 2036
- Global Market Analysis and Forecast, By Enterprise Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Enterprise Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Enterprise Size, 2026 to 2036
- Large Enterprises
- SMEs
- Y-o-Y Growth Trend Analysis By Enterprise Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Enterprise Size, 2026 to 2036
- Global Market Analysis and Forecast, By Vertical, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vertical, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vertical, 2026 to 2036
- Public Safety and Security
- Government and Defense
- Transportation and Logistics
- Travel and Hospitality
- Energy and Utility
- Y-o-Y Growth Trend Analysis By Vertical, 2021 to 2025
- Absolute $ Opportunity Analysis By Vertical, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- By Country
- Market Attractiveness Analysis
- By Country
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Offering
- By Network
- By Enterprise Size
- By Vertical
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Motorola Solutions
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Hytera
- JVCKENWOOD
- Airbus
- Zello
- Motorola Solutions
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Offering, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Network, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Enterprise Size, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Vertical, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Offering
- Figure 6: Global Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Network
- Figure 9: Global Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Enterprise Size
- Figure 12: Global Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Vertical
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Offering
- Figure 29: North America Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Network
- Figure 32: North America Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Enterprise Size
- Figure 35: North America Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Vertical
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Offering
- Figure 42: Latin America Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Network
- Figure 45: Latin America Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Enterprise Size
- Figure 48: Latin America Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Vertical
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Offering
- Figure 55: Western Europe Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Network
- Figure 58: Western Europe Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Enterprise Size
- Figure 61: Western Europe Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Vertical
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Offering
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Network
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Enterprise Size
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Vertical
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Offering
- Figure 81: East Asia Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Network
- Figure 84: East Asia Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Enterprise Size
- Figure 87: East Asia Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Vertical
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Offering
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Network
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Enterprise Size
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Vertical
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Offering, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Offering, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Offering
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Network, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Network, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Network
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Enterprise Size, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Enterprise Size, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Enterprise Size
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Vertical, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Vertical, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Vertical
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
What is the size of the Push-to-Talk Market?
The global push-to-talk market was valued at USD 40.36 billion in 2025 and is estimated at USD 44.80 billion in 2026. It is forecast to reach USD 127.21 billion by 2036, expanding at a CAGR of 11.0% from 2026 to 2036.
Which offering and network lead the Push-to-Talk Market?
Hardware is estimated to hold 44.2% of revenue by offering in 2026, while cellular or PoC services are estimated to account for 58.7% by network.
Which country is likely to grow fastest in the Push-to-Talk Market?
India is likely to grow at a 13.2% CAGR during the forecast period, followed by the United Kingdom at 12.8%, South Korea at 10.4%, the United States at 9.8% and Germany at 9.1%.
Does every push-to-talk application qualify for emergency response?
No. Enterprise group calling and mission-critical services require different evidence of reliability and operating behaviour, and the particular product, its implemented functions and its service contract determine whether it meets the intended duty.
Why might an organisation retain dedicated radios?
Dedicated radios provide familiar controls and suitable accessories for demanding shifts. An operator may also retain an established radio system to control coverage and direct communication while introducing broadband features selectively.
What should a push-to-talk pilot include?
A pilot should cover normal routes and difficult reception areas, talk-group changes and the loss of a dependent connection. Mixed radio and broadband services also need the complete path between speaker and recipient tested.
Are cellular airtime charges part of this market?
No. General mobile airtime is excluded. Dedicated push-to-talk service revenue is included within the defined communication offer, and general-purpose smartphones are included only when sold as part of a dedicated push-to-talk commercial package. Competitive Analysis of the Push-to-Talk Market Key Players
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
