

- Market Size (2026)
- USD 15.7 Bn
- Forecast (2036)
- USD 24.1 Bn
- CAGR (2026 to 2036)
- 4.4%
How Big is the Tilapia Market in 2026?
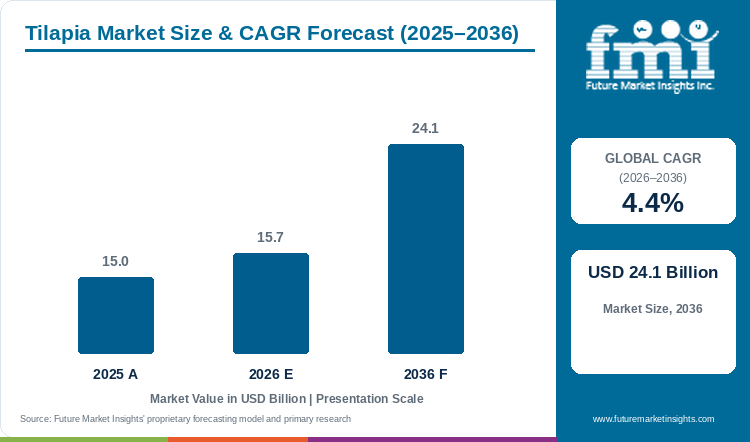
The tilapia market is valued at USD 15.7 billion in 2026 and is projected to reach USD 24.1 billion by 2036, growing at a 4.4% CAGR.
Tilapia market size is estimated at USD 15.7 Billion in 2026, up from USD 15.0 Billion in 2025, as per FMI, and sales will reach USD 24.1 Billion by 2036, about 1.5 times the 2026 base. Fish intake per head is moving in different directions. Germans ate 13.9 kg of fish per head in 2025, up from 12.3 kg a year earlier, and Japanese intake fell to 21.3 kg in 2024 [1] [2].
According to FMI's report, growth of the tilapia market at 4.4% will lead the parent pool. Sales of freshwater fish will contribute a valuation of USD 89.2 Billion to a 3% CAGR from 2026 to 2036. As a result, tilapia will continue to gain share inside the freshwater fish market. Demand for frozen formats will open adjacent opportunities for the market.
The frozen seafood market will add nearly USD 21.7 Billion at 5.7% over 2025 to 2035, and frozen fillets already made up 104,050 tonnes of USA tilapia imports in 2025 [3]. The fish feed market will create opportunities worth USD 47.7 Billion at 10.6% CAGR, and aquaculture vaccines market will add USD 662.6 Million at 8.6% CAGR. Mature whitefish buyers will add volume slowly, so growth will come from tilapia replacing pricier species on menus and freezer shelves.
Key Takeaways of Tilapia Market
- Conventional tilapia holds 61.1% of source market share in 2026.
- By species, Nile Tilapia will account for 80.4% of market share in 2026.
- Regal Springs, Yalelo, Charoen Pokphand Foods, BaiYang, Maoming Yuantian Food, Rangen, Skretting, and GenoMar Genetics are among the notable companies FMI profiles, out of many players covered in the full report.
- Sales of tilapia will grow the fastest in Japan (5.6%) and the USA (5.0%) through 2036.
- Demand in the USA shifted toward frozen fillets in 2025, with fillet imports up 9.3% even as total import value fell 7.3% [3].
Analyst Perspective
“As per my analysis, tilapia sales will grow from USD 15.7 Billion in 2026 to USD 24.1 Billion by 2036. With USA frozen fillet imports up 9.3% in 2025, I expect suppliers holding certified feed and steady fillet yield to take the next round of retail and foodservice contracts.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Tilapia Market Segmented?
FMI studies the tilapia market by source, species, and region.
Source covers conventional and organic tilapia.
Species covers Nile tilapia, Mozambique tilapia, blue tilapia, and Wami tilapia.
Why Does Conventional Tilapia Lead the Tilapia Market by Source?
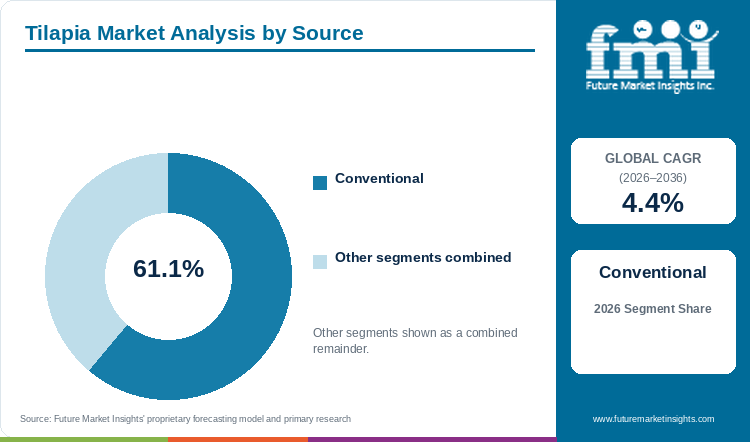
Accounting for 61.1% of source market share in 2026, conventional farming will lead the source category.
Most tilapia comes from cages and ponds run under standard farm rules, so processors can buy large lots at short notice. Brazil alone produced 707,495 tonnes in 2025, up 6.8% on 2024 [3].
Organic supply will grow from a much smaller base. Certified organic farms need approved feed, lower stocking and separate audits, and that cost shows up on the shelf. Retail buyers in the USA and Germany still buy mainly on price per fillet.
- By source, conventional tilapia will account for 61.1% of market share in 2026. Demand will stay driven by price per fillet and large lot sizes.
- Certification now reaches the feed mill, as ASC-certified farms have had to source feed from ASC-certified mills since October 31, 2025 [5].
Why is Nile Tilapia the Largest Species in the Tilapia Market?
By species, Nile Tilapia (OREOCHROMIS NILOTICUS) will account for 80.4% of market share in 2026.
Demand for Nile tilapia stays high because breeders, feed makers and processors have built decades of work around the species. Fast growth in warm water and good fillet yield give farms a predictable harvest size. GenoMar Genetics breeds Oreochromis niloticus lines for fast growth and disease resistance [6].
Larger Nile tilapia also open premium cuts. Regal Springs set a minimum King Tilapia loin of 106 g and 19 mm thickness, with cooking yield above 85% [7]. Mozambique, blue and Wami tilapia keep smaller regional roles.
- An 80.4% share of species market revenue in 2026 will belong to Nile Tilapia.
- In August 2026, GenoMar Genetics Vietnam reported annual output of nearly 150 million tilapia fingerlings, from the 35th generation of selected fish, and expected sales to rise 25% to 30% [8].
What are the Drivers, Restraints, and Opportunities in the Tilapia Market?
As per FMI, price-sensitive demand for whitefish will keep lifting sales of tilapia through 2036. Tariffs, freight and food safety checks add cost to the border. Premium grades and certified feed give suppliers the clearest room to grow.
- Driver: Cod and haddock prices keep rising, and chip shops, retailers and caterers are testing tilapia as a cheaper whitefish.
- Restraint: Tariffs, freight costs and food safety inspections raise land costs and can hold back shipments from new origins.
- Opportunity: Larger graded fish, certified feed and traceable farms let suppliers sell on quality instead of price alone.
Sales of tilapia face tariff and inspection risk at every border. FAO expects tariffs, freight costs and food safety requirements to keep shaping tilapia trade in 2026 [3]. USA tariffs on Chinese tilapia reached a cumulative 45%, and Vietnamese farms moved quickly into that gap [9]. Vietnam's tilapia export value rose more than 140% in 2025 to about USD 99 million, mostly to the USA [3]. Price adds a second constraint. USA import value fell 7.3% in 2025 even as volume rose 0.8% [3]. Feed makes up 60% to 70% of production cost on Vietnamese farms, owing to which feed price swings reach the landed price of a fillet quickly, a cost line FMI tracks in the aquafeed market study [8].
Which Country CAGRs are Profiled in the Tilapia Market?
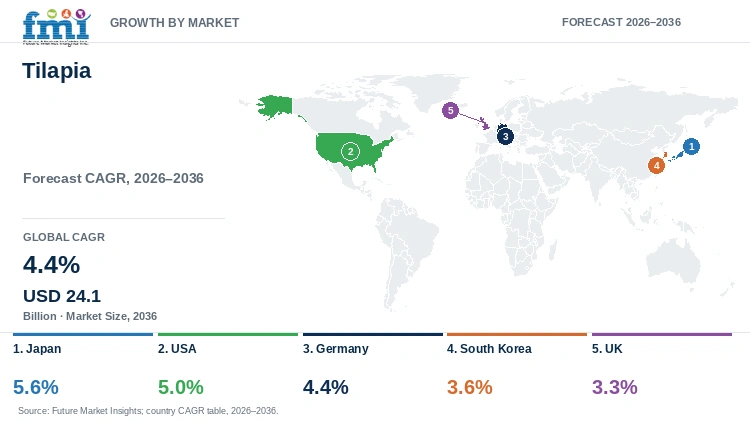
| Country | CAGR, 2026 to 2036 |
|---|---|
| Japan | 5.6% |
| USA | 5% |
| Germany | 4.4% |
| South Korea | 3.6% |
| UK | 3.3% |
How do Country-level CAGRs Compare in the Tilapia Market?
Tilapia market growth across the five profiled countries spans 2.3 percentage points till 2036, from Japan at 5.6% to the UK at 3.3%. The USA will follow at 5%; Germany will match the global pace at 4.4% CAGR through 2036. Import rules, fish intake and the price gap against cod decide most of the spread.
- Japan will grow the fastest from a small tilapia base. Importers will sell on value per portion as household fish intake keeps falling.
- Sales of tilapia in the USA rest on the largest import flow among the five, with 184,851 tonnes landed in 2025 [3].
- Germany will match the global CAGR.
- South Korea and the UK differ by only 0.3 points, though Korean consumers eat about 60 kg of seafood per head and UK chip shops still sell mostly cod and haddock [10] [11].
The full FMI report covers tilapia growth rates for more than 30 countries across seven regions, from North America and Latin America to East Asia, South Asia and Pacific, and the Middle East and Africa.
Country Outlook
- Demand for tilapia in Japan will grow at a 5.6% CAGR from 2026 to 2036, the fastest among the profiled countries. The 2025 Fisheries White Paper, released in June 2026, put seafood intake at 21.3 kg per head in 2024, down from 40.2 kg in 2001 [1]. Households buy less fish, so boneless frozen fillets that cook in minutes stand a better chance than whole fish, and FMI's seafood market study tracks the wider demand base.
- Sales of tilapia in the USA will rise at a 5.0% CAGR till 2036, from the largest import base among the five countries. FAO reported in May 2026 that USA tilapia imports reached 184,851 tonnes in 2025, worth USD 692 million, with frozen fillets at 104,050 tonnes [3]. Retail and foodservice buyers will keep moving toward fillets, and Vietnamese and Latin American suppliers will compete with China for those contracts.
- Growth of the tilapia market in Germany will reach a 4.4% CAGR, in line with the global rate. Destatis reported in June 2026 that German farms produced 16,600 tonnes of fish in 2025, led by trout at 59.5% and carp at 27.6% [12]. Tilapia does not appear among the main farmed species, so supply runs through importers. Discounters handled 49% of household fish purchases in 2025, and frozen tilapia fillets will need sharp pricing to gain shelf space [2].
- Sales of tilapia in South Korea will rise at a 3.6% CAGR through 2036. USDA's Seoul office reported in November 2025 that Korea imported USD 5.52 billion of seafood in 2024, with intake near 60 kg per head a year [11]. Frozen pollack, cod and plaice fillets already enter at 0% duty under KORUS, so tilapia competes against familiar whitefish and exporters with clean inspection records will gain listings first.
- A 3.3% CAGR from 2026 to 2036 places the UK at the lower end of the profiled range, yet the chip shop channel is starting to open. Seafish counted 7,210 fish and chip shops in a June 2026 report, with cod and chips averaging GBP 11.41 [10]. Regal Springs began rolling out King Tilapia to UK chip shops in August 2026 through F. Smales Fish Merchants, using fish from ASC-certified farms in Indonesia and Central America [13]. Shop owners will judge tilapia on portion cost and frying performance.
Who are the Notable Companies in the Tilapia Market?
FMI profiles Regal Springs, Yalelo, Charoen Pokphand Foods, BaiYang, Maoming Yuantian Food, Rangen, Skretting, and GenoMar Genetics among the notable companies in the tilapia market.
As per FMI, tilapia market share among suppliers follows control of farms, seed and feed more than brand names. Integrated farmers sell graded fish under own labels with the farm certificates retailers ask for. Chinese processors are building plants and farms in Vietnam and Ghana as tariffs reshape trade. FMI's fish processing market analysis tracks processor positions in more detail.
- Integrated Farmers Selling Branded Tilapia: Regal Springs and Yalelo farm, process and sell own-brand tilapia.
- Asian Agrifood and Processing Groups with Tilapia Lines: Charoen Pokphand Foods, BaiYang and Maoming Yuantian Food run tilapia feed, processing or farm projects across Asia and Africa.
- Feed and Genetics Suppliers to Tilapia Farms: Rangen, Skretting and GenoMar Genetics supply certified feed and selected Nile tilapia seed.
Competitive Benchmarking
| Company | Own Tilapia Farming and Processing | Tilapia Feed and Genetics | Certification and Traceability | Geographic Reach |
|---|---|---|---|---|
| Regal Springs | High | Low | High | Mexico, Honduras and Indonesia farms; USA, Canada and Europe sales |
| Yalelo | High | Low | Low | Zambia, Uganda, Kenya and the DRC |
| Charoen Pokphand Foods | Low | High | Low | Thailand and wider Asia |
| BaiYang | High | Medium | Low | China and Vietnam |
| Maoming Yuantian Food | Medium | Low | Low | China (Guangdong) and Ghana |
| Rangen | Low | High | High | USA (Idaho and Texas mills) |
| Skretting | Low | High | Medium | 18 countries, including Egypt, Honduras and Vietnam |
| GenoMar Genetics | Low | High | Medium | Vietnam, the Philippines, Malaysia and Latin America |
Scoring basis: Own Tilapia Farming and Processing measures documented tilapia farms and processing plants. Tilapia Feed and Genetics measures documented tilapia feed lines, broodstock programs and fingerling supply. Certification and Traceability measures documented ASC, BAP or comparable certification tied to tilapia. High indicates broad documented capability, Medium narrower documented capability and Low limited public documentation. In September 2026, FMI reviewed public company documentation and trade press to set these scores.
Key Developments
- In April 2026, Regal Springs introduced King Tilapia under a four-tier quality standard of King, Prime, Choice and Base, with King loins of at least 106 g [7].
- In November 2025, Rangen's Buhl, Idaho mill became the first US feed mill to gain ASC Feed Certification, with tilapia among the species in scope [5].
- In July 2026, Viet Nhat Group and BaiYang began operating an integrated tilapia processing plant in Vietnam with a first-line capacity of 200 tonnes a day, planned to reach 300 tonnes [14].
- In September 2026, Maoming Yuantian Food signed a commercial fish farming investment agreement in Ghana's Volta Basin [15].
Key Players
Integrated Farmers Selling Branded Tilapia
- Regal Springs
- Yalelo
Asian Agrifood and Processing Groups with Tilapia Lines
- Charoen Pokphand Foods
- BaiYang
- Maoming Yuantian Food
Feed and Genetics Suppliers to Tilapia Farms
- Rangen
- Skretting
- GenoMar Genetics
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | 3 categories: Source (Conventional, Organic), Species (Nile Tilapia, Mozambique Tilapia, Blue Tilapia, Wami Tilapia), and Region |
| Quantitative units | USD Billion |
| Market definition | Revenue from live, whole, fresh, chilled and frozen tilapia within the stated source and species segmentation, including primary-processed fillets and loins sold as tilapia products. The market excludes prepared meals, seasoned ready-to-eat products, restaurant markup, aquafeed revenue, hatchery-only inputs and substitute whitefish. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | 30+ countries, including Japan, the USA, Germany, South Korea, and the UK |
| Key companies profiled | A few of the notable companies out of many players covered by FMI include Regal Springs, Yalelo, Charoen Pokphand Foods, BaiYang, Maoming Yuantian Food, Rangen, Skretting, and GenoMar Genetics. |
| Forecast period | 2026 to 2036 |
| Approach | FMI applies a hybrid bottom-up and top-down sizing framework that reconciles farm output, import and export volumes, processor revenue signals and fillet prices with retail and foodservice demand in each country. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | FMI speaks with tilapia farmers, processors, feed and seed suppliers, importers, seafood distributors, retail category buyers and foodservice operators to test fillet prices, yield, certification timelines, landed cost and the split between fresh and frozen sales. |
| Desk research | The analysis reviews FAO trade reviews, national fisheries and customs statistics, import inspection rules in the profiled countries, certification standards, company announcements and trade press. FMI keeps sources that describe production, trade, certification or company activity inside the market boundary. |
| Market sizing and forecasting | The sizing framework combines farm output and trade volumes with average selling prices by product form and channel, tariff and freight costs, importer margins and the pace of retail and foodservice listings. Forecasts consider feed cost, tariff changes, origin shifts and movement between whole fish, fillets and premium grades. |
| Data validation | Company evidence is checked against trade statistics and channel data, and segment logic is tested against the revenue boundary. Prepared meals, feed and hatchery revenue, substitute whitefish and duplicate counting between importers and distributors are removed before final reconciliation. |
Tilapia Market by Segments
Tilapia Market Segmented by Source
- Conventional
- Organic
Tilapia Market Segmented by Species
- Nile Tilapia (OREOCHROMIS NILOTICUS)
- Mozambique Tilapia (OREOCHROMIS MOSSAMBICUS)
- Blue Tilapia (OREOCHROMIS AUREUS)
- Wami Tilapia (OREOCHROMIS UROLEPIS HORNORUM)
Tilapia Market Segmented by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] AgNavigator (2026, June 10). Japan is turning to aquaculture exports as domestic seafood demand falls.
- [2] Fisch-Informationszentrum (2026, September 11). Deutschlands Appetit auf Fisch wächst.
- [3] Food and Agriculture Organization of the United Nations (2026, May 27). Price-sensitive demand shifts tilapia trade towards frozen fillets.
- [4] SeafoodSource (2026, March 6). Regal Springs launches King Tilapia product alongside open standard to tackle whitefish supply gap.
- [5] SeafoodSource (2025, November 13). Rangen becomes first US firm to secure ASC Feed Certification.
- [6] GenoMar Genetics (2026, September). 35 years of tilapia breeding.
- [7] Regal Springs (2026, April 16). Introducing King Tilapia: A New Global Benchmark for Premium Tilapia.
- [8] SeafoodSource (2026, August 24). GenoMar Genetics Vietnam enjoying tilapia seed sales spike thanks to rapid sector expansion.
- [9] Aqua Culture Asia Pacific (2025, November 24). The tilapia in North Vietnam.
- [10] Restaurant Online (2026, June 29). The UK is home to 7,210 fish and chip shops, according to a new report.
- [11] U.S. Department of Agriculture, Foreign Agricultural Service (2025, November 25). Korea Seafood Market Update 2025.
- [12] Statistisches Bundesamt (2026, June 5). 1,2 % weniger Fisch aus Aquakulturen im Jahr 2025.
- [13] Undercurrent News (2026, August 28). Regal Springs launches first king tilapia at UK chippies.
- [14] Asian Agribiz (2026, July 9). Viet Nhat, BaiYang launch new integrated tilapia processing plant.
- [15] Undercurrent News (2026, September 22). Chinese tilapia processor signs Ghana aquaculture investment deal.
This bibliography is provided for reader reference and is not exhaustive. The full FMI report contains the complete reference list and detailed citations.
This Report Answers
- What will the Tilapia Market size be in 2026, and what value is FMI forecasting for 2036?
- Which import trends and buying habits will keep supporting demand for tilapia across retail and foodservice?
- Why will conventional tilapia hold the leading position within the Source category through 2036?
- How will Nile Tilapia (OREOCHROMIS NILOTICUS) shape breeding, feed and fillet supply across the Species category?
- How will growth rates differ across Japan, the USA, Germany, South Korea, and the UK till 2036?
- Which capabilities will separate integrated farmers, processing groups and feed and genetics suppliers?
- How will tariffs, freight costs and food safety checks slow new tilapia origins?
- Which channels will premium grades such as King Tilapia open in chip shops and retail?
- What will importers, retailers and caterers need to check before qualifying a new tilapia supplier?
Frequently Asked Questions
How big is the tilapia market in 2026?
FMI estimates the tilapia market at USD 15.7 Billion in 2026, up from USD 15.0 Billion in 2025. Frozen fillet imports into the USA and steady whitefish demand in retail and foodservice account for much of that value.
What is the CAGR of the tilapia market from 2026 to 2036?
According to FMI, the tilapia market will grow at a 4.4% CAGR from 2026 to 2036, taking sales to USD 24.1 billion by 2036. Premium grades and wider frozen distribution will add to the pace.
Which source segment holds the largest share of the tilapia market?
Conventional tilapia leads with 61.1% of source revenue in 2026. Standard cage and pond farms supply large lots at lower cost than certified organic farms.
Which species leads the tilapia market?
As per FMI, Nile Tilapia (OREOCHROMIS NILOTICUS) holds 80.4% of species revenue in 2026. Selective breeding, broad feed tolerance and good fillet yield keep Nile tilapia ahead.
Which country grows fastest in the tilapia market?
Sales of tilapia in Japan will grow at a 5.6% CAGR till 2036, ahead of the USA at 5.0%. The UK is the slowest of the five profiled countries at 3.3%.
What notable restraint affects the tilapia market?
Tariffs, freight costs and food safety checks will raise landed cost and slow new origins. Falling import prices in the USA will also squeeze margins for exporters.
Which are the key companies in the tilapia market?
Regal Springs, Yalelo, Charoen Pokphand Foods, BaiYang, Maoming Yuantian Food, Rangen, Skretting, and GenoMar Genetics are a few of the notable companies, out of many players covered by FMI.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Species, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Species, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Species, 2026 to 2036
- Nile Tilapia (OREOCHROMIS NILOTICUS)
- Mozambique Tilapia (OREOCHROMIS MOSSAMBICUS)
- Blue Tilapia (OREOCHROMIS AUREUS)
- Wami Tilapia (OREOCHROMIS UROLEPIS HORNORIUM)
- Y-o-Y Growth Trend Analysis By Species, 2021 to 2025
- Absolute $ Opportunity Analysis By Species, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Source
- By Species
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Species
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Species
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source
- By Species
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Regal Springs
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Yalelo
- Charoen Pokphand Foods
- BaiYang
- Maoming Yuantian Food
- Rangen
- Skretting
- GenoMar Genetics
- Regal Springs
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


