

- Market Size (2026)
- USD 14.9 Bn
- Forecast (2036)
- USD 416.3 Bn
- CAGR (2026 to 2036)
- 39.5%
How big is the Workflow-as-a-Service Market in 2026?
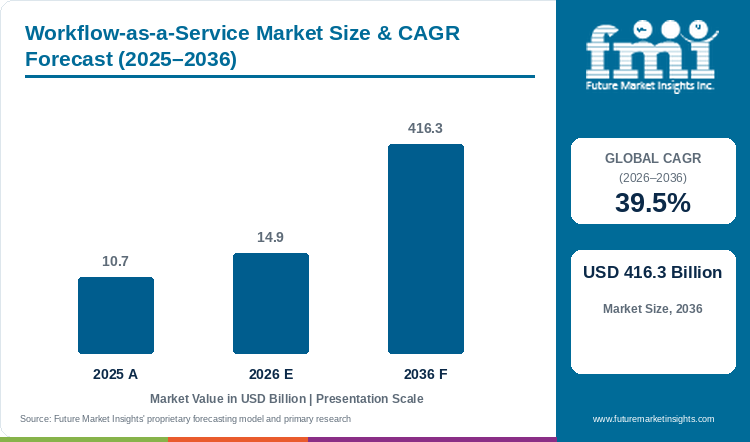
The global workflow-as-a-service market is estimated at USD 14.92 billion in 2026, compared with USD 10.69 billion in 2025, and is forecast to reach USD 416.27 billion by 2036, expanding at a CAGR of 39.5% from 2026 to 2036.
Demand for workflow-as-a-service is driven by large enterprises that coordinate approvals across many departments and is expanding to smaller firms as more of their business software moves online. Wider cloud use and the demand for control over automated actions are supporting this demand, and the market is expected to grow at a rate approaching 40% a year through 2036. One example is ServiceNow, which in its results published on 28 January 2026 reported 244 transactions worth more than USD 1 million each in net new annual contract value in the fourth quarter of 2025, and 603 customers with more than USD 5 million in annual contract value at year-end. [1] Another is Eurostat's finding that 52.7% of EU enterprises bought cloud services in 2025, up 7.4 percentage points from 2023. [2] These facts show where large automation budgets sit and how many online applications a hosted workflow can connect, and they do not show workflow-service revenue, because the ServiceNow counts cover its whole platform and the Eurostat figure covers all paid cloud services.
Control of automated actions is a second driver. NIST's concept paper of 5 February 2026 identifies agent identity, authorisation and auditing as questions for a proposed standards demonstration project. [3] In the UK government's 2025 AI adoption research, published in 2026, 67% of AI-using businesses reported significant human input or checking. [4] Therefore, workflows that retain approval steps and a record of automated actions meet a requirement that buyers are already raising. According to FMI analysis, providers that keep those controls alongside connections to business applications have a stronger case for continuing service contracts. The NIST paper is a concept paper and not a binding standard, so it signals the questions buyers will ask and not a compliance rule.
Market Size & Forecast
Table 1: Workflow-as-a-Service Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value | USD 10.69 billion |
| Estimated market size in 2026 | USD 14.92 billion |
| Projected market size by 2036 | USD 416.27 billion |
| CAGR (2026-2036) | 39.5% |
| Added revenue, 2026 to 2036 | USD 401.35 billion |
Key Market Trends & Insights
- IT and operations is estimated to account for 32.6% of revenue by business workflow in 2026, because access requests, approvals and withdrawals repeat often enough to be described and followed in a hosted service.
- Large enterprises are expected to hold 61.4% of revenue by enterprise size in 2026, so contracts that span many teams and applications set the base of sales.
- Large automation contracts are concentrated. ServiceNow's fourth-quarter 2025 results show 244 transactions above USD 1 million, [1] which supports workflow orders across departments.
- Cloud use widens the base of connectable applications. Paid cloud services reached 52.7% of EU enterprises in 2025, [2] which gives workflow suppliers more applications to link.
- Agent control enters supplier selection. NIST's February 2026 concept paper addresses identity, authorisation and auditing for software agents, [3] so visible permissions and action records influence the choice as workflows delegate more tasks to AI.
- Customer readiness differs within one buyer. Of AI-adopting UK businesses, 77.0% had fewer than half of their staff using AI, [4] so training and manual intervention remain part of the contract.
Regional Highlights
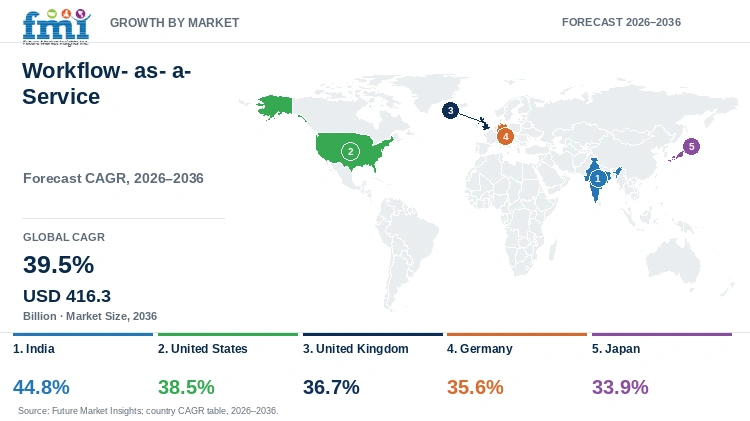
- India is likely to grow at a 44.8% CAGR during the forecast period, followed by the United States at 38.5%, the United Kingdom at 36.7%, Germany at 35.6% and Japan at 33.9%.
Analyst Perspective
“Enterprises pay for workflow services when approvals move reliably across applications. Providers that preserve spending authority and make exceptions easy to resolve can turn an initial automation project into a continuing service as customers introduce AI actions into existing processes.”
- Sudip Saha, Principal Consultant, FMI
How is the Workflow-as-a-Service Market segmented?
The Workflow-as-a-Service Market is segmented by solution, business workflow, enterprise size, industry and region.
- By Solution: Cloud Platform.
- By Business Workflow: HR, IT and Operations, Sales and Marketing, Finance and Accounting, Customer Service and Others.
- By Enterprise Size: SMEs and Large Enterprises.
- By Industry: IT and Telecom, BFSI, Retail, Manufacturing, Healthcare, Education and Others.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why is IT and Operations the Leading Business Workflow in the Workflow-as-a-Service Market?
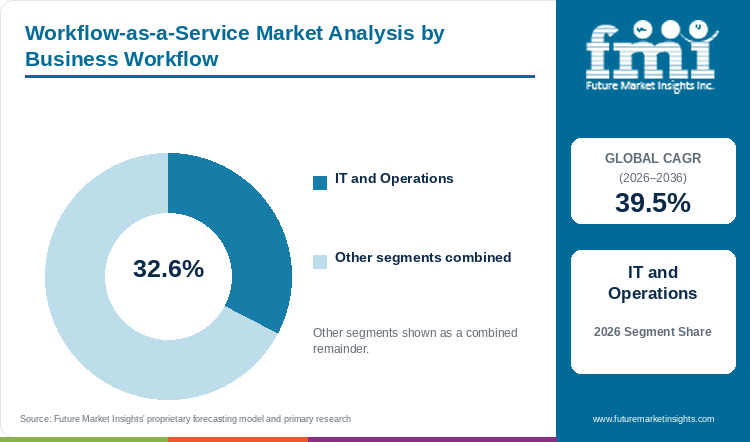
IT and operations accounts for an estimated 32.6% of workflow-as-a-service revenue by business workflow in 2026, equal to about USD 4.86 billion, as per FMI's analysis.
Table 2: Business Workflow Share for the Workflow-as-a-Service Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| IT and Operations | 32.6% |
| Other segments combined | 67.4% |
A request for system access needs an owner and an approval before the change is made, and access may need to be withdrawn when an employee leaves. These repeated steps give a service desk work that it can describe and follow without collecting separate emails from every participant. NIST's February 2026 concept paper identifies identity and authorisation questions for software and AI agents, [3] so a provider that shows which account carries out an access change makes the action easier for the customer to examine.
However, repeat requests are not all alike. A contractor may need a different approval from a permanent employee, and a connected application may be unavailable when the action is due, so the workflow has to show the exception and assign it to a responsible person.
The other business workflows together hold the remaining 67.4%. Providers best placed to retain the IT and operations contracts keep request ownership, action history and exception handling clear, and let operations teams change the process after the original implementation team has moved on.
Why are Large Enterprises the Leading Enterprise Size in the Workflow-as-a-Service Market?
Large enterprises hold an estimated 61.4% of workflow-as-a-service revenue by enterprise size in 2026.
Table 3: Enterprise Size Share for the Workflow-as-a-Service Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Large Enterprises | 61.4% |
| Other segments combined | 38.6% |
Their processes extend across more teams and applications, which increases the work covered by a contract. One department may require a local approval while another sends the same task to a central shared-service centre, so a hosted service must support both arrangements, and administration rights need to let a department improve its process without changing a corporate control.
Governance continues after deployment. A buyer may need to retain the history of a process after a new version is introduced or transfer responsibility when a business unit is reorganised, so ownership and version changes affect the case for wider deployment as much as the process-design interface does.
However, an organisation's size does not mean that all its staff are ready for automation. UK government research found that 77.0% of AI-adopting businesses had fewer than half of their staff using AI. [4] That is a measure of AI use and not of workflow-service adoption, but it shows why training and manual intervention can remain necessary within one customer. Providers best placed separate administration rights, preserve process history and support controlled expansion across departments.
What are the Key Drivers, Restraints and Opportunities in the Workflow-as-a-Service Market?
The workflow-as-a-service market is expected to grow from USD 14.92 billion in 2026 to USD 416.27 billion by 2036, which adds USD 401.35 billion over the forecast period. Repeated application handovers support demand, while unclear ownership and permissions can delay adoption, and maintained departmental workflows provide an opportunity for continuing subscriptions.
Driver: work across application boundaries. A request can start in one system and need an action in another, leaving staff to check whether it arrived and whether someone acted. Hosted coordination reduces that work when the applications have reliable interfaces. Integration platform as a service provides the connections, while the workflow determines the sequence and ownership of business actions, and the commercial case strengthens when a first deployment reduces delays and repeated manual intervention.
Restraint: permissions and unresolved exceptions. Automating an unclear approval process can repeat mistakes faster and make responsibility harder to establish. An AI action still needs an account and an authorised purpose, as the NIST concept paper makes clear, [3] and incomplete information or an unavailable approver can stop a process even when its diagram looks complete.
Opportunity: continuing maintenance of departmental work. An HR team can begin with onboarding tasks for equipment and building access, and a finance team can begin with an approval tied to spending authority. The OECD's December 2025 paper distinguishes SME adoption by digital maturity and use complexity, [5] so suppliers can serve these differences through help defining a first process for a smaller customer and controlled expansion for a larger one.
Providers that maintain the connections and make responsibility visible are best placed to capture continuing expenditure. A workflow that leaves the same unresolved request moving between applications has a weaker case for renewal.
How do Technical Guidance and Control Requirements Influence Workflow Demand?
Control requirements affect which work a customer will delegate to a hosted service. The published evidence covers software-agent permissions, the applications available to connect and the ability of staff to use the resulting process, and these are separate questions for implementation.
Guidance on the identity and authority of software agents
NIST's concept paper of 5 February 2026 addresses software and AI-agent identity and authorisation. [3] It is not a binding workflow product standard, but it gives a concrete basis for asking who performs an automated action, what that account can change and how an administrator can restrict it.
Evidence on the applications a workflow can connect
Eurostat's 2025 paid-cloud adoption figure of 52.7% describes a wider base of cloud services among EU enterprises. [2] However, cloud availability alone does not show that a particular application exposes a usable connection or that a customer has delegated a business process, so the supplier still needs to show how the proposed handover will operate.
Evidence on staff use and customer readiness
The UK finding that 77.0% of AI-adopting businesses had fewer than half of their staff using AI points to differences within a customer, [4] and the OECD also distinguishes firms by digital maturity and complexity of use. [5] These differences affect training, the first process selected and the amount of implementation support needed.
Published guidance and adoption evidence make the controls around a workflow more visible in procurement. A provider that can explain the permissions, show the action history and leave a clear route for human intervention has a stronger position when security and operations teams assess the service.
What Technical and Operational Constraints Affect Workflow Services?
The constraints arise both between applications and inside the customer's organisation, and connecting the software does not by itself settle who owns the work.
The first is the connection. A hosted workflow needs reliable application interfaces and support when those interfaces change. Existing robotic process automation can remain useful where an application lacks a suitable interface, but the workflow must coordinate that component without hiding failures.
The second is the exception. Information may be incomplete, an approver may be unavailable or a connected application may stop responding. The service needs to record the failed action, make it clear whether it can be repeated safely and direct the case to a person who can act.
The third is change. Staff move between roles, departments reorganise and a process gains a new version. The customer needs to retain the history of work already done and understand whether the change affects a continuing transaction or another department's authority.
The fourth is responsibility for administration. A customer comparing workflow management software with a hosted service needs a clear division of work between its administrators and the provider, and specific permissions with a visible route for human intervention can reduce delays during security and operations review.
These constraints favour providers with maintained connections, clear process records and continuing support. A process that repeatedly falls back to email gives the customer a limited incentive to expand the contract.
Where are the Commercial Opportunities for Workflow Providers?
The opportunity lies in a useful first process, continued support and expansion that the customer can govern. The broader business process automation market covers several delivery approaches, and hosted workflow suppliers compete through the connections and service obligations they maintain.
The first is departmental work with a clear outcome. Equipment and access tasks in onboarding, or an approval with a defined spending authority, let a supplier demonstrate the service on work the customer can follow. Delays and manual intervention can then be examined before more processes are added.
The second is implementation that matches the customer. The OECD's SME analysis identifies differences in digital maturity and use complexity, [5] so a smaller firm may need help documenting its first process, while a large enterprise may need separate administration rights and support for local and central approvals.
The third is a contract that supports increasing use. A workflow can run many times without a person opening its interface, so execution charges and limits on connected applications may matter more than the seat price. Failed executions, retries and the support provided after an application change affect the cost of wider deployment, and providers that explain those terms clearly can help a customer expand from one successful process to another.
Workflow-as-a-Service Market by Country (2026 to 2036)
Table 4: Country Growth Outlook for the Workflow-as-a-Service Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026-2036) |
|---|---|
| India | 44.8% |
| United States | 38.5% |
| United Kingdom | 36.7% |
| Germany | 35.6% |
| Japan | 33.9% |
What is driving workflow demand in India?
India is likely to grow at a 44.8% CAGR during the forecast period, the highest rate among the countries analysed.
ServiceNow's March 2026 India survey found that customer service representatives used an average of four systems to resolve a query. [6] That is an advantage for hosted workflows that connect those systems and reduce repeated transfers of work. The disadvantage is that the survey measures customer service practice and not workflow spending, and local implementation support can decide the order where established enterprise applications sit alongside smaller departmental tools.
Repeat service work across distributed offices and delivery teams gives providers a practical starting point, since a request reaches the person responsible while a central supervisor sees the exceptions. Use across an organisation also raises execution volume, which makes clear usage terms and maintainable connections important to continuing adoption.
What is supporting workflow demand in the United States?
The United States is likely to grow at a 38.5% CAGR during the forecast period.
The September 2025 OneGov agreement between the General Services Administration and ServiceNow offers eligible federal customers a 70% discount from list prices on ITSM Pro and Pro Plus bundle upgrades through September 2028. [7] The lower upgrade cost is an advantage because it supports expansion of automated service workflows across federal agencies. The disadvantage is that the discount applies to one supplier's bundles, and agents introduced into operational work still need an identified account and bounded permissions.
Providers need to show how an administrator can restrict an action and inspect its history. Existing robotic process automation may remain part of the work where applications lack suitable interfaces, so the hosted workflow has to coordinate those components and make failures visible.
What affects workflow adoption in the United Kingdom?
The United Kingdom is likely to grow at a 36.7% CAGR during the forecast period.
Government research published on 28 January 2026 found that 47% of businesses using or planning to use AI cited automation as a use case. [4] That is an advantage because it gives workflow providers an opening to connect AI actions with approvals and existing business systems. The disadvantage is that familiarity differs inside a business: the same research found that 77.0% of AI-adopting businesses had fewer than half of their staff using AI, and that figure concerns AI use and is not a workflow-market share.
One team may be ready to connect several applications while another first needs a clear procedure and training. Suppliers that keep manual intervention visible help staff complete the work and understand why an automated step stopped.
What shapes workflow purchasing in Germany?
Germany is likely to grow at a 35.6% CAGR during the forecast period.
In August 2025, the DFL Deutsche Fussball Liga selected ServiceNow to replace legacy systems and automate business workflows. [8] Replacing separate systems creates orders for workflow platforms and for the integration work needed to connect employees, clubs and partners, which is an advantage. The disadvantage is version control across locations, since a process change should not unexpectedly alter another department's authority or interrupt a continuing transaction.
A manufacturing or service organisation may need an approval to cross departments while responsibility remains assigned to a specific team. The purchasing discussion therefore covers which information sits in the hosted service and which remains in existing applications, and suppliers still need to demonstrate the proposed integration for each buyer.
What supports workflow implementation in Japan?
Japan is likely to grow at a 33.9% CAGR during the forecast period, the lowest rate among the countries analysed.
In January 2026, Fujitsu and Mizuho Bank announced development of an order and payment processing service after a demonstration streamlined approximately 70% of order-processing tasks. [9] A service that connects orders and payments and reduces manual data entry is an advantage for smaller customers. The disadvantage is that established working procedures have to be translated into a service that staff can use confidently, since a request may follow different approvals according to its value or the department involved.
Beginning with a process whose owner and outcome are clear gives staff a way to learn exception handling before more applications are connected. Continued support as existing software changes can then determine whether a departmental project becomes a wider contract.
Who are the notable companies in the Workflow-as-a-Service Market?
The named companies differ by the applications through which they reach the customer and the work their platforms coordinate. Microsoft, ServiceNow, Salesforce, Pegasystems and Appian are included for relevant capabilities and not for a revenue ranking.
Microsoft offers Power Automate cloud flows for Microsoft application users and connected services. ServiceNow provides workflow automation on its platform for service and operational process owners. These positions give each company a route into tasks already associated with an enterprise platform or service desk.
Salesforce provides Flow Builder and Flow Orchestration for customer-facing business operations. Pegasystems supplies workflow and case-management capabilities through Pega Platform, while Appian combines process automation with business application development. These positions offer different approaches to work that crosses systems or involves cases and business rules.
However, a broad portfolio does not show that a customer can govern the proposed process. An existing platform may suit one service desk, while another organisation needs a separate process platform to coordinate unrelated systems, and application changes, support incidents and the cost of operation continue to affect renewal. Providers best placed to retain customers keep the connections working and give process owners a clear way to stop, revise and examine the work after launch.
Key Developments in the Workflow-as-a-Service Market
- On 5 February 2026, NIST published its concept paper on software and AI-agent identity and authorisation, raising control questions for automated actions across systems. [3]
- On 3 February 2026, Eurostat reported that 52.7% of EU enterprises used paid cloud services in 2025. [2]
- On 28 January 2026, the UK Department for Science, Innovation and Technology published AI Adoption Research. [4]
- On 22 January 2026, Fujitsu and Mizuho Bank announced a partnership to develop an order and payment processing service for SMEs. [9]
- On 9 December 2025, the OECD published its G7 discussion paper on SME AI adoption, distinguishing firms by digital maturity and use complexity. [5]
- On 3 September 2025, the US General Services Administration and ServiceNow announced the OneGov agreement. [7]
Key Players in the Workflow-as-a-Service Market
- Microsoft
- ServiceNow
- Salesforce
- Pegasystems
- Appian
Workflow-as-a-Service Market Report Scope
Table 5: Report Scope for the Workflow-as-a-Service Market (coverage fields and definitions), 2026 to 2036
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Solution (Cloud Platform); Business Workflow (HR, IT and Operations, Sales and Marketing, Finance and Accounting, Customer Service, Others); Enterprise Size (SMEs, Large Enterprises); Industry (IT and Telecom, BFSI, Retail, Manufacturing, Healthcare, Education, Others) |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2036 |
| Market Definition | Revenue from cloud-delivered workflow platforms and associated services that coordinate business tasks, approvals and execution across users or applications. It excludes general cloud infrastructure, complete enterprise application expenditure and business-process outsourcing revenue without a dedicated hosted workflow service. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | India, United States, United Kingdom, Germany and Japan |
| Key Companies Covered | Microsoft, ServiceNow, Salesforce, Pegasystems and Appian |
| Forecast Period | 2026 to 2036 (with 2025 historical baseline) |
| Approach | Combined primary interviews, secondary literature analysis, and top-down data triangulation |
Workflow-as-a-Service Market - Research Methodology
The market assessment combines primary interviews with industry participants and secondary research drawn from company disclosures, trade data and industry publications. Market size is built from supply-side and demand-side estimates and validated top-down, and segment shares and competitive positioning are checked through data triangulation before publication.
Workflow-as-a-Service Market by Segments
By Solution
- Cloud Platform
By Business Workflow
- HR
- IT and Operations
- Sales and Marketing
- Finance and Accounting
- Customer Service
- Others
By Enterprise Size
- SMEs
- Large Enterprises
By Industry
- IT and Telecom
- BFSI
- Retail
- Manufacturing
- Healthcare
- Education
- Others
By Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] ServiceNow. ServiceNow Reports Fourth Quarter and Full-Year 2025 Financial Results; Board of Directors Authorizes Additional $5B for Share Repurchase Program. 28 January 2026.
- [2] Eurostat. 53% EU enterprises used paid cloud services in 2025. 3 February 2026.
- [3] National Institute of Standards and Technology. Accelerating the Adoption of Software and Artificial Intelligence Agent Identity and Authorization. 5 February 2026.
- [4] Department for Science, Innovation and Technology. AI Adoption Research. 28 January 2026.
- [5] Organisation for Economic Co-operation and Development. AI adoption by small and medium-sized enterprises: OECD discussion paper for the G7. 9 December 2025.
- [6] ServiceNow. Service Gaps Cost Indians 10.8 Hours a Year; 44% Ready to Switch Brands, Finds ServiceNow's Third CX Report. 5 March 2026.
- [7] U.S. General Services Administration. GSA and ServiceNow Strike Landmark OneGov Deal to Accelerate AI-Driven Government Modernization. 3 September 2025.
- [8] ServiceNow. ServiceNow and DFL Partner to Transform Workflows Across the Entire Bundesliga Ecosystem. 19 August 2025.
- [9] Fujitsu and Mizuho Bank. Fujitsu and Mizuho Bank partner to develop new order and payment processing service for SMEs. 22 January 2026.
Frequently Asked Questions
What is the size of the Workflow-as-a-Service Market?
The global workflow-as-a-service market was valued at USD 10.69 billion in 2025 and is estimated at USD 14.92 billion in 2026. It is forecast to reach USD 416.27 billion by 2036, expanding at a CAGR of 39.5% from 2026 to 2036.
Which business workflow and enterprise size lead the Workflow-as-a-Service Market?
IT and operations is estimated to hold 32.6% of revenue by business workflow in 2026, while large enterprises are estimated to account for 61.4% by enterprise size.
Which country is likely to grow fastest in the Workflow-as-a-Service Market?
India is likely to grow at a 44.8% CAGR during the forecast period, followed by the United States at 38.5%, the United Kingdom at 36.7%, Germany at 35.6% and Japan at 33.9%.
Does all cloud software qualify as workflow-as-a-service?
No. The scope requires a hosted function that coordinates tasks, approvals or execution. A general application licence is not counted in full because it contains one approval feature, and general infrastructure and outsourced business operations without a dedicated hosted workflow service are excluded.
Can a hosted workflow still involve people?
Yes. Human approval and exception handling can remain part of the process, and the service needs to make responsibility clear when information is incomplete or the normal sequence cannot continue.
What affects the ongoing contract cost?
Users, execution volume, connected applications and support requirements can affect the commercial terms. The treatment of failed executions and retries also matters as use increases.
Why do software-agent permissions matter?
An automated action can change a business record or initiate more work, so its identity and permitted actions need to remain visible to the customer, as the questions in NIST's concept paper illustrate. [3] Competitive Analysis of the Workflow-as-a-Service Market Key Players
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Solution, 2026 to 2036
- Cloud Platform
- Y-o-Y Growth Trend Analysis By Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Solution, 2026 to 2036
- Global Market Analysis and Forecast, By Business Workflow, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Business Workflow, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Business Workflow, 2026 to 2036
- HR
- IT and Operations
- Sales and Marketing
- Finance and Accounting
- Customer Service
- Others
- Y-o-Y Growth Trend Analysis By Business Workflow, 2021 to 2025
- Absolute $ Opportunity Analysis By Business Workflow, 2026 to 2036
- Global Market Analysis and Forecast, By Enterprise Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Enterprise Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Enterprise Size, 2026 to 2036
- SMEs
- Large Enterprises
- Y-o-Y Growth Trend Analysis By Enterprise Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Enterprise Size, 2026 to 2036
- Global Market Analysis and Forecast, By Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Industry, 2026 to 2036
- IT and Telecom
- BFSI
- Retail
- Manufacturing
- Healthcare
- Education
- Others
- Y-o-Y Growth Trend Analysis By Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Solution
- By Business Workflow
- By Enterprise Size
- By Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Microsoft
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ServiceNow
- Salesforce
- Pegasystems
- Appian
- Microsoft
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


