

- Market Size (2026)
- USD 318.1 Mn
- Forecast (2036)
- USD 770.0 Mn
- CAGR (2026 to 2036)
- 9.0%
How big is Allulose Market in 2026?
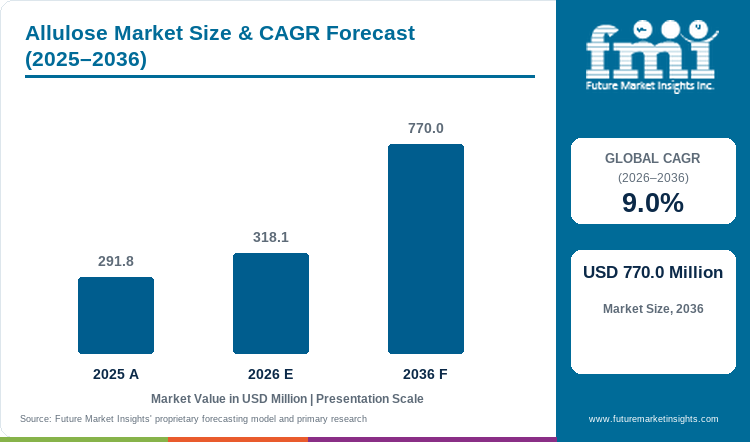
USD 318.1 million in 2026 and USD 770.0 million by 2036, expanding at 9.0% CAGR.
Demand for allulose is projected to expand at 9.0% CAGR between 2026 and 2036, growing from USD 291.8 million in 2025 to USD 318.1 million in 2026, and reaching USD 770.0 million by 2036. FDA guidance allows enforcement discretion for excluding allulose from Total Sugars and Added Sugars declarations and uses a 0.4 kcal/g factor for calorie calculation. This gives US developers a clear reformulation case when they need sugar-like bulk, browning and sweetness with a lower calorie declaration (FDA 2020; Tate & Lyle DOLCIA PRIMA).
The growth mechanism differs by country. In the USA, label treatment makes recipe performance and product qualification central to commercialization. Japan has a documented Mexico-to-Japan supply chain through Matsutani, while the UK and Germany remain more dependent on progress through novel-food requirements. Suppliers therefore face different launch conditions even when the technical role of allulose in a formulation is similar (FDA 2020; Matsutani Allulose product page; ACNFP 2025; EFSA NDA Panel 2025).
Key Takeaways of Allulose Market
- Sugar-reduction reformulation supports demand when allulose can lower declared sugar and calories without losing the bulk or processing functions expected from sugar (FDA 2020).
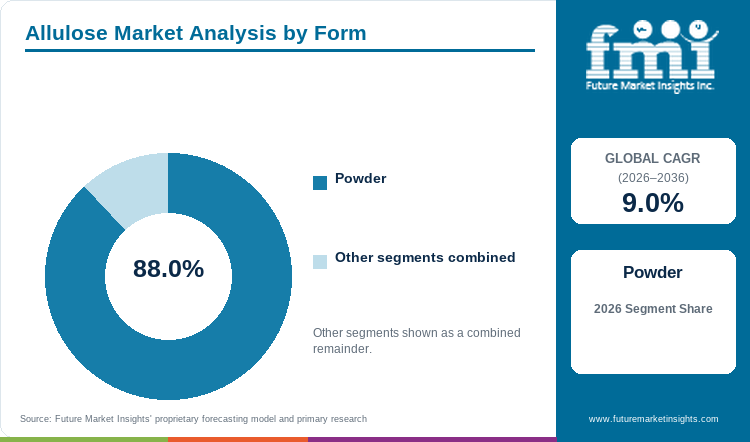
- Powder leads the Form category with 88.0% share in 2026, supported by flexible dosing into dry blends or dissolved processing steps.
- Food is a core End Use Application, with bakery, confectionery, dairy, sweet spreads, ice creams and desserts creating different functional requirements for browning, texture and freezing behavior.
- Novel-food requirements remain an important restraint in parts of Europe, making regulatory progress as important as formulation performance for launch planning (EFSA NDA Panel 2025; ACNFP 2025).
- USA records the highest profiled CAGR at 12.0%, followed by the UK at 11.0%, while South Korea, Japan and Germany show different growth and market-access conditions.
- Notable companies include Tate & Lyle PLC, Matsutani Chemical Industry Co., Ingredion Incorporated, CJ CheilJedang Corp. and Samyang Corporation.
Analyst Perspective
“Allulose becomes commercially useful when it solves both the nutrition-label objective and the physical job that sugar performs in the recipe. Suppliers that combine reliable ingredient supply with application support will be better placed to convert trials into repeat business.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Allulose Market segmented?
The allulose market is segmented by Form and End Use Application.
Form includes Powder, Crystals, and Liquid. End Use Application includes Food, Beverages, Pharmaceuticals, and Food Service Providers. Food covers bakery products, confectionery, dairy products, sweet spreads, ice creams and desserts. Beverages include carbonated beverages, fruit drinks and juice, and powdered drinks and mixes.
Why does powder lead demand within the form category?
Powder gives manufacturers a dry ingredient that can be weighed into premixes or dissolved during processing without adding carrier water at the dosing stage. That flexibility matters in bakery, confectionery and powdered systems where solids balance affects texture and process control. Crystals provide another dry route, while liquid allulose is better suited to operations designed around pumpable sweetener systems.
- Powder is forecast to hold 88.0% of the Form category in 2026, making it the clear leading physical format.
- Dry forms support accurate batching and storage, while liquid systems can reduce dissolution steps in beverage and syrup-based production lines.
Why is food a core demand center within the end use application category?
Food applications give allulose several routes to commercial value because the ingredient contributes more than sweetness. In bakery and confectionery it can support browning and bulk, while dairy and frozen desserts benefit from texture and freezing-point effects. This breadth makes food formulation a natural focus for supplier application teams serving multiple reduced-sugar product categories (Ingredion ASTRAEA; FDA GRN No. 400).
- Food covers bakery products, confectionery, dairy products, sweet spreads, ice creams and desserts.
- Ingredion lists ASTRAEA allulose for beverages, bakery, fruit preparations, ice creams and frozen desserts, and confectionery, showing how application requirements change by finished product.
What are the drivers, restraints and opportunities in the Allulose Market?
Sugar-reduction reformulation supports demand, market-access requirements can delay launches, and better conversion economics create room for wider use.
- Driver: Reformulation needs an ingredient that replaces more than sweetness.
- Restraint: Destination-specific eligibility can block a technically successful recipe.
- Opportunity: More efficient conversion could improve the economics of broader inclusion.
Sugar reduction changes sweetness, bulk and process behavior at the same time. Under FDA’s October 2020 guidance, allulose can be excluded from Total Sugars and Added Sugars declarations under enforcement discretion and can use a 0.4 kcal/g factor for calorie calculation. That creates a direct reformulation incentive in the USA, but the ingredient still has to deliver the texture, browning, freezing behavior or mouthfeel required by the finished product (FDA 2020).
Market access remains the main restraint in jurisdictions where allulose requires novel-food authorization. In June 2025, EFSA concluded that the safety of the D-allulose application it reviewed could not be established because requested information remained outstanding. The finding applies to that application, but it still affects launch timing because suppliers need a complete regulatory route before commercial sales can scale in the relevant markets (EFSA NDA Panel 2025).
Conversion efficiency remains an important opportunity because allulose competes with established sweetener systems on delivered cost as well as performance. Tate & Lyle and Codexis described improved enzyme variants designed to increase conversion efficiency in allulose production, while Samyang markets Nexweet products made with its own enzyme technology. Better process yield can widen the range of applications where allulose is economically viable, especially when suppliers pair ingredient supply with formulation support (Tate & Lyle 13 January 2021; Samyang Nexweet).
Which country CAGRs are profiled in the Allulose Market?
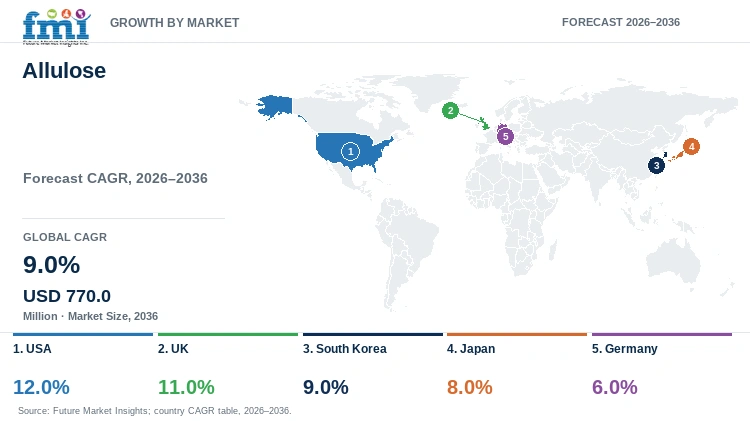
Country CAGRs for 2026 to 2036 are shown below.
| Country | CAGR |
|---|---|
| USA | 12.0% |
| UK | 11.0% |
| South Korea | 9.0% |
| Japan | 8.0% |
| Germany | 6.0% |
How do country-level CAGRs compare in the Allulose Market?
The profiled country CAGRs range from 12.0% in the USA to 6.0% in Germany. The USA and UK sit in the double-digit band, while South Korea and Japan occupy the middle of the range. Growth conditions differ by country because regulatory status, production history and customer access are not the same across these markets.
- USA combines the highest profiled CAGR at 12.0% with FDA label treatment that supports sugar-reduction reformulation (FDA 2020; GRN No. 400).
- UK is forecast at 11.0% CAGR, with commercial timing influenced by progress through the novel-food review process (ACNFP 2025).
- South Korea is forecast at 9.0% CAGR and has a domestic production base supported by CJ CheilJedang and Samyang Corporation.
- Japan is forecast at 8.0% CAGR, with Matsutani linking Mexican production to sieving, packaging and quality assurance in Japan.
- Germany is forecast at 6.0% CAGR, with EU novel-food authorization remaining central to market development.
Country-wise Analysis
- USA is forecast to expand at 12.0% CAGR from 2026 to 2036. FDA GRN No. 400 records a no-questions response for CJ CheilJedang’s notified D-psicose uses across bakery, confectionery, frozen dairy desserts, beverages and other food categories. This gives US developers a practical regulatory reference when they match the supplier specification with the intended finished-food use (FDA GRN No. 400).
- UK demand is forecast to rise at 11.0% CAGR through 2036. Minutes from the ACNFP’s February 2025 meeting recorded requests for additional information on an allulose application, including material related to identity and production. Regulatory dossier progress therefore remains a major factor in the timing of UK commercialization (ACNFP 2025).
- South Korea is forecast to grow at 9.0% CAGR from 2026 to 2036. CJ CheilJedang records the mass production of allulose in June 2015, while Samyang Corporation currently markets Nexweet liquid and crystalline allulose. This domestic production base supports product development across food and beverage applications (CJ CheilJedang History; Samyang Nexweet).
- Japan carries an 8.0% CAGR from 2026 to 2036. Matsutani describes ASTRAEA allulose as manufactured in Mexico and then imported into Japan for sieving, packaging and quality assurance. The model links overseas production with local final-quality activity and gives Japanese customers a defined commercial supply route (Matsutani Allulose product page).
- Germany is forecast to expand at 6.0% CAGR from 2026 to 2036. EU novel-food authorization remains the key market-access condition. EFSA’s June 2025 opinion concluded that the safety of the D-allulose application it reviewed could not be established because requested information was not supplied, keeping regulatory progress central to German launch planning (EFSA NDA Panel 2025; European Commission Union list).
Who are the notable companies in the Allulose Market?
Tate & Lyle PLC, Matsutani Chemical Industry Co., Ingredion Incorporated, CJ CheilJedang Corp. and Samyang Corporation are the notable companies profiled in this market.
Competition is led by ingredient suppliers that combine allulose production with formulation support and regional customer access. Tate & Lyle PLC and Ingredion Incorporated offer named allulose platforms for reduced-sugar formulation. Matsutani Chemical Industry Co. links ASTRAEA production in Mexico with finishing and quality activities in Japan. CJ CheilJedang Corp. has a long production history in South Korea, while Samyang Corporation markets Nexweet liquid and crystalline allulose for multiple food and beverage applications.
- Global formulation platforms: Tate & Lyle PLC and Ingredion Incorporated pair named allulose ingredients with application support across several food and beverage categories.
- Production-linked suppliers: Matsutani Chemical Industry Co. and CJ CheilJedang Corp. bring established production history and regulatory records to the competitive set.
- Specialty ingredient platform: Samyang Corporation commercializes Nexweet allulose in liquid and crystalline formats and supports applications across beverages, dairy, frozen desserts, sauces, bakery and confectionery.
Competitive Benchmarking: Allulose Market
| Company | Allulose Supply Evidence | Application Support | Enzymatic Process Evidence | Geographic Reach |
|---|---|---|---|---|
| Tate & Lyle PLC | High | High | High | USA and South Korea are named DOLCIA PRIMA markets; broader regional application support is documented. |
| Matsutani Chemical Industry Co. | High | Medium | High | Mexico production links to Japanese sieving, packaging and quality assurance, with an Asian commercial role. |
| Ingredion Incorporated | High | High | High | ASTRAEA is supplied in the Americas through a dedicated Mexican allulose plant and application-support network. |
| CJ CheilJedang Corp. | Medium | Medium | Medium | South Korean allulose production history and FDA GRN No. 400 support its documented market participation. |
| Samyang Corporation | High | High | High | Nexweet liquid and crystalline allulose are supported by South Korean production and international customer activity. |
Scoring basis: Allulose Supply Evidence is High for a current named product with a documented customer route and Medium for narrower or mainly historical production evidence. Application Support is High where the supplier provides multi-application technical material and Medium where documented support is more limited. Enzymatic Process Evidence reflects documented enzyme-based production or published process information. Geographic Reach states only the markets, facilities or customer routes identified in company documentation.
Key Developments in the Allulose Market
- In July 2026, Tate & Lyle shareholders approved Ingredion Incorporated’s recommended cash acquisition. Completion remains subject to closing conditions and is expected in the second half of 2027, so the two ingredient businesses continue to operate separately in the current market (Ingredion 28 July 2026; Ingredion Q2 2026 filing).
- In October 2025, EFSA published its assessment of a D-psicose 3-epimerase used in allulose production by Tate & Lyle Ingredients France SAS and identified no safety concerns under the intended conditions of use. The opinion relates to the specified production enzyme and is separate from novel-food authorization of allulose itself (EFSA Panel on Food Enzymes (FEZ Panel), 10 October 2025).
- In July 2026, Samyang Corporation participated in IFT First 2026 in Chicago (July 13 to 15), where it highlighted Nexweet Allulose alongside its AI-powered 3S Solution as part of a sugar-reduction platform combining specialty sweetener, dietary fiber and formulation support. The activity reinforces a move toward integrated application solutions rather than single-ingredient supply.
Key Players in the Allulose Market
Global allulose ingredient platforms
- Tate & Lyle PLC
- Ingredion Incorporated
Production and supply-chain specialists
- Matsutani Chemical Industry Co.
- CJ CheilJedang Corp.
Specialty allulose ingredient platform
- Samyang Corporation
Allulose Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form: Powder, Crystals, and Liquid. End Use Application: Food, Beverages, Pharmaceuticals, and Food Service Providers. |
| Quantitative Units | Revenue in USD Million and CAGR in %. |
| Market Definition | Revenue from allulose ingredient sales in Powder, Crystals, and Liquid form across Food, Beverages, Pharmaceuticals, and Food Service Providers. Downstream finished products and substitute sweeteners are excluded, as are enzyme, equipment, technology-licensing and unrelated service revenues. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
| Countries Covered | USA, UK, Germany, Japan, South Korea. |
| Key Companies Profiled | Tate & Lyle PLC, Matsutani Chemical Industry Co., Ingredion Incorporated, CJ CheilJedang Corp., Samyang Corporation. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Allulose Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments and findings from primary interviews. Validation also tested whether products, services, applications and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Allulose Market by Segments
Allulose Market segmented by Form:
- Powder
- Crystals
- Liquid
Allulose Market segmented by End Use Application:
- Food
- Beverages
- Pharmaceuticals
- Food Service Providers
Allulose Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- USA Food and Drug Administration (2020, October). Guidance for Industry: The Declaration of Allulose and Calories from Allulose on Nutrition and Supplement Facts Labels.
- USA Food and Drug Administration (2021). GRN No. 400: D-psicose (CJ CheilJedang). No-questions response issued August 12, 2021.
- USA Food and Drug Administration. GRN No. 498: D-psicose.
- EFSA Panel on Nutrition, Novel Foods and Food Allergens (2025, June 5). Safety of D-allulose as a novel food pursuant to Regulation (EU) 2015/2283.
- EFSA Panel on Food Enzymes (2025, October 10). Safety evaluation of the food enzyme d-psicose 3-epimerase from the genetically modified Escherichia coli strain K-12 W3110-TKO CDX-088.
- European Commission (n.d.). Union list of novel foods.
- Advisory Committee on Novel Foods and Processes (2025, July 2). Minutes of the 170th Meeting held on the 5th and 6th of February 2025.
- Tate & Lyle (n.d.). DOLCIA PRIMA® Allulose.
- Tate & Lyle (2021, January 13). Codexis introduces improved enzymes to further enhance Tate & Lyle’s stevia and allulose production.
- Tate & Lyle (2021, January 20). Tate & Lyle receives non-GMO project verification for crystalline DOLCIA PRIMA® Allulose.
- Ingredion Incorporated (2019, November 12). Ingredion opens first allulose plant in Latin America.
- Ingredion Incorporated (n.d.). ASTRAEA® Allulose.
- Ingredion Incorporated (2021, November 29). Ingredient Companies Create Consortium to Put Allulose on European Menus.
- Ingredion Incorporated (2026, July 28). Ingredion’s 595 pence All-Cash Offer to Acquire Tate & Lyle Accepted by Their Shareholders.
- Matsutani Chemical Industry Co (n.d).. Allulose (ASTRAEA™).
- Matsutani Chemical Industry Co (n.d).. Company History.
- CJ CheilJedang (n.d.). History.
- CJ Newsroom (2023, March 30). CJ Launches ALTIVE Plant-based Milk Alternatives.
- Samyang Corporation (n.d.). Nexweet® Allulose.
- Samyang Specialty (2026, July 1). Visit Samyang at IFT Chicago (#841): Sugar reduction solution and next-gen crystalline soluble fiber.
- Tate & Lyle Solutions USA LLC (2024, December 5). Alternative allulose crystal process (WO2024249338A1).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the allulose market in 2026, and what value is forecast for 2036?
- Which sugar-reformulation pressures can convert allulose interest into ingredient purchasing?
- Why does Powder hold the leading position within the Form category?
- How do Food, Beverages, Pharmaceuticals and Food Service Providers differ as End Use Application categories?
- How do growth rates and commercialization conditions differ across the profiled countries?
- Which companies provide commercial allulose ingredients, production capabilities and formulation support?
- What limits allulose adoption or a switch to another supplier?
- What should development and procurement teams verify before ordering allulose?
Frequently Asked Questions
How big is the allulose market in 2026, and what is forecast for 2036?
The allulose market is valued at USD 318.1 million in 2026 and is forecast to reach USD 770.0 million in 2036. The 2025 market value is USD 291.8 million.
What is the allulose market CAGR from 2026 to 2036?
The forecast CAGR is 9.0% from 2026 to 2036. It is a market-wide growth measure and should not be used as a company performance estimate.
Which Form segment leads the allulose market?
Powder leads with an 88.0% share in 2026. Its dry presentation gives formulators an option that does not add carrier water at the dosing stage.
Which End Use Application categories are covered in the allulose market?
End Use Application covers Food, Beverages, Pharmaceuticals, and Food Service Providers. Food includes bakery products, confectionery, dairy products, sweet spreads, ice creams and desserts.
Which profiled countries have the highest allulose growth rates?
USA at 12.0% and UK at 11.0% have the highest profiled CAGRs for 2026 to 2036. Their commercial conditions differ because the USA has established FDA labeling guidance while UK market development remains tied to novel-food review progress.
Which companies are profiled in the allulose market?
Tate & Lyle PLC, Matsutani Chemical Industry Co., Ingredion Incorporated, CJ CheilJedang Corp. and Samyang Corporation are profiled as notable participants in allulose supply, production and formulation support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Form, 2026 to 2036
- Powder
- Crystals
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use Application, 2026 to 2036
- Food
- Beverages
- Pharmaceuticals
- Food Service Providers
- Y-o-Y Growth Trend Analysis By End Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By End Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By End Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By End Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tate & Lyle PLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Matsutani Chemical Industry Co.
- Ingredion Incorporated
- CJ CheilJedang Corp.
- Samyang Corporation
- Tate & Lyle PLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


