
- Market Size (2026)
- USD 8.5 Bn
- Forecast (2036)
- USD 13.9 Bn
- CAGR (2026 to 2036)
- 5.1%
How big is Champagne Market in 2026?
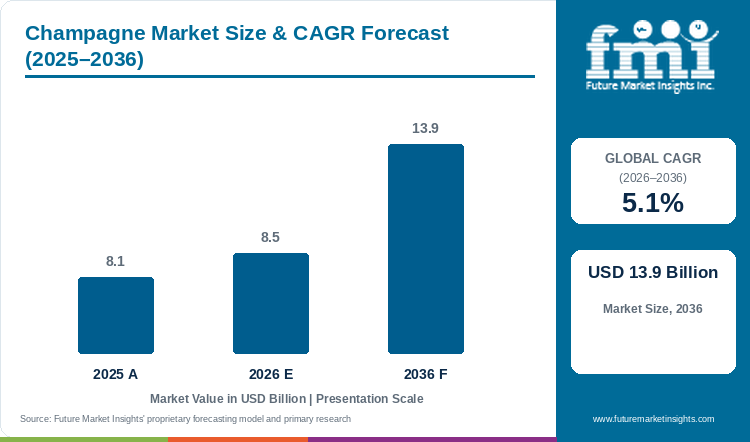
Sales in the champagne market are projected to grow at 5.1% CAGR, with the market size rising from USD 8.1 billion in 2025 to USD 8.5 billion in 2026 and reaching USD 13.9 billion by 2036.
Champagne demand is not moving only with the number of bottles sold, as the revenue side is being protected by exports, prestige labels and higher-value occasions. The market is valued at USD 8.1 billion in 2025 and is expected to reach USD 8.5 billion in 2026 before rising to USD 13.9 billion by 2036 at 5.1% CAGR. This movement adds USD 5.4 billion during the forecast period and indicates that pricing and mix will do more work than shipment expansion alone.
During 2025, 266.1 million bottles were shipped, while exports formed 57.1% of volume and 64.0% of revenue, showing that bottles sold outside France are bringing a stronger value contribution [1]. Luxury accounts for 55.0% in 2026 as buyers paying for gifting, hospitality and cellar-aged releases are less likely to shift only on price, although inflation, trade costs and uneven vintages can disturb the pace of purchase.
Key Market Trends & Insights
- By price range: Luxury is projected to account for 55.0% in 2026, driven by prestige gifting and high-value hospitality placement.
- By sales channel: Offline sales are estimated to hold 70.0% in 2026, owing to specialist retail advice and on-premise discovery.
- By application: Celebrations and events lead demand as weddings, corporate functions, and milestone occasions sustain recurring purchases.
- By deployment: On-premise consumption remains commercially important, supported by restaurants, hotels, clubs, and event venues.
Regional Highlights
- Fastest-growing evaluated country: China, at 6.5% CAGR from 2026 to 2036.
- By country: USA at 5.5%, UK at 4.2%, and Japan at 3.8% follow, while France records 3.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Champagne Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 8.1 billion |
| Estimated Market Size in 2026 | USD 8.5 billion |
| Projected Market Size by 2036 | USD 13.9 billion |
| CAGR, 2026 to 2036 | 5.1% |
| Added Revenue, 2026 to 2036 | USD 5.4 billion |
Shipment softness does not automatically place the revenue outlook under the same pressure. The 266.1 million bottles shipped during 2025 came at a time when inflation, geopolitical uncertainty and distributor stock correction were already affecting demand [2]. Houses can therefore protect value through fewer but better placed releases, yet this approach will work only where specialist retailers and hospitality accounts are able to explain why a cuvée is priced above an ordinary sparkling wine. Structural container economics also align with premium glass packaging design where bottle heft and pressure safety reinforce luxury cues.
Shipment and Revenue Conversion Sizing
Table 2: Shipment and Revenue Conversion Indicators for the Champagne Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 8.1 | 8.5 | 13.9 |
| Shipment base (million bottles) | 266.1 | 270 to 276 | 315 to 345 |
| Revenue per shipped bottle (USD) | 30.4 | 30.8 to 31.5 | 40.3 to 44.1 |
| Export share of volume | 57.1% | 57% to 59% | 60% to 64% |
Per-Bottle and Export-Market Sizing
Premium sparkling-wine buying is also widening interest in luxury wine categories, but Champagne holds a different position because supply is tied to one protected area and release value is built over ageing time. Export-led revenue can move faster than bottle volume when the sales mix shifts towards prestige cuvées, although currency, duty and freight changes can quickly reduce the gain available to producers and importers.
Table 3: Per-Bottle and Market-Access Indicators for the Champagne Market
| Metric | Value | Basis |
|---|---|---|
| 2025 bottles shipped | 266.1 million | Comité Champagne |
| 2025 export volume share | 57.1% | Official industry figure |
| 2025 export revenue share | 64.0% | Official industry figure |
| Implied 2025 market value per bottle | USD 30.4 | Calculated from FMI value and shipments |
Table 4: Leading External Market Shipment Indicators, 2025
| Country | Shipments (million bottles) | Commercial reading |
|---|---|---|
| USA | 26.5 | Largest external market by volume |
| UK | 22.7 | Mature retail and hospitality demand |
| Japan | 13.3 | Premium gifting and fine dining |
| Germany | 9.6 | Large specialist retail base |
| Australia | 7.6 | High-value urban consumption |
Analyst Perspective
“Champagne houses must protect scarcity while expanding occasions beyond year-end celebration. Selective distribution and lighter packaging will shape margin resilience.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the champagne market segmented?
The champagne market is segmented by price range, sales channel, application, and deployment.
By price range: Luxury, economy, and mid-range.
By sales channel: Offline sales and online sales.
By application: Celebrations and events, luxury gifting, and culinary use.
By deployment: On-premise consumption, events and celebrations, and off-premise consumption.
Why does Luxury lead the price range category?
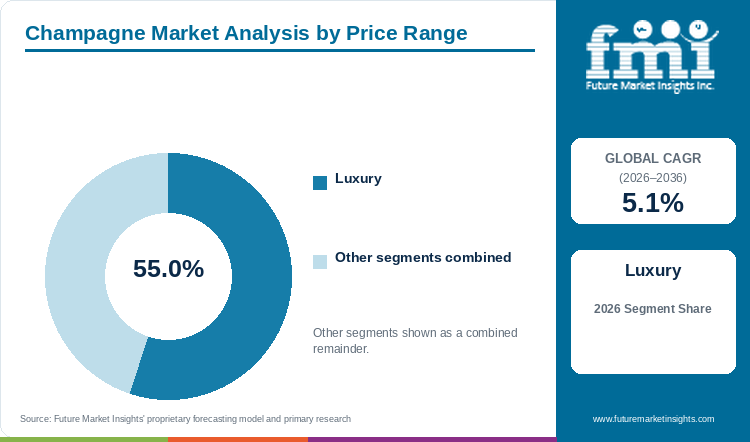
Luxury represents 55.0% of price range demand in 2026, linking protected origin with prestige-led purchasing.
Table 5: Price Range Share for the Champagne Market (percentage share), 2026
| Price Range | Share (2026) |
|---|---|
| Luxury | 55.0% |
| Other Segments Combined | 45.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Price Range Leadership and Market Growth, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.1% |
| Leading Segment | Luxury |
Luxury leads with 55.0% share in 2026 as ageing time, vintage availability and the name carried on the bottle give buyers more confidence when the purchase is meant for gifting or visible hospitality. The share is not supported by scarcity alone. It is supported when restaurants, merchants and collectors keep the difference between a prestige cuvée and a standard bottle clear; broad discounting could weaken the same reason for which buyers are paying more.
- Luxury is projected to hold 55.0% share in 2026, supported by heritage, scarcity, and premium presentation.
- Future Market Insights identifies luxury as the leading price range segment for 2026.
What supports Offline Sales as the preferred sales channel?
Offline sales account for 70.0% of channel demand in 2026, meeting discovery and advisory needs.
Offline sales hold 70.0% in 2026 because Champagne is frequently selected at the point where a buyer compares houses, bottle formats and the purpose of the occasion. Specialist merchants and restaurants can explain serving, pairing and provenance in a way that a product page may not. Online sales can still gain where repeat buyers know the label, but high delivery cost, temperature handling and weak discovery outside known brands may keep the channel from taking the lead.
- Offline sales are estimated at 70.0% in 2026, underpinned by specialist retail and hospitality access.
- The channel overlaps with specialty wine retail networks that support education and premium bottle selection.
What keeps Celebrations and Events ahead by application?
Celebrations and events lead application demand in 2026, supported by culturally embedded ceremonial consumption.
Celebrations and events remain ahead because Champagne purchasing is normally attached to a date, a guest list and a willingness to spend above an everyday sparkling wine. Weddings and year-end functions bring planned volume, while corporate hospitality adds repeat orders where brand visibility matters. The limitation is concentration of demand into fewer periods, which is why houses are trying to place Champagne with food and aperitif occasions without making it look routine.
- Celebrations and events remain the leading application, driven by recurring social and corporate occasions.
- Occasion-led purchases also interact with broader alcoholic beverages across hospitality and gifting.
How does On-Premise Consumption maintain relevance across deployment?
On-premise consumption anchors premium discovery through hotels, restaurants, clubs, and event-led service environments.
On-premise consumption remains commercially important because a restaurant can introduce a bottle through one glass before a consumer makes a full-bottle purchase. Sommelier recommendation and food pairing support higher-value labels, particularly where the difference is difficult to communicate on shelf. However, restaurant margins and slower nightlife traffic can narrow wine lists, so dependable allocation and staff education can decide which houses continue to receive space.
- On-premise demand remains important, enabled by trial, pairing, and premium hospitality presentation.
- Restaurants increasingly connect Champagne with hospitality catering through tasting menus and by-the-glass programs.
What are the drivers, restraints, and opportunities in the champagne market?
Premiumization broadens value creation, while shipment softness and trade friction restrain volume, and sustainable packaging creates differentiation.
- Driver: Prestige gifting, hospitality recovery, and protected-origin authenticity support high-value demand.
- Restraint: Inflation, tariff exposure, vintage variability, and inventory adjustment pressure shipment volumes.
- Opportunity: Lighter bottles, certified vineyards, and direct education can strengthen value without diluting exclusivity.
Growth Analysis and Future Potential: Premium Demand Catalysts
Limited vineyard geography gives Champagne the supply discipline that most sparkling-wine categories do not carry. This becomes more valuable when export buyers continue to pay for appellation, house history and gifting confidence even as shipment volume slows. In 2025, exports generated 64.0% of revenue from 57.1% of volume [1], suggesting that international mix is holding a higher return per bottle. Growth can continue when gastronomy and aperitif use adds occasions, but pushing the product into everyday discounting would work against the scarcity that supports the price.
Risk Assessment of the Champagne Market: Trade and Vintage Friction
The market can lose pace even when brand demand remains visible, as duties, exchange rates and distributor inventory decide the final shelf price before the consumer sees the bottle. The 2025 industry review placed geopolitical uncertainty and changing consumption patterns among the operating pressures [2]. Vintage variation can create another difficulty because houses must protect a familiar style while grape availability and reserve-wine use changes. Deep discounting may clear stock, but it also teaches the buyer to wait for a lower price and can damage future release value.
Commercial Opportunity Analysis: Sustainable Packaging and Value-Add Formats
Packaging is one of the few cost and carbon areas that can be changed without changing the wine inside the bottle. Telmont moved to an 800-gram bottle across its cuvées in April 2025; the bottle uses 35 grams less glass and lowers associated carbon emissions by about 4% [3]. If pressure resistance and appearance remain unchanged, lighter glass can reduce impact at scale. The opportunity can weaken where extra gift material is added back around the bottle, as the sustainability gain then becomes less convincing to buyers.
Champagne Market by Country (2026 to 2036)
As per Future Market Insights, China represents the fastest-growing champagne market among the five evaluated countries at 6.5% CAGR from 2026 to 2036, while France records 3.0%. Across these economies, commercial success depends on protecting appellation value, managing import economics, and maintaining premium distribution discipline.
Table 7: Country CAGR and Primary Growth Levers for the Champagne Market, 2026 to 2036
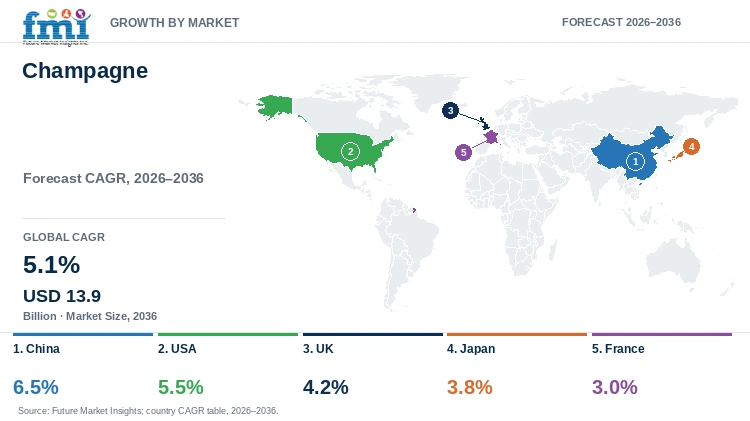
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 6.5% | Premium consumption growth and luxury retail expansion |
| USA | 5.5% | Largest external market volume and broad hospitality channels |
| UK | 4.2% | Mature specialist retail and celebration demand |
| Japan | 3.8% | High-value gifting and fine-dining culture |
| France | 3.0% | Domestic heritage with mature consumption patterns |
Source: Future Market Insights analysis
China Champagne Market Outlook (2026 to 2036)
China carries the highest evaluated CAGR at 6.5%, but the growth is likely to remain concentrated in cities where luxury retail, international hotels and trained distributors can explain Champagne beyond a status label. The market starts from a less mature consumption base than France or the UK, which gives it more room to rise, although import cost and uneven knowledge can make demand dependent on a narrow affluent group. Tastings, bilingual education and controlled hotel placements can push trial; uncontrolled distribution or discount-led selling could instead reduce the prestige needed to justify the import price. This also connects with luxury goods where channel cost and buyer expectations are moving in the same direction.
Key takeaway: Growth in China remains concentrated in cities where luxury retail infrastructure and trained distributor networks can communicate Champagne's value beyond a status label.
USA Champagne Market Outlook (2026 to 2036)
The United States already received 26.5 million bottles in 2025, making it the largest external market by volume [1]. Its 5.5% CAGR is supported by a wide hospitality base and affluent city demand, yet the route to the consumer is made expensive by the three-tier system and can become still harder when tariffs move. By-the-glass listings and limited releases can keep discovery active, while a large distributor markup may push entry bottles close to prestige pricing and delay repeat buying.
Key takeaway: The United States combines the largest external volume base with a wide hospitality network, though the three-tier distribution system and tariff exposure add cost between producer and consumer.
UK Champagne Market Outlook (2026 to 2036)
The United Kingdom received 22.7 million bottles in 2025 and remains a mature external market where consumers already understand the category [1]. The 4.2% CAGR is therefore less about first-time awareness and more about keeping Champagne relevant when household and hospitality budgets are tight. Half-bottles, mixed cases and restaurant partnerships can maintain access without openly cutting the main bottle price, though prolonged cost inflation can still move occasional buyers towards lower-priced sparkling wine.
Key takeaway: In the UK, mature consumption and tight hospitality budgets favor targeted formats and value-led brand partnerships.
Japan Champagne Market Outlook (2026 to 2036)
Japan received 13.3 million bottles in 2025 and its demand is more closely linked with formal gifting, department stores and precise restaurant service than with broad-volume promotion [1]. The 3.8% CAGR reflects a market where presentation and food pairing can carry value, but currency weakness quickly raises the landed cost. Smaller formats and carefully selected hotel or fine-dining accounts can protect frequency; price increases without visible service or packaging value may reduce entry-level purchases first.
Key takeaway: Japan's demand centers on formal gifting, department-store placement, and fine-dining service, where currency movement and presentation quality directly influence purchase frequency.
France Champagne Market Outlook (2026 to 2036)
France has the production base and the strongest cultural familiarity, but this also leaves less untapped demand than in China or the United States. Domestic buyers represented 42.9% of 2025 shipment volume [1], and the 3.0% CAGR points towards a market where revenue has to come from tourism, cellar-door visits and gastronomy rather than a sharp rise in bottle consumption. Inflation and lower alcohol intake can hold volume down, while direct experiences can keep the buyer connected with origin and support a higher-value mix.
Key takeaway: In France, domestic heritage with mature consumption patterns shapes supplier route-to-market and premium account selection.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Champagne Market?
Moët & Chandon, Veuve Clicquot, Dom Pérignon, Krug, Ruinart, Laurent-Perrier, Pernod Ricard (Perrier-Jouët and Mumm), Rémy Cointreau (Telmont) are the significant market players in this market.
Competition is divided between groups that can place several luxury houses across the world and independent producers that depend more on a clear house style and selected importer relationships. A broad network can secure hotel, retail and travel accounts, but too much availability can weaken the scarcity carried by prestige releases. Independent houses have less distribution weight, although family ownership, blending identity and controlled allocation can give buyers a reason to choose outside the largest portfolios. Category dynamics also intersect with broader sparkling wine production where cold fermentation and cellar aging set quality benchmarks.
- Global Luxury Portfolios: Moët & Chandon, Veuve Clicquot, Dom Pérignon, Krug, and Ruinart.
- Independent Prestige Houses: Laurent-Perrier and other family-controlled producers.
- Diversified Wine and Spirits Groups: Perrier-Jouët, Mumm, and Telmont connect Champagne with wider distribution systems.
Competitive Benchmarking: Champagne Market
Table 8: Competitive Benchmarking for the Champagne Market (qualitative capability ratings), 2026
| Company | Prestige Cuvée Depth | Hospitality Access | Sustainability Visibility | Geographic Reach |
|---|---|---|---|---|
| Moët & Chandon | High | High | High | High |
| Veuve Clicquot | High | High | High | High |
| Dom Pérignon | High | High | Medium | High |
| Krug | High | High | Medium | High |
| Ruinart | High | High | High | High |
| Laurent-Perrier | High | High | Medium | High |
| Perrier-Jouët / Mumm | High | High | Medium | High |
| Telmont | Medium | Medium | High | Medium |
Scoring basis: High indicates extensive public evidence across the named capability. Medium indicates meaningful but narrower evidence. Ratings are qualitative and do not represent financial rankings.
Key Developments in the Champagne Market
- In May 2026, Laurent-Perrier revealed Brut Millésimé 2018 as the house’s 32nd vintage release [4].
- In February 2026, Laurent-Perrier released Grand Siècle Iteration No. 27, a multi-vintage prestige blend drawing on the 2015, 2013, and 2012 harvests.
- In November 2025, Laurent-Perrier unveiled a limited Cuvée Rosé “Bubbles” metal jacket [6].
- In April 2025, Telmont introduced its 800-gram ultra-lightweight bottle with the Réserve Brut, reducing carbon emissions by 4% per bottle, with the format set to cover all production from 2025 onwards.
Key Players in the Champagne Market
Global Luxury Houses
- Moët & Chandon
- Veuve Clicquot
- Dom Pérignon
- Krug
- Ruinart
Independent and Diversified Platforms
- Laurent-Perrier
- Pernod Ricard (Perrier-Jouët and Mumm)
- Rémy Cointreau (Telmont)
Champagne Market - Report Scope
Table 9: Report Scope for the Champagne Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Price Range; Sales Channel; Application; Deployment |
| Quantitative Units | USD Billion |
| Market Definition | Commercial revenue from authentic Champagne protected by the Champagne appellation. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | China, USA, UK, Japan, France, and additional countries |
| Key Companies Covered | Moët & Chandon, Veuve Clicquot, Dom Pérignon, Krug, Ruinart, Laurent-Perrier, Pernod Ricard (Perrier-Jouët and Mumm), Rémy Cointreau (Telmont) |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Champagne Market - Research Methodology
Table 10: Research Methodology for the Champagne Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews with producers, distributors, specialist retailers, hospitality buyers, industry experts, and key opinion leaders validate market trends and purchasing decisions. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public sources were reviewed. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess shipment volumes, price mix, channel demand, and regional adoption for 2026 to 2036. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, shipment statistics, trade conditions, regulatory factors, and historical trends to improve accuracy. |
Champagne Market by Segments
Champagne Market segmented by Price Range:
- Luxury
- Economy
- Mid-range
Champagne Market segmented by Sales Channel:
- Offline sales
- Online sales
Champagne Market segmented by Application:
- Celebrations and events
- Luxury gifting
- Culinary use
Champagne Market segmented by Deployment:
- On-premise consumption
- Events and celebrations
- Off-premise consumption
Champagne Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- France
- Germany
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Comité Champagne. (2026). Champagne at a glance: Key figures of the Champagne industry in 2025.
- [2] Union des Maisons de Champagne. (2026, January 17). 2025 shipment review and outlook.
- [3] Rémy Cointreau. (2025, April 22). Telmont presents the 800-gram lightweight Champagne bottle.
- [4] Laurent-Perrier. (2026, May). Brut Millésimé 2018.
- [5] Laurent-Perrier. (2026, January 14). Grand Siècle Iteration No. 27.
- [6] Laurent-Perrier. (2025, November 3). Cuvée Rosé Bubbles.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the champagne market in 2026 and what is forecast for 2036?
- Which prestige and hospitality forces support Champagne demand?
- Why does luxury lead the price range category?
- Why do offline sales remain the largest sales channel?
- How do growth rates differ across China, USA, UK, Japan, and France?
- Which leading companies shape the market today?
- What limits adoption or supplier switching in the champagne market?
- What should buyers evaluate before purchasing Champagne?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Price Range, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Range, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Range, 2026 to 2036
- Luxury
- Economy
- Mid-range
- Y-o-Y Growth Trend Analysis By Price Range, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Range, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Offline sales
- Online sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Celebrations and events
- Luxury gifting
- Culinary use
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Deployment, 2026 to 2036
- On-premise consumption
- Events and celebrations
- Off-premise consumption
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- Germany
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- By Country
- Market Attractiveness Analysis
- By Country
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Price Range
- By Sales Channel
- By Application
- By Deployment
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Moët & Chandon
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Veuve Clicquot
- Dom Pérignon
- Krug
- Ruinart
- Laurent-Perrier
- Perrier-Jouët / Mumm
- Telmont
- Pernod Ricard (Perrier-Jouët and Mumm)
- Rémy Cointreau (Telmont)
- Moët & Chandon
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Price Range, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Deployment, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Price Range
- Figure 6: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Sales Channel
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Deployment
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Price Range
- Figure 29: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Sales Channel
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Deployment
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Price Range
- Figure 42: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 45: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Application
- Figure 48: Latin America Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Deployment
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Price Range
- Figure 55: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 58: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Application
- Figure 61: Western Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Deployment
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Price Range
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Application
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Deployment
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Price Range
- Figure 81: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 84: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Application
- Figure 87: East Asia Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Deployment
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Price Range
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Deployment
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Price Range, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Price Range, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Price Range
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Deployment, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Deployment, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Deployment
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the champagne market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global champagne market will reach USD 8.5 billion in 2026 and USD 13.9 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the champagne market is projected to expand at a 5.1% CAGR over the assessment period.
Which price range leads?
Luxury is projected to hold 55.0% share in 2026, supported by prestige, scarcity, and gifting demand.
Which sales channel leads?
Offline sales are projected at 70.0% share in 2026, supported by specialist retail and hospitality.
Which country has the strongest evaluated growth outlook?
China is projected to register a 6.5% CAGR from 2026 to 2036.
Who are the key players?
Key participants include Moët & Chandon, Veuve Clicquot, Dom Pérignon, Krug, Ruinart, Laurent-Perrier, Perrier-Jouët, Mumm, and Telmont.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
