
- Market Size (2026)
- USD 130.4 Mn
- Forecast (2036)
- USD 171.9 Mn
- CAGR (2026 to 2036)
- 2.8%
How big is Octabin Market in 2026?
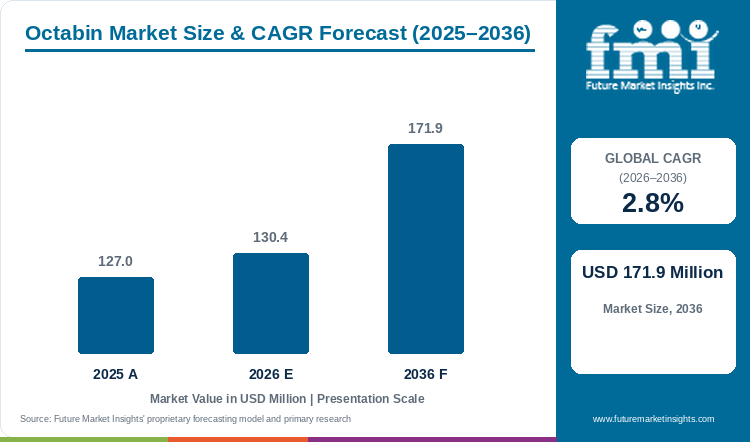
Assessed at USD 127.0 million in 2025 and progressing to USD 130.4 million in 2026, the octabin market valuation is on course to reach USD 171.9 million by 2036, supported by a forecast-period CAGR of 2.8%.
Petrochemical compounders and masterbatch blenders are replacing manual twenty-five-kilogram sack handling with octagonal bulk containers to cut forklift turnaround times and eliminate warehouse pallet clutter. The global octabin market was valued at USD 127.0 million in 2025 and is estimated to reach USD 130.4 million in 2026. The market is projected by FMI to reach USD 171.9 million by 2036, expanding at a compound annual growth rate (CAGR) of 2.8% between 2026 and 2036. Heavy Duty Double-Wall Corrugated containers hold an estimated 43.6% share of 2026 wall construction demand because B-C and E-B flute combinations prevent sidewall bulging under free-flowing resin loads. Demand for octagonal bulk bins tracks closely with heavy-duty corrugated packaging upgrades, as European Union packaging waste records compiled by Eurostat in October 2026 confirmed that paper and cardboard account for over 40% of municipal and industrial recovery streams [1]. Manufacturers are also investing in virgin kraftliner capacity to meet that structural specification, as Mondi Group plc started up its EUR 400 million kraft paper machine at Steti in May 2025 to add 210,000 metric tons of annual high-strength paper supply [2]. However, moisture-induced creep buckling during maritime container transit and shorter cellulose fibers from repeated recycling loops remain key hurdles restraining broader bulk qualification through 2036.
Key Market Trends & Insights
- By wall construction: Heavy Duty Double-Wall Corrugated units hold an estimated 43.6% share in 2026 because twin-fluted kraft liners resist outward hoop stress during bulk resin filling.
- By loading capacity: Standard 500 kg to 800 kg octabins represent 47.4% in 2026 as standard CP1 and Euro pallet footprints match automated resin bagging bays.
- By discharge design: Bottom Funnel Discharge Chute formats account for 51.1% in 2026 because integrated conical sleeves feed pneumatic extruder hoppers without container inversion.
- By end-use sector: Polymer Granules and Masterbatch Resin secure 54.8% in 2026 owing to high-volume polyolefin and compounding pellet shipments across continental trade corridors.
- By secondary end-use category: Chemical Powders and Intermediates with Bulk Food Grains and Dried Legumes represent 45.2% combined in 2026 through food-grade inner polyethylene liners.
Regional Takeaways
- Top national expansion: France leads national growth projections at a 3.0% CAGR through 2036 under industrial single-use plastic reduction rules and circular fiber recovery mandates.
- Broader country progression: Brazil tracks at a 2.9% CAGR ahead of Poland at 2.8% and Italy at 2.7%, whereas Japan advances at a 2.5% CAGR and Canada records a 2.4% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Octabin Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 127.0 million |
| Estimated Market Size in 2026 | USD 130.4 million |
| Projected Market Size by 2036 | USD 171.9 million |
| CAGR, 2026 to 2036 | 2.8% |
| Added Market Value, 2026 to 2036 | USD 41.5 million |
Polyolefin resin producers and agricultural bulk shippers face rising warehouse labor costs when unloading palletized twenty-five-kilogram bags into extrusion hoppers. Substitution of forty individual bags on a pallet with one octagonal corrugated sleeve and telescopic cap reduces line changeovers and eliminates polyethylene sack waste. In December 2025, materials scientists reporting in Polymers demonstrated that kraft lignin-based polyurethane coatings applied to linerboard improved air resistance up to 627.8 seconds per 100 cubic centimeters and reduced water absorptiveness by 98.8% to 99.5% [3]. Consequently, industrial packaging buyers pair moisture-treated outer kraft liners with corrugated board packaging architectures to preserve edge-crush strength during humid sea freight.
Bulk Resin Tonnage and Unit Container Sizing
Table 2: Shipped Resin Tonnage and Unit Container Sizing for the Octabin Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 127.0 | 130.4 | 171.9 |
| Bulk cargo shipped in octabins (million metric tons) | 3.1 to 3.5 | 3.2 to 3.6 | 4.2 to 4.7 |
| Commercial octabin unit shipments (million units) | 4.5 to 5.1 | 4.6 to 5.2 | 6.0 to 6.8 |
| Average unit realization per octabin assembly (USD) | 25.0 to 28.2 | 25.1 to 28.4 | 25.3 to 28.7 |
Operational note: Container volume ranges apply verified 500 kg to 1,200 kg payload capacities and commercial manufacturer average selling prices across double-wall and triple-wall octabin assemblies.
Cylindrical thermoplastic pellets behave like a column of liquid inside bulk containers and push outward against flat carton walls during road vibration. Eight-sided corner post geometry distributes that radial pressure evenly across eight diagonal panels so filled containers do not bow into adjacent trailer lanes. In January 2026, structural engineers publishing in Materials documented that corrugated wave profile geometry and adhesive layer bonding govern compressive stress at 10% deformation up to 17.3 kilopascals [4]. Converters apply those flute-bonding parameters to die-cut self-locking bases and telescopic lids that run smoothly on bulk container packaging palletizing conveyors.
Per Capita & Compounding Line Allocation Sizing
Table 3: Per Capita and Compounding Facility Allocation Indicators for the Octabin Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 15.5 | 15.7 | 19.1 |
| Annual procurement per compounding facility (USD thousand) | 28.5 to 33.0 | 29.2 to 33.8 | 36.5 to 42.0 |
| Bottom-funnel & automated discharge share (%) | 64.0% to 68.0% | 65.5% to 69.5% | 74.0% to 78.5% |
Table 4: Industrial Facility & Sector Allocation Indicators for the Octabin Market (USD million and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 130.4 million | 2026 global valuation baseline |
| Active bulk resin & dry-cargo filling lines global | 4,100 lines | Petrochemical compounding, masterbatch & grain bulk bays |
| Annual octabin allocation per filling line | USD 31,804.9 | Annualized octabin container procurement |
| Polymer Granules and Masterbatch Resin valuation, 2026 | USD 71.5 million | 54.8% end-use sector allocation |
Elimination of wooden crates and returnable metal bins allows resin exporters to avoid reverse-logistics freight on one-way intercontinental shipments. Extrusion plants specify heavy-duty kraftliner combinations with intermediate bulk containers so stacked octabins support two-high static warehouse loads without external steel frames. Per the August 2026 United States Environmental Protection Agency containers and packaging data release, corrugated boxes represent the largest single municipal and commercial packaging stream at over 33.3 million tons generated annually [5]. Warehouse receiving teams consequently compact empty octabin sleeves into mill-ready cardboard bales that generate secondary scrap rebates instead of landfill disposal fees.
Analyst Perspective
"Thermoplastic compounders do not procure octabins merely as disposable cardboard boxes. Buyers select octagonal corrugated bins to cut pneumatic hopper discharge labor and maximize container cube efficiency without paying return freight on rigid cages. Corrugated converters that pair high-compression semi-chemical fluting with pre-fitted bottom discharge cones will secure multi-year supply contracts across resin and food bulk terminals."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the octabin market segmented?
The octabin market is segmented by wall construction, loading capacity, discharge design, and end-use sector. In 2026, Heavy Duty Double-Wall Corrugated is projected at 43.6%, 500 kg to 800 kg Standard at 47.4%, Bottom Funnel Discharge Chute at 51.1%, and Polymer Granules and Masterbatch Resin at 54.8%.
By wall construction: Heavy Duty Double-Wall Corrugated and Heavy Duty Triple-Wall Corrugated with Quad-Wall Heavy Board.
By loading capacity: 500 kg to 800 kg Standard and 800 kg to 1200 kg High Load with Above 1200 kg Heavy Bulk.
By discharge design: Bottom Funnel Discharge Chute and Standard Top Flap Access with Tilter Dump Emptying System.
By end-use sector: Polymer Granules and Masterbatch Resin and Chemical Powders and Intermediates with Bulk Food Grains and Dried Legumes.
By region: North America and Latin America with Western Europe and Eastern Europe. Coverage also spans East Asia and South Asia and Pacific with Middle East and Africa.
Why does Heavy Duty Double-Wall Corrugated lead wall construction?
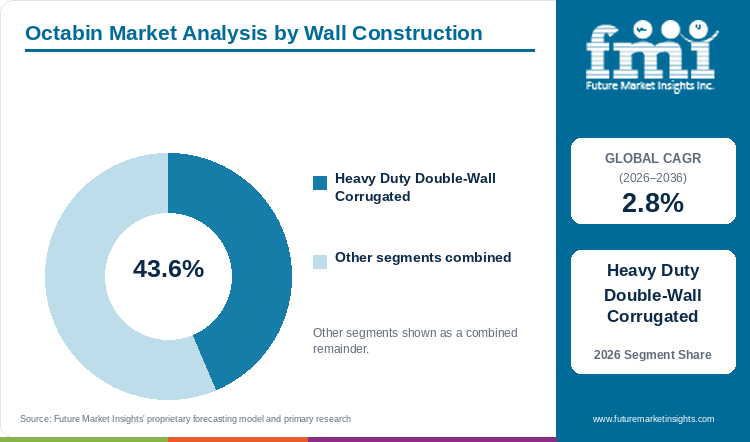
Heavy Duty Double-Wall Corrugated constructions hold an estimated 43.6% of wall construction demand in 2026, anchored by balanced stacking rigidity and fold-flat freight efficiency.
Table 5: Wall Construction Share for the Octabin Market (percentage share), 2026
| Wall Construction | Share (2026) |
|---|---|
| Heavy Duty Double-Wall Corrugated | 43.6% |
| Heavy Duty Triple-Wall & Quad-Wall Combined | 56.4%* |
| Total | 100.0% |
Note that Heavy Duty Triple-Wall Corrugated and Quad-Wall Heavy Board account for the remaining 56.4% of 2026 global octabin wall construction demand.
Table 6: Wall Construction Leadership and Market Growth for the Octabin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 2.8% |
| Leading Segment | Heavy Duty Double-Wall Corrugated |
Procurement managers at polyolefin and masterbatch plants favor Heavy Duty Double-Wall Corrugated sleeves because twin-flute board delivers sufficient box compression strength for single-stack road trailers at a lower unit price than triple-wall board. Integration of high-grammage kraftliner facings with semi-chemical fluting allows converters to fold flat sleeves that erect rapidly on folding intermediate bulk containers packing stations.
- Heavy Duty Double-Wall Corrugated holds 43.6% of wall construction value in 2026 because balanced B-C flute stiffness prevents corner buckling under 750-kilogram pellet loads.
- Mondi Group plc presented its semi-chemical fluting portfolio in April 2026 to reinforce dimensional stability and humidity resistance across heavy-duty supply chains [6]. That fluting upgrade allows double-wall octabin converters to match the vertical stacking endurance of heavier board grades while cutting inbound paper tonnage per pallet.
What sustains 500 kg to 800 kg Standard leadership in loading capacity?
500 kg to 800 kg Standard formats represent 47.4% of the loading capacity category in 2026, supported by CP1 and Euro pallet footprint compatibility.
Warehouse logistics directors standardize on 500 kg to 800 kg Standard octabins because two filled containers placed on standard 1,140-by-1,140-millimeter pallets match road axle weight limits without wasting trailer height. Unlike oversized bulk bins that require high-capacity forklifts, standard-payload octabins move smoothly through corrugated shipping boxes dock doors and automated stretch-wrapping turntables.
- Standard 500 kg to 800 kg formats represent 47.4% of the loading capacity segment in 2026 as resin compounders align batch sizes with standard extruder day-bins.
- Smurfit Westrock plc engineered a heavy-duty octagonal display and transport structure in July 2026 that combines rapid assembly with high vertical load stability [7]. Industrial resin packers apply similar quick-erect octagonal die-cuts to shorten manual bin setup times on high-speed bagging shifts.
How does Bottom Funnel Discharge Chute lead discharge design?
Bottom Funnel Discharge Chute designs account for 51.1% of discharge design volume in 2026, driven by dust-free gravity unloading into extrusion hoppers.
Plastic injection molders and chemical blenders specify Bottom Funnel Discharge Chute octabins to empty free-flowing pellets by gravity without vacuum lances that generate static dust or cross-batch contamination. Operators untie the integrated polyethylene cone through a die-cut base flap over a floor grate, pairing high-grammage virgin and recycled containerboard sleeves with clean room dosing hoppers.
- Bottom Funnel Discharge Chute configurations account for 51.1% of discharge design demand in 2026 because gravity unloading eliminates pneumatic suction labor and residual heel waste.
- Mondi Group plc engineered a streamlined corrugated packaging architecture for Stiebel Eltron in September 2026 that simplified warehouse handling and reduced component complexity [8]. Bulk compounders adopt comparable pre-assembled bottom-chute octabin kits to eliminate loose inner bag tying and speed up hopper changeovers.
Why does Polymer Granules and Masterbatch Resin lead end-use demand?
Polymer Granules and Masterbatch Resin secure 54.8% of end-use sector value in 2026, supported by high-volume polyolefin and compounding pellet logistics.
Thermoplastic resin producers and color masterbatch compounders represent the primary buyer base for octabins because cylindrical pellets exert high lateral fluid pressure that splits rectangular cartons. Eight-sided sleeves lined with anti-static polyethylene bags allow compounders to ship moisture-sensitive polyamide and polycarbonate resins with industrial paperboard packaging secondary cartons.
- Polymer Granules and Masterbatch Resin secure 54.8% of end-use sector value in 2026 as petrochemical crackers and compounding plants ship bulk pellets in single-trip octagonal bins.
- A January 2026 peer-reviewed study indexed in PubMed quantified plasticizer and additive concentrations in recycled polypropylene and polyethylene pellets shipped in bulk containers [9]. Resin blenders consequently mandate virgin barrier inner liners inside corrugated octabins to prevent additive cross-migration between successive resin batches.
How do Chemical Powders and Bulk Food Grains shape secondary end-use demand?
Chemical Powders and Intermediates with Bulk Food Grains and Dried Legumes command 45.2% of 2026 end-use demand, anchored by barrier-lined export octabins.
Beyond thermoplastic resins, specialty chemical manufacturers and pulse processors procure triple-wall and moisture-barrier octabins to ship titanium dioxide pigments and dried legumes with oilseed meal. Food exporters line octagonal sleeves with food-contact barrier films to prevent mycotoxin growth and insect ingress during maritime transit.
- Chemical Powders and Intermediates with Bulk Food Grains and Dried Legumes account for 45.2% of 2026 end-use demand across export terminals.
- In May 2025, food safety researchers reporting in Comprehensive Reviews in Food Science and Food Safety documented barrier design requirements to prevent chemical migration from recycled cardboard packaging [10]. Agricultural grain and chemical powder shippers therefore specify functional barrier inner liners or virgin inner kraft plies when qualifying octabins for export contracts.
What are the drivers and restraints with opportunities in the octabin market?
In the octabin market, automated bulk resin handling and twenty-five-kilogram sack replacement are projected to drive adoption whereas maritime humidity creep restrains untreated board and repulpable lignin barrier coatings create circular packaging opportunities.
- Driver: Rising labor and pallet disposal costs in resin compounding and food bulk logistics push plant managers to replace twenty-five-kilogram sacks with single-unit octabins.
- Restraint: High relative humidity in maritime shipping corridors softens untreated cellulosic fluting and reduces vertical stacking compression strength during prolonged storage.
- Opportunity: Bio-based lignin barrier coatings and water-activated glueline-free folding systems enable 100% repulpable octabins that comply with European Union recyclability mandates.
Growth Analysis and Future Potential: Qualitative Demand Drivers
Industrial bulk shippers are migrating away from timber crates and multi-wall paper sacks because manual bag slitting slows down automated extrusion lines and creates occupational lifting hazards. Single-unit octagonal containers filled at 750 to 1,000 kilograms allow one forklift operator to stage an entire production shift of resin or grain in minutes. Corrugated box plants are installing high-speed die-cutters and corrugated box converting equipment to manufacture heavy-duty octabins with locked corner joints. In August 2025, Stora Enso Oyj inaugurated its EUR 1,000 million consumer and packaging board production line in Oulu to reduce board weight by up to one-third while maintaining stiffness [11]. Lighter yet stiffer virgin fiber plies allow octabin converters to lower container tare weight and expand delivery radii around regional box plants.
Risk Assessment of the Octabin Market: Operational and Formulation Friction
Hygroscopic moisture absorption and fiber degradation across multiple recycling cycles represent the main technical barriers restricting corrugated octabins in high-humidity export lanes. When containerboard absorbs ambient moisture above 80% relative humidity, inter-fiber hydrogen bonds weaken and bottom octabins in a two-high stack risk buckling under static loads. Freight cost inflation further pressures converter margins, as Smurfit Westrock plc reported in October 2026 that full-year 2026 freight and energy headwinds reached approximately USD 700 million across its global paper and corrugated operations [12]. Plant engineers consequently pair octabin bases with paper-based slip sheets and wooden pallets to keep bottom flaps elevated above damp warehouse floors.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Corrugated converters capture margin expansion by replacing polyethylene film laminations and hot-melt adhesives with repulpable barrier coatings and water-mist bonding that qualify for single-stream paper recovery. Under European Union Packaging and Packaging Waste Regulation rules, industrial shippers face rising extended producer responsibility fees on composite bulk containers that cannot be recycled in standard paper mills. In May 2026, Smurfit Westrock plc launched its ActiBlu prototype technology, replacing traditional hot-melt glue with a fine water mist on packing lines to cut adhesive consumption by up to 60% [13]. Suppliers that pair glueline-free joints with pre-inserted conical discharge chutes capture recurring bulk contracts.
Octabin Market by Country (2026 to 2036)
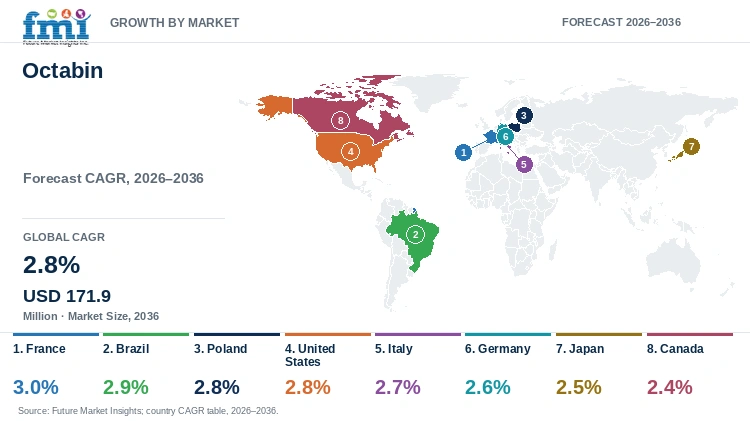
FMI country modeling indicates that France leads octabin market growth at a 3.0% CAGR through 2036, followed closely by Brazil at 2.9% and Poland at 2.8%, while Canada advances at a 2.4% CAGR. National adoption patterns reflect chemical compounding output and agricultural export volumes with statutory plastic-reduction timelines.
Table 7: Country CAGR and Primary Growth Levers for the Octabin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 3.0% | AGEC single-use plastic restrictions and chemical compounding bulk bin conversion |
| Brazil | 2.9% | Mercosur bulk grain export expansion and petrochemical pellet containerization |
| Poland | 2.8% | Central European masterbatch extrusion hubs and automated warehouse dosing |
| United States | 2.8% | Gulf Coast polyolefin resin bagging replacement and GMA pallet octabin lines |
| Italy | 2.7% | Northern masterbatch compounding clusters and dry-food bulk distribution |
| Germany | 2.6% | Rhine chemical park powder handling and triple-wall static stacking standards |
| Japan | 2.5% | Factory labor automation and precision electronics resin bulk handling |
| Canada | 2.4% | Cross-border pulse and polyolefin rail-to-truck bulk container logistics |
Source: Future Market Insights analysis
France Octabin Market Outlook (2026 to 2036)
Demand for octabins in France is projected to expand at a leading 3.0% CAGR through 2036 because national anti-waste statutory decrees penalize single-use plastic bulk wraps and incentivize recyclable fiber containers. Unlike neighbouring markets that still rely heavily on woven polypropylene flexible bulk bags, chemical compounders in Lyon and agro-processors in northern France specify double-wall corrugated octabins to meet domestic recovery quotas. Per the September 2026 USDA Foreign Agricultural Service report on France, the national AGEC law progressively restricts single-use plastic packaging while large general food retailers account for 58.6% of national distribution [14]. Local converters supply pre-glued telescopic octabins with removable inner liners so industrial buyers separate paperboard cleanly at receiving docks.
Key takeaway: In France, statutory plastic-reduction decrees under the AGEC framework and chemical compounding demand are projected to drive leading 3.0% CAGR expansion for recyclable corrugated octabins.
Brazil Octabin Market Outlook (2026 to 2036)
In contrast to regulation-driven Western European buyers, octabin adoption in Brazil is anchored by export-oriented oilseed and thermoplastic resin terminals seeking one-way bulk containers for maritime freight. Valuation in Brazil is forecast to progress at a 2.9% CAGR between 2026 and 2036 across southern petrochemical complexes and central agricultural corridors. Per the February 2026 USDA Foreign Agricultural Service assessment of the EU-Mercosur trade agreement signed on January 17, 2026, tariff liberalizations are set to expand bulk agricultural and food shipments from Brazil toward European ports [15]. Because humid tropical port storage challenges untreated board, converters in Sao Paulo coat outer kraft plies with hydrophobic resins to prevent stack collapse inside ocean containers.
Key takeaway: In Brazil, expanding bulk agricultural exports under Mercosur trade corridors and petrochemical pellet shipments are forecast to sustain a 2.9% CAGR for moisture-resistant octabins.
Poland Octabin Market Outlook (2026 to 2036)
Whereas Brazil focuses on seaborne commodity exports, Poland operates as Central Europe's primary land-freight manufacturing hub for masterbatch compounding and bulk food ingredients. Octabin market value in Poland is anticipated to grow at a 2.8% CAGR from 2026 to 2036 as multinational plastics processors expand regional extrusion capacity. Per the November 2025 USDA Foreign Agricultural Service report, Poland represents Central and Eastern Europe's largest food and beverage processing market, serving a domestic population of 38 million people and continental export chains [16]. Industrial buyers in Wroclaw and Katowice procure 800-kilogram bottom-discharge octabins from domestic kraftliner mills to feed automated dosing silos without manual bag handling or pallet return logistics.
Key takeaway: In Poland, expanding polymer compounding plants and Central European bulk ingredient logistics are anticipated to support a 2.8% CAGR for bottom-discharge octabins.
United States Octabin Market Outlook (2026 to 2036)
Demand in the United States is governed by Gulf Coast polyethylene and polypropylene resin production with Midwest dry-bulk food processing lines that require forklift-ready octagonal Gaylord bins. Market valuation in the United States is estimated to advance at a 2.8% CAGR through 2036 as resin blenders automate railcar-to-octabin repackaging for regional injection molders. In June 2026, Graphic Packaging Holding Company reported in its 2025 Impact Report that customer paperboard programs replaced 880 million plastic packages and generated USD 210 million in new paperboard demand during 2025 [17]. Corrugated converters across Texas and Ohio supply heavy-duty double-wall and triple-wall octabins fitted to standard forty-eight-by-forty-inch GMA wooden pallets for domestic road freight.
Key takeaway: In the United States, Gulf Coast resin compounding and corporate plastic-to-fiber substitution initiatives are estimated to maintain a 2.8% CAGR for pallet-matched octabins.
Italy Octabin Market Outlook (2026 to 2036)
Italy distinguishes itself through its dense concentration of specialty masterbatch formulators and pulse millers with packaging machinery builders across Emilia-Romagna and Lombardy. Octabin demand in Italy is projected to progress at a 2.7% CAGR between 2026 and 2036 as industrial buyers standardize automated tilter and bottom-cone discharge bins. Per the October 2026 USDA Foreign Agricultural Service report on Italy, national food retail distribution reached USD 202,900 million in 2025 following a 4.3% annual expansion across discount and supermarket chains [18]. Domestic corrugated plants pair recycled testliner inner plies with virgin kraft outer liners to give food and polymer processors high stacking strength under national paper recovery consortia.
Key takeaway: In Italy, northern masterbatch compounding clusters and expanding dry-food processing volumes are projected to sustain a 2.7% CAGR for hybrid kraft-testliner octabins.
Germany Octabin Market Outlook (2026 to 2036)
Unlike southern European markets with fragmented food packers, Germany anchors its octabin consumption in high-specification engineering plastics and specialty chemical powders across automated warehouse systems along the Rhine corridor. The octabin market in Germany is slated to expand at a 2.6% CAGR over the 2026 to 2036 period as chemical parks replace wooden crates with certified triple-wall octagonal bins. Per the September 2026 USDA Foreign Agricultural Service report on Germany, national food retail demand reached USD 323,800 million while agricultural and processing imports climbed to USD 172,400 million [19]. Buyers in Ludwigshafen and North Rhine-Westphalia mandate strict edge-crush certification and anti-static inner liners for hazardous powder transport.
Key takeaway: In Germany, specialty chemical powder handling and engineering plastics compounding are slated to underpin a 2.6% CAGR for high-compression triple-wall octabins.
Japan Octabin Market Outlook (2026 to 2036)
In Japan, chronic factory labor shortages and narrow warehouse aisles push electronics polymer compounders and food ingredient packers toward precision-engineered octagonal bulk containers with integrated discharge chutes. Octabin valuation in Japan is forecast to rise at a 2.5% CAGR through 2036 across Kanto and Kansai industrial logistics and manufacturing districts. Per the October 2026 USDA Foreign Agricultural Service report from Tokyo, international trade events at FOODEX Japan 2026 generated USD 7 million in projected twelve-month ingredient contracts as processors modernized bulk supply chains [20]. Domestic board mills engineer quad-wall and triple-wall octabins with moisture-vapor barrier liners that withstand humid summer storage while replacing heavy steel returnable totes.
Key takeaway: In Japan, factory automation imperatives and precision electronics resin logistics are forecast to drive a 2.5% CAGR for quad-wall and triple-wall octabins.
Canada Octabin Market Outlook (2026 to 2036)
Octabin procurement in Canada centers on Western prairie pulse and grain exporters with Ontario and Alberta petrochemical resin shippers supplying cross-border United States manufacturing plants. The market in Canada is anticipated to progress at a 2.4% CAGR between 2026 and 2036 as bulk packers improve intermodal rail and truckload cube efficiency across long continental corridors. Per the December 2025 USDA Foreign Agricultural Service report on Canada, cross-border consumer-oriented agricultural trade exceeded USD 21,800 million as processors expanded bulk ingredient packaging capacity [21]. Cold-weather warehouse operations require virgin softwood kraftliner facings that resist brittle score-line cracking during sub-zero winter forklift handling across domestic rail and highway distribution hubs.
Key takeaway: In Canada, cross-border resin and pulse export logistics combined with cold-climate virgin kraftliner durability are anticipated to support a 2.4% CAGR.
Full report country CAGRs cover: North America and Latin America with Western Europe and Eastern Europe. Coverage also includes East Asia and South Asia and Pacific with Middle East and Africa.
Who are the notable companies in the octabin market?
Mondi Group plc, Sonoco Products Company, International Paper Company, Graphic Packaging Holding Company, Stora Enso Oyj, Smurfit Westrock plc, DS Smith plc, Packaging Corporation of America, Oji Holdings Corporation, and Rengo Co. Ltd. are the notable companies in the octabin market.
Competitive positioning in the octabin industry separates integrated virgin kraftliner and heavy-duty corrugated groups from diversified industrial paperboard converters and regional heavy-wall box specialists. Mondi Group plc and Stora Enso Oyj with Smurfit Westrock plc and International Paper Company operate vertically integrated pulp and heavy-duty corrugated plants. Sonoco Products Company and Graphic Packaging Holding Company with DS Smith plc and PCA supply engineered paperboard and industrial converting solutions, while Oji Holdings Corporation and Rengo Co. Ltd. anchor East Asian triple-wall bulk packaging.
- Integrated Kraftliner and Heavy-Duty Corrugated Groups: Mondi Group plc and Stora Enso Oyj with Smurfit Westrock plc and International Paper Company combine virgin kraft pulp mills with multi-wall octabin converting networks.
- Industrial Paperboard and Bulk Packaging Converters: Sonoco Products Company and Graphic Packaging Holding Company with DS Smith plc and PCA engineer heavy-duty fiber containers and bulk industrial sleeves.
- Regional Multi-Wall and Heavy-Board Specialists: Oji Holdings Corporation and Rengo Co. Ltd. manufacture high-compression triple-wall and quad-wall octagonal bulk bins for Asian resin and machinery logistics.
Competitive Benchmarking: Octabin Market
Table 8: Competitive Benchmarking for the Octabin Market (qualitative capability ratings), 2026
| Company | Heavy-Wall Board Integration | Bulk Discharge Engineering | Recyclability & Barrier Fit | Geographic Reach |
|---|---|---|---|---|
| Mondi Group plc | High | High | High | European and international kraftliner mills and heavy-duty octabin converting |
| Sonoco Products Company | High | High | High | Global industrial paperboard and bulk fiber container manufacturing network |
| International Paper Company | High | High | High | North American and EMEA containerboard mills and heavy-duty box plants |
| Graphic Packaging Holding Company | Medium | High | High | North American and European paperboard innovation and plastic-replacement formats |
| Stora Enso Oyj | High | Medium | High | Nordic and European virgin kraftliner and lightweight CTMP board mills |
| Smurfit Westrock plc | High | High | High | 500+ global converting operations across 40 countries with octagonal designs |
| DS Smith plc | High | High | High | Pan-European heavy-duty industrial corrugated and bulk resin octabin network |
| Packaging Corporation of America | High | Medium | High | United States containerboard mills and heavy-duty bulk corrugated box plants |
| Oji Holdings Corporation | High | Medium | High | Japan and Southeast Asia heavy-duty triple-wall and bulk industrial board |
| Rengo Co. Ltd. | High | Medium | High | East Asian multi-wall corrugated board and heavy-load octagonal containers |
Assessment basis: Heavy-Wall Board Integration evaluates backward integration into virgin kraftliner and semi-chemical fluting mills, whereas Bulk Discharge Engineering rates proprietary bottom-chute and telescopic cap designs. Recyclability & Barrier Fit measures verified capability to replace plastic or wooden bulk containers with repulpable moisture-resistant fiber octabins.
Key Developments in the Octabin Market
- Mondi Group plc partnered with SwissKrono in June 2026 to transition industrial laminate packaging from plastic film to high-strength kraft paper containing 20% recycled fiber [22]. Industrial bulk converters apply that same high-tear kraft paper architecture to reinforce outer octabin facings against forklift abrasion.
- Sonoco Products Company reported third-quarter 2026 financial results on October 21, 2026, recording a 5.2% increase in Industrial Paper Packaging segment net value to USD 646 million [23]. Steady price realization across converted fiber products confirms resilient industrial demand for heavy-duty paperboard bulk containers.
- Stora Enso Oyj launched Trayforma Brown and reduced basis weight across its three-ply CTMP board range in April 2026 ahead of Interpack 2026 in Dusseldorf [24]. Lower basis weights at equivalent bending stiffness help bulk packaging buyers reduce per-unit container freight costs and EPR weight fees.
Key Players in the Octabin Market
Integrated Kraftliner and Heavy-Duty Corrugated Groups
- Mondi Group plc
- Stora Enso Oyj
- Smurfit Westrock plc
- International Paper Company
Industrial Paperboard and Bulk Packaging Converters
- Sonoco Products Company
- Graphic Packaging Holding Company
- DS Smith plc
- PCA (Packaging Corporation of America)
Regional Multi-Wall and Heavy-Board Specialists
- Oji Holdings Corporation
- Rengo Co. Ltd.
Octabin Market - Report Scope
Table 9: Report Scope for the Octabin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Wall Construction, Loading Capacity, Discharge Design, End-Use Sector |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial manufacturer valuation from multi-wall octagonal bulk corrugated containers (octabins) supplied with base trays, telescopic outer sleeves, top caps, and integrated bottom discharge chutes or inner liners across double-wall, triple-wall, and quad-wall constructions. Category Scope Note: Excludes flexible woven polypropylene bulk bags (FIBCs), rigid plastic or metal IBCs, cylindrical fiber drums, and standard four-sided RSC cartons. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | France, Brazil, Poland, United States, Italy, Germany, Japan, Canada, and additional countries in the full report |
| Key Companies Covered | Mondi Group plc, Sonoco Products Company, International Paper Company, Graphic Packaging Holding Company, Stora Enso Oyj, Smurfit Westrock plc, DS Smith plc, Packaging Corporation of America, Oji Holdings Corporation, Rengo Co. Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Octabin Market - Research Methodology
Table 10: Research Methodology for the Octabin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with petrochemical resin packaging engineers, masterbatch plant logistics directors, heavy-duty corrugated die-cutting managers, and agricultural bulk terminal operators to validate octabin payload weights and reuse rates. |
| Secondary Research | Analysis of Eurostat packaging waste registries, U.S. EPA containers and packaging datasets, USDA Foreign Agricultural Service GAIN country reports, peer-reviewed linerboard mechanics studies in PMC, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down industrial bulk packaging baselines (where octabins represent 6.8% of the parent industrial packaging category) reconciled against bottom-up shipped bulk tonnage (3.2M to 3.6M MT in 2026) and unit container realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight polyolefin compounding capacity, pulse and grain bulk export volumes, and statutory plastic-packaging replacement mandates across eight country markets. |
| Operational Benchmark Traceability | Bulk tonnage and compounding facility indicators in Tables 2, 3, and 4 trace to Eurostat recovery statistics, peer-reviewed BCT/ECT compression equations, and corporate containerboard production disclosures. |
| Data Triangulation and Validation | Valuation estimates isolate eight-sided heavy-duty corrugated bulk bin assemblies and strictly exclude woven flexible intermediate bulk containers, rigid metal cages, and standard retail shipping cartons with zero hierarchy anomalies. |
Octabin Market by Segments
Octabin Market segmented by Wall Construction:
- Heavy Duty Double-Wall Corrugated
- Heavy Duty Triple-Wall Corrugated
- Quad-Wall Heavy Board
Octabin Market segmented by Loading Capacity:
- 500 kg to 800 kg Standard
- 800 kg to 1200 kg High Load
- Above 1200 kg Heavy Bulk
Octabin Market segmented by Discharge Design:
- Bottom Funnel Discharge Chute
- Standard Top Flap Access
- Tilter Dump Emptying System
Octabin Market segmented by End-Use Sector:
- Polymer Granules and Masterbatch Resin
- Bulk Food Grains and Dried Legumes
- Chemical Powders and Intermediates
Octabin Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Eurostat. (2026, October 16). European Union packaging waste statistics: Statistics Explained. European Commission Eurostat.
- [2] Mondi Group plc. (2025, November 25). Mondi customers experience high-performance kraft paper firsthand at new paper machine in Steti mill. Mondi Group Newsroom.
- [3] de Oliveira, D. M. (2025, December 31). Kraft Lignin-Based Polyurethane with GVL: A Sustainable Coating for Linerboard Packaging. Polymers (PMCID PMC12787817).
- [4] Kosiachevskyi, D. (2026, January 4). Assessment of the Possibilities of Developing Effective Building and Packaging Materials from Corrugated Structures. Materials (PMCID PMC12787102).
- [5] United States Environmental Protection Agency. (2026, August 28). Containers and Packaging: Product-Specific Data. U.S. EPA Facts and Figures on Materials, Wastes and Recycling.
- [6] Mondi Group plc. (2026, April 9). Mondi showcases semi-chemical fluting portfolio for demanding food and heavy-duty supply chains. Mondi Group Newsroom.
- [7] Smurfit Westrock plc. (2026, July 7). Smurfit Westrock partners with Coca-Cola on World Cup packaging to capture spike in consumer demand. Smurfit Westrock Press Releases.
- [8] Mondi Group plc. (2026, September 22). Mondi case study on reducing packaging complexity for Stiebel Eltron water heater product range. Mondi Group Case Studies.
- [9] Tang, Z. (2026, January 10). Quantification of phthalates, non-phthalate plasticizers, and organophosphate esters in recycled polypropylene and polyethylene pellets. Chemosphere (PubMed PMID 41401757).
- [10] Bansal, V. & Gupta, R. (2025, May 22). Food Packaging and Chemical Migration: A Food Safety Perspective. Comprehensive Reviews in Food Science and Food Safety (PMCID PMC12096275).
- [11] Stora Enso Oyj. (2025, August 18). Stora Enso billion-euro investment in renewable packaging: Europe most modern consumer board production line inaugurated in Finland. Stora Enso Press Room.
- [12] Smurfit Westrock plc. (2026, October 28). Smurfit Westrock Reports Third Quarter 2026 Results. Smurfit Westrock Investor Relations.
- [13] Smurfit Westrock plc. (2026, May 5). Smurfit Westrock launches prototype of glueline-free packaging solution. Smurfit Westrock Newsroom.
- [14] USDA Foreign Agricultural Service. (2026, September 30). France: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [15] USDA Foreign Agricultural Service. (2026, February 19). Brazil: EU-Mercosur Trade Agreement The Brazilian Perspective and Agricultural Impacts. U.S. Department of Agriculture GAIN Report.
- [16] USDA Foreign Agricultural Service. (2025, November 19). Poland: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [17] Graphic Packaging Holding Company. (2026, June 30). Graphic Packaging Releases 2025 Impact Report on 880 Million Plastic Packages Replaced With Paperboard Innovations in 2025. Graphic Packaging News and Events.
- [18] USDA Foreign Agricultural Service. (2026, October 5). Italy: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [19] USDA Foreign Agricultural Service. (2026, September 25). Germany: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [20] USDA Foreign Agricultural Service. (2026, October 20). Japan: FOODEX Japan 2026 Report. U.S. Department of Agriculture GAIN Report.
- [21] USDA Foreign Agricultural Service. (2025, December 30). Canada: Retail Foods Annual. U.S. Department of Agriculture GAIN Report.
- [22] Mondi Group plc. (2026, June 9). Mondi enables SwissKrono transition from plastic to paper in laminate flooring packaging. Mondi Group Newsroom.
- [23] Sonoco Products Company. (2026, October 21). Sonoco Reports Third Quarter 2026 Results. Sonoco Investor Relations.
- [24] Stora Enso Oyj. (2026, April 29). Stora Enso launches Trayforma Brown and reduces basis weight across the Trayforma range. Stora Enso Press Room.
- [25] Mondi Group plc. (2025, August 19). Mondi launches Ad/Vantage Smooth Brown Semi Extensible paper built for performance. Mondi Group Newsroom.
- [26] International Paper Company. (2026, October 15). A New Chapter in Our Company Transformation: International Paper to Create Two Independent Public Companies. International Paper Corporate Announcements.
- [27] Mondi Group plc. (2025, November 18). Mondi launches extended corrugated and solid board portfolio for the food packaging industry. Mondi Group Newsroom.
- [28] Graphic Packaging Holding Company. (2026, October 2). Graphic Packaging Wins Three 2026 PPC Awards for Packaging Innovation. Graphic Packaging News and Events.
- [29] Smurfit Westrock plc. (2026, May 12). Smurfit Westrock launches new Better Planet targets as it reports key 2025 sustainability achievements. Smurfit Westrock Newsroom.
- [30] Stora Enso Oyj. (2026, June 10). Stora Enso Oulu pulp production granted internationally recognized food safety certification. Stora Enso Press Room.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the octabin market in 2026 and what is forecast for 2036?
- Which bulk resin handling and sack-replacement economics support demand for octabins?
- Why does Heavy Duty Double-Wall Corrugated lead the wall construction category?
- Why does 500 kg to 800 kg Standard lead the loading capacity category globally?
- How do growth rates differ across France and Brazil with Poland and Canada?
- Which leading companies supply integrated virgin kraftliner versus converted octabin sleeves today?
- What limits corrugated stack stability or causes moisture creep in the octabin market?
- What should thermoplastic compounders evaluate before switching from woven bags to octabins?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Wall Construction, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Wall Construction, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Wall Construction, 2026 to 2036
- Heavy Duty Double-Wall Corrugated
- Heavy Duty Triple-Wall Corrugated
- Quad-Wall Heavy Board
- Y-o-Y Growth Trend Analysis By Wall Construction, 2021 to 2025
- Absolute $ Opportunity Analysis By Wall Construction, 2026 to 2036
- Global Market Analysis and Forecast, By Loading Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Loading Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Loading Capacity, 2026 to 2036
- 500 kg to 800 kg Standard
- 800 kg to 1200 kg High Load
- Above 1200 kg Heavy Bulk
- Y-o-Y Growth Trend Analysis By Loading Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Loading Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Discharge Design, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Discharge Design, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Discharge Design, 2026 to 2036
- Bottom Funnel Discharge Chute
- Standard Top Flap Access
- Tilter Dump Emptying System
- Y-o-Y Growth Trend Analysis By Discharge Design, 2021 to 2025
- Absolute $ Opportunity Analysis By Discharge Design, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Polymer Granules and Masterbatch Resin
- Bulk Food Grains and Dried Legumes
- Chemical Powders and Intermediates
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Wall Construction
- By Loading Capacity
- By Discharge Design
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mondi Group plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sonoco Products Company
- International Paper Company
- Graphic Packaging Holding Company
- Stora Enso Oyj
- Smurfit Westrock plc
- DS Smith plc
- Packaging Corporation of America
- Oji Holdings Corporation
- Rengo Co. Ltd.
- PCA (Packaging Corporation of America)
- Mondi Group plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 26: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 28: East Asia Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 29: East Asia Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 30: East Asia Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Million) Forecast by Wall Construction, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Million) Forecast by Loading Capacity, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Million) Forecast by Discharge Design, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Wall Construction
- Figure 6: Global Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Loading Capacity
- Figure 9: Global Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Discharge Design
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Sector
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Wall Construction
- Figure 29: North America Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Loading Capacity
- Figure 32: North America Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Discharge Design
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Sector
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Wall Construction
- Figure 42: Latin America Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Loading Capacity
- Figure 45: Latin America Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Discharge Design
- Figure 48: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Wall Construction
- Figure 55: Western Europe Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Loading Capacity
- Figure 58: Western Europe Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Discharge Design
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Wall Construction
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Loading Capacity
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Discharge Design
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Wall Construction
- Figure 81: East Asia Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Loading Capacity
- Figure 84: East Asia Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Discharge Design
- Figure 87: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Wall Construction
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Loading Capacity
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Discharge Design
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Wall Construction, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Wall Construction, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Wall Construction
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Loading Capacity, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Loading Capacity, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Loading Capacity
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Discharge Design, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Discharge Design, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Discharge Design
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the octabin market in 2026, and what is forecast for 2036?
FMI estimates that the global octabin market size stood at USD 127.0 million in 2025 and reached USD 130.4 million in 2026. Total industry valuation is on track to hit USD 171.9 million by 2036 as resin compounders and food processors standardize octagonal bulk corrugated bins.
What is the CAGR for the octabin market from 2026 to 2036?
The octabin sector is projected to expand at a 2.8% CAGR over the 2026 to 2036 window, adding USD 41.5 million in incremental market value across bulk industrial shipping corridors.
Which wall construction segment leads the octabin market?
Heavy Duty Double-Wall Corrugated constructions hold 43.6% of wall construction demand in 2026 because twin-fluted kraft board balances stacking compression strength with low unit tare weight.
Which end-use sector leads the octabin market?
Polymer Granules and Masterbatch Resin represent 54.8% of the end-use category in 2026 as polyolefin and compounding plants ship free-flowing pellets in octagonal sleeves.
Which country has a notable growth outlook during the assessment period?
France leads national expansion projections at a 3.0% CAGR through 2036, followed by Brazil at 2.9% and Poland at 2.8% as industrial shippers adopt recyclable fiber bulk bins.
Who are the key players in the market?
Mondi Group plc and Sonoco Products Company with International Paper Company and Graphic Packaging Holding Company lead commercial supply. Stora Enso Oyj and Smurfit Westrock plc with DS Smith plc and PCA also hold major capacity with Oji Holdings Corporation and Rengo Co. Ltd.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
