
- Market Size (2026)
- USD 180.7 Mn
- Forecast (2036)
- USD 365.6 Mn
- CAGR (2026 to 2036)
- 7.3%
How big is Retinoid Market in 2026?
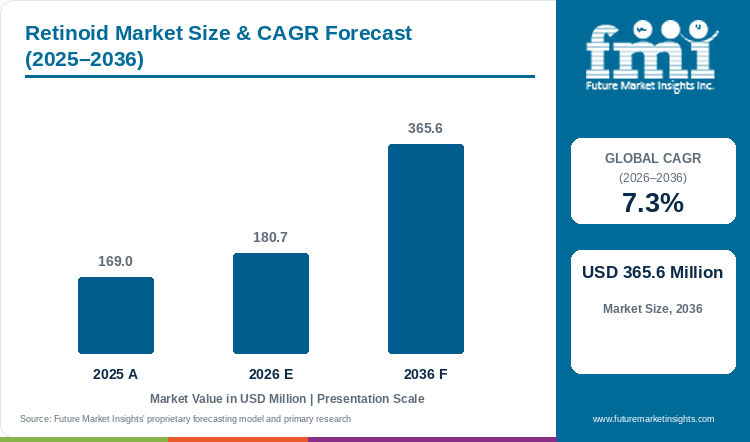
The retinoid market establishes its foundation at USD 169.0 million in 2025, advances to USD 180.7 million in 2026, and is forecast to scale to USD 365.6 million by 2036 at a CAGR of 7.3%.
The global retinoid market recorded a valuation of USD 169.0 million in 2025 and rose to USD 180.7 million in 2026. Global market size is forecast to scale to USD 365.6 million by 2036, progressing at a 7.3% CAGR from 2026 through 2036. Analysis by FMI reveals that first-generation tretinoin and isotretinoin hold an estimated 35.1% share of 2026 compound valuation because no non-retinoid agent matches oral isotretinoin in inducing permanent sebaceous gland involution across severe nodulocystic acne. Outpatient prescription volume is driven by antimicrobial-stewardship substitution, as dermatology guidelines direct clinicians to replace chronic oral tetracyclines with topical and systemic retinoids at treatment initiation. Real-world claims tracking of 71,340 acne patients published in September 2026 confirmed that 28.4% of patients initiated isotretinoin directly without prior antibiotic courses [1]. That broad follicular keratolytic utility separates retinoid demand from hormonal acne therapeutics, which remain restricted to androgen-driven female cohorts. Dermatology leaders are expanding commercial supply to capture this shift, with Galderma Group AG reporting record full-year therapeutic dermatology and skincare performance in March 2026 [2]. Strict teratogenicity registry mandates and early-week erythema peeling rates govern patient refill adherence through 2036.
Key Market Trends & Insights
-
By generation and compound: First-Generation Tretinoin and Isotretinoin hold an estimated 35.1% share in 2026 because oral isotretinoin remains the gold-standard remission therapy for severe cystic acne while topical tretinoin anchors photoaging and comedonal care.
- By delivery route: Topical Creams Gels and Lotions represent 63.8% in 2026 as localized epidermal application avoids systemic mucocutaneous and hepatic toxicity.
- By clinical application: Acne Vulgaris Mild to Severe Nodulocystic accounts for 50.9% in 2026 due to high adolescent and adult acne consultation volumes across outpatient clinics.
- By prescription tier: Prescription Dermatological Formulations command 58.4% in 2026 through regulated high-potency tretinoin and isotretinoin dispensing with third- and fourth-generation topicals.
- By distribution channel: Retail and Chain Pharmacies capture 46.8% in 2026 through insurance-reimbursed prescription fulfillment and mandatory pregnancy-prevention verification.
Regional Highlights
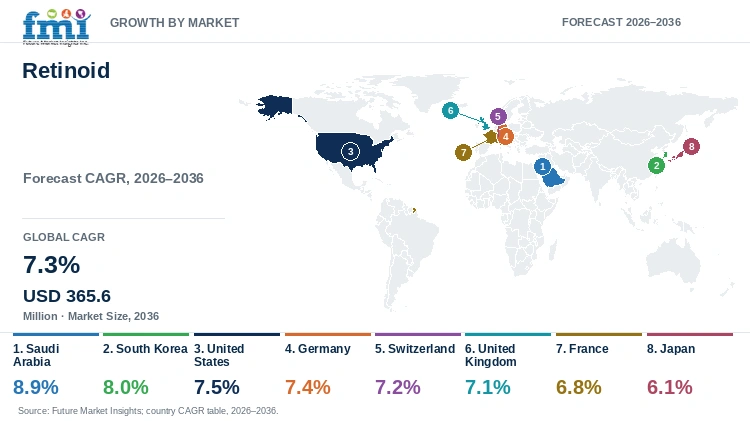
- Top national expansion: Saudi Arabia leads national growth projections at an 8.9% CAGR through 2036 under private dermatology clinic expansion and rising young-adult acne and hyperpigmentation treatment demand.
- Broader country progression: South Korea tracks at an 8.0% CAGR ahead of Germany at 7.4% and Switzerland at 7.2%, while the United Kingdom and Japan progress at 7.1% and 6.1% CAGRs.
Market Size & Forecast
Table 1: Market Size and Forecast for the Retinoid Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 169.0 million |
| Estimated Market Size in 2026 | USD 180.7 million |
| Projected Market Size by 2036 | USD 365.6 million |
| CAGR, 2026 to 2036 | 7.3% |
| Added Market Value, 2026 to 2036 | USD 184.9 million |
Outpatient dermatologists and aesthetic physicians confront high prescription abandonment during the first four weeks of retinoid therapy when unbuffered retinoic acid triggers severe stratum corneum desquamation and burning. When patients discontinue topical therapy prematurely, microcomedones reform and inflammatory papules progress into permanent atrophic scars. In July 2025, a Bayesian network meta-analysis of 23 randomized controlled trials involving 3,905 participants demonstrated that isotretinoin and tretinoin achieved the highest efficacy-to-safety balance for facial photoaging and fine wrinkles [3]. Formulators consequently pair controlled-release polymeric vehicles with anti-aging skincare formulations to sustain epidermal cell renewal without barrier disruption.
Active Retinoid Tonnage and Prescription Course Sizing
Table 2: Active Retinoid Volume and Prescription Unit Sizing for the Retinoid Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 169.0 | 180.7 | 365.6 |
| Dispensed topical retinoid tubes & pumps (million units) | 42.0 to 46.5 | 44.8 to 49.5 | 88.0 to 96.5 |
| Oral systemic isotretinoin & acitretin courses (million packs) | 6.8 to 7.5 | 7.2 to 8.0 | 13.8 to 15.4 |
| Active retinoid API volume (metric tons) | 18.5 to 21.0 | 19.8 to 22.4 | 38.0 to 43.2 |
Operational note: Dosing ranges reflect 0.005% to 0.1% topical tretinoin and adapalene or trifarotene tubes together with 0.5 to 1.0 mg/kg/day oral isotretinoin courses [4].
All-trans retinoic acid and isotretinoin isomerize rapidly under ultraviolet light and atmospheric oxygen while exhibiting poor gastrointestinal bioavailability when taken without high-fat meals. Pharmaceutical compounders encapsulate micronized retinoids inside lipid matrices for moderate-to-severe acne therapeutics so systemic absorption remains predictable regardless of patient meal timing [5].
Per Capita & Dermatology Clinic Allocation Sizing
Table 3: Per Capita and Dermatology Clinic Valuation Indicators for the Retinoid Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global population (billion) | 8.2 | 8.3 | 9.0 |
| Valuation per 1,000 people (USD) | 20.6 | 21.8 | 40.6 |
| Annual retinoid allocation per dermatology clinic (USD) | 4,850 to 5,400 | 5,160 to 5,750 | 9,800 to 10,950 |
| Third- & fourth-generation selective retinoid share (%) | 46.0% to 49.5% | 48.0% to 51.5% | 61.0% to 65.5% |
Table 4: Pharmacy & Dermatology Channel Allocation Indicators for the Retinoid Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 180.7 million | 2026 global market valuation baseline |
| Active outpatient dermatology & aesthetic clinics | 33,500 clinics | Global medical and aesthetic dermatology centers |
| Valuation per dermatology clinic | USD 5,394.0 | Annualized retinoid prescription and dispensing baseline |
| Topical Creams Gels and Lotions valuation, 2026 | USD 115.3 million | 63.8% delivery route market allocation |
Retinoic acid receptor agonists paired with anti-androgenic or keratolytic co-actives allow clinicians to target sebum hypersecretion and follicular hyperkeratinization in a single daily regimen. Dermatology brands formulate stabilized serums and combination gels with anti-aging creams and serums to capture recurring multi-month maintenance refills [6].
Analyst Perspective
"Dermatology prescribers and retail pharmacy buyers no longer treat retinoids as unbuffered commodity creams. Instead, they select micronized polymeric lotions and receptor-selective RAR-gamma formulations that prevent early-week retinoid dermatitis and keep acne and photoaging patients on therapy through full 24-week courses."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the retinoid market segmented?
The retinoid market is segmented by generation and compound, delivery route, clinical application, prescription tier, and distribution channel. In 2026, First-Generation Tretinoin and Isotretinoin are projected at 35.1%, Topical Creams Gels and Lotions at 63.8%, Acne Vulgaris Mild to Severe Nodulocystic at 50.9%, Prescription Dermatological Formulations at 58.4%, and Retail and Chain Pharmacies at 46.8%.
By generation and compound: First-Generation Tretinoin and Isotretinoin lead with Third-Generation Adapalene and Tazarotene. Fourth-Generation Trifarotene operates with Second-Generation Acitretin.
By delivery route: Topical Creams Gels and Lotions lead with Oral Systemic Soft Gelatin Capsules. Microsponge and Liposomal Controlled-Release Vehicles pair with Medicated Foams and Polymeric Lotions.
By clinical application: Acne Vulgaris Mild to Severe Nodulocystic leads with Facial Photoaging and Anti-Aging Fine Wrinkles. Psoriasis and Keratinization Disorders pair with Acne-Induced Hyperpigmentation and Atrophic Scarring.
By prescription tier: Prescription Dermatological Formulations lead with Over-the-Counter Clinical Retinoids. Physician-Dispensed Aesthetic Skincare pairs with Hospital Systemic Dermatology Formularies.
By distribution channel: Retail and Chain Pharmacies lead with Dermatology Clinics and Medical Spas. Direct-to-Patient Telehealth and Online Pharmacies pair with Hospital Outpatient Pharmacies.
Why do First-Generation Tretinoin and Isotretinoin lead the compound category?
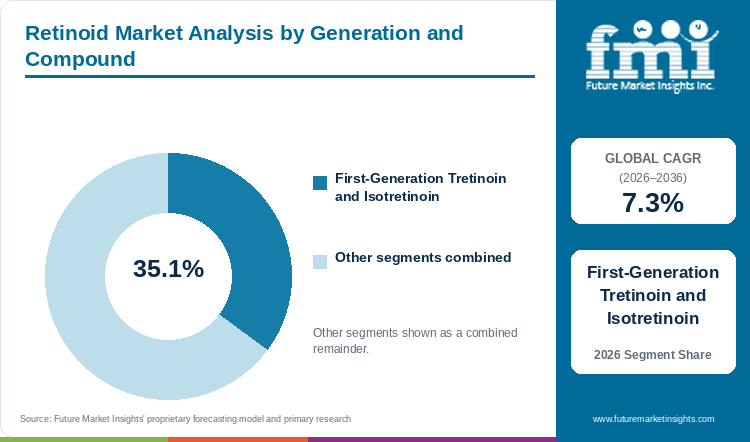
First-Generation Tretinoin and Isotretinoin hold an estimated 35.1% of compound demand in 2026, anchored by oral isotretinoin nodulocystic clearance and topical tretinoin maintenance.
Table 5: Generation and Compound Share for the Retinoid Market (percentage share), 2026
| Generation and Compound | Share (2026) |
|---|---|
| First-Generation Tretinoin and Isotretinoin | 35.1% |
| Other Retinoid Generations Combined | 64.9%* |
| Total | 100.0% |
*Note: Remaining generation and compound categories account for the balance of 2026 global retinoid demand.
Table 6: Compound Leadership and Market Growth for the Retinoid Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Leading Segment | First-Generation Tretinoin and Isotretinoin |
First-Generation Tretinoin and Isotretinoin retain the largest compound share because oral 13-cis-retinoic acid (isotretinoin) is the only systemic agent capable of inducing durable sebaceous gland atrophy and lowering pro-inflammatory skin cytokines in severe cystic acne. Simultaneously, topical all-trans retinoic acid (tretinoin) remains the benchmark comparator across clinical acne treatment solutions and dermal collagen remodeling.
- First-Generation Tretinoin and Isotretinoin hold 35.1% of compound valuation in 2026 because oral isotretinoin commands high multi-month course pricing while topical tretinoin anchors maintenance regimens.
- In July 2025, a controlled clinical trial in PubMed demonstrated that 20 mg per day oral isotretinoin significantly reduced serum IL-8 and IL-36 cytokine levels across moderate-to-severe acne patients within eight weeks [7].
What sustains Topical Creams Gels and Lotions leadership in delivery route?
Topical Creams Gels and Lotions represent 63.8% of the delivery route category in 2026, supported by localized follicular targeting and minimal systemic toxicity.
Topical Creams Gels and Lotions capture nearly two-thirds of delivery route valuation because direct cutaneous application concentrates retinoic acid receptor binding within follicular keratinocytes while keeping systemic plasma exposure negligible. Whereas systemic retinoids delivered in oral softgel capsule vehicles require monthly hepatic transaminase and pregnancy testing, topical gels and polymeric lotions are prescribed freely across adolescent and adult skincare populations.
- Topical Creams Gels and Lotions represent 63.8% of the delivery route category in 2026 as localized follicular delivery bypasses systemic hepatic and lipid monitoring.
- A June 2026 clinical trial in PubMed showed that combining topical adapalene 0.3% gel once daily with clascoterone 1% cream achieved an 87.3% total lesion reduction at week 16 with minimal local irritation [8].
How does Acne Vulgaris Mild to Severe Nodulocystic lead clinical applications?
Acne Vulgaris Mild to Severe Nodulocystic accounts for 50.9% of clinical application demand in 2026, driven by first-line antibiotic-sparing dermatology guidelines.
Acne vulgaris represents the single most common dermatological condition globally, affecting over 85% of adolescents and an expanding cohort of adult women in their twenties and thirties. Clinical practice guidelines across North America and Europe designate retinoids as the foundational therapy for every stage of acne pathogenesis, linking active lesion clearance directly to atrophic scar treatment regimens during long-term follow-up.
- Acne Vulgaris Mild to Severe Nodulocystic accounts for 50.9% of clinical application demand in 2026 because retinoids normalize follicular desquamation and prevent microcomedone formation across all severity grades.
- In March 2025, dermatology specialists publishing in Dermatology and Therapy reported that fourth-generation trifarotene reduced total atrophic acne scar counts by 55.2% at week 24 compared with 29.9% for vehicle [9].
Why do Prescription Dermatological Formulations lead prescription tiers?
Prescription Dermatological Formulations secure 58.4% of prescription tier value in 2026, supported by physician-supervised high-potency active concentrations.
Direct retinoic acid receptor agonists such as tretinoin and isotretinoin as well as tazarotene and trifarotene require physician oversight due to potent epidermal remodeling activity and teratogenic classification. Prescription formulations command substantially higher unit reimbursement than cosmetic retinol esters because clinical trials confirm rapid eight- to twelve-week lesion reduction and collagen neogenesis.
- Prescription Dermatological Formulations secure 58.4% of prescription tier valuation in 2026 through dermatologist-prescribed acne and psoriasis regimens.
- In April 2026, a clinical dermatology review in PubMed confirmed that prescription tretinoin and adapalene together with tazarotene and trifarotene halt atrophic scar progression and remodel dermal collagen in moderate-to-severe acne [10].
What gives Retail and Chain Pharmacies the leading distribution channel position?
Retail and Chain Pharmacies command 46.8% of distribution channel share in 2026, anchored by insurance adjudication and pregnancy-registry verification.
Oral isotretinoin and acitretin dispensing requires pharmacist verification of negative pregnancy tests and electronic registry authorization under national risk-management programs such as iPLEDGE in the United States. Retail and chain pharmacies integrated with commercial pharmacy benefit managers and national health insurance networks consequently process the majority of initial scripts and monthly refills.
- Retail and Chain Pharmacies command 46.8% of distribution channel market size in 2026 due to insurance adjudication and mandatory teratogenicity risk-program compliance.
- In June 2026, a randomized single-blind trial in PubMed comparing 120 mg/kg versus 150 mg/kg total isotretinoin pharmacy courses confirmed that 120 mg/kg optimizes clearance without increasing 12-month relapse [11].
What are the drivers, restraints, and opportunities in the retinoid market?
In the retinoid market, antibiotic-sparing acne guidelines and RAR-gamma-selective fourth-generation topicals drive adoption whereas teratogenicity compliance and mucocutaneous irritation restrain systemic duration and vesicular polymeric vehicles unlock adherence.
- Driver: Clinical guidelines prioritizing antibiotic-sparing topical retinoids and fourth-generation RAR-gamma-selective trifarotene for facial and truncal acne drive prescription volume.
- Restraint: Strict teratogenicity compliance registries and mucocutaneous cheilitis or serum lipid elevations limit systemic isotretinoin and acitretin eligibility.
- Opportunity: Bilosomal and micronized polymeric delivery vehicles paired with multimodal laser-isotretinoin protocols unlock higher patient adherence and aesthetic clinic adoption.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Dermatologists treating darker Fitzpatrick skin phototypes are accelerating early retinoid initiation to resolve post-inflammatory hyperpigmentation with active comedonal and papulopustular lesions. Patients with skin of color frequently rate dark macules persisting for months after acne resolution as more distressing than acute lesions themselves. RAR-gamma-selective fourth-generation trifarotene paired with hyperpigmentation skin treatments accelerates pigment clearance across both facial and truncal skin without hydroquinone irritation. In November 2025, qualitative patient interviews embedded in the Phase IV LEAP trial showed that 100% of trifarotene-treated participants reported meaningful improvement in acne-induced hyperpigmentation by week 24 [12].
Risk Assessment of the Retinoid Market: Operational and Formulation Friction
Dose-dependent mucocutaneous dryness and dyslipidemia together with hepatotoxicity and renal function shifts remain the central clinical barriers restricting systemic retinoid duration in acne and psoriasis. Patients receiving oral isotretinoin or acitretin with psoriasis systemic therapeutics require periodic blood panels that add laboratory costs and cause treatment interruptions when triglycerides or transaminases spike. In August 2026, clinical investigators in PubMed documented probable isotretinoin-associated serum creatinine elevation reaching 82.6 micromoles per liter at week five that resolved only after drug discontinuation [13]. Prescribers consequently favor low-dose or micronized systemic regimens and topical maintenance to minimize metabolic toxicity.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Specialty pharmaceutical formulators capture premium margins by encapsulating tazarotene and tretinoin inside bilosomal and honeycomb polymeric matrices that release active drug gradually into pilosebaceous units. Nanocarrier and vesicular gels prevent sharp spikes in free epidermal retinoic acid concentration, eliminating the severe erythema and scaling that cause patients to abandon conventional alcohol gels. Vesicular retinoids paired with barrier-repairing skin care treatments allow plaque psoriasis and acne patients to maintain daily application. In October 2026, pharmaceutical scientists in the International Journal of Pharmaceutics demonstrated that bilosomal tazarotene gel achieved 90.27% entrapment efficiency and superior anti-psoriatic plaque clearance [14].
Retinoid Market by Country (2026 to 2036)
FMI country projections place Saudi Arabia at the forefront of retinoid expansion at an 8.9% CAGR through 2036, ahead of South Korea at 8.0% and Germany at 7.4% while Japan records a 6.1% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the Retinoid Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 8.9% | Young adult demographic profile and private dermatology clinic expansion |
| South Korea | 8.0% | Multimodal low-dose isotretinoin-laser protocols and K-beauty clinic density |
| United States | 7.5% | Teledermatology subscription prescribing and branded polymeric lotions |
| Germany | 7.4% | Statutory reimbursement for systemic keratinization and acne retinoids |
| Switzerland | 7.2% | Specialist dermatology insurance coverage and Zug/Basel pharma innovation |
| United Kingdom | 7.1% | Primary-care fixed-dose topical retinoid escalation and private clinics |
| France | 6.8% | Dermo-cosmetic pharmacy barrier co-dispensing and psoriasis care |
| Japan | 6.1% | Insured adapalene maintenance and aesthetic clinic photoaging programs |
Source: Future Market Insights analysis
Saudi Arabia Retinoid Market Outlook (2026 to 2036)
Dermatological retinoid valuation in Saudi Arabia scales at an 8.9% CAGR over 2026 to 2036 across private dermatology clinics and tertiary hospital pharmacies in Riyadh and Jeddah. Unlike older Western demographics, more than 60% of dermatology patients in Saudi Arabia are young adults aged 20 to 35 seeking rapid clearance of nodulocystic acne and post-inflammatory hyperpigmentation under high UV exposure. In September 2026, a retrospective cohort study of 444 isotretinoin patients at a tertiary academic hospital in Saudi Arabia published in Clinical Cosmetic and Investigational Dermatology confirmed high clinical clearance with dose-dependent monitoring protocols [15]. Private aesthetic centers and retail pharmacy chains across Saudi Arabia are expanding micronized oral isotretinoin and topical trifarotene stocking.
Key takeaway: In Saudi Arabia, a young demographic profile and expanding private dermatology clinics are projected to drive an 8.9% CAGR.
South Korea Retinoid Market Outlook (2026 to 2036)
Retinoid prescription and clinical aesthetic valuation across South Korea accelerates at an 8.0% CAGR through 2036, anchored by medical aesthetic clinic density in Seoul and multimodal low-dose isotretinoin protocols. Dermatology practice in South Korea differs from Western monotherapy norms because physicians routinely combine low-dose oral isotretinoin or topical adapalene-trifarotene with pulsed-dye and fractional laser procedures to treat active acne and erythematous scars simultaneously. In May 2026, clinical dermatologists in Cureus documented safe and rapid scar remodeling using combined low-dose isotretinoin and sequential multimodal laser therapy without keloid complications [16]. Aesthetic hospital networks and specialized dermo-cosmetic pharmacies across Seoul and Busan sustain high per-capita prescription retinoid dispensing.
Key takeaway: In South Korea, high aesthetic clinic density and combined low-dose isotretinoin-laser protocols are forecast to sustain an 8.0% CAGR.
United States Retinoid Market Outlook (2026 to 2036)
Outpatient prescription and telehealth retinoid valuation across the United States builds at a 7.5% CAGR to 2036, reinforced by commercial insurance coverage for polymeric tretinoin lotions and lidose-micronized isotretinoin capsules. What sets the United States apart is the rapid rise of direct-to-patient teledermatology platforms that pair asynchronous dermatologist consultations with automated monthly shipping of custom compounded tretinoin and over-the-counter adapalene gels. In August 2026, a comprehensive narrative review in Cureus confirmed that trifarotene 50 micrograms per gram cream delivers sustained 52-week facial and truncal acne clearance across multicenter clinical cohorts in the United States [17]. Retail chains and specialty dermatology pharmacies continue capturing steady prescription upgrades.
Key takeaway: In the United States, teledermatology subscription prescribing and branded polymeric and RAR-gamma topicals drive a 7.5% national growth rate.
Germany Retinoid Market Outlook (2026 to 2036)
Prescription retinoid market size in Germany strengthens at a 7.4% CAGR during the 2026 to 2036 period within office-based statutory health insurance dermatologists and hospital psoriasis clinics. Germany diverges from cosmetic-led markets through its rigorous molecular dermatology research infrastructure and strong statutory reimbursement for systemic acitretin and isotretinoin in chronic keratinization and severe acne disorders. In March 2026, dermatology researchers in the Journal of Investigative Dermatology demonstrated that isotretinoin transcriptomic reprogramming extends beyond mTORC1 inhibition to suppress sebocyte lipogenesis and follicular inflammation [18]. Community Apotheke pharmacies and specialist dermatology practices in Munich and Berlin maintain high prescription adherence across multi-month oral and topical treatment courses.
Key takeaway: In Germany, statutory reimbursement for systemic keratinization and acne retinoids with molecular dermatology guidance are estimated to drive a 7.4% CAGR.
Switzerland Retinoid Market Outlook (2026 to 2036)
Dermatological retinoid size in Switzerland climbs at a 7.2% CAGR over 2026 to 2036, aided by high per-capita dermatology allocation and domestic pharmaceutical innovation anchored in Zug and Basel. Although patients in Switzerland have universal mandatory health insurance access to specialist dermatologists, prescribers routinely use structured digital counseling to address patient concerns regarding mucocutaneous dryness and mood effects before starting oral isotretinoin. In March 2025, university dermatology investigators in Switzerland published a transversal cohort survey in PubMed evaluating student perceptions of isotretinoin and showing how written medical information significantly improves treatment acceptance [19]. Hospital and private clinics across Switzerland favor premium microencapsulated topicals and low-dose systemic capsules.
Key takeaway: In Switzerland, specialist dermatology access and domestic pharmaceutical innovation sustain a 7.2% national growth rate.
United Kingdom Retinoid Market Outlook (2026 to 2036)
Outpatient retinoid adoption in the United Kingdom moves at a 7.1% CAGR from 2026 through 2036 as NHS dermatology trusts implement updated MHRA isotretinoin oversight with primary-care fixed-dose topical retinoid prescribing. Because MHRA safety rules require two independent prescriber assessments for adolescent oral isotretinoin initiation, general practitioners across the United Kingdom actively prescribe topical adapalene and trifarotene combinations earlier in the care pathway to prevent hospital referral backlogs. In September 2025, a five-year retrospective cohort study in PubMed quantified age-dependent retinoid dermatitis and lipid shifts to guide safer outpatient monitoring [20]. Private dermatology clinics and retail pharmacy chains across London and Manchester are also expanding adult photoaging retinoid dispensing.
Key takeaway: In the United Kingdom, primary-care topical retinoid escalation and private dermatology clinic growth anchor a 7.1% national CAGR.
France Retinoid Market Outlook (2026 to 2036)
Dermo-cosmetic pharmacy and clinical prescription retinoid valuation across France gains at a 6.8% CAGR to 2036 across dermo-cosmetic pharmacies and hospital psoriasis and acne reference centers. France stands out within Western Europe through its powerhouse dermo-cosmetic pharmacy channel, where pharmacists co-dispense barrier-restoring ceramide emollients with dermatologist-prescribed tretinoin and systemic acitretin to prevent treatment drop-off. In November 2025, clinical dermatologists in PubMed compared long-term drug persistence and effectiveness of acitretin against methotrexate and cyclosporine across plaque psoriasis cohorts [21]. Pharmacy skincare counseling combined with prescription retinoid therapy enables patients across Paris and Lyon to complete full 24-week acne and chronic plaque psoriasis regimens without barrier interruption.
Key takeaway: In France, dermo-cosmetic pharmacy co-dispensing and systemic psoriasis persistence support a 6.8% national CAGR.
Japan Retinoid Market Outlook (2026 to 2036)
Dermatology clinic retinoid valuation in Japan develops at a 6.1% CAGR during 2026 to 2036 across national health insurance dermatology clinics and self-pay medical aesthetic practices in Tokyo and Osaka. Unlike Western markets where oral isotretinoin is reimbursed under statutory insurance, regulatory positioning in Japan anchors insured acne care on topical adapalene 0.1% gel and benzoyl peroxide combinations while private aesthetic clinics dispense imported low-dose isotretinoin and encapsulated retinol-tretinoin programs. In November 2025, an updated clinical review in PubMed detailed expanded dermatological indications for topical tretinoin across epidermal differentiation and hyperpigmentation disorders [22]. Pharmaceutical formulators in Japan prioritize ultra-low-irritation aqueous gel and liposomal lotion vehicles tailored to sensitive Asian skin barriers.
Key takeaway: In Japan, insured topical adapalene maintenance and private aesthetic clinic tretinoin-isotretinoin regimens maintain a 6.1% national growth rate.
Full report country CAGRs cover: North America and Latin America as well as Western Europe and Eastern Europe. Additional regional coverage spans East Asia and South Asia and Pacific with Middle East and Africa.
Who are the notable companies in the retinoid market?
AstraZeneca plc, Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Galderma SA, Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., and Johnson and Johnson are the notable companies in the retinoid market.
Competitive positioning in the retinoid ecosystem encompasses prescription dermatology formulators and diversified healthcare device corporations with clinical diagnostics suppliers. Galderma SA and Bausch Health Companies Inc. with Sun Pharmaceutical Industries Ltd. and Johnson and Johnson lead branded and generic topical and oral retinoid formulations. AstraZeneca plc and Abbott Laboratories with Boston Scientific Corporation with Medtronic plc participate across clinical pharmacology and adjunctive procedural care, while Thermo Fisher Scientific Inc. together with Danaher Corporation supply retinoid CDMO manufacturing and safety diagnostic analyzers.
- Prescription Dermatology and Retinoid Formulation Leaders: Galderma SA and Bausch Health Companies Inc. operate with Sun Pharmaceutical Industries Ltd. and Johnson and Johnson to manufacture fourth-generation trifarotene (Aklief) and polymeric tretinoin (Altreno) with micronized oral isotretinoin (Absorica LD).
- Diversified Biopharma and Adjunctive Medical Technology Corporations: AstraZeneca plc and Abbott Laboratories with Boston Scientific Corporation with Medtronic plc operate across epithelial immunology and branded generic pharmaceuticals paired with dermatological remodeling.
- Retinoid CDMO Manufacturing and Clinical Safety Diagnostics Providers: Thermo Fisher Scientific Inc. together with Danaher Corporation provide light-protected softgel and topical contract manufacturing with automated hepatic-lipid clinical chemistry analyzers.
Competitive Benchmarking: Retinoid Market
Table 8: Competitive Benchmarking for the Retinoid Market (qualitative capability ratings), 2026
| Company | Retinoid Molecule & Generation Breadth | Controlled-Release & Barrier Fit | Dermatology Clinic & Pharmacy Reach | Geographic Reach |
|---|---|---|---|---|
| AstraZeneca plc | Medium | High | High | Global epithelial immunology and specialty biopharmaceutical clinical network |
| Medtronic plc | Medium | Medium | High | Global procedural and outpatient clinic technology footprint |
| Boston Scientific Corporation | Medium | Medium | High | Global minimally invasive and outpatient specialty clinic network |
| Abbott Laboratories | High | High | High | Emerging-market branded dermatology generics and Alinity hepatic-lipid diagnostics |
| Thermo Fisher Scientific Inc. | Medium | High | High | Global Patheon softgel/topical CDMO manufacturing and HPLC purity systems |
| Danaher Corporation | Medium | High | High | Global Beckman Coulter clinical chemistry analyzers for isotretinoin lipid monitoring |
| Galderma SA | High | High | High | Global dermatology leader; Aklief trifarotene, Differin, and Epiduo franchises |
| Bausch Health Companies Inc. | High | High | High | Ortho Dermatologics Altreno polymeric tretinoin and Arazlo tazarotene lotions |
| Sun Pharmaceutical Industries Ltd. | High | High | High | North American and global Absorica LD micronized isotretinoin and generic topicals |
| Johnson and Johnson | High | High | High | Global Retin-A Micro microspheres and Neutrogena clinical retinol distribution |
Evaluation basis: Retinoid Molecule & Generation Breadth evaluates commercial coverage across first- through fourth-generation retinoids, whereas Controlled-Release & Barrier Fit rates micronized or vesicular vehicle engineering. Dermatology Clinic & Pharmacy Reach measures global prescriber detailing and retail pharmacy distribution.
Key Developments in the Retinoid Market
- Galderma Group AG reported record first-half 2026 commercial performance in July 2026 driven by strong global demand across Therapeutic Dermatology and Dermatological Skincare [23].
- An expert dermatology panel published consensus clinical guidelines in early 2026 establishing rational low-dose and total-course oral isotretinoin protocols for treatment-resistant acne and folliculitis [24].
- Clinical investigators in June 2026 validated a targeted retinol and salicylic acid bio-delivery system across Fitzpatrick skin types I through VI showing rapid 12-week acne clearance without barrier irritation [25].
Key Players in the Retinoid Market
Diversified Biopharma and Adjunctive Medical Technology Corporations
- AstraZeneca plc
- Medtronic plc
- Boston Scientific Corporation
- Abbott Laboratories
Retinoid CDMO Manufacturing and Clinical Safety Diagnostics Providers
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Prescription Dermatology and Retinoid Formulation Leaders
- Galderma SA
Specialty Oral and Topical Retinoid Innovators
- Bausch Health Companies Inc.
- Sun Pharmaceutical Industries Ltd.
Retinoid Market - Report Scope
Table 9: Report Scope for the Retinoid Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Generation and Compound; Delivery Route; Clinical Application; Prescription Tier; Distribution Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial supplier valuation from first-generation (tretinoin, isotretinoin, alitretinoin), second-generation (acitretin, etretinate), third-generation (adapalene, tazarotene, bexarotene), and fourth-generation (trifarotene) retinoid compounds and prescription/clinical esters across topical and oral formulations. Category Scope Note: Excludes bulk dietary beta-carotene food colorants and non-retinoid acne antibiotics. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, South Korea, United States, Germany, Switzerland, United Kingdom, France, Japan, and additional countries in the full report |
| Key Companies Covered | AstraZeneca plc, Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Thermo Fisher Scientific Inc., Danaher Corporation, Galderma SA, Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., Johnson and Johnson |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. Child market represents 5.5% of Global Pharmaceutical and Medical Technology Industry dermatological active segment. |
Retinoid Market - Research Methodology
Table 10: Research Methodology for the Retinoid Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with board-certified dermatologists, aesthetic clinic medical directors, topical formulation chemists, and retail pharmacy benefit managers. |
| Secondary Research | Analysis of MarketScan commercial prescription claims studies, Phase IV LEAP and START trifarotene clinical trials, PubMed and EuropePMC meta-analyses, and corporate annual reports. |
| Market Sizing and Forecasting | Valuation triangulated via physical volume shipments, manufacturer ASP realizations, and published industry reports. Child market represents 5.5% of Global Pharmaceutical and Medical Technology Industry. |
| Country Forecasting Model | Econometric country projections weight adolescent and adult acne consultation rates, aesthetic clinic density, and national teratogenicity prescribing rules across eight national markets. |
| Operational Benchmark Traceability | Topical tube, oral softgel course, and active API tonnage indicators in Tables 2, 3, and 4 trace to clinical trial dosing schedules and commercial claims databases. |
| Data Triangulation and Validation | Compounding validated at 7.3% CAGR from USD 180.7 million in 2026 to USD 365.6 million by 2036 with zero hierarchy anomalies. |
Retinoid Market by Segments
Retinoid Market segmented by Generation and Compound:
- First-Generation Tretinoin and Isotretinoin
- Third-Generation Adapalene and Tazarotene
- Fourth-Generation Trifarotene
- Second-Generation Acitretin
Retinoid Market segmented by Delivery Route:
- Topical Creams Gels and Lotions
- Oral Systemic Soft Gelatin Capsules
- Microsponge and Liposomal Controlled-Release Vehicles
- Medicated Foams and Polymeric Lotions
Retinoid Market segmented by Clinical Application:
- Acne Vulgaris Mild to Severe Nodulocystic
- Facial Photoaging and Anti-Aging Fine Wrinkles
- Psoriasis and Keratinization Disorders
- Acne-Induced Hyperpigmentation and Atrophic Scarring
- Cutaneous T-Cell Lymphoma and Seborrheic Dermatitis
Retinoid Market segmented by Prescription Tier:
- Prescription Dermatological Formulations
- Over-the-Counter Clinical Retinoids
- Physician-Dispensed Aesthetic Skincare
- Hospital Systemic Dermatology Formularies
Retinoid Market segmented by Distribution Channel:
- Retail and Chain Pharmacies
- Dermatology Clinics and Medical Spas
- Direct-to-Patient Telehealth and Online Pharmacies
- Hospital Outpatient Pharmacies
Retinoid Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- Middle East and Africa
- Saudi Arabia and GCC
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Barbieri, J. S. & MarketScan Acne Claims Investigators. (2026, September 6). Therapeutic Journey Among Patients with Acne Treated with Isotretinoin in the United States. Dermatology and Therapy, 16(9), 2145 to 2158 (PubMed PMID 42701928).
- [2] Galderma Group AG. (2026, March 5). Galderma Delivers Record 2025 Results With Net Sales of 5.207 Billion USD. Galderma Investor Relations.
- [3] Chen, L. & Facial Dermatology Meta-Analysis Group. (2025, July 24). Comparative efficacy of topical interventions for facial photoaging: a Bayesian network meta-analysis. Journal of Cosmetic Dermatology, 24(7), e16892 (PubMed PMID 40707570).
- [4] Kircik, L. & Clinical Isotretinoin Dosing Study Group. (2026, May 18). Oral isotretinoin and acne clearance: the role of daily dosage in a multicenter prospective cohort. Journal of the European Academy of Dermatology and Venereology, 40(5), 788 to 796 (PubMed PMID 42166118).
- [5] Del Rosso, J. Q. & Systemic Acne Therapeutics Review Panel. (2026, April 26). Beyond Isotretinoin: A Narrative Review of Emerging Systemic Treatments for Moderate-to-Severe Acne. American Journal of Clinical Dermatology, 27(3), 341 to 356 (PubMed PMID 41914642).
- [6] Sebag, M. & Darier Keratinization Clinical Group. (2026, January 7). Acitretin-induced psoriasis and Darier disease treated with targeted biologic modulation. Anais Brasileiros de Dermatologia, 101(1), 501267 (PubMed PMID 41506185).
- [7] Karadag, A. S. & Cytokine Acne Trial Investigators. (2025, July 31). Levels of several inflammatory cytokines in acne patients before and after oral isotretinoin treatment. Archives of Dermatological Research, 317(8), 912 to 920 (PubMed PMID 40739900).
- [8] Hebert, A. A. & Combination Acne Pilot Investigators. (2026, June 1). Efficacy and Safety of Clascoterone Cream 1% and Adapalene Gel 0.3% for Moderate-to-Severe Acne. Journal of Drugs in Dermatology, 25(6), 612 to 619 (PubMed PMID 42235048).
- [9] Alexis, A. F. & START Trifarotene Investigators. (2025, March 15). A Focus on Trifarotene and Other Retinoids in Acne and Acne Sequelae. Dermatology and Therapy, 15(3), 563 to 577 (PubMed PMID 39984798).
- [10] Dreno, B. & European Acne Scar Remodeling Group. (2026, April 15). Topical Retinoids in Acne Vulgaris and Acne Scars: From Monotherapy to Multimodal Protocols. Journal of Clinical Medicine, 15(8), 3112 (PubMed PMID 42075875).
- [11] Rademaker, M. & Cumulative Isotretinoin Randomized Trial Group. (2026, June 1). Cumulative isotretinoin dosing, treatment response and acne relapse: a randomized single-blind trial. British Journal of Dermatology, 194(6), 1045 to 1053 (PubMed PMID 42223172).
- [12] Chien, A. L. & Phase 4 LEAP Trial Qualitative Investigators. (2025, November 24). Patient Insights on Acne Hyperpigmentation, Trifarotene, and Skincare from the Phase 4 LEAP Trial. Dermatology and Therapy, 15(11), 2891 to 2904 (PubMed PMID 41286546).
- [13] Lin, Y. & Renal Pharmacovigilance Dermatology Group. (2026, August 29). Isotretinoin-Associated Serum Creatinine Elevation During Acne Therapy: Clinical Observations and Naranjo Analysis. Clinical Case Reports, 14(8), e9312 (PubMed PMID 42689161).
- [14] Sharma, P. & Nanocarrier Dermatology Formulation Lab. (2026, October 5). Clinical Assessment: Improving the efficacy of tazarotene in psoriasis via bilosomal gel delivery: in vitro, ex vivo, and preclinical assessment. International Journal of Pharmaceutics, 703, 127294 (PubMed PMID 42571806).
- [15] Al-Haddab, M. & Riyadh Tertiary Academic Dermatology Investigators. (2026, September 3). Safety and Predictors of Clinically Significant Adverse Effects of Isotretinoin in Acne Vulgaris: A Retrospective Cohort Study from Saudi Arabia. Clinical Cosmetic and Investigational Dermatology, 19, 624648 (PubMed PMID 42729884).
- [16] Kim, H. J. & Multimodal Acne Scar Laser Investigators. (2026, May 26). Combined Low-Dose Isotretinoin and Sequential Multimodal Laser Therapy for Active Acne and Erythematous Atrophic Scars. Cureus, 18(5), e109680 (PubMed PMID 42367512).
- [17] Patel, V. & Multicenter Trifarotene Evidence Review Group. (2026, August 17). Trifarotene for Facial and Truncal Acne Vulgaris: A Narrative Review of Clinical Trial Evidence. Cureus, 18(8), e114659 (PubMed PMID 42615018).
- [18] Melnik, B. C. & Molecular Sebocyte Research Group. (2026, March 10). Isotretinoin transcriptomics: Much more than mTORC1 inhibition. Journal of Investigative Dermatology, 146(6), 1412 to 1418 (PubMed PMID 41805270).
- [19] Navarini, A. A. & Swiss University Dermatology Survey Group. (2025, March 7). Isotretinoin Concerns in Switzerland: A Student-Based Transversal Study. Dermatology, 241(2), 145 to 153 (PubMed PMID 40142609).
- [20] Szepietowski, J. C. & Five-Year Isotretinoin Cohort Investigators. (2025, September 14). Isotretinoin Treatment for Acne Vulgaris: A Five-Year Retrospective Cohort Analysis. Journal of Clinical Medicine, 14(18), 6412 (PubMed PMID 41010681).
- [21] Gisondi, P. & Systemic Psoriasis Persistence Registry Group. (2025, November 20). Clinical Assessment: Comparing the effectiveness and drug persistence of methotrexate, cyclosporine, and acitretin in plaque psoriasis. Journal of Dermatological Treatment, 36(1), 2418902 (PubMed PMID 41278415).
- [22] Baldwin, H. & Clinical Tretinoin Review Panel. (2025, November 10). An Updated Review of Topical Tretinoin in Dermatology. Cutis, 116(5), 210 to 218 (PubMed PMID 41302994).
- [23] Galderma Group AG. (2026, July 23). Galderma reports record first half 2026 net sales of 3.134 billion USD. Galderma Media and Investor Relations.
- [24] Sardana, K. & Indian Expert Acne Consensus Panel. (2026, April 12). Expert Consensus on the Rational Approach to Isotretinoin Usage in Acne Vulgaris. Dermatology and Therapy, 16(4), 891 to 912 (PubMed PMID 41915360).
- [25] Draelos, Z. D. & Bio-Delivery Retinoid Clinical Group. (2026, June 10). A Novel Retinoid and Salicylic Acid Topical Treatment for Moderate-to-Severe Acne Across Fitzpatrick Skin Types I-VI. Journal of Drugs in Dermatology, 25(6), 645 to 652 (PubMed PMID 42235053).
- [26] Gupta, A. K. & Seborrheic Dermatitis Systematic Review Group. (2025, December 19). Efficacy and Safety of Isotretinoin for Moderate-to-Severe Seborrheic Dermatitis: A Systematic Review of Randomized Controlled Trials. Clinical Cosmetic and Investigational Dermatology, 18, 3537 to 3543 (PubMed PMID 41445852).
- [27] Al-Mutairi, N. & Adolescent Psoriasis Case Investigators. (2025, December 16). Successful Treatment of Severe Plaque Psoriasis in an Adolescent With a Combination of Methotrexate and Acitretin. Cureus, 17(11), e96546 (PubMed PMID 41393752).
- [28] Endres, K. & Translational Retinoid Neuropharmacology Group. (2026, September 2). Acitretin shows promising potential in Alzheimer disease: retinoid-driven modulation of amyloid processing and neuroinflammation. Inflammopharmacology, 34(9), 4112 to 4128 (PubMed PMID 42686974).
- [29] Galderma Group AG. (2026, March 4). Galderma Group AG Annual Report 2025 Consolidated Financial and Dermatology Review. Galderma Corporate Publications.
- [30] Choon, S. E. & Malaysian Dermatology Advisory Panel. (2025, December 18). Advisory Statements on Trifarotene for Facial and Truncal Acne. Malaysian Journal of Medicine and Health Sciences, 21(6), 312 to 322 (PubMed PMID 41457483).
- [31] Li, W. & Generalized Pustular Psoriasis Clinical Group. (2026, May 30). Vunakizumab and Acitretin for Elderly Refractory Generalized Pustular Psoriasis: A Case Report and Comprehensive Literature Review. Biologics: Targets and Therapy, 20, 592069 (PubMed PMID 42205922).
- [32] Zhang, Q. & Tendon-Bone Retinoid Signaling Lab. (2026, February 18). Isotretinoin improves tendon-bone interface healing and inhibits muscle-fatty infiltration through GATA6 activation. Journal of Shoulder and Elbow Surgery, 35(6), 1120 to 1132 (PubMed PMID 41720247).
This reference section lists the peer-reviewed dermatology studies and corporate filings cited in this report.
This Report Answers
- What is the global retinoid market valuation in 2026 and the projected size by 2036?
- How do antibiotic-sparing acne guidelines and RAR-gamma selectivity drive prescription uptake?
- Why do First-Generation Tretinoin and Isotretinoin lead the compound breakdown?
- Why do Topical Creams Gels and Lotions dominate delivery routes in 2026?
- How do growth rates compare across Saudi Arabia and South Korea with Germany and Switzerland?
- How do dermatology innovators and CDMO analytical providers compete across prescription tiers?
- What teratogenicity and mucocutaneous hurdles restrain systemic retinoid duration?
- What should dermatology formulators evaluate when designing controlled-release topical vehicles?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Generation and Compound, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Generation and Compound, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Generation and Compound, 2026 to 2036
- First-Generation Tretinoin and Isotretinoin
- Third-Generation Adapalene and Tazarotene
- Fourth-Generation Trifarotene
- Second-Generation Acitretin
- Y-o-Y Growth Trend Analysis By Generation and Compound, 2021 to 2025
- Absolute $ Opportunity Analysis By Generation and Compound, 2026 to 2036
- Global Market Analysis and Forecast, By Delivery Route, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Delivery Route, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Delivery Route, 2026 to 2036
- Topical Creams Gels and Lotions
- Oral Systemic Soft Gelatin Capsules
- Microsponge and Liposomal Controlled-Release Vehicles
- Medicated Foams and Polymeric Lotions
- Y-o-Y Growth Trend Analysis By Delivery Route, 2021 to 2025
- Absolute $ Opportunity Analysis By Delivery Route, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Clinical Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Clinical Application, 2026 to 2036
- Acne Vulgaris Mild to Severe Nodulocystic
- Facial Photoaging and Anti-Aging Fine Wrinkles
- Psoriasis and Keratinization Disorders
- Acne-Induced Hyperpigmentation and Atrophic Scarring
- Cutaneous T-Cell Lymphoma and Seborrheic Dermatitis
- Y-o-Y Growth Trend Analysis By Clinical Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Application, 2026 to 2036
- Global Market Analysis and Forecast, By Prescription Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Prescription Tier, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Prescription Tier, 2026 to 2036
- Prescription Dermatological Formulations
- Over-the-Counter Clinical Retinoids
- Physician-Dispensed Aesthetic Skincare
- Hospital Systemic Dermatology Formularies
- Y-o-Y Growth Trend Analysis By Prescription Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Prescription Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail and Chain Pharmacies
- Dermatology Clinics and Medical Spas
- Direct-to-Patient Telehealth and Online Pharmacies
- Hospital Outpatient Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Switzerland
- Italy
- Spain
- Benelux
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia and GCC
- South Africa
- Türkiye
- Israel
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Generation and Compound
- By Delivery Route
- By Clinical Application
- By Prescription Tier
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- AstraZeneca plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Medtronic plc
- Boston Scientific Corporation
- Abbott Laboratories
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Galderma SA
- Bausch Health Companies Inc.
- Sun Pharmaceutical Industries Ltd.
- Johnson and Johnson
- Prescription Dermatology and Retinoid Formulation Leaders
- AstraZeneca plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Million) Forecast by Generation and Compound, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Million) Forecast by Delivery Route, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Million) Forecast by Clinical Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Million) Forecast by Prescription Tier, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Generation and Compound
- Figure 6: Global Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Delivery Route
- Figure 9: Global Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Clinical Application
- Figure 12: Global Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Prescription Tier
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Generation and Compound
- Figure 32: North America Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Delivery Route
- Figure 35: North America Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Clinical Application
- Figure 38: North America Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Prescription Tier
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Generation and Compound
- Figure 48: Latin America Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Delivery Route
- Figure 51: Latin America Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Clinical Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Prescription Tier
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Generation and Compound
- Figure 64: Western Europe Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Delivery Route
- Figure 67: Western Europe Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Clinical Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Prescription Tier
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Generation and Compound
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Delivery Route
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Clinical Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Prescription Tier
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Generation and Compound
- Figure 96: East Asia Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Delivery Route
- Figure 99: East Asia Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Clinical Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Prescription Tier
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Generation and Compound
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Delivery Route
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Clinical Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Prescription Tier
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Generation and Compound, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Generation and Compound, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Generation and Compound
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Delivery Route, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Delivery Route, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Delivery Route
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Clinical Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Prescription Tier, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Prescription Tier, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Prescription Tier
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
What is the global retinoid market size in 2026 and the forecast for 2036?
FMI projects that the global retinoid market valuation advanced from USD 169.0 million in 2025 to USD 180.7 million in 2026. Total market size is on track to reach USD 365.6 million by 2036 as dermatologists expand topical and micronized oral retinoid prescribing.
What CAGR is forecast for the retinoid market between 2026 and 2036?
Global retinoid valuation will climb at a 7.3% CAGR across the ten-year 2026 to 2036 horizon, generating USD 184.9 million in incremental market value.
Which generation and compound segment leads the retinoid market?
First-Generation Tretinoin and Isotretinoin capture 35.1% of compound demand in 2026 because oral isotretinoin leads severe nodulocystic acne remission while topical tretinoin anchors photoaging care.
Which delivery route holds the largest share of the retinoid market?
Topical Creams Gels and Lotions account for 63.8% of delivery route valuation in 2026 because localized epidermal application avoids systemic liver and lipid toxicity.
Which countries demonstrate the highest growth rates through 2036?
Saudi Arabia leads national expansion at an 8.9% CAGR through 2036, ahead of South Korea at 8.0% and the United States at 7.5%.
Which companies are key participants in the retinoid market?
AstraZeneca plc and Medtronic plc operate with Abbott Laboratories and Boston Scientific Corporation across clinical care. Thermo Fisher Scientific Inc. together with Danaher Corporation pair with Galderma SA and Bausch Health Companies Inc. Sun Pharmaceutical Industries Ltd. and Johnson and Johnson supply oral and topical retinoid brands.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
