
- Market Size (2026)
- USD 665.0 Mn
- Forecast (2036)
- USD 1332.8 Mn
- CAGR (2026 to 2036)
- 7.2%
How big is Saffron Market in 2026?
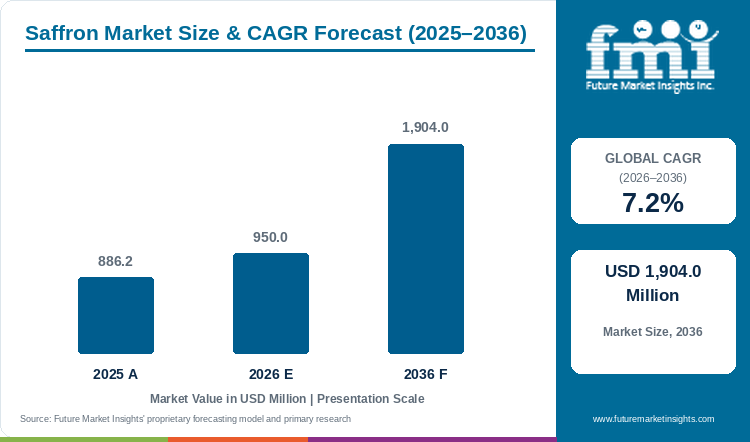
With a valuation of USD 620.0 million in 2025 and moving to USD 665.0 million in 2026, the saffron market is positioned to attain USD 1,332.8 million by 2036, exhibiting a CAGR of 7.2%.
The global saffron market was valued at USD 620.0 million in 2025 and is estimated to reach USD 665.0 million in 2026. Global market valuation is projected to attain USD 1,332.8 million by 2036, advancing at a compound annual growth rate (CAGR) of 7.2% over the 2026 to 2036 forecast period. Whole saffron threads and stigmas are expected to secure 62.5% of physical form demand in 2026, while first-grade Sargol and Super Negin filaments are anticipated to command 54.0% of quality grade demand as food and supplement buyers reject ungraded lots containing floral style waste. Commercial purchasing is shifting from bulk unbranded spice trading toward laboratory-certified crocin and safranal lots as beverage makers replace synthetic yellow azo dyes and wellness brands formulate standardized mood and sleep capsules. FMI finds that this bioactive potency premium separates the category from broader herbs and spices at a 3.5% CAGR, given that saffron procurement follows spectrophotometric absorbance thresholds and clinical extract dosing rather than commodity seasoning tonnage. Global supply remains anchored in Khorasan Razavi and South Khorasan, as the Food and Agriculture Organization of the United Nations reported in November 2025 that Iran produces 85% to 90% of global saffron output and launched a value-chain quality integrity program for pre-dosed and instant-dissolved formats [1]. Active ingredient houses and heritage growers are expanding high-purity lines, illustrated by Givaudan's November 2025 standardization of safranal aroma molecules for fine fragrance and flavor compounding [2]. Importers lock in multi-year contracts when exporters provide high-performance liquid chromatography certificates confirming zero synthetic dye adulteration through 2036.
Key Market Trends & Insights
- By physical form: Saffron Threads and Stigmas are projected to capture an estimated 62.5% share in 2026 given that intact crimson filaments prevent economic adulteration with turmeric or safflower.
- By quality grade: Grade I Sargol and Super Negin are anticipated to represent 54.0% in 2026 since all-red stigma cuts deliver spectrophotometric crocin coloring readings above 200.
- By end-use sector: Culinary and Gourmet Foodservice is estimated to account for 48.0% in 2026 owing to premium rice, seafood, and artisanal bakery preparation across hospitality and retail.
- By sourcing origin: Iranian Saffron is expected to command 72.0% in 2026 driven by deep corm acreage across Khorasan provinces and specialized optical thread-sorting plants.
- By distribution channel: Specialty Retail and Gourmet Grocers are forecast to hold 44.5% in 2026 through tamper-evident glass vials and origin-certified blister packs.
Regional Highlights
- Top national expansion: Brazil leads evaluated country growth projections at an 8.5% CAGR through 2036 supported by nutraceutical extract compounding and gourmet gastronomy imports.
- Broader country progression: The United States tracks at a 7.6% CAGR ahead of France at 7.3% and the United Kingdom at 7.2%, while Spain records 7.0% ahead of Germany at 6.8% and Japan at 6.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Saffron Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 620.0 million |
| Estimated Market Size in 2026 | USD 665.0 million |
| Projected Market Size by 2036 | USD 1,332.8 million |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 667.8 million |
Gourmet food processors, fine-dining restaurant groups, and botanical supplement manufacturers confront wide interannual swings in dried stigma yields caused by autumn temperature shifts and corm dormancy cycles. When field growers delay corm planting or use high-heat drying kilns, apocarotenoid pigments degrade and reduce commercial batch value. Quantitative nuclear magnetic resonance (qNMR) research published in Applied Sciences (MDPI) in August 2025 demonstrated that mean crocin concentrations in dried Crocus sativus stigmas ranged from 17.50 to 32.40 relative units and picrocrocin from 5.96 to 11.59 across controlled drying protocols [4]. Consequently, industrial spice buyers specify vacuum or controlled-temperature dehydrated Grade I threads to guarantee uniform golden color release per gram.
Dried Stigma Harvest Tonnage and Phytochemical Potency Sizing
Table 2: Dried Stigma Harvest Tonnage and ISO 3632 Potency Sizing for the Saffron Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 620.0 | 665.0 | 1,332.8 |
| Commercial dried saffron stigma output (metric tons) | 385.0 to 415.0 | 402.0 to 435.0 | 645.0 to 705.0 |
| Grade I Super Negin & Sargol crocin absorbance (E1% 440 nm) | 205 to 260 | 210 to 268 | 230 to 290 |
| Pharma, supplement & cosmetic extract crop share (%) | 24.0% to 27.5% | 26.0% to 29.5% | 36.5% to 41.0% |
Operational note: Harvest tonnage and spectrophotometric ranges reflect dried Crocus sativus L. stigmas (requiring 150,000 to 170,000 fresh flowers per kilogram) and standardized hydro-ethanolic extracts.
As documented in an October 2026 study in Frontiers in Sustainable Food Systems, sequential conversion of saffron crocins via response-surface-optimized hydrolysis achieved an 85.5% conversion yield into water-soluble disodium crocetinate while increasing co-recovered safranal content 12-fold [5]. This high-yield extraction chemistry allows pharmaceutical and beverage formulators to monetize both water-soluble coloring pigments and volatile aroma fractions from a single raw stigma lot.
Wholesale FOB Grade Pricing & Extract Allocation Benchmarks
Table 3: Wholesale FOB Grade Pricing and Moisture Benchmarks for the Saffron Market (USD per kilogram and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Wholesale Grade I Super Negin threads (USD/kg FOB) | 1,450 to 1,880 | 1,520 to 1,960 | 2,120 to 2,780 |
| Certified Kashmiri Mongra & Spanish PDO La Mancha (USD/kg) | 3,350 to 5,100 | 3,500 to 5,350 | 4,800 to 6,950 |
| Standardized 3.5% lepticrosalide botanical extract (USD/kg) | 2,600 to 3,550 | 2,720 to 3,700 | 3,550 to 4,850 |
| Maximum ISO 3632-1 whole-thread moisture limit (%) | 12.0% | 12.0% | 10.0% to 12.0% |
Table 4: Segment Allocation and Agronomic Reference Indicators for the Saffron Market (USD million and operational metrics), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 665.0 million | 2026 global saffron market valuation baseline |
| Iran share of global saffron production, 2025/26 | 85.0% to 90.0% | FAO and Iran Saffron Value Chain Quality Integrity Program (Nov 2025) |
| Jammu & Kashmir share of Indian production | 90.0% | UT Ladakh and Ministry of Agriculture saffron cultivation records (2026) |
| Culinary and Gourmet Foodservice allocation, 2026 | USD 319.2 million | 48.0% end-use sector share across hospitality and retail |
Yield stability across semi-arid highland terraces requires careful irrigation scheduling and soil organic matter management. As documented in a November 2025 Food and Agriculture Organization technical release for World Soil Day, Crocus sativus functions as a low-water-demand perennial geophyte suited to sloping arid lands where conventional irrigated row crops trigger soil erosion [6]. Because corms remain dormant through hot dry summers and flower following autumn rains, agricultural ministries in Iran and India are expanding drip-irrigated saffron terraces to secure exportable Grade I stigma supply.
Analyst Perspective
"Saffron procurement is bifurcating between visually intact Super Negin and Kashmiri Mongra threads for gourmet culinary presentation and HPLC-standardized crocin and safranal extracts for mood gummies, ocular capsules, and clean-label beverage coloring. Exporters that pair GI origin traceability with accredited laboratory testing against artificial colorants will command premium multi-year supply agreements."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the saffron market segmented?
The saffron market is segmented by physical form, quality grade, end-use sector, sourcing origin, and distribution channel. In 2026, Saffron Threads and Stigmas are projected at 62.5%, Grade I Sargol and Super Negin at 54.0%, Culinary and Gourmet Foodservice at 48.0%, Iranian Saffron at 72.0%, and Specialty Retail and Gourmet Grocers at 44.5%.
By physical form: Saffron Threads and Stigmas, Saffron Powder, Liquid Saffron Extracts and Concentrates, and Micro-Encapsulated Saffron Granules.
By quality grade: Grade I Sargol and Super Negin, Grade II Pushal, Grade III Bunch and Dasteh, and PDO and GI-Certified Specialty Grades.
By end-use sector: Culinary and Gourmet Foodservice, Pharmaceuticals and Dietary Supplements, Cosmetics and Personal Care, Textile Dyeing, and Fine Perfumery and Liqueurs.
By sourcing origin: Iranian Saffron, Kashmiri Saffron, Spanish Saffron, and Greek and Afghan Saffron.
By distribution channel: Specialty Retail and Gourmet Grocers, B2B Ingredient and Extract Direct Supply, Online Direct-to-Consumer Platforms, and Pharmacies and Herbal Dispensaries.
Why do Saffron Threads and Stigmas lead the physical form category?
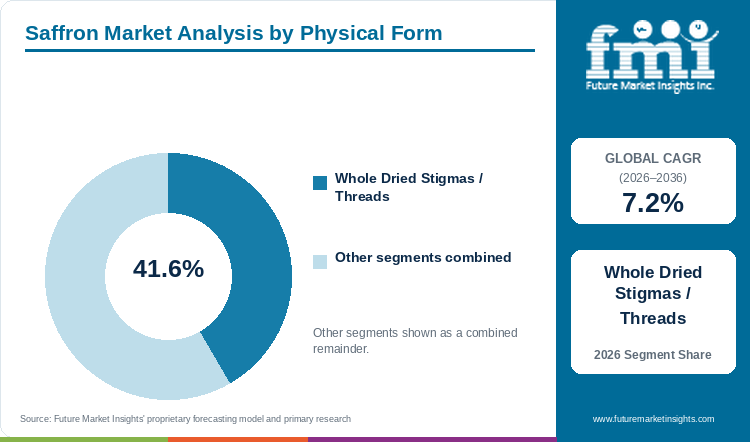
Saffron Threads and Stigmas hold an estimated 62.5% of physical form demand in 2026, anchored by visual authenticity inspection against pre-ground powder adulteration.
Table 5: Physical Form Share for the Saffron Market (percentage share), 2026
| Physical Form | Share (2026) |
|---|---|
| Saffron Threads and Stigmas | 62.5% |
| Other Segments Combined | 37.5%* |
| Total | 100.0% |
*Note: Remaining physical form categories account for the balance of 2026 global saffron demand.
Table 6: Physical Form Leadership and Market Growth for the Saffron Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Saffron Threads and Stigmas |
Whole crimson stigmas remain the preferred commercial format for culinary distributors, specialty grocers, and botanical extractors because intact trumpet-shaped filaments allow immediate visual and microscopic authentication prior to grinding or infusion. While beverage processors actively procure water-soluble saffron extract concentrates for rapid bottling-line dispersion, wholesale spice buyers rely on whole dried threads to prevent hidden dilution with turmeric powder or dyed corn silk. Nonetheless, brittle dried filaments fracture easily during long-distance transit if relative humidity drops too low, requiring cushioned glass jars or nitrogen-flushed tin canisters.
- Within the physical form segment, Saffron Threads and Stigmas are projected to account for a leading 62.5% share in 2026, driven by visual authenticity verification and slow golden crocin infusion.
- High-altitude expansion of authenticated whole stigma cultivation was reinforced in October 2026 when the Union Territory of Ladakh established new irrigated saffron plantation plots under Project Him Sarovar to supplement Indian whole-thread supply [9].
What sustains Grade I Sargol and Super Negin leadership in the quality grade segment?
Grade I Sargol and Super Negin represent an anticipated 54.0% of the quality grade category in 2026, supported by spectrophotometric crocin coloring strength exceeding 200.
Grade I Sargol and Super Negin specifications require hand-trimming the crimson three-pronged stigma cleanly above the pale yellow floral style so that spectrophotometric coloring strength at 440 nanometers exceeds 200 units under ISO 3632 testing. Nutraceutical refiners producing saffron derivatives and luxury food halls specify Super Negin cuts because removing unpigmented yellow style tissue reduces extraction solvent volumes and eliminates grassy off-notes in delicate broths and dairy desserts. Clinical demand for high-purity Grade I extracts was substantiated in May 2025 when a randomized controlled trial in The Journal of Nutrition confirmed that standardized saffron extract significantly improved mood and sleep scores in adults with subclinical depressive symptoms [7].
- In 2026, Grade I Sargol and Super Negin are anticipated to capture 54.0% of global quality grade demand, reflecting strict buyer specifications for crocin absorbance above 200.
- Over the forecast period, automated optical color-sorting lines across Khorasan and Kashmir will further widen Grade I supply share at the expense of untrimmed Grade III bunch lots.
How does Culinary and Gourmet Foodservice lead the end-use sector category?
Culinary and Gourmet Foodservice accounts for an estimated 48.0% of end-use sector demand in 2026, driven by premium rice, seafood, bakery, and festive gastronomy.
Upscale restaurants and hotel catering kitchens generate the largest share of global saffron consumption by infusing whole stigmas and ground powders into paella and biryani as well as festive bakery items. At the same time, clean-label dairy and beverage processors use standardized saffron infusions as global natural food colours to replace synthetic tartrazine, while prestige skincare laboratories formulate crocin and safranal into functional cosmetic ingredients for anti-photoaging serums. High per-gram ingredient cost remains the main hurdle in commercial foodservice, prompting chefs to use pre-measured liquid saffron infusions that prevent kitchen overdosing.
- By end-use sector, Culinary and Gourmet Foodservice is estimated to reach 48.0% of total category share in 2026 as hospitality kitchens and gourmet retailers expand authentic Mediterranean and Asian menu items.
- Cross-sector diversification into women's wellness is accelerating rapidly, as a June 2026 randomized clinical trial in Frontiers in Nutrition demonstrated that 28 mg daily saffron extract supplementation over 12 weeks reduced DASS-21 depression scores by 50.7% and improved self-esteem and sleep-related impairment [8].
Why does Iranian Saffron lead the sourcing origin category?
Iranian Saffron secures an expected 72.0% of sourcing origin volume in 2026, supported by extensive Khorasan corm acreage and specialized optical sorting facilities.
Calcareous loamy soils, cold winter vernalization, and dry sunny autumn harvest windows across Iran's Khorasan Razavi and South Khorasan provinces support more than 120,000 hectares of productive Crocus sativus corm beds. International spice packers and European re-exporters rely on Iranian origin harvests for bulk Super Negin and Sargol tonnage, whereas Kashmiri Mongra and Spanish La Mancha origins serve niche high-price organic spice and Protected Designation of Origin tiers. In November 2025, Khorasan Razavi farming cooperatives initiated a coordinated grading and direct-export organization push to stabilize farmgate prices and streamline ISO 3632 quality inspections for international buyers [23].
- Deep agricultural scale across Khorasan provinces places Iranian Saffron on course to hold an estimated 72.0% share of the sourcing origin category in 2026.
- Between 2026 and 2036, banking settlement friction and groundwater depletion in eastern Iran will encourage European and Asian buyers to dual-source supplemental volumes from Indian GI and Spanish PDO estates.
What gives Specialty Retail and Gourmet Grocers the leading position in distribution channel?
Specialty Retail and Gourmet Grocers command a forecast 44.5% of distribution channel share in 2026, anchored by origin-sealed glass vials and tamper-evident blister packs.
High-end supermarkets, ethnic grocery chains, and duty-free airport boutiques dominate commercial saffron distribution by merchandising 0.5-gram to 5-gram hermetic glass vials and tamper-evident blister cards with scannable origin QR codes. Household buyers and private chefs prefer inspected specialty retail shelves over unverified marketplace listings because established grocers audit batch certificates across herb and spice extracts and whole botanicals. Counterfeit spice substitution in informal bazaars remains a persistent channel risk, compelling specialty retailers to lock saffron vials inside security cases or point-of-sale dispensers.
- Specialty Retail and Gourmet Grocers are predicted to secure 44.5% of distribution channel demand in 2026, supported by consumer trust in origin-sealed glass vials and holiday gift packaging.
- Simultaneously, direct B2B extract supply to ophthalmic supplement brands is expanding, supported by an August 2026 systematic review in the Journal of Evidence-Based Integrative Medicine verifying clinical efficacy of 20 mg to 50 mg daily saffron and 5 mg to 15 mg daily crocin dosing across age-related macular degeneration and glaucoma trials [24].
What are the drivers, restraints, and opportunities in the saffron market?
In the saffron market, clinical validation of standardized mood and sleep extracts and natural yellow food dye replacement are projected to drive adoption whereas 400-hour manual harvest labor and spice fraud restrain supply and controlled-environment greenhouse cultivation creates year-round production avenues.
- Driver: Clinical validation of standardized crocin and safranal extracts for mood and retinal health as well as synthetic yellow dye replacement is accelerating B2B and retail procurement.
- Restraint: Intense manual dawn-harvesting labor requirements and low-sunshine corm shrinkage in emerging cultivation zones restrain raw stigma supply and elevate prices.
- Opportunity: Deploying controlled-environment vertical greenhouse corm forcing and water-soluble micro-encapsulated saffron concentrates opens year-round pharmaceutical and beverage supply.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clinical adoption of standardized Crocus sativus stigma bioactives across non-prescription mood, sleep, and age-related ocular health formulas is transforming saffron from a seasonal culinary garnish into a year-round nutraceutical ingredient. Formulators of herbal supplements pair 28-milligram to 30-milligram saffron extracts standardized to 3.5% lepticrosalides with macular carotenoids and adaptogens to address oxidative stress without sedative side effects. A November 2025 integrative review published in Frontiers in Nutrition documented that crocin and safranal exhibit multi-target antioxidant and neuroprotective activity across visual and neurological aging pathways [10]. This clinical evidence base gives supplement brands validated structure-function claims that support recurring subscription sales.
Risk Assessment of the Saffron Market: Operational and Formulation Friction
Strict agronomic dependence on high solar radiation during corm development and a narrow 15-day autumn picking window creates severe supply bottlenecks when growers attempt to expand cultivation into cloudy or industrial regions. Because Crocus sativus is a sterile triploid geophyte that reproduces solely through underground daughter corms, shrunken mother corms directly depress the following season's flower count and raise raw material costs for plant-based food colors processors. Plant physiologists reporting in Frontiers in Plant Science in January 2025 demonstrated that low light intensity inhibits starch synthesis enzymes in developing saffron corms, reducing daughter corm weight and floral bud initiation [11]. Combined with roughly 400 hours of manual labor needed to pick 150,000 flowers per dried kilogram, these agronomic constraints keep wholesale prices volatile.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Agritech growers and botanical extractors are overcoming field weather risks by adopting controlled-environment greenhouse forcing and soilless hydroponic tray cultivation that boost both corm multiplication and stigma phytochemical density. By regulating root-zone mineral nutrition and LED photoperiods, indoor growers harvest clean pesticide-free stigmas tailored to natural food flavors and pharmaceutical extraction. Agronomic trials published by Frontiers in Plant Science during June 2025 verified that optimized greenhouse practices significantly increase stigma dry yield and crocin concentration compared with open-field plots [12]. Expansion of indoor vertical cultivation near Western pharmaceutical and beverage plants eliminates cross-border tariff friction and cold-chain transit delays.
Saffron Market by Country (2026 to 2036)
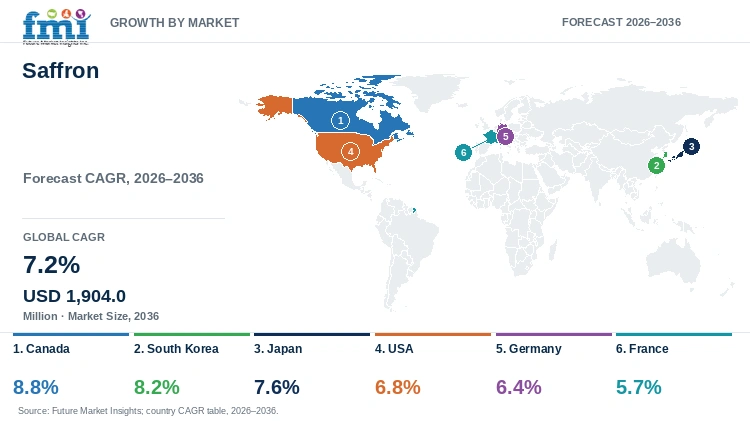
FMI country modeling indicates that Brazil leads evaluated national saffron market expansion at an 8.5% CAGR through 2036, while Italy advances at a 6.3% CAGR. Commercial growth across Latin American compounding pharmacies and North American supplement brands as well as European and Asian food processors reflects local regulatory approvals and origin-certified import standards.
Table 7: Country CAGR and Primary Growth Levers for the Saffron Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.5% | Compounding pharmacy satiety and mood extracts alongside gourmet Iberian and Mediterranean dining |
| United States | 7.6% | Clinical mood and sleep gummy launches, FD&C yellow dye replacement, and USDA SBIR indoor trials |
| France | 7.3% | Clinical mood-extract validation, Grasse perfumery safranal sourcing, and Quercy/Gatinais PDO terroir |
| United Kingdom | 7.2% | South Asian and Middle Eastern culinary manufacturing and FSA-screened supermarket spice vials |
| Spain | 7.0% | PDO Azafran de La Mancha export packaging and standardized Affron pharmaceutical extraction |
| Germany | 6.8% | Apotheke herbal mood preparations and organic clean-label bakery and dairy coloring foodstuffs |
| Japan | 6.5% | Foods with Function Claims (FFC) sleep and ocular supplements and Kampo botanical formulations |
| Italy | 6.3% | High-yield annual PDO Zafferano cultivation, soilless greenhouse systems, and Milanese gastronomy |
Source: Future Market Insights analysis
Brazil Saffron Market Outlook (2026 to 2036)
Demand for saffron in Brazil is projected to expand at a leading 8.5% CAGR between 2026 and 2036 as compounding pharmacies, dermocosmetic brands, and upscale Iberian and Mediterranean restaurants scale across Sao Paulo and Rio de Janeiro. What sets Brazil apart from traditional spice-consuming nations is the rapid uptake of standardized Crocus sativus satiety and mood extracts dispensed through magistral compounding pharmacies in addition to gourmet retail thread vials. Trade analysts at the USDA Foreign Agricultural Service reported in October 2026 that severe El Nino weather variability across Brazilian agriculture is elevating domestic specialty crop input costs and reinforcing reliance on high-value imported botanicals [13]. High Mercosur import tariffs on packaged retail spices encourage Brazilian distributors to import bulk Grade I threads and hydro-ethanolic extracts for local encapsulation and jarring.
Key takeaway: In Brazil, compounding pharmacy nutraceutical demand and gourmet hospitality expansion are projected to drive a leading 8.5% CAGR through 2036.
United States Saffron Market Outlook (2026 to 2036)
In the United States, saffron market growth is forecast to reach a 7.6% CAGR through 2036, driven by direct-to-consumer mood and sleep gummy brands and clean-label yellow beverage colorant reformulation. Compared with European markets anchored by traditional culinary threads, American growth is heavily weighted toward standardized botanical extracts and domestic controlled-environment cultivation trials. Project records from the USDA National Agricultural Library document federal Small Business Innovation Research (SBIR) funding for domestic saffron production utilizing novel plant cell culture and controlled-environment techniques to reduce import dependence [14]. Trade compliance restrictions on Iranian-origin goods steer U.S. importers toward Spanish PDO La Mancha, Kashmiri GI, and domestically cultivated stigma lots.
Key takeaway: In the United States, clinical mood-and-sleep supplement launches and USDA-backed domestic cultivation trials are forecast to sustain a 7.6% CAGR.
France Saffron Market Outlook (2026 to 2036)
Mediterranean seafood gastronomy, Grasse fine perfumery extraction, and artisanal domestic corm estates in Quercy and Gatinais shape demand across France. Consequently, French saffron adoption is anticipated to climb at a 7.3% CAGR over 2026 to 2036, outpacing continental Western European averages as Lyon nutraceutical laboratories and Parisian patisseries procure high-safranal threads and clinical extracts. Market assessments in the April 2026 USDA Foreign Agricultural Service study on France confirmed strong processor demand for origin-certified clean-label botanical ingredients across gourmet food and supplement lines [15]. High rural harvesting wages keep domestic French farm output small, sustaining reliance on Spanish and Persian Grade I imports.
Key takeaway: In France, clinical mood-extract validation and Grasse fragrance compounding are anticipated to support a 7.3% CAGR.
United Kingdom Saffron Market Outlook (2026 to 2036)
British saffron consumption is projected to progress at a 7.2% CAGR over the 2026 to 2036 forecast window, anchored by South Asian culinary retail corridors and premium supermarket private-label vials. What distinguishes the United Kingdom from continental Europe is the high volume of Kashmiri Mongra and Super Negin threads used in commercial ready-meal curries, festive bakery lines, and specialty foodservice. Official UK Department for Environment, Food and Rural Affairs statistics released in June 2026 showed that the UK food chain generated GBP 147.8 billion in gross value added with retail productivity rising 1.2% [16]. Strict UK Food Standards Agency border screening for illegal Sudan dyes and heavy metals favors certified Grade I exporters.
Key takeaway: In the United Kingdom, ethnic culinary manufacturing and supermarket specialty spice vials are projected to maintain a 7.2% CAGR through 2036.
Spain Saffron Market Outlook (2026 to 2036)
Spain's saffron market is estimated to expand at a 7.0% CAGR between 2026 and 2036, reinforced by Castile-La Mancha's Protected Designation of Origin (PDO) estates and major Mediterranean spice packaging and extraction hubs. Rather than competing on low bulk price, Spanish processors blend domestic PDO Azafran de La Mancha craftsmanship with advanced optical grading and standardized Affron nutraceutical extraction for global export. Agricultural attaché findings in the March 2026 USDA GAIN report on Spanish food processing show expanding gourmet retail and hospitality foodservice demand across the country [17]. Rural aging among Castile-La Mancha family farmers limits domestic field acreage, prompting Spanish houses to invest in mechanized flower stripping and greenhouse corm propagation.
Key takeaway: In Spain, PDO Azafran de La Mancha quality premiums and pharmaceutical extract manufacturing are estimated to drive a 7.0% CAGR.
Germany Saffron Market Outlook (2026 to 2036)
Apotheke pharmacy demand for standardized botanical mood drops and industrial bakery procurement of natural yellow coloring foodstuffs anchor saffron consumption in Germany. FMI country modeling indicates that German market growth is slated to track at a 6.8% CAGR through 2036 as organic supermarket chains and phytopharmaceutical manufacturers expand pesticide-free Crocus sativus product lines. Data published by the USDA Foreign Agricultural Service in March 2026 on German food manufacturing confirms that the country's fourth-largest industrial sector continues to reformulate packaged foods and snacks around certified natural ingredients [18]. Rigorous German retail laboratory testing for polycyclic aromatic hydrocarbons and synthetic dye adulteration requires suppliers to provide full ISO 3632-2 batch documentation.
Key takeaway: In Germany, Apotheke phytopharmaceutical formulations and organic food-coloring reformulation are slated to support a 6.8% CAGR.
Japan Saffron Market Outlook (2026 to 2036)
Japanese saffron demand is predicted to rise at a 6.5% CAGR across 2026 to 2036, driven by functional sleep-and-ocular supplements registered under the Foods with Function Claims (FFC) framework and natural crocin beverage coloring. Compared with Western markets that consume whole threads primarily in savory rice dishes, Japanese buyers incorporate high-purity crocin extracts into functional health drinks and Kampo herbal preparations. Tokyo agricultural attaché reporting in October 2026 on FOODEX Japan documented strong Japanese importer appetite for traceable specialty food ingredients and botanicals [19]. Japan's strict 0.01-ppm default agricultural chemical residue limit under the Positive List system disqualifies uncertified field lots and rewards indoor-cultivated or organic-certified saffron.
Key takeaway: In Japan, Foods with Function Claims sleep and eye-health supplements as well as clean-label beverage coloring are predicted to sustain a 6.5% CAGR.
Italy Saffron Market Outlook (2026 to 2036)
In Italy, the saffron market is expected to grow at a 6.3% CAGR between 2026 and 2036, anchored by Protected Designation of Origin Zafferano dell'Aquila and Sardegna artisanal production in addition to Milanese culinary and liqueur processing. In contrast to perennial multi-year cropping in arid Iran, Italian estates grow saffron as an intensive annual rotational crop that achieves average dry stigma yields up to 8.18 kilograms per hectare. Agronomic trials published in Plants (MDPI) in January 2025 demonstrated that soilless greenhouse cultivation systems in Italy help growers overcome annual soil-preparation costs and daily flower-harvesting labor bottlenecks while preserving distinctive genetic and aroma profiles [20]. High land and manual picking costs keep domestic Italian threads positioned in ultra-premium gourmet tiers.
Key takeaway: In Italy, high-yield annual PDO production and soilless greenhouse innovation are expected to support a 6.3% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the saffron market?
Gohar Saffron, Tarvand Saffron Co., Mehr Saffron, Baby Brand Saffron (USMS Saffron Co. Inc.), Rowhani Saffron Co., Saffron Business Co., Flora Saffron, Novin Saffron Co., HEA & Co Spanish Saffron, and Pharmactive Biotech Products S.L.U. are the notable companies in the saffron market.
Competitive positioning in the global saffron industry connects primary Khorasan sorting and dehydration houses, heritage Kashmiri and Spanish GI/PDO exporters, and clinical botanical extract manufacturers. Gohar Saffron and Tarvand Saffron as well as Novin Saffron and Rowhani Saffron manage large-scale Persian stigma collection and ISO 3632 Grade I Super Negin packaging across Mashhad and Ghaenat. Mehr Saffron and Baby Brand Saffron in addition to Saffron Business and Flora Saffron supply authenticated retail vials and Kashmiri culinary threads, while HEA & Co Spanish Saffron and Pharmactive Biotech lead European PDO packaging and clinical Affron extract production.
- Khorasan Optical-Grading and Export Leaders: Gohar Saffron and Tarvand Saffron as well as Novin Saffron and Rowhani Saffron operate ISO 3632 laboratory-equipped dehydration, sorting, and bulk export facilities.
- Kashmiri GI and International Retail Specialists: Baby Brand Saffron and Mehr Saffron along with Saffron Business and Flora Saffron distribute FSSAI-certified Kashmiri Mongra and authenticated gourmet retail jars and blister packs.
- European PDO and Clinical Extract Innovators: HEA & Co Spanish Saffron and Pharmactive Biotech Products supply PDO Azafran de La Mancha filaments and HPLC-standardized lepticrosalide extracts for supplements and functional foods.
Competitive Benchmarking: Saffron Market
Table 8: Competitive Benchmarking for the Saffron Market (qualitative capability ratings), 2026
| Company | ISO 3632 Grade I & GI Portfolio | Standardized Crocin/Safranal Extracts | HPLC Anti-Fraud Traceability | Geographic Reach |
|---|---|---|---|---|
| Gohar Saffron | High | High | High | Global export leader from Khorasan Razavi supplying Super Negin threads and sprays |
| Tarvand Saffron Co. | High | High | High | GI-42 Ghaenat certified organic and Grade I saffron exporter across 40+ countries |
| Mehr Saffron | High | Medium | High | International supplier of Grade I Persian and gourmet retail saffron packaging |
| Baby Brand Saffron | High | Medium | High | India and global diaspora leader in FSSAI-certified ISO Grade I Kashmiri Mongra |
| Rowhani Saffron Co. | High | Medium | High | Mashhad producer and global exporter of Super Negin, Sargol, and Pushal grades |
| Saffron Business Co. | Medium | Medium | Medium | Wholesale and private-label supplier of bulk culinary threads and ground powders |
| Flora Saffron | High | Medium | High | Specialty gourmet retail and foodservice distributor of laboratory-tested threads |
| Novin Saffron Co. | High | High | High | Integrated Khorasan processor operating optical sorting and liquid extract plants |
| HEA & Co Spanish Saffron | High | Medium | High | European exporter of PDO Azafran de La Mancha jars, blister cards, and powders |
| Pharmactive Biotech | Medium | High | High | Madrid manufacturer of patented Affron standardized 3.5% lepticrosalide extracts |
Evaluation basis: ISO 3632 Grade I and GI Portfolio evaluates documented Super Negin or PDO La Mancha certification, while Standardized Crocin and Safranal Extracts rates water-soluble and hydro-ethanolic extract production. HPLC Anti-Fraud Traceability measures laboratory purity testing against artificial colorants.
Key Developments in the Saffron Market
- The Agriculture Department of the Union Territory of Ladakh achieved first bloom within 30 days on November 2, 2026 in its high-altitude pilot saffron cultivation project across restored Igoo-Phey canal lands, opening new domestic Indian commercial supply avenues [3].
- French and Italian clinical nutrition researchers published randomized double-blind trial results in The American Journal of Clinical Nutrition in December 2025 demonstrating that six-week saffron extract supplementation improved autoperceived SF-12 mental health scores and modulated N-acetyl-phenylalanine in adults [22].
- India's Ministry of Environment, Forest and Climate Change highlighted national conservation and value-chain cultivation programs for Himalayan medicinal and aromatic plants including Kashmiri and Himalayan saffron clusters on March 3, 2026 [21].
Key Players in the Saffron Market
Khorasan Optical-Grading and Export Leaders
- Gohar Saffron
- Tarvand Saffron Co.
- Novin Saffron Co.
- Rowhani Saffron Co.
Kashmiri GI and International Retail Specialists
- Baby Brand Saffron (USMS Saffron Co. Inc.)
- Mehr Saffron
- Saffron Business Co.
- Flora Saffron
European PDO and Clinical Extract Innovators
- HEA & Co Spanish Saffron
- Pharmactive Biotech Products S.L.U.
Saffron Market - Report Scope
Table 9: Report Scope for the Saffron Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Physical Form; Quality Grade; End-Use Sector; Sourcing Origin; Distribution Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial wholesale and processor revenue from dried Crocus sativus L. stigmas and threads (Super Negin, Sargol, Pushal, Bunch, Kashmiri Mongra, and PDO La Mancha), ground saffron powders, and standardized liquid and hydro-ethanolic crocin and safranal extracts. Category Scope Note: Excludes finished multi-ingredient consumer dietary supplement retail bottle prices and synthetic saffron substitutes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, United States, France, United Kingdom, Spain, Germany, Japan, Italy, and additional countries in the full report |
| Key Companies Covered | Gohar Saffron, Tarvand Saffron Co., Mehr Saffron, Baby Brand Saffron (USMS Saffron Co. Inc.), Rowhani Saffron Co., Saffron Business Co., Flora Saffron, Novin Saffron Co., HEA & Co Spanish Saffron, Pharmactive Biotech Products S.L.U. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Saffron Market - Research Methodology
Table 10: Research Methodology for the Saffron Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with Khorasan, Kashmir, and Castile-La Mancha cooperative directors, ISO 3632 analytical chemists, botanical extract manufacturers, and gourmet retail spice buyers to validate FOB pricing and crocin absorbance thresholds. |
| Secondary Research | Analysis of FAO saffron value-chain reports, USDA FAS country ingredient studies, UT Ladakh and PIB India cultivation logs, qNMR and response-surface extraction studies in MDPI and Frontiers, and PubMed clinical trials. |
| Market Sizing and Forecasting | Top-down culinary spice, natural food colorant, and botanical extract budgets reconciled against bottom-up dried stigma harvest tonnage (402 to 435 MT in 2026) and FOB grade pricing from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight clinical mood-and-sleep supplement registrations, synthetic yellow food dye phase-outs, diaspora and Mediterranean culinary consumption, and customs authenticity screening across eight national markets. |
| Operational Benchmark Traceability | Harvest tonnage, crocin absorbance, and disodium crocetinate conversion benchmarks in Tables 2, 3, and 4 trace to FAO Iran records, MDPI qNMR assays, and Frontiers in Sustainable Food Systems hydrolysis models. |
| Data Triangulation and Validation | Revenue estimates isolate authentic Crocus sativus L. stigmas, powders, and primary standardized extracts while strictly excluding adulterated safflower/turmeric blends and finished retail supplement bottle markups. |
Saffron Market by Segments
Saffron Market segmented by Physical Form:
- Saffron Threads and Stigmas
- Saffron Powder
- Liquid Saffron Extracts and Concentrates
- Micro-Encapsulated Saffron Granules
Saffron Market segmented by Quality Grade:
- Grade I Sargol and Super Negin
- Grade II Pushal
- Grade III Bunch and Dasteh
- PDO and GI-Certified Specialty Grades
Saffron Market segmented by End-Use Sector:
- Culinary and Gourmet Foodservice
- Pharmaceuticals and Dietary Supplements
- Cosmetics and Personal Care
- Textile Dyeing
- Fine Perfumery and Liqueurs
Saffron Market segmented by Sourcing Origin:
- Iranian Saffron
- Kashmiri Saffron
- Spanish Saffron
- Greek and Afghan Saffron
Saffron Market segmented by Distribution Channel:
- Specialty Retail and Gourmet Grocers
- B2B Ingredient and Extract Direct Supply
- Online Direct-to-Consumer Platforms
- Pharmacies and Herbal Dispensaries
Saffron Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, November 25). FAO and Iran, New Step to Innovation and Quality Integrity in Saffron Value Chain. FAO Representation in the Islamic Republic of Iran.
- [2] Givaudan SA. (2025, November 11). Safranal: Spicy Saffron-Like Fragrance Ingredient and Aroma Molecule Specifications. Givaudan Fragrance and Beauty Ingredients.
- [3] Administration of Union Territory of Ladakh. (2026, November 2). Pilot Saffron Cultivation in Ladakh Receives First Bloom in Just 30 Days. Agriculture Department UT Ladakh Official Portal.
- [4] Acharya, B. S., Lamos, S. M., Hayes, B. L., Keshavarz Afshar, R., Skinner, M., & Ghalehgolabbehbahani, A. (2026, July 29). Saffron (Crocus sativus L.) Production in the Southern United States: Effects of Planting Date, Production System, and Drying Method. Applied Sciences (MDPI), 16(15), 7528.
- [5] Soleimani, M., Mirzajani, F., Valli, E., Shabani Azin, F., Tabesh, A., & Rezadoost, H. (2026, October 29). Optimized, sustainable and scalable strategy for producing disodium crocetinate from Crocus sativus L. stigmas. Frontiers in Sustainable Food Systems, 10, 1958025.
- [6] Food and Agriculture Organization of the United Nations. (2025, November 10). World soil day 2025, Cultivation of saffron on sloping lands. FAO Global Soil Partnership.
- [7] Lopresti, A. L., Smith, S. J., Marx, W., Diez-Municio, M., & Moran-Valero, M. I. (2025, May 23). An Examination into the Effects of a Saffron Extract (Affron) on Mood and General Wellbeing in Adults Experiencing Low Mood: A Randomized, Double-Blind, Placebo-Controlled Trial. The Journal of Nutrition, 155(7), 2300-2311 (PubMed PMID 40414301).
- [8] Lopresti, A. L., & Smith, S. J. (2026, June 16). The effects of a saffron extract (Affron) on mood, sleep, self-esteem, and exploratory measures of physical appearance in women aged 50 to 70 years experiencing low mood and poor sleep: a randomised, double-blind, placebo-controlled trial. Frontiers in Nutrition, 13, 1838513.
- [9] Administration of Union Territory of Ladakh. (2026, October 5). LG V K Saxena Launches Saffron Plantation Aimed at Promoting Crop Diversification and Creating New Avenues for Enhancing Farmers' Incomes. UT Ladakh Official Portal.
- [10] Ziani, A., Bekkouch, O., Ouahhoud, S., Baddaoui, S., Ben'Mbarek, S., Bekkouch, A., Khoulati, A., Jaouadi, B., Choi, J., & Saalaoui, E. (2025, November 28). Phytochemistry, Biological Activities, Molecular Mechanisms, and Toxicity of Saffron (Crocus sativus L.): A Comprehensive Overview. Antioxidants (MDPI), 14(12), 1433.
- [11] Yang, W., Li, X., Chang, F., Qiu, X., Huang, X., Feng, Z., Yan, J., Wu, Q., Wen, F., Pei, J., & Zhou, T. (2025, January 30). Low light reduces saffron corm yield by inhibiting starch synthesis. Frontiers in Plant Science, 16, 1544054.
- [12] Qaryouti, M., Al-Soqeer, A., Abdelaziz, M. E., Gruda, N. S., AlSahly, S., Alrasheed, W., Althobiti, S., Babiker, O., Sharafeldin, M., & Voogt, W. (2025, June 24). Cutting-edge greenhouse practices for better stigma yield and corm quality of saffron (Crocus sativus L.). Frontiers in Plant Science, 16, 1612791 (PubMed PMID 40630731).
- [13] USDA Foreign Agricultural Service. (2026, October 13). Brazil: Bracing for Impact - How the 2026 El Nino Affects Brazil's Agriculture. U.S. Department of Agriculture GAIN Report BR2026-0029.
- [14] Skoog, E., & Krokos Bio Inc. (2025, May 18). SBIR Phase I: A Method for Domestic Production of Saffron, Utilizing Novel Plant Cell Culture Techniques for Cell Adhesion and Immobilization. U.S. Department of Agriculture National Agricultural Library Project 2528085.
- [15] USDA Foreign Agricultural Service. (2026, April 3). France: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report FR2026-0005.
- [16] Department for Environment, Food and Rural Affairs. (2026, June 18). Total Factor Productivity of the United Kingdom Food Chain 2024. GOV.UK Accredited Official Statistics.
- [17] USDA Foreign Agricultural Service. (2026, March 31). Spain: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report SP2026-0003.
- [18] USDA Foreign Agricultural Service. (2026, March 30). Germany: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report GM2026-0007.
- [19] USDA Foreign Agricultural Service. (2026, October 20). Japan: FOODEX Japan 2026 Report. U.S. Department of Agriculture GAIN Report JA2026-0051.
- [20] Mariani, A., Marconi, G., Ferradini, N., Bocchini, M., Lorenzetti, S., Chiorri, M., Russi, L., & Albertini, E. (2025, January 1). A Proposed Saffron Soilless Cultivation System for a Quality Spice as Certified by Genetic Traceability. Plants (MDPI), 14(1), 51 (PubMed PMID 39795311).
- [21] Ministry of Environment, Forest and Climate Change, Government of India. (2026, March 3). Medicinal and Aromatic Plants: Conserving Health, Heritage and Livelihoods. Press Information Bureau (PIB Delhi Note ID 157632).
- [22] Amadieu, C., Leyrolle, Q., Farneti, M., Anesi, A., Bruchet, E., Montet, J., Dexpert, S., Gaudout, D., Mattivi, F., Pourtau, L., Castanon, N., & Capuron, L. (2025, December 1). Effect of saffron extract supplementation on mood in healthy adults with subclinical symptoms of depression: a randomized, double-blind placebo-controlled study. The American Journal of Clinical Nutrition, 122(6), 1625-1635 (PubMed PMID 41047129).
- [23] Valouzi, H., Dizadji, A., Golnaraghi, A., Salami, S. A., Fontdevila Pareta, N., Onder, S., Selmi, I., Rollin, J., Berhal, C., Tamisier, L., Maclot, F., Wang, L., Zhang, R., Bahlolzada, H., Lefeuvre, P., & Massart, S. (2025, August 4). A Virome Scanning of Saffron (Crocus sativus L.) at the National Scale in Iran Using High-Throughput Sequencing Technologies. Viruses, 17(8), 1079 (PubMed PMID 40872793).
- [24] Ferrara, S., & Schloss, J. (2026, August 13). Does Crocus sativus (Saffron) Have an Influence or Effect on Ocular Health: A Systematic Literature Review. Journal of Evidence-Based Integrative Medicine, 31, 2515690X261478846 (PubMed PMID 42594967).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the saffron market in 2026 and what is forecast for 2036?
- Which clinical mood-extract and clean-label food coloring trends support demand for saffron?
- Why do Saffron Threads and Stigmas lead the physical form category?
- Why do Grade I Sargol and Super Negin filaments lead the quality grade category globally?
- How do growth rates differ across Brazil and the United States compared with France and the United Kingdom?
- Which leading exporters, GI packers, and botanical extractors supply the saffron market today?
- What manual harvesting labor bottlenecks and dye adulteration risks restrain the saffron market?
- What should culinary, beverage, and supplement buyers evaluate when qualifying saffron suppliers?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Physical Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Physical Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Physical Form, 2026 to 2036
- Saffron Threads and Stigmas
- Saffron Powder
- Liquid Saffron Extracts and Concentrates
- Micro-Encapsulated Saffron Granules
- Y-o-Y Growth Trend Analysis By Physical Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Form, 2026 to 2036
- Global Market Analysis and Forecast, By Quality Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Quality Grade, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Quality Grade, 2026 to 2036
- Grade I Sargol and Super Negin
- Grade II Pushal
- Grade III Bunch and Dasteh
- PDO and GI-Certified Specialty Grades
- Y-o-Y Growth Trend Analysis By Quality Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Quality Grade, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Culinary and Gourmet Foodservice
- Pharmaceuticals and Dietary Supplements
- Cosmetics and Personal Care
- Textile Dyeing
- Fine Perfumery and Liqueurs
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Sourcing Origin, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sourcing Origin, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sourcing Origin, 2026 to 2036
- Iranian Saffron
- Kashmiri Saffron
- Spanish Saffron
- Greek and Afghan Saffron
- Y-o-Y Growth Trend Analysis By Sourcing Origin, 2021 to 2025
- Absolute $ Opportunity Analysis By Sourcing Origin, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Retail and Gourmet Grocers
- B2B Ingredient and Extract Direct Supply
- Online Direct-to-Consumer Platforms
- Pharmacies and Herbal Dispensaries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Physical Form
- By Quality Grade
- By End-Use Sector
- By Sourcing Origin
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Gohar Saffron
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Tarvand Saffron Co.
- Mehr Saffron
- Baby Brand Saffron
- Rowhani Saffron Co.
- Saffron Business Co.
- Flora Saffron
- Novin Saffron Co.
- HEA & Co Spanish Saffron
- Pharmactive Biotech
- Baby Brand Saffron (USMS Saffron Co. Inc.)
- Pharmactive Biotech Products S.L.U.
- Gohar Saffron
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Million) Forecast by Physical Form, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Million) Forecast by Quality Grade, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Million) Forecast by Sourcing Origin, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Million) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Physical Form
- Figure 6: Global Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Quality Grade
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sourcing Origin
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Physical Form
- Figure 32: North America Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Quality Grade
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Sector
- Figure 38: North America Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Sourcing Origin
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Physical Form
- Figure 48: Latin America Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Quality Grade
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 54: Latin America Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Sourcing Origin
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Physical Form
- Figure 64: Western Europe Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Quality Grade
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 70: Western Europe Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Sourcing Origin
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Physical Form
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Quality Grade
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Sourcing Origin
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Physical Form
- Figure 96: East Asia Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Quality Grade
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 102: East Asia Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Sourcing Origin
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Physical Form
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Quality Grade
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Sourcing Origin
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Physical Form
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Quality Grade, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Quality Grade, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Quality Grade
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Sourcing Origin, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Sourcing Origin, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Sourcing Origin
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the saffron market in 2026, and what is forecast for 2036?
FMI estimates that international Crocus sativus valuation stood at USD 620.0 million in 2025 and reached USD 665.0 million in 2026. Overall industry valuation is on course to hit USD 1,332.8 million by 2036 as food processors and supplement brands expand authenticated Grade I thread and extract procurement.
What is the CAGR for the saffron market from 2026 to 2036?
The saffron sector is projected to expand at a 7.2% CAGR over the 2026 to 2036 forecast window, adding USD 667.8 million in incremental revenue across culinary and nutraceutical channels.
Which physical form segment leads the saffron market?
Saffron Threads and Stigmas are projected to hold 62.5% of physical form demand in 2026 since intact crimson filaments enable visual inspection against pre-ground powder adulteration.
Which quality grade segment leads the saffron market?
Grade I Sargol and Super Negin are anticipated to represent 54.0% of the quality grade category in 2026 given that all-red trimmed stigmas deliver spectrophotometric crocin strength above 200.
Which country has a notable growth outlook during the assessment period?
Brazil leads evaluated country expansion projections at an 8.5% CAGR through 2036, ahead of the United States at 7.6% and France at 7.3%.
Who are the key players in the market?
Gohar Saffron and Tarvand Saffron lead commercial supply with Baby Brand Saffron. Rowhani Saffron and Mehr Saffron also hold major positions in addition to Novin Saffron and Saffron Business.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
