
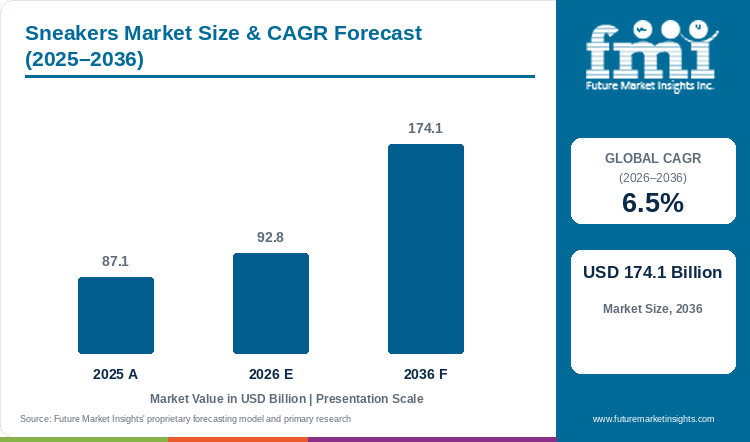
- Market Size (2026)
- USD 92.8 Bn
- Forecast (2036)
- USD 174.1 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is the Sneakers Market in 2026?
The Sneakers Market is forecast to reach USD 174.1 billion by 2036, from USD 92.8 billion in 2026 and USD 87.1 billion in 2025, at a 6.5% CAGR from 2026 to 2036. Wider online purchasing and rising recreational activity in some mature markets support the outlook by expanding access to new releases and demand for training footwear. Eurostat reports that 77% of EU internet users bought online in 2024, compared with 59% in 2014; this is channel evidence for Europe, rather than a global sneaker sales measure. Sport England records 64.6% of adults in England meeting activity guidelines in November 2024 to November 2025, up 859,000 people over the preceding year.
FMI's 2026 assessment places Adult Sneakers at 72.6% by Product Type, Lifestyle at 61.9% by Application and Multi-Brand Stores at 38.7% by Sales Channel. Growth faces inventory and import-cost pressure: the European Commission's prohibition on destroying unsold apparel and footwear applies to large companies from 19 July 2026. ASICS' reported SportStyle growth above 40% across its regions in 2025 illustrates one brand's lifestyle momentum; it does not establish the growth rate of the global application.
Key Market Trends & Insights
- Nike's 23 October 2025 innovation announcement united product-development teams across Nike, Jordan Brand and Converse. It introduced Nike Mind and Project Amplify alongside apparel platforms. [11] This is an example of one supplier investing across performance categories; development activity does not itself establish a global lifestyle sales trend. The casual shoes market overlaps with everyday sneaker purchasing.
- Channel strategies differ sharply between brands. On Holding's DTC channel grew faster than wholesale in Q2 2025, while Nike's fiscal 2025 digital revenue declined. [7][15] Retailers need to assess replenishment by brand and range rather than assume that online and owned stores gain at a uniform rate.
- Nike's June 2025 tariff-cost assessment was a gross figure before mitigation, while PUMA's July 2025 guidance referred to an expected impact after mitigation. [4][5] The distinction matters when comparing supplier cost exposure: a gross scenario and an anticipated residual cost cannot be treated as equivalent changes in future selling prices.
Regional Highlights
- East Asian retail demand includes purchases by visitors as well as residents. ASICS' separate inbound-sales disclosure for Japan identifies this distinction within its business. [8] Suppliers should distinguish visitor-facing store assortments from products replenished for resident customers; one company's results do not measure East Asia's total sneaker growth.
- EU-facing footwear brands in Western Europe face limits on destroying unsold stock. The European Commission's measures apply to covered large companies from 19 July 2026 and include disclosure obligations for discarded unsold goods. [3] FMI finds that the obligation makes responsibility for residual stock and returns a commercial term in distribution agreements.
Sneakers Market Size and Forecast
Table 1: Sneakers Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 87.1 billion |
| Estimated market size in 2026 | USD 92.8 billion |
| Projected market size by 2036 | USD 174.1 billion |
| CAGR from 2026 to 2036 | 6.5% |
Source: FMI Analysis
Analyst Perspective
“Lifestyle releases and performance footwear follow different development and retail cycles. Brands need to plan inventories and manufacturing commitments around those differences while accounting for changes in import costs, which can affect margins before a new range reaches the shelf.”
- Rahul Pandita, Principal Consultant, FMI
How is the Sneakers Market segmented?
- By Product Type: Adult Sneakers; Children's Sneakers
- By Application: Lifestyle; Sports; Competition
- By Consumer Orientation: Men; Women
- By Sales Channel: Online; Multi-Brand Stores; Independent Stores; Other Channels
- By Region: North America (USA, Canada); Latin America (Brazil, Mexico, Argentina, Chile); Western Europe (Germany, France, UK, Italy, Spain, Benelux, Nordics); Eastern Europe (Poland, Czech Republic, Romania, Hungary); East Asia (China, Japan, South Korea); South Asia and Pacific (India, ASEAN, Australia and New Zealand); Middle East and Africa (GCC Countries, South Africa, Türkiye, Israel)
The designer sneaker market overlaps with the premium Lifestyle segment, although this report also covers Sports, Competition and children's products. Product age, application, consumer orientation and sales channel remain separate classifications.
Why do Adult Sneakers lead by Product Type?
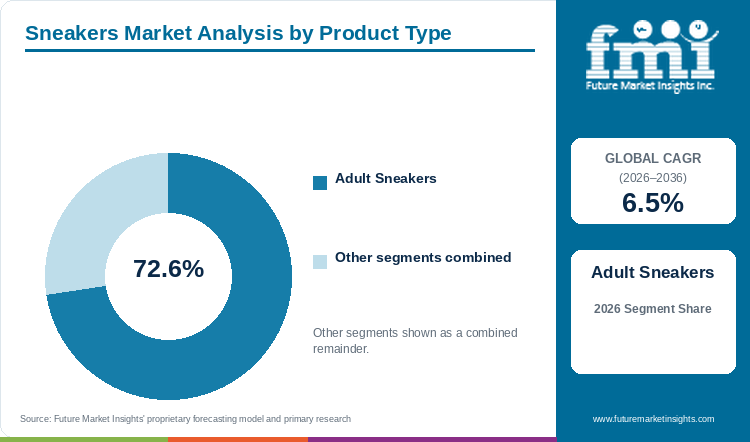
Adult Sneakers account for 72.6% of the Sneakers Market by Product Type in 2026, as per FMI's assessment.
Adult demand covers everyday Lifestyle purchases as well as Sports and Competition ranges, giving this category several sources of orders. ASICS reports separate Performance Running, SportStyle and Onitsuka Tiger businesses. Its Performance Running sales rose 11.2% in 2025, while SportStyle grew above 40% across its reported regions. [8] The different category results illustrate why retailers plan adult running and lifestyle assortments separately. They describe the company's portfolio rather than a global age-share survey.
Children's Sneakers account for the remaining 27.4% in the product comparison.
The adult assortment spans established running products and changing lifestyle silhouettes, with different launch and replenishment calendars. ASICS' category reporting shows both routes contributing to its business. [8] FMI finds that adult suppliers need to manage those product cycles separately: a running range with repeat specialist demand and a lifestyle release with strong initial orders do not create the same inventory commitment. This breadth supports the adult segment's leading position without assuming that children's products have lower margins or weaker loyalty.
Table 2: Product Type, 2026 Share of Demand
| Leading Share | 2026 market share |
|---|---|
| Adult Sneakers | 72.6% |
| All Other Segments Combined Share | 27.4% |
Source: FMI Analysis
Why does Lifestyle lead by Application?
Lifestyle accounts for 61.9% of the Sneakers Market by Application in 2026, as per FMI's assessment.
Heritage silhouettes and fashion-led releases compete through assortment, colourways and distribution as well as product specifications. ASICS' 2025 SportStyle and Onitsuka Tiger results illustrate those routes within one portfolio: SportStyle grew above 40% across its reported regions, while Onitsuka Tiger expanded its European store presence. [8] FMI sees the commercial effect in the inventory decisions behind that expansion. A lifestyle retailer commits to a particular silhouette and size range, while a specialist sports buyer follows a different product and replenishment calendar.
Sports and Competition together account for the remaining 38.1% in this application comparison.
Their outlook includes training participation, specialist launches and retailer replenishment rather than fashion demand alone. Nike's October 2025 innovation announcement provides an example of continuing performance development. [11] FMI distinguishes the application of a sneaker from the technology it contains: cushioning or construction may be shared across ranges sold for different uses. The related tennis shoes market covers a narrower sporting use than this global sneaker assessment.
Table 3: Application, 2026 Share of Demand
| Leading Share | 2026 market share |
|---|---|
| Lifestyle | 61.9% |
| All Other Segments Combined Share | 38.1% |
Source: FMI Analysis
Why do Multi-Brand Stores lead by Sales Channel?
Multi-Brand Stores account for 38.7% of the Sneakers Market by Sales Channel in 2026, as per FMI's assessment.
Major brands still distribute a substantial part of their ranges through retail partners. Adidas reports that wholesale represented 60% of its 2025 net sales. [17] PUMA's footwear disclosure separates EUR 2,838.3 million of wholesale sales from EUR 1,275.5 million of direct-to-consumer sales in the same year. [18] Together, these records show the scale of third-party distribution across different suppliers. Their reported product and geographic scopes remain distinct from FMI's global sneaker assessment.
Retailer channel data explain why wholesale revenue should not automatically be classified as online demand. JD Sports reported that stores generated 78% of group sales in the year to 31 January 2026, while online represented approximately 21%; its product mix was 60% footwear. [19] Physical multi-brand chains therefore remain a material route for sneaker ranges, even as the same retailers expand digital operations. The commercial issue for suppliers is allocation across competing brands and sizes within a retailer's available stock budget. Online orders through a chain's website belong to Online in this report; Multi-Brand Stores covers its physical stores. Brand-owned physical stores and mono-brand outlets sit within Other Channels, while physical independent specialists remain a separate category. These boundaries prevent a single retail transaction from being counted twice.
Table 4: Sneakers Market Sales Channel Share, 2026
| Leading Share | 2026 market share |
|---|---|
| Multi-Brand Stores | 38.7% |
| All Other Segments Combined Share | 61.3% |
Source: FMI Analysis
What are the key drivers restraints and opportunities?
The outlook combines demand for lifestyle ranges and sporting footwear with the cost of supplying them. Company results show different outcomes across brands, so the mechanisms below should be read within their stated scope.
Driver
Lifestyle range expansion supports demand where retailers and brand stores attract repeat purchases across different silhouettes. ASICS' SportStyle and Onitsuka Tiger results are evidence of this mechanism within its own portfolio, rather than proof that lifestyle footwear universally earns higher margins than performance ranges. [8] Inventory discipline matters because additional releases expand the number of sizes and colourways a retailer must fund. The casual shoes market overlaps with this application, although its coverage is broader than sneakers alone.
Restraint
Import-cost exposure constrains margins when orders have been priced before a tariff change. Nike's June 2025 management statement described a gross cost scenario and a plan to reduce China's share of footwear imported into the United States by the end of fiscal 2026. [4] PUMA's July 2025 preliminary guidance separately anticipated tariff pressure after mitigation. [5] FMI reads these dated disclosures as evidence of sourcing and pricing risk at those companies, with the actual effect depending on the origin of later shipments, tariff treatment and the terms of retail orders.
Opportunity
An opportunity exists in combining premium ranges with owned stores and online distribution, provided the additional retail and fulfilment costs leave an adequate margin. On Holding's DTC channel reached 41.1% of Q2 2025 net sales and grew faster than its wholesale channel in that quarter. [7] This company example supports an opportunity for brands with sufficient demand and retail capacity; it does not establish the most profitable channel for every supplier. The designer sneaker market is relevant to the premium end of this positioning.
How do trade and quality rules affect sneakers purchasing?
Footwear import classification depends on the product presented to customs. In Headquarters Ruling H338307, dated 28 August 2025, US Customs and Border Protection reclassified two specified men's winter boots from Vietnam under sports-footwear subheading 6402.19.90. [1] This is a product-specific ruling, rather than a duty rate for all sneakers. Its purchasing implication is to establish the construction, origin and classification of each range before relying on a landed-cost quotation.
Nike's dated tariff scenario illustrates the cost side of those decisions. [4] Separately, EU rules affect both residual inventory and the information supplied with new footwear: the Commission's unsold-stock measures apply to covered large companies, [3] and EU footwear labels must identify the materials in the upper, lining and insole, and outer sole. The manufacturer supplies an accurate label; for imports, the organisation first placing the footwear on the EU market assumes that responsibility. [12] FMI finds that buyers therefore need material specifications and compliant label artwork alongside commercial terms, while agreeing how covered unsold stock will be handled.
What limits reliable sneakers supply and sourcing?
A supplier changing its production origin must maintain the approved product specification while revising its delivery and cost commitments. Nike's June 2025 statement described reallocating US-bound footwear production across countries; PUMA's July 2025 guidance described tariff mitigation alongside other pressures on its results. [4][5] These are company-specific examples of the coordination required between factories, importers and retail partners. FMI finds that sourcing changes create a delivery risk when qualification, production allocation and an agreed retail launch date do not move together.
Counterfeit enforcement remains relevant to authorised distribution. US Customs and Border Protection recorded footwear seizures with a manufacturer's suggested retail price of USD 127.6 million across 604,553 items in fiscal 2024. [2] These are enforcement observations, not a measure of counterfeit market prevalence or of missed detection. Buyers need to distinguish authorised inventory from goods whose provenance cannot be established; the seizure ranking alone cannot show whether parcel shipments are harder to intercept or whether counterfeiting is increasing.
Where can suppliers win additional business in the sneakers market?
Owned stores and digital distribution provide an additional route to customers for brands able to support the associated costs. On Holding's Q2 2025 DTC results illustrate expansion through that channel within its own business. [7] Suppliers need to match replenishment and returns handling to the actual retailer contract, since DTC growth does not automatically mean smaller manufacturing batches. The women's footwear market overlaps with women's sneaker ranges but covers a wider set of products.
Performance development is another opportunity for specialist component suppliers when a brand moves from testing to production. Nike's 23 October 2025 announcement describes new product-development structures and innovation platforms, including Project Amplify. [11] Suppliers need evidence of a production programme before treating a technology presentation as a committed component order.
Unsold-stock controls create demand for inventory tracking and reverse logistics. The European Commission's destruction prohibition affects how covered large companies handle unsold footwear from 19 July 2026. [3] It does not by itself mandate recyclable or mono-material sneaker components. Suppliers seeking related contracts need to demonstrate the particular service or material requirement stated by the buyer, rather than treating the destruction rule as a blanket materials certification obligation.
Sneakers Market by Country (2026 to 2036)
Table 5: Sneakers Market Country Growth Forecast
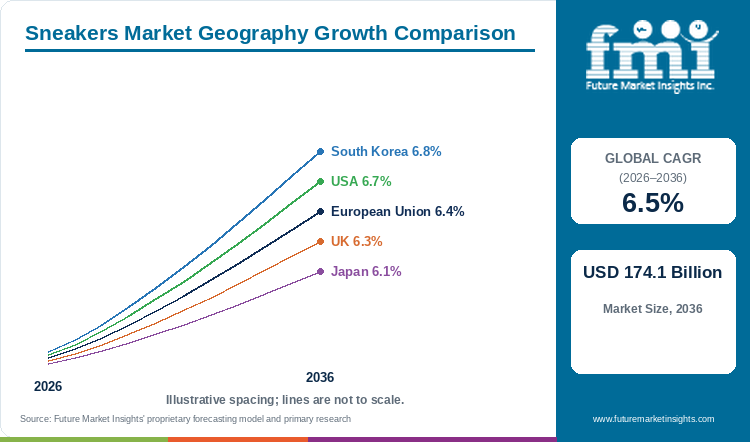
| Country | CAGR, 2026 to 2036 |
|---|---|
| South Korea | 6.8% |
| USA | 6.7% |
| European Union | 6.4% |
| UK | 6.3% |
| Japan | 6.1% |
Source: FMI Analysis
South Korea
FILA's established footwear franchises provide a firmer local demand signal than the wider profit figures of its parent. In its 19 March 2026 results announcement, Misto Holdings reported steady Korean demand for FILA footwear franchise models. [9] The group also includes Acushnet's golf businesses, so consolidated results cover a broader portfolio than sneakers. [9][10] FMI forecasts South Korea's Sneakers Market to grow at a 6.8% CAGR from 2026 to 2036, the highest rate among the profiled markets. The commercial argument rests on maintaining demand for those footwear ranges while developing the next assortment.
Misto's Greater China growth requires a separate interpretation. The company linked its expansion there to fashion brands including MARITHÉ+FRANÇOIS GIRBAUD, Matin Kim, Rest & Recreation and RAIVE. [9] That activity is not a measure of Korean sneaker consumption or of FILA footwear sales in China. For sneaker suppliers, the useful distinction is between building a domestic footwear franchise and distributing a broader Korean fashion portfolio overseas. Each requires its own range planning, partner commitments and inventory allocation.
FMI sees replenishment of established franchises as an important part of the Korean outlook. Orders tied to products with repeat demand give retailers a different stock commitment from new silhouettes whose later sell-through is uncertain. A supplier needs to keep successful sizes available while controlling the quantity committed to a launch. The restraint is financial as well as creative: inventory held across too many styles can absorb cash before the next season's range reaches stores. Misto's wider restructuring and profitability programme provides context for that discipline, while its reported Korean footwear demand remains the relevant local example. [9]
USA
Import costs and retailer inventories shape the US commercial outlook alongside demand for both lifestyle and performance sneakers. FMI forecasts a 6.7% CAGR for the USA from 2026 to 2036, compared with 6.5% globally. The Nike and PUMA disclosures describe material tariff exposure, but their guidance belongs to the dates and sourcing arrangements covered by each announcement. [4][5] They should not be read as a current tariff schedule or as a prediction of the same cost for every importer.
US Customs and Border Protection's Headquarters Ruling H338307 concerns a particular winter boot and its classification as sports footwear. [1] It demonstrates that the product's construction and the applicable tariff definition matter. A buyer cannot apply that ruling's rate to all sneakers merely because they are marketed for sport. Product-level classification and country of origin remain separate purchasing questions, particularly when a brand shifts manufacturing between countries.
The domestic opportunity includes established wholesale distribution and owned stores, rather than digital expansion alone. Nike's fiscal 2025 annual report records weaker digital sales, providing a counterweight to examples of faster DTC growth at smaller brands. [15] Retailers therefore need to evaluate replenishment and price realisation by brand instead of assuming that all premium lines gain together. FMI's forecast accommodates a large established market with selective brand growth; changes in landed cost could absorb part of that revenue gain before it reaches suppliers' margins.
European Union
The European Union's outlook combines an established online buying base with tighter controls on unsold inventory. FMI forecasts a 6.4% CAGR from 2026 to 2036, slightly below the 6.5% global rate. Eurostat's evidence concerns online purchasing across product groups, including clothing, shoes and accessories; it supports the presence of an established digital channel but does not isolate sneaker revenue. [13] The market's prospects therefore depend on brands winning purchases within an already competitive retail environment.
The European Commission's measures prohibit destruction of unsold apparel and footwear by covered large companies from 19 July 2026, with a later application date for medium-sized companies. [3] This changes the handling of residual stock. It does not prove that consumer demand will absorb the cost, nor does a manufacturer's share buyback establish that every retailer can fund the required operational changes. Buyers face the practical question of ordering enough sizes to serve customers without accumulating an unmanageable long tail of unsold goods.
Adidas' reported 2025 results provide a supplier example, not a standalone reading of total EU demand. [6] Its operations extend beyond the bloc and beyond sneakers. FMI sees the commercial opening in ranges that retain replenishment demand and in distribution arrangements that make stock movements visible across stores and online channels. The principal constraint is the cost of stock that fails to sell at the intended price. That balance explains a positive forecast without placing the EU above the global growth rate.
UK
Recreational activity provides a concrete demand context for the UK's mix of performance and everyday sneakers. Sport England reports that 64.6% of adults in England met physical-activity guidelines during November 2024 to November 2025. [14] This observation covers England rather than the whole UK and is not a footwear-spending measure. FMI's Sneakers Market forecast for the UK is a 6.3% CAGR from 2026 to 2036, below the global 6.5% rate.
Premium retail investment is a separate route to demand. ASICS' disclosure of Onitsuka Tiger store expansion in London indicates a commitment to a local sales presence, although the company's European sales growth cannot be assigned to the UK. [8] The store example matters for assortment and distribution: a brand-owned location controls presentation and stock allocation, while wholesale retailers must compare that brand against alternatives competing for the same shelf space. Neither a flagship opening nor a regional growth rate establishes a national market-share gain.
PUMA's weaker European sales in the reporting period provide a useful qualification. [5] Brands can experience different sales trends within the same geography, and broader sportswear figures include categories outside sneakers. FMI expects consumer activity and lifestyle purchases to support continued demand, while the cost of retail space, markdowns and imports affects the return on that demand. Supplier decisions should distinguish a repeatable range from a high-profile launch whose initial sales do not demonstrate later replenishment.
Japan
Tourist purchases complicate the reading of sneaker demand in Japan. ASICS distinguishes inbound sales from its wider Japanese operations, and the 2025 disclosure records strong growth in Onitsuka Tiger purchases by visitors. [8] These transactions are made in Japan but are not evidence of equivalent growth in purchases by Japanese residents. FMI forecasts the Japan Sneakers Market to grow at a 6.1% CAGR from 2026 to 2036, below the 6.5% global rate.
The distinction affects stock allocation. A retail location serving visitors may need different product and size availability from a store that primarily replenishes a local running customer base. ASICS' company results illustrate the coexistence of performance and lifestyle ranges, but its global Performance Running growth cannot be treated as a cleaner numerical measure of domestic Japanese demand. [8] Both the product scope and the geography differ. FMI therefore uses those disclosures to explain supplier positioning, rather than substituting them for a national expenditure series.
The commercial opportunity is to serve these purchase occasions separately while keeping replenishment flexible. Visitor-facing lifestyle demand can increase sales at particular locations, but it may also expose inventory plans to changes in travel patterns. Resident demand is spread across everyday use, training and competition, with different product requirements and replacement decisions. The forecast reflects a mature market with these distinct sources of purchases; one company's particularly strong year does not mean that the national market will sustain the same percentage increase over a decade.
Who are the notable companies in the Sneakers Market?
Nike, adidas, ASICS and On Holding represent different competitive positions in the Sneakers Market. Nike and adidas distribute broad lifestyle and performance ranges, while ASICS reports separate performance and heritage-led businesses and On Holding combines premium running products with an expanding owned channel. Their reported financial results cover different product and geographic boundaries, so growth percentages should not be read as directly comparable sneaker market-share movements. [6][7][8][15] Nike's fiscal 2025 report also shows that a large digital business can contract while another supplier's DTC channel grows. [15] That difference matters to retailers because a brand's sales momentum does not establish demand for every range in its assortment. ASICS' product disclosures illustrate how performance running and lifestyle lines can contribute differently within one group. [8] On Holding's Q2 2025 DTC share provides a separate example of channel strategy. [7] PUMA's results highlight cost and inventory pressure rather than proving that all established sportswear brands face the same trajectory. [5] FMI assesses these companies through their product roles, distribution arrangements and reported activities, while keeping wider players such as Skechers, New Balance and FILA in the competitive coverage without assigning unsupported global rankings.
Key Developments in the Sneakers Market
- 29 January 2026: adidas announced a share buyback of up to EUR 1 billion, planned to start in early February 2026, alongside its preliminary 2025 results. [6]
- 12 March 2026: Nike announced Fragment Concept Testing versions of the Mind 002 and other silhouettes with Hiroshi Fujiwara. The company scheduled the Mind styles for Fragment retail on 14 March and a wider SNKRS and selected-retailer release on 19 March. [16]
Key Players in the Sneakers Market
- Nike
- Adidas
- Puma
- Skechers
- New Balance
- ASICS
- Under Armour
- Reebok
- On Holding
- Veja
- FILA (Misto Holdings)
Sneakers Market Report Scope
Table 6: Sneakers Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Sneakers for Lifestyle, Sports and Competition, including adult and children's products; excludes non-sneaker footwear, apparel and accessories. |
| Product Type | Adult Sneakers; Children's Sneakers |
| Application | Lifestyle; Sports; Competition |
| Consumer Orientation | Men; Women |
| Sales Channel | Online: all online transactions; Multi-Brand Stores: physical multi-brand chains; Independent Stores: physical independent specialists; Other Channels: brand-owned physical stores, mono-brand outlets and other offline channels. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | South Korea, USA, European Union, UK, Japan |
| Companies covered | Nike; Adidas; Puma; Skechers; New Balance; ASICS; Under Armour; Reebok; On Holding; Veja; FILA (Misto Holdings) |
| Quantitative Units | USD billion |
Source: FMI Analysis
Sneakers Market Research Methodology
The Sneakers Market assessment uses secondary company publications and official public sources. Market values and the forecast CAGR were checked for consistent years, currency and units. Segment comparisons were checked against the report taxonomy and their full-share totals. FMI's sales-channel assessment draws on brand distribution disclosures and retailer channel evidence, while competitive review compares dated company activity within each source's product and geographic scope.
Sneakers Market by Segments
Sneakers Market segmented by Product Type:
- Adult Sneakers
- Children's Sneakers
Sneakers Market segmented by Application:
- Lifestyle
- Sports
- Competition
Sneakers Market segmented by Consumer Orientation:
- Men
- Women
Sneakers Market segmented by Sales Channel:
- Online
- Multi-Brand Stores
- Independent Stores
- Other Channels
Sneakers Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Customs and Border Protection, Headquarters Ruling H338307, August 28, 2025.
- [2] U.S. Customs and Border Protection. Intellectual Property Rights Seizure Statistics, Fiscal Year 2024. Accessed 3 November 2026.
- [3] European Commission, Commission adopts new measures to stop the destruction of unsold clothes and shoes, February 2026.
- [4] NIKE, Inc. FY25 Q4 Earnings Release Conference Call Transcript. 26 June 2025. https://investors.nike.com/_assets/_07be80eb1a0b76dace4543b752eda1f2/nike/db/938/9403/webcast_transcript/NIKE-Inc-Q4FY25-OFFICIAL-Transcript_-FINAL.pdf
- [5] PUMA SE, "PUMA Reports Sales Decline in Q2 and Lowers Outlook for 2025," corporate news release, July 24, 2025.
- [6] adidas AG. adidas Reports Record Revenues in 2025 and Launches Share Buyback. 29 January 2026; preliminary results announcement.
- [7] On Holding AG, Form 6-K, Q2 2025 Press Release, filed with the U.S. Securities and Exchange Commission, August 2025.
- [8] ASICS Corporation. Consolidated Financial Summary for the Fiscal Year Ended December 31, 2025, with script. 13 February 2026.
- [9] Misto Holdings Corp. Misto Holdings Announces Annual Operating Results for 2025. 19 March 2026. https://mistoholdings.com/newsroom/eng/press/detail/173.do
- [10] Acushnet Holdings Corp. Annual Report 2025, company history and ownership disclosure. Published 2026; accessed 3 November 2026. https://s21.q4cdn.com/797008351/files/doc_financials/2025/ar/Acushnet-2025-Annual-Report.pdf
- [11] NIKE, Inc. Nike Creates New Innovation Engine to Power Athletes Faster. 23 October 2025. https://about.nike.com/en/newsroom/releases/nike-new-innovation-engine-announcement
- [12] European Union, Your Europe. Footwear Label: mandatory material information and responsibility for footwear placed on the EU market. Accessed 3 November 2026. https://europa.eu/youreurope/business/product-rules-compliance/textiles-and-footwear/footwear-label/indexamp_en.htm
- [13] Eurostat. Online shopping in the EU keeps growing. 20 February 2025. https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20250220-3
- [14] Sport England. Active Lives Adult Survey, November 2024 to November 2025. Released April 2026; accessed 2 November 2026. https://www.sportengland.org/news-and-inspiration/england-getting-more-active-not-everyone-benefiting
- [15] NIKE, Inc. Annual Report on Form 10-K for the year ended 31 May 2025. Filed 17 July 2025. https://www.sec.gov/Archives/edgar/data/320187/000032018725000047/nke-20250531.htm
- [16] NIKE, Inc. Nike and Hiroshi Fujiwara Debut Exclusive Expressions of the Air Liquid Max, Mind 001 and Mind 002. 12 March 2026. https://about.nike.com/en/newsroom/releases/nike-hiroshi-fujiwara-fragment-concept-testing-air-liquid-max-mind-001-mind-002
- [17] adidas AG. Annual Report 2025, Markets and Sales Channels and Income Statement. Published 2026; accessed 2 November 2026. https://report.adidas-group.com/2025/en/group-management-report-our-company/description-of-business-model/markets-and-sales-channels.html
- [18] PUMA SE. Annual Report 2025, Sales Development. Published 2026; accessed 2 November 2026. https://annual-report.puma.com/2025/en/combined-management-report/economic-report/sales-development/index.html
- [19] JD Sports Fashion plc. Full Year Results 2025/26, year ended 31 January 2026. Published 2026; accessed 2 November 2026. https://www.jdplc.com/?p=5593
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Adult Sneakers
- Children's Sneakers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Lifestyle
- Sports
- Competition
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Consumer Orientation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Consumer Orientation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Consumer Orientation, 2026 to 2036
- Men
- Women
- Y-o-Y Growth Trend Analysis By Consumer Orientation, 2021 to 2025
- Absolute $ Opportunity Analysis By Consumer Orientation, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Online
- Multi-Brand Stores
- Independent Stores
- Other Channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Consumer Orientation
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nike
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- adidas
- On Holding
- ASICS
- PUMA
- Skechers
- New Balance
- Under Armour
- Reebok
- Veja
- FILA (Misto Holdings)
- Nike
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by Consumer Orientation, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Consumer Orientation
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Type
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: North America Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Consumer Orientation
- Figure 35: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sales Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type
- Figure 42: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Application
- Figure 45: Latin America Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Consumer Orientation
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Type
- Figure 55: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Application
- Figure 58: Western Europe Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by Consumer Orientation
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Application
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by Consumer Orientation
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Type
- Figure 81: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Application
- Figure 84: East Asia Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by Consumer Orientation
- Figure 87: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by Consumer Orientation
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by Consumer Orientation, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by Consumer Orientation, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by Consumer Orientation
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
What is the Sneakers Market forecast?
The Sneakers Market is forecast to rise from USD 92.8 billion in 2026 to USD 174.1 billion by 2036 at a 6.5% CAGR. The 2025 value is USD 87.1 billion.
Which product type leads the Sneakers Market?
Adult Sneakers account for 72.6% of the market by Product Type in 2026.
Which other segments lead the Sneakers Market?
Lifestyle leads Application with 61.9%, and Multi-Brand Stores lead Sales Channel with 38.7% in FMI's 2026 assessment.
Which country is growing fastest in the sneakers market?
South Korea leads FMI's country-level CAGR table at 6.8% between 2026 and 2036, ahead of the USA (6.7%), the European Union (6.4%), the UK (6.3%), and Japan (6.1%).
How do unsold-stock rules affect sneaker purchasing?
The European Commission's prohibition on destroying covered unsold apparel and footwear requires affected companies to plan how residual inventory is handled. It applies to covered large companies from 19 July 2026. [3]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
