
- Market Size (2026)
- USD 206.2 Bn
- Forecast (2036)
- USD 383.4 Bn
- CAGR (2026 to 2036)
- 6.4%
How big is Superfood Market in 2026?
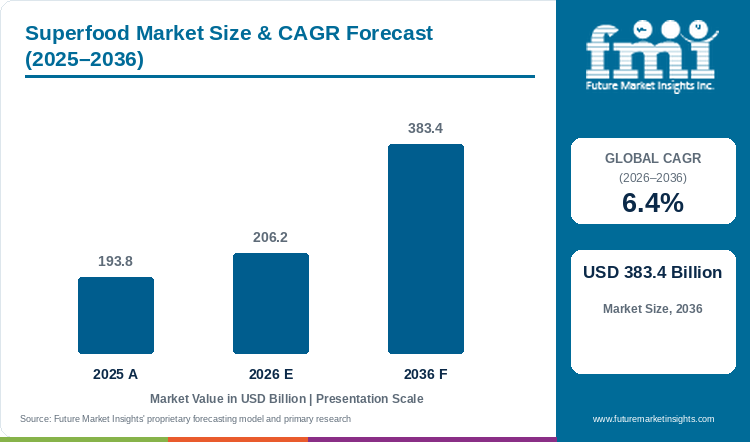
Starting from USD 193.8 billion in 2025, the superfood market valuation advanced to USD 206.2 billion in 2026, with projections pointing toward USD 383.4 billion by 2036 at a CAGR of 6.4%.
The global superfood market was valued at USD 193.8 billion in 2025 and is estimated to reach USD 206.2 billion in 2026. FMI demand analysis indicates that the market is projected to reach USD 383.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.4% between 2026 and 2036. Superfruits & Berries are expected to hold a 34.6% share of 2026 ingredient demand, given that food and beverage formulators purchase freeze-dried berry concentrates and frozen fruit purees to deliver natural antioxidant claims without synthetic fortificants. The demand for nutrient-dense botanicals is supported by daily functional dosage upgrading across grocery baskets, with the Organic Trade Association reporting in March 2026 that United States organic berry sales rose 10.5% to USD 4.4 billion in 2025 as shoppers traded up to certified antioxidant produce.
This whole-format grocery base explains why overall industry expansion trails spirulina functional beverages projected at a 14.3% CAGR, since bulk retail berries and culinary seeds scale with household grocery budgets whereas microalgal energy drinks capture rapid convenience trial. Manufacturers are also investing in brand consolidation and micronutrient formulation platforms to capture retail shelf space. For instance, Laird Superfood completed the acquisitions of Navitas Organics and Terrasoul Superfoods for USD 88.9 million in combined net cash by August 2026 to expand its retail superfood powder and seed distribution, while Ingredion introduced its FUSERA micronutrient-dense fruit and vegetable solutions at IFT FIRST in July 2026. Retailers allocate permanent aisle space to suppliers that guarantee heavy-metal residue compliance and mask vegetal bitterness across ready-to-mix formats through 2036.
Key Market Trends & Insights
- By ingredient category: Superfruits & Berries are projected to hold a 34.6% share in 2026 since natural polyphenol profiles and familiar berry flavors simplify consumer adoption in drinks and snacks.
- By physical format: Whole, Fresh & Frozen Formats are estimated to represent 41.2% in 2026 owing to high repeat purchase velocity across supermarket produce decks and frozen smoothie packs.
- By application: Functional Beverages, Smoothies & RTD Drinks are expected to account for 36.4% in 2026 driven by consumer preference for drinkable daily micronutrient and digestive blends.
- By nature: Conventional superfoods are anticipated to secure 56.4% in 2026 on account of lower raw material costs for mass-market bakery and cereal processors.
- By sales channel: Supermarkets & Hypermarkets are forecast to command 38.4% in 2026 supported by private-label organic seed pouches and dedicated wellness aisles.
Regional Highlights
- Top national expansion: India leads national growth projections at an 8.7% CAGR through 2036 supported by government Shree Anna millet initiatives and urban quick-commerce supplement delivery.
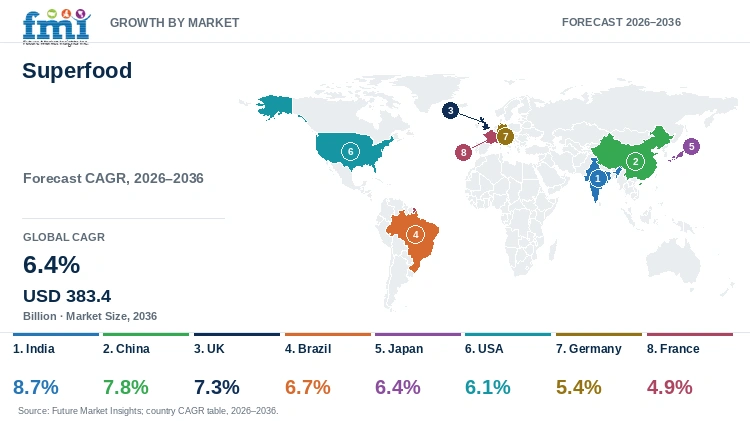
- Broader country progression: China tracks at a 7.8% CAGR ahead of the United Kingdom at 7.3% and Brazil at 6.7%, while Japan advances at a 6.4% CAGR and the United States progresses at a 6.1% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Superfood Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 193.8 billion |
| Estimated Market Size in 2026 | USD 206.2 billion |
| Projected Market Size by 2036 | USD 383.4 billion |
| CAGR, 2026 to 2036 | 6.4% |
| Added Revenue, 2026 to 2036 | USD 177.2 billion |
Packaged food brands and supplement formulators face rising consumer skepticism toward synthetic vitamins, which is shifting procurement toward whole-plant ingredients that provide naturally occurring polyphenols and dietary fibers. According to the Organic Trade Association in March 2026, total United States certified organic sales climbed 6.8% to reach USD 76.6 billion in 2025, with organic beverages reaching USD 10.2 billion and organic dietary supplements advancing 8.7% to USD 2.4 billion. This retail momentum confirms that household buyers are willing to pay a price premium for recognizable botanical ingredients in concentrated superfood powders when labels verify clean agricultural origin.
Global Superfood Raw Material and Active-Inclusion Sizing
Table 2: Raw Material Tonnage and Active-Inclusion Sizing for the Superfood Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 193.8 | 206.2 | 383.4 |
| Commercial superfruit & berry volume (million metric tons) | 14.2 to 15.6 | 15.1 to 16.5 | 26.8 to 29.4 |
| Cleaned ancient seeds & supergreens volume (million metric tons) | 8.4 to 9.3 | 8.9 to 9.9 | 16.2 to 18.0 |
| Cultivated food-grade microalgae & fungi (thousand metric tons) | 118.0 to 132.0 | 126.5 to 142.0 | 245.0 to 275.0 |
Beverage and snack processors require concentrated botanical inputs that preserve antioxidant activity during thermal pasteurization and high-shear extrusion. According to a June 2026 study in Foods, Brazilian extractive and cultivated acai production reached 1.94 million metric tons annually, and adding 6% upcycled acai seed flour into functional shakes raised insoluble dietary fiber from 3.2% to 10.7% while elevating antioxidant capacity by 172.9%. Industrial formulators are consequently pairing whole fruit purees with cleaned chia seeds to achieve verified fiber and polyphenol thresholds on front-of-pack nutrition panels.
Per Capita & Functional Household Basket Sizing
Table 3: Per Capita and Household Wellness Spending Indicators for the Superfood Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual superfood spend per capita (USD) | 23.6 | 24.8 | 42.6 |
| Certified organic share of global superfood value (%) | 42.8% to 43.4% | 43.2% to 44.0% | 47.5% to 49.5% |
| Beverage & smoothie application share (%) | 35.5% to 36.2% | 36.0% to 36.8% | 39.0% to 41.0% |
Table 4: Retail & Industrial Channel Spending Indicators for the Superfood Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 206.2 billion | 2026 global revenue baseline |
| U.S. certified organic marketplace sales, 2025 | USD 76.6 billion | Organic Trade Association 2026 report (organic berries USD 4.4B) |
| Brazilian annual acai berry production | 1.94 million metric tons | Extractive and cultivated harvest (Para state 68.1% share) |
| Supermarkets & Hypermarkets channel revenue, 2026 | USD 79.2 billion | 38.4% sales channel allocation |
Overcoming the grassy taste and dark green pigmentation of microalgae and leafy powders remains a decisive technical hurdle for mainstream food brands expanding beyond hardcore wellness shoppers. As per the Institute of Food Technologists in April 2025, United States retail sales of functional foods and beverages reached USD 320 billion alongside USD 64 billion in dietary supplements, with mood-support beverages rising 62%, digestive drinks climbing 34%, and mushroom supplements advancing 14.6% to USD 454 million. Product developers are addressing sensory fatigue by blending shade-grown matcha extracts and natural citrus maskers into daily greens and adaptogenic drink mixes.
Analyst Perspective
"Superfood buyers are moving past single-ingredient novelty hype toward daily functional formats that solve specific fiber, gut, and metabolic gaps without unpleasant earthy aftertastes. Ingredient suppliers and consumer brands that pair certified contaminant-free botanicals with cold-water dispersibility and clinical bioavailability data are positioned to lock in national grocery and club-store contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Superfood Market segmented?
The superfood market is segmented by ingredient category, physical format, application, nature, and sales channel. In 2026, Superfruits & Berries are projected at 34.6%, Whole, Fresh & Frozen Formats at 41.2%, Functional Beverages, Smoothies & RTD Drinks at 36.4%, Conventional at 56.4%, and Supermarkets & Hypermarkets at 38.4%.
By ingredient category: Superfruits & Berries, Supergreens & Leafy Vegetables, Superseeds, Ancient Grains & Pulses, Roots, Herbs & Functional Fungi, and Microalgae & Marine Superfoods.
By physical format: Whole, Fresh & Frozen Formats, Dehydrated, Freeze-Dried & Milled Powders, Liquid Extracts, Purees & Concentrates, and Capsules, Tablets, Gummies & Stick Packs.
By application: Functional Beverages, Smoothies & RTD Drinks, Bakery, Cereals & Healthy Snacks, Dietary Supplements & Nutraceutical Formulations, and Dairy Alternatives, Confectionery & Culinary Convenience Foods.
By nature: Conventional and Certified Organic.
By sales channel: Supermarkets & Hypermarkets, Online Retail & Direct-to-Consumer Subscriptions, Health Food, Natural & Specialty Stores, and B2B Industrial Ingredient & Foodservice Supply.
Why do Superfruits & Berries lead the ingredient category?
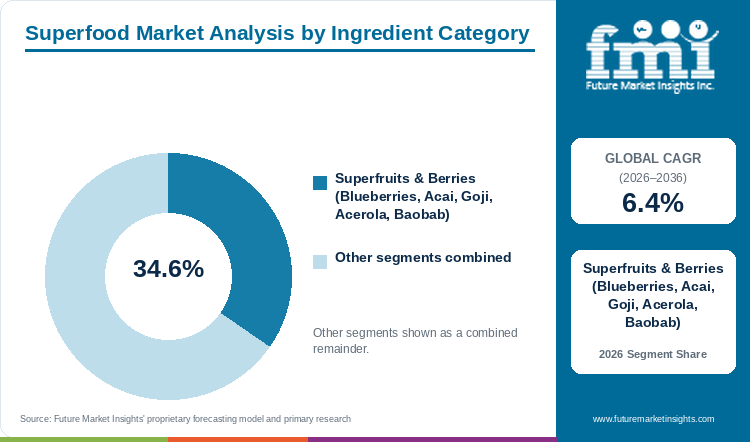
Superfruits & Berries hold an estimated 34.6% of ingredient category demand in 2026, anchored by high anthocyanin density and natural fruit flavor across beverages and snacks.
Table 5: Ingredient Category Share for the Superfood Market (percentage share), 2026
| Ingredient Category | Share (2026) |
|---|---|
| Superfruits & Berries | 34.6% |
| Other Segments Combined | 65.4%* |
| Total | 100.0% |
*Note: Remaining ingredient categories account for the balance of 2026 global superfood demand.
Table 6: Ingredient Category Leadership and Market Growth for the Superfood Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.4% |
| Leading Segment | Superfruits & Berries |
Superfruits & Berries lead ingredient demand since blueberries, acai, goji, acerola, and baobab provide natural anthocyanin pigments and recognizable fruit sweetness that require minimal flavor masking in beverages and snacks. Commercial buyers sourcing frozen acai berry pulp still face seasonal harvest swings when unseasonable freezes reduce orchard yields, as reflected in the July 2026 USDA Economic Research Service report showing that United States fresh sweet cherry availability reached 481 million pounds in 2025 before spring freezes reduced the 2026 domestic tart cherry crop by 36% to 91 million pounds.
- By ingredient category, Superfruits & Berries are projected to account for 34.6% of global demand in 2026 given that mass-market beverage and yogurt brands prioritize fruit-based antioxidant claims.
- Segment expansion is expected to remain resilient through 2036 as processors valorize fruit agro-waste, supported by June 2026 research in Foods showing that Brazilian acai harvests reach 1.94 million tons annually.
What sustains Whole, Fresh & Frozen Formats leadership in physical format?
Whole, Fresh & Frozen Formats represent 41.2% of the physical format category in 2026, supported by high-velocity retail berry produce, frozen smoothie packs, and whole seeds.
Whole, Fresh & Frozen Formats capture the largest physical format share because household shoppers routinely purchase fresh clam-shell berries, frozen smoothie fruit packs, and whole chia or quinoa seeds as everyday meal staples rather than occasional supplements. While cold-chain energy costs and pathogen recalls challenge frozen fruit distributors, whole and minimally processed formats avoid the chemical extraction steps required for standardized chlorella powders and cultivated algae harvests that reached 38 million metric tons globally according to the Food and Agriculture Organization in June 2026.
- In the physical format category, Whole, Fresh & Frozen Formats are anticipated to capture a leading 41.2% share in 2026 supported by high-frequency supermarket produce and freezer-case turnover.
- Dehydrated powders and unit-dose gummies are projected to gain incremental share over the forecast period, as Kerry Group reported in January 2026 that gummies, chews, powders, and stick packs now exceed 60% of global supplement format volume.
How do Functional Beverages, Smoothies & RTD Drinks lead by application?
Functional Beverages, Smoothies & RTD Drinks account for 36.4% of application demand in 2026, driven by daily wellness shots, prebiotic drinks, and ready-to-mix greens.
Functional Beverages, Smoothies & RTD Drinks anchor application demand as time-pressed consumers prefer drinking daily micronutrient, adaptogen, and prebiotic blends rather than preparing complex whole-food meals. Formulators blending dried moringa leaf infusions into ready-to-drink juices must manage sedimentation and color degradation during shelf storage, a technical focus highlighted when Symrise introduced its standardized Hibicyan anthocyanin hibiscus extract and Acerowell acerola beverage actives at Vitafoods Europe in April 2026.
- Within the application segment, Functional Beverages, Smoothies & RTD Drinks are estimated to hold 36.4% of 2026 demand owing to rapid retail rotation of wellness shots and prebiotic sodas.
- Bakery and pasta fortification represents a fast-expanding secondary application, as demonstrated by April 2026 research in Foods showing that adding 6% to 12% wet-milled royal quinoa fiber lifts pasta dietary fiber by more than 50%.
Why does Conventional lead the nature category?
Conventional formulations secure 56.4% of nature value in 2026, supported by raw material cost accessibility across commercial bakery, cereal, and snack bar lines.
Conventional nature positioning retains the majority share of global volume because multi-brand cereal, snack bar, and foodservice operators require reliable bulk tonnages of chia, flax, blueberries, and turmeric without paying organic certification premiums. Although conventional growers must still pass strict pesticide residue and heavy-metal screening at import ports, conventional crop yields allow ingredient blenders to hold unit prices steady for mainstream grocery shoppers.
- Across the nature category, Conventional products are forecast to secure 56.4% of 2026 demand as industrial food processors balance micronutrient fortification against retail price ceilings.
- Certified Organic offerings are projected to capture 43.6% in 2026 and expand steadily as agricultural conversion progresses, with Eurostat documenting that European Union organic farmland reached 16.9 million hectares or 10.5% of total agricultural land.
What gives Supermarkets & Hypermarkets the leading position in sales channel?
Supermarkets & Hypermarkets command 38.4% of sales channel share in 2026, anchored by private-label organic assortments and dedicated grocery wellness aisles.
Supermarkets & Hypermarkets dominate distribution because mainstream grocery chains and warehouse clubs have integrated organic berry freezers, ancient-grain bakery aisles, and private-label superfood powders into weekly household shopping trips. According to the USDA Economic Research Service in September 2026, mass-market grocery retailers accounted for 55% of all United States retail organic food sales across 17,181 certified organic operations, confirming that conventional supermarket shelves outell specialty health stores in total volume.
- By sales channel, Supermarkets & Hypermarkets are expected to command 38.4% of 2026 demand driven by private-label shelf expansion and cross-merchandising in produce and wellness aisles.
- Direct-to-consumer subscriptions and club stores provide strong omnichannel reinforcement, as reflected in August 2026 when Laird Superfood expanded its functional coffees and creamers into approximately 1,000 Walmart stores.
What are the drivers, restraints, and opportunities in the Superfood Market?
In the superfood market, preventive gut and metabolic nutrition is projected to drive adoption whereas frozen fruit pathogen recalls and vegetal off-notes restrain uncalibrated use and fermentation-modulated bioactives unlock mainstream food reformulation.
- Driver: Rising consumer adoption of preventive gut, metabolic, and immune nutrition is accelerating daily consumption of polyphenol-rich berries, prebiotic seeds, and microalgal powders.
- Restraint: Extreme weather crop volatility, microbiological contamination recalls in frozen produce, and earthy sensory notes in green powders limit uncalibrated formulation use.
- Opportunity: Fermentation-assisted color and flavor modulation, upcycled superfruit seed fibers, and GLP-1 companion nutrient-dense beverage blends unlock mainstream food integration.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer migration from reactive symptom treatment toward daily preventive nutrition is driving sustained procurement of high-protein microalgae, prebiotic seeds, and antioxidant superfruits across retail and foodservice channels. Formulators developing plant-based protein blends increasingly incorporate spirulina and chia to boost amino acid digestibility and water-binding capacity without synthetic stabilizers. An August 2026 review in Comprehensive Reviews in Food Science and Food Safety confirmed that Arthrospira platensis contains up to 70% protein by dry weight with a Protein Digestibility-Corrected Amino Acid Score of 86.6% and requires under 2.5 square meters of land per kilogram of protein. Similarly, July 2026 findings in Foods demonstrated that adding 1.0% ground chia seeds containing 42 grams per 100 grams of dietary fiber into meat batters held cooking loss below 0.70%.
Risk Assessment of the Superfood Market: Operational and Formulation Friction
Microbiological contamination risks in minimally processed frozen berries and sensory bitterness in concentrated green powders represent primary operational hurdles restraining broader category adoption. Because frozen superfruits are frequently blended directly into cold smoothies without a thermal kill step by consumers, pathogen outbreaks trigger costly retail recalls and import detentions. In October 2026, the U.S. Food and Drug Administration placed a Chilean fruit processor on Import Alert 99-35 and expanded recalls of 10-ounce and 12-ounce frozen organic blueberry and mixed berry packages following 17 E. coli O145:H28 illnesses. Meanwhile, manufacturers formulating vegan dietary supplements must also comply with strict national safety reviews, as highlighted by the German Federal Institute for Risk Assessment in its July 2025 food supplement risk dossier evaluating botanical intake thresholds.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient innovators are unlocking new commercial demand avenues by attenuating the dark green color and grassy odor of microalgae while upcycling superfruit and botanical side streams into high-fiber functional ingredients. In August 2026, researchers reporting in Foods demonstrated that heterotrophic fed-batch cultivation of Spirulina with 0.2 grams per liter of sodium acetate reduced chlorophyll-a from 29.1 to 18.0 milligrams per gram while preserving 32.18% protein and phycocyanin bioactivity for light-colored food matrices. Parallel February 2026 research in the International Journal of Molecular Sciences showed that enriching creamed honey with 1.2% blue spirulina phycocyanin raised soluble protein by 127% to 453.81 milligrams per 100 grams and doubled antioxidant reducing power over six months. Pairing these sensory-optimized bioactives with modified quinoa starch carriers allows brands to launch shelf-stable functional snacks and GLP-1 companion meal drinks.
Superfood Market by Country (2026 to 2036)
FMI country modeling indicates that India leads superfood expansion at an 8.7% CAGR through 2036, while France advances at a 4.9% CAGR. Commercial adoption across Asian quick-commerce channels, European organic grocery chains, and North American club stores depends on domestic crop valorization, novel-food clearances, and private-label retail penetration.
Table 7: Country CAGR and Primary Growth Levers for the Superfood Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 8.7% | 18.59M MT Shree Anna millet harvest, moringa extraction, and quick-commerce retail |
| China | 7.8% | Ningxia goji bioactive valorization and cross-border e-commerce supplement demand |
| UK | 7.3% | Defra 2026-2036 Organic Action Plan and supermarket private-label wellness lines |
| Brazil | 6.7% | 1.94M MT acai harvest base, freeze-drying expansion, and upcycled seed fiber |
| Japan | 6.4% | Matcha and chlorella processing plus 14,000 MT domestic cherry harvest rebound |
| USA | 6.1% | 17,181 certified organic operations, club-store greens, and GLP-1 companion drinks |
| Germany | 5.4% | Reformhaus and drugstore private-label superfoods under BfR safety standards |
| France | 4.9% | Nutri-Score fruit/fiber reformulation across 16.9M ha EU organic farmland base |
Source: Future Market Insights analysis
India Superfood Market Outlook (2026 to 2036)
Demand for superfoods in India is projected to expand at a leading 8.7% CAGR from 2026 to 2036, outpacing the global average as domestic food processors scale ancient millet grains, moringa leaf powder, and curcumin-rich turmeric into urban grocery and quick-commerce channels. National agricultural policy directly supports domestic supply, with the Agricultural and Processed Food Products Export Development Authority reporting in November 2026 that Indian Shree Anna millet production reached 18.59 million metric tons and export shipments totaled 138.69 thousand metric tons in fiscal year 2025 to 2026. Local D2C wellness brands are combining roasted pearl and finger millets with moringa and ashwagandha into ready-to-cook breakfast mixes and effervescent tablets, overcoming rural cold-chain limitations through ambient dry-powder packaging.
Key takeaway: In India, government-backed Shree Anna millet cultivation and rapid urban quick-commerce penetration are projected to drive leading demand for shelf-stable ancient grain and botanical superfoods.
China Superfood Market Outlook (2026 to 2036)
China is anticipated to record a 7.8% CAGR in the superfood market between 2026 and 2036, propelled by cross-border e-commerce supplement adoption and domestic value-chain upgrading across Ningxia goji berries, sea buckthorn, and spirulina. In July 2026, the USDA Foreign Agricultural Service confirmed that China ranks as the third-largest organic retail market globally after the United States and Germany, supported by rising urban middle-class demand for certified clean-label nutrition. Chinese processors are also commercializing botanical side streams into functional teas and baked goods, as evidenced by September 2026 research in Foods documenting that cultivated Ningxia goji leaves contain 16.03 to 16.33 milligrams per gram of rutin and yield 92.5% recovery of bioactive spermidine derivatives.
Key takeaway: In China, domestic goji and botanical extraction upgrading combined with livestream social-commerce retail are anticipated to sustain rapid superfood adoption.
UK Superfood Market Outlook (2026 to 2036)
Superfood consumption in the United Kingdom is forecast to advance at a 7.3% CAGR through 2036, supported by high supermarket private-label penetration of chia, flax, matcha, and kefir-berry smoothie packs. Domestic policy is actively addressing farmland supply constraints, with the Department for Environment, Food and Rural Affairs publishing the ten-year Organic Action Plan for England in October 2026 to lift organic farmland share from 3.4% toward 10% by 2036. British grocery chains and high-street pharmacy retailers are expanding plant-based gut-health and menopause-support powder blends, while post-Brexit border checks require importers of South American chia and acai to maintain digital phytosanitary traceability.
Key takeaway: In the United Kingdom, national organic farmland expansion targets and supermarket wellness aisle curation are forecast to accelerate retail superfood turnover.
Brazil Superfood Market Outlook (2026 to 2036)
Brazil is estimated to progress at a 6.7% CAGR from 2026 to 2036, operating both as the primary global harvesting hub for acai, acerola, and guarana and as a rapidly expanding domestic consumer market for ready-to-eat superfruit bowls and functional shakes. According to June 2026 findings published in Foods, Brazilian extractive and cultivated acai production totals 1.94 million metric tons annually with Para state generating 68.1% of national output, while upcycled seed flour representing 85% of fruit weight boosts functional shake fiber content more than threefold. Domestic freeze-drying and spray-drying investments in Para and Sao Paulo are helping Brazilian processors capture higher export value while insulating local beverage makers from raw pulp spoilage.
Key takeaway: In Brazil, industrial freeze-drying capacity and upcycled acai seed fiber valorization are estimated to strengthen both domestic functional beverage sales and export supply.
Japan Superfood Market Outlook (2026 to 2036)
Sales of superfoods in Japan are projected to grow at a 6.4% CAGR over the 2026 to 2036 forecast period, anchored by deeply rooted consumer adoption of ceremonial and culinary matcha, chlorella tablets, fermented botanical pastes, and antioxidant stone fruits. Domestic fruit supply is rebounding to support functional food processors, with the USDA Foreign Agricultural Service reporting in August 2026 that Japanese fresh cherry production is forecast to rise 25% to 14,000 metric tons alongside a 9.3% increase in domestic peach and nectarine harvests to 110,000 metric tons. Japanese convenience stores and drugstores prioritize compact stick-pack greens and Foods with Function Claims (FFC) dossiers tailored to healthy aging, visual fatigue, and metabolic maintenance.
Key takeaway: In Japan, strong domestic matcha and stone-fruit processing alongside Foods with Function Claims reformulation are projected to sustain steady superfood demand.
USA Superfood Market Outlook (2026 to 2036)
The United States superfood market is slated to expand at a 6.1% CAGR between 2026 and 2036, representing the largest national demand pool globally as warehouse clubs, conventional supermarkets, and D2C subscription brands scale daily greens, adaptogenic mushroom coffees, and organic berries. According to the USDA Economic Research Service in September 2026, domestic production is backed by 7.2 million certified organic acres and 17,181 certified organic operations, with mass-market grocery channels capturing 55% of national organic food volume and specialty natural retailers holding 33%. American beverage and supplement formulators are actively launching high-fiber and micronutrient-dense companion powders for consumers using metabolic weight-management therapies, while enforcing strict FDA import screening on frozen berry shipments.
Key takeaway: In the United States, warehouse-club distribution and GLP-1 companion micronutrient beverages are slated to anchor high-volume superfood growth.
Germany Superfood Market Outlook (2026 to 2036)
German superfood demand is likely to advance at a 5.4% CAGR through 2036, driven by Europe's highest penetration of discount-grocery organic private labels alongside specialized Reformhaus and drugstore nutrition aisles. Formulators selling concentrated botanical powders, ashwagandha capsules, and microalgae blends in Germany must navigate rigorous toxicology and maximum-intake scrutiny, as detailed by the German Federal Institute for Risk Assessment in its July 2025 food supplement assessment dossier. German bakery and muesli manufacturers continue to integrate chia, hemp, and golden flax seeds into whole-grain breads and breakfast flakes to meet clean-label vegan and high-protein consumer preferences.
Key takeaway: In Germany, private-label organic drugstore assortments and whole-seed bakery fortification are likely to support consistent superfood procurement under strict BfR safety standards.
France Superfood Market Outlook (2026 to 2036)
Procurement of superfoods in France is predicted to progress at a 4.9% CAGR from 2026 to 2036, supported by Nutri-Score front-of-pack reformulation incentives that reward food processors for raising fruit, vegetable, pulse, and dietary fiber percentages in packaged foods. European Union agricultural statistics from Eurostat confirm that total EU organic farmland reached 16.9 million hectares or 10.5% of farmed agricultural area, providing French millers and dairy-alternative makers with expanding regional supplies of organic hemp, flax, and berries. At the same time, new exotic botanicals must complete European Food Safety Authority novel-food safety evaluations taking up to nine months under Regulation (EU) 2015/2283 before entering French pharmacy and supermarket channels.
Key takeaway: In France, Nutri-Score fiber and fruit reformulation across biscuits and dairy alternatives is predicted to sustain steady demand for EFSA-authorized superfood ingredients.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Superfood Market?
Ingredion Incorporated, Archer Daniels Midland Company, Cargill, Incorporated, Roquette Freres SA, Kerry Group plc, Symrise AG, Givaudan SA, Döhler GmbH, Laird Superfood, Inc., and SunOpta, Inc. are the notable companies in the superfood market.
Competitive positioning in the superfood industry spans global B2B specialty ingredient processors, botanical and bioactive extract innovators, and vertically integrated branded consumer superfood groups. Ingredion Incorporated and Archer Daniels Midland Company with Cargill, Incorporated and Roquette Freres SA supply bulk plant proteins, pulse fibers, and fruit concentrates. Kerry Group plc and Symrise AG with Givaudan SA and Döhler GmbH engineer standardized superfruit actives, taste-masking systems, and probiotic-botanical blends, while Laird Superfood, Inc. and SunOpta, Inc. lead in retail and foodservice packaged superfoods.
- Global B2B Plant Protein, Fiber & Fruit Concentrates: Ingredion Incorporated, Archer Daniels Midland Company, Cargill, Incorporated, and Roquette Freres SA process bulk pulse proteins, ancient grain fibers, and fruit-vegetable concentrates for multinational food brands.
- Standardized Botanical Actives, Biosolutions & Taste Modulation: Kerry Group plc, Symrise AG, Givaudan SA, and Döhler GmbH formulate clinically backed superfruit polyphenols, postbiotics, and flavor-masking systems that neutralize earthy off-notes.
- Branded Omnichannel Superfood Powders, Seeds & Beverages: Laird Superfood, Inc. (incorporating Navitas Organics and Terrasoul Superfoods) and SunOpta, Inc. market organic daily greens, functional mushroom creamers, ancient seeds, and plant-based beverages across grocery and DTC channels.
Competitive Benchmarking: Superfood Market
Table 8: Competitive Benchmarking for the Superfood Market (qualitative capability ratings), 2026
| Company | Botanical & Micronutrient Portfolio | Sensory & Formulation Support | Organic & Traceability Fit | Geographic Reach |
|---|---|---|---|---|
| Ingredion Incorporated | High | High | High | Global B2B network; launched FUSERA fruit/vegetable and VITESSENCE protein solutions in July 2026 |
| Archer Daniels Midland Company | High | High | High | Global botanical extracts, ancient seeds, and plant proteins; 5 human nutrition plants in Brazil |
| Cargill, Incorporated | High | High | High | Global plant proteins, soluble fibers, and NextCoa cocoa-free botanical systems launched May 2026 |
| Roquette Freres SA | Medium | High | High | Europe, Americas, and Asia pea/microalgal proteins and soluble prebiotic fibers |
| Kerry Group plc | High | High | High | Global Proactive Health botanicals and 2026 Supplements Taste Charts across 9 regions |
| Symrise AG | High | High | High | Global Diana Food superfruit actives and Probi postbiotics; launched Hibicyan in April 2026 |
| Givaudan SA | High | High | High | Global Taste & Wellbeing botanical extracts, acerola, guarana, and natural flavor maskers |
| Döhler GmbH | High | High | High | Global Natural SuperHEROES botanicals, freeze-dried fruits, and GLP-1 meal drink bases |
| Laird Superfood, Inc. | High | Medium | High | North American omnichannel leader; acquired Navitas Organics and Terrasoul Superfoods in 2026 |
| SunOpta, Inc. | Medium | High | High | North American organic plant-based beverages, fruit snacks, and tea/botanical extraction |
Key Developments in the Superfood Market
- In August 2026, Laird Superfood, Inc. reported second-quarter 2026 net sales of USD 41.3 million, up 244.0% year-over-year, following the completed acquisitions of Navitas Organics and Terrasoul Superfoods. The company launched five coffee and creamer SKUs into more than 1,000 Walmart stores nationwide, expanding its retail distribution footprint [25].
- In July 2026, Ingredion Incorporated showcased its FUSERA® clean-label solutions at IFT FIRST 2026 in Chicago, alongside the VITESSENCE Pea and Rice 400 N plant protein for ready-to-mix and high-moisture applications. The company also introduced Ask Ingredion, an AI-powered formulation tool developed with Knowde to accelerate R&D decision-making for food and beverage brands [26].
- In May 2026, Symrise AG introduced Hibicyan, a hibiscus extract standardized for anthocyanin concentration and developed to support vascular health and beauty-from-within via microvascular circulation, at Vitafoods Europe in Barcelona. The launch was presented alongside Acerowell, an acerola-based healthy aging solution, and Rham271h, a postbiotic version of Lacticaseibacillus rhamnosus 271 from subsidiary Probi [27].
Key Players in the Superfood Market
Global B2B Plant Protein, Fiber & Fruit Concentrates
- Ingredion Incorporated
- Archer Daniels Midland Company
- Cargill, Incorporated
- Roquette Freres SA
Standardized Botanical Actives, Biosolutions & Taste Modulation
- Kerry Group plc
- Symrise AG
- Givaudan SA
- Döhler GmbH
Branded Omnichannel Superfood Powders, Seeds & Beverages
- Laird Superfood, Inc. (Navitas Organics / Terrasoul Superfoods)
- SunOpta, Inc.
Superfood Market - Report Scope
Table 9: Report Scope for the Superfood Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Ingredient Category; Physical Format; Application; Nature; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial B2B ingredient and B2C packaged retail revenue from nutrient-dense superfruits and berries, supergreens and leafy vegetables, ancient seeds and grains, adaptogenic roots and functional fungi, and cultivated food-grade microalgae. Category Scope Note: Excludes unfortified commodity cereal grains, conventional table fruits (apples, bananas, oranges), and synthetic single-vitamin pharmaceutical tablets. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | India, China, UK, Brazil, Japan, USA, Germany, France, and additional countries in the full report |
| Key Companies Covered | Ingredion Incorporated, Archer Daniels Midland Company, Cargill, Incorporated, Roquette Freres SA, Kerry Group plc, Symrise AG, Givaudan SA, Döhler GmbH, Laird Superfood, Inc., SunOpta, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Superfood Market - Research Methodology
Table 10: Research Methodology for the Superfood Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with B2B botanical extractors, freeze-dried fruit processors, organic seed cooperatives, and grocery wellness category directors to validate active inclusion rates and retail margins. |
| Secondary Research | Analysis of USDA ERS and FAS GAIN commodity reports, Organic Trade Association retail tracking, FAO aquaculture/algae statistics, Eurostat organic land registries, EFSA Novel Food dossiers, and peer-reviewed Foods and IJMS studies. |
| Market Sizing and Forecasting | Top-down global functional food and organic retail baselines reconciled against bottom-up commercial tonnage of superfruits (15.1M to 16.5M MT), ancient seeds/greens (8.9M to 9.9M MT), and microalgae/fungi from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight certified organic retail sales, domestic superfruit and millet harvests, quick-commerce penetration, and front-of-pack nutrition reformulation across eight key countries. |
| Operational Benchmark Traceability | Raw material tonnage and household spending indicators in Tables 2, 3, and 4 trace to OTA 2025 organic retail figures, USDA ERS farm registries, APEDA millet export logs, and Brazilian IBGE/Foods acai harvest studies. |
| Data Triangulation and Validation | Revenue estimates isolate verified nutrient-dense botanical, seed, fruit, fungal, and microalgal formats while strictly excluding commodity staple grains and synthetic vitamin isolates. |
Superfood Market by Segments
Superfood Market segmented by Ingredient Category:
- Superfruits & Berries (Blueberries, Acai, Goji, Acerola, Baobab)
- Supergreens & Leafy Vegetables (Kale, Spinach, Moringa, Matcha, Wheatgrass)
- Superseeds, Ancient Grains & Pulses (Chia, Quinoa, Hemp, Flax, Millets)
- Roots, Herbs, Functional Fungi & Microalgae (Turmeric, Maca, Ashwagandha, Reishi, Spirulina, Chlorella)
Superfood Market segmented by Physical Format:
- Whole, Fresh & Frozen Formats
- Dehydrated, Freeze-Dried & Milled Powders
- Liquid Extracts, Purees & Concentrates
- Capsules, Tablets, Gummies & Stick Packs
Superfood Market segmented by Application:
- Functional Beverages, Smoothies & RTD Drinks
- Bakery, Cereals & Healthy Snacks
- Dietary Supplements & Nutraceutical Formulations
- Dairy Alternatives & Functional Dairy
- Confectionery & Culinary Convenience Foods
Superfood Market segmented by Nature:
- Conventional
- Certified Organic (USDA Organic, EU-Bio, JAS)
- Regenerative Organic Certified
- Identity-Preserved Non-GMO
Superfood Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Online Retail & Direct-to-Consumer Subscriptions
- Health Food, Natural & Specialty Stores
- B2B Industrial Ingredient & Foodservice Supply
Superfood Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Organic Trade Association (OTA). (2026, March 04). U.S. Organic Marketplace Achieved Significant Growth in 2025. Organic Trade Association.
- [2] Fuller, K. B., & USDA Economic Research Service. (2026, September 16). Organic Agriculture: Market and Farm Sector Overview. U.S. Department of Agriculture, Economic Research Service.
- [3] Weber, C., Wakefield, H., & Wechsler, S.. (2026, July 23). Fruit and Tree Nuts Outlook: July 2026 (FTS-385). U.S. Department of Agriculture, Economic Research Service.
- [4] USDA Foreign Agricultural Service. (2026, August 19). Japan: Stone Fruit Annual (GAIN Report JA2026-0053). U.S. Department of Agriculture, Foreign Agricultural Service.
- [5] USDA Foreign Agricultural Service. (2026, July 21). China: China Organic Product Report (GAIN Report CH2026-0094). U.S. Department of Agriculture, Foreign Agricultural Service.
- [6] U.S. Food and Drug Administration (FDA). (2026, October 05). Outbreak Investigation of E. coli O145:H28: Frozen Blueberries (July 2026). U.S. Food and Drug Administration.
- [7] Food and Agriculture Organization of the United Nations (FAO). (2026, June 16). SOFIA 2026: Global Fisheries and Aquaculture Production Reaches New Highs. Food and Agriculture Organization of the United Nations.
- [8] Eurostat. (2024, June 19). EU Organic Farming: 16.9 Million Hectares in 2022. Statistical Office of the European Union (Eurostat).
- [9] European Food Safety Authority (EFSA). (2026, October 21). Novel Food Regulatory Framework and Union List Authorisations. European Food Safety Authority.
- [10] Frayne, C., & UK Department for Environment, Food & Rural Affairs. (2026, October 14). Organic Action Plan for England Published Today. UK Government, Department for Environment, Food & Rural Affairs (Defra).
- [11] German Federal Institute for Risk Assessment (BfR). (2025, July 18). BfR2GO Issue 1/2025: Main Topic Food Supplements. Bundesinstitut für Risikobewertung (BfR).
- [12] Agricultural and Processed Food Products Export Development Authority (APEDA). (2026, November 02). Indian Millets (Shree Anna) Production and Export Statistics. Ministry of Commerce and Industry, Government of India.
- [13] Sloan, A. E.. (2025, April 04). The Top 10 Functional Food Trends. Institute of Food Technologists (Food Technology Magazine).
- [14] Yurdagul, Y., & Ozturk, O. K.. (2026, August 22). Spirulina as a Multifunctional Ingredient: Challenges, Opportunities, Composition, Techno-Functional Properties, and Food Applications. Comprehensive Reviews in Food Science and Food Safety (PMC13499266).
- [15] Dzugan, M., Trybulec, K., Sidor, E., Milek, M., & Tomczyk, M.. (2026, February 18). The Use of Spirulina Powder to Enrich Honey with Antioxidants and Highly Digestible Protein. International Journal of Molecular Sciences (PMC12940547).
- [16] Gomes, K. S., Pacco-Huamani, M. C., de Morais, M. G., Santos, T. D., & Costa, J. A. V.. (2026, June 02). Acai Seeds for a Greener Future: Transforming Agro-Waste into Industrial Value. Foods (MDPI), 15(11), 1967.
- [17] de Brito, G. M. K., Costa, J. A. V., Barreira, L., & de Morais, M. G.. (2026, August 06). Color-Modulated Spirulina Biomass Produced Under Heterotrophic Cultivation as a Sustainable Food Ingredient. Foods (MDPI), 15(15), 2761.
- [18] Alonso-Alvarez, A., & Haros, C. M.. (2026, April 15). Fibre-Enriched Pasta from Wet Milled Royal Quinoa: Technological and Nutritional Characterisation. Foods (MDPI), 15(8), 1374.
- [19] Zou, J., Tian, X., Wang, S., & Sun, Y.. (2026, September 17). Goji Leaves and Buds as Food Resources: Composition, Processing, Safety, and Links to Side-Stream Valorization. Foods (MDPI), 15(18), 3298.
- [20] Conte, M., & Bohrer, B. M.. (2026, July 04). Effects of Red Seaweed, Psyllium Husk, and Chia Seeds on Structural and Functional Properties of Meat Batters. Foods (MDPI), 15(13), 2385.
- [21] Laird Superfood, Inc.. (2026, August 13). Laird Superfood Reports Second Quarter 2026 Financial Results. Laird Superfood, Inc. Investor Relations.
- [22] Ingredion Incorporated. (2026, July 06). Ingredion to Spotlight Next-Generation Solutions for Texture, Clean Labels and Positive Nutrition at IFT FIRST 2026. Ingredion Incorporated Newsroom.
- [23] Kerry Group plc. (2026, January 22). Balancing Flavour With Function: Kerry's 2026 Supplements Taste Charts Reveal the Winning Formula. Kerry Group plc Newsroom.
- [24] Symrise AG. (2026, April 29). Symrise Presents Health Active and Probi Portfolios at Vitafoods Europe to Deliver Science-Backed Wellness Solutions. Symrise AG Newsroom.
- [25] Laird Superfood, Inc. (2026). Laird Superfood Reports Second Quarter 2026 Financial Results. SEC Form 8-K, Exhibit 99.1. https://www.sec.gov/Archives/edgar/data/0001650696/000143774926027671/ex_996694.htm
- [26] Ingredion Incorporated. (2026). Ingredion to Showcase Clean Label, Texture and Nutrition Solutions at IFT FIRST 2026. https://www.ingredion.com/na/en-us/news-events/news/ingredion-ift-first-2026-clean-label-texture-nutrition
- [27] Symrise AG. (2026). Symrise presents Health Active and Probi portfolios at Vitafoods Europe to deliver science-backed wellness solutions. https://www.symrise.com/newsroom/article/symrise-presents-health-active-probir-portfolios-at-vitafoods-europe-to-deliver-science-backed-wellness-solutions/
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the superfood market in 2026 and what is forecast for 2036?
- Which preventive nutrition and functional beverage trends support demand for superfoods?
- Why do Superfruits & Berries lead the ingredient category globally?
- Why do Whole, Fresh & Frozen Formats lead the physical format category?
- How do growth rates differ across India, China, the United Kingdom, Brazil, Japan, and the USA?
- Which leading companies supply bulk B2B superfood ingredients versus branded consumer products?
- What microbiological, sensory, and regulatory hurdles restrain uncalibrated superfood formulations?
- What should food and supplement brands evaluate when sourcing certified organic superfood powders?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Ingredient Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Ingredient Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Ingredient Category, 2026 to 2036
- Superfruits & Berries (Blueberries, Acai, Goji, Acerola, Baobab)
- Supergreens & Leafy Vegetables (Kale, Spinach, Moringa, Matcha, Wheatgrass)
- Superseeds, Ancient Grains & Pulses (Chia, Quinoa, Hemp, Flax, Millets)
- Roots, Herbs, Functional Fungi & Microalgae (Turmeric, Maca, Ashwagandha, Reishi, Spirulina, Chlorella)
- Y-o-Y Growth Trend Analysis By Ingredient Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Ingredient Category, 2026 to 2036
- Global Market Analysis and Forecast, By Physical Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Physical Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Physical Format, 2026 to 2036
- Whole, Fresh & Frozen Formats
- Dehydrated, Freeze-Dried & Milled Powders
- Liquid Extracts, Purees & Concentrates
- Capsules, Tablets, Gummies & Stick Packs
- Y-o-Y Growth Trend Analysis By Physical Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Format, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Functional Beverages, Smoothies & RTD Drinks
- Bakery, Cereals & Healthy Snacks
- Dietary Supplements & Nutraceutical Formulations
- Dairy Alternatives & Functional Dairy
- Confectionery & Culinary Convenience Foods
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Certified Organic (USDA Organic, EU-Bio, JAS)
- Regenerative Organic Certified
- Identity-Preserved Non-GMO
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Online Retail & Direct-to-Consumer Subscriptions
- Health Food, Natural & Specialty Stores
- B2B Industrial Ingredient & Foodservice Supply
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Ingredient Category
- By Physical Format
- By Application
- By Nature
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ingredion Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Archer Daniels Midland Company
- Cargill, Incorporated
- Roquette Freres SA
- Kerry Group plc
- Symrise AG
- Givaudan SA
- Döhler GmbHLaird Superfood, Inc.
- SunOpta, Inc.
- Laird Superfood, Inc. (Navitas Organics / Terrasoul Superfoods)
- Ingredion Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Ingredient Category, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Physical Format, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Ingredient Category
- Figure 6: Global Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Physical Format
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Nature
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Ingredient Category
- Figure 32: North America Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Physical Format
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Nature
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Ingredient Category
- Figure 48: Latin America Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Physical Format
- Figure 51: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Nature
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Ingredient Category
- Figure 64: Western Europe Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Physical Format
- Figure 67: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Nature
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Ingredient Category
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Physical Format
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Ingredient Category
- Figure 96: East Asia Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Physical Format
- Figure 99: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Nature
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Ingredient Category
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Physical Format
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Ingredient Category, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Ingredient Category, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Ingredient Category
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Physical Format, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Physical Format, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Physical Format
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Superfood Market in 2026, and what is forecast for 2036?
FMI estimates that the global superfood market size stood at USD 193.8 billion in 2025 and reached USD 206.2 billion in 2026. Overall industry valuation is on track to hit USD 383.4 billion by 2036 as grocery shoppers and food processors expand daily adoption of antioxidant berries, ancient seeds, and microalgal powders.
What is the CAGR for the Superfood Market from 2026 to 2036?
The superfood sector is projected to expand at a 6.4% CAGR over the 2026 to 2036 window, generating USD 177.2 billion in incremental revenue across retail and B2B ingredient channels.
Which ingredient category segment leads the Superfood Market?
Superfruits & Berries hold an estimated 34.6% of ingredient category demand in 2026 because high anthocyanin density and natural fruit sweetness fit mainstream beverages, yogurts, and snacks.
Which physical format segment leads the Superfood Market?
Whole, Fresh & Frozen Formats represent 41.2% of the physical format category in 2026 as household consumers purchase fresh berries, frozen smoothie packs, and whole chia and quinoa seeds in weekly grocery trips.
Which country has a notable growth outlook during the assessment period?
India leads national expansion projections at an 8.7% CAGR through 2036, driven by government-backed Shree Anna millet production, domestic moringa and turmeric extraction, and urban quick-commerce supplement adoption.
Who are the key players in the market?
Ingredion Incorporated, Archer Daniels Midland Company, Cargill, Incorporated, Roquette Freres SA, Kerry Group plc, Symrise AG, Givaudan SA, Dohler GmbH, Laird Superfood, Inc., and SunOpta, Inc. lead commercial supply across B2B superfood ingredients and branded retail products.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
