

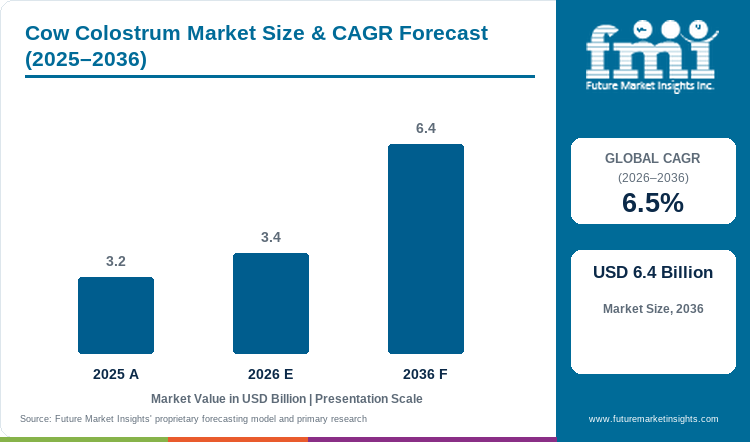
- Market Size (2026)
- USD 3.4 Bn
- Forecast (2036)
- USD 6.4 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is Cow Colostrum Market in 2026?
USD 3.4 billion in 2026 and USD 6.4 billion by 2036 at a 6.5% CAGR.
Sales of cow colostrum are projected to reach USD 3.4 billion in 2026, expanding at a CAGR of 6.5% to arrive at USD 6.4 billion by 2036. The cow colostrum market is moving through a phase where ingredient credibility is beginning to translate into mainstream commercial volume. What was once a niche supplement tied to elite sports nutrition is now drawing formulator attention across infant nutrition, immunity-focused functional foods, and clinical dietary products. The shift is being driven by accumulated clinical evidence linking bovine colostrum's bioactive compounds, particularly immunoglobulins and lactoferrin, to measurable immune and gut health outcomes. Consumers have proven more receptive to ingredient-backed immunity positioning, which is working in colostrum's favor.
Supply chain credibility remains a live constraint, with buyers scrutinizing IgG concentration, processing standards, and traceability before committing to commercial volume. Regulatory divergence across markets adds complexity, particularly where colostrum sits at the intersection of food and medicine. Powder formats and capsule delivery lead commercial adoption, while the United States is tracking well ahead of other markets in growth rate terms.
Key Takeaways of Cow Colostrum Market
- Repeatable IgG specifications are supporting demand as suppliers are converting cow colostrum into convenient supplement and functional-food formats under permitted claims.
- By nature, conventional cow colostrum is estimated to hold 87.0% of revenue in 2026. Its position is attributable to a broader qualified sourcing base for standardized commercial lots.
- By product type, colostrum finished products are forecast to represent 28.3% of category revenue in 2026. Their position is driven by channel-ready formats that reduce downstream formulation work for commercial brands.
- In 2026, B2C is expected to lead the end use category with 25.9% share. Its position is supported by direct retail channels for powders and prepared wellness formats.
- Claims review and uneven evidence quality are delaying some launch decisions because brands must reconcile ingredient specifications with permitted consumer messaging.
- Some of the key players in this market include ARMRA, Lifeway Foods, Inc., Codeage, Maolac, Immuron Limited, China Mengniu Dairy Company Limited, PanTheryx, WonderCow, Cymbiotika, and Glanbia plc.
Analyst Perspective
“Suppliers earn repeat cow colostrum business by documenting bioactive content alongside microbial safety and farm traceability. New dosage formats widen consumer reach, but every added claim and channel increases evidence and labeling work during launch qualification.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Cow Colostrum Market segmented?
The cow colostrum market is segmented by nature, product type, end use and region.
Nature includes conventional and organic while product type covers colostrum finished products, whole, chewable tablets, whole colostrum powder, capsules, skim colostrum powder, specialty colostrum powder and individual sachets. End use includes B2C, B2B, store based retail, online retailing, functional foods, sports nutrition, hypermarket/supermarket and dietary supplements.
How does conventional sourcing affect repeatable ingredient qualification within the nature category?
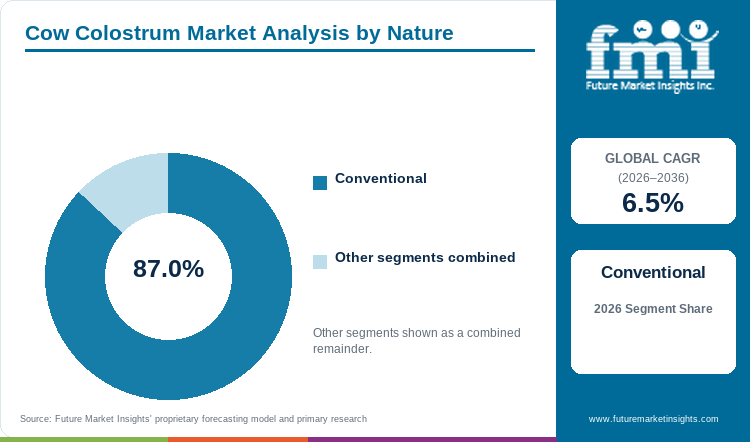
Conventional sourcing gives processors access to a broader dairy collection pool for blending raw material toward repeatable specifications. The commercial advantage comes from lot consistency and sourcing flexibility rather than any claim of superior biological performance. Glanbia’s June 2026 colostrum guidance describes integrated collection and processing controls that support traceability and repeatable ingredient specifications. Ingredient formulators are treating sourcing status as one part of a specification that also covers IgG, microbiology and traceability.
- By nature, conventional cow colostrum is estimated to hold 87.0% of category revenue in 2026. Its position is reinforced by a broader qualified sourcing base for standardized milk protein formulations during routine production planning.
- Brand owners are using repeated composition and safety documentation to qualify conventional cow colostrum ingredients for routine commercial production.
Why do finished colostrum formats reduce formulation work within the product type category?
Finished formats are shifting part of formulation and dosing work from brand owners to colostrum suppliers and contract manufacturers. Powders support flexible dosing while capsules and chewables simplify unit consumption and label instructions. Codeage currently sells grass-fed bovine colostrum in powder and capsule formats and identifies USA cGMP manufacturing for its capsule line. The current range shows how one colostrum specification can support separate consumer dosage forms without restricting the ingredient to bulk powder. Suppliers are strengthening this route by documenting compatibility and finished-product manufacturing controls alongside the colostrum specification.
- By product type, colostrum finished products are forecast to represent 28.3% of category revenue in 2026. Their position is influenced by formulators combining bovine colostrum with nutraceutical ingredients in channel-ready products.
- Finished-format suppliers are reducing separate vendor qualification steps by covering dosage form and ingredient identity within one technical file.
What makes direct consumer formats commercially important within the end use category?
B2C channels let colostrum brands explain dosage form and sourcing directly at the point of purchase. Consumer-facing claims are receiving immediate regulatory scrutiny, so convenient packaging does not compensate for weak substantiation. PanTheryx currently maintains consumer brands built around bovine colostrum and digestive-health applications for direct human nutrition use. Its consumer route shows that finished-product access still depends on upstream ingredient control during dosage-form and claim changes. Consumer brands are widening initial trial with convenient powders and other dosage formats sold through familiar wellness channels.
- In 2026, B2C is expected to lead the end use category with 25.9% share. Its position is tied to portable sports nutrition formats and familiar daily wellness purchase occasions.
- Consumer channels reward format convenience once brands can explain dose and sourcing with clear quality controls and compliant performance language.
What are the drivers, restraints and opportunities in the Cow Colostrum Market?
Consumer brands are widening cow colostrum purchase occasions, claims controls are increasing qualification work, and application support is expanding formulation routes.
- Driver: Consumer brands are introducing food and supplement formats that give bovine colostrum more purchase occasions beyond scoop-based powder routines.
- Restraint: Health-claim rules and uneven substantiation are increasing label-review work during entry into mainstream consumer channels.
- Opportunity: Distributors are pairing standardized colostrum specifications with application support to expand use in customer formulations.
Functional formats give cow colostrum more purchase occasions
Consumer brands are placing cow colostrum inside familiar nutrition routines that require less preparation than scoop-based powder products. Glanbia described continued development of its colostrum business in March 2026 within a dairy nutrition portfolio serving specialized ingredient applications. Formulators are testing bovine colostrum under the processing conditions used for functional foods and related supplements. Suppliers are supporting those trials with composition targets and handling guidance that remain consistent during scale-up. Stable specifications are widening purchase occasions without removing the technical qualification required for recurring production.
Claims controls raise the cost of commercial qualification
Cow colostrum brands are using gut and immune positioning, but consumer claims remain subject to each jurisdiction’s food or supplement rules. The UK Food Standards Agency updated its food-supplement guidance in June 2026 and states that supplements should not claim to prevent or treat medical conditions. Brands are reviewing immune health supplements against that boundary as they prepare consumer-facing copy for colostrum products. A supplier can lose a sale despite acceptable composition if the proposed message creates avoidable regulatory exposure. Detailed specifications and conservative claim support are reducing rework during packaging approval and national channel preparation.
Application support can convert standardized ingredients into new formulations
Formulators are seeking standardized colostrum ingredients that reduce repeated development work in different dosage formats. Caldic announced a partnership with Maolac in February 2026 to distribute colostrum-based ingredients in North American nutrition. The arrangement pairs concentrated biofunctional proteins with formulation and commercial support for supplement and food developers. Application teams are comparing colostrum with specialized lactoferrin and other dairy bioactives during formulation. Suppliers are shortening sample-to-order timing by providing compositional targets with sensory guidance and processing limits during pilot production. The practical opportunity lies in carrying one technical specification into several customer formulations without repeating the same validation work each time.
Which country CAGRs are profiled in the Cow Colostrum Market?
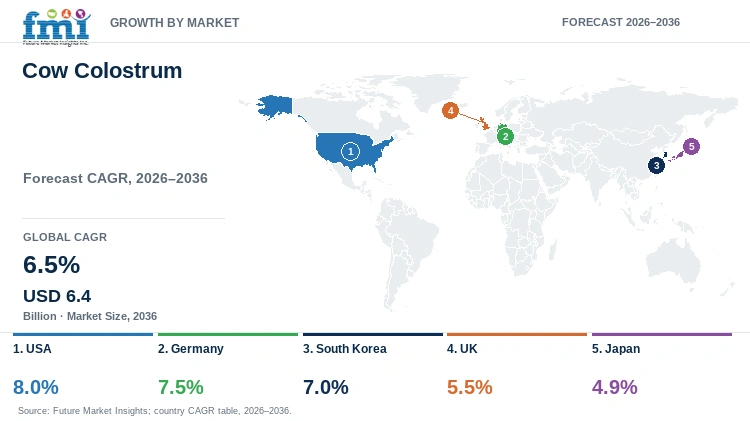
| Country | CAGR |
|---|---|
| USA | 8.0% |
| Germany | 7.5% |
| South Korea | 7.0% |
| UK | 5.5% |
| Japan | 4.9% |
How do country-level CAGRs compare in the Cow Colostrum Market?
The country forecasts form an upper group and a lower pair separated by 3.1 percentage points. The displayed spread measures forecast momentum rather than current national market size or installed consumer demand. USA, Germany and South Korea form the upper group while UK and Japan carry slower projected rates. The difference reflects national supplement-channel scale and claims requirements instead of a common pattern of current market size.
- USA pairs broad supplement participation with direct retail channels that are testing new cow colostrum formats at national scale.
- Germany requires supplement notification and disciplined food-law documentation at the start of national commercial distribution.
- South Korea gives ingredient status and health-functional-food labeling a central role in premium product positioning decisions.
- UK channels accept familiar dosage forms although consumer claims must stay within authorized health-claim language.
- Japan places scientific substantiation responsibility on business operators using the Foods with Function Claims route.
Comparable CAGRs still produce different entry conditions because national qualification rules alter the route from consumer interest to repeat orders. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- United States supplement channels give new cow colostrum formats access to a broad consumer base and multiple direct retail routes. Cow colostrum demand in USA is forecast to rise at 8.0% CAGR through 2036, supported by broad supplement use and online availability. National Center for Health Statistics data published in May 2026 found that 60.2% of adults used dietary supplements during August 2021 to August 2023. The large supplement user base gives colostrum brands an established channel for powders and prepared formats.
- Germany requires food-supplement notification ahead of commercial distribution and makes documentation part of routine market entry. Germany is estimated to post 7.5% CAGR over the forecast period, shaped by national notification and food-law controls. BVL stated in January 2025 that food supplements do not require premarket authorization but must be notified for marketing in Germany. Colostrum suppliers are preparing label information and traceable ingredient records during routine commercial launch planning. Manufacturers with complete compliance files are better positioned to serve digestive health supplements and related wellness products.
- South Korea gives health-functional-food labeling a visible role in consumer selection and regulated product communication. South Korea’s cow colostrum outlook is anticipated to advance at 7.0% CAGR over the assessment period, influenced by formal labeling and ingredient-status requirements. MFDS amended the Standards for Labeling of Health Functional Foods on September 15 2026 to improve mark distinction and reduce consumer confusion. The current framework does not list bovine colostrum as a separately approved functional ingredient under that system.
- UK supplement channels accept familiar tablets and powders but require authorized health-claim language for consumer-facing colostrum products. Cow colostrum sales in the UK are forecast to expand at 5.5% CAGR by 2036, tied to established supplement channels and strict claim review. The Department of Health and Social Care updated the Great Britain nutrition and health claims register in May 2026 and states that only authorized claims may be used. Colostrum brands are aligning product wording with the permitted national register during launch approval. National wellness channels apply the same discipline to gut barrier supplements containing colostrum ingredients.
- Japan requires business operators using the Foods with Function Claims route to submit safety and functionality information for notified products. The Japanese cow colostrum market is projected to record 4.9% CAGR during the assessment period, constrained by product-specific substantiation requirements. Consumer Affairs Agency guidance updated in October 2025 states that the government does not review efficacy in the same manner as FOSHU. Business operators remain responsible for the scientific basis and accurate display of each notified function. Cow colostrum suppliers are maintaining product-specific evidence and manufacturing records to support premium functional positioning.
Who are the notable companies in the Cow Colostrum Market?
ARMRA, Lifeway Foods, Inc., Codeage, Maolac, Immuron Limited, China Mengniu Dairy Company Limited, PanTheryx, WonderCow, Cymbiotika, and Glanbia plc are notable companies serving the defined cow colostrum market.
Competition currently spans dairy bioactive manufacturers and consumer brands using several distinct commercial routes. Ingredient suppliers are proving repeatable composition and current processing controls during finished-product qualification for commercial brands. Consumer brands are competing on dosage format and direct channel access while retaining the same underlying requirement for documented bovine colostrum quality.
- Glanbia plc and Maolac serve dairy-bioactive ingredient routes that overlap with whey protein ingredients used in nutrition formulations. China Mengniu Dairy Company Limited adds bovine colostrum within a large integrated dairy-processing platform.
- ARMRA and Codeage sell powder-based cow colostrum while WonderCow and Cymbiotika are extending the category into gummies and liquid formats.
- Lifeway Foods, Inc. uses functional-food formats while PanTheryx and Immuron Limited serve digestive-health or targeted oral-product routes with separate evidence requirements.
Competitive Benchmarking: Cow Colostrum Market
| Company | Colostrum Route Breadth | Quality & Process Documentation | Commercial Route Breadth | Geographic Reach |
|---|---|---|---|---|
| ARMRA | High | High | Medium | United States |
| Lifeway Foods, Inc. | Low | Medium | Medium | United States |
| Codeage | High | High | Medium | United States and international e-commerce |
| Maolac | High | High | High | North America, Europe and selected international markets |
| Immuron Limited | Medium | High | Medium | Australia, United States and Canada |
| China Mengniu Dairy Company Limited | Low | Medium | Medium | China |
| PanTheryx | High | Medium | High | United States and selected international channels |
| WonderCow | Medium | High | Medium | United States |
| Cymbiotika | Low | High | Medium | United States |
| Glanbia plc | High | High | High | Global |
Scoring basis: High route breadth requires at least three documented colostrum formats or application routes for the named company. Medium requires two documented routes while Low identifies one verified route within the defined cow colostrum market. High quality documentation requires public testing or controlled-processing evidence that can support routine commercial qualification decisions. Commercial breadth applies comparable thresholds to documented selling channels or end-use application routes supported by current public evidence.
Key Developments in the Cow Colostrum Market
- In April 2026, ARMRA introduced Colostrum Soda in four ready-to-drink flavors that place bovine colostrum inside a prepared beverage format.
- In December 2025, Immuron Limited executed a research agreement covering two hyper-immune bovine colostrum products for pre-clinical evaluation with United States military research partners.
- In May 2025, Codeage made available Multi Collagen Colostrum Platinum, a finished consumer powder combining bovine colostrum with lactoferrin, collagen peptides, and hyaluronic acid in a grass-fed formulation.
Key Players in the Cow Colostrum Market
Dairy Bioactive and Ingredient Platforms
- Glanbia plc
- Maolac
- China Mengniu Dairy Company Limited
- Immuron Limited
Consumer Supplement and Format Specialists
- ARMRA
- Codeage
- WonderCow
- Cymbiotika
Functional Nutrition and Digestive-Health Platforms
- Lifeway Foods, Inc.
- PanTheryx
Cow Colostrum Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By nature, product type, end use and region. |
| Quantitative Units | Revenue in USD billion and CAGR in %. |
| Market Definition | Revenue includes bovine colostrum ingredients and market-defined cow colostrum product formats sold for human nutrition within the stated segmentation universe. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | USA, Germany, South Korea, UK, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | ARMRA, Lifeway Foods, Inc., Codeage, Maolac, Immuron Limited, China Mengniu Dairy Company Limited, PanTheryx, WonderCow, Cymbiotika, and Glanbia plc. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Cow Colostrum Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Cow Colostrum Market by Segments
Cow Colostrum Market segmented by Nature:
- Conventional
- Organic
Cow Colostrum Market segmented by Product Type:
- Colostrum Finished Products
- Whole
- Chewable Tablets
- Whole Colostrum Powder
- Capsules
- Skim Colostrum Powder
- Specialty Colostrum Powder
- Individual Sachets
Cow Colostrum Market segmented by End Use:
- B2C
- B2B
- Store Based Retail
- Online Retailing
- Functional Foods
- Sports Nutrition
- Hypermarket/Supermarket
- Dietary Supplements
Cow Colostrum Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Glanbia plc. (2026, March 11). Glanbia Annual Report 2025.
- Stierman, B., Couch, C. A., Gahche, J. J., & Mishra, S. (2026, May 21). Dietary Supplement Use: United States, August 2021-August 2023. National Center for Health Statistics.
- Codeage. (2025, March 17). Experience the Fusion of Collagen and Colostrum with Multi Collagen Colostrum Powder.
- ARMRA. (2026, April 30). ARMRA Colostrum Soda: redefining the aisle.
- Lifeway Foods, Inc. (2025, August 22). Lifeway Foods Relaunches Basics Plus™ Line of Kefir and Colostrum Shots, Reviving a Functional Food Innovation 30 Years Ahead of Its Time.
- Food Standards Agency. (2026, June 25). Food supplements guidance.
- Caldic. (2026, February 19). Caldic and Maolac Partner to Bring Clinically backed colostrum based innovative Ingredients to the North American Nutrition Market.
- Bundesamt für Verbraucherschutz und Lebensmittelsicherheit. (2025, January 15). Keine Zulassung von Nahrungsergänzungsmitteln notwendig.
- Ministry of Food and Drug Safety, Republic of Korea. (2026, September 15). Amendment to Standards for Labeling of Health Functional Foods (No. 2026-66).
- Consumer Affairs Agency, Japan. (2025, October 1). Guidance for Notifications of Foods with Function Claims.
- Immuron Limited. (2026, August 28). FY26 Results Presentation.
- China Mengniu Dairy Company Limited. (2026, April 27). Annual Report 2025.
- WonderCow. (2025, December 9). Introducing the First Whole Colostrum Gummy.
- Cymbiotika. (2025, April 22). Liquid Colostrum Livestream.
- Glanbia plc. (2026, June 8). Colostrum opportunities in early life and family nutrition: Considerations for brands.
- Glanbia plc. (2026, August 26). Dairy bioactives: Where dairy expertise meets nutrition innovation.
- Department of Health and Social Care. (2026, May 19). Great Britain nutrition and health claims (NHC) register.
- Maolac. (2025, November 29). The Lemme product launch.
- Glanbia plc. (2026, March 18). Dairy innovation and consumer trends.
- Immuron Limited. (2025, December 10). Uniformed Services University to Release Topline Data.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cow colostrum market in 2026 and 2036?
- Which specifications determine whether cow colostrum converts into repeat commercial orders?
- Why does conventional sourcing hold the largest nature-category share in 2026?
- Why do finished colostrum products hold the largest product-type share in 2026?
- How do country growth rates differ among the five profiled markets?
- Which current companies serve ingredient, functional-food and consumer colostrum routes?
- Which claims and quality requirements can delay cow colostrum product qualification?
- How can application support shorten the route from ingredient sample to repeat volume?
Frequently Asked Questions
How big is the Cow Colostrum Market in 2026?
The cow colostrum market is valued at USD 3.4 billion in 2026 and is projected to reach USD 6.4 billion by 2036. Repeatable bioactive specifications and channel-ready dosage formats are supporting expansion by reducing buyer and regulatory claims friction.
What is the CAGR of the Cow Colostrum Market from 2026 to 2036?
The cow colostrum market is projected to grow at 6.5% CAGR between 2026 and 2036. Recurring orders depend on documented composition and permitted positioning that remain acceptable within the intended selling channel.
Which nature segment leads the Cow Colostrum Market?
By nature, the conventional segment is estimated to hold 87.0% of category revenue in 2026. A broader sourcing base is sustaining its position by supporting standardized commercial lots in routine production.
Which product type segment leads the Cow Colostrum Market?
By product type, colostrum finished products are forecast to represent 28.3% of category revenue in 2026. Channel-ready formats are influencing the segment by reducing formulation work for commercial brand development.
Which profiled countries record the highest Cow Colostrum Market growth?
USA is projected to grow at 8.0% CAGR through 2036, followed by Germany at 7.5% and South Korea at 7.0%. Different claims rules and channel structures are shaping the qualification work required for repeat commercial sales.
Which companies are active in the Cow Colostrum Market?
Current companies in the defined cow colostrum market include ARMRA, Lifeway Foods, Inc., Codeage, Maolac, Immuron Limited, China Mengniu Dairy Company Limited, PanTheryx, WonderCow, Cymbiotika, and Glanbia plc. Their positions span dairy bioactive manufacturing and finished consumer formats with different quality and channel requirements.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Colostrum Finished Products
- Whole
- Chewable Tablets
- Whole Colostrum Powder
- Capsules
- Skim Colostrum Powder
- Specialty Colostrum Powder
- Individual Sachets
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- B2C
- B2B
- Store Based Retail
- Online Retailing
- Functional Foods
- Sports Nutrition
- Hypermarket/Supermarket
- Dietary Supplements
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Nature
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By Product Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By Product Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By Product Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- ARMRA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Lifeway Foods, Inc.
- Codeage
- Maolac
- Immuron Limited
- China Mengniu Dairy Company Limited
- PanTheryx
- WonderCow
- Cymbiotika
- Glanbia plc
- ARMRA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


