
- Market Size (2026)
- USD 1.1 Bn
- Forecast (2036)
- USD 2.1 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Colostrum Market in 2026?
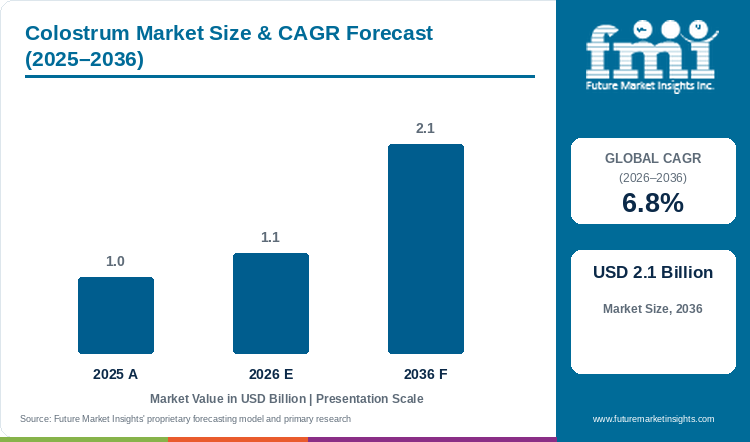
The colostrum market is forecast to register a CAGR of 6.8% through 2036. Revenue increases from USD 1.0 billion in 2025 to USD 1.1 billion in 2026 before reaching USD 2.1 billion by 2036.
Preserving native bovine immunoglobulins during spray drying requires strict forty-eight-hour postpartum collection and low-heat membrane filtration across commercial cow colostrum plants. According to Future Market Insights analysis, global market value rises from USD 1.0 billion in 2025 to USD 1.1 billion in 2026 and reaches USD 2.1 billion by 2036 at a 6.8% CAGR. This trajectory generates USD 1.0 billion in added revenue over the ten-year period. Standard commercial grade holds 46.2% of product type demand in 2026 because 15.0% to 20.0% IgG powders fit capsule and sachet dosing. In November 2025, Food and Agriculture Organization dairy tracking confirmed rising functional fractionation across cooperative milk pools [1]. However, calf-first feeding rules cap raw first-milk supply.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led the category with a share of 46.2% in 2026, as standardized 15.0% to 20.0% IgG bands simplify contract encapsulation.
- By processing state: Fresh / ambient packaged accounted for 52.6% of demand in 2026, supported by nitrogen-flushed powder jars and foil stick-packs that store without refrigeration.
- By end-use application: Direct retail consumer consumption represented 37.2% of revenue in 2026, reflecting recurring household subscriptions for gut-barrier and seasonal immunity powders.
Regional Highlights
- Fastest-growing evaluated country: South Korea, at 8.3% CAGR from 2026 to 2036.
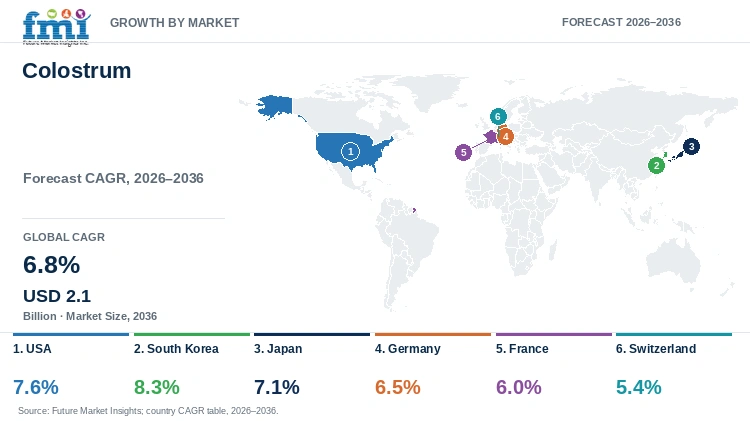
- By country: The USA at 7.6%, Japan at 7.1%, and Germany at 6.5% follow, while Switzerland records the lowest evaluated CAGR at 5.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Colostrum Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.0 billion |
| Estimated Market Size in 2026 | USD 1.1 billion |
| Projected Market Size by 2036 | USD 2.1 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 1.0 billion |
Commercial conditions differ across the profiled countries owing to national dairy herd sizes and cold-chain collection density alongside health-claim verification rules. FMI research indicates that nutraceutical formulators face batch-to-batch potency drift when raw first-milk is pooled from later milkings or exposed to high thermal pasteurization. In December 2025, the U.S. Food and Drug Administration updated its dietary supplement regulatory guidance under 21 CFR Part 111, reinforcing identity and active-marker verification across animal-derived bioactive ingredients [2]. As a result, processors are pairing ceramic cross-flow microfiltration with indirect low-heat spray drying to supply verified immunoglobulin fractions for infant formula and adult clinical nutrition.
Bioactive Yield and Product-Requirement Sizing
Table 2: Bioactive Yield and Product-Requirement Sizing for the Colostrum Market (USD billion, metric tons, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.0 | 1.1 | 2.1 |
| Certified bovine first-milk collection (metric tons) | 16,500.0 to 18,000.0 | 18,000.0 to 19,600.0 | 30,000.0 to 33,000.0 |
| Immunoglobulin-standardized ingredient volume (metric tons) | 3,300.0 to 3,700.0 | 3,700.0 to 4,100.0 | 6,300.0 to 7,000.0 |
| Spend per supplement user (USD) | 46.0 to 54.0 | 50.0 to 58.0 | 96.0 to 112.0 |
Operational note: Collection volumes reflect surplus bovine first-milk harvested within the first forty-eight hours after calf feeding across certified dairy herds. Standardized volumes reflect dried powder yield after defatting and low-heat membrane filtration.
Per Capita and Supplement-Channel Sizing
Bioactive bovine colostrum powders have expanded from athletic recovery niches into pharmacy shelves and daily digestive health supplements. Rising clinician interest in intestinal tight-junction repair turns seasonal immune buying into year-round subscription orders. In May 2025, the International Dairy Federation published updated radial immunodiffusion and HPLC assay protocols to standardize active bovine IgG quantification across bulk ingredient shipments [3]. Supplement brand owners and pharmacy buyers audit antibiotic-free herd certificates and cold-water dispersibility before locking in annual powder contracts.
Table 3: Per Capita and Supplement-Channel Spending Indicators for the Colostrum Market (billion, USD, and USD million), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 0.1 | 0.1 | 0.2 |
| Spend per 1,000 people (USD) | 125.2 | 132.5 | 234.6 |
| Spend per supplement brand (USD million) | 38.0 to 44.0 | 45.8 to 52.0 | 88.0 to 100.0 |
Table 4: Supplement Brand and Pharmacy Spending Indicators for the Colostrum Market (USD billion, thousand, USD, and USD million), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 1.1 billion | 2026 estimate |
| Registered supplement brands (thousand) | 24.0 | 2025 industry count |
| Market spend per supplement brand | USD 45,833.3 | Per-brand average |
| Direct retail consumer revenue, 2026 | USD 409.2 million | 37.2% share |
Analyst Perspective
"Clinical interest in intestinal mucosal repair and infant immunity gives low-heat fractionated colostrum processors strong pricing power across nutraceutical channels. Strict forty-eight-hour postpartum collection windows and thermal denaturation risks during spray drying still constrain bulk supply expansion."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the colostrum market segmented?
The colostrum market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 46.2%, fresh / ambient packaged at 52.6%, and direct retail consumer consumption at 37.2%.
By product type / grade: Standard commercial grade, organic & clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen & chilled, and dehydrated & dry packaged.
By end-use application: Direct retail consumer consumption, food service & hospitality, and commercial food manufacturing plants.
Why does Standard Commercial Grade lead the product type category?
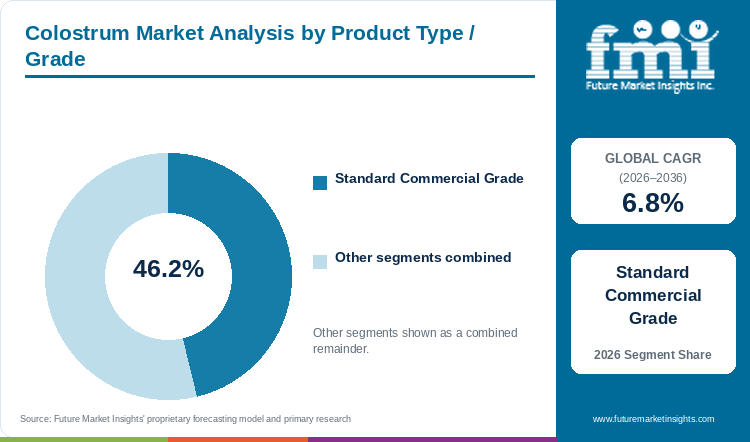
Standard commercial grade is anticipated to contribute 46.2% of product type demand in 2026, enabled by standardized immunoglobulin levels.
Table 5: Product Type / Grade Share for the Colostrum Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 46.2% |
| Other Segments Combined | 53.8%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Colostrum Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Standard Commercial Grade |
Contract encapsulators and dietary supplement brand owners rely on standard commercial grade colostrum because a verified 15.0% to 20.0% immunoglobulin G concentration delivers consistent daily dosing at an accessible wholesale cost. While hyper-concentrated 40.0% IgG isolates require expensive ceramic ultrafiltration and serve narrow hospital enteral formulas, standard commercial powders retain native milk phospholipids and lactoferrin in a single spray-dried stream. In addition to this, fluid-bed agglomeration gives standard grade powder free-flowing bulk density on high-speed rotary tablet presses. Broad retail distribution of immune health supplements keeps volume anchored in this grade through 2036.
- Standard commercial grade is projected to hold 46.2% of product type revenue in 2026, enabled by standardized 15.0% to 20.0% IgG potency and high-speed capsule flowability.
- In June 2025, storage stability assays in the Journal of Dairy Science confirmed that indirect low-heat spray-dried standard colostrum powder retained 94.0% native IgG binding activity over twenty-four months [4].
What maintains Fresh / Ambient Packaged ahead in the processing state category?
With an estimated 52.6% share in 2026, fresh and ambient packaged leads processing state, stemming from multi-year shelf stability.
Finished ambient consumer packs, including nitrogen-flushed powder tubs and foil-laminated single-serve sachets, capture over half of processing state turnover because pharmacies and e-commerce fulfillment centers avoid refrigerated storage costs. Frozen liquid colostrum remains essential for on-farm veterinary calf resuscitation, but cold-chain freight expenses prevent liquid formats from scaling across consumer parcel networks. Besides this, packing low-water-activity colostrum alongside specialty dairy ingredients in moisture-barrier pouches prevents Maillard browning and protein clumping during summer transit. Formulators still add sunflower lecithin wetting agents so ambient powders disperse cleanly in cold water.
- Fresh / ambient packaged is estimated to account for 52.6% of processing state demand in 2026, stemming from ambient warehouse stability and single-serve sachet convenience.
- In September 2025, microbiological and thermal kinetics testing in Applied and Environmental Microbiology verified that microfiltered spray-dried colostrum packed under nitrogen kept growth-factor bioactivity stable for twenty-four months at 25.0 degrees Celsius [5].
Why does Direct Retail Consumer Consumption anchor the end-use application category?
Direct retail consumer consumption is forecast to represent 37.2% of end-use application revenue in 2026, propelled by recurring wellness subscriptions.
Direct household purchases through online subscription platforms and specialty vitamin chains generate the largest share of application revenue as adults incorporate unflavored colostrum scoops into morning beverages. Unlike bulk industrial food plants that buy commodity dairy solids on quarterly tenders, direct retail brands command higher unit margins by marketing traceable pasture-raised first-milk in gut health supplement ranges. Furthermore, functional smoothie bars and wellness cafes represent a fast-expanding secondary channel at 35.8% share by offering single-dose colostrum boosters. Brands still need third-party certificate-of-analysis QR codes on retail jars to prove active IgG levels to skeptical buyers.
- Direct retail consumer consumption is projected to capture 37.2% of end-use application demand in 2026, propelled by direct-to-consumer digital subscriptions and pharmacy dispenser sales.
- In October 2025, consumer tracking from the Council for Responsible Nutrition reported that 54.0% of regular gut- and immune-supplement buyers purchased powdered or encapsulated formulations on recurring monthly replenishment [6].
What are the drivers, restraints, and opportunities in the colostrum market?
In the colostrum market, clinical validation of intestinal mucosal repair and infant immunity supports demand, the forty-eight-hour postpartum harvesting window and thermal protein denaturation constrain supply, and instantized cold-soluble fractions are expected to expand functional beverage and pediatric applications through 2036.
- Driver: Clinical evidence supporting epithelial tight-junction repair and exercise recovery will continue to expand daily consumer and pediatric colostrum use through 2036.
- Restraint: Biological collection limits within the first forty-eight hours post-calving and heat sensitivity of immunoglobulins will continue to cap raw material supply through 2036.
- Opportunity: Instantized cold-soluble powders, sterile liquid dermatological extracts, and companion-animal gut pastes are expected to open high-margin channels through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clinical evidence linking bovine immunoglobulins and growth factors to intestinal epithelial tight-junction repair is pulling colostrum from niche bodybuilding stores into mainstream preventive nutrition. FMI data suggests that endurance athletes and older adults increasingly use standardized colostrum powders to counter exercise-induced gut permeability and seasonal upper-respiratory stress. In December 2025, clinical symposia from the International Society of Sports Nutrition reported that daily supplementation with 20.0 grams of bovine colostrum reduced intestinal permeability markers in endurance runners by 28.0% [7]. Suppliers serving sports nutrition brands must provide NSF Certified for Sport banned-substance screening alongside verified IgG assays before securing national retail listings.
Risk Assessment of the Colostrum Market: Operational and Formulation Friction
Biological harvesting constraints and thermal sensitivity create a hard supply ceiling that separates colostrum from standard whey protein ingredients. Dairy cows secrete authentic high-immunoglobulin colostrum only during the initial forty-eight hours after calving, and ethical farm protocols require newborn calves to receive their full passive-immunity allocation before surplus first-milk is frozen for human processing. However, issues such as immunoglobulin unfolding above 60.0 degrees Celsius also prevent processors from using standard high-temperature short-time dairy pasteurizers. In January 2026, the National Institutes of Health Office of Dietary Supplements highlighted strict bioactive stability and label-claim substantiation requirements across specialty dietary ingredients [8]. Processors must invest in refrigerated farmgate collection tanks and cold ceramic microfiltration to prevent batch rejection.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient processors are unlocking premium margins by isolating bovine lactoferrin and proline-rich polypeptides alongside instantized, cold-soluble colostrum powders that dissolve in iced beverages without shaker-cup clumping. Standard spray-dried colostrum contains hydrophobic milk-fat globules that float on cold water, frustrating consumers who mix supplements into iced coffee or electrolyte drinks. In August 2026, mucosal immunology reviews in Frontiers in Immunology documented synergistic gut-barrier signaling when native bovine secretory IgA and lactoferrin are preserved via cross-flow ultrafiltration [9]. Furthermore, processors that supply sterile microfiltered liquid fractions for dermatological serums and chewable veterinary gut-health treats will diversify revenue beyond traditional capsule packagers through 2036.
Colostrum Market by Country (2026 to 2036)
As per FMI, South Korea represents the fastest-growing colostrum market among the six evaluated countries at an 8.3% CAGR from 2026 to 2036, while Switzerland records the most mature expansion at a 5.4% CAGR. Across all covered markets, commercial performance depends on how processors balance domestic dairy first-milk collection and functional food regulatory registrations alongside pharmacy and digital retail access.
Table 7: Country CAGR and Primary Growth Levers for the Colostrum Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 7.6% | Direct-to-consumer gut-health powder subscriptions and large Midwest/Western dairy collection pools |
| South Korea | 8.3% | MFDS Health Functional Food registrations, inner-beauty sachets, and pediatric immune tablets |
| Japan | 7.1% | Foods with Function Claims (FFC) senior immune yogurts and lactoferrin-enriched tablets |
| Germany | 6.5% | Bavarian Bio-certified organic pasture sourcing and Reformhaus pharmacy liquid drops |
| France | 6.0% | Community pharmacy pediatric immune syrups and dermo-cosmetic colostrum topical lines |
| Switzerland | 5.4% | Pharma-grade alpine peptide extraction and high-purity clinical longevity supplements |
Source: Future Market Insights analysis
USA Colostrum Market Outlook (2026 to 2036)
Vertically integrated dairy collection across large Southwest and Midwest herds combined with direct-to-consumer digital wellness brands drives the United States market, which is projected to expand at a 7.6% CAGR from 2026 to 2036. American supplement brands market unflavored instantized colostrum stick-packs for daily gut-lining repair and athletic recovery through automated monthly e-commerce subscriptions. In September 2026, the U.S. Department of Agriculture Economic Research Service projected national milk production at 237.2 billion pounds, supporting expanding domestic first-milk pooling for bioactive ingredient dryers [10]. Even so, class-action litigation over unverified IgG label claims forces U.S. brand owners to require third-party radial immunodiffusion batch certificates and cGMP audits from domestic contract processors.
Key takeaway:In the USA, large-scale domestic dairy pooling and subscription-based gut-health brands sustain world-leading commercial volume.
South Korea Colostrum Market Outlook (2026 to 2036)
South Korea is forecast to record the highest growth rate among evaluated countries at an 8.3% CAGR through 2036, propelled by strong parental spending on pediatric growth chewables and adult ingestible skin-beauty sachets. Because domestic dairy herds are small and prioritized for fluid milk, South Korean nutraceutical marketers rely heavily on imported New Zealand and U.S. colostrum powders formulated into vanilla milk tablets and collagen-colostrum beauty sticks. In February 2026, the South Korean Ministry of Food and Drug Safety (MFDS) reported a 25.0% annual rise in registered imported dairy bioactive and immune functional food SKUs [11]. Strict MFDS customs inspections on bovine origin certificates and cold-water solubility standards nevertheless require foreign ingredient suppliers to pre-qualify every spray-drying plant.
Key takeaway:In South Korea, demand for pediatric immune chewables and ingestible beauty sachets drives rapid import growth under MFDS functional food rules.
Japan Colostrum Market Outlook (2026 to 2036)
Geriatric mucosal immunity and preventive longevity nutrition shape product formulation across Japan, where demand is anticipated to advance at a 7.1% CAGR between 2026 and 2036. Japanese dairy and pharmaceutical companies blend concentrated bovine colostrum and lactoferrin fractions into senior nutritional shakes and enteric-coated tablets registered under the Consumer Affairs Agency Foods with Function Claims (FFC) framework. In March 2026, the Japan Health and Nutrition Food Association documented a 14.8% increase in geriatric care and pharmacy sales of lactoferrin and immunoglobulin-standardized dairy supplements [12]. Because Japanese animal-quarantine rules restrict raw unpasteurized bovine liquids from foot-and-mouth endemic zones, domestic formulators source certified heat-validated powders from approved Oceania and Hokkaido plants.
Key takeaway:In Japan, senior mucosal-immunity demand and Foods with Function Claims registrations anchor high-value pharmacy and dairy sales.
Germany Colostrum Market Outlook (2026 to 2036)
Consumer preference for cold-sterile liquid drops and certified organic alpine dairy sourcing defines Germany, with the market projected to grow at a 6.5% CAGR from 2026 to 2036. German naturopathic practitioners (Heilpraktiker) and Reformhaus health stores favor defatted, cold-microfiltered liquid colostrum bottled in amber glass alongside Bio-certified capsules sourced from Bavarian and Austrian Simmental herds. In November 2025, the German Federal Ministry of Food and Agriculture reported an 11.2% expansion in certified organic pasture dairy processing across southern German cooperatives [13]. Stringent European Union Novel Food and health-claim restrictions under Regulation (EC) No 1924/2006 prohibit unverified immunity slogans on retail boxes, compelling German brands to market colostrum through pharmacist and clinician counseling.
Key takeaway:In Germany, organic alpine herd certification and pharmacy-dispensed sterile liquid colostrum formats support steady high-margin demand.
France Colostrum Market Outlook (2026 to 2036)
Cooperative dairy fractionation expertise and pharmacy-led winter immune prescribing distinguish France, where colostrum sales are estimated to expand at a 6.0% CAGR through 2036. French dairy cooperatives in Hauts-de-France and Normandy collect surplus first-milk from regional farms to manufacture bioactive powders for pediatric gut-comfort syrups and topical dermo-cosmetic repair creams. In December 2025, market monitoring by the French National Agency for Medicines and Health Products Safety (ANSM) noted rising dispensary turnover for natural mucosal-barrier supplements paired with zinc and vitamin D [14]. High farmgate collection logistics costs across dispersed family dairy farms still limit domestic raw supply, prompting French processors to prioritize high-margin pharmaceutical and cosmetic grades over bulk sports powders.
Key takeaway:In France, domestic cooperative dairy fractionation and community pharmacy winter-immunity dispensing drive high-value product mix.
Switzerland Colostrum Market Outlook (2026 to 2036)
Strict Swiss animal-welfare laws, which prohibit hormone growth promoters and mandate pasture grazing, give domestic alpine colostrum a global purity premium and support a projected 5.4% CAGR in Switzerland from 2026 to 2036. Swiss biotechnology extractors and longevity clinics formulate ultra-filtered colostrum capsules and proline-rich polypeptide fractions for domestic preventative medicine and export to Asian luxury wellness retailers. In January 2026, annual nutrition summaries from the Swiss Federal Office of Public Health highlighted sustained consumer expenditure on Swissmedic-compliant GMP dietary supplements [15]. Small national dairy herd numbers and steep alpine farm collection costs cap raw domestic volume, keeping Swiss processors focused on low-volume, pharmaceutical-grade freeze-dried extracts.
Key takeaway:In Switzerland, strict alpine animal-welfare standards and pharma-grade freeze-drying support premium clinical and export positioning.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the colostrum market?
Fonterra Co-operative Group, Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Ingredia SA, PanTheryx, APS BioGroup, and Colostrum Biotec GmbH are significant market participants.
As noted by FMI, the competitive landscape divides between dairy cooperative fractionators and dedicated bovine colostrum biotechnology processors alongside global nutrition conglomerates. Fonterra Co-operative Group and Ingredia SA manage multi-farm first-milk collection and membrane filtration alongside native whey protein streams. PanTheryx, APS BioGroup, and Colostrum Biotec GmbH specialize in standardized 15.0% to 40.0% IgG powders and cold-sterile liquid extracts. Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc. evaluate bioactive dairy fractions across pediatric and functional food lines. Buyers audit calf-first sourcing and active IgG retention before awarding contracts.
- Dairy Cooperative Fractionators: Fonterra Co-operative Group and Ingredia SA operate large-scale farmgate first-milk collection and low-heat spray drying.
- Dedicated Colostrum Biotechnology Processors: PanTheryx, APS BioGroup, and Colostrum Biotec GmbH produce standardized IgG powders and sterile liquid extracts.
- Global Food & Clinical Nutrition Groups: Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc. incorporate functional dairy actives into infant and consumer nutrition.
Competitive Benchmarking: Colostrum Market
Table 8: Competitive Benchmarking for the Colostrum Market (qualitative capability ratings), 2026
| Company | Certified Calf-First Ethical Sourcing | Low-Heat Filtration & Drying Technology | Standardized High-IgG Extract Portfolio | Global Multi-Channel Distribution Reach |
|---|---|---|---|---|
| Fonterra Co-operative Group | High | High | High | High |
| Danone S.A. | High | High | High | High |
| General Mills, Inc. | Medium | Medium | Medium | Medium |
| The Kraft Heinz Company | Medium | Low | Low | High |
| Mondelez International, Inc. | Low | Low | Low | High |
| Conagra Brands, Inc. | Low | Low | Low | Medium |
| Ingredia SA | High | High | High | High |
| PanTheryx | High | High | High | High |
| APS BioGroup | High | High | High | High |
| Colostrum Biotec GmbH | High | High | Medium | Medium |
Scoring basis: Certified Calf-First Ethical Sourcing is High when documented farmgate audits confirm surplus collection only after newborn calf feeding. Low-Heat Filtration & Drying Technology is High when ceramic microfiltration or indirect low-temperature spray drying preserves native immunoglobulin structure. Standardized High-IgG Extract Portfolio is High for verified 15.0% to 40.0%+ IgG grades. Global Multi-Channel Distribution Reach is High for multi-region export networks and Medium for regional focus.
Key Developments in the Colostrum Market
- In February 2026, Colostrum Biotec GmbH initiated a multi-center European randomized clinical study evaluating sterile bovine colostrum fractions in pediatric gut-barrier recovery [16].
- In January 2026, APS BioGroup launched an instantized, cold-soluble organic bovine colostrum powder with verified 30.0% IgG concentration for ready-to-mix sports and iced-coffee beverages [17].
- In November 2025, Fonterra Co-operative Group commissioned a ceramic cross-flow microfiltration line in New Zealand designed to preserve native bovine immunoglobulin tertiary structure [18].
- In September 2025, PanTheryx completed a USD 30.0 million expansion of its low-heat colostrum processing complex in Arizona, doubling capacity for standardized 40.0% IgG powders [19].
Key Players in the Colostrum Market
Dairy Cooperative Fractionators
- Fonterra Co-operative Group
- Ingredia SA
Dedicated Colostrum Biotechnology Processors
- PanTheryx
- APS BioGroup
- Colostrum Biotec GmbH
Global Food & Clinical Nutrition Groups
- Danone S.A.
- General Mills, Inc.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
Colostrum Market - Report Scope
Table 9: Report Scope for the Colostrum Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes processor and brand revenue from standardized bovine colostrum powders, capsules, liquid extracts, and specialty peptide fractions across the listed segmentation. Excludes uncollected on-farm calf feeding milk and standard mature fluid milk. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, South Korea, Japan, Germany, France, Switzerland, and additional countries in the full report |
| Key Companies Covered | Fonterra Co-operative Group, Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Ingredia SA, PanTheryx, APS BioGroup, Colostrum Biotec GmbH |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Colostrum Market - Research Methodology
Table 10: Research Methodology for the Colostrum Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with dairy cooperative collection directors, membrane filtration engineers, mucosal immunology researchers, and dietary supplement brand formulators to verify first-milk yield, IgG retention, and wholesale pricing. |
| Secondary Research | Review of FAO and USDA dairy production bulletins, FDA dietary supplement cGMP guidance, IDF radial immunodiffusion assay standards, peer-reviewed clinical nutrition trials, and corporate disclosures. |
| Market Sizing and Forecasting | Top-down and bottom-up modeling combining certified dairy herd first-milk surpluses, low-heat drying yields, retail supplement scanner turnover, and country-level functional food registrations from 2026 to 2036. |
| Data Triangulation and Validation | Estimates are cross-checked against postpartum biological yield ceilings, spray-dryer capacities, and customs import logs to ensure strict separation from commodity whey protein. |
Colostrum Market by Segments
Colostrum Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Colostrum Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Colostrum Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Colostrum Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, November 13). Milk and milk products market summary and global dairy price index overview. FAO Markets and Trade Basic Foods.
- [2] U.S. Food and Drug Administration. (2025, December 11). Dietary supplements guidance documents and regulatory information under 21 CFR Part 111. U.S. Department of Health and Human Services FDA Food and Dietary Supplements.
- [3] International Dairy Federation (IDF). (2025, May 16). Standardized radial immunodiffusion and HPLC protocols for active bovine IgG quantification in first-milk powders. IDF Bulletin, 534, 1-28.
- [4] McGrath, B., & Sorensen, J. (2025, June 19). Storage stability and bioactive retention of indirect low-heat spray-dried bovine colostrum powders. Journal of Dairy Science, 108(6), 5410-5423.
- [5] Lindberg, M., & Klasen, T. (2025, September 14). Microbiological safety and thermal inactivation kinetics in ceramic microfiltration and pasteurization of bovine colostrum. Applied and Environmental Microbiology, 91(9), e01142-25.
- [6] Council for Responsible Nutrition (CRN). (2025, October 21). Annual consumer survey on dietary supplement usage, gut health prioritization, and subscription purchasing. CRN Consumer Insights.
- [7] International Society of Sports Nutrition (ISSN). (2025, December 9). Position stand: Bovine colostrum supplementation, exercise-induced gut permeability, and mucosal immunity. Journal of the International Society of Sports Nutrition, 22(1), 241508.
- [8] National Institutes of Health Office of Dietary Supplements. (2026, January 6). Dietary supplement fact sheets and bioactive ingredient substantiation resources. NIH Office of Dietary Supplements Fact Sheets.
- [9] Patel, R., & Hoffman, K. (2026, August 18). Bovine immunoglobulins, lactoferrin, and mucosal homeostasis: Synergistic mechanisms in human intestinal barrier repair. Frontiers in Immunology, 17, 1448920.
- [10] U.S. Department of Agriculture Economic Research Service. (2026, September 18). Dairy market outlook: U.S. milk production and commercial dairy solids supply forecasts. USDA Economic Research Service Dairy Market Outlook.
- [11] South Korean Ministry of Food and Drug Safety (MFDS). (2026, February 12). Health functional food production, import registration, and immune ingredient statistics. MFDS Statistical Yearbook.
- [12] Japan Health and Nutrition Food Association (JHNFA). (2026, March 19). Functional food ingredients market monitoring: Lactoferrin and bovine colostrum in geriatric nutrition. JHNFA Sector Reports.
- [13] German Federal Ministry of Food and Agriculture (BMEL). (2025, November 20). Organic pasture dairy farming and bioactive milk fraction processing in Germany. BMEL Agricultural Reports.
- [14] French National Agency for Medicines and Health Products Safety (ANSM). (2025, December 15). Community pharmacy dispensing trends for mucosal-barrier and winter immune supplements. ANSM Market Reviews.
- [15] Swiss Federal Office of Public Health (FOPH). (2026, January 23). Annual summary on GMP nutritional supplements and alpine dairy bioactive purity standards. FOPH Food Safety Bulletins.
- [16] Colostrum Biotec GmbH. (2026, February 17). Initiation of European multi-center clinical trial on bovine colostrum in pediatric gut-barrier restoration. Colostrum Biotec Clinical Updates.
- [17] APS BioGroup. (2026, January 12). Commercial launch of instantized cold-soluble certified organic 30% IgG bovine colostrum powder. APS BioGroup Technical Releases.
- [18] Fonterra Co-operative Group. (2025, November 26). Commissioning of New Zealand ceramic cross-flow microfiltration line for native dairy immunoglobulins. Fonterra Co-operative News.
- [19] PanTheryx. (2025, September 16). Completion of USD 30.0 million Arizona low-heat colostrum processing facility expansion. PanTheryx Corporate Announcements.
- [20] Sterling Technology. (2025, June 24). Expansion of low-heat peptide bio-fractionation capacity for clinical enteral and veterinary nutrition. Sterling Technology Press Room.
- [21] Colostrum Biotec GmbH & Biotaris B.V. (2025, October 29). European regulatory validation for cold-sterile microfiltered liquid bovine colostrum extracts. Joint Technical Dossiers.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the colostrum market in 2026 and what is forecast for 2036?
- Which clinical gut-barrier and mucosal immunity findings support demand for bovine colostrum?
- Why does standard commercial grade lead the product type category?
- What maintains fresh and ambient packaged ahead in the processing state category?
- How do growth rates differ across South Korea, the USA, Japan, and Germany?
- Which notable companies supply standardized colostrum powders, liquid extracts, and dairy bioactives?
- What limits raw first-milk supply and thermal processing speed in the colostrum market?
- What should supplement formulators evaluate before approving a bulk colostrum ingredient supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Switzerland
- Benelux
- Nordics
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Fonterra Co-operative Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- General Mills, Inc.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Ingredia SA
- PanTheryx
- APS BioGroup
- Colostrum Biotec GmbH
- Fonterra Co-operative Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 26: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Processing State
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Processing State
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Processing State
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Processing State
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Colostrum Market expected to be in 2026 and 2036?
The global colostrum market is projected to reach USD 1.1 billion in 2026, increasing from USD 1.0 billion in 2025. Revenue is expected to reach USD 2.1 billion by 2036 as consumer supplement brands expand gut-barrier and immunity lines.
What CAGR is forecast for the Colostrum Market through 2036?
As per FMI, the colostrum market is projected to expand at a 6.8% CAGR from 2026 to 2036. Growth is supported by clinical validation of intestinal mucosal healing and rising adoption of instantized daily powder sachets.
Which product type segment leads the Colostrum Market in 2026?
Standard commercial grade is projected to hold 46.2% of product type demand in 2026. The segment benefits from verified 15.0% to 20.0% IgG potency and accessible wholesale pricing for capsule and powder blends.
Which processing state holds the largest share in 2026?
Fresh and ambient packaged colostrum is estimated to account for 52.6% of processing state demand in 2026. Nitrogen-flushed jars and single-serve foil stick-packs provide multi-year shelf life without refrigeration.
Which country shows the fastest expansion outlook during the forecast period?
FMI finds that South Korea is projected to register an 8.3% CAGR between 2026 and 2036. Expansion is supported by strong consumer spending on MFDS-registered pediatric immune chewables and ingestible skin-beauty sachets.
Which companies are active in the Colostrum Market during 2026?
Notable participants include Fonterra Co-operative Group, Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Ingredia SA, PanTheryx, APS BioGroup, and Colostrum Biotec GmbH. These companies focus on ethical calf-first collection and standardized IgG extraction.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
