
- Market Size (2026)
- USD 207.0 Mn
- Forecast (2036)
- USD 289.2 Mn
- CAGR (2026 to 2036)
- 3.4%
How big is Cryoboxes Market in 2026?
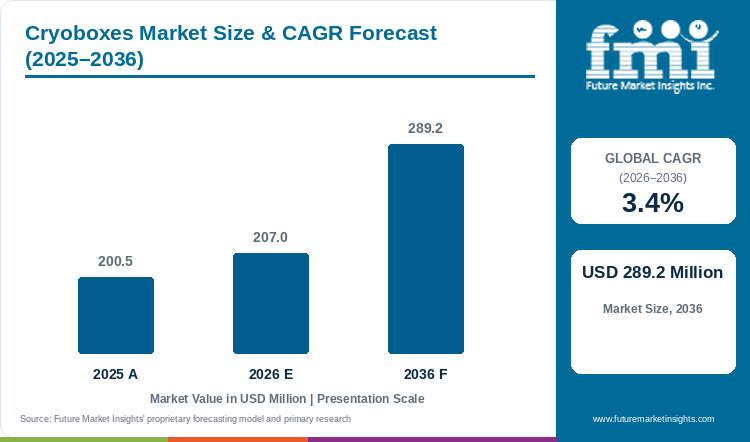
With a valuation of USD 200.5 million in 2025 and moving to USD 207.0 million in 2026, the cryoboxes market is positioned to attain USD 289.2 million by 2036, exhibiting a CAGR of 3.4%.
Hospital biobanks and oncology research centers are packing more patient samples into every freezer rack, driving steady orders for standardized high-density cryoboxes. The global cryoboxes market was valued at USD 200.5 million in 2025 and is estimated to reach USD 207.0 million in 2026. Industry valuation is projected to reach USD 289.2 million by 2036, expanding at a compound annual growth rate (CAGR) of 3.4% between 2026 and 2036. Polycarbonate transparent cryoboxes capture 47.4% of 2026 material formulation demand because clear lids let lab staff verify cryogenic vials at a glance without keeping freezer doors open. Per a December 2024 oncology biobanking study in Cancer Communications, researchers achieved a 95.2% organoid culture success rate from 42 frozen tumor tissues stored in cryoboxes across minus 80 degrees Celsius and liquid nitrogen tanks. Cold-storage vendors are pairing automated nitrogen tanks with barcoded boxes, with Cornell Veterinary Biobank documenting 21-day power-free hold times in Azenta CryoArc stores. Evidence compiled by FMI suggests that repeated washing and autoclaving of rigid plastic boxes in university labs remains the main factor moderating annual replacement volume through 2036.
Key Market Trends & Insights
- By material formulation: Polycarbonate Transparent Cryoboxes hold an estimated 47.4% share in 2026 because high-impact polymer walls resist cracking in liquid nitrogen vapor phase storage.
- By grid array capacity: The 81-Place 9x9 Array represents 51.1% in 2026 as standard 1.5 and 2.0 milliliter external-thread cryovials fit standard 133 by 133 millimeter freezer racks.
- By temperature rating: Ultra-Low Temperature -80C Freezer grades account for 71.5% in 2026 because mechanical upright chest freezers house the majority of hospital and academic biospecimens.
- By end-user facility: Biobanks and Biorepositories secure 58.6% in 2026 owing to multi-million-sample national population cohorts and longitudinal oncology tissue archiving.
- By lid closure and indexing: Alphanumeric Laser-Coded Friction Lids command 53.2% in 2026 through high-contrast permanent grid coordinates that prevent manual pipetting and retrieval mix-ups.
Regional Highlights
- Top national expansion: The United States leads national growth projections at a 3.9% CAGR through 2036 under federal precision-medicine biobanking and cell therapy repository buildouts.
- Broader country progression: Mexico tracks at a 3.8% CAGR ahead of the United Kingdom at 3.6% and Poland at 3.5%, whereas Canada advances at a 2.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Cryoboxes Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 200.5 million |
| Estimated Market Size in 2026 | USD 207.0 million |
| Projected Market Size by 2036 | USD 289.2 million |
| CAGR, 2026 to 2036 | 3.4% |
| Added Value, 2026 to 2036 | USD 82.2 million |
Stem-cell transplant clinics and biopharmaceutical cell banks face strict quality audits when frozen patient grafts sit in sub-zero storage for several years. When poorly vented or warped boxes trap frost around tube caps, uneven warming during rack pullouts lowers post-thaw cell survival. A October 2025 clinical study in Cancers tracked 72 frozen stem-cell products stored at minus 80 degrees Celsius for a median of 868 days and confirmed 94.8% post-thaw cell viability when kept in standardized freezer racks. That clinical reliability pushes repository managers to replace basic cardboard sleeves with vented polycarbonate and polypropylene cryogenic boxes that keep cold air flowing evenly.
Installed Freezer Rack Capacity and Cryobox Unit Sizing
Table 2: Installed Freezer Rack Capacity and Cryobox Unit Sizing for the Cryoboxes Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 200.5 | 207.0 | 289.2 |
| Annual commercial cryobox shipments (million units) | 68.0 to 75.0 | 70.2 to 77.5 | 96.0 to 106.0 |
| Archived cryovials housed in new boxes (billion vials) | 5.4 to 6.0 | 5.6 to 6.2 | 7.8 to 8.6 |
| Average manufacturer realization per cryobox (USD) | 2.67 to 2.95 | 2.68 to 2.96 | 2.73 to 3.01 |
Operational note: Unit shipment and archived vial ranges apply standard 133 by 133 millimeter 81-place and 100-place footprint boxes across polycarbonate, polypropylene, and moisture-resistant cardboard formats.
High-volume immunology and blood-processing labs need cryoboxes that move directly from minus 80 degrees Celsius mechanical freezers into vapor-phase liquid nitrogen tanks without cracking. Per a November 2025 hematology study in the International Journal of Laboratory Hematology, electromagnetic-field freezing cut white blood cell pre-cooling time from 3.0 hours to 0.25 hours before liquid nitrogen transfer. Faster freezing throughput increases daily batch turnover in ultra-low temperature freezers and drives lab buyers to order slotted drainage cryoboxes that shed liquid nitrogen safely.
Per Capita & Biorepository Facility Indicators
Table 3: Per Capita and Biorepository Facility Indicators for the Cryoboxes Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 24.5 | 24.9 | 32.1 |
| Annual cryobox outlay per major biobank facility (USD thousand) | 18.5 to 22.0 | 19.1 to 22.8 | 25.4 to 30.2 |
| 2D-barcoded and laser-indexed polymer box share (%) | 54.0% to 58.0% | 56.0% to 60.0% | 72.0% to 77.0% |
Table 4: Biorepository Facility & Channel Indicators for the Cryoboxes Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 207.0 million | 2026 global valuation baseline |
| Active biobanks, cell banks & clinical repositories global | 10,200 facilities | Academic, hospital, pharma & national biobanks |
| Market value per repository facility | USD 20,294.1 | Annualized cryobox consumable procurement |
| Biobanks and Biorepositories segment value, 2026 | USD 121.3 million | 58.6% end-user facility allocation |
National health surveys and multi-year clinical trials store blood and serum samples for decades, creating consistent demand for durable polymer cryoboxes that resist cracking at minus 196 degrees Celsius. Per a June 2026 Centers for Disease Control and Prevention study in Biopreservation and Biobanking, pristine serum aliquots kept in vapor-phase liquid nitrogen tanks between minus 140 and minus 196 degrees Celsius recorded zero container failures across 20 years of storage. Biobank directors expanding cryogenic vials and tubes collections therefore specify keyed-corner polycarbonate boxes with laser-etched grids so sample locations stay readable for decades.
Analyst Perspective
"Biobank directors no longer view cryoboxes as disposable cardboard cartons; they procure precision-molded storage arrays that govern freezer rack density and robotic camera readability. Consumable manufacturers that combine autoclavable polycarbonate or polypropylene durability with laser-etched alphanumeric and 2D-barcode indexing will lock in recurring repository supply agreements through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the cryoboxes market segmented?
The cryoboxes market is segmented by material formulation and grid array capacity, temperature rating, end-user facility and lid closure and indexing. In 2026, Polycarbonate Transparent Cryoboxes are projected at 47.4% and 81-Place 9x9 Array at 51.1% and Ultra-Low Temperature -80C Freezer at 71.5%, Biobanks and Biorepositories at 58.6% and Alphanumeric Laser-Coded Friction Lids at 53.2%.
By material formulation: Polycarbonate Transparent Cryoboxes, Polypropylene Autoclavable Cryoboxes, and Waterproof Moisture-Resistant Cardboard.
By grid array capacity: 81-Place 9x9 Array, 100-Place 10x10 Array, and 25-Place 5x5 Compact Array.
By temperature rating: Ultra-Low Temperature -80C Freezer and Liquid Nitrogen Vapor Phase -196C Cryogenic.
By end-user facility: Biobanks and Biorepositories, Academic and Clinical Research Labs, and Pharmaceutical and Biotech Companies.
By lid closure and indexing: Alphanumeric Laser-Coded Friction Lids, Hinged Attached-Lid Cryoboxes, 2D Barcode Bottom-Indexed Cryoboxes and Color-Coded Keyed-Corner Lids.
Why do Polycarbonate Transparent Cryoboxes lead the material formulation category?
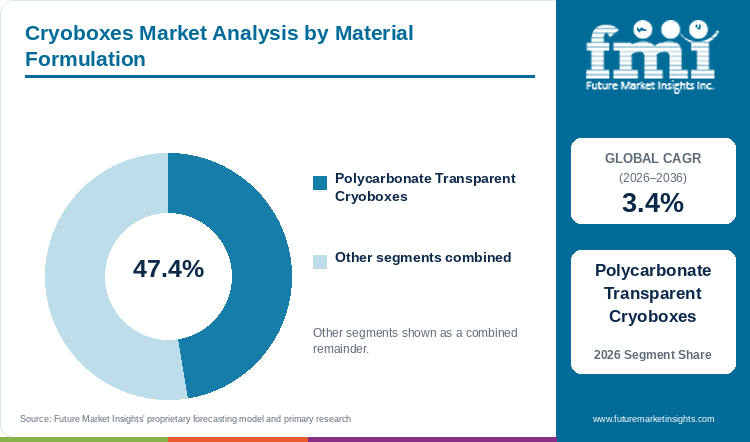
Polycarbonate Transparent Cryoboxes hold an estimated 47.4% of material formulation demand in 2026, anchored by optical clarity and minus 196 degrees Celsius impact strength.
Table 5: Material Formulation Share for the Cryoboxes Market (percentage share), 2026
| Material Formulation | Share (2026) |
|---|---|
| Polycarbonate Transparent Cryoboxes | 47.4% |
| Polypropylene Autoclavable Cryoboxes | 33.8% |
| Waterproof Moisture-Resistant Cardboard | 18.8% |
| Total | 100.0% |
*Note: Material formulation shares reflect global 2026 revenue allocations across polycarbonate, polypropylene, and coated fibreboard cryoboxes.
Table 6: Material Formulation Leadership and Market Growth for the Cryoboxes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.4% |
| Leading Segment | Polycarbonate Transparent Cryoboxes |
Cryogenic technicians retrieving frozen cell lines from liquid nitrogen dewars or minus 80 degrees Celsius racks must verify vial cap colors and sample labels within seconds to avoid thermal excursions. Injection-molded virgin polycarbonate cryoboxes provide glass-like lid transparency with high tensile resilience from minus 196 to plus 121 degrees Celsius. Laboratory procurement teams sourcing cryo box consumables favor polycarbonate over moisture-coated cardboard because molded vent slots and drain holes prevent frost delamination during multi-year storage.
- Polycarbonate Transparent Cryoboxes hold 47.4% of material formulation value in 2026 because impact-resistant clear lids speed sample identification without opening the box.
- In October 2025, biobanking quality-assurance researchers reporting in Biopreservation and Biobanking validated frozen indicator tubes across five years of minus 20 and minus 80 degrees Celsius storage with zero dye bleed.
What sustains 81-Place 9x9 Array leadership in the grid array capacity segment?
The 81-Place 9x9 Array represents 51.1% of the grid array capacity category in 2026, supported by universal compatibility with external-thread 1.5 and 2.0 mL cryovials.
Standard stainless-steel and aluminum freezer racks inside upright mechanical freezers and liquid nitrogen tanks are engineered around a 133 by 133 millimeter footprint. Within that footprint, an 81-place 9x9 divider grid accommodates 12.5 millimeter diameter external-thread and internal-thread cryovials with sufficient clearance for gloved finger or forceps extraction. Facilities operating cryopreservation freezers standardize on 81-place boxes for general clinical aliquots while reserving 100-place fixed-post boxes for internal-thread vials.
- The 81-Place 9x9 Array represents 51.1% of grid array capacity demand in 2026 as 9x9 dividers fit universal 133 millimeter freezer rack drawers.
- In November 2025, the PERSIAN Cohort Biobank documented in BMC Medical Research Methodology that standardized minus 80 degrees Celsius storage protocols preserve biospecimen integrity across multi-center national cohorts.
How does Ultra-Low Temperature -80C Freezer lead the temperature rating category?
Ultra-Low Temperature -80C Freezer boxes account for 71.5% of temperature rating volume in 2026, driven by widespread mechanical ULT freezer installations across hospitals and universities.
Whereas vapor-phase liquid nitrogen storage at minus 196 degrees Celsius is mandatory for viable stem cells and primary PBMC lines and the vast majority of DNA and RNA, serum, plasma and viral transport swabs are archived in mechanical minus 80 degrees Celsius freezers. Every new 700-liter upright ultra-low temperature freezer installation requires 400 to 600 cryoboxes to populate its sliding drawer racks at commissioning. Clinical trial laboratories also deploy cryogenic ampoules and cryovials inside minus 80 degrees Celsius rated polypropylene and polycarbonate boxes for Phase II and Phase III biomarker retention.
- Ultra-Low Temperature -80C Freezer boxes account for 71.5% of temperature rating demand in 2026 because mechanical ULT freezers anchor hospital and academic sample storage.
- In February 2026, biobank technology analysts publishing in MedComm documented how 5G-IoT telemetry and standardized storage consumables reduce human retrieval errors across modern biorepositories.
Why do Biobanks and Biorepositories lead the end-user facility category?
Biobanks and Biorepositories secure 58.6% of end-user facility value in 2026, supported by national genomic medicine cohorts and longitudinal disease registries.
Population-scale biobanks, oncology tissue repositories and contract biorepositories accession hundreds of thousands of blood, urine and biopsy aliquots annually under ISO 20387 accreditation rules. Unlike small university teaching labs that wash and reuse a few dozen boxes, accredited biorepositories permanently assign each incoming patient sample batch to a dedicated, laser-indexed cryobox for 10 to 30 years of storage. Reproductive and biodiversity repositories utilizing cryopreservation for in-vitro fertilization workflows further expand institutional cryobox consumption.
- Biobanks and Biorepositories secure 58.6% of end-user facility demand in 2026 because longitudinal sample archiving requires permanent one-way box allocation.
- In September 2026, hepatology researchers reporting in Liver International outlined standardized cryopreservation roadmaps for biobanked patient-derived liver organoids across multi-center clinical registries.
What gives Alphanumeric Laser-Coded Friction Lids the leading position in lid closure and indexing?
Alphanumeric Laser-Coded Friction Lids command 53.2% of lid closure and indexing share in 2026, anchored by frost-resistant permanent grid identification.
Adhesive paper labels and felt-tip marker inscriptions frequently peel or smudge when exposed to minus 80 degrees Celsius frost buildup and ethanol decontamination sprays. Molded high-contrast laser-etched alphanumeric grid coordinates (A1 through I9 or 1 through 81) directly on a keyed friction-fit lid ensure that sample positions remain legible throughout decades of sub-zero storage. Cell therapy quality-control teams pairing cryoboxes with cell therapy cryopreservation and thaw performance test platforms mandate keyed lids that can only be seated in one orientation.
- Alphanumeric Laser-Coded Friction Lids command 53.2% of lid closure and indexing value in 2026 because molded laser coordinates eliminate label detachment in sub-zero storage.
- In September 2026, biomedical reviewers in Pharmaceutics noted how approved cancer cell therapies require traceable, contamination-free cryopreservation consumables across clinical manufacturing.
What are the drivers, restraints, and opportunities in the cryoboxes market?
In the cryoboxes market, population biobank expansion and cell therapy clinical trials drive adoption whereas multi-year polymer box reuse restrains replacement frequency and 2D-barcoded automation-ready racks unlock LIMS-integrated upgrades.
- Driver: Broader national genomic biobanks, oncology organoid libraries, and commercial CAR-T cell therapy manufacturing require millions of new indexed cryoboxes annually.
- Restraint: High mechanical durability of autoclaved polycarbonate and polypropylene boxes allows academic laboratories to reuse containers across multiple study cycles.
- Opportunity: Addition of bottom-etched 2D DataMatrix barcodes and RFID tags in SBS-footprint and 9x9 cryoboxes unlocks automated camera rack-reader retrofits.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Precision oncology trials, newborn genomic screening programs, and biodiversity conservation repositories are generating unprecedented volumes of frozen biospecimens that must be cataloged in standardized grid arrays. Every patient enrolled in a longitudinal biomarker study yields 10 to 30 separate plasma, buffy-coat, and serum aliquots that must be segregated across primary and backup freezer locations. Deployment of paperboard cold chain cartons and insulated dry-ice shippers with rigid polycarbonate cryoboxes allows central reference laboratories to consolidate specimens from regional clinics. In August 2026, reproductive cryobiologists reporting in Frontiers in Veterinary Science demonstrated that rapid vitrification and combination cryoprotectant protocols achieved over 90% normal post-thaw embryo morphology.
Risk Assessment of the Cryoboxes Market: Operational and Formulation Friction
Mechanical warpage under rapid thermal shock and laboratory budget constraints favoring moisture-resistant cardboard boxes represent key friction points in the cryoboxes market. When technicians immerse unvented plastic boxes directly into liquid-phase nitrogen, trapped liquid expands approximately 700-fold during warming and can crack rigid lids or eject vials. Conversely, low-cost cardboard cryoboxes absorb ambient condensation during repeated benchtop thawing, softening cell dividers and risking cross-contamination. In November 2025, conservation scientists publishing in Animals documented that long-term deep-cold biobanking at minus 196 degrees Celsius requires durable, standardized storage vessels to safeguard somatic cell lines and gametes across global networks.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Consumable moulders capture higher per-box realizations by supplying automation-compatible cryoboxes with high-contrast laser-etched 1D linear and 2D DataMatrix barcodes on the box side and base. Pharmaceutical biorepositories transitioning from manual Excel logs to Laboratory Information Management Systems require whole-rack optical scanners that read all 81 or 100 tubes simultaneously through clear box bases. In August 2026, wildlife and clinical biobanking researchers reporting in Reproduction, Fertility and Development emphasized that integrating physical liquid-nitrogen and ultra-low temperature storage with digital metadata repositories is essential for next-generation omics discovery. Suppliers offering pre-barcoded, RNase-free and DNase-free certified cryoboxes win multi-year pharmaceutical discovery contracts.
Cryoboxes Market by Country (2026 to 2036)
FMI country modeling indicates that the United States leads cryoboxes expansion at a 3.9% CAGR through 2036, while Canada advances at a 2.9% CAGR. Commercial adoption across North American cell-therapy hubs, European national population biobanks, and East Asian regenerative medicine centers hinges on repository automation and ULT freezer density.
Table 7: Country CAGR and Primary Growth Levers for the Cryoboxes Market (CAGR percentage and operational drivers), 2026 to 2036
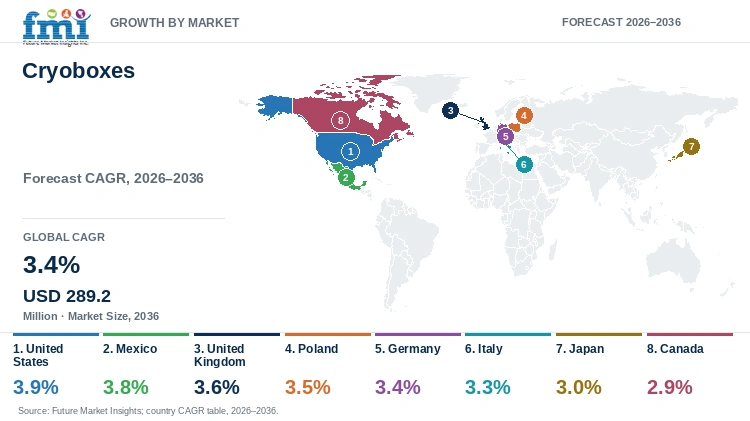
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| United States | 3.9% | NIH All of Us cohort archiving, FDA-approved cell therapies, and automated biorepositories |
| Mexico | 3.8% | Expanding clinical trial site networks, blood-bank modernization, and diagnostic exports |
| United Kingdom | 3.6% | UK Biobank robotic repository upgrades and cell-and-gene therapy manufacturing clusters |
| Poland | 3.5% | European BBMRI-ERIC biobanking node investments and contract clinical trial storage |
| Germany | 3.4% | Fraunhofer and Helmholtz biorepository networks and precision injection-molded labware |
| Italy | 3.3% | Oncology IRCCS hospital biobanks and biopharmaceutical cold-chain facility upgrades |
| Japan | 3.0% | iPSC regenerative medicine cell banks, aging cohort registries, and compact 100-place boxes |
| Canada | 2.9% | Provincial cancer research repositories and public health infectious-disease sample banks |
Source: Future Market Insights analysis
United States Cryoboxes Market Outlook (2026 to 2036)
Demand for cryoboxes in the United States is projected to expand at a leading 3.9% CAGR through 2036, anchored by federal precision-medicine cohorts, commercial CAR-T manufacturing and contract biorepositories. Unlike smaller national markets that rely on manual chest freezers, repositories in Massachusetts, California and North Carolina rapidly adopt 2D-barcoded polycarbonate boxes integrated with robotic liquid-nitrogen stores. In February 2026, Thermo Fisher Scientific documented its expanded Nalgene and Thermo Scientific CryoBox rack and ultra-low temperature storage portfolio for clinical biobanks across the United States. High sample accession volumes across oncology trials sustain recurring box orders, although academic grant consolidation encourages bulk distributor price negotiations across commercial buyer accounts in United States.
Key takeaway: In the United States, commercial cell-therapy repositories and federal genomic cohorts are projected to drive leading demand for 2D-barcoded polycarbonate cryoboxes.
Mexico Cryoboxes Market Outlook (2026 to 2036)
Whereas North American demand centers on automated genomic discovery, Mexico scales cryobox procurement through multinational Phase III clinical trial sites, private fertility clinics and regional blood-plasma collection centers. Market value for cryoboxes in Mexico is forecast to progress at a 3.8% CAGR between 2026 and 2036 across hospital and reference laboratory hubs in Mexico City, Monterrey, and Guadalajara. In May 2025, reproductive medicine specialists reporting in Frontiers in Veterinary Science noted how standardized cryopreservation protocols support tissue and gamete banking across emerging clinical and agricultural centers. Diagnostic laboratories in Mexico favor autoclavable polypropylene 81-place boxes and moisture-resistant cardboard sleeves that balance sub-zero durability against tight laboratory consumable budgets.
Key takeaway: In Mexico, expanding multi-center clinical trials and reproductive medicine clinics are forecast to sustain rising procurement of polypropylene and cardboard cryoboxes.
United Kingdom Cryoboxes Market Outlook (2026 to 2036)
What distinguishes the United Kingdom is the concentration of world-leading population genomics infrastructure, including UK Biobank in Manchester and cell-and-gene therapy catapult facilities in Stevenage. Market value for cryoboxes in the United Kingdom is anticipated to rise at a 3.6% CAGR through 2036 across National Health Service blood centers and pharmaceutical R&D campuses. In April 2025, bioprocessing researchers publishing in Biotechnology for Biofuels and Bioproducts demonstrated standardized sub-zero and enzymatic sample handling workflows across industrial and academic laboratories. Biorepository managers in the United Kingdom mandate SBS-footprint and laser-coded 81-place polycarbonate boxes that interface directly with automated high-density minus 80 degrees Celsius stores across commercial buyer accounts in United Kingdom.
Key takeaway: In the United Kingdom, national population biobanks and cell-therapy manufacturing hubs are anticipated to anchor demand for automation-ready cryoboxes.
Poland Cryoboxes Market Outlook (2026 to 2036)
Poland leads Central and Eastern European growth at a 3.5% CAGR from 2026 to 2036 because European Union structural funds and BBMRI.pl national biobanking network investments have modernized medical university repositories in Wroclaw, Gdansk, and Warsaw. Unlike legacy clinical labs that stored tubes in unindexed bags, Polish biobanks now enforce ISO 20387 quality management standards requiring traceable 9x9 and 10x10 cryobox grids. In October 2025, European laboratory materials researchers in Polymers documented sustainable polymer and cellulose composite engineering advances supporting specialized technical applications. Expanded contract clinical research outsourcing into Poland further boosts demand for color-coded polycarbonate boxes that segregate trial arms across multi-site oncology studies across commercial buyer accounts in Poland.
Key takeaway: In Poland, national biobanking network accreditation and contract clinical trial expansion are estimated to drive steady adoption of indexed polymer cryoboxes.
Germany Cryoboxes Market Outlook (2026 to 2036)
Germany diverges from other European markets because it houses both major academic biobank networks under the German Biobank Alliance and domestic precision injection-molding leaders including Eppendorf and Sarstedt. Industry valuation for cryoboxes in Germany is slated to expand at a 3.4% CAGR across the 2026 to 2036 horizon. In March 2026, Eppendorf SE detailed its laser-labeled polypropylene freezer storage box systems rated to minus 86 degrees Celsius and autoclaving at 121 degrees Celsius for 20 minutes. University hospitals and biotech firms in Germany actively replace solvent-coated cardboard boxes with reusable, high-contrast laser-indexed polypropylene arrays to reduce freezer frost accumulation and meet laboratory sustainability targets across commercial buyer accounts in Germany.
Key takeaway: In Germany, domestic precision labware manufacturing and university hospital biobank standardization are slated to sustain demand for autoclavable polypropylene cryoboxes.
Italy Cryoboxes Market Outlook (2026 to 2036)
Whereas demand in Germany is anchored by large industrial labware ecosystems, Italy concentrates cryobox procurement within specialized IRCCS research hospitals, regional cord-blood banks and northern contract biologics manufacturers in Lombardy and Tuscany. Procurement of cryoboxes in Italy is expected to advance at a 3.3% CAGR between 2026 and 2036. In September 2025, European laboratory scientists publishing in Separations demonstrated that strict contaminant control during sample preparation directly governs downstream analytical reproducibility. Oncology and rare-disease biobanks in Italy prioritize transparent polycarbonate 81-place boxes with keyed numeric lids for vapor-phase liquid nitrogen dewars, while regional hospital budget ceilings maintain steady demand for waterproof cardboard boxes in short-term storage.
Key takeaway: In Italy, oncology research hospital biobanks and biologics contract manufacturing are expected to support balanced demand across polycarbonate and cardboard cryoboxes.
Japan Cryoboxes Market Outlook (2026 to 2036)
Unlike Western laboratories with expansive basement freezer rooms, university hospitals and regenerative medicine centers in Japan face severe laboratory floor-space constraints in Tokyo, Kyoto and Osaka. Consequently, cryoboxes demand in Japan is projected to grow at a 3.0% CAGR through 2036 as repositories shift from 81-place boxes to high-density 100-place internal-thread arrays that boost per-rack vial capacity by 23%. In June 2025, biomaterials researchers reporting in Carbohydrate Polymers documented how precision biopolymer and enzymatic stabilization techniques preserve biological activity under storage stress. Induced pluripotent stem cell banks and national aging cohorts in Japan mandate ultra-clean, low-extractable polycarbonate and polypropylene cryoboxes compatible with seismic-latched ULT freezer racks.
Key takeaway: In Japan, laboratory floor-space optimization and iPSC regenerative medicine repositories are projected to favor high-density 100-place polymer cryoboxes.
Canada Cryoboxes Market Outlook (2026 to 2036)
Canada records a steady 2.9% CAGR from 2026 to 2036 across provincial cancer agency repositories, academic health science networks in Toronto, Montreal and Vancouver and federal infectious-disease reference laboratories. What shapes purchasing in Canada is the long-distance inter-provincial transport of frozen clinical specimens from northern and rural collection clinics to urban genomic sequencing hubs. In August 2026, the USDA Foreign Agricultural Service reported that Canada's bio-industrial and food manufacturing sector exceeded USD 125 billion in 2025 across more than 11,000 facilities supporting cold-chain and quality-testing laboratories. Biorepositories in Canada specify shatter-proof polycarbonate cryoboxes with positive friction-fit lids that prevent vial ejection during dry-ice air freight across commercial buyer accounts in Canada.
Key takeaway: In Canada, provincial oncology registries and long-distance dry-ice specimen transit are predicted to sustain demand for shatter-proof polycarbonate cryoboxes.
Full report country CAGRs cover North America and Latin America with Western Europe and Eastern Europe. Additional regional coverage spans East Asia, South Asia and Pacific, and Middle East and Africa.
Who are the notable companies in the cryoboxes market?
Thermo Fisher Scientific Inc. and Corning Incorporated and Eppendorf SE, Azenta Inc., Sarstedt AG & Co. KG and DWK Life Sciences GmbH and Greiner Bio-One International GmbH, Berry Global Group Inc., Smurfit Westrock plc and Sonoco Products Company are the notable companies in the cryoboxes market.
Competitive positioning in the cryoboxes industry separates primary life-science cold-storage consumable manufacturers, precision clinical polymer labware moulders, and secondary clinical fiberboard and cold-chain packaging suppliers. Thermo Fisher Scientific Inc. and Corning Incorporated with Eppendorf SE and Azenta Inc. engineer polycarbonate and polypropylene cryoboxes integrated with ultra-low temperature freezers and automated liquid-nitrogen stores. Sarstedt AG & Co. KG and DWK Life Sciences GmbH with Greiner Bio-One International GmbH and Berry Global Group Inc. mold high-precision cryovials, racks and polymer storage containers, whereas Smurfit Westrock plc and Sonoco Products Company participate via moisture-resistant clinical board boxes and insulated cold-chain shippers.
- Integrated Cold-Storage and Biobank Consumable Leaders: Thermo Fisher Scientific Inc., Corning Incorporated, Eppendorf SE and Azenta Inc. supply polycarbonate and polypropylene cryoboxes matched to ULT freezers and 2D barcode readers.
- Precision Clinical Labware and Polymer Moulders: Sarstedt AG & Co. KG, DWK Life Sciences GmbH, Greiner Bio-One International GmbH and Berry Global Group Inc. manufacture autoclavable freezer boxes, cryovials, and medical polymer enclosures.
- Clinical Fibreboard and Cold-Chain Packaging Suppliers: Smurfit Westrock plc and Sonoco Products Company produce waterproof coated fibreboard cryoboxes and phase-change insulated clinical specimen shippers.
Competitive Benchmarking: Cryoboxes Market
Table 8: Competitive Benchmarking for the Cryoboxes Market (qualitative capability ratings), 2026
| Company | Cryogenic Polymer Engineering | Barcode & LIMS Automation Fit | Freezer & Rack Integration | Geographic Reach |
|---|---|---|---|---|
| Thermo Fisher Scientific Inc. | High | High | High | Global Nalgene and Matrix cryobox and ULT freezer network across North America, Europe, and Asia |
| Corning Incorporated | High | High | High | Global Corning CoolBox, CryoBox, and cell-culture biobanking consumable distribution |
| Eppendorf SE | High | High | High | Global polypropylene laser-coded Storage Boxes and minus 86C freezer ecosystem |
| Azenta Inc. | High | High | High | Global FluidX 2D-barcoded cryoboxes and BioStore/CryoArc automated biorepository systems |
| Sarstedt AG & Co. KG | High | Medium | High | European and global clinical diagnostics and CryoPure tube-and-box storage systems |
| DWK Life Sciences GmbH | High | Medium | Medium | Global WHEATON KeepIT freezer boxes and specialty glass and polymer cryogenic labware |
| Greiner Bio-One International GmbH | High | High | High | Global Cryo.s biobanking tubes, 81/100-place polycarbonate boxes, and rack scanners |
| Berry Global Group Inc. | High | Low | Medium | Global cleanroom injection-molded healthcare polymers and diagnostic containment packaging |
| Smurfit Westrock plc | Medium | Low | Medium | Global moisture-resistant coated paperboard clinical boxes and sterile barrier cartons |
| Sonoco Products Company | Medium | Medium | Medium | Global Sonoco ThermoSafe sub-zero clinical shippers and composite cold-chain containers |
Evaluation basis: Cryogenic Polymer Engineering evaluates documented minus 80C and minus 196C impact resistance across virgin polycarbonate and polypropylene grades, whereas Barcode & LIMS Automation Fit rates laser-etched 1D/2D indexing and optical rack-scanner compatibility. Freezer & Rack Integration measures native dimensional matching with commercial upright ULT freezers and vapor-phase LN2 dewars.
Key Developments in the Cryoboxes Market
- Thermo Fisher Scientific Inc. expanded its Nalgene and Thermo Scientific CryoBox stainless-steel rack and barcoded polycarbonate box portfolio for clinical biobanks in February 2026.
- Azenta Inc. published updated cryogenic biobanking guidelines in January 2026 detailing how ISO-accredited repositories integrate 2D-barcoded boxes with CryoArc automated storage.
- Labware producer Corning Incorporated released its updated animal cell culture cryopreservation and CoolCell/CryoBox repository management framework in March 2026.
Key Players in the Cryoboxes Market
Integrated Cold-Storage and Biobank Consumable Leaders
- Thermo Fisher Scientific Inc.
- Labware producer Corning Incorporated
- Eppendorf SE
- Azenta Inc.
Precision Clinical Labware and Polymer Moulders
- Sarstedt AG & Co. KG
- DWK Life Sciences GmbH
- Greiner Bio-One International GmbH
- Berry Global Group Inc.
Clinical Fibreboard and Cold-Chain Packaging Suppliers
- Smurfit Westrock plc
- Sonoco Products Company
Cryoboxes Market - Report Scope
Table 9: Report Scope for the Cryoboxes Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material Formulation; Grid Array Capacity; Temperature Rating; End-User Facility; Lid Closure and Indexing |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial manufacturer revenue from rigid and semi-rigid cryogenic storage boxes (polycarbonate, polypropylene, and waterproof coated cardboard) engineered to organize and protect cryovials and microtubes at ultra-low (-80C) and cryogenic (-196C) temperatures. Category Scope Note: Excludes primary cryogenic vials/tubes themselves, stainless-steel freezer drawer racks, mechanical ULT freezers, and liquid-nitrogen dewars. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | United States, Mexico, United Kingdom, Poland, Germany, Italy, Japan, Canada, and additional countries in the full report |
| Key Companies Covered | Thermo Fisher Scientific Inc., Corning Incorporated, Eppendorf SE, Azenta Inc., Sarstedt AG & Co. KG, DWK Life Sciences GmbH, Greiner Bio-One International GmbH, Berry Global Group Inc., Smurfit Westrock plc, Sonoco Products Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Cryoboxes Market - Research Methodology
Table 10: Research Methodology for the Cryoboxes Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with ISO 20387 biobank directors, hospital stem-cell processing managers, and cleanroom labware injection moulders to validate box replacement rates and polycarbonate vs polypropylene price realizations. |
| Secondary Research | Analysis of NIH and PMC biopreservation studies, ISBER best-practice repository guidelines, corporate product catalogs from Thermo Fisher, Eppendorf, Corning, and Azenta, and clinical trial registry expansions. |
| Market Sizing and Forecasting | Top-down parent biobanking consumables and cold-storage labware baselines reconciled against bottom-up annual cryobox unit shipments (70.2M to 77.5M units in 2026) and ASP realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight active biobank facility counts, commissioned ULT freezer and vapor-phase LN2 tank capacity, and cell-therapy clinical trial volume across eight national markets. |
| Operational Benchmark Traceability | Unit shipment and repository indicators in Tables 2, 3, and 4 trace to standard 133x133 mm 81-place and 100-place freezer rack geometries and multi-year cohort accession schedules. |
| Data Triangulation and Validation | Valuation estimates isolate empty cryogenic storage boxes and dividers while strictly excluding pre-filled reagent kits, primary cryovials, and metal freezer racking. |
Cryoboxes Market by Segments
Cryoboxes Market segmented by Material Formulation:
- Polycarbonate Transparent Cryoboxes
- Polypropylene Autoclavable Cryoboxes
- Waterproof Moisture-Resistant Cardboard
Cryoboxes Market segmented by Grid Array Capacity:
- 81-Place 9x9 Array
- 100-Place 10x10 Array
- 25-Place 5x5 Compact Array
Cryoboxes Market segmented by Temperature Rating:
- Ultra-Low Temperature -80C Freezer
- Liquid Nitrogen Vapor Phase -196C Cryogenic
Cryoboxes Market segmented by End-User Facility:
- Biobanks and Biorepositories
- Academic and Clinical Research Labs
- Pharmaceutical and Biotech Companies
Cryoboxes Market segmented by Lid Closure and Indexing:
- Alphanumeric Laser-Coded Friction Lids
- Hinged Attached-Lid Cryoboxes
- 2D Barcode Bottom-Indexed Cryoboxes
- Color-Coded Keyed-Corner Lids
Cryoboxes Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Zhang W. et al. (2024 December 4). Protocol for a cryopreserved biobank of living tumor tissues for drug sensitivity testing and organoid culture. Cancer Communications (PMC11889390).
- [2] Azenta Inc. (2026 January 15). Rigor, Control, and Process Excellence in Cryogenic Biobanking from the First ISO-Accredited Biobank. Azenta Life Sciences Learning Center.
- [3] Marcu A. et al. (2025 October 4). Viable and Functional: Long-Term -80 C Cryopreservation of Hematopoietic Stem Cells. Cancers (PMC12525932).
- [4] Takahashi M. et al. (2025 November 20). Evaluation of the Activity of Peripheral Blood Mononuclear Cells Preserved via Electromagnetic Field Freezing Versus Standard Slow Freezing. International Journal of Laboratory Hematology (PMC12631015).
- [5] Centers for Disease Control and Prevention Researchers. (2026 June 12). The Stability of Never-Thawed Serum Biospecimens Stored in Vapor-Phase Liquid Nitrogen Tanks. Biopreservation and Biobanking (PMC13055869).
- [6] Reed J. et al. (2025 October 3). Indicator Tubes: A Novel Solution for Monitoring Temperature Excursions in Biobanking Ultra-Low-Temperature Storage. Biopreservation and Biobanking (PMC12566185).
- [7] Poustchi H. et al. (2025 November 24). PERSIAN cohort biobank: creating a large-scale national resource for biomedical research. BMC Medical Research Methodology (PMC12645788).
- [8] Chen H. et al. (2026 February 3). Current situation and future prospect of biobank technology and intelligent sample management. MedComm (PMC12931191).
- [9] Kruitwagen H. S. et al. (2026 September 10). Biobanked Liver Organoids: A Roadmap for Precision Hepatology and Standardized Repositories. Liver International (PMC13312996).
- [10] Awan M. et al. (2026 September 25). Closure of the Gap in Cryopreservation: A Review of Cryoprotectant Mechanisms and Cell Therapy Storage. Pharmaceutics (PMC13203093).
- [11] Wang X. et al. (2026 August 7). Research progress on novel bionic cryoprotectants in gamete and embryo cryopreservation. Frontiers in Veterinary Science (PMC13130884).
- [12] Mastromonaco G. F. et al. (2025 November 11). Progress in Wildlife Conservation Through Biobanking in South America and Global Deep-Cold Repositories. Animals (PMC12649330).
- [13] Comizzoli P. et al. (2026 August 18). Repository biobanking biodiversity: recent strategies, challenges, and integration of physical and digital biorepositories. Reproduction, Fertility and Development (PMC13286723).
- [14] Thermo Fisher Scientific Inc. (2026 February 10). CryoBox Freezer Racks and Standard Cryogenic Vial Storage Organization Systems. Thermo Fisher Scientific Technical Catalog.
- [15] Silva A. R. et al. (2025 May 14). Cryopreservation and culture strategies for testicular tissue and cells in domestic and conservation biobanks. Frontiers in Veterinary Science (PMC12307161).
- [16] Kumar V. et al. (2025 April 29). Synergistic cell-free enzyme cocktails and standardized laboratory bioprocessing protocols. Biotechnology for Biofuels and Bioproducts (PMC12042388).
- [17] Santos R. et al. (2025 October 30). Progress in Sustainable Production of High-Performance Cellulose and Polymer Materials. Polymers (PMC12610377).
- [18] Eppendorf SE. (2026 March 12). Eppendorf Storage Boxes: Autoclavable Polypropylene Lab Freezer Boxes for -86 C Sample Archiving. Eppendorf Cold Storage Product Specifications.
- [19] Horvath K. et al. (2025 September 2). Resolution of Contaminant Separation and Analytical Reproducibility in Laboratory Sample Processing. Separations (PMC12431526).
- [20] Al-Qahtani S. et al. (2025 June 15). Stabilized Biopolymer Matrices for Enhanced Thermal and Storage Stability in Laboratory Applications. Carbohydrate Polymers (PMC13052012).
- [21] USDA Foreign Agricultural Service. (2026 August 27). Canada: Food Processing Ingredients Annual and Bio-Industrial Sector Overview. U.S. Department of Agriculture GAIN Report CA2026-0022.
- [22] Thermo Fisher Scientific Inc. (2026 February 20). Cryopreservation Systems and Cold Storage Accessories for Life Science Repositories. Thermo Fisher Scientific US Life Science Portal.
- [23] Azenta Inc. (2026 January 28). Cryogenic Storage Solutions in Life Sciences: A Comprehensive Guide for Repository Decision-Making. Azenta Life Sciences Technical eBook.
- [24] Labware producer Corning Incorporated. (2026 March 5). General Guide for Cryogenically Storing Animal Cell Cultures and Managing Cell Repositories. Labware producer Corning Life Sciences Technical Resources.
- [25] Galula J. U. et al. (2026 July 10). Repository biobanking of vector-borne viruses in the Philippines. Tropical Medicine and Health (PMC13199461).
- [26] Thermo Fisher Scientific Inc. (2026 January 19). Nunc Storage Box and Rack 100-Vial Polycarbonate System Specifications. Thermo Fisher Scientific Catalog.
- [27] Thermo Fisher Scientific Inc. (2026 March 18). Thermo Scientific Cryogenic Storage Boxes Technical Brochure. Thermo Fisher Scientific Technical Documentation.
- [28] Eppendorf SE. (2026 January 22). Long-term storage in liquid nitrogen: Vapor phase versus liquid phase cryopreservation safety. Eppendorf Lab Academy Cell Biology.
- [29] Fisher Scientific. (2026 February 8). Azenta US Inc Hinged CryoBox 81-Place and 100-Place Freezer Storage Specifications. Fisher Scientific Laboratory Catalog.
- [30] Labware producer Corning Incorporated. (2026 March 15). Selection of the Best Cold Storage Solution for Your Lab: Preserving Samples for Experimental Success. Labware producer Corning Life Sciences At the Bench.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cryoboxes market in 2026 and what is forecast for 2036?
- Which population-biobanking and cell-therapy storage pressures support demand for cryoboxes?
- Why do Polycarbonate Transparent Cryoboxes lead the material formulation category?
- Why does the 81-Place 9x9 Array lead the grid array capacity category globally?
- How do growth rates differ across the United States and Mexico compared to Japan?
- Which leading companies supply integrated 2D-barcoded biobank boxes versus clinical fibreboard sleeves?
- What limits replacement frequency or causes thermal-shock cracking in the cryoboxes market?
- What should biobank directors evaluate before upgrading from cardboard to laser-indexed polymer cryoboxes?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material Formulation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Material Formulation, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Material Formulation, 2026 to 2036
- Polycarbonate Transparent Cryoboxes
- Polypropylene Autoclavable Cryoboxes
- Waterproof Moisture-Resistant Cardboard
- Y-o-Y Growth Trend Analysis By Material Formulation, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Formulation, 2026 to 2036
- Global Market Analysis and Forecast, By Grid Array Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Grid Array Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Grid Array Capacity, 2026 to 2036
- 81-Place 9x9 Array
- 100-Place 10x10 Array
- 25-Place 5x5 Compact Array
- Y-o-Y Growth Trend Analysis By Grid Array Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Grid Array Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Temperature Rating, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Temperature Rating, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Temperature Rating, 2026 to 2036
- Ultra-Low Temperature -80C Freezer
- Liquid Nitrogen Vapor Phase -196C Cryogenic
- Y-o-Y Growth Trend Analysis By Temperature Rating, 2021 to 2025
- Absolute $ Opportunity Analysis By Temperature Rating, 2026 to 2036
- Global Market Analysis and Forecast, By End-User Facility, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-User Facility, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-User Facility, 2026 to 2036
- Biobanks and Biorepositories
- Academic and Clinical Research Labs
- Pharmaceutical and Biotech Companies
- Y-o-Y Growth Trend Analysis By End-User Facility, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User Facility, 2026 to 2036
- Global Market Analysis and Forecast, By Lid Closure and Indexing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Lid Closure and Indexing, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Lid Closure and Indexing, 2026 to 2036
- Alphanumeric Laser-Coded Friction Lids
- Hinged Attached-Lid Cryoboxes
- 2D Barcode Bottom-Indexed Cryoboxes
- Color-Coded Keyed-Corner Lids
- Y-o-Y Growth Trend Analysis By Lid Closure and Indexing, 2021 to 2025
- Absolute $ Opportunity Analysis By Lid Closure and Indexing, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- By Country
- Market Attractiveness Analysis
- By Country
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material Formulation
- By Grid Array Capacity
- By Temperature Rating
- By End-User Facility
- By Lid Closure and Indexing
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Thermo Fisher Scientific Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Corning Incorporated
- Eppendorf SE
- Azenta Inc.
- Sarstedt AG & Co. KG
- DWK Life Sciences GmbH
- Greiner Bio-One International GmbH
- Berry Global Group Inc.
- Smurfit Westrock plc
- Sonoco Products Company
- Labware producer Corning Incorporated
- Thermo Fisher Scientific Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Million) Forecast by Material Formulation, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Million) Forecast by Grid Array Capacity, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Million) Forecast by Temperature Rating, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Million) Forecast by End-User Facility, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Million) Forecast by Lid Closure and Indexing, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Material Formulation
- Figure 6: Global Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Grid Array Capacity
- Figure 9: Global Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Temperature Rating
- Figure 12: Global Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-User Facility
- Figure 15: Global Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Material Formulation
- Figure 32: North America Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Grid Array Capacity
- Figure 35: North America Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Temperature Rating
- Figure 38: North America Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-User Facility
- Figure 41: North America Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Material Formulation
- Figure 48: Latin America Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Grid Array Capacity
- Figure 51: Latin America Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Temperature Rating
- Figure 54: Latin America Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-User Facility
- Figure 57: Latin America Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Material Formulation
- Figure 64: Western Europe Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Grid Array Capacity
- Figure 67: Western Europe Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Temperature Rating
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-User Facility
- Figure 73: Western Europe Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Material Formulation
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Grid Array Capacity
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Temperature Rating
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-User Facility
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Material Formulation
- Figure 96: East Asia Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Grid Array Capacity
- Figure 99: East Asia Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Temperature Rating
- Figure 102: East Asia Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-User Facility
- Figure 105: East Asia Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Material Formulation
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Grid Array Capacity
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Temperature Rating
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-User Facility
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Material Formulation, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Material Formulation, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Material Formulation
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Grid Array Capacity, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Grid Array Capacity, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Grid Array Capacity
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Temperature Rating, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Temperature Rating, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Temperature Rating
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-User Facility, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-User Facility, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-User Facility
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Lid Closure and Indexing, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Lid Closure and Indexing, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Lid Closure and Indexing
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the cryoboxes market in 2026, and what is forecast for 2036?
FMI estimates that the global cryoboxes market size stood at USD 200.5 million in 2025 and reached USD 207.0 million in 2026. Overall industry valuation is on track to hit USD 289.2 million by 2036 as biobanks and cell therapy facilities expand sub-zero sample archiving.
What is the CAGR for the cryoboxes market from 2026 to 2036?
The cryoboxes sector is projected to expand at a 3.4% CAGR over the 2026 to 2036 window, adding USD 82.2 million across clinical and research repositories.
Which material formulation segment leads the cryoboxes market?
Polycarbonate Transparent Cryoboxes hold 47.4% of material formulation demand in 2026 because impact-resistant transparent lids allow visual sample inspection down to minus 196 degrees Celsius.
Which grid array capacity segment leads the cryoboxes market?
The 81-Place 9x9 Array represents 51.1% of the grid array category in 2026 as 9x9 dividers fit universal 133 millimeter freezer racks and 2.0 milliliter external-thread cryovials.
Which country has a notable growth outlook during the assessment period?
The United States leads national expansion projections at a 3.9% CAGR through 2036, driven by NIH genomic cohorts, commercial CAR-T repositories and automated biobanking.
Who are the key players in the market?
Thermo Fisher Scientific Inc. and Corning Incorporated, Eppendorf SE, Azenta Inc. and Sarstedt AG & Co. KG lead commercial supply with DWK Life Sciences GmbH and Greiner Bio-One International GmbH, Berry Global Group Inc., Smurfit Westrock plc and Sonoco Products Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
