
- Market Size (2026)
- USD 1.6 Bn
- Forecast (2036)
- USD 2.4 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is the Defoamers Market in 2026?
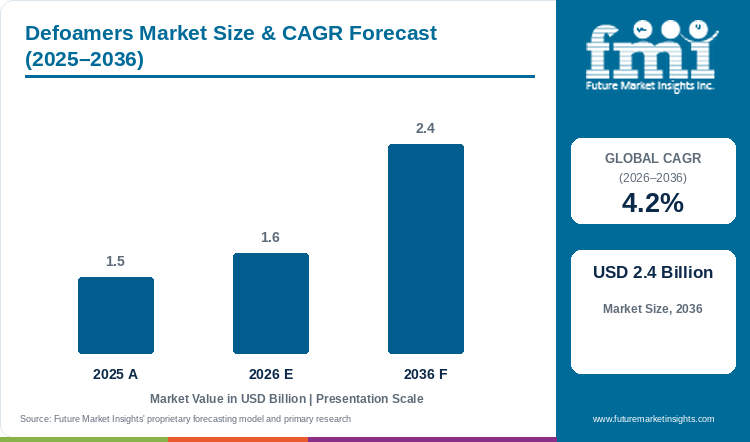
Repeat dosing in paper mills, paint plants and treatment works should lift the Defoamers Market to USD 2.4 billion by 2036. FMI estimates USD 1.6 billion for 2026 and a 4.2% CAGR from 2026 to 2036. The market was valued at USD 1.5 billion in 2025. Pulp and Paper holds 21.4% by application in 2026. Aqueous Systems account for 68.2% by medium of dispersion, and Silicone represents 38.6% by product type.
Defoamers are consumed in use, so volumes track plant throughput. Output is rising fastest in Asia. India's Ministry of Statistics and Programme Implementation recorded 11.7% growth in paper and paper products output in April to June 2026. China's National Bureau of Statistics reported 5.7% manufacturing growth in January to September 2026. Europe is flatter. Cepi reported paper and board production of 77.4 million tonnes in 2025, down 1.6%.
Input cost is the main restraint. Wacker Chemie raised silicone prices from 1 April 2026 after oil, gas and logistics prices climbed. Kemira expects about EUR 100.0 million of raw material and logistics cost inflation in 2026 and aims to recover roughly half through prices. Solenis offers a qualified example of new capacity. It broke ground in April 2026 on a 60,000-tonne papermaking chemicals plant in Beihai that will include defoamers. Operations are expected in the second quarter of 2027, and one plant does not prove regional demand growth.
Key Market Trends & Insights
- Europe is losing upstream siloxane capacity. Dow planned to shut its basic siloxanes operations at Barry in the United Kingdom by mid-2026 to right-size regional capacity. Its third-quarter 2026 results referred to the recent shutdown of that plant. Elkem completed the sale of most of its silicones division to Bluestar on 30 April 2026. European formulators of silicone grades should therefore qualify more than one siloxane source.
- Process chemical suppliers are pricing to recover cost. Ecolab lifted pricing by 5.0% in its July to September 2026 quarter to offset higher commodity costs. Its Paper business returned to growth on new business wins and better pricing. Mill buyers should expect the same pressure when defoamer contracts come up for renewal.
- Fluorine-free and silicone-free chemistries are entering mainstream ranges. BYK completed a switch of its full product range to PFAS-free production in 2025, and a BYK team won the ALTANA Innovation Award in 2026 for PFAS-free defoamers. Solenis is promoting silicone-free defoamers for pulp mills. These ranges give buyers options where fluorinated chemistry or silicone residues raise compliance questions.
Regional Highlights
- European paper demand is shifting towards packaging grades. Cepi reported that graphic paper output fell 7.3% in 2025 and cartonboard fell 5.4%, while packaging grades were stable. Output fell a further 2.4% in the first quarter of 2026. Defoamer suppliers in Europe will find steadier volume at packaging and board mills than at graphic paper sites.
- Latin America is drawing pulp chemical investment. Solenis moved its Pulp Center of Excellence from the United States to Paulínia in Brazil in October 2026. The company cited the region's rise as a pulp production hub and the share of announced projects in Mato Grosso do Sul. Suppliers that test programmes near new pulp lines are in a stronger position to win start-up chemical contracts.
Defoamers Market Size and Forecast
Table 1: Defoamers Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 1.5 billion |
| Estimated market size in 2026 | USD 1.6 billion |
| Projected market size by 2036 | USD 2.4 billion |
| CAGR from 2026 to 2036 | 4.2% |
Source: Future Market Insights analysis of the defoamers market, 2026.
Analyst Perspective
“Mills and paint makers buy defoamers on cost per tonne treated, and they judge that cost through plant trials. Suppliers win when their technical staff can match a formulation to the foam source and adjust it as raw materials change. Qualification is the main barrier to switching. A new product must pass plant trials, food-contact checks and siloxane residue limits before a buyer will approve it.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Defoamers Market segmented?
- By product type: Silicone, Oil, Polymer, Emulsion, and Powder. Higher-specification grades are tracked separately in the high-performance defoamers market.
- By medium of dispersion: Aqueous Systems and Solvent-based Systems.
- By application: Pulp and Paper, Paints and Coatings, Water and Wastewater Treatment, Food Processing, Chemicals, Construction Materials, Textile, Household and Personal Care, and Pharmaceuticals.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Pulp and Paper lead by Application in the Defoamers Market in 2026?
Pulp and Paper holds 21.4% of the Defoamers Market by application in 2026.
Pulp mills and paper machines pass large volumes of process water through washing and forming stages. Foam control is therefore a daily purchase for them. Solenis's new pulp centre in Brazil simulates each mill stage from cooking and brownstock washing through to bleaching. Its planned Beihai plant will make defoamers alongside polymers and silica for regional pulp and paper customers. Suppliers located close to mill clusters can deliver bulk volumes on short notice.
Mill throughput sets the volume. AF&PA reported that US containerboard mills ran at 91.9% of capacity in 2025 even as production fell 4.4% to 36.1 million tons. High operating rates keep dosing steady at the mills that stay open. In India, paper and paper products output grew 11.7% in April to June 2026. Many packaging mills also make coated grades covered in the barrier-coated papers market.
Paints and Coatings, Water and Wastewater Treatment, Food Processing, Chemicals, Construction Materials, Textile, Household and Personal Care, and Pharmaceuticals together hold the remaining 78.6% by application. This spread across end uses protects suppliers when paper output weakens. Graphic paper production fell 7.3% in Europe in 2025.
Table 2: Application, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Pulp and Paper | 21.4% |
| All Other Segments Combined Share | 78.6% |
Source: Future Market Insights analysis of the defoamers market, 2026.
Why do Aqueous Systems lead by Medium of Dispersion in the Defoamers Market in 2026?
Aqueous Systems account for 68.2% of the Defoamers Market by medium of dispersion in 2026.
Water-based processes dominate defoamer use. Paper stock, effluent treatment and most food lines are aqueous by nature. Paint rules add to that base. The EU VOC Directive caps trim and cladding paints at 130 g/l for water-based products against 300 g/l for solvent-based products. Paint makers that move into water-based systems need foam control designed for water-based binders.
Additive suppliers are designing products for these systems. Evonik launched TEGO Foamex 8051 in June 2025 for waterborne decorative coatings. The company states a VOC content of 0.08% and compliance with the EU Ecolabel criteria for paints. Dow reported higher price and volume in architectural coatings for the September 2026 quarter. Growth in decorative paint therefore adds volume to the aqueous segment.
Solvent-based Systems hold the remaining 31.8%. Solvent-borne technology remains one of the routes in the 2K coatings market, which serves buyers such as oil and gas, petrochemical and marine operators. These coatings need defoamers that stay compatible with solvent carriers.
Table 3: Medium of Dispersion, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Aqueous Systems | 68.2% |
| All Other Segments Combined Share | 31.8% |
Source: Future Market Insights analysis of the defoamers market, 2026.
Why does Silicone lead by Product Type in the Defoamers Market in 2026?
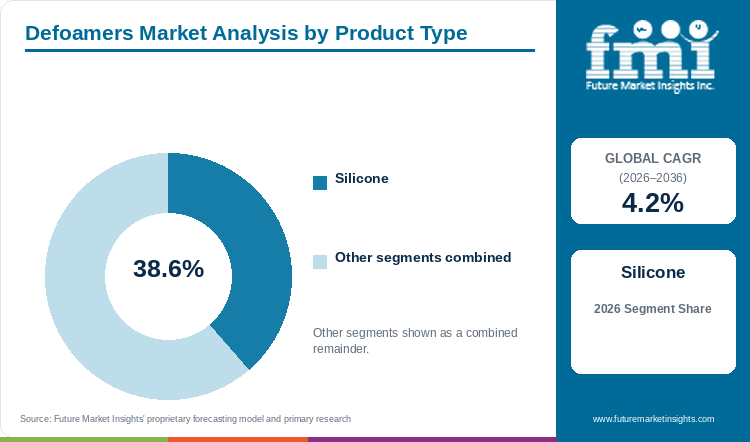
Silicone holds 38.6% of the Defoamers Market by product type in 2026.
Silicone grades work at very low addition rates. Momentive recommends a starting level of 10 ppm silicone for its AF9000NE antifoam in most applications. US food rules cap dimethylpolysiloxane at 10 ppm in ready-to-eat food. Low use levels help keep the cost per tonne treated competitive.
Silicone producers are reshaping supply. Wacker's silicones sales rose 6.0% to EUR 757.0 million in the second quarter of 2026. The company raised silicone prices in that quarter. Shin-Etsu is spending JPY 80.0 billion to reinforce capacity for silicone advanced functional products. Elkem exited most of its silicones exposure through the sale of the division majority to Bluestar in April 2026.
Oil, Polymer, Emulsion and Powder defoamers together account for the remaining 61.4%. US food rules list white mineral oil for sliced potato wash water at up to 0.008% of the wash water. Solenis has also developed a defoamer line without silicone for pulp customers.
Table 4: Product Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Silicone | 38.6% |
| All Other Segments Combined Share | 61.4% |
Source: Future Market Insights analysis of the defoamers market, 2026.
What are the key drivers restraints and opportunities?
Defoamer demand follows factory throughput across many process industries. Supplier margins depend on how fast silicone and oil costs can pass into contract prices.
Driver
Factory output in Asia is lifting dosing volumes. China's manufacturing value added rose 5.7% in January to September 2026, and food manufacturing grew 8.3%. India's textile output rose 14.3% in April to June 2026. Food processing and textile lines are both application segments in this market. Higher throughput in those plants raises the volume each site buys.
Restraint
Input costs can move faster than contract prices. Wacker raised silicone prices from 1 April 2026 after energy and raw material prices rose sharply. Kemira said it could only partly offset raw material and variable cost inflation through customer price increases between July and September 2026. Solenis announced an energy surcharge on 18 March 2026. Suppliers on fixed annual contracts carry these costs until prices reset.
Opportunity
Application-specific formulation backed by on-site technical service offers the best margin opportunity. Solenis runs 16 R&D centres and 11 customer application laboratories. Its Brazilian pulp centre tests treatment programmes across each stage of a mill. Ecolab grew its Paper and Heavy Water sales in the quarter to September 2026 on new business wins and improved pricing. Suppliers that prove savings in trials can price on results.
How do chemical and food-contact rules affect defoamer formulation?
Siloxane rules now affect silicone defoamer recipes in Europe. From 6 June 2026 the EU bars D4, D5 and D6 from the market in mixtures at 0.1% by weight or more, subject to listed exemptions. Mixtures that contain these substances as residues from silicone polymers are exempt within use-specific maximum levels. Leave-on cosmetics follow from 6 June 2027. Silicone suppliers therefore need to document residual cyclic content for grades sold into consumer and professional products.
Food-contact rules set dose ceilings. US rules allow dimethylpolysiloxane at up to 10 ppm in food ready for consumption and set a zero limit in milk. They also require defoamers to be added in amounts no greater than needed to inhibit foaming. Japan permits silicone resin in food at up to 0.050 g/kg and only for defoaming. These limits reward suppliers that can show low effective doses in plant trials.
What limits reliable defoamer supply and quality?
Siloxane supply in Europe is narrowing. Dow has shut its basic siloxanes operations at Barry, a closure it planned to right-size regional capacity and reduce merchant sales exposure. Elkem's silicones business now operates under Bluestar's majority ownership. Fewer merchant sources leave European formulators more exposed to import logistics and freight costs. Wacker tied its 2026 price rise to supply chain disruption from the conflict in the Middle East.
Product consistency matters as much as supply. Evonik lists defoaming persistence under high shear and stable performance after storage among the claims for TEGO Foamex 8051. Buyers test these properties in qualification trials before they approve a grade. A failed batch can halt a paper machine or a paint line, so buyers rarely switch without fresh trials.
Where can defoamer suppliers win additional business?
Suppliers can win share by adding local capacity and service near growing process clusters. Solenis expects the Beihai site to start operating in 2027. Kemira bought ANMAC Water Treatment Service in the United States in July 2026 and REPUR in Italy in August 2026. Water and Wastewater Treatment is one of the application segments here, and it overlaps with the water and wastewater treatment chemicals market. Specialty silicone capacity is another route, as Shin-Etsu's JPY 80.0 billion programme shows.
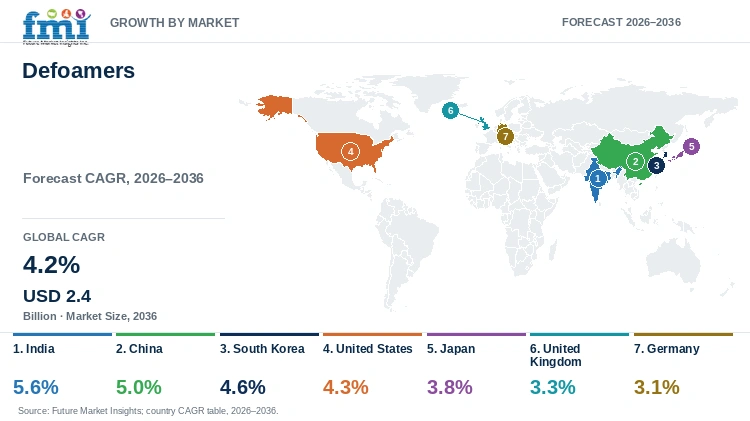
Defoamers Market by Country (2026 to 2036)
Table 5: Defoamers Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
| India | 5.6% |
| China | 5.0% |
| South Korea | 4.6% |
| United States | 4.3% |
| Japan | 3.8% |
| United Kingdom | 3.3% |
| Germany | 3.1% |
Source: Future Market Insights analysis of the defoamers market, 2026.
India
Indian paper mills are running faster than most of their peers. The Ministry of Statistics and Programme Implementation recorded 10.1% growth in paper and paper products output in June 2026. Growth reached 11.7% across April to June. Textile output rose 14.3% and food products rose 7.1% over the same quarter. Manufacturing as a whole grew 6.3% in that period. All three industries are application segments for defoamers.
Chemical production tells a different story. Output of chemicals and chemical products fell 0.6% in April to June 2026. The Department of Chemicals and Petrochemicals reported production of major chemicals and petrochemicals of 58,617 thousand tonnes in 2024-25. Capacity utilisation across those plants was 83.8%. Indian defoamer demand therefore leans on paper, textile and food lines more than on bulk chemical sites.
That mix places India first in the profiled group, with a 5.6% CAGR during 2026 to 2036. New paper and textile capacity has to be qualified during start-up. Suppliers with local application laboratories can run trials at the mill and secure the first supply contract. Imported silicone grades also carry freight and currency exposure. The Department of Chemicals and Petrochemicals also reports that output of chemical products grew at an 11.6% CAGR over five years at current prices. A larger domestic chemical base gives formulators more local raw material options.
China
Chinese demand rests on the breadth of its factory base. The National Bureau of Statistics reported that industrial value added rose 5.3% in January to September 2026. Food manufacturing grew 8.3% and textiles 3.2% over the same months. Raw chemical materials and chemical products grew 3.6%. That spread of growth reaches most of the application segments in this market.
Base chemical output supports local formulation. China produced 87.0 million tonnes of chemical fibre in 2025, up 4.9%. Caustic soda output rose 5.0% to 46.5 million tonnes. Total industrial value added rose 5.8% for the year to CNY 41,682.6 billion. Industrial value added then grew 5.5% in September 2026 alone, and manufacturing grew 6.0%. Ample domestic supply of base chemicals gives Chinese blenders a cost base that importers find hard to match.
International suppliers are adding plants close to Chinese mills. Solenis started building a site in Beihai in April 2026 with annual capacity of 60,000 tonnes. Its output will include defoamers, and the project costs RMB 250.0 million, about USD 35.0 million. Silicone ownership is also moving towards Chinese groups. Bluestar assumed majority control of Elkem's silicones division in April 2026. China's 5.0% CAGR across 2026 to 2036 rests on that broad output growth. The rate remains below India's because Chinese textile output is growing far more slowly than India's. Foreign suppliers will need local production to compete on price.
South Korea
An export manufacturing upswing is lifting South Korean plant activity. The Ministry of Economy and Finance reported that industrial production rose 4.2% year on year in June 2026. Exports grew 62.8% to USD 98.9 billion in July. Exports of semiconductors, ships, cosmetics and cars all increased. Output in the industrial sector rose 5.8% year on year in June.
Petrochemical producers are restructuring at the same time. The 2026 tax revision bill provides corporate income tax support for business restructuring in the petrochemical industry. Consolidation of bulk capacity can push domestic chemical firms towards specialty products and the additives those products need. That shift would favour defoamer suppliers with specialty grades. Restraint in commodity chemicals and strength in exports frame a South Korean outlook of 4.6% CAGR from 2026 to 2036, third among the profiled countries.
A Korean group also owns Momentive, a silicone antifoam supplier. KCC Corporation completed its acquisition of the remaining ownership of Momentive Performance Materials in May 2024. Momentive sells silicone antifoam for paints and inks as well as food processing and fermentation. It describes that grade as compositionally compliant with several US indirect food additive rules. Local ownership gives Korean buyers a direct route to a full silicone range. Cosmetics exports matter as well, since household and personal care is one of the application segments. A slowdown in chip or ship exports would cut factory hours and defoamer orders quickly.
United States
US paper capacity is contracting, but the mills that remain run hard. AF&PA reported that paper and paperboard production fell 3.7% to 66.3 million tons in 2025. Containerboard mills still ran at 91.9%. Printing-writing capacity fell 13.9% to 7.7 million tons. Tissue production declined 0.8% to 7.8 million tons. Containerboard capacity itself fell 5.1%, and total fibre consumption dropped 3.5%.
Paper offers little volume growth on current evidence. The Federal Reserve's paper production index stood at 79.1 in August 2026 against a 2017 base of 100.0. Food and water treatment offer more. Ecolab reported 8.0% growth in Food and Beverage and a return to growth in Paper and Heavy Water in its third-quarter 2026 results. Those gains show where service-led suppliers find new US accounts. Treatment plants and food processors also buy on service response times, which favours suppliers with field staff near the plant.
Food rules shape product choice. US regulations limit dimethylpolysiloxane to 10 ppm in the food as consumed and to zero in milk. Suppliers must prove effect at low doses to stay inside those limits. Dow's downstream silicones volume rose across all regions in the same quarter. With food processing and water treatment offsetting weak graphic paper, US demand is set to grow at a 4.3% CAGR between 2026 and 2036. Buyers will press suppliers to show cost per unit of output, since many mills have cut capacity.
Japan
Japanese paper output is still shrinking. The Ministry of Economy, Trade and Industry reported that pulp, paper and paper products production fell 5.5% year on year in May 2026. It also fell 3.6% from April. Shipments fell 5.5% on the year, and inventories were 6.6% lower. Mills that cut output buy less foam control.
Food processing offers steadier demand under strict rules. Japan permits silicone resin in all foods at up to 0.050 g/kg and only for defoaming. That standard gives silicone a defined and narrow role in food plants. Suppliers must keep dosing records that show compliance at each site.
Domestic silicone capacity supports specialty grades. Shin-Etsu reported net sales of JPY 1,420.7 billion for April to September 2026, up 10.6%. It is investing JPY 80.0 billion to reinforce capacity for silicone advanced functional products. The company says that new capacity is starting up gradually. The company also plans to accelerate launches of proprietary products that use silicones. Japan ranks fifth of the seven profiled countries, at a 3.8% CAGR for 2026 to 2036. Growth will come from higher value per kilogram more than from extra tonnes. Formulators that serve food and specialty chemical plants can hold their margins as paper customers shrink. Paper mill accounts will turn on cost savings per tonne, since volume gains are unlikely.
United Kingdom
The United Kingdom has lost a domestic source of basic siloxanes. Dow planned to shut its Barry operations by mid-2026. Its third-quarter 2026 results referred to the recent shutdown of the plant. UK formulators of silicone defoamers lose a nearby merchant supplier as a result. Freight and lead time now weigh more heavily in their purchasing.
Manufacturing output is mixed. The Office for National Statistics reported that manufacturing rose 1.2% in the three months to June 2026 against a year earlier. Total production rose only 0.3% on the same basis. Chemicals output fell 4.0% and wood, paper and printing fell 1.5%. Basic pharmaceutical products rose 2.6%, and food, beverages and tobacco rose 0.3%. Pharmaceutical output then fell 5.1% in June alone after two monthly gains. Pharmaceuticals are one of the application segments, so their quarterly growth softens the chemical decline. That mix of falling chemicals and uneven pharmaceutical output points to 3.3% CAGR for UK defoamer demand in 2026 to 2036.
Paper remains a meaningful base. Forest Research reported 3.3 million tonnes of UK paper and paperboard production in 2024, up 2.0% on the previous year. Most of that output uses recovered wastepaper or imported pulp. Suppliers with UK blending sites and technical staff can still win paper and pharmaceutical accounts. Short delivery times matter more once a nearby feedstock source has gone.
Germany
German papermaking is moving decisively towards packaging. Die Papierindustrie reported total output of 18.7 million tonnes in 2025, down 2.5%. Packaging paper and board rose 1.8% to 12.5 million tonnes. Case materials and core tube board rose 3.0% to 10.0 million tonnes. Graphic papers fell 16.7%. The number of mills fell from 139 to 133.
Mills recycle more fibre and water than in the past. The recovered paper utilisation rate reached 85.0% in 2025. Specific wastewater volume fell to 8.4 litres per kilogram in 2024 from 12.5 in 2000. Tighter water circuits can concentrate dissolved material in the process water. That gives packaging mills a reason to keep buying foam control even as total output falls.
Cost recovery matters more than volume in this market. Industry turnover fell 5.0% to EUR 14.2 billion in 2025. Power input still rose 3.5% to 14,543 GWh as energy use per tonne climbed. Wacker raised silicone and polymer prices in the second quarter of 2026 and passes added energy and raw material costs to customers. Mills under margin pressure will resist those increases at contract renewal. With packaging gains offset by the graphic paper decline, Germany shows the slowest rate in the profiled group at 3.1% CAGR over 2026 to 2036. Supplier revenue will depend on price and mix. Grades that cut dosage per tonne will find the readiest buyers.
Who are the notable companies in the Defoamers Market?
Dow, Wacker Chemie, Solenis and Kemira show the main commercial positions in defoamers. Dow and Wacker produce silicones and sell grades to formulators and end users. Solenis and Kemira supply process chemicals to paper mills and water treatment plants.
The silicone producers are managing cost and capacity. Dow lifted Performance Materials and Coatings sales 8.0% to USD 2.3 billion in the third quarter of 2026. Local price rose 5.0% and volume rose 3.0%, led by downstream silicones. Wacker grew silicones EBITDA 18.0% to EUR 123.0 million in the second quarter on cost savings and product mix.
The service-led suppliers compete on mill presence. Solenis operates 78 manufacturing facilities and 16 R&D centres. It is also adding papermaking chemical capacity in southern China. Kemira grew third-quarter revenue 3.0% to EUR 708.9 million, mainly through acquisitions. Its Fiber Essentials margin fell as Nordic pulp demand stayed subdued. Kemira also completed its purchase of SIDRA Wasserchemie in Germany in early October 2026. Buyers should compare trial support and price adjustment terms as closely as unit price.
Key Developments in the Defoamers Market
- On 16 April 2026, Solenis began construction of a papermaking chemicals facility in Beihai in Guangxi with 60,000 tonnes of annual capacity. Defoamers are among its planned products, and operations are expected to begin in April to June 2027.
- On 30 April 2026, Elkem completed the sale of the majority of its Silicones division to Bluestar. The deal was settled through the redemption of Bluestar's 52.9% shareholding in Elkem.
Key Players in the Defoamers Market
- Dow Inc.
- Wacker Chemie AG
- Shin-Etsu Chemical Co., Ltd.
- Bluestar Silicones
- Evonik Industries AG
- BASF SE
- Kemira Oyj
- Solenis
- Ecolab Inc.
- BYK (ALTANA AG)
- Momentive Performance Materials (KCC Corporation)
- Ashland Inc.
- Elementis plc
- Hubbard-Hall Inc.
- Blackburn Chemicals Ltd.
- Accepta Ltd.
Defoamers Market Report Scope
Table 6: Defoamers Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Silicone, oil, polymer, emulsion and powder additives that prevent or break foam in aqueous and solvent-based process liquids, including paints, paper stock, food, pharmaceuticals and wastewater. |
| Product Type | Silicone; Oil; Polymer; Emulsion; Powder |
| Medium of Dispersion | Aqueous Systems; Solvent-based Systems |
| Application | Pulp and Paper; Paints and Coatings; Water and Wastewater Treatment; Food Processing; Chemicals; Construction Materials; Textile; Household and Personal Care; Pharmaceuticals |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | India, China, South Korea, United States, Japan, United Kingdom, Germany |
| Companies covered | Dow Inc.; Wacker Chemie AG; Shin-Etsu Chemical Co., Ltd.; Bluestar Silicones; Evonik Industries AG; BASF SE; Kemira Oyj; Solenis; Ecolab Inc.; BYK (ALTANA AG); Momentive Performance Materials (KCC Corporation); Ashland Inc.; Elementis plc; Hubbard-Hall Inc.; Blackburn Chemicals Ltd.; Accepta Ltd. |
| Analytical subjects | Process output, siloxane and oil input costs, siloxane and food-contact rules, technical service and supplier capacity |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the defoamers market, 2026.
Defoamers Market Research Methodology
The defoamers assessment draws on national industrial production statistics, paper industry association data, regulatory texts and company disclosures. FMI measures annual sales value of additives used to prevent or break foam in aqueous and solvent-based process liquids. Segment values are classified by product type, medium of dispersion and application. Country forecasts reflect local process output, input costs and regulation over the same 2026 to 2036 period. Paper output, chemical production and supplier pricing are reviewed as separate measures.
Defoamers Market by Segments
Defoamers Market segmented by Product Type:
- Silicone
- Oil
- Polymer
- Emulsion
- Powder
Defoamers Market segmented by Medium of Dispersion:
- Aqueous Systems
- Solvent-based Systems
Defoamers Market segmented by Application:
- Pulp and Paper
- Paints and Coatings
- Water and Wastewater Treatment
- Food Processing
- Chemicals
- Construction Materials
- Textile
- Household and Personal Care
- Pharmaceuticals
Defoamers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Cepi (Confederation of European Paper Industries). (2026, July 2). Press release: 2025 Key Statistics.
- [2] American Forest & Paper Association. (2026, May 29). AF&PA Releases 66th Annual Paper Industry Capacity and Fiber Consumption Survey.
- [3] Ministry of Statistics and Programme Implementation, Government of India. (2026, July 28). Quick Estimates of Index of Industrial Production, June 2026. Press Information Bureau. https://static.pib.gov.in/WriteReadData/specificdocs/documents/2026/jul/doc2026728935801.pdf
- [4] National Bureau of Statistics of China. (2026, October 20). Industrial Production Operation in September 2026.
- [5] National Bureau of Statistics of China. (2026, February 28). Statistical Communiqué of the People's Republic of China on the 2025 National Economic and Social Development. https://www.stats.gov.cn/english/PressRelease/202602/t20260228_1962661.html
- [6] Wacker Chemie AG. (2026, March 20). WACKER raises prices for silicone products effective 1 April 2026. https://www.wacker.com/cms/media/de/documents/pressrelease-pdf/pm2026/silicones_prices_ii.pdf
- [7] Wacker Chemie AG. (2026, July 30). Second-quarter 2026 results press release. https://www.wacker.com/cms/media/de/documents/pressrelease-pdf/pm2026/wacker_q2_2026.pdf
- [8] Kemira Oyj. (2026, October 23). Kemira Oyj's January-September 2026 Interim Report: Revenue increased mainly driven by acquisitions, profitability burdened by high raw material costs.
- [9] Solenis. (2026, April 16). Solenis Breaks Ground on New 60,000-Tonne Production Facility in Beihai, Guangxi. https://www.solenis.com/en/resources/news-releases/2026/solenis-breaks-ground-on-new-60000-tonne-production-facility-in-beihai-guangxi/
- [10] Solenis. (2026, October 6). Solenis Relocates Pulp Center of Excellence to Brazil to Accelerate Innovation for the Global Pulp Industry. https://www.solenis.com/en/resources/news-releases/2026/solenis-relocates-pulp-center-of-excellence-to-brazil-to-accelerate-innovation-for-the-global-pulp-industry/
- [11] Solenis. (2026). News releases, including Solenis Announces Energy Surcharge Following Middle East Conflict (18 March 2026), accessed 3 November 2026. https://www.solenis.com/en/resources/news-releases/
- [12] Elkem ASA. (2026). Sale of the majority of the Silicones division to Bluestar: transaction overview, accessed 3 November 2026. https://www.elkem.com/transaction
- [13] Dow Inc. (2026, October 22). Dow Reports Third Quarter 2026 Results. https://s23.q4cdn.com/981382065/files/content_files/Dow-3Q26-Earnings-News-Release.pdf
- [14] Dow Inc. (2026). Form 10-K for the fiscal year ended December 31, 2025. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/1751788/000175178826000018/dow-20251231.htm
- [15] Ecolab Inc. (2026, October 27). Third Quarter 2026 Earnings Release. https://s204.q4cdn.com/218790897/files/content_files/Q3-2026-Earnings-Release.pdf
- [16] European Commission. (2024, May 16). Commission Regulation (EU) 2024/1328 amending Annex XVII to Regulation (EC) No 1907/2006 as regards D4, D5 and D6. Official Journal of the European Union. https://www.moew.government.bg/static/media/ups/articles/attachments/OJ_L_202401328_EN_TXT3bb31a3161bcab20b2f3051abd65574c.pdf
- [17] U.S. Food and Drug Administration. (2026). 21 CFR 173.340 Defoaming agents. Electronic Code of Federal Regulations, up to date as of 19 October 2026. https://www.ecfr.gov/current/title-21/chapter-I/subchapter-B/part-173/subpart-D/section-173.340
- [18] Ministry of Health, Labour and Welfare, Japan. (2021, February 3). Standards for Use of Food Additives (English translation). Japan Food Chemical Research Foundation. https://www.ffcr.or.jp/en/upload/StandardsforUseFeb32021.pdf
- [19] European Parliament and Council of the European Union. (2004, April 21). Directive 2004/42/EC on the limitation of emissions of volatile organic compounds in certain paints and varnishes and vehicle refinishing products. https://legislation.gov.uk/eudr/2004/42/pdfs/eudr_20040042_adopted_en.pdf
- [20] Evonik Industries AG. (2025, June 4). Evonik Coating Additives launches TEGO Foamex 8051, a highly efficient, long-lasting siloxane defoamer. https://www.evonik.com/en/news/press-releases/2025/06/evonik-coating-additives-launches-tego-foamex-8051.html
- [21] BYK-Chemie GmbH. (2026, July 3). BYK team wins the ALTANA Innovation Award. https://www.byk.com/zh/company-news/news/detail/byk-team-wins-the-altana-innovation-award
- [22] Board of Governors of the Federal Reserve System. (2026, September 18). Industrial Production and Capacity Utilization, G.17, Monthly Supplement, Table 1B. https://www.federalreserve.gov/RELEASES/g17/20260918/table1b_sup.htm
- [23] Shin-Etsu Chemical Co., Ltd. (2026, October 27). Consolidated Financial Results for the Second Quarter of the Fiscal Year Ending March 31, 2027. https://www.shinetsu.co.jp/wp-content/uploads/2026/07/20261027_con_E.pdf
- [24] Ministry of Economy, Trade and Industry, Japan. (2026). Indices of Industrial Production, May 2026 (preliminary report). https://www.meti.go.jp/statistics/tyo/iip/result/book/b2020_202605sj.html
- [25] Office for National Statistics. (2026, August 13). Index of Production, UK: June 2026. https://www.ons.gov.uk/economy/economicoutputandproductivity/output/bulletins/indexofproduction/june2026/pdf
- [26] Forest Research. (2025, September 25). Forestry Statistics 2025, Chapter 2: UK-Grown Timber. https://cdn.forestresearch.gov.uk/2025/09/FS2025_Ch2.pdf
- [27] Die Papierindustrie e.V. (2026). Papier 2026: Ein Leistungsbericht. https://www.papierindustrie.de/fileadmin/0002-PAPIERINDUSTRIE/00_Bilder/Leistungsbericht_Papier_2026.pdf
- [28] Department of Chemicals and Petrochemicals, Government of India. (2026). Annual Report 2025-26. https://chemicals.gov.in/sites/default/files/Reports/annual_report_2025-26_Eng_1.pdf
- [29] Ministry of Economy and Finance, Republic of Korea. (2026, September). Economic Bulletin (The Green Book), Vol. 48 No. 9. Korea Development Institute. https://eiec.kdi.re.kr/userdata/eco_bul/202609/202609.pdf
- [30] Momentive Performance Materials Inc. (2024, May 14). KCC Corporation Completes Acquisition of Momentive Performance Materials Group. https://www.momentive.com/en-us/news-events/kcc-corporation-completes-acquisition-of-momentive-performance-materials-group
- [31] Momentive Performance Materials Inc. (2026). AF9000NE Silicone Antifoam product information, accessed 3 November 2026. https://www.momentive.com/en-us/product-categories/additives/antifoams-defoamers/food-beverage-antifoams/af9000nesiliconeantifoam
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Silicone
- Oil
- Polymer
- Emulsion
- Powder
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Medium of Dispersion, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Medium of Dispersion, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Medium of Dispersion, 2026 to 2036
- Aqueous Systems
- Solvent-based Systems
- Y-o-Y Growth Trend Analysis By Medium of Dispersion, 2021 to 2025
- Absolute $ Opportunity Analysis By Medium of Dispersion, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Pulp and Paper
- Paints and Coatings
- Water and Wastewater Treatment
- Food Processing
- Chemicals
- Construction Materials
- Textile
- Household and Personal Care
- Pharmaceuticals
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Medium of Dispersion
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Medium of Dispersion
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Medium of Dispersion
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Medium of Dispersion
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Dow Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Wacker Chemie AG
- Solenis
- Kemira Oyj
- Ecolab Inc.
- Shin-Etsu Chemical Co., Ltd.
- Bluestar Silicones
- Evonik Industries AG
- BASF SE
- BYK (ALTANA AG)
- Momentive Performance Materials (KCC Corporation)
- Ashland Inc.
- Elementis plc
- Hubbard-Hall Inc.
- Blackburn Chemicals Ltd.
- Accepta Ltd.
- Dow Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Medium of Dispersion, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Medium of Dispersion
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Medium of Dispersion
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Medium of Dispersion
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Medium of Dispersion
- Figure 49: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Medium of Dispersion
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Medium of Dispersion
- Figure 69: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Medium of Dispersion
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Medium of Dispersion, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Medium of Dispersion, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Medium of Dispersion
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Defoamers Market in 2026?
FMI estimates the market at USD 1.6 billion in 2026, up from USD 1.5 billion in 2025. It is forecast to reach USD 2.4 billion by 2036 at a 4.2% CAGR.
Which application leads the Defoamers Market in 2026?
Pulp and Paper leads by application with 21.4% in 2026. All other applications together hold 78.6%.
Which medium of dispersion and product type lead in 2026?
Aqueous Systems hold 68.2% by medium of dispersion and Silicone holds 38.6% by product type in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
India has the highest forecast CAGR at 5.6% during 2026 to 2036, followed by China at 5.0%. These are FMI forecasts and are not rates reported by the cited public bodies.
How do EU siloxane rules affect silicone defoamers?
From 6 June 2026 the EU restricts D4, D5 and D6 at 0.1% by weight or more in mixtures. Residues from silicone polymers are exempt within use-specific maximum levels [16].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
