
- Market Size (2026)
- USD 7.3 Bn
- Forecast (2036)
- USD 65.8 Bn
- CAGR (2026 to 2036)
- 24.6%
How big is the Electrolyzer Market in 2026?
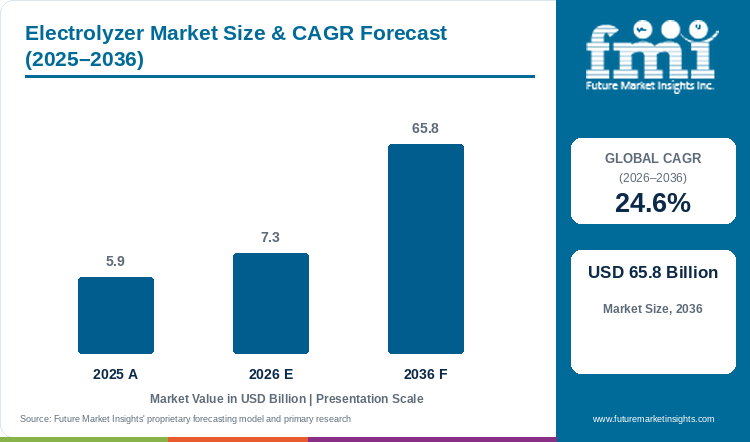
The global electrolyzer market is estimated at USD 7.30 billion in 2026, compared with USD 5.86 billion in 2025, and is forecast to reach USD 65.83 billion by 2036, expanding at a CAGR of 24.6% from 2026 to 2036.
The alkaline electrolyzer segment holds 52.4% by technology, systems above 2 MW 44.8% by capacity and the ammonia and fertilizer segment 26.9% by application in FMI's 2026 assessment. Large industrial projects support equipment spending when they move from an award to installation. Stegra completed installation of its final electrolyzer module on 2 April 2026, with pre-commissioning and commissioning still ahead. Plug Power reported installation of 100 MW of PEM equipment at Galp's Sines refinery in January 2026 and said commissioning was expected in subsequent months. The equipment milestones support a purchase cycle that precedes hydrogen production.
FMI finds that the constraint is the number of projects able to fund construction and sell their hydrogen. The IEA reports that installed electrolysis capacity doubled in 2025 to exceed 4 GW, with more than 2.5 GW under construction for intended operation in 2026. New investment decisions for low-emissions hydrogen nevertheless fell below 0.8 million tonnes a year of production capacity in 2025, after two years around 1 million.
Key Market Trends & Insights
- Nel's second-quarter 2026 disclosure attributed 96% of its NOK 230 million order intake to PEM. A quarter's new orders can differ sharply from an installed technology mix, making a supplier's backlog a better guide to its own workload than a global capacity ranking.
- Air Liquide's Normand'Hy plan allocates three-quarters of its 200 MW production capacity to industry and one-quarter to mobility. A single electrolyzer site can therefore serve several buyers rather than depending on a new hydrogen application to absorb all output.
Regional Highlights
- In East Asia, China accounted for nearly three-quarters of new global electrolysis installations in 2025, according to the IEA. Its large-project experience supports a supplier reference base, while surplus manufacturing capacity is increasing competitive pressure.
- In Europe, the Hydrogen Bank's May 2026 selection covered nine projects expected to install almost 1.1 GW. Four reserve projects, planning a further 77 MW, were invited to prepare grant agreements in June. The 13-project pipeline is therefore a sequence of support and construction decisions, rather than commissioned equipment.
Table 1: Electrolyzer Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 5.86 billion |
| Estimated market size in 2026 | USD 7.30 billion |
| Projected market size by 2036 | USD 65.83 billion |
| CAGR from 2026 to 2036 | 24.6% |
| Added revenue from 2026 to 2036 | USD 58.53 billion |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
Analyst Perspective
“Electrolyzer factories can have capacity while hydrogen projects wait for electricity, funding or a buyer. The order that matters is a contracted plant with a route to operate, not an announced gigawatt total.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Electrolyzer Market segmented?
Technology classifies the water-electrolysis system; capacity is the rated capacity of the completed system, rather than an individual stack. Applications follow the principal immediate contracted use of the hydrogen or system. Refining, chemicals and other industrial processing includes steelmaking, cement and other industrial process demand, with ammonia and fertilizer production classified separately. Power Generation & Grid Balancing includes power-to-gas and energy storage where that is the principal function; direct hydrogen transport and refuelling belong to Mobility & Transportation. Ammonia manufacture remains in Ammonia & Fertilizer even if its product is later sold as fuel. Industrial-gas companies are a buyer and supply role: their refinery supply projects and a refinery's own equipment purchases share the same application. Mixed-purpose contracts follow their documented principal use or a supported separate allocation, without counting the same equipment twice.
- By Technology: PEM electrolyzer, Alkaline electrolyzer segment, Solid oxide electrolyzer and Anion exchange membrane (AEM) electrolyzer.
- By Capacity: Below 500 kW, 500 kW to 2 MW inclusive and Above 2 MW.
- By Application: Ammonia and fertilizer segment; Refining, chemicals and other industrial processing; Power Generation & Grid Balancing; Mobility & Transportation.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does the alkaline electrolyzer segment lead by technology?
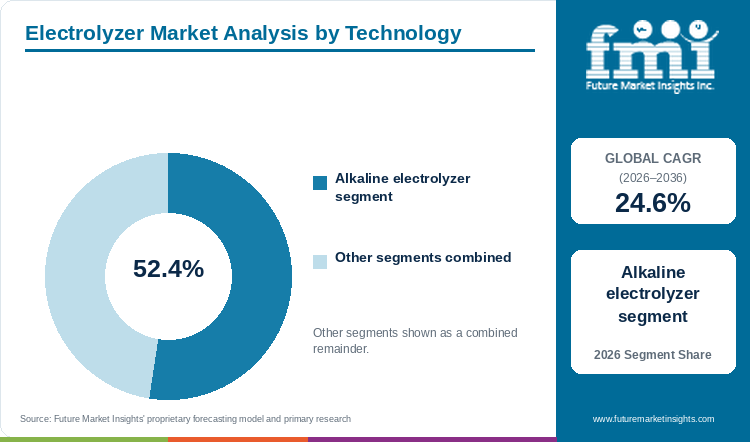
The alkaline electrolyzer segment holds 52.4% of the electrolyzer market by technology in 2026, in FMI's assessment.
Alkaline's capital-cost position supports its use in large industrial equipment programmes. DOE identifies lower-cost materials as an advantage of alkaline systems. Thyssenkrupp nucera identified its 200 MW Shell project and 740 MW Stegra project as work under way in May 2026. ANDRITZ's March 2026 presentation identifies the 100 MW Salzgitter plant as alkaline and in execution, with start-up in 2027. These contracts put multi-module production and plant engineering within the supplier's delivery scope, rather than leaving the sale at an individual stack.
Variable operation remains a technical constraint in the DOE assessment. The distinction matters in renewable-powered projects: a low equipment price does not establish performance through repeated changes in power input. PEM, solid oxide and anion exchange membrane systems together account for 47.6% in FMI's assessment. Technology choice therefore depends on the specified operating duty as well as the equipment cost.
Table 2: Electrolyzer Market Technology Share Comparison, 2026
| Leading Share | 2026 market share |
|---|---|
| Alkaline electrolyzer segment | 52.4% |
| All Other Segments Combined Share | 47.6% |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
Why are systems above 2 MW the largest capacity category?
Systems above 2 MW hold 44.8% of the electrolyzer market by complete-system capacity in 2026, in FMI's assessment.
Large refinery and industrial hydrogen programmes concentrate equipment spending in multi-module plants. Air Liquide describes Normand'Hy as a 200 MW PEM plant under construction, while Plug reported ten arrays installed at the 100 MW Galp project. The capacity category follows the completed system serving the project, so the use of smaller stacks does not turn either order into a collection of small-capacity installations.
Construction milestones extend beyond equipment installation. NEOM Green Hydrogen Company's update places the project in final construction completion and commissioning with energisation, with product availability expected in 2027. That schedule leaves integration and commissioning work between delivery of the equipment and sale of hydrogen. Systems at or below 2 MW together hold 55.2% in FMI's assessment. Smaller industrial orders remain a separate source of business: Nel said small-scale industrial products largely drove its second-quarter 2026 PEM revenue.
Table 3: Electrolyzer Market Capacity Share Comparison, 2026
| Leading Share | 2026 market share |
|---|---|
| Above 2 MW | 44.8% |
| All Other Segments Combined Share | 55.2% |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
What supports the ammonia and fertilizer segment as the leading application?
The ammonia and fertilizer segment holds 26.9% of the electrolyzer market by application in 2026, in FMI's assessment.
Ammonia projects connect a large electrolyzer package to a synthesis and export programme. NEOM Green Hydrogen Company describes a project designed to export green ammonia and places it in final construction completion and commissioning with energisation, with product availability expected in 2027. The equipment programme therefore precedes commercial ammonia supply. Its classification follows the immediate use of electrolytic hydrogen in ammonia manufacture, even when the exported product will serve a transport or energy customer.
Shell's refinery substitution programme links a new electrolyzer to identified industrial demand. Holland Hydrogen 1 remains under construction, with commissioning expected to start in 2027. Its output is intended for the Pernis refinery, replacing part of the fossil-based hydrogen used there. The downstream use is already established; the commercial task is to deliver the new supply at the cost and reliability required by that refinery.
Existing hydrogen consumption is much larger than the market for new electrolysis equipment. Industry and refining accounted for almost all global hydrogen demand in 2025, but only around 20% of newly signed hydrogen offtake volumes that year carried firm contractual commitments, according to the IEA. An established application therefore does not remove the contracting constraint. Refining, chemicals and other industrial processing, Power Generation & Grid Balancing, and Mobility & Transportation together account for 73.1% in FMI's assessment. Their equipment programmes also depend on the timing of the downstream plant or delivery route.
Table 4: Electrolyzer Market Application Share Comparison, 2026
| Leading Share | 2026 market share |
|---|---|
| Ammonia and fertilizer segment | 26.9% |
| All Other Segments Combined Share | 73.1% |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
What are the key drivers restraints and opportunities?
The forecast adds USD 58.53 billion between 2026 and 2036. Public support can close part of the hydrogen cost gap, while construction delays postpone equipment revenue. The growing operating fleet also creates an adjacent maintenance business outside this equipment-market total.
Driver
The European Hydrogen Bank supports a developer's production revenue rather than purchasing equipment. Its third auction offers a fixed premium on verified and certified hydrogen production for up to ten years, including a topic for electrolytic low-carbon hydrogen alongside renewable hydrogen. This ties the public payment to an operating plant's output. Equipment suppliers benefit through projects that can finance construction against those supported hydrogen revenues.
Restraint
The investment-decision stage remains a bottleneck. The IEA records lower new final investment decisions in 2025 despite a larger installed fleet. Factories built for an announced pipeline can therefore operate below capacity while customers delay projects. Suppliers bear the cost of maintaining engineering and manufacturing capability before revenue arrives.
Opportunity
Maintenance already produces a separate revenue stream for equipment suppliers. ITM Power reported GBP 1.253 million from maintenance contracts in the year ended 30 April 2026, compared with GBP 0.900 million a year earlier. It separately reported engineering consultancy and product sales. FMI sees an opportunity in supporting the installed fleet through maintenance contracts, with revenue tied to operating equipment rather than another construction award. Recurring maintenance revenue is outside this report's hardware and direct equipment-integration forecast.
How do quality and clean hydrogen rules affect purchasing?
Rules attach to hydrogen production and its electricity supply as well as to equipment. In South Korea, the clean hydrogen bidding market requires fuel meeting a lifecycle emissions limit of no more than 4 kg CO2e per kilogram of hydrogen. The rule does not reserve the market for electrolysis. FMI finds that an electrolyzer bidder must show how its proposed power and operating arrangement produces eligible hydrogen, while competing with other qualifying routes. A rated megawatt figure alone cannot establish that eligibility.
What limits reliable electrolyzer operation?
Renewable-power variability creates different operating duties for alkaline and PEM equipment. The World Bank's 2026 technical assessment finds that PEM is better suited to rapid power fluctuations, while large projects often favour alkaline's lower cost and commercial availability. It reports hybrid solar-wind supply and battery storage among the ways developers manage that variability. DOE also treats efficiency, durability and cost as separate technical objectives. A comparison based on rated megawatts alone therefore misses the operating conditions that determine output and component life.
Where can suppliers win additional business?
A build, own and operate contract extends an equipment supplier's role into hydrogen production. ITM's Hydropulse signed heads of terms for a 150 MW European refinery project in October 2026, with a front-end engineering study under way and an investment decision targeted in 2027. The planned arrangement puts plant development and operation within Hydropulse's offer to the refinery. Definitive agreements and financing still precede construction, so the opportunity remains a development-stage hydrogen-supply contract. Equipment sold into such a plant is counted at the equipment-invoice boundary; the subsequent hydrogen sales are separate.
Electrolyzer Market by Country (2026 to 2036)
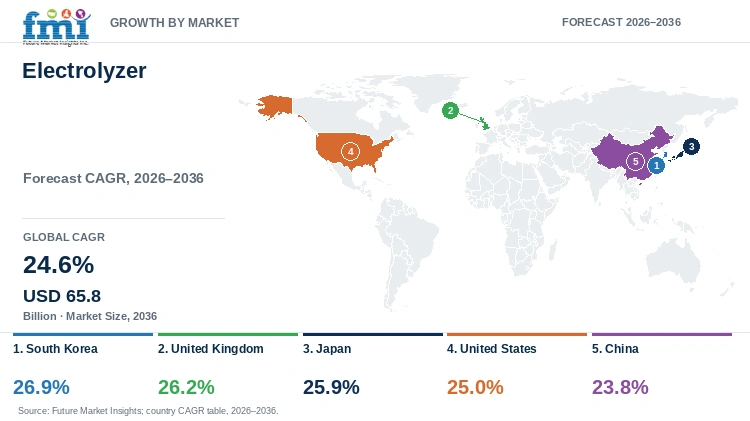
FMI's country forecasts reflect different routes from public support to domestic equipment orders. Power auctions, industrial support and existing project execution affect the timing in each market.
Table 5: Electrolyzer Market Country CAGR Comparison, 2026 to 2036
| Country | CAGR |
|---|---|
| South Korea | 26.9% |
| United Kingdom | 26.2% |
| Japan | 25.9% |
| United States | 25.0% |
| China | 23.8% |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
What supports electrolyzer demand in South Korea?
South Korea's power auctions create a long-term fuel market without reserving it for domestic electrolysis. The 30 October 2026 announcement offered 500 GWh a year in the clean-hydrogen track and 930 GWh a year in the general track. Clean-track fuel must meet a lifecycle limit of 4 kg CO2e per kilogram of hydrogen. The qualifying route and fuel origin therefore determine whether an award produces a Korean electrolyzer order.
The clean track provides a 15-year trading period, with generation due to begin by 2030 after project preparation; preferred bidders are scheduled for selection around June 2027. The government raised the non-price weighting from 40% to 50%, including fuel-supply security and industrial and economic contribution. This gives a domestic supply proposal a wider commercial test than the electricity bid price alone. Auction electricity volumes remain distinct from the megawatts of electrolysis required by any successful fuel supplier.
Domestic deployment is also advancing outside that auction. In September 2026, the ministry reported that Jeju's 3.3 MW Haengwon facility had produced about 200 kg of hydrogen a day since September 2024, supplying 17 hydrogen buses and passenger cars. This is an operating local production-and-delivery reference, rather than an announced manufacturing target.
FMI's 26.9% CAGR forecast for South Korea from 2026 to 2036, the highest among the five countries analysed, reflects expansion from these early domestic projects. Growth depends on converting eligible hydrogen demand into funded local equipment programmes; fuel imports and other qualifying production routes remain competing ways to serve the power market.
What turns the United Kingdom's pipeline into equipment demand?
The United Kingdom's allocation process is testing the cost of hydrogen before converting its project list into contracts. HAR2 shortlisted 27 projects representing about 765 MW in April 2025. The March 2026 parliamentary answer said due diligence and cost assurance were complete and projects that passed would enter an Invite to Offer stage, with contracts targeted for 2026. These are different stages of procurement: the shortlist identifies potential demand, while an award makes the revenue-support terms available to the successful developer.
The cost-assurance process reaches into the equipment offer. DESNZ asked shortlisted projects for measurable cost reductions, lower average hydrogen production costs than HAR1, financial information, and project data covering offtakers and output. Equipment price, plant configuration and hydrogen sales are consequently considered within the same project assessment. FMI's 26.2% CAGR forecast for the UK electrolyzer market from 2026 to 2036 follows the conversion of this supported pipeline into industrial installations, with engineering and delivery timing dependent on contract outcomes.
First-round projects show that this demand spans distinct local uses. Bradford's 24.5 MW alkaline scheme is intended to supply mobility customers, including JCB and Wrightbus; Cromarty's 11 MW project is intended to use nearby wind power to supply local industries, including distilleries. The government's April 2025 statement recorded signed support contracts for both. Their different end users and power arrangements give suppliers separate industrial and mobility references as the UK builds its operating fleet.
How does Japan's support framework affect domestic orders?
Aichi Steel's planned Chita project identifies both the equipment route and its industrial customer. Toyota Tsusho, Eurus Energy and Iwatani announced certification under Japan's price-gap support scheme in September 2025. Their proposal targets around 1,600 tonnes of hydrogen a year from wind-powered electrolysis, replacing natural gas in some steel-heating furnaces, with operation around 2030. It is a captive fuel-substitution project whose engineering and installation remain ahead.
The announced configuration also identifies an equipment supply chain: a Chiyoda system using Toyota Motor stacks, with a joint project company planned for March 2027. The scheme supports the gap between low-carbon hydrogen and conventional fuel prices for 15 years. For this project, long-term fuel support accompanies an on-site production model; it is not simply a grant to expand stack-manufacturing capacity.
Imported fuels follow a different route. JOGMEC's February 2026 support award to JERA covers low-carbon ammonia produced in Louisiana for Hekinan power station and industrial furnace users including Toyota Industries, AGC, NGK Insulators and AISIN Fukui. Those users enlarge the supported hydrogen-related fuel market without requiring a Japanese electrolyzer at each site.
FMI forecasts a 25.9% CAGR for Japan's electrolyzer market from 2026 to 2036. The local equipment opportunity lies in domestic electrolysis projects such as Chita within this wider support framework. Its named wind supplier, planned stack route and furnace use provide a defined procurement case, while the ammonia award shows why total support commitments cannot be treated as domestic electrolyzer orders.
How does the United States construction deadline shape demand?
The United States has shortened the construction window for projects seeking the 45V hydrogen production credit. Construction must begin before 1 January 2028, replacing the previous 2033 cutoff. This compresses the period in which a developer must commit its plant to construction. It can advance equipment procurement among financeable projects, while leaving later proposals to establish an economic case without that credit.
Electricity eligibility still shapes the plant after construction starts. Treasury's final rules require energy-attribute certificates used to identify a particular generator to meet incrementality, deliverability and time-matching conditions. Hourly matching begins in 2030; the transition permits annual matching beforehand. That change matters to systems ordered during the remaining construction window because the electricity arrangement will operate under the tighter matching regime during the plant's life. FMI's 25.0% CAGR forecast for the US electrolyzer market from 2026 to 2036 reflects expansion of hydrogen-production equipment subject to these financing and operating conditions, with different project schedules rather than a uniform annual order increase.
US manufacturing also serves orders outside the large-project cycle. Nel reported that small-scale industrial products largely drove second-quarter 2026 PEM revenue. In September, it said PEM stack production would remain in Wallingford, Connecticut, while Hydrasun developed balance-of-plant assembly and integration in Aberdeen for European deliveries. This separates a US stack-manufacturing role from final plant integration abroad. It also shows why the location of a factory, a hydrogen user and equipment revenue should be assessed separately.
Why does China remain important at a lower forecast rate?
China's large deployment base coexists with severe pressure on equipment prices. The IEA reports that China supplied nearly three-quarters of new electrolysis installations in 2025, helped by low technology costs and large-project experience, while surplus factories intensified competition. FMI's 23.8% CAGR forecast for China from 2026 to 2036 is the lowest among the five profiled countries against that larger starting base; it does not imply a small equipment market.
The October 2026 IEA cost assessment puts the imbalance in concrete terms: China had 35 GW a year of manufacturing capacity in 2025 against demand below 2 GW. It reports auction awards as low as USD 170 per kW and associates such prices with bidding below full cost. Additional factory capacity therefore gives a poor indication of supplier earnings. Lower prices can support deployment while reducing revenue per megawatt and the margin available to finance further production.
Export sales face a different cost boundary. In the IEA's comparison, importing a Chinese stack while procuring the rest of the equipment and construction in Europe reduced total capital expenditure by 8%. Shipping, maintenance access and possible efficiency differences narrowed the advantage further. Chinese manufacturers are looking overseas as domestic competition tightens, according to the IEA's broader review. Export opportunity consequently depends on the installed offer and operating performance in the destination market, with local engineering and support retaining value alongside the imported stack.
Who are the notable companies in the Electrolyzer Market?
Nel Hydrogen, Asahi Kasei, Siemens Energy and ITM Power occupy different positions in the equipment chain. Nel supplies alkaline and PEM platforms, Asahi Kasei is scaling alkaline technology through operating demonstrations, Siemens Energy supplies industrial PEM systems, and ITM manufactures PEM equipment while developing a hydrogen-supply model through Hydropulse. Their offers differ in how much equipment, integration and plant operation sits within the contract.
The integration boundary is explicit in Nel's September 2026 Hydrasun agreement. Nel retains PEM stack production in Connecticut; Hydrasun is to procure and integrate the surrounding balance of plant in Aberdeen. Asahi Kasei's 10 MW Fukushima pilot has operated since March 2020, providing an operating reference for its alkaline programme. Siemens Energy lists industrial PEM projects in its portfolio, while Hydropulse's refinery heads of terms targets an investment decision in 2027 under a planned build, own and operate arrangement. These are distinct commercial roles and stages of delivery.
Performance obligations also affect recognised revenue. ITM's 2026 annual report records GBP 3.5 million of constrained revenue for component replacements and liquidated damages. FMI finds that the equipment sale therefore carries exposure beyond factory dispatch: component performance and contractual remedies affect what a supplier earns. The disclosed projects and agreements establish supplier capabilities; they do not establish numerical company market shares.
Key Developments in the Electrolyzer Market
- On 23 January 2026, Plug Power announced completion of the installation of 100 MW of PEM equipment at Galp's Sines refinery. The company said commissioning was expected in subsequent months; installation was the reported milestone.
- On 2 April 2026, Stegra completed installation of all 37 electrolyzer modules at its Boden site and said pre-commissioning and commissioning were the next phases.
- On 6 May 2026, Nel commercially launched its next-generation pressurised alkaline platform, as recorded in its second-quarter results. The launch did not mean that customer plants using the platform were already operating.
Key Players in the Electrolyzer Market
- Nel Hydrogen
- Asahi Kasei
- Siemens Energy
- ITM Power
- Plug Power
- Thyssenkrupp nucera
- ANDRITZ
Electrolyzer Market Report Scope
Table 6: Electrolyzer Market Report Scope, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Calendar-year seller revenue from water-electrolysis hydrogen systems, associated hardware and direct equipment integration. A completed-system invoice is counted once; embedded stack and balance-of-plant resales are not added a second time. |
| Boundaries | Excludes renewable generators, downstream storage and transport assets, hydrogen output value, unrelated project CAPEX, recurring maintenance and unpriced in-house manufacture. Externally sold equipment for merchant gas operators and captive industrial users shares the same boundary. |
| Quantitative units | USD billion for equipment-market value; percentages for shares and forecast CAGR. |
| Physical indicators | MW and GW describe completed-system or project capacity with its actual status; they are not revenue shares. Capacity bands are below 500 kW, 500 kW to 2 MW inclusive, and above 2 MW. |
| Forecast period | 2026 to 2036, with USD 5.86 billion in 2025 as the preceding reference. |
| Earlier reference values | USD 4.7 billion in 2024 and USD 42.4 billion in 2034 remain earlier reference points, separate from the current endpoints. |
| Segments covered | Technology: Alkaline electrolyzer segment, PEM, solid oxide and AEM. Four principal immediate applications: Ammonia and fertilizer segment; Refining, chemicals and other industrial processing, including steelmaking and excluding ammonia; Power Generation & Grid Balancing, including power-to-gas and energy storage; Mobility & Transportation. Mixed-purpose contracts use a documented principal use or supported separate allocation, without duplication. |
| Countries analysed | South Korea, United Kingdom, Japan, United States and China; these profiles do not bound the global totals. |
| Geographic coverage | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Competitive coverage | Equipment suppliers and integrators; technology offers, construction milestones and operating references are distinguished from company market share. |
Source: Future Market Insights, Electrolyzer Market Report, 2026 to 2036.
Electrolyzer Market Research Methodology
The assessment reviews IEA deployment data, official support programmes, engineering assessments and company project disclosures, alongside analyst market assessment. The forecast measures calendar-year seller revenue from water-electrolysis hydrogen systems, associated hardware and direct equipment integration. Completed-system invoices are counted once; embedded stack and balance-of-plant resales are not added again. External equipment sales to merchant gas operators and captive industrial users use the same boundary, while unpriced in-house manufacture is excluded. Project configurations establish technology, completed-system capacity and principal immediate use. Market values and country forecasts are checked for consistent units and periods. Installed and manufacturing capacity remain distinct from equipment revenue. The work uses secondary evidence and analyst assessment, without new interviews or a manufacturer census.
Electrolyzer Market by Segments
Electrolyzer Market segmented by Technology:
- PEM electrolyzer
- Alkaline electrolyzer segment
- Solid oxide electrolyzer
- Anion exchange membrane (AEM) electrolyzer
Electrolyzer Market segmented by Capacity:
- Below 500 kW
- 500 kW to 2 MW inclusive
- Above 2 MW
Electrolyzer Market segmented by Application:
- Ammonia and fertilizer segment
- Refining, chemicals and other industrial processing
- Power Generation & Grid Balancing
- Mobility & Transportation
Electrolyzer Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Energy Agency. Global Hydrogen Review 2026, Production. 18 June 2026.
- [2] International Energy Agency. Global Hydrogen Review 2026, Executive summary. 18 June 2026.
- [3] European Commission. IF25 Hydrogen Auction, June 2026 selected projects and grant-agreement preparation status. Accessed 31 October 2026.
- [4] US Department of Energy. Hydrogen Shot Water Electrolysis Technology Assessment. December 2024.
- [5] Republic of Korea Ministry of Climate, Energy and Environment. Opening of the 2026 Hydrogen Power Generation Bidding Market. 30 October 2026.
- [6] UK Department for Energy Security and Net Zero. Hydrogen Allocation Round 2 shortlisted projects, 7 April 2025; parliamentary answer 116036, 3 March 2026. International Energy Agency. Hydrogen Allocation Round 2 policy record, updated 5 September 2025.
- [7] Toyota Tsusho. Toyota Tsusho, Eurus Energy, and Iwatani Consider Starting Onsite Low-Carbon Hydrogen Production and Supply Project at Aichi Steel. 30 September 2025.
- [8] Japan Organization for Metals and Energy Security. JOGMEC Grants Subsidies related to Support focusing on the price gap to JERA Co., Inc. 16 February 2026.
- [9] Stegra. Final electrolyzer module installed at Stegra's green hydrogen plant. 2 April 2026.
- [10] Plug Power. Plug Power Completes Installation of 100 MW GenEco Electrolyzer Units at Galp's Sines Refinery. 23 January 2026.
- [11] Nel Hydrogen. Second quarter 2026 financial results. 15 July 2026.
- [12] Air Liquide. Air Liquide Normand'Hy project overview. Accessed 31 October 2026.
- [13] UK Department for Energy Security and Net Zero. New hydrogen power projects to boost growth. 7 April 2025.
- [14] Thyssenkrupp nucera. Signs FEED Study for a 600 MW Green Hydrogen Project in Europe. 7 May 2026.
- [15] ANDRITZ. Company presentation, industrial-scale green hydrogen for green steelmaking. March 2026.
- [16] NEOM Green Hydrogen Company. Project construction and commissioning update. Accessed 1 November 2026.
- [17] Shell. Shell Hydrogen Projects, Holland Hydrogen 1 status. Accessed 31 October 2026.
- [18] US Department of Energy. Hydrogen and Fuel Cell Technologies Office Multi-Year Program Plan, Hydrogen Production. 2024.
- [19] ITM Power. Hydropulse signs Heads of Terms for 150 MW green hydrogen project. 12 October 2026.
- [20] US Congress. Public Law 119-21, section 70511, amendment to the clean hydrogen production credit construction deadline. 4 July 2025.
- [21] Asahi Kasei. Tanahashi Prize recognises long-term operation of the 10 MW alkaline-water electrolysis system. 19 March 2026.
- [22] Siemens Energy. Green Hydrogen Production, PEM Water Electrolysis product and project portfolio. Accessed 31 October 2026.
- [23] International Energy Agency. What explains the cost advantage of Chinese electrolysers? 15 October 2026.
- [24] Republic of Korea Ministry of Climate, Energy and Environment. Jeju green-hydrogen cooperation and Haengwon electrolysis demonstration results. 13 September 2026.
- [25] US Department of the Treasury. Final Rules for Clean Hydrogen Production Tax Credit. 3 January 2025.
- [26] UK Department for Energy Security and Net Zero. Hydrogen Allocation Round 2: due diligence and cost assurance. 7 April 2025.
- [27] Nel Hydrogen. Framework agreement with Hydrasun as a European integration partner for PEM electrolyser solutions. 10 September 2026.
- [28] World Bank Energy Sector Management Assistance Program. Electrolyzers for Hydrogen Production: Technical and Economic Characteristics, executive summary. February 2026.
- [29] ITM Power. Annual Report 2026, year ended 30 April 2026, note 5, page 66. Published 19 October 2026.
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- PEM electrolyzer
- Alkaline electrolyzer segment
- Solid oxide electrolyzer
- Anion exchange membrane (AEM) electrolyzer
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Capacity, 2026 to 2036
- Below 500 kW
- 500 kW to 2 MW inclusive
- Above 2 MW
- Y-o-Y Growth Trend Analysis By Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Ammonia and fertilizer segment
- Refining, chemicals and other industrial processing
- Power Generation & Grid Balancing
- Mobility & Transportation
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Technology
- By Capacity
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology
- By Capacity
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology
- By Capacity
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology
- By Capacity
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nel Hydrogen
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Asahi Kasei
- Siemens Energy
- ITM Power
- Plug Power
- Thyssenkrupp nucera
- ANDRITZ
- Nel Hydrogen
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Technology, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Capacity, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Technology
- Figure 6: Global Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Capacity
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Technology
- Figure 26: North America Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Capacity
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Technology
- Figure 36: Latin America Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Capacity
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Technology
- Figure 46: Western Europe Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Capacity
- Figure 49: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Technology
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Capacity
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Technology
- Figure 66: East Asia Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Capacity
- Figure 69: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Technology
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Capacity
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Technology, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Technology, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Technology
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Capacity, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Capacity, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Capacity
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
What is the forecast for the Electrolyzer Market?
The market is USD 5.86 billion in 2025 and is estimated at USD 7.30 billion in 2026. FMI forecasts USD 65.83 billion by 2036, at a 24.6% CAGR from 2026 to 2036.
Which technology leads the Electrolyzer Market?
The alkaline electrolyzer segment holds 52.4% by technology in FMI's 2026 assessment.
Which capacity and application categories lead?
Systems above 2 MW hold 44.8% by complete-system capacity and the ammonia and fertilizer segment 26.9% by principal immediate application in 2026.
Which profiled country has the highest growth forecast?
South Korea has the highest forecast CAGR at 26.9%, followed by the United Kingdom at 26.2% and Japan at 25.9% from 2026 to 2036.
Does an installed electrolyzer mean a project is producing hydrogen?
Installation can precede commissioning. Plug's January 2026 Galp announcement reported equipment installed and commissioning expected later. [10]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
