
- Market Size (2026)
- USD 46.2 Bn
- Forecast (2036)
- USD 286.1 Bn
- CAGR (2026 to 2036)
- 20.0%
How big is GLP-1 Receptor Agonist Market in 2026?
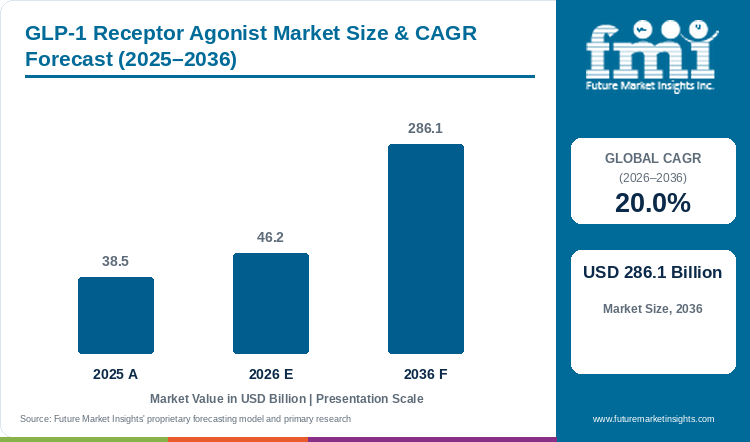
The GLP-1 receptor agonist market demonstrated steady progress from USD 38.5 billion in 2025 to USD 46.2 billion in 2026, building toward a targeted valuation of USD 286.1 billion by 2036 at a CAGR of 20.0%.
Public and commercial health insurers are converting incretin therapies from restricted second-line diabetes injections into reimbursed multi-organ maintenance regimens, lifting the global GLP-1 receptor agonist market from USD 38.5 billion in 2025 to an estimated USD 46.2 billion in 2026. Overall industry valuation is projected to reach USD 286.1 billion by 2036, expanding at a 20.0% compound annual growth rate (CAGR) over the forecast period. Semaglutide is projected to retain a 58.2% share of active drug substance demand in 2026 owing to its broad clinical label across glycemic control, cardiovascular event reduction, and steatohepatitis.
Industry analysis by FMI shows that prescription volume is accelerating through payer price-threshold release, as KFF reported in May 2026 that Medicare Part D gross spending reached USD 27.5 billion across 21.8 million claims before CMS established a USD 245 monthly net price and USD 50 beneficiary copay under the July 2026 Medicare GLP-1 Bridge. That multi-indication payer expansion propels incretin demand far ahead of synthetic peptide therapeutics at a 10.8% CAGR, since non-metabolic peptides lack mass-market primary care prescribing. Manufacturers are committing unprecedented capital to eliminate fill-finish bottlenecks, as Eli Lilly disclosed in February 2026 a USD 6.0 billion active ingredient facility in Alabama and a USD 3.0 billion European oral manufacturing expansion. Long-term market share through 2036 will depend on non-peptide oral tablet scalability and monthly maintenance dosing that prevent patient discontinuation.
Key Market Trends & Insights
- By active drug substance: Semaglutide holds an estimated 58.2% share in 2026 given its established global formulary coverage across Ozempic, Wegovy, and Rybelsus presentations.
- By therapeutic indication: Type 2 Diabetes Glycemic Control represents 54.0% in 2026 since statutory public health insurance programs universally reimburse incretins for glycemic management.
- By route and administration: Subcutaneous Weekly Injectable Auto-Injector Pens account for 88.0% in 2026 as once-weekly prefilled pens maximize patient convenience and bioavailability.
- By distribution channel: Retail Chain Pharmacies command 64.0% in 2026 supported by nationwide cold-chain dispensing infrastructure and commercial PBM network contracts.
- By receptor mechanism: Selective Single-Receptor GLP-1 Agonists secure 61.0% in 2026 owing to massive installed prescription bases and newly launched oral small-molecule tablets.
Regional Highlights
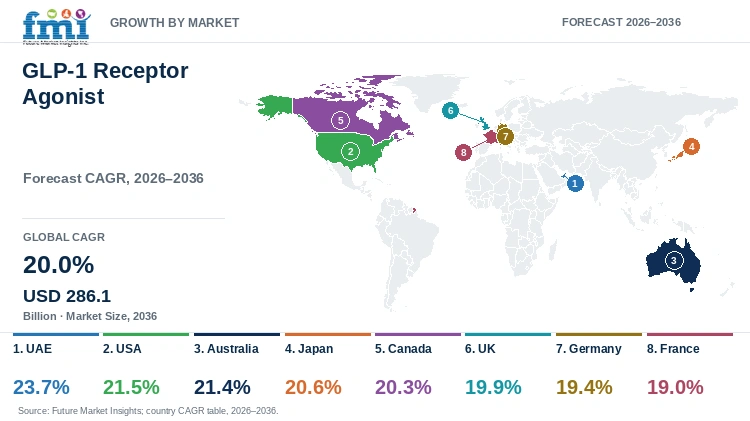
- Top national expansion: The UAE leads national growth projections at a 23.7% CAGR through 2036 driven by high insurance coverage and rapid private hospital uptake.
- Broader country progression: The USA tracks at a 21.5% CAGR ahead of Australia at 21.4% and Canada at 20.3%, while the UK advances at 19.9% and Germany records 19.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the GLP-1 Receptor Agonist Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 38.5 billion |
| Estimated Market Size in 2026 | USD 46.2 billion |
| Projected Market Size by 2036 | USD 286.1 billion |
| CAGR, 2026 to 2036 | 20.0% |
| Added Revenue, 2026 to 2036 | USD 239.9 billion |
Cardiometabolic prescribers are rapidly shifting treatment algorithms from late-stage insulin rescue toward early incretin intervention that addresses hyperglycemia, visceral adiposity, and cardiorenal inflammation simultaneously. Sustained demand for oral incretin tablet formulations and weekly auto-injectors enables primary care physicians to initiate therapy earlier among needle-averse patient populations.
Global Prescription Volume and Peptide API Sizing
Table 2: Global Treated Patient Pool and API Volume Sizing for the GLP-1 Receptor Agonist Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Net selective GLP-1 market size (USD billion) | 38.5 | 46.2 | 286.1 |
| Active global treated patient pool (million patients) | 24.5 to 27.0 | 31.0 to 34.5 | 185.0 to 210.0 |
| Annual 30-day prescription claims dispensed (million) | 265.0 to 290.0 | 335.0 to 370.0 | 2,050.0 to 2,300.0 |
| Active peptide & small-molecule API volume (metric tons) | 18.5 to 22.0 | 26.0 to 31.0 | 240.0 to 290.0 |
Novo Nordisk's 2025 Annual Report published in February 2026 confirms that global branded obesity volume expanded by 104% in 2025 while the company committed DKK 60.1 billion in capital expenditure for active ingredient and fill-finish capacity. As direct-to-patient telepharmacy channels expand home-delivered obesity injectables, multi-dose pen and oral tablet supply chains are scaling to serve tens of millions of chronic maintenance users.
Payer Negotiated Pricing & Clinical Expenditure Indicators
Table 3: Annualized Net Therapy Expenditure and Payer Claim Indicators for the GLP-1 Receptor Agonist Market (USD and claim counts), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global adult obesity population, WHO (billion) | 1.0 | 1.05 | 1.35 |
| CMS Medicare GLP-1 Bridge net 30-day price (USD) | 350.0 to 450.0 | 245.0 | 180.0 to 220.0 |
| LillyDirect / NovoCare self-pay monthly oral/vial price (USD) | 299.0 to 499.0 | 149.0 to 349.0 | 99.0 to 199.0 |
| Oral daily peptide & small-molecule tablet share (%) | 6.5% to 7.5% | 8.0% to 9.5% | 26.0% to 32.0% |
Table 4: Manufacturing CAPEX & Channel Allocation Indicators for the GLP-1 Receptor Agonist Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 46.2 billion | 2026 global net ex-manufacturer selective GLP-1 baseline |
| Novo Nordisk GLP-1 franchise net sales, 2025 | DKK 234.5 billion | Novo Nordisk Annual Report 2025 (Ozempic, Wegovy, Rybelsus) |
| Medicare Part D & Medicaid gross GLP-1 claims | 30.2 million claims | KFF analysis of 21.8M Part D and 8.4M Medicaid claims |
| Retail Chain Pharmacies channel revenue, 2026 | USD 29.6 billion | 64.0% distribution channel allocation |
Figures from the World Health Organization in December 2025 show that more than 1.0 billion people live with obesity globally while current incretin production will reach fewer than 10% of eligible patients by 2030 without expanded manufacturing and tiered pricing. Commercial uptake of clinical anti-obesity pharmacotherapies is therefore transitioning toward high-volume negotiated government models and room-temperature small-molecule tablets that bypass cold-chain constraints.
Analyst Perspective
"Pharmaceutical manufacturers are no longer competing merely on headline 52-week weight loss percentages; they are competing on sterile fill-finish reliability and oral small-molecule synthesis cost as well as hard cardiovascular and hepatic outcomes that compel public payers to reimburse lifelong therapy. Suppliers that pair USD 245 monthly government bridge pricing with once-daily non-peptide pills and monthly maintenance injectables will capture the next decade of global metabolic volume."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is theGLP-1 Receptor Agonist Market segmented?
The GLP-1 receptor agonist market is segmented by active drug substance, therapeutic indication, route and administration, distribution channel, and receptor mechanism. In 2026, Semaglutide is projected at 58.2%, Type 2 Diabetes Glycemic Control at 54.0%, Subcutaneous Weekly Injectable Auto-Injector Pens at 88.0%, Retail Chain Pharmacies at 64.0%, and Selective Single-Receptor GLP-1 Agonists at 61.0%.
By active drug substance: Semaglutide Ozempic Wegovy and Rybelsus and Tirzepatide Dual GIP and GLP-1 Mounjaro Zepbound lead selection. Additional options include Dulaglutide Trulicity, Liraglutide Victoza and Saxenda, and Exenatide Bydureon.
By therapeutic indication: Type 2 Diabetes Glycemic Control and Chronic Weight Management and Anti-Obesity account for core demand, followed by Cardiovascular Risk Reduction in Atherosclerotic Disease and Nonalcoholic Steatohepatitis NASH and Kidney Protection.
By route and administration: Subcutaneous Weekly Injectable Auto-Injector Pens, Subcutaneous Daily Injections, and Oral Daily Formulations.
By distribution channel: Retail Chain Pharmacies, Hospital Inpatient and Outpatient Formularies, and Specialty Mail-Order E-Pharmacies.
By receptor mechanism: Selective Single-Receptor GLP-1 Agonists, Dual GIP/GLP-1 and Glucagon/GLP-1 Co-Agonists, and Amylin-GLP-1 Combinations and Triple Agonists.
Why does Semaglutide lead the active drug substance category?
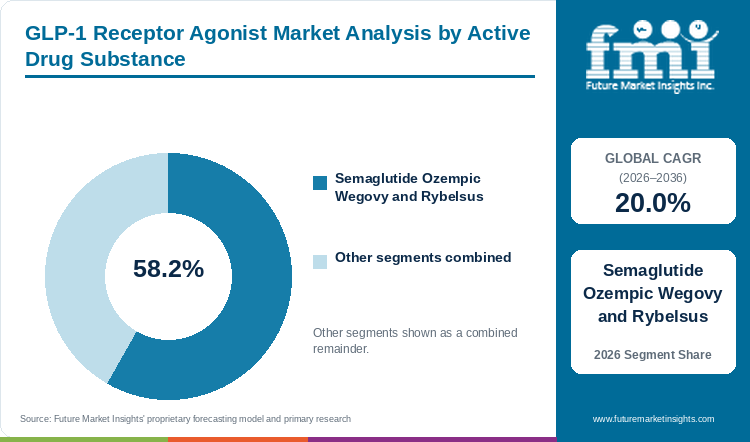
Semaglutide formulations hold an estimated 58.2% of active drug substance demand in 2026, anchored by Ozempic, Wegovy, and Rybelsus approvals across diabetes, obesity, cardiovascular disease, CKD, and MASH.
Table 5: Active Drug Substance Share for the GLP-1 Receptor Agonist Market (percentage share), 2026
| Active Drug Substance | Share (2026) |
|---|---|
| Semaglutide Ozempic Wegovy and Rybelsus | 58.2% |
| Other Segments Combined | 41.8%* |
| Total | 100.0% |
*Note: Remaining active drug substance categories account for the balance of 2026 global GLP-1 receptor agonist demand.
Table 6: Active Drug Substance Leadership and Market Growth for the GLP-1 Receptor Agonist Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 20.0% |
| Leading Segment | Semaglutide Ozempic Wegovy and Rybelsus |
Semaglutide anchors global prescription revenue because it is the only incretin molecule commercialized across both weekly subcutaneous auto-injector pens and daily oral tablets. Approved labels spanning glycemic control and weight management plus cardiovascular risk reduction and liver fibrosis reinforce its formulary position, while investments in prefilled pen auto-injectors and Catalent aseptic filling lines have resolved prior pharmacy backorders. However, escalating competition from dual GIP/GLP-1 co-agonists and upcoming 2026 to 2031 patent expirations in select emerging markets will pressure standalone mono-agonist pricing.
- By active drug substance, Semaglutide Ozempic Wegovy and Rybelsus is projected to account for 58.2% of category demand in 2026 owing to unmatched multi-indication payer coverage.
- In August 2025, the U.S. Food and Drug Administration granted accelerated approval to once-weekly Wegovy 2.4 mg for adults with noncirrhotic metabolic dysfunction-associated steatohepatitis and moderate-to-advanced liver fibrosis.
What sustains Type 2 Diabetes Glycemic Control leadership in the therapeutic indication segment?
Type 2 Diabetes Glycemic Control represents an estimated 54.0% of the therapeutic indication category in 2026 as national health insurance schemes universally reimburse diabetic glycemic control.
Type 2 diabetes glycemic control remains the foundational revenue pillar since public health ministries in Europe and Asia Pacific provide universal statutory reimbursement for diabetic glycemic management while restricting cosmetic weight-loss coverage. Data from the Phase 3 FLOW trial published in July 2024 showed that once-weekly semaglutide 1.0 mg reduced major kidney disease events by 24% and cardiovascular death by 29% across 3,533 patients with Type 2 diabetes and chronic kidney disease. As clinicians deploy parenteral drug delivery systems for cardiorenal protection, diabetes formularies authorize first-line incretin therapy with metformin.
- Within the therapeutic indication category, Type 2 Diabetes Glycemic Control is anticipated to capture a leading 54.0% share in 2026 supported by universal statutory insurance coverage.
- Chronic weight management, cardiovascular risk reduction, and steatohepatitis indications are forecast to expand at a faster pace through 2036 as Medicare GLP-1 Bridge and national health technology appraisals widen non-diabetic reimbursement.
How do Subcutaneous Weekly Injectable Auto-Injector Pens lead the route and administration category?
Subcutaneous Weekly Injectable Auto-Injector Pens account for an estimated 88.0% of route and administration demand in 2026 owing to high systemic bioavailability and once-weekly self-injection.
Subcutaneous weekly auto-injector pens dominate revenue because long-acting fatty-acid acylation allows patients to self-administer a single hidden-needle dose once every seven days with near-100% systemic bioavailability. High patient adherence to weekly pens underpins clinical weight loss interventions by avoiding the strict fasting rules and low gastrointestinal absorption of first-generation peptide tablets. Even so, cold-chain storage requirements between 2 and 8 degrees Celsius and plastic pen-injector assembly bottlenecks remain operational constraints across developing regions.
- Subcutaneous Weekly Injectable Auto-Injector Pens are estimated to represent 88.0% of route and administration demand in 2026 given superior bioavailability and once-weekly dosing convenience.
- In January 2026, the U.S. Food and Drug Administration approved the four-dose single-patient-use Zepbound KwikPen in addition to moderate-to-severe obstructive sleep apnea indications in adults with obesity.
Why do Retail Chain Pharmacies lead the distribution channel category?
Retail Chain Pharmacies command an estimated 64.0% of distribution channel value in 2026 supported by nationwide cold-chain pharmacy counters and PBM formulary networks.
Retail chain pharmacies dispense the majority of global prescriptions because outpatient endocrinologists and primary care physicians route insured 30-day and 90-day electronic scripts directly to neighborhood pharmacy networks equipped with refrigerated storage. A KFF national tracking poll in November 2025 found that 12% of United States adults currently take a GLP-1 drug, with 76% obtaining prescriptions from in-person physicians and 17% using online telehealth providers. Retail pharmacy margins nevertheless face compression from high wholesale acquisition costs and PBM clawbacks on refrigerated brand-name pens.
- Retail Chain Pharmacies are forecast to command 64.0% of distribution channel demand in 2026 supported by nationwide cold-chain pharmacy counters and commercial PBM contracts.
- Specialty mail-order and manufacturer direct-to-patient platforms such as LillyDirect and NovoCare Pharmacy are projected to capture rising share through 2036 by offering transparent self-pay cash bundles and home cold-pack delivery.
What gives Selective Single-Receptor GLP-1 Agonists the leading position in receptor mechanism?
Selective Single-Receptor GLP-1 Agonists secure an estimated 61.0% of receptor mechanism demand in 2026 through entrenched mono-agonist diabetes formularies and new oral small-molecule tablets.
Selective single-receptor GLP-1 agonists hold the largest mechanism share due to the massive global installed base of semaglutide and dulaglutide prescriptions across more than 70 countries and the 2026 commercial arrival of non-peptide oral GLP-1 pills. Single-receptor small molecules such as orforglipron and elecoglipron can be synthesized through standard chemical manufacturing without peptide fermenters or refrigerated cartridges. However, single-receptor agonists face intense efficacy competition from dual GIP/GLP-1 and glucagon/GLP-1 co-agonists that achieve 15% to 22% mean weight loss.
- Selective Single-Receptor GLP-1 Agonists are expected to secure 61.0% of receptor mechanism demand in 2026 supported by entrenched Type 2 diabetes formularies and oral tablet launches.
- In February 2026, Novo Nordisk announced that its dual amylin and GLP-1 combination CagriSema achieved a 1.91%-point HbA1c reduction and 14.2% weight loss in the Phase 3 REIMAGINE 2 trial.
What are the drivers, restraints, and opportunities in the GLP-1 Receptor Agonist Market?
In the GLP-1 receptor agonist market, cardiovascular, renal, sleep apnea, and MASH label expansions and Medicare Bridge coverage drive growth, out-of-pocket costs and GI discontinuation restrain persistence, and oral small-molecule pills and monthly injectables create major opportunities.
- Driver: Expanding FDA and EMA label approvals into cardiovascular risk reduction and chronic kidney disease as well as obstructive sleep apnea and MASH liver fibrosis open public and private reimbursement.
- Restraint: High out-of-pocket costs for uninsured patients, gastrointestinal side-effect discontinuation, and cold-chain pen manufacturing complexity restrain long-term therapy persistence.
- Opportunity: Commercializing room-temperature oral small-molecule GLP-1 pills and once-monthly maintenance injectables expands treatment access across primary care and emerging markets.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Clinical proof that incretin receptor agonists resolve hepatic steatohepatitis and prevent major cardiovascular and renal events is transforming payer economics from short-term pharmacy cost containment to long-term hospitalization avoidance. Medical adoption of incretin diabetes prescription drugs now extends into hepatology, cardiology, and nephrology clinics where specialists initiate therapy to halt organ fibrosis. In June 2025, the Phase 3 ESSENCE trial demonstrated that weekly semaglutide 2.4 mg resolved steatohepatitis without worsening fibrosis in 62.9% of MASH patients versus 34.3% on placebo at 72 weeks. These multi-organ outcomes compel government health systems and commercial insurers to fund chronic maintenance therapy.
Risk Assessment of the GLP-1 Receptor Agonist Market: Operational and Formulation Friction
High gross prescription prices and gastrointestinal adverse events including nausea and lean muscle loss cause substantial therapy drop-off after six to twelve months when insurance coverage is interrupted. While pharmaceutical developers advance oral weight management medications, public health budgets face severe fiscal strain from rapidly multiplying prescription claims. In January 2026, KFF reported that gross Medicaid outpatient spending on GLP-1 drugs surged ninefold from USD 999 million in 2019 to USD 8.6 billion across 8.4 million prescriptions in 2024, prompting several states to tighten fee-for-service obesity eligibility. Multi-year patient retention requires lower-cost oral maintenance regimens and structured nutritional counseling that preserve lean body mass.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Next-generation oral non-peptide small molecules and ultra-long-acting monthly injectables represent the largest commercial growth avenue because they eliminate refrigerated pen-assembly bottlenecks and daily fasting restrictions. Whereas traditional peptide injectables rely on prefilled cartridge auto-injectors, small-molecule oral tablets can be tableted at billion-dose scale in standard solid-dosage plants. In June 2026, AstraZeneca advanced its once-daily oral small-molecule GLP-1 agonist elecoglipron into Phase III EMBOLD and ELUMINATE trials after Phase IIb studies showed up to 11.8% weight loss and a 1.9% HbA1c reduction. Oral tablets and monthly maintenance injections will allow manufacturers to convert patients from weekly pens into convenient long-term maintenance therapy.
GLP-1 Receptor Agonist Market by Country (2026 to 2036)
FMI country modeling indicates that the UAE leads GLP-1 receptor agonist expansion at a 23.7% CAGR through 2036 ahead of the USA at 21.5% and Australia at 21.4%. Japan follows at 20.6% and Canada tracks at 20.3%, while the UK at 19.9% and Germany at 19.4% outpace France at 19.0%.
Table 7: Country CAGR and Primary Growth Levers for the GLP-1 Receptor Agonist Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| UAE | 23.7% | 371.7% hospital prescribing surge and 83.5% private/public health insurance coverage |
| USA | 21.5% | CMS July 2026 Medicare GLP-1 Bridge (USD 245 net / USD 50 copay) and Foundayo oral pill |
| Australia | 21.4% | PBS T2D subsidies and TGA approvals of Mounjaro and Wegovy across obesity and sleep apnea |
| Japan | 20.6% | MHLW June 2026 Wegovy MASH Optimal Use Guideline and strong oral Rybelsus uptake |
| Canada | 20.3% | CDA-AMC SR0841-000 positive Wegovy cardiovascular reimbursement recommendation |
| UK | 19.9% | NICE TA1026 NHS England commercial access rollout and private online pharmacy demand |
| Germany | 19.4% | BfArM March 2026 lifting of GLP-1 shortage directives and statutory GKV T2D/CV coverage |
| France | 19.0% | 870,000 reimbursed T2D GLP-1 patients and ANSM Specialized Obesity Center care pathways |
Source: Future Market Insights analysis
UAE GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
Revenue from GLP-1 receptor agonists in the UAE is projected to advance at a leading 23.7% CAGR from 2026 to 2036, driven by high adult cardiometabolic prevalence and broad private insurance reimbursement across Abu Dhabi and Dubai hospital networks. Emirati endocrinology centers rapidly adopt high-strength weekly dual and mono-incretin pens with minimal step-therapy delays compared with European single-payer systems. In April 2026, a retrospective UAE hospital study in BMC Endocrine Disorders analyzing 1,744 dispensing records documented a 371.7% surge in monthly GLP-1 treatment units between 2022 and 2024, with 83.5% of treated patients covered by health insurance. Cold-chain pharmacy distribution across high summer temperatures requires validated temperature-controlled courier networks for home pen delivery.
Key takeaway: In the UAE, 83.5% insurance coverage among treated hospital cohorts and rapid uptake of high-maintenance incretin doses are projected to drive world-leading growth.
USA GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
United States spending on GLP-1 receptor agonists is forecast to climb at a 21.5% CAGR over the 2026 to 2036 window as federal Medicare Bridge pricing, FDA oral pill approvals, and sleep apnea and MASH indications open coverage for millions of newly eligible patients. American commercialization combines traditional PBM retail pharmacy fulfillment with fast-growing manufacturer direct-to-patient telehealth portals such as LillyDirect and NovoCare. In October 2024, the Phase 3 SURMOUNT-OSA trial publication showed that weekly tirzepatide reduced apnea-hypopnea index events by up to 29.3 events per hour, supporting FDA obesity sleep apnea approval. Employer plan prior-authorization hurdles and statutory Medicare Part D price negotiations taking effect in 2027 will compress gross-to-net margins while accelerating prescription volume.
Key takeaway: In the USA, CMS Medicare GLP-1 Bridge coverage with standardized monthly copays and oral Foundayo and Wegovy tablet launches are anticipated to drive massive prescription scale.
Australia GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
Australian demand for GLP-1 receptor agonists is anticipated to advance at a 21.4% CAGR through 2036, supported by Pharmaceutical Benefits Scheme subsidies for Type 2 diabetes and surging private-market prescribing for weight management and sleep apnea. Stabilized global pen supply has enabled Australian community pharmacies to resolve the multi-year stockouts that previously constrained new patient initiations. In December 2025, the Australian Therapeutic Goods Administration published a regulatory update confirming five marketed brands including Mounjaro and Ozempic as well as Wegovy, with Mounjaro approved for obesity and obstructive sleep apnea. Lack of public PBS reimbursement for standalone obesity without diabetes keeps non-diabetic prescriptions reliant on private out-of-pocket spending.
Key takeaway: In Australia, restored pharmacy pen supply and expanded TGA indications across obesity and obstructive sleep apnea are expected to sustain rapid commercial expansion.
Japan GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
Japanese expenditure on GLP-1 receptor agonist therapies is slated to grow at a 20.6% CAGR from 2026 to 2036 as National Health Insurance reimbursement extends into metabolic dysfunction-associated steatohepatitis and specialist-supervised obesity care. Japanese clinicians exhibit a strong preference for oral daily incretin tablets such as Rybelsus in primary care diabetes while deploying weekly Wegovy 2.4 mg injections in certified specialist hospitals. In June 2026, Japan's Ministry of Health, Labour and Welfare and PMDA issued the Optimal Use Promotion Guideline for subcutaneous Wegovy in noncirrhotic MASH with stage F2 to F3 liver fibrosis across Japanese patients with BMI of 23.0 or higher. Strict MHLW facility certification rules requiring board-certified hepatologists or endocrinologists and bimonthly dietitian counseling regulate initial prescription velocity.
Key takeaway: In Japan, the June 2026 MHLW Optimal Use Guideline for Wegovy in MASH and strong oral Rybelsus prescribing are forecast to drive sustained NHI-reimbursed growth.
Canada GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
Canadian expenditure on GLP-1 receptor agonists is estimated to progress at a 20.3% CAGR between 2026 and 2036, driven by positive public health technology assessments for cardiovascular risk reduction and approaching generic semaglutide competition. Canadian market growth bridges public provincial drug plans for Type 2 diabetes and cardiovascular disease with extensive private employer benefit coverage. On June 17, 2025, Canada's Drug Agency issued final positive recommendation SR0841-000 advising public drug plans to reimburse Wegovy 2.4 mg for adults with a BMI of 27 or greater and established cardiovascular disease. Prior-authorization documentation across provincial formularies and private insurer annual spending caps remain practical hurdles for non-cardiovascular obesity patients.
Key takeaway: In Canada, positive CDA-AMC public reimbursement recommendations for cardiovascular risk reduction and strong private employer coverage are estimated to propel demand.
UK GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
GLP-1 receptor agonist expenditure in the UK is expected to expand at a 19.9% CAGR through 2036 as NHS England executes its phased primary care and specialist clinic rollout in parallel with booming private online pharmacy dispensing. Unlike pure private-pay markets, British public access is governed by strict NICE body-mass-index and comorbidity thresholds that stage NHS budget impact over multiple years. In September 2025, the National Institute for Health and Care Excellence updated Technology Appraisal Guidance TA1026 incorporating an NHS England commercial access agreement and phased commissioning for tirzepatide in adults with obesity. Capacity constraints inside NHS specialist weight management services continue to channel millions of self-paying British patients toward regulated online pharmacies.
Key takeaway: In the UK, NICE TA1026 NHS commissioning for tirzepatide and high-volume private e-pharmacy prescribing are slated to anchor strong double-digit growth.
Germany GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
Germany is projected to record a 19.4% CAGR across its GLP-1 receptor agonist market from 2026 to 2036 following the formal resolution of national pharmacy supply shortages and expanding cardiovascular and renal prescribing under statutory health insurance. While Germany's Social Code Book V lifestyle-drug exclusion clause restricts statutory GKV reimbursement for standalone cosmetic weight loss, diabetologists and cardiologists widely prescribe incretins for Type 2 diabetes and cardiovascular risk reduction. On March 25, 2026, Germany's Federal Institute for Drugs and Medical Devices formally lifted its multi-year supply shortage directives for Ozempic and Trulicity after verifying sustained nationwide pharmacy inventory. Strict AMNOG reference-price negotiations and statutory rebate mandates moderate net unit price increases across German public sickness funds.
Key takeaway: In Germany, BfArM's March 2026 lifting of GLP-1 supply shortage directives and broad statutory GKV diabetes and cardiorenal coverage are predicted to support strong volume expansion.
France GLP-1 Receptor Agonist Market Outlook (2026 to 2036)
France is anticipated to achieve a 19.0% CAGR for GLP-1 receptor agonist sales between 2026 and 2036, supported by a large reimbursed Type 2 diabetes patient base and structured obesity care pathways across Specialized Obesity Centers. French health authorities pair broad Assurance Maladie reimbursement for diabetic incretins with strict pharmacovigilance and nutritional monitoring to prevent unprescribed misuse. In January 2026, the French National Agency for the Safety of Medicines and Health Products confirmed a favorable benefit-risk profile across approximately 870,000 reimbursed diabetes GLP-1 patients as well as commercialized Wegovy and Mounjaro obesity cohorts. Economic price committee negotiations under CEPS and mandatory nutritional follow-up protocols govern the pace of public obesity reimbursement in France.
Key takeaway: In France, 870,000 reimbursed diabetes patients and structured ANSM care pathways for Wegovy and Mounjaro are expected to drive steady long-term expansion.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the GLP-1 Receptor Agonist Market?
Novo Nordisk A/S, Eli Lilly and Company, AstraZeneca plc, Sanofi SA, Pfizer Inc., Amgen Inc., Viking Therapeutics Inc., Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, and Zealand Pharma A/S represent the notable companies in the GLP-1 receptor agonist market.
Competitive positioning in the GLP-1 receptor agonist industry separates commercialized global incretin duopoly leaders, diversified big-pharma oral and monthly pipeline entrants, and specialized dual-agonist clinical innovators.
- Commercialized Global Incretin Leaders: Novo Nordisk A/S and Eli Lilly and Company command global prescription volume through multi-indication injectable pens, oral semaglutide and orforglipron tablets, and over USD 15 billion in annual peptide and fill-finish capital expenditure.
- Diversified Biopharma Oral & Monthly Entrants: AstraZeneca plc and Sanofi SA with Pfizer Inc. and Amgen Inc. compete through fixed-ratio basal-insulin lixisenatide combinations, Phase III oral small-molecule elecoglipron tablets, and Phase IIb/III monthly injectable PF-08653944 and MariTide programs.
- Next-Generation Co-Agonist & Amylin Innovators: Boehringer Ingelheim International GmbH and F. Hoffmann-La Roche Ltd with Viking Therapeutics Inc. and Zealand Pharma A/S advance Phase III glucagon/GLP-1 survodutide, dual GIP/GLP-1 VK2735, and co-formulated amylin petrelintide/CT-388 regimens.
Competitive Benchmarking: GLP-1 Receptor Agonist Market
Table 8: Competitive Benchmarking for the GLP-1 Receptor Agonist Market (qualitative capability ratings), 2026
| Company | Multi-Indication Clinical Evidence | Peptide & Oral Manufacturing Scale | Oral & Extended-Dosing Pipeline | Geographic Reach |
|---|---|---|---|---|
| Novo Nordisk A/S | High | High | High | Global leader (DKK 234.5B 2025 GLP-1 sales); Ozempic, Wegovy pill/pen, Rybelsus, CagriSema |
| Eli Lilly and Company | High | High | High | Global leader (USD 36.5B 2025 Mounjaro/Zepbound); FDA-approved oral Foundayo and retatrutide |
| AstraZeneca plc | Medium | High | High | Global cardiometabolic footprint; oral small-molecule elecoglipron in Phase III EMBOLD/ELUMINATE |
| Sanofi SA | Medium | High | Low | Global insulin-incretin reach; Soliqua (insulin glargine/lixisenatide) +9% Q3 2026 diabetes growth |
| Pfizer Inc. | Medium | High | High | Global biopharma scale; monthly injectable PF-08653944 advancing across 10 Phase III trials |
| Amgen Inc. | Medium | High | High | Phase III MARITIME program for monthly bispecific GLP-1 agonist/GIPR antagonist MariTide |
| Viking Therapeutics Inc. | Medium | Low | High | Phase III VANQUISH/SUNRISE subcutaneous and oral dual GLP-1/GIP agonist VK2735 |
| Boehringer Ingelheim International GmbH | High | High | Medium | Phase III SYNCHRONIZE and LIVERAGE obesity and MASH trials for dual agonist survodutide |
| F. Hoffmann-La Roche Ltd | Medium | High | High | Global diagnostics/pharma scale; CT-388 dual agonist and USD 5.3B Zealand petrelintide deal |
| Zealand Pharma A/S | Medium | Medium | High | Peptide discovery specialist co-developing weekly amylin petrelintide/CT-388 with Roche |
Key Developments in the GLP-1 Receptor Agonist Market
- In September 2026, Viking Therapeutics announced positive top-line results from a maintenance dosing study of VK2735, its dual GLP-1/GIP receptor agonist. Participants transitioning from weekly induction doses to every-other-week dosing maintained up to 97% of their mean weight loss over 12 weeks, while those transitioning to monthly dosing maintained up to 90%, both significantly superior to the 61% maintenance observed with placebo .
- In February 2026, Novo Nordisk announced headline results from REDEFINE 4, an open-label Phase III trial evaluating CagriSema (cagrilintide 2.4 mg combined with semaglutide 2.4 mg) against tirzepatide 15 mg in 809 adults with obesity. CagriSema demonstrated 23.0% weight loss at 84 weeks but did not meet the primary endpoint of non-inferiority to tirzepatide, which achieved 25.5% weight loss over the same period.
- In April 2026, Eli Lilly and Company received FDA approval for Foundayo (orforglipron), a once-daily oral small-molecule GLP-1 receptor agonist indicated for chronic weight management in adults with obesity or overweight with at least one weight-related comorbidity. Foundayo is the first oral GLP-1 that can be taken at any time of day without food or water restrictions, differentiated from prior peptide-based oral GLP-1 formulations that require fasting conditions.
Key Players in the GLP-1 Receptor Agonist Market
Commercialized Global Incretin Leaders
- Novo Nordisk A/S
- Eli Lilly and Company
- Diversified Biopharma Oral & Monthly Entrants
- AstraZeneca plc
Sanofi SA
- Pfizer Inc.
- Amgen Inc.
- Next-Generation Co-Agonist & Amylin Innovators
- Boehringer Ingelheim International GmbH
F. Hoffmann-La Roche Ltd
- Zealand Pharma A/S
GLP-1 Receptor Agonist Market - Report Scope
Table 9: Report Scope for the GLP-1 Receptor Agonist Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Active Drug Substance; Therapeutic Indication; Route and Administration; Distribution Channel; Receptor Mechanism |
| Quantitative Units | USD Billion |
| Market Definition | Isolates net ex-manufacturer realized prescription formulary revenue for selective GLP-1 and co-agonist incretin therapies |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | UAE, USA, Australia, Japan, Canada, UK, Germany, France, and additional regional markets |
| Key Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, AstraZeneca plc, Sanofi SA, Pfizer Inc., Amgen Inc., Viking Therapeutics Inc., Boehringer Ingelheim, Roche, Zealand Pharma |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with net-to-gross rebate reconciliation and patient-claim modeling |
GLP-1 Receptor Agonist Market - Research Methodology
Table 10: Research Methodology for the GLP-1 Receptor Agonist Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with endocrinologists, hepatologists, cardiologists, PBM rebate negotiators, and peptide CDMO directors |
| Secondary Research | Analysis of SEC Form 10-K/8-K filings, Novo Nordisk annual reports, FDA/EMA/PMDA labels, WHO guidelines, and KFF Medicare/Medicaid claims |
| Market Sizing and Forecasting | Bottom-up treated patient cohorts multiplied by annual 30-day prescription fills and net ex-manufacturer realized pricing after statutory rebates |
| Country Forecasting Model | Country projections weight adult T2D/obesity/MASH prevalence, national HTA reimbursement timelines, and local pen/tablet supply availability |
| Operational Benchmark Traceability | Patient counts, Medicare/Medicaid claim volumes, CMS Bridge net pricing, and API/fill-finish CAPEX in Tables 2, 3, and 4 validate revenue forecasts |
| Data Triangulation and Validation | Reconciles selective mono-GLP-1 net baseline (USD 38.5B in 2025; USD 46.2B in 2026) against gross all-incretin manufacturer disclosures |
GLP-1 Receptor Agonist Market by Segments
GLP-1 Receptor Agonist Market segmented by Active Drug Substance:
- Semaglutide Ozempic Wegovy and Rybelsus
- Tirzepatide Dual GIP and GLP-1 Mounjaro Zepbound
- Dulaglutide Trulicity
- Liraglutide Victoza and Saxenda
GLP-1 Receptor Agonist Market segmented by Therapeutic Indication:
- Type 2 Diabetes Glycemic Control
- Chronic Weight Management and Anti-Obesity
- Cardiovascular Risk Reduction in Atherosclerotic Disease
- Nonalcoholic Steatohepatitis NASH and Kidney Protection
GLP-1 Receptor Agonist Market segmented by Route and Administration:
- Subcutaneous Weekly Injectable Auto-Injector Pens
- Subcutaneous Daily Injections
- Oral Daily Formulations
- Multi-Dose Prefilled KwikPen & Cartridge Systems
- Monthly & Extended-Interval Subcutaneous Injectables
GLP-1 Receptor Agonist Market segmented by Distribution Channel:
- Retail Chain Pharmacies
- Hospital Inpatient and Outpatient Formularies
- Specialty Mail-Order E-Pharmacies
- Direct-to-Patient Telehealth Portals
GLP-1 Receptor Agonist Market segmented by Receptor Mechanism:
- Selective Single-Receptor GLP-1 Agonists
- Dual GIP/GLP-1 Receptor Co-Agonists
- Dual Glucagon/GLP-1 & Amylin Combinations
- Triple GIP/GLP-1/Glucagon Receptor Agonists
GLP-1 Receptor Agonist Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Freed, M., Cubanski, J., & Williams, E. (2026, May 11). What to Know About the BALANCE Model for GLP-1s in Medicare and Medicaid and the Medicare GLP-1 Bridge. KFF (Kaiser Family Foundation).
- [2] Eli Lilly and Company (2026, February 4). Form 8-K Exhibit 99.1: Lilly Reports Fourth-Quarter 2025 Financial Results and Provides 2026 Guidance. U.S. Securities and Exchange Commission (EDGAR Filing 0000059478-26-000008).
- [3] Novo Nordisk A/S (2026, February 3). Annual Report 2025: Strategic Aspirations, Financial Performance, and 2026 Outlook. Novo Nordisk A/S.
- [4] World Health Organization (WHO) (2025, December 1). WHO Issues Global Guideline on the Use of GLP-1 Medicines in Treating Obesity. World Health Organization.
- [5] U.S. Food and Drug Administration (FDA) (2025, August 15). Highlights of Prescribing Information: WEGOVY (semaglutide) Injection for Subcutaneous Use in MASH and Cardiovascular Risk Reduction (NDA 215256/S-024). U.S. Food and Drug Administration CDER.
- [6] Perkovic, V., Tuttle, K. R., Rossing, P., et al. (2024, July 11). Effects of Semaglutide on Chronic Kidney Disease in Patients with Type 2 Diabetes (FLOW Trial). New England Journal of Medicine (PubMed PMID 38785209).
- [7] U.S. Food and Drug Administration (FDA) (2026, January 20). Highlights of Prescribing Information: ZEPBOUND (tirzepatide) Injection and 4-Dose KwikPen Presentation (NDA 217806/S-002). U.S. Food and Drug Administration CDER.
- [8] KFF Public Opinion and Survey Research (2025, November 14). Poll: 1 in 8 Adults Say They Are Currently Taking a GLP-1 Drug for Weight Loss, Diabetes or Another Condition. KFF Health Tracking Poll.
- [9] Novo Nordisk A/S (2026, February 2). Company Announcement: CagriSema Demonstrated Superior HbA1c Reduction of 1.91%-Points and Weight Loss of 14.2% in Adults with Type 2 Diabetes in REIMAGINE 2. Novo Nordisk A/S Investor Relations.
- [10] Sanyal, A. J., Newsome, P. N., Kliers, I., et al. (2025, June 5). Phase 3 Trial of Semaglutide in Metabolic Dysfunction-Associated Steatohepatitis (ESSENCE Trial). New England Journal of Medicine (PubMed PMID 40305708).
- [11] Williams, E. (2026, January 16). Medicaid Coverage of and Spending on GLP-1s. KFF Medicaid Policy Analysis.
- [12] AstraZeneca plc (2026, June 8). Elecoglipron, an Oral Small Molecule GLP-1 RA, Moves to Phase III Programme and Unlocks Next Chapter in Cardiometabolic Portfolio. AstraZeneca Media Centre.
- [13] Almemari, S., Almulla, N., Alsarraf, Y., Badri, G., & Khan, N. S. (2026, April 12). Real-World Prescribing Patterns and Early Weight and Blood Pressure Outcomes of GLP-1-Based Therapies in the United Arab Emirates. BMC Endocrine Disorders (PMC13181871).
- [14] Malhotra, A., Grunstein, R. R., Fietze, I., et al. (2024, October 3). Tirzepatide for the Treatment of Obstructive Sleep Apnea and Obesity (SURMOUNT-OSA). New England Journal of Medicine (PubMed PMID 38912654).
- [15] Therapeutic Goods Administration (TGA) (2025, December 1). Medicine Safety Update: Updated Contraception Advice for Mounjaro (tirzepatide) and GLP-1 RAs Marketed in Australia. Australian Government Department of Health, Disability and Ageing.
- [16] Canada's Drug Agency (CDA-AMC) (2025, June 17). Reimbursement Review: Semaglutide (Wegovy) for Weight Management and Cardiovascular Risk Reduction (SR0841-000). Canada's Drug Agency.
- [17] National Institute for Health and Care Excellence (NICE) (2025, September 1). Tirzepatide for Managing Overweight and Obesity (Technology Appraisal Guidance TA1026). NICE United Kingdom.
- [18] Bundesinstitut fur Arzneimittel und Medizinprodukte (BfArM) (2026, March 25). GLP-1-Rezeptor-Agonisten: Aufhebung der Empfehlung des Beirates (Stand 18.03.2026). BfArM Germany.
- [19] Agence nationale de securite du medicament et des produits de sante (ANSM) (2026, January 7). Surveillance des aGLP-1: l'ANSM confirme le rapport benefice/risque favorable lorsque ces medicaments sont utilises conformement aux recommandations. ANSM France.
- [20] Ministry of Health, Labour and Welfare (MHLW) & PMDA Japan (2026, June 15). Optimal Use Promotion Guideline: Semaglutide (Wegovy Subcutaneous Injection) in Metabolic Dysfunction-Associated Steatohepatitis. PMDA Japan.
- [21] Boehringer Ingelheim International GmbH (2026, October 1). Boehringer Ingelheim's Survodutide Achieves Up to 13.1% Weight Loss in New Phase III SYNCHRONIZE-2 Trial in Obesity and Type 2 Diabetes. Boehringer Ingelheim Corporate Newsroom.
- [22] Viking Therapeutics, Inc. (2026, September 22). Viking Therapeutics Announces Positive Topline Results from Maintenance Study of GLP-1/GIP Agonist VK2735. Viking Therapeutics Investor Relations.
- [23] Eli Lilly and Company (2026, April 1). FDA Approves Lilly's Foundayo (orforglipron), the Only GLP-1 Pill for Weight Loss Taken Any Time of Day Without Food or Water Restrictions. Eli Lilly and Company Investor Relations.
- [24] Pfizer Inc. (2026, February 3). Pfizer's Ultra-Long-Acting Injectable GLP-1 RA Shows Continued Weight Loss with Monthly Dosing in Phase 2b VESPER-3 Trial. Pfizer Inc. Media Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations across all primary and secondary sources.
This Report Answers
- How large is the GLP-1 receptor agonist market in 2026 and what is forecast for 2036?
- Which Medicare Bridge pricing and cardiorenal-hepatic label expansions support demand for GLP-1 receptor agonists?
- Why does Semaglutide lead the active drug substance category?
- Why do Subcutaneous Weekly Injectable Auto-Injector Pens lead the route and administration category globally?
- How do growth rates differ across the UAE and the USA compared with Australia and Japan?
- Which leading companies supply commercialized weekly auto-injector pens versus oral small-molecule or monthly pipeline candidates today?
- What limits long-term patient persistence or causes gastrointestinal discontinuation in the GLP-1 receptor agonist market?
- What should health systems and PBMs evaluate when contracting across mono-GLP-1, dual GIP/GLP-1, and oral tablet formulations?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Active Drug Substance, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Active Drug Substance, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Active Drug Substance, 2026 to 2036
- Semaglutide Ozempic Wegovy and Rybelsus
- Tirzepatide Dual GIP and GLP-1 Mounjaro Zepbound
- Dulaglutide Trulicity
- Liraglutide Victoza and Saxenda
- Y-o-Y Growth Trend Analysis By Active Drug Substance, 2021 to 2025
- Absolute $ Opportunity Analysis By Active Drug Substance, 2026 to 2036
- Global Market Analysis and Forecast, By Therapeutic Indication, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapeutic Indication, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapeutic Indication, 2026 to 2036
- Type 2 Diabetes Glycemic Control
- Chronic Weight Management and Anti-Obesity
- Cardiovascular Risk Reduction in Atherosclerotic Disease
- Nonalcoholic Steatohepatitis NASH and Kidney Protection
- Y-o-Y Growth Trend Analysis By Therapeutic Indication, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapeutic Indication, 2026 to 2036
- Global Market Analysis and Forecast, By Route and Administration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Route and Administration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Route and Administration, 2026 to 2036
- Subcutaneous Weekly Injectable Auto-Injector Pens
- Subcutaneous Daily Injections
- Oral Daily Formulations
- Multi-Dose Prefilled KwikPen & Cartridge Systems
- Monthly & Extended-Interval Subcutaneous Injectables
- Y-o-Y Growth Trend Analysis By Route and Administration, 2021 to 2025
- Absolute $ Opportunity Analysis By Route and Administration, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail Chain Pharmacies
- Hospital Inpatient and Outpatient Formularies
- Specialty Mail-Order E-Pharmacies
- Direct-to-Patient Telehealth Portals
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Receptor Mechanism, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Receptor Mechanism, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Receptor Mechanism, 2026 to 2036
- Selective Single-Receptor GLP-1 Agonists
- Dual GIP/GLP-1 Receptor Co-Agonists
- Dual Glucagon/GLP-1 & Amylin Combinations
- Triple GIP/GLP-1/Glucagon Receptor Agonists
- Y-o-Y Growth Trend Analysis By Receptor Mechanism, 2021 to 2025
- Absolute $ Opportunity Analysis By Receptor Mechanism, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- By Country
- Market Attractiveness Analysis
- By Country
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- UAE
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Active Drug Substance
- By Therapeutic Indication
- By Route and Administration
- By Distribution Channel
- By Receptor Mechanism
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Novo Nordisk A/S
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Eli Lilly and Company
- AstraZeneca plc
- Sanofi SA
- Pfizer Inc.
- Amgen Inc.
- Viking Therapeutics Inc.
- Boehringer Ingelheim International GmbH
- F. Hoffmann-La Roche Ltd
- Zealand Pharma A/S
- Diversified Biopharma Oral & Monthly Entrants
- Next-Generation Co-Agonist & Amylin Innovators
- Case Studies
- Novo Nordisk A/S
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Active Drug Substance, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Therapeutic Indication, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Route and Administration, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Receptor Mechanism, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Active Drug Substance
- Figure 6: Global Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Therapeutic Indication
- Figure 9: Global Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Route and Administration
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Receptor Mechanism
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Active Drug Substance
- Figure 32: North America Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Therapeutic Indication
- Figure 35: North America Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Route and Administration
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Receptor Mechanism
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Active Drug Substance
- Figure 48: Latin America Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Therapeutic Indication
- Figure 51: Latin America Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Route and Administration
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Receptor Mechanism
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Active Drug Substance
- Figure 64: Western Europe Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Therapeutic Indication
- Figure 67: Western Europe Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Route and Administration
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Receptor Mechanism
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Active Drug Substance
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Therapeutic Indication
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Route and Administration
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Receptor Mechanism
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Active Drug Substance
- Figure 96: East Asia Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Therapeutic Indication
- Figure 99: East Asia Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Route and Administration
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Receptor Mechanism
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Active Drug Substance
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Therapeutic Indication
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Route and Administration
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Receptor Mechanism
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Active Drug Substance, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Active Drug Substance, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Active Drug Substance
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Therapeutic Indication, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Therapeutic Indication, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Therapeutic Indication
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Route and Administration, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Route and Administration, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Route and Administration
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Receptor Mechanism, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Receptor Mechanism, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Receptor Mechanism
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is theGLP-1 Receptor Agonist Market in 2026, and what is forecast for 2036?
FMI estimates that global GLP-1 receptor agonist valuation stood at USD 38.5 billion in 2025 and reached USD 46.2 billion in 2026. Total sector revenue is on track to hit USD 286.1 billion by 2036 as multi-indication coverage and oral tablets scale globally.
What is the CAGR for the GLP-1 Receptor Agonist Market from 2026 to 2036?
The GLP-1 receptor agonist sector is projected to expand at a 20.0% CAGR over the 2026 to 2036 window, adding USD 239.9 billion across diabetes and obesity as well as cardiorenal-hepatic indications.
Which active drug substance segment leads the GLP-1 Receptor Agonist Market?
Semaglutide Ozempic Wegovy and Rybelsus holds an estimated 58.2% of active drug substance demand in 2026 owing to broad regulatory clearances across diabetes and obesity as well as cardiovascular and liver fibrosis care.
Which route and administration segment leads the GLP-1 Receptor Agonist Market?
Subcutaneous Weekly Injectable Auto-Injector Pens represent an estimated 88.0% of the route and administration category in 2026 as prefilled weekly pens deliver high bioavailability and adherence.
Which country has a notable growth outlook during the assessment period?
The UAE leads national expansion projections at a 23.7% CAGR through 2036, driven by 83.5% insurance coverage among treated hospital cohorts and rapid adoption of weekly incretin pens.
Who are the key players in the market?
Eli Lilly and Company and Novo Nordisk A/S supply global demand with AstraZeneca plc, Sanofi SA, and Pfizer Inc. Additional active participants include Amgen Inc. and Viking Therapeutics Inc., while Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd, and Zealand Pharma A/S also compete.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
