
- Market Size (2026)
- USD 4.57 Bn
- Forecast (2036)
- USD 7.44 Bn
- CAGR (2026 to 2036)
- 5.0%
How Big Is the Guidewires Market in 2026?
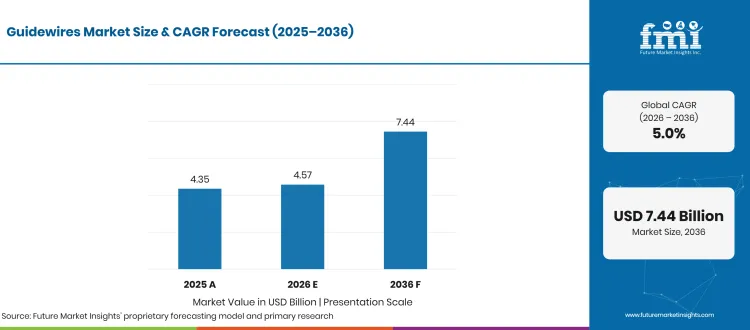
The global guidewires market reaches an estimated USD 4.57 billion in 2026, advancing from USD 4.35 billion in 2025, and Future Market Insights (FMI) forecasts category revenue to attain USD 7.44 billion by 2036, progressing at a 5.0% CAGR between 2026 and 2036 while generating USD 2.87 billion in 10-year incremental dollar expansion.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 4.35 billion |
| 2026 Market Size (Estimated) | USD 4.57 billion |
| 2036 Market Size (Projected) | USD 7.44 billion |
| Compound Annual Growth Rate (2026 to 2036) | 5.0% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 2.87 billion |
| Dominant Core Metallurgy (2026 to 2036 Share) | Nitinol Superelastic Kink-Resistant Core (40.5% in 2026, rising to 46.8% by 2036) |
| Leading Wire Caliper Diameter (2026 Share) | 0.014 Inch Coronary Intervention Standard (44.3% share in 2026, rising to 47.2% by 2036) |
| Leading Coating Technology (2026 Share) | Hydrophilic Lubricious Coating (48.0% share in 2026, rising to 54.0% by 2036) |
| Leading Clinical Application & End User | Interventional Cardiology PTCA (51.8% share) | Hospital Cath Labs (62.4% share) |
| Largest Country Markets (2026 Global Share) | United States (38.0%), Japan (10.0%), Germany (7.5%), South Korea (4.0%) |
| Fastest-Growing Country Markets (2026 to 2036) | South Korea (6.0% CAGR), Saudi Arabia (5.9% CAGR), Australia (5.3% CAGR), United States (5.1% CAGR) |
| Leading Tier-1 Companies | Terumo Corporation, Asahi Intecc Co., Ltd., Boston Scientific Corporation, Abbott Laboratories |
Source: Future Market Insights analysis of the guidewires market, 2026.
Executive Market Overview
Value concentrates in hospital catheterization laboratories and vascular suites, where two to four single-use guidewires are consumed in a complex intervention, and infection-control rules bar resterilization of fine-lumen coiled wires, so every percutaneous case becomes recurring disposable demand. North America, East Asia and Western Europe absorb most of that spend, while Gulf cardiac institutes add volume faster. The Journal of the American Heart Association (March 2026) reported a 507-case CTO study in which small-vessel occlusions below 3.0 mm made up 35.1% of cases, pulling operators toward tapered penetration and externalization wires. JACC: Advances (January 2026) showed 98% coronary access engagement across 2,298 transcatheter aortic valve replacement patients, including 11.8% requiring guidewire airmailing and guide extension, with 96% PCI technical success. Buyers now budget per-case wire consumption rather than shelf replenishment, pushing procurement toward higher torque wires.
Stainless-steel access mandrels still clear commodity tender pricing across hospital group purchasing organizations, which caps margin on routine diagnostic procedures. To lift value per procedure, manufacturers pair composite nitinol-tungsten crossing wires with intravascular lithotripsy and dual-sensor imaging catheters, selling a device family rather than a bare wire. FMI sees interventional cardiology devices expanding at an 8.4% CAGR and peripheral embolization devices at a 7.0% CAGR against 5.0% CAGR for foundational guidewires, so value sits in the accessory stack. Teleflex Incorporated (July 2025) completed its EUR 760 million purchase of BIOTRONIK's Vascular Intervention business on 1 July 2025, giving it coronary and peripheral guidewires to sell beside drug-coated balloons and stents. Market sizing covers single-use sterile interventional and diagnostic guidewires from 0.010-inch to 0.038-inch calipers, while excluding fractional flow reserve electronic pressure consoles, standalone guiding catheters, angioplasty balloons and permanent stents.
Analyst Perspective
"Guidewire suppliers will capture higher margin per procedure by shifting hospital consignment contracts from commodity stainless-steel access wires toward composite-core CTO crossing wires and steerable neurovascular micro-wires. The principal commercial risk is hospital tender bundling, where single-line wire producers lose shelf share to diversified medtech groups packaging guidewires with lithotripsy and imaging catheters."
- Anurag Sharma, Principal Consultant, Future Market Insights (FMI)
Major Market Trends and Insights
- Lithotripsy Trials Pull Support Wires Into Calcified Lesions: Operators advance acoustic lithotripsy balloons over dedicated 0.014-inch workhorse and extra-support wires before stent implantation, pulling the wire earlier into the case. Boston Scientific Corporation (May 2026) announced at EuroPCR on 19 May 2026 that its SEISMIQ 4CE catheter met all primary safety and effectiveness endpoints in the FRACTURE IDE trial. Abbott Laboratories (November 2026) reported 30-day TECTONIC IDE results at TCT on 1 November 2026, with 97% procedural success and a 0.3% 30-day target lesion failure rate across 335 patients using its investigational SonicForce coronary IVL system. Catheterization laboratories respond by lifting support wire par levels.
- Dual-Sensor Imaging Raises the Wire Count Per Complex PCI: Intravascular ultrasound and optical frequency domain imaging show calcified bifurcations and chronic total occlusions in real time, raising multi-wire utilisation and dwell time per patient with dual balloon angioplasty catheters. The American College of Cardiology (March 2026) reported RENOVATE-COMPLEX-PCI, where imaging guidance cut target lesion failure (hazard ratio 0.68; p=0.009) and cardiac death or target-vessel myocardial infarction (7.6% vs. 10.7%) versus angiography alone. Terumo Interventional Systems (June 2026) completed the first U.S. procedure at Mount Sinai Fuster Heart Hospital on 29 June 2026 with its FDA-cleared OPUSWAVE Dual Sensor Imaging System and 2.6 Fr DualView catheter.
- Purpose-Built Pacing Wires and Portfolio Deals Rewrite Cath Lab Rosters: Structural-heart operators and hospital value-analysis committees replace improvised left-ventricular pacing workarounds and fragmented vendor rosters with integrated single-wire pacing systems and consolidated catheterization bundles. Merit Medical Systems, Inc. (October 2026) commercialized the SOLO PACE FUSION Temporary LV Pacing System in October 2026, combining transcatheter heart valve delivery and rapid left-ventricular pacing in one guidewire package without subcutaneous needles. Integer Holdings Corporation (February 2026) reported on 19 February 2026 that full-year 2025 Cardio and Vascular sales rose 17% year-over-year to USD 1.107 billion after its Precision Coating and VSi Parylene acquisitions.
What Are the Main Drivers, Restraints, and Opportunities?
Complex coronary CTO and bifurcation procedures lift multi-wire consumption per intervention, while distal tip entrapment and coil fracture risks inside calcified lesions restrain aggressive manipulation, leaving steerable nitinol micro-wires as the primary high-margin growth avenue.
Driver: Rising Complex Coronary CTO and Bifurcation Procedures
Elderly and diabetic patients ineligible for open bypass are driving higher percutaneous revascularization volumes, and each complex case consumes 2.6 to 4.2 guidewires against 1.4 to 1.8 wires in routine single-vessel angioplasty. Operators crossing calcified small-vessel chronic total occlusions need tapered-core penetration and externalization wires that a workhorse mandrel cannot deliver, so catheterization laboratories order deeper wire sets per case. The Journal of the American Heart Association (March 2026) confirmed across 507 consecutive CTO-PCI procedures that small-vessel occlusions below 3.0 mm accounted for 35.1% of interventions, with diabetes in 57.9% and chronic kidney disease in 42.7% of the same cohort. Hospital purchasing therefore treats wire consumption as a procedure-linked consumable, keeping complex-lesion wire demand rising through the decade.
Restraint: Distal Tip Entrapment, Wire Fracture, and Coating Shear Hazards
Mechanical fatigue, distal coil unravelling, tip entrapment behind stent struts and hydrophilic polymer delamination during rotational manipulation in calcified bifurcations force operators to calibrate torque and keep backup peripheral micro catheters within reach, because a jammed coil against a plaque shelf can embolise and trigger coronary thrombosis or vessel perforation. Frontiers in Cardiovascular Medicine (September 2026) put coronary guidewire fracture at 0.2% to 0.8% of PCI procedures, describing a 59-year-old diabetic patient who needed a minimally invasive hybrid trans-brachial arteriotomy with endoluminal traction 34 days after PCI to retrieve a fractured Sion guidewire fragment from the left anterior descending artery. Committees read those cases as a reason to pay for tip durability and single-use exchange.
Opportunity: Steerable In-Vivo Nitinol Micro-Wires and Outpatient ASC Migration
Deflectable and steerable nitinol guidewires that let physicians adjust distal tip curvature in vivo carry a clear price premium across neurovascular and peripheral devices. Removing repeated wire exchanges during selective branch cannulation cuts fluoroscopy time and contrast load. On 18 September 2026 the U.S. Food and Drug Administration (September 2026) cleared Rapid Medical's Hyperdrive 35 Steerable Intravascular Guidewire under 510(k) K253146 (21 CFR 870.1330, Class II) for selective catheter placement across peripheral and neurovascular anatomy. The American College of Cardiology (August 2025) analysed revised 2026 Medicare work RVU valuations, including a +9.5% work RVU increase for complex stenting code 92X01 and 15.00 work RVUs for combined antegrade/retrograde CTO code 92X02, so reimbursement supports the premium.
How Is the Guidewires Market Segmented?
The global guidewires market is segmented by core metallurgy, wire caliper diameter, coating technology, clinical application, end user and region, with all values standardised to single-use sterile disposable wire units.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Main Growth Benchmark (2026 to 2036) |
|---|---|---|---|
| Core Metallurgy | Nitinol Superelastic Kink-Resistant Core, Stainless Steel High-Support Core, Hybrid Composite Platinum Tip Wire, Cobalt-Chromium Alloy Core | Nitinol Superelastic Core (40.5% revenue share) | Nitinol Superelastic Core share rises to 46.8% by 2036 |
| Wire Caliper Diameter | 0.014 Inch Coronary Intervention Standard, 0.018 Inch Peripheral Intervention, 0.035 Inch Diagnostic and Access Wire, 0.010 to 0.012 Inch Neurovascular Micro-Wires | 0.014 Inch Coronary Standard (44.3% revenue share) | 0.014 Inch Coronary Standard share reaches 47.2% by 2036 |
| Coating Technology | Hydrophilic Lubricious Coating, Hydrophobic PTFE Silicone Coating, Uncoated Radiopaque Distal Coils, Hybrid Distal-Hydrophilic Coating, Heparin Anti-Thrombogenic Coating | Hydrophilic Lubricious Coating (48.0% revenue share) | Hydrophilic Lubricious Coating share rises to 54.0% by 2036 |
| Clinical Application | Interventional Cardiology PTCA, Interventional Radiology and Peripheral Vascular, Endovascular Neuro-Intervention, Urological and GI Endoscopy | Interventional Cardiology PTCA (51.8% revenue share) | Complex CTO, bifurcation & neurovascular wire share reaches 48.0% to 52.5% by 2036 |
| End User | Hospital Catheterization Laboratories, Ambulatory Surgical Centers (ASCs), Specialty Cardiac and Vascular Institutes, Academic Medical Centers | Hospital Catheterization Laboratories (62.4% share) | Outpatient ASC procedure share rises from 17.5%-19.8% in 2026 to 26.0%-29.5% by 2036 |
| Region | North America, Western Europe, East Asia, South Asia & Pacific, Middle East & Africa, Latin America, Eastern Europe | North America (led by United States at 38.0% global share) | South Korea (6.0% CAGR) & Saudi Arabia (5.9% CAGR) lead national growth |
Source: Future Market Insights analysis of the guidewires market, 2026.
Why Does the Nitinol Superelastic Kink-Resistant Core Segment Lead by Core Metallurgy?
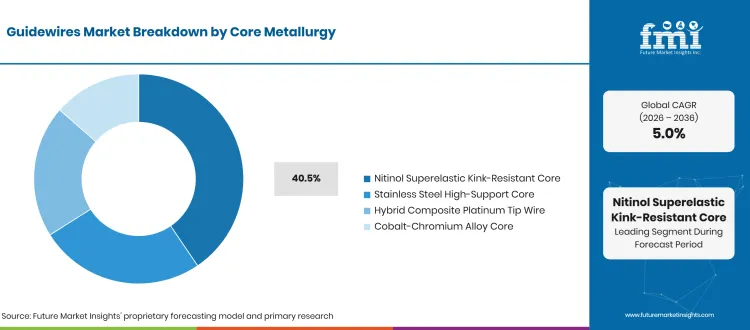
Core metallurgy is led by Nitinol Superelastic Kink-Resistant Core, holding 40.5% of global guidewires revenue in 2026 and projected to reach 46.8% by 2036. Equiatomic nickel-titanium mandrels undergo reversible stress-induced austenite-to-martensite transformation, so the wire negotiates acute 90-degree bifurcations and recovers its straight geometry without permanent kinking. Interventionalists buying steerable neurovascular guidewires and coronary workhorse wires prefer nitinol cores over conventional 304V stainless steel, because a kinked stainless mandrel loses one-to-one rotational torque transmission and is discarded mid-procedure, turning a metallurgical choice into a consumable cost. MDPI Actuators (May 2026) reported on 30 May 2026 that 0.4 mm medical-grade superelastic nitinol guidewire actuators tested at 37 °C physiological conditions show an austenite elastic modulus of 70 GPa and a transformation plateau stress near 480 MPa, with 6% to 8% recoverable strain and high cyclic fatigue life. Buyers pay for that fatigue life through repeated exchanges in one case, so nitinol keeps taking hospital tender share.
What Sustains 0.014 Inch Coronary Intervention Standard Leadership by Wire Caliper Diameter?
Wire caliper diameter is led by the 0.014 Inch Coronary Intervention Standard, which takes 44.3% of global revenue in 2026 and is forecast to reach 47.2% by 2036. The 0.014-inch (0.36 mm) outer diameter is the universal dimensional standard engineered to fit the inner guidewire lumen of all rapid-exchange coronary angioplasty balloons, drug-eluting stents, intravascular imaging probes and over-the-wire micro balloon catheters. Beyond coronary revascularization, vascular specialists pair 0.014-inch wires with low-profile microcatheter systems in below-the-knee infrapopliteal interventions for diabetic critical limb ischemia. Precision centreless grinding is required to taper the distal mandrel to 0.003 inches while maintaining tip radiopacity, so a supplier that cannot hold that tolerance loses the tender. Boston Scientific Corporation (May 2026) met primary FRACTURE IDE endpoints with its SEISMIQ 4CE lithotripsy catheter, and Abbott Laboratories (November 2026) achieved 97% procedural success in the 335-patient TECTONIC trial, both of which reinforce 0.014-inch wire demand in calcified lesions.
How Does Hydrophilic Lubricious Coating Lead by Coating Technology?
Coating technology is led by Hydrophilic Lubricious Coating, holding 48.0% of global guidewires revenue in 2026 and projected to expand to 54.0% by 2036. Cross-linked polyvinylpyrrolidone, polyurethane and hyaluronan polymer hydrogels absorb water upon blood contact to form a low-shear boundary layer that cuts vessel-wall friction by more than 80% against bare metal coils. Operators advancing vascular access catheters and crossing wires through tortuous radial arteries or subtotal calcified occlusions rely on hydrophilic jackets to prevent radial artery spasm and glide past plaque shelves. Regulated clearances show how suppliers combine distal lubricity with proximal polytetrafluoroethylene torque shafts, and on 26 August 2025 the U.S. Food and Drug Administration (August 2025) cleared Imperative Care's X-Wire Guidewire under 510(k) K244061 (21 CFR 870.1330, Class II) across 0.014-inch, 0.018-inch and 0.024-inch diameters and 200 cm to 300 cm lengths, a clearance hospital committees treat as a coating benchmark.
Why Does Interventional Cardiology PTCA Lead by Clinical Application?
Clinical application is led by Interventional Cardiology PTCA, commanding 51.8% of global revenue in 2026 on high coronary stenting volumes and multi-wire complex lesion protocols. Routine single-vessel stenting consumes one workhorse wire, while complex bifurcations, post-TAVR coronary cannulations and chronic total occlusions require side-branch protection wires, microcatheter exchange wires and 300 cm retrograde externalization wires, lifting complex CTO and bifurcation procedures from 37.5% to 41.0% of wire revenue in 2026 to 48.0% to 52.5% by 2036. The American College of Cardiology (March 2026) reported RENOVATE-COMPLEX-PCI, where intravascular imaging guidance cut target lesion failure by 32% (HR 0.68). Asahi Intecc Co., Ltd. (May 2026) reported in its Q3 FY2026 financial presentation that global Medical Division revenue rose 16.5% year-over-year on strong PCI guidewire and penetration catheter demand, which tells catheterization laboratories that supply expands in step with their own case volume.
What Gives Hospital Catheterization Laboratories the Leading Share by End User?
End user is led by Hospital Catheterization Laboratories, which account for 62.4% of global guidewires demand in 2026 through 24-hour emergency primary PCI for ST-elevation myocardial infarction, mechanical thrombectomy for acute ischemic stroke, and hybrid structural-heart TAVR procedures. High-acuity multi-vessel CTO and post-TAVR coronary interventions stay concentrated inside inpatient tertiary hospitals with on-site cardiothoracic surgical backup, as JACC: Advances (January 2026) showed 64.7% of post-TAVR PCI procedures performed urgently for acute coronary syndrome with 98% coronary guidewire and catheter engagement. At the same time, outpatient ambulatory surgical centers and office-based vascular labs are projected to expand their procedural share from 17.5% to 19.8% in 2026 to 26.0% to 29.5% by 2036, following the 2026 Medicare Physician Fee Schedule PCI code updates reviewed by the American College of Cardiology (August 2025), which shifts purchasing toward standardised consignment packs.
Guidewires Market by Region and Country (2026 to 2036)
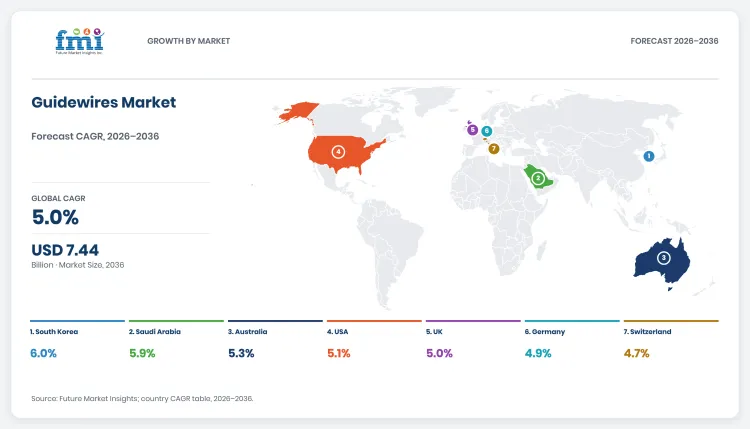
North America, East Asia and Western Europe generate the majority of global guidewire sales through 2036, while East Asian intravascular-imaging centres and Gulf tertiary cardiac institutes post the fastest compound annual growth rates. Divergence follows procedure mix rather than population, because catheterization suite build-out in Saudi Arabia and stroke centre expansion in South Korea add complex-case volume faster than replacement demand in North America. FMI projects the eight tracked countries in Table 3 to hold 67.7% of global revenue in 2026 (USD 3,093.9 million) and 68.1% by 2036 (USD 5,068.1 million), adding USD 1,974.2 million in 10-year incremental revenue. The United States stays the largest country market, moving from USD 1,736.6 million in 2026 to USD 2,855.8 million by 2036 at a 5.1% CAGR, while South Korea leads national growth at 6.0%.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 -> 2036) |
|---|---|---|---|---|---|
| United States | USD 1,736.6 million | USD 2,855.8 million | +USD 1,119.2 million | 5.1% | 38.0% -> 38.4% |
| Japan | USD 457.0 million | USD 709.7 million | +USD 252.7 million | 4.5% | 10.0% -> 9.5% |
| Germany | USD 342.8 million | USD 553.1 million | +USD 210.3 million | 4.9% | 7.5% -> 7.4% |
| South Korea | USD 182.8 million | USD 327.4 million | +USD 144.6 million | 6.0% | 4.0% -> 4.4% |
| United Kingdom | USD 159.9 million | USD 260.5 million | +USD 100.6 million | 5.0% | 3.5% -> 3.5% |
| Australia | USD 91.4 million | USD 153.2 million | +USD 61.8 million | 5.3% | 2.0% -> 2.1% |
| Saudi Arabia | USD 68.6 million | USD 121.7 million | +USD 53.1 million | 5.9% | 1.5% -> 1.6% |
| Switzerland | USD 54.8 million | USD 86.7 million | +USD 31.9 million | 4.7% | 1.2% -> 1.2% |
Source: Future Market Insights analysis of the guidewires market, 2026.
United States
Cardiac catheterization throughput in the United States is set to compound at a 5.1% CAGR from USD 1,736.6 million in 2026 to USD 2,855.8 million by 2036, adding USD 1,119.2 million while global share edges from 38.0% to 38.4%. Cardiac catheterization laboratories and outpatient vascular centers buy hydrophilic-coated steerable guidewires to negotiate complex calcified coronary lesions, and their buying decision rests on one-to-one torque response and durable lubricious coating on tortuous distal vessels. The U.S. Food and Drug Administration (September 2026) documents expanded 510(k) indications for specialized nitinol core guidewires used in intravascular lithotripsy and chronic total occlusion recanalization, which shortens the qualification list that hospital value-analysis committees work from. Expanding complex coronary interventions and peripheral arterial procedures will keep wire consumption heavy, so supplier contracts through 2036 reward vendors that hold consignment par levels without stock.
Japan
Japan's end-user wire demand is projected to compound at a 4.5% CAGR from USD 457.0 million in 2026 to USD 709.7 million by 2036, adding USD 252.7 million while global share eases from 10.0% to 9.5%. Japanese interventionalists lead the clinical practice of chronic total occlusion percutaneous coronary intervention, so precision micro-guidewires carry the buying decision rather than the standard workhorse. The Pharmaceuticals and Medical Devices Agency (March 2026) highlighted clearances for specialized coil-tapered guidewires built for retrograde CTO approaches, giving hospital committees approved product to plan around. Domestic producers Asahi Intecc and Terumo hold local catheterization suites with proprietary wire-drawing and torque-control technology, so local tenders lean toward domestic grade. High procedural complexity and universal health insurance coverage should sustain strong guidewire orders, keeping commercial returns stable through 2036.
Germany
German catheter demand is forecast to compound at a 4.9% CAGR from USD 342.8 million in 2026 to USD 553.1 million by 2036, delivering USD 210.3 million in incremental value while global share holds near 7.5% before easing to 7.4% in 2036. University heart centers and vascular surgery departments run high transcatheter aortic valve implantation and peripheral endovascular revascularization volumes, and their clinicians prioritize extra-stiff support wires that can deliver heavy structural heart prostheses safely. Clinical trial disclosures from BIOTRONIK SE & Co. KG (February 2025) and Boston Scientific Corporation (May 2026) confirm strong procedural success with specialized steerable guidewires in complex calcified anatomy, which shortens the approval argument inside German value-analysis committees. Comprehensive statutory hospital reimbursement and expanding peripheral intervention volumes will maintain steady guidewire procurement, supporting dependable market growth over the decade.
South Korea
South Korea posts the fastest growth among tracked guidewires markets, compounding at a 6.0% CAGR from USD 182.8 million in 2026 to USD 327.4 million by 2036, adding USD 144.6 million and lifting global share from 4.0% to 4.4%. Cardiovascular procedure volumes in Seoul's major medical centers and expanding peripheral endovascular work push orders for polymer-jacketed hydrophilic guidewires, and device evaluations from the Ministry of Food and Drug Safety confirm faster domestic adoption for neurovascular thrombectomy. Interventional radiologists select shape-retaining micro-wires for acute ischemic stroke treatment, which rewards suppliers that deliver consistent tip memory rather than a cheap one-off. Expanding insurance coverage for advanced vascular interventions and new regional stroke centers should accelerate guidewire procurement, driving healthy commercial growth through 2036.
United Kingdom
Guidewire sales in the United Kingdom are forecast to progress at a 5.0% CAGR from USD 159.9 million in 2026 to USD 260.5 million by 2036, adding USD 100.6 million while global share stays at 3.5% across the forecast. National Health Service regional cardiac centers procure frontline coronary and peripheral guidewires for coronary artery disease and critical limb ischemia, and they judge value on standardisation rather than premium feature sets. Device safety directives from the Medicines and Healthcare products Regulatory Agency (MHRA) stress lot traceability and tip-detachment resistance across endovascular consumables, so tender scoring rewards documented durability. British catheterization teams use central procurement frameworks to secure bulk deliveries of standardized workhorse guidewires. Continued NHS investment in cardiovascular diagnostic hubs and outpatient day-case catheterization will keep demand steady, ensuring durable commercial progression through 2036.
Australia
Australian catheter suite spending is projected to expand at a 5.3% CAGR from USD 91.4 million in 2026 to USD 153.2 million by 2036, adding USD 61.8 million while global share inches from 2.0% to 2.1%. Public hospital catheterization suites and private interventional cardiology groups buy coronary and neurovascular guidewires for minimally invasive vascular surgery, and their specialists expect hydrophilic polymer coatings that resist flaking during complex rotablation procedures. Regulatory announcements from the Therapeutic Goods Administration (August 2026) mandate Unique Device Identification labeling so post-market traceability runs end to end for surgical guide devices, which moves serialized pouches into tender specifications. Sustained Medicare funding for specialized endovascular revascularizations will hold purchase volumes steady, supporting durable commercial expansion through 2036.
Saudi Arabia
Saudi catheterization spend is projected to advance at a 5.9% CAGR from USD 68.6 million in 2026 to USD 121.7 million by 2036, delivering USD 53.1 million while global share climbs from 1.5% to 1.6%. Rapid expansion of tertiary cardiology hospitals and catheterization suites in Riyadh and Jeddah under Vision 2030 healthcare programs fuels ordering, and committees there buy premium hydrophilic and stiff guidewires to treat acute coronary syndromes and peripheral vascular disease. Regulatory announcements from the Saudi Food and Drug Authority (July 2025) stress stringent quality conformity certification for cardiovascular interventional devices, so registration paperwork decides which suppliers clear the shortlist. Government healthcare investment and new regional specialty cardiac centers should accelerate guidewire procurement, driving strong market gains through 2036.
Switzerland
Swiss wire revenue is forecast to grow at a 4.7% CAGR from USD 54.8 million in 2026 to USD 86.7 million by 2036, adding USD 31.9 million while global share remains at 1.2% across the forecast. University cardiology clinics and private vascular surgery centers procure high-performance nitinol and stainless steel guidewires for complex transcatheter valve and coronary revascularizations, and their operators buy on tactile feedback and distal tip durability for micro-vessel navigation. Regulatory notices from Swissmedic (July 2026) confirm full implementation of the swissdamed medical device registration database, which lets clinics monitor clinical performance device by device and supports premium positioning. High healthcare funding and broad clinical adoption of minimally invasive catheter technology should defend steady procurement, ensuring stable commercial returns through 2036.
Competitive Environment and Notable Companies
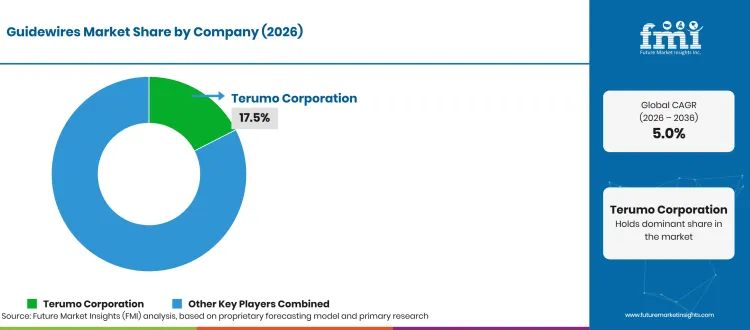
The guidewires market is served by Terumo Corporation, Asahi Intecc Co., Ltd., Boston Scientific Corporation, Abbott Laboratories, Medtronic plc, Teleflex Incorporated, Stryker Corporation, Cordis Corporation, Merit Medical Systems, Inc. and Integer Holdings Corporation. Supply is tiered, with precision Japanese wire-drawing and hydrophilic hydrogel houses setting the coronary CTO and radial access standard, diversified cardiovascular and neurovascular device groups selling wires inside stent and lithotripsy portfolios, and specialist steerable wire makers plus contract manufacturers supplying original equipment subassemblies to those brands. Tier one competes on clinical evidence and bundled device portfolios, tier two on guidewire specification and hospital contract price.
How Are Companies Positioned in the Guidewires Market?
Asahi Intecc Co., Ltd. (Sion, Fielder XT, Gaia Next, Chikai) and Terumo Corporation (Radifocus Glidewire, Runthrough NS) lead precision coronary CTO and hydrophilic access guidewires, with Asahi Intecc Co., Ltd. (May 2026) reporting 18.0% consolidated nine-month revenue growth to JPY 108,366 million in Q3 FY2026. Boston Scientific Corporation (July 2026) (Choice PT, V-18, Amplatz Super Stiff) and Abbott Laboratories (November 2026) (Hi-Torque BMW Universal II, Whisper, Pilot) bundle 0.014-inch wires with coronary lithotripsy and stent systems, while Teleflex Incorporated (July 2025), Stryker Corporation (July 2025) and Merit Medical Systems, Inc. (October 2026) lead vascular access, neurovascular and TAVR pacing.
What Matters When a Buyer Selects a Guidewires Supplier?
Hospital catheterization laboratory directors and health-system value-analysis committees evaluate guidewire suppliers on verified one-to-one rotational torque transmission, distal tip shape retention, zero hydrophilic polymer particulate shedding under ISO 11070 bench testing, and automated UDI barcode compliance. Because distal coil fracture occurs in 0.2% to 0.8% of PCI procedures per Frontiers in Cardiovascular Medicine (September 2026), and mandatory UDI rules took effect under the Therapeutic Goods Administration Australia (August 2026) and Swissmedic Swiss Agency for Therapeutic Products (July 2026) on 1 July 2026, hospital tenders now require solderless core-to-coil lock joints and full pouch serialization.
Which Capabilities Distinguish Product Offers?
Differentiation rests on proprietary wire-drawing metallurgy, multi-layer hydrophilic hydrogel chemistry and integrated catheter-system compatibility. Asahi Intecc Co., Ltd. uses ACT ONE hollow-stranded rope-coil torque technology across its Sion and Gaia Next CTO wires; Terumo Interventional Systems (June 2026) pairs M-coat hydrophilic Glidewire technology with its OPUSWAVE Dual Sensor IVUS/OFDI imaging platform; Boston Scientific Corporation (May 2026) and Abbott Laboratories (November 2026) co-develop 0.014-inch coronary wires with their SEISMIQ 4CE and SonicForce coronary IVL catheters; and Merit Medical Systems, Inc. (October 2026) integrates temporary LV pacing and TAVR valve delivery in the SOLO PACE FUSION wire.
How Does Geographic Reach Affect Competition?
Terumo Corporation, Asahi Intecc Co., Ltd., Boston Scientific Corporation and Abbott Laboratories operate direct cardiovascular sales and clinical field-specialist teams across more than 100 countries. In Q3 FY2026 disclosures, Asahi Intecc Co., Ltd. (May 2026) reported regional Medical Division sales growth of 21.6% in China, 18.1% in Europe, 12.6% in the United States and 5.2% in Japan, reinforced by its April 2026 TAME distribution partnership with South Korea's NEXTBIOMEDICAL. Meanwhile, Teleflex Incorporated (July 2025) expanded its European and Asia-Pacific cath lab footprint by acquiring Berlin-based BIOTRONIK's Vascular Intervention division.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 1 November 2026: Abbott Laboratories reported 97% procedural success and 0.3% 30-day TLF in the 335-patient TECTONIC IDE trial for its SonicForce Coronary IVL System at TCT 2026 (Abbott Laboratories, November 2026). | Increases pull-through demand for high-support 0.014-inch coronary guidewires during calcified lesion preparation. | Align cath lab consignment par levels for 0.014-inch workhorse and extra-support coronary wires with IVL balloon adoption. |
| 29 June 2026: Terumo Interventional Systems completed the first U.S. clinical case at Mount Sinai Fuster Heart Hospital using its OPUSWAVE Dual Sensor IVUS/OFDI Imaging System (Terumo Interventional Systems, June 2026). | Simultaneous IVUS and OFDI visualization expands complex bifurcation and CTO crossing procedures requiring precision-torque wires. | Evaluate bundled vendor contracting across dual-sensor intravascular imaging catheters and 0.014-inch composite-core guidewires. |
| 19 May & 29 July 2026: Boston Scientific announced positive FRACTURE IDE results for its SEISMIQ 4CE Coronary IVL Catheter and reported USD 5.442B Q2 2026 net sales (+7.8% organic CV growth) (Boston Scientific Corporation, May & July 2026). | Reinforces single-vendor cath lab contracting across calcium modification, drug-eluting stents, and Choice PT/V-18 guidewires. | Benchmark multi-year cath lab bundle discounts linking coronary guidewires with lithotripsy and stent commitments. |
| 1 July 2025 & 5 November 2026: Teleflex completed the EUR 760M acquisition of BIOTRONIK's Vascular Intervention division and divested its OEM unit for USD 1.5B to focus on Vascular and Interventional units (Teleflex Incorporated, July 2025 & November 2026). | Creates a consolidated global supplier of Arrow vascular access wires, CTO guidewires, drug-coated balloons, and Freesolve scaffolds. | Consolidate supplier qualification across coronary CTO guidewires, peripheral catheters, and vascular access kits. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| Terumo Corporation | Global hydrophilic guidewire pioneer (Radifocus Glidewire, Runthrough NS) and intravascular imaging leader | Completed the first U.S. clinical procedure using its FDA-cleared OPUSWAVE Dual Sensor IVUS/OFDI Imaging System and 2.6 Fr DualView catheter at Mount Sinai Fuster Heart Hospital on 29 June 2026 (Terumo Interventional Systems, June 2026). |
| Asahi Intecc Co., Ltd. | Japanese precision wire-drawing leader (Sion, Fielder XT, Gaia Next CTO, and Chikai neurovascular wires) | Signed an exclusive TAME distribution agreement with NEXTBIOMEDICAL on 9 April 2026 and reported 18.0% 9M FY2026 revenue growth to JPY 108,366 million on 15 May 2026 driven by PCI guidewires (Asahi Intecc Co., Ltd., April & May 2026). |
| Boston Scientific Corporation | Global interventional cardiology and peripheral leader (Choice PT, PT2, V-18, Amplatz Super Stiff, Synchro) | Reported positive FRACTURE IDE trial endpoints for its SEISMIQ 4CE Coronary IVL Catheter on 19 May 2026 and Q2 2026 net sales of USD 5.442 billion (+7.8% organic Cardiovascular growth) on 29 July 2026 (Boston Scientific Corporation, May & July 2026). |
| Abbott Laboratories | Global vascular device leader (Hi-Torque BMW Universal II, Whisper, Pilot, and Command peripheral wires) | Announced 30-day results from the 335-patient TECTONIC IDE study at TCT on 1 November 2026, achieving 97% procedural success and 0.3% TLF with its SonicForce Coronary IVL System over 0.014-inch wires (Abbott Laboratories, November 2026). |
| Medtronic plc | Global medical technology leader supplying Cougar, Zinger, and Thunder coronary wires and Confida TAVR support wires | Supplies pre-shaped 0.035-inch Confida Brecker left-ventricular guidewires for Evolut FX+ transcatheter aortic valve replacement and neurovascular micro-wires across global heart centers. |
| Teleflex Incorporated | Global vascular access (Arrow) and coronary/peripheral CTO guidewire (Watts, Minamo, Galeo) supplier | Completed the acquisition of BIOTRONIK's Vascular Intervention division on 1 July 2025 (BIOTRONIK SE & Co. KG, February 2025; Teleflex Incorporated, July 2025) and reported USD 567.8M Q3 2026 continuing revenue on 5 November 2026 (Teleflex Incorporated, November 2026). |
| Stryker Corporation | Global neurovascular (Synchro SELECT, Transend) and Inari peripheral thrombectomy leader | Launched the InThrill Over-the-Wire Thrombectomy System (via Inari Medical) on 29 July 2025 for small-vessel thrombosis interventions delivered over a 0.018-inch guidewire (Stryker Corporation, July 2025). |
| Cordis Corporation | Global cardiovascular and endovascular specialist (Stabilizer, Shinobi CTO, ATW, and Emerald diagnostic wires) | Supplies steerable 0.014-inch coronary crossing wires and PTFE-coated diagnostic access guidewires across hospital catheterization laboratories and outpatient vascular suites. |
| Merit Medical Systems, Inc. | Global manufacturer of InQwire diagnostic, SplashWire hydrophilic, True Form reshapeable, and SOLO PACE FUSION TAVR wires | Commercialized the SOLO PACE FUSION Temporary LV Pacing System in October 2026, integrating TAVR valve delivery and rapid left-ventricular pacing into a single guidewire package (Merit Medical Systems, Inc., October 2026). |
| Integer Holdings Corporation | World's largest medical device guidewire and coating CDMO (Greatbatch, Lake Region Medical, Precision Coating) | Reported 17% full-year 2025 Cardio and Vascular sales growth to USD 1.107 billion (out of USD 1.854 billion total sales) on 19 February 2026 following its Precision Coating and VSi Parylene acquisitions (Integer Holdings Corporation, February 2026). |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Guidewires Market Report Scope and Research Methodology
FMI sizes the global guidewires market by reconciling national coronary, peripheral endovascular and neurovascular catheterization procedure counts, running at 25.6 million to 28.2 million procedures in 2026 and rising to 38.5 million to 42.8 million by 2036, against verified disposable guidewire intensity ratios of 1.4 to 1.8 wires for routine diagnostic and single-vessel cases and 2.6 to 4.2 wires for complex CTO and neurovascular interventions, and against hospital contract average selling prices. Parent and child market calibration ensures the global guidewires valuation of USD 4.57 billion in 2026 sits inside the wider interventional cardiology and peripheral vascular device benchmarks, while the build aligns with clinical registries from JACC: Advances (January 2026), the Journal of the American Heart Association (March 2026), and FDA 510(k) product codes DQX and MOF.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Commercial manufacturer revenue from single-use sterile interventional and diagnostic guidewires across superelastic nitinol, stainless steel, hybrid composite platinum-tip, and cobalt-chromium core architectures (0.010-inch to 0.038-inch calipers). |
| Core metallurgies covered | Nitinol superelastic kink-resistant core, stainless steel high-support core, hybrid composite platinum tip wire, and cobalt-chromium alloy core. |
| Wire caliper diameters | 0.014 inch coronary intervention standard, 0.018 inch peripheral intervention, 0.035 inch diagnostic and access wire, and 0.010 to 0.012 inch neurovascular micro-wires. |
| Coating technologies | Hydrophilic lubricious coating, hydrophobic PTFE silicone coating, uncoated radiopaque distal coils, hybrid distal-hydrophilic coating, and heparin anti-thrombogenic surface coating. |
| Clinical applications | Interventional cardiology PTCA, interventional radiology and peripheral vascular, endovascular neuro-intervention, and urological and gastroenterological endoscopy. |
| End users | Hospital catheterization laboratories, ambulatory surgical centers (ASCs), specialty cardiac and vascular institutes, and academic medical centers. |
| Exclusions | Fractional flow reserve (FFR) electronic pressure-transducer consoles, standalone guiding catheters and sheaths, angioplasty dilatation balloons, atherectomy burrs, and permanent implantable stents. |
| Quantitative units | USD billion and USD million for value; million catheterization procedures and units consumed per procedure for volume. |
| Volume basis | Single-use sterile disposable guidewires consumed across global catheterization and endovascular procedures (1.78 to 1.98 average wires per procedure in 2026). |
| Value basis | Manufacturer hospital tender, GPO consignment, and ambulatory surgical center contract revenue counted in the country of clinical use. |
| Historical & base year | 2025 historical valuation (USD 4.35 billion / USD 4,350.0 million); 2026 estimated base year (USD 4.57 billion / USD 4,570.0 million). |
| Forecast period | 2026 to 2036 (projected to reach USD 7.44 billion / USD 7,444.0 million by 2036 at a 5.0% CAGR). |
| Regions covered | North America, Western Europe, East Asia, South Asia and Pacific, Middle East and Africa, Latin America, and Eastern Europe. |
| National coverage | United States, Japan, Germany, South Korea, United Kingdom, Australia, Saudi Arabia, and Switzerland. |
| Companies covered | Terumo Corporation, Asahi Intecc Co., Ltd., Boston Scientific Corporation, Abbott Laboratories, Medtronic plc, Teleflex Incorporated, Stryker Corporation, Cordis Corporation, Merit Medical Systems, Inc., and Integer Holdings Corporation. |
Source: Future Market Insights analysis of the guidewires market, 2026.
Research Sources and Bibliography
- Abbott Laboratories. (2026, November 1). Abbott's TECTONIC clinical trial demonstrates strong 30-day outcomes and 97% procedural success for its investigational SonicForce Coronary Intravascular Lithotripsy System.
- American College of Cardiology. (2025, August 13). New proposed values for percutaneous coronary intervention (PCI) CPT codes in the 2026 Medicare Physician Fee Schedule proposed rule. https://www.acc.org/latest-in-cardiology/articles/2025/08/13/17/24/new-proposed-values-for-pci-codes-2026-medicare-pfs-proposed-rule
- American College of Cardiology. (2026, March 10). RENOVATE-COMPLEX-PCI: Clinical benefit with intravascular imaging-guided complex percutaneous coronary intervention.
- Asahi Intecc Co., Ltd. (2026, April 9). Asahi Intecc enters exclusive distribution agreement with NEXTBIOMEDICAL for Nexsphere-F transcatheter arterial micro-embolization (TAME) systems. https://ir.asahi-intecc.co.jp/en/ir/pressrelease/pressrelease-1110378940809940271/main/0/teaserItems1/0/linkList/0/link/20260409300E.pdf?t=20260409134937
- Asahi Intecc Co., Ltd. (2026, May 15). Financial results of the 3rd quarter for fiscal year ending June 2026: PCI guidewire and non-cardiovascular revenue expansion.
- BIOTRONIK SE & Co. KG. (2025, February 27). BIOTRONIK driving the future of active device business: Company to divest its Vascular Intervention business division to Teleflex Inc. https://www.biotronik.com/en-int/BIOTRONIK-Driving-the-Future-of-Active-Device-Business
- Boston Scientific Corporation. (2026, May 19). FRACTURE IDE trial of the Boston Scientific SEISMIQ 4CE Coronary Intravascular Lithotripsy Catheter meets primary safety and effectiveness endpoints.
- Boston Scientific Corporation. (2026, July 29). Boston Scientific announces results for second quarter 2026: Net sales of USD 5.442 billion and 7.8% organic Cardiovascular growth. https://news.bostonscientific.com/2026-07-29-Boston-Scientific-announces-results-for-second-quarter-2026
- Frontiers in Cardiovascular Medicine. (2026, September 1). Minimally invasive hybrid retrieval of a fractured Sion guidewire during complex LAD percutaneous coronary intervention (PMC13574576). https://pmc.ncbi.nlm.nih.gov/articles/PMC13574576/
- Integer Holdings Corporation. (2026, February 19). Integer Holdings Corporation reports results for fourth quarter and full year 2025: Cardio & Vascular sales up 17% to USD 1.107 billion. https://investor.integer.net/news-events/press-releases/news-details/2026/Integer-Holdings-Corporation-Reports-Results-for-Fourth-Quarter-and-Full-Year-2025/default.aspx
- JACC: Advances. (2026, January 20). Percutaneous coronary interventions in patients with prior transcatheter aortic valve replacement: Coronary access and guidewire engagement outcomes (Kharsa, C., Goel, S. S., et al., PMC12856456). https://pmc.ncbi.nlm.nih.gov/articles/PMC12856456/
- Journal of the American Heart Association. (2026, March 15). Procedural success and long-term outcomes of chronic total occlusion percutaneous coronary intervention in small vessels (PMC13279637). https://pmc.ncbi.nlm.nih.gov/articles/PMC13279637/
- MDPI Actuators. (2026, May 30). Design and control-oriented simulation of a superelastic nitinol-based steerable intravascular guidewire and thrombectomy catheter system, Actuators, 11(3), 54. https://www.mdpi.com/2411-5134/11/3/54
- Merit Medical Systems, Inc. (2026, October 29). SOLO PACE FUSION System: Temporary left-ventricular pacing and transcatheter heart valve delivery guide wire package. https://www.merit.com/product/solo-pace-fusion-system/
- Pharmaceuticals and Medical Devices Agency Japan. (2026, March 15). PMDA Updates 2026: Toward simultaneous development and approval of cardiovascular medical devices in Japan and the US under Harmonization By Doing (HBD). https://www.pmda.go.jp/files/000278867.pdf
- Saudi Food and Drug Authority. (2025, July 28). SFDA strengthens global standing through regulation of 295 medical device clinical studies across Saudi Arabia. https://www.sfda.gov.sa/en/news/18702
- Stryker Corporation. (2025, July 29). Inari Medical, now part of Stryker, launches the all-new InThrill Over-the-Wire Thrombectomy System for small-vessel vascular interventions. https://www.stryker.com/us/en/about/news/2025/inari-medical-stryker-launches-all-new-inthrill-thrombectomy-system.html
- Swissmedic Swiss Agency for Therapeutic Products. (2026, July 1). swissdamed: As of 1 July 2026, mandatory registration applies to medical devices and procedure packs placed on the market in Switzerland. https://www.swissmedic.ch/swissmedic/en/home/news/mitteilungen/swissdamed-registrierungspflicht.html
- Teleflex Incorporated. (2025, July 1). Teleflex completes acquisition of BIOTRONIK's Vascular Intervention business. https://investors.teleflex.com/news/news-details/2025/Teleflex-Completes-Acquisition-of-BIOTRONIKs-Vascular-Intervention-Business/default.aspx
- Teleflex Incorporated. (2026, November 5). Teleflex reports third quarter 2026 financial results (USD 567.8M revenue), USD 1.5B OEM divestiture completion, and Vascular Intervention integration. https://investors.teleflex.com/news/news-details/2026/Teleflex-Reports-Third-Quarter-Financial-Results-and-Full-Year-2026-Outlook/default.aspx
- Terumo Interventional Systems. (2026, June 29). Terumo Interventional Systems announces first procedure using its OPUSWAVE Dual Sensor IVUS/OFDI Imaging System in the United States. https://www.terumomedical.com/news-and-events/news/opuswave-press-release.html
- Therapeutic Goods Administration Australia. (2026, August 5). Unique Device Identification (UDI) mandatory compliance and Consent to Supply process for Class IIb and Class III medical devices from 1 July 2026. https://www.tga.gov.au/products/medical-devices/labelling-and-advertising/unique-device-identification-udi-hub/udi-and-consent-supply/unique-device-identification-consent-supply-process
- U.S. Food and Drug Administration. (2025, August 26). 510(k) premarket notification summary K244061: Imperative Care X-Wire 0.014, 0.018, and 0.024 inch hydrophilic-PTFE guidewire (21 CFR 870.1330). https://www.accessdata.fda.gov/cdrh_docs/pdf24/K244061.pdf
- U.S. Food and Drug Administration. (2026, September 18). 510(k) premarket notification summary K253146: Rapid Medical Hyperdrive 35 steerable intravascular guidewire (21 CFR 870.1330). https://www.accessdata.fda.gov/cdrh_docs/pdf25/K253146.pdf
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Core Metallurgy, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Core Metallurgy, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Core Metallurgy, 2026 to 2036
- Nitinol Superelastic Kink-Resistant Core
- Stainless Steel High-Support Core
- Hybrid Composite Platinum Tip Wire
- Cobalt-Chromium Alloy Core
- Y-o-Y Growth Trend Analysis By Core Metallurgy, 2021 to 2025
- Absolute $ Opportunity Analysis By Core Metallurgy, 2026 to 2036
- Global Market Analysis and Forecast, By Wire Caliper Diameter, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wire Caliper Diameter, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wire Caliper Diameter, 2026 to 2036
- 0.014 Inch Coronary Intervention Standard
- 0.018 Inch Peripheral Intervention
- 0.035 Inch Diagnostic and Access Wire
- 0.010 to 0.012 Inch Neurovascular Micro-Wires
- Y-o-Y Growth Trend Analysis By Wire Caliper Diameter, 2021 to 2025
- Absolute $ Opportunity Analysis By Wire Caliper Diameter, 2026 to 2036
- Global Market Analysis and Forecast, By Coating Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coating Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coating Technology, 2026 to 2036
- Hydrophilic Lubricious Coating
- Hydrophobic PTFE Silicone Coating
- Uncoated Radiopaque Distal Coils
- Hybrid Distal-Hydrophilic Coating
- Heparin Anti-Thrombogenic Coating
- Y-o-Y Growth Trend Analysis By Coating Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Coating Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Application, 2026 to 2036
- Interventional Cardiology PTCA
- Interventional Radiology and Peripheral Vascular
- Endovascular Neuro-Intervention
- Urological and GI Endoscopy
- Y-o-Y Growth Trend Analysis By Clinical Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Application, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Hospital Catheterization Laboratories
- Ambulatory Surgical Centers (ASCs)
- Specialty Cardiac and Vascular Institutes
- Academic Medical Centers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Core Metallurgy
- By Wire Caliper Diameter
- By Coating Technology
- By Clinical Application
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Terumo Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Asahi Intecc Co., Ltd.
- Boston Scientific Corporation
- Abbott Laboratories
- Medtronic plc
- Teleflex Incorporated
- Stryker Corporation
- Cordis Corporation
- Merit Medical Systems, Inc.
- Integer Holdings Corporation
- Terumo Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Core Metallurgy, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Wire Caliper Diameter, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Coating Technology, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Core Metallurgy, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Wire Caliper Diameter, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Coating Technology, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Core Metallurgy, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Wire Caliper Diameter, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Coating Technology, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 19: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: East Asia Market Value (USD Billion) Forecast by Core Metallurgy, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Wire Caliper Diameter, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Coating Technology, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Core Metallurgy, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Wire Caliper Diameter, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Coating Technology, 2021 to 2036
- Table 29: South Asia and Pacific Market Value (USD Billion) Forecast by Clinical Application, 2021 to 2036
- Table 30: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Core Metallurgy, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Core Metallurgy, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Core Metallurgy
- Figure 6: Global Market Value Share and BPS Analysis by Wire Caliper Diameter, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Wire Caliper Diameter, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Wire Caliper Diameter
- Figure 9: Global Market Value Share and BPS Analysis by Coating Technology, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Coating Technology, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Coating Technology
- Figure 12: Global Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Clinical Application
- Figure 15: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End User
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Core Metallurgy, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Core Metallurgy, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Core Metallurgy
- Figure 29: North America Market Value Share and BPS Analysis by Wire Caliper Diameter, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Wire Caliper Diameter, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Wire Caliper Diameter
- Figure 32: North America Market Value Share and BPS Analysis by Coating Technology, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Coating Technology, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Coating Technology
- Figure 35: North America Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Clinical Application
- Figure 38: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End User
- Figure 41: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 42: Western Europe Market Value Share and BPS Analysis by Core Metallurgy, 2026 and 2036
- Figure 43: Western Europe Market Y-o-Y Growth Comparison by Core Metallurgy, 2026-2036
- Figure 44: Western Europe Market Attractiveness Analysis by Core Metallurgy
- Figure 45: Western Europe Market Value Share and BPS Analysis by Wire Caliper Diameter, 2026 and 2036
- Figure 46: Western Europe Market Y-o-Y Growth Comparison by Wire Caliper Diameter, 2026-2036
- Figure 47: Western Europe Market Attractiveness Analysis by Wire Caliper Diameter
- Figure 48: Western Europe Market Value Share and BPS Analysis by Coating Technology, 2026 and 2036
- Figure 49: Western Europe Market Y-o-Y Growth Comparison by Coating Technology, 2026-2036
- Figure 50: Western Europe Market Attractiveness Analysis by Coating Technology
- Figure 51: Western Europe Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 52: Western Europe Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 53: Western Europe Market Attractiveness Analysis by Clinical Application
- Figure 54: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 55: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 56: Western Europe Market Attractiveness Analysis by End User
- Figure 57: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 58: East Asia Market Value Share and BPS Analysis by Core Metallurgy, 2026 and 2036
- Figure 59: East Asia Market Y-o-Y Growth Comparison by Core Metallurgy, 2026-2036
- Figure 60: East Asia Market Attractiveness Analysis by Core Metallurgy
- Figure 61: East Asia Market Value Share and BPS Analysis by Wire Caliper Diameter, 2026 and 2036
- Figure 62: East Asia Market Y-o-Y Growth Comparison by Wire Caliper Diameter, 2026-2036
- Figure 63: East Asia Market Attractiveness Analysis by Wire Caliper Diameter
- Figure 64: East Asia Market Value Share and BPS Analysis by Coating Technology, 2026 and 2036
- Figure 65: East Asia Market Y-o-Y Growth Comparison by Coating Technology, 2026-2036
- Figure 66: East Asia Market Attractiveness Analysis by Coating Technology
- Figure 67: East Asia Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 68: East Asia Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 69: East Asia Market Attractiveness Analysis by Clinical Application
- Figure 70: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 71: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 72: East Asia Market Attractiveness Analysis by End User
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 74: South Asia and Pacific Market Value Share and BPS Analysis by Core Metallurgy, 2026 and 2036
- Figure 75: South Asia and Pacific Market Y-o-Y Growth Comparison by Core Metallurgy, 2026-2036
- Figure 76: South Asia and Pacific Market Attractiveness Analysis by Core Metallurgy
- Figure 77: South Asia and Pacific Market Value Share and BPS Analysis by Wire Caliper Diameter, 2026 and 2036
- Figure 78: South Asia and Pacific Market Y-o-Y Growth Comparison by Wire Caliper Diameter, 2026-2036
- Figure 79: South Asia and Pacific Market Attractiveness Analysis by Wire Caliper Diameter
- Figure 80: South Asia and Pacific Market Value Share and BPS Analysis by Coating Technology, 2026 and 2036
- Figure 81: South Asia and Pacific Market Y-o-Y Growth Comparison by Coating Technology, 2026-2036
- Figure 82: South Asia and Pacific Market Attractiveness Analysis by Coating Technology
- Figure 83: South Asia and Pacific Market Value Share and BPS Analysis by Clinical Application, 2026 and 2036
- Figure 84: South Asia and Pacific Market Y-o-Y Growth Comparison by Clinical Application, 2026-2036
- Figure 85: South Asia and Pacific Market Attractiveness Analysis by Clinical Application
- Figure 86: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 87: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 88: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 89: Global Market - Tier Structure Analysis
- Figure 90: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the guidewires market in 2026?
Future Market Insights estimates the global guidewires market at USD 4.57 billion in 2026, up from USD 4.35 billion in 2025, across single-use sterile interventional and diagnostic guidewires.
How fast is the guidewires market expected to grow through 2036?
FMI projects the global guidewires market to grow at a 5.0% CAGR from 2026 to 2036, reaching USD 7.44 billion by 2036 and adding USD 2.87 billion in incremental revenue.
Which core metallurgy segment leads the guidewires market?
Nitinol superelastic kink-resistant core wires lead with 40.5% of global core metallurgy revenue in 2026, and their share is projected to rise to 46.8% by 2036.
Which wire caliper diameter leads the guidewires market?
The 0.014-inch coronary intervention standard format captures 44.3% of global caliper revenue in 2026 and is forecast to reach 47.2% by 2036 due to universal rapid-exchange coronary catheter compatibility.
Which coating technology leads the guidewires market?
Hydrophilic lubricious coating systems account for 48.0% of global guidewires revenue in 2026 and are projected to reach 54.0% by 2036, supported by low-friction transradial access and tight stenosis crossing.
Which country is the largest guidewires market?
The United States is the largest national guidewires market globally, capturing 38.0% of global revenue in 2026 (USD 1,736.6 million) and projected to reach USD 2,855.8 million by 2036.
Which countries are expected to grow fastest in the guidewires market?
South Korea is projected to grow fastest at a 6.0% CAGR from 2026 to 2036, followed by Saudi Arabia at 5.9%, Australia at 5.3%, and the United States at 5.1%.
What drives demand for interventional and diagnostic guidewires?
Global guidewire demand is driven by multi-wire complex coronary CTO and bifurcation procedures, intravascular lithotripsy and dual-sensor imaging adoption, and steerable nitinol micro-wires cleared under FDA 21 CFR 870.1330.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
