
- Market Size (2026)
- USD 1.9 Bn
- Forecast (2036)
- USD 3.4 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Inulin Market in 2026?
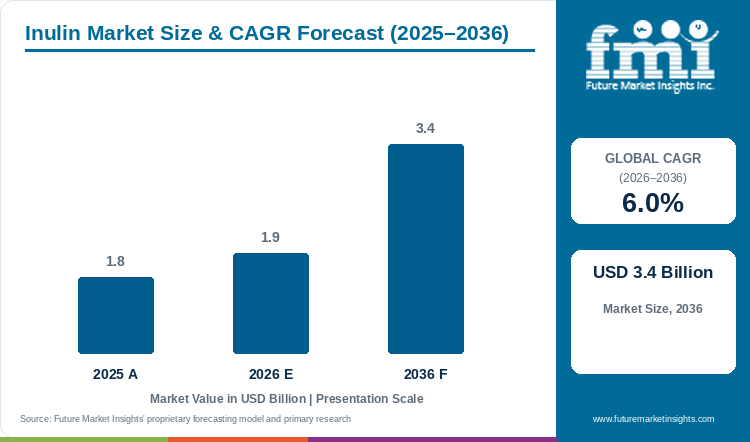
Assessed at USD 1.8 billion in 2025 and progressing to USD 1.9 billion in 2026, the inulin market valuation is on course to reach USD 3.4 billion by 2036, supported by a forecast-period CAGR of 6.0%.
Dairy and bakery manufacturers are reformulating everyday consumer products to cut added sugars and saturated fats while raising dietary fiber counts on nutrition panels. Formulation trend analysis by FMI indicates that the global inulin market size was valued at USD 1.8 billion in 2025 and is estimated to reach USD 1.9 billion in 2026. Overall industry valuation is projected to reach USD 3.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.0% during the forecast period. Chicory Root Extraction is anticipated to capture 76.5% of botanical source demand in 2026, given that European and Chilean root campaigns supply reliable beta-2,1-fructan purity for large-scale dairy and cereal plants. This dual sugar-and-fat replacement function separates the category from the agave inulin sector at 4.6% CAGR, since chicory grades form smooth cream-like micro-crystals in low-fat yogurts while branched agave fructans serve mainly in cold beverages.
Commercial demand for soluble prebiotic fiber is supported by corporate reformulation programs, as Tate & Lyle documented in August 2026 that its fiber fortification portfolio delivered 18.3 billion daily fiber-gap servings globally by March 2026 [1]. Suppliers are also expanding gut-microbiome applications, as seen when Soyprasert et al. reported in August 2026 that 94.1%-purity short-chain inulin oligomers selectively enrich Bifidobacterium and butyrate-producing bacteria in metabolic formulations [24]. Processors lock in annual supply contracts when inulin grades maintain digestive tolerance above five grams per serving.
Key Market Trends & Insights
- By botanical source: Chicory Root Extraction is projected to hold a 76.5% share in 2026 since industrial root diffusion provides high fructan yields and neutral sensory profiles.
- By polymerization degree: Standard Native Inulin DP 10 to 12 is estimated to represent 44.7% in 2026 owing to balanced sweetness and fat-mimicking viscosity in dairy matrices.
- By form: Spray-Dried Powder is anticipated to account for 77.0% in 2026 given that ambient dry powders integrate directly into dry bakery premixes and infant formula blenders.
- By commercial application: Dairy, Yogurts and Frozen Desserts are expected to secure 40.1% in 2026 through simultaneous butterfat replacement and probiotic culture stimulation.
- By certification claim: Conventional Food Grade is forecast to command 81.0% in 2026 on account of cost-effective bulk supply across mainstream supermarket dairy and cereal brands.
Regional Highlights
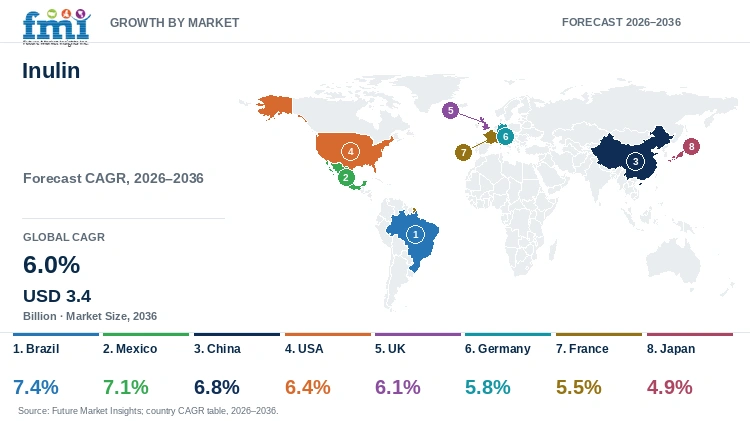
- Top national expansion: Brazil leads national growth projections at a 7.4% CAGR through 2036 under mandatory front-of-pack added-sugar warning label reformulations.
- Broader country progression: Mexico tracks at a 7.1% CAGR ahead of China at 6.8% and the USA at 6.4%, while Japan advances at a 4.9% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Inulin Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.8 billion |
| Estimated Market Size in 2026 | USD 1.9 billion |
| Projected Market Size by 2036 | USD 3.4 billion |
| CAGR, 2026 to 2036 | 6.0% |
| Added Revenue, 2026 to 2036 | USD 1.5 billion |
Commercial yogurt and cereal plants face mounting retail pressure to strip 25% to 40% of sucrose and milkfat from core recipes without creating thin mouthfeel or chalky aftertastes. When food technologists remove bulk sugar or cream alone, water activity rises and product texture collapses during chilled distribution. In August 2026, Ostrun et al. reported in Foods that commercial chicory root cultivars yield up to 45 tons per hectare with 40% to 70% dry-weight inulin that forms 100-nanometer crystallite particle gels capable of replacing fat in dairy and bakery systems [2]. Consequently, R&D directors combine native chicory inulin with prebiotic fiber blends to restore creamy body and qualify for front-of-pack fiber claims.
Chicory Root Processing and Active-Dosage Sizing
Table 2: Root Processing and Active-Dosage Sizing for the Inulin Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.8 | 1.9 | 3.4 |
| Processed chicory & agave root volume (million metric tons) | 2.5 to 2.8 | 2.7 to 3.0 | 4.6 to 5.1 |
| Commercial refined inulin shipment volume (thousand metric tons) | 395.0 to 425.0 | 418.0 to 450.0 | 720.0 to 775.0 |
| Average wholesale realization per metric ton (USD) | 4,350 to 4,650 | 4,400 to 4,720 | 4,550 to 4,900 |
Industrial extraction of beta-2,1-fructans requires hot-water diffusion and ion-exchange demineralization followed by spray drying to remove bitter sesquiterpene lactones from raw roots. In April 2026, European Union sugar annual filings from the USDA documented that beet and root crop processors adjusted contracted acreage for marketing year 2026/27 as industrial buyers shifted toward higher-margin specialty root derivatives [3]. This agricultural allocation directly governs raw root availability for chicory products extractors across Northwestern Europe.
Global Fiber Fortification & Industrial Plant Sizing
Table 3: Global Fiber Fortification and Line Spending Indicators for the Inulin Market (USD and volume metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Fortified dairy, bakery & beverage output (million metric tons) | 14.5 to 16.2 | 15.4 to 17.3 | 27.5 to 30.8 |
| Daily 15g fiber-gap equivalent servings delivered (billion) | 16.8 | 18.3 | 35.0 |
| Annual inulin procurement per major dairy/bakery plant (USD thousand) | 310.0 to 365.0 | 330.0 to 390.0 | 580.0 to 675.0 |
| High-purity long-chain & infant-grade share (%) | 28.0% to 31.0% | 29.5% to 33.0% | 38.0% to 42.5% |
Table 4: Industrial Extraction & Channel Spending Indicators for the Inulin Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.9 billion | 2026 global revenue baseline |
| Chicory root dry-matter inulin content | 40.0% to 70.0% | MDPI Foods August 2026 industrial cultivar benchmark |
| Verified prebiotic bifidogenic intake threshold | 3.0 to 5.0 g/day | ISAPP and Cosucra Fibruline clinical dossier baseline |
| Dairy, Yogurts & Frozen Desserts allocation, 2026 | 40.1% share | Primary commercial fat and sugar replacement application |
European specialty carbohydrate refiners operate continuous counter-current root diffusers and membrane fractionation columns to separate native inulin from short-chain oligofructose. As per Südzucker AG in its May 2026 annual report for fiscal year 2025/26, the Special Products division encompassing BENEO maintained resilient operating revenues supported by consumer demand for prebiotic chicory root fibers [4]. Multinational food manufacturers now co-contract native inulin and dietary fibres to secure multi-year volume guarantees.
Analyst Perspective
"Food and beverage formulators no longer purchase inulin merely to add a gram of fiber on the back label; they buy calibrated polymerization degrees that replace butterfat in yogurt or sucrose in cereal bars without triggering digestive discomfort. Extraction specialists that pair membrane-fractionated chicory grades with human milk oligosaccharides and low-FODMAP tolerance dossiers will capture multi-year global supply agreements."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Inulin Market segmented?
The inulin market is segmented by botanical source, polymerization degree, form, commercial application, and certification claim. In 2026, Chicory Root Extraction is projected at 76.5%, Standard Native Inulin DP 10 to 12 at 44.7%, Spray-Dried Powder at 77.0%, Dairy, Yogurts and Frozen Desserts at 40.1%, and Conventional Food Grade at 81.0%.
By botanical source: Chicory Root Extraction; Blue Agave Fructans; Jerusalem Artichoke; Enzymatic and Other Botanical Sources.
By polymerization degree: Standard Native Inulin DP 10 to 12; Short-Chain Prebiotic Oligofructose DP 2 to 9; High-Performance Long-Chain Inulin DP Above 23; Oligofructose-Enriched Inulin Blends.
By form: Spray-Dried Powder; Concentrated Liquid Syrup; Agglomerated Instant Granules; Micro-Milled Specialty Grades.
By commercial application: Dairy, Yogurts and Frozen Desserts; High-Fiber Bakery, Breads and Cereals; Dietary Supplements and Prebiotics; Infant and Early-Life Nutrition; Functional Beverages and Confectionery.
By certification claim: Conventional Food Grade; Certified Organic Inulin; Identity-Preserved Non-GMO; Clean-Label Plant-Based.
Why does Chicory Root Extraction lead the botanical source category?
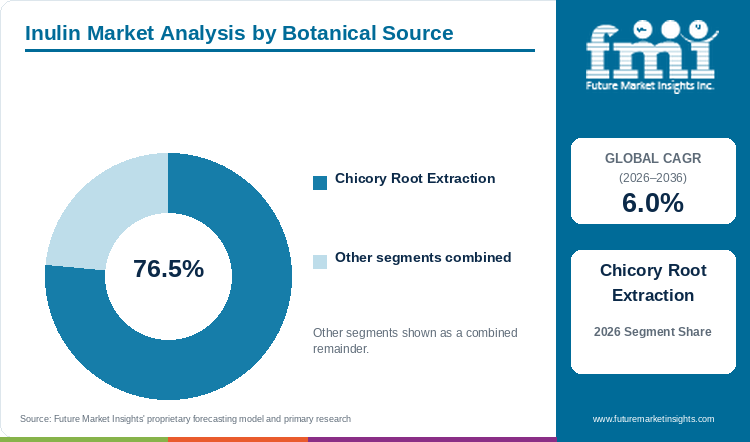
Chicory Root Extraction holds an estimated 76.5% of botanical source demand in 2026, anchored by high linear fructan purity and dual-hemisphere root refining.
Table 5: Botanical Source Share for the Inulin Market (percentage share), 2026
| Botanical Source | Share (2026) |
|---|---|
| Chicory Root Extraction | 76.5% |
| Other Segments Combined | 23.5%* |
| Total | 100.0% |
*Note: Remaining botanical source categories account for the balance of 2026 global inulin demand.
Table 6: Botanical Source Leadership and Market Growth for the Inulin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Chicory Root Extraction |
Chicory Root Extraction dominates commercial procurement because Cichorium intybus taproots yield linear beta-2,1-linked fructan chains free from the branched molecular structures that limit gelling in agave extracts. Agronomic breeding in Belgium and Chile allows processors of chicory root inulin to achieve dry-matter fructan concentrations above 65% during autumn harvest campaigns. High extraction purity lowers refining cost per metric ton, although wet autumn weather in Northwestern Europe can delay root lifting and tighten spot supply.
- Within the botanical source segment, Chicory Root Extraction is projected to account for a leading 76.5% share in 2026, driven by superior gelling functionality and established regulatory approvals.
- A 12-week randomized clinical trial by Omary et al. published in Cell Reports Medicine in July 2025 confirmed that daily intake of intrinsic chicory root fiber containing 70% inulin elevated Bifidobacterium abundance by 4.1-fold and fecal acetate by 56% [5].
What sustains Standard Native Inulin DP 10 to 12 leadership in polymerization degree?
Standard Native Inulin DP 10 to 12 represents 44.7% of the polymerization degree category in 2026, supported by balanced solubility and creamy mouthfeel.
Standard Native Inulin DP 10 to 12 bridges the functional gap between highly sweet short-chain oligofructose and zero-sweetness long-chain fractions. Food technologists formulating reduced-sugar yogurts and cereal coatings with fructo-oligosaccharides favor DP 10 to 12 grades since their 10% residual sweetness rounds out high-intensity sweeteners while longer chains build creamy mouthfeel. Research by Canazza et al. published in Gels in October 2025 demonstrated that chicory roots yield 5 to 11 tons per hectare of DP 10 to 14 native inulin whose chain-length distribution directly governs viscoelastic gel network formation in food matrices [6].
- In 2026, Standard Native Inulin DP 10 to 12 is anticipated to capture 44.7% of polymerization degree demand, reflecting its dual utility in sugar reduction and texture stabilization.
- Long-chain fractions above DP 23 are forecast to gain incremental share in premium fat-free spreads, yet higher membrane fractionation costs keep native DP 10 to 12 as the primary volume grade.
Why does Spray-Dried Powder lead the form segment?
Spray-Dried Powder accounts for 77.0% of form volume in 2026, driven by ambient stability and dry-premix dosing compatibility.
Spray-Dried Powder formats allow dairy and infant nutrition plants to meter prebiotic fiber through existing dry-ingredient loss-in-weight feeders without installing heated syrup tanks. Ambient shelf stability of 24 to 36 months also protects international buyers of functional dairy products against microbial spoilage during ocean freight to Asia and Latin America. Hygroscopic caking during humid warehouse storage remains the primary operational hurdle, prompting suppliers to offer agglomerated low-dust grades.
- By form, demand for Spray-Dried Powder is estimated to reach 77.0% of total category share in 2026 as dry blending lines dominate bakery and powdered formula manufacturing.
- BENEO released technical sports and gut nutrition guidelines in August 2026 showing how dry chicory root fiber powders disperse cleanly into protein recovery mixes and energy bars [7].
How do Dairy, Yogurts and Frozen Desserts lead commercial applications?
Dairy, Yogurts and Frozen Desserts secure 40.1% of commercial application demand in 2026, supported by butterfat replacement and probiotic synergy.
Dairy, Yogurts and Frozen Desserts represent the largest commercial volume outlet since sheared chicory inulin crystals form sub-micron particle networks that mimic milkfat globules on the palate. Yogurt processors replacing 1% to 3% butterfat also benefit from selective stimulation of Lactobacillus and Bifidobacterium starter cultures during fermentation. Formulators must still manage low-pH hydrolysis during pasteurization below pH 4.0 to prevent unintended fructose release. In February 2026, Kerry Group reported EUR 6.76 billion in 2025 group revenue and 3.5% volume expansion across food and dairy taste and texture systems [8].
- Strong repeat ordering across cultured dairy and ice cream plants places Dairy, Yogurts and Frozen Desserts on course to hold an estimated 40.1% share of commercial application demand in 2026.
- Functional carbonated soft drinks and prebiotic sodas represent the fastest-growing secondary application, though acid-hydrolysis stability requirements keep chilled dairy in the top volume position.
What gives Conventional Food Grade the leading position in certification claim?
Conventional Food Grade commands 81.0% of certification claim share in 2026, anchored by cost-effective bulk supply for mainstream food brands.
Conventional Food Grade inulin anchors bulk procurement given that mainstream yogurt and breakfast cereal brands operate on tight unit-margin ceilings that cannot absorb the 35% to 50% price premium of certified organic roots. Agronomic weed control in organic chicory fields requires intensive mechanical hoeing, which restricts certified organic acreage in Belgium and the Netherlands. Conventional chicory root remains naturally non-GMO and plant-derived, allowing brands to display clean-label dietary fiber declarations at standard commodity pricing.
- Conventional Food Grade is predicted to secure 81.0% of certification claim demand in 2026, supported by broad availability and competitive cost-in-use across national grocery brands.
- Roquette announced in February 2026 that its plant-based soluble fiber range earned NutraStrong Prebiotic Verified certification, reflecting how conventional plant fibers compete on clinical verification [9].
What are the drivers, restraints, and opportunities in the Inulin Market?
In the inulin market, front-of-pack sugar warning laws and dairy fat-reduction targets are projected to drive adoption whereas dose-dependent gastrointestinal flatulence restrains high-level beverage dosing and HMO-chicory synbiotic blends create new pediatric nutrition avenues.
- Driver: Mandatory front-of-pack sugar warning labels and retail calorie-reduction targets compel dairy and snack processors to replace refined sugar and milkfat using prebiotic chicory inulin.
- Restraint: Rapid colonic fermentation of short-chain fructans above 8 to 10 grams per serving can trigger gastrointestinal bloating and flatulence that limits single-serving beverage dosages.
- Opportunity: Co-formulating chicory root inulin with human milk oligosaccharides and slow-fermenting fibers creates high-margin synbiotic solutions for toddler milk and metabolic nutrition.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
National front-of-pack nutrition labeling laws and retailer health-score commitments are turning soluble fiber fortification from a niche wellness claim into a baseline shelf-access requirement. When European Nutri-Score algorithms and Latin American black octagonal warning seals penalize added sugars, food manufacturers turn to prebiotic ingredients to replace sucrose bulk while earning positive fiber points. Colonic simulation research by Ghyselinck et al. published in Frontiers in Nutrition in February 2026 demonstrated that fiber blends containing up to 83.3% chicory inulin increased total short-chain fatty acid output by up to 2.2-fold across human microbiota donors [10]. This verified physiological benefit drives multi-ton procurement across dairy and cereal chains.
Risk Assessment of the Inulin Market: Operational and Formulation Friction
Gastrointestinal osmotic sensitivity and strict regulatory scrutiny over unauthorized disease-prevention claims restrain aggressive high-dose inulin inclusion across ready-to-drink beverages. Rapid microbial fermentation of low-DP fructans in the proximal colon generates gas when consumers ingest multiple fortified snacks in a single day, leading formulators of sugar reduction mouthfeel recovery additives to cap single-serving doses. In June 2026, the U.S. Food and Drug Administration issued a compliance warning letter citing unapproved therapeutic disease claims made for fructooligosaccharide and inulin products [11]. Beverage and supplement brands must therefore restrict packaging language to authorized structure-function fiber claims.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient producers are capturing premium margins by blending chicory root inulin with human milk oligosaccharides and slow-fermenting dextrins to mimic natural breastmilk and extend fermentation across the entire colon. The combination of plant-derived beta-2,1-fructans with 2'-fucosyllactose opens new revenue streams in infant formula ingredients and stage-three growing-up milks across Asia and Europe. In June 2025, BENEO published research demonstrating that pairing chicory root prebiotics with the human milk oligosaccharide 2'-FL produces complementary gut microbiota modulation in toddler nutrition [12]. Suppliers offering clinically tested synbiotic premixes secure long-term pediatric nutrition contracts.
Inulin Market by Country (2026 to 2036)
FMI country modeling indicates that Brazil leads national inulin expansion at a 7.4% CAGR through 2036, while Japan advances at a 4.9% CAGR. Commercial adoption across Latin American reformulated dairy lines and Asian infant formula plants depends on national sugar-labeling rules and local root or agave supply.
Table 7: Country CAGR and Primary Growth Levers for the Inulin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 7.4% | ANVISA front-of-pack added-sugar warning label reformulation across yogurts and biscuits |
| Mexico | 7.1% | Domestic Jalisco blue agave fructan extraction and NOM-051 warning-seal compliance |
| China | 6.8% | National GB infant formula prebiotic standards and probiotic dairy drink expansion |
| USA | 6.4% | FDA Nutrition Facts dietary fiber recognition and prebiotic functional soda growth |
| UK | 6.1% | Updated Nutrient Profiling Model rewarding fiber density in cereals and yogurts |
| Germany | 5.8% | Domestic chicory refining infrastructure and retail food private-label reformulation |
| France | 5.5% | Hauts-de-France chicory root cooperatives and Nutri-Score bakery and dairy upgrades |
| Japan | 4.9% | FOSHU and Foods with Function Claims registrations across domestic food processing |
Source: Future Market Insights analysis
Brazil Inulin Market Outlook (2026 to 2036)
Demand for inulin in Brazil is projected to expand at a leading 7.4% CAGR between 2026 and 2036 as domestic dairy and biscuit processors reformulate recipes to avoid ANVISA front-of-pack high-added-sugar warning symbols. What distinguishes Brazil from mature European markets is the rapid incorporation of imported Chilean chicory inulin into mass-market drinkable yogurts and filled cookies. Official Sao Paulo agricultural attaché reporting in March 2026 confirmed that Brazil's food processing industry continues expanding output across functional dairy and bakery categories [13]. High import logistics costs from European ports still challenge smaller regional bakeries.
Key takeaway: In Brazil, mandatory front-of-pack sugar warning labels and expanding drinkable yogurt production are projected to drive leading South American demand for chicory inulin.
Mexico Inulin Market Outlook (2026 to 2036)
Mexico's food and beverage sector is anticipated to achieve a 7.1% CAGR in inulin sales from 2026 to 2036, anchored by domestic Blue Agave fructan extraction in Jalisco and strict NOM-051 octagonal warning-seal reformulations. Compared with European markets that rely exclusively on linear chicory root inulin, Mexican beverage and confectionery plants blend cold-soluble agave inulin with imported chicory powders to cut sugar calories. Mexico City GAIN reporting in April 2026 noted that domestic food processors are actively reformulating dairy drinks and baked goods to meet updated nutritional labeling thresholds [14]. Raw agave pinas price swings tied to tequila distillation cycles remain the primary local supply risk.
Key takeaway: In Mexico, domestic agave fructan extraction and NOM-051 sugar-warning reformulations are expected to sustain rapid adoption across beverages and bakery products.
China Inulin Market Outlook (2026 to 2036)
In China, commercial inulin consumption is forecast to advance at a 6.8% CAGR over the 2026 to 2036 period as infant formula manufacturers and probiotic dairy drink brands upgrade prebiotic fiber dosages. National GB infant and toddler formula standards encourage precise ratios of chicory oligofructose and native inulin to support infant digestive comfort. Shenyang agricultural trade filings in April 2026 documented that Chinese food processors are prioritizing specialized dairy nutrition and reduced-sugar beverage ingredients across urban retail channels [15]. Domestic chicory cultivation in Qinghai and Hebei is expanding, though high-purity infant-grade inulin still relies heavily on European imports.
Key takeaway: In China, national infant formula nutrition standards and functional probiotic dairy beverages are forecast to accelerate procurement of high-purity chicory inulin.
USA Inulin Market Outlook (2026 to 2036)
Commercial inulin demand in the USA is anticipated to progress at a 6.4% CAGR from 2026 through 2036, supported by FDA recognition of chicory root fructans as dietary fiber on Nutrition Facts panels and the rapid expansion of prebiotic functional sodas. While European buyers use inulin primarily in traditional dairy and bread, American beverage and supplement brands use soluble fructans to anchor gut-health marketing claims. Supplier commitment to North American prebiotic supply was reinforced in July 2026 when ADM and Matsutani marked 20 years of joint prebiotic dietary fiber innovation for food and beverage formulators [16]. Formulators must carefully balance chicory inulin with slower-fermenting fibers to maintain gastrointestinal comfort in 355-milliliter beverage cans.
Key takeaway: In the USA, FDA dietary fiber label recognition and retail prebiotic soda expansion are anticipated to drive sustained contract volumes for soluble inulin.
UK Inulin Market Outlook (2026 to 2036)
In the UK, market expansion for inulin is estimated to track at a 6.1% CAGR through 2036 as supermarket private-label suppliers reformulate breakfast cereals and yogurts under updated Nutrient Profiling Model restrictions. What sets the UK apart from continental Europe is the explicit regulatory credit given to dietary fiber content when calculating whether a food product is restricted from checkout and broadcast promotions. In March 2026, the UK Department of Health and Social Care announced consultations on applying the modernized Nutrient Profiling Model to bring sweetened yogurts and cereals into scope while rewarding higher fiber content [17]. Post-Brexit customs documentation and cold-weather chicory root harvest variability across the English Channel remain key procurement considerations.
Key takeaway: In the UK, Nutrient Profiling Model updates that reward fiber content against free sugars are estimated to drive widespread cereal and yogurt reformulation with chicory inulin.
Germany Inulin Market Outlook (2026 to 2036)
German inulin demand is slated to expand at a 5.8% CAGR from 2026 to 2036, supported by domestic chicory and sugar-beet refining infrastructure and strong retail penetration of clean-label dairy and high-fiber rye bakery products. Domestic food manufacturers work closely with local application laboratories in Mannheim and Offstein to replace butterfat in quark and chilled desserts. Berlin retail food attaché reporting in September 2026 confirmed that Germany represents Europe's largest consumer-oriented food market as shoppers prioritize health-conscious and private-label products [18]. High industrial energy and farm-contracting costs in Germany nonetheless pressure extractor operating margins.
Key takeaway: In Germany, integrated domestic chicory refining and large-scale private-label dairy reformulation are slated to maintain steady demand for native and long-chain inulin.
France Inulin Market Outlook (2026 to 2036)
French inulin procurement is expected to grow at a 5.5% CAGR between 2026 and 2036, driven by strict Nutri-Score algorithm revisions that penalize sugar and saturated fat in brioche and dairy desserts. French northern agricultural cooperatives in Hauts-de-France also supply a major share of Europe's raw chicory roots to cross-border Belgian and domestic extraction plants. In October 2026, Brussels Sugar Semi-Annual filings reported that industrial food processors across Western Europe are actively adjusting sweetener and bulking ingredient ratios in response to sugar market shifts [19]. Stringent consumer preference for short ingredient declarations favors natural chicory root fiber labeling over synthetic bulking agents.
Key takeaway: In France, stricter Nutri-Score grading criteria for baked goods and dairy products are likely to sustain reformulation demand for northern-grown chicory root fiber.
Japan Inulin Market Outlook (2026 to 2036)
Japanese demand for inulin is predicted to advance at a 4.9% CAGR from 2026 to 2036 across Foods for Specified Health Uses (FOSHU) and Foods with Function Claims (FFC) targeting postprandial blood glucose control and senior bowel regularity. Compared with Western markets that dose inulin at high levels for bulk sugar replacement, Japanese beverage and medical nutrition producers incorporate precision low-dose prebiotic fructans. Tokyo agricultural attaché reporting in April 2026 noted that Japanese food manufacturers maintained steady investment in health-functional and convenience ingredients despite a 3% real sector contraction in 2025 [20]. Reliance on imported European chicory powder exposes Japanese buyers to yen exchange-rate fluctuations.
Key takeaway: In Japan, Foods with Function Claims registrations for blood-glucose and digestive health are predicted to support consistent procurement of high-purity inulin.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the inulin market?
BENEO GmbH, Cosucra Groupe Warcoing S.A., Sensus B.V., Cargill, Incorporated, ADM, Ingredion Incorporated, Tate & Lyle PLC, Tierra Group International, Kerry Group plc, and dsm-firmenich AG are the notable companies in the inulin market.
Competitive positioning in the global inulin industry divides primary European and South American chicory root extractors from diversified multinational ingredient houses and specialized botanical formulators. BENEO GmbH and Cosucra Groupe Warcoing operate dedicated counter-current chicory root extraction and membrane fractionation refineries, as does Sensus B.V. in the Netherlands. Cargill and ADM integrate chicory and agave fructans into broader sugar-reduction portfolios; meanwhile Ingredion and Tate & Lyle supply prebiotic blends while Tierra Group, Kerry Group, and dsm-firmenich provide agave inulin and synbiotic texture systems.
- Primary Chicory Root Extraction Specialists: BENEO GmbH; Cosucra Groupe Warcoing S.A.; and Sensus B.V. (Royal Cosun) operate large-scale chicory root diffusion and fractionation plants in Belgium, the Netherlands, and Chile.
- Diversified Sweetener and Fiber Ingredient Houses: Cargill, Incorporated; Archer Daniels Midland Company (ADM); Ingredion Incorporated; and Tate & Lyle PLC combine chicory inulin with stevia and resistant dextrins for turnkey sugar reduction.
- Botanical Agave and Synbiotic Application Formulators: Tierra Group International, Ltd.; Kerry Group plc; and dsm-firmenich AG supply blue agave fructans and human milk oligosaccharide dairy blends.
Competitive Benchmarking: Inulin Market
Table 8: Competitive Benchmarking for the Inulin Market (qualitative capability ratings), 2026
| Company | Dedicated Root Extraction Capacity | Sugar and Fat Replacement Support | Clinical Prebiotic Dossier Depth | Geographic Reach |
|---|---|---|---|---|
| BENEO GmbH | High | High | High | Belgium and Chile chicory refineries; global Orafti prebiotic network |
| Cosucra Groupe Warcoing S.A. | High | High | High | Belgium Warcoing chicory plant; global Fibruline and Fibrulose distribution |
| Sensus B.V. (Royal Cosun) | High | High | High | Netherlands Roosendaal chicory refinery; Europe, Americas, and Asia supply |
| Cargill, Incorporated | Medium | High | High | Global Oliggo-Fiber chicory and sweetener co-formulation centers |
| ADM | Medium | High | High | Global dietary fiber and prebiotic application labs across 20+ countries |
| Ingredion Incorporated | Medium | High | High | Global Idea Labs network; North American and APAC prebiotic & stevia systems |
| Tate & Lyle PLC | Medium | High | High | Global soluble fiber and sugar-reduction formulation hubs; 18.3B fiber servings |
| Tierra Group International | High | Medium | Medium | Mexican blue agave inulin extraction and North American organic distribution |
| Kerry Group plc | Low | High | Medium | Global dairy, bakery, and supplement taste and texture application centers |
| dsm-firmenich AG | Low | High | High | Global HMO, probiotic, and sugar-reduction co-development network |
Evaluation basis: Dedicated Root Extraction Capacity measures direct ownership of primary chicory or agave root diffusion and chain-length fractionation plants, while Sugar and Fat Replacement Support rates pilot-scale dairy and bakery reformulation centers. Clinical Prebiotic Dossier Depth assesses published human intervention trials supporting ISAPP prebiotic status, EFSA health claims, and infant formula authorizations.
Key Developments in the Inulin Market
- Ingredion Incorporated spotlighted its expanded clean-label texture and positive-nutrition fiber and sweetener systems at IFT FIRST 2026 on July 6, 2026, helping food and beverage brands reduce added sugar while boosting dietary fiber density [21].
- BENEO GmbH launched a global metabolic health and weight-management reformulation initiative on March 4, 2026, featuring Orafti chicory root prebiotic inulin for GLP-1 companion nutrition and satiety-focused food products [22].
- dsm-firmenich AG published its 2025 Integrated Annual Report in February 2026, detailing expanded Taste, Texture and Health customer co-development across sugar-reduced dairy and gut-health formulations [23].
Key Players in the Inulin Market
Primary Chicory Root Extraction Specialists
- BENEO GmbH (Südzucker Group)
- Cosucra Groupe Warcoing S.A.
- Sensus B.V. (Royal Cosun)
- Tierra Group International, Ltd.
Diversified Sweetener and Fiber Ingredient Houses
- Cargill, Incorporated
- Archer Daniels Midland Company (ADM)
- Ingredion Incorporated
- Tate & Lyle PLC
Synbiotic and Taste-Texture Application Formulators
- Kerry Group plc
- dsm-firmenich AG
Inulin Market - Report Scope
Table 9: Report Scope for the Inulin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Botanical Source; Polymerization Degree; Form; Commercial Application; Certification Claim |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial processor revenue from food-, beverage-, and nutraceutical-grade inulin (beta-2,1-fructans across native DP 10-12, long-chain DP >23, and co-processed oligofructose-enriched inulin) extracted from chicory root, blue agave, and Jerusalem artichoke. Category Scope Note: Excludes standalone synthetic polydextrose, insoluble cereal bran fibers, and unrefined roasted chicory coffee substitutes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, China, USA, UK, Germany, France, Japan, and additional countries in the full report |
| Key Companies Covered | BENEO GmbH, Cosucra Groupe Warcoing S.A., Sensus B.V., Cargill, Incorporated, ADM, Ingredion Incorporated, Tate & Lyle PLC, Tierra Group International, Kerry Group plc, dsm-firmenich AG |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up physical volume and ASP triangulation. |
Inulin Market - Research Methodology
Table 10: Research Methodology for the Inulin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with European and Chilean chicory root agronomy directors, membrane fractionation process engineers, dairy and bakery R&D directors, and infant formula procurement leads. |
| Secondary Research | Analysis of USDA FAS Food Processing Ingredients and Sugar Annual reports, FDA and EFSA prebiotic and dietary fiber dossiers, peer-reviewed food hydrocolloid studies, and corporate annual filings. |
| Market Sizing and Forecasting | Bottom-up reconciliation of global refined inulin tonnage (418,000 to 450,000 MT in 2026) and grade-weighted wholesale realizations per metric ton across native, long-chain, and organic segments from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weighting front-of-pack sugar labeling enforcement, cultured dairy and prebiotic beverage launch velocity, and infant formula production across eight countries. |
| Operational Benchmark Traceability | Root processing, dry-matter fructan yields, and fiber-gap serving indicators in Tables 2, 3, and 4 trace to MDPI Foods cultivar studies, Südzucker/BENEO annual disclosures, and Tate & Lyle purpose reports. |
| Data Triangulation and Validation | Revenue estimates isolate refined beta-2,1-fructan ingredients while excluding parent functional food products, insoluble wheat/oat hulls, and roasted chicory beverage roots. |
Inulin Market by Segments
Inulin Market segmented by Botanical Source:
- Chicory Root Extraction
- Blue Agave Fructans
- Jerusalem Artichoke
- Enzymatic and Other Botanical Sources
Inulin Market segmented by Polymerization Degree:
- Standard Native Inulin DP 10 to 12
- Short-Chain Prebiotic Oligofructose DP 2 to 9
- High-Performance Long-Chain Inulin DP Above 23
- Oligofructose-Enriched Inulin Blends
Inulin Market segmented by Form:
- Spray-Dried Powder
- Concentrated Liquid Syrup
- Agglomerated Instant Granules
- Micro-Milled Specialty Grades
- Encapsulated and Co-Processed Blends
Inulin Market segmented by Commercial Application:
- Dairy, Yogurts and Frozen Desserts
- High-Fiber Bakery, Breads and Cereals
- Dietary Supplements and Prebiotics
- Infant and Early-Life Nutrition
Inulin Market segmented by Certification Claim:
- Conventional Food Grade
- Certified Organic Inulin
- Identity-Preserved Non-GMO
- Clean-Label Plant-Based
Inulin Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Tate & Lyle PLC. (2026, August 26). Tate & Lyle adds new purpose target to improve everyday consumer health through fibre fortification. Tate & Lyle Corporate Newsroom.
- [2] Ostrun, I., Mihatov, V., Pichler, A., Jozinović, A., Banjari, I., & Kopjar, M.. (2026, August 25). Application of Chicory Root Inulin and Commercial Inulin in Various Food Products and Impact on Their Quality. Foods, 15(17), 2979 (MDPI).
- [3] USDA Foreign Agricultural Service. (2026, April 20). European Union: Sugar Annual. U.S. Department of Agriculture GAIN Report E42026-0032.
- [4] Südzucker AG. (2026, May 20). Südzucker Group Annual Report 2025/26: Special Products and BENEO Segment Performance. Südzucker AG Investor Relations.
- [5] Omary, L., Canfora, E. E., Puhlmann, M. L., Gavriilidou, A., Rijnaarts, I., Holst, J. J., Op den Kamp-Bruls, Y. M. H., de Vos, W. M., & Blaak, E. E.. (2025, July 15). Intrinsic chicory root fibers modulate colonic microbial butyrate-producing pathways and improve insulin sensitivity in individuals with obesity. Cell Reports Medicine, 6(7), 102237 (PubMed Central PMC12281436).
- [6] Canazza, E., Grauso, M., Mihaylova, D., & Lante, A.. (2025, October 15). Techno-Functional Properties and Applications of Inulin in Food Systems. Gels, 11(10), 829 (PubMed Central PMC12564896).
- [7] BENEO GmbH. (2026, August 12). Sports Nutrition for Energy, Muscles and Gut: Prebiotic Chicory Root Fibre Formulations. BENEO Technical Institute.
- [8] Kerry Group plc. (2026, February 17). Kerry Group Preliminary Statement of Results for the Year Ended 31 December 2025. Kerry Group plc Media Releases.
- [9] Roquette Frères S.A.. (2026, February 3). NUTRIOSE Soluble Fibers Earn NutraStrong Prebiotic Verified Certification. Roquette Press Releases.
- [10] Ghyselinck, J., Verstrepen, L., Duysburgh, C., Wiche, R., Kuhn, K. S., Müller, M., Faerber-Frottier, V., & Marzorati, M.. (2026, February 17). Fiber mixtures containing chicory inulin, wheat dextrin, and cellulose, or tapioca dextrin alone, beneficially modulate microbial metabolic activity and composition in short-term colonic simulations. Frontiers in Nutrition, 13, 1749272.
- [11] U.S. Food and Drug Administration. (2026, June 2). Compliance Review on Fructooligosaccharides and Inulin Physiological Claims. U.S. Department of Health and Human Services.
- [12] BENEO GmbH. (2025, June 25). Chicory Root Prebiotics and 2'-FL Human Milk Oligosaccharides in Toddler Nutrition. BENEO Corporate News.
- [13] USDA Foreign Agricultural Service. (2026, March 31). Brazil: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report BR2026-0011.
- [14] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report MX2026-0022.
- [15] USDA Foreign Agricultural Service. (2026, April 1). China: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report CH2026-0042.
- [16] Archer Daniels Midland Company. (2026, July 28). ADM and Matsutani Mark 20 Years of Partnership and Prebiotic Dietary Fiber Innovation. ADM Corporate News Releases.
- [17] UK Department of Health and Social Care. (2026, March 26). Why we are taking action on 'less healthy' food and drink. UK Government Health in the Media.
- [18] USDA Foreign Agricultural Service. (2026, September 25). Germany: Retail Foods Annual. U.S. Department of Agriculture GAIN Report GM2026-0018.
- [19] USDA Foreign Agricultural Service. (2026, October 6). European Union: Sugar Semi-Annual. U.S. Department of Agriculture GAIN Report E42026-0076.
- [20] USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report JA2026-0012.
- [21] Ingredion Incorporated. (2026, July 6). Ingredion Spotlights Next-Generation Solutions for Texture, Clean Labels and Positive Nutrition at IFT FIRST 2026. Ingredion Newsroom.
- [22] BENEO GmbH. (2026, March 4). Metabolic Health and Prebiotic Chicory Root Fibre Reformulation Initiatives. BENEO News Releases.
- [23] dsm-firmenich AG. (2026, February 19). The Year in Review: dsm-firmenich Integrated Annual Report 2025. dsm-firmenich Corporate Publications.
- [24] Soyprasert, S., Saninjuk, K., Leangnim, N., Unban, K., Lalichatsakul, C., Phatthapong, P., Lungkaphin, A., Khanongnuch, C., & Kanpiengjai, A.. (2026, August 14). Short-Chain Inulin and Inulin Neoseries Oligosaccharides from Red Onions Enrich Beneficial Gut Taxa and Attenuate Obesity-Related Outcomes in a Rat Model. Foods, 15(16), 2841 (MDPI).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the inulin market in 2026 and what is forecast for 2036?
- Which front-of-pack sugar rules and dairy fat-replacement pressures support demand for inulin?
- Why does Chicory Root Extraction lead the botanical source category?
- Why does Spray-Dried Powder lead the form category globally?
- How do national growth rates compare across Brazil and Mexico versus China and the USA?
- Which leading companies operate primary chicory root extraction refineries versus multi-ingredient blending?
- What gastrointestinal tolerance limits or low-pH hydrolysis risks restrain inulin dosing?
- What should dairy and beverage formulators evaluate when selecting chain-length DP grades?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Botanical Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Botanical Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Botanical Source, 2026 to 2036
- Chicory Root Extraction
- Blue Agave Fructans
- Jerusalem Artichoke
- Enzymatic and Other Botanical Sources
- Y-o-Y Growth Trend Analysis By Botanical Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Botanical Source, 2026 to 2036
- Global Market Analysis and Forecast, By Polymerization Degree, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Polymerization Degree, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Polymerization Degree, 2026 to 2036
- Standard Native Inulin DP 10 to 12
- Short-Chain Prebiotic Oligofructose DP 2 to 9
- High-Performance Long-Chain Inulin DP Above 23
- Oligofructose-Enriched Inulin Blends
- Y-o-Y Growth Trend Analysis By Polymerization Degree, 2021 to 2025
- Absolute $ Opportunity Analysis By Polymerization Degree, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Spray-Dried Powder
- Concentrated Liquid Syrup
- Agglomerated Instant Granules
- Micro-Milled Specialty Grades
- Encapsulated and Co-Processed Blends
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Commercial Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Commercial Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Commercial Application, 2026 to 2036
- Dairy, Yogurts and Frozen Desserts
- High-Fiber Bakery, Breads and Cereals
- Dietary Supplements and Prebiotics
- Infant and Early-Life Nutrition
- Y-o-Y Growth Trend Analysis By Commercial Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Commercial Application, 2026 to 2036
- Global Market Analysis and Forecast, By Certification Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Certification Claim, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Certification Claim, 2026 to 2036
- Conventional Food Grade
- Certified Organic Inulin
- Identity-Preserved Non-GMO
- Clean-Label Plant-Based
- Y-o-Y Growth Trend Analysis By Certification Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Certification Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Botanical Source
- By Polymerization Degree
- By Form
- By Commercial Application
- By Certification Claim
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BENEO GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cosucra Groupe Warcoing S.A.
- Sensus B.V. (Royal Cosun)
- Cargill, Incorporated
- ADM
- Ingredion Incorporated
- Tate & Lyle PLC
- Tierra Group International
- Kerry Group plc
- dsm-firmenich AG
- BENEO GmbH (Südzucker Group)
- Tierra Group International, Ltd.
- Archer Daniels Midland Company (ADM)
- BENEO GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Botanical Source, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Polymerization Degree, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Commercial Application, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Certification Claim, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Botanical Source
- Figure 6: Global Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Polymerization Degree
- Figure 9: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Form
- Figure 12: Global Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Commercial Application
- Figure 15: Global Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Certification Claim
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Botanical Source
- Figure 32: North America Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Polymerization Degree
- Figure 35: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Form
- Figure 38: North America Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Commercial Application
- Figure 41: North America Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Certification Claim
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Botanical Source
- Figure 48: Latin America Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Polymerization Degree
- Figure 51: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Form
- Figure 54: Latin America Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Commercial Application
- Figure 57: Latin America Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Certification Claim
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Botanical Source
- Figure 64: Western Europe Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Polymerization Degree
- Figure 67: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Form
- Figure 70: Western Europe Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Commercial Application
- Figure 73: Western Europe Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Certification Claim
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Botanical Source
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Polymerization Degree
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Form
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Commercial Application
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Certification Claim
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Botanical Source
- Figure 96: East Asia Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Polymerization Degree
- Figure 99: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Form
- Figure 102: East Asia Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Commercial Application
- Figure 105: East Asia Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Certification Claim
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Botanical Source
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Polymerization Degree
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Commercial Application
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Certification Claim
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Botanical Source, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Botanical Source, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Botanical Source
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Polymerization Degree, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Polymerization Degree, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Polymerization Degree
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Commercial Application
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Certification Claim, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Certification Claim, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Certification Claim
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Inulin Market in 2026, and what is forecast for 2036?
Global inulin industry revenue stood at USD 1.8 billion during 2025 and is forecast to reach USD 1.9 billion in 2026. Total market valuation is on course to hit USD 3.4 billion by 2036 as dairy and beverage processors replace added sugars and saturated fat with prebiotic fiber.
What is the CAGR for the Inulin Market from 2026 to 2036?
The global inulin sector is projected to expand at a 6.0% CAGR over the 2026 to 2036 forecast window, generating USD 1.5 billion in incremental revenue across food and nutrition lines.
Which botanical source segment leads the Inulin Market?
Chicory Root Extraction holds an estimated 76.5% share of botanical source demand in 2026 since industrial root campaigns in Europe and Chile provide linear beta-2,1-fructans with superior gelling and prebiotic efficacy.
Which form segment leads the Inulin Market?
Spray-Dried Powder represents an estimated 77.0% of the form category in 2026 given that ambient dry powders integrate directly into bakery, cereal, and infant formula dry-blending equipment.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 7.4% CAGR through 2036, driven by mandatory front-of-pack high-added-sugar warning labels and rapid dairy beverage reformulation.
Who are the key players in the market?
BENEO GmbH; Cosucra Groupe Warcoing S.A.; Sensus B.V.; Cargill, Incorporated; ADM; Ingredion Incorporated; Tate & Lyle PLC; Tierra Group International; Kerry Group plc; and dsm-firmenich AG lead global commercial supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
