

- Market Size (2026)
- USD 5.6 Bn
- Forecast (2036)
- USD 27.9 Bn
- CAGR (2026 to 2036)
- 17.0%
How big is Kombucha Market in 2026?
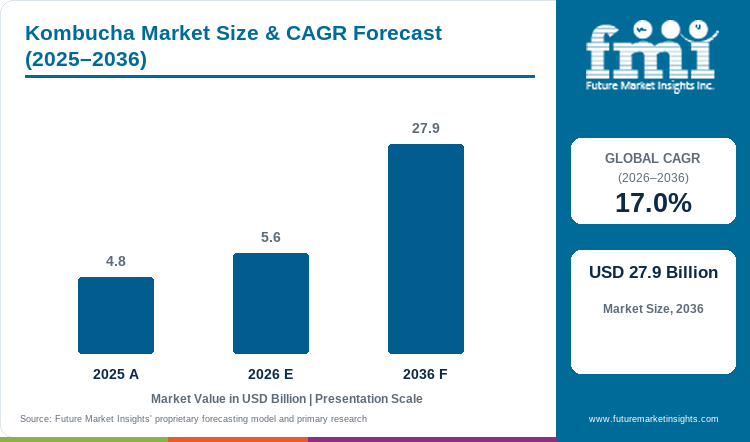
USD 5.6 Billion in 2026 and USD 27.9 Billion by 2036 at a 17.0% CAGR.
Sales of kombucha are estimated to grow at 17.0% from USD 5.6 Billion in 2026 to USD 27.9 Billion by 2036. The market was valued at USD 4.8 Billion in 2025. Growth increasingly depends on turning a specialist fermented tea into a routine refreshment. Accessible fruit profiles, lower-sugar recipes and familiar single-serve formats help reduce the taste barrier without removing fermentation from the core proposition.
The growth mechanism differs by country. Germany places strong scrutiny on health positioning, the UK is lowering its Soft Drinks Industry Levy threshold from 2028, and the USA requires close control of alcohol formation after bottling. Italy's scheduled sugar tax adds another formulation consideration. These pressures link kombucha increasingly with the wider functional beverage market, where product function needs to work alongside taste and regulatory fit.
Key Takeaways of Kombucha Market
- Fermentation and functional positioning attract trial, while flavor accessibility and reliable product handling influence repeat purchase.
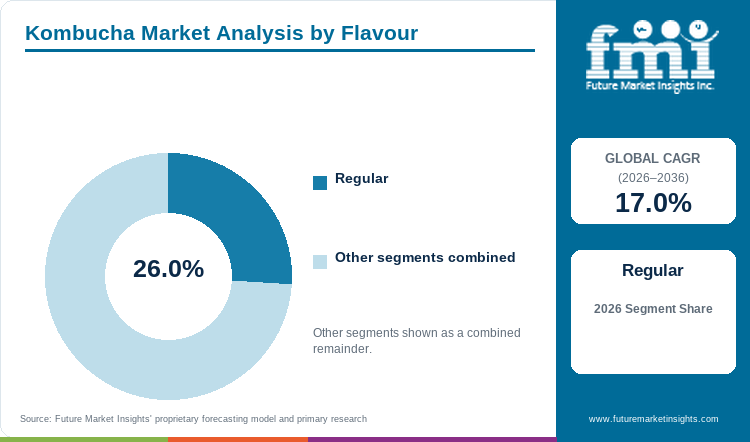
- In 2026, Regular leads the flavour segment with a 26.0% share because it provides a familiar reference point for fermented tea before consumers explore fruit and botanical blends.
- Food and Drink Specialty Store accounts for 46.0% of sales channel demand in 2026 because specialist retailers support product discovery, chilled merchandising, and ingredient explanation.
- Glass Bottles hold a 51.0% share of packaging demand in 2026 because they reinforce a premium fermented-beverage cue and suit refrigerated use.
- Continued fermentation can alter alcohol levels and sensory characteristics after packaging, while sugar content also affects product positioning and economics.
- Active companies include GT's Living Foods LLC, Health-Ade LLC, Humm Kombucha LLC, Brew Dr. Kombucha, Remedy Drinks Pty Ltd and PepsiCo Inc. through KeVita.
Analyst Perspective
“Kombucha is moving into a more demanding commercial phase. Consumers still value fermentation authenticity, but retailers need products that behave predictably after brewing. Brands that control alcohol, sugar and shelf performance while making the flavor easy to understand have the strongest route into repeat purchasing.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Kombucha Market segmented?
Kombucha Market is segmented by Flavour, Sales Channel, Packaging, and Region.
By flavour, it includes regular, berries, herbs and spices, citrus, apple, flowers, others, and coconut and mangoes. By sales channel, it covers food and drink specialty stores, online retail, hypermarkets/supermarkets, and convenience stores. By packaging, it comprises glass bottles and cans.
Why does regular lead demand within the flavour category?
Regular kombucha establishes the category's basic sensory reference through fermented tea acidity, effervescence and tea character without allowing one fruit or botanical flavor to dominate. This gives established drinkers an authenticity cue while giving retailers a stable core product around which seasonal extensions can rotate. The segment also connects kombucha with the wider Ready To Drink (RTD) Tea Market, although fermentation gives kombucha a more distinctive taste and handling profile.
- Regular commands a 26.0% share of Flavour demand in 2026, reflecting its role as a familiar entry point within the fermented beverage category.
- In February 2025, GT's Living Foods marked 30 years of SYNERGY Kombucha with “The Real Kombucha” positioning and a limited-edition Wildflower release, combining traditional fermentation with flavor innovation.
Why does food and drink specialty store lead demand within the sales channel category?
Specialty beverage and natural-food stores give kombucha more room for discovery than a conventional soft-drink shelf. Shoppers can compare fermentation style, ingredient choice, sugar levels and storage requirements while brands use chilled displays to introduce unfamiliar flavors. Health-Ade's March 2026 Strawberry Mango Chili launch used Sprouts and online distribution, showing how focused channels can test a distinctive flavor before wider expansion. The channel also overlaps naturally with consumers purchasing from the organic beverages market.
- Food and Drink Specialty Store contributes 46.0% of Sales Channel demand in 2026, reflecting its role in product discovery and differentiated beverage merchandising.
- Specialty placement gives emerging flavor concepts a focused setting for consumer trial before distribution extends into wider grocery networks.
Why do glass bottles lead demand within the packaging category?
Glass bottles reinforce the crafted and premium presentation historically associated with kombucha. They also work well for refrigerated products that may be resealed after opening. Cans are becoming more commercially important because they reduce weight and fit outdoor, convenience and single-serve occasions, but glass remains closely linked to the traditional kombucha shelf presence.
- Glass Bottles account for 51.0% of Packaging demand in 2026, underscoring the continued relevance of the established glass format.
- Humm's 2025 Probiome launch used an aluminum bottle, while its Nitro Kombucha range used cans, illustrating how suppliers are introducing lighter formats alongside the established glass packaging base.
What are the drivers, restraints and opportunities in the Kombucha Market?
Flavor-led functional refreshment supports demand, fermentation variability raises operating friction, and better process control creates room for lower-sugar and more widely distributed products.
- Driver: Consumers are gaining more approachable ways to enter the category through fruit, botanical and lower-sugar formats.
- Restraint: Alcohol formation, sugar exposure and storage requirements can complicate distribution and retail execution.
- Opportunity: Better fermentation control can widen availability while allowing brands to retain a credible fermented-tea identity.
Driver: Kombucha is increasingly competing for everyday beverage occasions rather than being purchased only by committed fermentation consumers. Health-Ade continued expanding fruit-led flavor choices during 2026, while Humm has developed both lower-sugar and texture-led formats. These launches broaden the sensory entry points into the category. The same shift is visible across the wider Probiotic Drinks & Fermented Beverage Market, where taste and convenience are becoming as commercially important as the fermentation story.
Restraint: Production does not end when the drink enters the package. Fermentation can continue, potentially changing alcohol content during storage. U.S. TTB guidance updated in January 2026 makes the 0.5% ABV threshold commercially significant for kombucha, including cases where alcohol rises after bottling. Sugar creates a second operating issue because it affects both sensory balance and the treatment of drinks under country-specific fiscal rules. Producers therefore need quality systems that connect brewing, packaging and shelf-life management.
Opportunity: Process control gives suppliers more options in distribution. Lower-sugar formulations can respond to both consumer preference and tax exposure, while controlled fermentation can reduce uncertainty around storage. Humm's 2025 Probiome and Nitro launches illustrate the use of functional ingredients, reduced sugar and alternative packaging to broaden the proposition. This moves kombucha further into the commercial territory occupied by the wider fermented beverages market without reducing it to a conventional soft drink.
Which country CAGRs are profiled in the Kombucha Market?
| Country | CAGR |
|---|---|
| Germany | 21.0% |
| Italy | 20.0% |
| UK | 19.0% |
| Russia | 18.0% |
| Japan | 17.0% |
| France | 16.0% |
| USA | 15.0% |
| Canada | 13.0% |
How do country-level CAGRs compare in the Kombucha Market?
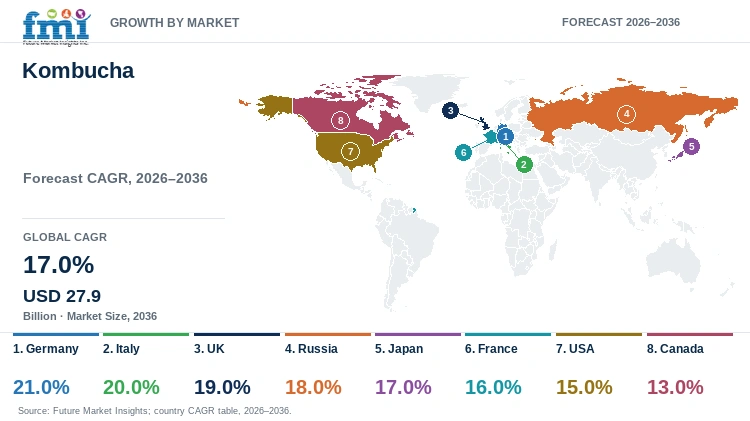
Germany and Italy form the highest-growth group at 21.0% and 20.0%. The UK and Russia follow at 19.0% and 18.0%, while Japan, France and the USA range from 15.0% to 17.0%. Canada has the lowest profiled CAGR at 13.0%. The spread between Germany and Canada is 8.0 percentage points and describes forecast pace rather than absolute market size.
- Germany: Strong interest in functional beverages exists alongside close scrutiny of sugar, alcohol content and health-related statements.
- Italy: The scheduled sugar tax increases the value of developing lower-sugar recipes before the levy begins.
- UK: The planned reduction in the Soft Drinks Industry Levy threshold makes sugar architecture increasingly important to product economics.
- Russia: Mandatory identification requirements for covered non-alcoholic beverages add packaging and distribution-system requirements.
- Japan: Functional positioning can differentiate a product, but businesses remain responsible for substantiating eligible claims.
- France: Added-sugar taxation makes residual sweetness a direct formulation and pricing consideration.
- USA: The 0.5% ABV threshold makes post-bottling fermentation control central to non-alcoholic positioning.
- Canada: Reliable storage, alcohol stability and clear product communication remain important as fermented beverages move into wider retail channels.
Country-wise Analysis
- Germany: Germany records the highest profiled CAGR at 21.0% from 2026 to 2036. Consumer scrutiny makes product communication unusually important. Verbraucherzentrale's August 2026 kombucha guidance emphasized that promoted health effects require care and noted that ready-to-drink products can contain both sugar and alcohol. For suppliers, the strongest commercial position is a clear fermented-tea proposition backed by straightforward nutrition information rather than exaggerated wellness language.
- Italy: Italy is forecast to expand at 20.0% CAGR. Budget measures have moved the scheduled start of the country's tax on sweetened non-alcoholic beverages to January 1, 2027. This gives manufacturers an additional reason to examine final sugar levels before setting price architecture and pack strategy. Products that use fermentation character, acidity and fruit complexity instead of high sweetness can protect both category identity and commercial flexibility.
- UK: The UK carries a 19.0% CAGR through 2036. HM Revenue & Customs announced in July 2026 that the Soft Drinks Industry Levy threshold will fall from 5g to 4.5g of added sugar per 100ml from January 1, 2028. Kombucha producers therefore have a clear reformulation horizon. Brands able to maintain flavor at lower sugar levels can reduce levy exposure while retaining the refreshment profile expected by mainstream consumers.
- Russia: Russia is profiled at an 18.0% CAGR. Identification and monitoring requirements for covered non-alcoholic beverages have become a practical route-to-market consideration, with additional enforcement stages taking effect during 2026. Kombucha suppliers need packaging and distribution systems that can support required product codes where their products fall within the covered classifications. Operational readiness therefore matters alongside flavor localization and distributor access.
- Japan: Japan is projected to grow at 17.0% CAGR. The Foods with Function Claims framework was updated further during 2025, keeping scientific substantiation and business responsibility central to functional positioning. Kombucha brands can use fermentation heritage and taste without making a formal functional claim, while suppliers pursuing specific health-function communication need a much more disciplined evidence and notification process.
- France: France has a 16.0% CAGR from 2026 to 2036. The country's taxation framework for non-alcoholic beverages with added sugar creates a direct link between recipe design and final economics. Changes during 2025 and 2026 reinforced the tiered approach to added sugar. Kombucha manufacturers therefore need to consider sweetness, acidity and shelf stability together instead of treating sugar reduction as an isolated nutrition exercise.
- USA: The USA is profiled at a 15.0% CAGR. U.S. kombucha economics depend heavily on controlling fermentation after bottling because products reaching 0.5% ABV can enter alcohol-beverage regulation. Brands also continue using specialty retailers to introduce new flavor combinations before wider rollout. Quality systems and flavor breadth therefore work together: process control protects distribution while innovation keeps consumers engaged.
- Canada: Canada is forecast to expand at 13.0% CAGR. The market offers room for fermented beverages that provide a distinctive alternative to conventional soft drinks, but suppliers still need clear storage instructions and dependable product stability. Retail expansion is easier when distributors can treat the beverage consistently through its shelf life. Lower sugar and straightforward labeling can also help kombucha compete beside other functional refreshment products.
Who are the notable companies in the Kombucha Market?
GT's Living Foods LLC, Health-Ade LLC, Humm Kombucha LLC, Brew Dr. Kombucha, Remedy Drinks Pty Ltd and PepsiCo Inc. through KeVita are among the notable active participants in the Kombucha Market.
Competition is increasingly concentrated among companies with active kombucha portfolios rather than diversified beverage groups that participated historically. GT's Living Foods emphasizes traditional fermentation and a refrigerated raw product proposition. Health-Ade competes through broad flavor rotation and extensive retail distribution. Humm combines kombucha with lower-sugar and explicitly functional formats, while Brew Dr. maintains both bottle and can options.
Remedy focuses strongly on low-sugar or no-sugar positioning and wider storage flexibility. PepsiCo participates through KeVita Master Brew Kombucha, which remains part of KeVita's current fermented beverage portfolio. These companies differ in how they balance fermentation authenticity, sugar reduction, packaging and route-to-market breadth.
- Traditional fermentation-led specialists: GT's Living Foods and Brew Dr. emphasize brewing process and fermented-tea identity.
- Flavor and functional innovators: Health-Ade and Humm use flavor cadence, lower-sugar recipes and functional positioning to broaden consumer entry points.
- Broader beverage platforms: Remedy and PepsiCo through KeVita extend kombucha across different packaging, distribution and refreshment occasions.
Competitive Benchmarking: Kombucha Market
| Company | Live-Culture Fermentation | Low/Zero-Sugar Breadth | Pack & Channel Flexibility | Geographic Reach |
|---|---|---|---|---|
| GT's Living Foods LLC | High | Medium | Medium | Broad USA retail and direct consumer access |
| Health-Ade LLC | High | Medium | High | Broad USA retail and online distribution |
| Humm Kombucha LLC | High | High | High | USA specialty retail and direct channels |
| Brew Dr. Kombucha | High | Medium | High | USA retail with bottle, can and online availability |
| Remedy Drinks Pty Ltd | High | High | High | Australia-based business with multiple kombucha formats |
| PepsiCo Inc. / KeVita | Medium | Medium | High | Large USA beverage distribution platform |
Key Developments in the Kombucha Market
- In June 2026, Health-Ade introduced Peach Strawberry Lychee as a permanent flavor and Raspberry Lime as a seasonal release. The launches used specialty, broader retail and online channels, extending the company's flavor-led recruitment strategy.
- In March 2025, Humm Kombucha announced Probiome and Nitro Kombucha. Probiome combined a lower-sugar recipe with multiple probiotic strains and an aluminum bottle, while Nitro used nitrogenation and cans to create a smoother drinking experience.
- In February 2025, GT's Living Foods marked the 30th anniversary of SYNERGY Kombucha. The company introduced “The Real Kombucha” wordmark and the Wildflower limited edition, reinforcing traditional fermentation while maintaining a rotating innovation pipeline.
Key Players in the Kombucha Market
Fermentation-led specialist brands
- GT's Living Foods LLC
- Health-Ade LLC
- Humm Kombucha LLC
- Brew Dr. Kombucha
- Remedy Drinks Pty Ltd
Diversified beverage platform
- PepsiCo Inc. / KeVita
Kombucha Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Flavour; Sales Channel; Packaging |
| Quantitative Units | Revenue in USD Billion and CAGR in %. |
| Market Definition | Revenue includes packaged ready-to-drink kombucha sold as fermented tea within the listed Flavour, Sales Channel and Packaging taxonomy. Home-brew cultures and kits, downstream menu revenue, unrelated fermented beverages and alcoholic hard-kombucha products are outside the defined market. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; Germany; UK; Russia; France; Italy; Canada; Japan |
| Key Companies Profiled | GT's Living Foods LLC; Health-Ade LLC; Humm Kombucha LLC; Brew Dr. Kombucha; Remedy Drinks Pty Ltd; PepsiCo Inc. / KeVita |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Kombucha Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gather input from kombucha manufacturers, distributors, retailers, beverage buyers and other industry participants. Interviews examine flavor demand, fermentation control, packaging choice, pricing and route-to-market requirements. |
| Desk Research | Desk research covers beverage regulations, taxation measures, retail activity, company product information and dated corporate developments. |
| Market Sizing and Forecasting | Market sizing combines the baseline market value with flavor mix, packaging, channel demand, retail expansion, pricing and country-level commercial conditions. |
| Data Validation | Estimates are compared with company activity, regulatory developments, distribution patterns and primary research findings to maintain consistency across segments and countries. |
Kombucha Market by Segments
Kombucha Market segmented by Flavour:
- Regular
- Berries
- Herbs & Spices
- Citrus
- Apple
- Flowers
- Others
- Coconut & Mangoes
Kombucha Market segmented by Sales Channel:
- Food and Drink Specialty Store
- Online Retail
- Hypermarket/Supermarket
- Convenience Store
Kombucha Market segmented by Packaging:
- Glass Bottles
- Cans
Kombucha Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Alcohol and Tobacco Tax and Trade Bureau. (2026, January 8). Kombucha Labeling.
- Verbraucherzentrale. (2026, August 10). Kombucha: Das sollten Sie über das Teegetränk aus Asien wissen.
- HM Revenue & Customs. (2026, July 13). Changes to the Soft Drinks Industry Levy.
- Senato della Repubblica. (2025). Budget documentation on the postponement of Italy's sugar tax to January 1, 2027.
- Government of the Russian Federation. (2026). Mandatory identification controls for selected non-alcoholic beverages and juices.
- Consumer Affairs Agency, Government of Japan. (2025). Foods with Function Claims guidance and notification framework.
- Légifrance. (2025). Article 1613 ter, Code général des impôts.
- Health-Ade. (2026, June 9). Health-Ade Introduces Two New Flavors: Peach Strawberry Lychee and Limited-Edition Raspberry Lime.
- Health-Ade. (2026, March 3). Health-Ade Debuts Strawberry Mango Chili.
- Health-Ade. (2026, January 15). Health-Ade Introduces Ginger Lemon Berry.
- Humm Kombucha. (2025, March 4). Humm Kombucha Unveils Probiome.
- Humm Kombucha. (2025, March 4). Humm Debuts Nitro Kombucha.
- GT's Living Foods. (2025, February 18). SYNERGY Celebrates 30 Years as the Pioneer of Real Kombucha.
- Brew Dr. Kombucha. Current Kombucha Product Range.
- Remedy Drinks. Current Kombucha Product Range.
- KeVita. Master Brew Kombucha Product Range.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Kombucha Market in 2026 and what value is forecast for 2036?
- What commercial factors are supporting repeat kombucha demand?
- Why does Regular lead the Flavour category?
- Why does Food and Drink Specialty Store lead the Sales Channel category?
- How do profiled country growth rates differ from 2026 to 2036?
- Which companies maintain active kombucha portfolios?
- What limits broader retail expansion of kombucha?
- What should buyers assess before listing or distributing kombucha?
Frequently Asked Questions
How big is the Kombucha Market in 2026?
The Kombucha Market is valued at USD 5.6 Billion in 2026 and is forecast to reach USD 27.9 Billion by 2036. The market was valued at USD 4.8 Billion in 2025.
What is the CAGR of the Kombucha Market from 2026 to 2036?
The market is forecast to expand at a 17.0% CAGR from 2026 to 2036 as fermented tea moves into wider retail and everyday refreshment occasions.
Which Flavour leads the Kombucha Market?
Regular leads Flavour with a 26.0% share in 2026 because it provides consumers with a clear reference profile for traditional fermented tea.
Which Sales Channel leads the Kombucha Market?
Food and Drink Specialty Store leads Sales Channel with a 46.0% share in 2026 because it supports chilled merchandising, discovery and product education.
Which Packaging format leads the Kombucha Market?
Glass Bottles lead Packaging with a 51.0% share in 2026. The format retains strong premium and traditional fermented-beverage associations.
Which profiled countries have the highest growth rates?
Germany has the highest profiled CAGR at 21.0%, followed by Italy at 20.0% and the UK at 19.0% from 2026 to 2036.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Flavour, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavour, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavour, 2026 to 2036
- Regular
- Berries
- Herbs & Spices
- Citrus
- Apple
- Flowers
- Others
- Coconut & Mangoes
- Y-o-Y Growth Trend Analysis By Flavour, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavour, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Food and Drink Specialty Store
- Online Retail
- Hypermarket/Supermarket
- Convenience Store
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging, 2026 to 2036
- Glass Bottles
- Cans
- Y-o-Y Growth Trend Analysis By Packaging, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Flavour
- By Sales Channel
- By Packaging
- By Country
- Market Attractiveness Analysis
- By Country
- By Flavour
- By Sales Channel
- By Packaging
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Flavour
- By Sales Channel
- By Packaging
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Flavour
- By Sales Channel
- By Packaging
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- GT's Living Foods LLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Health-Ade LLC
- Humm Kombucha LLC
- Brew Dr. Kombucha
- Remedy Drinks Pty Ltd
- PepsiCo Inc. / KeVita
- GT's Living Foods LLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


