
- Market Size (2026)
- USD 5.6 Bn
- Forecast (2036)
- USD 11.8 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Matcha Market in 2026?
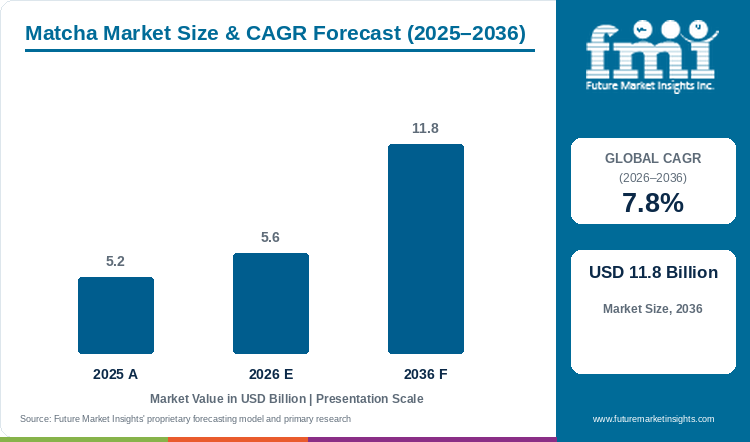
Assessed at USD 5.2 billion in 2025 and progressing to USD 5.6 billion in 2026, the matcha market valuation is on course to reach USD 11.8 billion by 2036, supported by a forecast-period CAGR of 7.8%.
Table 1: Market Size and Forecast for the Matcha Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.2 billion |
| Estimated Market Size in 2026 | USD 5.6 billion |
| Projected Market Size by 2036 | USD 11.8 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 6.2 billion |
The global matcha market was valued at USD 5.2 billion in 2025 and is estimated to reach USD 5.6 billion in 2026. The market is projected to reach USD 11.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.8% between 2026 and 2036. Ceremonial First-Harvest Grade powder is anticipated to capture 54.5% of grade type demand in 2026 given that beverage chains and retail shoppers pay premium prices for rich chlorophyll color and smooth umami taste. FMI analysis suggests that category consumption is accelerating as coffeehouse operators and grocery shoppers move shade-grown tencha powder from traditional hot tea preparation into all-day iced lattes and functional energy beverages. This menu expansion separates the sector from the broader ready-to-drink tea category growing at 5.8% CAGR since whole-leaf powder commands higher per-cup margins than steeped leaf infusions. Data from the Food and Agriculture Organization shows that global tea production reached an estimated 7.3 million metric tons with international imports of 2.0 million metric tons in 2025, reflecting steady demand for specialty green tea origins. Producers are adjusting specifications to ration scarce spring leaves, as seen when Ippodo Tea updated product specifications and pricing structures in September 2026 after multi-year harvest constraints tightened Japanese tencha availability. Multi-year supply contracts now depend on five-year tea bush maturation cycles and stone-milling capacity that preserve amino acid ratios through 2036.
Key Market Trends & Insights
- By grade type: Ceremonial First-Harvest Grade formulations hold an estimated 54.5% share in 2026 since spring-shaded tencha leaves provide high L-theanine content for premium lattes.
- By production method: Conventional Shade-Grown represents 62.0% in 2026 given that controlled nitrogen fertilization stabilizes leaf chlorophyll yields across Japanese prefectures.
- By application: Ready-to-Drink Beverages account for 48.0% in 2026 driven by cold-foam iced matcha rollouts across global coffeehouse chains.
- By packaging format: Nitrogen-Flushed Pouches secure 51.0% in 2026 owing to oxygen-barrier protection that prevents catechin oxidation and color fading.
- By distribution channel: Specialty Tea Bars command 46.5% in 2026 through customized barista powder blends and recurring wholesale supply contracts.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at an 8.7% CAGR through 2036 under urban functional beverage adoption and specialty cafe franchising.
- Broader country progression: The USA tracks at an 8.1% CAGR ahead of South Korea at 7.9% and Japan at 7.5%, while France advances at a 7.4% CAGR.
Market Size & Forecast
Beverage formulators and specialty cafe chains face acute raw material bottlenecks when sourcing spring-harvested tencha leaves from Kyoto and Uji as well as Kagoshima and Shizuoka estates. When beverage brands substitute unshaded summer green tea powder to cut ingredient costs, elevated catechin bitterness and brownish oxidation degrade consumer repeat purchases. Research published in Frontiers in Nutrition in October 2026 demonstrated that pre-harvest shading duration and milling technique directly govern chlorophyll retention and amino acid balance in powdered green tea . Consequently, commercial buyers lock in forward procurement agreements for green tea extracts and shaded tencha lots to guarantee consistent sensory profiles across retail batches.
Tencha Leaf Harvest and Milling Allocation Sizing
Table 2: Tencha Leaf Harvest and Milling Allocation Sizing for the Matcha Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.2 | 5.6 | 11.8 |
| Global milled tencha & matcha volume (thousand metric tons) | 42.5 to 46.8 | 45.8 to 50.4 | 94.0 to 104.5 |
| Japanese green tea & tencha export allocation (thousand metric tons) | 12.8 to 13.5 | 14.1 to 15.2 | 28.5 to 32.0 |
| Average wholesale ceremonial/cafe blend realization (USD per kg) | 110.0 to 135.0 | 115.0 to 142.0 | 125.0 to 158.0 |
Operational note: Tencha allocation ranges reflect covered first-flush and second-flush Camellia sinensis leaf harvests converted via de-stemming, tencha furnace drying and stone or ceramic ball milling.
Functional drink brands and dietary supplement makers specify standardized amino acid profiles when formulating relaxation and focus beverages. In September 2026, the U.S. FDA completed its evaluation of GRAS Notice GRN 001311 for high-purity L-theanine in beverage and food categories. Beverage developers pair natural tea extract fractions with stone-milled whole leaf powder to stabilize L-theanine dosing per serving across canned ready-to-drink lines.
Foodservice Cafe & Retail Channel Allocation Indicators
Table 3: Global Tea Trade and Specialty Matcha Intensity Indicators (Million Metric Tons and USD Billion), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global tea production baseline (FAO, million metric tons) | 7.3 | 7.5 | 9.1 |
| Global tea import trade volume (FAO, million metric tons) | 2.0 | 2.1 | 2.6 |
| Specialty shaded matcha share of global tea value (%) | 8.4% to 9.1% | 8.9% to 9.6% | 14.2% to 15.5% |
| Cafe iced latte & RTD beverage share of matcha usage (%) | 46.5% | 48.0% | 54.5% |
Table 4: Commercial Cafe & Retail Procurement Indicators for the Matcha Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 5.6 billion | 2026 global revenue baseline |
| Global tea production benchmark | 7.3 million metric tons | FAO International Tea Day commodity baseline |
| Ceremonial First-Harvest Grade share, 2026 | 54.5% | First-flush shaded tencha revenue allocation |
| Specialty Tea Bars revenue, 2026 | USD 2.6 billion | 46.5% distribution channel allocation |
International trade governance and pesticide maximum residue limits shape cross-border shipments of shaded green tea powder into European and North American ports. As reported by the Food and Agriculture Organization Intergovernmental Group on Tea, compliance with harmonized maximum residue limits and organic certification standards determines export returns for specialty tea producers . Importers blending green tea polyphenols and barista matcha grades therefore conduct lot-by-lot laboratory screening prior to customs clearance.
Analyst Perspective
"Cafe chains and beverage formulators no longer treat matcha as a seasonal novelty; they procure shaded tencha powder as a core daily caffeine and L-theanine platform. Suppliers that secure multi-prefecture Japanese leaf contracts and nitrogen-flushed milling capacity will capture long-term foodservice accounts while spot buyers face persistent first-harvest allocation caps."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the matcha market segmented?
The matcha market is segmented by grade type, production method, application, packaging format, and distribution channel. In 2026, Ceremonial First-Harvest Grade is projected at 54.5%, Conventional Shade-Grown at 62.0%, Ready-to-Drink Beverages at 48.0%, Nitrogen-Flushed Pouches at 51.0%, and Specialty Tea Bars at 46.5%.
By grade type: Ceremonial First-Harvest Grade, Classic Cafe Grade, Culinary Processing Grade and Industrial Extract Grade.
By production method: Conventional Shade-Grown, Certified Organic Shaded, Stone-Milled Tencha and Ball-Milled Commercial.
By application: Ready-to-Drink Beverages and Bakery Pastries, Confectionery Chocolates, Dairy Frozen Desserts and Botanical Skincare.
By packaging format: Nitrogen-Flushed Pouches, Single-Serve Stick Packs, Bulk Foodservice Bags and Ready-to-Drink Cans.
By distribution channel: Specialty Tea Bars, Supermarkets and Hypermarkets, Direct-to-Consumer E-Commerce and B2B Ingredient Distributors.
Why does Ceremonial First-Harvest Grade lead the grade type category?
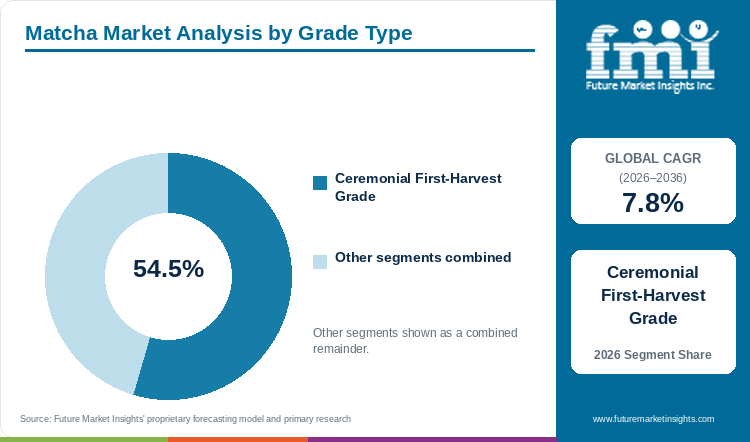
Ceremonial First-Harvest Grade formulations hold an estimated 54.5% of grade type demand in 2026, anchored by premium cafe latte pricing and high L-theanine umami quality.
Table 5: Grade Type Share for the Matcha Market (percentage share), 2026
| Grade Type | Share (2026) |
|---|---|
| Ceremonial First-Harvest Grade | 54.5% |
| Other Segments Combined | 45.5%* |
| Total | 100.0% |
*Note: Remaining grade type categories account for the balance of 2026 global matcha demand.
Table 6: Grade Type Leadership and Market Growth for the Matcha Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Ceremonial First-Harvest Grade |
Ceremonial First-Harvest Grade matcha produced from hand-picked or precision-sheared spring tencha leaves commands top revenue share since shading tea bushes for 20 to 30 days suppresses catechin conversion and elevates L-theanine content. Specialty coffeehouses and premium retail brands specify first-flush grades for straight whisked tea and unsweetened iced lattes where dull color or grassy bitterness would alienate buyers. In February 2026, Ippodo Tea documented that farmers shading a higher proportion of tea fields for first-harvest matcha must often skip second-harvest plucking so stressed tea plants can recover for the following spring . While granite stone mills grinding 40 grams per hour restrict rapid volume scaling, high unit prices keep first-harvest grades at the center of supplier revenue.
- Within the grade type segment, Ceremonial First-Harvest Grade is projected to account for a leading 54.5% share in 2026, driven by consumer willingness to pay premium prices for rich emerald color and sweet umami flavor.
- Classic Cafe Grade blends are anticipated to gain volume share across mid-tier chains as beverage formulators blend first-flush and second-flush tencha to balance cost per cup.
What sustains Conventional Shade-Grown leadership in the production method segment?
Conventional Shade-Grown represents 62.0% of the production method category in 2026, supported by higher per-hectare tencha yields and consistent leaf chlorophyll levels.
Conventional Shade-Grown dominates global tencha supply given that synthetic nitrogen fertilizers and targeted crop protection allow Japanese and Chinese estates to maintain high leaf amino acid levels under heavy black-net shading. When tea bushes are deprived of up to 85% of sunlight for three weeks, plant immunity drops and pest vulnerability rises sharply across humid growing valleys. Conversion of shaded estates to organic tea production reduces per-hectare leaf yield and requires strict buffer zones, which keeps conventional agronomy as the primary volume backbone for global beverage processors.
- In 2026, Conventional Shade-Grown is anticipated to capture 62.0% of production method demand, supported by higher leaf yields per hectare and predictable chlorophyll density.
- Chemical analysis published in Molecules in August 2026 confirmed that high-temperature tencha drying and controlled shading conditions govern the sweet roasted aroma and catechin balance required by commercial buyers.
How do Ready-to-Drink Beverages lead the application category?
Ready-to-Drink Beverages account for 48.0% of application demand in 2026, driven by year-round iced matcha latte and functional canned drink rollouts.
Ready-to-Drink Beverages anchor global consumption since younger consumers are replacing high-sugar carbonated soft drinks and jitter-inducing espresso shots with iced matcha lattes and canned botanical refreshers. Coffeehouse chains pair unsweetened shaded green tea powder with oat milk or almond milk and fruit purees to drive afternoon store traffic in parallel with plant-based energy drink launches. Evidence of this menu shift emerged when Starbucks reported in February 2026 that its introduction of unsweetened matcha powder in January 2025 allowed baristas to customize sweetness levels and contributed to nearly 40% higher matcha beverage sales among Gen Z customers. Dispersion stability and chlorophyll browning inside acidic bottled drinks remain the primary technical hurdles for beverage R&D teams.
- By application, demand for Ready-to-Drink Beverages is estimated to reach 48.0% of category share in 2026 as global coffee chains expand customized iced and protein-blended matcha menus.
- Bakery Pastries and Dairy Frozen Desserts are forecast to register steady formulation uptake as industrial bakers use heat-stable culinary grades for natural green coloration.
Why do Nitrogen-Flushed Pouches lead the packaging format category?
Nitrogen-Flushed Pouches secure 51.0% of packaging format share in 2026, supported by oxygen-barrier protection against chlorophyll and catechin oxidation.
Nitrogen-Flushed Pouches capture the largest share of packaged matcha sales considering that finely milled tencha powder has a high specific surface area that oxidizes rapidly when exposed to light, humidity or ambient oxygen. Even brief exposure to warehouse heat degrades green chlorophyll into dull pheophytin and diminishes volatile aroma compounds before the consumer opens the container. Multi-layer aluminum foil pouches and double-lid metal canisters flushed with inert nitrogen gas preserve sensory freshness across transoceanic shipping lanes serving bubble tea and specialty retail accounts.
- Strong repeat ordering across retail and foodservice channels places Nitrogen-Flushed Pouches on course to hold an estimated 51.0% share of the packaging format category in 2026.
- Food processing research published in Foods in August 2026 verified that processing-driven transformations and barrier storage conditions directly control the retention of flavonols, theanine and catechins in finished matcha powders.
What gives Specialty Tea Bars the leading position in distribution channel?
Specialty Tea Bars command 46.5% of distribution channel demand in 2026, anchored by daily iced beverage cup velocity and wholesale barista contracts.
Specialty Tea Bars lead channel distribution owing to high daily cup velocity and B2B supply contracts that lock in multi-ton pallet deliveries of barista-grade powder. Cafe operators require fine 5-to-15-micron particle sizes that suspend cleanly in cold milk and water without leaving gritty sediment at the bottom of the cup. In FY2025/2026 strategic disclosures, Ito En announced structural supply-chain reforms starting in fiscal 2026 to coordinate tencha ingredient procurement and product development for overseas foodservice distribution. While retail grocery shelves and iced tea aisles expand household trial, foodservice chains remain the primary volume engine.
- Specialty Tea Bars are predicted to secure 46.5% of distribution channel demand in 2026, supported by year-round iced beverage menu placement across quick-service and specialty cafe outlets.
- Direct-to-Consumer E-Commerce subscription platforms are projected to expand rapidly through 2036 as home consumers purchase farm-direct ceremonial tins and electric milk frothers online.
What are the drivers, restraints, and opportunities in the matcha market?
In the matcha market, L-theanine functional beverage demand and global coffeehouse iced latte rollouts are projected to drive adoption, whereas five-year tea bush maturation cycles and slow stone-milling throughput restrain supply and encapsulated catechin formats create new commercial avenues.
- Driver: Consumer preference for L-theanine and catechin functional beverages is driving cafe menu expansion and retail adoption of unsweetened matcha formats.
- Restraint: Multi-year tea bush maturation timelines and slow granite stone-milling throughput restrict rapid tencha supply expansion and elevate raw leaf procurement costs.
- Opportunity: Formulating encapsulated catechins and micro-milled tencha into functional supplements, ready-to-drink cans and botanical skincare creates high-margin revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer migration toward clean-energy beverages that deliver calm mental focus without synthetic caffeine crashes is driving sustained sales growth across the global matcha sector. Unlike conventional brewed green tea where steeped leaves are discarded, consuming whole stone-milled tencha powder delivers the full spectrum of epigallocatechin gallate and L-theanine directly into the beverage. Nutritional research published in Nutrients demonstrated that matcha bioactive compounds including theanine and catechins support cognitive attention and stress modulation without disrupting sleep architecture. This functional profile is prompting beverage brands to expand green tea supplements and unsweetened barista powders across mainstream retail and foodservice outlets.
Risk Assessment of the Matcha Market: Operational and Formulation Friction
Structural agricultural rigidities in Japanese tencha cultivation and milling bottlenecks represent the primary factors restraining volume expansion across the global matcha industry. Newly planted Camellia sinensis fields require approximately five years before leaves can be harvested commercially, and skipping second-flush harvests to let shaded tea bushes recover caps annual tonnage per hectare. In March 2026, Ippodo Tea implemented revised product lineups and purchasing limits after multi-season Japanese tencha shortages and summer heat stress tightened raw leaf inventories. Beverage procurement teams consequently face elevated wholesale kilo prices and strict allocation quotas when scaling new national product launches.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient processors and beverage formulators are capturing new commercial avenues by pairing authentic Japanese tencha with precision-fermented L-theanine and botanical extracts in ready-to-drink cans and stick packs. As regulatory agencies clear standardized amino acid ingredients, formulators can guarantee exact L-theanine milligram claims on front-of-pack labels in addition to yerba mate and adaptogenic drink lines. Product formulation releases from Encha Organic Matcha in December 2025 demonstrate how Uji barista-grade organic matcha integrates into functional peppermint and plant-milk seasonal lattes. Integration of verified bioactive potency with cold-water-dispersible agglomeration allows suppliers to win high-margin convenience and nutraceutical contracts.
Matcha Market by Country (2026 to 2036)
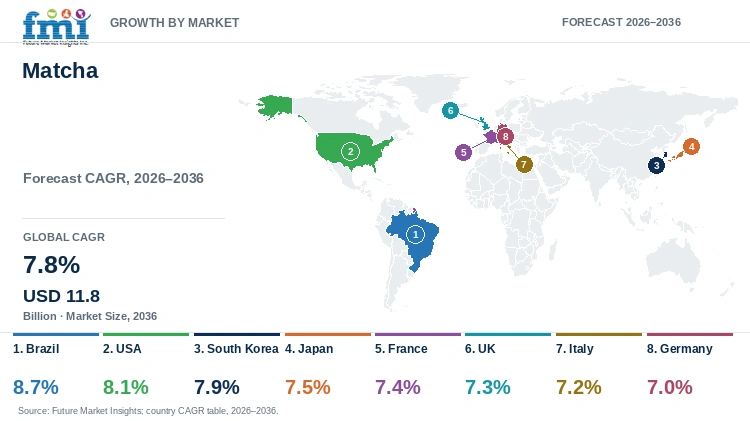
FMI country modeling indicates that Brazil leads national matcha expansion at an 8.7% CAGR through 2036, while Germany advances at a 7.0% CAGR. Commercial growth across Latin American metropolitan cafes and North American beverage chains as well as East Asian and European markets depends on tencha import allocations and clean-label beverage reformulation.
Table 7: Country CAGR and Primary Growth Levers for the Matcha Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.7% | Urban specialty tea bar franchising and tropical functional drink blending |
| USA | 8.1% | Nationwide coffeehouse unsweetened iced matcha latte customization |
| South Korea | 7.9% | Jeju Island tencha cultivation and convenience-store bakery integration |
| Japan | 7.5% | Farmer conversion from sencha to tencha and inbound tourist ceremonial demand |
| France | 7.4% | Fine patisserie culinary integration and certified organic tea retail |
| UK | 7.3% | Tariff-free Japanese tea imports and high-street coffee chain menu shifts |
| Italy | 7.2% | Artisanal gelato formulation and metropolitan specialty cafe adoption |
| Germany | 7.0% | Organic supermarket and drugstore private-label matcha standardization |
Source: Future Market Insights analysis
Brazil Matcha Market Outlook (2026 to 2036)
Demand for matcha in Brazil is projected to expand at a leading 8.7% CAGR between 2026 and 2036 as specialty beverage chains, fitness supplement brands and Japanese-Brazilian culinary outlets scale across Sao Paulo and Rio de Janeiro. What sets Brazil apart from mature Asian tea markets is the rapid incorporation of milled tencha into tropical fruit refreshers, functional pre-workout blends and artisanal gelato formulations. Official reporting from the USDA Sao Paulo agricultural office in March 2026 notes that Brazil's expanding food processing and modern retail sectors continue to increase imports of high-value functional food ingredients. While high import tariffs and customs clearance timelines challenge small independent cafes, national beverage distributors are locking in bulk culinary and barista tencha shipments to supply growing urban consumer demand.
Key takeaway: In Brazil, urban specialty cafe expansion and functional beverage formulation are projected to drive a leading 8.7% CAGR through 2036.
USA Matcha Market Outlook (2026 to 2036)
In the USA, matcha sales are anticipated to advance at an 8.1% CAGR from 2026 to 2036, anchored by nationwide coffeehouse menu permanent placements and multi-pack grocery canister velocity. American adoption is driven by customized cold-foam iced lattes, protein-fortified smoothie chains and single-serve hydration stick packs. In February 2026, Starbucks expanded its North American beverage lineup with Iced Double Berry Matcha and Iced Banana Bread Matcha creations built on its unsweetened shaded green tea powder base. Although port shipping delays and Japanese first-harvest allocation caps tighten spot supply for independent roasters, large U.S. foodservice operators mitigate risk through direct multi-year Japanese milling partnerships.
Key takeaway: In the USA, national coffeehouse menu innovation and unsweetened iced latte customization are anticipated to sustain an 8.1% CAGR through 2036.
South Korea Matcha Market Outlook (2026 to 2036)
South Korea's matcha sector is forecast to expand at a 7.9% CAGR during 2026 to 2036 as domestic bakery franchises, convenience stores and K-beauty cosmetic formulators integrate shaded green tea powder across product lines. Domestic cultivation on Jeju Island and Boseong estates supplements Japanese imports, giving Korean food processors a localized supply base for choco-pies, cream-filled pastries and bottled tea lattes. Country market filings published by the USDA Seoul agricultural office in May 2026 show that South Korea's advanced food manufacturing and convenience retail sectors actively prioritize low-sugar and functional botanical ingredients. Stringent domestic pesticide residue inspections on imported tea lots require overseas suppliers to maintain full agricultural traceability.
Key takeaway: In South Korea, domestic Jeju tencha cultivation combined with bakery and convenience-store beverage launches is forecast to support a 7.9% CAGR.
Japan Matcha Market Outlook (2026 to 2036)
Sales in the Japan matcha market are estimated to progress at a 7.5% CAGR between 2026 and 2036, supported by inbound tourism retail purchases and domestic ready-to-drink PET bottle innovation, farmer conversion from sencha to tencha. Domestic market momentum is supported by its position as the primary agricultural and stone-milling hub for authentic Uji, Nishio and Kagoshima tencha. Market assessments released by the USDA Tokyo agricultural office in April 2026 indicate that Japanese food and beverage manufacturers are actively reformulating retail products to serve health-focused domestic consumers and surging tourist demand. Older rural tea farming demographics and summer heatwaves constrain raw leaf tonnage, prompting Japanese tea corporations to invest in mechanized shading and long-term grower contracts.
Key takeaway: In Japan, farmer conversion from sencha to shaded tencha and inbound tourism demand for ceremonial grades are estimated to drive a 7.5% CAGR.
France Matcha Market Outlook (2026 to 2036)
France's matcha market is projected to register a 7.4% CAGR from 2026 to 2036 as Parisian patisseries, specialty tea salons and organic grocery chains expand ceremonial and culinary green tea assortments. French culinary adoption differs from standard beverage markets through deep integration of Uji and Nishio matcha into fine laminated pastries, macarons and white chocolate ganaches as well as botanical skincare lines. Annual food processing data from the USDA Paris agricultural office in April 2026 confirms that French food processors and retail chains maintain strong procurement demand for certified organic and origin-verified specialty ingredients. Strict European Union pesticide and novel packaging rules compel Japanese exporters to supply certified organic lots for French retail shelves.
Key takeaway: In France, patisserie culinary integration and specialty organic retail expansion are projected to sustain a 7.4% CAGR through 2036.
UK Matcha Market Outlook (2026 to 2036)
Commercial demand for matcha in the UK is anticipated to expand at a 7.3% CAGR through 2036 across high-street coffee chains, premium supermarket meal-deal aisles and direct-to-consumer wellness brands. British consumers with a long-standing black tea habit are shifting afternoon consumption toward iced oat-milk matcha lattes and canned functional green tea drinks that comply with national high-fat, salt and sugar promotional restrictions. Trade policy documentation from the U.S. Department of Agriculture confirms that tariff elimination on Japanese green tea under bilateral economic partnership frameworks strengthens the competitiveness of authentic Japanese tea imports in the UK. Price sensitivity among mainstream grocery shoppers encourages British blenders to offer tiered cafe and culinary grades.
Key takeaway: In the UK, tariff-free Japanese green tea trade and high-street coffeehouse iced latte adoption are anticipated to support a 7.3% CAGR.
Italy Matcha Market Outlook (2026 to 2036)
Italy's matcha market is forecast to advance at a 7.2% CAGR between 2026 and 2036 as artisanal gelaterias, specialty coffee roasters in Milan and Rome and natural cosmetics formulators adopt shaded green tea powder. Even within a domestic beverage culture anchored by espresso bars, young urban Italian shoppers and international tourists are driving brisk cafe orders for iced matcha cappuccinos and pistachio-matcha desserts. Sector reporting from the USDA Rome office in April 2026 documented that Italian food processors and HRI operators are expanding health-oriented and premium imported ingredient offerings across metropolitan centers. Barista training on proper bamboo-whisk and cold-frothing dispersion remains essential to prevent clumping in Italian cafe service.
Key takeaway: In Italy, artisanal gelato formulation and metropolitan specialty cafe menu additions are forecast to generate a 7.2% CAGR through 2036.
Germany Matcha Market Outlook (2026 to 2036)
German matcha revenue is predicted to climb at a 7.0% CAGR across 2026 to 2036, led by organic supermarket chains, drugstore wellness aisles and industrial bakery ingredient blenders. German retail buyers enforce some of Europe's strictest private-label specifications for organic certification, heavy-metal screening and recyclable outer packaging. Official wholesale price statistics released by Destatis in July 2026 tracked ongoing price adjustments across Germany's wholesale coffee and tea as well as cocoa and spice sector amid shifting global beverage commodity supplies. German beverage co-packers and tea houses consequently prioritize long-term supply agreements with JAS-certified and EU-organic verified tencha mills.
Key takeaway: In Germany, high organic drugstore and supermarket penetration with strict quality certification standards is predicted to anchor a 7.0% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the matcha market?
Ippodo Tea Co. Ltd., Marukyu Koyamaen Co. Ltd., The AOI Tea Company, Ito En Ltd., Aiya Co. Ltd., DoMatcha, Encha Organic Matcha, Sasaki Green Tea Company, Yamamasa Koyamaen Co. Ltd., and Nestlé S.A. are the notable companies in the matcha market.
Competitive positioning in the matcha industry separates heritage Japanese stone-milling houses, vertically integrated global green tea beverage corporations and specialized organic brand importers. Ippodo Tea, Marukyu Koyamaen, Yamamasa Koyamaen and AOI Tea control direct tencha estate relationships and traditional granite stone-milling rooms in Japan. Ito En, Aiya, Sasaki Green Tea and Nestlé operate high-capacity industrial milling and bottling networks while DoMatcha and Encha focus on organic retail.
- Heritage Japanese Ceremonial and Tencha Milling Specialists: Ippodo Tea Co. Ltd., Marukyu Koyamaen Co. Ltd., The AOI Tea Company and Yamamasa Koyamaen Co. Ltd. produce stone-ground first-harvest Uji and Nishio tencha for ceremonial and cafe accounts.
- Vertically Integrated Global Beverage and Industrial Ingredient Producers: Ito En Ltd., Aiya Co. Ltd., Sasaki Green Tea Company and Nestlé S.A. supply bulk foodservice powders, ready-to-drink bottled teas and commercial bakery extracts globally.
- Specialty Organic Retail and Barista Brand Innovators: DoMatcha and Encha Organic Matcha market JAS-certified and USDA-organic shaded green tea powders across North American and European omnichannel retail.
Competitive Benchmarking: Matcha Market
Table 8: Competitive Benchmarking for the Matcha Market (qualitative capability ratings), 2026
| Company | First-Harvest Tencha Access | Milling & Dispersion Tech | Organic & Residue Compliance | Geographic Reach |
|---|---|---|---|---|
| Ippodo Tea Co. Ltd. | High | High | High | Kyoto heritage producer; global e-commerce and U.S./global flagship tea stores |
| Marukyu Koyamaen Co. Ltd. | High | High | High | Uji, Kyoto stone-milling leader supplying ceremonial and confectionery accounts |
| The AOI Tea Company | High | High | High | Nishio tencha manufacturer with U.S. wholesale and private-label distribution |
| Ito En Ltd. | High | High | High | Global Japanese green tea and RTD beverage leader across Asia, Americas, Europe |
| Aiya Co. Ltd. | High | High | High | Nishio producer (since 1888) operating Aiya America and European ingredient hubs |
| DoMatcha | Medium | High | High | North American and international retail/barista brand with Kagoshima/Uji sourcing |
| Encha Organic Matcha | Medium | Medium | High | Uji farm-direct USDA-organic ceremonial and latte matcha across U.S. D2C channels |
| Sasaki Green Tea Company | High | High | High | Shizuoka integrated grower and processor exporting bulk and retail matcha globally |
| Yamamasa Koyamaen Co. Ltd. | High | High | Medium | Uji estate-grown ceremonial and culinary stone-milled matcha specialist |
| Nestlé S.A. | Medium | High | High | Multinational beverage and confectionery group marketing RTD and latte formats |
Evaluation basis: First-Harvest Tencha Access evaluates direct contracting with shaded Japanese tea estates in Uji and Nishio or Kagoshima, while Milling & Dispersion Technology rates granite stone-mill capacity and cold-water solubility. Organic & Residue Compliance measures JAS, USDA Organic and EU pesticide residue qualification for international foodservice and retail chains.
Key Developments in the Matcha Market
- In September 2026, the Japan External Trade Organization (JETRO) and JFOODO launched the OCHA SHOP CHANNEL in the United States to connect American consumers and retail buyers directly with authentic Japanese green tea and matcha producers.
- In June 2026, Ito En Ltd. published its FY2025 fourth-quarter and full-year financial presentation detailing group-wide supply chain integration and dedicated international expansion for its Japanese matcha and green tea beverage portfolio.
- In December 2025, DoMatcha introduced a savory culinary application pairing authentic Japanese stone-ground matcha with sea salt popcorn to expand all-day snacking occasions across North America.
Key Players in the Matcha Market
Heritage Japanese Ceremonial and Tencha Milling Specialists
- Ippodo Tea Co. Ltd.
- Marukyu Koyamaen Co. Ltd.
- The AOI Tea Company
- Yamamasa Koyamaen Co. Ltd.
Vertically Integrated Global Beverage and Industrial Ingredient Producers
- Ito En Ltd.
- Aiya Co. Ltd.
- Sasaki Green Tea Company
- Nestlé S.A.
Specialty Organic Retail and Barista Brand Innovators
- DoMatcha
- Encha Organic Matcha
Matcha Market - Report Scope
Table 9: Report Scope for the Matcha Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Grade Type; Production Method; Application; Packaging Format; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier and brand revenue from shade-grown, de-stemmed, and finely milled Camellia sinensis green tea powder (tencha-derived ceremonial, cafe/classic, and culinary matcha) and attributable matcha-based ready-to-drink beverages, bakery/confectionery inclusions, dairy desserts, and botanical skincare formulations. Category Scope Note: Excludes unshaded sencha green tea bags, loose-leaf steeped teas, and non-tea herbal powders. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, USA, South Korea, Japan, France, UK, Italy, Germany, and additional countries in the full report |
| Key Companies Covered | Ippodo Tea Co. Ltd., Marukyu Koyamaen Co. Ltd., The AOI Tea Company, Ito En Ltd., Aiya Co. Ltd., DoMatcha, Encha Organic Matcha, Sasaki Green Tea Company, Yamamasa Koyamaen Co. Ltd., Nestlé S.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Matcha Market - Research Methodology
Table 10: Research Methodology for the Matcha Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with Japanese agricultural cooperative directors in Uji, Nishio, and Kagoshima, granite stone-milling plant managers, coffeehouse beverage R&D formulators, and specialty tea importers. |
| Secondary Research | Analysis of FAO global tea production and trade databases, USDA Foreign Agricultural Service GAIN country food processing reports, FDA GRAS Notice filings for L-theanine, Destatis wholesale price indices, and peer-reviewed studies in Molecules, Foods, Nutrients, and Frontiers in Nutrition. |
| Market Sizing and Forecasting | Top-down global specialty tea and functional beverage baselines reconciled against bottom-up shaded tencha harvest tonnage (45.8K to 50.4K MT in 2026) and wholesale realization per kilogram across ceremonial, cafe, and culinary grades from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight specialty cafe store counts, cold-beverage menu penetration, bilateral green tea tariff schedules, and EU/FDA organic and pesticide residue compliance across eight national markets. |
| Operational Benchmark Traceability | Tencha allocation and global tea trade indicators in Tables 2, 3, and 4 trace to FAO international tea production statistics, Japanese export disclosures, and FDA GRAS amino acid usage thresholds. |
| Data Triangulation and Validation | Revenue estimates isolate shade-grown milled green tea powder and attributable value-added formulations while excluding unshaded loose-leaf green tea, black tea extracts, and generic botanical infusions. |
Matcha Market by Segments
Matcha Market segmented by Grade Type:
- Ceremonial First-Harvest Grade
- Classic Cafe Grade
- Culinary Processing Grade
- Industrial Extract Grade
Matcha Market segmented by Production Method:
- Conventional Shade-Grown
- Certified Organic Shaded
- Stone-Milled Tencha
- Ball-Milled Commercial
Matcha Market segmented by Application:
- Ready-to-Drink Beverages
- Bakery Pastries
- Confectionery Chocolates
- Dairy Frozen Desserts
- Botanical Skincare
Matcha Market segmented by Packaging Format:
- Nitrogen-Flushed Pouches
- Single-Serve Stick Packs
- Bulk Foodservice Bags
- Ready-to-Drink Cans
Matcha Market segmented by Distribution Channel:
- Specialty Tea Bars
- Supermarkets and Hypermarkets
- Direct-to-Consumer E-Commerce
- B2B Ingredient Distributors
Matcha Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- DoMatcha (Ecotrend Ecologics Ltd.). (2025, December 14). Ring in the New Year with Matcha & Sea Salt Popcorn. DoMatcha Official Releases.
- Encha Organic Matcha. (2025, December 16). Peppermint Matcha Latte Recipe: Organic Uji Barista Matcha Formulation. Encha Official Releases.
- FAO Intergovernmental Group on Tea. (2025, June 15). Current Global Tea Market Situation and Medium-Term Outlook. Food and Agriculture Organization OpenKnowledge Repository.
- Federal Statistical Office of Germany (Destatis). (2026, July 14). Wholesale Selling Prices in June 2026: Coffee, Tea, Cocoa and Spices Index. Destatis Press Release No. 247.
- Food and Agriculture Organization of the United Nations. (2025, May 21). International Tea Day: World Tea Production and Trade Overview. FAO Markets and Trade Portal.
- Foods Analytical Chemistry Consortium. (2026, August 14). Beyond Composition: Processing-Driven Transformations and Bioactive Retention in Matcha Tea. Foods, 15(16), 2782.
- Frontiers in Nutrition Research Team. (2026, October 19). Metabolic Characteristics and Chemical Basis of Matcha Processed from Shade-Grown Cultivars. Frontiers in Nutrition, 13, 1951952.
- Ippodo Tea Co. Ltd. (2026, February 19). Important Notice: Industry Supply Shortages, First-Harvest Shading, and Upcoming Bancha Availability. Ippodo Tea Global Announcements.
- Ippodo Tea Co. Ltd. (2026, March 1). Product Lineup and Purchasing Adjustments Coming Into Effect Starting March 2026. Ippodo Tea Global Corporate Notice.
- Ippodo Tea Co. Ltd. (2026, September 1). Oct./Nov. 2026: Revisions to Product Specifications and Pricing Amid Surge in Matcha Demand. Ippodo Tea Global Newsroom.
- Ito En Ltd. (2026, May 15). Message from the President: Strengthening the Global Matcha Supply Chain Starting in FY4/2026. Ito En Global Sustainability & Corporate Strategy.
- Ito En Ltd. (2026, June 1). Financial Results Presentation for FY2025 (Ended April 30, 2026). Ito En Investor Relations.
- Japan External Trade Organization (JETRO). (2026, September 17). JFOODO Launches OCHA SHOP CHANNEL to Help U.S. Consumers Discover Authentic Japanese Tea and Matcha. JETRO Official Announcements.
- Molecules Editorial Group. (2026, August 21). Focus on Matcha, Sencha, and Gyokuro: Tencha Drying and Bioactive Composition. Molecules, 31(16), 2934.
- Nutrients Clinical Sleep and Cognition Group. (2024, August 31). Matcha Does Not Affect Electroencephalography During Sleep but Enhances Metabolic and Cognitive Pathways. Nutrients, 16(17), 2907.
- Starbucks Corporation. (2026, February 3). Starbucks Launches New Iced Double Berry Matcha and Iced Banana Bread Matcha Drinks. Starbucks Official Press Room.
- Starbucks Corporation. (2026, February 25). Matcha Is Having a Moment, with Starbucks Unsweetened Matcha Powder Front-and-Center. Starbucks Stories & News.
- U.S. Food and Drug Administration. (2026, September 4). GRAS Notice (GRN) No. 001311 Agency Response Letter: L-Theanine for Food and Beverage Categories. FDA Center for Food Safety and Applied Nutrition.
- USDA Foreign Agricultural Service. (2025, August 11). Japan Treatment for UK Accession to CPTPP and Green Tea Tariff Elimination. U.S. Department of Agriculture GAIN Report.
- USDA Foreign Agricultural Service. (2026, March 31). Brazil: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report BR2026-0011.
- USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report JA2026-0012.
- USDA Foreign Agricultural Service. (2026, April 2). Italy: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report IT2026-0001.
- USDA Foreign Agricultural Service. (2026, April 3). France: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report FR2026-0008.
- USDA Foreign Agricultural Service. (2026, May 27). South Korea: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report KS2026-0011.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the matcha market in 2026 and what is forecast for 2036?
- Which cafe menu and functional beverage trends support demand for matcha?
- Why does Ceremonial First-Harvest Grade lead the grade type category?
- Why does Conventional Shade-Grown lead the production method category globally?
- How do growth rates differ across Brazil and the USA versus South Korea and Japan?
- Which leading companies operate heritage stone mills versus global beverage networks?
- What limits tencha harvest expansion or causes chlorophyll oxidation in the matcha market?
- What should beverage procurement teams evaluate before locking in annual Japanese matcha contracts?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Grade Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade Type, 2026 to 2036
- Ceremonial First-Harvest Grade
- Classic Cafe Grade
- Culinary Processing Grade
- Industrial Extract Grade
- Y-o-Y Growth Trend Analysis By Grade Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade Type, 2026 to 2036
- Global Market Analysis and Forecast, By Production Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Production Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Production Method, 2026 to 2036
- Conventional Shade-Grown
- Certified Organic Shaded
- Stone-Milled Tencha
- Ball-Milled Commercial
- Y-o-Y Growth Trend Analysis By Production Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Production Method, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Ready-to-Drink Beverages
- Bakery Pastries
- Confectionery Chocolates
- Dairy Frozen Desserts
- Botanical Skincare
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Nitrogen-Flushed Pouches
- Single-Serve Stick Packs
- Bulk Foodservice Bags
- Ready-to-Drink Cans
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Tea Bars
- Supermarkets and Hypermarkets
- Direct-to-Consumer E-Commerce
- B2B Ingredient Distributors
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Grade Type
- By Production Method
- By Application
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ippodo Tea Co. Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Marukyu Koyamaen Co. Ltd.
- The AOI Tea Company
- Ito En Ltd.
- Aiya Co. Ltd.
- DoMatcha
- Encha Organic Matcha
- Sasaki Green Tea Company
- Yamamasa Koyamaen Co. Ltd.
- Nestlé S.A.
- Ippodo Tea Co. Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Grade Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Production Method, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Grade Type
- Figure 6: Global Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Production Method
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Packaging Format
- Figure 15: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Distribution Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Grade Type
- Figure 32: North America Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Production Method
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Packaging Format
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Grade Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Production Method
- Figure 51: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 57: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Grade Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Production Method
- Figure 67: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 73: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Grade Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Production Method
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Grade Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Production Method
- Figure 99: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 105: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Grade Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Production Method
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Grade Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Grade Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Grade Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Production Method, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Production Method, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Production Method
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the matcha market in 2026, and what is forecast for 2036?
FMI estimates that global matcha revenue stood at USD 5.2 billion in 2025 and reached USD 5.6 billion in 2026. Total sector value is on track to hit USD 11.8 billion by 2036 as coffeehouse chains and drink makers scale iced latte and canned functional lines.
What is the CAGR for the matcha market from 2026 to 2036?
The matcha sector is projected to expand at a 7.8% CAGR over the 2026 to 2036 forecast window, generating USD 6.2 billion in incremental revenue across foodservice and retail channels.
Which grade type segment leads the matcha market?
Ceremonial First-Harvest Grade formulations are anticipated to hold 54.5% of grade type demand in 2026 since spring-shaded tencha leaves provide rich green color and high L-theanine sweetness.
Which production method segment leads the matcha market?
Conventional Shade-Grown is projected to represent 62.0% of the production method category in 2026 given that controlled fertilization maintains leaf yield under black-net shading.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at an 8.7% CAGR through 2036, driven by urban specialty tea bar openings and functional beverage launches.
Who are the key players in the market?
Key suppliers include Ippodo Tea, Marukyu Koyamaen and The AOI Tea Company as well as Ito En, Aiya and DoMatcha. Additional active participants include Encha Organic Matcha, Sasaki Green Tea, Yamamasa Koyamaen and Nestlé.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
