
- Market Size (2026)
- USD 238.0 Bn
- Forecast (2036)
- USD 646.0 Bn
- CAGR (2026 to 2036)
- 10.5%
How big is Organic Foods Market in 2026?
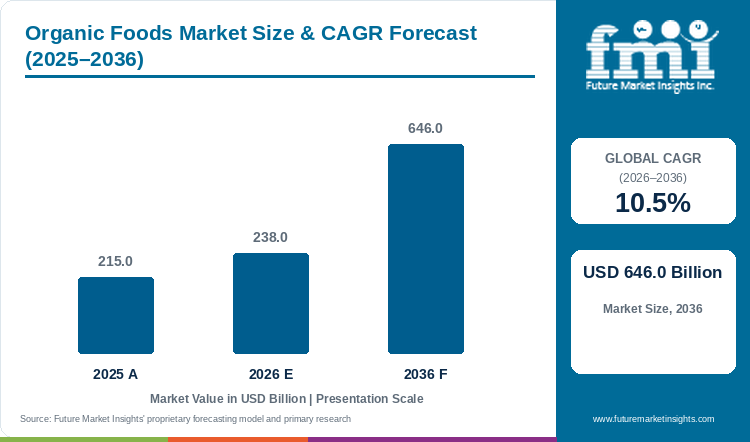
Assessed at USD 215.0 billion in 2025 and progressing to USD 238.0 billion in 2026, the organic foods market valuation is on course to reach USD 646.0 billion by 2036, supported by a forecast-period CAGR of 10.5%.
The global organic foods market was valued at USD 215.0 billion in 2025 and is estimated to reach USD 238.0 billion in 2026. The market is projected to reach USD 646.0 billion by 2036, expanding at a compound annual growth rate (CAGR) of 10.5% between 2026 and 2036. Organic fresh fruits and vegetables are projected to hold a leading 38.0% share of 2026 demand, given that supermarket chains use certified produce displays to anchor weekly household grocery trips. Demand for certified organic groceries is supported by narrowing price gaps between private-label organic lines and conventional items, with the Organic Trade Association reporting in March 2026 that U.S. organic food sales rose 6.9% to USD 70.1 billion in 2025 within a USD 76.6 billion certified organic marketplace [1].
FMI survey reflects that high weekly basket turnover separates the category from organic spices at a 4.3% CAGR, since households replenish fresh produce and dairy every week while seasoning jars remain in home pantries for months. Manufacturers are also investing in dedicated domestic processing lines to eliminate supply bottlenecks, as seen in June 2026 when SunOpta Inc. completed a USD 25 million production line expansion at its Omak plant in Washington to raise fruit snack capacity by 25% [2]. Grocery retailers and brand owners that lock in multi-year farm transition contracts and electronic import certificates are positioned to capture recurring household food budgets through 2036.
Key Market Trends & Insights
- By product category: Organic Fresh Fruits and Vegetables hold an estimated 38.0% share in 2026 since shoppers prioritize pesticide-free berries, leafy greens, and orchard fruits for daily family meals.
- By certification standard: USDA Organic Certified products represent a projected 62.0% in 2026 owing to bilateral equivalency agreements and mandatory electronic import certificates.
- By distribution channel: Specialty Organic Grocers account for an anticipated 54.0% in 2026 supported by dedicated natural-store curation and local farm sourcing.
- By storage format: Fresh and Chilled items secure an estimated 56.0% in 2026 through high-velocity refrigerated produce, dairy, and pasture-raised egg cases.
- By buyer type: Household Retail Consumers command a projected 64.0% in 2026 driven by weekly supermarket basket upgrades and infant nutrition spending.
Regional Highlights
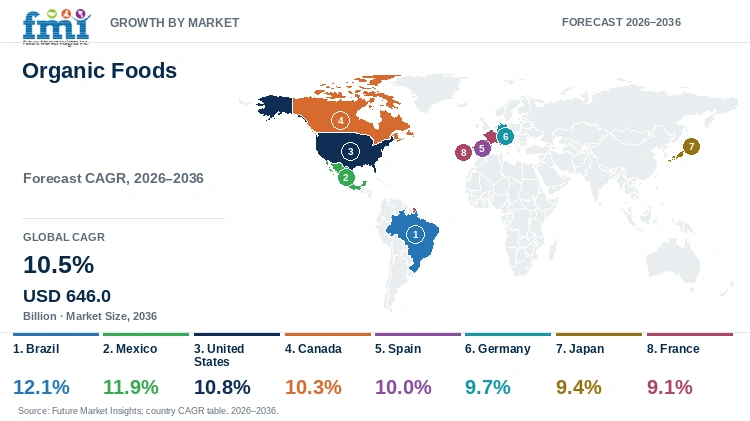
- Top national expansion: Brazil leads national growth projections at a 12.1% CAGR through 2036 under expanding bio-input farming programs and urban natural grocery chains.
- Broader country progression: Mexico tracks at an 11.9% CAGR ahead of the United States at 10.8% and Canada at 10.3%, while Spain advances at 10.0% and Japan records a 9.4% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Organic Foods Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 215.0 billion |
| Estimated Market Size in 2026 | USD 238.0 billion |
| Projected Market Size by 2036 | USD 646.0 billion |
| CAGR, 2026 to 2036 | 10.5% |
| Added Revenue, 2026 to 2036 | USD 408.0 billion |
Supermarket chains and natural food processors face persistent raw commodity shortages when conventional acreage takes thirty-six months to qualify for organic certification. When food brands rely on spot-market brokers for certified grains or fruit purees, seasonal yield drops trigger retail out-of-stocks and steep contract price spikes. In February 2026, the Research Institute of Organic Agriculture FiBL documented in its 27th edition yearbook that global certified organic farmland approached 99 million hectares managed by 4.8 million farmers across more than 180 countries [3]. Consequently, multinational grocery buyers pair direct grower transition subsidies with healthy food merchandising to stabilize year-round shelf availability.
Certified Farmland and Retail Basket Sizing
Table 2: Certified Farmland and Retail Basket Sizing for the Organic Foods Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 215.0 | 238.0 | 646.0 |
| Global certified organic farmland (million hectares, FiBL basis) | 98.9 to 101.5 | 103.0 to 106.5 | 165.0 to 182.0 |
| Certified organic agricultural producers (million farms, FiBL basis) | 4.8 to 4.9 | 5.0 to 5.2 | 7.4 to 8.1 |
| Average retail organic price premium over conventional (%) | 18.0% to 24.0% | 17.0% to 22.5% | 12.0% to 16.5% |
Maintaining unbroken segregation between certified organic harvests and conventional crops requires dedicated cleaning protocols across grain elevators, dairy tankers, and cold-storage depots. According to Eurostat organic farming statistics, certified organic cultivation covered 16.9 million hectares across the European Union, representing 10.5% of total utilized agricultural area along with 5.4 million organically reared bovine animals [4]. This expanding European and North American farm base enables beverage processors to scale organic beverages without relying solely on fragmented spot imports.
Per Capita & Certified Store Line Sizing
Table 3: Per Capita and Retail Store Spending Indicators for the Organic Foods Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Global organic food spend per capita (USD) | 26.2 | 28.7 | 71.8 |
| U.S. certified organic food sales (USD billion, OTA basis) | 70.1 | 75.0 to 76.5 | 162.0 to 175.0 |
| Private-label share of supermarket organic volume (%) | 36.0% to 39.0% | 38.0% to 41.5% | 48.0% to 53.0% |
Table 4: Retail Grocery & Channel Spending Indicators for the Organic Foods Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 238.0 billion | 2026 global revenue baseline |
| U.S. total certified organic sales, 2025 | USD 76.6 billion | Organic Trade Association March 2026 Market Report (USD 70.1B food) |
| EU utilized agricultural area under organic farming | 18.08 million hectares | Agence BIO 2026 EU report (11.1% of EU UAA; 438,033 farms) |
| Specialty Organic Grocers channel revenue, 2026 | USD 128.5 billion | 54.0% distribution channel allocation |
Transitioning conventional farmland to certified organic status requires growers to absorb three full years of lower crop yields before harvesting a single premium-priced bushel. As documented in a January 2026 agroecological review in Frontiers in Plant Science, U.S. certified organic cultivation exceeds 2 million hectares and achieves 22% to 35% higher farm profitability despite 10% to 18% lower yields while European Union policy targets 25% organic farmland by 2030 [5]. Ingredient buyers formulating organic milk powder and infant nutrition lines therefore sign multi-year forward purchase agreements that guarantee farmgate floor prices during conversion.
Analyst Perspective
"Grocery retailers no longer treat certified organic food as a niche perimeter display; they manage it as a core private-label loyalty engine. Food manufacturers and cooperatives that fund multi-year farmer transition pools and automate farm-to-shelf audit trails will win permanent supermarket shelf allocation as enforcement tightens."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Organic Foods Market segmented?
The organic foods market is segmented by product category, certification standard, distribution channel, storage format, and buyer type.
By product category: Organic Fresh Fruits and Vegetables, Organic Dairy Products and Eggs, Organic Packaged Grocery and Cereals, Organic Beverages Tea Coffee and Juices, and Organic Meat Poultry and Seafood.
By certification standard: USDA Organic Certified, EU Organic Leaf Certified, Demeter Biodynamic Certified, and JAS and National Equivalency Seals.
By distribution channel: Specialty Organic Grocers, Mainstream Supermarket Aisles, Farmers Markets and Community Supported Agriculture, and Online Subscription Boxes.
By storage format: Fresh and Chilled, Shelf-Stable Ambient, Frozen Certified, and Bulk Dry and Unpackaged.
By buyer type: Household Retail Consumers, Commercial Foodservice and Restaurants, Institutional and School Catering, and Artisanal Bakeries and Co-Packers.
Why do Organic Fresh Fruits and Vegetables lead the product category?
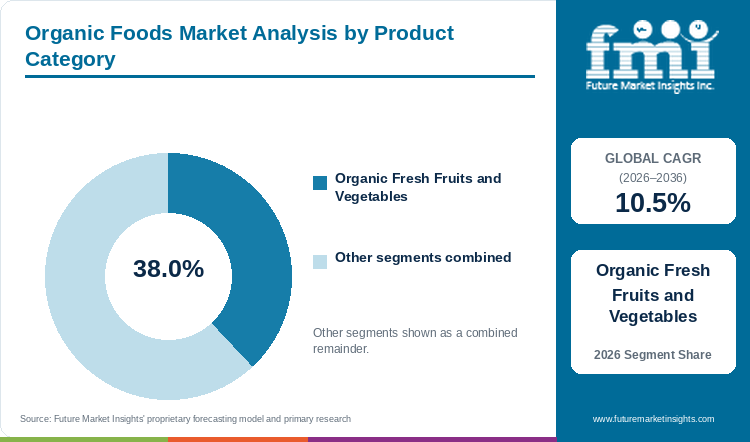
Organic Fresh Fruits and Vegetables hold an estimated 38.0% of product category demand in 2026, anchored by high weekly household basket penetration across berries, salads, and orchard fruits.
Table 5: Product Category Share for the Organic Foods Market (percentage share), 2026
| Product Category | Share (2026) |
|---|---|
| Organic Fresh Fruits and Vegetables | 38.0% |
| Other Segments Combined | 62.0%* |
| Total | 100.0% |
Table 6: Product Category Leadership and Market Growth for the Organic Foods Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.5% |
| Leading Segment | Organic Fresh Fruits and Vegetables |
Organic Fresh Fruits and Vegetables encompassing berries, leafy salad greens, and orchard crops serve as the primary gateway category for households reducing dietary pesticide exposure. Retailers position certified produce islands at store entrances to drive weekly foot traffic, while beverage formulators source certified orchard surpluses for organic tea and botanical infusions. This produce leadership is supported by official figures from the USDA Economic Research Service in September 2026, which confirmed that fresh produce accounted for 33% of total U.S. organic food retail sales across 7.2 million certified organic acres [6]. However, absence of post-harvest synthetic fungicides shortens ambient shelf life and requires rapid refrigerated transit from packinghouses to grocery wet racks.
- Within the product category segment, fresh organic produce is projected to account for a leading 38.0% share in 2026, driven by weekly household repurchases of berries, salads, and citrus.
- While fresh produce retains the largest category share through 2036, organic dairy, pasture-raised eggs, and high-protein packaged groceries are anticipated to post faster relative volume gains as families expand clean-label cooking across all meal occasions.
What sustains USDA Organic Certified leadership in the certification standard segment?
USDA Organic Certified products represent a projected 62.0% of the certification standard category in 2026, supported by federal Strengthening Organic Enforcement traceability and bilateral trade equivalency.
USDA Organic Certified labeling governs domestic and imported products that verify 95% or higher certified organic agricultural content and zero synthetic fertilizers or genetically engineered traits. Multinational food brands and co-packers supplying organic snack food lines favor USDA certification since bilateral equivalency arrangements with Canada, the European Union, and Japan streamline cross-border customs clearance without duplicate farm inspections. At the same time, stricter supply-chain audit mandates require formerly exempt brokers, grain traders, and importers to obtain independent certification, raising administrative compliance costs for smaller ingredient handlers.
- In 2026, USDA Organic Certified products are anticipated to capture 62.0% of global certification standard demand, reflecting unmatched consumer seal recognition and broad international trade equivalency.
- Regulatory records from the USDA Agricultural Marketing Service confirm that the National Organic Program Strengthening Organic Enforcement framework mandates electronic NOP Import Certificates for all certified shipments entering the United States to eliminate supply-chain fraud [7].
How do Specialty Organic Grocers lead the distribution channel category?
Specialty Organic Grocers account for an anticipated 54.0% of distribution channel volume in 2026, driven by dedicated natural store curation, bulk bins, and direct regional farm sourcing.
Specialty Organic Grocers including dedicated natural food chains and independent organic cooperatives lead distribution by offering full-basket certified assortments, bulk grain bins, and direct local farm partnerships that conventional supermarkets rarely match in depth. Parents shopping for bric organic baby food and allergen-free pantry staples rely on specialty natural chains to vet third-party certifications and regenerative farming credentials before granting shelf space. Financial disclosures from Sprouts Farmers Market, Inc. in February 2026 confirm this channel momentum, documenting that full-year 2025 net sales rose 14% with 7.3% comparable store sales growth and 37 new store openings across 477 locations [8]. Even so, specialty retailers face intense price competition as mass discount grocers and warehouse clubs expand lower-priced private-label organic staples.
- By distribution channel, demand through Specialty Organic Grocers is estimated to reach 54.0% of total category share in 2026, supported by high-margin perishables curation and loyal health-conscious shopper traffic.
- Over the 2026 to 2036 forecast window, mainstream supermarket chains and cold-chain online subscription boxes are projected to narrow the channel gap by bundling private-label organic produce with home delivery.
Why does Fresh and Chilled lead the storage format category?
Fresh and Chilled formats secure an estimated 56.0% of storage format value in 2026, supported by perimeter-aisle produce, pasture-raised dairy, and organic egg turnover.
Fresh and Chilled formats covering field-packed produce, pasteurized grass-fed milk, and refrigerated meats dominate consumer baskets because shoppers associate chilled perimeter aisles with minimal processing and peak nutrient retention. Unlike shelf-stable canned goods that undergo high-heat retort sterilization, chilled organic dairy and produce preserve natural flavor profiles while requiring continuous temperature control from farm cooling sheds to supermarket display cases. High refrigeration electricity costs and tighter sell-by dates nevertheless force retailers to use automated inventory forecasting to minimize shrink.
- Strong weekly perimeter-aisle turnover places Fresh and Chilled items on course to hold an estimated 56.0% share of the storage format category in 2026.
- Product rollouts from farmer-owned cooperatives reinforce this chilled format preference, as seen in June 2026 when Organic Valley launched individually wrapped pasture-raised organic Cheese Snack Sticks delivering 5 grams of protein per serving from over 1,500 organic family farms [9].
What gives Household Retail Consumers the leading position in buyer type?
Household Retail Consumers command a projected 64.0% of buyer type share in 2026, anchored by routine family supermarket replenishment and clean-label infant nutrition spending.
Household Retail Consumers represent the foundational revenue engine of the organic sector as parents and health-focused adults convert everyday breakfast cereals, milk, and cooking oils to certified organic equivalents. Major packaged food manufacturers are reformulating flagship household brands to capture this retail buyer pool, evidenced in November 2025 when General Mills, Inc. quadrupled its use of perennial Kernza grain across four Cascadian Farm organic cereals sold at Whole Foods and Sprouts [10]. During periods of elevated food inflation, household buyers occasionally trade down from branded organic snacks to retailer private labels, keeping promotional pricing discipline essential for national brands.
- Household Retail Consumers are predicted to secure 64.0% of buyer type demand in 2026, anchored by routine family grocery replenishment and clean-label infant and child nutrition priorities.
- Institutional school-lunch procurement programs and commercial restaurant chains are forecast to expand their buyer share through 2036 as municipal food charters set minimum organic sourcing targets.
What are the drivers, restraints, and opportunities in the Organic Foods Market?
In the organic foods market, expanding supermarket private-label ranges and pesticide-residue avoidance are projected to drive adoption, while three-year farm conversion timelines restrain raw supply and regenerative organic standards create premium growth avenues.
- Driver: Expanding supermarket private-label organic ranges and heightened consumer scrutiny of synthetic pesticide residues accelerate weekly household conversion across produce, dairy, and pantry staples.
- Restraint: Mandatory thirty-six-month farmland transition periods, rising certified organic livestock feed costs, and strict third-party audit fees inflate retail unit prices relative to conventional groceries.
- Opportunity: Integrating Regenerative Organic Certified soil-health standards and perennial grain rotations creates premium brand differentiation and long-term grower supply security.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Household grocery buyers across North America, Europe, and East Asia are shifting preventative health spending into the supermarket aisle by replacing conventional produce and dairy with third-party certified organic alternatives. When retail chains expand private-label organic offerings at price premiums under 15% above conventional equivalents, middle-income families move from occasional berry purchases to full-basket adoption across milk, eggs, and baby food. Livestock producers scaling organic feed rations also enable dairy and poultry cooperatives to meet surging supermarket contract volumes. Empirical panel findings published in the journal Sustainability in August 2026 across 41 European countries confirm this mechanism, showing that mean organic retail sales share rose from 1.42% to 4.49% while per capita spending climbed from EUR 25.82 to EUR 87.60 alongside certified processor growth [11]. This combination of trusted government seals and broader supermarket shelf space continues driving category sales growth through 2036.
Risk Assessment of the Organic Foods Market: Operational and Formulation Friction
Three-year agronomic transition timelines and elevated organic livestock feed costs represent the primary operational barriers restraining faster volume expansion across the global organic supply chain. Farmers converting conventional cropland must manage weeds and soil fertility without synthetic herbicides or ammonia fertilizers for thirty-six months while selling transitional harvests at conventional commodity prices. In the dairy and organic meat sectors, 100% certified organic forage and grain requirements expose cooperatives to severe margin squeezes whenever drought reduces organic corn and soybean yields. In February 2026, Arla Foods amba documented in its Consolidated Annual Report 2025 that while European retail demand for organic dairy strengthened, maintaining farmer milk-pool incentives required dedicated sustainability premiums to offset higher on-farm organic production costs [12]. These structural farm-level cost pressures limit aggressive retail price reductions in price-sensitive emerging markets.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Food manufacturers and dairy processors are capturing new demand avenues by combining certified organic credentials with high-protein, gut-health, and regenerative agriculture claims in ready-to-consume formats. Younger Millennial and Gen Z shoppers actively seek certified organic yogurts, plant-based oat beverages, and organic drinks that deliver functional protein and probiotic benefits without artificial stabilizers or refined sugars. Corporate financial disclosures from Danone SA in February 2026 substantiate this opportunity, showing that full-year 2025 sales rose 4.5% on a like-for-like basis to EUR 27,283 million with +2.7% volume/mix growth led by high-protein dairy, plant-based Alpro and Silk beverages, and specialized nutrition [13]. Brands that pair certified organic traceability with functional nutrition and regenerative carbon metrics are well positioned to command premium shelf facings across modern retail and quick-commerce channels.
Organic Foods Market by Country (2026 to 2036)
FMI country modeling indicates that Brazil leads organic foods expansion at a 12.1% CAGR through 2036, while France advances at a 9.1% CAGR. Commercial adoption across Latin American agro-export and urban retail hubs, North American natural supermarket corridors, and European Union green-deal farm networks depends on domestic certification infrastructure and private-label grocery pricing.
Table 7: Country CAGR and Primary Growth Levers for the Organic Foods Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 12.1% | National bio-input farming support, USD 248B food processing base, and urban specialty retail |
| Mexico | 11.9% | USDA/LPO export horticulture base and modern supermarket organic assortment growth |
| United States | 10.8% | USD 70.1B organic food baseline, natural supermarket chains, and USDA SOE enforcement |
| Canada | 10.3% | Updated March 2026 national organic standards and Prairie organic oat and pulse processing |
| Spain | 10.0% | 2.94M ha #1 EU organic crop area and supermarket private-label health assortment integration |
| Germany | 9.7% | Record EUR 17B–18.7B organic retail sales and deep discounter private-label penetration |
| Japan | 9.4% | MAFF Midori Green Food System targets and expanded JAS bilateral equivalency agreements |
| France | 9.1% | 2.71M ha AB-certified farm scale (61,877 farms) and Egalim 20% institutional catering mandates |
Brazil Organic Foods Market Outlook (2026 to 2036)
Demand for organic foods in Brazil is projected to expand at a leading 12.1% CAGR between 2026 and 2036 as urban supermarket chains and specialty natural stores scale certified tropical fruit, coffee, and grain assortments. What distinguishes Brazil from mature Northern Hemisphere markets is the rapid formalization of domestic Participatory Guarantee Systems and federal bio-input agriculture programs that lower certification barriers for smallholder cooperatives. In June 2026, the USDA Foreign Agricultural Service reported in its Brazil Exporter Guide Annual that Brazil's food processing industry expanded 8% in 2025 while modern supermarket chains and premium consumer-oriented food imports scaled across 40 million middle- and upper-income consumers [14]. High domestic logistics costs across interior states nevertheless compel Brazilian processors to concentrate chilled organic dairy distribution in southeastern metropolitan corridors.
Key takeaway: In Brazil, national bio-input farming support and urban specialty retail expansion are projected to drive a leading 12.1% CAGR through 2036.
Mexico Organic Foods Market Outlook (2026 to 2036)
Mexico's organic food sector is anticipated to advance at an 11.9% CAGR from 2026 to 2036, supported by dual momentum in export-certified horticulture and rising domestic middle-class supermarket adoption. Compared with global markets that rely heavily on imported off-season produce, Mexico operates vast USDA- and LPO-certified acreage of avocados, berries, and coffee that increasingly supply domestic gourmet grocers in Mexico City, Monterrey, and Guadalajara. According to the USDA Foreign Agricultural Service Mexico Exporter Guide Annual published in July 2026, U.S. agricultural exports to Mexico reached a record high in 2025 as consumer-oriented food shipments rose 13% across fresh vegetables, food preparations, and modern retail chains [15]. Local processors still face fragmented cold-chain warehousing outside major highway corridors, prompting co-packers to prioritize shelf-stable organic tortillas, salsas, and ancient-grain snacks.
Key takeaway: In Mexico, dual export-accredited produce supply and modern club-store expansion are anticipated to sustain an 11.9% CAGR through 2036.
United States Organic Foods Market Outlook (2026 to 2036)
In the United States, organic foods adoption is estimated to progress at a 10.8% CAGR through 2036 across the world's largest single-country certified retail grocery base. What sets the United States apart from smaller national markets is the scale of dedicated natural supermarket chains operating alongside mainstream grocery private labels under strict federal Strengthening Organic Enforcement import audits. Official agricultural census records from the USDA National Agricultural Statistics Service documented that U.S. farmgate organic product sales jumped 32% across 17,048 certified NOP farms led by California's premier organic harvest base even as transitioning acreage tightened [16]. Domestic dairy and poultry brands must still navigate elevated organic feed grain prices when regional droughts tighten Midwest corn and soybean supplies.
Key takeaway: In the United States, nationwide natural grocery chains and strict federal supply-chain enforcement are estimated to support a 10.8% CAGR through 2036.
Canada Organic Foods Market Outlook (2026 to 2036)
Canadian demand for organic foods is forecast to grow at a 10.3% CAGR over the 2026 to 2036 period, anchored by seamless U.S.-Canada organic equivalency trade and high household penetration in British Columbia, Ontario, and Quebec. Because severe winter climates limit year-round domestic fresh fruit and vegetable harvests, Canadian grocers combine Prairie-grown organic oats, pulses, and flaxseed with year-round certified produce imports from the United States and Mexico. In July 2026, the USDA Foreign Agricultural Service confirmed in its Canada FAIRS Country Report Annual that updated Canadian national organic standards were published in March 2026 to govern domestic and imported organic food labeling [17]. Provincial inter-market freight distances and bilingual packaging compliance under Safe Food for Canadians Regulations remain key operational requirements for entering brands.
Key takeaway: In Canada, updated March 2026 national organic standards and strong Prairie organic grain processing are forecast to drive a 10.3% CAGR through 2036.
Spain Organic Foods Market Outlook (2026 to 2036)
Spain's organic foods market is projected to record a 10.0% CAGR between 2026 and 2036 as Europe's leading producer of certified organic olive oil, citrus, and greenhouse vegetables converts more domestic shoppers into regular buyers. Historically, Spanish organic growers exported the vast majority of their harvests to Northern Europe, but domestic supermarket leaders and regional chains are now embedding EU Organic Leaf products directly into value-for-money private-label ranges. In October 2026, USDA Foreign Agricultural Service analysts documented in the Spain Retail Foods Annual that Spain's economy expanded nearly 3% in 2025 while private-label products surpassed half of total grocery basket value as retailers streamlined assortments toward health-oriented items [18]. Recurring Iberian drought cycles and irrigation restrictions in Andalusia and Murcia remain the primary supply hurdles requiring drip-irrigation investment.
Key takeaway: In Spain, private-label supermarket integration and Europe's largest Mediterranean organic crop base are projected to sustain a 10.0% CAGR.
Germany Organic Foods Market Outlook (2026 to 2036)
Commercial sales of organic foods in Germany are slated to expand at a 9.7% CAGR across the 2026 to 2036 horizon, supported by universal Bio-Siegel label recognition and deeply entrenched discounter and supermarket organic assortments. Germany differs from Southern European export hubs because national discount chains, full-service supermarkets, and specialist Bio-supermarkets compete aggressively on everyday organic dairy, bread, and infant nutrition pricing. In January 2026, the USDA Foreign Agricultural Service reported that German organic retail sales rose 5.7% to a record annual turnover in 2024 and expanded another 10.0% in 2025 across an 11.5% national organic farmland share as discount supermarkets widened private-label dry goods [19]. Tight retail margin negotiations by German buying groups require domestic and foreign organic processors to maintain high automated packaging efficiency.
Key takeaway: In Germany, record national organic retail turnover and deep discounter private-label penetration are slated to support a 9.7% CAGR.
Japan Organic Foods Market Outlook (2026 to 2036)
In Japan, organic foods demand is predicted to advance at a 9.4% CAGR from 2026 to 2036 as the Ministry of Agriculture, Forestry and Fisheries executes its Green Food System Strategy (Midori) to expand domestic organic farmland and school-lunch procurement. Compared with Western markets where large suburban hypermarkets dominate, Japanese adoption centers on urban specialty supermarkets, cooperative home-delivery networks (Seikatsu Club and Pal System), and JAS-certified green tea, soy, and rice staples. In January 2026, the USDA Foreign Agricultural Service documented in its Japan FAIRS Country Report Annual that expanded bilateral organic equivalency agreements now include alcoholic beverages such as organic grape wines alongside plant and processed foods [20]. Small average farm plot sizes and an aging rural agricultural workforce still constrain domestic Japanese organic crop supply, sustaining reliance on certified bulk grain and soybean imports.
Key takeaway: In Japan, Midori Green Food System policy targets and expanded JAS bilateral equivalency agreements are predicted to drive a 9.4% CAGR.
France Organic Foods Market Outlook (2026 to 2036)
French demand for organic foods is anticipated to grow at a 9.1% CAGR through 2036 across hypermarkets, dedicated Agriculture Biologique (AB) specialty stores, and public catering programs. What differentiates France within Western Europe is the combination of a massive domestic organic farm base with statutory Egalim public-procurement mandates requiring collective school and hospital canteens to source at least 20% certified organic ingredients. In February 2026, Agence BIO documented in its 2026 European Union sector report that France cultivated 2,711,567 hectares of organic farmland across 61,877 certified farms (10.2% of national utilized agricultural area, led by Occitanie at 22%) within an 18.08-million-hectare EU organic sector [21]. Retail price inflation between 2023 and 2025 prompted French hypermarkets to rationalize slow-moving niche SKUs and focus shelf space on core everyday organic private-label staples.
Key takeaway: In France, 2.71 million hectares of AB-certified farmland and statutory Egalim catering mandates are anticipated to sustain a 9.1% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Organic Foods Market?
Organic Valley, The Hain Celestial Group, Inc., General Mills, Inc., Danone SA, Amy's Kitchen Inc., SunOpta Inc., Whole Foods Market Services Inc., United Natural Foods, Inc., Sprouts Farmers Market, Inc., and Arla Foods amba are the notable companies in the organic foods market.
Competitive positioning in the organic foods industry divides multi-category branded organic processors, farmer-owned dairy and plant-based co-manufacturers, and specialized natural retail and wholesale distribution leaders. General Mills, Inc., Danone SA, The Hain Celestial Group, Inc., and Amy's Kitchen Inc. scale branded organic cereals, dairy, baby food, and prepared meals across international grocery chains. Organic Valley, SunOpta Inc., and Arla Foods amba anchor certified raw milk pools and aseptic plant-based manufacturing, while Whole Foods Market Services Inc., Sprouts Farmers Market, Inc., and United Natural Foods, Inc. control specialized retail and cold-chain wholesale distribution.
- Multi-Category Branded Organic Processors: Danone SA, General Mills, Inc., Amy's Kitchen Inc., and The Hain Celestial Group, Inc. supply certified cereals, yogurts, baby food, and entrees.
- Farmer Cooperatives and Plant-Based Co-Manufacturers: Organic Valley, SunOpta Inc., and Arla Foods amba manage certified organic dairy farm pools and aseptic fruit and plant-based beverage processing plants.
- Specialized Organic Retailers and Wholesale Distributors: Whole Foods Market Services Inc., Sprouts Farmers Market, Inc., and United Natural Foods, Inc. operate dedicated organic grocery stores, private-label programs, and national cold-chain distribution centers.
Competitive Benchmarking: Organic Foods Market
Table 8: Competitive Benchmarking for the Organic Foods Market (qualitative capability ratings), 2026
| Company | Certified Farm-Pool Traceability | Cold-Chain & Processing Scale | Private-Label & Retail Reach | Geographic Reach |
|---|---|---|---|---|
| Organic Valley | High | High | Medium | United States and Canada; cooperative of 1,500+ certified organic family farms |
| The Hain Celestial Group, Inc. | Medium | High | High | North America and Europe; Earth's Best Organic, Celestial Seasonings, Greek Gods |
| General Mills, Inc. | High | High | High | Global CPG network; Annie's Homegrown and Cascadian Farm organic cereals and snacks |
| Danone SA | High | High | High | 120+ countries; EUR 27.28B FY25 sales across Essential Dairy, Alpro, Silk, and nutrition |
| Amy's Kitchen Inc. | High | High | Medium | North America and Western Europe; dedicated organic vegetarian prepared meals and soups |
| SunOpta Inc. | High | High | High | 7 North American facilities; Omak USD 25M organic fruit snack line expansion in June 2026 |
| Whole Foods Market Services Inc. | High | Medium | High | 545+ stores across U.S., Canada, and U.K.; 365 by Whole Foods Market organic private label |
| United Natural Foods, Inc. | Medium | High | High | North American wholesale natural/organic cold-chain distributor serving 30,000+ locations |
| Sprouts Farmers Market, Inc. | Medium | Medium | High | 477+ U.S. specialty natural stores across 24 states; USD 8.8B FY2025 net sales |
| Arla Foods amba | High | High | High | Northern Europe and global export; world's largest cooperative organic dairy milk pool |
Key Developments in the Organic Foods Market
- The Hain Celestial Group, Inc. reported fiscal fourth-quarter and full-year 2026 financial results on September 14, 2026, recording 2% year-over-year organic net sales growth in North America during the fourth quarter driven by yogurt and meal preparation alongside gross margin and adjusted EBITDA margin expansion [22].
- United Natural Foods, Inc. convened more than 1,400 grocery retail representatives and 715 suppliers at its 2026 Holiday and Winter Selling Show on June 25, 2026 to showcase nearly 70 new-to-market brands and honor suppliers including Organic Valley and Frontier Co-op [23].
- SunOpta Inc. published its 2025 Sustainability Report on April 29, 2026, documenting 50 own-branded certified organic products, USD 30.8 million in non-GMO-labeled revenue, and 100% sourcing from GFSI-certified suppliers [24].
Key Players in the Organic Foods Market
Multi-Category Branded Organic Processors
- General Mills, Inc.
- Danone SA
- The Hain Celestial Group, Inc.
- Amy's Kitchen Inc.
Farmer Cooperatives and Plant-Based Co-Manufacturers
- Organic Valley
- SunOpta Inc.
- Arla Foods amba
- Whole Foods Market Services Inc.
Specialized Organic Retailers and Wholesale Distributors
- Sprouts Farmers Market, Inc.
- United Natural Foods, Inc.
Organic Foods Market - Report Scope
Table 9: Report Scope for the Organic Foods Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Category; Certification Standard; Distribution Channel; Storage Format; Buyer Type |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial retail and foodservice sales of third-party certified organic fresh fruits and vegetables, dairy and eggs, packaged groceries and cereals, organic non-alcoholic beverages (tea, coffee, juices, plant-based milks), and organic meat, poultry, and seafood meeting statutory national standards (USDA NOP, EU 2018/848, JAS, COR). Category Scope Note: Excludes non-food organic textiles, cosmetics, dietary supplements, pet food, and uncertified natural or conventional clean-label products. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, Canada, Spain, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Organic Valley, The Hain Celestial Group, Inc., General Mills, Inc., Danone SA, Amy's Kitchen Inc., SunOpta Inc., Whole Foods Market Services Inc., United Natural Foods, Inc., Sprouts Farmers Market, Inc., Arla Foods amba |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Organic Foods Market - Research Methodology
Table 10: Research Methodology for the Organic Foods Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with supermarket organic category directors, USDA- and EU-accredited certifying agents, farmer-owned dairy cooperative managers, and aseptic plant-based co-manufacturers to validate retail price premiums and conversion yields. |
| Secondary Research | Analysis of FiBL/IFOAM World of Organic Agriculture 2026 yearbook data, Organic Trade Association 2026 Market Report disclosures, Eurostat and Agence BIO organic farming registries, USDA ERS/NASS/FAS GAIN country reports, and corporate annual filings. |
| Market Sizing and Forecasting | Top-down global certified organic food and beverage retail baselines reconciled against bottom-up certified agricultural acreage (99M+ hectares), active organic operator counts (4.8M+ producers), and supermarket private-label basket penetration from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight certified national farmland conversion, bilateral organic equivalency agreements, public catering mandates (such as France Egalim), and natural grocery store openings across eight national markets. |
| Operational Benchmark Traceability | Certified farmland, per capita spend, and retail channel indicators in Tables 2, 3, and 4 trace to FiBL 2026 global acreage statistics, Organic Trade Association March 2026 U.S. retail sales, and Agence BIO / Eurostat UAA registries. |
| Data Triangulation and Validation | Revenue estimates isolate third-party certified organic food and beverage products while strictly excluding non-food organic textiles, personal care items, and uncertified natural or conventional clean-label groceries. |
Organic Foods Market by Segments
Organic Foods Market segmented by Product Category:
- Organic Fresh Fruits and Vegetables
- Organic Dairy Products and Eggs
- Organic Packaged Grocery and Cereals
- Organic Beverages Tea Coffee and Juices
Organic Foods Market segmented by Certification Standard:
- USDA Organic Certified
- EU Organic Leaf Certified
- Demeter Biodynamic Certified
- JAS and National Equivalency Seals
Organic Foods Market segmented by Distribution Channel:
- Specialty Organic Grocers
- Mainstream Supermarket Aisles
- Farmers Markets and Community Supported Agriculture
- Online Subscription Boxes
- Organic Meat Poultry and Seafood (Product Category Sub-Segment)
Organic Foods Market segmented by Storage Format:
- Fresh and Chilled
- Shelf-Stable Ambient
- Frozen Certified
- Bulk Dry and Unpackaged
Organic Foods Market segmented by Buyer Type:
- Household Retail Consumers
- Commercial Foodservice and Restaurants
- Institutional and School Catering
- Artisanal Bakeries and Co-Packers
Organic Foods Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Organic Trade Association. (2026, March 4). U.S. Organic Marketplace Achieved Significant Growth in 2025. Organic Trade Association Press Releases.
- [2] SunOpta Inc. (2026, June 1). One More Line, Lots More Snacks: SunOpta Expands Production in Omak. SunOpta Inc. Newsroom.
- [3] Willer, H., Schlatter, B., & Travnicek, J. (Eds.). (2026, February 10). The World of Organic Agriculture: Statistics and Emerging Trends 2026 (27th Edition). Research Institute of Organic Agriculture FiBL and IFOAM - Organics International.
- [4] Eurostat. (2024, June). Developments in organic farming. European Commission Eurostat Statistics Explained (ISSN 2443-8219).
- [5] Meshram, S., Mansor, H. B., & Adhikari, T. B. (2026, January 9). Recent advances in organic agriculture: innovations, challenges, and opportunities. Frontiers in Plant Science, 16, 1681928 (PubMed PMID 41584672).
- [6] USDA Economic Research Service. (2026, September 16). Organic Agriculture. U.S. Department of Agriculture Economic Research Service.
- [7] USDA Agricultural Marketing Service. (2025, October 20). National Organic Program. U.S. Department of Agriculture Agricultural Marketing Service.
- [8] Sprouts Farmers Market, Inc. (2026, February 19). Sprouts Farmers Market, Inc. Reports Fourth Quarter and Full Year 2025 Results. Sprouts Farmers Market Investor Relations.
- [9] Organic Valley. (2026, June 26). Organic Valley Elevates On-the-Go Snacking with New Cheese Snack Sticks. Organic Valley Cooperative Newsroom.
- [10] General Mills, Inc. (2025, November 10). General Mills Accelerates Kernza Market for U.S. Organic Farmers with New Cascadian Farm Cereals. General Mills Corporate Press Releases.
- [11] Santos, J., Jesus, M., & Mata, F. (2026, August 14). Certification and Market Development in Sustainable Food Systems: Evidence from Organic Agriculture in Europe. Sustainability, 18(16), 8333.
- [12] Arla Foods amba. (2026, February 25). Arla Foods Consolidated Annual Report 2025. Arla Foods Corporate Investor Publications.
- [13] Danone SA. (2026, February 19). 2025: Another year of strong delivery. Danone Group Newsroom.
- [14] USDA Foreign Agricultural Service. (2026, June 30). Brazil: Exporter Guide Annual. U.S. Department of Agriculture GAIN Report BR2026-0027.
- [15] USDA Foreign Agricultural Service. (2026, July 7). Mexico: Exporter Guide Annual. U.S. Department of Agriculture GAIN Report MX2026-0034.
- [16] USDA National Agricultural Statistics Service. (2024, September 12). 2022 Census of Agriculture Highlights: Organic Agriculture. U.S. Department of Agriculture NASS (ACH22-14).
- [17] USDA Foreign Agricultural Service. (2026, July 2). Canada: FAIRS Country Report Annual. U.S. Department of Agriculture GAIN Report CA2026-0010.
- [18] USDA Foreign Agricultural Service. (2026, October 1). Spain: Retail Foods Annual. U.S. Department of Agriculture GAIN Report SP2026-0019.
- [19] USDA Foreign Agricultural Service. (2026, January 29). Germany: Large Retail Chains Support Record Year for German Organic Sales. U.S. Department of Agriculture GAIN Report GM2026-0003.
- [20] USDA Foreign Agricultural Service. (2026, January 7). Japan: FAIRS Country Report Annual. U.S. Department of Agriculture GAIN Report JA2025-0065.
- [21] Agence BIO. (2026, February 5). Organic Sector in the European Union (2026 Edition). Agence Francaise pour le Developpement et la Promotion de l'Agriculture Biologique.
- [22] The Hain Celestial Group, Inc. (2026, September 14). Hain Celestial Reports Fiscal Fourth Quarter and Fiscal Year 2026 Financial Results. The Hain Celestial Group Investor Relations.
- [23] United Natural Foods, Inc. (2026, June 25). United Natural Foods Spotlights Top Industry Trends and Innovations to Help Grocery Retailers Differentiate this Holiday and Winter Selling Season. United Natural Foods Investor Relations.
- [24] SunOpta Inc. (2026, April 29). SunOpta Marks Another Year of Progress with 2025 Sustainability Report. SunOpta Inc. Corporate Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the organic foods market in 2026 and what is forecast for 2036?
- Which retail private-label and pesticide-avoidance factors support demand for organic foods?
- Why do Organic Fresh Fruits and Vegetables lead the product category?
- Why does USDA Organic Certified lead the certification standard category globally?
- How do growth rates differ across Brazil, Mexico, the United States, and Canada?
- Which leading companies manage certified organic farm pools versus natural retail chains today?
- What limits farmland conversion or raises organic livestock feed costs in the organic foods market?
- What should grocery buyers evaluate before signing multi-year organic co-packing contracts?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Category, 2026 to 2036
- Organic Fresh Fruits and Vegetables
- Organic Dairy Products and Eggs
- Organic Packaged Grocery and Cereals
- Organic Beverages Tea Coffee and Juices
- Y-o-Y Growth Trend Analysis By Product Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Category, 2026 to 2036
- Global Market Analysis and Forecast, By Certification Standard, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Certification Standard, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Certification Standard, 2026 to 2036
- USDA Organic Certified
- EU Organic Leaf Certified
- Demeter Biodynamic Certified
- JAS and National Equivalency Seals
- Y-o-Y Growth Trend Analysis By Certification Standard, 2021 to 2025
- Absolute $ Opportunity Analysis By Certification Standard, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty Organic Grocers
- Mainstream Supermarket Aisles
- Farmers Markets and Community Supported Agriculture
- Online Subscription Boxes
- Organic Meat Poultry and Seafood (Product Category Sub-Segment)
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Storage Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Storage Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Storage Format, 2026 to 2036
- Fresh and Chilled
- Shelf-Stable Ambient
- Frozen Certified
- Bulk Dry and Unpackaged
- Y-o-Y Growth Trend Analysis By Storage Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Storage Format, 2026 to 2036
- Global Market Analysis and Forecast, By Buyer Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Buyer Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Buyer Type, 2026 to 2036
- Household Retail Consumers
- Commercial Foodservice and Restaurants
- Institutional and School Catering
- Artisanal Bakeries and Co-Packers
- Y-o-Y Growth Trend Analysis By Buyer Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Buyer Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Category
- By Certification Standard
- By Distribution Channel
- By Storage Format
- By Buyer Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Organic Valley
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Hain Celestial Group, Inc.
- General Mills, Inc.
- Danone SA
- Amy's Kitchen Inc.
- SunOpta Inc.
- Whole Foods Market Services Inc.
- United Natural Foods, Inc.
- Sprouts Farmers Market, Inc.
- Arla Foods amba
- Organic Valley
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Certification Standard, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Storage Format, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Buyer Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Category
- Figure 6: Global Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Certification Standard
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Storage Format
- Figure 15: Global Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Buyer Type
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Category
- Figure 32: North America Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Certification Standard
- Figure 35: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Distribution Channel
- Figure 38: North America Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Storage Format
- Figure 41: North America Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Buyer Type
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Category
- Figure 48: Latin America Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Certification Standard
- Figure 51: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Storage Format
- Figure 57: Latin America Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Buyer Type
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Category
- Figure 64: Western Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Certification Standard
- Figure 67: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Storage Format
- Figure 73: Western Europe Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Buyer Type
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Category
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Certification Standard
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Storage Format
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Buyer Type
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Category
- Figure 96: East Asia Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Certification Standard
- Figure 99: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Storage Format
- Figure 105: East Asia Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Buyer Type
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Category
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Certification Standard
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Storage Format
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Buyer Type
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Category
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Certification Standard, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Certification Standard, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Certification Standard
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Storage Format, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Storage Format, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Storage Format
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Buyer Type, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Buyer Type, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Buyer Type
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the organic foods market in 2026, and what is forecast for 2036?
FMI estimates that global organic foods revenue stood at USD 215.0 billion in 2025 and reaches USD 238.0 billion in 2026, scaling to USD 646.0 billion by 2036 across retail aisles.
What is the CAGR for the organic foods market from 2026 to 2036?
The organic foods sector is projected to expand at a 10.5% CAGR over the 2026 to 2036 window, adding USD 408.0 billion across retail and foodservice channels.
Which product category segment leads the organic foods market?
Organic Fresh Fruits and Vegetables are projected to hold 38.0% of product category demand in 2026 since households prioritize certified berries, salads, and orchard fruits as their primary clean-label grocery entry point.
Which certification standard segment leads the organic foods market?
USDA Organic Certified products are anticipated to represent 62.0% of the certification standard category in 2026 owing to strict federal enforcement and bilateral trade equivalency agreements.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 12.1% CAGR through 2036, driven by national bio-input agriculture policies and urban specialty retail store openings.
Who are the key players in the market?
Organic Valley, The Hain Celestial Group, Inc., General Mills, Inc., Danone SA, Amy's Kitchen Inc., and SunOpta Inc. lead branded supply, while Arla Foods amba, Whole Foods Market, UNFI, and Sprouts Farmers Market anchor dairy and grocery distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
