

- Market Size (2026)
- USD 1.8 Bn
- Forecast (2036)
- USD 3.6 Bn
- CAGR (2026 to 2036)
- 7.2%
How big is Organic Tea Market in 2026?
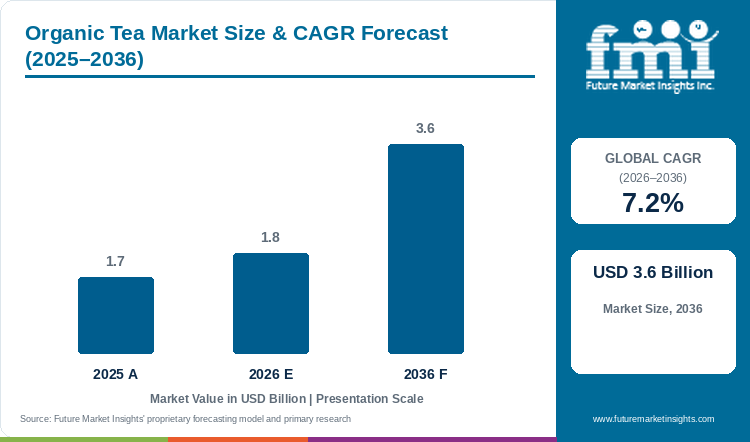
Sales in the organic tea market are projected to grow at 7.2% CAGR, with the market size rising from USD 1.7 billion in 2025 to USD 1.8 billion in 2026 and reaching USD 3.6 billion by 2036.
Stringent maximum residue limits on synthetic agrochemicals across imported botanical shipments compel beverage blenders to secure certified organic leaf supplies compliant with strict synthetic agrochemical prohibition standards before retail chains approve shelf listings. According to Future Market Insights analysis, the global organic tea market rises from USD 1.7 billion in 2025 to USD 1.8 billion in 2026 and reaches USD 3.6 billion by 2036, expanding at a 7.2% CAGR and generating USD 1.8 billion in added revenue. In February 2025, the Tea Association of the USA reported that certified organic tea turnover advanced 8.4% as households prioritized clean-label hot infusions [1]. Beverage formulators also pair whole-leaf infusions with concentrated green tea extracts in functional wellness lines, placing Organic Green Tea at 41.0% share in 2026. Evaluated national growth spans 5.8% in South Korea to 8.8% in Canada, though three-year farm conversion cycles restrict immediate leaf supply.
Key Market Trends & Insights
- By product type: Organic Green Tea led the market with a share of 41.0% in 2026, supported by unfermented steaming and pan-firing methods that retain natural catechin antioxidants.
- By format: Tea Bags & Sachets accounted for 58.0% of demand in 2026, reflecting consumer preference for pre-portioned brewing convenience and plastic-free polylactic acid pyramid mesh.
- By sales channel: With a 46.0% share in 2026, Supermarkets & Hypermarkets led the category, underpinned by dedicated natural-aisle planograms and private-label organic tea ranges.
Regional Highlights
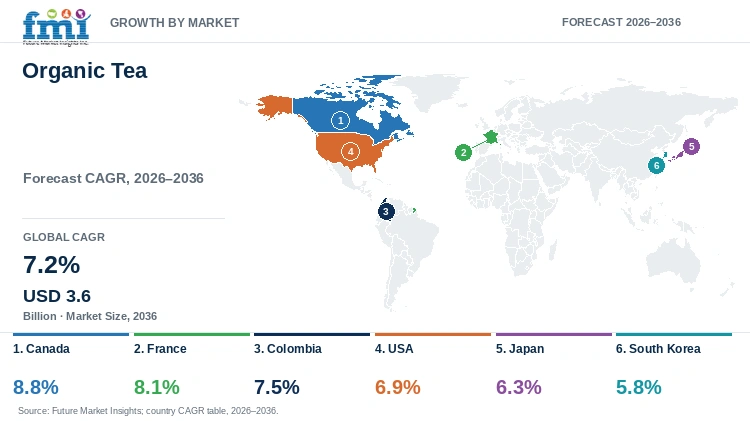
- Fastest-growing evaluated country: Canada, at 8.8% CAGR from 2026 to 2036.
- By country: France at 8.1%, Colombia at 7.5%, the USA at 6.9%, and Japan at 6.3% follow, while South Korea records the lowest evaluated CAGR at 5.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Organic Tea Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.7 billion |
| Estimated Market Size in 2026 | USD 1.8 billion |
| Projected Market Size by 2036 | USD 3.6 billion |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 1.8 billion |
Adoption develops differently across countries because highland estate conversion subsidies, customs pesticide screening protocols, and retail bio-label recognition vary across trading blocs. FMI research indicates that tea packers in Europe and North America must test every incoming container lot via gas chromatography to prevent cross-contamination from neighboring conventional gardens. In July 2026, the Food and Agriculture Organization Intergovernmental Group on Tea reported that global green tea output expanded 6.8% as estates prioritized high-margin unfermented flushes [2]. Consequently, specialty blenders are locking in direct-trade estate contracts and standardizing antioxidant green tea polyphenols across certified wellness infusions.
Estate Acreage and Conversion Yield Sizing
Table 2: Estate Acreage and Leaf Yield Indicators for the Organic Tea Market (USD billion, kilograms, and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.7 | 1.8 | 3.6 |
| Certified organic made-tea yield per hectare (kg) | 1,350 to 1,520 | 1,380 to 1,560 | 1,620 to 1,850 |
| Transitioning & certified organic tea area (thousand hectares) | 275 to 295 | 295 to 320 | 510 to 560 |
| Organic auction price premium over conventional leaf (%) | 22% to 28% | 24% to 30% | 28% to 35% |
Operational note: Estate indicators reflect cured leaf output across certified gardens in India, China, Japan, Sri Lanka, and Kenya, where three-year fallow transitions temporarily reduce bush yield before vermicompost soil recovery stabilizes harvests.
Per Capita & Specialty Retail Spending Sizing
Certified organic tea infusions have gained strong household loyalty in recent years due to their clean botanical flavor and absence of synthetic pesticide residues. Managing specialty tea blending requires balancing seasonal flush availability with strict moisture and volatile-oil preservation inside retail cartons. Owing to the advantages associated with ultrasonic-sealed plant-fiber sachets, grocery shoppers and workplace pantries are replacing bleached paper bags with compostable pyramid formats.
Table 3: Per Capita and Household Spending Indicators for the Organic Tea Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.207 | 0.217 | 0.402 |
| Spend per 1,000 people (USD) | 206.56 | 216.87 | 402.23 |
| Annual spend per regular organic tea household (USD) | 38 to 46 | 40 to 49 | 64 to 78 |
Table 4: Retail Channel & Product Allocation Indicators for the Organic Tea Market (USD billion and percentages), 2026
| Metric | Value | Sector Allocation |
|---|---|---|
| Market size, 2026 | USD 1.8 billion | Total global valuation |
| Tea bags & sachets revenue, 2026 | USD 1.0 billion | 58.0% format share |
| Supermarkets & hypermarkets revenue, 2026 | USD 0.8 billion | 46.0% sales channel share |
| Organic green tea revenue, 2026 | USD 0.7 billion | 41.0% product type share |
Analyst Perspective
"Ultrasonic-sealed sugarcane pyramid sachets and single-estate organic flushes let tea brands command premium shelf pricing across supermarkets. Three-year soil conversion yield drops still require long-term buyer forward contracts before smallholders expand acreage."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the organic tea market segmented?
The organic tea market is segmented by product type, format, sales channel, and region. In 2026, Organic Green Tea is projected at 41.0%, Tea Bags & Sachets at 58.0%, and Supermarkets & Hypermarkets at 46.0%.
By product type: Organic Green Tea, Organic Black Tea, and Herbal & Specialty Infusions.
By format: Tea Bags & Sachets, Whole Loose Leaf Tea, and Ready-to-Drink & Powders.
By sales channel: Supermarkets & Hypermarkets, Specialty Tea & Health Stores, and Online Retail & DTC Subscriptions.
What makes Organic Green Tea central to the product type category?
Organic green tea is estimated to represent 41.0% of the product type category in 2026, reflecting high catechin concentration.
Table 5: Product Type Share for the Organic Tea Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Organic Green Tea | 41.0% |
| Other Segments Combined | 59.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Organic Tea Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Organic Green Tea |
Organic green tea leads product type revenue because unwashed green tea leaves undergo immediate steaming or pan-firing after plucking, making pesticide-free cultivation essential for consumers worried about surface chemical residues. Retaining epigallocatechin gallate catechins without enzymatic oxidation attracts daily wellness drinkers who also purchase dietary green tea supplements for metabolic support. While fermented black teas and soluble black tea extracts remain staples in traditional breakfast blends, green tea varieties such as sencha, gunpowder, and shaded tencha command higher retail price per gram across organic grocery shelves.
- Organic Green Tea accounts for 41.0% of product type revenue in 2026, driven by unfermented leaf processing that preserves catechins while eliminating synthetic spray residues.
- In March 2025, the European Tea and Herbal Infusions Association reported an 11.2% annual increase in certified organic green tea and matcha imports across European member states [3].
Why do Tea Bags & Sachets anchor the format category?
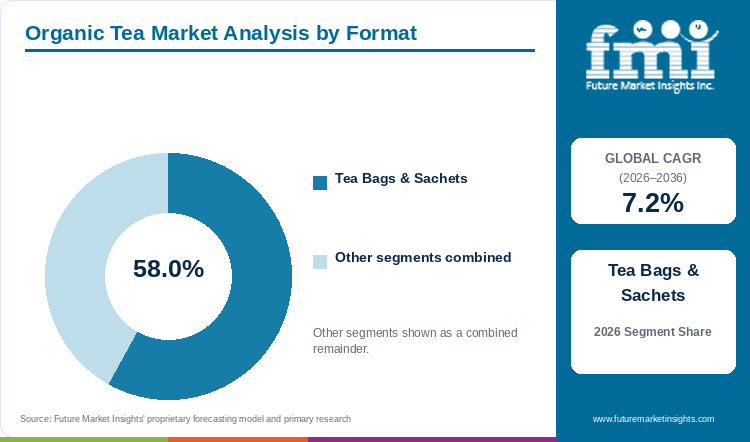
Tea bags & sachets are anticipated to contribute 58.0% of format sales in 2026, owing to convenient single-serve brewing.
Pre-portioned filter bags and pyramid sachets generate the largest share of format turnover because household and office tea drinkers want measured steeping without loose-leaf infusers or strainer cleanup. Packing houses fill biodegradable mesh sachets with caffeine-free herbal tea infusions and aromatic fruit tea blends that expand fully when steeped in hot water. Although loose leaf tins appeal to specialty connoisseurs and cold-brewed bottled iced tea beverages grow in convenience stores, single-chamber paper bags and ultrasonic-sealed pyramid sachets remain the primary repeat-purchase format in family grocery baskets.
- Tea Bags & Sachets hold 58.0% of format demand in 2026, supported by single-cup dosing speed and rapid brand conversion to plastic-free plant-fiber mesh.
- In August 2025, European Bioplastics Association laboratory trials confirmed that ultrasonic-sealed polylactic acid pyramid tea bags achieved complete industrial compostability without releasing microplastic particles [4].
What gives Supermarkets & Hypermarkets the leading position in sales channel?
Supermarkets & hypermarkets are set to command 46.0% of sales channel revenue in 2026, reinforced by private-label organic allocations.
Mainstream supermarkets and hypermarkets lead distribution because national grocery chains dedicate eye-level natural beverage sections to certified organic cartons alongside store-brand organic tea lines. Consolidating organic tea purchases into weekly household grocery trips lowers customer acquisition costs compared with standalone boutiques or direct-to-consumer shipping. While specialty tea bars promote handcrafted bubble tea drinks and single-estate tasting flights, mass retail multiples move high carton volumes through multi-box promotional pricing and verified USDA Organic or EU Euro-leaf shelf tags.
- Supermarkets & Hypermarkets represent 46.0% of sales channel turnover in 2026, backed by expanding shelf space for certified organic national and private-label tea boxes.
- In October 2026, the UK Department for Environment, Food and Rural Affairs reported that mainstream supermarket chains captured 64% of national organic food and beverage retail sales as total UK organic turnover reached GBP 3.9 billion [5].
What are the drivers, restraints, and opportunities in the organic tea market?
In the Organic Tea Market, synthetic pesticide avoidance and daily catechin wellness habits support demand, three-year estate soil conversion cycles and manual weeding costs constrain supply, and plastic-free sugarcane pyramid sachets alongside single-origin matcha tins create premium margin growth through 2036.
- Driver: Consumer avoidance of synthetic agricultural sprays on unwashed tea leaves and daily intake of antioxidant catechins and adaptogenic herbs drive repeat retail purchases.
- Restraint: Mandatory three-year organic soil transition periods reduce bush yields by 20% to 30% while raising manual weeding and organic composting expenses for smallholders.
- Opportunity: Replacing petroleum nylon mesh with ultrasonic-sealed polylactic acid pyramid sachets and marketing single-estate ceremonial matcha tins unlock premium retail pricing.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Heightened consumer scrutiny over synthetic fungicide and insecticide residues on dried botanical leaves acts as the primary demand catalyst for certified organic teas. Because tea leaves are plucked and dried without post-harvest washing, any soluble agrochemical applied in conventional gardens can transfer directly into the hot cup during steeping. FMI data suggests that health-conscious households treat organic certification as a baseline safety screen for daily green and herbal infusions. In June 2025, the U.S. Department of Agriculture Economic Research Service documented sustained growth in per capita availability of specialty and organic leaf teas across U.S. grocery channels [6]. Consequently, blenders must maintain batch-level residue testing certificates to retain supermarket shelf listings.
Risk Assessment of the Organic Tea Market: Operational and Formulation Friction
Multi-year agronomic transition rules and biological pest pressures create severe cash-flow bottlenecks for tea estates converting from conventional cultivation. Certifiers require a 36-month synthetic-chemical prohibition transition period before harvested leaves can carry an organic seal, during which time tea bushes suffer sharp yield declines as soil microbial balance adjusts. In July 2025, Tea Board of India field assessments indicated that estates undergoing organic conversion experienced a 22% drop in green leaf yield alongside an 18% rise in manual weeding and neem-oil biocontrol labor costs [7]. Without pre-harvest price guarantees from international packers, smallholder growers frequently abandon conversion halfway through the qualification window.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Eliminating microplastic-shedding nylon filters and expanding shaded organic green tea cultivation open high-margin revenue streams for specialty tea brands. Consumers who buy organic leaves for purity increasingly reject heat-sealed polypropylene paper bags and nylon sachets. In July 2026, the Research Institute of Organic Agriculture reported that global certified organic tea farmland expanded by 9.5% as highland estates in East Africa and East Asia targeted premium export buyers [8]. Tea brands that package whole-bud flushes inside non-GMO sugarcane ultrasonic pyramid tea bags and market nitrogen-flushed ceremonial stone-ground matcha tins capture substantially higher gross margins across natural food chains.
Organic Tea Market by Country (2026 to 2036)
As per FMI, Canada represents the fastest-growing organic tea market among the six evaluated countries, at an 8.8% CAGR from 2026 to 2036, while South Korea records the slowest expansion at 5.8% CAGR. Across all covered national markets, commercial growth depends on how effectively tea packers navigate organic import equivalency agreements, plastic-free packaging mandates, highland smallholder cooperative yields, and ready-to-drink cold-brew innovation.
Table 7: Country CAGR and Primary Growth Levers for the Organic Tea Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Canada | 8.8% | Canada Organic Regime equivalency imports and compostable plant-fiber sachet adoption |
| France | 8.1% | Specialized bio-cooperative grocery distribution and evening herbal digestion infusions |
| Colombia | 7.5% | High-altitude Andean organic Camellia sinensis and aromatic herb cooperative expansion |
| USA | 6.9% | Mainstream supermarket natural aisle expansion and organic RTD iced tea innovation |
| Japan | 6.3% | JAS-certified organic sencha and shaded tencha matcha production for domestic and export use |
| South Korea | 5.8% | Volcanic Jeju Island organic green tea branding and specialty café RTD tea tonics |
Source: Future Market Insights analysis
Canada Organic Tea Market Outlook (2026 to 2036)
Bilingual packaging laws and strict Canada Organic Regime equivalency checks shape a highly structured import environment across Canadian provinces. Sales of organic tea in Canada are forecast to expand at 8.8% CAGR through 2036, supported by strong consumer rejection of plastic-sealed teabags and rising winter demand for immunity herbal blends. In October 2025, Agriculture and Agri-Food Canada trade assessments noted a 10.8% annual rise in certified organic hot tea and herbal infusion retail sales across Ontario, British Columbia, and Quebec [9]. Trans-Pacific ocean freight surcharges and bilingual carton printing runs still raise landed unit costs for small blenders, so Canadian packers import bulk organic leaf sacks and run domestic ultrasonic pyramid-bagging lines in Vancouver and Toronto.
Key takeaway: In Canada, strict Canada Organic Regime labeling trust and domestic ultrasonic pyramid-sachet co-packing drive a leading 8.8% CAGR.
France Organic Tea Market Outlook (2026 to 2036)
Between 2026 and 2036, the France market is expected to progress at 8.1% CAGR, underpinned by a deeply rooted evening tisane culture and a dense network of specialized bio-grocery cooperatives. French households routinely purchase certified AB (Agriculture Biologique) chamomile, verbena, linden, and Darjeeling blends packaged in unbleached paperboard cartons. In October 2025, the French Organic Agency (Agence Bio) reported that organic tea and herbal infusion sales expanded 9.1% across dedicated organic stores and pharmacies [10]. However, European Union border inspection checks on pyrrolizidine alkaloids and pesticide residues can hold Asian leaf containers at Le Havre, prompting French maisons de thé to contract directly with audited organic cooperatives in Auvergne, Provence, and Darjeeling.
Key takeaway: In France, specialized bio-grocery retail channels and strict AB-certified herbal tisane procurement sustain an 8.1% CAGR.
Colombia Organic Tea Market Outlook (2026 to 2036)
Volcanic Andean slopes in Valle del Cauca and Antioquia give Colombia a year-round high-altitude microclimate where tea bushes face fewer insect pests than lowland tropical estates, enabling pesticide-free cultivation without heavy yield penalties. In Colombia, demand for organic tea is predicted to advance at 7.5% CAGR through 2036, stimulated by urban wellness cafés in Bogotá and Medellín alongside specialty export demand. In November 2025, the Colombian Ministry of Agriculture reported a 12.4% expansion in certified organic tea and aromatic botanical acreage across highland departments [11]. Steep mountain feeder roads and high domestic trucking tariffs still inflate transport costs to coastal ports, so grower cooperatives are installing shared solar-powered withering and drying sheds near farm gates.
Key takeaway: In Colombia, pest-resistant high-altitude Andean cultivation and shared solar drying cooperatives support a 7.5% CAGR.
USA Organic Tea Market Outlook (2026 to 2036)
Mainstream supermarket natural aisles, club-store multipacks, and refrigerated ready-to-drink cases make the United States the largest single-country buyer of certified organic tea globally. Demand across the USA organic tea sector is expected to increase at 6.9% CAGR through 2036, enabled by USDA Strengthening Organic Enforcement electronic import certificates that curb fraudulent bulk leaf shipments. In May 2026, the U.S. Department of Agriculture National Agricultural Statistics Service documented record certified organic specialty crop and botanical handling valuations across U.S. states [12]. Slotting fees in conventional grocery chains and price competition from non-organic RTD iced teas still pressure margins, leading U.S. brands to differentiate with Fair Trade Regenerative Organic Certified tulsi, matcha, and functional mushroom-tea blends.
Key takeaway: In the USA, USDA electronic import traceability enforcement and functional adaptogen tea blends support a 6.9% CAGR.
Japan Organic Tea Market Outlook (2026 to 2036)
Rapid international demand for stone-ground organic matcha and domestic preference for residue-free sencha are reshaping tea estates across Kagoshima, Shizuoka, and Miyazaki. The organic tea market in Japan is anticipated to grow at 6.3% CAGR between 2026 and 2036, as Prefectural agricultural subsidies help family estates convert conventional green tea fields into JAS-certified organic tencha gardens. In January 2026, the Japan Tea Central Council reported an 8.3% annual increase in JAS-certified organic green tea output [13]. However, an aging rural farming workforce and the high labor burden of mechanical brush weeding on terraced hillsides constrain leaf volume, prompting Japanese tea cooperatives to consolidate plots onto flatter mechanized volcanic plains in Kagoshima.
Key takeaway: In Japan, mechanized JAS-certified organic tencha and sencha conversion across southern prefectures sustains a 6.3% CAGR.
South Korea Organic Tea Market Outlook (2026 to 2036)
South Korea's organic tea market centers on volcanic Jeju Island and Hadong estates, where mineral-rich soils and coastal winds support certified organic green tea and fermented hwangcha production. Adoption of organic tea in South Korea is estimated to expand at 5.8% CAGR through 2036, driven by young urban consumers ordering sparkling organic matcha lattes and cold-brewed barley-green tea blends in specialty cafés. In February 2026, the Korea Tea Association reported that domestic retail sales of certified organic specialty teas and RTD infusions rose 7.2% [14]. Intense competition from low-price espresso chains and high domestic land and farm-labor costs still limit mass grocery volume, so Korean tea houses focus on single-estate gift sets and premium café syrups.
Key takeaway: In South Korea, volcanic Jeju Island single-estate branding and café cold-brew matcha menus support a 5.8% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the organic tea market?
Associated British Foods (Twinings), Lipton Teas and Infusions (Pukka Herbs), Tata Consumer Products, Hain Celestial Group, Organic India, Traditional Medicinals, Numi Organic Tea, and Yogi Tea are the notable companies in the organic tea market.
Competition in the global organic tea market divides between multinational beverage corporations and dedicated organic botanical specialists, an FMI analyst notes. Multinational tea houses leverage multi-country auction buying, high-speed blending hubs, and supermarket category captaincy to distribute certified organic green and black tea lines. Dedicated herbal apothecaries and ethical tea brands contract directly with smallholder farmer cooperatives for biodynamic chamomile, tulsi, and single-origin matcha. Retail grocery buyers evaluate suppliers on gas-chromatography pesticide screening, home-compostable sachet materials, and Fair Trade or Regenerative Organic certifications.
- Global Beverage & Multi-Brand Tea Platforms: Associated British Foods (Twinings), Lipton Teas and Infusions (Pukka Herbs), Tata Consumer Products, and Hain Celestial Group operate high-volume blending plants and international grocery distribution.
- Ayurvedic & Pharmacopeial Herbal Specialists: Organic India and Traditional Medicinals focus on regeneratively farmed Tulsi and pharmacopeial-grade medicinal botanical infusions.
- Ethical & Biodynamic Specialty Blenders: Numi Organic Tea and Yogi Tea differentiate through Fair Trade direct-sourcing partnerships and plant-based compostable packaging.
Competitive Benchmarking: Organic Tea Market
Table 8: Competitive Benchmarking for the Organic Tea Market (qualitative capability ratings), 2026
| Company | Organic Estate Sourcing Depth | Functional & Herbal Portfolio | Compostable Packaging Readiness | Geographic Reach |
|---|---|---|---|---|
| Associated British Foods (Twinings) | High | High | Medium | High |
| Lipton Teas and Infusions (Pukka) | High | High | High | High |
| Tata Consumer Products | High | Medium | Medium | High |
| Hain Celestial Group | Medium | High | Medium | High |
| Organic India | High | High | High | Medium |
| Traditional Medicinals | High | High | High | Medium |
| Numi Organic Tea | High | Medium | High | Medium |
| Yogi Tea | High | High | High | High |
Scoring basis: Organic Estate Sourcing Depth is High when corporate disclosures document multi-year direct contracts with certified organic gardens or smallholder cooperatives. Functional & Herbal Portfolio is High when green, black, and multi-herb wellness infusions are core. Compostable Packaging Readiness is High when plastic-free sachets and plant-based overwraps are commercially deployed. High Geographic Reach indicates multi-continental supermarket and specialty distribution.
Key Developments in the Organic Tea Market
- In June 2026, Lipton Teas and Infusions completed the transition of its Pukka Herbs European pyramid sachet line to home-compostable non-GMO sugarcane fiber mesh [15].
- In March 2026, Associated British Foods commissioned an expanded organic botanical blending and nitrogen-flushed packing line at its Twinings facility in Swarzedz, Poland [16].
- In October 2025, Tata Consumer Products expanded long-term offtake partnerships with certified organic high-altitude tea estates in Assam and Darjeeling for specialty export cartons [17].
Key Players in the Organic Tea Market
Global Beverage & Multi-Brand Tea Platforms
- Associated British Foods (Twinings)
- Lipton Teas and Infusions (Pukka Herbs)
- Tata Consumer Products
- Hain Celestial Group
Ayurvedic & Pharmacopeial Herbal Specialists
- Organic India
- Traditional Medicinals
Ethical & Biodynamic Specialty Blenders
- Numi Organic Tea
- Yogi Tea
Organic Tea Market - Report Scope
Table 9: Report Scope for the Organic Tea Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Format; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial brand and packer revenue from certified organic Camellia sinensis teas (green, black, white, oolong, matcha) and certified organic herbal infusions sold across retail and foodservice channels. Excludes uncertified conventional teas, coffee products, and raw farm-gate green leaf not processed into commercial tea formats. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Canada, France, Colombia, USA, Japan, South Korea, and additional countries in the full report |
| Key Companies Covered | Associated British Foods, Lipton Teas and Infusions (Pukka Herbs), Tata Consumer Products, Hain Celestial Group, Organic India, Traditional Medicinals, Numi Organic Tea, Yogi Tea |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Organic Tea Market - Research Methodology
Table 10: Research Methodology for the Organic Tea Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with organic tea estate managers, botanical blenders, compostable packaging engineers, supermarket category buyers, and organic certification auditors across the value chain to validate conversion yields, sachet costs, and retail velocity. |
| Secondary Research | Secondary research included company annual reports, FAO Intergovernmental Group on Tea bulletins, USDA NASS and ERS datasets, Agence Bio and AAFC trade reports, and certified organic acreage registries. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess certified organic leaf harvests, pack formats, retail price premiums, and channel distribution. |
| Data Triangulation and Validation | Data is validated against national organic import certificates, auction volume records, supermarket scanner data, and historical trend analysis to ensure high accuracy without double counting bulk leaf intermediates. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's specialty beverage econometric model, calibrating evaluated national growth rates against the 7.2% global baseline through verified certified organic tea estate acreage, retail clean-label premiumization, and whole-leaf functional tea bag adoption. |
| Operational Benchmark Traceability | Operational benchmarks (certified organic made-tea yield per hectare, three-year organic farm transition costs, and multi-residue pesticide screen clearance rates) represent modeled estimates synthesized from FAO Intergovernmental Group on Tea statistics, USDA AMS organic records, and commercial estate filings. |
Organic Tea Market by Segments
Organic Tea Market segmented by Product Type:
- Organic Green Tea
- Organic Black Tea
- Herbal & Specialty Infusions
Organic Tea Market segmented by Format:
- Tea Bags & Sachets
- Whole Loose Leaf Tea
- Ready-to-Drink & Powders
Organic Tea Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Specialty Tea & Health Stores
- Online Retail & DTC Subscriptions
Organic Tea Market by Region
- North America
- United States
- Canada
- Latin America
- Colombia
- Brazil
- Argentina
- Mexico
- Chile
- Western Europe
- France
- United Kingdom
- Germany
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- China
- South Asia and Pacific
- India
- Sri Lanka
- Australia and New Zealand
- ASEAN
- Middle East and Africa
- Kenya
- South Africa
- GCC Countries
- Türkiye
Research Sources and Bibliography
- [1] Tea Association of the USA. (2025, February 19). Annual state of the U.S. tea industry and certified organic segment review. Tea Association of the USA Trade Bulletins.
- [2] Food and Agriculture Organization of the United Nations. (2026, July 14). Global tea market situation and green tea production outlook. FAO Intergovernmental Group on Tea, Markets and Trade Division.
- [3] European Tea and Herbal Infusions Association (THIE). (2025, March 21). European import statistics and organic green tea market review. THIE Compendium and Market Reports.
- [4] European Bioplastics Association. (2025, August 18). Performance of ultrasonic-sealed polylactic acid mesh in hot beverage filtration. European Bioplastics Technical Series, 16(3), 41-53.
- [5] Department for Environment, Food and Rural Affairs. (2026, October 14). Organic action plan and UK organic retail market assessment. UK Government Publications (GOV.UK).
- [6] Economic Research Service. (2025, June 26). Food availability (per capita) data system: Coffee, tea, cocoa, and spices series. U.S. Department of Agriculture Economic Research Service.
- [7] Tea Board of India. (2025, July 25). Agronomic yield and weeding cost assessment during three-year organic tea estate conversion. Tea Board of India Technical Bulletins.
- [8] Research Institute of Organic Agriculture (FiBL). (2026, July 09). The world of organic agriculture: Global statistics on certified organic tea area. FiBL & IFOAM Organics International Yearbook.
- [9] Agriculture and Agri-Food Canada. (2025, October 29). Sector trend analysis: Coffee and tea hot and cold drinks in Canada. Government of Canada International Trade Reports.
- [10] Agence Bio. (2025, October 16). Barometer of organic food and herbal infusion consumption and retail channels in France. French Organic Agency Annual Publications.
- [11] Ministry of Agriculture and Rural Development of Colombia. (2025, November 14). National registry of certified organic highland tea and aromatic crops. Ministerio de Agricultura y Desarrollo Rural Bulletins.
- [12] National Agricultural Statistics Service. (2026, May 31). Organic production survey: Certified organic crop and beverage handling statistics. U.S. Department of Agriculture NASS.
- [13] Japan Tea Central Council. (2026, January 22). Annual statistical review of JAS-certified organic sencha and tencha production. Japan Tea Industry Reports.
- [14] Korea Tea Association. (2026, February 17). Domestic consumption patterns for Jeju organic green tea and specialty café infusions. Korea Tea Industry Review, 29(1), 14-28.
- [15] Lipton Teas and Infusions. (2026, June 12). Pukka Herbs completion of home-compostable sugarcane pyramid sachet rollout in Europe. Lipton Teas and Infusions Sustainability Releases.
- [16] Associated British Foods plc. (2026, March 19). Commissioning of expanded Twinings organic herbal blending and nitrogen-packing line in Poland. ABF Operational Announcements.
- [17] Tata Consumer Products Limited. (2025, October 27). Expansion of certified organic estate purchase partnerships in Assam and Darjeeling. Tata Consumer Corporate Filings.
- [18] Organic India Pvt. Ltd. (2026, January 15). Expansion of regeneratively farmed Tulsi herbal infusion distribution across North American grocers. Organic India Press Room.
- [19] Traditional Medicinals, Inc. (2025, August 28). Completion of solar-assisted botanical drying upgrades across partner chamomile cooperatives. Traditional Medicinals Impact Reports.
- [20] Numi, Inc. (Numi Organic Tea). (2026, April 09). Commercial rollout of plant-based moisture-barrier overwrap across single-origin brick packs. Numi Organic Tea Sustainability News.
- [21] Yogi Tea GmbH. (2025, September 23). Inauguration of gas-chromatography botanical residue testing laboratory in Imola, Italy. Yogi Tea Quality Assurance Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the organic tea market in 2026 and what is forecast for 2036?
- Which pesticide-residue and preventive wellness pressures support demand for organic tea?
- What makes Organic Green Tea central to the product type category?
- Why do Tea Bags & Sachets lead the format category globally?
- How do growth rates differ across Canada, France, Colombia, and the USA?
- Which leading companies supply certified organic leaf teas and herbal infusions today?
- What limits smallholder estate conversion or supplier switching in the organic tea market?
- What should retail buyers evaluate before approving an organic tea supplier?
Frequently Asked Questions
How large is the Organic Tea Market expected to be in 2026?
Industry valuation estimates indicate that the global organic tea market will reach USD 1.8 billion in 2026. The market is projected to expand further and reach USD 3.6 billion by 2036, driven by consumer avoidance of synthetic agrochemical residues on unwashed tea leaves.
What CAGR is forecast for the Organic Tea Market through 2036?
As per FMI, the organic tea market is projected to grow at a 7.2% CAGR from 2026 to 2036. Growth is supported by expanding supermarket natural-beverage aisles, ceremonial matcha adoption, and plastic-free compostable pyramid sachets.
Which product type holds a notable organic tea demand share in 2026?
Category projections show Organic Green Tea holding 41.0% of product type demand in 2026. The segment benefits from unfermented steaming and pan-firing processes that preserve natural catechin antioxidants.
Which format segment holds a notable organic tea share in 2026?
Demand assessments indicate that Tea Bags & Sachets will hold 58.0% of format demand in 2026. Demand is supported by convenient single-cup dosing and rapid brand transition toward ultrasonic-sealed sugarcane mesh bags.
Which country has a notable organic tea expansion outlook during the forecast period?
FMI finds that Canada is projected to expand at an 8.8% CAGR during the 2026 to 2036 assessment period. Growth is supported by strict Canada Organic Regime labeling trust and widespread consumer preference for plastic-free herbal and green tea sachets.
Which companies are active in the Organic Tea Market during 2026?
Notable market participants include Associated British Foods (Twinings), Lipton Teas and Infusions (Pukka Herbs), Tata Consumer Products, Hain Celestial Group, Organic India, Traditional Medicinals, Numi Organic Tea, and Yogi Tea. These companies are focusing on direct smallholder conversion contracts, gas-chromatography residue testing, and compostable packaging.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Organic Green Tea
- Organic Black Tea
- Herbal & Specialty Infusions
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Format, 2026 to 2036
- Tea Bags & Sachets
- Whole Loose Leaf Tea
- Ready-to-Drink & Powders
- Y-o-Y Growth Trend Analysis By Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Format, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Tea & Health Stores
- Online Retail & DTC Subscriptions
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Colombia
- Brazil
- Argentina
- Mexico
- Chile
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- United Kingdom
- Germany
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Sri Lanka
- Australia and New Zealand
- ASEAN
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kenya
- South Africa
- GCC Countries
- Türkiye
- By Product Type
- By Format
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Format
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- Colombia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Format
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Format
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Associated British Foods (Twinings)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Lipton Teas and Infusions (Pukka)
- Tata Consumer Products
- Hain Celestial Group
- Organic India
- Traditional Medicinals
- Numi Organic Tea
- Yogi Tea
- Lipton Teas and Infusions (Pukka Herbs)
- Associated British Foods (Twinings)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


