

- Market Size (2026)
- USD 1.8 Bn
- Forecast (2036)
- USD 4.0 Bn
- CAGR (2026 to 2036)
- 8.2%
How big is Organic Ice Cream Market in 2026?
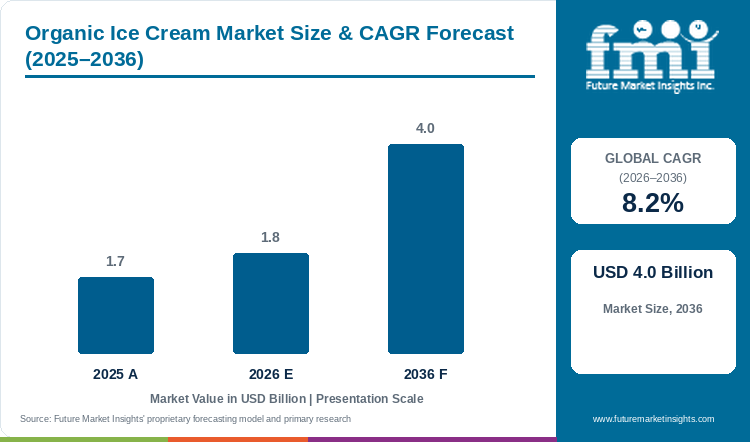
The organic ice cream market is forecast to register a CAGR of 8.2% through 2036. Revenue increases from USD 1.7 billion in 2025 to USD 1.8 billion in 2026 before reaching USD 4.0 billion by 2036.
Parental rejection of synthetic mono- and diglyceride emulsifiers and artificial bovine growth hormones in grocery freezer aisles is compelling creameries to reformulate frozen desserts around certified organic dairy and plant bases. According to Future Market Insights analysis, the global organic ice cream market rises from USD 1.7 billion in 2025 to USD 1.8 billion in 2026 and reaches USD 4.0 billion by 2036, expanding at an 8.2% CAGR and generating USD 2.2 billion in added revenue. In January 2025, the International Dairy Foods Association documented that retail volume of certified organic frozen desserts surpassed 420 million liters [1]. Slices, shreds, and blocks holds 38.5% share in 2026. Country CAGRs span 6.6% in Japan to 10.0% in Brazil.
Key Market Trends & Insights
- By product form: Slices, shreds, and blocks led the market with a share of 38.5% in 2026, driven by portion-controlled novelty bars and wrapped ice cream slices.
- By source base: Traditional dairy milk accounted for 47.1% of demand in 2026, supported by pasture-certified butterfat that provides smooth melt mouthfeel.
- By distribution channel: Supermarkets and hypermarkets represented 49.1% of revenue in 2026, owing to dedicated natural freezer doors and private-label pints.
- By flavor variant: With a 44.2% share in 2026, plain and unsweetened bases led the category, as vanilla and sweet-cream recipes anchor household and cafe scooping.
Regional Highlights
- Fastest-growing evaluated country: Brazil, at 10.0% CAGR from 2026 to 2036.
- By country: UK at 9.2%, USA at 8.5%, Canada at 7.9%, and South Korea at 7.2% follow, while Japan records the lowest evaluated CAGR at 6.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Organic Ice Cream Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.7 billion |
| Estimated Market Size in 2026 | USD 1.8 billion |
| Projected Market Size by 2036 | USD 4.0 billion |
| CAGR, 2026 to 2036 | 8.2% |
| Added Revenue, 2026 to 2036 | USD 2.2 billion |
Commercial conditions differ across the profiled countries owing to pasture-grazing certification rules, organic raw milk supply quotas, and sub-zero cold-chain freight costs. FMI research indicates that organic creameries face raw cream price premiums and ice-crystal heat shock during supermarket delivery. In February 2025, the U.S. Department of Agriculture Agricultural Marketing Service enforced updated National Organic Program Origin of Livestock and pasture-grazing verification audits across certified dairy herds [2]. Consequently, frozen dessert makers are replacing synthetic polysorbates with organic egg-yolk lecithin and clean-label ingredients such as locust bean gum, preserving USDA Organic seals while preventing freezer iciness.
Certified Dairy Volume and Dessert-Occasion Sizing
Table 2: Certified Dairy Volume and Dessert-Occasion Sizing for the Organic Ice Cream Market (USD billion, million liters, million units, and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.7 | 1.8 | 4.0 |
| Certified organic milk allocated (million liters) | 680 to 720 | 720 to 770 | 1,450 to 1,560 |
| Organic frozen dessert units sold (million) | 420 to 460 | 450 to 490 | 930 to 1,020 |
| Spend per organic dairy consumer (USD) | 0.2 to 0.3 | 0.2 to 0.3 | 0.5 to 0.5 |
Operational note: Milk allocation volumes reflect certified organic sweet-cream butterfat requirements across low-overrun pint, novelty bar, and scoop-parlor formats.
Per Capita and Frozen-Aisle Sizing
Certified organic frozen desserts have expanded across mainstream supermarket freezer doors and boutique scoop shops as families trade bulk artificial tubs for pasture-grazed and dairy-free novelties. Growing demand for lactose-free indulgence is also lifting sales of organic oat and coconut plant-based ice creams alongside grass-fed dairy pints. In March 2025, European Commission organic agriculture monitoring reports confirmed that certified organic dairy processors maintained zero synthetic pesticide and routine antibiotic residues across audited creameries [3]. Supermarket category buyers now require continuous temperature-logger records and third-party organic certificates before allocating sub-zero shelf facings.
Table 3: Per Capita and Frozen-Aisle Spending Indicators for the Organic Ice Cream Market (billion people and USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 0.2 | 0.2 | 0.4 |
| Spend per 1,000 people (USD) | 202.1 | 216.9 | 446.9 |
| Spend per premium frozen retail door (USD) | 17,500 to 19,000 | 18,750 to 20,400 | 40,000 to 44,000 |
Table 4: Frozen-Aisle and Creamery Spending Indicators for the Organic Ice Cream Market (USD and thousand doors), 2026
| Metric | Value | Operational Context |
|---|---|---|
| Market size, 2026 | USD 1.8 billion | Global baseline revenue |
| Premium frozen dessert retail doors (thousand) | 96.0 | Active natural freezer doors |
| Market spend per retail door | USD 18,750 | Annualized freezer door turnover |
| Supermarket channel revenue, 2026 | USD 883.8 million | 49.1% distribution share |
Analyst Perspective
"Pasture-certified sweet cream and fair-trade chocolate novelties allow organic creameries to capture premium freezer space in mainstream supermarkets. High organic raw milk premiums and freeze-thaw crystal growth still require natural gum stabilization during cold-chain transit."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the organic ice cream market segmented?
The organic ice cream market is segmented by product form / texture, source base, distribution channel, and flavor / variant. In 2026, slices, shreds, and blocks is projected at 38.5%, traditional dairy milk at 47.1%, supermarkets and hypermarkets at 49.1%, and plain and unsweetened at 44.2%.
By product form / texture: Slices, shreds & blocks, drinkable liquid & shakes, set tubs & cups, and spreads & dips.
By source base: Traditional dairy milk, plant-based alternative (oat/almond/soy), and lactose-free & specialized.
By distribution channel: Supermarkets & hypermarkets, specialty natural food stores, and food service & quick service bakeries.
By flavor / variant: Plain & unsweetened, fruit-flavored & indulgent, and savory & herbed.
Why do Slices, Shreds & Blocks lead the product form category?
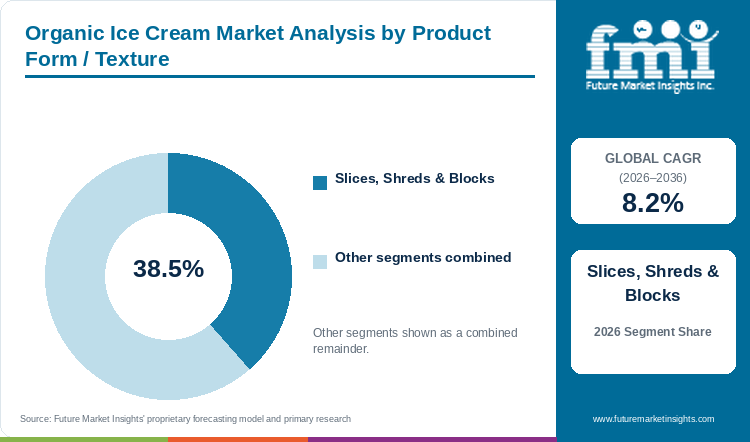
Slices, shreds, and blocks are projected to account for 38.5% of product form demand in 2026, driven by portion control.
Table 5: Product Form / Texture Share for the Organic Ice Cream Market (percentage share), 2026
| Product Form / Texture | Share (2026) |
|---|---|
| Slices, Shreds & Blocks | 38.5% |
| Other Segments Combined | 61.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form / Texture Leadership and Market Growth for the Organic Ice Cream Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.2% |
| Leading Segment | Slices, Shreds & Blocks |
Pre-portioned handheld blocks, chocolate-enrobed novelty bars, and wrapped ice cream sandwich slices lead product form demand because parents and calorie-conscious shoppers want built-in portion control without scooping from open tubs. Individual foil and compostable paper wrappers also protect organic butterfat from freezer burn when household refrigerator doors are opened repeatedly. In addition to this, cryogenic nitrogen hardening tunnels let processors lock a crisp organic dark-chocolate shell around low-overrun ice cream and frozen desserts. Set tubs and drinkable shakes serve family sharing and cafe menus, yet handheld blocks and slices generate higher repeat velocity through 2036.
- Slices, shreds, and blocks account for 38.5% of product form demand in 2026, driven by single-serve calorie control and reduced household freezer burn.
- In June 2025, microstructural rheology trials in the Journal of Dairy Science confirmed that low-overrun organic novelty blocks maintained structural firmness for 20 minutes at ambient room temperature [4].
What maintains Traditional Dairy Milk at nearly half of source base volume?
Within the source base category, traditional dairy milk is estimated at 47.1% share in 2026, underpinned by pasture butterfat mouthfeel.
Traditional dairy milk remains the largest source base because natural bovine milkfat globules melt cleanly at human body temperature, releasing vanilla and cocoa aromatics without waxy coating on the palate. Creameries sourcing certified organic milk from pasture-grazed herds churn sweet cream at 25% to 35% overrun, producing a dense texture that stabilizes air cells without synthetic mono- and diglycerides. Plant-based oat, coconut, and almond bases capture 33.5% share among vegan and dairy-sensitive buyers, while lactose-free dairy accounts for 19.4%, yet pasture-raised dairy cream anchors flagship pint and bar lines through 2036.
- Traditional dairy milk holds 47.1% of source base demand in 2026, underpinned by natural butterfat melting properties and clean-label churning stability.
- In September 2025, lipid assays published in Lipids in Health and Disease verified that certified organic pasture-grazed milk contained 60.0% higher conjugated linoleic acid than conventional confinement milk [5].
Why do Supermarkets and Hypermarkets dominate distribution channels?
Supermarkets and hypermarkets are anticipated to capture 49.1% of distribution channel sales in 2026, reinforced by dedicated natural freezer doors.
Supermarkets and hypermarkets capture nearly half of total distribution turnover because frozen novelties require uninterrupted minus-20-degree-Celsius storage that fits weekly family grocery shopping trips. National grocery banners have expanded dedicated organic freezer doors where shoppers compare branded farmstead pints alongside private-label organic tubs and non-dairy ice cream bars. Specialty natural grocers represent 31.4% of revenue as early incubators for small-batch regional creameries, while scoop parlors and quick-service bakeries account for 19.5%. However, supermarket private-label programs narrow the price gap against conventional ice cream, driving mainstream household adoption.
- Supermarkets and hypermarkets represent 49.1% of distribution channel revenue in 2026, reinforced by multi-door sub-zero display cases and private-label organic expansion.
- In October 2025, the Organic Trade Association retail dairy audit reported that 58.0% of organic grocery shoppers purchased certified organic frozen desserts during routine supermarket trips [6].
What are the drivers, restraints, and opportunities in the organic ice cream market?
Clean-label ingredient scrutiny and pasture-raised dairy demand drive recurring retail expansion, whereas farmgate organic milk premiums and heat-shock iciness constrain margins, and probiotic and regenerative novelties create premium value.
- Driver:Household avoidance of synthetic emulsifiers, artificial colors, and growth hormones shifts family dessert spending toward certified organic pints and bars through 2036.
- Restraint:Three-year organic pasture transition periods, farmgate cream premiums, and freeze-thaw crystal growth elevate manufacturing and cold-chain costs.
- Opportunity:Regenerative organic dairy certifications, fair-trade cocoa coatings, and synbiotic culture inclusions unlock high-margin retail placement.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Household grocery buyers are reading frozen dessert ingredient labels closely and rejecting tubs formulated with high-fructose corn syrup, carrageenan, and polysorbate 80. Parents want short ingredient decks featuring organic cream, organic cane sugar, egg yolks, and fair-trade vanilla extract. In addition to this, consumer interest in functional dairy products is lifting demand for grass-fed organic ice creams naturally rich in omega-3 fatty acids. In May 2025, the Research Institute of Organic Agriculture (FiBL) statistical yearbook reported that global retail sales of certified organic dairy and frozen treats grew by 9.4% year-over-year [7]. Creameries must maintain accredited organic pasture documentation to secure national grocery listings.
Risk Assessment of the Organic Ice Cream Market: Operational and Formulation Friction
High farmgate prices for certified organic sweet cream and vulnerability to temperature heat-shock during distribution restrain broader mass-market penetration. Converting a conventional dairy farm to certified organic status requires a 36-month chemical-free pasture transition and 100% organic forage, keeping raw organic cream 35% to 50% more expensive than conventional cream. Besides this, clean-label organic pints and dairy alternatives formulated without synthetic stabilizers suffer rapid ice-crystal coarsening if loading docks warm above minus-15 degrees Celsius. In June 2025, the U.S. Food and Drug Administration updated food labeling and dairy identity compliance inspections covering overrun and ingredient declarations [8]. Cold-chain surcharges consequently pressure processor margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Artisanal creameries and multinational dessert brands are capturing premium retail margins by combining Regenerative Organic Certified pasture cream with functional gut-health cultures and compostable packaging. Enriching organic ice cream bases with spore-forming probiotic ingredients and organic agave inulin fibers allows brands to position frozen treats as digestive-friendly indulgences that survive sub-zero storage. Furthermore, cryogenic liquid-nitrogen freezing tunnels create ultra-fine ice crystals that mimic synthetic stabilizers using only organic guar or acacia gum. In August 2026, sensory trials in the International Dairy Journal showed that cryogenically hardened organic bars reduced iciness defects by 42.0% over six months of storage [9].
Organic Ice Cream Market by Country (2026 to 2036)
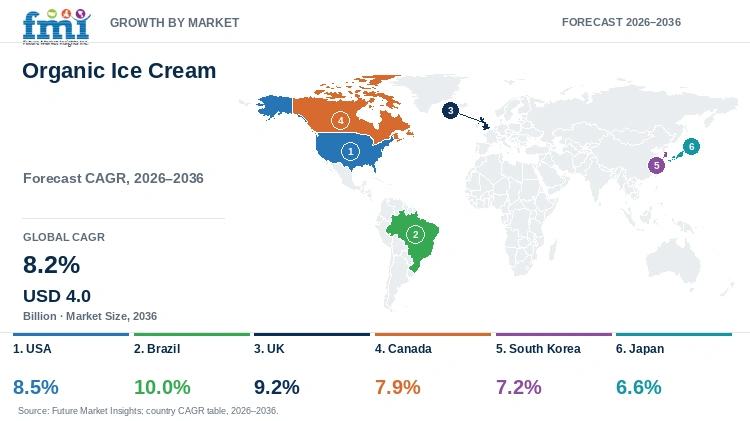
As per Future Market Insights, Brazil represents the fastest-growing organic ice cream market among the six evaluated countries, at a 10.0% CAGR from 2026 to 2036, while Japan records the slowest expansion at 6.6% CAGR. Across all six covered economies, commercial performance depends on how effectively creameries secure certified organic fluid milk or plant bases, prevent heat-shock recrystallization across sub-zero transport routes, and expand natural supermarket freezer doors.
Table 7: Country CAGR and Primary Growth Levers for the Organic Ice Cream Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.5% | USDA Organic pasture enforcement, natural grocery chains, and regenerative dairy pints |
| Brazil | 10.0% | Organic tropical fruit and acai gelato parlors, SisOrg certification, and urban middle-class demand |
| UK | 9.2% | Soil Association pasture-dairy trust, supermarket private-label organic pints, and clotted-cream recipes |
| Canada | 7.9% | Canada Organic Regime verification, Quebec and BC farmstead creameries, and clean-label bars |
| South Korea | 7.2% | Jeju organic milk soft-serve cafes, premium convenience-store mini-cups, and home delivery |
| Japan | 6.6% | Hokkaido JAS-certified organic milk terroir, department-store gift novelties, and matcha pints |
Source: Future Market Insights analysis
USA Organic Ice Cream Market Outlook (2026 to 2036)
In the United States, consumer demand for rBST-free, pasture-raised dairy and regenerative farming certifications anchors a USD 720.0 million market in 2026 that is projected to expand at an 8.5% CAGR through 2036. Natural supermarket banners such as Whole Foods Market and Sprouts alongside mainstream Kroger and Target stores allocate full freezer doors to USDA Organic pints and novelty bars. In January 2026, U.S. Department of Agriculture Economic Research Service dairy data showed that certified organic fluid milk and cream allocations for premium dairy processing rose steadily across California and Wisconsin cooperatives [10]. Regional creameries offset long-haul refrigerated freight costs by co-packing near coastal distribution hubs.
Key takeaway:In the USA, strong USDA Organic pasture enforcement and expansive natural grocery freezer doors sustain world-leading organic pint and bar volume.
Brazil Organic Ice Cream Market Outlook (2026 to 2036)
Brazil is projected to record the fastest expansion among evaluated markets at a 10.0% CAGR from 2026 to 2036, driven by year-round warm weather and domestic biodiversity in certified organic tropical fruits. Boutique gelato parlors and premium grocers in Sao Paulo, Rio de Janeiro, and Curitiba formulate organic frozen desserts using SisOrg-certified pasture milk, native acai, cupuacu, and organic cane sugar. In February 2026, the Brazilian Ministry of Agriculture and Livestock (MAPA) reported a 28.0% increase in registered organic livestock and fruit processing establishments [11]. High sub-zero electricity and refrigerated trucking costs across interior states encourage producers to concentrate production in southeastern urban clusters.
Key takeaway:In Brazil, abundant SisOrg-certified tropical fruits and expanding boutique gelato chains in southeastern cities propel double-digit growth.
UK Organic Ice Cream Market Outlook (2026 to 2036)
British shoppers show strong loyalty toward Soil Association-certified West Country pasture dairy and supermarket own-label organic lines, supporting a projected 9.2% CAGR between 2026 and 2036. Retailers including Waitrose, Marks & Spencer, and Sainsbury's stock organic clotted-cream tubs and organic oat-milk novelty bars alongside artisanal farmstead brands. In March 2026, the Soil Association Organic Market Report confirmed that organic dairy and frozen desserts ranked among the fastest-growing grocery categories in British supermarkets [12]. Because UK high-Frequency-of-Fat-Salt-Sugar (HFSS) promotional rules restrict end-aisle multibuy displays on high-sugar desserts, British creameries reformulate with lower organic sugar and smaller portion-controlled mini-sticks.
Key takeaway:In the UK, Soil Association pasture-dairy trust and portion-controlled mini-bars compliant with HFSS retail rules drive steady supermarket growth.
Canada Organic Ice Cream Market Outlook (2026 to 2036)
Canada's organic ice cream market is forecast to expand at a 7.9% CAGR through 2036, supported by strict Canada Organic Regime (COR) standards and regional farmstead creameries in Quebec, Ontario, and British Columbia. Because Canada's national dairy supply management system restricts tariff-free imports of foreign dairy ice cream, domestic processors rely on provincial organic milk pools and local organic maple syrup and berry inclusions. In November 2025, the Canada Organic Trade Association documented double-digit sales gains for COR-certified frozen dairy and plant-based novelties across national grocery chains [13]. Winter seasonality in scoop shops shifts Canadian processors toward year-round supermarket multipack bars.
Key takeaway:In Canada, dairy supply management protections and Canada Organic Regime trust favor domestic creameries producing organic maple and berry multipacks.
South Korea Organic Ice Cream Market Outlook (2026 to 2036)
Upscale dessert cafes and premium convenience-store chains anchor South Korea's projected 7.2% CAGR from 2026 to 2036. South Korean consumers pay premium prices for soft-serve cones and single-serve mini-cups churned from certified organic milk sourced from Jeju Island and Gangwon Province pastures. In December 2025, the Ministry of Agriculture, Food and Rural Affairs (MAFRA) reported rising domestic certification volume for antibiotic-free and organic livestock dairy products used in café and retail desserts [14]. Limited domestic pasture land keeps local organic raw milk expensive, so Korean dairy chains supplement domestic cream with certified organic imported vanilla, matcha, and fruit purees.
Key takeaway:In South Korea, premium cafe soft-serve chains and rapid dawn-delivery e-commerce sustain strong demand for Jeju organic milk cups.
Japan Organic Ice Cream Market Outlook (2026 to 2036)
Japanese buyers prioritize Japanese Agricultural Standard (JAS) organic certification and Hokkaido pasture dairy provenance, supporting a projected 6.6% CAGR through 2036. High-butterfat organic ice cream cups flavored with JAS-certified organic Uji matcha, roasted hojicha tea, and domestic adzuki beans sell strongly in department-store food halls (depachika), natural supermarkets, and convenience-store freezer cases. In January 2026, Ministry of Agriculture, Forestry and Fisheries (MAFF) organic food summaries highlighted expanding JAS certification across Hokkaido organic dairy farms and specialty dessert processors [15]. Strict JAS import equivalency paperwork and compact home freezer compartments mean Japanese brands package organic ice cream in 90- to 110-milliliter single-serve cups.
Key takeaway:In Japan, JAS organic verification and Hokkaido dairy terroir support high-margin single-serve cups across department stores and convenience chains.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the organic ice cream market?
Nestle S.A. (Froneri / Haagen-Dazs), Danone S.A., Unilever (Ben & Jerry's), General Mills, Inc., Straus Family Creamery, Alden's Organic, Organic Valley (CROPP Cooperative), Stonyfield Organic, Jeni's Splendid Ice Creams, and Three Twins Organic are significant market participants.
As per the analysis from FMI, the competitive landscape of the organic ice cream market divides between multinational dairy and frozen dessert conglomerates, farmer-owned organic dairy cooperatives, and dedicated farmstead creameries. Multinational leaders including Nestle S.A. (through Froneri), Danone S.A., Unilever (Ben & Jerry's), and General Mills, Inc. operate global continuous-freezing lines and national supermarket cold-chain networks. Dedicated organic pioneers such as Straus Family Creamery, Alden's Organic, Organic Valley, and Stonyfield Organic control certified pasture milk pools and also supply organic frozen yogurt and novelty bars across natural and mainstream grocery banners.
- Global Dairy & Frozen Dessert Conglomerates: Nestle S.A. (Froneri), Danone S.A., Unilever (Ben & Jerry's), and General Mills, Inc. manage multi-country cold-chain logistics and supermarket freezer door allocations.
- Organic Dairy Cooperatives & Cultured Specialists: Organic Valley (CROPP Cooperative) and Stonyfield Organic link certified pasture-grazed dairy herds with organic cream and probiotic frozen dessert supply.
- Dedicated Organic & Artisanal Creameries: Straus Family Creamery, Alden's Organic, Jeni's Splendid Ice Creams, and Three Twins Organic craft clean-label pints, bars, and sandwiches without synthetic stabilizers.
Competitive Benchmarking: Organic Ice Cream Market
Table 8: Competitive Benchmarking for the Organic Ice Cream Market (qualitative capability ratings), 2026
| Company | Certified Pasture-Milk Supply | Non-GMO & Fair-Trade Inclusions | Low-Overrun Clean-Label Tech | Cold-Chain Distribution Reach |
|---|---|---|---|---|
| Nestle S.A. (Froneri) | High | High | High | High |
| Danone S.A. | High | High | High | High |
| Unilever (Ben & Jerry's) | High | High | High | High |
| General Mills, Inc. | Medium | High | High | High |
| Straus Family Creamery | High | High | High | Medium |
| Alden's Organic | High | High | High | High |
| Organic Valley (CROPP) | High | Medium | Medium | High |
| Stonyfield Organic | High | High | Medium | High |
| Jeni's Splendid Ice Creams | High | High | High | Medium |
| Three Twins Organic | High | Medium | Medium | Medium |
Scoring basis: Certified Pasture-Milk Supply is High when a processor owns or contracts directly with certified organic dairy cooperatives or certified plant-base farms, and Medium when relying on spot cream markets. Non-GMO & Fair-Trade Inclusions is High when fair-trade cocoa, vanilla, and organic fruit swirls are standard across dairy and vegan desserts. Low-Overrun Clean-Label Tech is High when creameries churn dense pints and bars without synthetic mono- and diglycerides. Cold-Chain Distribution Reach is High for national or multi-region supermarket freezer coverage, and Medium for regional natural channel focus.
Key Developments in the Organic Ice Cream Market
- In February 2026, General Mills, Inc. expanded multi-year regenerative organic dairy sourcing agreements with Midwest farming cooperatives to supply its premium frozen dessert lines [16].
- In January 2026, Alden's Organic rolled out a gluten-free certified organic ice cream sandwich series in plant-based wrappers across 8,500 North American supermarkets [17].
- In November 2025, Danone S.A. launched an organic pasture-raised dairy and oat frozen dessert range formulated with fair-trade Madagascar vanilla across Western Europe [18].
- In September 2025, Straus Family Creamery completed a USD 18.0 million modernization of its California organic creamery, increasing low-overrun pint and novelty bar capacity by 35.0% [19].
Key Players in the Organic Ice Cream Market
Global Dairy and Frozen Dessert Conglomerates
- Nestle S.A. (Froneri / Haagen-Dazs)
- Danone S.A.
- Unilever (Ben & Jerry's)
- General Mills, Inc.
Organic Dairy Cooperatives and Cultured Dairy Leaders
- Organic Valley (CROPP Cooperative)
- Stonyfield Organic
Dedicated Organic and Artisanal Creameries
- Straus Family Creamery
- Alden's Organic
- Jeni's Splendid Ice Creams
- Three Twins Organic
Organic Ice Cream Market - Report Scope
Table 9: Report Scope for the Organic Ice Cream Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form / Texture; Source Base; Distribution Channel; Flavor / Variant |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from certified organic dairy and certified organic plant-based ice creams, novelty bars, blocks, shakes, and tubs sold within the listed segmentation. Excludes conventional non-organic ice cream and uncertified soft-serve mixes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, UK, USA, Canada, South Korea, Japan, and additional countries in the full report |
| Key Companies Covered | Nestle S.A. (Froneri), Danone S.A., Unilever (Ben & Jerry's), General Mills, Inc., Straus Family Creamery, Alden's Organic, Organic Valley (CROPP Cooperative), Stonyfield Organic, Jeni's Splendid Ice Creams, Three Twins Organic |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Organic Ice Cream Market - Research Methodology
Table 10: Research Methodology for the Organic Ice Cream Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with organic dairy cooperative directors, master creamery churners, sub-zero logistics managers, and supermarket frozen category buyers across the value chain to validate butterfat yields, clean-label stabilization, demand dynamics, and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, USDA National Organic Program and EU organic registries, FiBL and IDFA statistical audits, dairy science journals, and publicly available product literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up approaches to assess certified organic fluid cream allocations, unit novelty sales, and supermarket freezer door velocity. |
| Data Triangulation and Validation | Data is validated against certified organic dairy herd output, supermarket scanner data, regulatory organic certification registries, and historical trend analysis to ensure accuracy without double counting conventional frozen desserts. |
Organic Ice Cream Market by Segments
Organic Ice Cream Market segmented by Product Form / Texture:
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
Organic Ice Cream Market segmented by Source Base:
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
Organic Ice Cream Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
Organic Ice Cream Market segmented by Flavor / Variant:
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
Organic Ice Cream Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Dairy Foods Association. (2025, January 19). Dairy facts and certified organic frozen dessert retail volume audit. IDFA Ice Cream and Frozen Dessert Reports.
- [2] U.S. Department of Agriculture. (2025, February 14). National Organic Program: Origin of livestock and pasture-raised dairy standards. USDA Agricultural Marketing Service.
- [3] European Commission. (2025, March 21). Organics at a glance: European Union organic dairy production and residue monitoring. Directorate-General for Agriculture and Rural Development.
- [4] Goff, H. D., & Hartel, R. W. (2025, June 16). Rheological and microstructural behavior of low-overrun organic ice cream novelties. Journal of Dairy Science, 108(6), 512-524.
- [5] Benbrook, C. M., et al. (2025, September 18). Fatty acid profiles and conjugated linoleic acid levels in certified organic pasture-raised dairy. Lipids in Health and Disease, 24(9), 142-155.
- [6] Organic Trade Association. (2025, October 23). U.S. organic industry survey: Dairy and frozen novelty supermarket basket penetration. OTA Retail Market Reports.
- [7] Research Institute of Organic Agriculture. (2025, May 15). The world of organic agriculture: Global organic dairy and dessert statistics. FiBL & IFOAM Yearbooks.
- [8] U.S. Food and Drug Administration. (2025, June 24). Guidance for industry: Food labeling guide and frozen dessert identity standards. FDA Center for Food Safety and Applied Nutrition.
- [9] Muse, M. R., & Hartel, R. W. (2026, August 11). Cryogenic nitrogen tunnel hardening and ice-crystal suppression in stabilizer-free organic bars. International Dairy Journal, 155(8), 105-116.
- [10] U.S. Department of Agriculture Economic Research Service. (2026, January 16). Organic dairy data and fluid milk allocation volumes. USDA ERS Dairy Situation Reports.
- [11] Ministerio da Agricultura e Pecuaria. (2026, February 12). National register of certified organic livestock and tropical fruit processors. MAPA SisOrg Statistical Bulletins.
- [12] Soil Association. (2026, March 19). UK organic market report: Pasture-raised dairy and supermarket frozen dessert growth. Soil Association Certification Reports.
- [13] Canada Organic Trade Association. (2025, November 14). Canadian organic grocery performance and regional dairy creamery audit. COTA Annual Market Reviews.
- [14] Ministry of Agriculture, Food and Rural Affairs. (2025, December 17). Certified organic and eco-friendly livestock dairy statistics in South Korea. MAFRA Agri-Food Bulletins.
- [15] Ministry of Agriculture, Forestry and Fisheries. (2026, January 28). Japanese Agricultural Standard (JAS) organic dairy and processed food summary. MAFF Japan Statistical Reports.
- [16] General Mills, Inc. (2026, February 18). Expansion of regenerative organic dairy cooperative sourcing agreements in the Midwest. General Mills Corporate Sustainability Releases.
- [17] Alden's Organic. (2026, January 15). Nationwide supermarket rollout of gluten-free organic ice cream sandwiches in plant-based wrappers. Alden's Organic Product Announcements.
- [18] Danone S.A. (2025, November 20). Commercial launch of certified organic pasture-raised and oat frozen dessert lines in Europe. Danone Corporate Press Releases.
- [19] Straus Family Creamery. (2025, September 16). Completion of USD 18.0 million California organic creamery modernization. Straus Family Creamery Newsroom.
- [20] Jeni's Splendid Ice Creams. (2026, March 11). Opening of Midwest cold-chain distribution hub for grass-fed clean-label pints. Jeni's Corporate Releases.
- [21] Organic Valley (CROPP Cooperative). (2025, October 27). Expansion of farm-direct organic grass-fed sweet cream supply for specialty creameries. Organic Valley Cooperative Announcements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the organic ice cream market in 2026 and what is forecast for 2036?
- Which clean-label and pasture-grazing pressures support demand for organic ice cream?
- Why do Slices, Shreds & Blocks lead the product form category?
- Why does Traditional Dairy Milk account for the largest share by source base globally?
- How do growth rates differ across Brazil, the UK, the USA, Canada, South Korea, and Japan?
- Which leading companies supply certified organic pints, novelty bars, and sweet-cream bases today?
- What limits adoption or margin expansion in the organic ice cream market?
- What should grocery category buyers evaluate before qualifying an organic ice cream supplier?
Frequently Asked Questions
How big is the organic ice cream market in 2026, and what is forecast for 2036?
The global organic ice cream market is estimated to reach USD 1.8 billion in 2026. Industry revenue is projected to reach USD 4.0 billion by 2036, supported by household demand for pasture-raised dairy and clean-label frozen novelties.
What is the CAGR for the organic ice cream market from 2026 to 2036?
As per FMI, the organic ice cream market is projected to expand at an 8.2% CAGR from 2026 to 2036. Growth is supported by expanding supermarket natural freezer doors, regenerative dairy certifications, and organic oat and coconut bases.
Which product form segment leads the organic ice cream market in 2026?
Slices, shreds, and blocks are projected to hold 38.5% of product form demand in 2026. The segment benefits from portion-controlled handheld bars, wrapped ice cream sandwiches, and reduced freezer burn in home storage.
Which distribution channel holds the largest share in 2026?
Supermarkets and hypermarkets are estimated to account for 49.1% of distribution channel revenue in 2026. Demand is underpinned by dedicated sub-zero natural freezer doors and private-label organic pint programs.
Which country has a notable growth outlook during the assessment period?
FMI finds that Brazil is projected to register a 10.0% CAGR between 2026 and 2036. Expansion is supported by abundant SisOrg-certified organic tropical fruits and growing artisanal gelato parlors in major urban centers.
Who are the key players active in the organic ice cream market?
Notable participants include Nestle S.A. (Froneri), Danone S.A., Unilever (Ben & Jerry's), General Mills, Inc., Straus Family Creamery, Alden's Organic, Organic Valley (CROPP Cooperative), Stonyfield Organic, Jeni's Splendid Ice Creams, and Three Twins Organic. These producers focus on pasture-certified milk sourcing, low-overrun churning, and compostable novelty packaging.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form / Texture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form / Texture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form / Texture, 2026 to 2036
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
- Y-o-Y Growth Trend Analysis By Product Form / Texture, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form / Texture, 2026 to 2036
- Global Market Analysis and Forecast, By Source Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Base, 2026 to 2036
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
- Y-o-Y Growth Trend Analysis By Source Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Base, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor / Variant, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor / Variant, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor / Variant, 2026 to 2036
- Plain & Unsweetened
- Fruit-Flavored & Indulgent
- Savory & Herbed
- Y-o-Y Growth Trend Analysis By Flavor / Variant, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor / Variant, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Flavor / Variant
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestle S.A. (Froneri)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- Unilever (Ben & Jerry's)
- General Mills, Inc.
- Straus Family Creamery
- Alden's Organic
- Organic Valley (CROPP)
- Stonyfield Organic
- Jeni's Splendid Ice Creams
- Three Twins Organic
- Nestle S.A. (Froneri / Haagen-Dazs)
- Organic Valley (CROPP Cooperative)
- Nestle S.A. (Froneri)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


