

- Market Size (2026)
- USD 450.0 Bn
- Forecast (2036)
- USD 634.8 Bn
- CAGR (2026 to 2036)
- 3.5%
How big is Spirits Market in 2026?
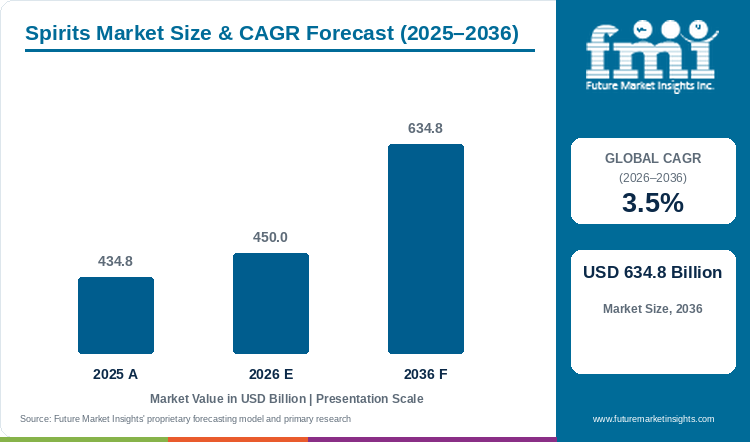
Between 2026 and 2036, global spirits valuation expands at an expected 3.5% CAGR after recording USD 434.8 billion during 2025, reaching a market size of USD 450.0 billion for 2026 and hitting USD 634.8 billion by 2036's close.
Adult drinkers are hosting more early-evening cocktail gatherings at home while trading up toward aged brown whiskies and 100% blue Weber agave tequilas. In February 2026, the Distilled Spirits Council of the United States reported in its Annual Economic Briefing that U.S. distilled spirits volume rose 1.9% to 318.1 million 9-liter cases in 2025 to preserve a leading 42.4% beverage alcohol share for the fourth consecutive year [1]. Global distilled spirits valuation logged USD 434.8 billion for the 2025 baseline and hits USD 450.0 billion across 2026 before climbing toward a 2036 target of USD 634.8 billion, where a 3.5% CAGR yields USD 184.8 billion across oak-matured distilled whiskeys. Within the 2026 landscape, Whiskey claims a projected 38.9% share of spirit categories and Oak-Cask Matured Brown Spirits represent a forecast 54.7% by maturation profile, whereas steep European excise duty hikes and distributor inventory resets continue to restrain unaged bulk white spirits.
Key Market Trends & Insights
- By spirit category: Whiskey captures a projected 38.9% during 2026 backed by strong emerging-market consumption of Indian and Scotch whiskies plus American bourbon.
- By price positioning: Mainstream & Value Spirits hold an estimated 54.9% for 2026 driven by high-volume everyday consumption across emerging markets and domestic off-trade chains.
- By sales channel: Off-Trade Liquor Stores & Supermarkets represent an expected 49.1% during 2026 owing to household spirits stocking and e-commerce liquor delivery.
- By ABV strength: Standard 37.5% to 43% ABV secures a forecast 51.3% for 2026 attributed to statutory bottling-proof definitions for whiskey and vodka along with gin and tequila.
- By primary container: 700 ml & 750 ml Flint/Amber Glass Bottles account for an anticipated 53.1% during 2026 enabled by harmonized international standard-of-fill regulations.
- By maturation profile: Oak-Cask Matured Brown Spirits are projected to hold 54.7% in 2026 fueled by charred-barrel vanillin extraction and age-statement prestige.
- By consumer occasion: At-Home Cocktail Mixing & Entertaining generates an estimated 56.3% occasion share for 2026 since home bartending lowers per-serve cocktail costs compared with nightclubs.
Regional Highlights
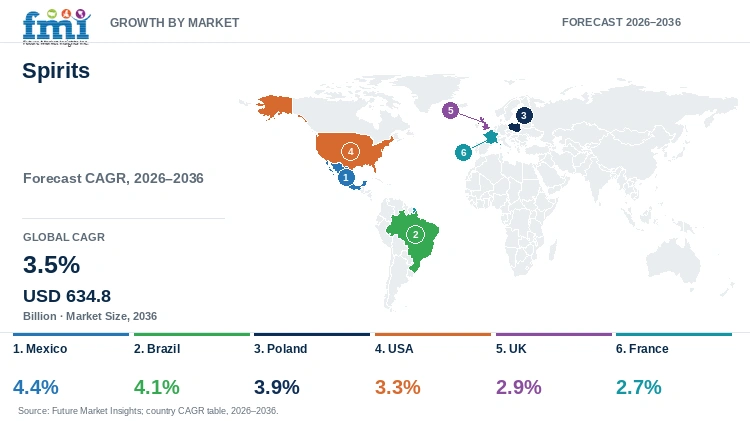
- Latin American agave and cane momentum: Mexican distilleries pace projected national spirits growth with a 4.4% CAGR until 2036 and Brazilian demand trails at 4.1% due to 100% agave tequila exports and aged cachaça adoption.
- European and North American trajectory: Polish spirits valuation expands at an expected 3.9% yearly clip accompanied by a 3.3% forecast rate in the USA, whereas British distilleries post 2.9% and French producers log 2.7% through aperitif and single-malt upgrades.
Market Size & Forecast
Table 1: Market Size and Forecast for the Spirits Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 434.8 billion |
| Estimated Market Size in 2026 | USD 450.0 billion |
| Projected Market Size by 2036 | USD 634.8 billion |
| CAGR, 2026 to 2036 | 3.5% |
| Added Market Value, 2026 to 2036 | USD 184.8 billion |
Regulatory harmonization of bottle capacities in the United States is allowing global distillers to unify European 700-milliliter glass molds with North American fractional cans and flasks. Federal bottling rules shifted in January 2025 when Treasury regulators at the TTB authorized 15 additional distilled-spirit container sizes spanning 187 milliliters to 3.75 liters while eliminating regulatory distinctions between cans and glass bottles [2]. Because of this rule change, multinational spirits houses are scaling fractional cocktail formats and spirit-based ready-to-drink cocktails across grocery and convenience shelves.
Distillery Case Volume and Cask Maturation Sizing
Table 2: Distillery Case Volume and Cask Maturation Sizing for the Spirits Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 434.8 | 450.0 | 634.8 |
| Global distilled spirits volume (billion 9-liter cases) | 2.68 to 2.76 | 2.72 to 2.81 | 3.28 to 3.45 |
| Maturing oak-cask spirit inventory (million barrels) | 84.0 to 91.0 | 86.5 to 94.0 | 108.0 to 118.0 |
| Average retail valuation per 9-liter case (USD) | 157.5 to 162.2 | 160.1 to 165.4 | 184.0 to 193.5 |
Operational note: Case volume and barrel inventory ranges reconcile global IWSR and DISCUS 9-liter case shipments against minimum 2-to-12-year bonded warehouse maturation schedules for Scotch and bourbon plus cognac and añejo tequila.
Distilleries maturing Scotch whisky and Kentucky straight bourbon along with reposado or añejo tequila must finance multi-year bonded warehouse inventories while losing 2% to 4% of liquid volume annually to evaporative angel's share. Consequently, master blenders pair aged brown spirits with unaged botanical-infused dry gins to balance immediate cash flow against long-term cask appreciation.
Per Capita & Off-Trade Channel Sizing
Table 3: Per Capita and Channel Valuation Indicators for the Spirits Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 53,024.4 | 54,216.9 | 70,533.3 |
| At-home cocktail occasion valuation share (%) | 55.8% | 56.3% | 58.9% |
| Oak-cask matured brown spirits share (%) | 54.2% | 54.7% | 57.4% |
Table 4: Segment & Container Valuation Indicators for the Spirits Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 450.0 billion | 2026 global spirits industry valuation baseline |
| Whiskey category market value, 2026 | USD 175.1 billion | 38.9% spirit category segment allocation |
| Off-trade liquor & supermarket value, 2026 | USD 221.0 billion | 49.1% sales channel segment allocation |
| 700 ml & 750 ml glass bottle value, 2026 | USD 239.0 billion | 53.1% primary container segment allocation |
Off-trade liquor stores and supermarket chains account for nearly half of global industry valuation because home hosts buy 700-milliliter and 750-milliliter bottles to mix margaritas and highballs plus spritzes at a fraction of bar menu prices. At the same time, hospitality groups stock artisanal smoky agave mezcals and aged Caribbean dark rums to anchor experiential cocktail menus.
Analyst Perspective
"Global distillers are navigating U.S. wholesaler destocking and European excise duty hikes by scaling 200-milliliter to 375-milliliter fractional flasks and bitter aperitif spritzes as well as emerging-market whiskies. Producers that pair bonded oak-cask reserves with agile standard-of-fill packaging will protect operating margins through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the spirits market segmented?
The spirits market is segmented by spirit category, price positioning, sales channel, ABV strength, primary container, maturation profile, consumer occasion, and region. In 2026, Whiskey is projected at 38.9%, Mainstream & Value Spirits at 54.9%, Off-Trade Liquor Stores & Supermarkets at 49.1%, Standard 37.5% to 43% ABV at 51.3%, 700 ml & 750 ml Glass Bottles at 53.1%, Oak-Cask Matured Brown Spirits at 54.7%, and At-Home Cocktail Mixing at 56.3%.
By spirit category: Whiskey, Vodka & White Spirits, Tequila, Mezcal & Agave Spirits, and Rum, Gin, Brandy & Liqueurs.
By price positioning: Mainstream & Value Spirits, and Premium, Super-Premium & Single-Malt.
By sales channel: Off-Trade Liquor Stores & Supermarkets, On-Trade Bars, Hotels & Restaurants, and Global Travel Retail / Duty-Free.
By ABV strength: Standard 37.5% to 43% ABV, Cask-Strength & Overproof Above 45% ABV, and Lower-ABV Spirit Aperitifs 20% to 35% ABV.
By primary container: 700 ml & 750 ml Flint/Amber Glass Bottles, 1.0L Travel-Retail & 1.75L Handle Formats, and Fractional 50 ml to 375 ml Flasks & Cans.
By maturation profile: Oak-Cask Matured Brown Spirits, Unaged Clear Rectified Spirits, and Botanical-Infused & Finished Cask Spirits.
By consumer occasion: At-Home Cocktail Mixing & Entertaining, On-Premise Bars, Nightlife & Fine Dining, and Luxury Gifting & Prestige Duty-Free.
Why does Whiskey lead the spirit category?
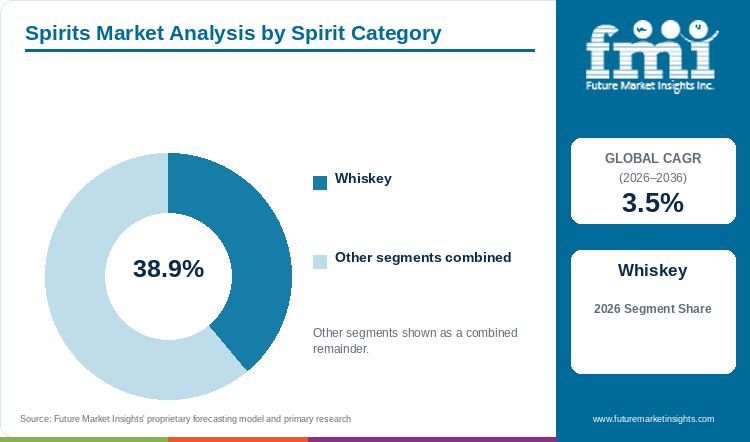
Whiskey claims 38.9% of 2026 spirit category valuation, supported by global demand for oak-aged malt and grain distillates.
Table 5: Spirit Category Share for the Spirits Market (percentage share), 2026
| Spirit Category | Share (2026) |
|---|---|
| Whiskey | 38.9% |
| Other Segments Combined | 61.1%* |
| Total | 100.0% |
*Note: Remaining spirit categories sum to 100.0% of 2026 spirits industry valuation.
Table 6: Spirit Category Leadership and Market Growth for the Spirits Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.5% |
| Leading Segment | Whiskey |
Whiskey anchors the global distilled spirits hierarchy because Scotch and American bourbon together with Irish and Indian malt whiskies span every price tier from everyday highballs to collector single malts. Furthermore, Oak-Cask Matured Brown Spirits account for a projected 54.7% slice across 2026 maturation profiles as charred oak barrels impart natural caramel color and smoky vanilla complexity. Distillers also extend whiskey brand equity into molasses and sugarcane distilled rums and cask-finished expressions.
- Whiskey commands a projected 38.9% weight across 2026 spirit category demand while Oak-Cask Matured Brown Spirits hold 54.7% by maturation profile.
- Pernod Ricard SA's August 2026 full-year release documented EUR 9,404 million in FY26 top-line receipts paired with EUR 2,423 million in recurring operating profit, led by 7% organic growth in India where Royal Stag reached roughly 32 million 9-liter cases [3].
Why do Mainstream & Value Spirits define the largest price positioning segment?
Mainstream & Value Spirits gather 54.9% of 2026 price positioning market size, driven by everyday household cocktail budgets.
While collector single malts and extra-añejo tequilas command high unit margins, mainstream and value bottles priced for everyday household budgets generate the majority of global case volume and category valuation. High food and housing inflation across North America and Europe has prompted middle-income shoppers to select trusted standard-tier bourbon and blended Scotch along with vodka and local cane spirits for routine entertaining. Meanwhile, brand owners reserve their luxury marketing budgets for high-end aged alcoholic beverages sold in fine dining and duty-free boutiques.
- Mainstream & Value Spirits command an estimated 54.9% across 2026 price positioning tiers due to resilient household demand for accessible 700-milliliter and 750-milliliter bottles.
- Diageo plc's August 2026 preliminary statement detailed USD 19,643 million across FY26 net receipts paired with USD 5,683 million in adjusted operating profit (+2.0% organic) while initiating an operating productivity program targeting USD 850 million in savings [4].
What keeps Off-Trade Liquor Stores & Supermarkets ahead by sales channel?
Off-Trade Liquor Stores & Supermarkets hold 49.1% of 2026 channel market size, reflecting home cocktail stocking.
State-licensed package liquor stores and supermarket beverage aisles together with club warehouses capture the largest share of spirits valuation because consumers prefer mixing cocktails at home rather than paying steep on-premise bar markups. In parallel, At-Home Cocktail Mixing & Entertaining holds an estimated 56.3% share across 2026 consumer occasions as afternoon spritzes and dinner-party cocktails replace late-night nightclub visits. Retailers support this shift by displaying bottled mixers with pre-mixed ready-to-serve bottled cocktails on end-cap gondolas.
- Off-Trade Liquor Stores & Supermarkets hold an expected 49.1% across 2026 sales channel valuation while At-Home Cocktail Mixing & Entertaining captures 56.3% by consumer occasion.
- In November 2025, Bacardi Limited published its 2026 Bacardi Cocktail Trends Report finding that 51% of younger legal-drinking-age adults in France and 34% in the United States are shifting toward earlier-evening social drinks and at-home spritz occasions [5].
Why does Standard 37.5% to 43% ABV lead the ABV strength category?
Standard 37.5% to 43% ABV represents 51.3% of 2026 strength market value, backed by statutory bottling proof laws.
Statutory spirit identity rules in the European Union and United Kingdom require a minimum 37.5% alcohol by volume for vodka and gin plus 40.0% ABV for Scotch whisky, while United States TTB standards mandate at least 40.0% ABV (80 proof) for bottled whiskey and agave spirits. Bottling within the 37.5% to 43.0% ABV band balances smooth cocktail mixability with per-liter alcohol excise tax efficiency. At the same time, distillers are expanding 20% to 35% ABV bitter aperitifs and zero-proof distilled spirit alternatives for daytime social occasions.
- Standard 37.5% to 43% ABV accounts for a forecast 51.3% within 2026 ABV strength market value because statutory identity laws anchor 40% ABV as the global bottling standard.
- Campari Group's March 2026 annual filing recorded EUR 3,051 million in 2025 net receipts (+2.4% organic) with EUR 637 million in adjusted EBIT, supported by 2% growth in its House of Aperitifs and 3% growth in its House of Agave [6].
What gives 700 ml & 750 ml Flint/Amber Glass Bottles the leading position in primary container?
700 ml & 750 ml Glass Bottles secure 53.1% of 2026 container market size, enabled by chemical inertness.
Heavyweight flint and amber glass bottles in 700-milliliter and 750-milliliter capacities remain the primary packaging format because glass is completely impermeable to oxygen and preserves high-proof ethanol ester profiles indefinitely. Following the January 2025 TTB standard-of-fill update permitting 700-milliliter spirits bottles in the United States, European and Japanese distillers can now run unified 700-milliliter bottling lines for global export. Meanwhile, distilleries package single-serve fractional cocktails in aluminum cans with single-serve canned cocktail beverages for stadium and beach venues.
- 700 ml & 750 ml Flint/Amber Glass Bottles capture an anticipated 53.1% across 2026 primary container valuation owing to unified trans-Atlantic bottle molds and bar back-bar ergonomics.
- Brown-Forman Corporation's December 2025 interim statement posted USD 2.0 billion across first-half fiscal 2026 operations and operating income of USD 565 million while launching Jack Daniel's Tennessee Blackberry and expanding New Mix RTDs by 28% [7].
What are the drivers, restraints, and opportunities in the spirits market?
In the spirits market, 100% blue agave tequila exports and emerging-market whiskey upgrades are projected to sustain valuation growth whereas alcohol excise tax hikes in Europe restrain volume and fractional 50 ml to 375 ml flasks create trial opportunities.
- Driver: Strong global demand for 100% blue Weber agave tequila and bitter aperitif spritzes plus aged whiskies supports steady per-case value expansion.
- Restraint: Steep excise duty increases across British and Polish tax regimes combined with cross-border tariff disputes pressure distributor inventory budgets.
- Opportunity: Fractional 50-milliliter to 375-milliliter flasks and botanical cask finishes along with spirits-based ready-to-drink cans attract younger legal-drinking-age cohorts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Distillers are capturing consistent value growth by shifting drinkers from unaged commodity spirits toward appellation-certified 100% agave tequilas and single-malt whiskies plus Italian bitter aperitifs. Even in regions where total alcohol volume is flat, cocktail enthusiasts seek out authentic geographic-indication bottles with verified barrel age statements. In April 2025, Constellation Brands, Inc. signed a definitive agreement to divest mainstream wine labels so management could concentrate its retained portfolio on high-margin craft spirits including High West Whiskey and Casa Noble Tequila while targeting over USD 200 million in annualized cost savings by fiscal 2028 [8]. Focused portfolio pruning allows major groups to reinvest behind high-velocity cocktail spirits.
Risk Assessment of the Spirits Market: Operational and Formulation Friction
Escalating national alcohol excise duties and retaliatory trade tariffs represent the sharpest operational headwinds confronting commercial distillers. When governments raise per-liter ethyl alcohol taxes to close fiscal deficits, retail bottle prices jump immediately and hospitality operators trim back-bar inventory depth. In April 2026, the Scotch Whisky Association and seven UK spirits trade bodies reported based on HMRC tax receipts data that UK spirits duty revenue fell by GBP 94 million in 2025/26-leaving receipts GBP 1.1 billion below original Treasury forecasts-following a 17% three-year spirits duty increase [9]. High excise burdens force distillers to absorb margin compression or offer smaller bottle sizes.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Producers are overcoming consumer price sensitivity by scaling fractional 50-milliliter and 200-milliliter flasks plus 375-milliliter bottles as well as real-spirit canned cocktails and lower-ABV botanical aperitifs. Fractional formats allow shoppers to sample super-premium bourbon or reposado tequila for under USD 15 before committing to a full 750-milliliter bottle. During February 2026, Suntory Holdings reported full-year 2025 alcoholic beverage results for Suntory Global Spirits while expanding Jim Beam and Maker's Mark along with Hibiki and -196 spirits-based RTDs across North American and European retail channels [10]. Accessible fractional sizes paired with authentic distillery provenance expand household penetration.
Spirits Market by Country (2026 to 2036)
Agave distillation in Mexico tops the six profiled spirits nations on an expected 4.4% yearly expansion clip through 2036, ahead of Brazilian cachaça and whiskey demand (4.1%) plus Polish spirit upgrades (3.9%). Across mature Western markets, United States industry size rises at a forecast 3.3% annual pace whereas British valuation gains 2.9% and French sales progress 2.7%.
Table 7: Country CAGR and Primary Growth Levers for the Spirits Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 4.4% | CRT-certified 100% Blue Weber agave tequila and artisanal mezcal production and tourism |
| Brazil | 4.1% | MAPA-registered oak-aged cachaça premiumization together with imported Scotch and gin growth |
| Poland | 3.9% | Protected-geographical-indication Polish vodka upgrades and flavored small-format flasks |
| USA | 3.3% | TTB expanded standards of fill, spirits-based RTDs, and bourbon and agave cocktail demand |
| UK | 2.9% | Single-malt Scotch tourism, bitter aperitif spritzes, and off-trade supermarket mixology |
| France | 2.7% | Early-evening spritz and rum cocktail adoption offsetting cognac export tariff headwinds |
Source: Future Market Insights analysis
Mexico Spirits Market Outlook (2026 to 2036)
Appellation-of-origin protection across Jalisco and four neighboring states makes Mexico the global epicenter for 100% blue Weber agave tequila and artisanal mezcal distillation. In March 2025, the Consejo Regulador del Tequila reported that Mexican tequila export volumes climbed 29.3% during January 2025 to hit 37.1 million liters across more than 120 countries, with 73% of shipments certified in the higher-value 100% Agave Tequila category [11]. In Mexico, projected spirits market value expands at a top-ranked 4.4% CAGR until 2036 fueled by lower raw agave piña costs and booming tequila cocktail tourism in Mexico City and Cancún. Distillers are also scaling agave-based ready-to-drink palomas across convenience chains.
Key takeaway: In Mexico, high-value 100% Blue Weber agave tequila certification and domestic paloma cocktail demand propel a projected 4.4% annual category gain.
Brazil Spirits Market Outlook (2026 to 2036)
Brazil combines massive domestic sugarcane cachaça distillation with rapidly growing urban middle-class consumption of imported Scotch whisky and London dry gin plus bitter aperitifs. According to the Cachaça Yearbook (Anuário da Cachaça) issued by federal agricultural authorities at MAPA in August 2026, registered cachaça distilleries across Minas Gerais and São Paulo are expanding amburana and oak-cask aged expressions together with federal export promotion programs [12]. Brazilian spirits market size climbs at a forecast 4.1% yearly pace across the ten-year forecast span to 2036 supported by on-trade cocktail bars and off-trade cash-and-carry atacarejo stores. Multinational beverage groups are also localizing gin and whiskey bottling plants across southeastern Brazil.
Key takeaway: In Brazil, oak-aged artisanal cachaça upgrades and expanding atacarejo off-trade distribution of whiskey and gin anchor a forecast 4.1% compound annual growth rate.
Poland Spirits Market Outlook (2026 to 2036)
Poland is the largest distilled spirits producer in Central and Eastern Europe, anchored by rye and potato vodkas together with fast-growing flavored liqueurs and imported Scotch whiskies. According to the Polish Ministry of Finance (podatki.gov.pl) excise duty schedule updated through July 2026, Poland's statutory excise tax rate on ethyl alcohol rose to PLN 7,991 per hectoliter of 100% vol. alcohol under the multi-year excise roadmap [13]. Despite retail price increases triggered by higher excise stamps, Polish spirits industry valuation advances at an expected 3.9% annual clip until 2036. Consumers are shifting from bulk unbranded clear spirits toward single-estate Polish vodkas and aged whiskies plus convenient 100-milliliter and 200-milliliter flavored pocket flasks.
Key takeaway: In Poland, consumer trade-up toward single-estate rye and potato vodkas and aged Scotch whisky underpins an expected 3.9% yearly expansion trajectory.
USA Spirits Market Outlook (2026 to 2036)
North American distillers anchor the world's highest-value national spirits pool across the USA, supported by 32 states plus Washington, D.C. permitting permanent cocktails-to-go and modernized TTB container rules. In its February 2026 Annual Economic Briefing presentation, DISCUS documented that premixed cocktails including spirits-based RTDs jumped 16.4% during 2025 to total USD 3.8 billion while vodka generated USD 7.0 billion and agave spirits totaled USD 6.4 billion ahead of American whiskey at USD 5.1 billion [14]. American spirits market size grows at an anticipated 3.3% annual rate until 2036 as bourbon tourism and 700-milliliter specialty imports together with real-spirit RTDs offset wholesaler inventory normalization across three-tier distribution channels.
Key takeaway: In the USA, 16.4% growth in spirit-based ready-to-drink cocktails and modernized TTB bottle-size rules are anticipated to anchor a 3.3% CAGR.
UK Spirits Market Outlook (2026 to 2036)
Home to the global Scotch whisky and London dry gin industries, the United Kingdom balances export-led single-malt distillation with dynamic domestic off-trade cocktail and aperitif culture. In February 2026, HM Revenue & Customs updated UK Alcohol Duty guidance setting the statutory duty rate for spirits above 22% ABV following inflation-linked budget uprating [15]. Although the 17% three-year excise duty climb has squeezed on-trade pub margins, British spirits market valuation expands at a predicted 2.9% annual pace from 2026 through 2036. Supermarket chains and Scottish distillery visitor centers are driving steady domestic value growth through single-malt cask editions and Italian bitter spritzes along with lower-ABV botanical infusions.
Key takeaway: In the UK, single-malt Scotch cask releases and off-trade bitter aperitif spritz growth maintain a predicted 2.9% compound annual pace despite high excise duties.
France Spirits Market Outlook (2026 to 2036)
France anchors European spirits craftsmanship through Charente cognac and Gascony armagnac along with aniseed pastis and overseas-department Martinique agricole rum. In February 2026, the Fédération des Exportateurs de Vins et Spiritueux de France reported that 2025 French wine and spirits export volumes declined 3% to 168 million cases while cognac shipments totaled 11.78 million cases amid Chinese and U.S. tariff friction [16]. Even with export headwinds on VSOP cognac, French domestic spirits valuation progresses at a slated 2.7% annual pace until 2036. French cocktail bars and hypermarket chains are recording strong domestic demand for spiced Caribbean rums and artisanal agave spirits plus early-evening low-ABV aperitif spritzes among younger urban adults.
Key takeaway: In France, rising domestic demand for aged Caribbean rum and early-evening aperitif spritzes delivers a slated 2.7% yearly expansion.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the spirits market?
Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Global Spirits, Brown-Forman Corporation, Campari Group, Constellation Brands, Inc., and Rémy Cointreau SA are the notable companies in the spirits market.
Market leadership across global distilled spirits hinges on multi-decade aging cask inventories and geographic-indication distillery ownership combined with three-tier wholesale and travel-retail distribution reach. Multinational portfolio leaders Diageo plc and Pernod Ricard SA span every major spirit category across more than 160 countries. Privately held Bacardi Limited and Suntory Global Spirits anchor rum and tequila plus American and Japanese whiskies, whereas Brown-Forman Corporation and Campari Group along with Constellation Brands, Inc. and Rémy Cointreau SA focus on high-margin bourbon and bitter aperitifs plus craft agave and fine cognac.
- Global Multi-Category Spirits Powerhouses: Diageo plc and Pernod Ricard SA operate worldwide route-to-market networks spanning Scotch and Irish whiskies along with agave spirits and vodka.
- International Whiskey, Rum & Agave Leaders: Bacardi Limited and Suntory Global Spirits together with Brown-Forman Corporation command vast maturing barrel reserves across Caribbean rum and Kentucky bourbon plus Japanese whisky and Highland tequila.
- Aperitif, Craft Spirits & Prestige Cognac Specialists: Campari Group together with Constellation Brands, Inc. and Rémy Cointreau SA target high-margin cocktail occasions across Italian bitter aperitifs and craft American whiskey plus Fine Champagne cognac.
Competitive Benchmarking: Spirits Market
Table 8: Competitive Benchmarking for the Spirits Market (qualitative capability ratings), 2026
| Company | Aged Cask & Category Breadth | Premium & Craft Positioning | Off-Trade / On-Trade Access | Geographic Reach |
|---|---|---|---|---|
| Diageo plc | High | High | High | High |
| Pernod Ricard SA | High | High | High | High |
| Bacardi Limited | High | High | High | High |
| Suntory Global Spirits | High | High | High | High |
| Brown-Forman Corporation | High | High | High | High |
| Campari Group | High | High | High | High |
| Constellation Brands, Inc. | Medium | High | High | Medium |
| Rémy Cointreau SA | Medium | High | Medium | High |
Scoring basis: Benchmark ratings assess verified maturing barrel inventories across Scotch and bourbon plus cognac and 100% agave tequila in addition to RTD and aperitif innovation. Channel and geographic ratings reflect three-tier U.S. distributor coverage and European off-trade listings as well as global duty-free presence.
Key Developments in the Spirits Market
- Diageo plc unveiled the first permanent prestige Scotch expression from its Johnnie Walker Vault luxury platform in October 2026 to expand collector single-malt and blended Scotch allocations [17].
- Pernod Ricard SA reported sequential organic improvement in its October 2026 first-quarter FY27 trading statement backed by its EUR 1 billion Fit for Future operational efficiency program [18].
- Diageo plc posted USD 10.5 billion across first-half fiscal 2026 operations in January 2026 for the six months ended December 31, 2025 while advancing Don Julio tequila and Guinness distribution [19].
Key Players in the Spirits Market
Global Multi-Category Spirits Powerhouses
- Diageo plc
- Pernod Ricard SA
International Whiskey, Rum & Agave Leaders
- Bacardi Limited
- Suntory Global Spirits
- Brown-Forman Corporation
Aperitif, Craft Spirits & Prestige Cognac Specialists
- Campari Group
- Constellation Brands, Inc.
- Rémy Cointreau SA
Spirits Market - Report Scope
Table 9: Report Scope for the Spirits Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Spirit Category; Price Positioning; Sales Channel; ABV Strength; Primary Container; Maturation Profile; Consumer Occasion; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial distiller and brand-owner market value from distilled alcoholic spirits including whiskey (Scotch, American bourbon/rye, Irish, Japanese, Canadian, Indian), vodka, tequila, mezcal, rum, cachaça, gin, brandy, cognac, liqueurs, bitter spirit aperitifs, and spirit-based premixed cocktails. Category Scope Note: Excludes fermented malt beer, hard malt seltzers, still and sparkling grape wines, and industrial fuel or pharmaceutical ethanol. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, Brazil, Poland, USA, UK, France, and additional countries in the full report |
| Key Companies Covered | Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Global Spirits, Brown-Forman Corporation, Campari Group, Constellation Brands, Inc., Rémy Cointreau SA |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Spirits Market - Research Methodology
Table 10: Research Methodology for the Spirits Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with master distillers, bonded warehouse directors, three-tier spirits wholesalers, off-trade retail liquor buyers, and duty-free category managers across North America, Latin America, and Europe. |
| Secondary Research | Analysis of corporate annual reports (Diageo, Pernod Ricard, Campari Group, Brown-Forman, Constellation Brands, Suntory, Bacardi), DISCUS economic briefings, TTB standard-of-fill rules, CRT tequila statistics, HMRC duty bulletins, FEVS export reports, and Polish Ministry of Finance excise schedules. |
| Market Sizing and Forecasting | Top-down distillery revenue and excise-adjusted retail valuation models reconciled against bottom-up 9-liter case shipments and maturing barrel inventories from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight legal-drinking-age demographic growth, alcohol excise tax schedules, agave and grain distillation capacity, and on-trade hospitality recovery across six major national markets. |
| Operational Benchmark Traceability | Case volume, barrel maturation, and channel valuation indicators in Tables 2, 3, and 4 trace to DISCUS 9-liter case statistics, CRT appellation registries, and TTB container standards. |
| Data Triangulation and Validation | Category valuation estimates are cross-checked against bonded distillery withdrawals and off-trade scanner audits without double counting malt-based seltzers or wine. |
Spirits Market by Segments
Spirits Market segmented by Spirit Category:
- Whiskey
- Vodka & White Spirits
- Tequila, Mezcal & Agave Spirits
- Rum, Gin, Brandy & Liqueurs
Spirits Market segmented by Price Positioning:
- Mainstream & Value Spirits
- Premium, Super-Premium & Single-Malt
Spirits Market segmented by Sales Channel:
- Off-Trade Liquor Stores & Supermarkets
- On-Trade Bars, Hotels & Restaurants
- Global Travel Retail / Duty-Free
Spirits Market segmented by ABV Strength:
- Standard 37.5% to 43% ABV
- Cask-Strength & Overproof Above 45% ABV
- Lower-ABV Spirit Aperitifs 20% to 35% ABV
Spirits Market segmented by Primary Container:
- 700 ml & 750 ml Flint/Amber Glass Bottles
- 1.0L Travel-Retail & 1.75L Handle Formats
- Fractional 50 ml to 375 ml Flasks & Cans
Spirits Market segmented by Maturation Profile:
- Oak-Cask Matured Brown Spirits
- Unaged Clear Rectified Spirits
- Botanical-Infused & Finished Cask Spirits
Spirits Market segmented by Consumer Occasion:
- At-Home Cocktail Mixing & Entertaining
- On-Premise Bars, Nightlife & Fine Dining
- Luxury Gifting & Prestige Duty-Free
Spirits Market by Region
- North America
- United States
- Canada
- Latin America
- Mexico
- Brazil
- Argentina
- Chile
- Colombia
- Western Europe
- United Kingdom
- France
- Germany
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Australia
- New Zealand
- ASEAN
- Middle East and Africa
- South Africa
- GCC Countries
- Turkiye
- Nigeria
Research Sources and Bibliography
- [1] Distilled Spirits Council of the United States (DISCUS). (2026, February 05). Distilled Spirits Council Annual Economic Briefing 2025. Distilled Spirits Council of the United States.
- [2] Alcohol and Tobacco Tax and Trade Bureau (TTB). (2025, January 10). TTB Adds New Standards of Fill for Wine and Distilled Spirits; Eliminates Distinction Between Standards of Fill for Distilled Spirits in Cans and Other Types of Containers. U.S. Department of the Treasury.
- [3] Pernod Ricard SA. (2026, August 27). FY26 Full-year Sales and Results. Pernod Ricard Group Regulated Information.
- [4] Diageo plc. (2026, August 06). 2026 Preliminary Results, year ended 30 June 2026. Diageo plc Investor Relations.
- [5] Bacardi Limited. (2025, November 17). Connections, Local Flavors, And Luxurious Experiences Top The 2026 Bacardi Cocktail Trends Report. Bacardi Limited Media Center.
- [6] Davide Campari-Milano N.V. (2026, March 04). Solid organic topline and margin growth leading to accelerated deleverage and dividend step-up: Full Year 2025 Results. Campari Group Investor Relations.
- [7] Brown-Forman Corporation. (2025, December 04). Brown-Forman Reports First Half Fiscal 2026 Results; Reaffirms Full Year Outlook. Brown-Forman Corporation Newsroom.
- [8] Constellation Brands, Inc. (2025, April 09). Constellation Brands Repositions Wine and Spirits Business to a Portfolio of Exclusively Higher-Growth, Higher-Margin Brands Aligned to Consumer-Led Premiumization Trends. Constellation Brands Corporate Newsroom.
- [9] The Scotch Whisky Association. (2026, April 21). Spirits sector responds to GBP 94m fall in UK spirits duty revenue. The Scotch Whisky Association Newsroom.
- [10] Suntory Global Spirits. (2026, February 13). Suntory Holdings 2025 Full-Year Alcoholic Beverage and Spirits Segment Performance Overview. Suntory Global Spirits Corporate Communications.
- [11] Consejo Regulador del Tequila (CRT). (2025, March 27). 2025 begins with an increase in Tequila exports. Consejo Regulador del Tequila A.C.
- [12] Ministerio da Agricultura e Pecuaria (MAPA). (2026, August 01). Anuario da Cachaca 2026: Registo de Produtores e Exportacoes de Cachaca. Ministerio da Agricultura e Pecuaria do Brasil.
- [13] Ministry of Finance of the Republic of Poland. (2026, July 04). Tax rates - Excise duty rates on ethyl alcohol and alcoholic beverages. Podatki.gov.pl Official Tax Portal.
- [14] Distilled Spirits Council of the United States (DISCUS). (2026, February 05). Annual Economic Briefing Presentation - 2026 U.S. Spirits Category and Premixed Cocktail Breakdown. Distilled Spirits Council of the United States.
- [15] HM Revenue & Customs (HMRC). (2026, February 01). Alcohol Duty rates. GOV.UK Official Statistics and Guidance.
- [16] Federation des Exportateurs de Vins et Spiritueux de France (FEVS). (2026, February 10). Exportations des vins et spiritueux francais en 2025. Federation des Exportateurs de Vins et Spiritueux de France.
- [17] Diageo plc. (2026, October 14). Johnnie Walker Vault Launches First Permanent Prestige Scotch Whisky Expression. Diageo plc Press Releases.
- [18] Pernod Ricard SA. (2026, October 15). Q1 FY27 Sales: Sequential Improvement in First-Quarter Organic Net Sales. Pernod Ricard Media & Reports.
- [19] Diageo plc. (2026, January 30). Diageo 2026 Interim Results: Six Months Ended 31 December 2025. Diageo plc Press Releases.
- [20] Davide Campari-Milano N.V. (2025, December 18). Campari Group Announces Portfolio Streamlining Disposals Exceeding EUR 210 Million. Campari Group Investor Relations.
- [21] Suntory Global Spirits. (2026, January 06). Suntory Global Spirits Names U.S. Chief Sales Officer and Expands North American Route-to-Market Alignment. Suntory Global Spirits Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the spirits market in 2026 and what is forecast for 2036?
- Which at-home cocktail and cask-maturation trends support global spirits demand?
- Why does Whiskey lead the spirit category ahead of white and agave spirits?
- Why do Mainstream & Value Spirits and Off-Trade channels capture the largest shares?
- How do growth rates differ across Mexico, Brazil, Poland, the USA, the UK, and France?
- Which multinational distillers lead global spirits production and barrel aging today?
- What excise tax and trade tariff hurdles restrain volume growth in mature markets?
- What should off-trade and hospitality buyers evaluate before selecting spirits suppliers?
Frequently Asked Questions
How big is the spirits market in 2026, and what is forecast for 2036?
After posting USD 434.8 billion during 2025, worldwide spirits market size stands at USD 450.0 billion in 2026 and is projected by FMI to attain a USD 634.8 billion industry valuation by 2036 as home bartenders favor aged whiskies and 100% agave tequilas.
What is the CAGR for the spirits market from 2026 to 2036?
Over the 2026 to 2036 forecast window, global spirits industry valuation is expected to expand at a 3.5% CAGR and generate USD 184.8 billion in net ten-year market growth according to FMI.
Which spirit category segment leads the spirits market?
Whiskey is projected to capture 38.9% of spirit category market value in 2026 backed by broad global consumption across Scotch and American bourbon plus Irish and Indian malt whiskies.
Which maturation profile and consumer occasion segments lead the spirits market?
Oak-Cask Matured Brown Spirits are projected to hold 54.7% by maturation profile in 2026 while At-Home Cocktail Mixing & Entertaining is estimated to command 56.3% by consumer occasion.
Which country has a notable growth outlook during the assessment period?
Mexico is projected to pace national growth at a 4.4% CAGR through 2036, driven by CRT-certified 100% Blue Weber agave tequila exports and domestic cocktail tourism.
Who are the key players in the market?
Diageo plc, Pernod Ricard SA, Bacardi Limited, Suntory Global Spirits, Brown-Forman Corporation, Campari Group, Constellation Brands, Inc., and Rémy Cointreau SA anchor global distillation and distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Spirit Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Spirit Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Spirit Category, 2026 to 2036
- Whiskey
- Vodka & White Spirits
- Tequila, Mezcal & Agave Spirits
- Rum, Gin, Brandy & Liqueurs
- Y-o-Y Growth Trend Analysis By Spirit Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Spirit Category, 2026 to 2036
- Global Market Analysis and Forecast, By Price Positioning, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Positioning, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Positioning, 2026 to 2036
- Mainstream & Value Spirits
- Premium, Super-Premium & Single-Malt
- Y-o-Y Growth Trend Analysis By Price Positioning, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Positioning, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Off-Trade Liquor Stores & Supermarkets
- On-Trade Bars, Hotels & Restaurants
- Global Travel Retail / Duty-Free
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By ABV Strength, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By ABV Strength, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By ABV Strength, 2026 to 2036
- Standard 37.5% to 43% ABV
- Cask-Strength & Overproof Above 45% ABV
- Lower-ABV Spirit Aperitifs 20% to 35% ABV
- Y-o-Y Growth Trend Analysis By ABV Strength, 2021 to 2025
- Absolute $ Opportunity Analysis By ABV Strength, 2026 to 2036
- Global Market Analysis and Forecast, By Primary Container, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Primary Container, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Primary Container, 2026 to 2036
- 700 ml & 750 ml Flint/Amber Glass Bottles
- 1.0L Travel-Retail & 1.75L Handle Formats
- Fractional 50 ml to 375 ml Flasks & Cans
- Y-o-Y Growth Trend Analysis By Primary Container, 2021 to 2025
- Absolute $ Opportunity Analysis By Primary Container, 2026 to 2036
- Global Market Analysis and Forecast, By Maturation Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Maturation Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Maturation Profile, 2026 to 2036
- Oak-Cask Matured Brown Spirits
- Unaged Clear Rectified Spirits
- Botanical-Infused & Finished Cask Spirits
- Y-o-Y Growth Trend Analysis By Maturation Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Maturation Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Consumer Occasion, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Consumer Occasion, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Consumer Occasion, 2026 to 2036
- At-Home Cocktail Mixing & Entertaining
- On-Premise Bars, Nightlife & Fine Dining
- Luxury Gifting & Prestige Duty-Free
- Y-o-Y Growth Trend Analysis By Consumer Occasion, 2021 to 2025
- Absolute $ Opportunity Analysis By Consumer Occasion, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Mexico
- Brazil
- Argentina
- Chile
- Colombia
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- France
- Germany
- Italy
- Spain
- Benelux
- Nordics
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- New Zealand
- ASEAN
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- GCC Countries
- Turkiye
- Nigeria
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- By Country
- Market Attractiveness Analysis
- By Country
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Spirit Category
- By Price Positioning
- By Sales Channel
- By ABV Strength
- By Primary Container
- By Maturation Profile
- By Consumer Occasion
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Diageo plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pernod Ricard SA
- Bacardi Limited
- Suntory Global Spirits
- Brown-Forman Corporation
- Campari Group
- Constellation Brands, Inc.
- Rémy Cointreau SA
- Diageo plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


