
- Market Size (2026)
- USD 85.8 Bn
- Forecast (2036)
- USD 134.5 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Glass Bottles Market in 2026?
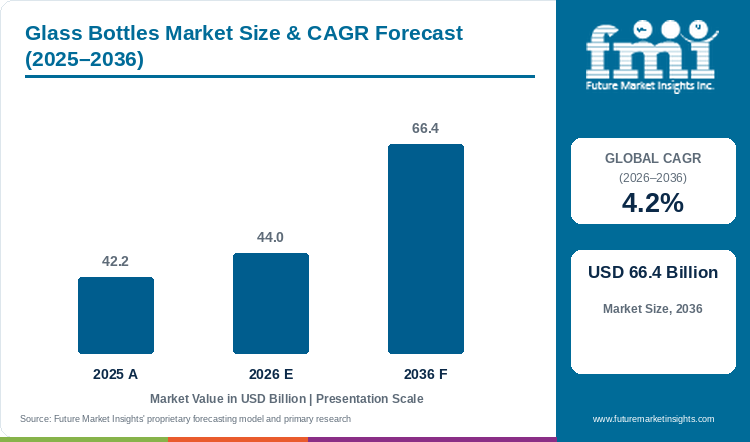
The glass bottles market demonstrated steady progress from USD 82.0 billion in 2025 to USD 85.8 billion in 2026, building toward a targeted valuation of USD 134.5 billion by 2036 at a CAGR of 4.6%.
The global glass bottles market was valued at USD 82.0 billion in 2025 and is estimated to reach USD 85.8 billion in 2026. Overall industry valuation is projected to reach USD 134.5 billion by 2036, expanding at a compound annual growth rate (CAGR) of 4.6% between 2026 and 2036. Alcoholic beverage containers for beer and spirits hold an estimated 44.5% share of 2026 demand, given that breweries and distilleries rely on chemically inert glass to prevent oxygen ingress and flavor scalping. FMI supply-chain analysis suggests that beverage and pharmaceutical brand owners are locking in multi-year bottle off-take contracts tied directly to furnace cullet ratios and Scope 3 carbon reductions, outpacing the broader commercial container glass baseline growth rate of 3.4%.
Official waste statistics updated by Eurostat in October 2026 confirm that the European Union achieved a 67.0% overall packaging waste recycling rate as member states enforce statutory 2030 recycling minimums of 75% for glass under the Packaging and Packaging Waste Regulation [1]. Glassmakers are rebuilding melting capacity to convert that compliance demand, evidenced when Verallia SA inaugurated its EUR 63 million hybrid melting tank at Zaragoza in April 2026 combining 70% renewable electricity with oxygen-fuel firing to produce up to 1.3 million containers per day [2]. Container producers that pair high-cullet hybrid melting with precision press-and-blow lightweighting secure long-term brewery and spirits supply tenders through 2036.
Key Market Trends & Insights
- By end-use industry: Beer Wine and Distilled Spirits Packaging holds an estimated 44.5% share in 2026 since returnable brewery bottle pools and prestige spirit flacons require zero gas permeability.
- By glass color grade: Amber Glass UV-Protective for Beer and Pharma represents 48.0% in 2026 owing to iron-sulfur-carbon chromophore absorption of wavelengths below 450 nanometers.
- By capacity volume: Up to 200 ml Miniature and Sample Sizes account for 41.5% in 2026 given high unit velocity across oral liquid medicines, functional wellness shots, and fractional spirit bottles.
- By glass chemistry: Soda-Lime Container Glass secures 68.0% in 2026 through continuous 300-to-500-tonne-per-day regenerative furnace economics and infinite cullet remelting.
- By neck finish: Crown and Twist-Off Beverage Finish commands 54.0% in 2026 supported by standardized 26mm pry-off and twist-off steel crown sealing on high-speed beer and soda lines.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at a 5.3% CAGR through 2036 under expanding returnable 600ml beer bottle pools and domestic furnace additions.
- Broader country progression: Mexico tracks at a 5.0% CAGR ahead of the United States at 4.8% and the United Kingdom at 4.6%. Germany advances at 4.5% and Japan at 4.4%, followed by Italy at 4.2% and France at 3.9%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Glass Bottles Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 82.0 billion |
| Estimated Market Size in 2026 | USD 85.8 billion |
| Projected Market Size by 2036 | USD 134.5 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 48.7 billion |
Electrification of 1,500-degree-Celsius glass melting furnaces combined with elevated post-consumer cullet batching has become the central economic lever governing container glass pricing. In January 2025, life-cycle assessment researchers publishing in MDPI Resources demonstrated that substituting virgin silica sand and soda ash with a 90% recycled glass cullet ratio reduces total bottle manufacturing energy demand by 27.2% while conserving 1.2 kilograms of virgin raw materials per kilogram of recycled glass [3]. Consequently, beverage procurement directors sourcing molded glass containers actively co-invest in municipal deposit-return schemes and optical cullet sorting plants to lock in lower-carbon bottle supply.
Furnace Tonnage and Cullet Energy Sizing
Table 2: Furnace Tonnage and Cullet Energy Sizing for the Glass Bottles Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 82.0 | 85.8 | 134.5 |
| Global container glass bottle output (million metric tons) | 88.5 to 93.0 | 91.8 to 96.5 | 132.0 to 140.0 |
| Post-consumer recycled cullet batch share (%) | 52.0% to 56.0% | 54.0% to 58.5% | 72.0% to 78.0% |
| Average furnace energy reduction via cullet (%) | 13.0% to 15.5% | 14.0% to 16.5% | 22.0% to 27.2% |
Chemical inertness and zero leachable migration separate glass bottles from polymeric and lined aluminum alternatives across sensitive pharmaceutical and premium beverage fillings. A January 2026 materials review in PubMed Central confirmed that container glass families encompassing soda-lime, pharmacopeial Type I borosilicate, and surface-dealkalized compositions provide unmatched hydrolytic stability and gas barrier protection for parenteral and liquid formulations [4]. This chemical stability explains why healthcare buyers expanding pharmaceutical glass packaging contracts specify Type I borosilicate and Type III amber soda-lime bottles despite higher freight weights.
Cullet Compliance & Furnace Technology Indicators
Table 3: Cullet Compliance and Furnace Technology Indicators for the Glass Bottles Market (percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| EU packaging waste overall recycling rate (%, Eurostat) | 67.0% | 68.5% | 76.0% |
| EU mandatory glass packaging recycling target (%) | 70.0% | 71.5% | 75.0%+ |
| Hybrid & electric glass furnace penetration (%) | 6.5% to 8.0% | 8.5% to 10.5% | 28.0% to 34.0% |
| Lightweight NNPB bottle share in beer & beverages (%) | 44.0% to 48.0% | 46.5% to 51.0% | 64.0% to 69.0% |
Table 4: Cullet Efficiency & Channel Spending Indicators for the Glass Bottles Market (USD and institutional baselines), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 85.8 billion | 2026 global glass bottles valuation baseline |
| 90% cullet batch energy reduction | 27.2% energy savings | MDPI Resources life-cycle craft-beer glass bottle study |
| Raw material saved per 1 kg recycled cullet | 1.2 kg virgin batch material | MDPI & GPI silica sand, soda ash, and limestone conservation |
| Beer, Wine and Spirits Packaging revenue, 2026 | USD 38.18 billion | 44.5% end-use industry allocation |
Optical cullet purification is resolving the historical trade-off between high recycled content and container mechanical strength on high-speed filling lines. Technical documentation from the Glass Packaging Institute in November 2025 notes that crushing post-consumer bottles to three-quarter-inch cullet and deploying multi-spectrum optical sorters removes ceramic, pyrex, and non-magnetic metal contaminants so new bottles return to store shelves within 30 days [5]. Wineries and spirit houses procuring premium wine packaging rely on color-separated flint, green, and amber cullet streams to achieve 70%+ recycled content without visual blisters or finish defects.
Analyst Perspective
"Beverage and pharmaceutical brands do not buy glass bottles as static commodity containers; they buy guaranteed shelf-life barrier protection paired with verifiable Scope 3 carbon reductions. Glassmakers that combine 70%-to-90% optically sorted cullet batches with hybrid electric furnaces and thin-wall NNPB forming will win multi-year supply agreements over legacy natural-gas plants."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Glass Bottles Market segmented?
The glass bottles market is segmented by end-use industry, glass color grade, capacity volume, glass chemistry, and neck finish. In 2026, Beer Wine and Distilled Spirits Packaging is projected at 44.5%, Amber Glass UV-Protective for Beer and Pharma at 48.0%, Up to 200 ml Miniature and Sample Sizes at 41.5%, Soda-Lime Container Glass at 68.0%, and Crown and Twist-Off Beverage Finish at 54.0%.
By end-use industry: Beer Wine and Distilled Spirits Packaging, Non-Alcoholic Beverages RTD Juices and Mineral Water, Pharmaceuticals and Liquid Medical Formulations, and Cosmetics Fragrances.
By glass color grade: Amber Glass UV-Protective for Beer and Pharma, Flint Clear Glass for Spirits and Premium Juices, Green Glass for Wine and Champagne, and Specialty Cobalt and Frosted Glass.
By capacity volume: Up to 200 ml Miniature and Sample Sizes, 201 ml to 500 ml Single-Serve Beverage Formats, 501 ml to 1000 ml Standard Wine and Spirit Bottles, and Above 1000 ml Large Formats.
By glass chemistry: Soda-Lime Container Glass, Type I Borosilicate Glass, Treated Type II De-Alkalized Glass, and High-Cullet Post-Consumer Recycled Glass.
By neck finish: Crown and Twist-Off Beverage Finish, Continuous Thread Screw Finish, Cork and Bar-Top Spirit Finish, and Crimp and Dropper Pharmaceutical Finish.
Why does Beer Wine and Distilled Spirits Packaging lead the end-use industry category?
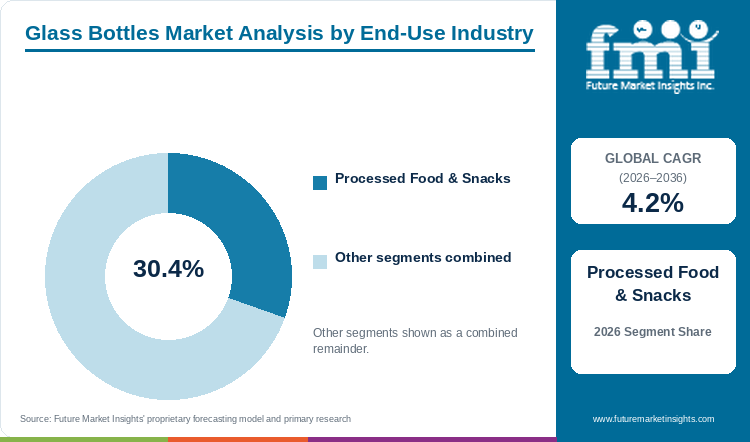
Beer Wine and Distilled Spirits Packaging holds an estimated 44.5% of end-use industry demand in 2026, anchored by oxygen impermeability and returnable brewery pool economics.
Table 5: End-Use Industry Share for the Glass Bottles Market (percentage share), 2026
| End-Use Industry | Share (2026) |
|---|---|
| Beer Wine and Distilled Spirits Packaging | 44.5% |
| Other Segments Combined | 55.5%* |
| Total | 100.0% |
*Note: Remaining end-use industry categories (Non-Alcoholic Beverages, Pharmaceuticals and Liquid Medical Formulations, plus Cosmetics Fragrances and Food Sauces Condiments) account for the balance of 2026 global demand.
Table 6: End-Use Industry Leadership and Market Growth for the Glass Bottles Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Beer Wine and Distilled Spirits Packaging |
Alcoholic beverage producers across commercial brewing, viticulture, and spirit distillation anchor container glass demand because glass is the only packaging substrate that prevents both oxygen ingress and ethanol or hop-ester aroma scalping over extended storage. Returnable brewery bottle pools in Latin America and Europe also circulate standard 330ml and 600ml glass bottles through twenty to forty washing and refilling trips, lowering per-fill packaging cost below aluminum cans. Bottlers evaluating rigid beverage bottles still face rising outbound freight bills on heavy export wine bottles, prompting estates to transition from 550-gram heritage moulds to 380-gram lightweight designs.
- Within the end-use industry segment, Beer Wine and Distilled Spirits Packaging is projected to account for a leading 44.5% share in 2026, supported by global craft beer and premium spirits demand.
- In June 2026, Close the Glass Loop and the European Container Glass Federation reported that European glass packaging collection for recycling reached a record 82.2%, with 85% of collected glass recycled in a closed bottle-to-bottle loop [6].
What sustains Amber Glass UV-Protective for Beer and Pharma leadership in the glass color grade segment?
Amber Glass UV-Protective for Beer and Pharma represents an estimated 48.0% of the glass color grade category in 2026, driven by 450-nanometer light filtration that prevents hop isohumulone skunky off-flavors and drug photolysis.
Amber container glass melted with iron oxide, sulfur, and carbon additions leads global color volume because the resulting ferri-sulfide chromophore blocks ultraviolet and blue visible light wavelengths below 450 nanometers. In brewing applications, amber glass prevents photochemical cleavage of hop iso-alpha-acids into 3-methyl-2-butene-1-thiol, which causes light-struck skunky off-flavors within minutes of sunlight exposure. A February 2026 study in MDPI Materials confirmed that amber and doped container glasses provide essential ultraviolet filtration and chemical durability for light-sensitive oral pharmaceuticals and biological formulations [7]. Producers of pressed glass tableware and container glass must still maintain tight redox control inside the furnace batch, since excessive organic contamination in post-consumer cullet can cause amber glass foaming.
- In 2026, Amber Glass UV-Protective for Beer and Pharma is anticipated to capture 48.0% of global glass color grade demand, reflecting critical photoprotection across beer and liquid medicine filling lines.
- Segment leadership is projected to hold firm through 2036 as amber cullet streams tolerate higher mixed-color recycled glass percentages than ultra-clear extra-flint spirit bottles.
How do Up to 200 ml Miniature and Sample Sizes lead the capacity volume category?
Up to 200 ml Miniature and Sample Sizes account for an expected 41.5% of capacity volume unit shipments in 2026, supported by single-dose pharmaceutical syrups, functional energy shots, and fractional spirit and fragrance flacons.
Small-format glass bottles holding 5ml to 200ml generate the highest unit volume across global forming machines because pharmaceutical oral syrups, cosmetic serums, and functional wellness shots require high-precision single-dose or multi-dose containment. High-speed individual-section forming machines configured in triple-gob or quad-gob operation produce up to 600 miniature bottles per minute from a single furnace forehearth, delivering strong unit economics. Brand owners sourcing retail glass packaging in small formats face higher glass-to-liquid weight ratios, driving engineers to adopt narrow-neck press-and-blow plungers for uniform thin wall distribution.
- By capacity volume, Up to 200 ml Miniature and Sample Sizes are estimated to reach 41.5% of total category share in 2026, driven by high-velocity pharmaceutical and cosmetic flacon demand.
- Gerresheimer AG reported in October 2026 that third-quarter group revenue reached EUR 605 million with EUR 103 million in adjusted EBITDA as pharmaceutical primary injectable glass stabilized [8].
Why does Soda-Lime Container Glass lead the glass chemistry category?
Soda-Lime Container Glass secures an anticipated 68.0% of glass chemistry demand in 2026, supported by continuous regenerative furnace throughput and closed-loop cullet remelting.
Soda-lime-silica glass composed of roughly 72% silica sand, 14% sodium oxide from soda ash, and 11% calcium oxide from limestone represents the foundational chemistry of the global bottle industry given its 1,500-degree-Celsius melting workability and full compatibility with post-consumer cullet loops. Unlike Type I borosilicate glass that requires expensive boron trioxide raw materials and higher melting temperatures, soda-lime glass forms rapidly on high-speed blow-and-blow and press-and-blow machines for beverages and oral medicines. In January 2025, O-I Glass detailed how increasing furnace electrification and cullet integration across its soda-lime container plants cuts greenhouse gas intensity while maintaining high-speed forming output [9]. Pharmaceutical fillers packaging high-pH parenteral biologics still specify Type I borosilicate or internal ammonium-sulfate de-alkalized Type II glass to prevent alkali ion delamination.
- Continuous regenerative furnace efficiency places Soda-Lime Container Glass on course to hold an estimated 68.0% share of the glass chemistry category in 2026.
- Over the 2026 to 2036 window, high-cullet soda-lime formulations incorporating 75% to 90% post-consumer recycled glass are forecast to capture the fastest incremental contract growth among beverage brands.
What gives Crown and Twist-Off Beverage Finish the leading position in neck finish?
Crown and Twist-Off Beverage Finish commands a projected 54.0% of neck finish share in 2026, enabled by high-speed rotary crowning lines and internal carbonation pressure retention.
Pry-off and twist-off 26mm crown neck finishes dominate global bottle production because they withstand internal carbonation pressures exceeding 4 to 6 bar during tunnel pasteurization and seal at speeds above 60,000 bottles per hour on rotary beverage fillers. Precision-ground neck ring moulds ensure exact lip profile tolerances so polymer-lined steel crowns maintain hermetic gas retention across transoceanic beer, cider, and carbonated soft-drink shipments. High-speed filling plants integrating infusion bottle seals and rotary crowners must still inspect every neck finish optically, since microscopic rim checks or out-of-roundness cause carbonation loss or glass chipping during capping.
- Crown and Twist-Off Beverage Finish is predicted to secure 54.0% of neck finish demand in 2026, supported by universal standardization across global beer and craft soda filling lines.
- In October 2026, computer-vision researchers publishing in MDPI Symmetry demonstrated that differential feature neural networks detect microscopic glass bottle finish and body defects with high segmentation accuracy on industrial inspection lines [10].
What are the drivers, restraints, and opportunities in the Glass Bottles Market?
In the glass bottles market, mandatory circular-packaging recyclability rules and premium alcoholic and pharmaceutical barrier needs are projected to drive adoption, whereas high natural-gas furnace energy costs and 12-year refractory rebuild capital lockups restrain rapid capacity additions and hybrid oxy-electric furnaces with narrow-neck press-and-blow lightweighting create new margin expansion avenues.
- Driver: Binding statutory glass recycling targets under EU PPWR and North American deposit laws paired with brand commitments to zero-plastic barrier packaging drive multi-year glass bottle procurement.
- Restraint: Intensive natural-gas furnace energy requirements, carbon-allowance costs, and multi-month furnace rebuild outages restrain short-term supply elasticity and squeeze producer margins.
- Opportunity: Commissioning hybrid oxy-electric melting furnaces capable of charging up to 90% recycled cullet and deploying narrow-neck press-and-blow lightweighting create low-carbon growth avenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Corporate decarbonization targets and consumer rejection of microplastic-leaching beverage containers are driving global breweries, spirit houses, and food brands to expand high-cullet glass bottle contracts. Because glass is 100% infinitely recyclable bottle-to-bottle without loss of mechanical clarity or barrier integrity, it satisfies stringent circularity grades under European Union Regulation (EU) 2025/40 and state extended producer responsibility statutes. In June 2026, German glassmaker Wiegand-Glas received an official funding commitment for its Project Eco2Furnace, a 420-tonne-per-day hybrid melting furnace engineered to operate on green electricity and incorporate up to 90% recycled post-consumer glass cullet [11]. This industrial transition allows glass bottle suppliers to cut container carbon footprints by more than half while securing long-term supply agreements with multinational beverage brands.
Risk Assessment of the Glass Bottles Market: Operational and Formulation Friction
Continuous 24-hour furnace operation at 1,500 degrees Celsius exposes container glass manufacturers to severe natural-gas price volatility, European Union Emissions Trading System carbon costs, and periodic refractory campaign rebuild disruptions. When a furnace reaches the end of its twelve-to-fifteen-year refractory life or suffers an unscheduled electrode or crown failure, taking the tank offline halts output for several months and inflates fixed unit overhead. In February 2026, O-I Glass reported its full-year 2025 financial results and detailed ongoing network capacity rationalization and furnace maintenance programs to offset elevated energy and operating pressures [12]. Brand owners procuring post-consumer cosmetic packaging consequently dual-source bottle moulds across multiple regional glass plants to insulate filling schedules against single-furnace rebuild outages.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Glassmakers capture substantial cost and environmental advantages by pairing press-and-blow container lightweighting with closed-loop hospitality and municipal cullet collection networks. Weight reductions on a standard 330ml beer bottle from 210 grams to 150 grams cut raw batch consumption, furnace melting energy, and outbound truck freight simultaneously without sacrificing vertical top-load strength. An October 2026 engineering study in MDPI Engineering Proceedings confirmed that post-consumer container glass recovery from beverage and food bottles represents the highest-value circular pathway for reducing industrial energy intensity and raw silica extraction [13]. Co-deployment of ultra-lightweight returnable glass bottles with polypropylene closure copolymers and wash-off labels enables beverage brands to achieve up to thirty refill cycles per bottle.
Glass Bottles Market by Country (2026 to 2036)
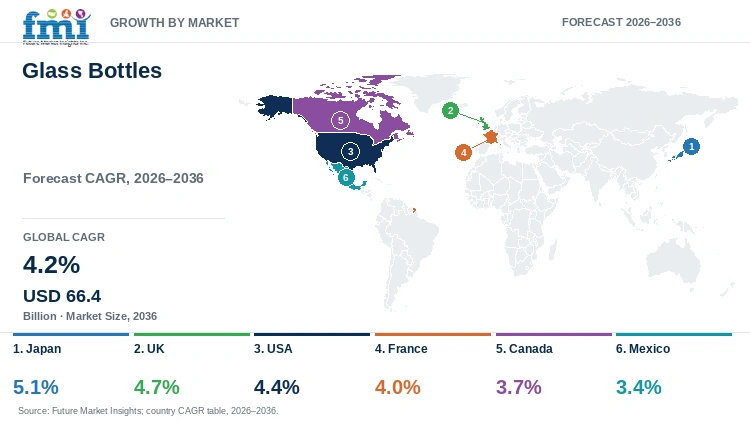
FMI country modeling indicates that Brazil leads glass bottles expansion at a 5.3% CAGR through 2036, followed by Mexico at 5.0% and the United States at 4.8%. National growth rates reflect differences in returnable brewery bottle pool infrastructure, export spirits and wine bottling capacity, and hybrid furnace electrification investments.
Table 7: Country CAGR and Primary Growth Levers for the Glass Bottles Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 5.3% | Returnable 600ml beer bottle pools and domestic Verallia and Vidrala furnaces |
| Mexico | 5.0% | Export tequila and craft beer bottling lines serving North American retail |
| United States | 4.8% | State EPR deposit expansion and domestic bourbon, craft beer, and pharma demand |
| United Kingdom | 4.6% | Scotch whisky export bottling and O-I Alloa low-carbon furnace investments |
| Germany | 4.5% | Mehrweg returnable brewery pools and Wiegand-Glas 90%-cullet hybrid furnaces |
| Japan | 4.4% | Lightweight single-serve functional tonic bottles and domestic cullet sorting |
| Italy | 4.2% | 76.4% packaging recycling rate and Prosecco, wine, and olive oil export bottling |
| France | 3.9% | Champagne, Cognac, and luxury perfumery flint and green bottle furnace rebuilds |
Source: Future Market Insights analysis
Brazil Glass Bottles Market Outlook (2026 to 2036)
Demand for glass bottles in Brazil is projected to expand at a leading 5.3% CAGR between 2026 and 2036 as major brewing groups and artisanal spirit distillers scale returnable 600ml amber bottle pools and single-serve long-neck formats. What distinguishes Brazil from North American beverage markets is the dominance of returnable glass beer bottles across neighborhood bars and supermarkets, supported by recent greenfield furnace additions from Verallia and Vidrala. In November 2025, USDA Foreign Agricultural Service analysts noted the resilience of Brazil's domestic food and beverage processing industry and expanding modern retail distribution channels [14]. Higher national disposable income and federal reverse-logistics glass recycling mandates further accelerate Brazilian glassmaker investments in cullet collection hubs across Sao Paulo, Minas Gerais, and southern brewing corridors.
Key takeaway: In Brazil, returnable 600ml brewery bottle pools and multi-furnace capacity expansions are projected to drive a leading 5.3% CAGR through 2036.
Mexico Glass Bottles Market Outlook (2026 to 2036)
The Mexican glass bottles market is anticipated to advance at a 5.0% CAGR from 2026 to 2036, supported by the country's position as the world's largest exporter of bottled beer and 100%-agave tequila and mezcal. Compared with European domestic wine markets, Mexican container glass furnaces operate at high utilization to supply cross-border export bottling plants concentrated in Jalisco and Nuevo Leon. In April 2026, Mexico City agricultural trade attachés documented sustained investment across Mexico's food and beverage processing sector despite macroeconomic headwinds [15]. Multinational glassmakers including Owens-Illinois, BA Glass, and Fevisa are expanding extra-flint spirit bottle decoration lines and high-speed amber beer bottle tanks in Mexico to serve North American premium alcohol demand.
Key takeaway: In Mexico, export beer and agave spirit bottling demand is anticipated to sustain a 5.0% CAGR over the 2026 to 2036 forecast period.
United States Glass Bottles Market Outlook (2026 to 2036)
In the United States, glass bottle sales are forecast to grow at a 4.8% CAGR over the 2026 to 2036 window across craft breweries and domestic bourbon and pharmaceutical fillers. American market dynamics differ from Europe because low municipal single-stream glass recycling rates historically constrained cullet availability, prompting industry coalitions and state legislatures to modernize bottle deposit and extended producer responsibility laws. In February 2026, the Glass Packaging Institute detailed how state extended producer responsibility frameworks taking effect in 2026 and state bottle deposit systems in Maine and Oregon are reshaping domestic cullet recovery [16]. New regional cullet processing hubs and quality upgrades at Ardagh, O-I Glass, and Anchor Glass plants strengthen domestic supply security.
Key takeaway: In the United States, state EPR and bottle-deposit cullet recovery paired with premium spirits and pharma bottling are forecast to support a 4.8% CAGR.
United Kingdom Glass Bottles Market Outlook (2026 to 2036)
Sales of glass bottles in the United Kingdom are estimated to progress at a 4.6% CAGR between 2026 and 2036, driven by Scotch whisky and gin export distillation and domestic craft brewing. What sets the United Kingdom apart from continental Europe is the heavy concentration of prestige flint spirit bottle production in Scotland and Northern England, where distillers require bespoke embossed moulds and low-carbon furnace credentials. In September 2026, the UK Department for Business and Trade issued updated compliance guidance on European Union Regulation (EU) 2025/40, detailing recyclability and packaging minimization rules taking effect from August 2026 for UK exporters shipping bottled goods into the EU [17]. Major furnace modernization investments by O-I Glass at Alloa and Encirc and Vidrala in England support British distillers' net-zero packaging roadmaps.
Key takeaway: In the United Kingdom, Scotch whisky export bottling and low-carbon furnace upgrades are estimated to drive a 4.6% CAGR through 2036.
Germany Glass Bottles Market Outlook (2026 to 2036)
Market demand in Germany is slated to climb at a 4.5% CAGR across 2026 to 2036, anchored by Europe's largest returnable Mehrweg beer and mineral-water bottle deposit network and a strong domestic pharmaceutical glass sector. Unlike single-use export bottle markets, German breweries and mineral-water wells rely on standardized pool bottles that undergo dozens of washing and refilling cycles before being crushed into color-pure cullet at an 80%+ national recycling rate. In March 2026, Berlin agricultural analysts reported that Germany's food and beverage processing industry represents the country's fourth-largest industrial sector [18]. German glassmakers led by Wiegand-Glas, Gerresheimer, and Ardagh are advancing hybrid oxy-electric furnace investments to insulate domestic beverage and pharma customers from natural-gas price swings.
Key takeaway: In Germany, the national Mehrweg returnable bottle pool and 90%-cullet hybrid furnace projects are slated to sustain a 4.5% CAGR.
Japan Glass Bottles Market Outlook (2026 to 2036)
Japanese glass bottle demand is predicted to rise at a 4.4% CAGR across the 2026 to 2036 horizon, supported by high-velocity 100ml functional nutritional tonic bottles and strict municipal color-sorted cullet collection. Japan diverges from Western container glass markets through its pioneering adoption of ultra-lightweight press-and-blow forming and external polymer scuff-coating technologies that allow thin-wall glass bottles to run safely in vending and retail channels. In September 2026, Tokyo agricultural trade analysts documented steady demand across Japan's retail food and ready-to-drink beverage chains as inbound tourism and premium domestic spirits consumption expanded [19]. Domestic glassmakers continue to optimize electric-boosted furnaces and high-cullet amber and flint batches to lower unit energy intensity.
Key takeaway: In Japan, high-volume 100ml nutritional tonic bottles and ultra-lightweight sake and whisky containers are predicted to support a 4.4% CAGR.
Italy Glass Bottles Market Outlook (2026 to 2036)
In Italy, the glass bottles market is forecast to record a 4.2% CAGR from 2026 through 2036 on the strength of global export demand for bottled Prosecco and extra-virgin olive oil. Italian glassmakers operate within one of Europe's most mature circular collection systems, with national packaging waste recycling already exceeding the European Union's 2030 statutory threshold at 76.4%. In April 2026, Rome agricultural attachés reported strong international export performance across Italy's wine and specialty food processing industries [20]. Domestic furnace operators including Verallia Italia, Zignago Vetro, and Bormioli Luigi are investing in high-cullet UV-filtering green and amber tanks and extra-flint cosmetic and spirits lines to serve Italian export brands.
Key takeaway: In Italy, export wine and olive oil bottling paired with a 76.4% packaging recycling infrastructure are forecast to maintain a 4.2% CAGR.
France Glass Bottles Market Outlook (2026 to 2036)
French glass bottle revenue is projected to grow at a 3.9% CAGR during the 2026 to 2036 timeframe, representing Europe's premier value market for luxury Champagne and haute-parfumerie flacons. Compared with volume-driven beer bottle markets, France generates exceptional revenue per ton of melted glass because luxury spirits and fragrance houses specify heavy punt bases and intricate acid-etched or screen-printed bottle finishes. In April 2026, Paris agricultural attachés confirmed that France remains a dominant global wine and spirits supplier while domestic food processors adapt to national circular-packaging and reuse statutes [21]. Operation of Verallia's 100% electric furnace in Cognac and subsequent hybrid furnace investments across French glass plants enable luxury beverage and cosmetic brands to cut Scope 3 packaging emissions.
Key takeaway: In France, luxury Champagne and perfumery bottle production on electric and hybrid furnaces is estimated to support a 3.9% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Glass Bottles Market?
O-I Glass, Inc., Ardagh Group SA, Verallia SA, Vidrala SA, Gerresheimer AG, BA Glass BV, Wiegand-Glas GmbH, Anchor Glass Container Corporation, Vetropack Holding AG, and Stoelzle Glass Group are the notable companies in the glass bottles market.
Competitive structure in the glass bottles industry separates multinational multi-furnace beverage container giants, specialized pharmaceutical and prestige flacon manufacturers, and regional high-cullet European and American champions. O-I Glass, Inc. and Ardagh Group SA lead global beer, wine, and spirits bottle tonnage joined by Verallia SA and Vidrala SA across Europe and the Americas. Gerresheimer AG and Stoelzle Glass Group compete in Type I borosilicate pharmaceutical vials and extra-flint luxury spirits, while BA Glass BV and Wiegand-Glas GmbH compete with Anchor Glass Container Corporation and Vetropack Holding AG across regional beverage and food container supply.
- Multinational Beverage and Food Container Leaders: O-I Glass, Inc. and Ardagh Group SA, joined by Verallia SA and Vidrala SA, operate global networks of regenerative and hybrid glass furnaces.
- Pharmaceutical and Prestige Flacon Specialists: Gerresheimer AG and Stoelzle Glass Group engineer Type I borosilicate and extra-flint glass bottles for pharma, spirits, and perfumery.
- Regional High-Cullet and Specialty Champions: BA Glass BV and Wiegand-Glas GmbH, joined by Anchor Glass and Vetropack Holding, supply high-cullet amber and flint beverage containers.
Competitive Benchmarking: Glass Bottles Market
Table 8: Competitive Benchmarking for the Glass Bottles Market (qualitative capability ratings), 2026
| Company | Hybrid & Electric Furnace Tech | Lightweight NNPB & Cullet Rate | Beverage & Pharma Reach | Geographic Reach |
|---|---|---|---|---|
| O-I Glass, Inc. | High | High | High | Americas and Europe; MAGMA modular melting and hybrid furnace upgrades |
| Ardagh Group SA | High | High | High | Europe, North America, and Africa; NextGen hybrid furnace and quality systems |
| Verallia SA | High | High | High | Europe and Latin America; Cognac 100% electric and Zaragoza hybrid furnaces |
| Vidrala SA | Medium | High | High | Iberia, UK, Italy, and Brazil; high-margin beer, wine, and food container network |
| Gerresheimer AG | High | Medium | High | Global pharmaceutical Type I, II, and III molded and tubular glass bottle leader |
| BA Glass BV | High | High | Medium | Iberia, Poland, Greece, Southeast Europe, and Mexico; 12B+ containers/year |
| Wiegand-Glas GmbH | High | High | Medium | Germany; 420-tonne/day Eco2Furnace hybrid project with up to 90% cullet |
| Anchor Glass Container Corporation | Medium | Medium | Medium | United States specialty beer, liquor, and food glass manufacturing across 4 plants |
| Vetropack Holding AG | High | High | Medium | Switzerland, Austria, Czechia, Croatia, Italy, and Eastern Europe Strategy 2035 |
| Stoelzle Glass Group | High | Medium | High | Austria, Poland, UK, France, and USA prestige spirits, pharma, and perfumery glass |
Key Developments in the Glass Bottles Market
- In April 2026, Verallia SA inaugurated its first hybrid furnace at its Zaragoza plant in Cuarte de Huerva, Spain, in a project developed with Sorg representing a total investment of EUR 63 million. The furnace combines 70.0% renewable electricity with 30.0% natural gas or biofuel across three production lines and, at full capacity, will raise the site’s output to 1.3 million containers per day [25].
- In September 2026, Vetropack Holding AG presented Strategy 2035 and its first medium-term financial outlook for 2030 at a Capital Markets Day held at its head office in Bülach, Switzerland. The revised strategy targets profitable growth through optimisation of the product mix, efficiency improvements, and targeted initiatives for market development, with Vetropack aiming for a double-digit return on capital employed in the medium term [26].
- In October 2026, Vidrala, S.A. expanded its share buyback and treasury-share amortisation programme to 4.0% of share capital, raising the maximum aggregate amount to EUR 120 million. The expansion followed two earlier extensions to the programme first announced in December 2025 and represents the largest shareholder-remuneration commitment in the company’s history [27].
Key Players in the Glass Bottles Market
Multinational Beverage and Food Container Leaders
- O-I Glass, Inc.
- Ardagh Group SA
- Verallia SA
- Vidrala SA
Pharmaceutical and Prestige Flacon Specialists
- Gerresheimer AG
- Stoelzle Glass Group
- BA Glass BV
- Wiegand-Glas GmbH
Regional High-Cullet and Specialty Champions
- Anchor Glass Container Corporation
- Vetropack Holding AG
Glass Bottles Market - Report Scope
Table 9: Report Scope for the Glass Bottles Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | End-Use Industry; Glass Color Grade; Capacity Volume; Glass Chemistry; Neck Finish |
| Quantitative Units | USD Billion |
| Market Definition | Includes global manufacturer revenue from narrow-neck and specialty blown or pressed-and-blown glass bottles across beer, wine, spirits, non-alcoholic beverages, pharmaceuticals, cosmetics/perfumery, and liquid food condiments. Category Scope Note: Excludes wide-mouth household mason canning jars, flat architectural float glass, automotive windshields, and laboratory optical glassware. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Germany, Japan, Italy, France, and additional countries in the full report |
| Key Companies Covered | O-I Glass, Inc., Ardagh Group SA, Verallia SA, Vidrala SA, Gerresheimer AG, BA Glass BV, Wiegand-Glas GmbH, Anchor Glass Container Corporation, Vetropack Holding Ltd., Stoelzle Glass Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Glass Bottles Market - Research Methodology
Table 10: Research Methodology for the Glass Bottles Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with container glass furnace engineers, optical cullet sorting operators, brewery and distillery packaging directors, and pharmaceutical Type I/III glass quality managers to validate cullet batch ratios and per-ton melting costs. |
| Secondary Research | Analysis of Eurostat packaging waste datasets, European Commission Regulation (EU) 2025/40 (PPWR), Glass Packaging Institute (GPI) and OIV technical standards, USDA FAS global beverage reports, and corporate financial filings. |
| Market Sizing and Forecasting | Top-down global rigid packaging baselines reconciled against bottom-up container glass furnace pull tonnage (91.8M to 96.5M MT in 2026) and average selling prices across amber, flint, and green bottles from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight domestic brewing and distillation output, returnable deposit-return bottle pool turn rates, cullet collection infrastructure, and hybrid furnace capital expenditures across eight national markets. |
| Operational Benchmark Traceability | Tonnage, cullet energy savings, and recycling indicators in Tables 2, 3, and 4 trace to Eurostat October 2026 waste statistics, MDPI January 2025 craft-beer glass LCA models, and GPI technical documentation. |
| Data Triangulation and Validation | Revenue estimates isolate commercial glass bottles across beverage, pharmaceutical, cosmetic, and condiment filling lines while strictly excluding flat glass, fiberglass, and metal closures. |
Glass Bottles Market by Segments
Glass Bottles Market segmented by End-Use Industry:
- Beer Wine and Distilled Spirits Packaging
- Non-Alcoholic Beverages RTD Juices and Mineral Water
- Pharmaceuticals and Liquid Medical Formulations
- Cosmetics Fragrances and High-End Perfumery
Glass Bottles Market segmented by Glass Color Grade:
- Amber Glass UV-Protective for Beer and Pharma
- Flint Clear Glass for Spirits and Premium Juices
- Green Glass for Wine and Champagne
- Specialty Cobalt Blue and Frosted Glass
Glass Bottles Market segmented by Capacity Volume:
- Up to 200 ml Miniature and Sample Sizes
- 201 ml to 500 ml Single-Serve Beverage Formats
- 501 ml to 1000 ml Standard Wine and Spirit Bottles
- Above 1000 ml Large Formats and Flagons
- Multi-Trip Returnable Pool Formats
Glass Bottles Market segmented by Glass Chemistry:
- Soda-Lime Container Glass
- Type I Borosilicate Glass
- Treated Type II De-Alkalized Glass
- High-Cullet Post-Consumer Recycled Glass
Glass Bottles Market segmented by Neck Finish:
- Crown and Twist-Off Beverage Finish
- Continuous Thread Screw Finish
- Cork and Bar-Top Spirit Finish
- Crimp and Dropper Pharmaceutical Finish
Glass Bottles Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Eurostat. (2026, October 16). Packaging waste statistics. European Commission Eurostat Statistics Explained.
- [2] Verallia SA. (2026, April 16). Verallia inaugurates its first hybrid furnace in Zaragoza, Spain, as a strategic milestone towards a more innovative and sustainable glass production model. Verallia Group Press Room.
- [3] Wojnarowska, M., Muradin, M., Paiano, A., & Ingrao, C. (2025, January 29). Recycled Glass Bottles for Craft-Beer Packaging: How to Make Them Sustainable? An Environmental Impact Assessment from the Combined Accounting of Cullet Content and Transport Distance. Resources, 14(2), 23 (MDPI Open Access).
- [4] National Library of Medicine. (2026, January 27). Packaging Glasses: From Containers to Encapsulation Composition, Properties, and Processing (PMCID: PMC12897758). PubMed Central Open Access.
- [5] Glass Packaging Institute. (2025, November 14). Glass Recycling Facts & Benefits: Glass Packaging Institute (GPI). Glass Packaging Institute Technical Publications.
- [6] Close the Glass Loop & FEVE. (2026, June 30). Glass Packaging Reaches Record High Collection for Recycling Rate at 82,2%. European Container Glass Federation Brussels Press Releases.
- [7] MDPI Materials. (2026, February 5). Packaging Glasses: From Containers to Encapsulation Composition across Soda-Lime, Borosilicate, and Recycled Cullet Families. Materials, 19(3), 506 (MDPI Open Access).
- [8] Gerresheimer AG. (2026, October 30). Gerresheimer Reports Revenue Growth and Stable Adjusted EBITDA in the Third Quarter of 2026. Gerresheimer AG Corporate News.
- [9] O-I Glass, Inc. (2025, January 22). O-I's Sustainable Progress Towards Decarbonization in Glass Packaging. Owens-Illinois Inc. Corporate Newsroom.
- [10] MDPI Symmetry. (2026, October 21). Glass Packaging Bottle Defect Segmentation via Differential Feature Selection and Spatial Feature Reconstruction. Symmetry, 18(10), 1753 (MDPI Open Access).
- [11] Wiegand-Glas Holding GmbH. (2026, June 30). Project "Eco2Furnace" receives funding commitment. Wiegand-Glas Corporate News.
- [12] O-I Glass, Inc. (2026, February 10). O-I Glass Reports Full Year and Fourth Quarter 2025 Results. Owens-Illinois Inc. Investor Relations.
- [13] MDPI Engineering Proceedings. (2026, October 27). Recent Developments in the Utilization of Glass Waste for Sustainable Applications. Engineering Proceedings, 147(1), 23 (MDPI Open Access).
- [14] USDA Foreign Agricultural Service. (2025, November 21). Brazil: Retail Foods Annual (GAIN Report BR2025-0035). U.S. Department of Agriculture Global Agricultural Information Network.
- [15] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual (GAIN Report MX2026-0022). U.S. Department of Agriculture Global Agricultural Information Network.
- [16] Glass Packaging Institute. (2026, February 12). A Shifting Landscape: Glass Packaging Institute (GPI). Glass Packaging Institute Policy Briefs.
- [17] GOV.UK & Department for Business and Trade. (2026, September 4). EU PPWR: Packaging and Packaging Waste Regulation. UK Government Official Business Guidance.
- [18] USDA Foreign Agricultural Service. (2026, March 30). Germany: Food Processing Ingredients Annual (GAIN Report GM2026-0007). U.S. Department of Agriculture Global Agricultural Information Network.
- [19] USDA Foreign Agricultural Service. (2026, September 28). Japan: Retail Foods Annual. U.S. Department of Agriculture Global Agricultural Information Network.
- [20] USDA Foreign Agricultural Service. (2026, April 2). Italy: Food Processing Ingredients Annual (GAIN Report IT2026-0001). U.S. Department of Agriculture Global Agricultural Information Network.
- [21] USDA Foreign Agricultural Service. (2026, April 3). Report Name: Food Processing Ingredients Annual (Paris, France, FR2026-0003). U.S. Department of Agriculture Global Agricultural Information Network.
- [22] Vidrala SA. (2026, October 28). Vidrala strengthens shareholder returns with a new share buyback programme. Vidrala SA Official Press Room.
- [23] Ardagh Group S.A. (2026, September 29). Glass Excellence in Action: AGP-North America Delivers 38% Improvement in Quality Performance. Ardagh Group Corporate News Centre.
- [24] Vetropack Holding Ltd. (2026, September 16). Vetropack presents new Strategy 2035 at Capital Markets Day. Vetropack Group Media News.
- [25] Verallia SA. (2026). Verallia inaugurates its first hybrid furnace in Zaragoza, Spain. Press release, 16 April 2026.https://www.verallia.com/wp-content/uploads/2026/04/PR_Verallia_Zaragoza_hybrid_furnace_inauguration_20260416.pdf
- [26] Vetropack Holding AG. (2026). Semi-annual report 2026 / Strategy 2035 Capital Markets Day. https://report.vetropack.com/h2026/?p=4578
- [27] Vidrala, S.A. (2026, October 28). Vidrala amplía su recompra de acciones hasta el 4% del capital y 120 millones de euros. https://www.vinetur.com/es/20261028109966/vidrala-amplia-su-recompra-de-acciones-hasta-el-4-del-capital-y-120-millones-de-euros.html
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the glass bottles market in 2026 and what is forecast for 2036?
- Which hybrid furnace electrification and cullet recycling factors support demand for glass bottles?
- Why does Beer Wine and Distilled Spirits Packaging lead the end-use industry category?
- Why does Amber Glass UV-Protective for Beer and Pharma lead the glass color grade category?
- How do growth rates differ across Brazil, Mexico, and the United States?
- Which leading companies operate hybrid beverage furnaces versus pharmaceutical glass plants?
- What natural-gas energy and furnace rebuild hurdles restrain the glass bottles market?
- What should beverage brands evaluate when specifying lightweight NNPB and high-cullet bottles?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Beer Wine and Distilled Spirits Packaging
- Non-Alcoholic Beverages RTD Juices and Mineral Water
- Pharmaceuticals and Liquid Medical Formulations
- Cosmetics Fragrances and High-End Perfumery
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Glass Color Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Glass Color Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Glass Color Grade, 2026 to 2036
- Amber Glass UV-Protective for Beer and Pharma
- Flint Clear Glass for Spirits and Premium Juices
- Green Glass for Wine and Champagne
- Specialty Cobalt Blue and Frosted Glass
- Y-o-Y Growth Trend Analysis By Glass Color Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Glass Color Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity Volume, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Capacity Volume, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Capacity Volume, 2026 to 2036
- Up to 200 ml Miniature and Sample Sizes
- 201 ml to 500 ml Single-Serve Beverage Formats
- 501 ml to 1000 ml Standard Wine and Spirit Bottles
- Above 1000 ml Large Formats and Flagons
- Multi-Trip Returnable Pool Formats
- Y-o-Y Growth Trend Analysis By Capacity Volume, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity Volume, 2026 to 2036
- Global Market Analysis and Forecast, By Glass Chemistry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Glass Chemistry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Glass Chemistry, 2026 to 2036
- Soda-Lime Container Glass
- Type I Borosilicate Glass
- Treated Type II De-Alkalized Glass
- High-Cullet Post-Consumer Recycled Glass
- Y-o-Y Growth Trend Analysis By Glass Chemistry, 2021 to 2025
- Absolute $ Opportunity Analysis By Glass Chemistry, 2026 to 2036
- Global Market Analysis and Forecast, By Neck Finish, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Neck Finish, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Neck Finish, 2026 to 2036
- Crown and Twist-Off Beverage Finish
- Continuous Thread Screw Finish
- Cork and Bar-Top Spirit Finish
- Crimp and Dropper Pharmaceutical Finish
- Y-o-Y Growth Trend Analysis By Neck Finish, 2021 to 2025
- Absolute $ Opportunity Analysis By Neck Finish, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By End-Use Industry
- By Glass Color Grade
- By Capacity Volume
- By Glass Chemistry
- By Neck Finish
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- O-I Glass, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Ardagh Group SA
- Verallia SA
- Vidrala SA
- Gerresheimer AG
- BA Glass BV
- Wiegand-Glas GmbH
- Anchor Glass Container Corporation
- Vetropack Holding AG
- Stoelzle Glass Group
- O-I Glass, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Glass Color Grade, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Capacity Volume, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Glass Chemistry, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Neck Finish, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by End-Use Industry
- Figure 6: Global Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Glass Color Grade
- Figure 9: Global Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Capacity Volume
- Figure 12: Global Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Glass Chemistry
- Figure 15: Global Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Neck Finish
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Industry
- Figure 32: North America Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Glass Color Grade
- Figure 35: North America Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Capacity Volume
- Figure 38: North America Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Glass Chemistry
- Figure 41: North America Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Neck Finish
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 48: Latin America Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Glass Color Grade
- Figure 51: Latin America Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Capacity Volume
- Figure 54: Latin America Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Glass Chemistry
- Figure 57: Latin America Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Neck Finish
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 64: Western Europe Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Glass Color Grade
- Figure 67: Western Europe Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Capacity Volume
- Figure 70: Western Europe Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Glass Chemistry
- Figure 73: Western Europe Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Neck Finish
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Glass Color Grade
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Capacity Volume
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Glass Chemistry
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Neck Finish
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 96: East Asia Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Glass Color Grade
- Figure 99: East Asia Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Capacity Volume
- Figure 102: East Asia Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Glass Chemistry
- Figure 105: East Asia Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Neck Finish
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Glass Color Grade
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Capacity Volume
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Glass Chemistry
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Neck Finish
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Glass Color Grade, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Glass Color Grade, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Glass Color Grade
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Capacity Volume, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Capacity Volume, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Capacity Volume
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Glass Chemistry, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Glass Chemistry, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Glass Chemistry
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Neck Finish, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Neck Finish, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Neck Finish
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Glass Bottles Market in 2026, and what is forecast for 2036?
FMI calculates 2025 global glass bottles demand at USD 82.0 billion, rising to USD 85.8 billion in 2026 and reaching a projected USD 134.5 billion by 2036.
What is the CAGR for the Glass Bottles Market from 2026 to 2036?
The glass bottles sector is projected to expand at a 4.6% CAGR over the 2026 to 2036 window, adding USD 48.7 billion in incremental revenue across beverage and pharma lines.
Which end-use industry segment leads the Glass Bottles Market?
Beer Wine and Distilled Spirits Packaging holds an estimated 44.5% of end-use industry demand in 2026 since glass prevents oxygen ingress and preserves flavor profiles.
Which glass color grade segment leads the Glass Bottles Market?
Amber Glass UV-Protective for Beer and Pharma represents an estimated 48.0% of glass color grade demand in 2026 owing to ultraviolet light filtration below 450 nanometers.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at a 5.3% CAGR through 2036, driven by returnable 600ml beer bottle pools and domestic furnace capacity additions.
Who are the key players in the market?
Owens-Illinois Inc. and Ardagh Group SA lead global supply with Verallia SA and Vidrala SA. Gerresheimer and BA Glass also compete globally with Wiegand-Glas, Anchor Glass, Vetropack and Stoelzle.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
