

- Market Size (2026)
- USD 12,031.7 Mn
- Forecast (2036)
- USD 16,013.2 Mn
- CAGR (2026 to 2036)
- 2.9%
How big is Glass Tableware Market in 2026?
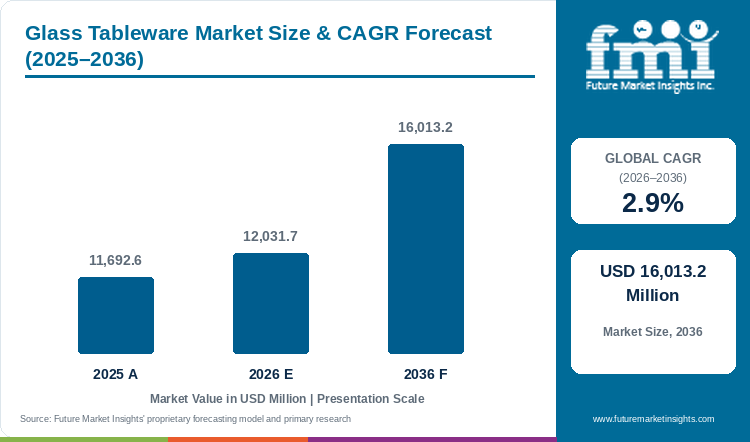
The CAGR for glass tableware over 2026 to 2036 comes to 2.9%. Sales came to USD 11,692.6 million in 2025. The 2026 estimate is USD 12,031.7 million. By 2036 the projection reaches USD 16,013.2 million.
The glass tableware market is on course for USD 16,013.2 million by 2036, expanding at a 2.9% CAGR between 2026 and 2036 on the FMI forecast. The 2026 estimate is USD 12,031.7 million, up from USD 11,692.6 million in 2025.
Glass plates, bowls and tumblers compete for table space in the tableware market, a parent category on a 4.3% CAGR from 2026 to 2036. At 2.9%, glass will cover a smaller part of each table setting. Porcelain bids for the same hotel plate orders, and the porcelain tableware market rises on a 7.2% CAGR over the decade to 2036. The 4.3-point CAGR gap between porcelain and glass will move hotel dinner plates to porcelain kilns.
Fuel supply sets glass tableware output, since furnaces burn fuel around the clock. Energy suppliers restricted LPG to the Borosil site in Jaipur under a force majeure notice, Glass International reported on 13 March 2026.[1] The borosilicate pressware furnace was suspended.[1]
Gas-fired makers will face limits in passing LPG and gas shocks into list prices. Electric and hybrid melting will gain as a fuel hedge, and hotel groups and retail chains will add supply security to unit price in annual tenders.
Beverage ware leads product sales on an estimated 46.3% share in 2026, and drinking glasses will therefore keep the largest block of furnace hours. Kitchen storage jars and jugs are expanding market boundaries through new applications.
Key Market Trends & Insights
- Product type: beverage ware leads with an estimated 46.3% in 2026, and tableware follows at about 31.8%.
- End-use: household buying carries an estimated 68.4% of 2026 sales. Borosil approved a Bharuch facility in March 2026 to meet growing demand for storage jars, glass bottles and glass jugs.[2]
- Sales channel: specialty stores take an estimated 27.6%, ahead of online retailers at about 18.7%.
Regional Highlights
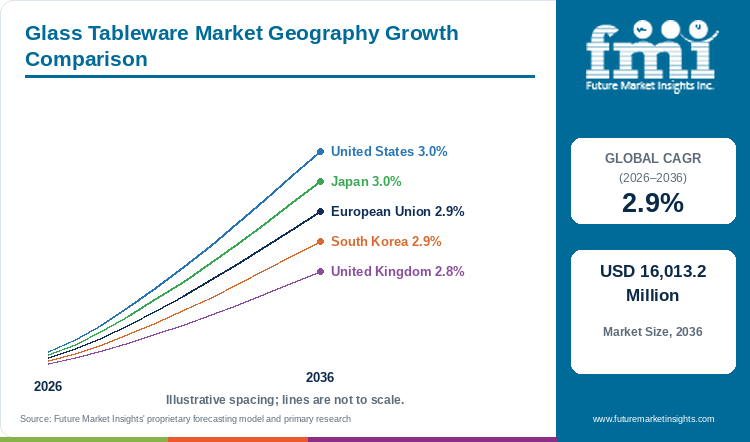
- The United States and Japan share the top profiled CAGR of 3% from 2026 to 2036.
- The United Kingdom posts the lowest CAGR for 2026 to 2036, 2.8%, below the European Union and South Korea on 2.9% each. FMI names Asia-Pacific as the fastest-growing region.
- In India, Borosil told the exchanges on 3 April 2026 that the Jaipur pressware and opal furnaces were fully restored to normal capacity.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Glass Tableware Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11,692.6 million |
| Estimated Market Size in 2026 | USD 12,031.7 million |
| Projected Market Size by 2036 | USD 16,013.2 million |
| CAGR, 2026 to 2036 | 2.9% |
| Added Revenue, 2026 to 2036 | USD 3,981.5 million |
| Market Expansion Multiple | 1.3x |
Glass tableware grows slower than tableware of all materials. Glass and ceramic pieces fill the same table settings in the tableware market, which posts a 4.3% CAGR from 2026 to 2036. Hotel groups re-equip dining rooms with porcelain plates, and the porcelain tableware market moves faster on a 7.2% CAGR over the same years. FMI data show glass tableware on a 2.9% CAGR, behind both, so glass makers will lean on drinkware more than on plates. Replacement buying of tumblers and stemware, part of the 46.3% beverage ware share, will carry the largest block of volume. Premium crystal and heat-resistant ranges will add value per piece faster than unit counts grow.
Fuel Supply, Furnace Rebuilds and Melting Capacity
Fuel cost and furnace size set the economics of scaling production in glassware. Borosil, Arc and Sisecam spent 2025 and 2026 resizing furnaces and cutting fuel exposure. Borosil plans to raise the Rajasthan borosilicate pressware furnace to 32 tons per day from 25 TPD, with the third forming line aligned to the rebuild cycle in January 2028, Glass International reported on 10 March 2026.[2] Borosilicate pressware uses the same glass chemistry as the wider borosilicate glass market. The March 2026 Borosil approval covered an INR420 million facility at Bharuch, with commercial production expected by December.[2] Borosil told analysts in August 2025 that power and fuel costs fell from INR20.4 crores to INR17.5 crores, helped by solar projects in Rajasthan.[4] Borosil put glassware utilization at around 60% to 65% on the August 2025 call.[4] Arc reported production capacity of 3 million glassware articles per day in 2025, and over a third of the Group furnaces are electric.[5] Sisecam relocated handmade glass production from Denizli to Kırklareli, Glass International reported in March 2026.[6] France had three hybrid furnaces commissioned in 2026, and some hybrid units have cut CO2 emissions by up to 64%.[7] Makers that time electric conversion to a planned rebuild will carry lower fuel risk into the 2030s.
Table 2: Furnace Energy and Capacity Indicators for the Glass Tableware Market (tons per day, units, INR and percentage), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Borosil Jaipur LPG supply, March 2026 | Pressware furnace suspended; opal furnaces at lower capacity | Fuel supply cuts halt glassware output quickly. | [1] |
| Borosil Jaipur furnaces, April 2026 | Fully restored to normal capacity | Recovery after LPG supply was secured. | [3] |
| Borosil borosilicate furnace plan, March 2026 | 32 TPD from 25 TPD | Capacity added at the rebuild cycle. | [2] |
| Borosil Bharuch facility, March 2026 | INR420 million | New mass lines for jars, bottles and jugs. | [2] |
| Borosil power and fuel cost, August 2025 call | INR17.5 crores from INR20.4 crores | Solar power cut energy costs at a glassware maker. | [4] |
| Borosil glassware utilization, August 2025 | Around 60% to 65% | Spare melting capacity in pressed glassware. | [4] |
| Arc production capacity, 2025 | 3 million glassware articles per day | Scale of the largest share holder. | [5] |
| Hybrid furnaces commissioned in France, 2026 | Three | Electrified melting reaches French glassmaking. | [7] |
Analyst Perspective
“Every furnace rebuild at a glassware plant gives makers the best chance to cut fuel risk, and I expect makers that move to electric or hybrid melting at a rebuild will hold steadier prices for retail buyers. Retail chains and hotel groups are ready to reward suppliers that can show secure melting capacity, and that opening is widest in borosilicate and opal ranges.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the glass tableware market segmented?
Product type, end-use and sales channel form the three product axes, with region on top. Beverage ware is the largest product slice at an estimated 46.3% in 2026, household use the largest end-use slice at about 68.4%, and specialty stores the largest channel at an estimated 27.6%.
By product type: beverage ware, tableware, baby bottles, and others.
By end-use: household and commercial.
By sales channel: hypermarkets/supermarkets, specialty stores, multi-brand stores, convenience stores, online retailers, wholesalers & distributors, and other sales channels.
By region: South Asia & Pacific, Latin America, Western Europe, East Asia, Middle East & Africa, North America, and Eastern Europe.
Why does beverage ware lead product type sales?
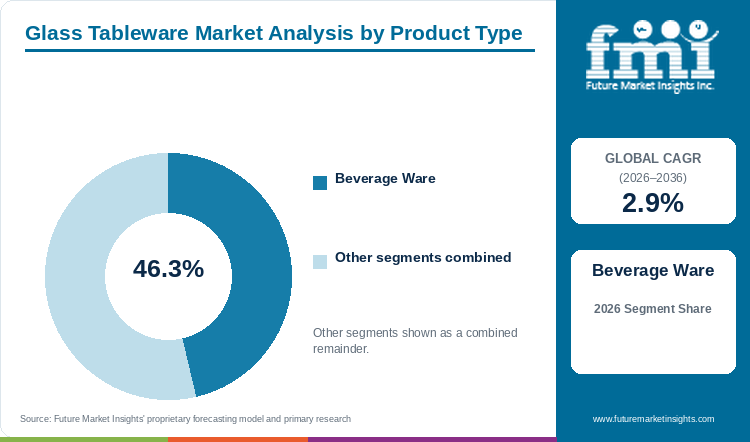
Beverage ware leads the product split in 2026 with about 46.3% (estimated), ahead of tableware, baby bottles and other items.
Table 3: Product Type Share for the Glass Tableware Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Beverage Ware | 46.3% |
| Tableware | 31.8% |
| Baby Bottles | 7.6% |
| Others | 14.3% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Glass Tableware Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 2.9% |
| Leading Segment | Beverage Ware |
Tumblers, mugs and stemware will break and wear out faster than plates, and households and bars will reorder drinking glass more often. FMI finds beverage ware likely to lead product demand. Beverage ware holds an estimated 46.3%, and plates and bowls in the tableware group follow at about 31.8%. Baby bottles carry an estimated 7.6% and other items 14.3%. Arc lists production sites in France, the United States, China and the United Arab Emirates.[5] Plants in Europe, North America, Asia and the Middle East let Arc serve retail chains on several continents. Beverage ware will keep the top slot through 2036 on bar, café and home replacement cycles.
- Tableware will gain from opal and tempered dinner sets sold to young households.
- Borosil runs an opalware capacity of 84 tons per day, the company told analysts in August 2025.[4]
Why do households lead end-use sales?
Household buying makes up about 68.4% of the 2026 end-use split, against an estimated 31.6% for commercial buyers.
Table 5: End-Use Share for the Glass Tableware Market (percentage share), 2026
| End-Use | Estimated Share (2026) |
|---|---|
| Household | 68.4% |
| Commercial | 31.6% |
| Total | 100.0% |
A family buying a new set of glasses decides on size, finish and price in one store visit. Household applications hold a major share of end-use sales, in the FMI end-use split. Homes take an estimated 68.4%, and hotels, restaurants and caterers account for about 31.6%. Borosil has sourced storage jars, glass bottles and glass jugs from the Borosil Scientific plant at Bharuch, Glass International reported in March 2026.[2] A new facility at the same site will serve growing demand for storage jars, bottles and jugs.[2] Storage jars and jugs add a second household purchase next to drinking glass. Commercial buying, at 31.6%, will grow with hotel openings, and households will keep the 68.4% base.
- Commercial kitchens will favour tempered glass that survives dishwashers and heavy handling.
- Arc reported investment of €40 million in 2025, with 10% going to research and development.[5]
Why do specialty stores lead sales channel sales?
Specialty stores are the top channel in 2026 at an estimated 27.6%, with online retailers second at about 18.7%.
Table 6: Sales Channel Share for the Glass Tableware Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Specialty Stores | 27.6% |
| Online Retailers | 18.7% |
| Hypermarkets/Supermarkets | 16.2% |
| Wholesalers & Distributors | 14.1% |
| Multi-brand Stores | 12.4% |
| Convenience Stores | 6.3% |
| Other Sales Channels | 4.7% |
| Total | 100.0% |
Shoppers looking for designer glassware and artisan-crafted pieces want expert advice and exclusive collections, so specialty stores take an estimated 27.6% of channel sales. Bridal registries, luxury homeware gifting and seasonal collections keep specialty stores the usual stop for premium glassware. Online retailers follow at about 18.7%, and hypermarkets and supermarkets take an estimated 16.2%. Wholesalers and distributors carry about 14.1%. Multi-brand stores account for an estimated 12.4%, convenience stores 6.3% and other channels 4.7%. Specialty retailers will push suppliers for limited-edition ranges, and online sellers will take share in gift sets.
- Online retailers will gain in gift sets and crystal, which ship in protective packs.
- Grocery formats will keep boxed tumbler sets in front of weekly shoppers at fixed annual prices.
What are the drivers, restraints, and opportunities in the glass tableware market?
Demand for glass tableware rises with home storage needs, hotel and café growth and new capacity in India. Electric melting, fuel supply risk and steady price pressure form the key trends in glass tableware.
- Driver: Borosil storage lines at Bharuch and hotel buying support volume.
- Restraint: LPG cuts such as the March 2026 Jaipur force majeure and price competition squeeze margins.
- Opportunity: Electric and hybrid furnaces timed to rebuild cycles.
Kitchen Storage and Pressware Pull New Lines into India
Indian growth in glass tableware will come from storage and pressware. Borosil approved a Bharuch facility in March 2026 with dedicated mass production lines.[2] The Bharuch plan adds capacity for jars, bottles and jugs close to western Indian buyers. Pressware lines in Rajasthan will gain a third forming line at the January 2028 rebuild.[2] Indian supply will move closer to the kitchen storage buyer over the decade, and imported jars will lose shelf space.
Fuel Shocks and Price Pressure Squeeze Margins
FMI describes a saturated market with price competition among many brands. Key challenges faced by manufacturers include fuel supply cuts and a crowded shelf. Borosil reported muted glassware growth in Q1 FY26, with revenues of INR56.2 crores against INR55.7 crores a year earlier.[4] Soda ash is the main batch input after sand, so the soda ash market sets a second cost line for each furnace. Soda ash posts a 4.3% CAGR from 2026 to 2036 against 2.9% for glass tableware, so tableware makers will compete with faster-growing glass users for each soda ash shipment and will pay firmer batch costs. Flat Borosil glassware revenue and 60% to 65% utilization leave little room to raise prices after a fuel spike. Smaller makers with one furnace will feel each supply cut hardest.
Electric Melting Timed to Each Rebuild
Three hybrid furnaces were commissioned in France in 2026, Glass International reported in September 2026.[7] Some hybrid furnaces have achieved up to 64% CO2 emission reductions, the same report said.[7] Sales potential is expected to emerge from glassware made in electric and hybrid furnaces. Hotel groups with emission targets will ask for lower-carbon glass in tenders. Makers that convert at the next rebuild will meet lower-carbon hotel tenders first.
Which country CAGRs are profiled in the glass tableware market?
Table 7: Country CAGR Comparison for the Glass Tableware Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| United States | 3% |
| Japan | 3% |
| European Union | 2.9% |
| South Korea | 2.9% |
| United Kingdom | 2.8% |
How do country-level CAGRs compare in the glass tableware market?
Profiled national rates stay close to the 2.9% global CAGR. According to FMI, the United States and Japan form the regional centres of market expansion in the profiled group, each posting a 3% CAGR from 2026 to 2036. The European Union and South Korea match the global CAGR at 2.9%. The United Kingdom posts the lowest CAGR at 2.8%. Country rates between 2.8% and 3% will turn on retail pricing and furnace costs in each market.
- United States buyers will mix supermarket tumblers with branded crystal.
- Japan will pair fine dining glass with home gifting.
- European Union makers will face the highest fuel and carbon costs among the five.
- South Korea will lean on online sales of imported and branded sets.
- United Kingdom sales will track pubs, restaurants and imported ranges.
Full report country CAGRs cover: Western Europe, Latin America, South Asia & Pacific, Eastern Europe, North America, East Asia, and Middle East & Africa.
Country-wise Analysis
United States Glass Tableware Market Outlook (2026 to 2036)
Arc lists Millville, New Jersey among four global production sites.[5] Local melting gives American retailers a domestic source for pressed tumblers and stemware. Lead-free and tempered glass are the newer types gaining ground with American buyers. Sales in the United States post a 3% CAGR from 2026 to 2036, level with Japan at the top of the profiled group. Zwiesel Kristallglas integrated US partner Fortessa Tableware Solutions in 2022, and the group markets the complete table setting in North and South America.[8] American hotel and restaurant buyers can source stemware and dinnerware from one supplier. Tariffs on imported glassware will favour suppliers with plants inside the country.
Key takeaway: Chains in the United States will favour glassmakers with local furnaces and short truck routes.
Japan Glass Tableware Market Outlook (2026 to 2036)
Japan shares the top profiled CAGR, 3% from 2026 to 2036. Noritake will compete for buyers who set high standards for finish and gift packaging. Department stores and specialty shops will keep a larger role in Japan than in the United States and Europe. Home cooks will pay for thin, clear drinking glass and small-batch serving pieces. Hotel and restaurant openings in tourist cities will add commercial orders through the decade.
Key takeaway: Japan will reward finish and gift packaging, and specialty retail will hold more of the sale than in the West.
European Union Glass Tableware Market Outlook (2026 to 2036)
French production makes up about 50% of Arc global sales revenue.[5] German crystal maker Zwiesel Kristallglas reported sales of €214.5 million and over 1,000 employees in September 2025.[8] France commissioned three hybrid furnaces in 2026.[7] High-end tableware, packaging rules and recycled glass shape European buying. The European Union posts a 2.9% CAGR from 2026 to 2036, level with the global rate. Container plants in the glass packaging market compete with tableware makers for the same furnace builders. Fuel and carbon costs will push EU makers to electrify at each rebuild.
Key takeaway: EU plants will carry the highest energy exposure, and electrified melting will decide which ones keep export orders.
South Korea Glass Tableware Market Outlook (2026 to 2036)
Online platforms will carry Korean gift-set and branded glassware sales, with imported brands and local labels side by side. Café culture in Seoul and other cities will keep commercial orders for tumblers and cold-drink glasses steady. South Korea matches the 2.9% global CAGR for 2026 to 2036. Apartment kitchens will favour stackable storage jars and heat-resistant containers.
Key takeaway: Korean demand for glassware will track café openings and online gift sales, and suppliers with fast delivery will gain.
United Kingdom Glass Tableware Market Outlook (2026 to 2036)
With a 2.8% CAGR from 2026 to 2036, the United Kingdom posts the lowest profiled rate. Pubs, restaurants and hotels will form a large commercial base for tumblers and pint glasses. Much of the retail range will come from European and Asian plants. Price-led supermarket buying will hold average selling prices flat.
Key takeaway: The UK will grow on hospitality refits, and importers with steady freight costs will hold the retail shelf.
Who are the notable companies in the glass tableware market?
Arc International, Libbey Inc., Bormioli Rocco, Ocean Glass Public Company, Borosil Ltd., Pasabahce (Sisecam Group), Anchor Hocking, Zwiesel Kristallglas AG, Luigi Bormioli and Noritake Co., Ltd. make up the main supplier group in glass tableware.
FMI puts the Arc International share at 17% to 21%. Libbey Inc. holds 13% to 17%, Bormioli Rocco 10% to 14%, Ocean Glass 7% to 11% and Borosil 5% to 9%. Other companies take 35% to 45% combined. Smaller brands compete on price within the 35% to 45% held by other companies.
Furnace capacity is the next battleground for market share, with 2025 and 2026 moves from Arc, Borosil and Sisecam. Arc reported 3 million glassware articles a day of capacity in 2025.[5] Borosil set a furnace expansion and a new Bharuch facility in March 2026.[2] Sisecam moved handmade glass production to Kırklareli.[6]
- Higher-share suppliers: Arc International, Libbey Inc., Bormioli Rocco, Ocean Glass Public Company and Borosil Ltd.
- Other key suppliers: Pasabahce (Sisecam Group), Anchor Hocking, Zwiesel Kristallglas AG, Luigi Bormioli and Noritake Co., Ltd.
Competitive Benchmarking: Glass Tableware Market
Table 8: Competitive Benchmarking for the Glass Tableware Market (qualitative documentation ratings), 2026
| Company | Furnace Investment | Fuel Exposure Data | Capacity Data | Disclosure |
|---|---|---|---|---|
| Arc International | Medium | Low | High | Medium |
| Borosil Ltd. | High | High | High | High |
| Pasabahce (Sisecam Group) | Medium | Low | Low | High |
| Libbey Inc. | Low | Low | Low | Low |
| Bormioli Rocco | Low | Low | Low | Low |
Column marks run from High to Low by the amount of dated company and trade coverage.
Key Developments in the Glass Tableware Market
- In September 2026, Glass International reported three hybrid furnaces commissioned in France in 2026.[7]
- In April 2026, Borosil reported Jaipur pressware and opal furnaces fully restored to normal capacity.[3]
- In March 2026, Glass International reported the 2025 move of Sisecam handmade glass production from Denizli to Kırklareli.[6]
- In March 2026, Borosil restricted output at Jaipur after LPG suppliers cited force majeure.[1]
- In March 2026, the Borosil board approved a Bharuch facility and a 32 TPD borosilicate furnace plan.[2]
- In February 2026, Arc published a 2026 company profile with capacity of 3 million articles per day.[5]
- In September 2025, Zwiesel Kristallglas AG announced a change of name to ZWIESEL FORTESSA AG from 1 October.[8]
- In August 2025, Borosil reported lower power and fuel costs on solar power in Rajasthan.[4]
Key Players in the Glass Tableware Market
Higher-Share Suppliers
- Arc International
- Libbey Inc.
- Bormioli Rocco
- Ocean Glass Public Company
- Borosil Ltd.
Other Key Suppliers
- Pasabahce (Sisecam Group)
- Anchor Hocking
- Zwiesel Kristallglas AG
- Luigi Bormioli
- Noritake Co., Ltd.
Glass Tableware Market - Report Scope
Table 9: Report Scope for the Glass Tableware Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end-use; sales channel; region |
| Quantitative units | USD million |
| Market definition | Glass tableware covering beverage ware, tableware, baby bottles and other glass items for household and commercial use. |
| Regions covered | North America; Latin America; East Asia; South Asia & Pacific; Eastern Europe; Western Europe; Middle East & Africa |
| Countries covered | United States; United Kingdom; European Union; Japan; South Korea |
| Key companies profiled | Arc International, Libbey Inc., Bormioli Rocco, Ocean Glass Public Company, Borosil Ltd., Pasabahce (Sisecam Group), Anchor Hocking, Zwiesel Kristallglas AG, Luigi Bormioli, Noritake Co., Ltd. |
| Forecast period | 2026 to 2036 |
Glass Tableware Market - Research Methodology
Table 10: Research Methodology for the Glass Tableware Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Glassmaker filings, exchange notices, company profiles and glass trade press dated May 2025 or later supply the furnace and capacity facts. |
| Desk Research | Desk work tracked fuel supply events, furnace rebuild plans, plant moves and electric melting projects. |
| Market Sizing and Forecasting | The forecast builds on the 2025 base of USD 11,692.6 million and a 2.9% CAGR for 2026 to 2036. |
| Data Validation | Furnace and capacity figures were matched across company filings and trade reports of the same month. |
Glass Tableware Market by Segments
Glass Tableware Market segmented by Product Type:
- Beverage Ware
- Tableware
- Baby Bottles
- Others
Glass Tableware Market segmented by End-Use:
- Household
- Commercial
Glass Tableware Market segmented by Sales Channel:
- Hypermarkets/Supermarkets
- Specialty Stores
- Multi-brand Stores
- Convenience Stores
- Online Retailers
- Wholesalers & Distributors
- Other Sales Channels
Glass Tableware Market by Region
- North America
- Latin America
- East Asia
- South Asia & Pacific
- Eastern Europe
- Western Europe
- Middle East & Africa
Research Sources and Bibliography
- [1] Glass International. (2026, March 13). Iran conflict hits Borosil glass energy supply. https://www.glass-international.com/news/iran-conflict-hits-borosil-glass-energy-supply
- [2] Glass International. (2026, March 10). Borosil plots Indian glass furnace investment. https://www.glass-international.com/news/borosil-plots-indian-glass-furnace-investment
- [3] Borosil Limited (NSE filing). (2026, April 3). Intimation under Regulation 30 of SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015. https://nsearchives.nseindia.com/corporate/BOROSIL_03042026155515_SEINTIMATIONUpdate.pdf
- [4] Borosil Limited. (2025, August 18). Transcript of earnings conference call for Q1 FY26. https://www.borosil.com/site/assets/files/8494/transcript_on_concall_held_on_august_18_2025.pdf
- [5] Arc. (2026, February). 200 years of innovation, corporate press kit, 2026 edition. https://www.arc-intl.com/files/uploads/2026/02/DP-Corp-EN-Feb2026.pdf
- [6] Glass International. (2026, March 27). Sisecam CEO discusses challenging 2025. https://glass-international.com/news/sisecam-ceo-discusses-challenging-2025
- [7] Glass International. (2026, September 23). French glass industry focused on hybrid furnaces. https://www.glass-international.com/news/french-glass-industry-focused-on-hybrid-furnaces
- [8] Zwiesel Kristallglas AG. (2025, September). New name, clear vision: Redefining table settings worldwide. https://www.zwiesel-glas.com/media/b7/64/27/1759218169/PI_Change_Zwiesel%20Fortessa_EN.pdf
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will glass tableware sales reach in 2026 and 2036?
- At what CAGR will the market expand from 2026 to 2036?
- Which product type will hold the largest share?
- Will households or commercial buyers account for more sales?
- How will furnace fuel costs and rebuild cycles shape supply?
- Which countries and companies will set the pace through 2036?
Frequently Asked Questions
What is the size of the glass tableware market in 2026?
Glass tableware sales will total about USD 12,031.7 million in 2026 (estimated). By 2036, sales will reach USD 16,013.2 million on the FMI forecast. At what rate will the glass tableware market grow? Demand for glass tableware will record a 2.9% CAGR between 2026 and 2036. Replacement buying of drinking glass and new storage ranges will carry most of the gain.
Which product type will lead in 2026?
Beverage ware will lead with an estimated 46.3% share, ahead of tableware at about 31.8%. Will household buyers stay ahead of commercial buyers? Yes. Homes will take about 68.4% of 2026 sales, and hotels and restaurants will add steady commercial orders. Specialty stores will remain the main place to buy, with an estimated 27.6% of channel sales.
Which countries will grow fastest?
Top growth, a 3% CAGR from 2026 to 2036, will come from the United States and Japan, on FMI figures, ahead of the 2.8% CAGR in the United Kingdom.
Which companies will shape supply?
Arc International, Libbey, Bormioli Rocco, Ocean Glass and Borosil will hold the largest shares, with Pasabahce, Anchor Hocking and Zwiesel Kristallglas among the other key suppliers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Beverage Ware
- Tableware
- Baby Bottles
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use, 2026 to 2036
- Household
- Commercial
- Y-o-Y Growth Trend Analysis By End-Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Hypermarkets/Supermarkets
- Specialty Stores
- Multi-brand Stores
- Convenience Stores
- Online Retailers
- Wholesalers & Distributors
- Other Sales Channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- East Asia
- South Asia & Pacific
- Eastern Europe
- Western Europe
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Sales Channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End-Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Arc International
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Borosil Ltd.
- Pasabahce (Sisecam Group)
- Libbey Inc.
- Bormioli Rocco
- Ocean Glass Public Company
- Anchor Hocking
- Zwiesel Kristallglas AG
- Luigi Bormioli
- Noritake Co., Ltd.
- Arc International
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


