

- Market Size (2026)
- USD 165.5 Mn
- Forecast (2036)
- USD 245.9 Mn
- CAGR (2026 to 2036)
- 4.0%
How big is Anti-Seize Compounds Market in 2026?
USD 165.5 million in 2026 and USD 245.9 million by 2036 at a 4.0% CAGR.
Demand for anti-seize compounds is projected to expand at 4.0% CAGR between 2026 and 2036 as installed equipment keeps threaded joints inside routine maintenance schedules. The USA Energy Information Administration recorded 18.4 million barrels per calendar day of operable refinery capacity in June 2025. Refinery maintenance therefore sustains recurring flange and valve service even without major capacity additions at processing sites. Plant engineers evaluate anti-seize beside industrial lubricants once torque behavior and service temperature are documented for the intended joint.
Country demand separates more clearly through manufacturing intensity and maintenance workload than through the basic need to prevent seizure. Destatis documented German manufacturing order backlogs 7.5% above February 2025 in its April 2026 release. The backlog keeps component activity active while qualification requirements continue to govern maintenance chemistry changes. Route-to-market planning should therefore consider lubricant additives and local service practices beside the approved country growth rates.
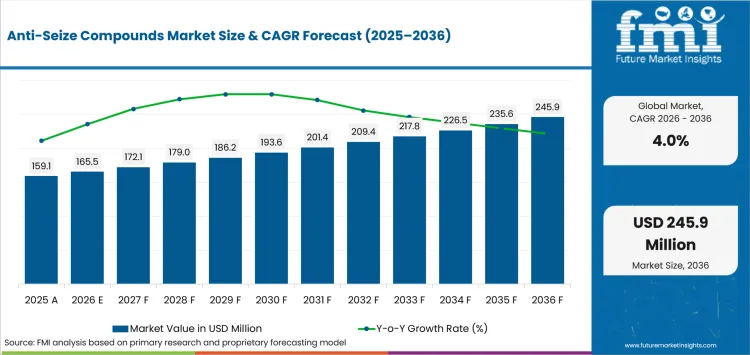
Key Takeaways of Anti-seize Compounds Market
- Installed vehicles and process equipment require threaded joints to remain removable following repeated exposure to heat, corrosion and service cycles.
- By container type, can is estimated to hold 34.8% in 2026 owing to brush application that suits localized maintenance work.
- Automotive & transportation is forecast to represent 42.0% of end-user demand in 2026 driven by repeated service on exposed threaded hardware.
- Copper grade is projected to hold 23.9% of grade type demand in 2026 attributable to broad high-temperature use on compatible steel fasteners.
- Incorrect nut-factor assumptions or metal compatibility can alter clamp load and delay approval for a replacement anti-seize formulation.
- Some of the key players in this market include Henkel AG & Co. KGaA (Loctite), Permatex, CRC Industries, DuPont, A.W. Chesterton Company, FUCHS SE, Jet-Lube, and Anti-Seize Technology.
Analyst Perspective
"An anti-seize specification should begin with fastener metallurgy, target clamp load and the temperature reached during actual service. Margin follows from preventing damaged threads and repeat qualification work, not from selling a larger package at the lowest unit price."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Anti-seize Compounds Market segmented?
The anti-seize compounds market is segmented by container type, end-user, grade type and sales channel.
Container type includes can, other containers, drum and cartridge. End-user covers automotive & transportation, petrochemical, power generation, mining equipment and construction equipment. Grade type includes copper grade, nickel grade, nuclear grade, zinc/aluminum grade and marine grade. Sales channel distinguishes online and offline purchasing routes.
What makes Can central to the Container Type category?
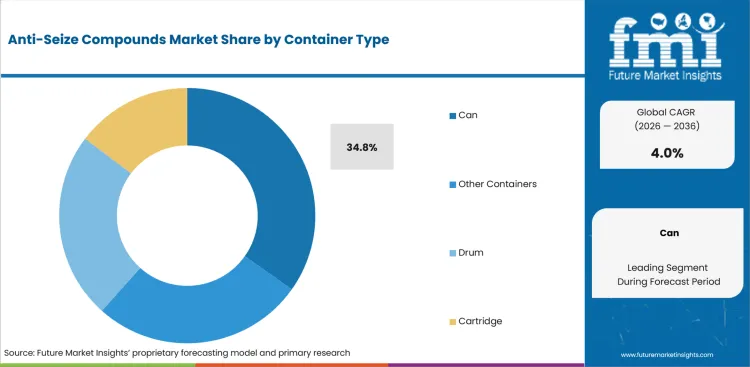
Field technicians often service isolated fasteners where bulk dispensing equipment would add setup time without improving application control. The USA Bureau of Labor Statistics counted about 538,300 industrial machinery mechanics and related workers in 2024. The maintenance workforce keeps portable cans relevant for localized repair tasks on installed factory equipment. Comparable metalworking fluids also require controlled point-of-use handling during scheduled plant maintenance and repair work.
- By container type, can is estimated to hold 34.8% in 2026 owing to brush-top application on individual threaded connections.
- Drums fit centralized high-volume use better, while portable cans reduce preparation time for dispersed repair tasks and planned shutdown work.
Why does Automotive & Transportation lead the End-User category?
Brake, exhaust and drivetrain service repeatedly exposes threaded hardware to road moisture and thermal cycling during normal vehicle maintenance.
- Automotive & transportation is forecast to represent 42.0% of end-user demand in 2026 driven by repeated servicing of exposed threaded vehicle assemblies.
- Workshop activity provides a large recurring service base for anti-seize demand in routine vehicle maintenance. The USA Bureau of Labor Statistics counted about 805,600 automotive service technicians and mechanics in 2024. Their work repeatedly returns approved compounds to bolts that must separate cleanly during later repairs. Adjacent automotive oil products use the same established workshop replenishment channels once specifications are standardized.
What supports Copper Grade in the Grade Type category?
Copper grade fits many high-temperature steel fasteners provided the application accepts copper and the expected service temperature stays within formulation limits.
- EIA stated in May 2025 that USA refinery utilization ended the first quarter at 86% following seasonal maintenance and major turnarounds. Turnaround shutdowns concentrate service work on threaded connections that require heat-resistant compounds and reliable later disassembly. Engineers compare copper grades with specialty oils only after metallurgy and contamination limits are settled.
- Copper grade is projected to hold 23.9% of grade type demand in 2026 attributable to broad use on compatible high-temperature steel assemblies.
How does Online Shape the Sales Channel category?
Digital ordering works best for maintenance programs that already know the approved grade, package size and exact part number needed for routine replenishment.
- Online is estimated to account for 71.2% of sales channel demand in 2026 because standardized SKUs simplify repeat ordering after technical approval.
- USA Census Bureau data published in August 2026 placed e-commerce at 17.1% of total retail sales during the second quarter. Distributors remain important during first qualification and for bulk supply that requires application-specific technical support. The same split appears in grease products once plants separate technical approval from routine replenishment.
What are the drivers, restraints and opportunities in the Anti-Seize Compounds Market?
Preventive maintenance sustains repeat demand while specification errors slow grade substitution and documented specialty formulations expand access to controlled applications.
- Driver: Installed industrial equipment requires repeated maintenance on threaded connections exposed to heat and corrosion during normal operating cycles.
- Restraint: Grade changes alter friction behavior and may conflict with metallurgy or purity requirements during controlled bolting procedures.
- Opportunity: Application-specific formulations gain controlled maintenance work once qualification records match the exact site and fastener requirement.
Installed Equipment Keeps Fastener Maintenance Recurring
Installed machinery produces repeat anti-seize demand because maintenance crews must reopen assemblies without damaged threads or extended outage time. BLS counted 541,070 industrial machinery installation and repair jobs in May 2025 in the United States. The 541,070-job base measures ongoing equipment service activity beyond new machinery production and installation cycles. Related metal-forming fluids follow the same installed-asset logic whenever scheduled maintenance brings treated metal surfaces back into service.
Qualification Risk Limits Easy Grade Substitution
Anti-seize chemistry changes the friction relationship used to convert tightening torque into clamp load, so substitution requires more than matching temperature limits. DuPont announced in January 2025 that MOLYKOTE HP-300 Grease met ISO 14687:2019 hydrogen purity requirements following controlled exposure at 700 bar. Contamination-sensitive plants therefore require application evidence before changing lubrication chemistry in hydrogen or similarly controlled systems. Similar qualification controls apply to metal fabrication fluids used in tightly specified manufacturing and maintenance processes.
Certified Specialty Formulations Expand Addressable Maintenance Work
Restricted maintenance environments provide higher-value work for formulations carrying documentation that a general-purpose metallic grade cannot supply. NSF registered a CRC food-grade lubricant under its H1 program in September 2025 for incidental food-contact applications. The H1 registration gives plant maintenance teams a defined qualification route for lubricant use in controlled food-processing areas. Comparable documentation requirements also affect corrosion protection coatings used in regulated production and maintenance settings.
Which country CAGRs are profiled in the Anti-Seize Compounds Market?
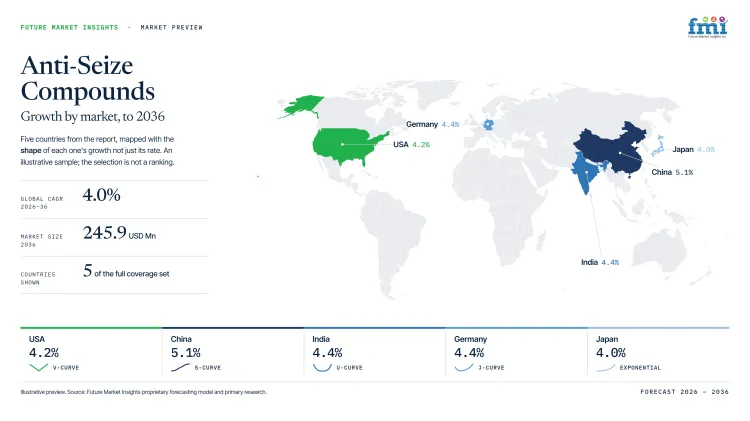
| Country | CAGR |
|---|---|
| China | 5.1% |
| India | 4.4% |
| Germany | 4.4% |
| USA | 4.2% |
| Japan | 4.0% |
How do country-level CAGRs compare in the Anti-Seize Compounds Market?
The 1.1-point range places China at the top, with India and Germany close behind at 4.4%. The USA and Japan form the lower end at 4.2% and 4.0%, respectively. Forecast rates describe pace, not present market size. Industrial activity, maintenance intensity, and distribution structure explain more of the difference than anti-seize function alone.
- China’s manufacturing base supports broad anti-seize demand across industrial maintenance.
- India’s expanding industrial activity strengthens demand for maintenance compounds.
- Germany’s machine-building sector supports steady industrial maintenance demand.
- USA’s automotive and industrial repair activity sustains year-round demand.
- Japan’s concentrated manufacturing hubs support consistent specialized compound use.
Similar CAGRs produce different qualification costs, stocking priorities and support requirements for entrants. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- China’s large manufacturing and machinery base supports widespread anti-seize use across industrial maintenance and equipment servicing. Anti-seize demand is projected to grow at 5.1% CAGR through 2036, supported by expanding industrial capacity and maintenance requirements. Strong local engineering networks favor technical grade trials, while established plants often prefer proven formulations. Suppliers can gain an advantage by documenting metallurgy, temperature limits, and friction behavior clearly for maintenance teams.
- India’s expanding manufacturing, infrastructure, and heavy-equipment base is strengthening demand for anti-seize compounds. The market is projected to grow at 4.4% CAGR through 2036, supported by rising equipment installation and maintenance activity. Local distributors improve product availability, while maintenance teams typically favor grades with established compatibility. Clear technical documentation can help suppliers secure repeat orders across industrial accounts.
- Germany’s machine-building base keeps technical distributors close to industrial maintenance accounts nationwide. Anti-seize demand is projected to grow at 4.4% CAGR through 2036, reflecting replacement work across a mature industrial base. Engineering expertise supports local grade trials, although established plants often prefer approved formulations. Clear metallurgy and friction records help maintenance engineers retain existing bolting procedures during scheduled turnarounds.
- USA refineries and industrial facilities provide a broad installed base for anti-seize use on valves, flanges, and threaded equipment. Demand is forecast to rise at 4.2% CAGR through 2036, supported by MRO distribution and continuing equipment maintenance. Existing regional distributors simplify replenishment, while site procedures favor previously approved grades. Regional stock becomes particularly valuable once formulations meet torque and compatibility requirements.
- Japan’s established machinery and automotive production base supports consistent demand for specialized anti-seize compounds. The market is estimated to grow at 4.0% CAGR through 2036, with manufacturers emphasizing repeatable assembly conditions and material compatibility. Lengthy qualification can slow product switching, making technical files and disciplined trial support important during precision-manufacturing evaluations.
Who are the notable companies in the Anti-Seize Compounds Market?
Henkel AG & Co. KGaA (Loctite), Permatex, CRC Industries, DuPont, A.W. Chesterton Company, FUCHS SE, Jet-Lube, and Anti-Seize Technology are the notable companies profiled in this market.
The competitive field separates broad MRO brands from engineered lubricant groups and dedicated thread-compound specialists. Henkel, Permatex and CRC Industries reach familiar automotive and industrial maintenance channels through broad distributor networks. DuPont and FUCHS SE bring larger specialty-lubrication platforms, while Jet-Lube and Anti-Seize Technology focus more directly on threaded compounds. A.W. Chesterton Company supplies dedicated nickel and food-grade anti-seize compounds for industrial assembly and maintenance work. Entry depends first on compatibility evidence, then on replenishment reach into adjacent metalworking fluid additives and corrosion-control accounts.
- Broad MRO access: Henkel AG & Co. KGaA (Loctite), Permatex and CRC Industries serve automotive and industrial maintenance channels with stocked small-package products.
- Specialty lubrication platforms: DuPont, A.W. Chesterton Company and FUCHS SE compete where chemistry depth and technical documentation influence qualification decisions.
- Thread-compound specialists: Jet-Lube and Anti-Seize Technology focus directly on anti-seize grades for refinery, mining and heavy-maintenance applications.
Competitive Benchmarking: Anti-Seize Compounds Market
| Company | Grade Breadth & Specialty Coverage | Compatibility & Qualification Documentation | Packaging & Replenishment Access | Geographic Reach |
|---|---|---|---|---|
| Henkel AG & Co. KGaA (Loctite) | High | High | High | Global |
| Permatex | High | High | High | North America, UK and exports to 85+ countries |
| CRC Industries | Medium | Medium | High | Global automotive and industrial channels |
| DuPont | High | High | High | Global |
| A.W. Chesterton Company | High | High | High | Global sales and service network |
| FUCHS SE | High | High | High | Global |
| Jet-Lube | High | High | High | USA, Canada, UK and international distribution |
| Anti-Seize Technology | High | Medium | High | North America and international distributors |
Scoring basis: High grade breadth requires several documented anti-seize or specialty-lubricant routes while Medium indicates a narrower verified range. High documentation requires clear compatibility or qualification records while Medium indicates useful but less extensive public guidance. High replenishment access requires broad documented distribution or purchasing routes while Medium identifies narrower channel coverage. Low identifies a documented limitation in the scoring framework and never substitutes for missing evidence in a benchmark rating.
Key Developments in the Anti-Seize Compounds Market
- In November 2025, DuPont broke ground on a MOLYKOTE specialty lubricants plant in Zhangjiagang to expand regional production and technical response in Asia.
- In November 2025, Jet-Lube parent Whitmore Manufacturing acquired Hydrotex Partners to broaden performance lubrication offerings for industrial and transportation end markets.
- In June 2025, FUCHS SE consolidated the Swiss LUBCON and STRUB activities under FUCHS SWISS LUBRICANTS AG with local development and production capacity.
Key Players in the Anti-Seize Compounds Market
Broad MRO and Automotive Maintenance Platforms
- Henkel AG & Co. KGaA (Loctite)
- Permatex
- CRC Industries
Engineered Specialty Lubrication Platforms
- DuPont
- A.W. Chesterton Company
- FUCHS SE
Dedicated Anti-Seize and Thread-Compound Specialists
- Jet-Lube
- Anti-Seize Technology
Anti-Seize Compounds Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By container type, end-user, grade type, sales channel and region. |
| Quantitative Units | USD Million. |
| Market Definition | Commercial sales of purpose-formulated anti-seize compounds and pastes used to protect threaded metal connections during assembly and later maintenance. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Germany, USA, Japan, France, Australia, and 20+ countries included in the full report. |
| Key Companies Profiled | Henkel AG & Co. KGaA (Loctite), Permatex, CRC Industries, DuPont, A.W. Chesterton Company, FUCHS SE, Jet-Lube, and Anti-Seize Technology. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Anti-Seize Compounds Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Anti-Seize Compounds Market by Segments
Anti-Seize Compounds Market segmented by Container Type:
- Can
- Other Containers
- Drum
- Cartridge
Anti-Seize Compounds Market segmented by End-User:
- Automotive & Transportation
- Petrochemical
- Power Generation
- Mining Equipment
- Construction Equipment
Anti-Seize Compounds Market segmented by Grade Type:
- Copper Grade
- Nickel Grade
- Nuclear Grade
- Zinc/Aluminum Grade
- Marine Grade
Anti-Seize Compounds Market segmented by Sales Channel:
- Online
- Offline
Anti-Seize Compounds Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- USA Energy Information Administration. (2025, June 30). USA refining capacity largely unchanged as of January 2025.
- Federal Statistical Office of Germany. (2026, April 20). Stock of orders in manufacturing in February 2026: +1.0% on the previous month.
- USA Bureau of Labor Statistics. (2025, August 28). Industrial machinery mechanics, machinery maintenance workers, and millwrights.
- USA Bureau of Labor Statistics. (2025, September 16). Automotive service technicians and mechanics.
- USA Energy Information Administration. (2025, May 15). Oil prices and refinery margins fell slightly in first quarter of 2025.
- USA Census Bureau. (2026, August 18). Quarterly retail e-commerce sales.
- USA Bureau of Labor Statistics. (2026, May). National employment and wage data by occupation, May 2025.
- DuPont. (2025, January 21). DuPont MOLYKOTE HP-300 Grease proven to meet strict hydrogen purity standards.
- NSF International. (2025, September 12). Certificate of Registration: CRC Food Grade Syntha-Tech Lubricant.
- Federal Statistical Office of Germany. (2026, February 6). Production in December 2025: -1.9% on the previous month.
- USA Energy Information Administration. (2026, June 29). USA refining capacity decreased during 2025.
- Ministry of Economy, Trade and Industry, Japan. (2025, March 28). FY2025 Vision for the Machine Parts and Tooling Industries Formulated.
- RTE. (2025, January 20). La production d'électricité française a atteint son plus haut niveau depuis 5 ans.
- Australian Bureau of Statistics. (2026, February 26). New capital expenditure rises 0.4 per cent.
- DuPont. (2025, November 18). DuPont breaks ground on MOLYKOTE lubricants manufacturing plant in China.
- Whitmore Manufacturing. (2025, November 5). Whitmore Manufacturing acquires Hydrotex - expanding its performance lubrication products portfolio.
- FUCHS SE. (2025, June 30). FUCHS unites STRUB and LUBCON in Switzerland: Uniform presence under FUCHS SWISS LUBRICANTS AG strengthens market position.
- Henkel AG & Co. KGaA. (2026, April 21). Henkel launches global threadlocking program for industrial assembly.
- Illinois Tool Works Inc. (2026, February 13). Annual report for the fiscal year ended December 31, 2025.
- A.W. Chesterton Company. (2025, July 16). Safety Data Sheet: 725(E) Nickel Anti-Seize Compound (Bulk).
- CRC Industries. (2025, October 9). Sta-Lube Food Grade Anti-Seize & Lubricating Compound, 8 Wt Oz Safety Data Sheet.
- FUCHS Lubricants Co. (2026, August 11). FUCHS announces grand opening of Americas Technology Center in Massachusetts.
- Whitmore Manufacturing. (2025, November 20). Whitmore Manufacturing acquires ProAction Fluids - expanding Jet-Lube product portfolio to include drilling fluids.
- Anti-Seize Technology. (2025, August 21). H-P Stainless Steel Anti Seize, Nuclear Grade, Safety Data Sheet.
- A.W. Chesterton Company. Direct Office Locations Worldwide. Retrieved August 23, 2026.
- DuPont de Nemours, Inc. (2026, February 17). Annual Report on Form 10-K for the year ended December 31, 2025.
- FUCHS SE. (2025, April 2). FUCHS acquires IRMCO® - Manufacturer of metal forming lubricants.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the anti-seize compounds market in 2026 and 2036?
- Which installed-asset conditions sustain repeat demand for anti-seize compounds?
- Why does can hold the largest approved container type share in 2026?
- Why does automotive & transportation account for the largest approved end-user share?
- How do copper grade and alternative chemistries differ during qualification?
- Why does online purchasing account for a large approved sales channel share?
- How do country growth rates differ among Germany, the USA, Japan, France and Australia?
- Which companies compete through broad MRO access and specialist thread-compound depth?
- Which compatibility checks make grade substitution difficult in controlled bolting work?
Frequently Asked Questions
How big is the anti-seize compounds market in 2026?
The anti-seize compounds market is valued at USD 165.5 million in 2026 and is projected to reach USD 245.9 million by 2036. Installed industrial and vehicle assets sustain repeat maintenance demand on threaded connections exposed to heat and corrosion.
What is the CAGR of the anti-seize compounds market from 2026 to 2036?
The anti-seize compounds market is projected to grow at a CAGR of 4.0% between 2026 and 2036. Preventive maintenance sustains expansion because operating equipment requires controlled assembly and later disassembly of threaded connections.
Which container type leads the anti-seize compounds market?
The can segment is expected to hold 34.8% of the anti-seize compounds market in 2026, driven by brush-top formats suited to localized threaded-fastener maintenance. Portable packages reduce setup work during dispersed repairs and scheduled service at workshops that reorder already approved maintenance grades.
Which grade type holds an additional dominant share of the anti-seize compounds market?
The copper grade segment is anticipated to represent 23.9% of the anti-seize compounds market in 2026, attributable to broad high-temperature use on compatible steel fasteners. Nickel and nonmetallic alternatives remain necessary in applications where copper contamination rules or higher temperatures restrict copper-grade use.
How much value will the anti-seize compounds market add between 2026 and 2036?
The anti-seize compounds market is expected to add USD 80.4 million in value between 2026 and 2036 based on the authorized endpoints. Repeat MRO purchasing and application-specific grade selection account for that incremental opportunity within installed industrial and vehicle assets.
Which countries are projected to record the highest growth in the anti-seize compounds market?
Germany is projected to grow at 4.4% CAGR, followed by the U.S. at 4.2% and Japan at 4.0% through 2036. Machinery maintenance, refinery activity and disciplined component qualification shape different purchasing conditions for product approval in these countries.
Which companies are active in the anti-seize compounds market?
Key companies operating in the anti-seize compounds market include Henkel AG & Co. KGaA (Loctite), Permatex, CRC Industries, DuPont, A.W. Chesterton Company, FUCHS SE, Jet-Lube, and Anti-Seize Technology. The companies compete on grade coverage and distribution access that support qualification and repeat maintenance purchasing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Container Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Container Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Container Type, 2026 to 2036
- Can
- Other Containers
- Drum
- Cartridge
- Can
- Y-o-Y Growth Trend Analysis By Container Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Container Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-User, 2026 to 2036
- Automotive & Transportation
- Petrochemical
- Power Generation
- Mining Equipment
- Construction Equipment
- Automotive & Transportation
- Y-o-Y Growth Trend Analysis By End-User, 2021 to 2025
- Absolute $ Opportunity Analysis By End-User, 2026 to 2036
- Global Market Analysis and Forecast, By Grade Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Grade Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Grade Type, 2026 to 2036
- Copper Grade
- Nickel Grade
- Nuclear Grade
- Zinc-Aluminum Grade
- Marine Grade
- Copper Grade
- Y-o-Y Growth Trend Analysis By Grade Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Online
- Offline
- Online
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Container Type
- By End-User
- By Grade Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Henkel AG & Co. KGaA (Loctite)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- 3M Company
- Permatex
- DuPont
- Bostik
- CRC Industries
- FUCHS SE
- Jet-Lube
- Anti-Seize Technology
- Bel-Ray Company
- Henkel AG & Co. KGaA (Loctite)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


