

- Market Size (2026)
- USD 9.5 Bn
- Forecast (2036)
- USD 14.3 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Blanket Market in 2026?
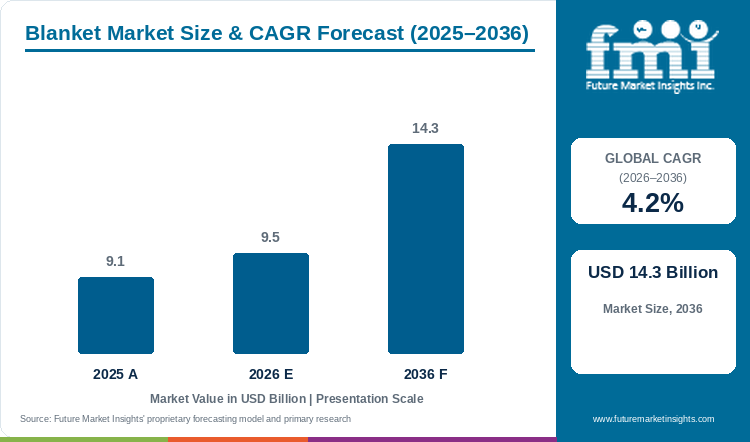
Blanket market size stood at USD 9.1 billion in 2025, reaches USD 9.5 billion in 2026 and is projected at USD 14.3 billion by 2036. Demand for blankets is set to expand at a 4.2% CAGR from 2026 to 2036, as households and hospitality buyers replace worn bedding and add electric formats for winter comfort.
Sales of blankets move with winter temperature, not only population size. NOAA's outlook of October 17, 2025, covering the 2025-26 winter, pointed to below normal temperatures across the Northern Plains and the Upper Midwest, and above normal temperatures across the southern half of the United States, fact [1]. Due to this, blanket sales in colder northern US states ran ahead of the national average that season, while demand in the warmer south stayed closer to simple replacement levels. This NOAA outlook is US-specific; FMI has not confirmed a comparable climate split for other temperate countries. Within the United States, this seasonal intensity gap between colder and warmer regions is anticipated to recur with each below normal winter through 2036.
Key Market Trends & Insights
- By product type, regular blankets lead with the large majority of 2026 sales, as buyers continue to favour a simple, lower-cost layer; electric blankets hold a smaller 16.5% share, supported by adjustable heat settings for winters with uneven temperature swings. The U.S. Consumer Product Safety Commission recalled about 8,560 MaxKare electric blankets in June 2025 over overheating and fire risk [2].[2]
- By material type, polyester and fleece blankets lead 2026 sales, as low-cost, easy-care synthetic fill suits mass-market replacement purchases. Wool holds a smaller, premium-priced 13.5% share, supported by certified wool standards. Australian wool production is forecast to fall 12.6% in the 2025 to 2026 season to 244.7 million kilograms greasy [3]. Due to this, wool blanket makers are anticipated to face tighter raw wool supply through the medium term.[3]
- By end user, residential buyers take 62.5% of 2026 sales, as seasonal and household replacement purchases outpace commercial orders. Hospitality linen refresh cycles keep demand steady among commercial buyers even as residential volume leads.
- By sales channel, online retailers collect 34% of 2026 sales, as e-commerce platforms widen access to electric and premium wool blankets. Online listings with detailed wash guidance and safety information are anticipated to keep this channel ahead through 2036.
- By country, China grows fastest among the five profiled countries at a 6.9% CAGR, as online platform shopping widens access to wool and electric blankets. Australia posts the slowest profiled rate at 4% CAGR, as its milder climate and already high household blanket ownership limit replacement urgency.
Regional Highlights
- China outpaces the other profiled countries, compounding at 6.9% a year through 2036.
- USA (5.4%) and Germany (5.1%) follow, while Australia trails the profiled set at 4% through 2036.
- Colder-than-normal winters across the Northern Plains and the Upper Midwest lifted blanket sales in the United States above the national average during the 2025-26 season, according to NOAA's outlook of October 17, 2025, fact [1].
Market Size & Forecast
Table 1: Market Size and Forecast for the Blanket Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.1 billion |
| Estimated Market Size in 2026 | USD 9.5 billion |
| Projected Market Size by 2036 | USD 14.3 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Market Value, 2026 to 2036 | USD 4.8 billion |
| Market Expansion Multiple | 1.5x |
Most blanket purchases are seasonal replacements ahead of winter. Lower household heating cost is a main reason buyers choose an electric blanket over central heating in bedrooms. Colder winters raise this seasonal pull: NOAA's US outlook showed the Northern Plains and the Upper Midwest facing below normal temperatures in the 2025-26 winter, fact [1]. At the premium end, pillow and quilt buyers often add a wool blanket from the same collection, a pattern that keeps certified wool blankets on shelves at a higher price. Tight wool supply and rising freight cost can still slow restocking at smaller retailers. Replacement of worn blankets ahead of each winter is anticipated to drive most orders through 2036.
Climate Exposure and Wool Supply Economics
Sales of blankets respond to both winter temperature and raw material cost, not population growth alone. NOAA's US outlook showed the Northern Plains and the Upper Midwest facing below normal temperatures in the 2025-26 winter [1]. The southern half of the United States stayed above normal over the same period [1]. Due to this, cold-region US retailers saw blanket sales run ahead of national averages that season. Warm-region retailers sold mainly routine replacement units. Wool supply is tightening at the same time. Australian wool production is forecast to fall 12.6% in the 2025 to 2026 season to 244.7 million kilograms greasy [3]. FMI expects wool blanket makers to pay more for raw wool through the near term, a change that favours makers holding forward supply contracts.[1][1][3]
Ownership change is reshaping blanket retail in North America. A Canadian court approved the sale of Hudson's Bay Company intellectual property, including the iconic striped blanket design, to Canadian Tire for about CAD 30 million on June 3, 2025. Due to this, the striped point blanket pattern now belongs to a mass retailer instead of a department store chain, widening the design's shelf reach. Quilt and throw buyers in premium channels are anticipated to keep paying for certified wool blankets even as mass retail competes mainly on price.Quilt
Table 2: Climate Exposure and Wool Supply Indicators for the Blanket Market (percentage changes, units, USD and EUR values), 2025 to 2026
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| U.S. electric blanket recall, June 2025 | About 8,560 units; 34 overheating reports; 3 burn injuries | Safety recalls push retailers toward certified safety-labelled models. | [2] |
| Australian wool production, 2025 to 2026 | 244.7 million kg greasy, forecast down 12.6% | Falling wool supply raises raw material cost for wool blanket makers. | [3] |
| Hudson's Bay Company IP sale | Completed 3 June 2025; about CAD 30 million to Canadian Tire | An iconic blanket design moves to a mass retailer. | — |
| NOAA winter outlook, 2025 to 2026 | Below normal temperatures in Northern Plains and Upper Midwest | Colder regions are set for above-average blanket replacement. | [1] |
| China blanket market CAGR, 2026 to 2036 | 6.9% | Platform commerce widens access to wool and electric blankets. | Future Market Insights |
| Electric blanket product type share, 2026 | 16.5% | Regular blankets lead; electric blankets hold a smaller, fast-growing share. | Future Market Insights |
| Wool material type share, 2026 | 13.5% | Polyester and fleece lead; certified wool supports premium pricing for a minority share. | Future Market Insights |
| Residential end user share, 2026 | 62.5% | Seasonal household replacement leads demand. | Future Market Insights |
| Online retailer sales channel share, 2026 | 34% | E-commerce widens access to electric and premium wool blankets. | Future Market Insights |
Table 3: Retail Ownership and Labour Cost Benchmarks for the Blanket Market (mixed units and currencies), 2025 to 2026
| Indicator | Reported value | Related figure | Source |
|---|---|---|---|
| Blanket market, 2025 to 2026 | USD 9.1 billion to USD 9.5 billion | 4.2% CAGR, 2026 to 2036 | Future Market Insights |
| Hudson's Bay Company IP sale value | About CAD 30 million | Paid by Canadian Tire, 3 June 2025 | — |
| U.S. electric blanket recall units | About 8,560 units | 34 overheating reports, 3 burn injuries | [2] |
| Australian wool production, 2025 to 2026 | 244.7 million kg greasy | Forecast down 12.6% from 2024 to 2025 | [3] |
| NOAA colder region, winter 2025 to 2026 | Northern Plains and Upper Midwest | Below normal temperatures forecast | [1] |
| NOAA warmer region, winter 2025 to 2026 | Southern United States | Above normal temperatures forecast | [1] |
| China blanket CAGR | 6.9% | Fastest among five profiled countries, 2026 to 2036 | Future Market Insights |
Analyst Perspective
“Blanket brands that pair certified wool with safety-tested electric formats will gain replacement orders fastest in colder regions. Retailers that secure wool supply ahead of each shearing season will protect margin as raw wool volume tightens.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the blanket market segmented?
The blanket market is studied across four commercial segments plus region, namely product type, material type, end user and sales channel. In 2026, regular blankets hold 83.5% and electric blankets 16.5% of product type sales, polyester and fleece lead material type sales while wool holds 13.5%, residential buyers take 62.5% and online retailers 34% of respective segment sales.
By product type: electric blanket, and regular blanket.
By material type: wool, cotton, polyester, and others.
By end user: residential, and commercial.
By sales channel: online retailers, hypermarkets and supermarkets, specialty stores, multi brand stores, independent stores retailers, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do regular blankets lead product type sales?
Regular blankets hold 83.5% of product type sales in 2026, as buyers continue to favour a simple, lower-cost layer over single-thickness fill.
Table 4: Product Type Share for the Blanket Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Electric Blanket | 16.5% |
| Regular Blanket | 83.5% |
| Total | 100% |
Table 5: Product Type Leadership and Market Growth for the Blanket Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Regular Blanket |
Demand for regular blankets stays steady, as most buyers want a simple, lower-cost layer without a power cord. FMI finds that regular blankets account for 83.5% of product type sales in 2026, while electric blankets hold a smaller but growing 16.5%, as some buyers want adjustable heat instead of a single thickness of fill. The U.S. Consumer Product Safety Commission recalled about 8,560 MaxKare electric blankets in June 2025 over overheating and fire risk [2]. Safety-tested electric formats with auto shut-off are anticipated to keep gaining share through 2036.
- Regular blankets hold 83.5% of product type sales in 2026, while electric blankets account for 16.5%, since most homes still favour a simple, lower-cost layer.
- Buyers comparing electric blankets should check auto shut-off, wattage and the safety label, since these factors set burn and fire risk.
Why do polyester and fleece lead material type sales?
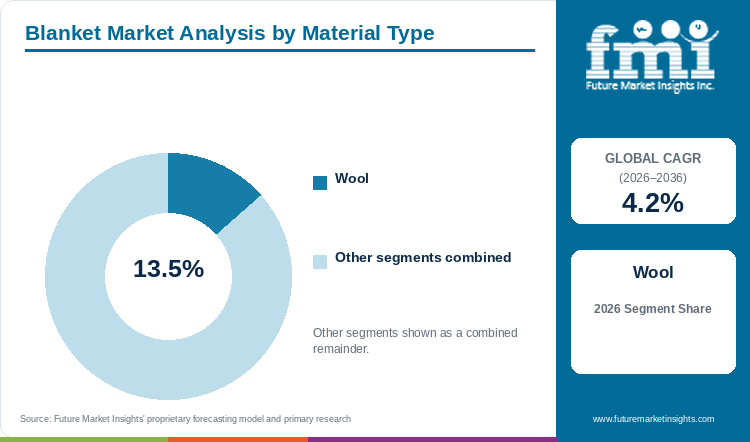
Wool blankets hold a smaller, premium-priced 13.5% of material type sales in 2026; polyester and fleece lead overall material type volume.
Demand for polyester and fleece blankets leads the market, as low-cost, easy-care synthetic fill suits mass replacement purchases. As per FMI estimates, wool holds a smaller, premium-priced 13.5% of material type sales in 2026. Cotton still suits buyers weighing price ahead of warmth, and other fibres serve budget ranges. Australian wool production is forecast to fall 12.6% in the 2025 to 2026 season to 244.7 million kilograms greasy [3]. Tighter wool supply is expected to keep raw material cost high for premium blanket makers through the near term.
- Wool blankets hold a smaller, premium-priced 13.5% of material type sales in 2026, as certified wool standards support pricing even though polyester and fleece lead overall material type volume.
- Buyers of wool blankets should check the shearing season and supply contract terms, since raw wool volume is tightening.
Why do residential buyers lead end user sales?
Residential buyers take 62.5% of end user sales in 2026, led by seasonal household replacement.
Demand for blankets among residential buyers is rising, as households replace worn bedding each winter. FMI data shows residential buyers making up 62.5% of end user sales in 2026. Commercial buyers, including hotels and care homes, replace blankets on a planned linen cycle instead of a seasonal one. Hospitality linen refresh programs keep commercial orders steady even as residential volume leads. Household replacement ahead of each winter is expected to keep residential buyers in front through 2036.
- Residential buyers take 62.5% of end user sales in 2026, and seasonal replacement will keep this group in front.
- Hospitality buyers should plan linen refresh orders around a fixed cycle, since bulk blanket orders need lead time.
Why do online retailers lead sales channel demand?
Online retailers capture 34% of sales channel revenue in 2026, supported by wider e-commerce reach.
Demand for blankets through online retailers is rising, as e-commerce listings widen access to electric and premium wool formats. FMI estimates that online retailers capture 34% of sales channel revenue in 2026. Hypermarkets, supermarkets and specialty stores still draw buyers who want to feel the fabric before paying. Online listings with wash guidance and safety information are anticipated to build buyer confidence in electric blankets bought sight unseen. Growth of online blanket sales is anticipated to continue through 2036.
- Online retailers hold 34% of sales channel revenue in 2026, supported by wider reach for electric and premium wool blankets.
- Specialty and multi brand stores should keep staff trained on wash care and safety labels, since in-store buyers often ask before paying.
What are the drivers, restraints, and opportunities in the blanket market?
Household replacement purchases drive most blanket sales, safety recalls and promotion-heavy pricing slow approvals, and certified wool and safety-tested electric formats open the main opportunity.
- Driver: Key drivers of the blanket market include household and hospitality replacement purchases ahead of each winter season.
- Restraint: Promotion-heavy retail cycles and rising freight cost compress margin on commodity blankets. Overheating risk in cheaper electric models also slows buyer confidence.
- Opportunity: Certified wool and safety-tested electric formats open growth for premium blanket brands in colder regions.
Safety Recalls Shape Electric Blanket Demand
Safety concerns are shaping which electric blankets buyers trust. The U.S. Consumer Product Safety Commission recalled about 8,560 MaxKare electric blankets in June 2025, after 34 overheating reports and three burn injuries [2]. Due to this, retailers are favouring brands with published safety labels and auto shut-off features. Sales of certified, safety-labelled electric blankets are anticipated to grow faster than unverified low-cost imports through 2036.[2]
Colder Winters Lift Regional Demand
Winter temperature swings are changing which regions see the fastest blanket demand growth within the United States. NOAA's outlook of October 17, 2025 pointed to below normal temperatures across the Northern Plains and the Upper Midwest for the 2025-26 winter [1]. Retailers in these colder US states saw blanket sales run ahead of the national average that season. Sales of electric and wool blankets are anticipated to keep tracking winter severity through 2036.[1]
Tight Wool Supply Raises Input Cost
Wool blanket makers are facing a smaller raw material pool. Australian wool production is forecast to fall 12.6% in the 2025 to 2026 season to 244.7 million kilograms greasy [3]. Due to this, makers of certified wool blankets are anticipated to pay more per kilogram of raw wool through the near term. Buyers of premium wool blankets are anticipated to keep paying higher prices for a smaller, well-documented supply.[3]
Which country CAGRs are profiled in the blanket market?
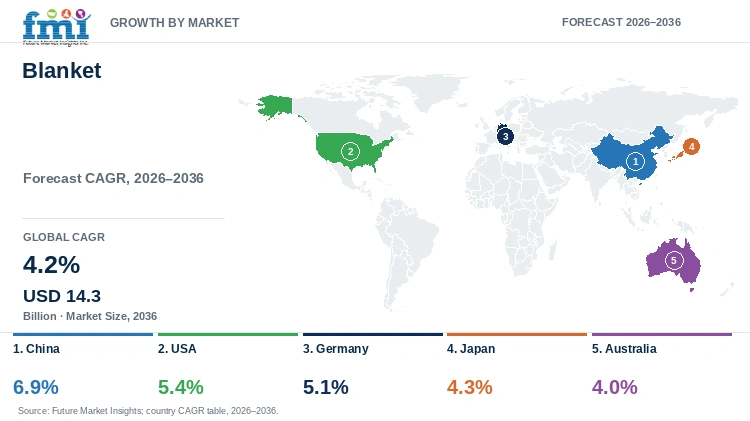
Sales of blankets in China grow fastest among the five profiled countries, at a 6.9% CAGR between 2026 and 2036. Australia posts the slowest rate, a 4% CAGR over the same period. Across all five, winter severity and wool supply set the pace of local demand.
Table 6: Country CAGRs and Primary Growth Levers for the Blanket Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026-2036) | Primary Growth Lever |
|---|---|---|
| China | 6.9% | Platform commerce widening access to wool and electric blankets |
| USA | 5.4% | Premium bedding demand and colder northern states |
| Germany | 5.1% | Certified wool demand amid rising labour cost |
| Japan | 4.3% | Compact electric blankets for localised heating |
| Australia | 4% | Steady demand against tightening wool supply |
Source: Future Market Insights
China Blanket Market Outlook (2026-2036)
China is set for the fastest profiled rate, a 6.9% CAGR for 2026 to 2036. Platform commerce keeps widening access to both electric and wool blankets for urban households. FMI finds that home furnishing spending on platforms has grown alongside wider online adoption of heated bedding. Due to this, online retailers are anticipated to keep gaining blanket sales in China ahead of physical stores.
Key takeaway: Online platform reach will draw most new Chinese blanket orders.
USA Blanket Market Outlook (2026-2036)
The USA is set for a 5.4% CAGR for 2026 to 2036. NOAA's outlook of October 17, 2025 pointed to below normal temperatures across the Northern Plains and the Upper Midwest, with above normal temperatures across the southern states, for the 2025-26 winter [1]. Due to this, blanket demand in colder northern states ran ahead of the national average that season. Premium bedding demand and safety-tested electric formats are anticipated to support most U.S. orders through 2036.[1]
Key takeaway: Colder northern states will draw the fastest U.S. blanket replacement orders.
Germany Blanket Market Outlook (2026-2036)
Germany is projected to add blanket sales at a 5.1% CAGR through 2036. Scrutiny of sustainability claims under EU textile rules is anticipated to keep certified wool blankets ahead in premium channels, supporting steady replacement demand.
Key takeaway: EU sustainability scrutiny will keep certified-wool ranges ahead in German premium channels.
Japan Blanket Market Outlook (2026-2036)
Japan is set for a 4.3% CAGR through 2036. Japanese households have long favoured compact electric blankets for localised winter heating in small rooms. FMI expects this preference to keep electric formats ahead of regular blankets through the forecast period.
Key takeaway: Compact electric formats will remain the main Japanese replacement purchase.
Australia Blanket Market Outlook (2026-2036)
Australia posts the slowest profiled rate, a 4% CAGR through 2036, as its milder climate and already high household blanket ownership limit replacement urgency compared with the other profiled markets.
Key takeaway: A milder climate and high existing bedding ownership will keep Australian demand growing at the slowest pace among profiled markets.
Who are the notable companies in the blanket market?
Pendleton Woolen Mills, Faribault Woolen Mill Co., American Blanket Company, Canadian Tire, Urbanara, Boll & Branch Co., Sunbeam (Newell Brands), Biddeford Blankets LLC, Beurer GmbH, Morphy Richards Ltd., and Shanghai Easun Group are the leading companies profiled in this market.
Blanket makers profiled here come from the United States, Germany, the United Kingdom and China, and differ in fibre focus, price tier and retail reach. Pendleton Woolen Mills, Faribault Woolen Mill Co. and American Blanket Company concentrate on heritage wool and woven blankets, and Canadian Tire now carries the heritage striped blanket design through its 2025 acquisition of Hudson's Bay Company's intellectual property. Urbanara and Boll & Branch Co. supply premium retail ranges. Sunbeam (Newell Brands), Biddeford Blankets LLC, Beurer GmbH, Morphy Richards Ltd. and Shanghai Easun Group complete the supplier set with electric and technical blankets.
- Heritage wool and woven blanket makers: Pendleton Woolen Mills, Faribault Woolen Mill Co., American Blanket Company, and Canadian Tire (IP owner of the Hudson's Bay striped blanket design) supply woven and wool blankets.
- Premium retail and comfort brands: Urbanara and Boll & Branch Co. cover premium home textiles.
- Electric and technical blanket makers: Sunbeam (Newell Brands), Biddeford Blankets LLC, Beurer GmbH, Morphy Richards Ltd., and Shanghai Easun Group supply heated and technical blankets.
Competitive Benchmarking: Blanket Market
Table 7: Competitive Benchmarking for the Blanket Market (qualitative capability ratings), 2026
| Company | Wool Design | Electric Format | Safety Testing | Retail Reach |
|---|---|---|---|---|
| Pendleton Woolen Mills | High | Low | Medium | High |
| Faribault Woolen Mill Co. | High | Low | Medium | Medium |
| American Blanket Company | Medium | Low | Medium | Medium |
| Canadian Tire | High | Low | Medium | High |
| Urbanara | Medium | Low | Medium | Medium |
| Boll & Branch Co. | Low | Low | Medium | Medium |
| Biddeford Blankets LLC | Low | High | Medium | Medium |
| Beurer GmbH | Low | High | High | High |
| Morphy Richards Ltd. | Low | High | High | Medium |
| Shanghai Easun Group | Low | High | Medium | High |
A company earns High when its blanket manufacturing activity is broadly documented, Medium when documentation covers only part of the range, and Low when public documentation is limited. Beurer GmbH is rated on the electric blanket range, and Canadian Tire on heritage woven designs.
Key Developments in the Blanket Market
- In June 2025, a Canadian court approved the sale of Hudson's Bay Company intellectual property, including the striped blanket design, to Canadian Tire for about CAD 30 million.
- In June 2025, the U.S. Consumer Product Safety Commission recalled about 8,560 MaxKare electric blankets over overheating and fire risk [2].[2]
- In December 2025, Australian Wool Innovation forecast shorn wool production falling 12.6% for the 2025 to 2026 season, tightening supply for wool blanket makers [3].[3]
Key Players in the Blanket Market
Heritage Wool and Woven Blanket Makers
- Pendleton Woolen Mills
- Faribault Woolen Mill Co.
- American Blanket Company
- Canadian Tire
Premium Retail and Comfort Brands
- Urbanara
- Boll & Branch Co.
Electric and Technical Blanket Makers
- Beurer GmbH
- Morphy Richards Ltd.
- Shanghai Easun Group
- Sunbeam (Newell Brands)
- Biddeford Blankets LLC
Blanket Market - Report Scope
Table 8: Report Scope for the Blanket Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; material type; end user; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Sales of electric blankets, regular blankets and related wool, cotton, polyester and other fibre blankets sold to residential and commercial buyers. Mattress pads, pillows and non-blanket bedding are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; USA; Germany; Japan; Australia |
| Key companies profiled | Pendleton Woolen Mills, Faribault Woolen Mill Co., American Blanket Company, Canadian Tire, Urbanara, Boll & Branch Co., Sunbeam (Newell Brands), Biddeford Blankets LLC, Beurer GmbH, Morphy Richards Ltd., Shanghai Easun Group |
| Forecast period | 2026 to 2036 |
| Approach | A bottom-up build was reconciled against top-down estimates covering retail sell-through, replacement cycles, wool supply conditions and country winter severity, checked against company data and primary interviews. |
Blanket Market - Research Methodology
Table 9: Research Methodology for the Blanket Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary research includes interviews with blanket brand managers, retail buyers, distributors and procurement teams. Interviews cover fibre sourcing, safety testing, pricing and seasonal demand. |
| Desk Research | Desk research draws on safety recall data, wool production reports, retail ownership records and winter temperature outlooks. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and adds retail sell-through, replacement cycle length, average selling price, segment splits and winter severity in each country. |
| Data Validation | Each estimate is tested against company disclosures, recall and supply data, and primary interviews. Non-blanket bedding stays outside market value, so no sale is counted twice. |
Blanket Market by Segments
Blanket Market segmented by Product Type:
- Electric blanket
- Regular blanket
Blanket Market segmented by Material Type:
- Wool
- Cotton
- Polyester
- Others
Blanket Market segmented by End User:
- Residential
- Commercial
Blanket Market segmented by Sales Channel:
- Online retailers
- Hypermarkets and supermarkets
- Specialty stores
- Multi brand stores
- Independent stores retailers
- Others
Blanket Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] NOAA, via WIS-TV. (2025, October 17). First Alert: NOAA releases winter outlook for 2025-26.https://www.wistv.com/2025/10/17/first-alert-noaa-releases-winter-outlook-2025-26
- [2] U.S. Consumer Product Safety Commission. (2025, June 18). MaxKare Electric Blankets Recalled Due to Burn and Fire Hazards Manufactured by Yumo and Sold Exclusively on Walmart.com.https://www.cpsc.gov/Recalls/2025/MaxKare-Electric-Blankets-Recalled-Due-to-Burn-and-Fire-Hazards-Manufactured-by-Yumo-and-Sold-Exclusively-on-Walmart-com
- [3] Australian Wool Innovation (Wool.com). (2025, December). Australian Wool Production Forecast Report, December 2025.https://www.wool.com/market-intelligence/wool-production-forecasts/australian-wool-production-forecast-report-december-2025/
This Report Answers
- What value will blanket sales reach in 2026?
- By 2036, what market value will blankets reach?
- Which product type takes the largest share of sales?
- What material type and end user do buyers favour?
- Which profiled countries show the fastest growth in blanket sales?
- Which companies lead the supply of blankets to retailers?
Frequently Asked Questions
What is the blanket market worth in 2026?
Blanket sales are valued at USD 9.5 billion in 2026, according to FMI. The market will reach USD 14.3 billion by 2036 as households and hospitality buyers replace worn bedding.
What CAGR is projected for the blanket market through 2036?
FMI projects a 4.2% CAGR for the blanket market from 2026 to 2036. Winter severity and certified wool supply will shape much of this growth.
Which product type holds a leading share in 2026?
Regular blankets hold 83.5% of product type sales in 2026. Electric blankets account for a smaller but growing 16.5%, as some buyers choose this format for adjustable heat during cold spells.
Which material type holds a leading share in 2026?
Polyester and fleece lead material type sales in 2026. Wool accounts for a smaller, premium-priced 13.5% share; certified wool standards support that premium pricing even as raw wool supply tightens.
Which country has a leading growth outlook through 2036?
China leads the profiled countries with a 6.9% CAGR for blanket sales over 2026 to 2036. Online platform shopping keeps widening access to wool and electric formats.
Which companies lead the supply of blankets to retailers?
Key companies include Pendleton Woolen Mills, Faribault Woolen Mill Co., American Blanket Company, Canadian Tire, Urbanara, Boll & Branch Co., Sunbeam (Newell Brands), Biddeford Blankets LLC, Beurer GmbH, Morphy Richards Ltd., and Shanghai Easun Group. These brands compete on fibre quality, safety testing and retail reach.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Electric blanket
- Regular blanket
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Type, 2026 to 2036
- Wool
- Cotton
- Polyester
- Others
- Y-o-Y Growth Trend Analysis By Material Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Type, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Residential
- Commercial
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Online retailers
- Hypermarkets and supermarkets
- Specialty stores
- Multi brand stores
- Independent stores retailers
- Others
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Material Type
- By End User
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pendleton Woolen Mills
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Faribault Woolen Mill Co.
- American Blanket Company
- Canadian Tire
- Urbanara
- Boll & Branch Co.
- Biddeford Blankets LLC
- Beurer GmbH
- Morphy Richards Ltd.
- Shanghai Easun Group
- Sunbeam (Newell Brands)
- Pendleton Woolen Mills
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


