
- Market Size (2026)
- USD 0.8 Bn
- Forecast (2036)
- USD 2.0 Bn
- CAGR (2026 to 2036)
- 10.0%
How big is Colloidal Silver Market in 2026?
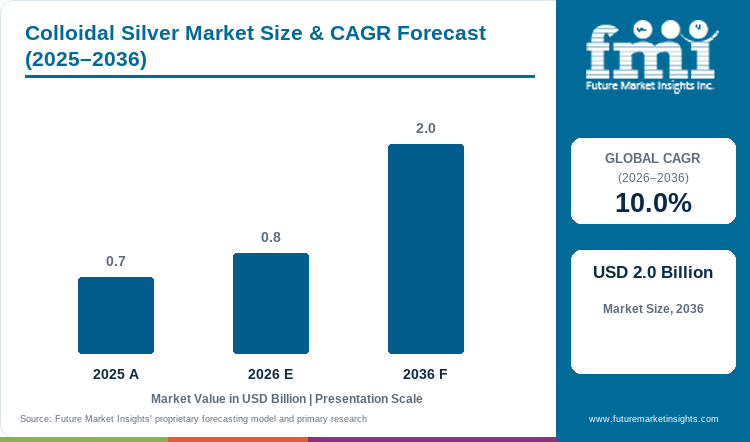
The colloidal silver market is valued at USD 0.8 billion in 2026 and is projected to reach USD 2.0 billion by 2036, growing at a 10.0% CAGR.
The colloidal silver market is valued at USD 0.8 Billion in 2026 and is forecast to reach USD 2.0 Billion by 2036 at a 10.0% CAGR. A formulator buying silver particles needs to know how they will behave once mixed into a coating, gel or other carrier. Concentration alone does not provide the full picture. Particle size and other physical properties also matter. A 2025 laboratory study found antibacterial activity in silver nanoparticles with an average particle size of 44.5 nm. Such findings still need to be tested in the final product. The 2025 base is estimated at USD 0.7 Billion.
The intended use affects which silver product a supplier can sell and what claims can be made. Research materials, topical products and oral products can face different requirements. Health Canada lists a Sovereign Silver oral suspension as an active licensed product. In the EU, colloidal silver in nanoform is prohibited in cosmetics under Commission Regulation (EU) 2024/858. Suppliers need to establish the intended use before selecting a particle grade or making product claims. Specifications for nanomaterials require particle-size and stability evidence.
Key Takeaways of Colloidal Silver Market
- Demand mechanism: Demand concentrates where buyers can connect silver particle specifications to a defined antimicrobial, materials or formulation requirement without crossing the product category's regulatory boundary.
- Form – Powder (leading form in 2026): Dry material lets formulators set loading and choose the downstream carrier closer to production.
- Particle Size – 21–50 nm (leading band in 2026): This band balances nanoscale surface effects with routine characterization across supplier catalogs.
- End Use – Healthcare (leading category in 2026): Silver remains relevant to qualified antimicrobial wound-care and medical-material workflows.
- Purchasing friction: Safety data, particle characterization, permitted claims and product-category compliance can delay conversion even when silver functionality is technically attractive.
- Profiled companies: American Biotech Labs, Sovereign Silver, Purest Colloids Inc.; Silver Biotics; Natural Path Silver Wings; Alfa Aesar (Thermo Fisher Scientific) and nanoComposix.
Analyst Perspective
Particle size has commercial value only when a supplier can reproduce it in the finished formulation and document safety for the intended route. No wound-dressing result establishes the safety of an oral product.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Colloidal Silver Market segmented?
The market is segmented by Form, Particle Size and End Use.
The colloidal silver market uses three segment axes with region as the geographic split.
Form covers powder and liquid.
Particle size covers 21-50 nm, 51-100 nm, 11-20 nm, 101-200 nm, and 5-10 nm.
End use covers healthcare, dietary supplements, pharmaceutical products, wound dressing, food & beverage processing, other industrial, consumer goods, medical devices, cosmetics & personal care, and others.
Why does Powder lead the Form category?
Powder gives formulators a concentrated input that can be weighed into coatings, composites or later dispersion systems without transporting the full carrier volume. It also separates silver loading from the final liquid chemistry. This matters when downstream buyers control pH or stabilizers themselves. The format still requires careful re-dispersion and agglomeration control. A 2025 U.S. patent publication assigned to American Silver LLC describes anhydrous compositions made by removing water from silver-particle suspensions and rehydrating them later.
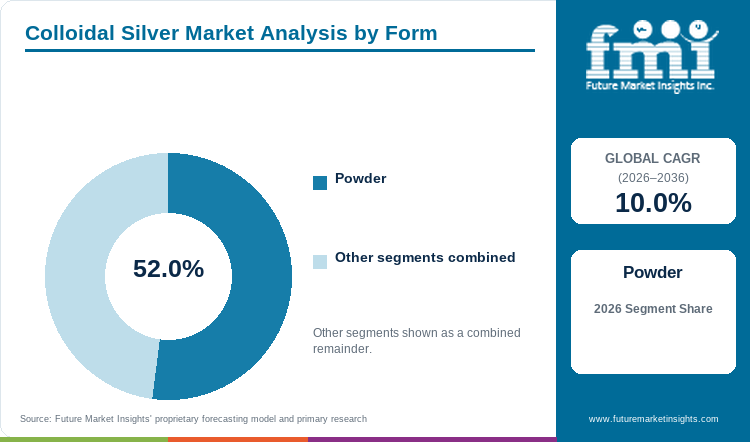
- Powder leads Form and accounts for 52.0% of Form in 2026: Formulators can set silver loading after choosing the final carrier. A premixed dispersion fixes both choices earlier.
- Dated example: The February 2025 American Silver patent publication covers anhydrous silver-particle compositions that can be reconstituted with water. A dry format can reduce carrier volume in transport before the buyer makes the final dispersion.
Why does 21-50 nm anchor the Particle Size category?
Particle size changes the surface area and behavior of silver nanoparticles in a dispersion. A 2025 laboratory study reported a mean particle diameter of 44.5 nm for a silver formulation with antibacterial activity. That result is specific to the tested material; it does not make every grade in the band equivalent. nanoComposix lists 30 nm and 40 nm silver nanospheres with batch characterization, while Thermo Scientific Chemicals offers size-specified dispersions. Buyers can write a size range into a purchase specification and then test whether it holds in their own carrier.
- The 21–50 nm band leads Particle Size and accounts for 23.0% of Particle Size in 2026: Buyers can specify a size-resolved material instead of purchasing on silver concentration alone.
- A 2025 laboratory study measured silver particles at 44.5 nm on average and tested antibacterial behavior. The result supports particle characterization as a purchasing variable, not a claim for every finished product in this size band.
What keeps Healthcare at the center of the End Use category?
Healthcare use is tied to the finished dressing or device, not to silver as a free-standing treatment. Japan's PMDA lists antimicrobial wound dressing and protection material as a Class III device category. A 2025 randomized study compared a silver-nanoparticle dressing with another pressure-ulcer treatment and found no significant difference between the two groups. These are defined clinical and regulatory settings. They do not support oral colloidal-silver claims. The antimicrobial coated medical devices category illustrates why finished-product testing matters.
- Healthcare leads End Use and accounts for 29.0% of End Use in 2026: Buyers can test a silver-containing wound product against a defined device indication, distinct from oral wellness claims.
- A 2025 randomized pressure-ulcer study evaluated a specific silver-nanoparticle dressing. Its findings belong to that dressing and treatment setting, showing why healthcare buyers qualify the finished product rather than the metal alone.
What are the drivers, restraints and opportunities in the Colloidal Silver Market?
In the colloidal silver market, the key driver is application demand persisting where silver particle behavior can be tied to antimicrobial coatings, wound-related materials, or engineered formulations, since size-defined grades let buyers specify a material and test its stability and performance in their own intended carrier. The key restraint is safety uncertainty and route-specific restrictions, which raise the burden for ingestible, cosmetic, and disease-claim products, as seen in the EU's prohibition of colloidal silver in nanoform in cosmetics and the FDA's limits on OTC disease-treatment claims in the US. The key opportunity is suppliers capturing more value through tight particle characterization, controlled formats, and documentation matched to the buyer's intended product category, letting research-grade nanomaterial suppliers turn repeatable specifications into a commercial advantage for healthcare and technical formulators.
- Driver: Application demand persists where silver particle behavior can be tied to antimicrobial coatings, wound-related materials or engineered formulations.
- Restraint: Safety uncertainty and route-specific restrictions raise the burden for ingestible, cosmetic and disease-claim products.
- Opportunity: Suppliers can capture more value through tight particle characterization, controlled formats and documentation matched to the buyer's intended product category.
Silver particles interest a formulator when they can be controlled in a specific coating, gel or other material, including wound dressings. A 2025 laboratory study measured particles averaging 44.5 nm and tested antibacterial behavior in its own formulation. That result does not predict the behavior of every dispersion. Thermo Scientific Chemicals and nanoComposix offer size-defined grades; letting a buyer specify the material and then test stability and performance in the intended carrier.
Consumer-facing uses raise product-specific safety and claims questions. Commission Regulation (EU) 2024/858 prohibits colloidal silver in nanoform in EU cosmetics. The UK’s 2026 cosmetics safety workplan lists micronised silver for assessment; that is a different material and an assessment, not an approval. Neither source establishes the safety or effectiveness of an oral silver product. Suppliers need to confirm the permitted use and supporting evidence before making health-related claims.
Size-characterized grades can reduce development work for healthcare and technical formulators. Singapore's HSA requires antimicrobial effectiveness testing for topical antiseptics whose actives lack established safety and efficacy support. The 2025 silver-particle study also shows why a buyer may ask for a measured distribution rather than a nominal concentration. nanoComposix offers batch characterization and custom materials, while Thermo Scientific Chemicals sells defined research grades. The commercial opening is in repeatable specifications matched to an actual application.
Which country CAGRs are profiled in the Colloidal Silver Market?
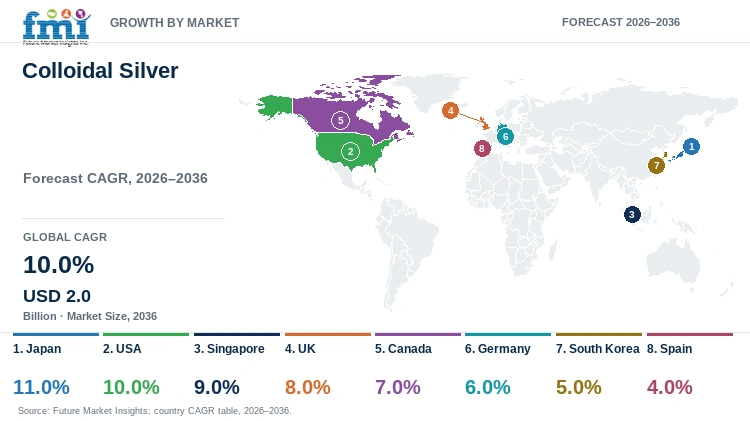
The profiled country CAGRs below cover 2026 to 2036.
| Country | CAGR |
|---|---|
| Japan | 11.0% |
| USA | 10.0% |
| Singapore | 9.0% |
| UK | 8.0% |
| Canada | 7.0% |
| Germany | 6.0% |
| South Korea | 5.0% |
| Spain | 4.0% |
How do country-level CAGRs compare in the colloidal silver market?
The profiled rates form three practical bands. Japan, the USA and Singapore sit at 9.0% or above. The UK and Canada form a middle band, while Germany, South Korea and Spain grow more slowly. The spread from Japan at 11.0% to Spain at 4.0% is 7 percentage points.
- Japan: a formal Class III pathway for antimicrobial wound dressings supports healthcare qualification, but product-specific evidence remains central to approval and adoption.
- USA: deep research and specialty-supplier availability supports formulation activity, while FDA limits OTC disease-treatment claims for colloidal silver.
- Singapore: HSA's topical-antiseptic framework makes claims, ingredient quality and efficacy testing explicit commercial gates.
- UK: nanomaterial notification requirements place particle identity and toxicological characterization close to the commercialization decision for cosmetics.
- Canada: authorized natural health product pathways coexist with enforcement against unauthorized colloidal metal health products.
- Germany: BfR's longstanding nanosilver safety caution and EU cosmetic restrictions push suppliers toward tightly bounded industrial or qualified uses.
- South Korea: MFDS guidance on nanomaterial-containing medicines raises the documentation threshold for pharmaceutical development.
- Spain: EU cosmetic restrictions reduce one visible consumer route, increasing the importance of permitted industrial and healthcare applications.
Country rates reflect different starting positions and product pathways.
Country-wise Analysis
- Japan has the fastest profiled growth rate at 11.0% from 2026 to 2036. The country offers a structured medical-device route for antimicrobial wound materials. PMDA lists antimicrobial wound dressing and protection material as a Class III device category. That classification matters because silver functionality must be packaged inside an approved device pathway rather than treated as a free-standing efficacy claim. Suppliers targeting Japanese healthcare buyers therefore need quality documentation that can be transferred into the finished product dossier. Research or industrial sales face a different threshold. Commercial success depends on proving fit with the buyer's regulated application and quality system.
- The USA is profiled at a 10.0% CAGR from 2026 to 2036. Its scientific-material suppliers offer size-defined silver particles and a 2025 American Silver patent publication describes anhydrous compositions that can be reconstituted. Those are technical product routes, not evidence for broad health claims. A buyer developing a coating or dressing needs to control particle size and the finished formulation; a consumer health product needs a separate, defensible regulatory and safety basis. The distinction shapes which suppliers can serve each account.
- Singapore carries a 9.0% CAGR for 2026 to 2036. HSA updated its topical-antiseptic guidance in August 2026 and sets explicit requirements for import, manufacture and sale. The agency states that actives lacking recognized safety and efficacy support must demonstrate antimicrobial effectiveness through testing. Claims and labels are also controlled. This environment can support specialty silver formulations when evidence is strong because buyers can see the qualification path clearly. It also filters weakly documented products. Suppliers seeking healthcare or consumer channels need clean ingredient specifications and test packages before distribution partners can treat a colloidal silver formulation as a repeatable commercial product.
- The UK is profiled at an 8.0% CAGR from 2026 to 2036. Great Britain's current cosmetic notification guidance asks for particle characteristics, exposure information and toxicology when a nanomaterial falls within its notification route. The country's 2026 safety workplan also includes micronised silver for assessment. That is not a decision on colloidal silver. For a formulator, the practical task is to define the material precisely before scheduling tests or making a cosmetic claim.
- Canada is profiled to expand at 7.0% from 2026 to 2036. Health Canada's current database lists Sovereign Silver under an active Natural Product Number. That listing is product-specific: it does not authorize every colloidal silver formulation or claim. A distributor considering another silver product must check its own authorization, label and quality file rather than assume the listed product's status transfers across the category.
- Germany is profiled at a 6.0% CAGR from 2026 to 2036. EU rules prohibit colloidal silver in nanoform in cosmetics under Commission Regulation (EU) 2024/858. A 2026 Commission regulation addresses other forms of silver while confirming the existing nanoform prohibition. Cosmetic formulators therefore need to identify the particle form before considering a product. Research and other technical uses require separate assessment.
- South Korea is profiled at a 5.0% CAGR from 2026 to 2036. Its Ministry of Food and Drug Safety was added to the WHO Listed Authority framework for its regulatory functions in 2025. That does not approve silver nanoparticles. For a medicine sponsor, it points to the need for a defined material, reproducible particle data and product-specific safety work. Suppliers selling a research dispersion face a different buying decision from those hoping to enter a regulated medical product.
- Spain has the lowest profiled growth rate at 4.0% from 2026 to 2036. Commission Regulation (EU) 2024/858 prohibits colloidal silver in nanoform in EU cosmetics. Spanish buyers considering industrial, research or healthcare uses need to assess those product routes separately. The intended use and applicable rules come before the particle specification and product claims.
Who are the notable companies in the Colloidal Silver Market?
American Biotech Labs, Sovereign Silver, Purest Colloids Inc., Silver Biotics, Natural Path Silver Wings, Alfa Aesar (Thermo Fisher Scientific) and nanoComposix are the notable companies profiled in this market.
The competitive set spans consumer formulations, medical products and research-grade particles. American Biotech Labs, Sovereign Silver; Purest Colloids Inc.; Silver Biotics and Natural Path Silver Wings sell silver formulations or consumer-facing products. Alfa Aesar (Thermo Fisher Scientific) and nanoComposix supply size-defined particles for research and technical buyers. Particle data; application qualification and supply format shape each company’s route to market.
- Formulation and consumer silver specialists: American Biotech Labs, Sovereign Silver, Purest Colloids Inc., Silver Biotics and Natural Path Silver Wings.
- Research-grade nanomaterial and chemical suppliers: Alfa Aesar (Thermo Fisher Scientific) and nanoComposix.
- Bulk and wholesale channels: Purest Colloids Inc. and Natural Path Silver Wings.
Competitive Benchmarking: Colloidal Silver Market
| Company | Particle Specification Depth | Application Qualification Evidence | Supply Format / Custom Scale | Geographic Reach |
|---|---|---|---|---|
| American Biotech Labs | Medium | High | High | United States manufacturing and consumer channels |
| Sovereign Silver | Medium | High | Medium | United States and Canada through an active Canadian NPN |
| Purest Colloids Inc. | Medium | Medium | High | United States direct sales and bulk supply |
| Silver Biotics | Medium | Medium | Medium | United States consumer channels; products manufactured within the affiliated American Silver group |
| Natural Path Silver Wings | Medium | Medium | Medium | United States with wholesale and international-order channels |
| Alfa Aesar (Thermo Fisher Scientific) | High | Medium | High | North America, Europe and Asia through Thermo Fisher scientific-chemicals channels |
| nanoComposix | High | High | High | Global customer base from the United States within Fortis Life Sciences |
Key Developments in the Colloidal Silver Market
- In February 2025, an American Silver patent application was published for anhydrous silver-particle compositions that can be reconstituted. The proposed dry format addresses the problem of shipping a dispersion before the final carrier has been chosen. A published application documents a technical approach; it does not establish commercial adoption.
- A Thermo Scientific Chemicals Certificate of Analysis for an 80 nm silver nanoparticle dispersion supplied in 2 mM sodium citrate (Catalogue No. J67252) carries a quality test and release date of March 2026. The document gives technical buyers a defined size and carrier to evaluate. That is a different proposition from selling a finished consumer silver formulation.
Key Players in the Colloidal Silver Market
Formulation and Consumer Silver Specialists
- American Biotech Labs
- Sovereign Silver
- Purest Colloids Inc.
- Silver Biotics
- Natural Path Silver Wings
Research-Grade Nanomaterial and Chemical Suppliers
- Alfa Aesar (Thermo Fisher Scientific)
- nanoComposix
Colloidal Silver Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form, Particle Size and End Use |
| Quantitative Units | Revenue in USD Million and CAGR in %. |
| Market Definition | Revenue includes colloidal silver material and silver-particle formulations sold within the stated Form, Particle Size and End Use universe. It includes direct colloidal silver products when the named silver formulation is the commercial product. It excludes the value of downstream finished devices, dressings, cosmetics or other products when colloidal silver is only one component. Adjacent silver salts, ionic-only systems and substitute antimicrobial materials are excluded when they are not sold as colloidal silver. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Canada, Japan, UK, Spain, Singapore, South Korea, Germany |
| Key Companies Profiled | American Biotech Labs, Sovereign Silver, Purest Colloids Inc., Silver Biotics, Natural Path Silver Wings, Alfa Aesar (Thermo Fisher Scientific), nanoComposix |
| Forecast Period | 2026 to 2036 |
| Approach | Recent public studies, product records and regulatory rules reviewed against the FMI forecast. |
Colloidal Silver Market - Research Methodology
| Method | Approach |
|---|---|
| Market Scope | The report separates research dispersions, topical products, device materials and consumer products because each has a different buyer and claim boundary. Particle size and carrier stability are discussed only where they affect a defined use. |
| Public Evidence | Evidence includes 2025 laboratory and dressing studies, current supplier specifications, Health Canada listings and 2026 European cosmetics rules. A laboratory antibacterial result is not treated as a finished-product efficacy claim. |
| Forecast Interpretation | The 2026 and 2036 values and country CAGRs are FMI forecasts. Public particle studies and regulatory records help explain market conditions; they do not independently calculate colloidal-silver revenue. |
| Source Checks | Claims were checked against the material form, product category and jurisdiction named in the source. Research grades, licensed products and prohibited cosmetic uses were kept distinct. |
Colloidal Silver Market by Segments
Colloidal Silver Market segmented by Form:
- Powder
- Liquid
Colloidal Silver Market segmented by Particle Size:
- 21-50 nm
- 51-100 nm
- 11-20 nm
- 101-200 nm
- 5-10 nm
Colloidal Silver Market segmented by End Use:
- Healthcare
- Dietary Supplements
- Pharmaceutical Products
- Wound Dressing
- Food & Beverage Processing
- Other Industrial
- Consumer Goods
- Medical Devices
- Cosmetics & Personal Care
- Others
Colloidal Silver Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- National Center for Complementary and Integrative Health (n.d.). Colloidal Silver: What You Need To Know.
- Office for Product Safety and Standards (n.d.). How to notify products containing nanomaterials.
- Health Sciences Authority, Singapore (2026, August 7). Topical antiseptics.
- Pharmaceuticals and Medical Devices Agency, Japan (n.d.). JMDN information: Antimicrobial wound dressing and protection material.
- Thermo Scientific Chemicals (2026). Silver nanoparticles, 80 nm, 0.02 mg/mL, supplied in 2 mM sodium citrate, 457 nm absorption. Catalogue No. J67252.
- Thermo Fisher Scientific (n.d.). Alfa Aesar now Thermo Scientific Chemicals.
- nanoComposix (n.d.). 30 nm Silver Nanospheres.
- nanoComposix (n.d.). 75 nm Silver Nanospheres.
- Purest Colloids Inc. (n.d.). Bulk Colloids.
- Purest Colloids Inc. (n.d.). MesoSilver.
- Natural Path Silver Wings (n.d.). The Silver Specialists.
- Sovereign Silver (n.d.). Immune Support Liquid Drops.
- Natural Path Silver Wings (n.d.). Contact Us.
- Silver Biotics (n.d.). Silver Biotics.
- Google Patents (2025, February 13). US20250049038A1 - Anhydrous silver compositions and uses thereof.
- Nouryon (n.d.). Contact Nouryon - a global specialty chemicals leader.
- UK Office for Product Safety and Standards (2026). SAG-CS Workplan January to December 2026.
- Original 2025 silver-nanoparticle formulation study
- Original 2025 pressure-ulcer dressing trial
- European Commission, 2026 silver cosmetics regulation
- Clifton Mining, October 2025 company update
- American Silver, February 2025 patent publication
- Thermo Scientific Chemicals, May 2026 silver nanoparticle specification
- Health Canada, current Sovereign Silver licensed-product entry
- UK government, current cosmetic nanomaterial notification guidance
- UK government, 2026 chemical-safety assessment workplan
- Republic of Korea, 2025 MFDS WHO authority listing
This Report Answers
- How large is the Colloidal Silver Market in 2026, and what value is forecast for 2036?
- Which industry pressures support demand for colloidal silver across qualified applications?
- Why does Powder hold the leading position in the Form category?
- Why does 21-50 nm hold the leading position in the Particle Size category?
- How do the profiled country growth rates differ from 2026 to 2036?
- Which profiled companies supply silver formulations, research-grade nanoparticles or related market capabilities?
- What limits adoption or supplier switching in regulated and technically demanding applications?
- What should buyers evaluate before purchasing colloidal silver or a silver-particle formulation?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Powder
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Particle Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Particle Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Particle Size, 2026 to 2036
- 21-50 nm
- 51-100 nm
- 11-20 nm
- 101-200 nm
- 5-10 nm
- Y-o-Y Growth Trend Analysis By Particle Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Particle Size, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Healthcare
- Dietary Supplements
- Pharmaceutical Products
- Wound Dressing
- Food & Beverage Processing
- Other Industrial
- Consumer Goods
- Medical Devices
- Cosmetics & Personal Care
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Form
- By Particle Size
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Particle Size
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- Singapore
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Particle Size
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Particle Size
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- American Biotech Labs
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sovereign Silver
- Purest Colloids Inc.
- Silver Biotics
- Natural Path Silver Wings
- Alfa Aesar (Thermo Fisher Scientific)
- nanoComposix
- American Biotech Labs
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Form, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Particle Size, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Form
- Figure 6: Global Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Particle Size
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Form
- Figure 26: North America Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Particle Size
- Figure 29: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End Use
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Form
- Figure 36: Latin America Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Particle Size
- Figure 39: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End Use
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Form
- Figure 46: Western Europe Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Particle Size
- Figure 49: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End Use
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Form
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Particle Size
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Form
- Figure 66: East Asia Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Particle Size
- Figure 69: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End Use
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Form
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Particle Size
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Form, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Form, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Form
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Particle Size, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Particle Size, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Particle Size
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Colloidal Silver Market in 2026, and what is forecast for 2036?
The market is valued at USD 0.8 Billion in 2026 and is forecast to reach USD 2.0 Billion by 2036. The increase reflects expanding use of controlled silver-particle formulations across the supplied end-use universe.
What is the CAGR for the Colloidal Silver Market from 2026 to 2036?
The market is forecast to grow at a 10.0% CAGR from 2026 to 2036. The rate describes the overall forecast path and should not be applied to individual companies or countries unless separately stated.
Which Form segment leads the Colloidal Silver Market?
Powder leads Form in 2026. Its position reflects the flexibility of dry silver inputs for controlled loading and later selection of a dispersion or carrier system.
Which Particle Size segment leads the Colloidal Silver Market?
The 21-50 nm segment leads Particle Size in 2026. This range combines nanoscale functional behavior with widely available particle-characterization and supply options.
Which profiled countries have the highest growth rates in the Colloidal Silver Market?
Japan has the highest profiled CAGR at 11.0% from 2026 to 2036. The USA follows at 10.0%, while Singapore is profiled at 9.0% over the same period.
Which companies are active in the Colloidal Silver Market?
American Biotech Labs, Sovereign Silver, Purest Colloids Inc.; Silver Biotics and Natural Path Silver Wings supply silver formulations or consumer-facing products. Alfa Aesar (Thermo Fisher Scientific) and nanoComposix supply research-grade nanoparticles.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
