
- Market Size (2026)
- USD 792.6 Mn
- Forecast (2036)
- USD 1487.8 Mn
- CAGR (2026 to 2036)
- 6.5%
How big is Isomalto-oligosaccharide Market in 2026?
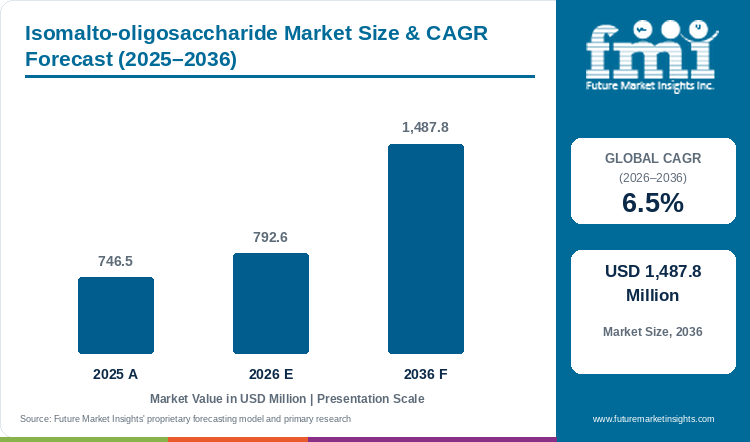
With a valuation of USD 746.5 million in 2025 and moving to USD 792.6 million in 2026, the isomalto-oligosaccharide market is positioned to attain USD 1,487.8 million by 2036, exhibiting a CAGR of 6.5%.
Sports snack co-packers and functional confectionery brands are replacing high-glycemic glucose syrups with low-viscosity oligosaccharide binders that prevent slab-bar hardening during ambient shelf storage. Procurement analysis by FMI finds that the global isomalto-oligosaccharide market was valued at USD 746.5 million in 2025 and is estimated to reach USD 792.6 million in 2026. Overall industry valuation is projected to reach USD 1,487.8 million by 2036, expanding at a compound annual growth rate (CAGR) of 6.5% over the forecast period. Liquid IMO Syrup at 75 to 80 Brix is projected to hold a 58.4% share of 2026 demand, given that high-solids liquid syrups pump directly into continuous bar-mixing extruders without energy-intensive spray drying.
This functional humectant role separates the market from the modified starch category at 3.8% CAGR, since conventional starches thicken cooked sauces while alpha-1,6-linked oligosaccharides replace sucrose bulk and inhibit sugar recrystallization in cold-processed snacks. Commercial demand for enzymatic oligosaccharides is supported by sponge-cake and bar reformulation trials, as Smaoui reported in Foods in June 2026 that simultaneous saccharification and transglucosylation yields up to 96 grams per liter of isomalto-oligosaccharides while enabling 25% to 100% sucrose replacement [1]. Ingredient makers are also expanding clean-label starch substrates, as seen when dsm-firmenich detailed its 2025 Taste, Texture and Health sugar-reduction formulation investments in February 2026 [24]. Co-packers renew multi-year IMO supply contracts when suppliers guarantee low residual free glucose below 5% to protect low-glycemic label claims.
Key Market Trends & Insights
- By physical state: Concentrated Liquid IMO Syrup 75 to 80 Brix is projected to capture 58.4% in 2026 since heated bulk syrups act as direct liquid binders in nutrition bar slab lines.
- By raw feedstock: Enzymatic Conversion of Corn Starch is estimated to hold 64.5% in 2026 owing to abundant wet-milling starch supply and low transglucosidase conversion cost.
- By commercial application: Protein Nutrition Bars and Sports Snacks are anticipated to account for 32.6% in 2026 given that alpha-1,6 oligomers prevent protein-powder bar hardening over twelve-month shelf life.
- By certification and grade: Conventional Food Grade is expected to secure 71.5% in 2026 on account of cost-in-use advantages across mainstream sports snacks and functional beverages.
- By sales channel: Direct to Nutritional Bar and Food Manufacturers is forecast to command 57.0% in 2026 through customized dextrose-equivalent and free-sugar specification contracts.
Regional Highlights
- Top national expansion: China leads national growth projections at a 7.6% CAGR through 2036 under large-scale Shandong enzymatic corn-starch biomanufacturing and domestic dairy drink fortification.
- Broader country progression: Canada tracks at a 6.9% CAGR ahead of the USA at 6.6% and the UK at 6.3%, while Japan advances at a 4.8% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Isomalto-oligosaccharide Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 746.5 million |
| Estimated Market Size in 2026 | USD 792.6 million |
| Projected Market Size by 2036 | USD 1,487.8 million |
| CAGR, 2026 to 2036 | 6.5% |
| Added Revenue, 2026 to 2036 | USD 695.2 million |
High-protein snack bar and gummy supplement manufacturers confront severe texture hardening when whey or plant proteins absorb free moisture from conventional corn syrups during warehouse storage. When formulators substitute sugar alcohols such as maltitol, excessive dosing above 15 grams per bar triggers laxative warnings and cooling off-notes. In October 2025, Roquette introduced its AMYSTA L 123 thermally soluble pea starch platform to address clean-label texturizing and soluble carbohydrate demand across modern food matrices [2]. Accordingly, snack formulators pair enzymatic isomalto-oligosaccharide syrups with isomalt sweeteners to lock in bar softness and mild 40% sucrose-equivalent sweetness.
Starch Transglucosylation and Active-Dosage Sizing
Table 2: Starch Conversion and Active-Dosage Sizing for the Isomalto-oligosaccharide Market (USD million and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 746.5 | 792.6 | 1,487.8 |
| Converted corn, tapioca & pulse starch input (thousand metric tons) | 485.0 to 530.0 | 512.0 to 560.0 | 920.0 to 1,010.0 |
| Commercial IMO syrup & powder shipment volume (thousand metric tons) | 355.0 to 388.0 | 375.0 to 410.0 | 675.0 to 740.0 |
| Blended wholesale realization per metric ton (USD) | 1,980 to 2,150 | 2,010 to 2,180 | 2,080 to 2,260 |
Industrial IMO synthesis relies on sequential liquefaction of corn or tapioca starch using bacterial alpha-amylase followed by beta-amylase saccharification and fungal alpha-transglucosidase conversion of alpha-1,4 bonds into digestion-resistant alpha-1,6 linkages. As per Tate & Lyle PLC in August 2026, global food and drink manufacturers absorbed 18.3 billion daily fiber-gap servings and 12 million metric tons of sugar removal between April 2020 and March 2026 [3]. That structural shift toward reduced-sugar carbohydrate binders directly supports demand for tapioca ingredients and enzymatic starch oligosaccharides.
Enzymatic Bioconversion & Co-Packer Line Sizing
Table 3: Enzymatic Bioconversion and Co-Packer Spending Indicators for the Isomalto-oligosaccharide Market (USD and operational metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Cold-extruded protein bar & gummy batch volume (thousand metric tons) | 1,120 to 1,250 | 1,190 to 1,330 | 2,180 to 2,420 |
| Annual IMO binder spend per commercial bar co-packer line (USD thousand) | 145.0 to 175.0 | 154.0 to 186.0 | 275.0 to 330.0 |
| High-purity IMO-900 low-glucose grade share (%) | 62.0% to 66.0% | 64.0% to 68.0% | 76.0% to 81.0% |
| Non-GMO tapioca & organic pulse feedstock share (%) | 31.0% to 34.0% | 33.5% to 36.5% | 44.0% to 48.5% |
Table 4: Industrial Starch Conversion & Channel Spending Indicators for the Isomalto-oligosaccharide Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 792.6 million | 2026 global revenue baseline |
| Sucrose replacement range in sponge cakes & bars | 25.0% to 100.0% | MDPI Foods June 2026 oligosaccharide baking benchmark |
| Gummy, chew & powder share of global supplement sales | Over 60.0% share | Kerry 2026 Supplements Taste Charts industry benchmark |
| Protein Nutrition Bars & Sports Snacks allocation, 2026 | 32.6% share | Primary commercial binder and humectant application |
High panose and isomaltotetraose yields above 70% total oligosaccharides require high-activity fungal transglucosidase enzymes coupled with simulated moving-bed chromatography to strip digestible maltose and glucose. In August 2026, Novonesis reported 9% organic revenue growth in its Food and Health Biosolutions division during the first half of 2026, driven by strong enzyme demand across food and beverage starch processing [4]. Specialty carbohydrate refiners also evaluate pea starch feedstocks to satisfy non-corn and grain-free label specifications.
Analyst Perspective
"Protein bar and gummy co-packers do not buy isomalto-oligosaccharides merely as a bulk sweetener; they buy water-activity control that keeps a 20-gram protein bar chewable at month ten without spiking free sugar counts. Refiners that invest in chromatographic glucose removal to deliver low-glycemic, non-GMO tapioca and pea-based IMO grades will win long-term North American and European supply contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Isomalto-oligosaccharide Market segmented?
The isomalto-oligosaccharide market is segmented by physical state, raw feedstock, commercial application, certification and grade, and sales channel.
By physical state: Concentrated Liquid IMO Syrup 75 to 80 Brix; Spray-Dried IMO Soluble Fine Powder; Agglomerated Instant Granules; Blended Prebiotic Premixes.
By raw feedstock: Enzymatic Conversion of Corn Starch; Tapioca Starch Hydrolysates; Organic Pea and Pulse Starch; Rice and Cereal Starches.
By commercial application: Protein Nutrition Bars and Sports Snacks; Low-Sugar Functional Beverages; Dietary Fiber Supplements and Gummies; Confectionery and Reduced-Calorie Fillings; High-Fiber Bakery and Extruded Cereals.
By certification and grade: Conventional Food Grade; Certified Organic IMO; Identity-Preserved Non-GMO; Clean-Label Low-Digestible Grade.
By sales channel: Direct to Nutritional Bar and Food Manufacturers; Specialty Ingredient Distributors; Contract Nutraceutical Co-Packers; B2B Digital Ingredient Platforms.
Why does Concentrated Liquid IMO Syrup 75 to 80 Brix lead the physical state category?
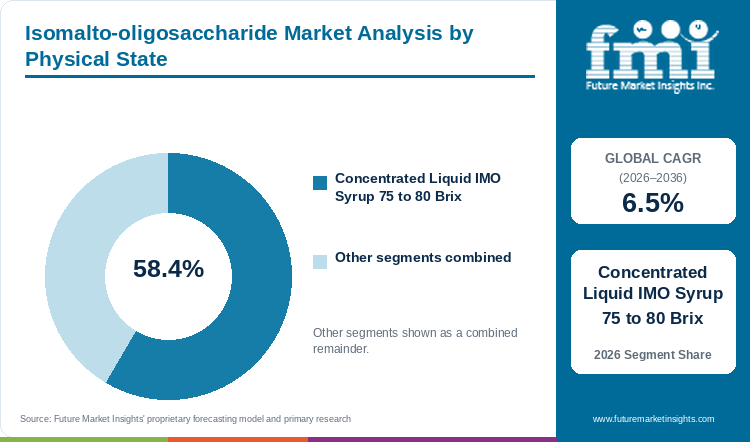
Concentrated Liquid IMO Syrup 75 to 80 Brix holds an estimated 58.4% of physical state demand in 2026, anchored by direct liquid bar-binder pumping and lower processing cost.
Table 5: Physical State Share for the Isomalto-oligosaccharide Market (percentage share), 2026
| Physical State | Share (2026) |
|---|---|
| Concentrated Liquid IMO Syrup 75 to 80 Brix | 58.4% |
| Other Segments Combined | 41.6%* |
| Total | 100.0% |
*Note: Remaining physical state categories account for the balance of 2026 global isomalto-oligosaccharide demand.
Table 6: Physical State Leadership and Market Growth for the Isomalto-oligosaccharide Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.5% |
| Leading Segment | Concentrated Liquid IMO Syrup 75 to 80 Brix |
High-Brix Liquid IMO Syrup leads commercial volume since cold-extruded protein bar, cereal cluster, and pectin gummy lines require a pumpable liquid binder to coat dry protein isolates and nut pieces. Direct procurement of liquid syrup from enzymatic starch refiners eliminates the 25% to 35% spray-drying toll required for powders, lowering unit binder cost for nutritional bars manufacturers. Heated jacketed tote storage at 35 to 45 degrees Celsius is still required in winter climates to prevent high-Brix viscosity spikes during unloading.
- Within the physical state segment, Concentrated Liquid IMO Syrup 75 to 80 Brix is projected to account for a leading 58.4% share in 2026, supported by direct liquid binder integration and lower processing cost.
- In September 2026, Yoshida et al. reported in Frontiers in Nutrition that starch-derived glucose oligosaccharides with a degree of polymerization of 3 or higher and an average molecular weight of 2,000 Daltons ferment gradually and maintain colonic pH stability over 48 hours [5].
What sustains Enzymatic Conversion of Corn Starch leadership in raw feedstock?
Enzymatic Conversion of Corn Starch represents 64.5% of the raw feedstock category in 2026, supported by integrated wet-milling supply and high transglucosidase yields.
Enzymatic Conversion of Corn Starch anchors global output since integrated wet-milling complexes in China, the United States, and Europe supply purified corn starch slurry directly into adjacent transglucosylation reactors via pipeline. Continuous pipeline feeding avoids intermediate starch drying and cuts raw feedstock cost by 20% to 30% compared with imported cassava roots used in vegan protein bars. In April 2026, Madrid agricultural attaché filings reported that European Union industrial grain starch demand continues expanding even as feed grain usage moderates [6].
- In 2026, Enzymatic Conversion of Corn Starch is anticipated to capture 64.5% of raw feedstock demand, reflecting integrated wet-mill economics and high enzymatic conversion yields.
- Tapioca and organic pea starch hydrolysates are projected to gain share among grain-free and allergen-friendly snack brands, though corn starch retains the core volume baseline.
How do Protein Nutrition Bars and Sports Snacks lead commercial applications?
Protein Nutrition Bars and Sports Snacks account for 32.6% of commercial application volume in 2026, driven by anti-hardening humectancy and mild sweetness.
Protein Nutrition Bars and Sports Snacks represent the primary demand engine since concentrated whey, soy, and pea protein isolates aggressively bind water and turn brittle within weeks unless plasticized by branched oligosaccharides. Alpha-1,6-linked IMO oligomers inhibit Maillard browning reactions between reducing sugars and lysine amino groups, preserving golden bar color and soft bite across sports nutrition distribution channels. Formulators in jurisdictions where standard IMO does not qualify as dietary fiber on nutrition panels often blend IMO with soluble corn fiber or allulose.
- By commercial application, demand for Protein Nutrition Bars and Sports Snacks is estimated to reach 32.6% of total category share in 2026 as high-protein snacking expands across mainstream grocery aisles.
- Kerry Group published its 2026 Supplements Taste Charts in January 2026, reporting that gummies and convenient snack formats now account for over 60% of supplement and functional nutrition sales [7].
Why does Conventional Food Grade lead the certification and grade category?
Conventional Food Grade secures 71.5% of certification and grade value in 2026, supported by cost-in-use efficiency across mainstream sports nutrition brands.
Conventional Food Grade formulations capture the majority of commercial volume because large-scale sports bar, carbonated beverage, and bakery plants prioritize low per-kilogram binder cost and consistent dextrose-equivalent viscosity. Certified organic IMO requires identity-preserved organic corn or tapioca starch plus non-GM enzyme processing, which raises finished syrup pricing by 40% to 65%. In February 2026, Roquette earned NutraStrong Prebiotic Verified certification for its soluble fiber portfolio, illustrating how conventional plant-derived carbohydrates establish clinical credibility across global food brands [8].
- Strong repeat procurement across contract bar and beverage plants places Conventional Food Grade on course to hold an estimated 71.5% share of certification and grade demand in 2026.
- Identity-Preserved Non-GMO tapioca grades represent the fastest-growing premium tier as clean-label retail standards tighten across North America and Western Europe.
What gives Direct to Nutritional Bar and Food Manufacturers the leading position in sales channel?
Direct to Nutritional Bar and Food Manufacturers commands 57.0% of sales channel share in 2026, anchored by bulk tanker delivery and custom low-glucose specifications.
Direct to Nutritional Bar and Food Manufacturers dominates channel distribution because multi-line co-packers consume 20-metric-ton tank trucks and 1,250-kilogram intermediate bulk containers that ship directly from starch refineries. Direct supply contracts allow buyers to specify exact panose-to-isomaltose ratios and maximum residual glucose ceilings below 3% or 5% to prevent crystallization on high-speed slab lines. Smaller emerging snack brands rely on specialty ingredient distributors for palletized drum and 25-kilogram bag deliveries.
- Direct to Nutritional Bar and Food Manufacturers is predicted to secure 57.0% of sales channel demand in 2026, anchored by bulk tanker economics and custom oligosaccharide specification audits.
- Ingredion and Batory Foods signed an expanded North American ingredient distribution agreement in March 2026 to strengthen regional delivery of specialty sweeteners and functional fibers to mid-market food processors [9].
What are the drivers, restraints, and opportunities in the Isomalto-oligosaccharide Market?
In the isomalto-oligosaccharide market, high-protein snack bar and gummy expansion is projected to drive adoption whereas partial small-intestinal cleavage of disaccharide fractions restrains U.S. dietary-fiber labeling and chromatographically enriched tapioca grades open clean-label growth.
- Driver: Rapid expansion of cold-extruded protein bars and pectin gummies requires anti-crystallizing oligosaccharide binders that maintain soft texture and low water activity.
- Restraint: Partial brush-border hydrolysis of short-chain disaccharide isomaltose by human small-intestinal isomaltase restricts dietary-fiber label qualification under strict FDA and EFSA definitions.
- Opportunity: Chromatographic enrichment of long-chain DP 4 to DP 10 oligomers and enzymatic synthesis from non-GMO tapioca and pea starches open low-glycemic clean-label formulations.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Consumer migration from chocolate confectionery toward 20-gram protein bars and functional gummy supplements is driving sustained volumetric demand for non-crystallizing carbohydrate binders. When co-packers run high-speed starchless depositing or cold slab extrusion in place of molding starch mogul lines, IMO syrups provide the exact glass-transition temperature needed to prevent wrapper sticking without adding sucrose. Peer-reviewed research by Fan et al. published in Frontiers in Nutrition in January 2026 confirmed that undigested prebiotic oligosaccharides selectively stimulate Bifidobacterium, Faecalibacterium prausnitzii, and Roseburia taxa to elevate colonic butyrate output [10]. This dual technological and prebiotic profile sustains repeat bulk ordering.
Risk Assessment of the Isomalto-oligosaccharide Market: Operational and Formulation Friction
Regulatory divergence regarding whether alpha-1,6-linked glucose oligomers qualify as non-digestible dietary fiber versus partially digestible carbohydrate represents the primary commercial restraint facing IMO suppliers. While Health Canada authorizes VitaFiber IMO as a novel dietary fiber source, the U.S. Food and Drug Administration denied general dietary-fiber status for standard high-isomaltose IMO after clinical assays showed partial small-intestinal cleavage, prompting some American brands to blend digestion resistant maltodextrin. In February 2026, Ghyselinck et al. documented in Frontiers in Nutrition that European Union Directive 2008/100/EC requires carbohydrate polymers to resist small-intestinal hydrolysis and undergo colonic fermentation to qualify as dietary fiber [11].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Starch bioprocessors are capturing higher margins by installing simulated moving-bed chromatography and engineered transglucosidases that strip digestible disaccharides and enrich DP 4 to DP 10 panose and isomaltotetraose fractions. The combination of slow-hydrolyzing long-chain IMO with xylo-oligosaccharides or tapioca dextrins allows beverage and bar formulators to achieve both low glycemic impact and verified prebiotic fermentation. In July 2026, ADM and Matsutani celebrated 20 years of joint innovation in prebiotic dietary fibers, highlighting ongoing development of clean-label tapioca-based fiber solutions for global food and beverage brands [12].
Isomalto-oligosaccharide Market by Country (2026 to 2036)
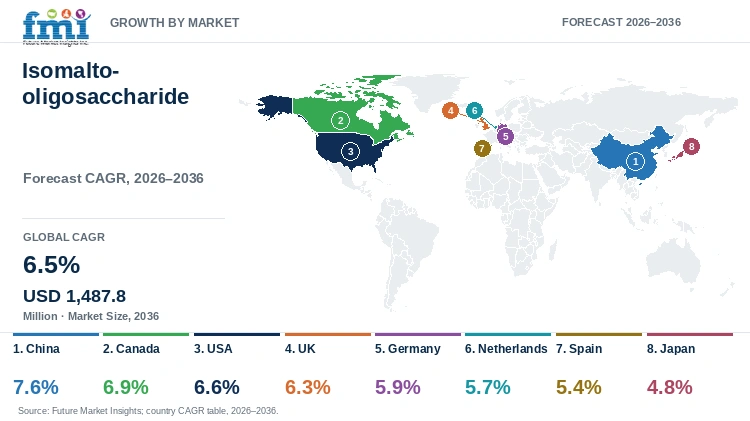
FMI country modeling indicates that China leads national isomalto-oligosaccharide expansion at a 7.6% CAGR through 2036, while Japan advances at a 4.8% CAGR. Commercial demand across Chinese starch biomanufacturing hubs, Canadian novel-fiber snack plants, and European confectionery lines reflects local dietary-fiber regulations and starch feedstock availability.
Table 7: Country CAGR and Primary Growth Levers for the Isomalto-oligosaccharide Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 7.6% | Shandong enzymatic corn-starch fermentation cluster and domestic functional dairy drinks |
| Canada | 6.9% | Health Canada approved dietary-fiber status and mandatory January 2026 sugar warning labels |
| USA | 6.6% | Contract protein bar extrusion and non-GMO tapioca gummy binder reformulation |
| UK | 6.3% | HFSS retail promotional rules and private-label reduced-sugar protein snack bars |
| Germany | 5.9% | Sports nutrition contract manufacturing and spray-dried prebiotic beverage mixes |
| Netherlands | 5.7% | Rotterdam bulk ingredient distribution hubs and Benelux dairy and snack formulation |
| Spain | 5.4% | Reduced-sugar Mediterranean bakery, turron confectionery, and sports snack lines |
| Japan | 4.8% | Mature FOSHU digestive-health syrups and anti-retrogradation bakery applications |
Source: Future Market Insights analysis
China Isomalto-oligosaccharide Market Outlook (2026 to 2036)
Demand for isomalto-oligosaccharides in China is projected to expand at a leading 7.6% CAGR between 2026 and 2036, anchored by the world's largest enzymatic corn-starch fermentation cluster in Shandong province. What sets China apart from Western import-dependent markets is vertical integration from domestic corn wet-milling into IMO-500 and IMO-900 syrup and powder refining by Yucheng and Dezhou biomanufacturers. Shenyang agricultural trade filings in April 2026 confirmed that Chinese food and beverage processors are rapidly expanding functional dairy drinks, prebiotic teas, and nutritional bakery items across urban retail channels [13]. Domestic price competition among mid-tier Shandong refiners nonetheless compresses standard IMO-500 margins.
Key takeaway: In China, vertically integrated Shandong corn-starch biomanufacturing and domestic functional dairy beverage expansion are projected to drive leading global IMO growth.
Canada Isomalto-oligosaccharide Market Outlook (2026 to 2036)
Canada's isomalto-oligosaccharide market is anticipated to grow at a 6.9% CAGR from 2026 through 2036, supported by Health Canada's official recognition of isomalto-oligosaccharides as an approved dietary fiber source and strong domestic production in Alberta. Compared with the United States where standard IMO cannot be declared as dietary fiber on Nutrition Facts panels, Canadian snack bar and cereal processors use IMO to simultaneously cut added sugar and claim grams of prebiotic fiber. Toronto agricultural attaché filings in August 2026 documented steady growth across Canada's functional food and snack processing sector as mandatory front-of-package high-sugar warning symbols took effect in January 2026 [14]. Export-oriented Canadian bar manufacturers selling into U.S. grocery chains must still maintain dual packaging labels to accommodate cross-border regulatory differences.
Key takeaway: In Canada, approved dietary-fiber regulatory status and mandatory 2026 front-of-package sugar warning labels are anticipated to sustain strong domestic IMO adoption.
USA Isomalto-oligosaccharide Market Outlook (2026 to 2036)
Commercial demand for isomalto-oligosaccharides in the USA is forecast to expand at a 6.6% CAGR during 2026 to 2036, driven by functional gummy vitamin manufacturing and sports nutrition co-packing. Even without FDA dietary-fiber label credit, American formulators purchase organic tapioca IMO syrups for their cold-binding flexibility and non-GMO clean-label declaration compared with corn glucose syrup. In October 2026, Cargill's Future of Sweeteners consumer research confirmed that 25% of U.S. Gen Z and millennial shoppers prioritize reduced-sugar formulations over 17% seeking zero-sugar products [15]. Import tariffs on Chinese corn oligosaccharides have further accelerated U.S. buyer migration toward North American and Southeast Asian tapioca-derived grades.
Key takeaway: In the USA, high-protein nutrition bar co-packing and non-GMO tapioca gummy binder demand are forecast to drive steady procurement of low-glucose IMO syrups.
UK Isomalto-oligosaccharide Market Outlook (2026 to 2036)
In the UK, market demand for isomalto-oligosaccharides is estimated to progress at a 6.3% CAGR through 2036 as grocery private-label suppliers and sports snack brands reformulate confectionery and cereal bars under HFSS promotional restrictions. British retailers allocate prime aisle end-caps to reduced-sugar protein bars and high-fiber snacks that pass nutrient-profiling thresholds. London agricultural attaché reporting in October 2026 noted that UK private-label lines captured a record 52.2% of grocery spending in early 2026 as shoppers sought health and free-from products [16]. Novel food and fiber labeling compliance across Great Britain remains a key qualification step for imported oligosaccharides.
Key takeaway: In the UK, retail HFSS promotional rules and private-label protein snack expansion are estimated to support steady adoption of enzymatic IMO binders.
Germany Isomalto-oligosaccharide Market Outlook (2026 to 2036)
German demand for isomalto-oligosaccharides is slated to expand at a 5.9% CAGR from 2026 to 2036 within contract sports-bar manufacturers, functional gummy co-packers, and clean-label bakery improver houses. Compared with North American markets that favor liquid tapioca syrups, German food processors procure high-purity spray-dried IMO powders for dry protein shake mixes and compressed dextrose-alternative tablets. Berlin agricultural attaché reporting in September 2026 highlighted strong German consumer demand for health-conscious snacking, organic options, and premium private-label nutrition products [17]. Strict European Union Novel Food authorization scope and EFSA health-claim rules govern how German brands market oligosaccharide ingredients.
Key takeaway: In Germany, contract sports-nutrition manufacturing and dry functional beverage blending are slated to sustain demand for spray-dried and liquid IMO grades.
Netherlands Isomalto-oligosaccharide Market Outlook (2026 to 2036)
The Netherlands is projected to record a 5.7% CAGR in isomalto-oligosaccharide consumption from 2026 to 2036, anchored by Rotterdam bulk ingredient import terminals and Dutch dairy and bar formulation centers. Dutch specialty ingredient distributors and starch processors blend imported corn and tapioca IMO into customized sweetening and binding premixes for Benelux food manufacturers. In February 2026, dsm-firmenich highlighted the inauguration of its Van Marken Food Innovation Center in Delft and its new Taste Hub in Wageningen to accelerate European sugar-reduction and texturizing co-development [18]. Active surveillance of nutrition claims by the Netherlands Food and Consumer Product Safety Authority requires precise back-of-pack carbohydrate disclosures.
Key takeaway: In the Netherlands, Benelux ingredient distribution hubs and dairy-and-snack co-development labs are projected to drive steady regional IMO throughput.
Spain Isomalto-oligosaccharide Market Outlook (2026 to 2036)
Spanish isomalto-oligosaccharide sales are expected to increase at a 5.4% CAGR over the 2026 to 2036 forecast window across Mediterranean bakery, turron confectionery, and sports nutrition contract plants. Spanish pastry and cereal bar producers use liquid IMO syrups to reduce added sucrose and retain soft moisture during warm summer distribution across Southern Europe. Madrid agricultural attaché filings in March 2026 confirmed that Spain ranks as the third-largest agricultural and food processing powerhouse in the European Union with rising demand for specialized food ingredients [19]. High electricity and freight costs across Iberian processing corridors remain an operational hurdle for mid-sized bakeries.
Key takeaway: In Spain, reduced-sugar confectionery and Mediterranean bakery reformulation are expected to support consistent adoption of humectant IMO syrups.
Japan Isomalto-oligosaccharide Market Outlook (2026 to 2036)
Japanese demand for isomalto-oligosaccharides is predicted to rise at a 4.8% CAGR between 2026 and 2036 across FOSHU digestive-health tabletop syrups, traditional wagashi confectionery, and senior clinical nutrition products. After pioneering commercial enzymatic starch transglucosylation in the 1980s, Japan represents a mature, technically sophisticated market where buyers specify narrow DP 3 to DP 5 panose profiles to prevent retrogradation in chilled rice and bakery snacks. Tokyo agricultural market filings in April 2026 documented that Japanese food processors continue prioritizing functional health and convenience ingredients across retail channels [20]. Demographic aging supports steady senior digestive-health demand while limiting overall volume acceleration.
Key takeaway: In Japan, established FOSHU digestive-health approval and anti-retrogradation bakery applications are predicted to maintain stable demand for high-purity IMO.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Isomalto-oligosaccharide Market?
BioNeutra North America Inc., Baolingbao Biology Co., Ltd., Shandong Bailong Chuangyuan Bio-Tech Co., Ltd., Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères S.A., Top Health Ingredients Inc., ADM, Novonesis, and dsm-firmenich AG are the notable companies in the isomalto-oligosaccharide market.
Competitive positioning in the global isomalto-oligosaccharide market separates dedicated enzymatic IMO refiners in North America and China from global starch-derivative majors and upstream enzymatic biosolutions providers. BioNeutra North America and Top Health Ingredients in Canada as well as Baolingbao Biology and Bailong Chuangyuan in China specialize in commercial IMO-900 syrups and spray-dried powders across corn, tapioca, and pulse feedstocks. Tate & Lyle and Ingredion compete with Roquette and ADM in broader starch hydrolysates and soluble fibers, while Novonesis and dsm-firmenich provide the industrial transglucosidase enzymes and taste-modulation systems required to produce and formulate low-sugar oligosaccharides.
- Dedicated Isomalto-oligosaccharide Refiners and Specialists: BioNeutra North America Inc. and Top Health Ingredients Inc. in Canada along with Baolingbao Biology Co., Ltd. and Shandong Bailong Chuangyuan in China produce high-purity corn, tapioca, and organic pulse IMO syrups and powders.
- Global Starch Hydrolysate and Soluble Fiber Majors: Tate & Lyle PLC; Ingredion Incorporated; Roquette Frères S.A.; and Archer Daniels Midland Company (ADM) operate multi-continent wet-milling and specialty carbohydrate refineries.
- Enzymatic Transglucosylation and Taste Biosolutions Providers: Novonesis and dsm-firmenich AG supply fungal alpha-transglucosidases, pullulanases, and sweetness modulators used in IMO synthesis and bar formulation.
Competitive Benchmarking: Isomalto-oligosaccharide Market
Table 8: Competitive Benchmarking for the Isomalto-oligosaccharide Market (qualitative capability ratings), 2026
| Company | Enzymatic Transglucosylation Capacity | Non-GMO and Organic Feedstock Breadth | Bar and Confectionery Application Support | Geographic Reach |
|---|---|---|---|---|
| BioNeutra North America Inc. | High | High | High | Canada and USA VitaFiber IMO corn, tapioca, and pea syrup and powder network |
| Baolingbao Biology Co., Ltd. | High | High | Medium | Shandong Yucheng biomanufacturing base; global export to 60+ countries |
| Shandong Bailong Chuangyuan | High | High | Medium | China Dezhou functional oligosaccharide and soluble fiber export refineries |
| Tate & Lyle PLC | Medium | High | High | Global soluble fiber, mouthfeel, and sugar-reduction application centers |
| Ingredion Incorporated | Medium | High | High | Global Idea Labs network and expanded North American Batory distribution |
| Roquette Frères S.A. | Medium | High | High | Global plant-based pea and corn starch derivatives and prebiotic fibers |
| Top Health Ingredients Inc. | Medium | High | High | Edmonton Canada organic tapioca and pulse prebiotic syrup and powder supply |
| ADM | Medium | High | High | Global corn and tapioca dietary fiber and sweetener formulation centers |
| Novonesis | High | Medium | High | Global industrial alpha-amylase and transglucosidase enzyme biosolutions |
| dsm-firmenich AG | Low | Medium | High | Global Taste, Texture and Health sugar-reduction and flavor-modulation labs |
Evaluation basis: Enzymatic Transglucosylation Capacity measures direct production of alpha-1,6-linked oligosaccharide syrups and powders or proprietary transglucosidase enzymes, while Non-GMO and Organic Feedstock Breadth rates availability of identity-preserved tapioca and organic corn IMO grades. Bar and Confectionery Application Support assesses pilot-scale slab-bar extrusion and gummy depositing laboratories.
Key Developments in the Isomalto-oligosaccharide Market
- Ingredion Incorporated presented its expanded clean-label texture and positive-nutrition sweetener and fiber solutions at IFT FIRST 2026 on July 6, 2026, supporting sugar-reduced snack bar and beverage formulation [21].
- Novonesis reported 7% full-year organic sales growth and a 37.1% adjusted EBITDA margin on February 25, 2026, driven by strong adoption of food and beverage starch-processing and baking biosolutions [22].
- Tate & Lyle PLC announced its six-month financial results and CP Kelco combination progress in November 2025, expanding its integrated mouthfeel and specialty fiber formulation capabilities [23].
Key Players in the Isomalto-oligosaccharide Market
Dedicated Isomalto-oligosaccharide Refiners and Specialists
- BioNeutra North America Inc.
- Baolingbao Biology Co., Ltd.
- Shandong Bailong Chuangyuan Bio-Tech Co., Ltd.
- Top Health Ingredients Inc.
Global Starch Hydrolysate and Soluble Fiber Majors
- Tate & Lyle PLC
- Ingredion Incorporated
- Roquette Frères S.A.
- Archer Daniels Midland Company (ADM)
Enzymatic Transglucosylation and Taste Biosolutions Providers
- Novonesis
- dsm-firmenich AG
Isomalto-oligosaccharide Market - Report Scope
Table 9: Report Scope for the Isomalto-oligosaccharide Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Physical State; Raw Feedstock; Commercial Application; Certification and Grade; Sales Channel |
| Quantitative Units | USD Million |
| Market Definition | Includes processor revenue from food-, beverage-, and nutraceutical-grade isomalto-oligosaccharides (alpha-1,6-linked glucose oligomers including isomaltose, panose, isomaltotriose, and higher DP 4-10 fractions across IMO-500 and IMO-900 grades) produced via enzymatic transglucosylation of corn, tapioca, pea, and rice starches. Category Scope Note: Excludes hydrogenated sugar alcohol isomalt (E953), standard high-fructose corn syrup, and unmodified native starches. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | China, Canada, USA, UK, Germany, Netherlands, Spain, Japan, and additional countries in the full report |
| Key Companies Covered | BioNeutra North America Inc., Baolingbao Biology Co., Ltd., Shandong Bailong Chuangyuan Bio-Tech Co., Ltd., Tate & Lyle PLC, Ingredion Incorporated, Roquette Frères S.A., Top Health Ingredients Inc., ADM, Novonesis, dsm-firmenich AG |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up starch conversion volume and ASP triangulation. |
Isomalto-oligosaccharide Market - Research Methodology
Table 10: Research Methodology for the Isomalto-oligosaccharide Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with enzymatic starch bioprocess directors in Shandong and Alberta, protein bar and gummy co-packer R&D leads, and industrial enzyme application scientists. |
| Secondary Research | Analysis of Health Canada novel fiber dossiers, USDA FAS Food Processing Ingredients and Grain Annual filings, MDPI Foods and Nutrients oligosaccharide studies, and corporate financial reports. |
| Market Sizing and Forecasting | Bottom-up reconciliation of global IMO syrup and spray-dried powder shipments (375,000 to 410,000 MT in 2026) and grade-weighted wholesale realizations per metric ton across corn, tapioca, and pulse feedstocks from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weighting protein bar and gummy supplement co-packing output, national dietary-fiber label eligibility, and front-of-pack sugar warning mandates across eight countries. |
| Operational Benchmark Traceability | Starch conversion, sucrose replacement ranges, and supplement format shares in Tables 2, 3, and 4 trace to MDPI Foods June 2026 reviews, Kerry 2026 Taste Charts, and Tate & Lyle purpose disclosures. |
| Data Triangulation and Validation | Revenue estimates isolate enzymatically transglucosylated alpha-1,6-oligosaccharides while strictly excluding hydrogenated isomalt polyols, maltodextrins, and parent functional snack revenues. |
Isomalto-oligosaccharide Market by Segments
Isomalto-oligosaccharide Market segmented by Physical State:
- Concentrated Liquid IMO Syrup 75 to 80 Brix
- Spray-Dried IMO Soluble Fine Powder
- Agglomerated Instant Granules
- Blended Prebiotic Premixes
Isomalto-oligosaccharide Market segmented by Raw Feedstock:
- Enzymatic Conversion of Corn Starch
- Tapioca Starch Hydrolysates
- Organic Pea and Pulse Starch
- Rice and Cereal Starches
Isomalto-oligosaccharide Market segmented by Commercial Application:
- Protein Nutrition Bars and Sports Snacks
- Low-Sugar Functional Beverages
- Dietary Fiber Supplements and Gummies
- Confectionery and Reduced-Calorie Fillings
- High-Fiber Bakery and Extruded Cereals
Isomalto-oligosaccharide Market segmented by Certification and Grade:
- Conventional Food Grade
- Certified Organic IMO
- Identity-Preserved Non-GMO
- Clean-Label Low-Digestible Grade
Isomalto-oligosaccharide Market segmented by Sales Channel:
- Direct to Nutritional Bar and Food Manufacturers
- Specialty Ingredient Distributors
- Contract Nutraceutical Co-Packers
- B2B Digital Ingredient Platforms
Isomalto-oligosaccharide Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Smaoui, S.. (2026, June 14). Advances in Enzymatic Production of Prebiotic Oligosaccharides from Agro-Industrial Waste: A Critical Review and Industrial Framework. Foods, 15(12), 2156 (MDPI).
- [2] Roquette Frères S.A.. (2025, October 30). AMYSTA L 123 Thermally Soluble Pea Starch Marks the Start of Roquette's Next-Generation Label-Friendly Starch Range. Roquette Press Releases.
- [3] Tate & Lyle PLC. (2026, August 26). Tate & Lyle adds new purpose target to improve everyday consumer health through fibre fortification. Tate & Lyle Corporate Newsroom.
- [4] Novonesis. (2026, August 19). H1 2026: Novonesis delivered strong 8% organic sales growth and increases full-year outlook. Novonesis Corporate News.
- [5] Yoshida, K., Matsubara, T., Morita, S., Sakata, Y., Sonoki, H., & Miyaji, K.. (2026, September 2). Combined effects of resistant dextrin and inulin on the reduction of harmful metabolites during in vitro fecal fermentation in older adults. Frontiers in Nutrition, 13, 1909212.
- [6] USDA Foreign Agricultural Service. (2026, April 20). European Union: Grain and Feed Annual Food, Seed and Industrial Starch Use. U.S. Department of Agriculture GAIN Report E42026-0034.
- [7] Kerry Group plc. (2026, January 22). Balancing Flavour With Function: Kerry's 2026 Supplements Taste Charts Reveal the Winning Formula. Kerry Group plc Media Releases.
- [8] Roquette Frères S.A.. (2026, February 3). NUTRIOSE Soluble Fibers: NutraStrong Prebiotic Verified Certification. Roquette Press Releases.
- [9] Ingredion Incorporated. (2026, March 12). Ingredion and Batory Foods Sign New Ingredient Distribution Partnership Across North America. Ingredion Newsroom.
- [10] Fan, X., Wang, X., Chao, Y., & Xu, E.. (2026, January 18). Probiotic and prebiotic mechanisms in IBD-associated colorectal carcinogenesis: recent advances. Frontiers in Nutrition, 12, 1693875.
- [11] Ghyselinck, J., Verstrepen, L., Duysburgh, C., Wiche, R., Kuhn, K. S., Müller, M., Faerber-Frottier, V., & Marzorati, M.. (2026, February 17). Fiber mixtures containing chicory inulin, wheat dextrin, and cellulose, or tapioca dextrin alone, beneficially modulate microbial metabolic activity and composition in short-term colonic simulations. Frontiers in Nutrition, 13, 1749272.
- [12] Archer Daniels Midland Company. (2026, July 28). ADM and Matsutani Mark 20 Years of Partnership and Tapioca Dietary Fiber Innovation. ADM Corporate News Releases.
- [13] USDA Foreign Agricultural Service. (2026, April 1). China: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report CH2026-0042.
- [14] USDA Foreign Agricultural Service. (2026, August 27). Canada: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report CA2026-0022.
- [15] Cargill, Incorporated. (2026, October 28). Craftiva Reduced-Sugar Syrups and Sweeteners. Cargill Corporate Newsroom.
- [16] USDA Foreign Agricultural Service. (2026, October 1). United Kingdom: Retail Foods Annual. U.S. Department of Agriculture GAIN Report UK2026-0029.
- [17] USDA Foreign Agricultural Service. (2026, September 25). Germany: Retail Foods Annual. U.S. Department of Agriculture GAIN Report GM2026-0018.
- [18] dsm-firmenich AG. (2026, February 19). The Year in Review: dsm-firmenich Integrated Annual Report 2025. dsm-firmenich Corporate Publications.
- [19] USDA Foreign Agricultural Service. (2026, March 31). Spain: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report SP2026-0009.
- [20] USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report JA2026-0012.
- [21] Ingredion Incorporated. (2026, July 6). Ingredion Spotlights Next-Generation Solutions for Texture, Clean Labels and Positive Nutrition at IFT FIRST 2026. Ingredion Newsroom.
- [22] Novonesis. (2026, February 25). Novonesis Delivered Strong Organic Sales Growth of 7% in 2025 Across Food and Health Biosolutions. Novonesis Financial Releases.
- [23] Tate & Lyle PLC. (2025, November 6). Tate & Lyle PLC Results for the Six Months Ended 30 September 2025 and CP Kelco Integration. Tate & Lyle Investor Relations.
- [24] dsm-firmenich AG. (2026, February 19). Taste, Texture and Health: dsm-firmenich Integrated Annual Report 2025. dsm-firmenich Corporate Publications.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the isomalto-oligosaccharide market in 2026 and what is forecast for 2036?
- Which protein-bar binding and sugar-reduction pressures support demand for isomalto-oligosaccharides?
- Why does Concentrated Liquid IMO Syrup 75 to 80 Brix lead the physical state category?
- Why does Enzymatic Conversion of Corn Starch lead the raw feedstock category?
- How do national growth rates compare across China and Canada versus the USA and the UK?
- Which leading companies supply dedicated IMO-900 syrups versus broader soluble fibers and enzymes?
- How does brush-border isomaltose digestibility affect dietary-fiber labeling across jurisdictions?
- What should snack and gummy formulators evaluate when choosing corn versus tapioca IMO feedstocks?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Physical State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Physical State, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Physical State, 2026 to 2036
- Concentrated Liquid IMO Syrup 75 to 80 Brix
- Spray-Dried IMO Soluble Fine Powder
- Agglomerated Instant Granules
- Blended Prebiotic Premixes
- Y-o-Y Growth Trend Analysis By Physical State, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical State, 2026 to 2036
- Global Market Analysis and Forecast, By Raw Feedstock, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Raw Feedstock, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Raw Feedstock, 2026 to 2036
- Enzymatic Conversion of Corn Starch
- Tapioca Starch Hydrolysates
- Organic Pea and Pulse Starch
- Rice and Cereal Starches
- Y-o-Y Growth Trend Analysis By Raw Feedstock, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Feedstock, 2026 to 2036
- Global Market Analysis and Forecast, By Commercial Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Commercial Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Commercial Application, 2026 to 2036
- Protein Nutrition Bars and Sports Snacks
- Low-Sugar Functional Beverages
- Dietary Fiber Supplements and Gummies
- Confectionery and Reduced-Calorie Fillings
- High-Fiber Bakery and Extruded Cereals
- Y-o-Y Growth Trend Analysis By Commercial Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Commercial Application, 2026 to 2036
- Global Market Analysis and Forecast, By Certification and Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Certification and Grade, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Certification and Grade, 2026 to 2036
- Conventional Food Grade
- Certified Organic IMO
- Identity-Preserved Non-GMO
- Clean-Label Low-Digestible Grade
- Y-o-Y Growth Trend Analysis By Certification and Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Certification and Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to Nutritional Bar and Food Manufacturers
- Specialty Ingredient Distributors
- Contract Nutraceutical Co-Packers
- B2B Digital Ingredient Platforms
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Physical State
- By Raw Feedstock
- By Commercial Application
- By Certification and Grade
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BioNeutra North America Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Baolingbao Biology Co., Ltd.
- Shandong Bailong Chuangyuan
- Tate & Lyle PLC
- Ingredion Incorporated
- Roquette Frères S.A.
- Top Health Ingredients Inc.
- ADM
- Novonesis
- dsm-firmenich AG
- Shandong Bailong Chuangyuan Bio-Tech Co., Ltd.
- Archer Daniels Midland Company (ADM)
- BioNeutra North America Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 6: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 16: Latin America Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 21: Western Europe Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 22: Western Europe Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 24: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 36: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Million) Forecast by Physical State, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Million) Forecast by Raw Feedstock, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Million) Forecast by Commercial Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Million) Forecast by Certification and Grade, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Physical State
- Figure 6: Global Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Raw Feedstock
- Figure 9: Global Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Commercial Application
- Figure 12: Global Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Certification and Grade
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Physical State
- Figure 32: North America Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Raw Feedstock
- Figure 35: North America Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Commercial Application
- Figure 38: North America Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Certification and Grade
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Physical State
- Figure 48: Latin America Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Raw Feedstock
- Figure 51: Latin America Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Commercial Application
- Figure 54: Latin America Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Certification and Grade
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Physical State
- Figure 64: Western Europe Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Raw Feedstock
- Figure 67: Western Europe Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Commercial Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Certification and Grade
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Physical State
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Raw Feedstock
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Commercial Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Certification and Grade
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Physical State
- Figure 96: East Asia Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Raw Feedstock
- Figure 99: East Asia Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Commercial Application
- Figure 102: East Asia Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Certification and Grade
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Physical State
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Raw Feedstock
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Commercial Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Certification and Grade
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Physical State, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Physical State, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Physical State
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Raw Feedstock, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Raw Feedstock, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Raw Feedstock
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Commercial Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Commercial Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Commercial Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Certification and Grade, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Certification and Grade, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Certification and Grade
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Isomalto-oligosaccharide Market in 2026, and what is forecast for 2036?
Global isomalto-oligosaccharide industry revenue stood at USD 746.5 million during 2025 and is forecast to reach USD 792.6 million in 2026. Total market valuation is on course to hit USD 1,487.8 million by 2036 as nutrition bar and supplement manufacturers replace glucose syrups with prebiotic oligosaccharide binders.
What is the CAGR for the Isomalto-oligosaccharide Market from 2026 to 2036?
The global isomalto-oligosaccharide sector is projected to expand at a 6.5% CAGR over the 2026 to 2036 forecast window, generating USD 695.2 million in incremental revenue across food and nutrition lines.
Which physical state segment leads the Isomalto-oligosaccharide Market?
Concentrated Liquid IMO Syrup (75 to 80 Brix) captures an estimated 58.4% share of the physical state segment in 2026 given that heated liquid syrups pump directly into cold-extruded protein bar and gummy lines without spray-drying costs.
Which raw feedstock segment leads the Isomalto-oligosaccharide Market?
Enzymatic Conversion of Corn Starch represents an estimated 64.5% of the raw feedstock category in 2026 given that integrated corn wet-milling complexes provide low-cost starch slurry directly to transglucosylation reactors.
Which country has a notable growth outlook during the assessment period?
China leads national expansion projections at a 7.6% CAGR through 2036, driven by large-scale Shandong enzymatic starch biomanufacturing and domestic functional dairy and beverage fortification.
Who are the key players in the market?
BioNeutra North America Inc.; Top Health Ingredients Inc.; Baolingbao Biology Co., Ltd.; Shandong Bailong Chuangyuan Bio-Tech Co., Ltd.; Tate & Lyle PLC; Ingredion Incorporated; Roquette Frères S.A.; ADM; Novonesis; and dsm-firmenich AG lead global supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
