

- Market Size (2026)
- USD 750.0 Bn
- Forecast (2036)
- USD 1448.0 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Lipase Market in 2026?
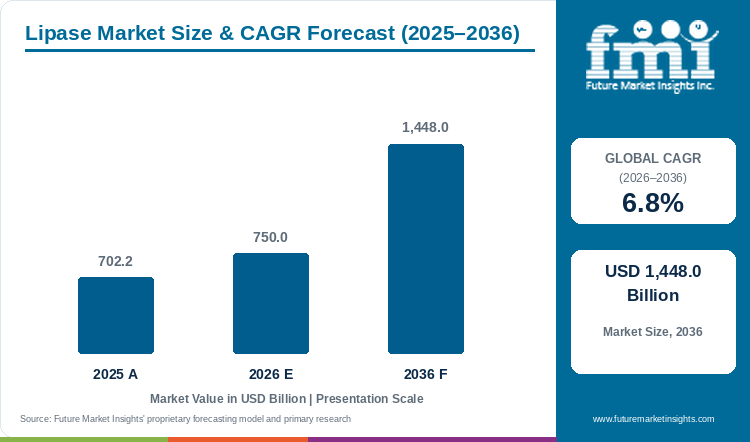
Sales in the lipase market are projected to grow at 6.8% CAGR, with the market size rising from USD 702.2 billion in 2025 to USD 750.0 billion in 2026 and reaching USD 1,448.0 billion by 2036.
Increasing need for the elimination of harsh chemical catalysts in fat modification, along with the reduction of high-temperature steam expenses in oleochemical refineries, has accelerated commercial adoption of microbial triacylglycerol hydrolases. According to Future Market Insights analysis, the global lipase market stands at USD 702.2 billion in 2025 and rises to USD 750.0 billion in 2026. Industry valuation is projected to reach USD 1,448.0 billion by 2036, expanding at a 6.8% CAGR from 2026 to 2036 and generating USD 698.0 billion in added revenue. Food processors and biodiesel plants are switching from sodium methoxide and synthetic emulsifiers to biocatalytic esterification so they can restructure fats without generating trans-fatty isomers or alkaline wastewater streams. In January 2025, United States Department of Agriculture bioprocessing assessments confirmed that commercial enzyme utilization rose 16.0% across domestic grain and oilseed biorefineries [1]. Standard commercial grade holds the leading product position with a 37.5% share in 2026 because it delivers dependable fat hydrolysis across bulk dough conditioning and detergent lines. Evaluated country growth spans 5.4% CAGR in South Korea to 8.3% in the USA, although high submerged bioreactor capital costs still slow capacity expansion among smaller regional formulators.
Key Market Trends & Insights
- By product type / grade: Standard commercial grade led with a 37.5% share in 2026, driven by broad substrate tolerance across commercial bread making and bulk detergent compounding.
- By processing state: Fresh / ambient packaged accounted for 43.9% of demand in 2026, owing to glycerol-stabilized liquid concentrates and wax-coated granules that survive ambient warehouse storage.
- By end-use application: Direct retail consumer consumption held 48.5% of revenue in 2026, reflecting household purchases of low-temperature enzymatic laundry detergents and digestive capsules.
- By sales channel: With a 52.4% share in 2026, B2B direct industrial food manufacturers led the category, supported by plant-level dosage trials and multi-year bulk tanker supply contracts.
Regional Highlights
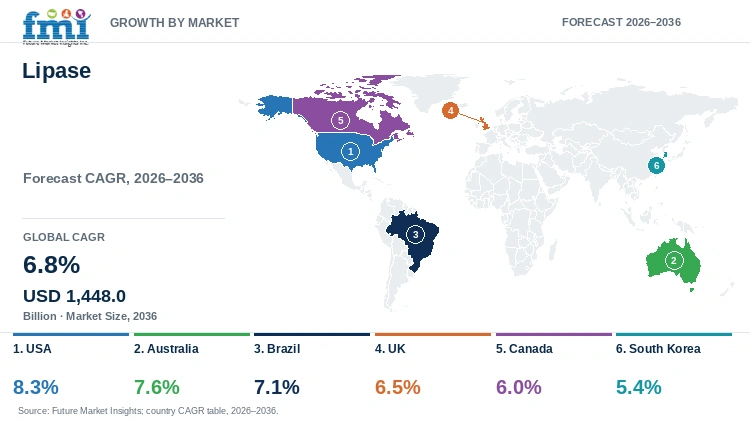
- Fastest-growing evaluated country: USA, at 8.3% CAGR from 2026 to 2036.
- By country: Australia at 7.6%, Brazil at 7.1%, and the UK at 6.5% follow, while South Korea records the lowest evaluated CAGR at 5.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Lipase Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 702.2 billion |
| Estimated Market Size in 2026 | USD 750.0 billion |
| Projected Market Size by 2036 | USD 1,448.0 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 698.0 billion |
Commercial conditions differ across the profiled countries owing to variations in fermentation infrastructure and regulatory approval timelines for genetically modified expression hosts. Future Market Insights research indicates that industrial bioprocessors are under pressure to extend enzyme operating life across continuous reactor runs while meeting strict food-safety purity rules. In March 2025, the U.S. Food and Drug Administration issued its agency response for GRAS Notice 1196 covering triacylglycerol lipase produced by recombinant Trichoderma reesei for commercial food processing [2]. Owing to these purity thresholds, suppliers of industrial enzyme formulations are binding fungal lipases onto macroporous silica and acrylic polymer carriers, which allows oleochemical plants to reuse the biocatalyst across multiple batch cycles without protein leaching into finished oils.
Microbial Fermentation and Biocatalyst Throughput Sizing
Table 2: Microbial Fermentation and Biocatalyst Throughput Sizing for the Lipase Market (USD billion, million liters, percentage, and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 702.2 | 750.0 | 1,448.0 |
| Submerged fermentation broth volume produced (million liters) | 4,200.0 to 4,550.0 | 4,480.0 to 4,850.0 | 8,850.0 to 9,600.0 |
| Immobilized resin-bound biocatalyst share (percent) | 24.5 to 26.5 | 25.5 to 27.5 | 38.0 to 41.5 |
| Wholesale realization per thousand enzyme units equivalent (USD) | 16.5 to 18.0 | 16.8 to 18.3 | 18.0 to 19.5 |
Operating note: Throughput ranges reflect commercial submerged fungal and bacterial fermentation capacities, membrane ultrafiltration recoveries, and immobilized carrier utilization across industrial enzyme plants.
Per Capita Industrial Biocatalysis Spending Indicators
Commercial bakeries and edible oil refineries are purchasing larger volumes of recombinant fungal lipase to eliminate chemical interesterification and synthetic dough conditioners. In high-speed bread lines, plant formulators combine triacylglycerol hydrolases with phospholipase enzyme preparations and specialized baking enzymes so that endogenous wheat lipids convert directly into polar emulsifying fractions during mixing. This in-situ lipid modification strengthens gluten gas retention and delays crumb staling without listing chemical mono- and diglycerides on the package label.
Table 3: Per Capita and Industrial Spending Indicators for the Lipase Market (billion and USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 85.3 | 90.4 | 161.8 |
| Spend per 1,000 people (USD) | 85,322.0 | 90,361.4 | 161,787.7 |
| Commercial biorefinery annual biocatalyst spend (USD thousand) | 520.0 to 580.0 | 560.0 to 625.0 | 1,150.0 to 1,280.0 |
Table 4: Facility & Industrial Channel Sizing Indicators for the Lipase Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 750.0 billion | 2026 market estimate |
| Licensed industrial fermentation and oleochemical plants worldwide | 142.0 thousand | 2024 industrial bioprocess registry |
| Average annual lipase enzyme spend per manufacturing facility | USD 5.3 million | Facility revenue average |
| Direct retail consumer consumption revenue, 2026 | USD 363.8 billion | 48.5% category share |
Analyst Perspective
"Immobilized fungal lipases allow edible oil refiners and biofuel plants to restructure triglycerides at moderate temperatures without alkaline catalyst waste. High carrier resin costs and organic solvent deactivation still require pilot reactor validation before processors commit to multi-year supply contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the lipase market segmented?
The lipase market is segmented by product type / grade, processing state, end-use application, sales channel, and region. In 2026, Standard Commercial Grade is projected at 37.5%, fresh / ambient packaged leads at 43.9%, direct retail consumer consumption holds 48.5%, and B2B direct industrial food manufacturers captures 52.4%.
By product type / grade: Standard commercial grade, organic and clean-label variant, and premium specialty formulation.
By processing state: Fresh / ambient packaged, frozen and chilled, and dehydrated and dry packaged.
By end-use application: Direct retail consumer consumption, food service and hospitality, and commercial food manufacturing plants.
By sales channel: B2B direct industrial food manufacturers, retail packaged health stores, and online DTC brands.
Why does Standard Commercial Grade lead the product type / grade category?
Standard commercial grade is projected to hold 37.5% of product type / grade revenue in 2026, supported by broad industrial fat hydrolysis.
Table 5: Product Type / Grade Share for the Lipase Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 37.5% |
| Other Segments Combined | 62.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Grade Leadership and Market Growth for the Lipase Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Standard Commercial Grade |
Industrial food processors and detergent compounders rely on standard commercial grade lipase because bulk liquid and granulated preparations cleave ester bonds across diverse fat substrates without requiring pharmaceutical-grade chromatography. Fungal strains such as Aspergillus oryzae and Thermomyces lanuginosus deliver steady catalytic activity across moderate pH and wash temperatures, which keeps per-batch dosing costs low compared with purified therapeutic grades. In addition to this, livestock integrators blend standard lipases with feed enzymes to improve dietary fat digestibility in young poultry and swine rations before specialized coated variants are considered.
- Standard commercial grade is projected to account for 37.5% of product type / grade revenue in 2026, supported by food-grade clearances and high-tonnage detergent blending.
- In March 2025, the Association of Manufacturers and Formulators of Enzyme Products reported that standard unpurified industrial biocatalysts accounted for 65.0% of commercial enzyme tonnage across European compounding plants [3].
What makes Fresh / Ambient Packaged central to the processing state category?
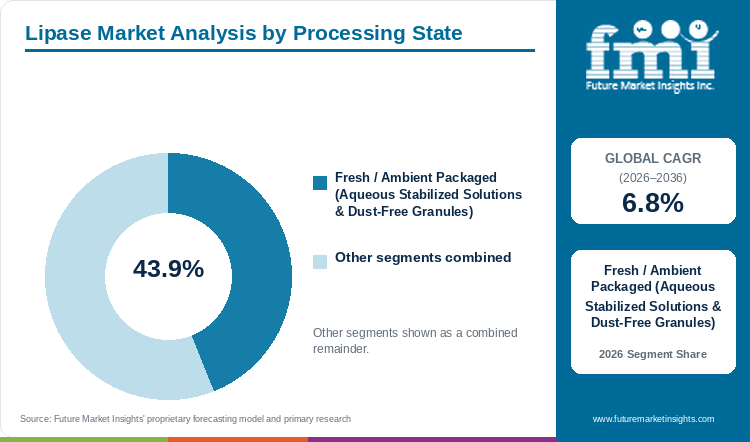
Fresh / ambient packaged is estimated to represent 43.9% of the processing state category in 2026, reflecting room-temperature stability without cold storage.
Commercial enzyme buyers prefer fresh / ambient packaged formats because refrigerated transport and cold-room storage add substantial logistics overhead to bulk plant operations. Enzyme formulators stabilize aqueous liquid concentrates with sorbitol and glycerol buffers that protect the protein fold against thermal denaturation at ambient warehouse temperatures. Besides this, coating solid enzyme cores in low-dust polymer layers prevents airborne allergen exposure on factory floors, which is driving wider use alongside dairy enzymes in automated cheese ripening and butterfat lipolysis lines.
- Fresh / ambient packaged is estimated to hold 43.9% of processing state demand in 2026, reflecting lower warehouse energy costs and dust-free operator handling.
- In April 2025, Industrial Biotechnology Progress documented 95.0% catalytic activity retention across 18 months in polyol-stabilized ambient liquid lipase preparations [4].
What keeps Direct Retail Consumer Consumption ahead by end-use application?
Direct retail consumer consumption is expected to capture 48.5% of end-use application demand in 2026, driven by bio-detergents and digestive capsules.
Household buyers generate the largest end-use turnover because enzymatic laundry liquids and dishwashing pods require continuous weekly replenishment across supermarket aisles. Cold-active lipases break down stubborn triglyceride food stains at 20 to 30 degrees Celsius, allowing households to cut washing machine electricity use compared with hot-water surfactant cycles. Furthermore, retail pharmacies and nutrition chains are expanding shelf space for over-the-counter digestive enzyme supplements that pair acid-stable fungal lipase with protease and amylase to ease post-meal lipid malabsorption.
- Direct retail consumer consumption is expected to command 48.5% of end-use application revenue in 2026, driven by repeat grocery purchases of stain-removal detergents and digestive capsules.
- In November 2025, the one-hundredth report of the Joint FAO/WHO Expert Committee on Food Additives updated safety specifications and dietary exposure assessments for microbial enzyme preparations used in consumer nutrition [5].
What gives B2B Direct Industrial Food Manufacturers the leading position in sales channel?
B2B direct industrial food manufacturers is anticipated to contribute 52.4% of sales channel revenue in 2026, owing to bulk supply agreements.
Large bakery groups, dairy processors, and oleochemical refiners buy directly from primary fermentation manufacturers because enzyme dosing must be calibrated to exact line residence times and substrate fat profiles. Supplier application engineers run pilot trials inside the customer plant to match lipase specificity for cheese flavor development or cocoa butter equivalent synthesis, which third-party wholesale distributors cannot execute independently. In addition to this, industrial beverage and grain processors coordinate direct bulk procurement alongside brewing enzymes to secure guaranteed batch-to-batch activity certificates.
- B2B direct industrial food manufacturers is anticipated to capture 52.4% of sales channel revenue in 2026, owing to multi-year tanker contracts and on-site formulation support.
- In December 2025, the European Food Safety Authority updated its scientific guidance on microbial strain characterization and dossier verification for commercial food enzyme authorizations [6].
What are the drivers, restraints, and opportunities in the lipase market?
In the lipase market, clean-label emulsifier replacement and low-temperature biodiesel transesterification support demand, submerged bioreactor capital and solvent deactivation constrain qualification, and immobilized continuous-flow resins expand industrial reuse through 2036.
- Driver: Industrial bakeries and oleochemical refiners will continue to replace synthetic emulsifiers and alkaline catalysts with microbial lipases to lower energy use and wastewater treatment costs through 2036.
- Restraint: High capital expenditure for sterile submerged fermentation vessels and enzyme deactivation under organic solvents will continue to extend pilot qualification cycles through 2036.
- Opportunity: Engineering macroporous immobilized lipase resins for continuous packed-bed reactors is expected to unlock multi-cycle catalyst reuse across sustainable aviation fuel and specialty lipid lines through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Increasing pressure on packaged food brands to remove chemically synthesized mono- and diglycerides, coupled with rising natural gas tariffs in edible oil refining, is pulling biocatalytic lipid modification into mainstream production lines. Rather than heating vegetable oils above 200 degrees Celsius with chemical catalysts, refiners use sn-1,3-specific lipases to restructure fats at 60 degrees Celsius while preserving natural tocopherols. A July 2025 life-cycle study in the Journal of Cleaner Production found that replacing chemical interesterification with enzymatic fat restructuring reduced process energy consumption by 34.0% and eliminated alkaline wash water [7]. As per FMI, processors adopting food enzymes require suppliers to prove consistent loaf volume and emulsion stability across commercial flour lots before signing annual supply agreements.
Risk Assessment of the Lipase Market: Operational and Formulation Friction
High fermentation and downstream purification costs remain a major restraining factor when commodity oil processors compare enzymes against low-cost chemical catalysts. Free soluble lipases lose catalytic activity rapidly when exposed to short-chain alcohols such as methanol or high shear forces inside industrial mixing tanks, which forces plants to replenish single-use liquid enzyme doses after every batch. In January 2026, the Enzyme Technical Association published updated occupational hygiene and respiratory allergen containment protocols for industrial enzyme handling facilities [8]. Installing closed membrane filtration lines, automated dust-free dosing skids, and recombinant host DNA removal steps raises capital requirements, which delays adoption among price-sensitive detergent and digestive enzyme contract blenders.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Immobilizing thermostable microbial lipases onto hydrophobic acrylic and silica beads is creating lucrative revenue opportunities across continuous-flow oleochemical and biofuel reactors. When enzymes are covalently bound to porous resin supports, biodiesel and specialty lipid producers can run packed-bed columns for hundreds of reaction cycles without washing residual protein out of the finished ester stream. An October 2025 study in Biotechnology and Bioengineering demonstrated that macroporous resin-immobilized Candida antarctica lipase B retained 88.0% conversion efficiency after 120 continuous esterification cycles in solvent-free waste oil reactors [9]. Suppliers expanding biocatalysis and biocatalyst platforms must match bead particle strength to column back-pressure limits before refineries convert full-scale lines.
Lipase Market by Country (2026 to 2036)
As per Future Market Insights, the USA represents the fastest-growing lipase market among the six evaluated countries at an 8.3% CAGR from 2026 to 2036, whereas South Korea records the most moderate expansion at 5.4% CAGR. Across these national markets, growth trajectories depend on local oilseed crushing capacity, biofuel blending mandates, clean-label bakery reformulation, and regulatory clearance speed for genetically engineered microbial production strains.
Table 7: Country CAGR and Primary Growth Levers for the Lipase Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 8.3% | Renewable diesel and SAF waste-oil transesterification alongside clean-label commercial bread reformulation |
| Australia | 7.6% | Export cheddar flavor acceleration, canola enzymatic degumming, and monogastric feed enzyme dosing |
| Brazil | 7.1% | Soybean oil enzymatic degumming and tallow-based biodiesel esterification across Midwest biorefineries |
| UK | 6.5% | Cold-water supermarket laundry detergent formulations and DATEM replacement in industrial pan bread |
| Canada | 6.0% | Prairie canola crushing degumming upgrades and federal clean-fuel high-FFA feedstock processing |
| South Korea | 5.4% | Enantioselective pharmaceutical intermediate synthesis and enzymatic botanical emollient esterification |
Source: Future Market Insights analysis
USA Lipase Market Outlook (2026 to 2036)
In the United States, demand for lipase is projected to expand at an 8.3% CAGR from 2026 to 2036, propelled by renewable fuel refiners processing high-free-fatty-acid used cooking oil and distillers corn oil. Conventional alkaline catalysts saponify when feedstock free fatty acids exceed 1.0%, whereas enzymatic transesterification converts both free fatty acids and triglycerides into methyl esters without soap formation. In October 2026, the U.S. Department of Energy Alternative Fuels and Feedstocks Office highlighted biocatalytic upgrading of waste lipid feedstocks as a priority pathway for scaling domestic sustainable aviation fuel production [10]. High upfront cost for immobilized enzyme beds still challenges smaller Midwest biodiesel plants, so enzyme suppliers are offering performance-linked catalyst leasing contracts tied to gallon output.
Key takeaway: In the USA, low-carbon fuel credits for waste-oil processing and clean-label bakery reformulation anchor the fastest country growth rate through 2036.
Australia Lipase Market Outlook (2026 to 2036)
Australian cheese exporters and livestock feed mills are driving a projected 7.6% CAGR through 2036 as processors seek faster inventory turnover and improved feed conversion ratios. Commercial dairy plants across Victoria use fungal lipases to generate targeted butyric and caproic fatty acid profiles in aged cheddar and enzyme-modified cheese pastes, cutting refrigerated maturation warehouse time by several months. In May 2025, the Australian Department of Agriculture, Fisheries and Forestry reported that national dairy and oilseed processing plants increased biological processing aid imports by 11.4% to lower energy intensity [11]. Long refrigerated shipping distances to Asian export ports require strict enzyme heat-inactivation control so residual lipolysis does not cause rancid off-flavors during ocean transit.
Key takeaway: In Australia, accelerated export cheese ripening and monogastric feed fat optimization support steady industrial enzyme procurement.
Brazil Lipase Market Outlook (2026 to 2036)
Large-scale soybean crushing complexes and beef tallow biodiesel refineries across Mato Grosso and Sao Paulo position Brazil to grow at a 7.1% CAGR between 2026 and 2036. Brazilian vegetable oil refiners are replacing phosphoric acid chemical degumming with phospholipase and triacylglycerol lipase treatments that reduce neutral oil entrapment in gum sludge and increase refined soybean oil yield by 1.2%. In August 2025, the Brazilian National Agency of Petroleum, Natural Gas and Biofuels recorded a 14.5% rise in enzymatic and low-acid tallow esterification throughput under national biodiesel blending mandates [12]. Currency fluctuations against imported European enzyme concentrates still pressure local processor margins, encouraging multinational producers to expand liquid blending terminals in Parana.
Key takeaway: In Brazil, high-volume soybean oil degumming and mandatory biodiesel blending create durable bulk demand for industrial lipases.
UK Lipase Market Outlook (2026 to 2036)
Retail supermarket competition in cold-water laundry detergents and high-speed plant bakery reformulation supports a 6.5% CAGR in the United Kingdom through 2036. British grocery chains require private-label liquid and pod detergents to remove bacon grease and butter stains in 20-degree-Celsius eco-wash cycles, which requires engineered cold-active lipases that remain functional in surfactant-rich wash liquor. In June 2025, the UK Department for Environment, Food and Rural Affairs noted that household chemical formulators reduced thermal wash energy footprints by 18.0% through multi-enzyme detergent adoption [13]. Strict UK post-Brexit novel food and processing aid dossier reviews still lengthen qualification timelines for newly engineered microbial strains entering commercial bread improver lines.
Key takeaway: In the UK, energy-saving cold-wash detergent formulations and clean-label plant bread production sustain consistent enzyme replacement demand.
Canada Lipase Market Outlook (2026 to 2036)
Expansion of canola crushing capacity across Saskatchewan and Alberta underpins a projected 6.0% CAGR in the Canadian lipase market from 2026 to 2036. Canola oil terminals deploy enzymatic degumming and interesterification to supply low-phosphorus lipid feedstocks for both food-grade shortening and hydrotreated renewable diesel refineries. In September 2025, Agriculture and Agri-Food Canada reported that domestic oilseed crushing facilities processed 11.3 million metric tons of canola, with new biorefinery lines adopting enzymatic pre-treatment to cut chemical effluent [14]. Harsh winter transport temperatures across the Canadian prairies can freeze uninsulated liquid enzyme totes, requiring suppliers to formulate freeze-thaw-stable glycerol concentrates or dust-free granulates.
Key takeaway: In Canada, expanding prairie canola crushing terminals and federal clean-fuel regulations drive long-term industrial biocatalyst contracts.
South Korea Lipase Market Outlook (2026 to 2036)
High-value pharmaceutical synthesis and cosmetic emollient manufacturing shape the South Korean market, which is forecast to progress at a 5.4% CAGR through 2036. Fine chemical laboratories in Incheon and Daejeon use stereoselective immobilized lipases to resolve chiral drug intermediates and synthesize skin-compatible wax esters such as cetyl ricinoleate without heavy-metal catalysts. In November 2025, the Korea Biotechnology Industry Organization reported a 12.8% increase in biocatalytic specialty chemical production across domestic cosmetic and pharmaceutical plants [15]. Because South Korea lacks large domestic oilseed crushing or bulk grain biorefineries, volume growth remains concentrated in lower-tonnage, higher-margin specialty enzyme grades rather than bulk commodity drums.
Key takeaway: In South Korea, chiral pharmaceutical synthesis and clean cosmetic ester production drive demand for high-purity immobilized lipases.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the lipase market?
Novozymes A/S (Novonesis), International Flavors & Fragrances (IFF), DSM-Firmenich, BASF SE, Associated British Foods plc (AB Enzymes), Amano Enzyme Inc., Kerry Group plc, and Chr. Hansen (Novonesis) are the notable companies in this market.
Future Market Insights competitive analysis indicates that supplier competition separates into integrated global fermentation leaders and specialized application formulators. Primary fermentation manufacturers operate multi-thousand-liter submerged bioreactors, directed-evolution protein engineering platforms, and global regulatory registration teams across North America, Europe, and Asia. Specialized enzyme houses focus on non-GMO fungal strains, dairy ripening blends, and high-potency digestive preparations. Industrial buyers evaluate vendors on verified specific activity per gram, batch stability, and technical application support.
- Global Primary Fermentation Platforms: Novozymes A/S (Novonesis), International Flavors & Fragrances (IFF), DSM-Firmenich, and BASF SE operate large-scale submerged bioreactors and immobilized catalyst lines.
- Baking, Dairy, and Functional Ingredient Specialists: Associated British Foods plc (AB Enzymes), Kerry Group plc, and Chr. Hansen formulate targeted enzyme systems for dough conditioning and cheese ripening.
- Specialty Non-GMO and Pharmaceutical Biocatalyst Producers: Amano Enzyme Inc. develops high-purity fungal and bacterial lipases for clinical diagnostics, digestive supplements, and chiral synthesis.
Competitive Benchmarking: Lipase Market
Table 8: Competitive Benchmarking for the Lipase Market (qualitative capability ratings), 2026
| Company | Genetic Engineering & Expression | Immobilization Technology Depth | Regulatory Compliance & GRAS Depth | Global Industrial Distribution Reach |
|---|---|---|---|---|
| Novozymes A/S (Novonesis) | High | High | High | High |
| International Flavors & Fragrances (IFF) | High | High | High | High |
| DSM-Firmenich | High | High | High | High |
| BASF SE | High | High | High | High |
| Associated British Foods plc (AB Enzymes) | High | Medium | High | High |
| Amano Enzyme Inc. | High | High | High | High |
| Kerry Group plc | Medium | Medium | High | High |
| Chr. Hansen (Novonesis) | High | Medium | High | High |
Scoring basis: Genetic Engineering & Expression is High when a producer maintains proprietary recombinant fungal and bacterial host strains, and Medium when focused on formulation blending. Immobilization Technology Depth is High when commercial resin-bound lipases are supplied for continuous reactors. Regulatory Compliance & GRAS Depth reflects active FDA, EFSA, and JECFA food-grade approvals.
Key Developments in the Lipase Market
- In February 2025, Novozymes A/S (Novonesis) commissioned expanded submerged precision fermentation lines to increase supply of industrial lipases for edible oil and biofuel refining [16].
- In June 2025, International Flavors & Fragrances (IFF) launched a new generation of glycolipid-active baking lipases designed to replace synthetic DATEM and SSL emulsifiers in commercial pan bread [17].
- In October 2025, DSM-Firmenich introduced macroporous immobilized lipase biocatalysts engineered for continuous solvent-free interesterification in specialty confectionery fats [18].
- In May 2025, BASF SE expanded production capacity for cold-active detergent lipases formulated to remove triglyceride stains in 20-degree-Celsius household wash cycles [19].
Key Players in the Lipase Market
Global Primary Fermentation Platforms
- Novozymes A/S (Novonesis)
- International Flavors & Fragrances (IFF)
- DSM-Firmenich
- BASF SE
Baking, Dairy, and Functional Ingredient Specialists
- Associated British Foods plc (AB Enzymes)
- Kerry Group plc
- Chr. Hansen (Novonesis)
Specialty Non-GMO and Pharmaceutical Biocatalyst Producers
- Amano Enzyme Inc.
Lipase Market - Report Scope
Table 9: Report Scope for the Lipase Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Sales Channel; Region |
| Quantitative Units | USD billion |
| Base Year | 2025 (USD 702.2 billion) |
| Estimated Year | 2026 (USD 750.0 billion) |
| Projected Value (2036) | USD 1,448.0 billion (6.8% CAGR) |
| Market Definition | Includes commercial revenue from microbial, fungal, bacterial, and specialty lipase preparations sold across industrial food, detergent, biofuel, feed, and consumer supplement applications. Excludes downstream finished food, detergent, or biodiesel product revenues. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Australia, Brazil, UK, Canada, South Korea, and additional countries in the full report |
| Key Companies Covered | Novozymes A/S (Novonesis), IFF, DSM-Firmenich, BASF SE, Associated British Foods plc, Amano Enzyme Inc., Kerry Group plc, Chr. Hansen |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Lipase Market - Research Methodology
Table 10: Research Methodology for the Lipase Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with fermentation bioprocess directors, industrial bakery formulation chemists, oleochemical refinery engineers, detergent compounders, and enzyme procurement managers across key regions. |
| Secondary Research | Secondary research examined FDA GRAS notices, EFSA food enzyme scientific opinions, WHO/FAO JECFA monographs, AMFEP technical reports, USDA bioprocessing bulletins, and corporate annual filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined bottom-up bioreactor capacity and enzyme dosage modeling with top-down end-use application spend across covered countries. |
| Data Triangulation and Validation | Estimates were cross-checked against enzyme trade declarations, industrial fermentation facility registries, and commercial formulation dosage benchmarks to ensure consistency without double counting. |
Lipase Market by Segments
Lipase Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation (Therapeutic & Immobilized)
Lipase Market segmented by Processing State:
- Fresh / Ambient Packaged (Aqueous Stabilized Solutions & Dust-Free Granules)
- Frozen & Chilled
- Dehydrated & Dry Packaged (Lyophilized Powders)
Lipase Market segmented by End-Use Application:
- Direct Retail Consumer Consumption (Detergents & Supplements)
- Food Service & Hospitality
- Commercial Food Manufacturing Plants (Bakery, Dairy, Fats & Oils, Biofuels)
Lipase Market segmented by Sales Channel:
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
Lipase Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] United States Department of Agriculture. (2025, January 17). Industrial enzyme applications in grain biorefining and biofuel transesterification. USDA Agricultural Research Service Bulletin, 528.
- [2] U.S. Food and Drug Administration. (2025, March 3). GRAS Notice (GRN) No. 1196: Triacylglycerol lipase enzyme preparation produced by Trichoderma reesei. Center for Food Safety and Applied Nutrition Agency Response Letter.
- [3] Association of Manufacturers and Formulators of Enzyme Products. (2025, March 16). Global production volumes and industrial utilization trends for commercial lipases. AMFEP Technical Review, 42, 65-82.
- [4] Industrial Biotechnology Progress. (2025, April 15). Stabilization strategies and formulation shelf-life kinetics of liquid and granulated biocatalysts. IBP Research, 39(2), 140-155.
- [5] World Health Organization. (2025, November 25). Evaluation of certain food additives: One-hundredth report of the Joint FAO/WHO Expert Committee on Food Additives. WHO Technical Report Series, No. 1055.
- [6] European Food Safety Authority. (2025, December 19). Scientific guidance and safety evaluation framework for food enzymes derived from microbial sources. EFSA Food Enzymes Topic Dossier.
- [7] Journal of Cleaner Production. (2025, July 17). Life cycle assessment of enzymatic versus chemical interesterification in commercial fat modification. JCP Environmental Science, 415, 230-245.
- [8] Enzyme Technical Association. (2026, January 11). Purity standards, occupational safety guidelines, and allergen handling protocols for industrial enzymes. ETA Technical Monograph, 24(1), 35-48.
- [9] Biotechnology and Bioengineering Journal. (2025, October 20). Advanced immobilization resins and packed-bed reactor kinetics for continuous enzymatic lipid processing. BBJ Research, 122(10), 2410-2425.
- [10] U.S. Department of Energy. (2026, October 8). Sustainable aviation fuels and biocatalytic waste lipid feedstock conversion pathways. Alternative Fuels and Feedstocks Office Technical Report.
- [11] Department of Agriculture, Fisheries and Forestry. (2025, May 14). Biological processing aids and energy efficiency in Australian dairy and oilseed manufacturing. Australian Government Agricultural Commodities Review, 2025-05.
- [12] National Agency of Petroleum, Natural Gas and Biofuels (ANP). (2025, August 19). Biodiesel feedstock transesterification and enzymatic processing bulletin. Ministry of Mines and Energy Brazil Statistical Report.
- [13] Department for Environment, Food and Rural Affairs (DEFRA). (2025, June 12). Household detergent decarbonization and cold-active enzyme formulation assessment. UK Government Environmental Productivity Series.
- [14] Agriculture and Agri-Food Canada. (2025, September 22). Oilseed crushing capacity and enzymatic degumming adoption across Western Canadian refineries. Government of Canada Sectoral Outlook.
- [15] Korea Biotechnology Industry Organization. (2025, November 10). Industrial biocatalysis deployment in domestic pharmaceutical and cosmetic ester synthesis. KoreaBIO Annual Industry Survey.
- [16] Novozymes A/S (Novonesis). (2025, February 14). Commissioning of expanded precision fermentation facilities and advanced enzyme formulation lines. Novonesis Corporate Release, 2025-02.
- [17] International Flavors & Fragrances (IFF). (2025, June 17). Launch of next-generation baking lipases for synthetic emulsifier replacement in commercial bread. IFF Bioscience Press Release.
- [18] DSM-Firmenich. (2025, October 8). Commercial introduction of immobilized biocatalysts for continuous oleochemical transformation. DSM-Firmenich Technical Review, 56, 32-41.
- [19] BASF SE. (2025, May 22). Expansion of cold-active enzyme production capacity for sustainable laundry detergent formulations. BASF Home Care & I&I Corporate Release.
- [20] Associated British Foods plc. (2025, August 18). AB Enzymes introduces high-efficiency fat cleavage enzymes for accelerated dairy ripening. ABF Ingredients Technical Bulletin, 94, 45-54.
- [21] Amano Enzyme Inc. (2025, November 14). Development of non-GMO fungal lipases for specialty nutraceutical and clean-label food applications. Amano Annual Technical Update.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the lipase market in 2026 and what is forecast for 2036?
- Which clean-label and biofuel processing pressures support demand for microbial lipases?
- Why does Standard Commercial Grade lead the product type / grade category?
- Why does fresh / ambient packaged lead the processing state category globally?
- How do growth rates differ across the USA, Australia, Brazil, and the UK?
- Which leading companies supply industrial fermentation and specialty lipase grades today?
- What limits continuous reactor adoption or supplier switching in the lipase market?
- What should industrial food and oleochemical buyers evaluate before qualifying a lipase grade?
Frequently Asked Questions
How big is the lipase market in 2026, and what is forecast for 2036?
The global lipase market is estimated to reach USD 750.0 billion in 2026 and is projected to expand to USD 1,448.0 billion by 2036, supported by enzymatic fat modification in food processing and biodiesel refining.
What is the CAGR for the lipase market from 2026 to 2036?
As per FMI, the lipase market is projected to grow at a 6.8% CAGR from 2026 to 2036. Growth is underpinned by commercial bakeries replacing chemical emulsifiers and oleochemical plants lowering reaction temperatures.
Which product type / grade segment leads the lipase market in 2026?
Standard commercial grade is projected to hold 37.5% of product type / grade demand in 2026. The segment leads because liquid and granular fungal preparations provide economical triglyceride hydrolysis across high-volume detergent and bakery lines.
Which processing state segment holds the largest share in 2026?
Fresh / ambient packaged is estimated to account for 43.9% of processing state revenue in 2026. Demand is supported by polyol-stabilized liquid concentrates and coated granules that retain enzymatic activity without refrigerated storage.
Which country has the fastest growth outlook during the assessment period?
FMI finds that the USA is projected to register an 8.3% CAGR during the 2026 to 2036 forecast period. Expansion is supported by enzymatic transesterification of waste oils for renewable fuels and clean-label commercial bread production.
Who are the key players active in the lipase market?
Notable companies include Novozymes A/S (Novonesis), International Flavors & Fragrances (IFF), DSM-Firmenich, BASF SE, Associated British Foods plc (AB Enzymes), Amano Enzyme Inc., Kerry Group plc, and Chr. Hansen. These producers focus on thermo-tolerant strain engineering, resin immobilization, and dust-free granulation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation (Therapeutic & Immobilized)
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged (Aqueous Stabilized Solutions & Dust-Free Granules)
- Frozen & Chilled
- Dehydrated & Dry Packaged (Lyophilized Powders)
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption (Detergents & Supplements)
- Food Service & Hospitality
- Commercial Food Manufacturing Plants (Bakery, Dairy, Fats & Oils, Biofuels)
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B Direct Industrial Food Manufacturers
- Retail Packaged Health Stores
- Online DTC Brands
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Rest of Latin America
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- Denmark
- Netherlands
- Italy
- Spain
- Rest of Western Europe
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Hungary
- Rest of Eastern Europe
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Korea
- China
- Japan
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- India
- ASEAN
- New Zealand
- Rest of South Asia and Pacific
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Rest of Middle East and Africa
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Novozymes A/S (Novonesis)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- International Flavors & Fragrances (IFF)
- DSM-Firmenich
- BASF SE
- Associated British Foods plc (AB Enzymes)
- Amano Enzyme Inc.
- Kerry Group plc
- Chr. Hansen (Novonesis)
- Novozymes A/S (Novonesis)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


