
- Market Size (2026)
- USD 5.2 Bn
- Forecast (2036)
- USD 16.9 Bn
- CAGR (2026 to 2036)
- 12.5%
How big is the Plant-Based Burger Market in 2026?
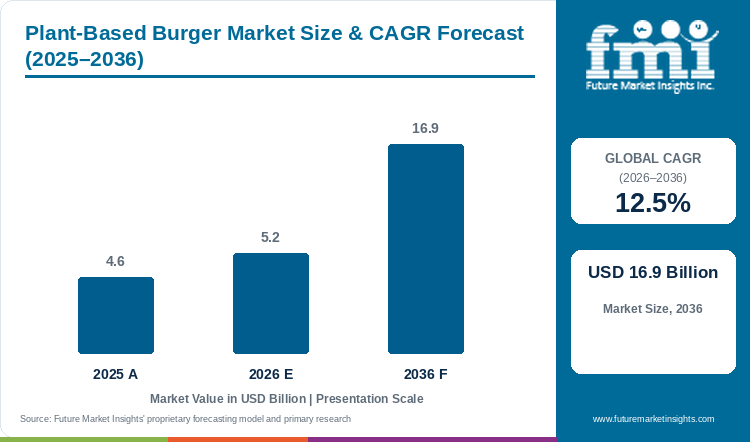
Demand for plant-based burgers is projected to expand at 12.5% CAGR between 2026 and 2036. Industry value grows from USD 4.6 billion in 2025 to USD 5.2 billion in 2026 and is projected to reach USD 16.9 billion by 2036.
According to Future Market Insights analysis, the global plant-based burger market stands at USD 4.6 billion in 2025 and rises to USD 5.2 billion in 2026. Industry valuation is projected to reach USD 16.9 billion by 2036, expanding at a 12.5% CAGR and generating USD 11.7 billion in added revenue. Food manufacturers face persistent household repeat-purchase friction when plant-based patties fail to replicate the sizzle, lipid release, and fibrous mouthfeel of conventional ground beef. In 2026, Good Food Institute market intelligence documented that global plant-based meat and seafood retail sales totaled USD 6.6 billion during 2025, revealing that category expansion relies heavily on closing taste and price parity gaps.
Plant-based beef burgers capture the leading position with 55.7% share in 2026, as multi-protein extrusion technology mimics whole-muscle chewiness. Growth across evaluated economies spans 10.0% in Israel to 15.2% in France, although retail price premiums and ingredient-list skepticism continue to temper mainstream adoption.
Key Market Trends & Insights
- By product type: Plant-based beef burgers led with 55.7% share in 2026, because familiar center-of-plate burger formats reduce trial hesitation for flexitarian omnivores.
- By protein source: Soy protein accounted for 38.4% in 2026, because established fractionation infrastructure delivers high protein density at favorable commercial cost.
- By processing state: Frozen and chilled products held 42.1% in 2026, as extended retail shelf-life insulates supermarket merchandisers from inventory spoilage.
- By distribution channel: Supermarkets and hypermarkets represented 54.2% in 2026, driven by dedicated plant-based meat sections positioned adjacent to meat counters.
- By end-use application: Direct retail consumer consumption held 46.7% in 2026, underpinned by flexitarian households cooking weeknight meals at home.
- By claim: Standard commercial formulation accounted for 51.8% in 2026, reflecting mainstream brand efforts to achieve competitive retail pricing.
Regional Highlights
- Fastest-growing evaluated country: France, at 15.2% CAGR from 2026 to 2036.
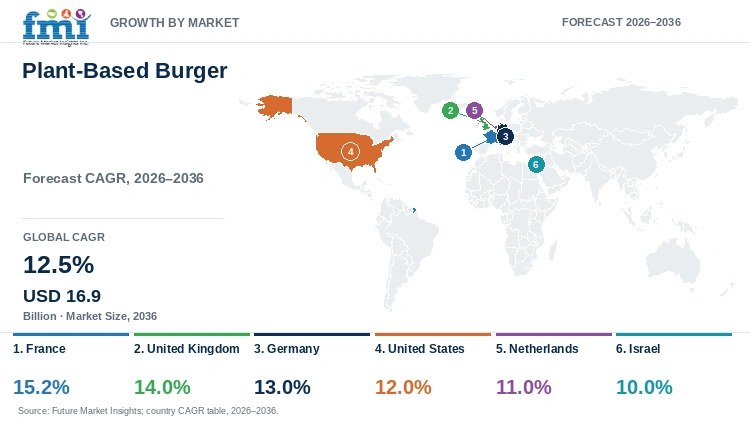
- By country: United Kingdom at 14.0%, Germany at 13.0%, and the United States at 12.0% follow, while Netherlands at 11.0% and Israel record 10.0% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Plant-Based Burger Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.6 billion |
| Estimated Market Size in 2026 | USD 5.2 billion |
| Projected Market Size by 2036 | USD 16.9 billion |
| CAGR, 2026 to 2036 | 12.5% |
| Added Revenue, 2026 to 2036 | USD 11.7 billion |
Household Penetration and Dietary Cohort Sizing Indicators
Table 2: Household Penetration and Flexitarian Cohort Sizing for the Plant-Based Burger Market (million households and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.6 | 5.2 | 16.9 |
| Flexitarian households in evaluated regions (million) | 145 to 160 | 155 to 175 | 240 to 275 |
| Annual burger patty unit purchases per household | 18 to 22 | 19 to 24 | 32 to 38 |
| Average retail price per two-patty pack (USD) | 4.85 to 5.20 | 4.70 to 5.05 | 3.80 to 4.15 |
Per Capita & Foodservice Outlet Sizing
Plant-based burgers have gained immense popularity in recent years due to their nutritional benefits and lower environmental footprint in supporting sustainable dietary transitions. Managing modern quick-service dining requires balancing kitchen cooking speed with authentic beef-like charring. Surging demand from flexitarian consumers converts dining occasions into recurring commercial food service procurement. Casual dining restaurants and quick-service chains represent central volume purchasers for standardized plant patties.
Table 3: Per Capita and Grocery Retail Spending Indicators for the Plant-Based Burger Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.559 | 0.627 | 1.888 |
| Spend per 1,000 people (USD) | 558.93 | 626.51 | 1,888.27 |
| Spend per flexitarian consumer (USD) | 12.50 to 14.20 | 13.10 to 14.80 | 26.50 to 30.20 |
Table 4: Foodservice & Retail Distribution Spending Indicators for the Plant-Based Burger Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 5.2 billion | Report value |
| Foodservice and commercial restaurants worldwide | 16.5 million | 2024 secondary hospitality estimate |
| Market spend per commercial restaurant | USD 315.15 | Calculated |
| Direct retail consumer consumption revenue, 2026 | USD 2.43 billion | 46.7% share |
Analyst Perspective
“Formulating plant-based burgers that achieve sensory and price parity with conventional beef patties is the decisive threshold separating casual trial from permanent household adoption. Food manufacturers that simplify ingredient panels while utilizing localized pea and faba bean proteins will secure sustainable grocery retail distribution.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Plant-Based Burger Market segmented?
Plant-Based Burger Market is segmented across six primary commercial axes and region: Product Type, Protein Source, Processing State, Distribution Channel, End-Use Application, Claim, and Region.
- By product type: Plant-based beef burgers, vegetable burgers, bean and legume burgers, grain burgers, and mushroom burgers.
- By protein source: Soy, pea, wheat, fava bean, mixed plant proteins, and mycoprotein.
- By processing state: Fresh or ambient packaged, frozen and chilled, and dehydrated or dry mixes.
- By distribution channel: Supermarkets and hypermarkets, convenience stores, online retail, foodservice distributors, and direct-to-consumer.
- By end-use application: Direct retail consumer consumption, foodservice and hospitality, and commercial food manufacturing.
- By claim: Standard commercial formulation, organic and clean-label, and premium specialty formulation.
Why do Plant-Based Beef Burgers Lead Product Type Demand?
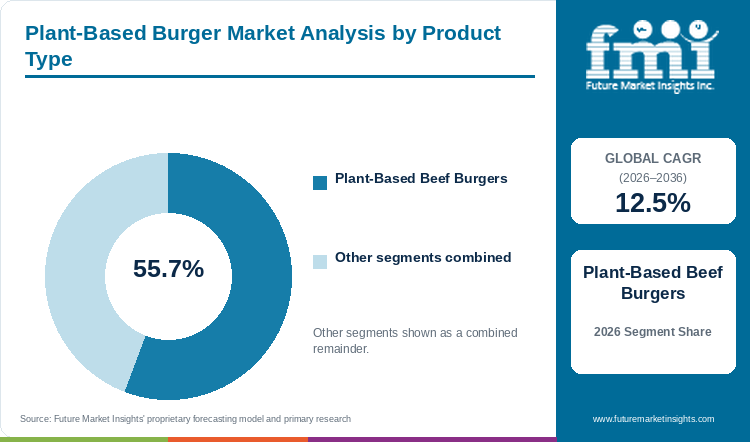
Plant-based beef burgers are projected to account for 55.7% of product type revenue in 2026, supported by authentic culinary familiarization.
Table 5: Product Type Share for the Plant-Based Burger Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Plant-based beef burgers | 55.7% |
| Other Segments Combined | 44.3%* |
| Total | 100.0% |
Table 6: Product Type Leadership and Market Growth for the Plant-Based Burger Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.5% |
| Leading Segment | Plant-based beef burgers |
FMI research indicates that flexitarian consumers prioritize recognizable meal substitutes that fit traditional burger buns, grilling styles, and condiment pairings. Incorporating methylcellulose alternatives and textured legume isolates into plant-based food formulations delivers the authentic bite, chewiness, and browning reaction required to satisfy meat-eating household members without demanding specialized culinary preparation.
- Plant-based beef burgers account for 55.7% of product type revenue in 2026, supported by authentic culinary familiarization and center-of-plate versatility.
- In 2025, consumer purchasing analyses revealed that over 95% of households buying plant-based burgers routinely purchased conventional meat, confirming that flexitarian omnivores represent the primary commercial audience.
What Keeps Frozen and Chilled Formats Dominant in Processing State?
Frozen and chilled products are estimated to hold 42.1% of processing state revenue in 2026, reflecting extended grocery shelf-life stability.
Cold-chain distribution provides essential retail merchandising flexibility by extending sell-by windows and reducing grocery stock write-downs. Maintaining frozen storage allows food processors to supply multi-pack family boxes and bulk restaurant cartons of commercial meat substitutes, protecting lipid stability and structural integrity against temperature fluctuations during long-haul transport.
- Frozen and chilled formats represent 42.1% of processing state revenue in 2026, reflecting extended grocery shelf-life stability and frozen warehouse inventory management.
- The Good Food Institute confirmed in 2026 that global plant-based meat retail sales reached USD 6.6 billion during 2025 across monitored food retail channels.
How Does Direct Retail Consumption Command Primary End-Use Share?
Direct retail consumer consumption is anticipated to capture 46.7% of end-use revenue in 2026, driven by recurring household meal preparation.
FMI data suggests that household grocery shopping remains the foundational volume driver as consumers trial alternative proteins in home kitchens before ordering them in dine-in restaurants. Offering pre-seasoned vegetable burger patties in standardized twin-packs encourages casual impulse buying during weekly grocery shopping, allowing brands to build household brand loyalty.
- Direct retail consumer consumption commands 46.7% of end-use revenue in 2026, driven by recurring household meal preparation and prominent supermarket placement.
- Consumer sensory studies published in 2026 established that taste and mouthfeel represent the primary purchase criteria determining repeat household buying among flexitarian shoppers.
What are the drivers, restraints, and opportunities in the Plant-Based Burger Market?
Flexitarian health awareness and environmental concerns drive household trial, whereas premium price gaps and textural inconsistencies restrain repeat purchases, and optimized plant lipid encapsulation unlocks superior eating experiences across mainstream channels.
- Driver: Expanding flexitarian demographics and consumer desire to reduce red meat consumption drive household trial across retail grocery aisles.
- Restraint: Significant retail price premiums relative to subsidized conventional beef and lingering consumer skepticism regarding ultra-processed ingredient lists restrain repeat purchases.
- Opportunity: Next-generation fat encapsulation technologies and clean-label pulse protein texturization enable brands to deliver juicy, short-ingredient burgers that appeal to health-conscious families.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
An FMI analyst notes that mainstream consumer adoption is expanding as food formulators utilize high-solubility plant protein isolates to replicate animal meat texture without off-flavors. Mainstream supermarket chains are dedicating permanent linear shelf space to alternative proteins, improving shopper visibility. In 2025, French retail leader Carrefour expanded its plant-based assortment across domestic stores under the Plant-Based Treaty initiative, normalizing plant patties as standard grocery items for middle-income shoppers.
Risk Assessment of the Plant-Based Burger Market: Operational and Formulation Friction
Persistent retail price premiums compared to conventional ground beef represent the primary economic barrier restricting mass category conversion. During periods of food inflation, budget-conscious consumers frequently trade down to cheaper animal proteins, leaving premium plant-based items unsold on refrigerated shelves. In January 2025, Quorn Foods announced comprehensive product renovations and packaging updates in the UK to counteract volume declines. Balancing high extrusion equipment amortization with competitive consumer pricing remains a severe margin constraint for emerging brands.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Government funding for national protein self-sufficiency is unlocking substantial innovation in regional crop processing. Utilizing non-GMO fractionated pea protein and upcycled brewer’s yeast allows manufacturers to create allergen-free burger formulations with clean ingredient statements. In 2025, the German Federal Ministry of Food and Agriculture allocated dedicated budget funding toward alternative protein research and farmer transition programs, providing ingredient developers with capital to scale cost-effective domestic extrusion facilities.
Plant-Based Burger Market by Country (2026 to 2036)
As per FMI, France represents the fastest-growing plant-based burger market among evaluated economies at a 15.2% CAGR through 2036, while Israel records 10.0% CAGR.
Table 7: Country CAGR and Primary Growth Levers for the Plant-Based Burger Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 15.2% | National protein strategy, pulse value chains, and retail Treaty commitments |
| United Kingdom | 14.0% | Mature chilled supermarket ranges and competitive retail price promotions |
| Germany | 13.0% | Federal protein transition funding and discount grocer private-label scale |
| United States | 12.0% | Flexitarian household penetration and brand portfolio recipe renovations |
| Netherlands | 11.0% | Wageningen food-tech cluster extrusion pilots and European export hubs |
| Israel | 10.0% | Alternative-protein culinary tech accelerators and novel cellular fat blending |
France Plant-Based Burger Market Outlook (2026 to 2036)
Public food policy and agricultural investment anchor the plant-based burger landscape in France. The national protein strategy actively supports domestic legume cultivation, providing processors with localized pea and faba bean crops that minimize reliance on imported functional soy protein. Major supermarket chains like Carrefour expanded plant-based meat merchandising under the Plant-Based Treaty initiative in 2025, supporting a leading 15.2% CAGR through 2036. However, traditional culinary conservatism requires burger formulators to satisfy demanding gastronomic standards.
Key takeaway: In France, national protein cultivation strategies coupled with progressive grocery retail merchandising create an exceptionally structured commercial growth environment for locally sourced plant-based burgers.
United Kingdom Plant-Based Burger Market Outlook (2026 to 2036)
A highly developed chilled meat-free retail grocery infrastructure underpins the market in the United Kingdom. British supermarkets feature dedicated plant-based aisles, facilitating regular household browsing and supporting a 14.0% CAGR through 2036. In January 2025, Quorn Foods introduced reformulated mycoprotein products to improve juiciness and consumer value. However, household budget sensitivity during periods of food price inflation has intensified competition, compelling brands to narrow the price gap with conventional beef through multi-buy promotions.
Key takeaway: In the United Kingdom, mature chilled supermarket distribution and vigorous price competition make retail value parity the decisive factor for sustained household patty consumption.
Germany Plant-Based Burger Market Outlook (2026 to 2036)
Germany’s progressive dietary policies and dominant discount supermarket networks drive rapid alternative protein adoption across all income demographics. Dedicated federal budget support for alternative protein research and farm transformation underpins an anticipated 13.0% CAGR through 2036 while boosting frozen retail foods. In 2025, German authorities expanded research allocations for plant-based ingredient manufacturing. Discount giants like Aldi and Lidl maintain aggressive private-label price-parity strategies, expanding market volume while compressing supplier gross margins.
Key takeaway: In Germany, substantial federal protein transition funding combined with discount supermarket private-label scale establishes high-volume, cost-disciplined demand for plant-based patties.
United States Plant-Based Burger Market Outlook (2026 to 2036)
In the United States, commercial success is dictated by appealing to a massive cohort of flexitarian consumers who refuse to sacrifice taste or value. Retail data confirms that over 95% of category shoppers also purchase conventional meat, supporting a forecasted 12.0% CAGR through 2036. Following recent category dollar sales contractions, brands like Beyond Meat and Impossible Foods are renovating recipes to enhance sizzle while shortening ingredient lists. Overcoming negative consumer perceptions regarding ultra-processing represents the critical operational hurdle.
Key takeaway: In the USA, brand portfolio renovations emphasizing cleaner ingredient decks and tighter price parity are critical to restoring repeat purchasing among flexitarian households.
Netherlands Plant-Based Burger Market Outlook (2026 to 2036)
The Netherlands acts as the culinary and technological epicenter of Europe’s plant-based food industry, anchored by Wageningen University and Foodvalley innovation clusters. Dutch food tech developers optimize extrusion processes using clean-label food ingredients. In 2025, commercial brand Vivera expanded its familiar meal portfolio across Benelux grocery shelves, fostering an 11.0% CAGR through 2036. Although the domestic market size is modest, extensive pilot facilities position the Netherlands as the central export gateway for Western Europe.
Key takeaway: In the Netherlands, world-class food extrusion clusters and strategic European export infrastructure make the country the leading pilot development hub for advanced plant-based meat formulations.
Israel Plant-Based Burger Market Outlook (2026 to 2036)
Israel’s highly innovative alternative-protein venture ecosystem leads globally in precision fermentation, cellular lipid synthesis, and 3D food printing that integrate into commercial foodservice distribution. The Israel Innovation Authority continues to finance food-tech incubators developing plant-fat matrixes that melt realistically during burger cooking, supporting a 10.0% CAGR through 2036. A compact grocery consumer base shifts commercial attention toward licensing proprietary intellectual property to global food corporations.
Key takeaway: In Israel, intense government-backed food technology innovation centers on developing novel fat-mimicking technologies that solve core sensory hurdles for international burger manufacturers.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Plant-Based Burger Market?
A few notable companies in the Plant-Based Burger Market include Beyond Meat, Impossible Foods, Nestlé, Unilever, Kellanova, Quorn Foods, Kraft Heinz Not Company, and Greenleaf Foods.
As per the analysis from FMI, competition divides between pioneering alternative-meat specialists and diversified consumer packaged goods conglomerates. Specialized brands differentiate through patented flavor chemistry and high-profile foodservice burger partnerships incorporating novel alternative protein ingredients. Simultaneously, multinational food giants leverage established temperature-controlled logistics, private-label manufacturing scale, and multi-category marketing power. Retailers evaluate suppliers on fill-rate reliability, consumer price promotional funding, and sensory consistency.
- Burger Specialists: Beyond Meat and Impossible Foods focus exclusively on whole-muscle texture mimicry, proprietary heme technology, and quick-service restaurant partnerships.
- Diversified Global Packaged-Food Groups: Nestlé (Garden Gourmet), Unilever (The Vegetarian Butcher), and Kellanova (MorningStar Farms) utilize massive manufacturing scale and multi-category frozen distribution.
- Joint Ventures and Specialty Formulators: Kraft Heinz Not Company combines national brand equity with AI-driven plant-protein recipe engineering, while Quorn Foods supplies unique fermentation-derived mycoprotein platforms.
Competitive Benchmarking: Plant-Based Burger Market
Table 8: Competitive Benchmarking for the Plant-Based Burger Market (qualitative capability ratings), 2026
| Company | Portfolio Depth | Current Activity | Geographic Reach |
|---|---|---|---|
| Beyond Meat | High | High | High |
| Impossible Foods | High | High | Medium |
| Nestlé | High | Medium | High |
| Unilever | Medium | Medium | High |
| Kellanova | Medium | Medium | High |
| Quorn Foods | High | High | Medium |
| Kraft Heinz Not Company | Medium | High | Medium |
| Greenleaf Foods | Medium | Medium | Medium |
Key Developments in the Plant-Based Burger Market
- Beyond The Plant Protein Co. (formerly Beyond Meat) rebranded to "Beyond," dropping "Meat" from its corporate identity and packaging, and pivoted to a broader plant-protein portfolio including the four-ingredient Beyond Ground product and the Beyond Immerse sparkling protein drink .
- In April 2025, Kraft Heinz Not Company broadened its plant-based portfolio across major retail grocery channels under established consumer food brands.
- In August 2025, Quorn Foods rolled out updated packaging for its core UK frozen range, removing all artificial ingredients from its mince and pieces products and introducing new high-protein claims across the line.
Key Players in the Plant-Based Burger Market
Meat-Like Burger Specialists: Beyond Meat; Impossible Foods.
- Diversified Packaged-Food Participants: Nestlé; Unilever; Kellanova; Kraft Heinz Not Company.
- Established Meat-Free Portfolio Companies: Quorn Foods; Greenleaf Foods.
Plant-Based Burger Market - Report Scope
Table 9: Report Scope for the Plant-Based Burger Market (coverage fields and definitions), 2026 to 2036
| Scope item | Coverage |
|---|---|
| Market boundary | Finished plant-based burger patties and commercially sold burger mixes sold through retail and foodservice channels. |
| Excluded | Cultivated or cell-cultured meat, conventional livestock meat burgers, and unrelated plant-based ready meals without burger patty formats. |
| Base year | 2025 |
| Estimate year | 2026 |
| Forecast period | 2026–2036 |
| Unit | USD billion |
| Geography | Seven major regions with selected country forecasts |
| Commercial axes | Product type, protein source, processing state, distribution channel, end-use application, claim, and region |
Plant-Based Burger Market - Research Methodology
Table 10: Research Methodology for the Plant-Based Burger Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | FMI analysts conducted primary interviews with food extrusion engineers, alternative-protein brand executives, retail supermarket category managers, foodservice chefs, and flavor chemistry specialists to validate formulation trends, retail price points, and menu adoption rates. |
| Desk Research | Secondary research encompassed government agricultural statistics, alternative-protein think-tank reports, commercial scanner sales data, patent filings, corporate financial disclosures, and food regulation publications. Sources were cross-verified for methodology consistency and scope boundary adherence. |
| Market Sizing and Forecasting | The market model integrated baseline retail sales with historical volume growth, flexitarian household penetration rates, private-label substitution trends, and regional foodservice expansion. Projections were calibrated against agricultural pulse output and processing capacity investments. |
| Data Validation | Estimates were validated against retail scanner audits, corporate earnings reports, food industry trade associations, and primary interview findings to ensure absolute accuracy without double-counting adjacent meat alternative categories. |
Plant-Based Burger Market by Segments
Plant-Based Burger Market segmented by Product Type:
- Plant-Based Beef Burgers
- Vegetable Burgers
- Bean and Legume Burgers
- Grain Burgers
- Mushroom Burgers
Plant-Based Burger Market segmented by Protein Source:
- Soy
- Pea
- Wheat
- Fava Bean
- Mixed Plant Proteins
- Mycoprotein
Plant-Based Burger Market segmented by Processing State:
- Fresh or Ambient Packaged
- Frozen and Chilled
- Dehydrated or Dry Mixes
Plant-Based Burger Market segmented by Distribution Channel:
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Foodservice Distributors
- Direct-to-Consumer
Plant-Based Burger Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Foodservice and Hospitality
- Commercial Food Manufacturing
Plant-Based Burger Market segmented by Claim:
- Standard Commercial Formulation
- Organic and Clean-Label
- Premium Specialty Formulation
Plant-Based Burger Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Western Europe
- France
- United Kingdom
- Germany
- Netherlands
- Rest of Western Europe
- Eastern Europe
- Poland
- Russia
- Rest of Eastern Europe
- East Asia
- Japan
- South Korea
- Rest of East Asia
- South Asia and Pacific
- Australia
- Indonesia
- Rest of South Asia and Pacific
- Middle East and Africa
- Israel
- GCC countries
- South Africa
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] Good Food Institute. (2026). State of the Industry: Plant-based meat, seafood, eggs, dairy, and ingredients. GFI Research Reports.
- [2] Good Food Institute Europe. (2026). European plant-based foods retail market insights. GFI Europe Publications.
- [3] Good Food Institute. (2026). Analyzing plant-based meat and seafood retail sales trends. GFI Industry Briefs.
- [4] Good Food Institute. (2026). Retail trends and dollar volume for plant-based products. GFI Commercial Data.
- [5] Good Food Institute. (2026). Consumer sensory and price research on plant-based meat. GFI Consumer Insights.
- [6] Carrefour Group. (2025). Carrefour advances plant-based product access and assortment expansion. Corporate Communications.
- [7] Quorn Foods. (2025). Quorn announces product renovation and packaging updates. Quorn Corporate Newsroom.
- [8] Vivera. (2025). Vivera expands familiar plant-based meal formats across European retail. Commercial Product News.
- [9] Israel Innovation Authority. (2026). Food-tech and alternative-protein incubation programs review. Government Innovation Reports.
- [10] Beyond Meat Inc. (2026, September). Beyond Meat announces portfolio and brand reset for whole plant nutrition. Investor Relations.
- [11] Impossible Foods Inc. (2026, May). Impossible Foods expands foodservice availability and restaurant partnerships. Press Releases.
- [12] The Kraft Heinz Company. (2025, April). Kraft Heinz Not Company expands plant-based portfolio across retail aisles. Corporate Announcements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What is the Plant-Based Burger Market value in 2026?
- What growth is forecast for plant-based burgers through 2036?
- Which product type holds a notable plant-based burger share?
- Which processing state represents a notable share in 2026?
- Which country has a notable plant-based burger growth outlook?
- Which companies participate in the Plant-Based Burger Market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Plant-Based Beef Burgers
- Vegetable Burgers
- Bean and Legume Burgers
- Grain Burgers
- Mushroom Burgers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Protein Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Protein Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Protein Source, 2026 to 2036
- Soy
- Pea
- Wheat
- Fava Bean
- Mixed Plant Proteins
- Mycoprotein
- Y-o-Y Growth Trend Analysis By Protein Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Protein Source, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh or Ambient Packaged
- Frozen and Chilled
- Dehydrated or Dry Mixes
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Foodservice Distributors
- Direct-to-Consumer
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Foodservice and Hospitality
- Commercial Food Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Claim, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Claim, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Claim, 2026 to 2036
- Standard Commercial Formulation
- Organic and Clean-Label
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Claim, 2021 to 2025
- Absolute $ Opportunity Analysis By Claim, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Rest of Latin America
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- France
- United Kingdom
- Germany
- Netherlands
- Rest of Western Europe
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Russia
- Rest of Eastern Europe
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- Rest of East Asia
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- Indonesia
- Rest of South Asia and Pacific
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Israel
- GCC countries
- South Africa
- Rest of Middle East and Africa
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Israel
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Protein Source
- By Processing State
- By Distribution Channel
- By End-Use Application
- By Claim
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Beyond Meat
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Impossible Foods
- Nestlé
- Unilever
- Kellanova
- Quorn Foods
- Kraft Heinz Not Company
- Greenleaf Foods
- Diversified Packaged-Food Participants: Nestlé; Unilever; Kellanova; Kraft Heinz Not Company.
- Established Meat-Free Portfolio Companies: Quorn Foods; Greenleaf Foods.
- Beyond Meat
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 7: Global Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 14: North America Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 19: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 20: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: Latin America Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 25: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 26: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 27: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 28: Western Europe Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Eastern Europe Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 32: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 33: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 34: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: Eastern Europe Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 38: East Asia Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 39: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 40: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 41: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 42: East Asia Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 43: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: South Asia and Pacific Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 46: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 47: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 49: South Asia and Pacific Market Value (USD Billion) Forecast by Claim, 2021 to 2036
- Table 50: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 51: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 52: Middle East and Africa Market Value (USD Billion) Forecast by Protein Source, 2021 to 2036
- Table 53: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 54: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 55: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 56: Middle East and Africa Market Value (USD Billion) Forecast by Claim, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Protein Source
- Figure 9: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Processing State
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End-Use Application
- Figure 18: Global Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Claim
- Figure 21: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 22: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 23: Global Market Attractiveness Analysis by Region
- Figure 24: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 29: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 30: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 31: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 32: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Product Type
- Figure 35: North America Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Protein Source
- Figure 38: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Processing State
- Figure 41: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Distribution Channel
- Figure 44: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 45: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 46: North America Market Attractiveness Analysis by End-Use Application
- Figure 47: North America Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 48: North America Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 49: North America Market Attractiveness Analysis by Claim
- Figure 50: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 51: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Product Type
- Figure 54: Latin America Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Protein Source
- Figure 57: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Processing State
- Figure 60: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 61: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 62: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 63: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 64: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 65: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 66: Latin America Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 67: Latin America Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 68: Latin America Market Attractiveness Analysis by Claim
- Figure 69: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 70: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Product Type
- Figure 73: Western Europe Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Protein Source
- Figure 76: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: Western Europe Market Attractiveness Analysis by Processing State
- Figure 79: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 82: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 83: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 84: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 85: Western Europe Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 86: Western Europe Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 87: Western Europe Market Attractiveness Analysis by Claim
- Figure 88: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 92: Eastern Europe Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 93: Eastern Europe Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 94: Eastern Europe Market Attractiveness Analysis by Protein Source
- Figure 95: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 96: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 97: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 98: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 99: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 100: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 101: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 102: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 103: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 104: Eastern Europe Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 105: Eastern Europe Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 106: Eastern Europe Market Attractiveness Analysis by Claim
- Figure 107: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 108: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 109: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 110: East Asia Market Attractiveness Analysis by Product Type
- Figure 111: East Asia Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 112: East Asia Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 113: East Asia Market Attractiveness Analysis by Protein Source
- Figure 114: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 115: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 116: East Asia Market Attractiveness Analysis by Processing State
- Figure 117: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 118: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 119: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 120: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 121: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 122: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 123: East Asia Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 124: East Asia Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 125: East Asia Market Attractiveness Analysis by Claim
- Figure 126: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 127: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 128: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 129: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 130: South Asia and Pacific Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 131: South Asia and Pacific Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 132: South Asia and Pacific Market Attractiveness Analysis by Protein Source
- Figure 133: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 134: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 135: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 136: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 137: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 138: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 139: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 140: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 141: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 142: South Asia and Pacific Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 143: South Asia and Pacific Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 144: South Asia and Pacific Market Attractiveness Analysis by Claim
- Figure 145: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 146: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 147: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 148: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 149: Middle East and Africa Market Value Share and BPS Analysis by Protein Source, 2026 and 2036
- Figure 150: Middle East and Africa Market Y-o-Y Growth Comparison by Protein Source, 2026-2036
- Figure 151: Middle East and Africa Market Attractiveness Analysis by Protein Source
- Figure 152: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 153: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 154: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 155: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 156: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 157: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 158: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 159: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 160: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 161: Middle East and Africa Market Value Share and BPS Analysis by Claim, 2026 and 2036
- Figure 162: Middle East and Africa Market Y-o-Y Growth Comparison by Claim, 2026-2036
- Figure 163: Middle East and Africa Market Attractiveness Analysis by Claim
- Figure 164: Global Market - Tier Structure Analysis
- Figure 165: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Plant-Based Burger Market in 2026?
Future Market Insights estimates the global plant-based burger market at USD 5.2 billion in 2026. The market is projected to reach USD 16.9 billion by 2036, driven by expanding flexitarian demographics.
What CAGR is expected from 2026 to 2036?
FMI forecasts a 12.5% CAGR for the plant-based burger market between 2026 and 2036. Growth is supported by recipe renovations and public protein transition initiatives.
Which product type holds a notable share in 2026?
Plant-based beef burgers are projected to account for 55.7% of product type revenue in 2026. Center-of-plate familiarization and meat-like cooking performance drive this leading position.
Which processing state is prominent in the 2026 market?
Frozen and chilled products are estimated to hold 42.1% of processing state revenue in 2026. Extended retail shelf-life and multi-pack grocery merchandising underpin category demand.
Which country has a notable growth outlook through 2036?
France is projected to record a leading 15.2% CAGR through 2036, supported by national plant-protein cultivation strategies and proactive grocery retail assortments.
Which companies are notable in the Plant-Based Burger Market?
Notable companies include Beyond Meat, Impossible Foods, Nestlé, Unilever, Kellanova, Quorn Foods, Kraft Heinz Not Company, and Greenleaf Foods. Manufacturers focus on sensory improvement, cleaner ingredient decks, and foodservice penetration.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
