
- Market Size (2026)
- USD 6.6 Bn
- Forecast (2036)
- USD 14.5 Bn
- CAGR (2026 to 2036)
- 8.1%
How big is the Sourdough Market in 2026?
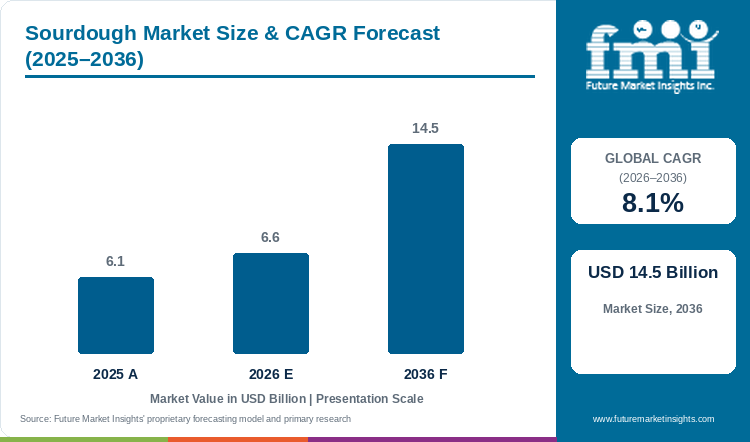
The global Sourdough Market is forecast to reach USD 14.5 billion by 2036, rising from USD 6.6 billion in 2026 and USD 6.1 billion in 2025, at an 8.1% CAGR from 2026 to 2036. FMI sees demand for commercial preparations growing as industrial bakers extend fermented flavours across grain formats and develop differentiated wholegrain ranges. Those recipes increase the importance of grain-specific preparation specifications, including their acidity and dough performance. In 2026, Conventional leads Nature revenue at 79.9%, Food Processing Industry leads End-Use at 53.0%, and Type III leads Starter Culture at 50.0%, according to FMI's assessment.
Flavour and crumb performance support the use of sourdough across grain formulations. A 2024 academic review in Foods documents effects on bread quality and grain components, with results depending on flour, microorganisms and process conditions. This variation also limits scale-up: acidity and dough behaviour need validation in each bakery process before repeat production (Foods). IREKS's iba 2025 range provides a qualified example, with durum, sprouted-seed, oat and buckwheat formulations containing sourdough. It documents formulation breadth at that supplier. Related FMI coverage includes the sourdough sweet goods market.
Key Market Trends & Insights
- Culture origin alone is a weak proxy for its baking performance. A 2021 eLife study examined 500 household starters, with most samples coming from the United States, and found little evidence of broad geographic patterns in their microbial communities [10]. The commercial implication concerns testing: a culture's place of origin does not replace measurement of the rise and aroma required by the purchasing bakery.
- France's levain provisions allow baker's yeast to be added at final kneading at no more than 0.2% of the flour used at that stage [11]. The complete process specification therefore matters to a qualifying claim, even when the starting preparation uses a live culture. Purchasers need to distinguish the culture type from additional leavening permitted in the finished dough. FMI's wider starter cultures market coverage addresses the ingredient category.
Regional Highlights
- Western European specifications need to be read at product and country level. France's levain provisions include conditions for dehydrated preparations [11], while the UK's flour guidance addresses nutrient composition [2]. For a supplier selling across the region, matching one country's ingredient or naming requirements does not settle the requirements in the next.
- North American bread naming also requires a destination-specific review. Canada's inspection agency explains that products which differ from the bread standard may need an alternative common name or an appropriate qualifier [12], while the United States applies its own bakery standards under Part 136 [1]. Suppliers should resolve those differences before extending a common formulation across both markets. FMI also covers the bread improvers market.
Table 1: Sourdough Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 6.1 Billion |
| Estimated market size in 2026 | USD 6.6 Billion |
| Projected market size by 2036 | USD 14.5 Billion |
| CAGR from 2026 to 2036 | 8.1% |
Source: Future Market Insights
Analyst Perspective
“Scaling sourdough production requires repeatable fermentation without losing the flavor and texture expected in the finished product. Starter suppliers need to show how their cultures perform under the bakery's actual process conditions, including the production time and food-safety controls available on the line.”
- Nandini Roy Choudhury, Principal Consultant, FMI
How is the Sourdough Market segmented?
FMI segments commercial sourdough starters, preparations and mixes by Nature, End-Use, Starter Culture and Region. End-use describes the preparation's customer channel. Retail covers preparations sold through retail channels for baking, while finished loaves and meals provide downstream application context.
- By Nature: Conventional; Organic
- By End-Use: Food Processing Industry; Food Service Industry; Retail
- By Starter Culture: Type III; Type II; Type I
- By Region: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa
FMI also examines the wider ingredient category in its starter cultures market coverage.
Why does Conventional lead by Nature?
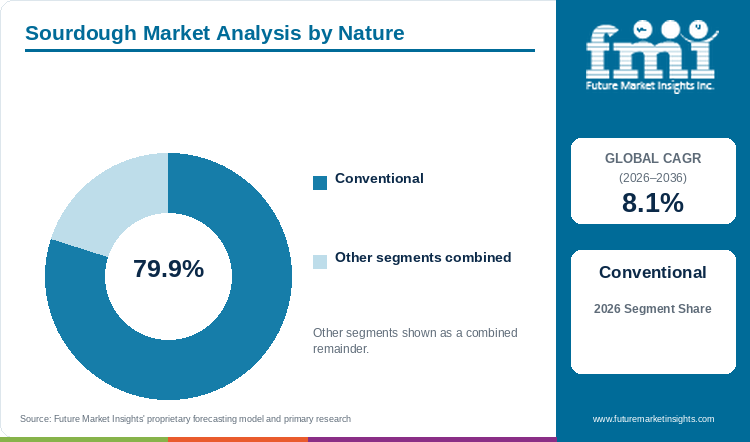
Conventional accounts for 79.9% of the Sourdough Market by Nature in 2026, according to FMI's assessment.
Organic accounts for the remaining 20.1%.
Conventional leadership reflects the broader commercial-preparation supply serving the Food Processing Industry, which holds 53.0% by End-Use. The Nature classification concerns the preparation's organic status, independently of its starter-culture type or customer channel.
IREKS describes TEN SPROUTS as meeting its own clean-label definition and identifies dried wheat sourdough among its ingredients [7]. That description does not establish organic certification, and clean-label language should not be treated as a substitute for it. FMI sees an advantage for suppliers that state both the fermentation specification and certification status clearly: a processor can assess conventional and organic offers on the requirements of the intended product. The remaining 20.1% is material, so conventional leadership does not imply that certified organic supply is commercially irrelevant.
Table 2: Sourdough Market Share by Nature Segment
| Leading Share | 2026 market share |
|---|---|
| Conventional | 79.9% |
| All Other Segments Combined Share | 20.1% |
Source: Future Market Insights
Why does the Food Processing Industry lead by End-Use?
Food Processing Industry accounts for 53.0% of the Sourdough Market by End-Use in 2026, according to FMI's assessment.
Food Service Industry and Retail together account for 47.0%.
The processing channel combines repeat purchases of commercial preparations for food production. Food service and retail identify other channels for these preparations; finished bread and meal sales are outside the revenue boundary.
IREKS's iba 2025 material identifies durum sourdough in CRAFT MASTER DURUM, dried wheat sourdough in TEN SPROUTS and wholemeal oat sourdough in IREKS SOFT OAT [7]. This range gives processors several ingredient specifications for different recipes. Supplier retention depends on demonstrating the required flavour and dough behaviour in each production process. Paris Baguette's Singapore Paran menu illustrates downstream bread and meal formats [9]. Those applications indicate distinct formulation requirements; their finished-product sales are not added to the commercial-preparation market.
Table 3: Sourdough Market Share by End-Use Segment
| Leading Share | 2026 market share |
|---|---|
| Food Processing Industry | 53.0% |
| All Other Segments Combined Share | 47.0% |
Source: Future Market Insights
Why does Type III lead by Starter Culture?
Type III accounts for 50.0% of the Sourdough Market by Starter Culture in 2026, according to FMI's assessment.
Type I and Type II together account for 50.0%.
Dried preparations place fermentation upstream at the ingredient producer and provide an alternative to live or liquid systems maintained at the bakery. The classification describes the commercial preparation, independently of its organic status or end-use channel.
IREKS identifies dried wheat sourdough from its own production in TEN SPROUTS [7]. This is relevant evidence of a supplied dried format, but the product page does not disclose the company's market share or the full manufacturing specification needed to assign every IREKS product to a starter class. Type III preparations also should not automatically be described as active leavening cultures: drying and formulation affect microbial activity, and the finished dough may require another leavening source [8]. FMI sees the leading share as reflecting demand for prepared ingredients alongside continuing demand for live and liquid systems, without assuming that one format will replace the others.
Table 4: Sourdough Market Share by Starter Culture Segment
| Leading Share | 2026 market share |
|---|---|
| Type III | 50.0% |
| All Other Segments Combined Share | 50.0% |
Source: Future Market Insights
What are the key drivers restraints and opportunities?
FMI's outlook depends on broader bakery formulation use, constrained by process consistency and the evidence required for product claims. Those factors affect ingredient demand in different ways.
Driver
Broader grain formulations give sourdough suppliers additional recipes to serve within the same bakery customer. IREKS's iba 2025 range includes oat and buckwheat sourdough components alongside wheat and durum formats [7]. FMI reads this as a route to repeat ingredient demand across several products, rather than relying on a single premium loaf. Research presented in the programme for the 2026 International Sourdough Symposium included faba-bean flour sourdough [6], extending the formulation questions being studied without proving a commercial launch or a permitted health claim. Related FMI coverage includes bread improvers market.
Restraint
Fermentation results depend on the flour, culture and process conditions, which makes transfer between recipes and production lines demanding. The 2024 Foods review describes variation in acidity, dough properties and quality outcomes across sourdough systems [8]. A supplier's result therefore needs confirmation under the purchaser's process. Claims of improved digestibility or other health benefits require their own evidence; the use of sourdough alone does not establish the same effect in every bread. FMI sees process validation and claim substantiation as constraints on the pace at which new formulations become repeat orders. Related FMI coverage includes yeast market.
Opportunity
Suppliers can win business by developing grain-specific sourdough preparations with documented performance in the customer's finished recipe. The opportunity is to reduce repeated formulation work while retaining the intended flavour and texture. IREKS's product-specific range provides an example of this approach [7]. Puratos's February 2026 symposium programme separately identified work on faba-bean flour sourdough and postbiotic-enriched sourdough [6]. These are research topics and should not be presented as proof that a finished product has an authorised health claim or demonstrated consumer demand.
How do trade and quality rules affect sourdough purchasing?
The product's form at import affects UK purchasing requirements. Government guidance brings qualifying imported non-wholemeal common wheat flour within the flour-fortification rules, but excludes imported multi-ingredient products containing flour from those requirements [2]. A flour shipment and a compound sourdough preparation therefore need separate classification checks. Buyers need the composition and intended use documented before applying a flour requirement to a supplier's mix.
France's bread decree permits dehydrated levain under specified live-flora conditions and requires it to provide proper leavening after rehydration [11]. A buyer requiring that qualifying levain function needs a preparation with the relevant viability and performance specification; a dried flavour ingredient is not automatically equivalent. Pane di Altamura PDO separately has its own product-specific specification [4]. These requirements favour suppliers that document the actual preparation and destination claim, rather than relying on the general word sourdough.
What limits reliable sourdough supply, quality, or performance?
Control of acidity and fermentation performance is a practical constraint when a bakery changes flour or scales a recipe. The 2024 Foods review describes the influence of starter microorganisms, fermentation conditions and flour composition on bread quality [8]. FMI sees the commercial risk in inconsistent finished batches and additional validation work, rather than in a universal development timeline for every culture.
Supplied dried preparations move some fermentation work to the ingredient producer. IREKS identifies its own dried wheat sourdough in TEN SPROUTS [7]. That does not remove the need to confirm dosage, dough behaviour and the final bread's characteristics in the customer's process. Live, liquid and dried systems involve different production arrangements; none should be described as eliminating variability or providing health benefits without evidence for that formulation.
Where can suppliers win additional business in the Sourdough Market?
Product development for wholegrain and mixed-grain bread gives ingredient suppliers a specific route to additional business. A formulation brief that identifies the grain mix, desired acidity and production conditions is more commercially useful than an unsupported promise of better health. Puratos's 2026 symposium programme included faba-bean flour sourdough and postbiotic-enriched sourdough research [6]. The programme establishes the subjects being investigated, not approved claims or sales volumes.
Bakery chains developing several meal formats create distinct formulation briefs for ingredient suppliers. Paris Baguette's Singapore Paran range includes multigrain rye, rustic multiseed and oat breads, with some used in sandwiches and breakfast dishes [9]. These are downstream application examples. The supplier opportunity lies in matching preparations to the texture, flavour and handling required by each recipe while meeting the destination's purchasing and claims requirements.
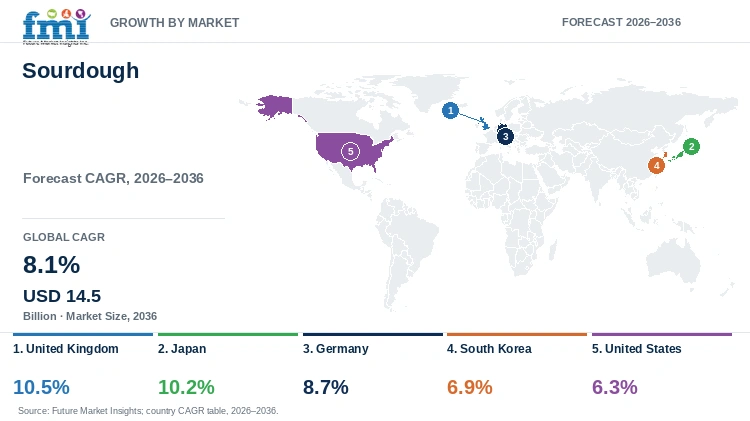
Sourdough Market by Country (2026 to 2036)
Table 5: Sourdough Market Country Growth Forecast
| Country | CAGR (2026 to 2036) |
|---|---|
| United Kingdom | 10.5% |
| Japan | 10.2% |
| Germany | 8.7% |
| South Korea | 6.9% |
| United States | 6.3% |
Source: Future Market Insights
United Kingdom
The UK's bakery ingredient market faces a concrete flour-specification change during the base year. Government guidance states that folic acid must be added to non-wholemeal common wheat flour from 13 December 2026, alongside revised requirements for some existing nutrients [2]. This matters to sourdough manufacturers using those flours because ingredient specifications and packaging must reflect the applicable composition. It is not a sourdough-specific health endorsement, and wholemeal flour has a different treatment under the guidance.
Against this background, FMI forecasts sourdough demand in the United Kingdom to grow at 10.5% CAGR from 2026 to 2036. The commercial argument centres on differentiated bakery ranges and repeat purchases of preparations that perform consistently in the selected flour mix. Bakers marketing wholemeal or mixed-grain loaves need to distinguish the flour's composition, the fermentation process and any claim made for the finished bread. Those are related purchasing questions, but evidence for one does not settle the others.
The previous consultation should not be mistaken for a continuing policy process: the government published its response in January 2024 [3]. For suppliers, the immediate task is serving the rules and recipes now specified, while documenting any later changes. A broad product range may support several customer formulations, but a supplier still needs to validate the relevant result in each recipe. FMI therefore sees process documentation and formulation support as routes to retaining business; the regulatory documents themselves do not establish the forecast rate or a premium that UK consumers will necessarily pay.
Japan
Marketing sourdough in Japan requires care with the claim printed beside its name. The Consumer Affairs Agency's guidance on additive non-use labelling, documented by USDA's Foreign Agricultural Service, identifies labels that may mislead consumers [5]. Fermentation does not by itself establish that a bread contains no additives, and an additive-free claim does not establish a health advantage. This distinction affects both domestic manufacturers and suppliers selling preparations for Japanese finished products.
FMI forecasts a 10.2% CAGR for Japan's commercial sourdough preparation market from 2026 to 2036. The market opening lies in differentiated flavour and grain formulations that can be explained accurately at the point of sale. A supplier offering a starter for a new loaf must consider the entire recipe before advising on a label: the flour, processing aids and other ingredients may affect the final claim. The guidance's focus on avoiding misleading impressions makes precise product descriptions commercially relevant even when no special sourdough claim is made.
Japan's forecast should not be read as evidence that the guidance caused demand to rise. The rule describes how products may be presented, while sales still depend on the bread's taste, price and repeat acceptance. Suppliers can support a bakery with specifications and documented process results, but those records need to relate to the finished Japanese formulation. An overseas ingredient's marketing language cannot simply be copied onto a local package. FMI sees an advantage in separating the fermentation description from optional nutrition or additive claims, allowing the bakery to develop a differentiated range without making unsupported promises.
Germany
German ingredient development provides a clear example of sourdough being offered across several grain formats. IREKS's iba 2025 portfolio included CRAFT MASTER DURUM, TEN SPROUTS, IREKS SOFT OAT and UNSER BUCHWEIZENVOLLKORN [7]. The company identifies different sourdough components in those formulations. This is evidence of product breadth at one supplier, rather than a measurement of national bakery adoption or proof that all German suppliers follow the same strategy.
That formulation breadth is relevant to FMI's forecast of 8.7% CAGR for the German sourdough market from 2026 to 2036. Demand can develop through several recipes at an existing customer, with each formulation creating its own ingredient requirement. The distinction matters when an ingredient supplier extends an existing bakery customer's range: growth does not require every bakery to introduce an entirely new product category, but it does require recipes that customers continue to buy. Suppliers compete on the performance of the preparation in the selected grain mix as well as its flavour.
There are limits to what the portfolio demonstrates. A product containing wholemeal oat sourdough is not automatically interchangeable with a durum or buckwheat preparation, and the page does not disclose sales by product [7]. Nor does a clean-label description establish organic certification. FMI's view is that the opportunity for German suppliers lies in extending application support across these differences, rather than treating sourdough as one universal additive. Documenting dosage and process conditions can make repeat procurement easier, while trials remain necessary before a formulation is transferred to another customer's line.
South Korea
South Korean bakery brands provide a visible route from a fermented-bread proposition to a wider menu. Paris Baguette's Paran range is also offered in Singapore, where the operator lists rustic multiseed, multigrain rye and oat breads alongside sandwiches and breakfast dishes made with them [9]. This is evidence of one company's product offer outside Korea. It does not establish the share of Korean commercial preparation purchases represented by that operator or the proportion of the range that meets a particular starter-culture classification.
FMI forecasts South Korea's sourdough preparation market to grow at 6.9% CAGR from 2026 to 2036. The commercial argument is that bakery chains can extend a differentiated bread base into several eating occasions, creating demand for consistent upstream formulations. Fermented and fortified breads differ in composition and processing, so the branded range involves several formulation requirements rather than one universal ingredient specification. Added probiotics, where advertised by the operator, should not be confused with proof that ordinary baked sourdough retains live cultures or delivers the same effect.
For Korean suppliers, the downstream opportunity is therefore recipe-specific. A preparation intended for a sliced bread sold by itself may face different texture and handling requirements when used in sandwiches. The Singapore menu demonstrates these applications but provides no controlled comparison of sales or fermentation performance [9]. FMI sees scope for ingredient suppliers to work with chains on documented specifications across those formats. Export business remains subject to the destination's ingredients, claims and certification requirements; one branded range cannot establish that a starter or certificate is automatically transferable to every market.
United States
US bread standards allow more formulation detail than the absence of a separate sourdough identity standard might suggest. Part 136 defines several bread categories and includes lactic-acid-producing bacteria among the permitted ingredients for standardised bread [1]. It does not provide a distinct sourdough standard. This narrower finding should not be expanded into a claim that sourdough labelling or food safety is unregulated, or that any fermentation statement is acceptable without support.
Within this framework, FMI forecasts 6.3% CAGR for the United States commercial sourdough preparation market from 2026 to 2036. The market argument concerns differentiated bakery products and the preparations used to make them consistently, rather than a forecast of new legal protection for the word sourdough. Processors selling several bread formats can compare supplied cultures and dried preparations against their actual production requirements. The absence of a separate standard also makes a clear description of the product's fermentation route useful in commercial specifications.
A particular preparation's performance still needs evidence. Academic literature describes variation in bread quality with the microorganisms, flour and fermentation conditions used [8], so a favourable result for one bread cannot certify every US sourdough recipe. Buyers considering claims about digestibility or nutrition need evidence appropriate to the finished product. FMI sees a commercial role for suppliers that combine ingredients with application support and clear records of the process tested. The forecast does not imply that regulation is the reason US growth trails the other profiled countries, nor that consumer willingness to pay follows automatically from a fermentation label.
Who are the notable companies in the Sourdough Market?
Lesaffre, Lallemand, Puratos and IREKS are among the suppliers FMI follows in the sourdough market. The wider company coverage also includes AB Mauri, Bakels, Ernst Bocker, Philibert Savours and GoodMills Innovation. These names describe the report's coverage rather than a ranking or a disclosure of audited market shares.
The verified activities show two different approaches to product development. Puratos's February 2026 International Sourdough Symposium programme identified contributions on faba-bean flour sourdough and postbiotic-enriched sourdough [6]. That research agenda can inform formulation work, but a programme announcement does not demonstrate a finished product launch, clinical benefit or authorised claim. IREKS's iba 2025 material instead presents grain-specific commercial formulations, including durum, sprouted-seed, oat and buckwheat formats containing sourdough [7]. Its product range provides application choices without establishing sales in each segment.
FMI sees competition in how suppliers turn those capabilities into consistent results for the purchasing bakery. Research, ingredient manufacture and application support serve different parts of that task. A supplier's broader fermentation portfolio may be relevant, but buyers still need performance evidence for the actual preparation, flour mix and production process being purchased.
Key Developments in the Sourdough Market
- 10 March 2026: Puratos and Dawn Foods announced a definitive agreement under which Puratos intended to acquire Dawn Foods, subject to customary regulatory approvals. The announcement identified Puratos's fermentation and sourdough capabilities alongside Dawn's bakery applications and distribution network; it expected completion by the end of 2026 [13].
Key Players in the Sourdough Market
- Lesaffre
- Lallemand
- AB Mauri
- Puratos
- IREKS
- Bakels
- Ernst Bocker
- Philibert Savours
- GoodMills Innovation
Sourdough Market Report Scope
Table 6: Sourdough Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Commercial sourdough starters and preparations, including live cultures, liquid ferments, dried sourdough and sourdough-containing bakery mixes. |
| Nature | Conventional; Organic |
| End-Use | Food Processing Industry; Food Service Industry; Retail |
| Starter Culture | Type III; Type II; Type I |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | United Kingdom, Japan, Germany, South Korea, United States |
| Companies covered | Lesaffre; Lallemand; AB Mauri; Puratos; IREKS; Bakels; Ernst Bocker; Philibert Savours; GoodMills Innovation |
| Market analysis | Demand drivers, restraints, opportunities, purchasing rules and operational constraints. |
| Quantitative Units | USD billion |
| Revenue boundary and exclusions | First external sale of the commercial preparation or mix. Excludes finished bread and other finished bakery goods, distributor resales, and separately counted flour, yeast or intermediate ingredients already embodied in that preparation. |
Source: Future Market Insights
Sourdough Market Research Methodology
The Sourdough Market assessment covers commercial starters, preparations and sourdough-containing mixes by nature, end use, starter culture and region. Secondary review of the cited regulatory documents, academic research and company disclosures establishes product and purchasing context. FMI's numerical assessments are reconciled across the market-size table, segment comparisons, country forecasts and FAQ answers. Checks cover currency, units, periods, classifications and share complements. Downstream bread examples explain applications within the commercial-preparation scope.
Sourdough Market by Segments
Sourdough Market segmented by Nature:
- Conventional
- Organic
Sourdough Market segmented by End-Use:
- Food Processing Industry
- Food Service Industry
- Retail
Sourdough Market segmented by Starter Culture:
- Type III
- Type II
- Type I
Sourdough Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Western Europe
- Eastern Europe
- Poland
- Russia
- Rest of Eastern Europe
- East Asia
- Japan
- South Korea
- China
- South Asia and Pacific
- India
- Australia and New Zealand
- ASEAN
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] 21 CFR Part 136, Bakery Products. U.S. Food and Drug Administration, Code of Federal Regulations. Accessed 2 November 2026.
- [2] Bread and Flour: Labelling and Composition. UK Government guidance, published 23 April 2025.
- [3] UK Government. Summary of responses and government response: amending the Bread and Flour Regulations. Updated 17 January 2024. Consultation held 1 September to 23 November 2022.
- [4] Pane di Altamura PDO Specification. European Commission eAmbrosia Geographical Indications Register, registered under Regulation (EEC) No. 1291/2003. Accessed 2 November 2026.
- [5] USDA Foreign Agricultural Service. Japan publishes guidelines on the use of No Food Additive Used labeling. GAIN report JA2022-0095, 2022.
- [6] Sourdough Symposium. Puratos company newsroom, 9th International Sourdough Symposium, Brussels, 23 to 27 February 2026. Programme announcement published 9 February 2026.
- [7] IBA 2025: It's Your Choice. IREKS GmbH company newsroom, product launch coverage. Accessed 2 November 2026.
- [8] Sourdough Bread Quality: Facts and Factors. Foods, 2024, volume 13, article 2132. doi:10.3390/foods13132132. Open academic review.
- [9] Paris Baguette Singapore. Paran Label product and menu page. Accessed 2 November 2026.
- [10] Landis et al. The diversity and function of sourdough starter microbiomes. eLife, 26 January 2021, 10:e61644. doi:10.7554/eLife.61644.
- [11] French Republic. Decree 93-1074 of 13 September 1993, Article 4. Current text on Legifrance, accessed 2 November 2026.
- [12] Canadian Food Inspection Agency. Labelling and composition requirements for grain and bakery products. Accessed 2 November 2026.
- [13] Puratos. Puratos to Acquire Dawn Foods. Company announcement, 10 March 2026. Accessed 2 November 2026.
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use, 2026 to 2036
- Food Processing Industry
- Food Service Industry
- Retail
- Y-o-Y Growth Trend Analysis By End-Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use, 2026 to 2036
- Global Market Analysis and Forecast, By Starter Culture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Starter Culture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Starter Culture, 2026 to 2036
- Type III
- Type II
- Type I
- Y-o-Y Growth Trend Analysis By Starter Culture, 2021 to 2025
- Absolute $ Opportunity Analysis By Starter Culture, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Rest of Latin America
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Western Europe
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Russia
- Rest of Eastern Europe
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia and New Zealand
- ASEAN
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- By Nature
- By End-Use
- By Starter Culture
- By Country
- Market Attractiveness Analysis
- By Country
- By Nature
- By End-Use
- By Starter Culture
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Nature
- By End-Use
- By Starter Culture
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Nature
- By End-Use
- By Starter Culture
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Puratos
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- IREKS
- Paris Baguette (SPC Group)
- Lesaffre
- Lallemand
- AB Mauri
- Bakels
- Ernst Bocker
- Philibert Savours
- GoodMills Innovation
- Puratos
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Nature, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by End-Use, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Starter Culture, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Nature
- Figure 6: Global Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End-Use
- Figure 9: Global Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Starter Culture
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Nature
- Figure 26: North America Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by End-Use
- Figure 29: North America Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Starter Culture
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Nature
- Figure 36: Latin America Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by End-Use
- Figure 39: Latin America Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Starter Culture
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Nature
- Figure 46: Western Europe Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by End-Use
- Figure 49: Western Europe Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Starter Culture
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by End-Use
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Starter Culture
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Nature
- Figure 66: East Asia Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by End-Use
- Figure 69: East Asia Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Starter Culture
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Nature
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by End-Use
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Starter Culture
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Nature
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by End-Use, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by End-Use
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Starter Culture, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Starter Culture, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Starter Culture
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the sourdough market in 2026?
The commercial sourdough preparation market is valued at USD 6.6 billion in 2026 and is forecast to reach USD 14.5 billion by 2036, at an 8.1% CAGR from 2026 to 2036.
Which segment leads the sourdough market by Nature?
Conventional sourdough leads with 79.9% of Nature revenue in 2026, against 20.1% for Organic.
Which end-use and starter culture lead the sourdough market?
Food Processing Industry leads End-Use revenue with 53.0% in 2026, and Type III leads Starter Culture with 50.0%, in FMI's assessment. These are distinct classifications, alongside Conventional's 79.9% share by Nature.
Which country has the fastest-growing sourdough market?
The United Kingdom has the fastest CAGR among the countries FMI tracks in detail, at 10.5% between 2026 and 2036, ahead of Japan at 10.2% and Germany at 8.7%.
What should bakeries check before buying dried sourdough?
Confirm whether the preparation supplies flavour or qualifying leavening activity. France's dehydrated-levain provisions require live flora and proper leavening after rehydration [11]. Buyers targeting that function need the corresponding viability and performance documentation, rather than treating all dried preparations as interchangeable.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
