
- Market Size (2026)
- USD 112.8 Bn
- Forecast (2036)
- USD 211.7 Bn
- CAGR (2026 to 2036)
- 6.5%
How big is the Styrenics Market in 2026?
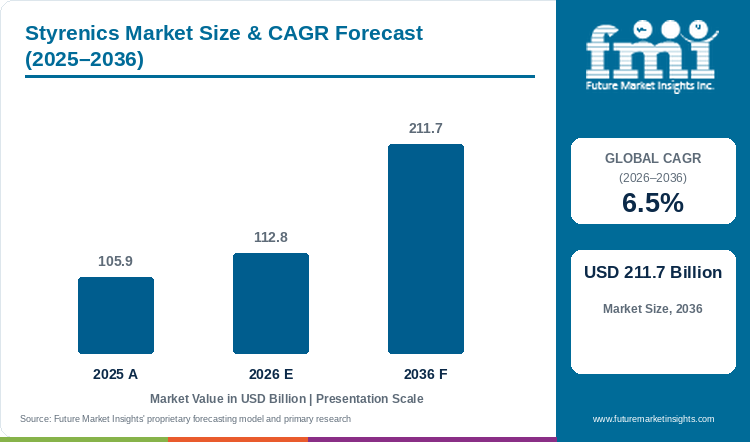
The global styrenics market is estimated at USD 112.8 billion in 2026, compared with USD 105.9 billion in 2025, and is forecast to reach USD 211.7 billion by 2036, expanding at a CAGR of 6.5% from 2026 to 2036.
As per FMI's analysis, packaging and building programmes are adding to resin orders. INEOS Styrolution reported on 26 August 2025 that sour cream cups made with 30% recycled polystyrene had been on sale in ALDI SÜD stores across Germany since the beginning of that year. BASF will add 50,000 tonnes of Neopor capacity at Ludwigshafen, bringing it to 250,000 tonnes a year from the beginning of 2027.
Excess capacity is changing where converters buy resin. On 18 June 2026 INEOS Styrolution announced the closure of its Channahon, Illinois polystyrene plant, which has about 400,000 tonnes of annual capacity, citing industry oversupply and margin pressure. Its North American polystyrene production will continue at Decatur, Alabama and Altamira, Mexico, so converters in the region will be served from those two plants.
Market Size & Forecast
Table 1: Styrenics Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 Value | USD 105.9 billion |
| Estimated market size in 2026 | USD 112.8 billion |
| Projected market size by 2036 | USD 211.7 billion |
| CAGR (2026-2036) | 6.5% |
| Added revenue, 2026 to 2036 | USD 98.9 billion |
Key Market Trends & Insights
- Polystyrene is estimated to account for 34.8% of styrenics demand by polymer type in 2026.
- Packaging is expected to hold 29.6% of demand by application in 2026.
- INEOS Styrolution's recycled polystyrene, at 30% of the material in each cup, is now in sour cream packaging sold by ALDI SÜD across Germany.
- BASF's Neopor capacity at Ludwigshafen will rise by 50,000 tonnes to 250,000 tonnes a year from the beginning of 2027.
- INEOS Styrolution will close its 400,000-tonne Channahon polystyrene plant by the fourth quarter of 2026.
- Japan's polystyrene imports in January to July 2026 were 22% higher than a year earlier.
Regional Highlights
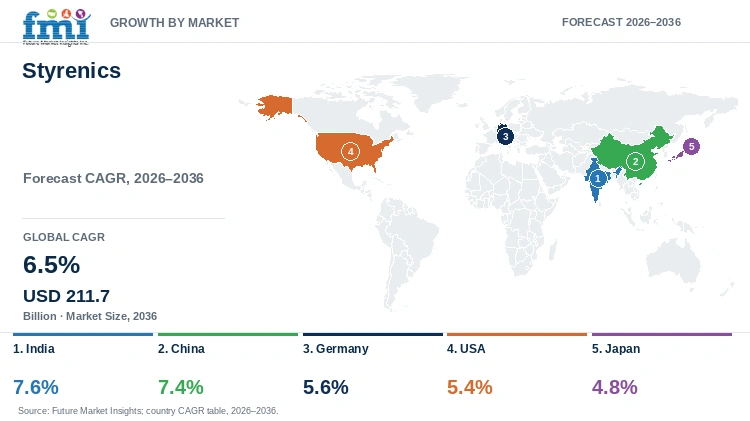
- India is likely to grow at a 7.6% CAGR during the forecast period, followed by China at 7.4%, Germany at 5.6%, the USA at 5.4% and Japan at 4.8%.
Analyst Perspective
“Oversupply is putting pressure on styrenics margins while converters prepare recycled-content packaging. Documented recycled content and successful processing trials give resin producers a stronger case for repeat orders as customers review their sourcing after plant closures.”
- Nikhil Kaitwade, Principal Consultant, FMI
How is the Styrenics Market segmented?
The Styrenics Market is segmented by polymer type, application and region.
- By Polymer Type: Polystyrene, Styrene Butadiene Rubber, Acrylonitrile Butadiene Styrene (ABS), Unsaturated Polyester Resin and Others.
- By Application: Automotive, Electrical and Electronics, Building and Construction, Packaging, Consumer Products and Others.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why is Polystyrene the Leading Polymer Type in the Styrenics Market?
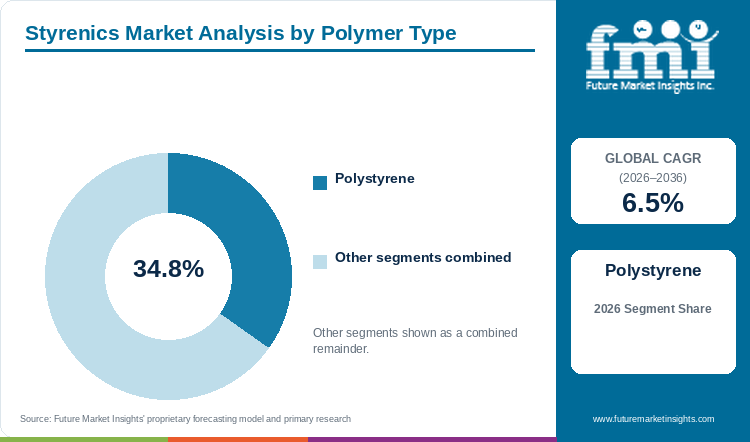
Polystyrene accounts for an estimated 34.8% of styrenics demand by polymer type in 2026, equal to about USD 39.3 billion, as per FMI's analysis.
Table 2: Polymer Type Share for the Styrenics Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Polystyrene | 34.8% |
| Other segments combined | 65.2% |
Packaging and foam uses are the main outlets for polystyrene. In August 2026, packaging took 15,300 tonnes and foam styrene uses 9,600 tonnes of the 32,600 tonnes shipped to domestic customers in Japan. Orders from both outlets repeat for as long as the customer's package or product stays in production.
Insulation is a separate outlet. BASF said on 1 July 2025 that it was focusing its strategy on expandable polystyrene under the Neopor and Styropor brands and wanted to expand its EPS business, and its Neopor expansion at Ludwigshafen is aimed at EPS insulation materials for building renovation.
However, polystyrene does not meet every requirement. Styrene butadiene rubber, ABS, unsaturated polyester resin and other polymers share the remaining 65.2% of demand. A customer that has approved ABS for a molded part must requalify the part before changing material, so the share of polystyrene depends on packaging and insulation orders rather than on price alone.
Producers best placed to hold this share match grades to the customer's forming equipment, document the recycled content of each grade and keep insulation grades apart from packaging grades.
Why is Packaging the Leading Application in the Styrenics Market?
Packaging is estimated to hold 29.6% of styrenics demand by application in 2026, as per FMI's analysis.
Table 3: Application Share for the Styrenics Market (percentage share of revenue), 2026
| Segment | Share (2026) |
|---|---|
| Packaging | 29.6% |
| Other segments combined | 70.4% |
INEOS Styrolution described the sour cream cups sold by ALDI SÜD as its second commercial roll-out of food-grade recycled polystyrene with a leading German retailer. The cups contain 30% recycled polystyrene, and ALDI SÜD and Unternehmensgruppe Theo Müller are the development partners.
A converter that has qualified a recycled grade for one package has limited incentive to change it, so each retailer programme produces repeat orders for the same resin.
However, one approved cup does not cover other formats. Regulation (EU) 2025/40 sets different minimum recycled content for contact-sensitive plastic packaging and for other plastic packaging, so each new format needs its own evidence of recycled content.
Producers best placed provide the resin that fits the package, support trials on the converter's line and keep the specification unchanged in later deliveries.
What are the Key Drivers, Restraints and Opportunities in the Styrenics Market?
The styrenics market is expected to grow from USD 112.8 billion in 2026 to USD 211.7 billion by 2036, which adds USD 98.9 billion over the forecast period. Recurring packaging and building orders support demand, while oversupply and thin margins limit what producers can charge, and recycled-content grades are the main opportunity.
Driver: building and packaging programmes that reorder the same resin. BASF expects demand for materials used in energy-efficient building renovation to increase significantly, and it is adding Neopor capacity to meet it. Packaging converters reorder an approved grade for as long as the package stays in production, so the volume depends on how many packages remain in production.
Restraint: oversupply and thin margins. INEOS Styrolution cited persistent margin pressure and industry oversupply when it decided to close its Channahon plant. Adjusted EBITDA at Americas Styrenics was USD 1 million in the second quarter of 2026, USD 7 million below the prior year, because of higher benzene costs and soft end market demand.
Opportunity: recycled-content grades. Regulation (EU) 2025/40 sets minimum recycled content for plastic packaging from 2030, and retailers are already specifying it, as the ALDI SÜD cups show. Suppliers that can document recycled content for each grade and plant have the strongest opportunity with converters preparing for those minimums.
Suppliers that keep grades consistent and document recycled content are best placed to win a share of the USD 98.9 billion added between 2026 and 2036.
How do Packaging Rules and Customer Specifications Influence Demand?
Packaging rules and customer specifications decide which resin a converter can approve. They act at two points: the recycled content required in a package and the surface finish required in a molded part.
Recycled content in plastic packaging
Regulation (EU) 2025/40 applies from 12 August 2026. By 1 January 2030, or three years after the relevant implementing act enters into force if that is later, plastic packaging must contain a minimum share of recycled content recovered from post-consumer plastic waste, measured as an average per manufacturing plant and year. The minimum is 10% for contact-sensitive packaging made from plastics other than PET, excluding single-use beverage bottles, and 35% for other plastic packaging. By 1 January 2040 the minimums rise to 25% and 65%. A producer of polystyrene grades therefore needs recycled feedstock that meets the post-consumer definition and a way to show the recycled content of each grade to converters.
Finish and performance of durable parts
Appearance is a purchasing condition for visible parts. LG Chem described low gloss ABS for appliance and automotive parts on 4 July 2025. A converter making such parts checks that a resin gives the specified finish on its existing tools before moving a part to a new grade, and a supplier that cannot hold the finish across batches is excluded from the order.
Together, these conditions favor suppliers that can show recycled content for packaging and hold a specified finish for durable parts. They also limit how far a grade approved for one use can be sold into another.
What Technical and Operational Constraints Affect Styrenics Supply?
The constraints sit at several stages, from feedstock cost to delivery of the finished grade, and more nominal capacity does not resolve each of them.
The first is feedstock cost and availability. Styrene prices stayed volatile in the second quarter of FY2027, and Supreme Petrochem, which received no supplies from the Gulf region, is establishing alternate sources for all its imported raw materials.
The second is plant availability. Trinseo reported a force majeure at its Tessenderlo polystyrene site from the end of March to the beginning of May 2026 after storm damage, with operations fully restored by the end of May. A converter on a single-source contract has no resin for that period unless a second grade is already qualified.
The third is logistics. Supreme Petrochem's export volumes were considerably lower than a year earlier because of higher ocean freight rates, longer voyage times, price volatility and limited availability of styrene.
The fourth is the timing of new capacity. BASF's additional Neopor capacity is expected from the beginning of 2027, and Supreme Petrochem's projects at Amdoshi are scheduled for completion between March 2027 and March 2029, so announced capacity adds to supply only once it is running.
Producers with dependable operation and a qualified second source for key grades have an advantage with converters, while distributors can serve smaller buyers that need manageable quantities.
Where are the Commercial Opportunities for Styrenics Suppliers?
The opportunities lie in recycled packaging grades, insulation and local supply to markets that rely on imports, and each needs an offer built for a particular customer rather than more volume alone.
The first is recycled polystyrene for defined packages. Retailers are already specifying recycled content, and the 2030 minimums in Regulation (EU) 2025/40 apply that requirement to a wider range of formats. Suppliers that document recycled content by grade and plant can support converters across several formats.
The second is expandable polystyrene for building renovation. A supplier serving this business must match the thermal and processing requirements of the building system and the delivery schedule of construction customers.
The third is local supply to markets that rely on imports. Japan's rising polystyrene imports and India's duty-free imports of polystyrene and ABS show that converters buy abroad when local prices allow. Domestic producers that offer consistent grades and technical support retain customers when import prices fall.
Styrenics Market by Country (2026 to 2036)
Table 4: Country Growth Outlook for the Styrenics Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026-2036) |
|---|---|
| India | 7.6% |
| China | 7.4% |
| Germany | 5.6% |
| USA | 5.4% |
| Japan | 4.8% |
What is supporting styrenics demand in India?
India is likely to grow at a 7.6% CAGR during the forecast period, the highest rate among the countries analysed.
Domestic production is concentrated in a few plants. Supreme Petrochem's Amdoshi complex in Maharashtra has installed capacity of 300,000 tonnes a year of polystyrene, 115,000 tonnes of expandable polystyrene and 70,000 tonnes of ABS. Local capacity is an advantage for converters that need short supply lines. The disadvantage is exposure to imports: duty-free imports of polymers were allowed until 15 July 2026, and large volumes of polystyrene and ABS arrived from ASEAN countries and China, which put pressure on local selling prices in the first two months of the second quarter of FY2027.
Growth is likely to follow new local capacity. Supreme Petrochem has projects worth INR 900 crore (USD 95 million) under way at Amdoshi, including an 80,000-tonne-a-year polystyrene line and a 70,000-tonne second phase of its ABS project, with completion scheduled between March 2027 and March 2029. Its sales volume rose by about 24% year on year to 95,242 tonnes in the second quarter of FY2027, although half-year volume fell by 2.8% to 166,085 tonnes on lower exports.
Why does ABS capacity matter for styrenics demand in China?
China is likely to grow at a 7.4% CAGR during the forecast period, the second highest rate among the countries analysed.
China added ABS capacity quickly. PetroChina scheduled a 600,000-tonne-a-year ABS plant at Jilin City to start in mid-November 2025, after Shandong Yulong, Daqing Petrochemical and Shandong Yike had started plants of 300,000, 200,000 and 225,000 tonnes a year between May and July. INEOS Styrolution's joint venture ABS plant at Ningbo, with a capacity of 600,000 tonnes a year, was being started up and optimised in 2024. A large local supply base is an advantage for converters that buy ABS in China. The disadvantage is borne by producers: losses averaged CNY 971 (USD 146) a tonne by mid-September 2026 and forced major producers to cut output.
Expansion halted in 2026. No new ABS plants came online in China in 2026, and only Sinopec Shanghai Gaoqiao Petrochemical added capacity, from 200,000 to 300,000 tonnes a year. Production cuts lifted prices by 30% from July to September 2026. Demand growth is likely to be absorbed by existing plants before new ones are justified.
What are the key sources of styrenics demand in Germany?
Germany is likely to grow at a 5.6% CAGR during the forecast period.
Insulation demand follows building activity, which is recovering from a low base. Permits were issued for 126,300 dwellings in the first half of 2026, 15.1% more than a year earlier but about 31% fewer than the 182,800 issued in the first half of 2016. The low base is a disadvantage for insulation resin. The advantage is local production: BASF makes Neopor at Ludwigshafen and expects demand for materials used in energy-efficient building renovation to increase significantly.
Growth is likely to follow renovation and packaging together. Permits in June 2026 were 13.8% higher than a year earlier, and German retailers are already selling food in recycled polystyrene cups, ahead of the minimum recycled content that Regulation (EU) 2025/40 sets from 2030.
Where does supply consolidation affect styrenics demand in the USA?
The USA is likely to grow at a 5.4% CAGR during the forecast period.
Producers are reducing polystyrene capacity because margins are weak. INEOS Styrolution said on 18 June 2026 that it would close the Channahon plant, and its North American polystyrene production will continue at Decatur, Alabama and Altamira, Mexico. Capacity leaving the market is an advantage for the producers that remain, because it reduces oversupply. The disadvantage is borne by converters served from Channahon, which must move to other plants and delivery routes before the closure is completed in the fourth quarter of 2026.
More supply changes are likely. Trinseo restarted the sale of its 50% interest in Americas Styrenics with its joint venture partner in the second quarter of 2026. Growth over the forecast period is likely to depend on a recovery in the durable goods and packaging demand that Americas Styrenics described as soft in that quarter.
How does import competition influence styrenics demand in Japan?
Japan is likely to grow at a 4.8% CAGR during the forecast period, the lowest rate among the countries analysed.
Domestic polystyrene shipments were lower in August 2026. Shipments to domestic customers were 32,600 tonnes, 4% below August 2025, and imports in the first seven months of 2026 totalled 50,600 tonnes, 22% more than a year earlier. Rising imports against falling shipments are a disadvantage for domestic producers. The advantage lies in recycling: Denka and its affiliate Toyo Styrene completed a plant at Denka's Chiba site on 19 March 2024 that depolymerises used polystyrene into styrene monomer for repolymerisation, with a processing capacity of about 3,000 tonnes a year.
Growth is likely to stay the lowest of the five while domestic shipments lag production. Polystyrene production rose by 7% year on year to 49,500 tonnes in August 2026 against the 4% fall in domestic shipments, and stocks of 100,900 tonnes were 13% higher than a year earlier, equal to 2.9 months of shipments.
Who are the notable companies in the Styrenics Market?
The companies are positioned at different points of the styrenics chain. INEOS Styrolution and Supreme Petrochem sell polystyrene, BASF sells expandable polystyrene for insulation, LG Chem sells ABS and Trinseo holds a 50% interest in Americas Styrenics. The positions are not equivalent in capacity, and no global share ranking is implied.
INEOS Styrolution sells recycled polystyrene into dairy packaging in Germany and is closing its Channahon plant in the United States. BASF completed the transfer of its Styrodur business to BACHL with effect from 30 June 2025 and retained its Styropor and Neopor EPS brands.
Trinseo, which is in Chapter 11 proceedings in the Southern District of Texas, restarted the sale of its Americas Styrenics interest, while Supreme Petrochem is building new capacity in India. LG Chem sells ABS, including low gloss grades for appliance and automotive parts.
A comparison starts with the polymer and the article the customer makes. The companies to watch are those that maintain dependable supply and consistent grades within their own segment.
Key Developments in the Styrenics Market
- On 23 October 2026, Supreme Petrochem reported INR 900 crore (USD 95 million) of capacity projects at Amdoshi, including an 80,000-tonne-a-year polystyrene line, scheduled for completion between March 2027 and March 2029.
- On 6 August 2026, Trinseo reported that Americas Styrenics earned an adjusted EBITDA of USD 1 million in the second quarter and that the sale of its interest had restarted.
- On 18 June 2026, INEOS Styrolution announced the closure of its Channahon, Illinois polystyrene plant, which has about 400,000 tonnes of annual capacity.
- On 26 August 2025, INEOS Styrolution reported that sour cream cups with 30% recycled polystyrene had been on sale in ALDI SÜD stores across Germany since the beginning of the year.
- On 1 July 2025, BASF completed the Styrodur transfer to BACHL and announced that Neopor capacity at Ludwigshafen would rise by 50,000 tonnes to 250,000 tonnes a year from the beginning of 2027.
Key Players in the Styrenics Market
- INEOS Styrolution
- BASF
- Trinseo
- LG Chem
- Supreme Petrochem
Styrenics Market Report Scope
Table 5: Report Scope for the Styrenics Market (coverage fields and definitions), 2026 to 2036
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Polymer Type (Polystyrene, Styrene Butadiene Rubber, Acrylonitrile Butadiene Styrene (ABS), Unsaturated Polyester Resin, Others); Application (Automotive, Electrical and Electronics, Building and Construction, Packaging, Consumer Products, Others) |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2036 |
| Market Definition | Commercial sales of styrenic polymers across polystyrene, styrene butadiene rubber, ABS, unsaturated polyester resin and other styrenic materials. Polystyrene includes solid and expanded forms. It excludes upstream styrene monomer sold as feedstock and the revenue of finished articles. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | India, China, Germany, USA and Japan |
| Key Companies Covered | INEOS Styrolution, BASF, Trinseo, LG Chem and Supreme Petrochem |
| Forecast Period | 2026 to 2036 (with 2025 historical baseline) |
| Approach | Combined primary interviews, secondary literature analysis, and top-down data triangulation |
Styrenics Market - Research Methodology
The market assessment combines primary interviews with industry participants and secondary research drawn from company disclosures, trade data and industry publications. Market size is built from supply-side and demand-side estimates and validated top-down, and segment shares and competitive positioning are checked through data triangulation before publication.
Styrenics Market by Segments
By Polymer Type
- Polystyrene
- Styrene Butadiene Rubber
- Acrylonitrile Butadiene Styrene (ABS)
- Unsaturated Polyester Resin
- Others
By Application
- Automotive
- Electrical and Electronics
- Building and Construction
- Packaging
- Consumer Products
- Others
By Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] INEOS Styrolution. INEOS Styrolution expands its supply of recycled polystyrene for dairy packaging across German supermarkets. 26 August 2025.
- [2] BASF. BASF and BACHL complete transfer of Styrodur business to BACHL. 1 July 2025.
- [3] INEOS Styrolution. INEOS Styrolution announces closure of polystyrene site in Channahon, Illinois. 18 June 2026.
- [4] Japan Styrene Industry Association. Overview of PS and SM results for August 2026. 16 September 2026.
- [5] BASF. BASF invests in increasing production capacity of Neopor at Ludwigshafen site. 24 October 2024.
- [6] European Parliament and Council of the European Union. Regulation (EU) 2025/40 on packaging and packaging waste, Articles 7 and 71. 19 December 2024.
- [7] Trinseo PLC. Trinseo Reports Second Quarter 2026 Financial Results (Exhibit 99.1 to Form 8-K). 6 August 2026.
- [8] LG Chem. FOCUS ON: Low Gloss ABS. 4 July 2025.
- [9] Supreme Petrochem Limited. Earnings Presentation Q2/H1 FY2027. 23 October 2026.
- [10] OPIS. PetroChina's new Jilin ABS plant set to pressure markets. 12 November 2025.
- [11] INEOS. INEOS in review 2024. 2025.
- [12] Mysteel Global. Losses trigger production cuts and Chinese ABS prices see partial recovery. 15 September 2026.
- [13] Statistisches Bundesamt (Destatis). Baugenehmigungen für Wohnungen im Juni 2026: +13,8 % zum Vorjahresmonat, press release no. 291. 18 August 2026.
- [14] Denka Company Limited. Denka Launches Japan's Largest Polystyrene Chemical Recycling Plant in Cooperation with Governments. 19 March 2024.
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Polymer Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Polymer Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Polymer Type, 2026 to 2036
- Polystyrene
- Styrene Butadiene Rubber
- Acrylonitrile Butadiene Styrene (ABS)
- Unsaturated Polyester Resin
- Others
- Y-o-Y Growth Trend Analysis By Polymer Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Polymer Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Automotive
- Electrical and Electronics
- Building and Construction
- Packaging
- Consumer Products
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Polymer Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Polymer Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Polymer Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Polymer Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- INEOS Styrolution
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- BASF
- Trinseo
- LG Chem
- Supreme Petrochem
- INEOS Styrolution
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 7: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Billion) Forecast by Polymer Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Polymer Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Polymer Type
- Figure 23: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Application
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Polymer Type
- Figure 30: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by Application
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Polymer Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by Application
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Polymer Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by Application
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Polymer Type
- Figure 51: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by Application
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Polymer Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Polymer Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Polymer Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Polymer Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
What is the size of the Styrenics Market?
The global styrenics market was valued at USD 105.9 billion in 2025 and is estimated at USD 112.8 billion in 2026. It is forecast to reach USD 211.7 billion by 2036, expanding at a CAGR of 6.5% from 2026 to 2036.
Which polymer type and application lead the Styrenics Market?
Polystyrene is estimated to account for 34.8% of demand by polymer type in 2026, while packaging is estimated to account for 29.6% by application.
Which country is likely to grow fastest in the Styrenics Market?
India is likely to grow at a 7.6% CAGR during the forecast period, followed by China at 7.4%, Germany at 5.6%, the USA at 5.4% and Japan at 4.8%.
Does the market include styrene monomer?
No. Upstream styrene monomer sold as feedstock is excluded, as is the revenue of finished packaging and insulation products. The market covers sales of styrenic polymers.
What recycled content does the EU require in plastic packaging?
Regulation (EU) 2025/40 sets a minimum of 10% recycled content for contact-sensitive plastic packaging other than PET and 35% for other plastic packaging by 1 January 2030, or three years after the relevant implementing act enters into force if that is later. [6]
Why do plant closures matter to converters?
A closure such as INEOS Styrolution's Channahon plant, with about 400,000 tonnes of annual capacity, ends supply from that site and moves customers to other plants and delivery routes. [3] Competitive Analysis of the Styrenics Market Key Players
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
