
- Market Size (2026)
- USD 22.8 Bn
- Forecast (2036)
- USD 34.7 Bn
- CAGR (2026 to 2036)
- 4.3%
How big is Syringes Market in 2026?
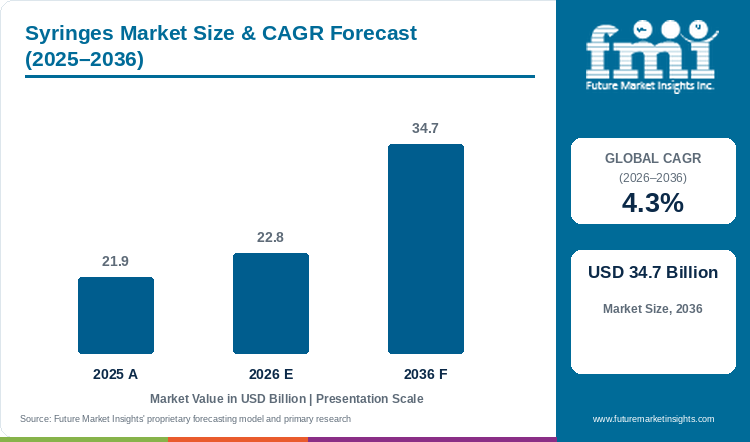
Sales in the syringes market are projected to grow at 4.3% CAGR, with the market size rising from USD 21.9 billion in 2025 to USD 22.8 billion in 2026 and reaching USD 34.7 billion by 2036.
Hospital medication dosing errors and rising biologic viscosity have compelled healthcare networks to replace manual vial drawing with prefilled injection systems. According to Future Market Insights analysis, the global syringes market stands at USD 21.9 billion in 2025 and rises to USD 22.8 billion in 2026. Valuation is projected to reach USD 34.7 billion by 2036 at a 4.3% CAGR, generating USD 11.9 billion in added revenue. In January 2025, the World Health Organization reported over 16.0 billion annual medical injections worldwide, reinforcing demand for single-use sterile medical devices. Rigid containers & bottles hold 39.8% share in 2026 as nested tubs prevent barrel breakage. Country CAGRs span 3.4% in Australia to 5.2% in France.
Key Market Trends & Insights
- By packaging format: Rigid containers & bottles led with 39.8% share in 2026, underpinned by sterile nested tubs and blister trays that prevent glass and polymer barrel breakage during filling.
- By material substrate: Recycled paperboard accounted for 41.9% in 2026, supported by serialized secondary folding cartons and tamper-evident hospital dispensary multi-packs.
- By end-use sector: Food & beverage held 40.3% in 2026, driven by high-precision analytical sampling syringes deployed across chromatography and microbiological food safety laboratories.
Regional Highlights
- Fastest-growing evaluated country: France, at 5.2% CAGR from 2026 to 2036.
- By country: Canada at 4.8%, the USA at 4.5%, and Mexico at 4.1% follow, while Australia records the lowest evaluated CAGR at 3.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Syringes Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 21.9 billion |
| Estimated Market Size in 2026 | USD 22.8 billion |
| Projected Market Size by 2036 | USD 34.7 billion |
| CAGR, 2026 to 2036 | 4.3% |
| Added Revenue, 2026 to 2036 | USD 11.9 billion |
Adoption develops differently across countries because national sharps-injury laws and outpatient biologic reimbursement rules directly govern hospital purchasing budgets and tender specifications. FMI research indicates that parenteral device makers face strict extractables limits and cleanroom validation bottlenecks when scaling prefillable barrels. In February 2026, United States Food and Drug Administration requirements on essential drug delivery outputs took effect for injectors and syringe combination products to guarantee dose accuracy and break-loose force consistency. As a result, medical device manufacturers are replacing commodity hypodermics with retractable needle safety syringes and ready-to-fill nested polymer tubs that protect biologic stability while preventing occupational needlestick injuries.
Injection Volume and Device-Requirement Sizing
Table 2: Injection Volume and Device-Requirement Sizing for the Syringes Market (USD billion and unit ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 21.9 | 22.8 | 34.7 |
| Sterile syringes manufactured (billion units) | 54.0 to 58.0 | 58.0 to 62.0 | 88.0 to 96.0 |
| Prefilled syringe units filled (billion) | 9.5 to 10.5 | 10.5 to 11.6 | 21.0 to 24.0 |
| Spend per hospital bed (USD) | 118.0 to 128.0 | 126.0 to 138.0 | 205.0 to 228.0 |
Operational note: Unit volumes reflect global clinical injection procedures and laboratory analytical sampling demand. Prefilled volumes reflect ongoing migration of monoclonal antibodies, vaccines, and metabolic therapies into ready-to-administer barrels. Figures represent operational scenario ranges for capacity planning rather than metered registry counts.
Per Capita and Healthcare-Facility Sizing
Sterile injection devices and primary containment formats have expanded across acute hospitals, outpatient clinics, and analytical testing laboratories to balance operator safety with volumetric precision. Rising subcutaneous biologics adoption converts routine administration into recurring procurement of safety needles and prefilled auto-injectors. In December 2025, the European Medicines Agency updated scientific guidelines governing excipient labeling and primary container quality documentation for human medicinal products. Hospital procurement teams therefore audit sub-visible particulate counts, plunger glide force, and sterile barrier integrity before approving supplier contracts.
Table 3: Per Capita and Healthcare-Facility Spending Indicators for the Syringes Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 2.7 | 2.7 | 3.9 |
| Spend per 1,000 people (USD) | 2,670.7 | 2,747.0 | 3,855.6 |
| Spend per hospital (USD thousand) | 126.0 to 138.0 | 132.0 to 145.0 | 195.0 to 215.0 |
Table 4: Hospital and Clinic Spending Indicators for the Syringes Market (USD and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 22.8 billion | Report value |
| Hospitals worldwide (thousand) | 165.0 | 2025 industry estimate |
| Market spend per hospital | USD 138.2 thousand | Facility allocation ratio |
| Food & beverage end-use revenue, 2026 | USD 9.2 billion | 40.3% share |
Analyst Perspective
"Prefilled polymer barrels and ready-to-use nested tubs allow pharmaceutical fillers to run high-speed biologics lines with minimal glass breakage. Silicone-oil migration and extractables validation still require extensive stability testing before hospital formulary approval."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the syringes market segmented?
The syringes market is segmented by packaging format, material substrate, and end-use sector. In 2026, rigid containers & bottles are projected at 39.8%, recycled paperboard at 41.9%, and food & beverage at 40.3%.
By packaging format: Rigid containers & bottles, flexible wraps & bags, and secondary bulk packaging.
By material substrate: Recycled paperboard, thermoplastic polymers, sustainable plant fibers, and specialty alloys.
By end-use sector: Food & beverage, pharmaceuticals & healthcare, personal care & homecare, and industrial manufacturing.
What positions Rigid Containers & Bottles ahead in packaging format?
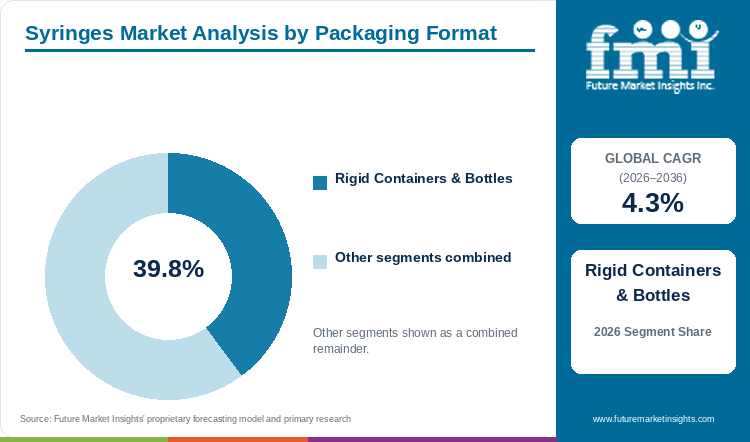
Rigid containers & bottles are expected to hold 39.8% of packaging format demand in 2026, underpinned by nested tub protection.
Table 5: Packaging Format Share for the Syringes Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 39.8% |
| Other Segments Combined | 60.2%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Syringes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.3% |
| Leading Segment | Rigid Containers & Bottles |
Pharmaceutical fill-finish plants depend on rigid nested tubs and thermoformed blister trays to isolate prefillable glass and cyclic olefin polymer barrels during aseptic processing. By suspending each barrel by its flange inside a rigid nest, manufacturers prevent glass-to-glass contact, flange chipping, and plunger displacement. Owing to the advantages associated with mechanical isolation, rigid containers & bottles hold 39.8% of packaging format demand in 2026, ahead of flexible wraps & bags at 36.2% and secondary bulk packaging at 24.0%. In addition to this, sterile medical packaging tubs allow robotic de-nesting on high-speed lyophilization lines. However, bulky rigid tubs still increase cold-room storage volume.
- Rigid containers & bottles account for 39.8% of packaging format demand in 2026, supported by barrel flange isolation and automated aseptic filling compatibility.
- In January 2026, Stevanato Group completed commercial validation of robotic high-speed EZ-fill syringe tub and nest handling platforms for contract pharmaceutical fillers.
Why does Recycled Paperboard lead the material substrate category?
Recycled paperboard is projected to represent 41.9% of material substrate volume in 2026, reflecting serialized hospital folding carton demand.
While primary syringe barrels and blister webs rely on borosilicate glass and medical polymers, outer secondary folding cartons and hospital dispensary multi-packs consume vast tonnages of recycled paperboard. High-stiffness recycled boxboard provides smooth printing surfaces for two-dimensional DataMatrix serialization codes, tamper-evident glue flaps, and cold-chain dosage instructions. Consequently, recycled paperboard captures 41.9% of material substrate volume in 2026, outpacing thermoplastic polymers at 31.5%, sustainable plant fibers at 16.8%, and specialty alloys at 9.8%. Besides this, pharmaceutical plastic packaging converters pair mono-material blister trays with FSC-certified paperboard sleeves to meet hospital waste-reduction targets. High-humidity refrigeration can still soften unlaminated board edges.
- Recycled paperboard accounts for 41.9% of material substrate volume in 2026, driven by serialized secondary folding cartons and hospital circular procurement mandates.
- In February 2026, the Confederation of European Paper Industries documented stable pharmaceutical folding boxboard demand as hospital tenders prioritized fiber-based secondary cartons.
What keeps Food & Beverage ahead across end-use sectors?
Food & beverage applications are estimated to hold 40.3% of end-use sector volume in 2026, reinforced by chromatography sampling protocols.
Regulated food and beverage quality-control laboratories and automated fortification lines utilize large volumes of precision analytical sampling syringes and micro-dosing injectors. Gas and liquid chromatography autosamplers require borosilicate micro-liter syringes and sterile syringe filters to test raw milk, edible oils, and beverages for pesticide residues, mycotoxins, and volatile flavor compounds. As a result, food & beverage accounts for 40.3% of end-use sector volume in 2026, followed by pharmaceuticals & healthcare at 33.2%, personal care & homecare at 16.5%, and industrial manufacturing at 10.0%. Furthermore, with the use of single-use syringe formats, dairy and beverage plants prevent cross-batch microbial contamination during inline sampling.
- Food & beverage represents 40.3% of end-use sector volume in 2026, underpinned by automated chromatography sample preparation and microbiological safety testing.
- In October 2025, AOAC International updated official chromatography sample-preparation methods requiring precision glass micro-syringes for multi-residue pesticide screening in commercial food matrices.
What are the drivers, restraints, and opportunities in the syringes market?
In the syringes market, injectable biologics expansion and needlestick safety mandates will continue to support demand, silicone-oil protein aggregation and leachables scrutiny will constrain qualification, and cyclic olefin polymer barrels are expected to unlock deep-cold drug delivery through 2036.
- Driver:Expanding monoclonal antibody and GLP-1 therapeutic pipelines alongside mandatory sharps-injury laws drive recurring procurement of prefilled and safety-engineered syringes.
- Restraint:Silicone-oil droplet migration and glass flange breakage during high-speed filling trigger protein aggregation and extend regulatory stability audits.
- Opportunity:Adopting silicone-free cyclic olefin polymer barrels and thin-wall staked needles enables subcutaneous self-administration of high-viscosity biologics.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Expanding commercialization of GLP-1 receptor agonists, monoclonal antibodies, and mRNA vaccines is shifting pharmaceutical demand toward ready-to-administer prefillable barrels. Biologic developers package injectable drug formulations in pre-sterilized syringes to eliminate overfill waste and prevent hospital dilution errors. FMI data suggests that occupational sharps-safety legislation reinforces this transition across acute-care wards. In June 2026, the Centers for Disease Control and Prevention updated clinical injection and sharps-safety guidance emphasizing engineered needle-retraction mechanisms to prevent bloodborne pathogen transmission among healthcare workers. Consequently, device suppliers must demonstrate consistent plunger break-loose forces and passive safety-shield activation before hospital purchasing groups award multi-year supply agreements.
Risk Assessment of the Syringes Market: Operational and Formulation Friction
Silicone-oil-induced protein aggregation and glass barrel delamination remain the primary technical hurdles delaying prefilled syringe qualification for sensitive biologics. Conventional borosilicate barrels require sprayed polydimethylsiloxane lubrication so rubber stoppers glide smoothly, yet sub-visible silicone droplets can slough into solution and denature therapeutic proteins. In June 2025, Parenteral Drug Association technical evaluations highlighted that silicone oil migration and tungsten residual pins inside glass cones elevate sub-visible particulate counts during stability storage. Qualifying baked-on silicone or fluoropolymer plunger coatings inside pharmaceutical primary packaging raises unit barrel manufacturing costs and extends formal regulatory stability testing timelines by 12 to 24 months across biologics lines.
Commercial Opportunity Analysis: Polymer Barrels and High-Viscosity Delivery
Engineering silicone-free cyclic olefin polymer barrels and ultra-thin-wall staked needles creates a high-margin opportunity for suppliers targeting home-administered biologics. High-concentration subcutaneous formulations often exceed 15 centipoise in viscosity, requiring high injection forces that can shatter thin glass flanges inside spring-loaded autoinjectors. In April 2025, the International Organization for Standardization updated ISO 11040-4 dimensional and mechanical resistance standards for subassembled prefilled parenteral syringes. In addition to this, public health immunization agencies are piloting needle-free injection systems alongside recyclable paperboard blister trays to eliminate sharps disposal costs. Device manufacturers offering cryogenic-stable polymer barrels and pre-validated nested tubs will capture multi-year cell and gene therapy supply contracts.
Syringes Market by Country (2026 to 2036)
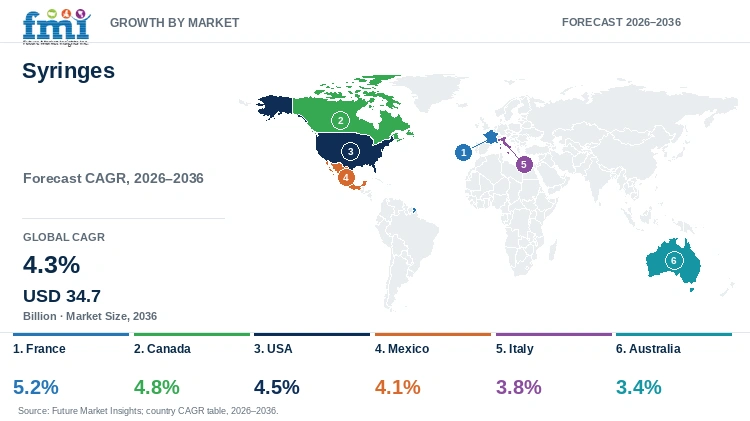
As per FMI, France represents the fastest-growing syringes market among the six evaluated countries, at a 5.2% CAGR from 2026 to 2036, while Australia records the slowest expansion at 3.4% CAGR. Across all six covered economies, commercial performance is governed by how effectively device manufacturers comply with national needlestick prevention mandates, qualify low-extractable prefilled barrels for domestic vaccine and biologic fillers, and meet hospital sustainability rules for secondary carton packaging.
Table 7: Country CAGR and Primary Growth Levers for the Syringes Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| France | 5.2% | Rhône-Alpes vaccine fill-finish clusters and public hospital prefilled safety syringe tenders |
| Canada | 4.8% | Provincial outpatient home-biologics self-injection programs and sterile barrier packaging demand |
| USA | 4.5% | Biopharmaceutical GLP-1 and monoclonal antibody pipelines and OSHA sharps-safety enforcement |
| Mexico | 4.1% | Northern border medical device contract manufacturing maquiladoras and IMSS immunization tenders |
| Italy | 3.8% | High-speed pharmaceutical fill-finish machinery hubs and regional hospital anticoagulant syringes |
| Australia | 3.4% | PBS reimbursement for subcutaneous biologics and strict TGA sterility assurance standards |
Source: Future Market Insights analysis
France Syringes Market Outlook (2026 to 2036)
Large-scale vaccine and sterile injectable fill-finish plants concentrated in the Auvergne-Rhône-Alpes corridor make France the primary European demand engine for ready-to-fill nested syringes. Consequently, the French syringes market is projected to expand at a leading 5.2% CAGR from 2026 to 2036. In February 2026, the French National Agency for Medicines and Health Products Safety published updated medical-device vigilance data confirming rising hospital procurement of prefilled safety syringes to prevent dosing and sharps incidents. Strict national anti-waste laws restricting single-use plastic packaging in public hospitals still challenge secondary blister converters. Suppliers address this rule by pairing sterile Tyvek nest lidding with 100% recycled paperboard outer cartons.
Key takeaway:In France, domestic vaccine fill-finish capacity and public hospital tenders for prefilled safety syringes drive the fastest growth among evaluated countries.
Canada Syringes Market Outlook (2026 to 2036)
Between 2026 and 2036, the Canada syringes market is expected to progress at a 4.8% CAGR, supported by provincial healthcare initiatives that shift rheumatoid arthritis, multiple sclerosis, and diabetes care toward home self-injection. In October 2025, Health Canada medical device licensing registries recorded increased approvals for prefilled syringe and autoinjector combination systems designed for outpatient administration. Unlike hospital-centric markets, Canadian distribution relies heavily on cold-chain specialty pharmacies shipping across vast geographic distances to northern and rural provinces. Sub-zero winter transit risks freezing sensitive biologics and cracking glass barrels, prompting suppliers to qualify cyclic olefin polymer syringes packed in insulated corrugated shippers.
Key takeaway:In Canada, provincial home-biologics programs and cold-chain polymer syringe adoption sustain strong demand across outpatient pharmacy networks.
USA Syringes Market Outlook (2026 to 2036)
Valued at USD 8.7 billion in 2026, the United States represents the largest national market for syringes and is projected to grow at a 4.5% CAGR through 2036. Commercial volume is anchored by domestic biopharmaceutical production of GLP-1 metabolic therapies and oncology biologics, alongside federal workplace safety rules. Under Occupational Safety and Health Administration Bloodborne Pathogens Standard 29 CFR 1910.1030, acute-care hospitals and clinics must deploy safety-engineered sharps devices and maintain annual injury logs. Group purchasing organization price caps on commodity disposable syringes still compress manufacturer margins, pushing domestic plants to shift capacity toward high-value prefillable glass and polymer barrels.
Key takeaway:In the USA, commercial GLP-1 and biologic fill-finish demand combined with OSHA needlestick enforcement anchors high-value prefilled syringe procurement.
Mexico Syringes Market Outlook (2026 to 2036)
Medical device contract manufacturing clusters across Baja California and Chihuahua position Mexico as a vital sterile assembly and export hub for North American hospital supply chains. Demand in the Mexican syringes market is forecast to rise at a 4.1% CAGR from 2026 to 2036. In November 2025, Mexico's National Institute of Statistics and Geography reported sustained output growth across IMMEX export cleanrooms producing disposable syringes, needle cannulas, and sterile blister packs. Domestic public tenders through IMSS also generate high-volume orders for childhood immunization syringes. However, reliance on imported medical-grade polypropylene resins and USP Type I glass tubing exposes local converters to cross-border tariff and currency swings.
Key takeaway:In Mexico, northern border medical device maquiladoras and national public immunization tenders support steady sterile syringe and blister production.
Italy Syringes Market Outlook (2026 to 2036)
Global leadership in automated pharmaceutical fill-finish and blistering machinery across Bologna and northern Lombardy shapes syringe demand in Italy. The Italian market is anticipated to expand at a 3.8% CAGR between 2026 and 2036. In March 2026, the Italian National Institute of Health highlighted expanded regional hospital utilization of prefilled antithrombotic and biologic safety syringes to reduce ward preparation errors. Local glass tubing converters and contract fillers work closely with machinery builders to standardize ready-to-use nested syringe tubs for European export. Lengthy regional healthcare tender cycles and public hospital budget ceilings in southern regions still restrain premium autoinjector uptake.
Key takeaway:In Italy, close integration between northern pharmaceutical machinery builders, glass barrel converters, and hospital antithrombotic programs supports reliable growth.
Australia Syringes Market Outlook (2026 to 2036)
High per-capita utilization of reimbursed biologic therapies and strict national sterility auditing characterize the commercial environment in Australia. Adoption of syringes across Australia is estimated to expand at a 3.4% CAGR through 2036. In January 2026, the Therapeutic Goods Administration updated conformity assessment procedures for sterile medical devices containing medicinal substances and prefilled delivery systems. While Pharmaceutical Benefits Scheme subsidies support steady outpatient uptake of prefilled insulin and autoimmune pens, limited domestic glass barrel manufacturing leaves Australian hospitals heavily dependent on sea and air imports. Suppliers mitigate long ocean lead times by maintaining buffer stocks of pre-validated sterile nested syringes in Sydney and Melbourne depots.
Key takeaway:In Australia, Pharmaceutical Benefits Scheme biologic coverage and stringent TGA sterility standards sustain steady demand for imported prefilled syringes.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the syringes market?
Becton, Dickinson and Company, Gerresheimer AG, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Mondi plc, Sonoco Products Company, Ball Corporation, and Crown Holdings, Inc. are the significant market players in this market.
According to FMI, the competitive landscape spans primary sterile barrel manufacturers, flexible medical barrier converters, and secondary pharmaceutical paperboard suppliers. Primary device leaders including Becton, Dickinson and Company (BD) and Gerresheimer AG manufacture borosilicate glass and cyclic olefin polymer syringe barrels, staked needles, and passive safety shields. Sterile barrier converters such as Amcor plc, Berry Global Group, Inc., and Sealed Air Corporation supply peelable Tyvek lidding and thermoformed blister packaging trays. Secondary packaging producers including Smurfit Westrock plc, Mondi plc, Sonoco Products Company, Ball Corporation, and Crown Holdings, Inc. deliver serialized folding cartons and protective transit containers.
- Primary Syringe & Parenteral Device Manufacturers: Becton, Dickinson and Company (BD) and Gerresheimer AG engineer sterile glass and polymer barrels, safety needles, and nested ready-to-fill tubs.
- Sterile Barrier & Flexible Medical Packaging Suppliers: Amcor plc, Berry Global Group, Inc., and Sealed Air Corporation supply medical blister webs, peelable sterilization pouches, and insulated shippers.
- Secondary Healthcare Paperboard & Container Converters: Smurfit Westrock plc, Mondi plc, Sonoco Products Company, Ball Corporation, and Crown Holdings, Inc. provide serialized folding cartons, rigid canisters, and protective outer packaging.
Competitive Benchmarking: Syringes Market
Table 8: Competitive Benchmarking for the Syringes Market (qualitative capability ratings), 2026
| Company | Sterile Barrier Packaging Portfolio | Low-Silicone Barrel Technology | Automated High-Speed Assembly Lines | Geographic Reach |
|---|---|---|---|---|
| Becton, Dickinson and Company (BD) | High | High | High | High |
| Gerresheimer AG | High | High | High | High |
| Amcor plc | High | Medium | High | High |
| Berry Global Group, Inc. | High | Medium | High | High |
| Smurfit Westrock plc | Medium | Low | High | High |
| Sealed Air Corporation | High | Low | High | High |
| Mondi plc | Medium | Low | High | High |
| Sonoco Products Company | Medium | Low | High | Medium |
| Ball Corporation | Low | Low | High | High |
| Crown Holdings, Inc. | Low | Low | High | High |
Scoring basis: Sterile Barrier Packaging Portfolio is High when documented capabilities include ISO 11607-compliant nested tubs, blister webs, or peelable sterile pouches, and Medium when focused on secondary cartons. Low-Silicone Barrel Technology is High when proprietary baked-on silicone or silicone-free polymer syringe barrels are core, and Medium when supplying associated polymer components. Automated High-Speed Assembly Lines is High when high-throughput converting or molding automation is documented. High Geographic Reach indicates multi-continent healthcare supply presence, and Medium indicates regional concentration. Low is reserved for documented specialization outside primary barrel molding.
Key Developments in the Syringes Market
- In February 2026, Smurfit Westrock plc unveiled an FSC-certified 100% recycled paperboard folding carton with integrated tamper-evident tear strips for hospital injectable pharmaceuticals.
- In January 2026, Amcor plc launched an all-film recyclable sterile barrier blister pouch for medical syringes and injection devices engineered without chlorinated plastics.
- In November 2025, Gerresheimer AG inaugurated a cleanroom production facility in Germany dedicated to silicone-free cyclic olefin copolymer prefillable syringe barrels.
- In September 2025, Becton, Dickinson and Company (BD) completed a USD 65.0 million expansion of its sterile prefilled syringe manufacturing center in Columbus, Nebraska, increasing capacity for glass safety syringes.
Key Players in the Syringes Market
Primary Syringe and Parenteral Device Manufacturers
- Becton, Dickinson and Company (BD)
- Gerresheimer AG
Sterile Barrier and Flexible Medical Packaging Suppliers
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
Secondary Healthcare Paperboard and Container Converters
- Smurfit Westrock plc
- Mondi plc
- Sonoco Products Company
- Ball Corporation
- Crown Holdings, Inc.
Syringes Market - Report Scope
Table 9: Report Scope for the Syringes Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from medical and analytical syringes, prefillable barrel assemblies, sterile nested carrier tubs, and in-scope packaging substrates sold within the listed segmentation. Excludes revenue from standalone infusion pumps and downstream pharmaceutical drug substances. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | France, Canada, USA, Mexico, Italy, Australia, and additional countries in the full report |
| Key Companies Covered | Becton, Dickinson and Company (BD), Gerresheimer AG, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Mondi plc, Sonoco Products Company, Ball Corporation, Crown Holdings, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Syringes Market - Research Methodology
Table 10: Research Methodology for the Syringes Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with hospital procurement directors, parenteral packaging engineers, pharmaceutical fill-finish managers, and cleanroom converting specialists across the value chain to validate device adoption, sterile barrier qualification, and pricing trends. |
| Secondary Research | Secondary research included company annual reports, investor presentations, FDA 510(k) and combination-product guidance, ISO 11040 and ISO 11607 standards, WHO injection safety surveillance, EMA regulatory publications, and technical literature relevant to the market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down injectable dose and laboratory procedure modeling combined with bottom-up syringe barrel and sterile packaging unit sales aggregation. |
| Data Triangulation and Validation | Data is validated against biopharmaceutical fill-finish capacity additions, hospital sharps-safety procurement logs, and historical trend analysis to ensure high accuracy without double counting adjacent categories. |
Syringes Market by Segments
Syringes Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Syringes Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Syringes Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Syringes Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] World Health Organization (WHO). (2025, January 24). Global injection safety surveillance and single-use sterile medical device procurement summary. World Health Organization Infection Prevention and Control Reports.
- [2] United States Food and Drug Administration (FDA). (2026, February 2). Essential drug delivery outputs for devices intended to deliver drugs and biological products. Center for Devices and Radiological Health Regulatory Guidance.
- [3] European Medicines Agency (EMA). (2025, December 5). Quality of medicines and excipient labeling guidelines for parenteral medicinal products for human use. European Medicines Agency Scientific Guidelines.
- [4] Stevanato Group S.p.A. (2026, January 19). Validation of robotic high-speed EZ-fill syringe tub and nest handling platforms for pharmaceutical CMOs. Stevanato Group Corporate Releases.
- [5] Confederation of European Paper Industries (Cepi). (2026, February 12). European packaging paper and pharmaceutical folding boxboard production and recyclability review. Cepi Industry Statistics Bulletins.
- [6] AOAC International. (2025, October 16). Official methods of analysis for automated chromatography syringe sampling in food residue testing. Journal of AOAC International, 108(5), 714-726.
- [7] Centers for Disease Control and Prevention (CDC). (2026, June 15). Injection and sharps safety workbook for designing and evaluating healthcare needlestick prevention programs. National Institute for Occupational Safety and Health Publications.
- [8] Parenteral Drug Association (PDA). (2025, June 20). Technical Report No. 73: Sub-visible particle control and silicone oil interactions in prefilled syringes. PDA Journal of Pharmaceutical Science and Technology, 79(3), 310-325.
- [9] International Organization for Standardization (ISO). (2025, April 18). ISO 11040-4: Prefilled syringes - Part 4: Glass barrels for injectables and sterilized subassembled syringes ready for filling. ISO Medical Device Standards.
- [10] Agence Nationale de Sécurité du Médicament et des Produits de Santé (ANSM). (2026, February 25). Annual materiovigilance and hospital safety syringe procurement review. French Ministry of Health Regulatory Bulletins.
- [11] Health Canada. (2025, October 21). Medical Devices Active Licence Listing (MDALL) review for prefilled syringe and autoinjector systems. Health Products and Food Branch Publications.
- [12] Occupational Safety and Health Administration (OSHA). (2025, July 14). Compliance directive for the Bloodborne Pathogens Standard 29 CFR 1910.1030 and engineered sharps injury protection. U.S. Department of Labor Enforcement Summaries.
- [13] Instituto Nacional de Estadística y Geografía (INEGI). (2025, November 18). Monthly manufacturing survey of IMMEX medical device and sterile disposable syringe export plants. Government of Mexico Statistical Releases.
- [14] Istituto Superiore di Sanità (ISS). (2026, March 11). Health technology assessment of prefilled anticoagulant and biologic safety syringes in regional hospitals. Italian National Institute of Health Reports.
- [15] Therapeutic Goods Administration (TGA). (2026, January 28). Conformity assessment procedures for sterile medical devices incorporating medicinal substances. Australian Government Department of Health and Aged Care.
- [16] Smurfit Westrock plc. (2026, February 10). Launch of FSC-certified 100% recycled paperboard folding cartons with tamper-evident tear strips for hospital injectables. Smurfit Westrock Packaging News.
- [17] Amcor plc. (2026, January 14). Commercial rollout of all-film recyclable sterile barrier blister pouches for medical syringes. Amcor Healthcare Packaging Releases.
- [18] Gerresheimer AG. (2025, November 19). Inauguration of German cleanroom facility for silicone-free cyclic olefin polymer prefillable syringe barrels. Gerresheimer Corporate News.
- [19] Becton, Dickinson and Company (BD). (2025, September 16). Completion of USD 65.0 million sterile prefilled syringe manufacturing expansion in Columbus, Nebraska. BD Investor Relations.
- [20] SCHOTT Pharma AG & Co. KGaA. (2026, March 12). Opening of advanced manufacturing facility for prefillable polymer syringes tailored for deep-cold mRNA and biologic drugs. SCHOTT Pharma Press Releases.
- [21] Terumo Corporation. (2025, July 22). Commercial launch of ultra-thin-wall staked-needle syringes for high-viscosity subcutaneous biologics. Terumo Medical Device Announcements.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the syringes market in 2026 and what is forecast for 2036?
- Which clinical and biologics pressures support demand for syringes?
- What positions Rigid Containers & Bottles ahead in packaging format?
- Why does Recycled Paperboard lead the material substrate category globally?
- How do growth rates differ across France, Canada, the USA, and Mexico?
- Which leading companies supply relevant primary barrel, sterile barrier, and carton categories today?
- What limits adoption or supplier switching in the syringes market?
- What should buyers evaluate before qualifying a syringe and sterile packaging supplier?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Becton, Dickinson and Company (BD)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Gerresheimer AG
- Amcor plc
- Berry Global Group, Inc.
- Smurfit Westrock plc
- Sealed Air Corporation
- Mondi plc
- Sonoco Products Company
- Ball Corporation
- Crown Holdings, Inc.
- Becton, Dickinson and Company (BD)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Packaging Format
- Figure 6: Global Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Packaging Format
- Figure 26: North America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Material Substrate
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Sector
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 36: Latin America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Material Substrate
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 46: Western Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Material Substrate
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Material Substrate
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 66: East Asia Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Material Substrate
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Material Substrate
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Material Substrate
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the syringes market in 2026, and what is forecast for 2036?
Global syringes sales are estimated to reach USD 22.8 billion in 2026. Market revenue is projected to reach USD 34.7 billion by 2036, driven by injectable biologics expansion and hospital needlestick safety mandates.
What is the CAGR for the syringes market from 2026 to 2036?
As per FMI, the syringes market is projected to expand at a 4.3% CAGR from 2026 to 2036. Growth is supported by prefilled syringe conversion and outpatient self-injection therapies.
Which packaging format segment leads the syringes market in 2026?
Rigid containers & bottles are expected to hold 39.8% of packaging format demand in 2026. The segment benefits from sterile nested tubs and thermoformed blister trays that prevent barrel breakage on automated filling lines.
Which material substrate segment holds the largest share in 2026?
Recycled paperboard is projected to account for 41.9% of material substrate volume in 2026. Demand is supported by serialized secondary folding cartons and hospital sustainability preferences.
Which country has a notable expansion outlook during the assessment period?
FMI finds that France is projected to register a 5.2% CAGR between 2026 and 2036. High growth is underpinned by domestic vaccine fill-finish clusters and public hospital safety syringe procurement.
Who are the key players active in the syringes market?
Notable participants include Becton, Dickinson and Company (BD), Gerresheimer AG, Amcor plc, Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Mondi plc, Sonoco Products Company, Ball Corporation, and Crown Holdings, Inc., alongside parenteral specialists SCHOTT Pharma AG, Terumo Corporation, and Stevanato Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
