

- Market Size (2026)
- USD 1.0 Bn
- Forecast (2036)
- USD 3.2 Bn
- CAGR (2026 to 2036)
- 12.0%
How big is Adaptive Front Lighting Market in 2026?
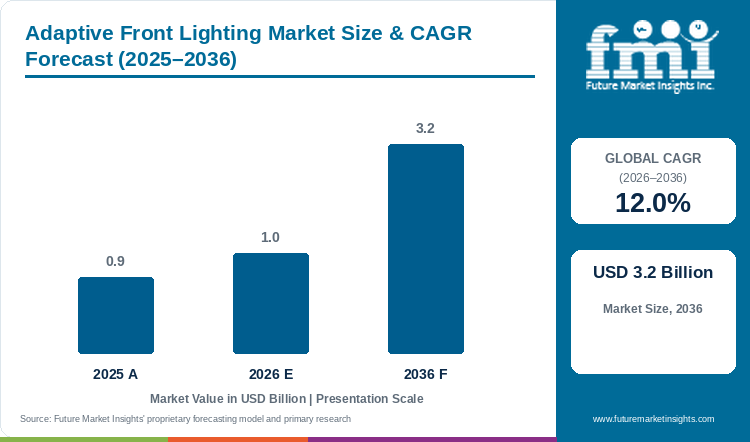
Demand for adaptive front lighting will grow at a CAGR of 12% from 2026 to 2036. Market size was USD 0.9 billion in 2025, is USD 1.0 billion in 2026 and is projected to reach USD 3.2 billion by 2036.
Adaptive front lighting market size was USD 0.9 billion in 2025, is USD 1.0 billion in 2026 and is projected to reach USD 3.2 billion by 2036. Demand for adaptive front lighting will grow at a CAGR of 12% from 2026 to 2036, as per FMI. Rules shape lamp design in each region. On 6 October 2026, NHTSA opened a negotiated rulemaking on FMVSS No. 108, the first use of that method for vehicle lighting in more than 25 years[1].
A rulemaking of this kind signals that US lighting standards are open to change. Lamp makers will watch the outcome closely, as new test methods can decide which beam designs reach the US market. Sales potential is expected to emerge from adaptive systems that avoid glare for other drivers and light more of the road. Key challenges faced by lamp makers include design costs for separate regional versions and long approval cycles. Key drivers of the market include safety ratings and the shift of lighting from a fixed part to a software-controlled system. Growth of the adaptive front lighting market at 12% will favour suppliers that serve several regions from one platform.
Key Market Trends & Insights
- By product, camera sensors led the market with a 34% share in 2026, ahead of radar sensors at 20% and ultrasonic sensors at 13%, as beam shading around other vehicles starts with a forward camera view.
- By sales channel, OEM supply accounted for 61% of sales in 2026, ahead of the aftermarket at 39%, as vehicle makers fix lamp and sensor choices during platform design.
- By vehicle type, passenger vehicles held about 74% of sales in 2026, ahead of light commercial vehicles at 18%. Passenger cars were 71.1% of the 99.8 million vehicles sold worldwide in 2025, Global Fleet reported using OICA data.[2]
- By lighting function, adaptive beam accounted for about 46% of sales in 2026, ahead of cornering lights at 32%, and GRE adopted draft Supplement 8 to the 01 series of UN Regulation No. 149 at the 94th session.[3]
- By end use, passenger mobility accounted for about 78% of sales in 2026, ahead of commercial transport at 15%. NHTSA said on 6 October 2026 that the lighting update will study glare for other road users.[1]
Regional Highlights
- Fastest-growing profiled country: South Korea (12.6% CAGR, 2026 to 2036).
- By country: the USA (12.5%), Japan (12.3%) and the EU (12%) follow, with the UK recording the lowest profiled CAGR at 11.8%.
- Australian Design Rule 103/00, dated 11 June 2026, lists UN Regulation No. 149 as an alternative standard for road illumination lamps.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Adaptive Front Lighting Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 0.9 billion |
| Estimated Market Size in 2026 | USD 1.0 billion |
| Projected Market Size by 2036 | USD 3.2 billion |
| CAGR, 2026 to 2036 | 12% |
| Added Revenue, 2026 to 2036 | USD 2.2 billion |
| Market Expansion Multiple | 3.2x |
Orders for adaptive front lighting come mostly from vehicle programs that already carry LED headlamps. As per FMI, growth is constrained by system cost in economy segments, with matrix LED, ADAS integration and commercial vehicle adoption as the main openings. Beam control also links to driver assistance, the field tracked in the automotive active safety system market. Supplier results show mixed conditions. FORVIA HELLA Lighting Business Group sales fell on the phase-out of several high-volume series projects in China and the Americas and on market weakness in Europe.[5] Valeo said on 22 July 2026 that the BRAIN and LIGHT Divisions outperformed global automotive production in the first half.[6] Beam control grows at 12% a year, and vehicle volumes move far slower, so content per vehicle carries the forecast.
Lighting Rules and Type-Approval Readiness
Type approval is the first gate for beam control, and the UN text sets the common route. The UN register records UN Regulation No. 149 as in force from 15 November 2019, with 59 parties.[7] Japan, the EU, the UK and South Korea show the same application date, and Australia follows from 24 December 2024.[7] China and the United States do not appear in the register.[7] In June 2026, Australia issued Design Rule 103/00, which lists the regulation as an alternative standard and notes that the text combines the earlier UN Regulations Nos. 19, 98, 112, 113, 119 and 123.[4] Amendment notices dated 24 June 2025, 6 October 2025 and 12 June 2026 show that approval files keep changing.[7] As per FMI, a supplier with one tested design for the UN route reaches the widest group of export markets with the least repeat testing.
FMVSS No. 108 follows a separate path in the United States. AutoConnectedCar reported on 6 October 2026 that NHTSA approved adaptive driving beam headlights in 2022 after a Toyota petition of 2013, and that industry voices argued the final rule held adaptive systems to higher glare standards than conventional lights.[8] The new negotiated rulemaking has up to 18 stakeholders, comments due on 9 November 2026 and a stated aim of harmonizing US lighting rules with international standards.[1] China took a national route, with GB 4599-2024 in force from 1 July 2025 for M and N category vehicles and a clause for adaptive passing beams.[9] The UN glare task force met in Brussels on 9 June 2026, and the draft recommendations include mandatory cleaning on AFS and ADB lamps and better ADB latency and vehicle detection.[10] Draft Supplement 8 to the 01 series is agenda item 4.8.2 at WP.29 Session 200 from 16 to 20 November 2026.[3] Programs now have to choose whether to design to the UN text first or to wait for the US rewrite.
Table 2: Lighting Rule and Type-Approval Indicators for the Adaptive Front Lighting Market (dates, counts and requirements), mixed reporting years from 2019 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| UN Regulation No. 149 | In force 15 November 2019; 59 parties | One approval text serves lamp suppliers selling into many countries. | [7] |
| Amendment notices, UN Regulation No. 149 | 24 June 2025, 6 October 2025 and 12 June 2026 | Approval files stay under review across the forecast period. | [7] |
| Japan, EU, UK and South Korea | Application from 15 November 2019 | Four profiled countries accept the same approval text. | [7] |
| Australian Design Rule 103/00 | Instrument dated 11 June 2026 | A further export market accepts the UN text. | [4] |
| NHTSA lighting rulemaking | Announced 6 October 2026; comments due 9 November 2026 | US lamp rules are set to move closer to international standards. | [1] |
| US approval of adaptive driving beam | Approved in 2022 after a Toyota petition of 2013 | US buyers have had access for under five years. | [8] |
| China GB 4599-2024 | In force 1 July 2025 for M and N category vehicles | A national route runs beside the UN route. | [9] |
| UN glare task force, 8th session | 9 June 2026, Brussels | Draft items cover lamp cleaning, ADB latency and vehicle detection. | [10] |
| Draft Supplement 8 to the 01 series | WP.29 Session 200, 16 to 20 November 2026 | The agenda item covers ADB luminous intensity for category L3. | [3] |
Analyst Perspective
“Approval status is now the main gate for beam control, and one tested design opens several markets. The NHTSA rewrite of FMVSS No. 108 and the UN draft Supplement 8 will set the glare and detection tests that programs awarded after 2026 have to pass.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the adaptive front lighting market segmented?
The adaptive front lighting market is segmented into product, sales channel, vehicle type, lighting function and end use, and region. In 2026, camera sensors hold 34% of product sales, OEM supply holds 61% of sales channel sales, passenger vehicles hold 74% of vehicle type sales, adaptive beam holds 46% of lighting function sales and passenger mobility holds 78% of end use sales.
By product: ultrasonic sensors, LiDAR sensors, radar sensors, camera sensors, infrared sensors, and pressure sensors.
By sales channel: OEM and aftermarket.
By vehicle type: passenger vehicles, light commercial vehicles, and heavy commercial vehicles.
By lighting function: adaptive beam, cornering lights, and automatic leveling.
By end use: passenger mobility, commercial transport, and industrial use.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do camera sensors lead product sales?
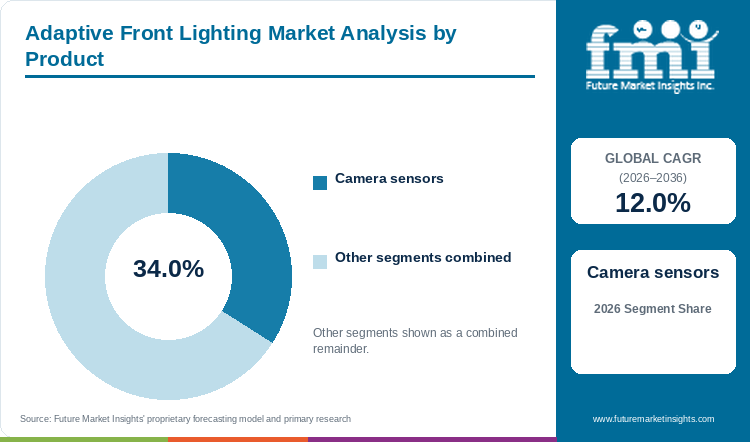
Camera sensors account for 34% of product sales in 2026, ahead of radar sensors at 20%, as beam shading around other vehicles starts with a camera view of the road.
Table 3: Product Share for the Adaptive Front Lighting Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Camera Sensors | 34% |
| Radar Sensors | 20% |
| Ultrasonic Sensors | 13% |
| LiDAR Sensors | 12% |
| Infrared Sensors | 11% |
| Pressure Sensors | 10% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Adaptive Front Lighting Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12% |
| Leading Segment | Camera Sensors |
An adaptive driving beam shades the main beam around oncoming and preceding vehicles, so the lamp needs a view of the road before anything else. Camera sensors supply that view, and FMI places them ahead of ultrasonic, LiDAR, radar, infrared and pressure sensors. The UN glare task force draft of 9 June 2026 asks for better ADB latency and vehicle detection.[10] Radar and LiDAR sensors serve premium and automated driving programs, and the solid-state LiDAR sensor market tracks that hardware separately. Detection tests, more than sensor price, now separate one camera module from another.
- Detection tests, not price, separate camera modules.
- Buyers comparing camera modules can check detection latency and vehicle detection, the two items named in the draft glare recommendations.[10]
Why does OEM supply account for most sales channel sales?
OEM supply holds 61% of sales channel sales in 2026, ahead of the aftermarket at 39%, as vehicle makers fix lamp and sensor choices during platform design.
Table 5: Sales Channel Share for the Adaptive Front Lighting Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| OEM | 61% |
| Aftermarket | 39% |
| Total | 100.0% |
Platform awards fix OEM supply early, because beam control links the lamp, the camera and the control unit. A program that ends takes supplier volume away, as FORVIA HELLA showed with an 8.3% fall in Lighting Business Group sales to EUR 3.7 billion in fiscal 2025.[5] Aftermarket sales through authorized service and independent workshops cover repair and replacement, and FMI estimates OEM supply well ahead of that route. Suppliers that hold several platform awards face less exposure.
- Aftermarket sales cover repair and replacement only.
- FORVIA HELLA cited the end of several high-volume series projects in China and the Americas for the 2025 lighting sales fall.[5]
Why do passenger vehicles lead vehicle type sales?
Passenger vehicles hold about 74% of vehicle type sales in 2026, ahead of light commercial vehicles at 18% and heavy commercial vehicles at 8%.
Table 6: Vehicle Type Share for the Adaptive Front Lighting Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Passenger Vehicles | 74% |
| Light Commercial Vehicles | 18% |
| Heavy Commercial Vehicles | 8% |
| Total | 100.0% |
Of the 99.8 million vehicles sold worldwide in 2025, passenger cars were 71.1%, Global Fleet reported in May 2026 using OICA data.[2] Passenger vehicles therefore carry the volume that beam control needs, covering hatchbacks, sedans and SUVs. US buyers gained access to adaptive driving beam only after the 2022 approval that followed a Toyota petition of 2013.[8] Light commercial vehicles such as delivery vans and pickups come next, and heavy trucks and buses form the smallest group. Fleet buyers still have to weigh night-driving safety gains against added lamp cost.
- Heavy trucks and buses form the smallest group.
- The 2022 US approval widened the buyer base for passenger vehicles.[8]
Why is adaptive beam the focus of lighting function rule changes?
Adaptive beam, cornering lights and automatic leveling are the three lighting functions studied, and adaptive beam accounts for about 46% of lighting function sales in 2026, with cornering lights at 32% and automatic leveling at 22%.
Table 7: Lighting Function Share for the Adaptive Front Lighting Market (percentage share), 2026
| Lighting Function | Estimated Share (2026) |
|---|---|
| Adaptive Beam | 46% |
| Cornering Lights | 32% |
| Automatic Leveling | 22% |
| Total | 100.0% |
Adaptive beam draws the most rule work in 2026, ahead of cornering lights and automatic leveling. NHTSA said on 6 October 2026 that the update will study glare for other road users caused by modern headlight technology.[1] GRE adopted draft Supplement 8 to the 01 series at the 94th session, and the proposal specifies luminous intensity requirements for ADB on vehicles of category L3.[3] The UN glare task force draft adds mandatory cleaning on AFS and ADB lamps.[10] The three functions are studied together, and the rule texts change at different speeds.
- Cornering lights and automatic leveling draw fewer changes.
- Draft Supplement 8 covers ADB luminous intensity for category L3 and is agenda item 4.8.2 at WP.29 Session 200.[3]
Why does passenger mobility account for most end use sales?
Passenger mobility, covering private and shared vehicles, accounts for about 78% of end use sales in 2026, ahead of commercial transport at 15% and industrial use at 7%.
Table 8: End Use Share for the Adaptive Front Lighting Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Passenger Mobility | 78% |
| Commercial Transport | 15% |
| Industrial Use | 7% |
| Total | 100.0% |
A February 2026 AAA survey found that six in ten drivers see headlight glare as a problem after dark, AutoConnectedCar reported on 6 October 2026.[8] Private and shared cars carry most of that night driving on mixed roads, which keeps passenger mobility the largest end use. Commercial transport in logistics and public transport, and industrial use in construction and utility fleets, buy in smaller volumes. Interior ambient lighting is outside this study and is covered in the automotive interior ambient lighting market. Ride-hailing and car-sharing fleets are the buyer group to watch.
- Ride-hailing and car-sharing fleets are the group to watch.
- NHTSA said on 6 October 2026 that the lighting update will study glare for other road users.[1]
What are the drivers, restraints, and opportunities in the adaptive front lighting market?
In the adaptive front lighting market, safety rules that mandate advanced headlamp functions drive sales, system cost in economy segments constrains fitment, and matrix LED, ADAS integration and commercial vehicle adoption open the main opportunities.
- Driver: Expanding safety regulation mandates advanced headlamp functions for pedestrian protection.
- Restraint: System cost constrains growth in economy segments.
- Opportunity: Matrix LED, ADAS integration and commercial vehicle adoption open new awards.
Safety Rules Open the Door to Beam Control
Key drivers of the adaptive front lighting market include rules that allow beam control in markets that once held beam control back. NHTSA approved adaptive driving beam headlights in 2022, and the agency opened a rewrite of FMVSS No. 108 on 6 October 2026.[8][1] Harmonizing US lighting rules with international standards is among the stated goals of the rewrite.[1] Closer rules lower the testing needed to sell one lamp design in several regions. The automotive electronics market supplies the control electronics that link camera and lamp. Beam control sales are likely to rise fastest in markets with a clear approval route.
System Cost Slows Economy Vehicle Fitment
System cost of camera sensors, LED assemblies and control electronics is high per vehicle. As per FMI, growth is constrained by system cost in economy segments. Economy vehicles therefore adopt beam control later than premium models. Draft recommendations on lamp cleaning, latency and vehicle detection from the 9 June 2026 glare task force session may add content to each system.[10] Cost relief is more likely to come from volume than from lighter rules.
Matrix LED and Fleets Open New Awards
Growth of the adaptive front lighting market in new vehicle groups follows matrix LED, driver assistance links and commercial fleets. Valeo reported on 22 July 2026 group sales of EUR 10.4 billion for the first half and said the BRAIN and LIGHT Divisions outperformed global automotive production.[6] Suppliers of matrix LED and digital headlamps stand to gain platform awards as electric vehicle programs bundle lighting with driver assistance packages. Commercial vehicle fleets are a smaller but separate buyer group.
Which country CAGRs are profiled in the adaptive front lighting market?
Table 9: Country CAGR Comparison for the Adaptive Front Lighting Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| South Korea | 12.6% |
| USA | 12.5% |
| Japan | 12.3% |
| EU | 12% |
| UK | 11.8% |
How do country-level CAGRs compare in the adaptive front lighting market?
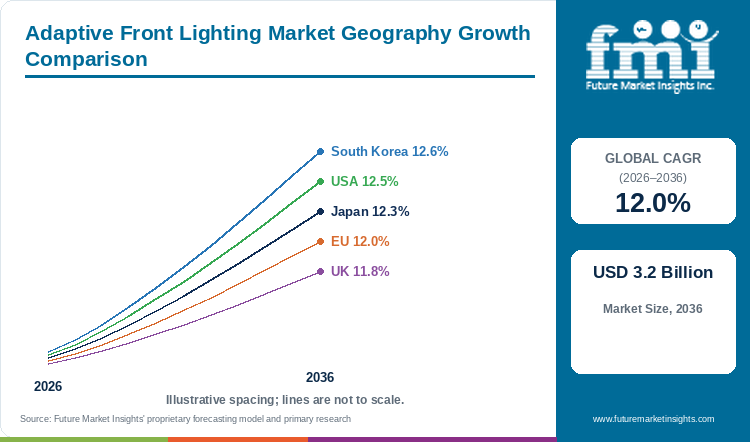
Growth across the five profiled countries separates by approval route, OEM base and rule timing. As per the analysis from FMI, South Korea is projected at 12.6% CAGR from 2026 to 2036, followed by the USA at 12.5% and Japan at 12.3%. The EU is estimated at 12%, and the UK is projected at 11.8%. The gap between first and last is 0.8 points, so approval timing matters more than raw growth.
- South Korea pairs Hyundai-Kia OEM integration with domestic component manufacturing and government safety technology support.
- The USA combines the NHTSA adaptive driving beam rule with consumer demand for ADAS features and OEM differentiation.
- Japan links domestic OEM adoption and LED headlamp manufacturing leadership to strict vehicle lighting safety standards.
- The EU draws on UN ECE regulation leadership and a strong premium OEM presence.
- The UK draws on UN ECE regulation compliance, premium vehicle market strength and post-Brexit type-approval alignment.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
South Korea Adaptive Front Lighting Market Outlook (2026 to 2036)
Hyundai-Kia OEM integration, domestic component manufacturing and government safety technology support drive growth, and South Korea leads the profiled countries at 12.6% CAGR from 2026 to 2036. The UN register shows that Korea has applied UN Regulation No. 149 since 15 November 2019, the same date as Japan, the EU and the UK.[7] Domestic programs therefore design beam control to one UN text. Hyundai Mobis is the main Korean supplier, so sourcing decisions stay close to the OEM group.
Key takeaway: Korea leads at 12.6% because one OEM group and one UN text keep approval and sourcing in the same place.
USA Adaptive Front Lighting Market Outlook (2026 to 2036)
On 6 October 2026, NHTSA announced a negotiated rulemaking on FMVSS No. 108 with up to 18 stakeholders, and comments are due on 9 November 2026.[1] Adaptive driving beam headlights were approved in 2022 after a decade of work, AutoConnectedCar reported, and industry voices argued the final rule set higher glare standards for these systems.[8] The adaptive driving beam final rule, consumer demand for ADAS features and OEM differentiation drive growth, and the USA is projected at 12.5% CAGR from 2026 to 2036. China and the United States are the two large markets outside the UN register.[7]
Key takeaway: US growth of 12.5% now waits on a rewrite whose glare tests are still being negotiated.
Japan Adaptive Front Lighting Market Outlook (2026 to 2036)
Japan is projected at 12.3% CAGR from 2026 to 2036, third among the profiled countries. Domestic OEM adoption, LED headlamp manufacturing leadership and strict vehicle lighting safety standards support growth. The country has applied UN Regulation No. 149 since 15 November 2019.[7] The UN glare task force scheduled the ninth session for Tokyo on 8 September 2026, and the 8th session in Brussels had already drafted rules on lamp cleaning and ADB latency.[10]
Key takeaway: Japan was set to host the ninth glare task force session, which kept draft cleaning and latency rules close to Japanese lamp makers.
EU Adaptive Front Lighting Market Outlook (2026 to 2036)
FORVIA HELLA reported on 19 March 2026 that Lighting Business Group sales fell 8.3% to EUR 3.7 billion in fiscal 2025, citing project phase-outs in China and the Americas and market weakness in Europe.[5] The EU has applied UN Regulation No. 149 since 15 November 2019.[7] UN ECE regulation leadership and a strong premium OEM presence, including BMW, Mercedes, Audi and Volvo, shape demand, and the EU is projected at 12% CAGR from 2026 to 2036.
Key takeaway: EU growth of 12% comes from premium platforms and UN texts, set against a soft European lamp market.
UK Adaptive Front Lighting Market Outlook (2026 to 2036)
The UK records the lowest profiled CAGR at 11.8% from 2026 to 2036, a small gap to the 12.6% of South Korea. UN ECE regulation compliance, premium vehicle market strength and post-Brexit type-approval alignment underpin UK demand. The UN register lists the UK among the parties applying UN Regulation No. 149 from 15 November 2019.[7] Draft Supplement 8 to the 01 series is on the WP.29 agenda for 16 to 20 November 2026, and adopted text is expected to reach UK approvals through the same register.[3]
Key takeaway: UK buyers follow UN texts closely, so the lower 11.8% points to a smaller premium base and not a different rulebook.
Who are the notable companies in the adaptive front lighting market?
Robert Bosch GmbH, Koito Manufacturing, Stanley Electric Co. Ltd., FORVIA HELLA, Valeo SA, Magneti Marelli, Hyundai Mobis, Denso Corporation and Continental AG are the leading companies profiled in this market, with Aeva Technologies, Opsys Tech and Actasys as emerging players.
The company set splits into established lamp and systems suppliers and a short list of emerging developers. Bosch, Koito, Stanley Electric, FORVIA HELLA, Valeo and Magneti Marelli lead the market as per FMI, with Hyundai Mobis, Denso and Continental also active as major suppliers. Aeva Technologies, Opsys Tech and Actasys are emerging developers.
Positioning differs by role and by documented activity. FORVIA HELLA reported Lighting Business Group sales of EUR 3.7 billion for fiscal 2025, down 8.3%.[5] Valeo named lighting among the two divisions that outperformed global automotive production in the first half of 2026.[6] Approval coverage across the UN, US and Chinese routes now separates suppliers more than lamp optics alone.
- Established lamp and systems suppliers: Robert Bosch GmbH, Koito Manufacturing, Stanley Electric Co. Ltd., FORVIA HELLA, Valeo SA, Magneti Marelli, Hyundai Mobis, Denso Corporation, and Continental AG.
- Emerging developers: Aeva Technologies, Opsys Tech, and Actasys.
Competitive Benchmarking: Adaptive Front Lighting Market
Table 10: Competitive Benchmarking for the Adaptive Front Lighting Market (qualitative documentation ratings), 2026
| Company | Lighting Results | Dated Release | Product Detail | Disclosure |
|---|---|---|---|---|
| FORVIA HELLA | High | High | Low | High |
| Valeo | Low | High | Low | Medium |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Adaptive Front Lighting Market
- In October 2026, NHTSA announced a negotiated rulemaking to update FMVSS No. 108, with comments and nominations due on 9 November 2026.[1]
- In September 2026, WP.29 document 2026/185 set out draft Supplement 8 to the 01 series of UN Regulation No. 149, with ADB luminous intensity requirements for category L3 vehicles.[3]
- In July 2026, Valeo reported first-half results and said the BRAIN and LIGHT Divisions outperformed global automotive production.[6]
- In June 2026, the UN glare task force met in Brussels, and Australia issued Design Rule 103/00 listing UN Regulation No. 149 as an alternative standard.[10][4]
- In March 2026, FORVIA HELLA reported fiscal 2025 Lighting Business Group sales down 8.3% to EUR 3.7 billion.[5]
- In July 2025, China's GB 4599-2024 on road illumination devices and systems for motor vehicles took effect.[9]
Key Players in the Adaptive Front Lighting Market
Lamp-led Suppliers
- Koito Manufacturing Co., Ltd.
- Stanley Electric Co., Ltd.
- FORVIA HELLA
- Valeo SA
- Magneti Marelli
Sensor and Systems Suppliers
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Hyundai Mobis
Emerging Developers
- Aeva Technologies
- Opsys Tech
- Actasys
Adaptive Front Lighting Market - Report Scope
Table 11: Report Scope for the Adaptive Front Lighting Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; sales channel; vehicle type; lighting function; end use; region |
| Quantitative units | USD billion |
| Market definition | Sales of commercially traded adaptive front lighting systems that adjust beam pattern, intensity and distribution to driving conditions, including camera, radar and LiDAR sensor-based systems with LED, matrix LED, laser and conventional lighting technologies. Static headlamp assemblies, aftermarket bulb replacements and interior ambient lighting are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | South Korea; USA; Japan; EU; UK |
| Key companies profiled | Robert Bosch, Koito Manufacturing, Stanley Electric, FORVIA HELLA, Valeo, Magneti Marelli, Hyundai Mobis, Denso, Continental, Aeva Technologies, Opsys Tech, Actasys |
| Forecast period | 2026 to 2036 |
Adaptive Front Lighting Market - Research Methodology
Table 12: Research Methodology for the Adaptive Front Lighting Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Regulatory and company facts come from regulator publications, company releases and trade press dated May 2025 or later. |
| Desk Research | Desk research covers UN regulation records, national lighting standards, NHTSA notices and company results releases. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 0.9 billion and the 12% CAGR. |
| Data Validation | Regulation dates and supplier results are compared across UN, NHTSA and company records. |
Adaptive Front Lighting Market by Segments
Adaptive Front Lighting Market segmented by Product:
- Ultrasonic sensors
- LiDAR sensors
- Radar sensors
- Camera sensors
- Infrared sensors
- Pressure sensors
Adaptive Front Lighting Market segmented by Sales Channel:
- OEM
- Aftermarket
Adaptive Front Lighting Market segmented by Vehicle Type:
- Passenger vehicles
- Light commercial vehicles
- Heavy commercial vehicles
Adaptive Front Lighting Market segmented by Lighting Function:
- Adaptive beam
- Cornering lights
- Automatic leveling
Adaptive Front Lighting Market segmented by End Use:
- Passenger mobility
- Commercial transport
- Industrial use
Adaptive Front Lighting Market by Region
- North America
- USA
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Western Europe
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
Research Sources and Bibliography
- [1] National Highway Traffic Safety Administration. (2026, October 6). Press release on modernizing outdated vehicle lighting standards. https://www.nhtsa.gov/press-releases/modernize-outdated-vehicle-lighting-standards
- [2] Global Fleet. (2026, May 18). Global auto market nears 100 million units as China reshapes industry balance. https://www.globalfleet.com/en/fleet-strategy/global/features/global-auto-market-nears-100-million-units-china-reshapes-industry-balance
- [3] Global Auto Regulations, citing UNECE WP.29. (2026, September 4). UN R149, Proposal for a Supplement 8 to the 01 series of amendments (WP.29/2026/185). https://globalautoregs.com/documents/43474
- [4] Australian Government, Federal Register of Legislation. (2026, June 11). Vehicle Standard (Australian Design Rule 103/00 - Road Illumination Devices (Lamps)) 2026. https://www.legislation.gov.au/F2026L00929/asmade/2026-07-08/text/original/epub/OEBPS/document_1/document_1.html
- [5] FORVIA HELLA. (2026, March 19). Fiscal Year 2025 press release. https://www.hella.com/en/Newsroom/Press-Releases/2026-03-19-Fiscal-Year-2025-9134/
- [6] Valeo. (2026, July 22). H1 2026 financial results press release. https://www.valeo.com/en/press-release-h1-2026-results/
- [7] United Nations Treaty Collection. (2026, June 12). UN Regulation No. 149, Road Illumination Devices, adoption, entry into force and depositary notifications. https://treaties.un.org/doc/Publication/MTDSG/Volume%20I/Chapter%20XI/XI-B-16-149.en.pdf
- [8] AutoConnectedCar. (2026, October 6). NHTSA opens for comments, changing headlights for fewer glaring errors. https://www.autoconnectedcar.com/2026/10/nhtsa-opens-for-comments-changing-headlights-for-fewer-glaring-errors/
- [9] State Administration for Market Regulation and Standardization Administration of China (GB 4599-2024, via ChineseStandard.net). (2025, July 1). Road illumination devices and systems for motor vehicles. https://www.chinesestandard.net/PDF.aspx/GB4599-2024
- [10] Global Auto Regulations, citing the UNECE GRE Task Force on Glare Prevention. (2026, June 9). Glare Prevention, report of the 8th (June 2026) session. https://globalautoregs.com/meetings/3865
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What market size is estimated for adaptive front lighting in 2026?
- What market size is projected by 2036?
- Which product holds the leading share?
- Which sales channel holds a notable share?
- Which countries show the fastest growth?
- Which suppliers are notable in the market?
Frequently Asked Questions
How large is the adaptive front lighting market expected in 2026?
Future Market Insights estimates that the adaptive front lighting market is estimated at USD 1.0 billion in 2026, up from USD 0.9 billion in 2025. The market is projected to reach USD 3.2 billion by 2036 as OEMs fit camera-led beam control across more models.
What CAGR is projected for the adaptive front lighting market through 2036?
As per FMI analysis, sales of adaptive front lighting are projected to grow at a 12% CAGR from 2026 to 2036. Safety rules that allow beam control in UN, US and Chinese systems support the outlook.
Which product holds the leading market share in 2026?
Camera sensors account for 34% of product sales in 2026. Beam shading around oncoming and preceding vehicles starts with a camera view of the road.
Which sales channel holds a notable market share in 2026?
OEM supply accounts for 61% of sales channel sales in 2026. Vehicle makers fix lamp and sensor choices during platform design.
Which country has a notable expansion outlook through 2036?
South Korea is projected to record the fastest growth at 12.6% CAGR from 2026 to 2036, according to FMI. Hyundai-Kia OEM integration and domestic component manufacturing lead Korean growth.
Who are the key companies in the adaptive front lighting market?
Notable companies include Robert Bosch, Koito Manufacturing, Stanley Electric, FORVIA HELLA, Valeo, Magneti Marelli, Hyundai Mobis, Denso and Continental, with Aeva Technologies, Opsys Tech and Actasys as emerging players.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Ultrasonic sensors
- LiDAR sensors
- Radar sensors
- Camera sensors
- Infrared sensors
- Pressure sensors
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- OEM
- Aftermarket
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Passenger vehicles
- Light commercial vehicles
- Heavy commercial vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By Lighting Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Lighting Function, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Lighting Function, 2026 to 2036
- Adaptive beam
- Cornering lights
- Automatic leveling
- Y-o-Y Growth Trend Analysis By Lighting Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Lighting Function, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Passenger mobility
- Commercial transport
- Industrial use
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- Mexico
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- EU
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Sales Channel
- By Vehicle Type
- By Lighting Function
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- FORVIA HELLA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Valeo
- Koito Manufacturing Co., Ltd.
- Stanley Electric Co., Ltd.
- Valeo SA
- Magneti Marelli
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Hyundai Mobis
- Aeva Technologies
- Opsys Tech
- Actasys
- FORVIA HELLA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


