
- Market Size (2026)
- USD 2.1 Bn
- Forecast (2036)
- USD 6.2 Bn
- CAGR (2026 to 2036)
- 11.3%
How big is Coloured Gemstone Market in 2026?
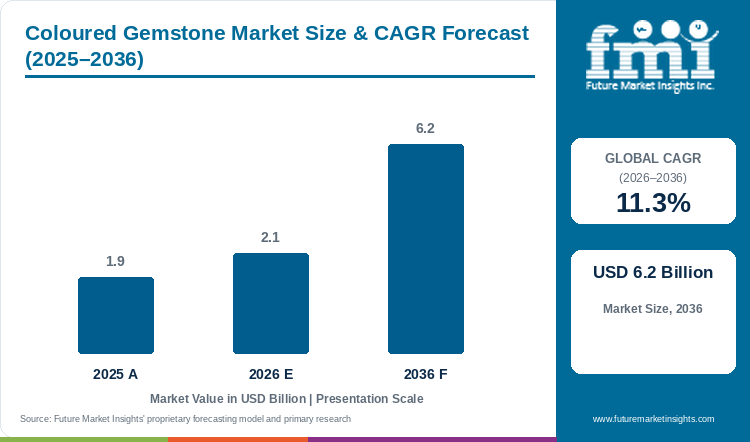
The coloured gemstone market is estimated at USD 1.9 billion in 2025 and is expected to reach USD 2.1 billion in 2026. Sales of coloured gemstones are projected to grow at an 11.3% CAGR and reach USD 6.2 billion by 2036.
Jewellers, cutters and collectors are expected to buy USD 2.1 billion of coloured gemstones in 2026, against an estimated USD 1.9 billion in 2025, as the coloured gemstone market moves toward a projected USD 6.2 billion by 2036 on an 11.3% CAGR. Jewellery is likely to hold an estimated 71% of end-use sales in 2026, as rings, pendants and earrings absorb most cut stones.
Through 2036, mine-to-market supply sold at scheduled auctions with traceable origin is set to be the main growth route, as brands want stones that pass origin checks. For example, Gemfields reported ruby and emerald auction sales of USD 102.9 million for January to June 2026, 72% more than the USD 60 million of the first half of 2025, National Jeweler reported on 31 July 2026.[1] Such auctions of graded, traceable lots give cutters and brands a steady source of stones that pass origin checks, so more retail collections can feature emeralds and rubies at scale.
FMI analysts recommend that jewellery brands secure multi-auction buying plans for emerald and ruby, since lot prices move with each round and rough with certified origin is the scarcest input. As a result, brands holding that supply will be first to scale coloured stone collections.
Key Market Trends & Insights
- Sapphire is expected to lead the product type split in 2026 with a 31% share, on the wide colour range and hardness that suit daily-wear rings. Behind sapphire, emerald is likely to hold 22% and ruby 18%.
- Natural products are projected at 74% of 2026 product format sales against 26% for synthetic stones, as rarity and origin set the price of mined stones. Exceptional natural stones still draw strong tender competition. At the rare end, Petra Diamonds sold a 41.82 carat Type IIb blue diamond in a competitive tender in Q3 FY 2026.[2] Sales of that kind confirm the premium buyers pay for rare natural colour, which synthetics cannot match at the top end.
- Jewellery is estimated at 71% of end use in 2026, with investment and collection at 17%, as luxury houses build more collections around coloured stones. For instance, Watches & Jewelry at LVMH grew 9% organically over January to June 2026.[3] Growth of that order at the largest luxury jewellery group keeps high-jewellery demand for premium sapphires, emeralds and rubies firm.
Regional Highlights
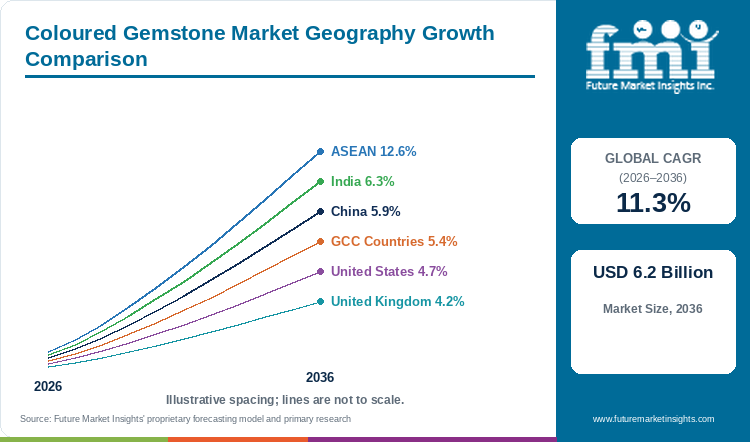
- FMI projects ASEAN to grow fastest, at 12.6%, ahead of the market average of 11.3%, as Thai cutting and trading centres expand gem exports.
- India (6.3%) and China (5.9%) lead the large consumer markets, followed by GCC Countries (5.4%) and the United States (4.7%). By comparison, the mature ring trade in the United Kingdom points to the slowest rate, 4.2%.
- Gulf trading hubs are handling a larger part of stone flows between Africa and Asia. Dubai coloured gemstone trade reached USD 1.1 billion in 2025, up 48%, with imports up 68.8%, Khaleej Times reported on 13 July 2026.[4] Import growth of that pace makes Dubai a main clearing point for rough and cut stones, which adds dealer and grading activity in GCC Countries.
Market Size & Forecast
Table 1: Market Size and Forecast for the Coloured Gemstone Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.9 billion |
| Estimated Market Size in 2026 | USD 2.1 billion |
| Projected Market Size by 2036 | USD 6.2 billion |
| CAGR, 2026 to 2036 | 11.3% |
| Added Revenue, 2026 to 2036 | USD 4.1 billion |
| Market Expansion Multiple | 3.0x |
Auction prices for coloured rough are rising as more cutters and brands compete for graded lots. For instance, Gemfields sold all 44 lots of commercial-quality emeralds for USD 29.6 million in an auction that closed on 10 September 2026.[5] A full clearance of every lot shows bidder demand running ahead of commercial emerald supply. The ruby side added USD 23.1 million in June 2026 at an average of USD 66.30 per carat.[6] Ruby lots at that price level keep mid-grade stones within reach of jewellery brands. Within gems overall, coloured stones are a fast-moving part of a larger pool, as the gemstones market grows at a forecast 6.6% CAGR. In FMI's projection, the coloured gemstone market will triple between 2026 and 2036, adding about USD 4.1 billion. Buyer access to sales events is the weak point. However, travel disruption around Middle East tensions is the near-term risk, as Petra Diamonds said in April 2026 that tender attendance suffered.[2] Lower attendance thins the bidder pool at tenders, so miners with online bidding and several sales locations hold prices better.
Auction Supply, Coloured Diamonds and Retail Jewellery
Premium ruby supply is tightening as grades fall at the main mine. In rubies, Gemfields reported low premium ruby grades at Montepuez, 0.025 carats per tonne, and said the second processing plant made a meaningful contribution to volume.[1] Lower grades mean fewer top rubies reach each auction, even with more ore processed. By contrast, Kagem in Zambia kept healthy premium emerald output over the same half.[1] Steady emerald output makes that stone the more reliable choice for brands planning large collections, and the ruby shortfall keeps top-grade auction prices high.
Coloured diamonds occupy the top of the price range. For example, Petra Diamonds recovered the 41.82 carat blue diamond at Cullinan in December 2025 and keeps a share of the profit from the polished stone.[2] Profit sharing on the polished stone lets the miner capture more of the value of rare colour. Mass jewellers are also selling at higher price points. On the retail side, Signet Jewelers reported Q2 FY27 sales of USD 1,528.1 million, with same store sales up 2.2% and average unit retail up about 6%.[7] These higher ticket prices at mass jewellers leave more room for sapphire and emerald styles.
Table 2: Auction, Mine and Retail Indicators for the Coloured Gemstone Market (sales, prices and trade), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Gemfields auction sales, H1 2026 | USD 102.9 million; up 72% | Ruby and emerald supply | [1] |
| Gemfields commercial emerald auction, September 2026 | USD 29.6 million; 44 of 44 lots sold | Emerald price trend | [5] |
| Gemfields Trade Select ruby auction, June 2026 | USD 23.1 million; USD 66.30 per carat | Ruby and sapphire price trend | [6] |
| Petra Diamonds blue diamond sale, Q3 FY 2026 | 41.82 carat Type IIb stone sold by tender | Coloured diamond supply | [2] |
| Dubai coloured gemstone trade, 2025 | USD 1.1 billion; up 48% | Trading hub demand | [4] |
| Thailand gem and jewellery exports excluding gold, H1 2026 | USD 8,253.19 million; up 11.58% | Cutting and export activity in ASEAN | [8] |
| LVMH Watches & Jewelry, H1 2026 | EUR 5,225 million; up 9% organic | Luxury jewellery demand | [3] |
Analyst Perspective
“Emeralds and rubies with a proven mine of origin will draw the strongest bids through 2036, and auction houses that publish lot counts and prices give buyers the confidence to commit. I expect lab-created stones to take the lower price points in fashion jewellery, widening the bidder pool for traded emerald lots, and miners will keep the premium end natural. Retailers who tell the origin story at the counter will sell more coloured stone engagement rings.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the coloured gemstone market segmented?
The market is segmented into product type, product format, end use, and region. Sapphire leads product type with 31% share in 2026, and natural stones lead product format with 74%.
By product type: sapphire, emerald, ruby, coloured diamonds, and others.
By product format: natural and synthetic.
By end use: jewellery, investment and collection, and watches and accessories.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does sapphire lead coloured gemstone sales by product type?
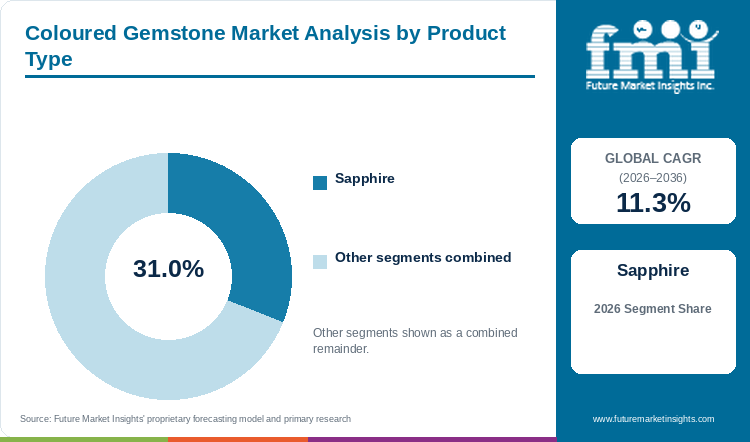
Sapphire is expected to lead product type sales with 31% share in 2026, ahead of emerald at 22% and ruby at 18%.
Table 3: Product Type Share for the Coloured Gemstone Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Sapphire | 31% |
| Emerald | 22% |
| Ruby | 18% |
| Coloured Diamonds | 15% |
| Others | 14% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Coloured Gemstone Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 11.3% |
| Leading Segment | Sapphire |
Sapphire is expected to lead the stone mix with 31% of 2026 sales, as sapphire comes in blue, pink, yellow and padparadscha tones, is hard enough for daily rings and is mined in many countries. By comparison, emerald, at 22%, carries strong bridal and high-jewellery appeal but needs oil treatment and careful setting. Ruby, at 18%, comes from a few mines, and Montepuez reported low premium grades in H1 2026.[1] Thin premium output caps ruby volume, so jewellers fill colour ranges with sapphire. Coloured diamonds, at 15%, are the costliest per carat and so sell in small volumes. Tanzanite, spinel, tourmaline and other stones make up 14%. Auction houses are widening the sapphire offer. On supply, Gemfields introduced sapphire categories at the June 2026 Trade Select ruby auction.[6] Over time, wider sapphire supply through auctions will keep blue stones the first choice for engagement rings.
- Blue sapphire, fancy-colour sapphire and padparadscha make up the sapphire group.
- Mixed ruby and sapphire auctions are clearing most of the lots offered. At the June 2026 auction, 82 of 89 lots sold, covering 348,409 carats.[6] A high sell-through on that volume shows cutters absorbing commercial-grade corundum at current prices.
Why do natural stones lead coloured gemstone sales by product format?
Natural stones are projected to lead product format sales with 74% share in 2026, with synthetic stones at 26%.
Table 5: Product Format Share for the Coloured Gemstone Market (percentage share), 2026
| Product Format | Estimated Share (2026) |
|---|---|
| Natural | 74% |
| Synthetic | 26% |
| Total | 100.0% |
Natural stones are projected to hold 74% in 2026, as buyers pay for rarity and origin. By contrast, synthetic stones, at 26%, offer the same chemistry and colour at a fraction of the price, and brands such as Chatham Created Gems sell them for fashion pieces and budget engagement rings. This price gap keeps synthetics growing in carats faster than in value. Demand for mined rough remains broad despite cheaper synthetics. Even so, Gemfields drew bids from 63 companies at the September 2026 commercial emerald auction.[5] Bidder numbers at that level keep natural emerald prices firm even as synthetics expand at the low end. Lab-grown stones also compete with mined diamonds, a contest reflected in the 5.1% CAGR projected for the synthetic diamond market. Natural stones will keep the value lead as long as origin and rarity set price.
- Mined emerald, ruby and sapphire rough, cut in Thailand, India and Sri Lanka, forms the natural base.
- Miner finances shape how much natural rough reaches auction. Gemfields reported net debt of USD 44.2 million at 30 June 2026, before USD 33.3 million of auction receivables.[1] Receivables covering most of that debt let Gemfields keep a regular auction calendar without cutting supply.
Why does jewellery lead coloured gemstone sales by end use?
Jewellery is estimated to lead end-use sales with 71% share in 2026, ahead of investment and collection at 17% and watches and accessories at 12%.
Table 6: End Use Share for the Coloured Gemstone Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Jewellery | 71% |
| Investment and Collection | 17% |
| Watches and Accessories | 12% |
| Total | 100.0% |
Jewellery is estimated to lead end-use demand at 71% in 2026, as rings, pendants and earrings absorb most cut stones. Investment and collection, at 17%, covers top-grade stones bought at auction and held by collectors, a channel limited by the small number of certified premium stones. Smaller still, watches and accessories, at 12%, use calibrated sapphires and rubies on dials and bezels. Luxury houses are featuring coloured stones more prominently. In high jewellery, Bulgari reported strong growth and high demand for the Eclettica high jewellery vision in H1 2026.[3] Collections of that kind use top sapphires, emeralds and rubies, which supports prices at the premium end. Fine jewellery demand also drives the luxury fine jewellery market, which is forecast at a 6% CAGR. In all, jewellers will remain the main buyer of cut coloured stones.
- Engagement rings, high jewellery and fashion pieces form the jewellery segment.
- Chinese jewellers are moving beyond gold into high jewellery. Chow Tai Fook launched Timeless Harmony, the group's first high jewellery collection, in FY2026.[9] A first high jewellery line from a gold-led retailer opens Chinese store counters to coloured stones.
What are the drivers, restraints, and opportunities in the coloured gemstone market?
Traceable auction supply and colour-led bridal choices keep demand for coloured gemstones rising. Thin premium mine grades and travel disruption restrain trade, and lab-created stones open lower-priced fashion lines.
- Driver: Couples choosing colour over white diamonds and brands building collections around named origins create repeat demand for graded stones.
- Restraint: A few mines supply most premium rubies and emeralds, so weak grades or travel disruption cut supply and raise prices at the next auction.
- Opportunity: Lab-created sapphires and emeralds let fashion jewellers offer colour at lower prices, adding buyers who would not pay for mined stones.
Origin-Documented Auctions Build Buyer Confidence
Traceable supply turns coloured stones from a trader-only purchase into a branded product. For example, Gemfields auction sales rose 72% in the first half of 2026.[1] Higher auction revenue shows brands and cutters paying more for traceable lots. At the same time, the average commercial emerald price rose to USD 9.72 per carat from USD 7.46 in the November 2025 round.[5] As a result, brands can now plan collections around a known flow of graded stones, though at a rising cost per carat.
Thin Premium Grades and Travel Disruption Restrain Supply
Premium carats come from a small number of deposits, and a weak grade period cannot be made up quickly. For instance, Montepuez premium ruby output ran at 0.025 carats per tonne in H1 2026.[1] At that grade, miners process more ore for each premium stone, which raises unit cost. Demand-side disruption adds to the supply squeeze. In addition, Petra Diamonds said Middle East tensions dampened sentiment and travel in early 2026.[2] Consequently, in FMI's view, buyers of top-grade rubies face the tightest supply through 2028.
Lab-Created Stones Open Lower-Priced Fashion Lines
Lab-created sapphires and emeralds let jewellers sell colour at entry prices. Mass jewellers are adding fashion colour lines as shoppers trade up. At the mass end, Signet Jewelers raised average unit retail about 6% in Q2 FY27, with growth in both bridal and fashion.[7] Rising ticket sizes in both bridal and fashion give mass retailers room to add lab-created colour lines next to mined stones. In turn, fashion ranges using lab-created colour will bring younger buyers into the category.
Which country CAGRs are profiled in the coloured gemstone market?
Table 7: Country CAGR Comparison for the Coloured Gemstone Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| ASEAN | 12.6% |
| India | 6.3% |
| China | 5.9% |
| GCC Countries | 5.4% |
| United States | 4.7% |
| United Kingdom | 4.2% |
How do country-level CAGRs compare in the coloured gemstone market?
Cutting and trading centres in Southeast Asia are growing faster than consumer markets. Thailand exported USD 8,253.19 million of gems and jewellery excluding gold in January to June 2026, up 11.58%.[8] On this export base, FMI expects the South Asia and Pacific region to grow at 13.2%, with ASEAN the fastest of the six countries at 12.6%, 1.3 points faster than the global CAGR. Behind ASEAN, large jewellery buyer bases add volume in India (6.3%) and China (5.9%). GCC Countries are forecast at 5.4% on Dubai trading, and the United States at 4.7% on bridal and fashion sales. By comparison, the United Kingdom, at 4.2%, is a mature market for coloured stone rings. Much of the 11.3% global rate comes from cutting and trading centres in South Asia and Pacific, and the large consumer countries grow more slowly.
- Bangkok and Chanthaburi cutters process rough from Africa and Asia for re-export, so ASEAN demand centres on rough buying at auction, and miners selling graded lots gain steady Thai bidders.
- Jaipur workshops turn commercial emerald rough into calibrated stones for export and Indian bridal sets, giving emerald miners a large, price-sensitive buyer group in India.
- Chinese jewellers built around gold are adding coloured stones to high jewellery and fixed-price lines, a shift that opens premium store space in China for suppliers of calibrated, certified stones.
- Dubai acts as a clearing house between African mines and Asian cutters; rising re-exports add dealer and grading demand across GCC Countries more than local jewellery buying does.
- Rising average tickets at Signet give mass retailers in the United States room for sapphire and emerald styles, though a large, mature bridal base keeps growth under the global pace.
- High-income British buyers already own many coloured stone rings, so demand in the United Kingdom rests on replacement and collector purchases through London dealers and auction houses.
Full report country CAGRs cover: one cutting hub well above 11.3% and five consumer markets between 4.2% and 6.3%, with remaining standard countries shown by region.
Country-wise Analysis
ASEAN Coloured Gemstone Market Outlook (2026 to 2036)
Thai exporters are adding gem volume on strong overseas demand. Thailand ranked gems and jewellery, including gold, as the second most important export group in H1 2026, with an 8.60% share of total exports, the Gem and Jewelry Institute of Thailand said.[8] A high export share keeps Thai cutters buying rough throughout the year. At the trade level, Bangkok and Chanthaburi cutters process sapphire and ruby rough from Africa and Asia. FMI analysts expect a 12.6% CAGR for ASEAN on that cutting base.
Key takeaway: Thai cutting capacity makes ASEAN the main buyer of graded rough, so miners with regular auctions secure the most consistent Asian demand.
India Coloured Gemstone Market Outlook (2026 to 2036)
Miners are courting Indian cutters directly. Gemfields held private viewings in Jaipur before the September 2026 commercial emerald auction, which drew 63 bidding companies.[5] Viewings in Jaipur bring Indian buyers closer to graded supply and raise bidder competition. Locally, Jaipur cutters turn commercial emerald rough into calibrated stones for export and domestic jewellery. As a result, Indian demand is predicted to rise at 6.3%, helped by bridal buying.
Key takeaway: Indian growth rests on emerald cutting for export and bridal jewellery, which ties local demand closely to auction prices.
China Coloured Gemstone Market Outlook (2026 to 2036)
Large Chinese jewellers are widening collections beyond gold. Chow Tai Fook reported FY2026 revenue of HK$94,398 million, up 5.3%, and launched Timeless Harmony as the group's first high jewellery collection.[9] However, gold still dominates Chinese jewellery, so coloured stones grow from a small base in premium stores. FMI projects a 5.9% CAGR for China as premium stores add coloured lines.
Key takeaway: Coloured stones in China grow through premium counters at gold-led chains, so suppliers of calibrated stones gain as these chains add high jewellery.
GCC Countries Coloured Gemstone Market Outlook (2026 to 2036)
Dubai is drawing more of the coloured stone trade. Dubai coloured gemstone imports rose 68.8% and re-exports 33.5% in 2025, according to Dubai Customs data released by DMCC.[4] In practice, traders route stones from Africa and Asia through Dubai to buyers in the Gulf, Europe and Asia. Such re-export trade points to a 5.4% CAGR for GCC Countries.
Key takeaway: Gulf demand comes mainly from dealers and re-exporters, so trading volumes, more than local jewellery sales, set growth in GCC Countries.
United States Coloured Gemstone Market Outlook (2026 to 2036)
American jewellery sales are steady at both mass and luxury levels. Signet Jewelers expects FY27 sales of USD 6.7 billion to USD 6.9 billion and raised the adjusted operating income outlook in September 2026.[7] A higher profit outlook suggests mass jewellers are selling at better margins, which supports coloured stone styles at mid prices. Alongside this, LVMH said growth in the United States accelerated in the first half of 2026.[3] FMI projects demand in the United States to grow at 4.7%, with mass and luxury jewellers sharing the gains.
Key takeaway: US buyers spread purchases across mass and luxury jewellers, and a mature bridal base keeps growth below the global pace.
United Kingdom Coloured Gemstone Market Outlook (2026 to 2036)
British jewellers such as Boodles sell sapphire and emerald rings to a mature, high-income buyer base. London also hosts gem dealers and auction houses that resell collector stones. Given this mature base, the United Kingdom is projected at 4.2%.
Key takeaway: British demand relies on replacement buying and collector resale, which favours London dealers over new retail entrants.
Who are the notable companies in the coloured gemstone market?
Gemfields, Fura Gems, Greenland Ruby, MIF Gems, Petra Diamonds, Gem Diamonds, De Beers Group, Tiffany & Co., Bulgari, Cartier, Signet Jewelers, Chow Tai Fook, Brilliant Earth, Swarovski and Chatham Created Gems are the profiled companies.
The profiled companies span miners, luxury and mass jewellers, and lab-created gem makers. Among the miners, Gemfields mines emeralds at Kagem in Zambia and rubies at Montepuez in Mozambique.[1] Control of two large deposits gives Gemfields a regular supply of graded emerald and ruby lots. At LVMH, Watches & Jewelry profit from recurring operations rose 9% to EUR 831 million in H1 2026.[3] Higher jewellery profit gives LVMH room to buy top stones for high jewellery. Likewise, Chow Tai Fook reported a profit of HK$9,004 million for FY2026.[9] Strong profit gives Chow Tai Fook scope to widen coloured stone ranges.
- Miners and producers: Gemfields, Fura Gems, Greenland Ruby, MIF Gems, Petra Diamonds, Gem Diamonds and De Beers Group.
- Jewellers and brands: Tiffany & Co., Bulgari, Cartier, Signet Jewelers, Chow Tai Fook, Brilliant Earth and Swarovski.
- Lab-created gem makers: Chatham Created Gems.
Competitive Benchmarking: Coloured Gemstone Market
Table 8: Competitive Benchmarking for the Coloured Gemstone Market (qualitative ratings), 2026
| Company | Rough Supply | Retail Jewellery | Auction Pricing | Recent Activity |
|---|---|---|---|---|
| Gemfields | High | Low | High | High |
| Petra Diamonds | Medium | Low | Medium | High |
| Tiffany & Co. | Low | High | Low | High |
| Signet Jewelers | Low | High | Low | High |
| Chow Tai Fook | Low | High | Low | Medium |
Ratings compare the companies on rough supply, retail jewellery, auction pricing and recent activity.
Key Developments in the Coloured Gemstone Market
- Gemfields announced USD 29.6 million from a commercial-quality emerald auction on 11 September 2026, a result that confirms steady demand for mid-grade emerald.[5]
- In results of 9 September 2026, Signet Jewelers raised the FY27 adjusted operating income outlook alongside Q2 sales of USD 1,528.1 million, which signals steady mass bridal demand in the United States.[7]
- Gemfields raised USD 23.1 million from the first Trade Select ruby auction, as reported on 4 August 2026; for buyers, this adds a new route to commercial ruby and sapphire.[6]
- Gemfields auction sales for H1 2026 rose 72%, as reported on 31 July 2026, which points to strong bidding for traceable emerald and ruby.[1]
- On 27 July 2026, LVMH said Bulgari and Tiffany & Co. drove Watches & Jewelry to EUR 5,225 million in H1 sales, showing luxury jewellery demand holding firm.[3]
- Dubai coloured gemstone trade reached USD 1.1 billion for 2025, according to Dubai Customs data reported on 13 July 2026, which confirms Dubai as a growing trading hub.[4]
- Chow Tai Fook's FY2026 results of 11 June 2026 showed mainland same-store sales up 6.9%, giving the group room to expand high jewellery.[9]
- On 1 April 2026, Petra Diamonds reported the sale of a 41.82 carat Type IIb blue diamond, a reminder of the premium that rare coloured diamonds draw at tender.[2]
Key Players in the Coloured Gemstone Market
Miners and Producers
- Gemfields
- Fura Gems
- Greenland Ruby
- MIF Gems
- Petra Diamonds
- Gem Diamonds
- De Beers Group
Jewellers and Brands
- Tiffany & Co.
- Bulgari
- Cartier
- Signet Jewelers
- Chow Tai Fook
- Brilliant Earth
- Swarovski
Lab-Created Gem Makers
- Chatham Created Gems
Coloured Gemstone Market - Report Scope
Table 9: Report Scope for the Coloured Gemstone Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; product format; end use; region |
| Quantitative units | USD billion |
| Market definition | Cut and rough coloured precious and semi-precious stones, including sapphire, emerald, ruby, coloured diamonds and other gems, natural or lab-created, sold for jewellery, collection and accessories. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Gemfields, Fura Gems, Greenland Ruby, MIF Gems, Petra Diamonds, Gem Diamonds, De Beers Group, Tiffany & Co., Bulgari, Cartier, Signet Jewelers, Chow Tai Fook, Brilliant Earth, Swarovski, Chatham Created Gems |
| Forecast period | 2026 to 2036 |
Coloured Gemstone Market - Research Methodology
Table 10: Research Methodology for the Coloured Gemstone Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government trade statistics and jewellery trade publications. |
| Desk Research | Auction prices and lot counts, mine grades, coloured diamond tenders, trading hub flows and retail jewellery results. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 2.1 billion and the 11.3% CAGR for 2026 to 2036. |
| Data Validation | Auction, trade and sales figures are cross-checked across company, industry and government sources. |
Coloured Gemstone Market by Segments
Coloured Gemstone Market segmented by Product Type:
- Sapphire
- Emerald
- Ruby
- Coloured Diamonds
- Others
Coloured Gemstone Market segmented by Product Format:
- Natural
- Synthetic
Coloured Gemstone Market segmented by End Use:
- Jewellery
- Investment and Collection
- Watches and Accessories
Coloured Gemstone Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] National Jeweler. (2026, July 31). Gemfields' H1 revenue jumps 72%. https://nationaljeweler.com/articles/15183-gemfields-h1-revenue-jumps-72
- [2] Petra Diamonds Limited. (2026, April 1). Sales results for Q3 FY 2026 and sale of 41.82 carat Type IIb blue diamond. https://news.cision.com/petra-diamonds-limited/r/sales-results-for-q3-fy-2026-and-sale-of-41-82-carat-type-iib-blue-diamond,c4329703
- [3] LVMH Moët Hennessy Louis Vuitton. (2026, July 27). Accelerating growth in the second quarter: solid first half results. https://www.lvmh.com/en/publications/accelerating-growth-in-the-second-quarter---solid-first-half-results
- [4] Khaleej Times. (2026, July 13). Dubai's diamond trade sparkles to record $41.7 billion in 2025. https://www.khaleejtimes.com/business/dubais-diamond-trade-sparkles-to-record-417-billion-in-2025
- [5] Gemfields Group Limited. (2026, September 11). Auction Results: Commercial-Quality Emeralds. https://www.investegate.co.uk/announcement/rns/gemfields-group-limited--gem/auction-results-commercial-quality-emeralds/9766633
- [6] Agência de Informação de Moçambique, via AllAfrica. (2026, August 4). Mozambique: Gemfields earns $23.1 million from auction of ruby. https://allafrica.com/stories/202608040030.html
- [7] Signet Jewelers Limited. (2026, September 9). Signet Jewelers Reports Second Quarter Fiscal 2027 Results (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000832988/000083298826000227/fy27ex99109x09x26pressrele.htm
- [8] The Gem and Jewelry Institute of Thailand. (2026, August 11). Thailand Gem and Jewelry Import-Export Performance January - June 2026. https://infocenter.git.or.th/en/article/article-20260811
- [9] Chow Tai Fook Jewellery Group. (2026, June 11). Chow Tai Fook Jewellery reports record high profit, brand transformation delivering high-quality earnings growth. https://www.accessnewswire.com/newsroom/en/metals-and-mining/chow-tai-fook-jewellery-reports-record-high-profit-brand-transformation-deliverin-1175989
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the coloured gemstone market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which product format holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Sapphire
- Emerald
- Ruby
- Coloured Diamonds
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Product Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format, 2026 to 2036
- Natural
- Synthetic
- Y-o-Y Growth Trend Analysis By Product Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Jewellery
- Investment and Collection
- Watches and Accessories
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Product Format
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Product Format
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Product Format
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Product Format
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Gemfields
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Petra Diamonds
- Tiffany & Co.
- Signet Jewelers
- Chow Tai Fook
- Fura Gems
- Greenland Ruby
- MIF Gems
- Gem Diamonds
- De Beers Group
- Bulgari
- Cartier
- Brilliant Earth
- Swarovski
- Chatham Created Gems
- Gemfields
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Product Format, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Product Format
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Format
- Figure 29: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End Use
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Product Format
- Figure 39: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End Use
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Product Format
- Figure 49: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End Use
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Product Format
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Product Format
- Figure 69: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End Use
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Product Format
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Product Format, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Product Format, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Product Format
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the coloured gemstone market expected in 2026?
In FMI's estimate, the coloured gemstone market will reach USD 2.1 billion in 2026, against USD 1.9 billion in 2025. Sales of coloured gemstones are projected to reach USD 6.2 billion by 2036.
What CAGR is projected for the coloured gemstone market through 2036?
The coloured gemstone market is expected to grow at an 11.3% CAGR through 2036. Auction supply with traceable origin and colour-led bridal jewellery carry that growth.
Which product type holds a notable market share in 2026?
Sapphire is expected to lead with 31% share. Emerald follows at 22%.
Which product format holds a notable market share in 2026?
Natural stones will lead with 74% share. Synthetic stones hold 26%.
Which country has a notable expansion outlook through 2036?
FMI expects ASEAN to expand quickest, at a 12.6% CAGR. India follows at 6.3%.
Who are the key companies in the coloured gemstone market?
Gemfields, Fura Gems, Greenland Ruby, MIF Gems, Petra Diamonds, Gem Diamonds and De Beers Group supply stones. Tiffany & Co., Bulgari, Cartier, Signet Jewelers, Chow Tai Fook, Brilliant Earth, Swarovski and Chatham Created Gems sell finished jewellery and lab-created stones.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
