
- Market Size (2026)
- USD 39.8 Bn
- Forecast (2036)
- USD 74.7 Bn
- CAGR (2026 to 2036)
- 6.5%
How Big Is the Dispersants Market in 2026?
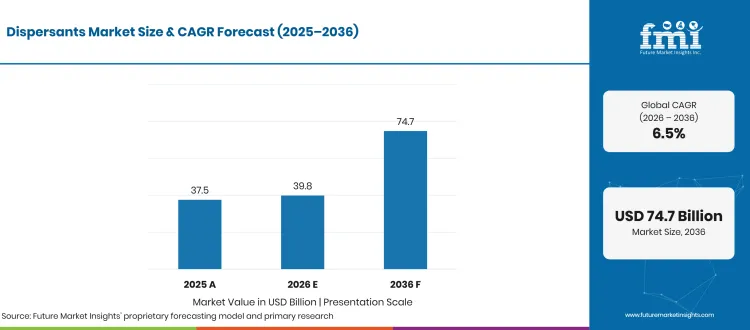
The global dispersants market reaches USD 39.8 billion in 2026, up from USD 37.5 billion in 2025, and is projected by Future Market Insights (FMI) to reach USD 74.7 billion by 2036, expanding at a 6.5% CAGR from 2026 to 2036 and generating USD 34.9 billion in incremental revenue over the 10-year forecast period.
| Market Metric | Valuation / Share / Forecast Benchmark |
|---|---|
| 2025 Market Size (Historical) | USD 37.5 billion |
| 2026 Market Size (Estimated) | USD 39.8 billion |
| 2036 Market Size (Projected) | USD 74.7 billion |
| Compound Annual Growth Rate (2026 to 2036) | 6.5% CAGR |
| Incremental Dollar Opportunity (2026 to 2036) | USD 34.9 billion (1.88-fold expansion) |
| Dominant Chemical Type (2026 to 2036 Share) | Polymeric Dispersants (44.2% in 2026, rising to 47.5% by 2036) |
| Leading & Fastest-Growing Chemical Types | Polymeric Dispersants (44.2% share in 2026) | Bio-Based & Lignosulfonate Dispersants (7.4% CAGR) |
| Leading & Fastest-Growing End-Use Industries | Construction (29.5% share in 2026) | Paints & Coatings (6.9% CAGR) |
| Dominant Physical Form (2026 Share) | Liquid Dispersants (68.4% revenue share in 2026) | Powder & Granular (6.1% CAGR) |
| Largest Country Markets (2026 Global Share) | China (22.0%, USD 8.76 billion), United States (20.0%, USD 7.96 billion), Germany (7.0%, USD 2.79 billion) |
| Fastest-Growing Country Markets (2026 to 2036) | China (7.8% CAGR), United States (7.2% CAGR), Australia (7.0% CAGR), Canada (6.9% CAGR) |
| Leading Tier-1 Companies | BASF SE, Sika AG, Evonik Industries AG, Arkema SA, The Lubrizol Corporation, Clariant AG, Croda International Plc, Borregaard ASA, Nouryon, Ecolab Inc., Eastman Chemical Company |
Source: Future Market Insights analysis of the dispersants market, 2026.
Executive Market Overview
Buyers of dispersants are formulators and plant engineers who rarely pick a molecule on chemistry alone, because what they pay for is pigment that stays dispersed and cement that stays workable. Their purchasing habits follow distinct routines. A coatings plant qualifies a dispersant on a mill and then keeps that grade for years, so an approved additive sits inside a paint formula far longer than its development cycle. A concrete plant buys per truckload and changes supplier when a new aggregate source shifts the clay load. Regional value follows the same pattern, with North America and East Asia holding 58.4% of consumption in 2026, while Latin American coating plants still converting solventborne lines to waterborne add a disproportionate slice of new volume from the smallest base.
Margin pressure on the baseline product sits in the acrylic acid and maleic anhydride feedstocks every supplier buys, and it lands hardest on commodity sulfonate grades where there is little left to differentiate. The commercial answer is to move the customer up the value curve without asking for a new mixing vessel. BASF SE (July 2026) put a REDcert2 biomass-balanced dispersant on the market so a paint buyer can cut Scope 3 emissions without touching the plant, and Borregaard ASA (July 2026) showed wood-based lignosulfonate coatings cutting ammonia loss from urea granules by 20% to 40%. FMI sees polymeric dispersants advancing at a 6.2% CAGR against 6.8% for bio-based polymeric grades through 2036. Scope covers aqueous and solventborne dispersing additives for paints, construction, agrochemicals and industrial water treatment, and excludes thickeners, defoamers, unformulated mineral fillers and standalone flocculants.
Analyst Perspective
"Formulators in ready-mixed concrete and industrial coatings are shifting procurement toward comb-branched polymeric and biomass-balanced dispersants because low-clinker blended cements and universal waterborne colorants require steric stabilization that conventional sulfonates cannot hold. Suppliers that pair regional synthesis capacity in China and North America with verified clay-tolerance and zero-VOC performance data are capturing multi-year supply contracts through 2036." The primary operational risk stems from volatile acrylic acid and maleic anhydride feedstock costs alongside tightening REACH restrictions on legacy alkylphenol ethoxylate surfactants.
- Rahul Pandita, Principal Consultant, Future Market Insights (FMI)
Major Market Trends and Insights
- Controlled Free-Radical Polymerization Scales High-Solids Coating Dispersants: Coating plants are consolidating solventborne and waterborne tinting lines around high-solids polymeric dispersants that keep pigment from re-agglomerating, and the grinder time they recover is what makes the switch pay. BASF SE started a dedicated CFRP dispersant line at Nanjing in November 2025, and The Lubrizol Corporation introduced Solsperse W60 in July 2025, a 90% active APE-free grade delivering 103.6% color strength in oil-based enamels and 97.5% in latex paints, sold in a package that already carries anti-foaming agents and defoamers.
- Nanomaterial and Biomass Monomer Grafting Upgrades Cement Superplasticizers: Admixture producers graft functional nanomaterial and cellulose monomers onto polycarboxylate backbones to cut cement carbon intensity without giving up early strength, the only route a readymix producer accepts when a specifier tightens the embodied-carbon limit. Zhang, Gan, Lu, Li and Lu (March 2025) in Nanomaterials found PCE-modified graphene oxide lifts 7-day paste flexural strength by 23.7% and compressive strength by 12.6% while cutting total porosity 45.3%. Kou, Huang, Chen, Chu, Zhou and Yin (July 2025) in Materials showed 5% TPEG replaced by acryloyl hydroxyethyl cellulose at 0.4% dosage delivering 27.3% water reduction and a 30% to 40% mortar strength gain.
- Biodegradable Polymeric Dispersants Capture High-Electrolyte Crop Protection: Agrochemical formulators are retiring nonylphenol ethoxylates in favour of readily biodegradable acrylic and polymeric grades that keep suspension concentrates and water-dispersible granules stable when the electrolyte load is high and the tank sits in the sun. BASF SE launched Sokalan CP 301 in April 2025 for exactly that duty, and Clariant AG brought Dispersogen PSL 100 and Tonnegel 50 to CAC 2026 in Shanghai in March 2026 to stabilize biological and high-load crop formulations paired with agricultural coatings.
- Automated Scale Control Boosts Water-Treatment Dispersants: Hyperscale data centres and microelectronics fabs are replacing manual dosing of polymeric scale inhibitors with monitored dosing loops, because a cooling tower run a point hot loses makeup water and chemical in equal measure. Ecolab Inc. launched Ecolab Water Navigator IQ across more than 170 countries in April 2026, combining real-time sensor telemetry with industrial wastewater treatment chemicals and polyacrylate dispersants that block calcium carbonate and silica deposition before a scale layer ever forms on the fill.
What Are the Main Drivers, Restraints, and Opportunities?
Low-clinker blended cements and data-centre construction pull dispersant dosage higher, while swelling clay in quarry aggregates and stricter surfactant audits push formulators toward expensive specialty grades and away from the commodity baseline.
Driver: Low-Clinker Blended Cements and Infrastructure Construction
Ready-mixed concrete producers are switching to Type IL portland-limestone and slag-blended cements, and each of those mixes demands more steric-hindrance PCE dispersant to hold pumpability at an unchanged water-to-binder ratio. The U.S. Geological Survey (February 2026) reported blended cement at 63% of United States cement shipments through the first nine months of 2025, and Sika AG (October 2026) posted nine-month sales of CHF 8.71 billion, up 4.8% in local currency, with EMEA up 8.3% on German federal infrastructure disbursement. Contractors pairing PCE superplasticizers with concrete surface treatment chemicals cut water demand and shorten formwork turnaround on transport and power projects, which is what turns a compliance-driven cement switch into a paid additive order.
Restraint: Swelling Clay Interference in Aggregates and Stricter Surfactant Reviews
Washed river sand is running out, so concrete plants are working crushed manufactured sand carrying montmorillonite and muscovite that intercalate the polyoxyethylene side chains and strip PCE dispersants from solution before they reach cement. A June 2025 review by Gao, Liu, Wang, Liu, Cao and Yong in Materials measured montmorillonite adsorbing up to 415 mg/g of PCE against cement particles, with 6 wt% muscovite cutting paste spread flow by 51% at a 0.14% PCE dosage. On the regulatory side the U.S. Environmental Protection Agency (August 2026) issued its Reference Guide for Structural Classifications of Surfactants under TSCA Section 5, which lengthens pre-manufacture review for new amphiphilic dispersing substances and raises the cost of qualifying a fresh molecule in the US.
Opportunity: Biomass-Balanced Acrylics and Lignosulfonate Fertilizer Coatings
Bio-based and mass-balance grades let a paint or fertilizer buyer cut Scope 3 product carbon without rebuilding a mixing vessel, which removes the usual objection to a specification change. Borregaard ASA (July 2026) demonstrated that 0.1% to 1.0% w/w wood-based lignosulfonate applied as a urea granule coating and dust-control binder cuts ammonia volatilization by 20% to 40% and lifts nitrogen-use efficiency by 30% to 40%. In architectural coatings BASF SE (July 2026) launched REDcert2-certified Dispex AA 4145 MB, which replaces fossil feedstocks with certified renewable hydrocarbons at identical pigment-stabilization efficiency, so the buyer pays a premium for a claim rather than for a performance gain.
How Is the Dispersants Market Segmented?
The market splits by chemical type, end-use industry and physical form, with every axis benchmarked against the share it holds in 2026 and the pace at which it is being bought.
| Segmentation Axis | Sub-Segments Covered | 2026 Leading Segment & Share | Main Growth Benchmark (2026 to 2036) |
|---|---|---|---|
| Chemical Type | Polymeric Dispersants (PCE, Acrylics, Polyurethanes), Naphthalene Sulfonates (SNF/PNS), Lignosulfonates, Inorganic Phosphates, Bio-Based & Other Surfactants | Polymeric Dispersants (44.2% revenue share) | Polymeric share rises to 47.5% by 2036; Bio-Based & Lignosulfonates expand fastest at 7.4% CAGR |
| End-Use Industry | Construction, Paints & Coatings, Pulp & Paper, Detergents & Cleaning Agents, Oil & Gas, Agriculture, Water Treatment, Others | Construction (29.5% revenue share) | Paints & Coatings leads end-use expansion at 6.9% CAGR through 2036 |
| Physical Form | Liquid (Aqueous & Solvent-Based Solutions), Powder & Granular (Spray-Dried & Prilled) | Liquid Dispersants (68.4% revenue share) | Liquid expands at 6.7% CAGR vs. Powder & Granular at 6.1% CAGR |
| Region | East Asia, North America, Europe, South Asia & Pacific, Latin America, Middle East & Africa | East Asia (led by China at 22.0% global share) | China (7.8% CAGR) and United States (7.2% CAGR) pace global revenue additions |
Source: Future Market Insights analysis of the dispersants market, 2026.
Why Does the Polymeric Dispersants Segment Lead by Chemical Type?
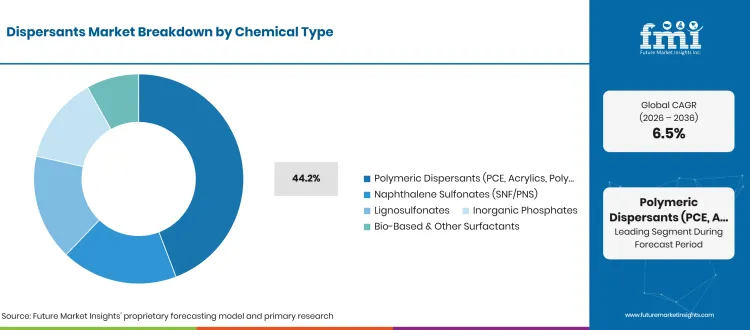
Polymeric dispersants hold 44.2% of global dispersants revenue in 2026 and are on course to reach 47.5% by 2036, ahead of naphthalene sulfonates and inorganic phosphates, because comb-branched polycarboxylates and controlled-architecture acrylics stabilize pigment at a dosage where a linear sulfonate condensate simply gives up. In high-electrolyte cement pore solutions or in high-pigment-volume coatings a sulfonate leans on electrostatic repulsion alone and loses effectiveness, whereas a polymeric grade anchors on the particle surface and pushes hydrophilic side chains into the continuous phase. The Lubrizol Corporation (July 2025) proved that mechanism commercially with Solsperse W60, a 90% active polymeric dispersant reaching 103.6% color strength in alkyd enamels and 97.5% in architectural latex, and formulators blending polymeric grades with silicone surfactants recover substrate wetting on low-energy industrial plastics as well.
Why Does the Construction Segment Lead by End-Use Industry?
Construction takes 29.5% of global dispersants revenue in 2026, held there by the mandatory dosing of superplasticizer into ready-mixed concrete, precast structural elements, self-leveling underlayments and gypsum wallboard. The U.S. Geological Survey (February 2026) confirmed that 70% to 75% of United States hydraulic cement shipments go straight to ready-mixed producers, and the move to Type IL portland-limestone, already 63% of nine-month 2025 shipments, forces tailored PCE dispersants that hold water demand down while the binder changes underneath. Paints and coatings is the faster-growing major end-use at a 6.9% CAGR through 2036, with architectural and automotive OEM formulators taking CFRP pigment dispersants from BASF SE (November 2025) and colloidal silica hybrids from Nouryon (April 2026), while deep-well drilling operators specify oilfield mud additives to thin bentonite and barite muds under high temperature.
Why Does the Liquid Segment Lead by Physical Form?
Liquid grades take 68.4% of global revenue in 2026 and expand at a 6.7% CAGR to 2036, with powder and granular products on 31.6% and 6.1%, because the buyers who matter run continuous processes. Ready-mixed batching plants, automated paint tinting lines and industrial cooling-water skids meter liquid aqueous solutions between 30% and 90% active solids straight through positive-displacement pumps, with no dust collection and no dissolution lag at the dosing point. BASF SE (July 2026) extended its European liquid architectural additive range with Dispex AA 4145 MB, an aqueous ammonium polyacrylate solution delivered in bulk IBC totes, and Borregaard ASA (July 2026) supplied lignosulfonate binders on the same bulk-handling logic. Spray-dried PCE and lignosulfonate powders remain essential in dry-mix tile adhesives and grouts, and in water-dispersible granules for crop protection.
Dispersants Market by Region and Country (2026 to 2036)
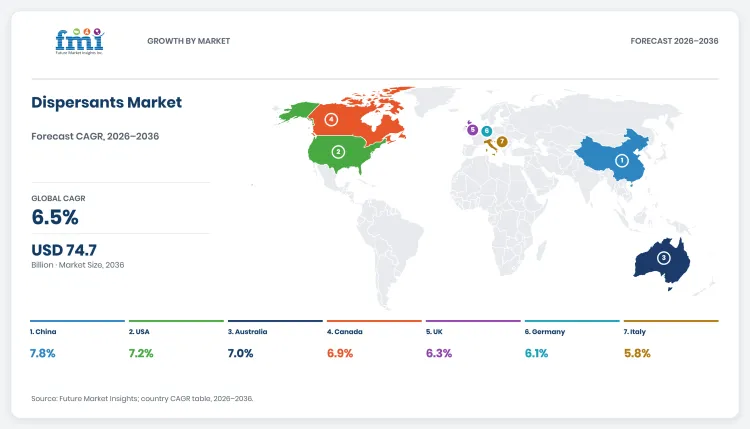
East Asia and North America absorb the largest share of the incremental value through 2036, and they do it for different reasons. Chinese coatings capacity and battery cathode slurry preparation add volume at a scale no other region matches, while United States chemical and data-centre construction pull dosage into architectural and industrial formulas. Europe behaves differently and for longer, because its coating and admixture plants are not adding volume so much as re-specifying what they buy, moving toward certified biomass-balanced grades and renovation-grade admixtures as solvent and microplastic rules tighten. The eight countries tracked below hold the largest national pools, with China alone at USD 8.76 billion in 2026, and their combined ten-year additions account for the bulk of the global USD 34.9 billion of new value.
| Country | 2026 Revenue | 2036 Revenue | 10-Year Addition | 2026 to 2036 CAGR | Global Share (2026 → 2036) |
|---|---|---|---|---|---|
| China | USD 8.76 billion | USD 18.56 billion | +USD 9.80 billion | 7.8% | 22.0% → 24.8% |
| United States | USD 7.96 billion | USD 15.95 billion | +USD 7.99 billion | 7.2% | 20.0% → 21.4% |
| Australia | USD 0.80 billion | USD 1.57 billion | +USD 0.77 billion | 7.0% | 2.0% → 2.1% |
| Canada | USD 1.19 billion | USD 2.32 billion | +USD 1.13 billion | 6.9% | 3.0% → 3.1% |
| United Kingdom | USD 1.59 billion | USD 2.93 billion | +USD 1.34 billion | 6.3% | 4.0% → 3.9% |
| Germany | USD 2.79 billion | USD 5.04 billion | +USD 2.25 billion | 6.1% | 7.0% → 6.7% |
| Italy | USD 1.39 billion | USD 2.44 billion | +USD 1.05 billion | 5.8% | 3.5% → 3.3% |
| France | USD 1.59 billion | USD 2.77 billion | +USD 1.18 billion | 5.7% | 4.0% → 3.7% |
Source: Future Market Insights analysis of the dispersants market, 2026.
China
China carries the largest national pool and the fastest growth rate, moving from USD 8.76 billion in 2026 to USD 18.56 billion by 2036 at a 7.8% CAGR, an addition of USD 9.80 billion that lifts its share of global value from 22.0% to 24.8%. The buying pattern here is industrial volume rather than premium specification. Ready-mixed concrete infrastructure, waterborne paint manufacturing and lithium iron phosphate cathode slurry preparation consume dispersants in bulk, and the specification is won on delivered cost. National Bureau of Statistics of China (October 2026) put cement output at 1.33 billion metric tons in mid-2026, and Nouryon (April 2026) commissioned an organic peroxide and dispersant plant at Ningbo to serve that volume. Through 2036 the limit on this market is not formulation know-how but how much of that 1.33 billion tons is still being poured.
United States
United States demand is set to rise at a 7.2% CAGR from USD 7.96 billion in 2026 to USD 15.95 billion by 2036, adding USD 7.99 billion of new sales and moving its share from 20.0% to 21.4%. The pull comes from low-VOC architectural coatings and construction admixtures supported by the Infrastructure Investment and Jobs Act, where federal spending turns into a specified additive order. The U.S. Census Bureau (October 2026) put total construction spending at USD 2,186.1 billion annualized in September 2026, and The Lubrizol Corporation (July 2025) brought hyperdispersant technology to water-based tinting systems that shortens mill work a pigment needs. What sets this market apart is the regulatory trigger, since formulators buy the substitute grade because a rule requires it. Through 2036 the USD 7.99 billion addition should keep arriving while commercial construction and low-VOC rules hold.
Australia
Australian volume expands at a 7.0% CAGR, from USD 0.80 billion in 2026 to USD 1.57 billion by 2036 for a 10-year addition of USD 0.77 billion, with the country holding roughly 2.0% of global value. The reason sits in the mining economy rather than in construction. Heavy civil engineering, iron-ore and lithium tailings management and coastal infrastructure projects need high-range water reducers and slurry viscosity modifiers that hold up in saline process water, a condition that shuts ordinary grades out. The Australian Bureau of Statistics (May 2026) reported construction work done up 3.4% quarter-on-quarter to AUD 83.4 billion in the March 2026 quarter, with engineering construction up 6.9% to AUD 38.7 billion. The multi-year resource pipeline means the buyer signs project agreements, not spot orders, so the USD 0.77 billion addition should arrive on the schedule of those contracts.
Canada
Canada grows at a 6.9% CAGR from USD 1.19 billion in 2026 to USD 2.32 billion by 2036, adding USD 1.13 billion over the decade and nudging its global share from 3.0% to 3.1%. Cold-weather placement drives the mix. Ready-mixed producers in a long freeze season need high-range polycarboxylate superplasticizers that keep workable at low temperature, and oil sands tailings dewatering adds a second stream of mineral slurry chemistry. Statistics Canada (October 2026) reported chemical sector factory sales up 2.8% year-over-year in August 2026, while Clariant AG (March 2026) expanded its agricultural and industrial adjuvant lines to serve that order book. Federal low-carbon procurement rules on Canadian infrastructure work add a specification driver firmer here than in several larger markets. Through 2036 the USD 1.13 billion addition should track project sanction rather than consumer demand.
United Kingdom
United Kingdom sales grow at a 6.3% CAGR, from USD 1.59 billion in 2026 to USD 2.93 billion by 2036, a 10-year addition of USD 1.34 billion, leaving the global share close to flat at 4.0% and 3.9%. The demand base is repair, not new build. British buyers spend on waterborne architectural repair coatings, home-care specialty polymers and civil repair admixtures, and the Office for National Statistics (October 2026) recorded repair and maintenance output up 0.4% in August 2026 even as new housing contracted 1.9%. Croda International Plc (July 2026) posted H1 2026 sales of GBP 880.5 million, up 4.6% organically, with New and Protected Products up 6.9%. Because the buyer is a refurbishment contractor on a fixed programme, the same grade is repurchased for years, so through 2036 the USD 1.34 billion addition should hold pace on refurbishment volume.
Germany
Germany remains Europe's largest national market, expanding 1.81-fold at a 6.1% CAGR from USD 2.79 billion in 2026 to USD 5.04 billion in 2036 for an addition of USD 2.25 billion, the global share easing from 7.0% to 6.7%. German chemical and admixture producers lead European commercialization of mass-balance architectural dispersants and low-clinker superplasticizers, which makes the country a specification market for the region, not a volume market. BASF SE (July 2026) launched its REDcert2 biomass-balanced Dispex AA 4145 MB pigment dispersant from Ludwigshafen, and Sika AG (October 2026) reported 8.3% EMEA local-currency growth in the first nine months of 2026, naming accelerating construction chemical sales in Germany as federal funds moved into execution. Through 2036 the USD 2.25 billion addition should be decided less by German construction volume than by how many European formulators copy a grade qualified here.
Italy
Italian consumption expands at a 5.8% CAGR from USD 1.39 billion in 2026 to USD 2.44 billion by 2036, adding USD 1.05 billion while the global share slips from 3.5% to 3.3%. The technical centre of gravity sits in the Sassuolo ceramic cluster, where tile body and glaze need deflocculation that will not tolerate the settling a cheaper grade allows, and precast admixtures follow rail corridors funded at European level. Sika AG (October 2026) logged 8.3% EMEA revenue growth across the first nine months of 2026 as Southern European infrastructure projects and commercial renovation offset residential softness, and BASF SE (July 2026) widened zero-VOC, APEO-free Dispex grades to Mediterranean coating formulators. Through 2036 the USD 1.05 billion addition should be carried by export-driven ceramic slab output and civil upgrades rather than the domestic building cycle.
France
French demand grows at a 5.7% CAGR from USD 1.59 billion in 2026 to USD 2.77 billion in 2036, an addition of USD 1.18 billion, with the global share moving from 4.0% to 3.7%. Rules do the buying. Low-carbon cement mandates under the RE2020 building framework and embodied-carbon thresholds on public works pull formulators toward dispersants that hold performance at lower clinker ratios, while agricultural formulation hubs add a second stream. Arkema SA (November 2026) reported Q3 2026 sales of EUR 2.4 billion, up 8.1% year-over-year, with EBITDA of EUR 332 million, and pointed to Coating Solutions growth driven by low-VOC rheology additives. Because the French buyer writes compliance into the tender document, the qualified grade changes less often than in markets where price decides, so through 2036 the USD 1.18 billion addition should follow the tightening of embodied-carbon thresholds.
Competitive Environment and Notable Companies
Notable companies operating in the global dispersants market include BASF SE, Sika AG, Evonik Industries AG, Arkema SA, The Lubrizol Corporation, Clariant AG, Croda International Plc, Borregaard ASA, Nouryon, Ecolab Inc., and Eastman Chemical Company. The value chain has three commercial tiers: integrated polymer and surfactant groups that make their own monomers and run regional application laboratories, construction-chemical specialists with captive polycarboxylate synthesis selling into readymix plants, and service providers that sell dosing and monitoring rather than the molecule. Tier-1 multinational producers hold roughly 52% to 58% of global market value, which is why monomer cycles still set the price floor for the category.
How Are Companies Positioned in the Dispersants Market?
The market divides into companies that make the molecule, companies that make it work in one application, and companies that sell the dosing service. BASF SE, Evonik Industries AG, Arkema SA, The Lubrizol Corporation and Clariant AG control the chemistry from monomer to application laboratory, while Sika AG runs captive polycarboxylate synthesis aimed at readymix plants. The 2026 shift is regional. BASF SE (November 2025) and Nouryon (April 2026) added Chinese production at Nanjing and Guangzhou to serve Asia-Pacific formulators directly, and Evonik Industries AG (February 2026) consolidated its United States and Canadian distributor network to shorten technical qualification cycles for North American coating accounts.
What Matters When a Buyer Selects a Dispersant Supplier?
Ready-mixed concrete and industrial coating procurement teams judge a supplier on active-solids concentration, clay and electrolyte tolerance, volatile-organic-compound compliance and bulk-tank delivery reliability. In concrete batching the test is the aggregate, and Gao et al. (June 2025) showed montmorillonite clay adsorbing 415 mg/g of PCE, which makes sacrifice-agent compatibility and side-chain density the deciding criteria, not price per kilo. In coatings the buyer wants one grade that works across waterborne latex and solventborne alkyd, and Lubrizol's 90% active Solsperse W60 (The Lubrizol Corporation, July 2025) is bought for that universality, because a second approval cycle on a new line costs more than the premium.
Which Capabilities Distinguish Product Offers?
Portfolios now separate on manufacturing control and certification rather than chemistry. BASF SE (July 2026) sets its European architectural range apart with Dispex AA 4145 MB, a drop-in bio-attributed substitution that needs no reformulation and no re-qualification on the customer line. Clariant AG (March 2026) pairs Dispersogen PSL 100 polymeric dispersants with attapulgite clay rheology modifiers for biological crop protection, where settling control and shelf life are bought together. Borregaard ASA (July 2026) supplies modified softwood lignosulfonates that cut urea nitrogen loss by 20% to 40%. A supplier that cannot document active content, clay tolerance and carbon attribution in the same file loses the specification.
How Does Geographic Reach Affect Competition?
Aqueous liquid dispersants, at 68.4% of revenue, cost more to move than dry solids, so regional manufacturing decides who can serve whom. Ethoxylation and sulfonation plants have to sit near the construction and coatings hubs they supply, which is why Sika AG (October 2026) operates more than 400 factories across its global network to reach local readymix demand rather than shipping concentrate across an ocean. Ecolab Inc. (April 2026) solves the same problem with service, deploying the Water Navigator IQ platform across more than 170 countries to lock in recurring cooling-water contracts. Regional converters in India and Mexico hold their ground on local safety stock.
| Verified Company Evidence (2025 to 2026) | Commercial Effect | Buyer Action |
|---|---|---|
| 25 November 2025: BASF SE commissioned a new CFRP high-performance dispersant production line in Nanjing, China, followed by REDcert2 Dispex AA 4145 MB in July 2026 (BASF SE, November 2025; July 2026). | Expands regional supply of narrow-molecular-weight pigment dispersants in Asia and certified bio-attributed architectural grades in Europe. | Qualify CFRP and biomass-balanced Dispex grades to cut mill-base grinding time and Scope 3 coating emissions. |
| 5 February 2026: Evonik Coating Additives streamlined its U.S. and Canadian distribution network effective 1 May 2026 around Dorset & Jackson, Palmer Holland, Chem-Materials, and Andicor (Evonik Industries AG, February 2026). | Consolidates technical sales, regional warehousing, and formulation support for TEGO Dispers grades across North America. | Align North American multi-plant coating procurement with Evonik's four designated regional distributors. |
| 17 March 2026: Clariant AG launched Dispersogen PSL 100 polymeric dispersant and Tonnegel 50 rheology modifier at CAC 2026 in Shanghai (Clariant AG, March 2026). | Prevents particle settling and crystal growth in high-load suspension concentrates and biological crop formulations. | Test Dispersogen PSL 100 + Tonnegel 50 pairings to extend shelf life in biological and multi-active SC formulations. |
| 13 April 2026: Nouryon expanded Levasil colloidal silica manufacturing capacity in Guangzhou, China, and Ecolab launched Water Navigator IQ on 22 April 2026 (Nouryon, April 2026; Ecolab Inc., April 2026). | Strengthens Asia-Pacific supply of inorganic colloidal dispersions and automates scale-dispersant dosing in data-center cooling towers. | Integrate AI-monitored scale-dispersant dosing in evaporative cooling loops and evaluate silica-hybrid industrial coatings. |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
| Company | Core Positioning | Verified Activity & Source Attribution |
|---|---|---|
| BASF SE | Global leader in CFRP coating dispersants (Dispex, Efka), PCE concrete admixtures (MasterGlenium), and biodegradable agro-dispersants (Sokalan) | Started up Nanjing CFRP dispersant line in November 2025 (BASF SE, November 2025); launched Sokalan CP 301 in April 2025 (BASF SE, April 2025) and REDcert2 Dispex AA 4145 MB in July 2026 (BASF SE, July 2026). |
| Sika AG | Global leader in polycarboxylate ether (PCE) concrete superplasticizers (ViscoCrete, Sikament) and construction chemicals | Generated CHF 8.71 billion in 9M 2026 sales (+4.8% local currency), with EMEA up 8.3% on German infrastructure demand and Americas up 4.1% on data centers (Sika AG, October 2026). |
| Evonik Industries AG | Specialty wetting and dispersing additives for architectural, industrial, printing-ink, and composite coatings (TEGO Dispers) | Restructured U.S. and Canadian Coating Additives distribution effective May 1, 2026 with Palmer Holland, Dorset & Jackson, Chem-Materials, and Andicor (Evonik Industries AG, February 2026). |
| Arkema SA | Rheology and polyacrylate dispersing additives (Coatex, Rheotech, Coadis) for waterborne coatings, mineral slurries, and concrete | Reported Q3 2026 sales of EUR 2.4 billion (+8.1% YoY) and EBITDA of EUR 332 million (+7.0% YoY), driven by Coating Solutions UV and rheology/dispersing additives (Arkema SA, November 2026). |
| The Lubrizol Corporation | Hyperdispersants and high-solids polymeric dispersing agents (Solsperse) for coatings, inks, and thermoplastics | Commercialized 90% active APE-free Solsperse W60 polymeric dispersant in July 2025, achieving 103.6% color strength in alkyd enamel and 97.5% in latex (The Lubrizol Corporation, July 2025). |
| Clariant AG | Polymeric agrochemical, pigment, and personal-care dispersing agents (Dispersogen, Sapogenat) | Launched Dispersogen PSL 100 polymeric dispersant and Tonnegel 50 attapulgite rheology modifier at CAC 2026 in Shanghai (Clariant AG, March 2026). |
| Croda International Plc | Bio-based polymeric surfactants and dispersing agents (Hypermer, Atlox) for crop protection, beauty care, and industrial emulsions | Delivered H1 2026 sales of GBP 880.5 million (+4.6% organic growth), with Consumer Care up 8% and New & Protected Products up 6.9% organically (Croda International Plc, July 2026). |
| Borregaard ASA | World's largest producer of wood-based lignosulfonate biopolymer dispersants and granule binders (Borresperse, Ultrazine) | Demonstrated in July 2026 that 0.1% to 1.0% w/w lignosulfonate fertilizer coatings cut ammonia volatilization by 20% to 40% and lift nitrogen efficiency by 30% to 40% (Borregaard ASA, July 2026). |
| Nouryon | Colloidal silica dispersions (Levasil) and specialty alkoxylated and polymeric dispersants (Berol, Ethylan, Agrilan) | Announced Guangzhou Levasil colloidal silica capacity expansion in April 2026 following its November 2025 Shanghai innovation center opening (Nouryon, April 2026). |
| Ecolab Inc. / Eastman Chemical | Digital cooling-water scale dispersants (Ecolab) and specialty coalescents and pigment-dispersing additives (Eastman) | Ecolab launched Water Navigator IQ across 170+ countries in April 2026 (Ecolab Inc., April 2026); Eastman grew Q3 2026 Additives & Functional Products revenue 9% YoY (Eastman Chemical Company, October 2026). |
Source: Verified corporate disclosures and Future Market Insights analysis, 2026.
Dispersants Market Report Scope and Research Methodology
Future Market Insights sizes the global dispersants market bottom-up from merchant chemical shipment volumes and average realized selling prices across polycarboxylate, acrylic, naphthalene sulfonate and lignosulfonate dispersing chemistries, then reads the demand side from end-use production in ready-mixed concrete, architectural and industrial coatings, agrochemicals, pulp and paper and industrial water treatment. Top-down, the totals are checked against audited corporate segment disclosures and national statistical agency releases for construction output, cement shipments and chemical production. Values are held in current United States dollars at factory-gate ex-works pricing across a 2025 historical benchmark, a 2026 estimated base year and a 2026 to 2036 forecast. Every national figure reconciles to the global total in each year, and the segment architecture is built from the same shipment and price evidence rather than from a separate secondary estimate.
| Coverage Field | Report Scope |
|---|---|
| Market definition | Chemical additives (polymeric, sulfonate, lignosulfonate, phosphate, and surfactant-based) engineered to wet, deflocculate, and stabilize solid particles or droplets in liquid or dry-mix media. |
| Chemical types covered | Polymeric dispersants (PCE, acrylics, polyurethanes), naphthalene sulfonates (SNF/PNS), lignosulfonates, inorganic phosphates, and bio-based and other surfactants. |
| End-use industries covered | Construction, paints and coatings, pulp and paper, detergents and cleaning agents, oil and gas, agriculture, water treatment, and other industrial applications. |
| Physical forms covered | Liquid (aqueous solutions and solventborne concentrates) and powder and granular (spray-dried and prilled solids). |
| Exclusions | Neat carrier solvents, unformulated mineral fillers and pigments, standalone polymeric flocculants/coagulants, and crude oil pipeline drag-reducing polymers. |
| Quantitative units | USD billion (and USD million where noted) for value at factory-gate (ex-works) realization. |
| Base, estimated, and forecast years | 2025 (historical benchmark), 2026 (estimated base year), and 2026 to 2036 (10-year forecast period). |
| Regions covered | East Asia, North America, Europe, South Asia and Pacific, Latin America, and Middle East and Africa. |
| National coverage | China, United States, Germany, United Kingdom, France, Italy, Canada, Australia, plus regional aggregations. |
| Companies covered | BASF SE, Sika AG, Evonik Industries AG, Arkema SA, The Lubrizol Corporation, Clariant AG, Croda International Plc, Borregaard ASA, Nouryon, Ecolab Inc., and Eastman Chemical Company. |
Source: Future Market Insights analysis of the dispersants market, 2026.
Research Sources and Bibliography
- American Chemistry Council. (2026, March 27). Weekly Chemistry and Economic Trends (03-27-26).
- Arkema SA. (2026, November 5). Third-quarter 2026 results. https://www.arkema.com/global/en/media/newslist/news/global/investorrelations/2026/20261105-third-quarter-2026-results/
- Australian Bureau of Statistics. (2026, May 27). Construction Work Done, Australia, Preliminary, March 2026.
- BASF SE. (2025, April 7). BASF launches Sokalan CP 301: A readily biodegradable dispersant with optimal performance for stable agricultural formulations. https://www.basf.com/global/en/media/news-releases/2025/04/p-25-069
- BASF SE. (2025, November 25). BASF launches high-performance dispersant production line in Nanjing, China.
- BASF SE. (2026, July 13). BASF expands certified biomass-balanced additives portfolio for architectural coatings. https://www.basf.com/global/en/media/news-releases/2026/07/p-26-128
- Borregaard ASA. (2026, July 15). Lignosulfonates in fertilizer coatings: Adding value to fertilizer granules.
- Clariant AG. (2026, March 17). Clariant advances formulation stability and biological compatibility for improved agriculture at CAC 2026. https://www.clariant.com/en/Corporate/News/2026/03/Clariant-advances-formulation-stability-and-biological-compatibility-for-improved-agriculture-at-CAC
- Croda International Plc. (2026, July 28). Half Year Results Announcement 2026. https://www.croda.com/en-gb/media-hub/news/general/2026-half-year-results
- Eastman Chemical Company. (2026, October 29). Eastman announces third-quarter 2026 financial results. https://www.eastman.com/en/media-center/news-stories/2026/eastman-announces-third-quarter-2026-financial-results
- Ecolab Inc. (2026, April 22). Ecolab unleashes water intelligence to drive growth in the AI era. https://investor.ecolab.com/news/news-details/2026/Ecolab-Unleashes-Water-Intelligence-to-Drive-Growth-in-the-AI-Era/default.aspx
- Evonik Industries AG. (2026, February 5). Evonik Coating Additives announces streamlined distribution network for the U.S. and Canada. https://www.evonik.com/en/news/press-releases/2026/02/evonik-coating-additives-announces-streamlined-distribution-netw.html
- Gao, Y., Liu, Y., Wang, G., Liu, J., Cao, Z., Yong, Q., & Zhao, H. (2025, June 5). Interaction between polycarboxylate superplasticizer and clay in cement and its sensitivity inhibition mechanism: A review. Materials, 18(11), 2662. https://www.mdpi.com/1996-1944/18/11/2662
- Kou, Z., Huang, K., Chen, M., Chu, H., Zhou, L., & Yin, T. (2025, July 21). Synthesis of biomass polycarboxylate superplasticizer and its performance on cement-based materials. Materials, 18(14), 3416. https://www.mdpi.com/1996-1944/18/14/3416
- Nouryon. (2026, April 13). Nouryon expands China manufacturing to meet growing demand for premium colloidal silica in catalysts and advanced coatings. https://www.nouryon.com/newsroom/news-overview/2026/nouryon-expands-china-manufacturing-to-meet-growing-demand-for-premium-colloidal-silica-in-catalysts-and-advanced-coatings/
- Office for National Statistics. (2026, October 15). Construction output in Great Britain: August 2026. https://www.ons.gov.uk/businessindustryandtrade/constructionindustry/bulletins/constructionoutputingreatbritain/august2026
- Sika AG. (2026, October 23). Sika delivers strong nine-month results with 4.8% sales growth in local currencies and reiterates 2026 guidance. https://www.sika.com/en/media/media-releases/2026/nine-month-results-2026.html
- Statistics Canada. (2026, October 15). The Daily: Monthly Survey of Manufacturing, August 2026. https://www150.statcan.gc.ca/n1/daily-quotidien/261015/dq261015a-eng.htm
- The Lubrizol Corporation. (2025, July 31). Universal colorants: High-performing dispersant enables broad compatibility with water-based and solvent-based paint systems. https://www.lubrizol.com/company/insights/2025/07/high-performing-dispersant
- U.S. Environmental Protection Agency. (2026, August 27). Reference guide for structural classifications of surfactants for use in determining if a new chemical substance is a surfactant. https://www.epa.gov/system/files/documents/2026-08/ncd-icb-surfactants-ref-guide-final_08-27-2026.pdf
- U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Cement. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-cement.pdf
- Zhang, H., Gan, X., Lu, Z., Li, L., & Lu, L. (2025, March 8). Polycarboxylate superplasticizer-modified graphene oxide: Dispersion and performance enhancement in cement paste. Nanomaterials, 15(6), 419. https://www.mdpi.com/2079-4991/15/6/419
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemical Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chemical Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chemical Type, 2026 to 2036
- Polymeric Dispersants (PCE
- Acrylics
- Polyurethanes)
- Naphthalene Sulfonates (SNF/PNS)
- Lignosulfonates
- Inorganic Phosphates
- Bio-Based & Other Surfactants
- Y-o-Y Growth Trend Analysis By Chemical Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemical Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Construction
- Paints & Coatings
- Pulp & Paper
- Detergents & Cleaning Agents
- Oil & Gas
- Agriculture
- Water Treatment
- Others
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Physical Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Physical Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Physical Form, 2026 to 2036
- Liquid (Aqueous & Solvent-Based Solutions)
- Powder & Granular (Spray-Dried & Prilled)
- Y-o-Y Growth Trend Analysis By Physical Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Form, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemical Type
- By End-Use Industry
- By Physical Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- France
- By Chemical Type
- By End-Use Industry
- By Physical Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemical Type
- By End-Use Industry
- By Physical Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- Rest of world aggregate
- By Chemical Type
- By End-Use Industry
- By Physical Form
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Type
- By End-Use Industry
- By Physical Form
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemical Type
- By End-Use Industry
- By Physical Form
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- BASF SE
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Sika AG
- Evonik Industries AG
- Arkema SA
- The Lubrizol Corporation
- Clariant AG
- Croda International Plc
- Borregaard ASA
- Nouryon
- Ecolab Inc. / Eastman Chemical
- BASF SE
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Chemical Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Chemical Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 9: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Western Europe Market Value (USD Billion) Forecast by Chemical Type, 2021 to 2036
- Table 11: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 12: Western Europe Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 13: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: East Asia Market Value (USD Billion) Forecast by Chemical Type, 2021 to 2036
- Table 15: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 16: East Asia Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 17: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: South Asia and Pacific Market Value (USD Billion) Forecast by Chemical Type, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chemical Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chemical Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chemical Type
- Figure 6: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End-Use Industry
- Figure 9: Global Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Physical Form
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Chemical Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Chemical Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Chemical Type
- Figure 23: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End-Use Industry
- Figure 26: North America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Physical Form
- Figure 29: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 30: Western Europe Market Value Share and BPS Analysis by Chemical Type, 2026 and 2036
- Figure 31: Western Europe Market Y-o-Y Growth Comparison by Chemical Type, 2026-2036
- Figure 32: Western Europe Market Attractiveness Analysis by Chemical Type
- Figure 33: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 34: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 35: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 36: Western Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 37: Western Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 38: Western Europe Market Attractiveness Analysis by Physical Form
- Figure 39: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 40: East Asia Market Value Share and BPS Analysis by Chemical Type, 2026 and 2036
- Figure 41: East Asia Market Y-o-Y Growth Comparison by Chemical Type, 2026-2036
- Figure 42: East Asia Market Attractiveness Analysis by Chemical Type
- Figure 43: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 44: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 45: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 46: East Asia Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 47: East Asia Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 48: East Asia Market Attractiveness Analysis by Physical Form
- Figure 49: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 50: South Asia and Pacific Market Value Share and BPS Analysis by Chemical Type, 2026 and 2036
- Figure 51: South Asia and Pacific Market Y-o-Y Growth Comparison by Chemical Type, 2026-2036
- Figure 52: South Asia and Pacific Market Attractiveness Analysis by Chemical Type
- Figure 53: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 54: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 55: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 56: South Asia and Pacific Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 57: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 58: South Asia and Pacific Market Attractiveness Analysis by Physical Form
- Figure 59: Global Market - Tier Structure Analysis
- Figure 60: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the dispersants market in 2026?
Future Market Insights estimates the global dispersants market at USD 39.8 billion in 2026, up from USD 37.5 billion in 2025, driven by high-range water reducer consumption in blended cement concrete and polymeric pigment stabilization in waterborne coatings.
How fast is the dispersants market expected to grow through 2036?
FMI projects the global dispersants market to expand at a 6.5% CAGR from 2026 to 2036, reaching USD 74.7 billion by 2036 and generating USD 34.9 billion in incremental revenue (1.88-fold expansion).
Which chemical type leads the dispersants market?
Polymeric dispersants lead the market with 44.2% of global revenue in 2026 (projected to reach 47.5% by 2036), while bio-based and lignosulfonate dispersants record the fastest chemical-type growth at a 7.4% CAGR.
Which end-use industry accounts for the largest share of dispersant sales?
Construction is the largest end-use industry at 29.5% of global revenue in 2026 due to widespread polycarboxylate superplasticizer dosing in ready-mixed and precast concrete, while paints and coatings grow fastest at a 6.9% CAGR through 2036.
Which physical form dominates global dispersants demand?
Liquid dispersants capture 68.4% of global revenue in 2026 (expanding at a 6.7% CAGR) because aqueous solutions integrate directly into automated concrete batching and tinting pumps, whereas powder and granular grades hold 31.6% share (6.1% CAGR).
Which countries are the largest and fastest-growing dispersants markets?
China is both the largest and fastest-growing national market, rising at a 7.8% CAGR from USD 8.76 billion in 2026 (22.0% global share) to USD 18.56 billion by 2036 (24.8% share), followed by the United States at a 7.2% CAGR (USD 7.96 billion to USD 15.95 billion) and Australia at a 7.0% CAGR.
What is the primary technical restraint in the dispersants market?
Swelling clay minerals such as montmorillonite and muscovite in crushed concrete aggregates adsorb up to 415 mg/g of polycarboxylate superplasticizer and can cut paste spread flow by 51% (Gao et al., June 2025), requiring clay-tolerant side-chain engineering or sacrificial blockers.
Which companies lead the global dispersants market?
Leading companies include BASF SE, Sika AG, Evonik Industries AG, Arkema SA, The Lubrizol Corporation, Clariant AG, Croda International Plc, Borregaard ASA, Nouryon, Ecolab Inc., and Eastman Chemical Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
