

- Market Size (2026)
- USD 12.3 Bn
- Forecast (2036)
- USD 19.8 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Antiscalants and Dispersants Market in 2026?
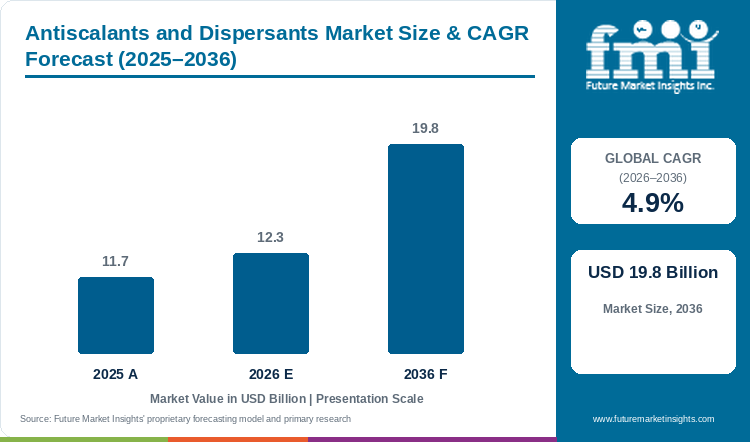
The antiscalants and dispersants market is estimated at USD 11.7 billion in 2025 and is expected to reach USD 12.3 billion in 2026. Sales of antiscalants and dispersants are projected to grow at a 4.9% CAGR and reach USD 19.8 billion by 2036.
Sales of antiscalants and dispersants are highest in oilfield production and water treatment, as calcium, barium and silica deposits can choke wells, boilers and reverse osmosis membranes within weeks. The antiscalants and dispersants market is estimated at USD 11.7 billion in 2025 and is expected to reach USD 12.3 billion in 2026. Demand for antiscalants and dispersants is projected to increase at a 4.9% CAGR across the forecast period, reaching USD 19.8 billion by 2036. In June 2026, Kuwait's water ministry awarded a WABAG and HEISCO joint venture the 60 MIGD Doha seawater reverse osmosis Stage II plant on a design, build and operate basis.[1] Every reverse osmosis train is fed antiscalant ahead of the membranes during each hour of service, so one large plant becomes a supply contract for the full operating term.
FMI analysts expect Germany to expand at a 6.2% CAGR to 2036, against 4.6% for the United States. BASF said in July 2026 that 88% of production units at Ludwigshafen now rank as highly competitive, up from 78% in 2024.[2] Fuller chemical sites run more cooling towers, boilers and process water loops, so each restarted unit adds a dosing programme in Germany. American buyers already treat a large base of towers and shale wells, and new orders there come mostly from replacing older phosphate chemistries.
Key Market Trends & Insights
- Antiscalants are expected to lead product type with 61.8% share in 2026, as phosphonates and polyacrylates go into desalination, boiler and oilfield dosing. Dispersants, from silicates to cellulose derivatives, are estimated at 38.2%.
- By end use, oil and gas is projected to lead at an estimated 32.6% in 2026, with water treatment close behind near 30.4%. Higher sales of production chemicals in U.S. land supported SLB in the June 2026 quarter.[3]
Regional Highlights
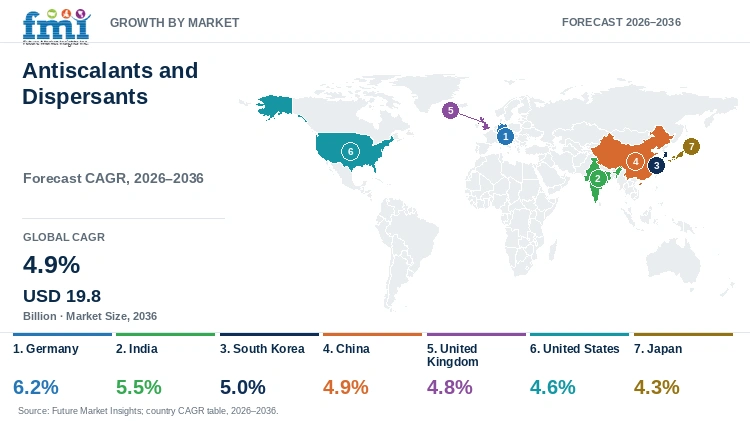
- Germany is the quickest of the seven profiled countries at a 6.2% CAGR, per FMI's country model, faster than the market average of 4.9% as chemical sites raise utilization.
- India follows at 5.5%, and South Korea at 5% keeps a narrow lead over China, level with the global rate at 4.9%. The United Kingdom on 4.8% and the United States on 4.6% come next, and Japan, on 4.3%, is last in the country ranking.
- Urban India generated about 52,644 MLD of sewage against roughly 31,885 MLD of installed treatment capacity, a parliamentary committee reported in August 2026.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Antiscalants and Dispersants Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.7 billion |
| Estimated Market Size in 2026 | USD 12.3 billion |
| Projected Market Size by 2036 | USD 19.8 billion |
| CAGR, 2026 to 2036 | 4.9% |
| Added Revenue, 2026 to 2036 | USD 7.5 billion |
| Market Expansion Multiple | 1.6x |
Orders for antiscalants and dispersants follow running hours, since a dosing pump feeds product into a well, tower or membrane train for as long as the system operates. SLB credited higher sales of production chemicals in U.S. land for sequential growth in North America in Q2 2026, a quarter in which acquired ChampionX businesses added USD 865 million to Production Systems.[3] Water treatment orders arrive the same way, and Ecolab's Light Water business improved across manufacturing over April to June 2026.[5] Membrane cleaners and antiscalants often ship together, and the membrane chemicals market is projected to grow at a 6.1% CAGR, which keeps reverse osmosis operators buying both from one supplier. The FMI forecast leaves sales of antiscalants and dispersants USD 7.5 billion higher in 2036 than in 2026, about 1.6 times the size estimated for 2026. Feedstock shocks are the main near-term risk, as phosphonate and acrylic monomer costs move with crude oil.
Desalination, Oilfield Dosing and Cost Pass-Through
Desalination and produced water projects bring the longest new dosing contracts. The Kuwaiti Doha plant will take 36 months to build and then run under a five-year operation and maintenance period.[1] Kemira said urban water demand stayed stable in the June 2026 quarter, and lower demand came mainly from packaging, pulp and industrial water customers.[6] Suppliers chasing growth are moving sales teams toward large membrane plants and oilfield operators, since those buyers sign multi-year dosing terms.
Cost pass-through decides margins in 2026. Solenis applied a global energy surcharge of 8% to 14% from 1 April 2026, citing higher fuel, feedstock and freight costs after the Middle East conflict.[7] Clariant reported raw material prices up 7.4%, energy up 6% and logistics up 8.1% in Q2 2026.[8] Kemira expects about EUR 100 million of raw material and logistics cost impact for 2026, with roughly half covered by price increases.[6] Water treatment groups with service contracts are recovering costs faster than commodity sellers of phosphonate drums.
Table 2: Desalination, Oilfield and Input Cost Indicators for the Antiscalants and Dispersants Market (contract, sales and price data), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Doha SWRO Stage II, Kuwait, June 2026 | 60 MIGD; about USD 371.5 million; design, build and operate | New antiscalant dosing points in desalination | [1] |
| SLB Production Systems, Q2 2026 | USD 3.77 billion; ChampionX USD 865 million | Scale inhibitor sales in oilfield production | [3] |
| Ecolab Global Water, Q2 2026 | Fixed currency sales up 10%; organic up 4% | Treatment programme growth | [5] |
| Solenis energy surcharge, April 2026 | 8% to 14% global surcharge | Price pass-through to treated water users | [7] |
| Clariant input costs, Q2 2026 | Raw materials up 7.4%; energy up 6%; logistics up 8.1% | Feedstock pressure on formulators | [8] |
| Kemira cost impact, 2026 | About EUR 100 million; about 50% covered by price | Margin exposure for water chemical makers | [6] |
Analyst Perspective
“Desalination plants and produced water systems will, in my view, offer the best antiscalant contracts of the next decade, as those operators dose every hour and cannot afford a fouled membrane or a blocked well. Suppliers who bundle monitored dosing with phosphate-free polymer chemistry are unlocking a second tier of service income from each plant, and I expect them to hold those accounts well beyond the first contract term.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the antiscalants and dispersants market segmented?
The market is segmented into product type, end use, and region. Antiscalants are expected to lead product type with 61.8% share in 2026, and oil and gas is projected to lead end use with an estimated 32.6%.
By product type: antiscalants and dispersants.
By end use: water treatment, detergents and cleaners, oil and gas, mining, and others.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do antiscalants lead antiscalants and dispersants sales by product type?
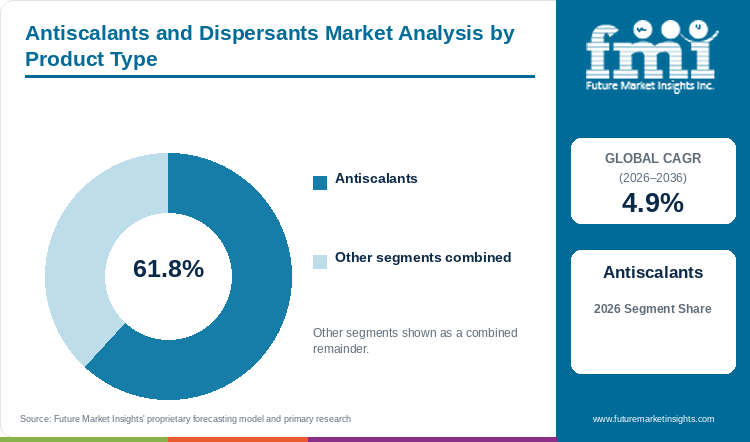
Antiscalants are expected to lead product type sales with 61.8% share in 2026, against an estimated 38.2% for dispersants.
Table 3: Product Type Share for the Antiscalants and Dispersants Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Antiscalants | 61.8% |
| Dispersants | 38.2% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Antiscalants and Dispersants Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.9% |
| Leading Segment | Antiscalants |
With desalination, boiler and oilfield operators all fighting mineral scale, antiscalants are expected to lead with 61.8% share in 2026. Phosphonates and polyacrylates stop calcium carbonate, calcium sulphate and barium sulphate crystals from growing at a few parts per million, and a reverse osmosis plant or a producing well cannot run long without them. Dispersants, estimated at 38.2%, keep particles suspended after crystals form, and much of the dispersant volume goes into detergents, mineral slurries and paper coatings with lower dose rates per tonne. Detergent makers can also switch between dispersant polymers on price, so dispersant contracts turn over faster than antiscalant programmes tied to a membrane warranty. Mineral slurry users form a separate pool, and the mineral processing dispersants market is forecast to expand at a 5.1% CAGR, close to the pace for antiscalants and dispersants as a whole. Plant operators will keep antiscalants as the core purchase and add dispersants as a second line when fouling comes from silt and organics.
- Phosphonate, polyacrylate and maleic copolymer grades form the bulk of antiscalant volume.
- Kemira acquired Clear Water Technologies, a boiler and cooling tower service provider in California, on 16 June 2026.[9]
Why does oil and gas lead antiscalants and dispersants sales by end use?
Oil and gas is projected to lead end use sales with an estimated 32.6% share in 2026, ahead of water treatment near 30.4% and detergents and cleaners at about 18.3%.
Table 5: End Use Share for the Antiscalants and Dispersants Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Oil and Gas | 32.6% |
| Water Treatment | 30.4% |
| Detergents and Cleaners | 18.3% |
| Mining | 11.2% |
| Others | 7.5% |
| Total | 100.0% |
Produced water in mature fields carries barium, strontium and calcium, and operators squeeze scale inhibitor into the reservoir to keep each well flowing, so oil and gas is projected to lead with 32.6% share in 2026. Water treatment, near 30.4%, buys for cooling towers, boilers and desalination, and municipal budgets spread those orders over long tenders. Detergents and cleaners, about 18.3%, use dispersant polymers to stop soil redepositing on fabric, and brand owners buy on price per wash. Mining, an estimated 11.2%, doses antiscalant into heap leach and tailings water, and order size follows ore throughput. Other users such as pulp mills and geothermal plants account for 7.5%. Treatment groups selling cooling water programmes link these chemicals to the water and wastewater treatment chemicals market, projected at a 4.6% CAGR, a little slower than oilfield dosing. Field operators will keep oil and gas in front as long as produced water volumes rise with well age.
- Squeeze treatments, continuous downhole dosing and topside inhibitor injection make up most oilfield volume.
- SLB said the acquired ChampionX businesses delivered a third straight quarter of sequential margin expansion in Q2 2026.[3]
What are the drivers, restraints, and opportunities in the antiscalants and dispersants market?
Scale control is a running cost for every well, tower and membrane plant, so demand for antiscalants and dispersants renews with each hour of operation. Petrochemical feedstock costs squeeze formulators, and desalination and water reuse open long dosing contracts.
- Driver: Operators of wells, boilers and reverse osmosis plants dose scale inhibitor without pause, so every new system in service becomes a lasting buyer.
- Restraint: Phosphonate and acrylic inputs follow crude oil and energy prices, and suppliers on fixed-price contracts absorb the gap until the next tender.
- Opportunity: Water utilities and industrial sites moving to reuse and desalination want phosphate-free, monitored dosing, which rewards suppliers with service teams.
Hourly Dosing Turns Every System into a Buyer
Demand for antiscalants and dispersants grows with the stock of systems in service, as dosing stops only when a plant stops. Ecolab said Light Water improved on solid gains across manufacturing in Q2 2026, and the headwind from Heavy Water and Paper continued to ease.[5] Production chemicals were a named growth line for SLB in U.S. land over the same months.[3] Each new cooling loop, boiler or flowing well therefore adds a contract that renews for as long as the asset runs.
Feedstock and Freight Costs Squeeze Formulators
Producers of phosphonates and polymer dispersants carry the heaviest cost exposure, as both chemistries start from petrochemical and phosphorus inputs. Solenis said Brent crude peaked at USD 120 per barrel during the Middle East conflict and remained about 30% above pre-conflict levels in March 2026.[7] Kemira reported Q2 2026 operative EBITDA of EUR 111.7 million, down 15%, on higher raw material and logistics costs.[6] Suppliers will keep using surcharges and shorter price periods until feedstock costs stabilise.
Desalination and Reuse Open Long Dosing Contracts
New membrane plants hold the largest adoption potential for antiscalants, since a seawater or reuse plant signs a chemical programme before start-up. The Doha Stage II plant in Kuwait combines seawater reverse osmosis with on-site solar power and a five-year operation period.[1] Kemira described industrial water treatment services as a business growing faster than traditional water treatment when buying Clear Water Technologies.[9] Suppliers bidding with monitored dosing, membrane cleaning and phosphate-free chemistry will gain the longest contracts.
Which country CAGRs are profiled in the antiscalants and dispersants market?
Table 6: Country CAGR Comparison for the Antiscalants and Dispersants Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| Germany | 6.2% |
| India | 5.5% |
| South Korea | 5% |
| China | 4.9% |
| United Kingdom | 4.8% |
| United States | 4.6% |
| Japan | 4.3% |
How do country-level CAGRs compare in the antiscalants and dispersants market?
Ludwigshafen and other German chemical sites are running fuller, and BASF reported higher capacity utilization across the group's plants in July 2026.[2] FMI analysts expect Germany to lead the table at 6.2%, as more towers and boilers come back into service. India follows on 5.5%, with sewage treatment and city water projects adding dosing points, and South Korea, at 5%, gains from chip plant ultrapure water and petrochemical cooling. China grows in line with the 4.9% rate for antiscalants and dispersants. The United Kingdom, on 4.8%, and the United States, on 4.6%, already treat large installed bases. Japan, at 4.3%, relies mainly on replacement orders from long-running power and chemical plants.
- German chemical complexes running at higher utilization need more cooling and boiler programmes.
- Sewage treatment plants and city water schemes are adding membrane dosing in India.
- Ultrapure water plants at chip fabs push antiscalant use in South Korea.
- Refinery, coal chemical and desalination plants keep orders steady in China.
- In the United Kingdom, ageing North Sea fields bring up more scaling water as wells mature.
- American shale operators dose scale inhibitor into every producing well.
- Replacement orders from mature power and chemical plants carry demand in Japan.
Full report country CAGRs cover: three countries above the 4.9% global rate (Germany, India and South Korea), China level with the global rate, three below (the United Kingdom, the United States and Japan), and the remaining standard countries by region.
Country-wise Analysis
Germany Antiscalants and Dispersants Market Outlook (2026 to 2036)
At BASF's Ludwigshafen site, highly competitive production units rose from 78% of the total in 2024 to 88% by July 2026.[2] Integrated sites of this kind run hundreds of cooling and boiler circuits, and each one is dosed with antiscalant and dispersant. Per FMI's country model, Germany is projected to grow at a 6.2% CAGR, faster than the market average of 4.9%, as restarted units at chemical parks bring cooling and boiler circuits back into service.
Key takeaway: Fuller chemical sites and phosphate-free detergents give Germany the top rate.
India Antiscalants and Dispersants Market Outlook (2026 to 2036)
India is forecast to grow at a 5.5% CAGR in antiscalant and dispersant sales. A parliamentary committee reported in August 2026 that urban India treats only part of about 52,644 MLD of sewage, with an installed capacity gap of more than 20,700 MLD.[4] New sewage and reuse plants under AMRUT 2.0 use membranes and boilers that need scale control, and refineries add cooling water programmes alongside them.
Key takeaway: Treatment plant construction drives Indian dosing demand.
South Korea Antiscalants and Dispersants Market Outlook (2026 to 2036)
Memory chip makers at Pyeongtaek and Icheon run ultrapure water plants with several reverse osmosis stages, and each stage is dosed with antiscalant. Petrochemical complexes at Ulsan and Yeosu add cooling tower demand. South Korea is projected to grow at a 5% CAGR, as new fab lines bring fresh membrane trains.
Key takeaway: Chip plant water systems keep South Korea above the global pace.
China Antiscalants and Dispersants Market Outlook (2026 to 2036)
Coal chemical plants, refineries and coastal desalination units in China use large volumes of phosphonate antiscalant, and local producers supply many commodity grades. Growth in China is likely to match the global rate at 4.9%, as coastal desalination adds membrane trains. Global groups compete there on monitoring services and specialty polymers for zero liquid discharge plants.
Key takeaway: Local supply and zero liquid discharge plants shape the Chinese outlook.
United Kingdom Antiscalants and Dispersants Market Outlook (2026 to 2036)
North Sea operators treat produced water from ageing fields, and scale squeezes are routine on many platforms. British water companies are also adding reuse and membrane stages under drought plans. The FMI outlook for the United Kingdom is a 4.8% CAGR, close to the global figure.
Key takeaway: Ageing offshore fields and water reuse keep the United Kingdom near the global rate.
United States Antiscalants and Dispersants Market Outlook (2026 to 2036)
SLB's North American revenue of USD 2.24 billion in Q2 2026 rose on higher sales of production chemicals and valves in U.S. land.[3] Kemira bought Clear Water Technologies in California in June 2026 to grow boiler and cooling tower services for light industry.[9] The United States is projected to grow at a 4.6% CAGR, as a large treated base turns growth toward services and chemistry upgrades.
Key takeaway: Shale wells and service-led cooling contracts carry the United States.
Japan Antiscalants and Dispersants Market Outlook (2026 to 2036)
Japanese power stations, steel mills and chemical plants have run treated water systems for decades, so most orders replace existing programmes under long service agreements. FMI's figure for Japan is a 4.3% CAGR, with new semiconductor fabs adding the main fresh demand.
Key takeaway: Replacement demand and new fabs shape Japan.
Who are the notable companies in the antiscalants and dispersants market?
Ecolab, Solenis, Kemira, Veolia, Kurita, Buckman, H2O Innovation, BASF, Dow, Italmatch Chemicals, Clariant, LANXESS, SNF, Ashland, Innospec and SLB are the profiled companies.
Top companies operating in the antiscalants and dispersants market include water treatment service groups, specialty chemical makers and an oilfield chemicals supplier. Ecolab reported Q2 2026 net sales of USD 4,415.4 million, up 10%, with pricing improved to 4%.[5] At SLB, ChampionX businesses added USD 870 million of revenue across the group in the same quarter.[3] Kemira kept Q2 2026 revenue stable at EUR 693.0 million, helped by acquisitions.[6] Clariant's Care Chemicals sales grew 4.2% in local currency.[8] FMI's profiled set also covers Solenis, Veolia, Kurita, Buckman, H2O Innovation, BASF, Dow, Italmatch Chemicals, LANXESS, SNF, Ashland and Innospec.
- Water treatment service groups: Ecolab, Solenis, Kemira, Veolia, Kurita, Buckman and H2O Innovation.
- Specialty chemical makers: BASF, Dow, Italmatch Chemicals, Clariant, LANXESS, SNF, Ashland and Innospec.
- Oilfield chemicals supplier: SLB.
Competitive Benchmarking: Antiscalants and Dispersants Market
Table 7: Competitive Benchmarking for the Antiscalants and Dispersants Market (qualitative documentation ratings), 2026
| Company | Water Treatment | Oilfield Chemicals | Polymer Chemistry | Recency |
|---|---|---|---|---|
| Ecolab | High | Medium | Medium | High |
| Kemira | High | Low | Medium | High |
| Solenis | High | Low | Medium | High |
| SLB | Low | High | Low | High |
| Clariant | Low | Medium | High | High |
| BASF | Low | Low | High | High |
Column ratings follow the depth of 2025 and 2026 company disclosures and carry no market share meaning.
Key Developments in the Antiscalants and Dispersants Market
- On 25 August 2026, Saudi Gulf Projects reported that a WABAG and HEISCO joint venture had signed the USD 371.5 million Doha SWRO Stage II contract in Kuwait.[1]
- On 5 August 2026, Water Today reported an urban sewage treatment capacity gap in India of more than 20,700 MLD.[4]
- On 31 July 2026, Clariant announced Q2 2026 sales of CHF 941.3 million, with group pricing up 3%.[8]
- On 29 July 2026, BASF raised the 2026 outlook for EBITDA before special items to EUR 6.9 billion to EUR 7.7 billion.[2]
- On 28 July 2026, Ecolab credited 29% organic growth in Global High-Tech for faster Global Water performance.[5]
- On 24 July 2026, SLB reported Production Systems revenue of USD 3.77 billion, 7% higher than the prior quarter.[3]
- On 17 July 2026, Kemira reiterated a 2026 revenue outlook of EUR 2,600 million to EUR 3,000 million.[6]
- On 16 June 2026, Kemira completed the acquisition of Clear Water Technologies, the second North American industrial water purchase after Water Engineering.[9]
- On 18 March 2026, Solenis announced a global energy surcharge of 8% to 14%, effective 1 April 2026.[7]
Key Players in the Antiscalants and Dispersants Market
Water Treatment Service Groups
- Ecolab
- Solenis
- Kemira
- Veolia
- Kurita
- Buckman
- H2O Innovation
Specialty Chemical Makers
- BASF
- Dow
- Italmatch Chemicals
- Clariant
- LANXESS
- SNF
- Ashland
- Innospec
Oilfield Chemicals Supplier
- SLB
Antiscalants and Dispersants Market - Report Scope
Table 8: Report Scope for the Antiscalants and Dispersants Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end use; region |
| Quantitative units | USD billion |
| Market definition | Chemicals dosed into water, brine, oil production streams, slurries or wash liquor to stop mineral scale from forming and to keep particles suspended, including phosphonate and polymer antiscalants and silicate, phosphate, ester and cellulose dispersants. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Ecolab, Solenis, Kemira, Veolia, Kurita, Buckman, H2O Innovation, BASF, Dow, Italmatch Chemicals, Clariant, LANXESS, SNF, Ashland, Innospec, SLB |
| Forecast period | 2026 to 2036 |
Antiscalants and Dispersants Market - Research Methodology
Table 9: Research Methodology for the Antiscalants and Dispersants Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Water treatment and chemical company results, oilfield service filings, desalination contract reports and parliamentary water data dated May 2025 or later. |
| Desk Research | Desk research covers desalination, oilfield scale control, cooling and boiler water, detergents, mining water and input costs. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 12.3 billion and the 4.9% CAGR for 2026 to 2036. |
| Data Validation | Sales, cost and capacity figures were matched to the release, filing or article that first carried them. |
Antiscalants and Dispersants Market by Segments
Antiscalants and Dispersants Market segmented by Product Type:
- Antiscalants
- Dispersants
Antiscalants and Dispersants Market segmented by End Use:
- Water Treatment
- Detergents and Cleaners
- Oil and Gas
- Mining
- Others
Antiscalants and Dispersants Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Saudi Gulf Projects. (2026, August 25). WABAG–HEISCO JV Signs $371.5 Million Doha SWRO Desalination Plant Contract in Kuwait. https://www.saudigulfprojects.com/2026/08/wabag-heisco-jv-signs-371-5-million-doha-swro-desalination-plant-contract-in-kuwait/
- [2] BASF SE. (2026, July 29). BASF Group second quarter 2026 results. https://www.basf.com/basf/www/global/en/media/news-releases/2026/07/p-26-123.html
- [3] SLB. (2026, July 24). SLB Announces Second-Quarter 2026 Results (Form 8-K, Exhibit 99). https://www.sec.gov/Archives/edgar/data/0000087347/000119312526315068/d122193dex99.htm
- [4] Water Today. (2026, August 5). India's Urban Sewage-Treatment Gap Crosses 20,700 MLD, Parliamentary Panel Warns. https://magazine.watertoday.org/news/national/india-urban-sewage-treatment-gap-20700-mld-amrut-2026
- [5] Ecolab Inc. (2026, July 28). Ecolab Delivers Accelerated Sales Growth and Double-Digit EPS Growth (Form 8-K, Exhibit 99.1). https://www.sec.gov/Archives/edgar/data/0000031462/000162828026049933/ecl_ex99x1.htm
- [6] Kemira Oyj. (2026, July 17). Kemira Oyj's Half-Year Financial Report 2026: Profitability weakened by cost inflation, performance improvement measures continue. https://news.cision.com/kemira-oyj/r/kemira-oyj-s-half-year-financial-report-2026--profitability-weakened-by-cost-inflation--performance-,c4375563
- [7] Solenis (PR Newswire). (2026, March 18). Solenis Announces Energy Surcharge Following Middle East Conflict. https://www.prnewswire.com/news-releases/solenis-announces-energy-surcharge-following-middle-east-conflict-302717420.html
- [8] Clariant. (2026, July 31). Clariant delivers continued strong results in volatile operating environment. https://www.clariant.com/Corporate/News/2026/07/Clariant-delivers-continued-strong-results-in-volatile-operating-environment--Court-dismisses-Shells
- [9] Kemira Oyj. (2026, June 16). Kemira acquires the business of Clear Water Technologies, LLC. https://news.cision.com/kemira-oyj/r/kemira-acquires-the-business-of-clear-water-technologies--llc,c4363976
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the antiscalants and dispersants market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the antiscalants and dispersants market expected in 2026?
In FMI's view, the antiscalants and dispersants market is estimated at USD 12.3 billion in 2026, up from USD 11.7 billion in 2025. By 2036, the antiscalants and dispersants market is projected to reach USD 19.8 billion.
What CAGR is projected for the antiscalants and dispersants market through 2036?
The antiscalants and dispersants market is expected to grow at a 4.9% CAGR from 2026 to 2036. Continuous dosing in oil wells, desalination plants, boilers and cooling towers carries that growth.
Which product type holds a notable market share in 2026?
Antiscalants are expected to lead with 61.8% share in 2026. Dispersants account for an estimated 38.2%.
Which end use holds a notable market share in 2026?
With an estimated 32.6% share in 2026, oil and gas is projected to lead end use. Water treatment follows at about 30.4%.
Which country has a notable expansion outlook through 2036?
Germany has the strongest outlook, at a 6.2% CAGR in FMI's country table. India follows at 5.5%.
Who are the key companies in the antiscalants and dispersants market?
Ecolab, Solenis, Kemira, Veolia and Kurita lead the water treatment service group, and SLB supplies oilfield scale inhibitors. BASF, Dow, Italmatch Chemicals, Clariant, LANXESS, SNF, Ashland, Innospec, Buckman and H2O Innovation complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Antiscalants
- Dispersants
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Water Treatment
- Detergents and Cleaners
- Oil and Gas
- Mining
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Ecolab
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kemira
- Solenis
- SLB
- Clariant
- BASF
- Veolia
- Kurita
- Buckman
- H2O Innovation
- Dow
- Italmatch Chemicals
- LANXESS
- SNF
- Ashland
- Innospec
- Ecolab
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


