
- Market Size (2026)
- USD 2.4 Bn
- Forecast (2036)
- USD 7.8 Bn
- CAGR (2026 to 2036)
- 12.5%
How big is Eco-Friendly Straws Market in 2026?
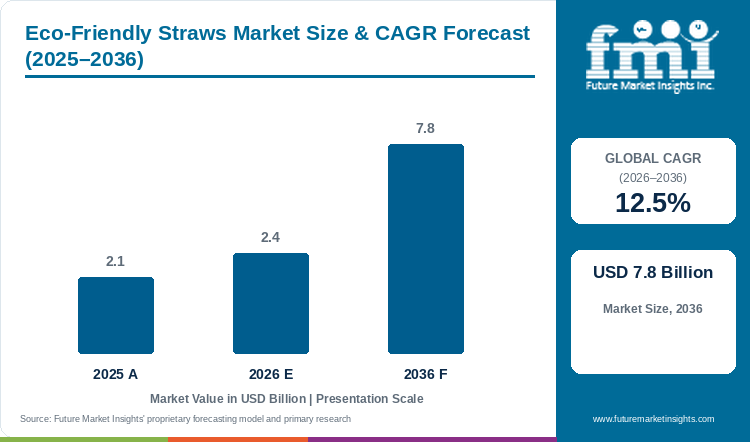
Assessed at USD 2.1 billion in 2025 and progressing to USD 2.4 billion in 2026, the eco-friendly straws market valuation is on course to reach USD 7.8 billion by 2036, supported by a forecast-period CAGR of 12.5%.
Statutory phase-outs of petrochemical single-use plastics and strict fluorochemical food-contact bans are turning eco-friendly drinking straws from voluntary sustainability gestures into mandatory foodservice procurement items. The global eco-friendly straws market was valued at USD 2.1 billion in 2025 and is estimated to reach USD 2.4 billion in 2026. Industry valuation is projected to reach USD 7.8 billion by 2036, expanding at a compound annual growth rate (CAGR) of 12.5% between 2026 and 2036. Certified kraft paper straws hold an estimated 48.0% share of 2026 demand, given that multi-ply virgin kraft reels run at over 500 meters per minute on high-speed spiral-winding machinery. This 12.5% expansion rate nearly doubles the broader commercial drinking straws growth rate of 6.4%, since legacy polypropylene units are being legislated out of quick-service restaurants in favor of higher-value fiber and biopolymer formats. Official minutes from the 12th Meeting of the European Food Safety Authority Food Contact Materials Network confirm that European authorities are harmonizing strict paper and board migration testing under BfR Recommendation XXXVI while targeting residual PFAS in paper straws [1]. Converters are scaling integrated plastic-free production to capture this regulatory wave, evidenced when Footprint LLC acquired Transcend Packaging's polyethylene-free beverage cup and paper straw business in July 2026 for European manufacturing in Poland [2]. FMI procurement survey findings reflect that suppliers guaranteeing extended cold-beverage wet stiffness via fluorochemical-free aqueous adhesives lock in multi-year fast-food contracts through 2036.
Key Market Trends & Insights
- By raw material base: FSC-Certified Paper and Kraft Pulp holds an estimated 48.0% share in 2026 since long-fiber northern bleached softwood kraft delivers high wet-tensile rigidity at competitive wholesale pricing.
- By degradability profile: Marine Biodegradable Formats represent 54.0% in 2026 owing to coastal municipality mandates and rapid seawater disintegration of uncoated cellulose and PHA esters.
- By commercial channel: Fast-Food and Coffee Chains account for 62.0% in 2026 given that iced espresso, smoothie, and drive-thru soft-drink orders require single-use wrapped straws.
- By straw geometry: Straight Standard-Bore Straws secure 56.0% in 2026 through automated high-speed tube cutting and universal compatibility with slotted cold-cup lids.
- By barrier coating: Water-Based Dispersion Coated straws command 51.0% in 2026 as converters eliminate fluorochemical water repellents ahead of North American and EU PFAS bans.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at a 14.8% CAGR through 2036 under federal circular-economy reforms and hospitality plastic prohibitions across coastal resorts.
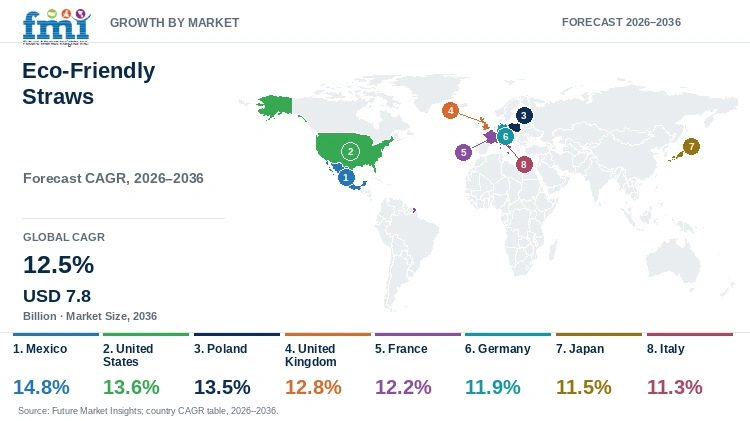
- Broader country progression: The United States tracks at a 13.6% CAGR ahead of Poland at 13.5% and the United Kingdom at 12.8%. France advances at 12.2% and Germany at 11.9%, followed by Japan at 11.5% and Italy at 11.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Eco-Friendly Straws Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.1 billion |
| Estimated Market Size in 2026 | USD 2.4 billion |
| Projected Market Size by 2036 | USD 7.8 billion |
| CAGR, 2026 to 2036 | 12.5% |
| Added Revenue, 2026 to 2036 | USD 5.4 billion |
Mandatory substitution of petroleum polypropylene straws under European Union Directive 2019/904 and parallel national bans has created a permanent structural floor for renewable straw converters. An April 2025 life-cycle assessment published in MDPI Polymers demonstrated that substituting single-use plastic straws across European foodservice channels lowers life-cycle environmental burdens while requiring high-efficiency paper and biopolymer converting lines [3]. As quick-service chains convert their remaining regional franchises toward certified compostable straws, procurement teams evaluate suppliers on wet-crush strength and verified forest or agricultural chain-of-custody.
Unit Volume and Fiber Converting Sizing
Table 2: Unit Volume and Fiber Converting Sizing for the Eco-Friendly Straws Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.1 | 2.4 | 7.8 |
| Global eco-friendly straw shipments (billion units) | 92.0 to 104.0 | 105.0 to 118.0 | 320.0 to 365.0 |
| Converted FSC paper & agricultural fiber (thousand MT) | 135.0 to 152.0 | 155.0 to 174.0 | 460.0 to 520.0 |
| Wholesale B2B price per 1,000 eco-straws (USD) | 19.5 to 23.0 | 19.8 to 23.5 | 21.0 to 25.0 |
Operational note: Fiber converting ranges apply an average finished straw weight of 1.2 to 1.6 grams across standard 6mm three-ply kraft straws and 10mm-to-12mm jumbo smoothie and boba formats.
Complete elimination of per- and polyfluoroalkyl substances and phthalate plasticizers from wet-strength paper and plant-fiber straws has become the most urgent technical requirement governing 2026 contract renewals. In August 2026, environmental medicine researchers reporting in PubMed Central evaluated commercial 7mm regular and 12mm smoothie drinking straws immersed in human saliva, detecting di-n-butyl phthalate migration up to 30.097 micrograms per liter from unverified paper adhesives paired with trace fluorochemicals [4]. To avoid regulatory delisting and brand-reputation liability, beverage chains procuring biodegradable disposable tableware now require third-party analytical certificates proving zero PFAS and phthalate-free food-safe seam adhesives.
Regulatory Recycling & Material Mix Indicators
Table 3: Regulatory Recycling and Material Mix Indicators for the Eco-Friendly Straws Market (billion units and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| EU annual straw consumption baseline (billion units, MDPI) | 30.0 | 31.2 | 39.5 |
| EU overall packaging waste recycling rate (%, Eurostat) | 67.0% | 68.2% | 75.5% |
| PFAS-free aqueous barrier paper straw share (%) | 68.0% to 72.0% | 76.0% to 81.0% | 96.0% to 99.0% |
| Marine-degradable PHA & bagasse share (%) | 24.0% to 27.5% | 26.5% to 30.0% | 38.0% to 43.0% |
Table 4: Regulatory Threshold & Channel Spending Indicators for the Eco-Friendly Straws Market (USD and institutional baselines), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 2.4 billion | 2026 global eco-friendly straws revenue baseline |
| EU PFHxA food-contact limit, Oct 2026 | 25 ppb homogeneous limit | EFSA FCM Network 12th Meeting regulatory threshold |
| EU paper & cardboard recycling target | 85.0% by 2030 | Eurostat Packaging Waste Directive statutory benchmark |
| Fast-Food and Coffee Chains revenue, 2026 | USD 1.49 billion | 62.0% commercial channel allocation |
Statutory recycling and waste-reduction quotas enacted across Europe and North America are accelerating foodservice conversion toward mono-material fiber straws that can be repulped in the same stream as paper cups. In October 2026, Eurostat reported that overall European Union packaging waste recycling reached 67.0% as member states scale collection to meet mandatory 2030 targets of 85% for paper and cardboard and 55% for plastics under Regulation (EU) 2025/40 [5]. Foodservice operators pairing paper cups with bagasse disposable cutlery favor dispersion-coated paper straws that repulp cleanly in standard paper mills without contaminating fiber recovery loops.
Analyst Perspective
"Quick-service restaurant buyers no longer judge an eco-friendly straw solely on whether it is plastic-free; they demand three-hour cold-drink structural integrity paired with zero-PFAS lab certification. Converters that master hydrophobic water-based dispersion coatings on high-grammage kraft paper and marine-degradable PHA blends will capture the lion's share of global beverage chain tenders."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the eco-friendly straws market segmented?
The eco-friendly straws market is segmented by raw material base, degradability profile, commercial channel, straw geometry, and barrier coating. In 2026, FSC-Certified Paper and Kraft Pulp is projected at 48.0%, Marine Biodegradable Formats at 54.0%, Fast-Food and Coffee Chains at 62.0%, Straight Standard-Bore Straws at 56.0%, and Water-Based Dispersion Coated at 51.0%.
By raw material base: FSC-Certified Paper and Kraft Pulp, Sugarcane Bagasse and Coffee Grounds, Polylactic Acid PLA and PHA Biopolymers, and Bamboo and Natural Reed Stalks.
By degradability profile: Marine Biodegradable Formats, Home Compostable Certified Formats, Industrial Facility Compostable Formats, and Repulpable Paper-Stream Formats.
By commercial channel: Fast-Food and Coffee Chains, Hospitality Luxury Hotels and Resorts, Retail Packaged Straw Packs for Homes, and Aseptic Beverage Carton Manufacturers.
By straw geometry: Straight Standard-Bore Straws, Jumbo Boba and Smoothie Straws, Flexible Concertina Bendable Straws, and U-Shaped Carton Straws.
By barrier coating: Water-Based Dispersion Coated, Uncoated Natural Fiber, Biopolymer Wax-Calendered, and Mineral-Filled Aqueous Barrier.
Why does FSC-Certified Paper and Kraft Pulp lead the raw material base category?
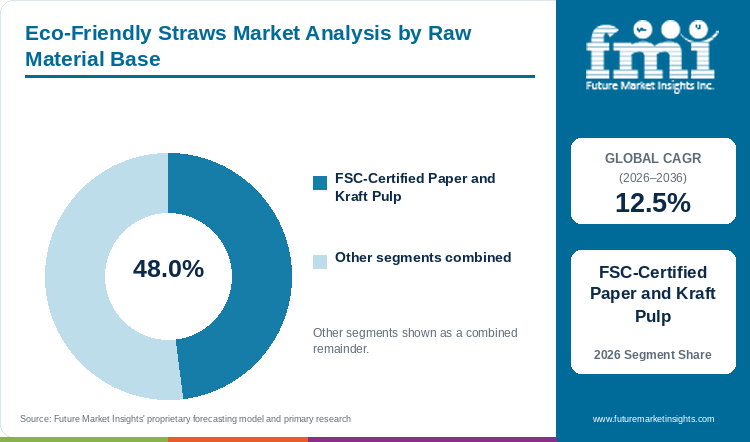
FSC-Certified Paper and Kraft Pulp holds an estimated 48.0% of raw material base demand in 2026, anchored by high-speed spiral-winding lines and municipal paper-stream compatibility.
Table 5: Raw Material Base Share for the Eco-Friendly Straws Market (percentage share), 2026
| Raw Material Base | Share (2026) |
|---|---|
| FSC-Certified Paper and Kraft Pulp | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining raw material base categories (Sugarcane Bagasse and Coffee Grounds, Polylactic Acid PLA and PHA Biopolymers, plus Bamboo and Wheat Stems) account for the balance of 2026 global demand.
Table 6: Raw Material Base Leadership and Market Growth for the Eco-Friendly Straws Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 12.5% |
| Leading Segment | FSC-Certified Paper and Kraft Pulp |
Virgin food-grade kraft paper certified by the Forest Stewardship Council anchors the raw material base category because three-ply spiral winding of 120-gsm inner cores with 60-gsm outer wraps delivers reliable hoop strength at the lowest cost per thousand straws. Unlike extruded biopolymers that require specialized resin drying and chill-roll calibration, paper straw winders operate at high linear speeds and accept food-safe soy or water-based brand printing. Converters supplying molded fiber packaging still confront consumer complaints when uncoated paper edges soften after forty-five minutes in carbonated fountain drinks, driving mills to refine internal alkyl ketene dimer wet-strength sizing.
- Within the raw material base segment, FSC-Certified Paper and Kraft Pulp is projected to account for a leading 48.0% share in 2026, supported by established paper-mill supply chains and broad regulatory acceptance.
- In March 2026, Stora Enso detailed how its unbleached kraft dispersion-barrier technology replaces conventional polyethylene layers while achieving DIN EN 13432 industrial compostability and standard paper-mill repulpability [6].
What sustains Marine Biodegradable Formats leadership in the degradability profile segment?
Marine Biodegradable Formats represent an estimated 54.0% of the degradability profile category in 2026, driven by coastal resort plastic bans and ocean-safe cellulosic and PHA digestion.
Straws engineered to disintegrate in coastal marine environments without requiring 60-degree-Celsius industrial composting chambers command the largest degradability share as island nations, cruise lines, and coastal municipalities enforce strict ocean-litter statutes. Cellulosic paper tubes and polyhydroxyalkanoate biopolymers synthesized by bacterial fermentation contain hydrolysable glycosidic or ester linkages that marine microorganisms cleave naturally within months. A July 2025 study published in ACS Omega confirmed that polyhydroxyalkanoate biopolymers undergo complete microbial depolymerization in natural environments while matching the thermoplastic melt processability needed for thin-wall foodservice articles [7]. Procurement officers sourcing bioplastics and biopolymers must still manage higher raw resin pricing for marine-certified PHA compared with standard industrial-compostable polylactic acid.
- In 2026, Marine Biodegradable Formats are anticipated to capture 54.0% of global degradability profile demand, reflecting corporate commitments to eliminate persistent ocean microplastics.
- Segment growth through 2036 is projected to accelerate as compounders blend micro-fibrillated cellulose with PHA to reduce unit resin cost while retaining TÜV Austria OK biodegradable MARINE certification.
How do Fast-Food and Coffee Chains lead the commercial channel category?
Fast-Food and Coffee Chains account for an expected 62.0% of commercial channel volume in 2026, supported by iced coffee, cold foam, and drive-thru beverage programs.
Quick-service restaurant franchises and specialty coffee chains generate nearly two-thirds of global commercial demand because iced lattes, cold-foam refreshers, and drive-thru fountain drinks represent high-frequency daily consumption occasions. National restaurant chains purchase straws under centralized annual supply tenders requiring billions of individually paper-wrapped tubes that withstand lid-slot puncture without buckling. Operators bundling straws with polylactic acid resins cold cups face logistical storage pressures at compact urban coffee kiosks, prompting distributors to supply high-density nested carton packs.
- By commercial channel, Fast-Food and Coffee Chains are estimated to reach 62.0% of total category share in 2026, driven by year-round cold beverage menu expansion across global QSR networks.
- Huhtamaki Oyj reported in October 2026 that its Foodservice Packaging division generated EUR 252.6 million in third-quarter net sales and recognized a EUR 23 million European smooth molded fiber foodservice contract as quick-service chains consolidate fiber procurement [8].
Why do Straight Standard-Bore Straws lead the straw geometry category?
Straight Standard-Bore Straws secure an anticipated 56.0% of straw geometry demand in 2026, enabled by universal fit across 12-ounce to 24-ounce cold drink lids.
Straight cylindrical drinking straws with a 5.5mm-to-6.5mm internal diameter represent the core volume workhorse of the industry given that standard cold-drink, juice, and water service does not require secondary corrugation or diagonal piercing tips. Omission of the mechanical crimping step required for flexible bendable straws allows spiral paper winders and biopolymer extruders to run at maximum throughput with near-zero scrap rates. Technical specifications from Tembo Paper B.V. in February 2026 show that precision spiral-winding platforms manufacture straight paper straws from 3mm up to jumbo diameters with zero-failure output and minimal physical factory footprint [9]. Beverage chains expanding boba pearl and thick fruit-smoothie menus are simultaneously boosting demand for 10mm-to-12mm jumbo-bore variants.
- High-speed converting economics place Straight Standard-Bore Straws on course to hold an estimated 56.0% share of the straw geometry category in 2026.
- Over the 2026 to 2036 horizon, diagonal-cut jumbo boba straws and U-shaped aseptic carton straws are forecast to post rapid secondary gains as bubble-tea retail and school-milk programs expand.
What gives Water-Based Dispersion Coated formats the leading position in barrier coating?
Water-Based Dispersion Coated formats command a projected 51.0% of barrier coating share in 2026, replacing fluorinated greaseproof agents ahead of strict 2026 PFAS prohibitions.
Aqueous styrene-acrylate and bio-wax dispersion coatings applied directly to kraft paper plies have overtaken traditional polyethylene film laminations and fluorochemical treatments because they provide three-hour liquid holdout without violating plastic-free or PFAS-free statutes. When applied at ultra-thin coat weights below 5% of total straw mass, water-based dispersions seal inter-fiber pores against carbonic acid bubbling in sodas while allowing the used straw to disintegrate in municipal paper pulpers. Brands transitioning toward biodegradable food packaging still monitor adhesive curing times closely, since high humidity in tropical converting plants can slow water evaporation on high-speed winding mandrels.
- Water-Based Dispersion Coated straws are predicted to secure 51.0% of barrier coating demand in 2026, anchored by October 2026 European PFHxA limits and U.S. state PFAS prohibitions.
- In April 2026, Stora Enso expanded its dispersion-coated paperboard barrier portfolio engineered to protect chilled and fatty foodservice applications against moisture penetration while remaining recyclable in standard fiber streams [10].
What are the drivers, restraints, and opportunities in the eco-friendly straws market?
In the eco-friendly straws market, binding single-use plastic bans and cold-beverage QSR menu expansion are projected to drive adoption, whereas wet-sogginess complaints and industrial composting sorting gaps restrain uncalibrated PLA grades and spent-coffee-ground and bagasse composites create new circular feedstock avenues.
- Driver: Statutory single-use plastic straw prohibitions and mandatory PFAS-free food-contact rules compel global restaurant, coffee, and beverage carton brands to lock in compliant paper and biopolymer straw contracts.
- Restraint: Premature fiber softening in carbonated beverages and municipal sorting incompatibility for industrial-compostable PLA straws restrain consumer satisfaction and waste-stream recovery.
- Opportunity: Upcycling agricultural byproducts such as spent coffee grounds, sugarcane bagasse, and wheat stems into rigid home-compostable straws opens low-cost circular feedstock avenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
National legislation outlawing single-use fossil-fuel plastic straws across Europe, Latin America, and North America is forcing hospitality and beverage operators to sign multi-year conversion contracts. Beyond initial European Union Single-Use Plastics Directive enforcement, Brussels regulators are tightening statutory consumption reduction targets and extended producer responsibility obligations through 2026. In December 2025, the European Commission Directorate-General for Environment launched its formal impact evaluation of Directive (EU) 2019/904 covering the mandatory EU-wide ban on single-use plastic drinking straws and foodservice disposables [11]. This statutory framework guarantees recurring replacement demand as airlines, stadiums, and fast-food operators standardize compliant plant-based straws.
Risk Assessment of the Eco-Friendly Straws Market: Operational and Formulation Friction
Consumer frustration with soggy first-generation paper straws and waste-management friction around polylactic acid biopolymers represent the primary operational hurdles restraining margin expansion. While polylactic acid straws offer plastic-like wet stiffness, they do not biodegrade in cold marine waters and frequently contaminate high-density polyethylene and PET mechanical recycling streams when consumers toss them into mixed recycling bins. A May 2026 study in MDPI Recycling demonstrated that inadvertent polylactic acid contamination degrades polyolefin recyclate quality and creates sorting bottlenecks in municipal material recovery facilities [12]. Consequently, foodservice buyers sourcing biodegradable paper packaging actively demand either certified home-compostable PHA blends or 100% repulpable aqueous-coated paper straws.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Straw manufacturers can capture substantial raw-material cost savings and brand storytelling value by compounding lignocellulosic agro-industrial wastes such as spent coffee grounds, sugarcane bagasse, and wheat bran into rigid biodegradable tubes. Coffee chains and quick-service restaurants generate hundreds of thousands of tons of spent coffee grounds annually that typically incur landfill tipping fees. In September 2025, chemical engineers publishing in MDPI Processes developed and validated biodegradable drinking straws formulated from spent coffee grounds and renewable starch matrices, demonstrating strong textural rigidity and zero reliance on wood pulp or petroleum resins [13]. Co-deployment of upcycled coffee-ground and bagasse straws with corn-based packaging resins enables coffee franchises to close their own waste loops on site.
Eco-Friendly Straws Market by Country (2026 to 2036)
FMI country modeling indicates that Mexico leads eco-friendly straws expansion at a 14.8% CAGR through 2036, followed by the United States at 13.6% and Poland at 13.5%. National growth rates reflect the timing of municipal and federal plastic straw prohibitions, domestic paperboard and biopolymer converting investments, and cold-beverage foodservice density.
Table 7: Country CAGR and Primary Growth Levers for the Eco-Friendly Straws Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 14.8% | Federal LGPGIR circular economy enforcement and coastal resort plastic bans |
| United States | 13.6% | State food-contact PFAS bans and QSR iced-beverage chain conversion |
| Poland | 13.5% | EU SUPD transposition and Footprint European paper-straw scaling hub |
| United Kingdom | 12.8% | Plastic Packaging Tax incentives and national takeaway straw restrictions |
| France | 12.2% | AGEC anti-waste law fast-food compliance and home-compostable mandates |
| Germany | 11.9% | BfR paper food-contact standards and dispersion-coated kraft straw demand |
| Japan | 11.5% | Plastic Resource Circulation Act targets across 56,000+ convenience stores |
| Italy | 11.3% | 76.4% packaging recycling rate and EN 13432 biodegradable foodservice rules |
Source: Future Market Insights analysis
Mexico Eco-Friendly Straws Market Outlook (2026 to 2036)
Demand for eco-friendly straws in Mexico is projected to expand at a leading 14.8% CAGR between 2026 and 2036 as coastal tourist resorts, quick-service chains, and beverage bottlers phase out conventional polyethylene straws. What distinguishes Mexico from Northern European markets is the widespread availability of domestic sugarcane bagasse, agave fiber, and avocado-seed biopolymer feedstocks that compete directly with imported kraft paper straws. In November 2025, USDA Foreign Agricultural Service analysts reported steady expansion across Mexico's formal retail and hospitality foodservice sectors as tourism inflows hit record levels [14]. Federal circular-economy reforms and strict state-level single-use plastic bans across Quintana Roo, Baja California Sur, and Mexico City compel hotel groups and restaurant operators to procure certified biodegradable plant-fiber straws.
Key takeaway: In Mexico, coastal hospitality plastic bans and abundant domestic bagasse and agave fiber feedstocks are projected to drive a leading 14.8% CAGR.
United States Eco-Friendly Straws Market Outlook (2026 to 2036)
The United States eco-friendly straws market is anticipated to advance at a 13.6% CAGR from 2026 to 2036, driven by cold-beverage menu growth across drive-thru coffee and fast-food chains and strict prohibitions on fluorinated food packaging. Compared with European markets that prohibit bioplastic straws under the Single-Use Plastics Directive, U.S. municipal regulations in California, Washington, and New York permit BPI-certified compostable PHA and PLA biopolymer straws in addition to PFAS-free paper formats. In January 2025, the U.S. Food and Drug Administration issued a formal Federal Register determination revoking 35 Food Contact Notifications for PFAS-containing grease-proofing agents applied to paper and paperboard food packaging [15]. American foodservice distributors are consequently shifting high-volume iced-coffee and smoothie accounts toward domestic Aardvark paper straws and marine-degradable PHA tubes.
Key takeaway: In the United States, QSR cold-drink volume and strict PFAS-free food-contact compliance are anticipated to sustain a 13.6% CAGR through 2036.
Poland Eco-Friendly Straws Market Outlook (2026 to 2036)
In Poland, eco-friendly straw sales are forecast to grow at a 13.5% CAGR over the 2026 to 2036 period as the country scales into Central Europe's primary manufacturing and export hub for fiber foodservice packaging. Poland diverges from Western European importing nations by combining competitive industrial converting labor with abundant domestic wheat-bran and kraft-paper supply chains. In December 2025, Warsaw agricultural attachés documented Poland's full statutory implementation of EU Directive 2019/904 under the amended Polish Packaging and Packaging Waste Management Act [16]. As evidence of Poland's manufacturing centrality, Footprint LLC announced in July 2026 that it is scaling its newly acquired polyethylene-free cup and paper straw line through its Polish production facility to supply pan-European restaurant chains.
Key takeaway: In Poland, statutory EU SUPD enforcement and large-scale export converting investments are forecast to support a 13.5% CAGR through 2036.
United Kingdom Eco-Friendly Straws Market Outlook (2026 to 2036)
Sales of eco-friendly straws in the United Kingdom are estimated to progress at a 12.8% CAGR between 2026 and 2036 across national coffee chains, pub groups, and school milk carton programs. What sets the United Kingdom apart from North America is its nationwide statutory ban on retail and foodservice plastic drinking straws paired with fiscal penalties under the UK Plastic Packaging Tax. In October 2026, HM Revenue and Customs published its final evaluation of the Plastic Packaging Tax, confirming that the levy reduced virgin plastic packaging and cut annual emissions by an estimated 260,000 tonnes of CO2 equivalent between 2022/23 and 2025/26 [17]. British beverage brands and quick-service operators rely heavily on FSC-certified spiral paper straws manufactured with water-based dispersion adhesives to satisfy UK Extended Producer Responsibility recyclability assessments.
Key takeaway: In the United Kingdom, national plastic straw prohibitions and Plastic Packaging Tax incentives are estimated to drive a 12.8% CAGR.
France Eco-Friendly Straws Market Outlook (2026 to 2036)
Market demand in France is slated to climb at a 12.2% CAGR from 2026 to 2036, shaped by Europe's strictest anti-waste foodservice legislation under the French AGEC Law and national home-composting standards. While dine-in fast-food restaurants in France have transitioned to reusable tableware, takeaway beverage counters and dairy carton packers generate substantial demand for PFAS-free paper and wheat-stem straws. In late September 2026, Paris agricultural trade analysts released their France Retail Foods Annual report noting strong French consumer and retail alignment around bio-sourced packaging formats [18]. French converters must also comply with national bans on mineral-oil inks and perfluorinated grease barriers, accelerating adoption of unbleached kraft and natural agricultural-stem drinking straws.
Key takeaway: In France, takeaway beverage growth under the AGEC anti-waste law and mineral-oil-free ink mandates are projected to sustain a 12.2% CAGR.
Germany Eco-Friendly Straws Market Outlook (2026 to 2036)
German eco-friendly straw revenue is predicted to advance at an 11.9% CAGR across the 2026 to 2036 horizon, anchored by Europe's largest commercial foodservice and packaged beverage market. German procurement standards differ from southern European markets because domestic retail and bakery-cafe chains enforce rigorous BfR Recommendation XXXVI compliance on paper food-contact materials and dual-system recycling compatibility. In March 2026, Berlin agricultural analysts reported that Germany's foodservice sector represents Europe's largest out-of-home dining market across quick-service and bakery channels [19]. German beverage fillers and fast-food operators actively specify three-ply dispersion-coated kraft straws and natural cereal-stem tubes that pass strict sensory taint and migration testing.
Key takeaway: In Germany, Europe's largest foodservice base and strict BfR paper food-contact standards are slated to anchor an 11.9% CAGR through 2036.
Japan Eco-Friendly Straws Market Outlook (2026 to 2036)
Consumption of eco-friendly straws in Japan is forecast to rise at an 11.5% CAGR between 2026 and 2036 as convenience stores and coffee chains execute plastic-weight reduction plans under the Plastic Resource Circulation Promotion Act. Unlike European regulators that ban biopolymer straws outright, Japan's Ministry of the Environment actively certifies both FSC paper straws and marine-biodegradable PHBH and biomass-plastic straws across its 56,000 convenience store counters. In late 2026, Tokyo food retail analysts documented how Japanese convenience chains and food retailers are modernizing private-label ready-to-drink coffee and chilled beverage assortments [20]. Japanese consumers place a high premium on smooth mouthfeel and zero paper taste, encouraging local converters to supply ultra-thin calendered kraft straws and marine-degradable biopolymer formats.
Key takeaway: In Japan, convenience-store iced-coffee volume and government backing for biomass-certified and paper straws are predicted to support an 11.5% CAGR.
Italy Eco-Friendly Straws Market Outlook (2026 to 2036)
In Italy, the eco-friendly straws market is estimated to record an 11.3% CAGR over the 2026 to 2036 forecast window, supported by dense cafe and coastal hospitality beverage service. Italian regulatory policy differs from standard EU member states by permitting EN 13432 certified biodegradable and compostable bioplastics where reusable alternatives are impractical, paired with widespread municipal organic-waste collection. In April 2026, Rome agricultural attachés noted the expansion of Italy's hotel and catering sector driven by international tourism and out-of-home aperitivo and coffee culture [21]. Italian beverage and hospitality buyers procure both wrapped FSC paper straws and certified compostable biopolymer straws that enter municipal organic waste recovery streams with food scraps.
Key takeaway: In Italy, tourism-driven bar and cafe service and mature municipal organics collection are estimated to maintain an 11.3% CAGR through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the eco-friendly straws market?
Footprint LLC, Huhtamaki Oyj, Hoffmaster Group Inc., Tembo Paper BV, Sulapac Oy, Biotrem Sp. z o.o., GreenGood USA, World Centric, Tetra Pak International SA, and Stora Enso Oyj are the notable companies in the eco-friendly straws market.
Competitive structure in the eco-friendly straws sector spans global fiber foodservice converters, precision paper-straw machinery and board specialists, and marine-degradable biopolymer and agro-fiber innovators. Footprint LLC and Huhtamaki Oyj lead multinational quick-service restaurant supply joined by Hoffmaster Group Inc. and Tembo Paper BV through high-speed spiral-wound paper straw platforms. Sulapac Oy and Biotrem Sp. z o.o. compete against GreenGood USA and World Centric in marine-biodegradable PHA and plant-fiber formats, while Tetra Pak International SA and Stora Enso Oyj anchor aseptic carton straws and dispersion-coated kraft paperboard supply.
- Global Fiber Foodservice and QSR Straw Converters: Footprint LLC and Huhtamaki Oyj, joined by Hoffmaster Group and Tembo Paper, manufacture high-volume PFAS-free spiral paper straws and winding systems.
- Biopolymer and Agro-Residue Straw Innovators: Sulapac Oy and Biotrem formulate marine-degradable wood-biopolymer and wheat-bran straws, while GreenGood USA and World Centric supply compostable plant-fiber lines.
- Aseptic Carton and Barrier Paperboard Specialists: Tetra Pak International SA and Stora Enso Oyj supply attached U-shaped beverage-carton paper straws and dispersion-coated kraft straw board.
Competitive Benchmarking: Eco-Friendly Straws Market
Table 8: Competitive Benchmarking for the Eco-Friendly Straws Market (qualitative capability ratings), 2026
| Company | PFAS-Free Wet Stiffness | Biopolymer & Fiber Breadth | QSR & Beverage Chain Reach | Geographic Reach |
|---|---|---|---|---|
| Footprint LLC | High | High | High | North America and European manufacturing hub in Poland; PE-free cup and straw systems |
| Huhtamaki Oyj | High | High | High | Global foodservice converting across Europe, North America, Asia, and Oceania |
| Hoffmaster Group Inc. | High | Medium | High | North American foodservice disposable tabletop and Aardvark paper straw pioneer |
| Tembo Paper BV | High | Medium | Medium | Global supplier of high-speed 3mm-to-jumbo paper straw spiraling machinery and straws |
| Sulapac Oy | High | High | Medium | European and global marine-biodegradable wood-and-PHA biopolymer straw compounds |
| Biotrem Sp. z o.o. | Medium | High | Medium | Poland and EU agricultural wheat-bran and agro-residue biodegradable tableware and straws |
| GreenGood USA | Medium | High | Medium | North American BPI-certified compostable PLA, paper, and bagasse foodservice supply |
| World Centric | High | High | Medium | North American FSC-certified paper and plant-fiber jumbo and standard compostable straws |
| Tetra Pak International SA | High | Medium | High | Global aseptic beverage carton U-shaped paper straw integration across 160+ countries |
| Stora Enso Oyj | High | High | Medium | Nordic and global supplier of dispersion-coated virgin kraft paperboard for straw winding |
Evaluation basis: PFAS-Free Wet Stiffness assesses documented three-hour liquid immersion integrity using non-fluorinated aqueous coatings and adhesives, while Biopolymer & Fiber Breadth rates capability across FSC kraft paper and PHA or agro-residue substrates. QSR & Beverage Chain Reach measures multi-region quick-service restaurant and beverage-carton supply contracts.
Key Developments in the Eco-Friendly Straws Market
- Sulapac Oy scaled commercial hospitality deployment of its Sulapac Flow 1.7 drinking straw material in 2026, delivering 72% USDA-certified biobased content and 75.5% marine biodegradation with zero detected PFAS [22].
- Huhtamaki Oyj published its Half-Yearly Report in July 2026 recording EUR 1,955.8 million in first-half net sales and EUR 198.2 million in adjusted EBIT across its global fiber and foodservice packaging network [23].
- Tembo Paper B.V. expanded commercial deployment of its custom-developed high-speed paper straw winding machines in 2025, enabling beverage converters to launch automated multi-ply paper straw production lines with maximum process flexibility [24].
Key Players in the Eco-Friendly Straws Market
Global Fiber Foodservice and QSR Straw Converters
- Footprint LLC
- Huhtamaki Oyj
- Hoffmaster Group Inc.
- Tembo Paper BV
Biopolymer and Agro-Residue Straw Innovators
- Sulapac Oy
- Biotrem Sp. z o.o.
- GreenGood USA
- World Centric
Aseptic Carton and Barrier Paperboard Specialists
- Tetra Pak International SA
- Stora Enso Oyj
Eco-Friendly Straws Market - Report Scope
Table 9: Report Scope for the Eco-Friendly Straws Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Raw Material Base; Degradability Profile; Commercial Channel; Straw Geometry; Barrier Coating |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer revenue from single-use and multi-cycle eco-friendly drinking straws fabricated from FSC-certified kraft paper, sugarcane bagasse and spent coffee grounds, polylactic acid (PLA) and polyhydroxyalkanoate (PHA) biopolymers, natural bamboo and reed stalks, and wheat stems. Category Scope Note: Excludes conventional fossil-fuel polypropylene and polystyrene drinking straws, rigid reusable metal tumblers, and beverage cup lids. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, United States, Poland, United Kingdom, France, Germany, Japan, Italy, and additional countries in the full report |
| Key Companies Covered | Footprint LLC, Huhtamaki Oyj, Hoffmaster Group Inc., Tembo Paper BV, Sulapac Oy, Biotrem Sp. z o.o., GreenGood USA, World Centric, Tetra Pak International SA, Stora Enso Oyj |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Eco-Friendly Straws Market - Research Methodology
Table 10: Research Methodology for the Eco-Friendly Straws Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with quick-service restaurant packaging procurement directors, paper-straw spiral-winding engineers, aqueous dispersion coating chemists, and municipal composting facility operators to validate wet-tensile retention and B2B unit pricing. |
| Secondary Research | Analysis of EFSA Food Contact Materials Network dockets, European Commission PPWR Regulation (EU) 2025/40 and SUPD filings, Eurostat packaging waste datasets, USDA FAS global foodservice reports, and peer-reviewed MDPI and ACS polymer studies. |
| Market Sizing and Forecasting | Top-down global foodservice disposables baselines reconciled against bottom-up annual straw consumption volumes (105B to 118B eco-straws in 2026) and wholesale price per thousand units across paper, bagasse, PLA/PHA, bamboo, and wheat-stem tiers from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight national single-use plastic straw bans, PFHxA and PFAS food-contact limits, quick-service cold beverage store counts, and domestic paperboard and biopolymer converting capacity across eight national markets. |
| Operational Benchmark Traceability | Unit shipment, fiber tonnage, and regulatory compliance indicators in Tables 2, 3, and 4 trace to EFSA FCM Network October 2025 minutes, Eurostat October 2026 packaging waste releases, and MDPI European straw substitution assessments. |
| Data Triangulation and Validation | Revenue estimates isolate biodegradable, compostable, and natural plant-stem drinking straws while strictly excluding conventional petrochemical plastic straws, cup lids, and molded fiber plates. |
Eco-Friendly Straws Market by Segments
Eco-Friendly Straws Market segmented by Raw Material Base:
- FSC-Certified Paper and Kraft Pulp
- Sugarcane Bagasse and Coffee Grounds
- Polylactic Acid PLA and PHA Biopolymers
- Bamboo and Natural Reed Stalks
Eco-Friendly Straws Market segmented by Degradability Profile:
- Marine Biodegradable Formats
- Home Compostable Certified Formats
- Industrial Facility Compostable Formats
- Repulpable Paper-Stream Formats
Eco-Friendly Straws Market segmented by Commercial Channel:
- Fast-Food and Coffee Chains
- Hospitality Luxury Hotels and Resorts
- Retail Packaged Straw Packs for Homes
- Aseptic Beverage Carton Manufacturers
- Institutional Healthcare and School Catering
Eco-Friendly Straws Market segmented by Straw Geometry:
- Straight Standard-Bore Straws
- Jumbo Boba and Smoothie Straws
- Flexible Concertina Bendable Straws
- U-Shaped Carton Straws
Eco-Friendly Straws Market segmented by Barrier Coating:
- Water-Based Dispersion Coated
- Uncoated Natural Fiber
- Biopolymer Wax-Calendered
- Mineral-Filled Aqueous Barrier
Eco-Friendly Straws Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Food Safety Authority. (2025, December 12). Network Meeting on the Cooperation and Harmonisation of Risk Assessment of Food Contact Materials (FCM): Minutes of the 12th Meeting. EFSA Food Ingredients and Packaging Unit.
- [2] Footprint LLC. (2026, July 21). Footprint Expands Into PE-Free Cups with Proven Alternative to Plastic-Lined Paper Cups. Footprint Corporate Newsroom.
- [3] Eleni, P., & Boukouvalas, C. (2025, April 30). Environmental and Economic Impacts of Substituting Single-Use Plastic Straws: A Life-Cycle Assessment for Greece. Polymers, 17(9), 1235 (MDPI Open Access).
- [4] Baek, K. (2026, August 20). Migration of phthalates and per- and polyfluoroalkyl substances from paper and plastic drinking straws immersed in human saliva: a pilot migration study. Annals of Occupational and Environmental Medicine, 38, e39 (PMCID: PMC13648140).
- [5] Eurostat. (2026, October 16). Packaging waste statistics. European Commission Eurostat Statistics Explained.
- [6] Stora Enso Oyj. (2026, March 25). Engineering grease resistance for foodservice packaging: Aristo's success with CKB Nude Aqua. Stora Enso Renewable Materials Newsroom.
- [7] Upeksha, S., et al. (2025, July 23). PHA, the Greenest Plastic So Far: Advancing Microbial Synthesis, Recovery, and Sustainable Applications for Circularity. ACS Omega, 10(30), 32564.
- [8] Huhtamäki Oyj. (2026, October 29). Continued comparable net sales growth despite muted demand environment. Huhtamäki Oyj Stock Exchange Releases.
- [9] Tembo Paper B.V. (2026, February 18). We use technology for better alternatives: Tembo Paper. Tembo Paper Engineering Documentation.
- [10] Stora Enso Oyj. (2026, April 10). New barrier solutions to replace plastic in packaging. Stora Enso Packaging Materials Technical Series.
- [11] European Commission. (2025, December 23). Have your say: what is the impact of the Single-Use Plastics Directive?. Directorate-General for Environment Official News.
- [12] MDPI Recycling. (2026, May 12). The Drop-In Delusion: Technical and Systemic Impacts of PLA Contamination on Circular Waste Streams. Recycling, 11(5), 90 (MDPI Open Access).
- [13] MDPI Processes. (2025, September 24). Development of Biodegradable Straws Using Spent Coffee Grounds. Processes, 13(10), 3055 (MDPI Open Access).
- [14] USDA Foreign Agricultural Service. (2025, November 19). Mexico: Retail Foods Annual (GAIN Report MX2025-0050). U.S. Department of Agriculture Global Agricultural Information Network.
- [15] U.S. Food and Drug Administration. (2025, January 3). Market Phase-Out of Grease-Proofing Substances Containing PFAS. U.S. Department of Health and Human Services, Food and Drug Administration.
- [16] USDA Foreign Agricultural Service. (2025, December 30). Report Name: FAIRS Country Report Annual (Warsaw, Poland, PL2025-0028). U.S. Department of Agriculture Global Agricultural Information Network.
- [17] HM Revenue and Customs & GOV.UK. (2026, October 28). Plastic Packaging Tax Evaluation: final evaluation. UK Government Official Publications.
- [18] USDA Foreign Agricultural Service. (2026, September 30). France: Retail Foods Annual. U.S. Department of Agriculture Global Agricultural Information Network.
- [19] USDA Foreign Agricultural Service. (2026, March 30). Germany: Food Processing Ingredients Annual (GAIN Report GM2026-0007). U.S. Department of Agriculture Global Agricultural Information Network.
- [20] USDA Foreign Agricultural Service. (2026, September 28). Japan: Retail Foods Annual. U.S. Department of Agriculture Global Agricultural Information Network.
- [21] USDA Foreign Agricultural Service. (2026, April 2). Italy: Food Processing Ingredients Annual (GAIN Report IT2026-0001). U.S. Department of Agriculture Global Agricultural Information Network.
- [22] Sulapac Oy. (2026, May 27). Sustainable straws that don't get soggy: Sulapac Flow 1.7 Material Specifications. Sulapac Ltd. Foodservice Documentation.
- [23] Huhtamäki Oyj. (2026, July 23). Huhtamäki Oyj's Half-yearly Report January 1 to June 30, 2026. Huhtamäki Oyj Stock Exchange Releases.
- [24] Tembo Paper B.V. (2025, August 14). Your Paper Straw Production Line: With Our Paper Straw Machines. Tembo Paper B.V. Industrial Machinery Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the eco-friendly straws market in 2026 and what is forecast for 2036?
- Which single-use plastic bans and PFAS-free food-contact rules support demand for eco-friendly straws?
- Why does FSC-Certified Paper and Kraft Pulp lead the raw material base category?
- Why do Marine Biodegradable Formats lead the degradability profile category?
- How do growth rates differ across Mexico, the United States, and Poland?
- Which leading companies supply high-speed spiral paper straws versus marine-degradable PHA straws?
- What wet-sogginess and PLA waste-sorting challenges restrain the eco-friendly straws market?
- What should QSR chains evaluate before switching to water-based dispersion-coated paper straws?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Raw Material Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Raw Material Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Raw Material Base, 2026 to 2036
- FSC-Certified Paper and Kraft Pulp
- Sugarcane Bagasse and Coffee Grounds
- Polylactic Acid PLA and PHA Biopolymers
- Bamboo and Natural Reed Stalks
- Y-o-Y Growth Trend Analysis By Raw Material Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Material Base, 2026 to 2036
- Global Market Analysis and Forecast, By Degradability Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Degradability Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Degradability Profile, 2026 to 2036
- Marine Biodegradable Formats
- Home Compostable Certified Formats
- Industrial Facility Compostable Formats
- Repulpable Paper-Stream Formats
- Y-o-Y Growth Trend Analysis By Degradability Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Degradability Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Commercial Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Commercial Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Commercial Channel, 2026 to 2036
- Fast-Food and Coffee Chains
- Hospitality Luxury Hotels and Resorts
- Retail Packaged Straw Packs for Homes
- Aseptic Beverage Carton Manufacturers
- Institutional Healthcare and School Catering
- Y-o-Y Growth Trend Analysis By Commercial Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Commercial Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Straw Geometry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Straw Geometry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Straw Geometry, 2026 to 2036
- Straight Standard-Bore Straws
- Jumbo Boba and Smoothie Straws
- Flexible Concertina Bendable Straws
- U-Shaped Carton Straws
- Y-o-Y Growth Trend Analysis By Straw Geometry, 2021 to 2025
- Absolute $ Opportunity Analysis By Straw Geometry, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier Coating, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier Coating, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier Coating, 2026 to 2036
- Water-Based Dispersion Coated
- Uncoated Natural Fiber
- Biopolymer Wax-Calendered
- Mineral-Filled Aqueous Barrier
- Y-o-Y Growth Trend Analysis By Barrier Coating, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier Coating, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Raw Material Base
- By Degradability Profile
- By Commercial Channel
- By Straw Geometry
- By Barrier Coating
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Footprint LLC
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Huhtamaki Oyj
- Hoffmaster Group Inc.
- Tembo Paper BV
- Sulapac Oy
- Biotrem Sp. z o.o.
- GreenGood USA
- World Centric
- Tetra Pak International SA
- Stora Enso Oyj
- Footprint LLC
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Raw Material Base, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Degradability Profile, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Commercial Channel, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Straw Geometry, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Barrier Coating, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Raw Material Base
- Figure 6: Global Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Degradability Profile
- Figure 9: Global Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Commercial Channel
- Figure 12: Global Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Straw Geometry
- Figure 15: Global Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Barrier Coating
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Raw Material Base
- Figure 32: North America Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Degradability Profile
- Figure 35: North America Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Commercial Channel
- Figure 38: North America Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Straw Geometry
- Figure 41: North America Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Barrier Coating
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Raw Material Base
- Figure 48: Latin America Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Degradability Profile
- Figure 51: Latin America Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Commercial Channel
- Figure 54: Latin America Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Straw Geometry
- Figure 57: Latin America Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Barrier Coating
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Raw Material Base
- Figure 64: Western Europe Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Degradability Profile
- Figure 67: Western Europe Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Commercial Channel
- Figure 70: Western Europe Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Straw Geometry
- Figure 73: Western Europe Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Barrier Coating
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Raw Material Base
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Degradability Profile
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Commercial Channel
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Straw Geometry
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Barrier Coating
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Raw Material Base
- Figure 96: East Asia Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Degradability Profile
- Figure 99: East Asia Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Commercial Channel
- Figure 102: East Asia Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Straw Geometry
- Figure 105: East Asia Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Barrier Coating
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Raw Material Base
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Degradability Profile
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Commercial Channel
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Straw Geometry
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Barrier Coating
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Raw Material Base, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Raw Material Base, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Raw Material Base
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Degradability Profile, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Degradability Profile, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Degradability Profile
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Commercial Channel, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Commercial Channel, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Commercial Channel
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Straw Geometry, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Straw Geometry, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Straw Geometry
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Barrier Coating, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Barrier Coating, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Barrier Coating
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the eco-friendly straws market in 2026, and what is forecast for 2036?
FMI calculates 2025 global eco-friendly straws demand at USD 2.1 billion, advancing to USD 2.4 billion in 2026 and reaching a projected USD 7.8 billion by 2036.
What is the CAGR for the eco-friendly straws market from 2026 to 2036?
The eco-friendly straws sector is projected to expand at a 12.5% CAGR over the 2026 to 2036 window, adding USD 5.4 billion in incremental revenue across foodservice channels.
Which raw material base segment leads the eco-friendly straws market?
FSC-Certified Paper and Kraft Pulp holds an estimated 48.0% of raw material base demand in 2026 since spiral-wound kraft tubes satisfy plastic bans at low converting cost.
Which commercial channel segment leads the eco-friendly straws market?
Fast-Food and Coffee Chains represent an estimated 62.0% of commercial channel demand in 2026 owing to high-volume iced coffee, smoothie, and drive-thru beverage service.
Which country has a notable growth outlook during the assessment period?
Mexico leads national expansion projections at a 14.8% CAGR through 2036, driven by coastal tourism plastic prohibitions and domestic sugarcane bagasse and agave fiber supply.
Who are the key players in the market?
Footprint LLC and Huhtamaki Oyj lead global supply with Hoffmaster Group and Tembo Paper BV. Sulapac and Biotrem also compete globally with GreenGood, World Centric, Tetra Pak and Stora Enso.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
