
- Market Size (2026)
- USD 123.7 Bn
- Forecast (2036)
- USD 470.7 Bn
- CAGR (2026 to 2036)
- 14.3%
How big is the Edtech Market in 2026?
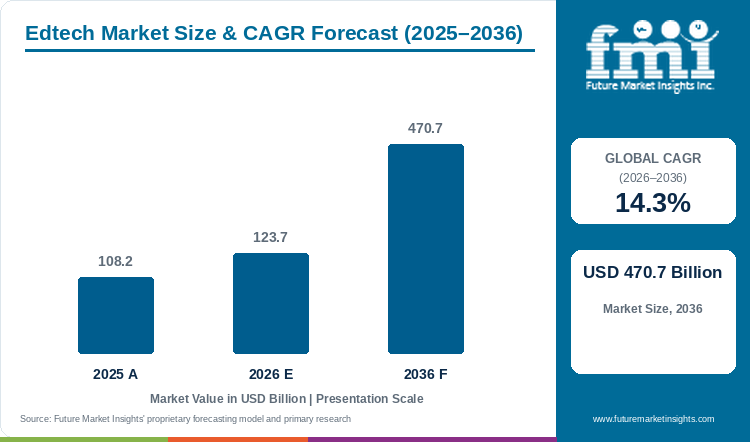
The global edtech market is estimated at USD 123.7 billion in 2026, compared with USD 108.22 billion in 2025, and is forecast to reach USD 470.7 billion by 2036, expanding at a CAGR of 14.3% from 2026 to 2036.
Demand for education devices is supported by planned school replacement programmes, which provide hardware suppliers with purchasing opportunities beyond initial classroom installations. Japan's Ministry of Education has established a 2025-2027 ICT infrastructure plan, with annual local financial support of JPY 37.3 billion planned for one-device-per-student provision under the GIGA School programme. Growth in online learning is also reflected in platform enrolment figures. According to Coursera, Professional Certificate enrolments reached 6.0 million in 2025, increasing 22% over 2024, while total course enrolments rose 10% to 54.4 million. The platform had approximately 197 million registered learners by December 2025. Course providers are also expanding their offerings to capture demand for professional qualifications. In September 2026, Coursera announced 25 new Professional Certificates and welcomed 16 new university and industry partners, strengthening its course portfolio across AI, technology and business education.
Institutional purchasing also extends beyond lessons. Australia's Education Funding System began delivery on 17 November 2025 and is progressively replacing SchoolsHUB for funding and reporting. [3] FMI's view is that moving payment and reporting functions creates work for identity, data migration and support providers, while leaving classroom content to a different buying decision. A platform provider can win this administrative work without proving that its product raises examination scores; a learning-content provider still has to establish its educational value.
Key Market Trends & Insights
- Coursera recorded 5.0 million generative-AI course enrolments in 2025. [1] This is activity in one platform, but it gives course publishers a concrete reason to refresh skills content more often than an academic textbook cycle.
- UNESCO's 2023 review found that only 40% of primary schools worldwide were connected to the internet. [2] For suppliers serving poorly connected schools, a lighter application and material that remains usable offline can matter more than adding another online feature.
Regional Highlights
- East Asia combines school-device replacement in Japan with a large higher-education population in China. MEXT's second GIGA phase and China's reported 48.73 million higher-education students in 2025 point to different sales routes: school tenders and university systems. [4][8]
- Western Europe's school-technology opportunity has a defined funding channel in Germany. The Digitalpakt 2.0 agreement took effect on 1 September 2026 with EUR 5 billion from federal and state governments over five years, giving infrastructure and teacher-development suppliers a programme against which to plan bids. [5]
Table 1: Edtech Market Size and Forecast (USD billion and CAGR percentage), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 108.22 billion |
| Estimated market size in 2026 | USD 123.7 billion |
| Projected market size by 2036 | USD 470.7 billion |
| CAGR from 2026 to 2036 | 14.3% |
| Added revenue from 2026 to 2036 | USD 347.0 billion |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
Analyst Perspective
“A school's device purchase and a paid course platform have different budgets and renewal dates. Coursera's 197 million cumulative registrations show reach, but a buyer should judge the next contract by actual use, such as its 54.4 million enrolments in 2025, and by teaching outcomes.”
- Sudip Saha, Principal Consultant, FMI
How is the Edtech Market segmented?
- By Component: Hardware, software and digital content.
- By End User: Academic institution segment, individual learners, and corporate and other buyers.
- By Application: Preschool, K-12, higher education, and workforce and lifelong learning.
- By Region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does hardware lead by component?
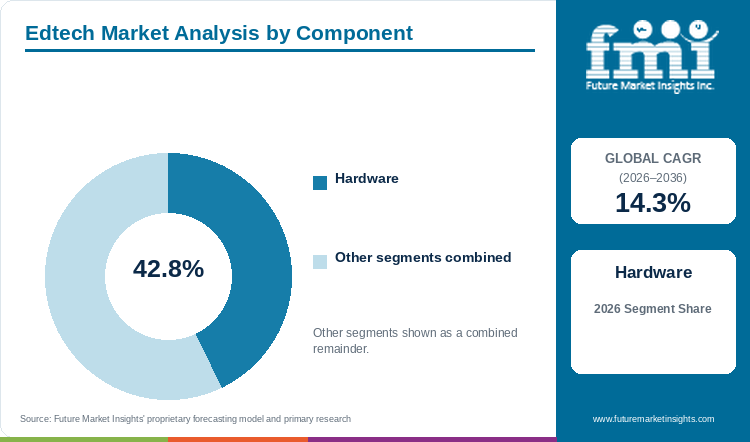
Hardware holds 42.8% of the Edtech Market by component in 2026, as per FMI's assessment.
The hardware order pays for a physical device fleet that must remain available across lessons and school years. This makes repair, replacement and management part of the purchase decision. Japan's second GIGA School phase specifically concerns renewing one-to-one student terminals. [4] FMI finds that such a programme gives suppliers a route to repeat orders when an installed fleet reaches its replacement date; a popular application alone does not create the same device requirement.
Hardware's lead does not mean software has little influence over the award. Microsoft's A3 education plan adds desktop applications, security and device management to its entry offering. [7] A school comparing devices therefore needs to consider what it will cost to manage them with the software it chooses. Suppliers able to deliver a supported fleet and explain the recurring licence cost have a clearer offer than sellers quoting only a unit price.
Table 2: Edtech Market Component Share Comparison (percentage), 2026
| Leading Share | 2026 market share |
|---|---|
| Hardware | 42.8% |
| All Other Segments Combined Share | 57.2% |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
Why is the academic institution segment the largest end-user group?
The academic institution segment holds 53.4% of the Edtech Market by end user in 2026, as per FMI's assessment.
Schools and universities buy for a cohort rather than a single learner, so an institutional decision can cover devices, content access and the systems used to administer both. Google's paid Classroom editions include imports of student rosters from a student information system. [6] FMI finds that this connection matters at the start of term: teachers need the right students in the right classes before an application can become a routine teaching tool.
The institutional lead also creates a longer sales process. The education provider has to decide who controls learner records and how a new product fits its existing systems. Australia's EFS transition keeps funding payments and data collections running while functions move from SchoolsHUB. [3] This supports demand for implementation and continuing support rather than a single software installation. Individual learners and employers remain distinct customers, with different payment arrangements and renewal decisions.
Table 3: Edtech Market End-user Share Comparison (percentage), 2026
| Leading Share | 2026 market share |
|---|---|
| Academic institution segment | 53.4% |
| All Other Segments Combined Share | 46.6% |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
What supports higher education as the leading application?
Higher education holds 45.0% of the Edtech Market by application in 2026, as per FMI's assessment.
Universities need digital material that fits the subject being taught and produces feedback during a course. Pearson offers MyLab, Mastering and Revel alongside its Pearson+ eTextbooks. [11] FMI finds that this gives the content provider a place in course selection rather than relying solely on a general-purpose application being adopted across the campus. An instructor can buy a subject-specific assessment tool even when the institution already has a central learning platform.
Scale reinforces this opportunity. China's government reported a higher-education gross enrolment rate of 61.3% and 48.73 million students in 2025. [8] Those figures describe China, rather than the global market share, but they show why universities are a large addressable customer group. Providers still need to demonstrate that their material fits the curriculum and that learners can access it throughout the term. Student numbers alone do not establish paid digital-content revenue.
Table 4: Edtech Market Application Share Comparison (percentage), 2026
| Leading Share | 2026 market share |
|---|---|
| Higher education | 45.0% |
| All Other Segments Combined Share | 55.0% |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
What are the key drivers restraints and opportunities?
Replacement programmes support device orders, while evidence of classroom benefit determines whether learning products are renewed. The opening for providers lies in solving a specific teaching or administrative problem within these budgets.
Driver
Scheduled renewal brings an existing device base back to market. MEXT's second GIGA phase funds renewal of one-to-one student terminals. [4] FMI finds that this creates demand for deployment, repair arrangements and migration alongside the machines. Suppliers that plan these services around the school calendar can reduce the disruption that makes an otherwise cheap replacement unattractive.
Restraint
Weak evidence of educational benefit makes a learning subscription harder to defend. UNESCO found that impartial evidence on edtech's impact remains scarce and that much of the available research comes from wealthier countries. [2] A result from one setting therefore needs to be tested against the buyer's learners and teaching conditions. This increases the importance of a manageable trial before a wider contract.
Opportunity
Providers can win continuing revenue by linking course material to a defined skills requirement and reporting its use clearly. Coursera distinguishes consumer and enterprise activities in its financial reporting. [1] FMI finds that employers and institutions can use this kind of contract to buy learning access for a group while keeping completion and skills assessment central to the renewal decision.
How do privacy and purchasing rules affect edtech contracts?
In the United States, the FTC's COPPA guidance allows a school to consent on parents' behalf only within the educational context; that authority does not permit unrelated commercial use of children's data. [9] FMI finds that a vendor must be able to explain the purpose of each data collection before a school can assess the service. A product that requires unnecessary personal information can face resistance even when its classroom functions are useful.
What limits reliable classroom operation?
A lesson can fail if the application assumes a connection or workflow the school cannot provide. The US National Educational Technology Plan separates access, design and use divides, showing that equipment alone does not resolve how technology is taught with. [12] FMI's view is that suppliers should test login, content access and teacher preparation in the actual lesson environment. Training and usable materials belong in the delivery plan rather than being left for the teacher to solve after purchase.
Where can suppliers win additional edtech business?
There is room to sell support that helps institutions use what they already own. Germany's Digitalpakt 2.0 includes teacher development and shared digital solutions as well as infrastructure. [5] FMI finds that a provider able to connect technical deployment with teacher preparation can compete for a broader programme. The opportunity depends on the funded work and the tender, rather than assuming that every school-technology allocation becomes device revenue.
Edtech Market by Country (2026 to 2036)
Table 5: Edtech Market Country CAGR Comparison (percentage), 2026 to 2036
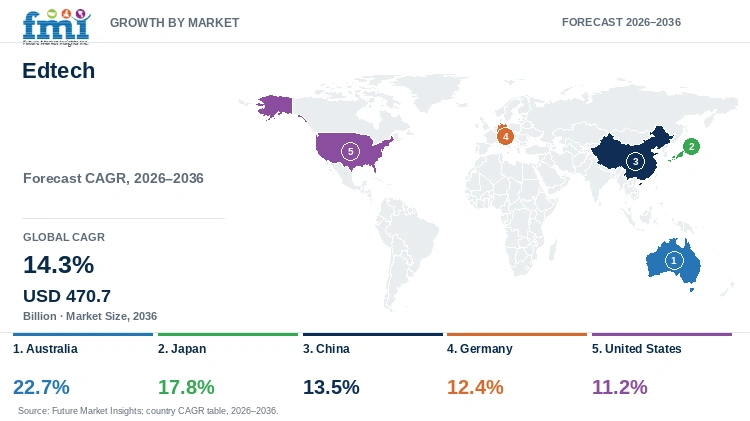
| Country | CAGR |
|---|---|
| Australia | 22.7% |
| Japan | 17.8% |
| China | 13.5% |
| Germany | 12.4% |
| United States | 11.2% |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
Australia
Moving school funding and reporting onto a new system creates work that follows payment and data-collection deadlines. Australia's Department of Education began EFS delivery on 17 November 2025. Approved authorities can use Digital ID to enter the system, view payments and submit data collections. [3] Suppliers have to make these functions work with the education provider's existing records and staff responsibilities. This administrative work, alongside purchases for teaching, supports FMI's 22.7% CAGR forecast for Australia from 2026 to 2036, the highest rate among the five countries profiled.
The transition is being organised around readiness and business timeframes rather than a single release of every function. The department says block grant authorities are due to onboard in November 2026. [3] That gives an implementation provider a specific operational milestone to work towards. A required collection still has to be submitted while staff learn the new system, so data migration, access and preparation need to fit the provider's reporting calendar. Completing the software installation alone does not settle that work.
A funding platform records obligations and payments; its rollout does not establish gains in classroom learning. Suppliers serving administration and learning content therefore need different evidence for each offer. An integration specialist can demonstrate that records arrived correctly and on time. A content provider must instead establish use and learning within a course. Australia's outlook leaves room for both, but each contract depends on the function being bought and the institution's ability to adopt it. Administrative implementation cannot stand in for evidence that a teaching product works.
Japan
MEXT's second GIGA School phase brings devices already assigned to Japanese pupils back into the purchasing cycle. The ministry explicitly identifies renewal of one device per student. [4] This gives hardware suppliers a recurring replacement market with a visible reason for an order: the school needs to replace an existing terminal. General enthusiasm for digital lessons does not create the same requirement. An installed fleet also gives the buyer a practical basis for deciding what repair and deployment support it needs from the next supplier.
Keeping that fleet available during teaching is part of the commercial task behind Japan's 17.8% CAGR forecast from 2026 to 2036. Replacing equipment means transferring access and preparing staff, with the work arranged around the school year. The supplier's ability to organise these steps can influence an award alongside its hardware price. A terminal that remains difficult to administer leaves the school with recurring work whenever a learner changes class or loses access, even after the replacement order has been delivered.
GIGA is intended to improve individual and collaborative learning through devices and networks, as MEXT describes it. [4] Buyers still have to decide how teachers will use the equipment and whether selected material fits the lesson. Training and classroom support can therefore accompany a fleet renewal, while content providers need a separate case for adoption. A new terminal does not automatically create another paid application subscription. The 17.8% forecast reflects this cycle of replacement and use rather than a single tender date; suppliers need a credible repair arrangement and a deployment plan that schools can carry out.
China
China's universities give education suppliers access to large groups of enrolled learners through a course or departmental purchase. The government reported 48.73 million higher-education students in 2025 and a gross enrolment rate of 61.3%. [8] That institutional scale supports FMI's 13.5% CAGR forecast for China from 2026 to 2036: a successful university deployment can reach a substantial cohort without a separate sale to every student. The opportunity is to serve those institutions, rather than count every enrolled student as a paying digital customer.
A campus system and a learning product address different decisions within that customer base. The university needs reliable records and access across courses; an instructor may choose material for a particular subject. Suppliers need to explain which of those jobs their product performs. A platform useful for administration can still require content from another publisher before it serves a specific lesson. Treating the two purchases as interchangeable can obscure who controls the budget and who must be persuaded to adopt the offer.
Large cohorts also make support a purchasing issue. An access problem at the start of term can affect many learners at once. Institutions therefore need to see how users enter a system, how material is assigned and how records are recovered when something goes wrong. An implementation plan answers these questions more directly than the breadth of a supplier's catalogue.
The 13.5% outlook allows for new purchases and wider use within existing institutions. These are commercial implications of the reported enrolment base, not a conversion of that base into paid revenue. Providers still have to establish that their material fits the local curriculum and that the budget holder will pay for the function being offered.
Germany
The timing of funded school projects matters to German edtech suppliers as much as the size of the announced budget. The Digitalpakt 2.0 administrative agreement took effect on 1 September 2026, after the minister signed it on 31 August. Federal and state governments are providing EUR 5 billion over five years, with EUR 2.5 billion from each side. [5] Suppliers have a defined programme against which to plan bids, but an available allocation is not yet an order.
FMI's 12.4% CAGR forecast for Germany from 2026 to 2036 depends on that funding becoming usable projects. The ministry includes infrastructure, teacher development and joint digital solutions among the programme's objectives. [5] A bidder has to decide whether its offer covers installation, continuing technical service or support for teaching. Quoting only the hardware can leave a school with costs and responsibilities that the funded work also needs to address.
Common standards can affect how suppliers develop their products. The ministry stresses shared solutions and avoiding duplicate development across states. [5] A product that works within that approach has a route to repeat deployment without a separate design for every school. Local implementation still matters: staff need preparation, and the existing network must support the service that the school chooses. A common specification does not complete these tasks for the provider.
The 12.4% outlook therefore turns on when tenders open, which activities are eligible and when schools can put the resulting systems to work. Suppliers should separate programme budgets from revenue already awarded. Their delivery plans and recognition of orders need to follow the practical demands of each school, rather than assume that the full funding commitment becomes equipment sales at once.
United States
Privacy can determine whether a service reaches a US school before its classroom features are tested. Under the FTC's COPPA guidance, school-authorised collection for education is distinct from unrelated commercial use of children's information. [9] A vendor serving younger learners needs a clear account of its data practices that the school can assess. This creates work in product design and contracting before a wider deployment, rather than leaving data use to be explained after the product has been adopted.
Purchases also depend on how technology is used. The US National Educational Technology Plan treats access, design and use as separate divides. [12] Equipment availability is therefore only part of the school opportunity. FMI's 11.2% CAGR forecast for the United States from 2026 to 2036 covers several routes through schools, universities and employers; a single platform's audience cannot measure that national market. Each buyer needs a service suited to the work it is funding.
For higher education, adoption may rest with a course rather than a central technology team. Pearson's US offer includes subject learning platforms and eTextbooks. [11] A publisher can reach a defined group of students through that course decision, while an employer may buy continuing skills access across job roles. Reporting activity in a form that helps the relevant buyer decide whether to renew is part of both offers.
Although the 11.2% forecast is the lowest among the five profiled countries, it still implies expansion across these purchasing routes. Suppliers need to demonstrate a specific learning or operational benefit. Registrations can show distribution, but an institutional buyer needs evidence that the paid service is used and fits its purpose. Reach alone does not settle the next contract.
Who are the notable companies in the Edtech Market?
Google for Education, Microsoft Education, Coursera and Pearson occupy different parts of the education purchase. Google and Microsoft supply classroom and institutional tools, Coursera distributes courses and credentials, and Pearson supplies subject content and assessment products. [6][7][1][11] FMI finds that their offers can appear in the same institution without serving the same contract.
Google's published Classroom functions include roster imports and grading tools. [6] These functions place it in the routine work of organising classes. Microsoft's education plans combine teaching tools with security and device-management options. [7] Its commercial position therefore includes the administration of an institution's estate as well as the applications used in lessons.
Coursera connects learners with university and industry content providers, while Pearson's named platforms attach content and assessment to courses. [1][11] FMI's view is that the important distinction is who controls adoption: a central technology team, a course instructor, an employer or an individual learner. Suppliers have to earn renewal from that decision-maker. Coursera's completed combination with Udemy on 11 May 2026 changes the corporate structure of online skills learning, although the company said the platforms would initially remain separate. [10] Integration of the offer should therefore be distinguished from the completion of the transaction.
Key Developments in the Edtech Market
- On 11 May 2026, Coursera completed its combination with Udemy. The company told learners that the two remained separate platforms at that time, making this a completed corporate transaction rather than an already unified product experience. [10]
Key Players in the Edtech Market
- Google for Education
- Microsoft Education
- Coursera
- Pearson
Edtech Market Report Scope
Table 6: Edtech Market Report Scope, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Paid education hardware, software and digital content supplied to institutions and learners. |
| Boundaries | Education technology purchases; broad education funding and total enrolment are contextual indicators rather than market revenue. |
| Quantitative units | USD billion for market value; percentages for shares and forecast CAGRs. |
| Period | 2025 reference value, 2026 base year and forecasts to 2036. |
| Component coverage | Hardware, software and digital content. |
| Buyer and application coverage | Academic institution segment, individual learners and corporate buyers; preschool through lifelong learning. |
| Detailed country profiles | Australia, Japan, China, Germany and United States. |
| Global coverage | Seven regions with the nested country and subregion coverage listed below. |
| Competitive coverage | Classroom platforms, institutional software and course-content providers; verified company activity and purchasing implications. |
Source: Future Market Insights, Edtech Market Report, 2026 to 2036.
Edtech Market Research Methodology
The Edtech Market assessment draws on government programme documents, a company regulatory filing, published product specifications and UNESCO's education review. Market values, segment shares and country forecasts reflect FMI's outlook. The analysis separates enrolment, registration, platform activity and revenue, and distinguishes announced functionality from delivered services. Public programme scope and company capabilities inform the discussion of purchasing and competitive positions.
Edtech Market by Segments
Edtech Market segmented by Component:
- Hardware
- Software
- Digital content
Edtech Market segmented by End User:
- Academic institution segment
- Individual learners
- Corporate and other buyers
Edtech Market segmented by Application:
- Preschool
- K-12
- Higher education
- Workforce and lifelong learning
Edtech Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- Taiwan
- South Asia and Pacific
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Coursera. Form 10-K for the year ended 31 December 2025. Filed February 2026.
- [2] UNESCO. Global Education Monitoring Report 2023: Technology in education, a tool on whose terms? 2023.
- [3] Australian Department of Education. EFS delivery; Release 1 - November 2025. Accessed 31 October 2026.
- [4] Japan Ministry of Education, Culture, Sports, Science and Technology. GIGA School programme; renewal of one device per student through the second-phase fund. Accessed 31 October 2026.
- [5] German Federal Ministry of Education and Family Affairs. Karin Prien signs the Digitalpakt 2.0 administrative agreement. 1 September 2026.
- [6] Google for Education. Google Classroom is made for teaching. Accessed 31 October 2026.
- [7] Microsoft Education. Microsoft 365 Education plans. Accessed 31 October 2026.
- [8] State Council of China, reporting the Ministry of Education via Xinhua. China's population with higher education reaches 270 million. 23 September 2026.
- [9] US Federal Trade Commission. Complying with COPPA: Frequently Asked Questions, section N, COPPA and Schools. Accessed 31 October 2026.
- [10] Coursera. How the Coursera and Udemy combination will impact Coursera learners. 11 May 2026.
- [11] Pearson. For College: eTextbooks, study tools and learning platforms. Accessed 31 October 2026.
- [12] US Department of Education. A Call to Action for Closing the Digital Access, Design, and Use Divides: 2024 National Educational Technology Plan. January 2024.
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- Hardware
- Software
- Digital content
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Academic institution segment
- Individual learners
- Corporate and other buyers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Preschool
- K-12
- Higher education
- Workforce and lifelong learning
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- Taiwan
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Singapore
- Other ASEAN countries
- Australia and New Zealand
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Component
- By End User
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By End User
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By End User
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By End User
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Google for Education
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Microsoft Education
- Coursera
- Pearson
- Google for Education
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Component, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Component
- Figure 6: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End User
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Component
- Figure 26: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by End User
- Figure 29: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Component
- Figure 36: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by End User
- Figure 39: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Component
- Figure 46: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by End User
- Figure 49: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Component
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by End User
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Component
- Figure 66: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by End User
- Figure 69: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Component
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Component, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Component, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Component
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
What is the Edtech Market forecast?
FMI forecasts USD 470.7 billion by 2036 from USD 123.7 billion in 2026, compared with USD 108.22 billion in 2025, at a 14.3% CAGR from 2026 to 2036.
Which component leads the Edtech Market?
Hardware holds 42.8% of the 2026 market by component in FMI's assessment.
Which end user and application lead the Edtech Market?
The academic institution segment holds 53.4% by end user and higher education holds 45.0% by application in 2026, as per FMI's assessment.
Which profiled country grows fastest?
Australia has the highest FMI forecast CAGR at 22.7% from 2026 to 2036, followed by Japan at 17.8%.
What makes an edtech subscription worth renewing?
FMI finds that the buyer needs evidence of use and benefit for its teaching or skills objective. UNESCO cautions that access to technology alone does not establish educational value. [2]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
